2 days ago
Clark Howard calls Medicare Advantage plans "disadvantage plans," warning the new SCAN Costco HMO prioritizes cost savings over patient care through prior authorization denials.
In a serious illness year, a $0-premium Advantage plan can cost $6,807 more than Original Medicare plus Medigap Plan G, which caps costs at $283 annually.
Choosing Advantage at 65 may permanently lock you out of Medigap coverage if you get sick later, since most states allow insurers to deny or upcharge applicants.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
"Costco. Do you know what you're doing here? You know who you're messing around with?" Consumer advocate Clark Howard, usually one of the warehouse club's biggest fans, said that on his show on October 5.
#clark #plan #plans

3 days ago
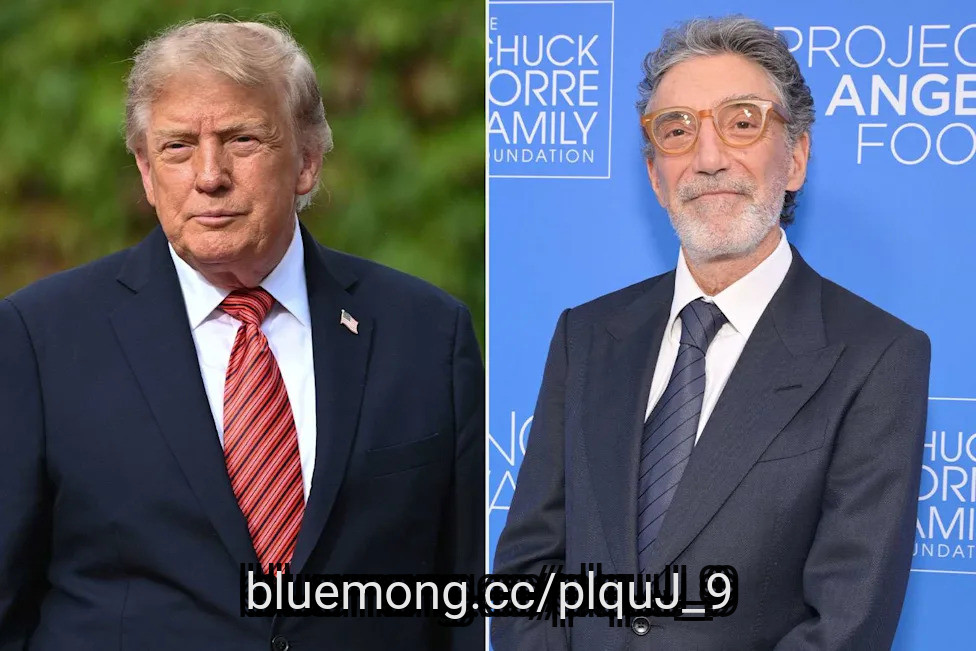
Chuck Lorre ignited a feud with White House after a charity gala speech put Donald Trump on notice.
Lorre lamented that while he'd love to champion a "compassionate government," he instead feels compelled to "say a few words about that bloated orange piece of s--- in the White House."
A spokesperson for the White House responded, encouraging Lorre to "immediately seek psychiatric help to treat his severe case of Trump Derangement Syndrome."
Add Chuck Lorre to the overstuffed rolodex of Hollywood legends who have personal beef with Donald Trump.
The creator of such modern classics as The Big Bang Theory and Two and a Half Men took no prisoners in his acceptance speech after winning the Founders Award at a Project Angel Food fundraiser in Los Angeles on Sept. 26. "Sure, I'd love to stand here and talk about my deep yearning for a more compassionate government, one that prioritizes the health and welfare of its citizens," he lamented. "But the burden of my profession demands that I take this opportunity to say a few words about that bloated orange piece of s--- in the White House" (per The Daily Beast).
#lorre #speech #compassionate
27 days ago
Gisele Bündchen welcomed her third child, a son, in February 2025 with husband Joaquim Valente
She prioritizes family over work, turning down most jobs to spend time with her three children
Bündchen says becoming a mother again has reshaped her priorities and brought profound personal growth
Gisele Bündchen is opening up about welcoming her third baby at this moment in her life.
The supermodel, 46, was interviewed by i-D 377 for their cover story and addressed welcoming her third baby, a son, in February 2025. Bündchen, who is also mom to daughter Vivian, 13, and son Benjamin, 16, called growing her family "such a gift."
#Third #gisele #february #valente


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
30 days ago
CNBC reported that The Goodyear Tire & Rubber Company (NASDAQ:GT) has extended the timeline for its "Goodyear Forward" turnaround plan after key financial targets went unmet.
CEO Mark Stewart told CNBC the company is trying to reach a 10% operating margin and generate meaningful cash flow, but debt remained above $7 billion at the end of the second quarter. Goodyear posted a $453 million net loss through the first half of the year against operating income of just $131 million, a 1.6% margin. The business has been hit by tariffs, elevated raw material costs, and expanding competition from cheaper Chinese tire imports. Capital expenditures, which ran roughly $2 billion combined in 2024 and 2025, are expected to fall to $725 million this year as the company prioritizes debt paydown and refinancing.
Copyright: baranq / 123RF Stock Photo
The core business is still generating a positive operating margin even amid a large net loss. Operating income of $131 million over six months shows The Goodyear Tire & Rubber Company (NASDAQ:GT)'s core tire operations are not losing money at the operating level, suggesting the much larger net loss stems mainly from the cost of servicing its debt rather than the core business itself failing.
Management is showing real capital discipline and not just promises since cutting planned capital expenditures to $725 million this year from roughly $1 billion annually in 2024 and 2025 combined is a measurable step toward freeing up cash for debt reduction. Moreover, tangible customer-facing investments, like the new retail concept store Stewart showcased in Detroit.
#goodyear #tire

1 month ago
By Marcela Ayres
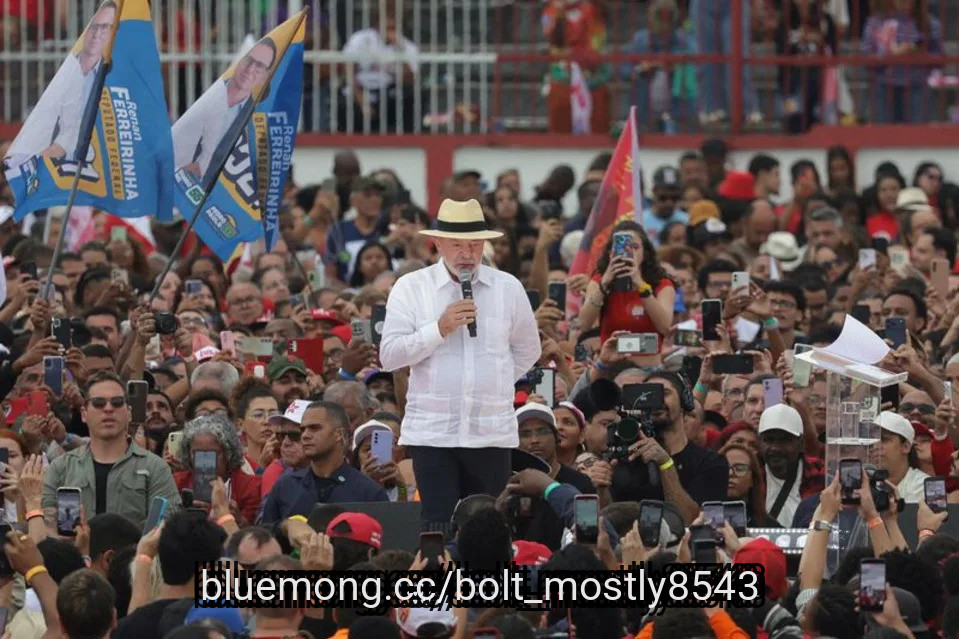
BRASILIA, Sept 4 (Reuters) - Brazil's wealthiest captured a record share of national income under President Luiz Inacio Lula da Silva, tax-return data show, offering a striking counterpoint to the leftist leader's effort to convince voters that gains have been widely shared under his administration as he seeks reelection in October.
Lula has pointed to falling inequality, as measured by a record-low Gini coefficient in 2024, and rising employment as evidence that his administration prioritizes poorer Brazilians.
But tax-return data paint a more complex picture: high interest rates, partly a consequence of increased government spending, fueled a boom in financial income that disproportionately benefited the wealthy, even as stronger labor markets, wage gains, and social programs improved conditions at the bottom of the income distribution.
"If government benefits, on the one hand, are well targeted, they can have a positive social impact," said Otaviano Canuto, a former World Bank vice president.
#income #record
1 month ago
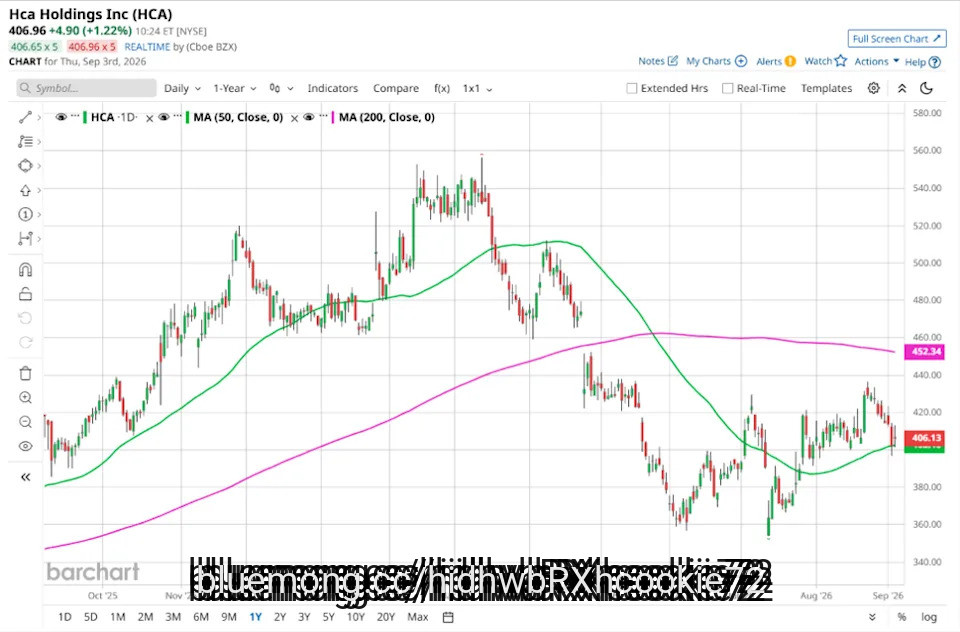
HCA Healthcare, Inc. (HCA), headquartered in Nashville, Tennessee, owns and operates hospitals and related healthcare entities. Valued at $87 billion by market cap, the company provides diagnosis, treatments, consultancy, nursing, surgeries, and other services, as well as medical education, physician resource center, and training programs.
Companies worth $10 billion or more are generally described as "large-cap stocks," and HCA definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical care facilities industry. HCA's strengths include its scale, cost leadership, and diversified portfolio. With a strong presence in high-growth states like Florida, Texas, and Tennessee, HCA leverages favorable demographics and growing healthcare demand. Its brand recognition fosters patient trust, and innovation through tech partnerships and digital health investments drives growth. HCA prioritizes talent management, positioning itself for long-term success in value-based care and telehealth trends.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ****** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#market #medical

1 month ago
Danny Sprinkle and the Washington Huskies are set to host one of the nation's top prospects on an official visit on September 5 when four-star guard Jimmie Haywood returns home.
The 6-foot-3, 170-pound product of Compass Prep in Chandler, Arizona, who is ranked as the No. 128 overall prospect and No. 15 shooting guard in the 2027 class by 247Sports, began his career at Garfield High School in Seattle before moving south.
Now, as Sprinkle prioritizes local talent as he continues to rebuild the program, Haywood could emerge as a top target for the Huskies in the months leading up to signing day.
Among Sprinkle's other top targets in the 2027 class is another local product, five-star guard Jalen Davis out of Bremerton High School, and as the Huskies look to replenish the depth on their roster through the high school ranks, the pair has the potential to become building blocks for their hometown team.
During his visit, Haywood will also likely be accompanied by five-star power forward Ahmed Nur, who is slated to arrive on Sunday, September 6. Washington is also expected to host one of the top players in the 2028 class, five-star guard Jordan Mize, on Friday, September 18.
#school #class #sprinkle
1 month ago
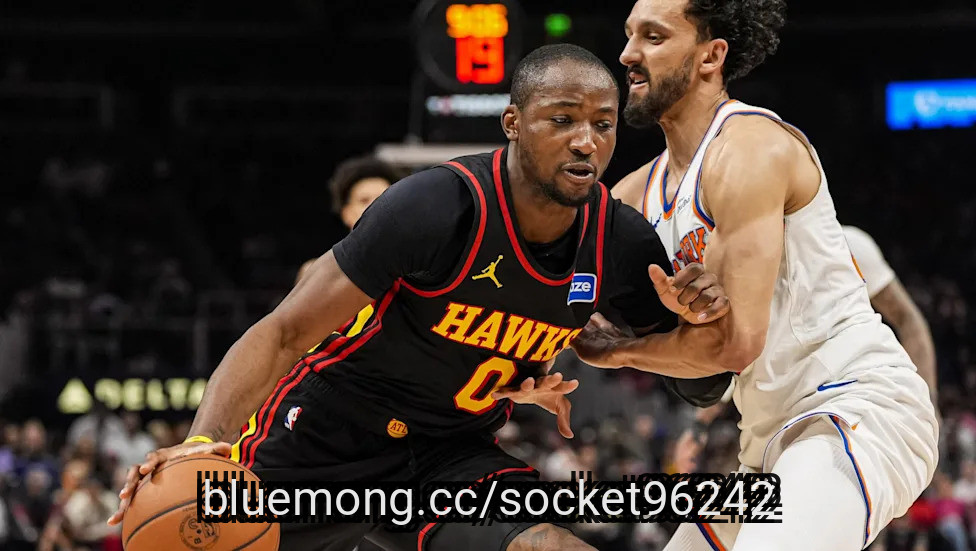
Jonathan ******* inga picked the Minnesota Timberwolves over the Los Angeles Lakers, a move that stunned fans expecting a bigger paycheck. The 23-year-old forward signed a two-year, $12.4 million deal that includes a player option for the 2027-28 season. This structure lets him test free agency again next summer when more teams will have cash to spend.
His agent, Aaron Turner, told The Athletic that defense was the main reason for the switch. Turner said, "Ant was super active in the recruitment of him," referring to Anthony Edwards' role in the process. Edwards focused his message on the team's defensive identity rather than just offense.
Turner explained that while everyone else looked at the offensive side of the ball, ******* inga and his team looked at the defensive end. "He made this decision because of the defensive versatility of this team," Turner stated. The Lakers offered a sign-and-trade that would have locked ******* inga into a three-year deal worth $12 million a year. Minnesota offered a shorter path to a massive payday later. ******* inga wants to prove he can guard multiple positions before signing a long-term contract in 2027. The Timberwolves need that specific skill set to win now, and ******* inga sees a clear role where he can shine.
This choice follows a pattern of ******* inga turning down safer options to bet on his future value. Before leaving the Golden State Warriors, he declined a three-year, $75 million extension. According to reports, prioritizing finances over the game doesn't sustain the ability to generate increasing revenue. The Warriors didn't offer a clear starting role, so ******* inga felt he couldn't bet on himself there. He took the shortest option available, which eventually led to his trade to the Atlanta Hawks and then to Minnesota.
The Hawks declined his $24.3 million team option, making him an unrestricted free agent. Now, he faces a new challenge in Minnesota alongside stars like Anthony Edwards and Jaden McDaniels. This mindset fits a team that prioritizes winning over individual numbers. ******* inga knows he must play well to maximize his next contract, and the Timberwolves provide the right system to show off his two-way potential.
#timberwolves #edwards #team
1 month ago
The Schwab International Equity ETF (NYSEMKT:SCHF) provides exposure to developed markets outside the U.S., while the Vanguard FTSE Emerging Markets ETF (NYSEMKT:VWO) targets developing economies, often marketed as a trade-off between established stability and higher growth potential.
Developing an international portfolio often requires choosing between established economies and high-growth emerging ones. While the Vanguard FTSE Emerging Markets ETF seeks to capture the rapid expansion of developing nations, the Schwab International Equity ETF prioritizes the relative stability and industrial might of mature, non-U.S. markets. This comparison ****** yzes how these two distinct approaches impact total returns, cost structures, and underlying volatility for long-term investors.
Metric
VWO
SCHF
#markets #schf #vanguard #ftse

1 month ago
Shares of Affirm Holdings, Inc. (NASDAQ:AFRM) fell 1.3% on August 18 as Klarna plunged more than 22% after reducing its 2026 volume and revenue forecasts. Klarna now expects full-year gross merchandise volume of $149 billion-$151 billion, down from more than $155 billion, and revenue of $4.08 billion-$4.16 billion, down from $4.34 billion. Yet the warning was not cleanly industrywide. Klarna's second-quarter revenue increased 27%, overall volume rose 18%, and U.S. volume grew 27%. Management tied the weaker outlook primarily to soft German retail conditions, while currency translation reduced projected volume by approximately $600 million. Affirm shares rebounded 5.1% the next session. For Affirm Holdings, Inc. (NASDAQ:AFRM), the August 27 earnings report must show whether the initial decline reflected a broader consumer-credit warning or an opportunity to capture share from a slowing competitor.
Affirm Holdings, Inc. (NASDAQ:AFRM) enters the report with stronger momentum than Klarna's guidance might suggest. Fiscal third-quarter gross merchandise volume increased 35% to $11.6 billion, while revenue rose 33% to $1.04 billion. Active consumers grew 22% to 26.8 million, and active merchants increased 44% to 515,000.
The strongest argument for Affirm Holdings, Inc. (NASDAQ:AFRM) is that its growth is spreading beyond the online checkout ****** on. Affirm Card volume jumped 146% to $2.1 billion, while active cardholders more than doubled to 4.4 million. Direct-to-consumer volume increased 48%, and wallet and software partnerships helped expand the merchant network.
Affirm Holdings, Inc. (NASDAQ:AFRM) also has substantial funding capacity to support further share gains. Capacity reached $28.2 billion in March, up from $23.3 billion a year earlier, while the average annualized cost of funds declined 126 basis points to 5.8%. The company estimated that its funding arrangements could support more than $65 billion of annual volume. If Klarna prioritizes profitability over aggressive near-term growth, as some ****** ysts inferred, the slower volume outlook could create room for Affirm without requiring the company to strain its balance sheet.
Affirm Holdings, Inc. (NASDAQ:AFRM) remains exposed to the same consumer and financing pressures affecting the broader BNPL category. The 30-plus-day delinquency rate on monthly installment loans, excluding Peloton and Pay in X, increased 29 basis points year over year to 2.8%. The allowance for credit losses rose to 6.0% of loans held for investment from 5.7% a year earlier.
#NASDAQ #year #increased #klarna
2 months ago
Baron Capital, an investment management company, released its Q2 2026 investor letter for the "Baron Discovery Fund". A copy of the letter is available to download here. Baron Discovery Fund appreciated by 19.08% (Institutional Shares) in the quarter, underperforming the Russell 2000 Growth Index, which gained 25.71%. This lag was primarily due to a momentum-driven "AI winners" trade, with these stocks largely contributing to the Benchmark's performance. The Fund experienced a 6.63% underperformance, largely driven by an underweight in strong-performing Momentum and Beta factors. The Fund prioritizes a long-term balanced portfolio over chasing momentum. The letter discussed parallels between the current AI market and the late 1990s dot-com bubble. The firm remains focused on company fundamentals and long-term valuation. Please review the fund's top five holdings to gain insights into their key selections for 2026.
In its Q2 2026 investor letter, Baron Discovery Fund highlighted Forgent Power Solutions, Inc. (NYSE:FPS) as a leading contributor to performance. Forgent Power Solutions, Inc. (NYSE:FPS) is a leading industrial company that designs and manufactures electrical distribution equipment used in data centers, the power grid, and energy-intensive industrial facilities. On August 10, 2026, Forgent Power Solutions, Inc. (NYSE:FPS) closed at $37.60 per share, reflecting a market capitalization of $11.45 billion. Forgent Power Solutions, Inc. (NYSE:FPS) posted a one-month return of -6.12%.
Baron Discovery Fund stated the following regarding Forgent Power Solutions, Inc. (NYSE:FPS) in its Q2 2026 investor letter:
"Forgent Power Solutions, Inc. (NYSE:FPS) is a leading manufacturer of electrical distribution equipment used in data centers, the power grid, and industrial applications. Forgent is a low- and medium voltage equipment specialist focused on custom, "engineered-to order" products (over 90% of revenue) whereas larger competitors in the industry generally focus more on higher voltage and standard products. The stock rose during the quarter as Forgent continued to deliver very strong financial results reflecting improving demand for its products amidst the broader data points on AI infrastructure and grid buildout continuing to point to strong growth for the next several years. Forgent is gaining share with its ability to offer customized products at industry-leading lead times and is still just scratching the surface of its opportunity having sold very little directly to the biggest customers in the market. The company has invested heavily in capacity and people to support future growth, and we see many strong years of growth and margin expansion ahead as it grows from an approximate $1.2 billion revenue run rate currently into its $5 billion manufacturing footprint."
#fund #baron #discovery #Growth

2 months ago
Luka Dončić and his ex-fiancée, Anamaria Goltes, appear to be taking a step toward resolving their family matters outside the courtroom.
According to newly filed court documents obtained by TMZ, Goltes has asked a Los Angeles judge to dismiss her California child support petition without prejudice, saying she intends to work toward a mutual agreement with Dončić that prioritizes the well-being of their two young children.
"I am withdrawing my Petition for Child Support with the specific intention of resolving this matter amicably and by a mutual agreement which is in the best interests of our children," Goltes stated in the filing.
The request marks the latest development in the former couple's legal dispute, which began after Goltes sought child support and attorneys' fees in California.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#california #toward

2 months ago
A 50/50 blend of SCHD and JEPQ produces a ~5.7% blended yield, requiring roughly $737,000 to generate $42,000 annually.
JEPQ's 8.5% yield ties to volatile Nasdaq option premiums, not growing earnings, making it a poor sole holding over a 25-year retirement.
Hold JEPQ inside an IRA or Roth since its distributions are taxed as ordinary income, while SCHD's qualified dividends face lower rates.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
A 61-year-old aiming to replace roughly $3,500 a month in take-home income is targeting $42,000 a year from a portfolio. That is the classic pre-Social-Security bridge number: enough to cover housing, healthcare premiums, and basic living costs for a household that has already paid down the mortgage. Two ETFs get most of the attention for this job, and the reason is simple: one prioritizes dividend growth, the other prioritizes cash yield today.
#Retirement #advisor #prioritizes
2 months ago
Aug 4 (Reuters) - Defense supplier Leidos Holdings lifted the lower end of its 2026 profit and revenue forecasts, banking on strong demand for military technology amid heightened geopolitical tensions.
Shares of the company rose nearly 10% in morning trading.
Here are some details:
• Defense contractors have been benefiting as the U.S. government prioritizes military spending, with Trump proposing a record a record military budget of $1.5 trillion for fiscal 2027.
• Leidos reported increased demand for defense tech products, energy and air traffic management solutions as well as support for intelligence missions.
#record #here #Trump

2 months ago
For years, the electric vehicles (EVs) conversation has revolved around Tesla (TSLA). While Tesla captured headlines with rapid sales growth, industry-leading battery technology, and an ever-expanding lineup of EVs, legacy automakers like General Motors Company (GM) and Ford Motor Company (F) were seen trying hard to catch up. Today, as Tesla prioritizes its bold AI ambitions, its core automotive business is under pressure. Meanwhile, General Motors and Ford have quietly accelerated their own EV strategies. Both companies have invested billions in new platforms, expanded their EV portfolios, and are emerging as serious competitors in the U.S. EV market.
But only one of these legacy players is poised to win the EV race.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ******* ysis you won't find anywhere else.
With a market cap of $77.9 billion, General Motors is one of the world's largest automakers, with a portfolio spanning Chevrolet, GMC, Cadillac, and Buick. For years, GM was criticized for moving too cautiously in the EV business while Tesla stormed ahead. But management repeatedly argued that the company would scale its EV business only if it improved its long-term profitability. Its recent Q2 earnings show that the strategy is beginning to pay off.
Its EV portfolio now includes the Chevrolet Equinox EV, Blazer EV, Cadillac LYRIQ, and the GMC Hummer EV, giving the company a presence across both mass-market and luxury segments. The initial phases of the EV boom rewarded companies that launched vehicles fast into the market. But this phase of EVs is more about which company is actually making money by selling them. And that is precisely what GM is trying to do. Instead of quickly ramping up production, GM has spent the past year restructuring its EV operations to better match actual consumer demand.
#tesla #chevrolet #cadillac #years


2 months ago
Jaclyn Hill said that she became "addicted to being thin" after using a GLP-1 weight-loss medication
The beauty influencer shared her struggles with weight gain and online criticism after her former makeup brand's controversial lipstick launch in 2019
Hill credits strength training for helping her regain confidence and says she now prioritizes being strong over skinny
Jaclyn Hill opened up about her experience taking a GLP-1 and said that it led to her becoming "addicted to being thin." Reflecting on the experience, she credited strength training with helping her overcome struggles with body image.
The beauty influencer, 36, posted side-by-side pictures showing her progress in the gym to Instagram on Monday, Aug. 3 — and shared her turbulent journey with weight-loss medication in the caption.
#addicted


2 months ago
Investment management company Vulcan Value Partners recently released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. Vulcan Value Partners prioritizes long-term returns and lower risk over short-term performance. In the quarter, the Large Cap Composite (Net) returned 9.5%, the Small Cap Composite (Net) returned 13.3%, the Focus Composite (Net) returned 10.4%, the Focus Plus Composite (Net) returned 10.5%, and the All-Cap Composite (Net) returned 9.0%. The firm reported strong compounding across its strategies in Q2 2026. Management highlighted that their exceptional holdings remain deeply undervalued relative to "what is working" in the market, viewing this as an excellent opportunity for patient investors. In addition, please check the Firm's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Vulcan Value Partners highlighted CarMax, Inc. (NYSE:KMX), which it exited during the year. CarMax, Inc. (NYSE:KMX) is a used vehicle retailer headquartered in Richmond, Virginia. On July 29, 2026, CarMax, Inc. (NYSE:KMX) closed at $59.11 per share, reflecting a market capitalization of $8.39 billion. CarMax, Inc. (NYSE:KMX) posted a one-month return of 15.95%, while its shares gained 1.87% over the past 52 weeks.
Vulcan Value Partners stated the following regarding CarMax, Inc. (NYSE:KMX) in its Q2 2026 investor update:
"CarMax, Inc.'s (NYSE:KMX) stock performed well during the quarter. Fiscal 1Q 2027 (which ends in May) results were in line with management expectations and volumes continued to respond favorably to targeted investments in price. We are excited about the new CEO, Keith Barr, who was hired earlier this year. Our favorable impression of Keith dates back to his long successful tenure as CEO of InterContinental Hotels Group, another MVP company. With the stock price rising and our value stable, we took the opportunity to reallocate capital to more discounted names in the portfolio."
CarMax, Inc. (NYSE:KMX) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 51 hedge fund portfolios held CarMax, Inc. (NYSE:KMX) at the end of the first quarter, compared to 52 in the previous quarter. While we acknowledge the potential of CarMax, Inc. (NYSE:KMX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #value #partners #quarter


2 months ago
Investment management company Vulcan Value Partners recently released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. Vulcan Value Partners prioritizes long-term returns and lower risk over short-term performance. In the quarter, the Large Cap Composite (Net) returned 9.5%, the Small Cap Composite (Net) returned 13.3%, the Focus Composite (Net) returned 10.4%, the Focus Plus Composite (Net) returned 10.5%, and the All-Cap Composite (Net) returned 9.0%. The firm reported strong compounding across its strategies in Q2 2026. Management highlighted that their exceptional holdings remain deeply undervalued relative to "what is working" in the market, viewing this as an excellent opportunity for patient investors. In addition, please check the Firm's top five holdings to know its best picks in 2026.
Vulcan Value Partners' Q2 2026 investor letter highlighted ServiceNow, Inc. (NYSE:NOW), noting its inclusion in the firm's All-Cap strategy this quarter. ServiceNow, Inc. (NYSE:NOW) is a cloud-based software company that provides a platform for automating and managing digital workflows. On July 29, 2026, ServiceNow, Inc. (NYSE:NOW) closed at $115.76 per share, reflecting a market capitalization of $119.7 billion. ServiceNow, Inc. (NYSE:NOW) posted a one-month return of 4.56%, while its shares lost 44.33% over the past 52 weeks.
Vulcan Value Partners stated the following regarding ServiceNow, Inc. (NYSE:NOW) in its Q2 2026 investor update:
"We purchased three new positions during the quarter: Veeva Systems Inc., Equifax Inc., and ServiceNow, Inc. (NYSE:NOW). We believe that ServiceNow is also one of the best businesses in the world. ServiceNow automates workflows in large and complex enterprises. Their platform sits on top of all of an enterprise's data and systems of record. This very unique and enviable position allows ServiceNow to orchestrate and automate work across departments, enterprise wide. To use an **** ogy, if a large enterprise is an airport, and its multiple software applications are planes, ServiceNow is the control tower coordinating all of these planes/applications.
The company has grown from its roots in IT and now has very large businesses in sales and service, HR, finance, supply chain, operations, and security, as well as in industry specific verticals like Financial Services, Healthcare, and Government. ServiceNow grew revenue 21%, adjusted EBIT 28%, and free cash flow per share 33% in 2025. This growth at scale puts ServiceNow in elite company. Despite the strong performance, the stock is down approximately 40% year to date and 60% since the beginning of 2025. The company has been on our MVP list for over 5 years and has compounded its value at an incredible rate over that period. It has never been materially discounted until recently…." (Click here to read the full text)
#servicenow #composite #company #returned
2 months ago
Investment management company Vulcan Value Partners recently released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. Vulcan Value Partners prioritizes long-term returns and lower risk over short-term performance. In the quarter, the Large Cap Composite (Net) returned 9.5%, the Small Cap Composite (Net) returned 13.3%, the Focus Composite (Net) returned 10.4%, the Focus Plus Composite (Net) returned 10.5%, and the All-Cap Composite (Net) returned 9.0%. The firm reported strong compounding across its strategies in Q2 2026. Management highlighted that their exceptional holdings remain deeply undervalued relative to "what is working" in the market, viewing this as an excellent opportunity for patient investors. In addition, please check the Firm's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Vulcan Value Partners highlighted Veeva Systems Inc. (NYSE:VEEV), noting its inclusion in the firm's All-Cap strategy this quarter. Veeva Systems Inc. (NYSE:VEEV) is a technology company that provides a cloud-based software platform for the life sciences industry. On July 29, 2026, Veeva Systems Inc. (NYSE:VEEV) closed at $207.91 per share, reflecting a market capitalization of $33.77 billion. Veeva Systems Inc. (NYSE:VEEV) posted a one-month return of 7.87%, while its shares lost 26.84% over the past 52 weeks.
Vulcan Value Partners stated the following regarding Veeva Systems Inc. (NYSE:VEEV) in its Q2 2026 investor update:
"We purchased three new positions during the quarter: Veeva Systems Inc. (NYSE:VEEV), Equifax Inc., and ServiceNow Inc. Veeva is the dominant vertical market software system of record for the life sciences industry. Their customers rely on and trust Veeva to help them run their entire business. Everything from the development, regulatory approval, and manufacturing of drugs to the selling and marketing of drugs runs on Veeva's platform.
Veeva grew revenue and EBIT 16% and 24%, respectively in 2025 and it is off to a strong start in 2026. Despite these strong results, the stock is down close to 20% year to date through the end of June in sympathy with the rest of the application software sector.…." (Click here to read the full text)
#systems #veev #vulcan #quarter

2 months ago
Investment management company Vulcan Value Partners recently released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. Vulcan Value Partners prioritizes long-term returns and lower risk over short-term performance. In the quarter, the Large Cap Composite (Net) returned 9.5%, the Small Cap Composite (Net) returned 13.3%, the Focus Composite (Net) returned 10.4%, the Focus Plus Composite (Net) returned 10.5%, and the All-Cap Composite (Net) returned 9.0%. The firm reported strong compounding across its strategies in Q2 2026. Management highlighted that their exceptional holdings remain deeply undervalued relative to "what is working" in the market, viewing this as an excellent opportunity for patient investors. In addition, please check the Firm's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Vulcan Value Partners highlighted SAP SE (NYSE:SAP). Headquartered in Walldorf, Germany, SAP SE (NYSE:SAP) is a leading enterprise application and business solutions provider. On July 29, 2026, SAP SE (NYSE:SAP) closed at $185.99 per share, reflecting a market capitalization of $214.67 billion. SAP SE (NYSE:SAP) posted a one-month return of 14.39%, while its shares lost 35.13% over the past 52 weeks.
Vulcan Value Partners stated the following regarding SAP SE (NYSE:SAP) in its Q2 2026 investor update:
"SAP SE (NYSE:SAP) is the global leader in enterprise resource planning (ERP) software, which serves as the operating system for many of the world's largest companies. SAP's ERP solutions often have decades of embedded data, business processes, and software customizations. It is extremely rare for companies to switch ERP vendors due to the cost, time, and disruption risk that switching creates. SAP's Q1 results were very strong, with total revenue up 12% and EBIT up 16%. Cloud revenue grew 27% and their cloud backlog grew 25%. They also repurchased €2.6B of stock in the quarter and maintained full-year guidance. Our value continues to grow and we believe its shares remain significantly discounted. We took advantage of stock price volatility to add to our position in SAP during the quarter."
SAP SE (NYSE:SAP) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 33 hedge fund portfolios held SAP SE (NYSE:SAP) at the end of the first quarter, compared to 36 in the previous quarter. While we acknowledge the potential of SAP SE (NYSE:SAP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#letter

2 months ago
Investment management company Vulcan Value Partners recently released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. Vulcan Value Partners prioritizes long-term returns and lower risk over short-term performance. In the quarter, the Large Cap Composite (Net) returned 9.5%, the Small Cap Composite (Net) returned 13.3%, the Focus Composite (Net) returned 10.4%, the Focus Plus Composite (Net) returned 10.5%, and the All-Cap Composite (Net) returned 9.0%. The firm reported strong compounding across its strategies in Q2 2026. Management highlighted that their exceptional holdings remain deeply undervalued relative to "what is working" in the market, viewing this as an excellent opportunity for patient investors. In addition, please check the Firm's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Vulcan Value Partners highlighted PROG Holdings, Inc. (NYSE:PRG). Based in Draper, Utah, PROG Holdings, Inc. (NYSE:PRG) is a financial technology holding company. On July 29, 2026, PROG Holdings, Inc. (NYSE:PRG) closed at $42.78 per share, reflecting a market capitalization of $1.71 billion. PROG Holdings, Inc. (NYSE:PRG) posted a one-month return of -3.06%, while its shares gained 34.36% over the past 52 weeks.
Vulcan Value Partners stated the following regarding PROG Holdings, Inc. (NYSE:PRG) in its Q2 2026 investor update:
"PROG Holdings, Inc. (NYSE:PRG) provides lease-to-own financing to retailers and their non-prime customers. Its acquisition of Purchasing Power closed in the first quarter, which brings another attractive tool to the company's financing ecosystem. Additionally, the business, especially its buy now, pay later business, Four Technologies, has continued to execute well in a mixed environment."
PROG Holdings, Inc. (NYSE:PRG) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 28 hedge fund portfolios held PROG Holdings, Inc. (NYSE:PRG) at the end of the first quarter, compared to 34 in the previous quarter. While we acknowledge the potential of PROG Holdings, Inc. (NYSE:PRG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#prog #NYSE

2 months ago
Investment management company Vulcan Value Partners recently released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. Vulcan Value Partners prioritizes long-term returns and lower risk over short-term performance. In the quarter, the Large Cap Composite (Net) returned 9.5%, the Small Cap Composite (Net) returned 13.3%, the Focus Composite (Net) returned 10.4%, the Focus Plus Composite (Net) returned 10.5%, and the All-Cap Composite (Net) returned 9.0%. The firm reported strong compounding across its strategies in Q2 2026. Management highlighted that their exceptional holdings remain deeply undervalued relative to "what is working" in the market, viewing this as an excellent opportunity for patient investors. In addition, please check the Firm's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Vulcan Value Partners highlighted Badger Meter, Inc. (NYSE:BMI), a recent addition to the firm's small‑cap strategy. Badger Meter, Inc. (NYSE:BMI) is a US-based flow measurement, quality, control, and communication solutions company with a strong focus on Utility water smart metering solutions and software technologies. On July 29, 2026, Badger Meter, Inc. (NYSE:BMI) closed at $133.54 per share, reflecting a market capitalization of $3.87 billion. Badger Meter, Inc. (NYSE:BMI) posted a one-month return of -8.61%, while its shares lost 29.38% over the past 52 weeks.
Vulcan Value Partners stated the following regarding Badger Meter, Inc. (NYSE:BMI) in its Q2 2026 investor update:
"We purchased Badger Meter, Inc. (NYSE:BMI) and TPG Inc. during the quarter. Badger Meter is the only pure-play, publicly traded manufacturer of water meters in North America. More than 120 years old, the company now supports over 50,000 water utilities across the country. It is one of three players that have controlled roughly 85% of the North American water meter market for decades. Water meters are essential tools for water utilities in generating revenue. If meter readings are outdated or inaccurate, the utility risks losing revenue by underbilling end customers. Given the cost of failure is high, it comes as no surprise that 85% of Badger Meter's revenue is derived from replacement demand. In addition to stable unit volume growth over the long term, Badger Meter has and will continue to benefit from positive mix benefits tied to its advanced metering infrastructure and ***** ociated software offering, both of which carry higher margins. Despite slowing industry growth due to difficult post-Covid comparisons, we expect operating performance to improve as the company executes against its strong pipeline of opportunities over the coming years. Badger Meter has a long history of profitable growth, is supported by a net cash balance sheet, and is led by a management team compensated on metrics such as FCF conversion and returns on invested capital. After many years of watching the company's success from afar, we

2 months ago
For much of the past decade, the New York Jets operated with a familiar sense of urgency. Every offseason seemed to feature another move designed to accelerate the rebuild.
A high-profile free agent... A blockbuster trade... A veteran expected to solve a lingering problem overnight... The philosophy often centered on finding the missing piece that would finally push the franchise into contention.
Sometimes those moves generated optimism. Too often, they failed to produce lasting results. Now, however, the Jets appear to be taking a different approach, one that prioritizes patience, player development and sustainable roster building over short-term fixes.
Aaron Glenn inherited a roster with talent, but also one that needed a clearer long-term direction. Rather than relying on aging veterans to carry the franchise, the Jets have **** embled one of the NFL's more intriguing young cores.
Garrett Wilson has already established himself as one of the league's top receivers. First-round pick Omar Cooper Jr. and Kenyon Sadiq, bring additional offensive firepower, while last year's addition, Adonai Mitchell, enters the season with an opportunity to become a dependable complement to Wilson after flashing promise in 2025.
#franchise #term #aaron

2 months ago
VYM's high-yield strategy leads VIG 13% to 9% in 2026 year-to-date returns, but dividend growth ETFs have historically delivered stronger long-term total returns.
A high dividend yield often signals slower earnings growth or a declining share price, sacrificing future capital appreciation for current income.
Don't wait: the ***** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
Many income investors ***** ume that the highest-yielding dividend ETF is automatically the better investment. However, that has not necessarily been the case in 2026. While high-yield strategies continue to attract investors seeking immediate income, dividend growth ETFs have historically delivered stronger long-term total returns by investing in companies with growing earnings, rising dividends, and high-quality fundamentals.
Two of the most popular ETFs representing these approaches are the Vanguard Dividend Appreciation ETF (NYSEARCA: VIG) and the Vanguard High Dividend Yield ETF (NYSEARCA: VYM). VIG prioritizes companies with long records of increasing dividends, while VYM focuses on stocks offering above-average current yields. For investors deciding between dividend growth vs. high yield, understanding the trade-offs between these two strategies may be more important than simply chasing the highest payout.
#etfs #returns #income #vanguard


3 months ago
Under Deion Sanders, the Colorado Buffaloes have rebuilt their roster each offseason through the transfer portal. It's the new way to build a roster in college football, placing greater emphasis on current production than on internal development.
That new philosophy has completely changed the average age of college football rosters, with most now slightly older since the transfer portal's implementation. Considering Colorado added 40-plus transfers this offseason, are the Buffs an old or young team?
Unsurprisingly, Colorado is on the older side with an average age of 20.63, according to data from RotoWire. The Buffs are tied for the 16th oldest roster in the FBS. CU is also the fifth-oldest team in the Power Four and the third-oldest in the Big 12. The two older Big 12 teams are Oklahoma State and UCF.
Considering Colorado frequently uses the transfer portal, an average age close to 21 (normally a college senior) is not surprising.
Georgia is the youngest team in the country (19.81 average age), which is not surprising given their propensity to land highly ranked freshman recruiting classes. The oldest team is UTSA (21.02 average age), as a team that prioritizes development and has many players who have been with the program for 3-4 years.
#transfer

3 months ago
The unexpected termination of former Pittsburgh Steelers safety Ryan Clark from ESPN sent shockwaves across sports media. While many fans focused on the harshness of Clark being removed during a live broadcast, industry insiders are examining the cold financial reality driving the decision: a massive shift in how networks allocate talent payroll.
As traditional networks pivot toward digital giants and creator-led platforms, the sports media landscape has undergone a seismic transformation.
Former NFL linebacker Emmanuel Acho broke down the financial mechanics on his podcast, "Speakeasy," pointing out how multi-million-dollar mega-deals for star personalities inevitably squeeze out traditional ****** yst budgets.
"There's two mega stars at ESPN left doing daily shows: Stephen A. Smith and Pat McAfee," Acho explained. "They have to make room for Pat McAfee. 'The Pat McAfee Show' will get $60 million. But with that being said, you got to start to find that money. Well, if Ryan is making $2 or $3 million, bet, if I got to find $10 or $15 more for Pat, where can I find it? Hey, I can find a couple mil from Ryan."
Acho's co-hosts underscored that modern broadcasting increasingly prioritizes built-in digital reach and viral engagement over traditional ex-player credentials. With networks pouring unprecedented funds into external licensing deals for giant independent brands, legacy studio roles face intense budget pressure.
#mcafee #million #espn


3 months ago
Comparing the iShares Core MSCI Total International Stock ETF (NASDAQ:IXUS) and the State Street SPDR MSCI ACWI Climate Paris Aligned ETF (NASDAQ:NZAC) comes down to a choice between ultra-low-cost, ex-U.S. diversification and a more targeted global strategy built around climate-aligned corporate performance.
While both funds offer global equity exposure, they differ fundamentally in geographic and thematic construction. IXUS prioritizes low-cost coverage of developed and emerging markets outside the U.S., while NZAC layers in a climate-focused screen that -- notably -- still includes domestic U.S. equities.
Metric
IXUS
NZAC
#nzac

3 months ago
Hannah Waddingham admitted to feeling "mom guilt" after taking a Game of Thrones role weeks after giving birth
She said she feels it when she's away from her daughter, Kitty, on the set of projects and during press runs
However, the actress said that she also prioritizes her daughter by honoring her in meaningful ways, like on the red carpet
Hannah Waddingham admits that she experiences "mom guilt."
The Ride or Die star, 51, recalled in an interview with The Guardian published on Saturday, July 18, one instance of experiencing that feeling while filming a memorable Game of Thrones scene just weeks after she gave birth to her daughter, Kitty, who is now 12.


3 months ago
From Red Raiders to Redbirds, the St. Louis Cardinals have drafted 1B Caden Ferraro with their final pick on day 1 of the 2026 Amateur draft. Ferraro slashed .374/.481/.604 this year for Texas Tech with 8 HR. Obviously, as a corner infielder, all of the pressure is on the bat to carry him to the big leagues. Ferraro will have the chance to compete with Jack Gurevitch and Josh Kross as the potential 1B of the future in the Gateway to the West!
Few college hitters combine the ability to execute good swing decisions, make consistent contact and generate premium exit velocities as well as Ferraro. A left-handed hitter, he has flipped his profile from power-over-hit at Blinn to hit-over-power with the Red Raiders. He owns plus raw pop but prioritizes drilling line drives from gap to gap rather than trying to crush ***** to his pull side.
Ferraro is a well-below-average runner who’s conservative on the bases. He has spent most of this spring at DH with sporadic starts in right field, where he has limited range. He was a substandard defender at first base in junior college, though he does have average arm strength and displayed an upper-80s fastball when he pitched as a freshman.
Grades:
Hit: 55

3 months ago
High-yield municipal bonds combine higher income with tax advantages: Their federally tax-exempt income can produce tax-equivalent yields that rival many taxable high-yield corporate bond funds.
HYMU and HYD take different approaches: HYMU emphasizes active management and higher yields, while HYD prioritizes somewhat stronger credit quality, lower duration, and passive index tracking.
Pay attention to credit quality and duration, not just yield: Lower-rated issuers increase credit risk, while longer-duration portfolios are more sensitive to interest rate changes, making both important considerations before investing.
Don't wait: the ***** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
I'm generally not a fan of high-yield corporate bond ETFs for retirees, and it has very little to do with credit risk. My bigger concern is taxes. Unless you hold them inside a tax-advantaged account such as a Roth IRA, the interest they generate is typically taxed as ordinary income at the federal level and, in many cases, at the state and local levels as well.