3 days ago
Three decades ago, the advent and proliferation of the internet lit a fire under Wall Street's major indexes. Today, the artificial intelligence (AI) infrastructure build-out is stoking the same enthusiasm and fueling a multitrillion-dollar addressable opportunity.
Though dozens of tech-driven companies are benefiting from the AI revolution, Nvidia (NASDAQ:NVDA), Palantir Technologies (NASDAQ:PLTR), and Google parent Alphabet (NASDAQ:GOOGL)(NASDAQ:GOOG) are at the forefront of this game-changing technology.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia's graphics processing units hold a virtual monopoly in AI-accelerated data centers, making it one of the most widely held stocks among retail investors.
Image source: Getty Images.
#NVIDIA #three #nvda


18 days ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ

19 days ago
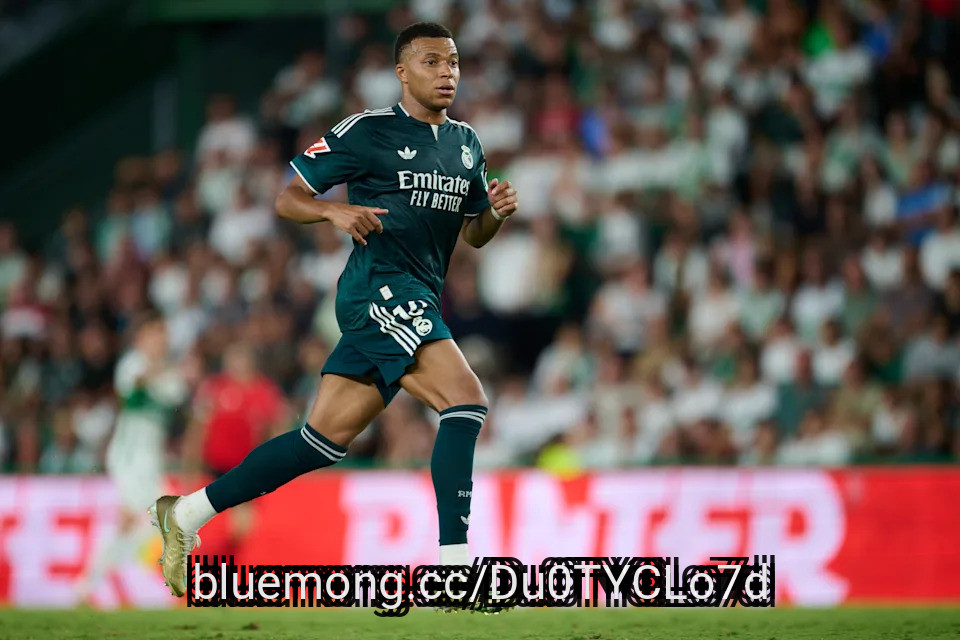
On Holding's (ONON) entry into the soccer category through a partnership with World Cup champion Kylian Mbappé marks the latest step for the company as it aims to tread its own path as a premium global sports brand.
The Swiss sportswear company signed Mbappé, whose contract with Nike (NKE) expired this past summer after seven years, beating out competitors such as Adidas (ADS.DE) and Under Armor (UA) for a partnership with the soccer superstar.
The company did not disclose the size of the deal. As part of the announcement, soccer pundit Thierry Henry was named the company's director of football, after working with the brand since 2025.
"The announcement is a direct challenge to Nike and Adidas (which have a near-monopoly in the category)," Evercore ISI ******* yst Michael Binetti wrote in a note to clients. "We expect a major investment in a large global category will be a positive near-term catalyst for the stock."
On stock rose slightly after the deal was announced, but shares remain down 40% year to date amid a challenging retail environment for sneaker stocks. Nike's stock fell 2% on Friday.
#category #company #partnership
22 days ago
ASML Holding N.V. (NASDAQ:ASML) is examining ways to produce more than 110 EUV lithography systems in 2028, according to JPMorgan ***** ysts following a meeting with CFO Roger Dassen. The company is already nearly sold out for 2027 and expects to produce at least 80 EUV systems that year, meaning output above 110 in 2028 would represent at least a 37.5% increase from the 2027 level. JPMorgan said the main constraint has shifted toward ***** embly speed rather than the availability of critical components, suggesting ASML believes additional capacity can be unlocked through manufacturing and ***** embly improvements.
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company

27 days ago
Mexico's government is slashing financial ******* istance for the state energy major by as much as 70% despite Pemex's continued struggle to pay down debt and boost production. The decision rests on expectations that the company will benefit from the oil and gas price rally spurred by the U.S. and Israeli war against Iran.
Per a Bloomberg report from this week, the government of Mexico sees Pemex posting a rare cash surplus of some 95 billion pesos, or around $5.63 billion, as a result of the oil price rally. Based on those expectations, the Scheinbaum government stipulated financial help of just 81 billion pesos for the company in next year's budget, equivalent to some $4.8 billion. This was down by 70% from this year.
"We said that by 2027, support for Pemex would be very limited, and that's indeed the case," President Sheinbaum told media this week. "Pemex now receives very little support from the Mexican government, and its own finances will sustain its development."
Mexico's energy major is the most indebted company in the world, with a load of some $105 billion as of mid-2025, of which some $20 billion is in unpaid bills to suppliers. Since then, the company has managed to reduce the debt pile to some $79 billion as of the end of the first quarter of this year. The company said in a news release at the time that this was the lowest its debt has been since 2014.
Meanwhile, however, boosting refining output has turned out to be a challenge, and issues with crude quality—including high water content—have alienated key buyers over the past couple of years. The previous administration of Mexico focused on supporting the company by turning it back into a monopoly on the Mexican energy market. The Scheinbaum government, on the other hand, moved to open up the Mexican oil industry to other players as well, launching a new contract framework for joint ventures, the so-called mixed contracts. In mixed development allocations, Pemex can enter into an agreement with one or more private firms.
#PEMEX #government #scheinbaum #since

1 month ago
SpaceX must pull off rocket reusability if the company is to reach a stratospheric market valuation in the not-too-distant future.
"A successful investment case in ****** eX at the current $2 trillion enterprise value rests almost entirely on a single admittedly massive engineering bottleneck: Starship reusability (i.e. 20-50 flights per Starship with relatively inexpensive and quick refurbishment/redeployment)," Pivotal Research Group ****** yst Jeffrey Wlodarczak wrote in a note on Tuesday. "If Elon Musk can solve for this fundamental issue it potentially drives down the cost of launches to ****** e to the equivalent of terrestrial freight opening up an unarguably massive opportunity."
Wlodarczak initiated coverage of ****** eX with a Buy rating and $220 price target.
That massive opportunity, Wlodarczak said, includes Starlink taking a material share of the wireless industry and serving as a ****** e monopoly, with others having to pay ****** eX for entry.
"In the end, investors are debating xAI, Colossus, and Starlink take-rates," Wlodarczak added. "Those matter only after Starship works. Our $220 target is a call on reuse 20–50 flights per vehicle, cheap refurb, fast turnaround. If that is solved, the rest of the model can happen. If it is not, SPCX is a different and much smaller company."
#SpaceX


1 month ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ***** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Danaher Corporation (NYSE:DHR). Danaher Corporation (NYSE:DHR) is a healthcare and life science tools company operating through Biotechnology, Life Sciences, and Diagnostics segments. On September 02, 2026, Danaher Corporation (NYSE:DHR) closed at $209.91 per share. Over the past month, Danaher Corporation (NYSE:DHR) returned 4.97%, and its shares gained 5.47% over the past 52 weeks. Danaher Corporation (NYSE:DHR) has a market capitalization of $147.56 billion.
Eagle Capital Management stated the following regarding Danaher Corporation (NYSE:DHR) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher Corporation (NYSE:DHR), S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ***** ets, network effects, or regulatory moats. Danaher is a leading life sciences company, selling a broad mix of consumables and tooling for biological R&D and drug production.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy nor

1 month ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Mastercard Incorporated (NYSE:MA). Mastercard Incorporated (NYSE:MA) is a leading global payment technology company that provides transaction processing and other payment-related products and services. On September 02, 2026, Mastercard Incorporated (NYSE:MA) closed at $588.14 per share. Over the past month, Mastercard Incorporated (NYSE:MA) returned 2.12% while its shares lost 1.26% over the past 52 weeks. Mastercard Incorporated (NYSE:MA) has a market capitalization of $515.22 billion.
Eagle Capital Management stated the following regarding Mastercard Incorporated (NYSE:MA) in its Q2 2026 investor letter:
High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard Incorporated (NYSE:MA), A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. Mastercard operates as part of a global duopoly of payment rails and standards.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards m
1 month ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Arthur J. Gallagher & Co. (NYSE:AJG). Arthur J. Gallagher & Co. (NYSE:AJG) provides insurance and reinsurance brokerage, consulting, and third-party property/casualty claims settlement and administration services to entities and individuals. On September 02, 2026, Arthur J. Gallagher & Co. (NYSE:AJG) closed at $264.46 per share. Over the past month, Arthur J. Gallagher & Co. (NYSE:AJG) was up 5.05%, while its shares lost 11.91% over the past 52 weeks. Arthur J. Gallagher & Co. (NYSE:AJG) has a market capitalization of $67.78 billion.
Eagle Capital Management stated the following regarding Arthur J. Gallagher & Co. (NYSE:AJG) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. A.J. Gallagher is a commercial insurance broker that continues to gain share in a consolidating industry.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. Howev

1 month ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment **** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted S&P Global Inc. (NYSE:SPGI). S&P Global Inc. is a financial services and **** ytics company that provides benchmarks, data, **** ytics, and workflow solutions in the global capital, energy, commodity, and automotive markets. On September 02, 2026, S&P Global Inc. closed at $431.71 per share, reflecting a market capitalization of $127.27 billion. S&P Global Inc. posted a one‑month return of 6.40%, while its shares lost 14.62% over the past 52 weeks.
Eagle Capital Management stated the following regarding S&P Global Inc. (NYSE:SPGI) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global Inc. (NYSE:SPGI), Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly **** ets, network effects, or regulatory moats. S&P Global owns the S&P ratings franchise, S&P Indexes, Platts, and Capital IQ.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy normalize back towards mid businesses should demonstrate significant outperfor
1 month ago
A federal judge says Google runs a monopoly — but it looks like the feds will only slap the company's wrist.
We saw the same thing happen last year, and we are seeing the same trend play out all over Big Tech.
The US government failed to write new rules for Big Tech. So it tried court cases. Those are failing, too.
Last year, a federal judge said Google was illegally monopolizing some ad markets.
This week, we learned about the punishment Google is likely to receive for its sins: Not much at all.
#last #same #monopoly
1 month ago
The Justice Department has spent years attempting to break up Google's gargantuan advertising business across two separate antitrust lawsuits: one filed in 2020 focused on Google's dominance in search, and a second filed in 2023 that specifically targeted Google's ad-technology business. Both cases argued that the search giant's grip on the digital ad economy represents an illegal monopoly.
Courts have largely sided with the government in both cases. In 2024, a court determined that Google's search business, including its exceedingly lucrative search-ad operation, was an illegal monopoly, claiming that the tech giant had "exercised its monopoly power" to dominate the search industry and search ads. Last April, a second court case — this one focused specifically on Google's ad-tech business — also came to the same conclusion.
Following the 2024 ruling, Justice Department officials suggested a variety of ways Google's search business could be broken up, including divesting its Chrome browser and Android operating system. But in September 2025, the judge overseeing that case, Amit Mehta, rejected those divestiture requests, ruling that Google could keep both Chrome and Android. He did order the company to end exclusive default-placement deals and share certain search data with competitors (remedies that Google is currently appealing).
That same pattern held this week. In a ruling handed down on Wednesday, federal judge Leonie M. Brinkema of the Eastern District of Virginia, who oversaw the ad-tech case, said that Google would be able to keep its advertising business. Instead of selling it, the search giant will instead be required to adjust its business practices to favor competitors, Brinkema said. The New York Times notes that the judge's ruling "did not provide specifics" as to how Google should go about doing that.
Brinkema's full written ruling will remain under seal for 14 days to allow those involved to issue necessary redactions. Her finding that Google had acted illegally in maintaining its ad-tech business dates back to April of last year; this week's decision addressed only the remedy.
#ruling #Tech

1 month ago
A federal judge on Wednesday ordered Google to retool the system powering its monopoly in digital advertising, sparing the company from a wrenching breakup sought by the U.S. government.
The initial two-page decision by U.S. District Judge Leonie Brinkema in Virginia marks the second time in a year that Google has received a reprieve from a Justice Department proposal to dismantle its internet empire. Meanwhile, what courts have described as the company's anti-competitive practices have enriched Google's corporate parent, Alphabet Inc., which has a market value of $4.11 trillion.
The judge's full opinion, which includes the specific remedies, will remain under seal for 14 days to allow the parties to review it and propose any necessary redactions.
"We're very pleased the Court rejected the DOJ's proposal to break apart tools that help small businesses reach new customers and grow," said Lee-Anne Mulholland, Google's vice president for regulatory affairs.
After a judge declared Google's ubiquitous search engine as an illegal monopoly in 2024, the Justice Department pushed for a penalty that would have required the company to sell its popular Chrome web browser. But it was rebuffed last September by another federal judge overseeing that case.
#district

1 month ago
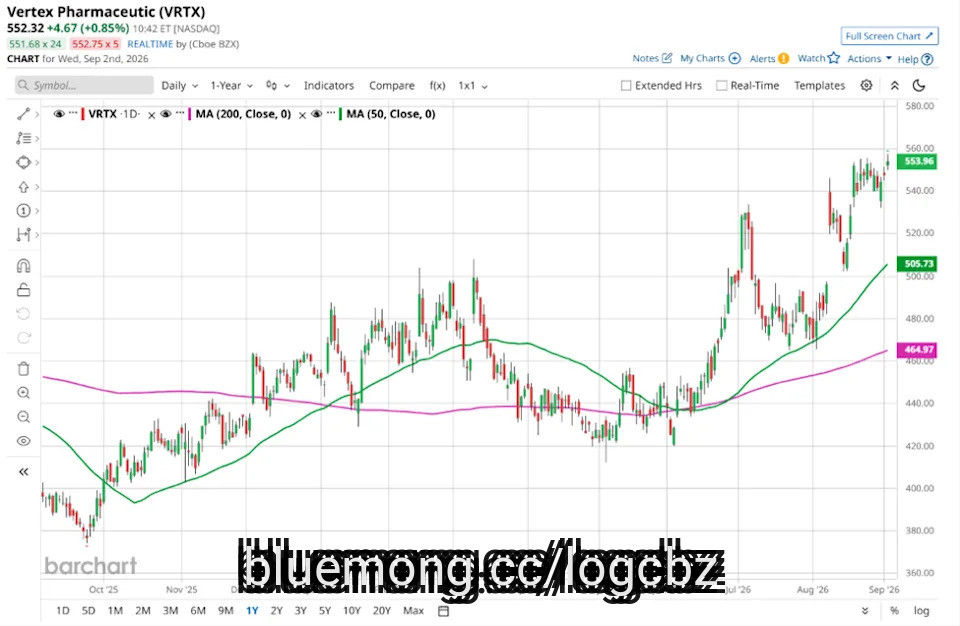
Boston, Massachusetts-based Vertex Pharmaceuticals Incorporated (VRTX) develops and commercializes therapies for treating cystic fibrosis (CF). Valued at $139 billion by market cap, the company invests in scientific innovation to create transformative medicines for people with serious diseases.
Companies worth $10 billion or more are generally described as "large-cap stocks," and VRTX perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the biotechnology industry. VRTX derives its primary competitive strength from its global monopoly in CF treatments, anchored by flagship blockbusters like Trikafta/Katori which generate robust cash flow to fuel its high-impact clinical pipeline.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#vrtx #massachusetts

1 month ago
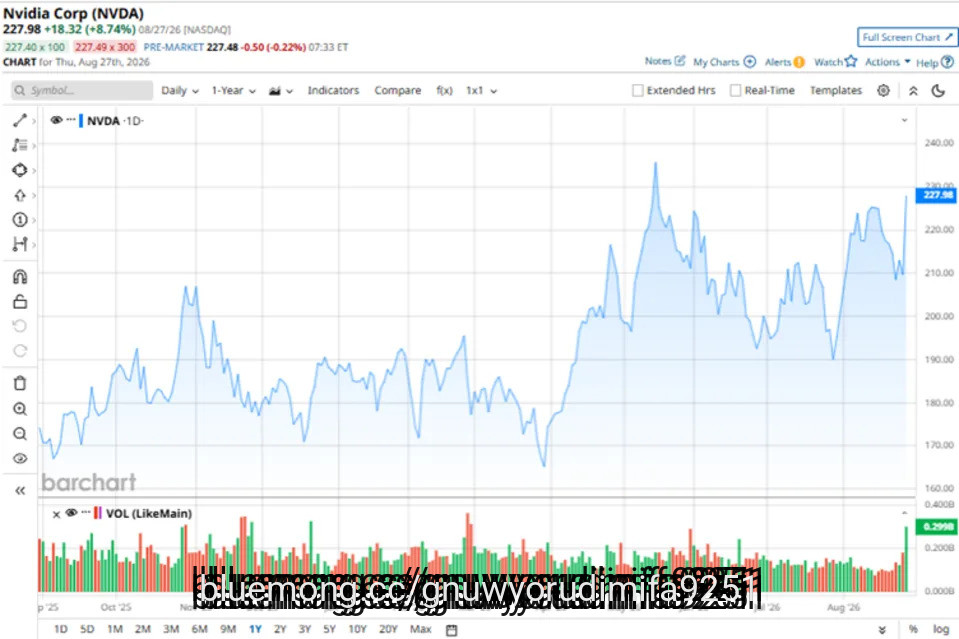
Nvidia (NVDA) reported blockbuster second-quarter fiscal 2027 results on Aug. 26, led by a solid surge in data-center revenue, which climbed by a whopping 117% year-over-year (YOY) to $89 billion. With the data-center business making up more than 90% of its top line, Nvidia has capitalized on the fact that more companies need large GPU clusters.
While the semiconductor industry leader faces "threats" that its near-monopoly on advanced artificial intelligence (AI) chips may be coming to an end, Nvidia remains the primary beneficiary of the AI boom. The company is also reportedly set to buy open-source AI platform Hugging Face for $12.9 billion, aligning with CEO Jensen Huang's strategy of building the AI world on the American stack.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#fans #hour #data #year
1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) as a notable contributor to performance. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's leading contract chip manufacturer, producing advanced semiconductors for major global technology companies. On August 31, 2026, Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) closed at $415.32 per share. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) fell 0.44% over the past month, while its shares gained 81.85% over the past 52 weeks. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) has a market capitalization of $1.97 Trillion.
Baron Fifth Avenue Growth Fund stated the following regarding Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) in its Q2 2026 investor letter:
"Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's largest contract chipmaker and the leading manufacturer of advanced logic semiconductors used in modern AI accelerators. Shares rose 41.6% during the quarter as the company continues to report stellar financial results underpinned by AI demand with revenue growth of 35% year-on-year and EPS growth of 58%, with 66% gross margins and 58% operating margins. High-performance computing now represents the majority of TSMC's business. AI demand is consuming so much leading-edge capacity that smartphone and PC production is increasingly shifting to older technology nodes, reversing a dynamic that defined the foundry industry for much of the past decade. Management also raised its full-year outlook and increased capital spending to support demand that remains well above available supply. We retain long term conviction in TSMC and view its leading-edge manufacturing monopoly, pricing power, and technology roadmap as durable advantages that support a long duration of growth."
#baron
1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) as a notable contributor to performance. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's leading contract chip manufacturer, producing advanced semiconductors for major global technology companies. On August 31, 2026, Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) closed at $415.32 per share. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) fell 0.44% over the past month, while its shares gained 81.85% over the past 52 weeks. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) has a market capitalization of $1.97 Trillion.
Baron Fifth Avenue Growth Fund stated the following regarding Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) in its Q2 2026 investor letter:
"Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's largest contract chipmaker and the leading manufacturer of advanced logic semiconductors used in modern AI accelerators. Shares rose 41.6% during the quarter as the company continues to report stellar financial results underpinned by AI demand with revenue growth of 35% year-on-year and EPS growth of 58%, with 66% gross margins and 58% operating margins. High-performance computing now represents the majority of TSMC's business. AI demand is consuming so much leading-edge capacity that smartphone and PC production is increasingly shifting to older technology nodes, reversing a dynamic that defined the foundry industry for much of the past decade. Management also raised its full-year outlook and increased capital spending to support demand that remains well above available supply. We retain long term conviction in TSMC and view its leading-edge manufacturing monopoly, pricing power, and technology roadmap as durable advantages that support a long duration of growth."
#company #fund #

1 month ago
The PGA Tour finally pulled the trigger on a massive overhaul for its season finale. After years of sticking to the same starting-strokes format at East Lake, the circuit is shifting to a two-week match play event. We're seeing a complete reinvention of how the season ends, not just a tweak. The changes kick in for the 2028 season. Fans who love the drama of head-to-head golf now have a reason to tune in for the final two weeks of the year.
The new structure breaks the final event into two distinct parts. The first week features a group stage, according to Golf Monthly. Thirty-two players will split into eight groups of four. They will play three rounds of stroke play within their groups. The top two from each group move on. Week two shifts to pure match play. This format hasn't been seen on the PGA Tour since the 2023 WGC-Dell Technologies Match Play. Brian Rolapp, the PGA Tour CEO, addressed the media ahead of the current Tour Championship to clarify the path forward. He noted that the current model is just the start of a broader evolution.
The goal is to create more excitement and higher stakes. The season-long points list will still determine who qualifies. The top 32 on that list earn their spot in the finale. But the way they compete will be totally different. The top 90 players on the points list will still retain their cards, but only the elite 32 get to fight for the trophy in this new way.
For years, East Lake Golf Club in Atlanta has been the only home for the Tour Championship. That ends in 2028. The tournament will now rotate between prestigious venues. The Tour has promised to include courses that the modern circuit hasn't traditionally been able to feature. This opens up the door for historic layouts to host the finale. Rolapp confirmed that conversations are already underway to secure these new locations. He told reporters that East Lake is still a strong option for the future, but it won't hold a monopoly anymore.
East Lake remains among the options being considered for upcoming Tour Championship events. This flexibility allows the Tour to bring the championship to different markets and fan bases. It also adds a layer of novelty that the starting-strokes format lacked. The rotation ensures that the final event feels like a grand tour rather than a local fixture.
#east #play #season #golf

1 month ago
The reigning Super Bowl champion Seattle Seahawks are not content to rest on their laurels.
We know this because they have the second-most starters returning from a championship team in the last 15 years. It would be natural for basically the same group of players and coaches to have the same exact ambition: Continuing what they started with February's Lombardi Trophy victory and going for the legendary repeat.
We also know the Seahawks are not content to sit back based on the money they've thrown around this offseason, and even dating back to last summer. Seattle has spent so much money on key members of its current championship core for the foreseeable future that you almost wonder whether the currency they're using is actually Monopoly money. Where does it keep coming from? Oh right, the Seahawks have the Park Place and Boardwalk squares, as well as all the railroads.
With the Thursday news that the Seahawks had extended All-Pro defensive lineman Leonard Williams to a three-year, $90 million contract (with $56 million guaranteed), their plan for the rest of the decade is in full focus. The Seahawks clearly believe they can wring out another championship or two with the current make-up of their team (they are probably correct), because why else would they throw out $634 million in new contracts over the last calendar year? For the fun of it? C'mon now. By total guaranteed money, the recent extensions awarded over just the last several weeks to Williams, star cornerback Devon Witherspoon, and arguably the NFL's best receiver in Jaxon Smith-Njigba come out to over $273 million.
That's, uh, a lot of cheddar. Let's put it this way: If the Seahawks didn't think they could wrack up a dynasty of sorts, they wouldn't be handing out proverbial blank checks like this all at once. (Note: It would also be a lot harder to spend this money if quarterback Sam Darnold wasn't on such a team-friendly contract. But here we are!)
#seahawks #money #championship #rest


1 month ago
Interested in Comfort Systems USA, Inc.? Here are five stocks we like better.
Comfort Systems USA, Piper Sandler, and FTAI Aviation each delivered strong Q2 2026 earnings despite operating outside the tech sector.
Comfort Systems posted more than 50% revenue growth and a record $14.1 billion backlog, benefiting from AI infrastructure spending.
Piper Sandler and FTAI Aviation both beat expectations, with ***** ysts projecting substantial upside of 27% and 60%, respectively, for their shares.
Q2 2026 was an impressive quarter for many companies, with wave after wave of earnings wins across the S&P 500 in recent weeks. Headlines have focused on AI stock wins, but these companies do not have a monopoly on noteworthy earnings. A number of firms outside the tech sector delivered the kinds of results investors seek out, including accelerating revenue growth, margin expansion, and guidance increases.
#earnings #ftai #aviation

1 month ago
Nvidia risks a 20% drop to $165 if it misses earnings, with virtually no margin for error built into its current stock price.
Customers Microsoft and Meta are building competing AI chips, threatening the near-monopoly behind Nvidia's $91 billion quarterly revenue forecast.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
How low can a stock go if it misses earnings? Well, look at its 52-week low. If that happens to Nvidia (NASDAQ: NVDA), the stock would drop 20% to $165, where it was in late March. That was when AI suddenly fell out of vogue amid worries it wasn't the greatest invention of all time.
Oracle(NYSE: ORCL) missed earnings, dropping more than half, but it is considered the weakest of the large tech companies. IBM (NYSE: IBM) fell 20% on a miss, but it is a third-tier company. Before Meta (NASDAQ: META) posted poor results, it fell 20% and is down over 25% for the year.
#NVIDIA #Microsoft #NYSE

2 months ago
MU trades at just 6x forward earnings with $100 billion in contracted AI-memory revenue locked in through 2030, while 40 ***** ysts rate it a buy with zero sells.
Unlike WDC and STX, which have zero HBM exposure, Micron's Core Data Center unit posted 87% gross margins last quarter, a figure that neither competitor comes close to matching.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Micron Technology didn't make the cut. Grab the names FREE today.
Micron Technology (NASDAQ:MU) stands out as the cleanest AI-memory exposure for long-horizon portfolios right now, and the math is not close. At $966.78 with a forward P/E of around 13, investors are being handed a hyperscaler-adjacent monopoly-like memory franchise at a value multiple. This is a rare valuation window on a company whose earnings power just tripled in a single fiscal year.
Micron's trailing P/E sits at 21, but the forward multiple is where the thesis crystallizes: 6. That reflects Q4 FY2026 guidance of $50 billion in revenue and $31 non-GAAP EPS, with gross margins of roughly 86%. Wall Street's average price target of $1,501.98 implies substantial upside, and the ***** yst tally reads nine Strong Buy ratings, 31 Buy ratings, five hold ratings and zero Sell ratings.
#ratings #exposure


2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ******* umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML) provides lithography solutions for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems. On August 18, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,802.98 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was 0.06% and its shares gained 140.56% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $682.12 billion.
Eagle Capital Management stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"Half of our capital here is invested in TSMC and ASML Holding N.V. (NASDAQ:ASML), two of the most dominant businesses in the semiconductor supply chain. The other half is invested across the three major hyperscalers. We ascribe a portion of the value of each of these three companies to their cloud business and the balance to the remainder of the company; i.e., 60% of the value of Amazon is from AWS and 40% is from retail.
TSMC and ASML are two of the best businesses in the semiconductor industry. ASML has a monopoly in extreme ultraviolet lithography ("EUV"), which is required for leading-edge semiconductor manufacturing. Both companies are well positioned over the next 5-10 years to participate in the sector's secular growth while maintaining their competitive positions. That said, they will face pressures when the next downturn comes.
#holding #capital #Growth

2 months ago
On August 18, Comcast Corp. (NASDAQ:CMCSA) announced Xfinity Shield, a new home security platform meant to make its broadband service harder to leave. The rollout matters because Comcast has spent much of 2026 managing broadband subscriber losses, and a bundled security product gives the company something fiber and wireless rivals cannot easily replicate. Xfinity Shield combines Wi-Fi-based protection, cybersecurity, and family controls inside the existing Xfinity app, folding a new revenue lever onto a business that badly needs one.
Xfinity Shield ships free to every Xfinity Internet customer, with a $15-a-month tier adding an indoor camera, door and window sensors, cloud video storage, and 24/7 urgent response. Comcast product chief Fraser Stirling described the strategy plainly, saying the company is "lowering the barrier of entry to the idea of a total security product under Xfinity Shield." The timing lines up with how connected the average home has become. Comcast says the typical Xfinity customer now runs 36 devices on their home Wi-Fi, and its network filters an average of 30 million threats every day, numbers that make a bundled security layer feel less like an add-on and more like a necessity.
That stickiness push sits on top of a business that already throws off serious cash. Comcast generated nearly $21.9 billion in free cash flow in FY 2025 and turned $123.7 billion in revenue into roughly $20.0 billion of net income, a 16.2% margin. Execution has held up too. Peacock turned profitable for the first time, wireless lines crossed a major milestone, and Comcast beat earnings estimates in its most recent quarter, evidence that the company can still deliver even while restructuring around it.
None of that changes the core problem Xfinity Shield is designed to fix: broadband subscribers are still leaving. Comcast faces intensifying competition from fiber providers and 5G fixed wireless rivals, a fight that keeps chipping away at what was once a near-monopoly business. The balance sheet reflects a company carrying real leverage, with a debt-to-equity ratio of 1.1x and a current ratio of 0.9x, meaning short-term liabilities outweigh short-term ***** ets as of the December 2025 balance sheet.
Comcast also paused its share buyback program ahead of a planned NBCUniversal spinoff, a separation that adds years of complexity for investors trying to value the pieces separately. The company took an $8.6 billion noncash impairment tied to Sky, and rising costs for sports broadcasting rights, including the NFL and NBA, continue to pressure the media segment. There is also an uncomfortable irony in Comcast selling a cybersecurity product months after agreeing to a $117.5 million settlement over a prior Xfinity data breach, a reminder that the company's own network security has already been tested and found wanting once.
#home #broadband

2 months ago
On August 18, Comcast Corp. (NASDAQ:CMCSA) announced Xfinity Shield, a new home security platform meant to make its broadband service harder to leave. The rollout matters because Comcast has spent much of 2026 managing broadband subscriber losses, and a bundled security product gives the company something fiber and wireless rivals cannot easily replicate. Xfinity Shield combines Wi-Fi-based protection, cybersecurity, and family controls inside the existing Xfinity app, folding a new revenue lever onto a business that badly needs one.
Xfinity Shield ships free to every Xfinity Internet customer, with a $15-a-month tier adding an indoor camera, door and window sensors, cloud video storage, and 24/7 urgent response. Comcast product chief Fraser Stirling described the strategy plainly, saying the company is "lowering the barrier of entry to the idea of a total security product under Xfinity Shield." The timing lines up with how connected the average home has become. Comcast says the typical Xfinity customer now runs 36 devices on their home Wi-Fi, and its network filters an average of 30 million threats every day, numbers that make a bundled security layer feel less like an add-on and more like a necessity.
That stickiness push sits on top of a business that already throws off serious cash. Comcast generated nearly $21.9 billion in free cash flow in FY 2025 and turned $123.7 billion in revenue into roughly $20.0 billion of net income, a 16.2% margin. Execution has held up too. Peacock turned profitable for the first time, wireless lines crossed a major milestone, and Comcast beat earnings estimates in its most recent quarter, evidence that the company can still deliver even while restructuring around it.
None of that changes the core problem Xfinity Shield is designed to fix: broadband subscribers are still leaving. Comcast faces intensifying competition from fiber providers and 5G fixed wireless rivals, a fight that keeps chipping away at what was once a near-monopoly business. The balance sheet reflects a company carrying real leverage, with a debt-to-equity ratio of 1.1x and a current ratio of 0.9x, meaning short-term liabilities outweigh short-term ****** ets as of the December 2025 balance sheet.
Comcast also paused its share buyback program ahead of a planned NBCUniversal spinoff, a separation that adds years of complexity for investors trying to value the pieces separately. The company took an $8.6 billion noncash impairment tied to Sky, and rising costs for sports broadcasting rights, including the NFL and NBA, continue to pressure the media segment. There is also an uncomfortable irony in Comcast selling a cybersecurity product months after agreeing to a $117.5 million settlement over a prior Xfinity data breach, a reminder that the company's own network security has already been tested and found wanting once.
#company

2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment **** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML) provides lithography solutions for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems. On August 18, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,802.98 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was 0.06% and its shares gained 140.56% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $682.12 billion.
Eagle Capital Management stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"Half of our capital here is invested in TSMC and ASML Holding N.V. (NASDAQ:ASML), two of the most dominant businesses in the semiconductor supply chain. The other half is invested across the three major hyperscalers. We ascribe a portion of the value of each of these three companies to their cloud business and the balance to the remainder of the company; i.e., 60% of the value of Amazon is from AWS and 40% is from retail.
TSMC and ASML are two of the best businesses in the semiconductor industry. ASML has a monopoly in extreme ultraviolet lithography ("EUV"), which is required for leading-edge semiconductor manufacturing. Both companies are well positioned over the next 5-10 years to participate in the sector's secular growth while maintaining their competitive positions. That said, they will face pressures when the next downturn comes.
#asml #NASDAQ #management #letter

2 months ago
Brown Advisory, an investment management company, released its "Brown Advisory Global Leaders Strategy" for the second quarter of 2026 investor letter. A copy of the letter can be downloaded here. Brown Advisory's Global Leaders Strategy delivered a net return of 4.6% in the second quarter of 2026, underperforming its benchmark, the MSCI ACWI Net Index, which returned 14.9%. The relative weakness was driven mainly by underexposure to semiconductors and technology hardware, while software, cloud services, and financial holdings also weighed on performance. The strategy benefited from holdings in areas tied to AI infrastructure, with semiconductor exposure and AI-related investments gaining from strong demand. Looking ahead, Brown Advisory sees an attractive environment for active stock-picking, with its ready-to-buy list at its highest level since the COVID-19 period and an estimated 12%-13% average five-year base-case IRR, while maintaining a focus on quality, valuation discipline, and long-term cash-flow generation. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Brown Advisory Global Leaders Strategy Fund highlighted stocks like ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML) develops and manufactures advanced lithography systems used by semiconductor manufacturers to produce cutting-edge chips. The one-month return of ASML Holding N.V. (NASDAQ:ASML) was 0.87% while its shares traded between $716.20 and $1999.96 over the last 52 weeks. On August 7, 2026, ASML Holding N.V. (NASDAQ:ASML) stock closed at approximately $1704.37 per share, with a market capitalization of about $668.71 billion.
Brown Advisory Global Leaders Strategy Fund stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
ASML Holding N.V. (NASDAQ:ASML) continues to benefit from the build-out of AI infrastructure and remains a critical enabler of leading-edge semiconductor manufacturing. ASML's dominant position in Extreme Ultraviolet (EUV) lithography, where it holds a monopoly in the equipment required for leading-edge semiconductor manufacturing, positions it well to benefit from continued AI-driven capacity expansion and meaningful long-term revenue growth.
For illustration purposes only. Photo from Pixabay/Pexels
#NASDAQ #advisory #strategy #letter
2 months ago
Emerald Wealth Partners, an independent ***** et and wealth management firm based in Zurich, released its Q2 2026 investor letter for the "Focused Equity Strategy." A copy of the letter can be downloaded here. The Strategy reported a 0.8% gross return for the second quarter of 2026. Equity markets rallied after the first quarter's Iran shock faded and oil prices reversed their spike, but the advance remained narrow and concentrated in cyclical semiconductor and memory stocks benefiting from supply constraints. The letter warned that investors were treating peak-cycle earnings as durable, while FOMO, IPO demand, and a US cyclically adjusted P/E ratio near 40 pointed to late-cycle market behavior. Long-term fundamentals are currently undervalued by the market, leading to underperformance in the strategy, notably due to the portfolio's avoidance of low-quality momentum-driven semiconductor stocks, which boosted the benchmark this quarter. It remains focused on enterprise infrastructure, digital platforms, custom silicon, and networking businesses that hold customer relationships, workflow data, distribution, and efficiency advantages, which could allow them to monetize AI rather than be displaced by it. Please review the Strategy's top five holdings for its key selections.
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML), a lithography solutions provider for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems, contributed 156 bps to the strategy's performance during the quarter. On August 4, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,711.89 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was -3.21% and its shares gained 147.76% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $648.21 billion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"ASML Holding N.V. (NASDAQ:ASML) rose 51.0%, adding 156 bps benefitting from the euphoria surrounding the semiconductor sector. Its monopoly in advanced lithography remains one of the most durable competitive positions we own. Each new generation of its machines allows chipmakers to pack more transistors into less silicon. This steady improvement in efficiency — better performance per watt, easier thermal management, a lower cost per unit of compute — is what underpins further advances in AI, and every other application where efficient chips matter."
#wealth

2 months ago
After a year at the helm, Novo Nordisk's CEO Maziar Mike Doustdar's task of closing the gap to pacesetter Eli Lilly doesn't look to be getting any easier.
Doustdar joined Novo at the height of spiralling erosion to rivals in the obesity and type 2 diabetes market segments. While the Danish drugmaker has since gained approval for oral Wegovy, a drug that set a record-breaking pace for a glucagon-like peptide-1 receptor agonist (GLP-1RA) at launch, other pipeline products have had mixed clinical results. Earlier this week, cardiovascular disease drug ziltivekimab failed a Phase III trial, while CagriSema fell short in a non-inferiority trial comparing it to Lilly's tirzepatide.
Coupled with ongoing sales decline, dealmaking presents an obvious avenue in which to boost pipeline offerings. Novo has already said it is actively targeting bolt-on acquisitions, with Doustdar reiterating during the Q2 earnings call that large-scale, transformative deals are still a way off.
"I'm very proud of our internal R&D and pipeline, but no company has a monopoly on good ideas. I've also said we are in every data room to try and see who else has a better idea, who else can give us ******* ets that we can bolt on, and complement what [our internal R&D teams] are doing," Doustdar said.
"I'm a person who never starts with a no to one day [being able to conduct transformative M&A], but you have to be in a very different situation than Novo Nordisk is in today," he added.
#pipeline
2 months ago
Emerald Wealth Partners, an independent ****** et and wealth management firm based in Zurich, released its Q2 2026 investor letter for the "Focused Equity Strategy." A copy of the letter can be downloaded here. The Strategy reported a 0.8% gross return for the second quarter of 2026. Equity markets rallied after the first quarter's Iran shock faded and oil prices reversed their spike, but the advance remained narrow and concentrated in cyclical semiconductor and memory stocks benefiting from supply constraints. The letter warned that investors were treating peak-cycle earnings as durable, while FOMO, IPO demand, and a US cyclically adjusted P/E ratio near 40 pointed to late-cycle market behavior. Long-term fundamentals are currently undervalued by the market, leading to underperformance in the strategy, notably due to the portfolio's avoidance of low-quality momentum-driven semiconductor stocks, which boosted the benchmark this quarter. It remains focused on enterprise infrastructure, digital platforms, custom silicon, and networking businesses that hold customer relationships, workflow data, distribution, and efficiency advantages, which could allow them to monetize AI rather than be displaced by it. Please review the Strategy's top five holdings for its key selections.
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML), a lithography solutions provider for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems, contributed 156 bps to the strategy's performance during the quarter. On August 4, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,711.89 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was -3.21% and its shares gained 147.76% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $648.21 billion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"ASML Holding N.V. (NASDAQ:ASML) rose 51.0%, adding 156 bps benefitting from the euphoria surrounding the semiconductor sector. Its monopoly in advanced lithography remains one of the most durable competitive positions we own. Each new generation of its machines allows chipmakers to pack more transistors into less silicon. This steady improvement in efficiency — better performance per watt, easier thermal management, a lower cost per unit of compute — is what underpins further advances in AI, and every other application where efficient chips matter."
#asml #Equity