17 hours ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Gold can play a role in a diversified retirement portfolio, but it's generally better suited as a complement to stocks, bonds, and other investments than as a primary retirement ****** et.
Gold may help diversify a portfolio because it can perform differently from stocks and bonds under certain market conditions. But gold also has drawbacks, including lower long-term returns than stocks and, in the case of a gold IRA, potentially high storage and custodial fees.
How much gold belongs in your retirement portfolio depends on factors including your age, risk tolerance, time until retirement, and investment goals.
Gold can help diversify a retirement portfolio, but it shouldn't replace stocks, bonds, and other investments.
#Portfolio #including
Gold can play a role in a diversified retirement portfolio, but it's generally better suited as a complement to stocks, bonds, and other investments than as a primary retirement ****** et.
Gold may help diversify a portfolio because it can perform differently from stocks and bonds under certain market conditions. But gold also has drawbacks, including lower long-term returns than stocks and, in the case of a gold IRA, potentially high storage and custodial fees.
How much gold belongs in your retirement portfolio depends on factors including your age, risk tolerance, time until retirement, and investment goals.
Gold can help diversify a retirement portfolio, but it shouldn't replace stocks, bonds, and other investments.
#Portfolio #including



2 days ago
To summarize my investment approach, I prefer to buy companies with long histories of dividend increases and historically high yields. Those two traits don't come around all that often, and sometimes I find clusters of stocks in specific sectors. I need to think specifically about diversification, one of the simplest and most effective ways to reduce risk. Here's how I've done it as I've built my portfolio of around 34 investments.
The Motley Fool recommends that investors own 50 stocks. That's a perfectly fine number, but also a lot of work. And just owning 50 stocks doesn't actually mean you are diversified. You could own 50 technology stocks, for example, which would leave you with exposure to just a single sector. That's not diversification. Diversification is really about owning a reasonable number of investments across a wide range of sectors and ****** et classes.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My first step toward diversification was to take an honest look at what I want to achieve and what I'm capable of. My goal is a mixture of income and capital appreciation. I am fairly confident in my ability to select dividend stocks, though every investor makes mistakes from time to time, and I know I can only juggle so many stocks at once. In other words, 50 stocks are too many for me, so a core part of my diversification strategy is to outsource some of my work.
For example, I own two Baron mutual funds to gain exposure to growth stocks and smaller companies. I own several closed-end funds: one focused on healthcare stocks with an option income overlay, one investing in convertible securities, and one with a broadly diversified dividend portfolio. And I own three exchange-traded funds: one with an option income focus and two that use very different screening approaches to pick dividend stocks.
#Diversification #funds
The Motley Fool recommends that investors own 50 stocks. That's a perfectly fine number, but also a lot of work. And just owning 50 stocks doesn't actually mean you are diversified. You could own 50 technology stocks, for example, which would leave you with exposure to just a single sector. That's not diversification. Diversification is really about owning a reasonable number of investments across a wide range of sectors and ****** et classes.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My first step toward diversification was to take an honest look at what I want to achieve and what I'm capable of. My goal is a mixture of income and capital appreciation. I am fairly confident in my ability to select dividend stocks, though every investor makes mistakes from time to time, and I know I can only juggle so many stocks at once. In other words, 50 stocks are too many for me, so a core part of my diversification strategy is to outsource some of my work.
For example, I own two Baron mutual funds to gain exposure to growth stocks and smaller companies. I own several closed-end funds: one focused on healthcare stocks with an option income overlay, one investing in convertible securities, and one with a broadly diversified dividend portfolio. And I own three exchange-traded funds: one with an option income focus and two that use very different screening approaches to pick dividend stocks.
#Diversification #funds


4 days ago
VYMI mirrors VYM's rules-based dividend methodology across 1,500 non-US stocks and has outperformed its domestic twin by 11 percentage points over the past year.
VYMI's $22 billion in **** ets is dwarfed by VYM's $83 billion, revealing how overlooked international dividend investing remains despite paying higher yields.
IDV concentrates its international yield hunt into roughly 100 holdings at a 0.50% fee, making it the higher-income, higher-risk alternative to VYMI's diversified approach.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Ask a typical income investor for a Vanguard dividend ETF, and you'll hear Vanguard High Dividend Yield ETF (NYSEARCA:VYM) before the question is finished. Ask about its overseas sibling, and you'll usually get a blank stare. Vanguard International High Dividend Yield ETF (NASDAQ:VYMI) runs the same playbook outside the United States, pays a fatter distribution, and has quietly outperformed its famous American cousin over the past year. Even the established international name in the category, iShares International Select Dividend ETF (CBOE:IDV), doesn't get much airtime alongside the domestic heavyweights.
#international #vanguard
VYMI's $22 billion in **** ets is dwarfed by VYM's $83 billion, revealing how overlooked international dividend investing remains despite paying higher yields.
IDV concentrates its international yield hunt into roughly 100 holdings at a 0.50% fee, making it the higher-income, higher-risk alternative to VYMI's diversified approach.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
Ask a typical income investor for a Vanguard dividend ETF, and you'll hear Vanguard High Dividend Yield ETF (NYSEARCA:VYM) before the question is finished. Ask about its overseas sibling, and you'll usually get a blank stare. Vanguard International High Dividend Yield ETF (NASDAQ:VYMI) runs the same playbook outside the United States, pays a fatter distribution, and has quietly outperformed its famous American cousin over the past year. Even the established international name in the category, iShares International Select Dividend ETF (CBOE:IDV), doesn't get much airtime alongside the domestic heavyweights.
#international #vanguard


4 days ago
Apple is skipping the base iPhone 18 this fall in favor of three premium devices: the iPhone 18 Pro, the iPhone 18 Pro Max, and its first foldable — rumored to be called the iPhone Ultra, Duo, or Fold. The foldable is the headline. It's expected to feature a 7.8-inch internal display, a 5.3-inch external screen, an A20 Pro chip, and a thickness of just 4.5mm unfolded, with pricing estimated between $1,999 and $2,399 and limited initial supply. It marks Apple's entry into the foldable category years after rivals — a potentially major new product cycle for one of the world's most valuable companies.
Here's the pattern every ETF investor should understand before today's close. Nearly two decades of data show that Apple tends to "sell the news" on launch day itself. AAPL averages a roughly 0.3% decline on iPhone launch days, with a median drop of about 0.6% — the classic case of anticipation being priced in before the reveal.
But the weakness rarely lasts. Apple has averaged a 0.5% gain the very next session (positive in 15 of 24 releases), and the longer-term picture is decisively bullish: AAPL has gained in the 60 days following an iPhone reveal 17 times since the original 2007 launch. The biggest such move was a 20% gain in the 60 days after the iPhone 11 reveal in 2019. In other words, launch-day dips have historically been buying opportunities, not warning signs. **** ysts have also downplayed fears about the ~$2,000 foldable price tag, arguing a premium halo product is unlikely to dent Apple's overall economics.
Apple is not just a stock — it's one of the largest weights in the entire ETF universe. As one of the biggest companies in the world, it sits near the top of the S&P 500, the Nasdaq-100, and virtually every technology index. That means a move in AAPL ripples through hundreds of funds, and millions of investors have significant Apple exposure without realizing it. When Apple moves on event day, these are the ETFs that move with it.
A handful of funds carry outsized Apple weights and will feel today's move most acutely. GXPT (Global X PureCap MSCI Information Technology ETF) holds roughly 19.2% in Apple — the highest of any diversified fund. FTEC (Fidelity MSCI Information Technology Index ETF) holds about 16.3%, VGT (Vanguard Information Technology ETF) about 16.2%, TRUT (VanEck Technology TruSector ETF) roughly 15.1%, and TOPT (iShares Top 20 U.S. Stocks ETF) around 14.5%. For these funds, Apple is a dominant driver of daily returns.
#iphone #foldable #launch #aapl
Here's the pattern every ETF investor should understand before today's close. Nearly two decades of data show that Apple tends to "sell the news" on launch day itself. AAPL averages a roughly 0.3% decline on iPhone launch days, with a median drop of about 0.6% — the classic case of anticipation being priced in before the reveal.
But the weakness rarely lasts. Apple has averaged a 0.5% gain the very next session (positive in 15 of 24 releases), and the longer-term picture is decisively bullish: AAPL has gained in the 60 days following an iPhone reveal 17 times since the original 2007 launch. The biggest such move was a 20% gain in the 60 days after the iPhone 11 reveal in 2019. In other words, launch-day dips have historically been buying opportunities, not warning signs. **** ysts have also downplayed fears about the ~$2,000 foldable price tag, arguing a premium halo product is unlikely to dent Apple's overall economics.
Apple is not just a stock — it's one of the largest weights in the entire ETF universe. As one of the biggest companies in the world, it sits near the top of the S&P 500, the Nasdaq-100, and virtually every technology index. That means a move in AAPL ripples through hundreds of funds, and millions of investors have significant Apple exposure without realizing it. When Apple moves on event day, these are the ETFs that move with it.
A handful of funds carry outsized Apple weights and will feel today's move most acutely. GXPT (Global X PureCap MSCI Information Technology ETF) holds roughly 19.2% in Apple — the highest of any diversified fund. FTEC (Fidelity MSCI Information Technology Index ETF) holds about 16.3%, VGT (Vanguard Information Technology ETF) about 16.2%, TRUT (VanEck Technology TruSector ETF) roughly 15.1%, and TOPT (iShares Top 20 U.S. Stocks ETF) around 14.5%. For these funds, Apple is a dominant driver of daily returns.
#iphone #foldable #launch #aapl


4 days ago
VOO (Vanguard S&P 500 ETF) tracks the S&P 500, the 500 largest U.S. companies across every sector, at an ultra-low fee. QQQ (Invesco QQQ Trust) tracks the Nasdaq-100, an Index of the 100 largest non-financial companies on the Nasdaq, heavily tilted toward technology. In short: VOO is the diversified, low-cost core; QQQ is the concentrated, higher-growth, higher-volatility tech bet. Neither is "better" in the abstract — they suit different goals.
Feature
VOO
QQQ
Index tracked
#NASDAQ #invesco
Feature
VOO
QQQ
Index tracked
#NASDAQ #invesco


4 days ago
During a segment on the September 3 episode, Mad Money host Jim Cramer shared a detailed bullish thesis on Amazon.com, Inc. (NASDAQ:AMZN). He stated:
Let's start with Amazon. Ever since we went out to see Amazon earlier this year, I've been stuck on something that CEO Andy Jassy told me. He said they're going to make an immense amount of money in artificial intelligence. They were going to profit from their gigantic commitment to data centers and next year will be huge for the compute sales. Well, I think it's being pulled forward. I think it may already be huge right now. I also remember Andy talking about the $50 billion semiconductor business that's buried in the company. I like the healthcare initiatives... Amazon Web Services is doing incredibly well. Their grocery delivery business, wow...
Alright, what can I say? All this for a stock that's up just 12% for the year; that's wrong. Amazon's balance sheet isn't as good as it was a year ago; enough already. What if Amazon Web Services is able to make four times what it just paid for 2 million GPUs from NVIDIA? That ratio, by the way, is what NVIDIA CEO Jensen Huang told me companies can expect to get when they buy NVIDIA chips. That makes me think that Amazon is cheap. We've all kind of forgotten that there's a reason why a smart executive like Andy Jassy is willing to wreck Amazon's balance sheet like the old days. It's because they're going to make fortunes with the money they spend. And we are getting closer and closer to seeing huge profits for investments that the Street has hated. You can't wait until next year to buy the stock of Amazon. And that's why it is a screaming buy with the stock trading at about 20 times this year's earnings. That's wrong.
Amazon Web Services remains the primary profit engine for the company. In the second quarter, AWS revenue surged 37% year over year to reach $42.2 billion, putting its annual run rate at roughly $169 billion. Operating income for the cloud unit jumped to $16.6 billion. Companies shifting their operations to handle AI and heavy workloads are turning those massive data center investments into high-margin profits. Aside from basic cloud hosting, Amazon.com, Inc. (NASDAQ:AMZN) is leaning into its own custom chips, like Trainium and Graviton, and growing adoption of the Bedrock platform to keep its revenue streams strong and diversified.
Not everyone on Wall Street shares Cramer's enthusiasm, as it could be pointed out that Amazon.com, Inc.'s (NASDAQ:AMZN) balance sheet is noticeably weaker than it was a year ago as its long-term debt increased from nearly $66 billion at the end of 2025 to nearly $129 billion by mid-2026. Heavy capital commitments and soaring data center expenses, with full-year capital expenditure guidance climbing around $220 billion, have strained cash flow flexibility. Investors could be worried that the company is spending too aggressively. If enterprise demand for artificial intelligence tools slows down or if the massi
Let's start with Amazon. Ever since we went out to see Amazon earlier this year, I've been stuck on something that CEO Andy Jassy told me. He said they're going to make an immense amount of money in artificial intelligence. They were going to profit from their gigantic commitment to data centers and next year will be huge for the compute sales. Well, I think it's being pulled forward. I think it may already be huge right now. I also remember Andy talking about the $50 billion semiconductor business that's buried in the company. I like the healthcare initiatives... Amazon Web Services is doing incredibly well. Their grocery delivery business, wow...
Alright, what can I say? All this for a stock that's up just 12% for the year; that's wrong. Amazon's balance sheet isn't as good as it was a year ago; enough already. What if Amazon Web Services is able to make four times what it just paid for 2 million GPUs from NVIDIA? That ratio, by the way, is what NVIDIA CEO Jensen Huang told me companies can expect to get when they buy NVIDIA chips. That makes me think that Amazon is cheap. We've all kind of forgotten that there's a reason why a smart executive like Andy Jassy is willing to wreck Amazon's balance sheet like the old days. It's because they're going to make fortunes with the money they spend. And we are getting closer and closer to seeing huge profits for investments that the Street has hated. You can't wait until next year to buy the stock of Amazon. And that's why it is a screaming buy with the stock trading at about 20 times this year's earnings. That's wrong.
Amazon Web Services remains the primary profit engine for the company. In the second quarter, AWS revenue surged 37% year over year to reach $42.2 billion, putting its annual run rate at roughly $169 billion. Operating income for the cloud unit jumped to $16.6 billion. Companies shifting their operations to handle AI and heavy workloads are turning those massive data center investments into high-margin profits. Aside from basic cloud hosting, Amazon.com, Inc. (NASDAQ:AMZN) is leaning into its own custom chips, like Trainium and Graviton, and growing adoption of the Bedrock platform to keep its revenue streams strong and diversified.
Not everyone on Wall Street shares Cramer's enthusiasm, as it could be pointed out that Amazon.com, Inc.'s (NASDAQ:AMZN) balance sheet is noticeably weaker than it was a year ago as its long-term debt increased from nearly $66 billion at the end of 2025 to nearly $129 billion by mid-2026. Heavy capital commitments and soaring data center expenses, with full-year capital expenditure guidance climbing around $220 billion, have strained cash flow flexibility. Investors could be worried that the company is spending too aggressively. If enterprise demand for artificial intelligence tools slows down or if the massi

5 days ago
IG Wealth Management and Goldman Sachs ******* et Management have entered a partnership, covering a range of investment portfolios.
The arrangement links IG's financial planning operations with Goldman Sachs ******* et Management's investment management capabilities.
The firms are intended to give IG clients and retail investors in Canada access to diversified strategies spanning equities, fixed income and alternative ******* ets, using approaches previously used by institutional investors.
Goldman Sachs ******* et Management global head and multi-asset solutions co-chief investment officer and portfolio manager Alexandra Wilson-Elizondo said: "We believe a modern approach to ******* et allocation, dynamic investment strategies, robust risk management processes and well-diversified portfolios help clients achieve their objectives across market environments.
"We are excited to partner with IG to bring the capabilities of our Multi-Asset Solutions team to IG's clients across Canada."
#goldman #sachs #canada #portfolios
The arrangement links IG's financial planning operations with Goldman Sachs ******* et Management's investment management capabilities.
The firms are intended to give IG clients and retail investors in Canada access to diversified strategies spanning equities, fixed income and alternative ******* ets, using approaches previously used by institutional investors.
Goldman Sachs ******* et Management global head and multi-asset solutions co-chief investment officer and portfolio manager Alexandra Wilson-Elizondo said: "We believe a modern approach to ******* et allocation, dynamic investment strategies, robust risk management processes and well-diversified portfolios help clients achieve their objectives across market environments.
"We are excited to partner with IG to bring the capabilities of our Multi-Asset Solutions team to IG's clients across Canada."
#goldman #sachs #canada #portfolios

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
Minneapolis, Minnesota-based Ameriprise Financial, Inc. (AMP) is a diversified financial services company that helps individuals and institutions build, manage, and protect their wealth. Its business combines financial advice, investment management, and retirement and insurance solutions, giving it multiple ways to earn revenue from long-term client relationships.
Companies valued at $10 billion or more are typically classified as "large-cap stocks," and AMP, with a market cap of $50.4 billion, fits the label perfectly. Its market leadership comes from its diversified wealth-management platform, recurring fee-based revenue, and strong client relationships. Its advisor network supports long-term customer retention, while its ****** et-management and retirement businesses provide additional revenue streams.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#diversified
Companies valued at $10 billion or more are typically classified as "large-cap stocks," and AMP, with a market cap of $50.4 billion, fits the label perfectly. Its market leadership comes from its diversified wealth-management platform, recurring fee-based revenue, and strong client relationships. Its advisor network supports long-term customer retention, while its ****** et-management and retirement businesses provide additional revenue streams.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#diversified

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
The diversified S&P 500 (SNPINDEX: ^GSPC) and the technology-heavy Nasdaq-100 are two widely followed stock market indexes that are packed with America's highest-quality companies. They have returned 12.7% and 17% respectively so far in 2026, as of the market close last Friday, Sept. 4.
But then there is the Russell 2000 index, which is sitting on an even better year-to-date gain of 20.2%. It tracks the performance of approximately 2,000 of America's smallest listed companies, and since many of them generate most of their revenue domestically, they are more insulated from headwinds like the ongoing conflict in the Middle East compared to larger, multinational companies.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The Vanguard Russell 2000 ETF (NASDAQ: VTWO) is an exchange-traded fund (ETF) that mimics the Russell 2000. It could face a reckoning on Sept. 15 and 16, when the U.S. Federal Reserve holds its next policy meeting. The odds of an interest rate hike are increasing, and for reasons I'll soon explain, small American companies tend to be more sensitive to such policy adjustments than their larger counterparts.
The companies in both the S&P 500 and the Russell 2000 come from 11 different economic sectors, so both indexes are highly diversified. However, the technology sector alone accounts for over one-third of the value of the entire S&P, whereas the Russell is far more balanced. The five largest sectors (by weight) in the Vanguard Russell 2000 ETF are as follows:
#NVIDIA #sept
But then there is the Russell 2000 index, which is sitting on an even better year-to-date gain of 20.2%. It tracks the performance of approximately 2,000 of America's smallest listed companies, and since many of them generate most of their revenue domestically, they are more insulated from headwinds like the ongoing conflict in the Middle East compared to larger, multinational companies.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The Vanguard Russell 2000 ETF (NASDAQ: VTWO) is an exchange-traded fund (ETF) that mimics the Russell 2000. It could face a reckoning on Sept. 15 and 16, when the U.S. Federal Reserve holds its next policy meeting. The odds of an interest rate hike are increasing, and for reasons I'll soon explain, small American companies tend to be more sensitive to such policy adjustments than their larger counterparts.
The companies in both the S&P 500 and the Russell 2000 come from 11 different economic sectors, so both indexes are highly diversified. However, the technology sector alone accounts for over one-third of the value of the entire S&P, whereas the Russell is far more balanced. The five largest sectors (by weight) in the Vanguard Russell 2000 ETF are as follows:
#NVIDIA #sept

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
5 days ago
Newark, New Jersey-based Prudential Financial, Inc. (PRU) is a diversified global financial services company that helps individuals and institutions protect wealth, prepare for retirement and pursue long-term financial goals. Valued at a market cap of $41.2 billion, its businesses span life insurance, annuities, retirement solutions, group insurance and investment management through PGIM, its global ****** et-management arm.
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PRU fits right into that category. Prudential dominates the market due to its diversified insurance, retirement and investment-management businesses, which provide multiple sources of earnings and reduce reliance on any single market or product. Its established brand, extensive distribution network, large institutional and individual customer base and PGIM ****** et-management platform support scale, recurring fee income and cross-selling opportunities.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#management #financial #prudential #Stock
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PRU fits right into that category. Prudential dominates the market due to its diversified insurance, retirement and investment-management businesses, which provide multiple sources of earnings and reduce reliance on any single market or product. Its established brand, extensive distribution network, large institutional and individual customer base and PGIM ****** et-management platform support scale, recurring fee income and cross-selling opportunities.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#management #financial #prudential #Stock


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance outperformance was driven by disciplined channel management, with legacy field inventory reduced by approximately 30% year-over-year to improve turns to better than pre-pandemic levels.
The MasterCraft brand's success was anchored by the next-generation X Series rollout, which drove a favorable premium mix and offset lower industry-wide volumes.
Management attributed the 730 basis point expansion in legacy adjusted EBITDA margin to improved fixed cost absorption on higher unit volumes and lower promotional discounting.
The combination with Chaparral and Robalo is framed as a transformational pivot to a larger, more diversified platform spanning inland and coastal markets with broader price points.
#management #lower #NVIDIA
Performance outperformance was driven by disciplined channel management, with legacy field inventory reduced by approximately 30% year-over-year to improve turns to better than pre-pandemic levels.
The MasterCraft brand's success was anchored by the next-generation X Series rollout, which drove a favorable premium mix and offset lower industry-wide volumes.
Management attributed the 730 basis point expansion in legacy adjusted EBITDA margin to improved fixed cost absorption on higher unit volumes and lower promotional discounting.
The combination with Chaparral and Robalo is framed as a transformational pivot to a larger, more diversified platform spanning inland and coastal markets with broader price points.
#management #lower #NVIDIA

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

7 days ago
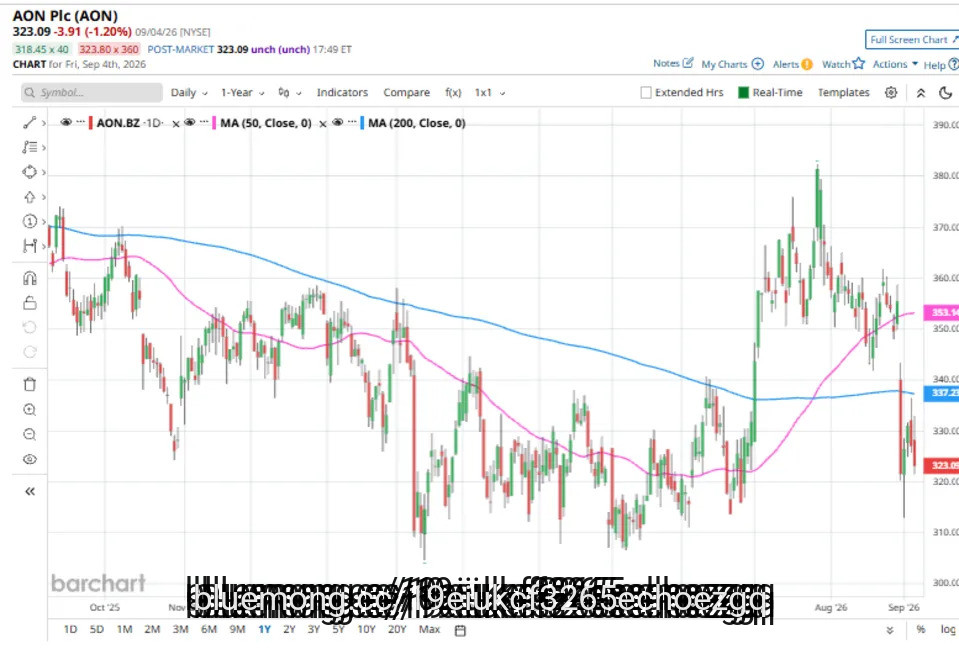
Dublin, Ireland-based Aon plc (AON) is a global professional services firm that helps businesses manage two critical challenges: risk and people. Valued at a market cap of $68.5 billion, the company delivers data-driven solutions to corporate, institutional, and commercial clients to reduce operational volatility and optimize workforce performance.
Companies valued at $10 billion or more are typically classified as "large-cap stocks," and AON fits the label perfectly, with its market cap exceeding this threshold, underscoring its size, influence, and dominance within the insurance brokers industry. Aon's competitive advantage lies in its global scale, proprietary data and ****** ytics, and broad risk and human capital expertise. Its presence across more than 120 countries, combined with a diversified client base, supports a strong international network and helps it serve complex, multinational clients.
How to Play SNPS Stock as Layoffs Hit Synopsys
Micron Stock More Than Tripled in 2026. Now Taiwan Strike Threat Could Shake the AI Boom.
Dear Adobe Stock Fans, Mark Your Calendars for September 10
#risk #market
Companies valued at $10 billion or more are typically classified as "large-cap stocks," and AON fits the label perfectly, with its market cap exceeding this threshold, underscoring its size, influence, and dominance within the insurance brokers industry. Aon's competitive advantage lies in its global scale, proprietary data and ****** ytics, and broad risk and human capital expertise. Its presence across more than 120 countries, combined with a diversified client base, supports a strong international network and helps it serve complex, multinational clients.
How to Play SNPS Stock as Layoffs Hit Synopsys
Micron Stock More Than Tripled in 2026. Now Taiwan Strike Threat Could Shake the AI Boom.
Dear Adobe Stock Fans, Mark Your Calendars for September 10
#risk #market

7 days ago
Impax ***** et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Verizon Communications Inc. (NYSE:VZ). Verizon Communications Inc. (NYSE:VZ) is a leading telecommunication company that engages in the provision of communications, technology, information, and streaming products and services. On September 04, 2026, Verizon Communications Inc. (NYSE:VZ) closed at $50.14 per share. Over the past month, Verizon Communications Inc. (NYSE:VZ) returned 6.61%, but its shares are up 15.74% over the past year. Verizon Communications Inc. (NYSE:VZ) has a market capitalization of $208.32 billion, and its stock has traded within a 52-week range of $38.39 to $51.68.
Impax US Sustainable Economy Fund stated the following regarding Verizon Communications Inc. (NYSE:VZ) in its Q2 2026 investor letter:
"Verizon Communications Inc. (NYSE:VZ) (Wireless Telecommunication Services, Communication Services) is held for its high Corporate Resilience score and its sustainability opportunity exposure in areas including Digital Infrastructure and Meeting Basic Needs. The stock fell during the quarter as investor focus shifted away from defensive yield plays toward growth and cyclical sectors. Concerns about subscriber churn in a highly competitive wireless market, and the heavy capital expenditure requirements of continued network infrastructure investment, weighed on the share price."
#sustainable
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Verizon Communications Inc. (NYSE:VZ). Verizon Communications Inc. (NYSE:VZ) is a leading telecommunication company that engages in the provision of communications, technology, information, and streaming products and services. On September 04, 2026, Verizon Communications Inc. (NYSE:VZ) closed at $50.14 per share. Over the past month, Verizon Communications Inc. (NYSE:VZ) returned 6.61%, but its shares are up 15.74% over the past year. Verizon Communications Inc. (NYSE:VZ) has a market capitalization of $208.32 billion, and its stock has traded within a 52-week range of $38.39 to $51.68.
Impax US Sustainable Economy Fund stated the following regarding Verizon Communications Inc. (NYSE:VZ) in its Q2 2026 investor letter:
"Verizon Communications Inc. (NYSE:VZ) (Wireless Telecommunication Services, Communication Services) is held for its high Corporate Resilience score and its sustainability opportunity exposure in areas including Digital Infrastructure and Meeting Basic Needs. The stock fell during the quarter as investor focus shifted away from defensive yield plays toward growth and cyclical sectors. Concerns about subscriber churn in a highly competitive wireless market, and the heavy capital expenditure requirements of continued network infrastructure investment, weighed on the share price."
#sustainable

7 days ago
Impax ***** et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Zoetis Inc. (NYSE:ZTS). Zoetis Inc. (NYSE:ZTS), an animal health company focused on animal health medications, vaccines, and diagnostic products, detracted from the Fund's performance during the quarter. On September 04, 2026, Zoetis Inc. (NYSE:ZTS) closed at $75.81 per share. Over the past month, Zoetis Inc. (NYSE:ZTS) returned 1.31%, but its shares are down 50.04% over the past year. Zoetis Inc. (NYSE:ZTS) has a market capitalization of $31.33 billion.
Impax US Sustainable Economy Fund stated the following regarding Zoetis Inc. (NYSE:ZTS) in its Q2 2026 investor letter:
"Zoetis Inc. (NYSE:ZTS) (Pharmaceuticals, Health Care) is owned for its attractive sustainability opportunity profile in areas including Wellbeing and Evolving Health Care Challenge, as well as its strong governance profile. The stock declined sharply in the quarter following a downward revision to near-term earnings guidance. Sales of Librela, the company's key canine arthritis pain management product, continued to face headwinds from safety perception concerns among some veterinarians, and management indicated that the ramp-up of next-generation product launches would extend into the following year."
#economy #Health
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Zoetis Inc. (NYSE:ZTS). Zoetis Inc. (NYSE:ZTS), an animal health company focused on animal health medications, vaccines, and diagnostic products, detracted from the Fund's performance during the quarter. On September 04, 2026, Zoetis Inc. (NYSE:ZTS) closed at $75.81 per share. Over the past month, Zoetis Inc. (NYSE:ZTS) returned 1.31%, but its shares are down 50.04% over the past year. Zoetis Inc. (NYSE:ZTS) has a market capitalization of $31.33 billion.
Impax US Sustainable Economy Fund stated the following regarding Zoetis Inc. (NYSE:ZTS) in its Q2 2026 investor letter:
"Zoetis Inc. (NYSE:ZTS) (Pharmaceuticals, Health Care) is owned for its attractive sustainability opportunity profile in areas including Wellbeing and Evolving Health Care Challenge, as well as its strong governance profile. The stock declined sharply in the quarter following a downward revision to near-term earnings guidance. Sales of Librela, the company's key canine arthritis pain management product, continued to face headwinds from safety perception concerns among some veterinarians, and management indicated that the ramp-up of next-generation product launches would extend into the following year."
#economy #Health


7 days ago
Impax ****** et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Adobe Inc. (NASDAQ:ADBE). Adobe Inc. (NASDAQ:ADBE) is a multinational technology company that offers creative, digital media, and document management products. On September 04, 2026, Adobe Inc. (NASDAQ:ADBE) closed at $266.51 per share. Over the past month, Adobe Inc. (NASDAQ:ADBE) declined 2.36%, but its shares are down 25.69% over the past year. Adobe Inc. (NASDAQ:ADBE) has a market capitalization of $105.94 billion.
Impax US Sustainable Economy Fund stated the following regarding Adobe Inc. (NASDAQ:ADBE) in its Q2 2026 investor letter:
"Adobe Inc. (NASDAQ:ADBE) (Application Software, Information Technology) is held for its high Sustainability Lens opportunity profile across Digital Infrastructure and Education themes and its strong Corporate Resilience score. The stock declined in the quarter following results that, while solid in absolute terms, fell short of the elevated investor expectations that had built over the prior year. Concerns about the pace of monetization from its AI-integrated creative tools, and competitive pressure from lower-cost generative AI platforms, weighed on sentiment and drove a valuation de-rating."
#letter
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Adobe Inc. (NASDAQ:ADBE). Adobe Inc. (NASDAQ:ADBE) is a multinational technology company that offers creative, digital media, and document management products. On September 04, 2026, Adobe Inc. (NASDAQ:ADBE) closed at $266.51 per share. Over the past month, Adobe Inc. (NASDAQ:ADBE) declined 2.36%, but its shares are down 25.69% over the past year. Adobe Inc. (NASDAQ:ADBE) has a market capitalization of $105.94 billion.
Impax US Sustainable Economy Fund stated the following regarding Adobe Inc. (NASDAQ:ADBE) in its Q2 2026 investor letter:
"Adobe Inc. (NASDAQ:ADBE) (Application Software, Information Technology) is held for its high Sustainability Lens opportunity profile across Digital Infrastructure and Education themes and its strong Corporate Resilience score. The stock declined in the quarter following results that, while solid in absolute terms, fell short of the elevated investor expectations that had built over the prior year. Concerns about the pace of monetization from its AI-integrated creative tools, and competitive pressure from lower-cost generative AI platforms, weighed on sentiment and drove a valuation de-rating."
#letter


7 days ago
Impax **** et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Micron Technology, Inc. (NASDAQ:MU) as a material contributor to performance. Micron Technology, Inc. is a leading semiconductor company that manufactures memory and storage products, delivering solutions for a wide range of applications. On September 04, 2026, Micron Technology, Inc. (NASDAQ:MU) closed at $1,016.59 per share. The one-month return of Micron Technology, Inc. (NASDAQ:MU) was 18.07% and its shares gained 673.31% over the past 52 weeks. Micron Technology, Inc. (NASDAQ:MU) has a market capitalization of $1.15 trillion.
Impax US Sustainable Economy Fund stated the following regarding Micron Technology, Inc. (NASDAQ:MU) in its Q2 2026 investor letter:
"Micron Technology, Inc. (NASDAQ:MU) (Semiconductors, Information Technology) is held for its high Sustainability Lens opportunity profile across Digital Infrastructure, Meeting Basic Needs and Education themes, and carries a strong Corporate Resilience score. The stock surged during the quarter as demand for high-bandwidth memory used in AI training and inference applications accelerated sharply. The data center build-out by hyperscale providers drove a significant uplift to Micron's pricing power and volume outlook, and the company revised its forward guidance meaningfully higher, prompting a sharp re-rating from investors."
#NASDAQ #sustainable #economy #class
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Micron Technology, Inc. (NASDAQ:MU) as a material contributor to performance. Micron Technology, Inc. is a leading semiconductor company that manufactures memory and storage products, delivering solutions for a wide range of applications. On September 04, 2026, Micron Technology, Inc. (NASDAQ:MU) closed at $1,016.59 per share. The one-month return of Micron Technology, Inc. (NASDAQ:MU) was 18.07% and its shares gained 673.31% over the past 52 weeks. Micron Technology, Inc. (NASDAQ:MU) has a market capitalization of $1.15 trillion.
Impax US Sustainable Economy Fund stated the following regarding Micron Technology, Inc. (NASDAQ:MU) in its Q2 2026 investor letter:
"Micron Technology, Inc. (NASDAQ:MU) (Semiconductors, Information Technology) is held for its high Sustainability Lens opportunity profile across Digital Infrastructure, Meeting Basic Needs and Education themes, and carries a strong Corporate Resilience score. The stock surged during the quarter as demand for high-bandwidth memory used in AI training and inference applications accelerated sharply. The data center build-out by hyperscale providers drove a significant uplift to Micron's pricing power and volume outlook, and the company revised its forward guidance meaningfully higher, prompting a sharp re-rating from investors."
#NASDAQ #sustainable #economy #class
7 days ago
Impax ******* et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD) as a key contributor. Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 04, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $477.57 per share, reflecting a market capitalization of $779.62 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 1.71%, but its shares are up 215.42% over the past year.
Impax US Sustainable Economy Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"Advanced Micro Devices, Inc. (NASDAQ:AMD) (Semiconductors, Information Technology) is held for its attractive sustainability opportunity set, particularly in Digital Infrastructure, and for its high Corporate Resilience score across environmental and governance dimensions. The stock rose substantially in the quarter, driven by strong adoption of its AI-optimized GPU (graphics processing unit) and data center processor products. A series of major partnership announcements with cloud computing providers and continued evidence of market share gains in AI accelerator hardware reinforced investor confidence in the company's multi-year earnings growth trajectory."
#NASDAQ #impax #sustainable #letter
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD) as a key contributor. Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 04, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $477.57 per share, reflecting a market capitalization of $779.62 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 1.71%, but its shares are up 215.42% over the past year.
Impax US Sustainable Economy Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"Advanced Micro Devices, Inc. (NASDAQ:AMD) (Semiconductors, Information Technology) is held for its attractive sustainability opportunity set, particularly in Digital Infrastructure, and for its high Corporate Resilience score across environmental and governance dimensions. The stock rose substantially in the quarter, driven by strong adoption of its AI-optimized GPU (graphics processing unit) and data center processor products. A series of major partnership announcements with cloud computing providers and continued evidence of market share gains in AI accelerator hardware reinforced investor confidence in the company's multi-year earnings growth trajectory."
#NASDAQ #impax #sustainable #letter

7 days ago
Impax ******* et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Applied Materials, Inc. (NASDAQ:AMAT) as a notable contributor to performance. Applied Materials, Inc. (NASDAQ:AMAT) provides materials engineering solutions, equipment, services, and software to the semiconductor and related industries. On September 04, 2026, Applied Materials, Inc. (NASDAQ:AMAT) closed at $454.71 per share. Over the past month, Applied Materials, Inc. (NASDAQ:AMAT) declined 12.91%, but its shares are up 180.60% over the past year. Applied Materials, Inc. (NASDAQ:AMAT) has a market capitalization of $360.86 billion, and its stock has traded within a 52-week range of $161.75 - $739.67
Impax US Sustainable Economy Fund stated the following regarding Applied Materials, Inc. (NASDAQ:AMAT) in its Q2 2026 investor letter:
"Applied Materials, Inc. (NASDAQ:AMAT) (Semiconductor Equipment, Information Technology) is owned for its Sustainability Lens exposure to Digital Infrastructure and Education themes, and for its high Corporate Resilience score. The stock benefited from a recovery in semiconductor capital expenditure, with leading-edge logic and memory chipmakers restarting investment programs deferred from the prior year. Applied Materials reported strong order intake and revised its full-year guidance upward, reflecting the broad-based nature of the semiconductor equipment recovery."
#NASDAQ #sustainable #economy
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Applied Materials, Inc. (NASDAQ:AMAT) as a notable contributor to performance. Applied Materials, Inc. (NASDAQ:AMAT) provides materials engineering solutions, equipment, services, and software to the semiconductor and related industries. On September 04, 2026, Applied Materials, Inc. (NASDAQ:AMAT) closed at $454.71 per share. Over the past month, Applied Materials, Inc. (NASDAQ:AMAT) declined 12.91%, but its shares are up 180.60% over the past year. Applied Materials, Inc. (NASDAQ:AMAT) has a market capitalization of $360.86 billion, and its stock has traded within a 52-week range of $161.75 - $739.67
Impax US Sustainable Economy Fund stated the following regarding Applied Materials, Inc. (NASDAQ:AMAT) in its Q2 2026 investor letter:
"Applied Materials, Inc. (NASDAQ:AMAT) (Semiconductor Equipment, Information Technology) is owned for its Sustainability Lens exposure to Digital Infrastructure and Education themes, and for its high Corporate Resilience score. The stock benefited from a recovery in semiconductor capital expenditure, with leading-edge logic and memory chipmakers restarting investment programs deferred from the prior year. Applied Materials reported strong order intake and revised its full-year guidance upward, reflecting the broad-based nature of the semiconductor equipment recovery."
#NASDAQ #sustainable #economy
7 days ago
NVIDIA Corporation (NASDAQ:NVDA) biggest lingering investor concern was customer concentration, CNBC reported. Nvidia relies on hyperscalers Amazon, Google, and Microsoft, along with major buyers Meta and ****** eX, for an outsized share of revenue, and in May began splitting its data center reporting into "hyperscalers" versus everyone else, a group it calls AI clouds, industrial, and enterprise, or ACIE. In the first quarter, the two segments were nearly even, at $37.9 billion for hyperscalers and $37.5 billion for ACIE, with ACIE growing 31% versus a slower pace for hyperscalers. CEO Jensen Huang has said the "easiest go-to-market" is hyperscalers "because there are only five or six of them," versus "250,000 companies" in the broader industry Nvidia hopes to reach.
NVIDIA Corporation (NASDAQ:NVDA)'s actual results answered the concentration question better than investors feared. In a later quarter, Data Center revenue reached $89 billion (beating the $85.8 billion forecast), while CFO Colette Kress noted that hyperscale revenue more than doubled. ACIE revenue surged 138%, an outcome showing the smaller, more diversified customer base is now growing even faster than the concentrated hyperscaler group Nvidia has leaned on most heavily.
Huang's own framing shows the concentration is a go-to-market choice, not a structural ceiling. Huang has described hyperscalers as simply the "easiest" customers to sell to first because there are only a handful of them, while pointing to roughly 250,000 other companies as the long-term addressable market. It means today's concentration shows where Nvidia started selling, not the limit of where it can sell.
Even Nvidia's most concentrated customers keep buying at scale despite their own cost pressures. Hyperscalers have continued purchasing GPUs in bulk even as their free cash flow gets squeezed by capital spending, evidence that AI infrastructure remains a top spending priority for these companies rather than an area facing near-term cutbacks.
The underlying dependence is still there, even if this quarter's mix improved. Nvidia continues to draw an outsized share of revenue from just three hyperscalers plus Meta and ****** eX. Each of those companies is actively designing its own custom chips specifically to reduce reliance on Nvidia. It is a long-term competitive threat that one strong ACIE quarter does not eliminate.
#NVIDIA #acie
NVIDIA Corporation (NASDAQ:NVDA)'s actual results answered the concentration question better than investors feared. In a later quarter, Data Center revenue reached $89 billion (beating the $85.8 billion forecast), while CFO Colette Kress noted that hyperscale revenue more than doubled. ACIE revenue surged 138%, an outcome showing the smaller, more diversified customer base is now growing even faster than the concentrated hyperscaler group Nvidia has leaned on most heavily.
Huang's own framing shows the concentration is a go-to-market choice, not a structural ceiling. Huang has described hyperscalers as simply the "easiest" customers to sell to first because there are only a handful of them, while pointing to roughly 250,000 other companies as the long-term addressable market. It means today's concentration shows where Nvidia started selling, not the limit of where it can sell.
Even Nvidia's most concentrated customers keep buying at scale despite their own cost pressures. Hyperscalers have continued purchasing GPUs in bulk even as their free cash flow gets squeezed by capital spending, evidence that AI infrastructure remains a top spending priority for these companies rather than an area facing near-term cutbacks.
The underlying dependence is still there, even if this quarter's mix improved. Nvidia continues to draw an outsized share of revenue from just three hyperscalers plus Meta and ****** eX. Each of those companies is actively designing its own custom chips specifically to reduce reliance on Nvidia. It is a long-term competitive threat that one strong ACIE quarter does not eliminate.
#NVIDIA #acie

9 days ago
Coca-Cola (NYSE: KO) is one of the best-known companies in the world, thanks to its namesake beverage brand, so it needs little introduction. However, what's most impressive right now is the stock's performance. It is up 28% over the past year, as of this writing. The average consumer staples stock is only up 5% over that span. Even the S&P 500 index (SNPINDEX: ^GSPC) is "only" up 20%. After a run like that, is Coca-Cola a buy, hold, or sell?
Coca-Cola is a well-run business. It is one of the world's largest consumer staples companies. It is globally diversified and has industry-leading capabilities in distribution, marketing, and innovation. The company's fundamental strength is evident in its status as a Dividend King, with 64 consecutive annual dividend increases. The only consumer staples peer with a better record is Procter & Gamble (NYSE: PG), but P&G doesn't make food. So, Coca-Cola is the food company with the best dividend record.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to own industry-leading businesses, Coca-Cola should be on your short list. And, with an above-market yield of 2.4%, you could easily justify adding it to your portfolio. That's particularly true given recent results, with organic revenue growth of 6% in the second quarter of 2026, even as consumers tighten their belts. In fact, Coca-Cola raised its full-year guidance despite the broader food industry's struggles.
Certainly, if you have owned Coca-Cola for years, selling it right when it is performing so well as a business probably isn't something you should be considering. Unless, of course, the stock's valuation was running ahead of its historical norms. But that's not the case.
#staples
Coca-Cola is a well-run business. It is one of the world's largest consumer staples companies. It is globally diversified and has industry-leading capabilities in distribution, marketing, and innovation. The company's fundamental strength is evident in its status as a Dividend King, with 64 consecutive annual dividend increases. The only consumer staples peer with a better record is Procter & Gamble (NYSE: PG), but P&G doesn't make food. So, Coca-Cola is the food company with the best dividend record.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to own industry-leading businesses, Coca-Cola should be on your short list. And, with an above-market yield of 2.4%, you could easily justify adding it to your portfolio. That's particularly true given recent results, with organic revenue growth of 6% in the second quarter of 2026, even as consumers tighten their belts. In fact, Coca-Cola raised its full-year guidance despite the broader food industry's struggles.
Certainly, if you have owned Coca-Cola for years, selling it right when it is performing so well as a business probably isn't something you should be considering. Unless, of course, the stock's valuation was running ahead of its historical norms. But that's not the case.
#staples


9 days ago
The Vanguard FTSE Emerging Markets ETF (VWO) is held in target-date funds, robo-advisor portfolios, and retirement accounts across the country, with roughly $122 billion across roughly 6,300 emerging-market stocks as of June 30, 2026.
For most holders, the VWO is a set-it-and-forget-it allocation to developing economies across Asia, Latin America, and Africa.
A clause buried in the fund's February 2026 statutory prospectus reframes what those holders own, and few appear to have noticed.
The disclosure warns that VWO can legally shift from a diversified fund to a nondiversified one through ordinary market movement or an index rebalance.
No shareholder vote is required, and Vanguard's portfolio managers do not need to take any deliberate action for that transition to occur.
#across #emerging #market #vanguard
For most holders, the VWO is a set-it-and-forget-it allocation to developing economies across Asia, Latin America, and Africa.
A clause buried in the fund's February 2026 statutory prospectus reframes what those holders own, and few appear to have noticed.
The disclosure warns that VWO can legally shift from a diversified fund to a nondiversified one through ordinary market movement or an index rebalance.
No shareholder vote is required, and Vanguard's portfolio managers do not need to take any deliberate action for that transition to occur.
#across #emerging #market #vanguard

10 days ago
Nvidia rose only 0.8% on September 4, while Astera Labs jumped 9.8% and Marvell gained 7.1%. The comparison was consistent with investors broadening the AI trade beyond accelerators into connectivity suppliers. Astera's rally also coincided with speculation that the company could be added to the S&P 500, although it was ultimately not selected in the September rebalance. Bigger accelerator clusters need retimers, switches, optical links, and custom silicon to move data without leaving expensive processors idle. Astera Labs, Inc. (NASDAQ:ALAB) and Marvell Technology, Inc. (NASDAQ:MRVL) monetize that connectivity bottleneck from different positions.
Photo from Astera Labs
Astera is the focused rack-scale connectivity play. Its second-quarter update said a Q3 production ramp of the Scorpio X-Series 320-lane fabric switch was expected to drive the next revenue inflection, alongside growth opportunities across Aries, Taurus, and Leo. The bull case is content growth: each new generation of AI rack can require more connectivity silicon and software. The bear case is dependence on a concentrated group of hyperscale customers, product-transition timing, and a valuation that ***** umes strong adoption before every design win becomes revenue.
Hedge-fund breadth strengthened before the rally. Insider Monkey counted 73 funds holding Astera Labs, Inc. (NASDAQ:ALAB) at June 30, up from 53 at March 31. Lee Ainslie's Maverick Capital disclosed 1,067,215 shares, 12% more than in Q1. The quarter-end filing cannot show whether Maverick participated in the September move.
Marvell is more diversified. Its data-center business spans custom compute, electro-optics, switching, and interconnect, giving it multiple ways to benefit as cloud companies redesign AI systems. That breadth is the bull case because one customer's architecture can pull several product families. It is also the risk: custom programs can be lumpy, development costs arrive before revenue, and investors may overestimate the near-term contribution of announced wins.
#september #alab
Photo from Astera Labs
Astera is the focused rack-scale connectivity play. Its second-quarter update said a Q3 production ramp of the Scorpio X-Series 320-lane fabric switch was expected to drive the next revenue inflection, alongside growth opportunities across Aries, Taurus, and Leo. The bull case is content growth: each new generation of AI rack can require more connectivity silicon and software. The bear case is dependence on a concentrated group of hyperscale customers, product-transition timing, and a valuation that ***** umes strong adoption before every design win becomes revenue.
Hedge-fund breadth strengthened before the rally. Insider Monkey counted 73 funds holding Astera Labs, Inc. (NASDAQ:ALAB) at June 30, up from 53 at March 31. Lee Ainslie's Maverick Capital disclosed 1,067,215 shares, 12% more than in Q1. The quarter-end filing cannot show whether Maverick participated in the September move.
Marvell is more diversified. Its data-center business spans custom compute, electro-optics, switching, and interconnect, giving it multiple ways to benefit as cloud companies redesign AI systems. That breadth is the bull case because one customer's architecture can pull several product families. It is also the risk: custom programs can be lumpy, development costs arrive before revenue, and investors may overestimate the near-term contribution of announced wins.
#september #alab

10 days ago
Deere & Co. (NYSE: DE) stock had a strong week, hitting a record high above $700 per share. Shares have jumped 10% since last Friday's close, according to data provided by S&P Global Market Intelligence.
After a strong fiscal third-quarter report on Aug. 20, Deere boosted the low end of its full-year net income guidance by $250 million. One ******* yst thinks that signals the start of a recovery cycle in agricultural equipment sales, and thinks Deere stock is still a buy near its record high.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Investors noticed when Deere CEO John May helped make the case for agriculture and construction stocks, stating, "As we look ahead, we continue to believe 2026 will mark the bottom of the current ag equipment cycle."
That would be welcome as companies like Deere & Co. navigate a dynamic tariff and tariff refund environment. Tariff rates have changed, and refunds have been distributed in some cases, making it difficult to set pricing and plan capital spending. But Deere is confident, citing its diversified product groups, advanced technology offerings, and what May called "stable U.S. market conditions."
#signal #market #flashing
After a strong fiscal third-quarter report on Aug. 20, Deere boosted the low end of its full-year net income guidance by $250 million. One ******* yst thinks that signals the start of a recovery cycle in agricultural equipment sales, and thinks Deere stock is still a buy near its record high.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Investors noticed when Deere CEO John May helped make the case for agriculture and construction stocks, stating, "As we look ahead, we continue to believe 2026 will mark the bottom of the current ag equipment cycle."
That would be welcome as companies like Deere & Co. navigate a dynamic tariff and tariff refund environment. Tariff rates have changed, and refunds have been distributed in some cases, making it difficult to set pricing and plan capital spending. But Deere is confident, citing its diversified product groups, advanced technology offerings, and what May called "stable U.S. market conditions."
#signal #market #flashing

10 days ago
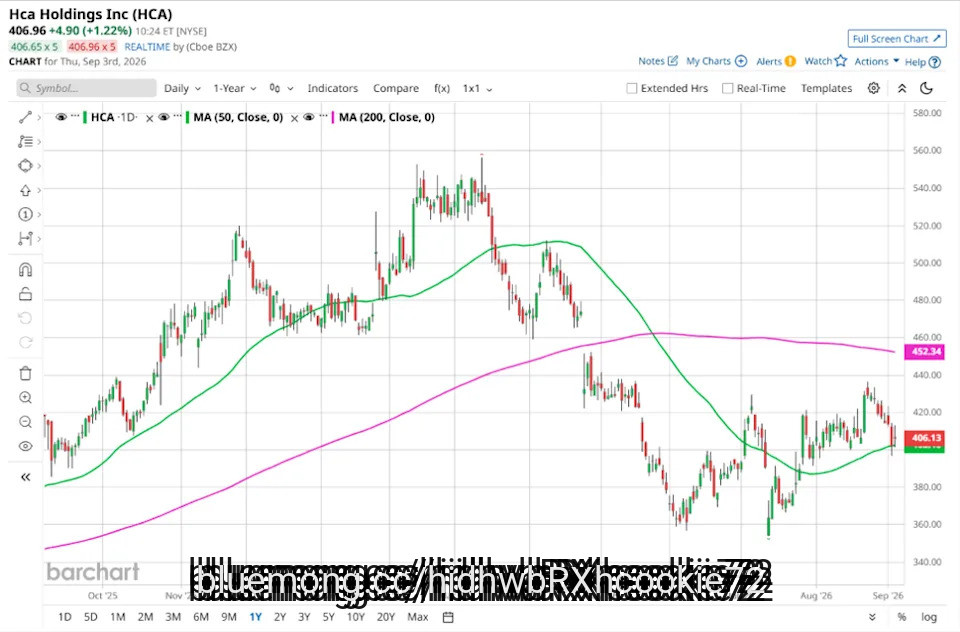
HCA Healthcare, Inc. (HCA), headquartered in Nashville, Tennessee, owns and operates hospitals and related healthcare entities. Valued at $87 billion by market cap, the company provides diagnosis, treatments, consultancy, nursing, surgeries, and other services, as well as medical education, physician resource center, and training programs.
Companies worth $10 billion or more are generally described as "large-cap stocks," and HCA definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical care facilities industry. HCA's strengths include its scale, cost leadership, and diversified portfolio. With a strong presence in high-growth states like Florida, Texas, and Tennessee, HCA leverages favorable demographics and growing healthcare demand. Its brand recognition fosters patient trust, and innovation through tech partnerships and digital health investments drives growth. HCA prioritizes talent management, positioning itself for long-term success in value-based care and telehealth trends.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ****** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#market #medical
Companies worth $10 billion or more are generally described as "large-cap stocks," and HCA definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical care facilities industry. HCA's strengths include its scale, cost leadership, and diversified portfolio. With a strong presence in high-growth states like Florida, Texas, and Tennessee, HCA leverages favorable demographics and growing healthcare demand. Its brand recognition fosters patient trust, and innovation through tech partnerships and digital health investments drives growth. HCA prioritizes talent management, positioning itself for long-term success in value-based care and telehealth trends.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ****** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#market #medical


10 days ago
Interested in Diversified Energy Company PLC? Here are five stocks we like better.
Diversified Energy agreed to acquire Birch Resources for approximately $1.8 billion, with closing expected in the fourth quarter of 2026. The deal would add 480 net wells, roughly 68,000 barrels of oil equivalent per day and 1.2 trillion cubic feet equivalent of reserves.
The acquisition would significantly expand Diversified's Permian presence, lifting production from about 9,000 to 77,000 barrels of oil equivalent per day and increasing projected Permian adjusted EBITDA from $64 million to $612 million. The ****** ets are about 70% liquids-weighted and include related infrastructure.
Diversified plans to finance the purchase mainly with ****** et-backed securities and expects operational synergies, while targeting nearly $2 billion of deleveraging over four years. The company said the transaction should increase total production by 35%, adjusted EBITDA by 55% and more than double free cash flow.
Premium Retail's Stress Test Is Separating Winners From Losers
#equivalent #energy #ebitda
Diversified Energy agreed to acquire Birch Resources for approximately $1.8 billion, with closing expected in the fourth quarter of 2026. The deal would add 480 net wells, roughly 68,000 barrels of oil equivalent per day and 1.2 trillion cubic feet equivalent of reserves.
The acquisition would significantly expand Diversified's Permian presence, lifting production from about 9,000 to 77,000 barrels of oil equivalent per day and increasing projected Permian adjusted EBITDA from $64 million to $612 million. The ****** ets are about 70% liquids-weighted and include related infrastructure.
Diversified plans to finance the purchase mainly with ****** et-backed securities and expects operational synergies, while targeting nearly $2 billion of deleveraging over four years. The company said the transaction should increase total production by 35%, adjusted EBITDA by 55% and more than double free cash flow.
Premium Retail's Stress Test Is Separating Winners From Losers
#equivalent #energy #ebitda
10 days ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ******* umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted UnitedHealth Group Incorporated (NYSE:UNH). UnitedHealth Group Incorporated (NYSE:UNH), a diversified healthcare company, contributed 2.5% to the Fund's performance during the quarter. On September 02, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $399.66 per share. Over the past month UnitedHealth Group Incorporated (NYSE:UNH) was down 1.07%, and its shares gained 28.76% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $358.73 billion and its stock has traded within a 52-week range of $255.97 - $461.62.
Eagle Capital Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group Incorporated (NYSE:UNH), Humana, Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Since returning as CEO at UnitedHealth last year, Stephen Hemsley and the management team have been correcting some of the company's missteps. Recent results provide growing evidence that the turnaround is well on track. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly e
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted UnitedHealth Group Incorporated (NYSE:UNH). UnitedHealth Group Incorporated (NYSE:UNH), a diversified healthcare company, contributed 2.5% to the Fund's performance during the quarter. On September 02, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $399.66 per share. Over the past month UnitedHealth Group Incorporated (NYSE:UNH) was down 1.07%, and its shares gained 28.76% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $358.73 billion and its stock has traded within a 52-week range of $255.97 - $461.62.
Eagle Capital Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"Managed care (13% of capital): UnitedHealth Group Incorporated (NYSE:UNH), Humana, Elevance: These managed care companies have significant scale advantages in a consolidated industry that outgrows the overall economy. The industry moves with its own cycle and, over the last several years, has faced cost/price pressures in Medicare Advantage and Medicaid. Even the largest firms are earning poor margins, and some weaker firms are unprofitable. We believe conditions have bottomed out and that we are transitioning to a multi-year improvement in margins and earnings. Al-driven technology projects can both reduce costs and improve service quality. Since returning as CEO at UnitedHealth last year, Stephen Hemsley and the management team have been correcting some of the company's missteps. Recent results provide growing evidence that the turnaround is well on track. We expect EPS growth of 15-20% over the next several years, driven by moderate revenue growth and significantly e
11 days ago
Based in Atlanta, Georgia, Intercontinental Exchange, Inc. (ICE) is a global financial markets infrastructure company that operates exchanges, clearing networks, and data services. It provides technology, market data, indexing, and mortgage technology solutions across major **** et classes, helping improve transparency, price discovery, efficiency, and decision-making. The company has a market capitalization of approximately $89.6 billion.
Companies worth $10 billion to $200 billion are generally described as "large-cap stocks," and Intercontinental Exchange definitely fits that description. Intercontinental Exchange benefits from a diversified business model spanning exchanges, fixed income and data services, and mortgage technology. Its strong technology infrastructure, NYSE ownership, brand recognition, and recurring revenue streams strengthen customer relationships, support operational efficiency, and provide resilience across different financial market conditions.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential **** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#intercontinental #technology #financial
Companies worth $10 billion to $200 billion are generally described as "large-cap stocks," and Intercontinental Exchange definitely fits that description. Intercontinental Exchange benefits from a diversified business model spanning exchanges, fixed income and data services, and mortgage technology. Its strong technology infrastructure, NYSE ownership, brand recognition, and recurring revenue streams strengthen customer relationships, support operational efficiency, and provide resilience across different financial market conditions.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential **** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#intercontinental #technology #financial

11 days ago
Boston, Massachusetts-based American Tower Corporation (AMT) is a leading global real estate investment trust (REIT) focused on communications infrastructure, primarily owning and operating wireless communications towers and other critical telecom ******* ets. With a market cap of $87.1 billion, the company leases antenna sites on multi-tenant towers for a diverse range of wireless communications industries, including personal communications services, paging, and cellular.
Companies worth $10 billion or more are generally described as "large-cap stocks," and AMT perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty REIT industry. With a large, geographically diversified portfolio of communications sites, American Tower benefits from the growing demand for wireless connectivity and data consumption. Its ******* et-heavy infrastructure business also generates recurring, long-term rental revenue, making AMT a key player in the global digital infrastructure ecosystem.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ******* eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#wireless #tower #business
Companies worth $10 billion or more are generally described as "large-cap stocks," and AMT perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty REIT industry. With a large, geographically diversified portfolio of communications sites, American Tower benefits from the growing demand for wireless connectivity and data consumption. Its ******* et-heavy infrastructure business also generates recurring, long-term rental revenue, making AMT a key player in the global digital infrastructure ecosystem.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ******* eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#wireless #tower #business



11 days ago
Billionaire David Tepper used the second quarter to make a striking trade within the AI hardware chain. Appaloosa Management cut its Micron Technology, Inc. (NASDAQ:MU) share count by 41.4%, while increasing Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) for a sixth consecutive quarter. The filing does not disclose Tepper's rationale. The positions instead contrast a cyclical HBM supplier with a diversified advanced foundry serving nearly every major chip designer. That makes the comparison about earnings durability as much as exposure to total AI demand.
Charles Knowles / Shutterstock.com
Micron Technology, Inc. (NASDAQ:MU) has a powerful rebuttal. It reported record fiscal third-quarter results as high-bandwidth memory became critical to AI accelerators. HBM requires more capacity and technical sophistication than conventional memory, potentially supporting stronger pricing and margins. If supply remains disciplined while demand expands, Micron's cycle may be structurally better than the old commodity pattern. The bear case is its planned capital spending of more than $25 billion and the possibility that today's shortages invite too much future supply.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) offers a broader toll-road thesis. Its second-quarter gross margin reached 67.7%, and the ongoing 2-nanometer ramp can deepen its lead in advanced manufacturing. It benefits whether customers favor Nvidia, AMD, custom accelerators, or other designs. However, that dominance brings enormous fabrication costs, customer concentration, geopolitical exposure, and the difficulty of maintaining exceptional margins while new capacity comes online.
The two holdings do not necessarily predict weaker AI demand. They simply provide two different ways to monetize it. Micron has greater operating leverage if HBM prices stay tight, but Taiwan Semiconductor has more diversified exposure across the entire computing stack. The first offers a sharper cyclical upside; the second offers a more durable platform with risks investors cannot ignore. That tradeoff explains why reducing one position need not invalidate its thesis.
#quarter #semiconductor
Charles Knowles / Shutterstock.com
Micron Technology, Inc. (NASDAQ:MU) has a powerful rebuttal. It reported record fiscal third-quarter results as high-bandwidth memory became critical to AI accelerators. HBM requires more capacity and technical sophistication than conventional memory, potentially supporting stronger pricing and margins. If supply remains disciplined while demand expands, Micron's cycle may be structurally better than the old commodity pattern. The bear case is its planned capital spending of more than $25 billion and the possibility that today's shortages invite too much future supply.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) offers a broader toll-road thesis. Its second-quarter gross margin reached 67.7%, and the ongoing 2-nanometer ramp can deepen its lead in advanced manufacturing. It benefits whether customers favor Nvidia, AMD, custom accelerators, or other designs. However, that dominance brings enormous fabrication costs, customer concentration, geopolitical exposure, and the difficulty of maintaining exceptional margins while new capacity comes online.
The two holdings do not necessarily predict weaker AI demand. They simply provide two different ways to monetize it. Micron has greater operating leverage if HBM prices stay tight, but Taiwan Semiconductor has more diversified exposure across the entire computing stack. The first offers a sharper cyclical upside; the second offers a more durable platform with risks investors cannot ignore. That tradeoff explains why reducing one position need not invalidate its thesis.
#quarter #semiconductor

11 days ago
Chinese diversified technology conglomerate Tencent (TCEHY) recently reported that its new artificial intelligence (AI) model performs better than models belonging to relatively newer labs like Z.AI and Moonshot. While Z.AI is known for its General Language Model (GLM), Moonshot's Kimi models have grabbed headlines following the release of its flagship K3 model.
Now, Tencent claims its Hy4 Preview has reportedly outperformed the models of these newer AI upstarts. Primarily aimed toward coding, game development, and scientific research, the model works on 770 billion parameters, has 49 billion active parameters per token, and a token context window exceeding 1 million.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#model #deal #chinese
Now, Tencent claims its Hy4 Preview has reportedly outperformed the models of these newer AI upstarts. Primarily aimed toward coding, game development, and scientific research, the model works on 770 billion parameters, has 49 billion active parameters per token, and a token context window exceeding 1 million.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#model #deal #chinese