9 days ago
Mizzou Basketball lost their exhibition game against UNLV on Thursday night. The game didn't count, so as much as I'm not going to talk up their win over Kansas State, I'm not going to talk down this loss to UNLV. Winning always feel better than losing, regardless of whether the game counts or not. But it looked like Dennis Gates was willing to make a few concessions with his lineups early. Also, Jamier Jones, CJ Gunn, and Jaylen Carey were all sidelined and not dressed out.
Anyway, here's the box score screen cap from Statbroadcast:
There are 13 players listed as having played, but I don't remember Luke Northweather seeing the floor. But there was a lot to think about, so let me try to parse through things quickly, since the 9pm tip means I'm starting this out well after 11.
My biggest takeaway was that one team played a lot harder than the other. The Tigers didn't have their full foster of players, but neither did UNLV. But you could see early the Rebels were focused on crashing the glass and being incredibly physical.
Jason Crowe played 36 minutes, Toni Bryant played 28, Aidan Chronister played 15. Those three players were able to overwhelm K-State, a team who is very focused on skill. Against UNLV the three freshmen, and not just those three but the whole roster, just got bodied by the effort of the Rebels. Lindenwood transfer Dontrez Williams, a Sikeston native, was only 1-5 from the floor and scored just 4 points, but he was +21. Mainly because he was out there playing his ****** off.
#three #didn 't #talk
Anyway, here's the box score screen cap from Statbroadcast:
There are 13 players listed as having played, but I don't remember Luke Northweather seeing the floor. But there was a lot to think about, so let me try to parse through things quickly, since the 9pm tip means I'm starting this out well after 11.
My biggest takeaway was that one team played a lot harder than the other. The Tigers didn't have their full foster of players, but neither did UNLV. But you could see early the Rebels were focused on crashing the glass and being incredibly physical.
Jason Crowe played 36 minutes, Toni Bryant played 28, Aidan Chronister played 15. Those three players were able to overwhelm K-State, a team who is very focused on skill. Against UNLV the three freshmen, and not just those three but the whole roster, just got bodied by the effort of the Rebels. Lindenwood transfer Dontrez Williams, a Sikeston native, was only 1-5 from the floor and scored just 4 points, but he was +21. Mainly because he was out there playing his ****** off.
#three #didn 't #talk


9 days ago
It's the final week of the regular season, as Alabama high school football has reached Week 10.
The 2026 AHSAA football playoffs, for the most part, are set with a lingering regional game left to be played here and there due to rescheduling issues in the wake of Hurricane Isaias.
Teams that play in Week 10 are mainly using the games as tune-up opportunities against competitive teams before postseason play begins. Others will enjoy playing their last game of the 2026 season.
Below are live scoring updates of Week 10 AHSAA football scores across the state.
#teams #play #alabama
The 2026 AHSAA football playoffs, for the most part, are set with a lingering regional game left to be played here and there due to rescheduling issues in the wake of Hurricane Isaias.
Teams that play in Week 10 are mainly using the games as tune-up opportunities against competitive teams before postseason play begins. Others will enjoy playing their last game of the 2026 season.
Below are live scoring updates of Week 10 AHSAA football scores across the state.
#teams #play #alabama

19 days ago
PARIS (AP) — The weekend of riots and looting in France did not spare soccer clubs Marseille and Lille.
The Ligue 1 teams said their shops have been vandalized during the protests against rising living costs and poor conditions in schools. Over half a million mainly peaceful protesters took to the streets on Saturday but small groups of people set fires in the streets and looted businesses in Paris, Lyon, Marseille and other cities.
Marseille said in a statement on Monday the looters caused "significant damage" to its official store located on La Canebière — the southern port city's most famous avenue — which has been temporarily closed.
Up north, Lille's city center store "suffered extensive damage and widespread looting," the club said, adding that the shop will remain closed until further notice.
Lille thanked "everyone who has offered their support over the past few hours — first and foremost, our store employees, but also the many passersby, whether supporters or not, who spontaneously stepped forward to offer their help, practical ****** istance and comfort."
#closed #ligue
The Ligue 1 teams said their shops have been vandalized during the protests against rising living costs and poor conditions in schools. Over half a million mainly peaceful protesters took to the streets on Saturday but small groups of people set fires in the streets and looted businesses in Paris, Lyon, Marseille and other cities.
Marseille said in a statement on Monday the looters caused "significant damage" to its official store located on La Canebière — the southern port city's most famous avenue — which has been temporarily closed.
Up north, Lille's city center store "suffered extensive damage and widespread looting," the club said, adding that the shop will remain closed until further notice.
Lille thanked "everyone who has offered their support over the past few hours — first and foremost, our store employees, but also the many passersby, whether supporters or not, who spontaneously stepped forward to offer their help, practical ****** istance and comfort."
#closed #ligue


1 month ago
America's older households sit on nearly $140 trillion in wealth, and much of it showed up recently.
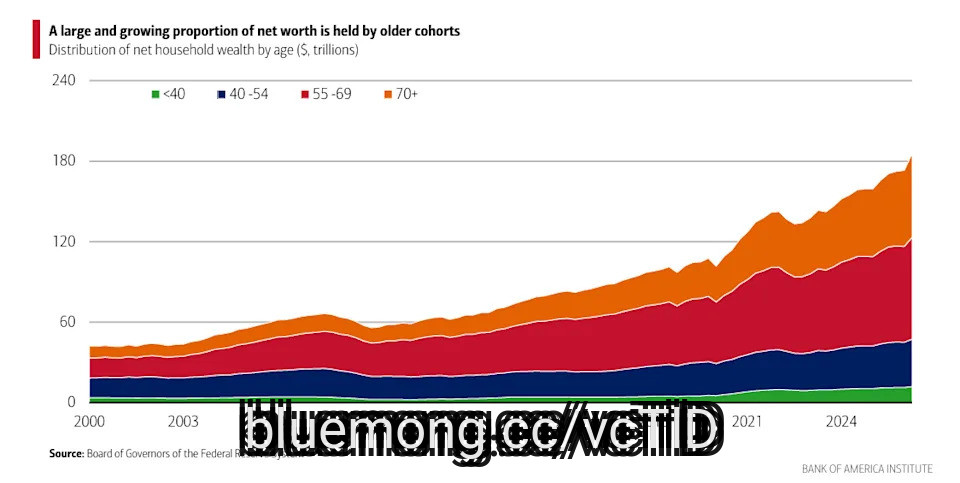
Households age 55 and over held around three-quarters of the nation's total net worth in the second quarter of 2026, according to an Oct. 1 report from Bank of America Institute, based on ******* ysis of Federal Reserve data. "With equity markets rising strongly," wrote senior economist David Michael Tinsley, those households have seen "a more than 20% increase in their net worth over the past two years."
That rally has run on AI. The Magnificent Seven accounted for more than half of the S&P 500's gains last year, Fortune reported in April, and Goldman Sachs strategists found technology stocks drove 85% of the index's return through mid-May this year. "AI-driven return has been the single most important structural driver of equity performance," Capgemini's Luca Russignan told Yahoo Finance in June. Boomers own 54% of all U.S. stocks.
That's a lopsided split. Americans 55 and over make up about 31% of the population, according to Census Bureau estimates, but control roughly 75% of its net worth.
The pile gives many older Americans what the institute calls "considerable capacity to spend on travel and other leisure categories." Add their growing share of the population and their extra free time, and they become an increasingly influential market for businesses chasing consumer dollars. The BofA report focused mainly on the economic implications of a growing mass of older consumers, but the generational wealth composition was striking.
#households #institute #according #report
Households age 55 and over held around three-quarters of the nation's total net worth in the second quarter of 2026, according to an Oct. 1 report from Bank of America Institute, based on ******* ysis of Federal Reserve data. "With equity markets rising strongly," wrote senior economist David Michael Tinsley, those households have seen "a more than 20% increase in their net worth over the past two years."
That rally has run on AI. The Magnificent Seven accounted for more than half of the S&P 500's gains last year, Fortune reported in April, and Goldman Sachs strategists found technology stocks drove 85% of the index's return through mid-May this year. "AI-driven return has been the single most important structural driver of equity performance," Capgemini's Luca Russignan told Yahoo Finance in June. Boomers own 54% of all U.S. stocks.
That's a lopsided split. Americans 55 and over make up about 31% of the population, according to Census Bureau estimates, but control roughly 75% of its net worth.
The pile gives many older Americans what the institute calls "considerable capacity to spend on travel and other leisure categories." Add their growing share of the population and their extra free time, and they become an increasingly influential market for businesses chasing consumer dollars. The BofA report focused mainly on the economic implications of a growing mass of older consumers, but the generational wealth composition was striking.
#households #institute #according #report

1 month ago
Prince Harry has faced accusations of "selling secrets" after reports suggested he is considering a documentary about his late mother, Princess Diana. Royal commentator Carole Malone made the claim while discussing Harry's reported plans to mark the 30th anniversary of Diana's death.
Harry has reportedly begun contacting people who knew Diana as he explores ways to commemorate her life and legacy. Reports suggest the Duke of Sussex could produce a documentary ahead of the 30th anniversary of Diana's death next year.
However, Malone strongly criticized the idea during the first episode of the Daily Express' Royals Unscripted. Malone claimed Harry was "100% monetising" his mother's death.
She added, "This is all Harry can do. He can only sell secrets and stories about his family. He has no career as such. He did his military service, and from all the reports, he did very well in that, but that was a long time ago. That's over, and he has nothing else to do now."
She argued that Harry's public work now focuses mostly on his family and their private experiences. She also questioned what other career options he has. The commentator said Harry did well during his military service, but noted that period of his life ended years ago. She then claimed that Harry's current opportunities mainly involve sharing stories and details about his family.
#death #diana #documentary
Harry has reportedly begun contacting people who knew Diana as he explores ways to commemorate her life and legacy. Reports suggest the Duke of Sussex could produce a documentary ahead of the 30th anniversary of Diana's death next year.
However, Malone strongly criticized the idea during the first episode of the Daily Express' Royals Unscripted. Malone claimed Harry was "100% monetising" his mother's death.
She added, "This is all Harry can do. He can only sell secrets and stories about his family. He has no career as such. He did his military service, and from all the reports, he did very well in that, but that was a long time ago. That's over, and he has nothing else to do now."
She argued that Harry's public work now focuses mostly on his family and their private experiences. She also questioned what other career options he has. The commentator said Harry did well during his military service, but noted that period of his life ended years ago. She then claimed that Harry's current opportunities mainly involve sharing stories and details about his family.
#death #diana #documentary


2 months ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

2 months ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
2 months ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
2 months ago
The shipping industry group continues to show why it's one of the best in the current stock market, with boatloads of stocks making new highs. Among them, Scorpio Tankers (STNG) and Matson (MATX) remain in buy zones.
Shares of Monaco-based Scorpio climbed above the 87.39 buy point from an 18-week pattern. The buy zone goes to 91.76. It had already climbed above resistance around 81, a level that could have been treated as an early entry.
After slumping for much of 2024 and 2025, earnings growth surged 157%, 193% and 232% the past three quarters. Sales growth accelerated 26%, 48% and 76%. Scorpio, Tuesday's IBD Stock of the Day, has a 98 IBD Composite Rating.
Matson made new highs the past week but has settled back near its 230.74 buy point from a seven-week base. The buy range goes to 242.28. The company, which mainly serves the Hawaiian islands, has a 98 Composite Rating.
Genco Shipping & Trading (GNK) is at the top of a buy range in choppy trading following a breakout past a 26.80 handle buy point. Genco is the largest U.S.-based shipper of dry-bulk commodities. Iron ore is one of its principal shipments. It made a 52-week high Thursday.
#scorpio #genco
Shares of Monaco-based Scorpio climbed above the 87.39 buy point from an 18-week pattern. The buy zone goes to 91.76. It had already climbed above resistance around 81, a level that could have been treated as an early entry.
After slumping for much of 2024 and 2025, earnings growth surged 157%, 193% and 232% the past three quarters. Sales growth accelerated 26%, 48% and 76%. Scorpio, Tuesday's IBD Stock of the Day, has a 98 IBD Composite Rating.
Matson made new highs the past week but has settled back near its 230.74 buy point from a seven-week base. The buy range goes to 242.28. The company, which mainly serves the Hawaiian islands, has a 98 Composite Rating.
Genco Shipping & Trading (GNK) is at the top of a buy range in choppy trading following a breakout past a 26.80 handle buy point. Genco is the largest U.S.-based shipper of dry-bulk commodities. Iron ore is one of its principal shipments. It made a 52-week high Thursday.
#scorpio #genco

2 months ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax
2 months ago
GE Vernova Inc. (NYSE:GEV) is trying to recover after an 8.5% decline, with Bernstein defending the stock as "wired to win" and highlighting that data centers account for only 38% of its electrification order book. This supports the argument that the company's utility exposure extends beyond AI power demand alone. That diversification is a real consideration, but it does not directly address the concern raised by GLJ Research. The firm's Sell rating is not based on doubts about AI-driven power demand. Instead, GLJ Research argues that GE Vernova is still a fundamentally cyclical gas-turbine manufacturer, while its current valuation reflects an **** umption that the ongoing boom can remain permanent.
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data
2 months ago
Wolfe Research upgraded two prominent pharmaceutical companies to Outperform on August 13. The firm upgraded both Biogen Inc. (NASDAQ:BIIB) and AbbVie Inc. (NYSE:ABBV)'s ratings from Peer Perform, with Wolfe ***** igning them similar $300 price targets. The firm's logic in each case was based on a comparable set of factors: pipelines that the market appears to undervalue, and valuations that Wolfe believes are too low given each company's growth track.
Wolfe's thesis for Biogen Inc. (NASDAQ:BIIB) is mainly based on late-stage clinical programs, which it believes the stock has yet to reflect. The firm focused on two experimental therapies in particular, both of which have key late-stage clinical readouts expected over the coming year: litifilimab, which Wolfe believes could be the first biologic approved for cutaneous lupus erythematosus, and felzartamab, which the firm claims represents a bigger commercial opportunity in antibody-mediated transplant rejection than Wall Street currently thinks.
Wolfe also cited Biogen's acquisition of Apellis Pharmaceuticals as strengthening its near-term revenue base through the FDA-approved drugs Empaveli and Syfovre. That move is part of an overall pattern of Biogen Inc. (NASDAQ:BIIB) diversifying beyond its core neurology brand, with the company completing its acquisition of RayThera on August 6, adding another early-stage immunology platform to its pipeline.
Wolfe's Biogen Inc. (NASDAQ:BIIB) thesis is incomplete without valuation. The firm believes the stock is trading at a discount to the broader market, despite the company's development on Leqembi, its Alzheimer's medication, and what Wolfe described as solid commercial execution overall.
AbbVie's upgrade is based on a slightly different premise: patent strength and cash generation rather than simple clinical events. Wolfe stated that AbbVie's 2027 earnings multiple of 14.6x seemed too low for a company that forecasts high-single-digit revenue growth for the rest of the decade. AbbVie's patent position, according to Wolfe, sets the company apart from its competitors in a way that the market has yet to completely price in.
#wolfe #firm #market #clinical
Wolfe's thesis for Biogen Inc. (NASDAQ:BIIB) is mainly based on late-stage clinical programs, which it believes the stock has yet to reflect. The firm focused on two experimental therapies in particular, both of which have key late-stage clinical readouts expected over the coming year: litifilimab, which Wolfe believes could be the first biologic approved for cutaneous lupus erythematosus, and felzartamab, which the firm claims represents a bigger commercial opportunity in antibody-mediated transplant rejection than Wall Street currently thinks.
Wolfe also cited Biogen's acquisition of Apellis Pharmaceuticals as strengthening its near-term revenue base through the FDA-approved drugs Empaveli and Syfovre. That move is part of an overall pattern of Biogen Inc. (NASDAQ:BIIB) diversifying beyond its core neurology brand, with the company completing its acquisition of RayThera on August 6, adding another early-stage immunology platform to its pipeline.
Wolfe's Biogen Inc. (NASDAQ:BIIB) thesis is incomplete without valuation. The firm believes the stock is trading at a discount to the broader market, despite the company's development on Leqembi, its Alzheimer's medication, and what Wolfe described as solid commercial execution overall.
AbbVie's upgrade is based on a slightly different premise: patent strength and cash generation rather than simple clinical events. Wolfe stated that AbbVie's 2027 earnings multiple of 14.6x seemed too low for a company that forecasts high-single-digit revenue growth for the rest of the decade. AbbVie's patent position, according to Wolfe, sets the company apart from its competitors in a way that the market has yet to completely price in.
#wolfe #firm #market #clinical


2 months ago
There's an old investing rule, popularized by investing legend Peter Lynch, to invest in what you know. It's deceptively simple advice: The better you understand a business, the better equipped you are to recognize its opportunities.
Likewise, greater knowledge of a business improves your ability to recognize things that could potentially go wrong. That second part is especially important.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
When it comes to NuScale Power (NYSE: SMR), there's one thing investors should probably know before buying the dip: what its small modular reactors (SMRs) could actually cost to operate. This isn't, to be sure, a question investors can answer with much certainty today, mainly because NuScale doesn't have a commercial reactor in operation.
That said, a newly released study, which has not yet gone through peer review, offers a sobering estimate. And if the findings hold up, the operating costs for NuScale's reactors could pose a much bigger problem to its business than previously thought.
#recognize
Likewise, greater knowledge of a business improves your ability to recognize things that could potentially go wrong. That second part is especially important.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
When it comes to NuScale Power (NYSE: SMR), there's one thing investors should probably know before buying the dip: what its small modular reactors (SMRs) could actually cost to operate. This isn't, to be sure, a question investors can answer with much certainty today, mainly because NuScale doesn't have a commercial reactor in operation.
That said, a newly released study, which has not yet gone through peer review, offers a sobering estimate. And if the findings hold up, the operating costs for NuScale's reactors could pose a much bigger problem to its business than previously thought.
#recognize


2 months ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period

2 months ago
On September 10, Zumiez Inc. (NASDAQ:ZUMZ) reported weaker-than-expected results for its second quarter ended August 1, 2026, with the results falling short of Wall Street estimates and sending the stock lower.
For the second quarter of fiscal 2026, Zumiez Inc. (NASDAQ:ZUMZ) reported net sales of $209 million, down 2.5% year-over-year. Comparable sales declined 2.1%, with the weakness mainly coming from the US. Canada, Europe, and Australia all had positive comparable sales growth for the quarter. The company said it saw strong sales growth across its international markets, but softer domestic sales and lower foot traffic weighed on overall results.
The company also posted a net loss of $2.7 million, or $0.17 per share, compared with a net loss of $1.0 million, or $0.06 per share, in the second quarter of fiscal 2025.
Third-Quarter Outlook Disappoints, But Is It All Bad?
Zumiez Inc. (NASDAQ:ZUMZ) introduced third-quarter guidance, which also failed to provide much relief as it came in below Wall Street expectations. For the three months ending October 31, 2026, the company expects net sales of $222 million to $226 million, while earnings per share are projected to range from $0.00 to $0.10.
#quarter #sales
For the second quarter of fiscal 2026, Zumiez Inc. (NASDAQ:ZUMZ) reported net sales of $209 million, down 2.5% year-over-year. Comparable sales declined 2.1%, with the weakness mainly coming from the US. Canada, Europe, and Australia all had positive comparable sales growth for the quarter. The company said it saw strong sales growth across its international markets, but softer domestic sales and lower foot traffic weighed on overall results.
The company also posted a net loss of $2.7 million, or $0.17 per share, compared with a net loss of $1.0 million, or $0.06 per share, in the second quarter of fiscal 2025.
Third-Quarter Outlook Disappoints, But Is It All Bad?
Zumiez Inc. (NASDAQ:ZUMZ) introduced third-quarter guidance, which also failed to provide much relief as it came in below Wall Street expectations. For the three months ending October 31, 2026, the company expects net sales of $222 million to $226 million, while earnings per share are projected to range from $0.00 to $0.10.
#quarter #sales

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval
2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f


2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Allison Transmission Holdings, Inc. (NYSE:ALSN). Allison Transmission Holdings, Inc. (NYSE:ALSN) is a manufacturer of commercial-duty automatic transmissions and hybrid propulsion systems for medium- and heavy-duty vehicles. On September 14, 2026, Allison Transmission Holdings, Inc. (NYSE:ALSN) closed at $123.49 per share. Over the past month, Allison Transmission Holdings, Inc. (NYSE:ALSN) declined 1.56%, but its shares are up 40.84% over the past year. Allison Transmission Holdings, Inc. (NYSE:ALSN) has a market capitalization of $10.2 billion, and its stock has traded within a 52-week range of $76.01 to $137.62.
Fidelity Dividend Growth Fund stated the following regarding Allison Transmission Holdings, Inc. (NYSE:ALSN) in its Q2 2026 investor letter:
"Elsewhere in the industrials sector, Allison Transmission Holdings, Inc. (NYSE:ALSN) was another meaningful overweight at the end of June. This provider of automatic transmissions for medium- and heavy-duty vehicles has continued to benefit from accelerating industrial activity, driven by federal support for infrastructure and onshoring. In January, the company completed a major acquisition with the purchase of the Off-Highway Drive & Motion Systems business of Dana Incorporated, a leading provider of drivetrain and propulsion solutions. We like the prospects for this acquisition."
Allison Transmission Holdings, Inc. (NYSE:ALSN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 48 hedge fund portfolios held Allison Transmission Holdings, Inc. (NYSE:ALSN) at the end of the second quarter, which was 44 in the previous quarter. While we acknowledge the potential of Allison Transmission Holdings, Inc. (NYSE:ALSN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely underval

2 months ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Western Digital Corporation (NASDAQ:WDC). Western Digital Corporation (NASDAQ:WDC) is a data storage company that engages in the manufacturing and distribution of data storage devices and solutions based on hard disk drive (HDD) technology. On September 14, 2026, Western Digital Corporation (NASDAQ:WDC) closed at $426.94 per share. Over the past month, Western Digital Corporation (NASDAQ:WDC) declined 13.95%, and its shares are up 314.14% over the past year. Western Digital Corporation (NASDAQ:WDC) has a market capitalization of $153.93 billion, and its stock has traded within a 52-week range of $93.92 to $799.87.
Fidelity Dividend Growth Fund stated the following regarding Western Digital Corporation (NASDAQ:WDC) in its Q2 2026 investor letter:
"Among individual holdings, a sizable overweight in Western Digital Corporation (NASDAQ:WDC) (+140%) topped the list of relative contributors. In late April, the data-storage maker reported better-than-expected quarterly financial results, including higher earnings and gross profit margin. In its report, management said brisk demand for the firm's storage solutions for AI capabilities contributed to the solid quarter. Also, the company raised its financial guidance."
Western Digital Corporation (NASDAQ:WDC) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 98 hedge fund portfolios held Western Digital Corporation (NASDAQ:WDC) at the end of the second quarter, up from 83 in the previous quarter. While we acknowledge the potential of Western Digital Corporation (NASDAQ:WDC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-te

2 months ago
New vehicle sales in Indonesia surged by a further 32% year-on-year to 81,756 units in August 2026, up from weak year-earlier sales of 61,771 units, according to wholesale data compiled by the local automotive industry ***** ociation, Gaikindo. The market last month was driven higher by strong demand for trucks and battery electric vehicles (BEVs).
In the first eight months of 2026, the country's vehicle market expanded by 20% to 599,491 units, after declining by 11% to 499,315 units a year earlier, with sales of light passenger vehicles rising by over 13% to 437,374 units, while commercial vehicle sales increased by 42% to 162,117 units, driven by a 54% surge in light- and medium-duty trucks to 131,813 units.
The truck market this year has been supported by government plans to procure vehicles to support the development of rural cooperatives and improve local logistics networks nationwide.
Sales of BEVs almost doubled to 103,300 units year-to-date, up from 53,100 units in the same period a year earlier, driven by Chinese brands and supported by government tax incentives.
GDP growth moderated to 5.3% year-on-year in the second quarter of 2026, down from a peak of 5.6% in the first quarter, underpinned mainly by strong government spending and investment. Private consumption growth slowed to 5.1% from 5.5%, after the central bank hiked its benchmark interest rate by 100 basis points to 5.75% in the second quarter to support the rupiah and rein in rising inflation. Government spending grew by 16%, down from a peak of 22%, driven by social programmes and rising fuel subsidy costs.
#year
In the first eight months of 2026, the country's vehicle market expanded by 20% to 599,491 units, after declining by 11% to 499,315 units a year earlier, with sales of light passenger vehicles rising by over 13% to 437,374 units, while commercial vehicle sales increased by 42% to 162,117 units, driven by a 54% surge in light- and medium-duty trucks to 131,813 units.
The truck market this year has been supported by government plans to procure vehicles to support the development of rural cooperatives and improve local logistics networks nationwide.
Sales of BEVs almost doubled to 103,300 units year-to-date, up from 53,100 units in the same period a year earlier, driven by Chinese brands and supported by government tax incentives.
GDP growth moderated to 5.3% year-on-year in the second quarter of 2026, down from a peak of 5.6% in the first quarter, underpinned mainly by strong government spending and investment. Private consumption growth slowed to 5.1% from 5.5%, after the central bank hiked its benchmark interest rate by 100 basis points to 5.75% in the second quarter to support the rupiah and rein in rising inflation. Government spending grew by 16%, down from a peak of 22%, driven by social programmes and rising fuel subsidy costs.
#year

2 months ago
Interested in Johnson & Johnson? Here are five stocks we like better.
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested

2 months ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company

2 months ago
Led by Elliot Anderson, reloaded Man City midfield gets first chance to impress in Manchester derby originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
Manchester City were one of the biggest spenders in the free-wheeling 2026 summer transfer window, as the Premier League side made a host of big-money moves ahead of the current season.
Always known as one of the most lavish clubs in the world with their transfer budget, they went especially big this summer as they looked to refurbish the squad in a period of transition after the departure of legendary manager Pep Guardiola.
The club mainly focused on the central midfield position, where multiple key players departed and an immediate refresh was needed to keep the club's levels up.
With the new players now slotting into their established roles and Enzo Maresca's system beginning to become evident, Sunday's Manchester derby at Old Trafford is the perfect showcase for all the pieces to finally come together.
#manchester #transfer #players
Manchester City were one of the biggest spenders in the free-wheeling 2026 summer transfer window, as the Premier League side made a host of big-money moves ahead of the current season.
Always known as one of the most lavish clubs in the world with their transfer budget, they went especially big this summer as they looked to refurbish the squad in a period of transition after the departure of legendary manager Pep Guardiola.
The club mainly focused on the central midfield position, where multiple key players departed and an immediate refresh was needed to keep the club's levels up.
With the new players now slotting into their established roles and Enzo Maresca's system beginning to become evident, Sunday's Manchester derby at Old Trafford is the perfect showcase for all the pieces to finally come together.
#manchester #transfer #players


2 months ago
On September 8, ServiceTitan, Inc. (NASDAQ:TTAN) reported its fiscal second-quarter financial results, which showed impressive growth. The company's revenue increased 21% year-over-year to $292.8 million and non-GAAP free cash flow reached a record $50.5 million. The company's non-GAAP operating margin also improved to 15.2%.
A key highlight of the quarter was the growing adoption of ServiceTitan, Inc.'s (NASDAQ:TTAN) AI-powered Max package. The company exceeded its target as the number of Max locations more than doubled during the quarter. It now expects to reach more than 700 Max locations by the end of the fiscal year.
The company also said that it is currently focusing on Max and AI, as these represent the highest return on investment. However, this also means that the company is deferring expansion into new commercial trades.
GTV Growth Slows Despite Strong Results
While overall results were solid, ServiceTitan, Inc. (NASDAQ:TTAN) saw some moderation in gross transaction volume (GTV) growth. GTV increased 17% year-over-year in the fiscal second quarter, down from the 23% growth seen in the first quarter. The company attributed the slower growth mainly to lower lead volumes among customers, particularly in the HVAC market.
#NASDAQ
A key highlight of the quarter was the growing adoption of ServiceTitan, Inc.'s (NASDAQ:TTAN) AI-powered Max package. The company exceeded its target as the number of Max locations more than doubled during the quarter. It now expects to reach more than 700 Max locations by the end of the fiscal year.
The company also said that it is currently focusing on Max and AI, as these represent the highest return on investment. However, this also means that the company is deferring expansion into new commercial trades.
GTV Growth Slows Despite Strong Results
While overall results were solid, ServiceTitan, Inc. (NASDAQ:TTAN) saw some moderation in gross transaction volume (GTV) growth. GTV increased 17% year-over-year in the fiscal second quarter, down from the 23% growth seen in the first quarter. The company attributed the slower growth mainly to lower lead volumes among customers, particularly in the HVAC market.
#NASDAQ

2 months ago
Braze, Inc. (NASDAQ:BRZE) reported strong Q2 results on September 8, but investors appeared more focused on the company's outlook. Despite the solid performance, the company's shares had fallen sharply following the earnings report, declining nearly 20% in the September 9 session.
In its second quarter of fiscal 2027, the company generated $227.2 million in revenue, up 26.2% year-over-year. Braze, Inc. (NASDAQ:BRZE) said growth was mainly driven by new customers, along with upsells and renewals from existing customers. Subscription revenue increased 21% to reach $207.7 million.
Non-GAAP net income also improved 26% to more than $21.23 million, or $0.19 per share. Revenue and adjusted earnings were ahead of Wall Street expectations. **** ysts were expecting Braze, Inc. (NASDAQ:BRZE) to report revenue of slightly more than $220 million and adjusted earnings of $0.15 per share.
The company also showed improvement in its cash generation as it reported record second-quarter cash flow from operations of $24 million and free cash flow of $22 million.
Guidance Becomes the Main Concern
#september
In its second quarter of fiscal 2027, the company generated $227.2 million in revenue, up 26.2% year-over-year. Braze, Inc. (NASDAQ:BRZE) said growth was mainly driven by new customers, along with upsells and renewals from existing customers. Subscription revenue increased 21% to reach $207.7 million.
Non-GAAP net income also improved 26% to more than $21.23 million, or $0.19 per share. Revenue and adjusted earnings were ahead of Wall Street expectations. **** ysts were expecting Braze, Inc. (NASDAQ:BRZE) to report revenue of slightly more than $220 million and adjusted earnings of $0.15 per share.
The company also showed improvement in its cash generation as it reported record second-quarter cash flow from operations of $24 million and free cash flow of $22 million.
Guidance Becomes the Main Concern
#september


2 months ago
Ollie's Bargain Outlet Holdings Inc.'s (NASDAQ:OLLI) second quarter results were characterized by robust loyalty membership growth, store count expansion, and a notable boost in earnings despite weakness in comparable store sales. During the quarter, the retailer opened 15 new locations and shut down one store because of storm-related damages. This pushed its overall store count to 686 across 36 states, a year-over-year jump of 11.9%. The ongoing growth in its store network continues to be the core focus of Ollie's expansion roadmap, as the management recently confirmed its plans to open 75 new stores by the end of this fiscal year. Such a strategy strongly reflects on the extended growth potential of Ollie's existing business model.
Photo by Franki Chamaki on Unsplash
The company's loyalty program, Ollie's Army, continued to gain momentum during the recent quarter, raising its reach to 18.1 million members. This helped push net sales higher by 9.1% to $741.3 million, with the gain coming mainly from newly opened stores rather than sales at existing locations. Even with comparable sales trending downward, key profitability figures showed clear improvement.
With lower supply chain-related costs, gross margins expanded to 43.5%. A key factor behind this jump was the IEEPA tariff refunds, which contributed 380 basis points to gross margin on their own, in addition to broader reductions in tariff rates. This tariff-related benefit served as a meaningful cushion, helping to overcome the drop in comparable sales.
Together, these factors fueled substantial growth in the bottom line as the adjusted net income climbed 40.3% to $85.4 million, and adjusted net income per diluted share rose 43.4% to $1.42. This represented an outsized growth compared to overall sales growth, which highlights the impact of tariff refunds and margin improvements on the overall results.
#Growth #tariff
Photo by Franki Chamaki on Unsplash
The company's loyalty program, Ollie's Army, continued to gain momentum during the recent quarter, raising its reach to 18.1 million members. This helped push net sales higher by 9.1% to $741.3 million, with the gain coming mainly from newly opened stores rather than sales at existing locations. Even with comparable sales trending downward, key profitability figures showed clear improvement.
With lower supply chain-related costs, gross margins expanded to 43.5%. A key factor behind this jump was the IEEPA tariff refunds, which contributed 380 basis points to gross margin on their own, in addition to broader reductions in tariff rates. This tariff-related benefit served as a meaningful cushion, helping to overcome the drop in comparable sales.
Together, these factors fueled substantial growth in the bottom line as the adjusted net income climbed 40.3% to $85.4 million, and adjusted net income per diluted share rose 43.4% to $1.42. This represented an outsized growth compared to overall sales growth, which highlights the impact of tariff refunds and margin improvements on the overall results.
#Growth #tariff