

6 mins. ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve doesn't set student loan rates directly, but its federal funds rate influences the 10-year Treasury yield (which determines federal loan rates) and the prime rate (which determines private loan rates).
But exactly how the Fed affects your cost of borrowing depends on the type of student loans and interest rate you have.
After the Federal Reserve's September 2026 meeting, it raised interest rates by 25 basis points. See how that might impact the cost of your student loans.
One of the Federal Reserve's main goals is to keep inflation under control. It does this partly by adjusting the federal funds rate — the rate banks charge one another for short-term loans.
#funds
The Federal Reserve doesn't set student loan rates directly, but its federal funds rate influences the 10-year Treasury yield (which determines federal loan rates) and the prime rate (which determines private loan rates).
But exactly how the Fed affects your cost of borrowing depends on the type of student loans and interest rate you have.
After the Federal Reserve's September 2026 meeting, it raised interest rates by 25 basis points. See how that might impact the cost of your student loans.
One of the Federal Reserve's main goals is to keep inflation under control. It does this partly by adjusting the federal funds rate — the rate banks charge one another for short-term loans.
#funds


53 mins. ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Today, the Federal Reserve increased its target interest rate by 25 basis points — its first rate hike in more than three years.
When the Fed changes interest rates, the impact reaches far beyond Wall Street. Higher rates can help savers earn more on their cash, while lower rates can make mortgages, car loans, and credit cards more affordable. But because every rate move creates both winners and losers, there's no simple answer to whether high or low rates are best.
Understanding why the Fed raises and lowers rates — and how those decisions affect your money — can help you make smarter choices about saving and borrowing.
The Federal Reserve is mandated by Congress to promote stable prices and maximum employment within the U.S. economy. One of the tools it has at its disposal to achieve these goals is the federal funds rate.
#federal #reserve #interest #make
Today, the Federal Reserve increased its target interest rate by 25 basis points — its first rate hike in more than three years.
When the Fed changes interest rates, the impact reaches far beyond Wall Street. Higher rates can help savers earn more on their cash, while lower rates can make mortgages, car loans, and credit cards more affordable. But because every rate move creates both winners and losers, there's no simple answer to whether high or low rates are best.
Understanding why the Fed raises and lowers rates — and how those decisions affect your money — can help you make smarter choices about saving and borrowing.
The Federal Reserve is mandated by Congress to promote stable prices and maximum employment within the U.S. economy. One of the tools it has at its disposal to achieve these goals is the federal funds rate.
#federal #reserve #interest #make



56 mins. ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#federal #rates #loans
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#federal #rates #loans


1 hr. ago
Sept 16 (Reuters) - Top U.S. banks raised their prime lending rate on Wednesday after the Federal Reserve lifted its benchmark interest rate, a move that would increase borrowing costs for consumers and businesses with loans.
Following the Fed's first rate hike since 2023, the prime rate of JPMorgan , Bank of America, Citigroup, Wells Fargo, KeyCorp, Huntington Bancshares, Fifth Third Bancorp and Truist Financial from Thursday will rise to 7% from 6.75%.
The Fed raised rates by a quarter of a percentage point on Wednesday and flagged further increases in borrowing costs in the coming months as policymakers focus on addressing persistent inflation.
Shares of big banks ended lower amid broader weakness in U.S. stocks. BofA closed down 2.7%, Citi 2.4%, Wells Fargo 3%, and JPMorgan 1%. Morgan Stanley slipped 1.9% and Goldman Sachs fell 4%.
The prime rate, which follows the federal funds rate, is used by U.S. banks as a reference for setting rates on many financial products such as credit cards and personal loans.
#prime #jpmorgan #raised
Following the Fed's first rate hike since 2023, the prime rate of JPMorgan , Bank of America, Citigroup, Wells Fargo, KeyCorp, Huntington Bancshares, Fifth Third Bancorp and Truist Financial from Thursday will rise to 7% from 6.75%.
The Fed raised rates by a quarter of a percentage point on Wednesday and flagged further increases in borrowing costs in the coming months as policymakers focus on addressing persistent inflation.
Shares of big banks ended lower amid broader weakness in U.S. stocks. BofA closed down 2.7%, Citi 2.4%, Wells Fargo 3%, and JPMorgan 1%. Morgan Stanley slipped 1.9% and Goldman Sachs fell 4%.
The prime rate, which follows the federal funds rate, is used by U.S. banks as a reference for setting rates on many financial products such as credit cards and personal loans.
#prime #jpmorgan #raised

2 hours ago
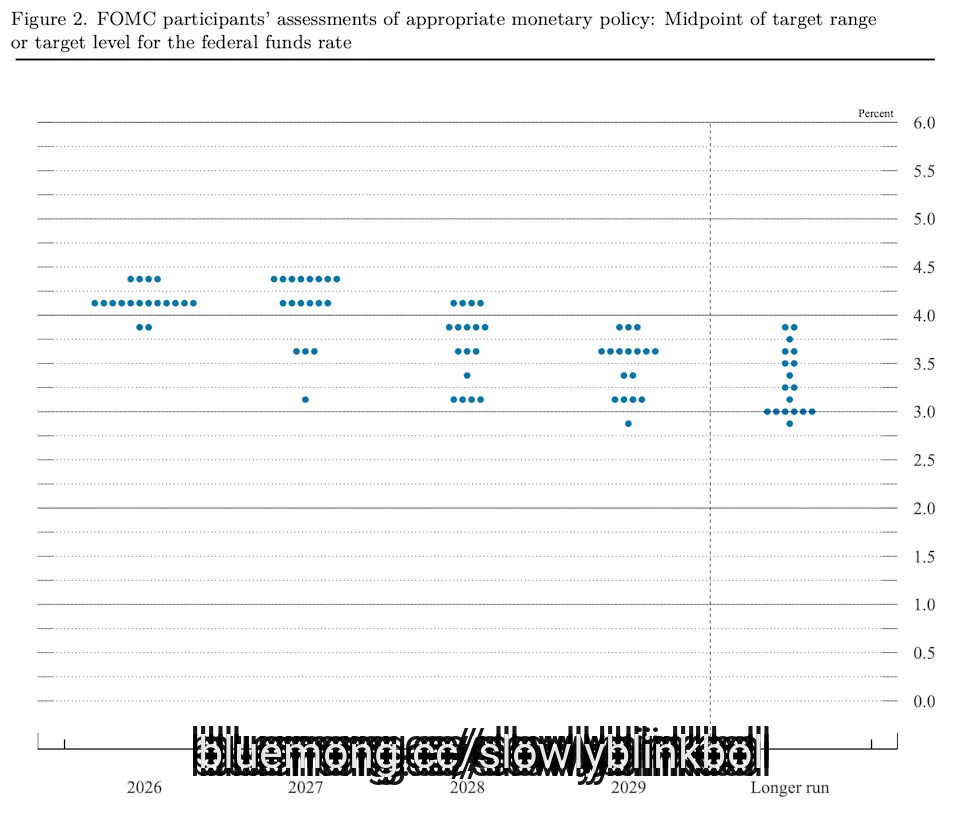
The Federal Reserve voted to raise interest rates by 25 basis points on Wednesday to a range of 3.75%-4% amid persistently high inflation. The decision was unanimous.
The median Fed official expects one more rate hike this year, according to the central bank's Summary of Economic Projections, also known as the dot plot.
The move was the Fed's first increase in the fed funds rate since 2023, when the Jerome Powell-led central bank concluded its post-pandemic hiking campaign. It was also largely priced in by the market, even as Federal Reserve Chairman Kevin Warsh has been adamant about not providing markets with forward guidance.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
Stocks were little changed when the decision was first announced but turned lower during Warsh's brief press conference.
#rate
The median Fed official expects one more rate hike this year, according to the central bank's Summary of Economic Projections, also known as the dot plot.
The move was the Fed's first increase in the fed funds rate since 2023, when the Jerome Powell-led central bank concluded its post-pandemic hiking campaign. It was also largely priced in by the market, even as Federal Reserve Chairman Kevin Warsh has been adamant about not providing markets with forward guidance.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
Stocks were little changed when the decision was first announced but turned lower during Warsh's brief press conference.
#rate

2 hours ago
Monthly car payments continue to hit record levels for both new and used cars.
The overall cost of car ownership remains elevated due to steep insurance and car maintenance prices in addition to the cost of a loan.
Good credit scores are key to qualifying for the best auto loan rates and driving away with a competitive monthly payment.
New car prices remain steep, with monthly payments for new cars soaring to the highest levels ever recorded. Amid this environment, buyers are taking on increasingly larger loans to make vehicle purchases, and some are also stretching repayment over a longer timeline — in some cases, up to seven years.
Whether you have poor credit or are looking to refinance your current loan, it's important to understand typical monthly payments and rates so you can feel confident that you are getting the best deal. While auto loan rates in 2026 are projected to lower slightly, it won't be enough to put a serious dent in the many factors that are driving up the cost of car ownership, including continued high cost of auto insurance and maintenance expenses.
#payments #rates #levels #ownership
The overall cost of car ownership remains elevated due to steep insurance and car maintenance prices in addition to the cost of a loan.
Good credit scores are key to qualifying for the best auto loan rates and driving away with a competitive monthly payment.
New car prices remain steep, with monthly payments for new cars soaring to the highest levels ever recorded. Amid this environment, buyers are taking on increasingly larger loans to make vehicle purchases, and some are also stretching repayment over a longer timeline — in some cases, up to seven years.
Whether you have poor credit or are looking to refinance your current loan, it's important to understand typical monthly payments and rates so you can feel confident that you are getting the best deal. While auto loan rates in 2026 are projected to lower slightly, it won't be enough to put a serious dent in the many factors that are driving up the cost of car ownership, including continued high cost of auto insurance and maintenance expenses.
#payments #rates #levels #ownership

3 hours ago
The financial unraveling of Jon Venetos' Lurin Capital is now the subject of a Federal Bureau of Investigation probe.
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.
#email
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.

3 hours ago
While the average personal loan interest rate is 12.44%, borrowers with excellent credit may have access to rates as low as 5.96%.
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.64% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting just below 6%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#average #rates #lowest #borrowing
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.64% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting just below 6%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#average #rates #lowest #borrowing

3 hours ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve — the country's central bank — periodically adjusts its target rate to keep the economy running smoothly and consumer prices in check. When the federal funds rate moves up or down, so do the interest rates on bank accounts and loans.
In other words, changes in the Fed's rate impact how much your savings can grow and how much you pay to borrow money.
So how does today's federal funds rate compare to past years? Here's a look at historical Fed interest rates so you can better understand how your bottom line is affected.
The federal funds rate is set by the Federal Reserve and dictates what a bank can charge another bank for ultra-short-term loans (usually overnight) in order to meet reserve requirements. It's expressed as a range, and financial institutions can negotiate a specific rate between each other within that range.
#federal #funds #rates
The Federal Reserve — the country's central bank — periodically adjusts its target rate to keep the economy running smoothly and consumer prices in check. When the federal funds rate moves up or down, so do the interest rates on bank accounts and loans.
In other words, changes in the Fed's rate impact how much your savings can grow and how much you pay to borrow money.
So how does today's federal funds rate compare to past years? Here's a look at historical Fed interest rates so you can better understand how your bottom line is affected.
The federal funds rate is set by the Federal Reserve and dictates what a bank can charge another bank for ultra-short-term loans (usually overnight) in order to meet reserve requirements. It's expressed as a range, and financial institutions can negotiate a specific rate between each other within that range.
#federal #funds #rates

4 hours ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Today, the Federal Reserve increased its target interest rate by 25 basis points — its first rate hike in more than three years.
When the Fed changes interest rates, the impact reaches far beyond Wall Street. Higher rates can help savers earn more on their cash, while lower rates can make mortgages, car loans, and credit cards more affordable. But because every rate move creates both winners and losers, there's no simple answer to whether high or low rates are best.
Understanding why the Fed raises and lowers rates — and how those decisions affect your money — can help you make smarter choices about saving and borrowing.
The Federal Reserve is mandated by Congress to promote stable prices and maximum employment within the U.S. economy. One of the tools it has at its disposal to achieve these goals is the federal funds rate.
#federal #interest #disclosure
Today, the Federal Reserve increased its target interest rate by 25 basis points — its first rate hike in more than three years.
When the Fed changes interest rates, the impact reaches far beyond Wall Street. Higher rates can help savers earn more on their cash, while lower rates can make mortgages, car loans, and credit cards more affordable. But because every rate move creates both winners and losers, there's no simple answer to whether high or low rates are best.
Understanding why the Fed raises and lowers rates — and how those decisions affect your money — can help you make smarter choices about saving and borrowing.
The Federal Reserve is mandated by Congress to promote stable prices and maximum employment within the U.S. economy. One of the tools it has at its disposal to achieve these goals is the federal funds rate.
#federal #interest #disclosure

5 hours ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#Consumer
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#Consumer


5 hours ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve doesn't set student loan rates directly, but its federal funds rate influences the 10-year Treasury yield (which determines federal loan rates) and the prime rate (which determines private loan rates).
But exactly how the Fed affects your cost of borrowing depends on the type of student loans and interest rate you have.
After the Federal Reserve's September 2026 meeting, it raised interest rates by 25 basis points. See how that might impact the cost of your student loans.
One of the Federal Reserve's main goals is to keep inflation under control. It does this partly by adjusting the federal funds rate — the rate banks charge one another for short-term loans.
#rate #loan #determines #interest
The Federal Reserve doesn't set student loan rates directly, but its federal funds rate influences the 10-year Treasury yield (which determines federal loan rates) and the prime rate (which determines private loan rates).
But exactly how the Fed affects your cost of borrowing depends on the type of student loans and interest rate you have.
After the Federal Reserve's September 2026 meeting, it raised interest rates by 25 basis points. See how that might impact the cost of your student loans.
One of the Federal Reserve's main goals is to keep inflation under control. It does this partly by adjusting the federal funds rate — the rate banks charge one another for short-term loans.
#rate #loan #determines #interest

5 hours ago
Amazon raised minimum starting pay for its U.S. full-time core operations employees to $20 an hour on Wednesday, a $1-per-hour increase for front-line workers who sort, pack, and transport orders.
Amazon said the typical hourly rate for those workers climbs to nearly $24, and that when benefits are counted, total compensation comes out to more than $32 an hour. Amazon said its minimum starting pay has risen more than 17% over the past three years.
The announcement arrives as Amazon approaches the peak holiday shopping season. According to The Wall Street Journal, Amazon hired 250,000 full-time, part-time, and seasonal workers in advance of last year's holiday period.
Along with the pay increase, Amazon announced two new benefits. Beginning Oct. 1, all U.S. Amazon employees will receive a grocery discount — 10% off eligible groceries and everyday essentials on Amazon.com and Whole Foods Market online, and 20% off in-store at Whole Foods. The discount can be combined with existing Prime member discounts, the company said.
Amazon also said it is launching a banking benefit called Day 1 Financial, through which qualified employees and their families can obtain a lifelong membership in First Tech Federal Credit Union. The benefit includes accounts with no overdraft fees, no monthly maintenance fees, and no account minimums, as well as access to credit cards, auto loans, and home loans for those who qualify. The company said the rollout will start in late 2026, with broad availability expected in 2027.
#time #employees #credit #starting
Amazon said the typical hourly rate for those workers climbs to nearly $24, and that when benefits are counted, total compensation comes out to more than $32 an hour. Amazon said its minimum starting pay has risen more than 17% over the past three years.
The announcement arrives as Amazon approaches the peak holiday shopping season. According to The Wall Street Journal, Amazon hired 250,000 full-time, part-time, and seasonal workers in advance of last year's holiday period.
Along with the pay increase, Amazon announced two new benefits. Beginning Oct. 1, all U.S. Amazon employees will receive a grocery discount — 10% off eligible groceries and everyday essentials on Amazon.com and Whole Foods Market online, and 20% off in-store at Whole Foods. The discount can be combined with existing Prime member discounts, the company said.
Amazon also said it is launching a banking benefit called Day 1 Financial, through which qualified employees and their families can obtain a lifelong membership in First Tech Federal Credit Union. The benefit includes accounts with no overdraft fees, no monthly maintenance fees, and no account minimums, as well as access to credit cards, auto loans, and home loans for those who qualify. The company said the rollout will start in late 2026, with broad availability expected in 2027.
#time #employees #credit #starting


12 hours ago
Welltower and Ventas posted SHOP NOI growth of 20.5% and 16.3%, respectively, as senior occupancy rates climb and new supply starts remain at record lows.
Roughly 2 million people turn 80 in 2026, and Ventas CEO Debra Cafaro says the senior population growth rate will more than double over the next decade.
OHI's 5.68% yield carries real tenant risk: Genesis Healthcare is in Chapter 11 with $148 million in loans outstanding and the CEO is retiring.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing and skilled nursing REITs are riding a demographic tide that shows up in the operating data. Roughly two million people will turn 80 in 2026 alone, and Ventas Chair and CEO Debra A. Cafaro told investors that "the leading edge of the nearly 70 million baby boomers has just begun turning 80 this year, ushering in a decade where the growth rate of the senior population more than doubles, yet new starts remain at record lows." Four US-listed equity REITs sit squarely in that trade. Dividend safety leads the **** ysis, so every payout is measured against FFO or AFFO, not GAAP earnings.
#ventas #welltower
Roughly 2 million people turn 80 in 2026, and Ventas CEO Debra Cafaro says the senior population growth rate will more than double over the next decade.
OHI's 5.68% yield carries real tenant risk: Genesis Healthcare is in Chapter 11 with $148 million in loans outstanding and the CEO is retiring.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing and skilled nursing REITs are riding a demographic tide that shows up in the operating data. Roughly two million people will turn 80 in 2026 alone, and Ventas Chair and CEO Debra A. Cafaro told investors that "the leading edge of the nearly 70 million baby boomers has just begun turning 80 this year, ushering in a decade where the growth rate of the senior population more than doubles, yet new starts remain at record lows." Four US-listed equity REITs sit squarely in that trade. Dividend safety leads the **** ysis, so every payout is measured against FFO or AFFO, not GAAP earnings.
#ventas #welltower

1 day ago
When a caller inquired about SoFi Technologies, Inc. (NASDAQ:SOFI) during the September 10 episode of Mad Money, Jim Cramer commented:
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge


1 day ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
At the beginning of 2026, the biggest question surrounding the Federal Reserve and interest rates was whether the Fed would cut its target rate at some point this year. However, it's become increasingly clear that a rate cut won't happen any time soon. In fact, it's possible that the Fed may increase its benchmark rate before the year is over.
Following the Federal Open Market Committee (FOMC)'s most recent meeting in July, under the leadership of new Fed Chair Kevin Warsh, the committee announced its decision to maintain the target range for the federal funds rate at 3.50%-3.75%.
In its statement, the committee noted that "inflation remains elevated relative to the Committee's 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability."
The Fed has not cut rates since late 2025, yet interest rates on consumer loans and bank accounts steadily decreased throughout 2026 — at least, until recently. Recent rate increases are a sign that the market is already pricing in a rate hike. And with a few more Fed meetings on the calendar for the remainder of 2026, consumers are wondering how potential rate changes could impact their bottom lines.
#year
At the beginning of 2026, the biggest question surrounding the Federal Reserve and interest rates was whether the Fed would cut its target rate at some point this year. However, it's become increasingly clear that a rate cut won't happen any time soon. In fact, it's possible that the Fed may increase its benchmark rate before the year is over.
Following the Federal Open Market Committee (FOMC)'s most recent meeting in July, under the leadership of new Fed Chair Kevin Warsh, the committee announced its decision to maintain the target range for the federal funds rate at 3.50%-3.75%.
In its statement, the committee noted that "inflation remains elevated relative to the Committee's 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability."
The Fed has not cut rates since late 2025, yet interest rates on consumer loans and bank accounts steadily decreased throughout 2026 — at least, until recently. Recent rate increases are a sign that the market is already pricing in a rate hike. And with a few more Fed meetings on the calendar for the remainder of 2026, consumers are wondering how potential rate changes could impact their bottom lines.
#year

1 day ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ***** ysis delivered straight to their inbox with the free CRE Daily newsletter.
Dallas, Tarrant, and Collin county records show 1,197 commercial and multifamily loans totaling $13.3 billion maturing over the next 12 months, with another $12.5 billion in loans already past their maturity date.
Only 3 of the 1,197 forward-maturing loans carry a recorded distress filing, underscoring how little of the real risk shows up in public records before a loan actually fails.
The wall stems from two colliding loan vintages: roughly $4.3 billion in 2016-2017 peak-era loans and $2.6 billion in short-term bridge debt originated since 2025.
DFW loan maturities over the next 12 months total $13.3 billion, according to a county-by-county read of deed of trust records by Circlemark. That's on top of $12.5 billion in loans that have already passed their stated maturity date and remain open. Circlemark, which reads scanned county clerk instruments rather than relying on servicer-reported data, calls its own $13.3 billion figure a floor, not a ceiling.
#records
Dallas, Tarrant, and Collin county records show 1,197 commercial and multifamily loans totaling $13.3 billion maturing over the next 12 months, with another $12.5 billion in loans already past their maturity date.
Only 3 of the 1,197 forward-maturing loans carry a recorded distress filing, underscoring how little of the real risk shows up in public records before a loan actually fails.
The wall stems from two colliding loan vintages: roughly $4.3 billion in 2016-2017 peak-era loans and $2.6 billion in short-term bridge debt originated since 2025.
DFW loan maturities over the next 12 months total $13.3 billion, according to a county-by-county read of deed of trust records by Circlemark. That's on top of $12.5 billion in loans that have already passed their stated maturity date and remain open. Circlemark, which reads scanned county clerk instruments rather than relying on servicer-reported data, calls its own $13.3 billion figure a floor, not a ceiling.
#records

1 day ago
The CoinEx crypto exchange is shutting down its operations after nine years, citing a "prolonged" crypto market downturn, shrinking trading activity and rising compliance costs across major jurisdictions.
The exchange said the wind-down will begin on Sep. 15, with services being withdrawn in stages before the platform closes completely on Dec. 22.
Related: Coinbase CEO doubles down on bullish Bitcoin target
CoinEx will immediately stop new user registrations, referral commissions and several new product subscriptions. Futures markets are moving into reduce-only mode, while no new orders will be accepted for margin trading, loans, staking, earn products and several other services.
All non-spot services are scheduled to end on Sep. 22. On-chain deposits will also close that day, with the exception of deposits in CoinEx Token, or CET, which will remain available until Sep. 29.
#Services #exchange #trading
The exchange said the wind-down will begin on Sep. 15, with services being withdrawn in stages before the platform closes completely on Dec. 22.
Related: Coinbase CEO doubles down on bullish Bitcoin target
CoinEx will immediately stop new user registrations, referral commissions and several new product subscriptions. Futures markets are moving into reduce-only mode, while no new orders will be accepted for margin trading, loans, staking, earn products and several other services.
All non-spot services are scheduled to end on Sep. 22. On-chain deposits will also close that day, with the exception of deposits in CoinEx Token, or CET, which will remain available until Sep. 29.
#Services #exchange #trading

1 day ago
The White House said Tuesday that banning yield on stablecoins would do little to increase bank lending, pushing back against estimates that stablecoin rewards could result in large amounts of deposits leaving the traditional banking system.
In an update to an April ****** ysis by the Council of Economic Advisers (CEA), the White House said eliminating stablecoin yield would increase bank lending by about $2.1 billion under its baseline ****** umptions. That represents just 0.02% of outstanding bank loans.
Community banks would account for roughly $500 million of the additional lending, or about 0.03% of their loan books, according to the ****** ysis.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#yield #increase #tuesday
In an update to an April ****** ysis by the Council of Economic Advisers (CEA), the White House said eliminating stablecoin yield would increase bank lending by about $2.1 billion under its baseline ****** umptions. That represents just 0.02% of outstanding bank loans.
Community banks would account for roughly $500 million of the additional lending, or about 0.03% of their loan books, according to the ****** ysis.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#yield #increase #tuesday


1 day ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather


1 day ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year

4 days ago
Kansas City, Missouri — Vice President JD Vance announced Monday the Trump administration will suspend roughly 870,000 people suspected of defrauding pandemic-era small business programs from receiving future federal loans.
The vice president contended that borrowers who stole taxpayer money should no longer be eligible to receive loans from government-backed programs.
"If you screwed the American taxpayer, the federal government is now going to say you're cut off, no more," Vance told reporters. "You shouldn't be applying anymore, and if you do apply, you're no longer able to get those benefits."
His remarks came as the Justice Department announced a slew of cases in a nationwide crackdown on fraud involving the COVID-19-era Paycheck Protection Program.
The department's enforcement push, which ran from June 12 through Sept. 1 and was dubbed "Heartland fraud surge," resulted in actions involving more than 160 defendants and approximately $245 million in intended losses to taxpayers. The operation was put into action more than five years after the government pushed emergency loans to businesses nationwide that were struggling as a result of the coronavirus pandemic.
#president #pandemic #federal
The vice president contended that borrowers who stole taxpayer money should no longer be eligible to receive loans from government-backed programs.
"If you screwed the American taxpayer, the federal government is now going to say you're cut off, no more," Vance told reporters. "You shouldn't be applying anymore, and if you do apply, you're no longer able to get those benefits."
His remarks came as the Justice Department announced a slew of cases in a nationwide crackdown on fraud involving the COVID-19-era Paycheck Protection Program.
The department's enforcement push, which ran from June 12 through Sept. 1 and was dubbed "Heartland fraud surge," resulted in actions involving more than 160 defendants and approximately $245 million in intended losses to taxpayers. The operation was put into action more than five years after the government pushed emergency loans to businesses nationwide that were struggling as a result of the coronavirus pandemic.
#president #pandemic #federal


4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates


5 days ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ***** ysis, subscribe to Bisnow's free suite of newsletters.
Despite office vacancy falling in most major cities, most landlords are still watching their margins shrink a half-decade after tenants embraced remote work.
Median total operating expense growth has exceeded revenue every year from 2021 through 2025, according to a Trepp ***** ysis of office properties backing CMBS loans.
Operating expenses have increased 2.7% annually, compared with a 1.3% growth rate for revenues. Net operating income has been squeezed to just a 0.2% uptick annually as a result.
Overall, the implied five-year growth rate is 14.3% for operating expenses and 6.7% for revenues. NOI was up just 1% during the period, according to Trepp's model.
#year #expenses
Despite office vacancy falling in most major cities, most landlords are still watching their margins shrink a half-decade after tenants embraced remote work.
Median total operating expense growth has exceeded revenue every year from 2021 through 2025, according to a Trepp ***** ysis of office properties backing CMBS loans.
Operating expenses have increased 2.7% annually, compared with a 1.3% growth rate for revenues. Net operating income has been squeezed to just a 0.2% uptick annually as a result.
Overall, the implied five-year growth rate is 14.3% for operating expenses and 6.7% for revenues. NOI was up just 1% during the period, according to Trepp's model.
#year #expenses


5 days ago
All eyes are on the Fed with another higher than expected reading for core inflation. Jeff Klingelhofer, CFA, Managing Director, Portfolio Manager & Senior Research **** yst, Securitized **** ets at Aristotle Pacific, talks with host Brad Roth on this episode of Behind the Ticker about why the new Fed Chair stepping into an environment of high inflation matters for investors and bonds, and what that means for how the firm is positioning their strategies that include three new ETFs, the Aristotle Core Plus Income ETF (ARCP), the Aristotle Multi-Sector Income ETF (ARMS), and the Aristotle Short Term Income ETF (SDUR).
You can also watch this conversation here or on our YouTube, as well as find it on any of your preferred podcast streaming platforms.
A non-traditional path to fixed income: Jeff Klingelhofer started at PIMCO, moved through Tokyo and London, then took an unexpected detour into a five-person hedge fund during his Chicago MBA. That experience shaped his career trajectory, from building Thornburg's taxable fixed income desk from scratch to joining Aristotle Pacific in 2024.
The relative value philosophy: Instead of chasing yield by taking more risk within a single **** et class, Klingelhofer compares opportunities across all of fixed income, including corporates, ABS, CLOs, bank loans, and more. His go-to example: in 2020, an American Airlines corporate bond and its aircraft-backed EETC priced identically, but a month later one traded at 27 cents on the dollar while the other held at 65 cent, proof that siloed desks miss cross-market mispricing.
Three ETFs, one philosophy: Aristotle Pacific's new suite of SDUR (short-term income), ARCP (core plus), and ARMS (multi-sector income) applies this relative value lens across the risk spectrum, each targeting a different level of duration and credit exposure. All three aim to outperform passive benchmarks through active security selection rather than added risk.
#jeff #etfs
You can also watch this conversation here or on our YouTube, as well as find it on any of your preferred podcast streaming platforms.
A non-traditional path to fixed income: Jeff Klingelhofer started at PIMCO, moved through Tokyo and London, then took an unexpected detour into a five-person hedge fund during his Chicago MBA. That experience shaped his career trajectory, from building Thornburg's taxable fixed income desk from scratch to joining Aristotle Pacific in 2024.
The relative value philosophy: Instead of chasing yield by taking more risk within a single **** et class, Klingelhofer compares opportunities across all of fixed income, including corporates, ABS, CLOs, bank loans, and more. His go-to example: in 2020, an American Airlines corporate bond and its aircraft-backed EETC priced identically, but a month later one traded at 27 cents on the dollar while the other held at 65 cent, proof that siloed desks miss cross-market mispricing.
Three ETFs, one philosophy: Aristotle Pacific's new suite of SDUR (short-term income), ARCP (core plus), and ARMS (multi-sector income) applies this relative value lens across the risk spectrum, each targeting a different level of duration and credit exposure. All three aim to outperform passive benchmarks through active security selection rather than added risk.
#jeff #etfs
5 days ago
Block, Inc. (NYSE:XYZ) is taking another step toward consolidating its digital **** et operations under a federal regulatory framework. On September 8, it filed an application with the Office of the Comptroller of the Currency (OCC) to charter Builders Bank & Trust, N.A.
If chartered, the Builders Bank & Trust could become an important part of Block's digital **** et custody infrastructure, giving the company a federally supervised framework for custody and related services involving bitcoin and stablecoins.
Builders Bank & Trust would be an uninsured national trust bank, meaning it would not accept deposits or make traditional loans. Instead, its focus would be on fiduciary and custody services, allowing Block to build specialized infrastructure for safeguarding digital **** ets.
The structure could be particularly valuable as Block, Inc. (NYSE:XYZ) seeks to expand its institutional customer base. A federally supervised custody operation could give larger financial institutions greater confidence in Block's ability to safeguard Bitcoin and other digital **** ets.
Stablecoins represent a potentially important opportunity for Block, particularly through its Cash App ecosystem. A regulated custody infrastructure could eventually support broader stablecoin-related products and payments if Block chooses to expand further in this area.
#Bitcoin
If chartered, the Builders Bank & Trust could become an important part of Block's digital **** et custody infrastructure, giving the company a federally supervised framework for custody and related services involving bitcoin and stablecoins.
Builders Bank & Trust would be an uninsured national trust bank, meaning it would not accept deposits or make traditional loans. Instead, its focus would be on fiduciary and custody services, allowing Block to build specialized infrastructure for safeguarding digital **** ets.
The structure could be particularly valuable as Block, Inc. (NYSE:XYZ) seeks to expand its institutional customer base. A federally supervised custody operation could give larger financial institutions greater confidence in Block's ability to safeguard Bitcoin and other digital **** ets.
Stablecoins represent a potentially important opportunity for Block, particularly through its Cash App ecosystem. A regulated custody infrastructure could eventually support broader stablecoin-related products and payments if Block chooses to expand further in this area.
#Bitcoin


5 days ago
U.S. Bancorp (NYSE:USB) has raised its quarterly dividend by 3.8% to $0.54 per share. That brings the annualized payout at $2.16 and the yield at 3.5%.
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth

6 days ago
First Citizens BancShares, Inc. (NASDAQ:FCNCA), through its First-Citizens Bank & Trust Company subsidiary, completed the acquisition of 138 BMO Bank N.A. branches on September 4. The locations span 11 states across the Midwest, Great Plains and West.
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens
The completion announcement did not disclose final transferred balances. At the announcement, First Citizens BancShares, Inc. (NASDAQ:FCNCA) expected to ****** ume approximately $5.7 billion of deposits and acquire $1.1 billion of loans. Its July 2026 update lowered those estimates to $5.3 billion and $700 million, respectively. Both estimates imply roughly $4.6 billion of net liquidity. That difference represents funding capacity, not transaction income, and remains subject to final balances and acquisition accounting.
The deposit franchise could be the transaction's most valuable ****** et. At announcement, the acquired deposits carried a weighted average rate of 1.43%, with 21% in noninterest-bearing demand accounts. First Citizens BancShares, Inc. (NASDAQ:FCNCA) reported a 2.07% average total deposit cost in the second quarter of 2026. Retaining the acquired accounts near their original pricing could lower the consolidated funding cost.
The 138 branches also establish or deepen a presence across 11 states. The original transaction presentation identified approximately $1.0 billion of wealth ****** ets under management, creating opportunities to cross-sell commercial lending, treasury services, and wealth products. Retaining branch personnel could help preserve local relationships.
First Citizens BancShares, Inc. (NASDAQ:FCNCA) can deploy the surplus funding in several ways. As of June 30, 2026, the company held $151.03 billion of loans and $32.19 billion of borrowings, including a $28.42 billion purchase money note owed to the Federal Deposit Insurance Corporation. The acquired liquidity could support loan growth, replace more expensive funding, or be invested in securities. The original presentation projected immediate earnings-per-share accretion and an approximately 27-basis-point reduction in the Common Equity Tier 1 capital ratio.
#billion #first #citizens



6 days ago
Horizon Technology Finance Corp., an affiliate of Monroe Capital, on September 10 said that the RoHo Capital Opportunity Fund LLC, a joint venture formed by Horizon and CR Financial Holdings, Inc., the holding company for Roth Capital Partners, LLC, has provided a $20-million senior credit facility to NeoVolta, Inc., with the ability to increase the facility to $30 million upon mutual agreement. An initial $20 million was funded at closing to support NeoVolta's continued growth.NeoVolta is an energy technology company focused on developing and manufacturing domestic battery energy storage systems (BESS). Together with its joint venture partner LONGi, NeoVolta is developing a 210,600-square-foot manufacturing facility in Pendergrass, Georgia, to produce BESS systems designed to meet U.S. domestic content and supply-chain requirements. The facility is expected to have an initial annual production capacity of up to 2 GWh, with the potential to scale to 8 GWh over time."Providing growth capital to innovative companies operating in attractive, high-growth markets is a core focus of RoHo's investment strategy," said Paul Seitz, chief investment officer of Horizon. "Formed by Horizon and Roth Capital, RoHo pairs Horizon's venture lending and structuring expertise with Roth's deep public markets relationships to deliver flexible growth capital to small- and micro-cap public companies. We are pleased to support NeoVolta's growth plans with a tailored financing solution and look forward to continuing to deploy capital through RoHo in support of innovative public companies pursuing significant market opportunities.""Horizon and Roth Capital bring valuable experience and a collaborative approach as we advance NeoVolta's domestic battery energy storage systems manufacturing platform," said Ardes Johnson, CEO of NeoVolta. "As we ramp our Georgia facility and pursue larger commercial and utility-scale opportunities, this relationship supports our ability to execute on our long-term growth strategy."Horizon Technology Finance Corp. is a specialty finance company that provides capital in the form of secured loans to venture capital and private equity-backed companies and publicly traded companies in the technology, life science, healthcare information and services, and sustainability industries. The investment objective of Horizon is to maximize its investment portfolio's return by generating current income from the debt investments it makes and capital appreciation from the warrants it receives when making such debt investments. Horizon is headquartered in Farmington, Connecticut, with a regional office in Pleasanton, California, and investment professionals located throughout the U.S.Monroe Capital is a premier ****** et management firm specializing in private credit markets across various strategies, including direct lending, technology finance, venture debt, opportunistic, structured credit, real estate and equity.CR Financial Holdings, Inc., is a private hol


7 days ago
While the average personal loan interest rate is 12.21%, borrowers with excellent credit may have access to rates as low as 6.20%.
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.72% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting at 6.20%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12.06%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#loan
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.72% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting at 6.20%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12.06%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#loan

