21 days ago
American Tower Corporation (NYSE:AMT) traded at around $165 on October 6, within five dollars of its 52-week low of $160.06.
The company keeps 45.41% of revenue as operating profit on a portfolio of communications towers leased to wireless carriers. A business that profitable sitting at a 52-week low is usually a disagreement about the future rather than the present.
READ ALSO: What is eBay's (EBAY) Economic Moat, and is it Widening or Narrowing?
A tower is difficult to replicate for reasons that have nothing to do with engineering. Local authorities restrict where new structures can go, so an existing site near a highway or a dense suburb cannot simply be copied next door.
The economics follow from that scarcity. The first tenant on a tower covers the construction and the ground lease, and each additional tenant is close to pure margin. Gross margin of 73.77% is what that layering produces, and the 45.41% operating margin is what survives after the overheads.
#NYSE


22 days ago
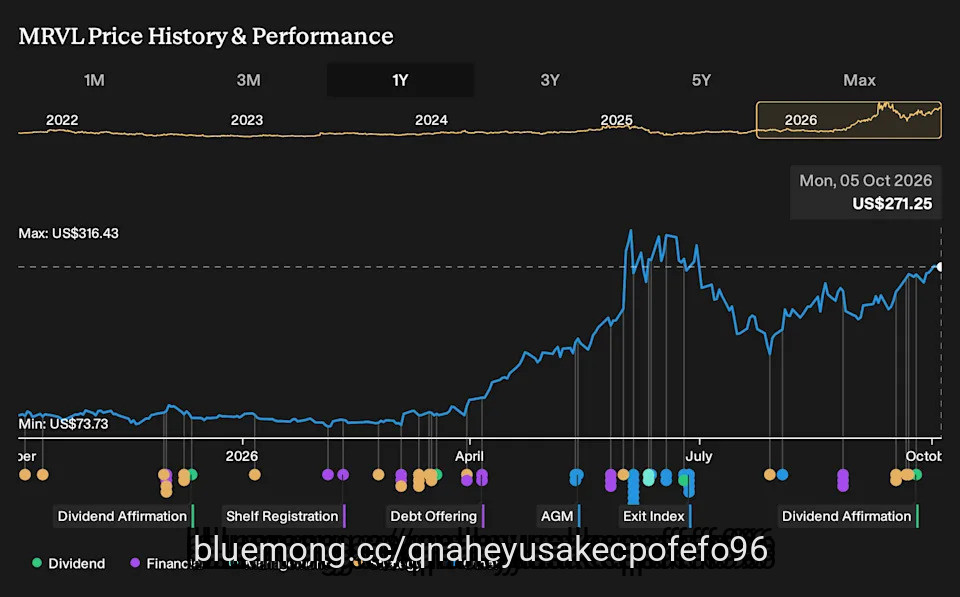
In late September 2026, AT&S Austria Technologie & Systemtechnik AG announced an expanded collaboration with Marvell Technology to increase advanced IC substrate capacity for next-generation AI and cloud infrastructure, while Marvell also affirmed a quarterly dividend of US$0.06 per share payable on October 29, 2026.
This deeper manufacturing partnership gives Marvell greater access to complex packaging technologies that are increasingly critical for high-performance AI chips and data center hardware.
Next, we'll examine how this expanded AT&S manufacturing capacity could influence Marvell's AI-focused growth story and longer-term investment narrative.
The future of work is here. Discover the 89 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
To own Marvell, you need to believe its AI and data center franchises can justify today's rich valuation and eventually translate into stronger, more consistent earnings power. The expanded AT&S IC substrate deal directly supports Marvell's near term AI optics and custom silicon ramp, while also amplifying the existing risk that long term supplier prepayments and capacity commitments could weigh on margins and free cash flow if AI demand or customer ramps slow.
#term #substrate #Manufacturing #data

22 days ago
Google and Constellation Energy announced a 20-year power purchase agreement on Tuesday to bring 890 megawatts of new nuclear capacity onto the PJM Interconnection grid, with Constellation committing more than $4.3 billion to fund the build-out.
The capacity will be generated through turbine, steam generator, and digital control system upgrades at 11 Constellation nuclear units in Illinois, Pennsylvania, and New Jersey, the companies said. The first uprate is expected to be delivered by 2028. The agreement is expected to sustain roughly 4,400 existing jobs and create approximately 7,200 new construction jobs during the building period.
Alongside the power purchase agreement, the companies entered into a separate 15-year energy supply agreement covering an additional 2,700 megawatts from Constellation's existing fleet in the PJM market, the company said.
"We're committed to meeting our growth responsibly by actively investing in clean, reliable power that brings new capacity to our nation's grids," Amanda Peterson Corio, global head of energy and power at Google, said in a statement. "Our agreement with Constellation to fund nuclear reactor uprates will strengthen the PJM grid, which serves 67 million people, all while protecting energy affordability and supporting local union jobs."
Joe Dominguez, chairman, president and CEO of Constellation, said in a statement that the collaboration "can serve as a model for how technology companies and the energy industry can work together to responsibly develop the digital economy."
#energy #capacity #Jobs

22 days ago
Oct 6 (Reuters) - Governments, courts and companies are considering restrictions and examining existing rules on smart glasses amid worries that the technology, brought to mainstream by Meta's Ray-Bans, could be used to photograph, film or audio-record confidential materials or people without their knowledge.
Here is a summary of what countries and regions are doing to protect people's privacy, in alphabetical order.
AUSTRALIA
The federal government said in September it was considering barring the use of camera-equipped smart glasses in government workplaces due to privacy and security concerns.
Public Service Minister Katy Gallagher asked the country's Public Service Commission for advice on whether their use should be prohibited and what exemptions might be required.
#governments


22 days ago
A source claims that Prince Harry and Meghan Markle are not seeing eye to eye on an important decision. The news comes as the Sussexes are settling back into life in the UK following their return after six years. However, the transition has not been entirely smooth due to security concerns regarding their children's schools and King Charles' confirmation of their status as private citizens.
Prince Harry and Meghan Markle are reportedly "not on the same page" regarding a crucial element of their move back to the UK.
Adding to their existing challenges, the Sussexes may now be facing another disagreement. As reported by Heat World, the pair are divided over their Christmas plans. A source told the publication, "With the kids in school, they can't keep bouncing between California and the UK whenever they feel like it, so they've got some difficult decisions coming up because they are not on the same page."
The insider further shared that the Duke wants to remain in Britain for the holidays, as Christmas is the time he cherishes most. On the other hand, the "Suits" star is reportedly missing home and longing to be with her mother, Doria Ragland.
They stated, "[Meghan] misses her friends, she misses her day-to-day routine and she really misses her mom. She talks to Doria every day, usually multiple times but it's not the same as spending every weekend with her."
#markle #sussexes
25 days ago
Black may be one of the safest colors in formal fashion, but the 2026 Venice Film Festival showed how unpredictable it can become in the right hands. Across premieres and ceremonies, stars embraced lace, velvet, satin, sculptural tailoring and elaborate draping. Instead of relying on color to create impact, designers used texture and silhouette to give each outfit a distinctive personality. Laura Dern, Susan Sarandon, Amal Clooney, Maggie Gyllenhaal and Rooney Mara all approached the classic shade differently. Together, their appearances demonstrated why black continues to have such staying power on major red carpets.
Laura Dern embraced intricate detailing for the premiere of Wild Horse Nine. Her sleeveless black Dior gown featured a V neckline, delicate lace and floral embroidery across the upper section. The design transitioned into a fuller shimmering skirt, giving the monochrome look depth through contrasting textures. Black Dior pumps maintained the restrained palette, while a Cartier necklace provided a polished finishing touch.
Susan Sarandon chose a more streamlined interpretation at the premiere of The Echo Chamber. Her black Fendi dress featured long sleeves and an off the shoulder neckline, with a fluid silhouette that followed the body without requiring elaborate embellishment. Statement jewelry, sunglasses and bright red lipstick added personality, demonstrating how accessories can completely change the mood of an otherwise minimalist black dress.
For the festival's opening ceremony, Amal Clooney turned to Tom Ford. Her floor length column gown used rippled fabric panels and subtle leather detailing to create movement and texture. Pointed pumps and a coordinating clutch continued the sleek approach. The result demonstrated how carefully constructed fabric can make a single color visually interesting without overwhelming the overall silhouette.
Maggie Gyllenhaal brought archival fashion into the conversation with an Armani Privé velvet gown originally created in 2015. The design combined sharply defined shoulders, long sleeves and a plunging embellished neckline. Its return more than a decade later also highlighted the growing red carpet practice of revisiting existing fashion rather than treating older couture as something that belongs permanently in an archive.
#susan


30 days ago
Vista Gold Corp. (NYSEAMERICAN:VGZ) announced on September 21 that it had agreed to be acquired by Artemis Gold Inc. (TSXV:ARTG). Under the agreement signed September 20, shareholders would receive 0.0966 buyer common shares for each existing common share and own approximately 5% of the combined company. That ownership calculation excludes the buyer's existing 4.95% stake in Vista Gold Corp. (NYSEAMERICAN:VGZ), which it intends to cancel at completion.
For shareholders, the trade-off is a smaller interest in a larger mining business with an operating ***** et and development expertise. The central question is whether that combination can supply the capital and execution needed to bring Australia's Mt Todd gold project into production.
Artemis Gold Inc. (TSXV:ARTG) operates the Blackwater mine in British Columbia and expects its future cash generation to support Mt Todd. That offers Vista Gold a potential funding source alongside a team experienced in building and operating mines.
The financial starting point explains the appeal. Vista Gold Corp. (NYSEAMERICAN:VGZ) ended June 2026 with $49.5 million in cash and no debt. Management described that cash as sufficient for interim development objectives. Joining an operating producer could broaden the resources available for the much larger task of construction.
The acquisition requires no cash consideration or new acquisition debt. Preserving the buyer's financial capacity could leave more room for investment, although the share exchange itself does not raise construction funding.
#cash

1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#gaap #revenue #launch #anderson

1 month ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

1 month ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management


1 month ago
On September 9, 2026, Reuters reported that Amazon.com, Inc. (NASDAQ:AMZN) raised £4.25 billion, or about $5.76 billion, in its first-ever sterling bond sale, slightly more than initially expected, as part of a four-tranche deal spanning 3 to 19 years. Final investor demand came in at more than £10.65 billion, roughly 2.5 times the amount raised, but that was notably lower than the demand Alphabet saw for its own sterling debut in February, a sign ******* ysts said shows hyperscaler borrowing may be starting to test the limits of investor appetite.
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn
1 month ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue

1 month ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional

1 month ago
SPX Technologies, Inc. (NYSE:SPXC) announced on September 15 that it completed the acquisition of FIS Water, LLC for approximately $410 million in cash, including certain tax attributes. The acquired business is expected to generate approximately $105 million of revenue in 2026.
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE
1 month ago
Veteran ******* yst Jim Cramer sees something in Apple's (AAPL) latest launch that is more than a reason for its customers to buy another replacement phone.
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran


1 month ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo

1 month ago
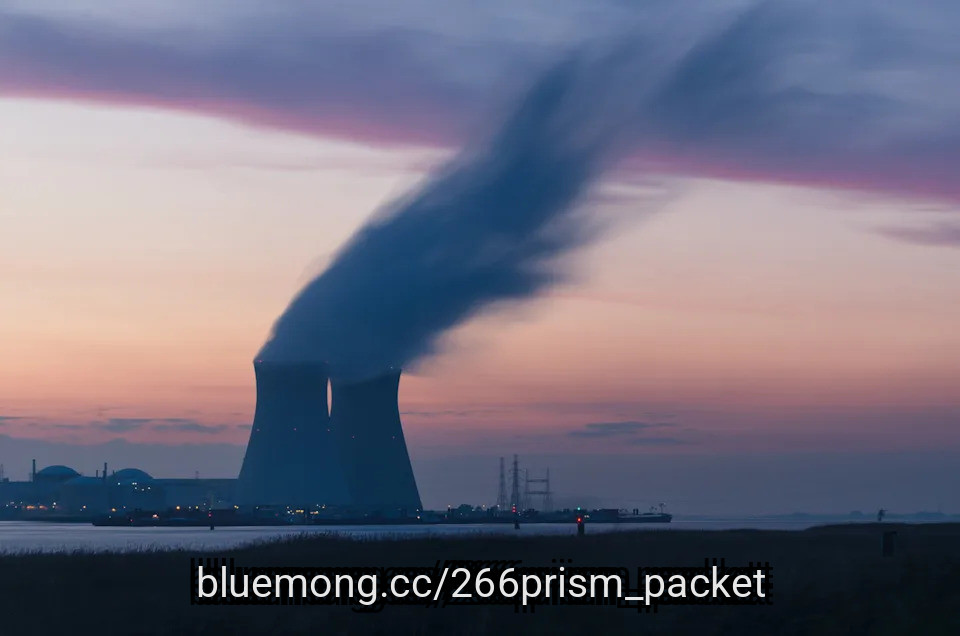
NextEra Energy, Inc. (NYSE:NEE) announced on September 8 that it had secured a loan of up to $1.9 billion from the U.S. Department of Energy to support the restart of a shuttered nuclear power plant in Iowa. The Duane Arnold Energy Center ceased operations in 2020 after 45 years of service. The plant is now expected to resume operations in early 2029, pending regulatory approvals.
The federal funding is intended to help restore the facility and add reliable generation capacity as the US electricity demand soars to record levels amid the AI boom. To help meet the growing demand, President Trump is making efforts to accelerate the expansion of nuclear energy. He has signed an executive order to get 10 large conventional reactors under construction by 2030 and has also called for federal funding to support the restart of shuttered nuclear plants.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"Restarting Duane Arnold is about delivering new power to meet new demand while generating billions of dollars in economic value for Iowans. Just as importantly, it shows how America can support rapid economic growth and rising electricity demand while helping keep power affordable for existing customers. By bringing new generation online to serve new demand, we can strengthen the grid, create hundreds of good-paying jobs and help ensure Iowa families and businesses are not asked to bear the costs of growth. We appreciate the Administration's leadership in advancing America's nuclear renaissance and share its commitment to an all-of-the-above energy strategy that expands supply, strengthens energy security and keeps America competitive."
Photo by Frédéric Paulussen on Unsplash
#duane #arnold

1 month ago
If you're trying to build a consumer-focused corner of your portfolio that can grow through a lot of different economic backdrops, three names stand out right now: Church & Dwight Co. (NYSE: CHD), YETI Holdings (NYSE: YETI), and Newell Brands (NASDAQ: NWL). Each of these is making deliberate moves in 2026 and into 2027 that communicate to me more about their future than any single rocky quarter's earnings line.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic


1 month ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Ripple-backed XRP treasury company Evernorth Holdings has lined up $30 million in new financing as it prepares to go public through a merger with Armada Acquisition Corp. II (NASDAQ:XRPN).
The deal would bring Evernorth onto Nasdaq under the XRPN ticker, giving public-market investors exposure to a company built around accumulating XRP (CRYPTO: XRP) and deploying it across the XRP ecosystem.
Evernorth said the new financing may be used to buy more XRP and fund other ecosystem investments. The $30 million arrives when the merger closes, which the company expects in the fourth quarter.
Evernorth and an affiliate held 473.1 million XRP at the end of 2025. At around $1.38 per token, $30 million would buy roughly another 21.7 million XRP, or less than 5% of that existing position.
#financing #merger

1 month ago
Boeing locked Korean Air into a $36.2 billion order spanning 737 MAX, 787-10, and 777X variants, but no deliveries arrive until the early 2030s.
Lockheed Martin posts steady profits while Boeing burns cash lifting production rates, carrying $600 million in quarterly interest expense that pressures GAAP results.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Boeing didn't make the cut. Enter your email to see the names that beat BA. The report is free. Enter your email and see if any of your stocks made the cut.
Boeing (NYSE:BA) confirmed a firm Korean Air order for the stretched 737 MAX, 787-10, and 777X in passenger and freighter variants, valued at $36.2 billion. Deliveries begin in the early 2030s.
These aircraft were previously logged as unidentified orders from a commitment announced last summer, so this is existing backlog getting a customer name rather than fresh demand.
#boeing #deliveries


1 month ago
Costco is expanding its same-day delivery network as it looks to grow e-commerce sales and compete with retailers like Walmart and Target.
The retailer this week launched collaborations with DoorDash (NASDAQ: DASH) and Uber (NYSE: UBER) to pick up online orders at U.S. stores and drive them to the customer's door. The arrangements give Costco more channels to reach customers through ultra-fast delivery, made possible by gig drivers who use the platforms to select ******* ignments.
DoorDash, best known for delivering restaurant food, announced that Costco (NASDAQ: COST) members can now order groceries, dry goods, household essentials and other products from its marketplace and then arrange fast delivery from their local store, all through the DoorDash app. The U.S. launch extends the existing relationship between the companies in Australia, New Zealand, Sweden, Iceland and Puerto Rico.
DoorDash now serves eight of the 10 largest food retailers in North America.
On Wednesday, Uber announced a major expansion of its partnership with Costco to deliver products in 47 states, up from 17 states. Nearly 600 Costco locations are now available on the Uber Eats app, where shoppers can arrange on-demand and scheduled delivery.
#Food #announced

1 month ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ****** e, recently expanded its strategic alliance with CrowdStrike. As part of the revised arrangement, the company's SailPoint SecOps Identity Intelligence will be integrated with CrowdStrike Falcon Next-Gen SIEM. This will help in expediting threat detection procedures, and will also incorporate access data and identity governance into the overall investigation process. The expanded partnership will facilitate security teams in lining up the identity insights with Falcon's existing security telemetry.
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next

1 month ago
Corning (GLW) stock took a sharp hit this week after the company opened the door to a potential $2 billion equity offering that could dilute existing shareholders. The stock dropped 13.7% on Sept. 14, marking its worst one-day decline in years. At the same time, Corning is expanding its capacity and signing major deals with some of the world's biggest tech companies, including Nvidia (NVDA) and Amazon (AMZN). Its latest Verizon (VZ) agreement alone covers over 80 million miles of optical fiber and connectivity products through 2032. Corning shares have since recovered, shifting attention away from dilution fear to whether the capital raise was a sensible decision, how much stock Corning actually sells, how quickly Optical Communications grows, and whether new capacity generates the returns management expects.
Let's find out more on what matters for investors now.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Stock #sept

1 month ago
Investors are largely in agreement that most of Berkshire Hathaway's (NYSE: BRKA) (NYSE: BRKB) stock holdings are solid picks. Every now and then, though, one of its selections raises a few eyebrows.
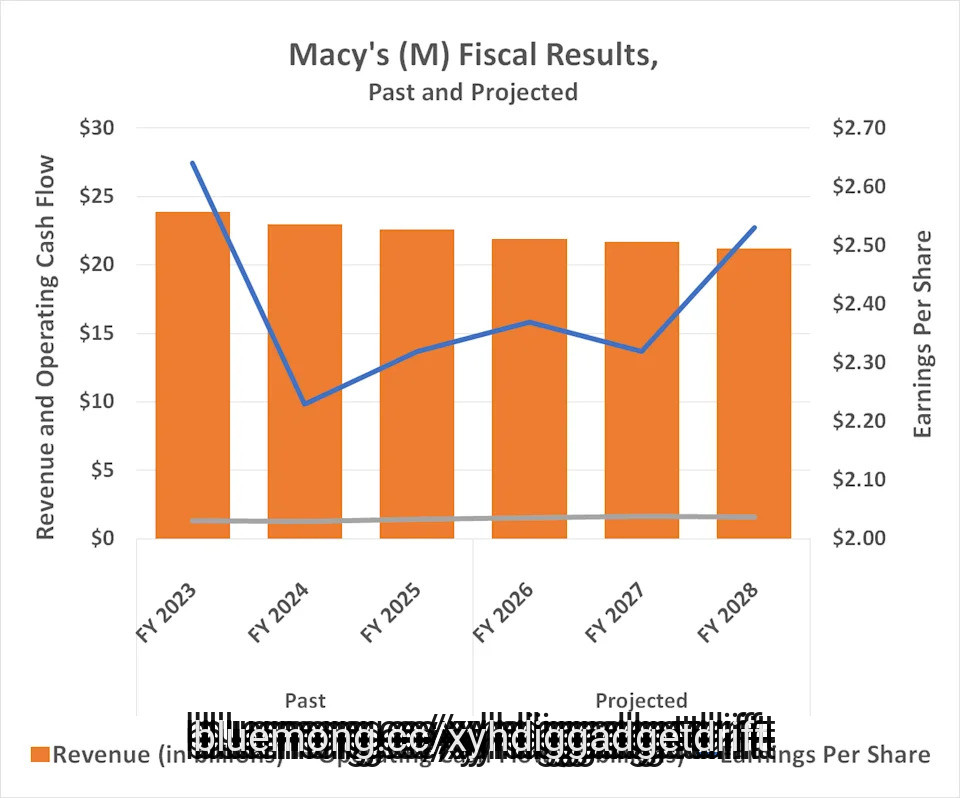
That's what happened when Berkshire bought 3 million shares of department store chain Macy's (NYSE: M) in the first quarter of this year. Most people appreciate that the struggling company owns a real estate portfolio that may well be worth more than the organization's current market cap of just under $6 billion. To unlock that value, however, the company would need to take on the expensive -- and business-destructive -- headache of winding down at least some of its existing retailing operations, perhaps undermining the value of that real estate in the process.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But maybe Berkshire Hathaway isn't looking at what's since grown to a 7.4 million share/$162 million stake in Macy's as a real estate bet after all. It could be a legitimate turnaround play.
This premise could be difficult to digest given the so-called retail apocalypse that's been underway since the advent of e-commerce. And, anyone who's been keeping close tabs on the brick-and-mortar retailing industry's struggle probably knows that department store chains' revenue peaked in the early 2000s, and has been dwindling ever since.
#real



1 month ago
Bitcoin's most violent rally of its two-year drawdown wasn't powered by fresh bullish bets. It was powered by bears getting crushed, according to a new report from ******* ytics firm Glassnode and crypto exchange Bybit.
Over five days in August, Bitcoin climbed 24.6% even as coin-denominated open interest, a measure of active leverage, fell 12.6%, the report found. That combination is the tell: rather than traders piling into new long positions, the move ran on the forced unwinding of existing shorts.
Roughly 64,000 BTC worth of open interest was closed out, and short positions supplied 89% of every liquidated dollar during the stretch.
The options market told the same story. Puts, the contracts traders buy to protect against a fall, had priced richer than calls for 361 straight days. A single session ended that run, flipping roughly a year of downside positioning as the market scrambled to reprice.
Bybit's own volatility index traveled four times its normal daily range in one session, and the front of the futures curve repriced sharply while longer-dated contracts barely moved, a sign the market read the move as a one-off event rather than a lasting regime change.
#interest

1 month ago
Owning a $400,000 Villages home costs owners roughly 4.5% annually in forgone investment income alone, before taxes, insurance, or CDD bond payments.
Annual rentals run between $2,200 and $3,000 a month, but renting beats owning only for stays under eight years once all costs are counted.
A 75-year-old facing a forced sale in a narrow buyer pool at 3.98 million existing home sales risks losing the flexibility a lease ending provides.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
At the end of the day, renting versus buying in The Villages comes down to one thing: math. More owners are running the numbers and finding that renting wins on the spreadsheet, so here is what the comparison actually looks like when every line is filled in.
#income


1 month ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


1 month ago
On September 17, Coherent Corp. (NYSE:COHR) announced an upgraded Pluggable Optical Line System that covers the full C-band and fits in a compact QSFP module, the same slot ordinary transceivers use. That is a lot of networking gear shrunk into a plug, and it follows a quarter of 34% revenue growth. Here is what the launch means, and where the stock's story gets harder to read.
Start with what the product does. The upgraded system can pack 32 wavelengths onto a single pair of fibers, which Coherent says adds up to as much as 25.6Tbps of traffic on links running 2km to 200km. It is designed for the latest 800G coherent optics, and it configures itself, handling link setup and laser safety without a technician tuning each connection. Coherent also says the system is generally available and already shipping in high volume, in 400G and 800G versions that work with existing network setups. Madhu Krishnaswamy, who runs the company's telecom transport unit, describes the goal as easing the usual trade-off between raw performance and operational simplicity.
The launch also sits on top of a business that is already moving. On August 12, Coherent reported results for its fiscal fourth quarter, which ended June 30: revenue of $2.05 billion, up 34% from a year earlier. Non-GAAP earnings per share rose to $1.74 from $1.00, and CEO Jim Anderson noted that for the full year, that measure grew more than twice as fast as revenue. Management guided to revenue of $2.2 billion to $2.4 billion for the first quarter of fiscal 2027, and Anderson says AI data centers are increasingly moving from copper to optical links.
Now look at the two versions of profit. Coherent's non-GAAP earnings came to $1.74 per share, but under GAAP the figure was $1.19. The gap comes from items management leaves out, including stock-based pay, amortization on acquired intangibles, and restructuring and integration costs. Operating margin shows it more clearly, at 21.8% on a non-GAAP basis and 12.4% under GAAP. Some of those costs are non-cash, but they are real, and anyone anchoring on the higher figure is skipping them.
Then there is how much weight this launch can carry. The announcement puts no sales figure on the product, so its contribution to a company that booked $2.05 billion in a quarter cannot be sized from what has been published. The bullish story also rests on management's own read of where AI networks are headed, and on a capacity build-out that CFO Sherri Luther says gets priority in spending. Money spent on capacity only pays off if the demand management describes keeps arriving.
#quarter #launch #anderson

1 month ago
GE Vernova Inc. (NYSE:GEV) is trying to recover after an 8.5% decline, with Bernstein defending the stock as "wired to win" and highlighting that data centers account for only 38% of its electrification order book. This supports the argument that the company's utility exposure extends beyond AI power demand alone. That diversification is a real consideration, but it does not directly address the concern raised by GLJ Research. The firm's Sell rating is not based on doubts about AI-driven power demand. Instead, GLJ Research argues that GE Vernova is still a fundamentally cyclical gas-turbine manufacturer, while its current valuation reflects an **** umption that the ongoing boom can remain permanent.
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data

1 month ago
Trump signed the legislation into law on Friday, the White House said.
LONDON -- Ukrainian President Volodymyr Zelenskyy on Friday thanked President Donald Trump for signing into law a bill championed by the late Sen. Lindsey Graham, which allows for the expansion of sanctions on Russia related to Moscow's ongoing full-scale invasion of Ukraine.
Trump signed the bill on Friday, the White House said in a statement, after the legislation passed both the House and Senate with strong bipartisan backing. The legislation "authorizes and expands statutory sanctions, tariffs and prohibitions on Russia and extends existing sanctions on Iran," the White House said.
The bill's passage came about two months after Graham died suddenly following a tear in his aorta. Graham had long been an advocate of U.S. support for Kyiv and more stringent measures on Russia and the regime headed by President Vladimir Putin. In 2024, Russia's state financial monitoring agency added Graham to its list of alleged "terrorists and extremists."
In a post to Telegram on Friday night, Zelenskyy thanked Trump for signing what he called "critically important legislation," extending his thanks to "all the senators and members of the House of Representatives who supported it."
#legislation #white #Russia #zelenskyy