

2 days ago
The Kanye West Yeezy brand is returning to the runway after more than four years. Ye, formerly known as Kanye West, has announced a new fashion presentation in Los Angeles ******* led Yeezy Season 01. The event marks the label's first full-scale runway show since October 2022 and comes as the brand continues rebuilding its retail presence.
According to Business of Fashion, Yeezy Season 01 is scheduled for Wednesday, November 4, at 8 p.m. local time. The presentation will take place at Yeezy Flagship Droam 1, located at 4317 Beverly Boulevard in Los Angeles.
Invitations sent to members of the press reportedly listed the event's start time. The presentation will also celebrate the opening of the brand's first brick-and-mortar store, bringing its runway and retail operations together.
This will be Yeezy's first full-scale runway presentation since Season 9, which debuted in Paris in October 2022. That show attracted widespread criticism after West and several models appeared in shirts bearing the slogan "White Lives Matter."
The controversy intensified later that month when West made a series of antisemitic remarks. Adidas subsequently terminated its partnership with the designer, while other companies also distanced themselves from him.
#yeezy #kanye #angeles #fashion
According to Business of Fashion, Yeezy Season 01 is scheduled for Wednesday, November 4, at 8 p.m. local time. The presentation will take place at Yeezy Flagship Droam 1, located at 4317 Beverly Boulevard in Los Angeles.
Invitations sent to members of the press reportedly listed the event's start time. The presentation will also celebrate the opening of the brand's first brick-and-mortar store, bringing its runway and retail operations together.
This will be Yeezy's first full-scale runway presentation since Season 9, which debuted in Paris in October 2022. That show attracted widespread criticism after West and several models appeared in shirts bearing the slogan "White Lives Matter."
The controversy intensified later that month when West made a series of antisemitic remarks. Adidas subsequently terminated its partnership with the designer, while other companies also distanced themselves from him.
#yeezy #kanye #angeles #fashion

2 months ago
Investors are largely in agreement that most of Berkshire Hathaway's (NYSE: BRKA) (NYSE: BRKB) stock holdings are solid picks. Every now and then, though, one of its selections raises a few eyebrows.
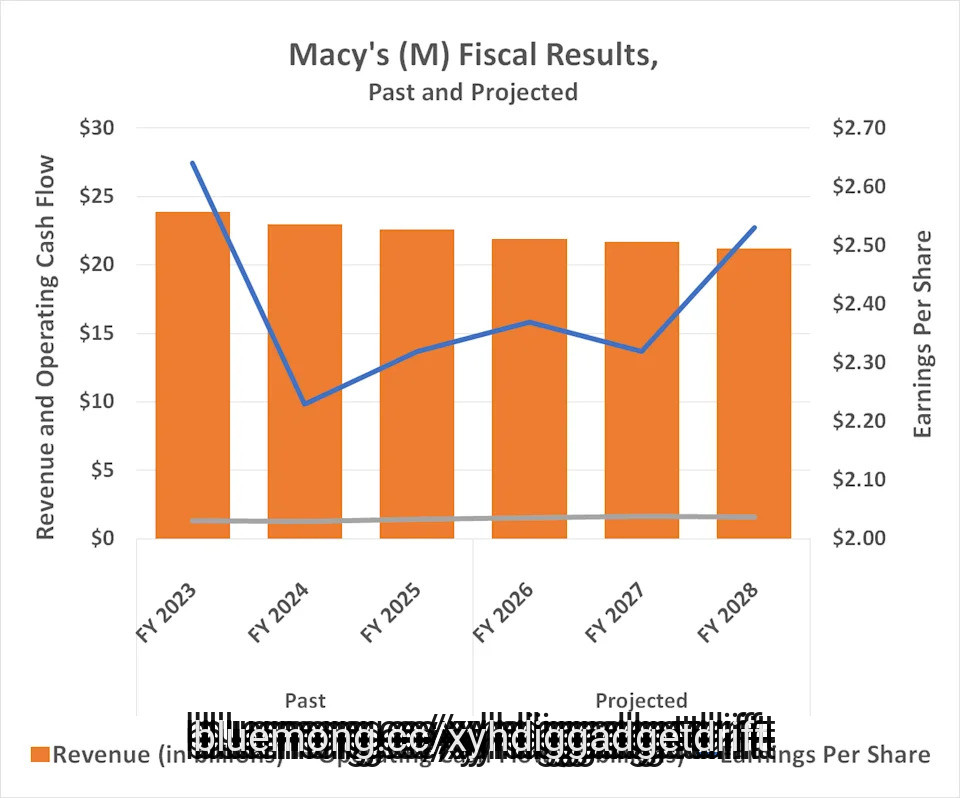
That's what happened when Berkshire bought 3 million shares of department store chain Macy's (NYSE: M) in the first quarter of this year. Most people appreciate that the struggling company owns a real estate portfolio that may well be worth more than the organization's current market cap of just under $6 billion. To unlock that value, however, the company would need to take on the expensive -- and business-destructive -- headache of winding down at least some of its existing retailing operations, perhaps undermining the value of that real estate in the process.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But maybe Berkshire Hathaway isn't looking at what's since grown to a 7.4 million share/$162 million stake in Macy's as a real estate bet after all. It could be a legitimate turnaround play.
This premise could be difficult to digest given the so-called retail apocalypse that's been underway since the advent of e-commerce. And, anyone who's been keeping close tabs on the brick-and-mortar retailing industry's struggle probably knows that department store chains' revenue peaked in the early 2000s, and has been dwindling ever since.
#real
That's what happened when Berkshire bought 3 million shares of department store chain Macy's (NYSE: M) in the first quarter of this year. Most people appreciate that the struggling company owns a real estate portfolio that may well be worth more than the organization's current market cap of just under $6 billion. To unlock that value, however, the company would need to take on the expensive -- and business-destructive -- headache of winding down at least some of its existing retailing operations, perhaps undermining the value of that real estate in the process.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But maybe Berkshire Hathaway isn't looking at what's since grown to a 7.4 million share/$162 million stake in Macy's as a real estate bet after all. It could be a legitimate turnaround play.
This premise could be difficult to digest given the so-called retail apocalypse that's been underway since the advent of e-commerce. And, anyone who's been keeping close tabs on the brick-and-mortar retailing industry's struggle probably knows that department store chains' revenue peaked in the early 2000s, and has been dwindling ever since.
#real



2 months ago
This story was originally published on Supply Chain Dive. To receive daily news and insights, subscribe to our free daily Supply Chain Dive newsletter.
TJX Companies is confident in navigating weather-related events such as El Niño due to its warehouse distribution model, CEO Ernie Herrman said in a Q2 earnings call on Aug. 19.
Herrman said since the company keeps its liquidity and shipping out of its warehouses, it has better control than traditional retailers. Inventory doesn't need to go straight to the stores if the off-price retailer thinks there's going to be an unusual weather pattern in a certain region, he added.
"[T]his is a benefit of our model where we stage goods in our warehouses versus goods at most brick-and-mortar retailers come into the warehouse and have to go out," Herrman told **** ysts. He added that the company's "planning organization is really good at reacting to any wild swings in weather or natural disasters or any of those red flags."
Off-price retailers and classic retailers tend to have different supply chain models when it comes to how they manage their inventory, but it's not one-size fits all, Dheera Anand, a partner at Bain and Co., told Supply Chain Dive in an interview. The supply chain strategy Hermann described in TJX's earnings call is known as the hold and flow, or staged, model, Anand said.
#supply
TJX Companies is confident in navigating weather-related events such as El Niño due to its warehouse distribution model, CEO Ernie Herrman said in a Q2 earnings call on Aug. 19.
Herrman said since the company keeps its liquidity and shipping out of its warehouses, it has better control than traditional retailers. Inventory doesn't need to go straight to the stores if the off-price retailer thinks there's going to be an unusual weather pattern in a certain region, he added.
"[T]his is a benefit of our model where we stage goods in our warehouses versus goods at most brick-and-mortar retailers come into the warehouse and have to go out," Herrman told **** ysts. He added that the company's "planning organization is really good at reacting to any wild swings in weather or natural disasters or any of those red flags."
Off-price retailers and classic retailers tend to have different supply chain models when it comes to how they manage their inventory, but it's not one-size fits all, Dheera Anand, a partner at Bain and Co., told Supply Chain Dive in an interview. The supply chain strategy Hermann described in TJX's earnings call is known as the hold and flow, or staged, model, Anand said.
#supply


2 months ago
Dick's Sporting Goods has been one of the big success stories in the brick-and-mortar retail ***** e.
At a time when many rivals have been shrinking their physical store counts, the sporting goods giant has leaned into stores, creating new experiential concepts and generally rethinking its retail strategy.
The chain has selectively built House of Sport locations that offer running tracks, batting cages, golf simulators, and other interactive options.
"House of Sport locations now seeing 5-6 times the number of visits per location compared to the rest of the chain. For reference, the average ***** 's Sporting Goods store is roughly 50K square feet square feet compared to 100K-120K square feet for House of Sport, indicating that House of Sport is also outperforming on a visit per square foot basis," according to 2024 data from Placer.ai.
That's a win, and the overall company delivered a nearly 5% comparable store sales gain in the second quarter. Chairman Edward Stack celebrated that success during the chain's second-quarter earnings call.
#square
At a time when many rivals have been shrinking their physical store counts, the sporting goods giant has leaned into stores, creating new experiential concepts and generally rethinking its retail strategy.
The chain has selectively built House of Sport locations that offer running tracks, batting cages, golf simulators, and other interactive options.
"House of Sport locations now seeing 5-6 times the number of visits per location compared to the rest of the chain. For reference, the average ***** 's Sporting Goods store is roughly 50K square feet square feet compared to 100K-120K square feet for House of Sport, indicating that House of Sport is also outperforming on a visit per square foot basis," according to 2024 data from Placer.ai.
That's a win, and the overall company delivered a nearly 5% comparable store sales gain in the second quarter. Chairman Edward Stack celebrated that success during the chain's second-quarter earnings call.
#square


2 months ago
For much of the past year, the "AI trade" has been focused on infrastructure: processors, data centers, and cloud capacity. Snowflake Inc. (NYSE:SNOW)'s blowout quarter, which was reported after the market closed on September 2, provided something unique: clear evidence that AI is translating into real, incremental spending within software companies that are closer to the end customer. The reaction echoed throughout corporate software the next morning, adding to a rally that, for Salesforce, Inc. (NYSE:CRM) in particular, had already begun for its own reasons.
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter

2 months ago
Chinese e-commerce giants such as Shein and Temu have reshaped the retail landscape amid economic uncertainty, higher prices, and cautious consumer spending by offering shoppers a wide range of products at extremely low prices.
Their growth has prompted established companies such as Amazon, Target, and Walmart to invest in strategies like third-party marketplaces, supply chain infrastructure, and digital tools to keep pace with changing consumer habits.
Now, one online-first fashion retailer is taking a different approach. While many established brands have been reassessing their physical footprints and closing underperforming stores, this e-commerce fashion company is moving in the opposite direction by expanding its brick-and-mortar presence in the U.S.
Founded in 2020 as an online-first womenswear brand, Cider has built its business around affordable, trend-driven fashion and a digital-focused shopping experience.
Cider opened its second permanent U.S. retail location on September 4, 2026, at Westfield Valley Fair in San Jose, California. The 11,269-square-foot store is located at 2855 Stevens Creek Blvd., ****** e No. 2411.
#fashion #cider #prices #first
Their growth has prompted established companies such as Amazon, Target, and Walmart to invest in strategies like third-party marketplaces, supply chain infrastructure, and digital tools to keep pace with changing consumer habits.
Now, one online-first fashion retailer is taking a different approach. While many established brands have been reassessing their physical footprints and closing underperforming stores, this e-commerce fashion company is moving in the opposite direction by expanding its brick-and-mortar presence in the U.S.
Founded in 2020 as an online-first womenswear brand, Cider has built its business around affordable, trend-driven fashion and a digital-focused shopping experience.
Cider opened its second permanent U.S. retail location on September 4, 2026, at Westfield Valley Fair in San Jose, California. The 11,269-square-foot store is located at 2855 Stevens Creek Blvd., ****** e No. 2411.
#fashion #cider #prices #first


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Today's CD rates still hover well above the national average. The Federal Reserve reduced its target interest rate three times in 2025 and has left rates alone in 2026. This has had a ripple effect on deposit account rates, making now a great opportunity to lock in today's high rates with a certificate of deposit (CD). Here's a look at today's best CD rates and where you can find the best offers.
Today, Monday, September 7, 2026, the highest CD rate is 4.35%. Marcus by Goldman Sachs offers it on its 18-month CD.
Here is a look at some of the best CD rates available today from our verified partners:
If you're considering a CD, these rates are among the highest available, especially compared to the national average, which is significantly lower. It's also worth noting that online banks and credit unions generally offer more competitive rates than traditional brick-and-mortar banks.
#today #look
Today's CD rates still hover well above the national average. The Federal Reserve reduced its target interest rate three times in 2025 and has left rates alone in 2026. This has had a ripple effect on deposit account rates, making now a great opportunity to lock in today's high rates with a certificate of deposit (CD). Here's a look at today's best CD rates and where you can find the best offers.
Today, Monday, September 7, 2026, the highest CD rate is 4.35%. Marcus by Goldman Sachs offers it on its 18-month CD.
Here is a look at some of the best CD rates available today from our verified partners:
If you're considering a CD, these rates are among the highest available, especially compared to the national average, which is significantly lower. It's also worth noting that online banks and credit unions generally offer more competitive rates than traditional brick-and-mortar banks.
#today #look

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Today's CD rates still hover well above the national average. The Federal Reserve reduced its target interest rate three times in 2025 and has left rates alone in 2026. This has had a ripple effect on deposit account rates, making now a great opportunity to lock in today's high rates with a certificate of deposit (CD). Here's a look at today's best CD rates and where you can find the best offers.
Today, Monday, September 7, 2026, the highest CD rate is 4.35%. Marcus by Goldman Sachs offers it on its 18-month CD.
Here is a look at some of the best CD rates available today from our verified partners:
If you're considering a CD, these rates are among the highest available, especially compared to the national average, which is significantly lower. It's also worth noting that online banks and credit unions generally offer more competitive rates than traditional brick-and-mortar banks.
#national #average #deposit #highest
Today's CD rates still hover well above the national average. The Federal Reserve reduced its target interest rate three times in 2025 and has left rates alone in 2026. This has had a ripple effect on deposit account rates, making now a great opportunity to lock in today's high rates with a certificate of deposit (CD). Here's a look at today's best CD rates and where you can find the best offers.
Today, Monday, September 7, 2026, the highest CD rate is 4.35%. Marcus by Goldman Sachs offers it on its 18-month CD.
Here is a look at some of the best CD rates available today from our verified partners:
If you're considering a CD, these rates are among the highest available, especially compared to the national average, which is significantly lower. It's also worth noting that online banks and credit unions generally offer more competitive rates than traditional brick-and-mortar banks.
#national #average #deposit #highest


2 months ago
On August 5, LiveRamp (NYSE:RAMP) reported first-quarter fiscal 2027 results for the period ended June 30, and the numbers looked less like a company coasting toward a sale than one hitting its stride. Revenue rose 10% to $214 million, but the more striking move was further down the income statement, where operating income more than doubled. LiveRamp skipped its usual earnings call this quarter, a direct result of its pending acquisition by Publicis Groupe, but that silence has not slowed the underlying business.
GAAP operating income jumped to $20 million from $7 million a year earlier, pushing operating margin up six points to 9%. Non-GAAP operating income rose 41% to $50 million, with margin expanding five points to 24%, meaning more of every new revenue dollar is dropping to profit rather than being spent to chase it. Diluted earnings per share more than doubled on a GAAP basis to $0.28 from $0.12, while operating cash flow flipped from a $16 million outflow a year ago to $17 million generated this quarter.
LiveRamp is also positioning itself inside the AI advertising buildout rather than at its edges. The company launched LiveRamp Agent Builders, a program pulling outside AI agents into its network for planning and measurement work, and added integrations tied to OpenAI's advertising tools, Databricks' new Agentic Customer Data Platform, and Adobe's commerce content pipeline, alongside a measurement partnership with DoorDash. None of that shows up in a revenue line yet, but customer behavior already reflects some payoff. LiveRamp ended the quarter with 132 customers paying more than $1 million a year, up from 127, and subscription net retention held at 103%. Annualized recurring revenue grew 7% to $539 million, and Data Marketplace revenue climbed 13% to $40 million.
None of that operational improvement changes the number shareholders actually care about: $38.50 a share, the all-cash price Publicis Groupe agreed to pay when the deal was announced on May 17, 2026. However much operating income grows from here, the merger agreement fixes what LiveRamp holders collect if the transaction closes, so this quarter's beat does not translate into upside for anyone holding the stock for the buyout. LiveRamp also confirmed it will not hold a conference call or issue guidance while the deal is pending, which limits how much investors can independently verify beyond what is in this release.
The transaction still has to clear a shareholder vote scheduled for August 17, and closing remains subject to customary conditions even though management called it on track for before the end of calendar 2026. That leaves a few weeks of real, if narrow, uncertainty. The growth numbers are also decelerating slightly at the edges: total revenue grew 10% this quarter versus 11% in the prior year period, and subscription revenue growth slowed to 8% from 10%. Marketplace and Other revenue, the more variable, usage-driven part of the business, is doing more of the work
GAAP operating income jumped to $20 million from $7 million a year earlier, pushing operating margin up six points to 9%. Non-GAAP operating income rose 41% to $50 million, with margin expanding five points to 24%, meaning more of every new revenue dollar is dropping to profit rather than being spent to chase it. Diluted earnings per share more than doubled on a GAAP basis to $0.28 from $0.12, while operating cash flow flipped from a $16 million outflow a year ago to $17 million generated this quarter.
LiveRamp is also positioning itself inside the AI advertising buildout rather than at its edges. The company launched LiveRamp Agent Builders, a program pulling outside AI agents into its network for planning and measurement work, and added integrations tied to OpenAI's advertising tools, Databricks' new Agentic Customer Data Platform, and Adobe's commerce content pipeline, alongside a measurement partnership with DoorDash. None of that shows up in a revenue line yet, but customer behavior already reflects some payoff. LiveRamp ended the quarter with 132 customers paying more than $1 million a year, up from 127, and subscription net retention held at 103%. Annualized recurring revenue grew 7% to $539 million, and Data Marketplace revenue climbed 13% to $40 million.
None of that operational improvement changes the number shareholders actually care about: $38.50 a share, the all-cash price Publicis Groupe agreed to pay when the deal was announced on May 17, 2026. However much operating income grows from here, the merger agreement fixes what LiveRamp holders collect if the transaction closes, so this quarter's beat does not translate into upside for anyone holding the stock for the buyout. LiveRamp also confirmed it will not hold a conference call or issue guidance while the deal is pending, which limits how much investors can independently verify beyond what is in this release.
The transaction still has to clear a shareholder vote scheduled for August 17, and closing remains subject to customary conditions even though management called it on track for before the end of calendar 2026. That leaves a few weeks of real, if narrow, uncertainty. The growth numbers are also decelerating slightly at the edges: total revenue grew 10% this quarter versus 11% in the prior year period, and subscription revenue growth slowed to 8% from 10%. Marketplace and Other revenue, the more variable, usage-driven part of the business, is doing more of the work


2 months ago
On August 25, Box Inc. (NYSE:BOX) reported second-quarter fiscal 2027 results that beat management's own guidance across the board, with revenue climbing 9% to $321.1 million as customers piled into the company's priciest tier, Enterprise Advanced. The bigger story sits underneath the headline number. Box is repositioning itself as the security layer that lets AI agents from Anthropic, Databricks, and Slack actually touch a company's files, and that shift is starting to show up in the billings line.
Billings jumped 17% to $309.5 million, a figure management tied directly to booking strength and record second-quarter wins, which suggests customers are signing bigger contracts rather than trickling in seat by seat. Net retention rose to 106%, ahead of the 105% the company had guided to, driven by both seat expansion and higher price per seat. That combination matters because it means existing customers are both growing their headcount on the platform and paying more per person, a dual engine that is harder to replicate than growth from new logos alone. Suites, Box's bundled higher-tier offering, now make up 69% of revenue, up from 63% a year earlier, and customers paying at least $100,000 annually grew 10% year over year.
A major federal agency illustrated the pattern in the flesh, upgrading to Enterprise Advanced with a fourfold seat expansion to replace several separate software vendors it had been using for contract management and research. Operating margin expanded to 29.4%, and free cash flow jumped 67% to $59.7 million, evidence that the growth is not being bought with discounts. Box also introduced new Model Context Protocol integrations with partners including Anthropic, Databricks, and Slack, letting AI agents execute multistep tasks directly inside a customer's Box environment rather than just answering questions about files stored there.
Not everything in the quarter was clean. CFO Dylan Smith flagged that gross margin faces a constraint tied to "limited access to certain components of the infrastructure," language that points to capacity limits at the cloud providers Box relies on to run its AI features, and management guided third-quarter gross margin down to roughly 80.5% from the 81.2% just posted. Operating margin guidance for the third quarter also steps down to about 28%, a full percentage point below the 29.4% Box just delivered, even as the top line keeps growing.
Currency is another drag that will not disappear on its own. The company absorbed a $0.04 per share hit from foreign exchange in the quarter and expects roughly $0.09 off full-year earnings per share, which is baked into the raised full-year EPS guidance of $1.54. And while 9% reported revenue growth beat expectations, it is still a business growing in the high single digits, a pace that leaves little room for stumbles if Enterprise Advanced adoption cools or larger AI platforms decide to build competing file-governance tools of their own rather than partner with B
Billings jumped 17% to $309.5 million, a figure management tied directly to booking strength and record second-quarter wins, which suggests customers are signing bigger contracts rather than trickling in seat by seat. Net retention rose to 106%, ahead of the 105% the company had guided to, driven by both seat expansion and higher price per seat. That combination matters because it means existing customers are both growing their headcount on the platform and paying more per person, a dual engine that is harder to replicate than growth from new logos alone. Suites, Box's bundled higher-tier offering, now make up 69% of revenue, up from 63% a year earlier, and customers paying at least $100,000 annually grew 10% year over year.
A major federal agency illustrated the pattern in the flesh, upgrading to Enterprise Advanced with a fourfold seat expansion to replace several separate software vendors it had been using for contract management and research. Operating margin expanded to 29.4%, and free cash flow jumped 67% to $59.7 million, evidence that the growth is not being bought with discounts. Box also introduced new Model Context Protocol integrations with partners including Anthropic, Databricks, and Slack, letting AI agents execute multistep tasks directly inside a customer's Box environment rather than just answering questions about files stored there.
Not everything in the quarter was clean. CFO Dylan Smith flagged that gross margin faces a constraint tied to "limited access to certain components of the infrastructure," language that points to capacity limits at the cloud providers Box relies on to run its AI features, and management guided third-quarter gross margin down to roughly 80.5% from the 81.2% just posted. Operating margin guidance for the third quarter also steps down to about 28%, a full percentage point below the 29.4% Box just delivered, even as the top line keeps growing.
Currency is another drag that will not disappear on its own. The company absorbed a $0.04 per share hit from foreign exchange in the quarter and expects roughly $0.09 off full-year earnings per share, which is baked into the raised full-year EPS guidance of $1.54. And while 9% reported revenue growth beat expectations, it is still a business growing in the high single digits, a pace that leaves little room for stumbles if Enterprise Advanced adoption cools or larger AI platforms decide to build competing file-governance tools of their own rather than partner with B

2 months ago
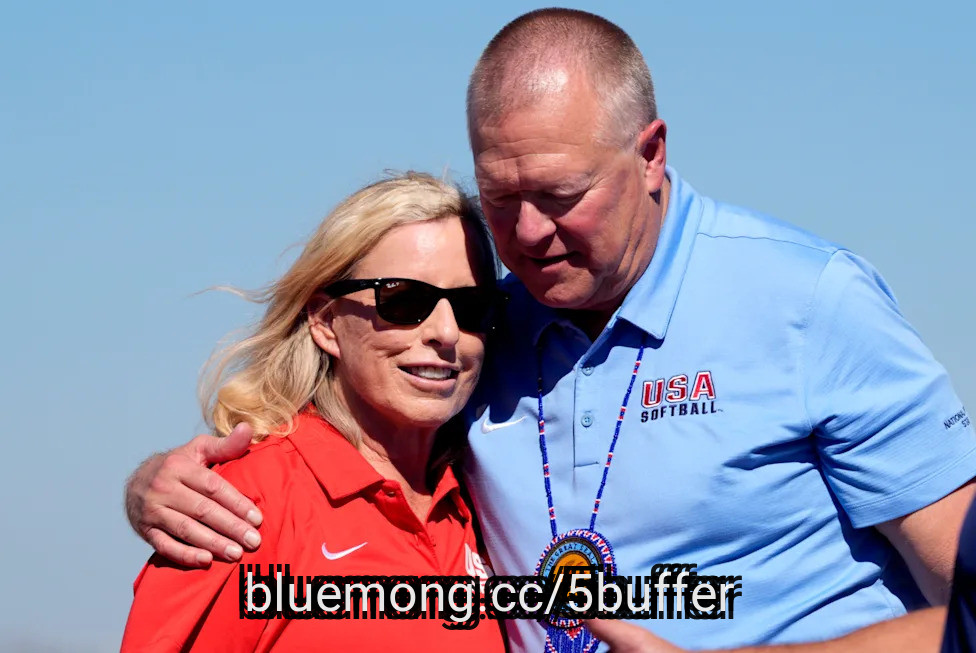
Oklahoma City and USA Softball have broken ground on the Choctaw Nation Fieldhouse, a new indoor softball practice facility at Devon Park.
The 30,000-square-foot, split-level brick building is expected to help secure Devon Park as the home of the NCAA Women's College World Series beyond 2035, according to a news release
The facility will include two indoor practice infields, team locker rooms, and areas for sports medicine, player development and administration. An enclosed, climate-controlled connection will link the fieldhouse to the stadium, allowing staff, coaches and players to move between the buildings without exposure to weather.
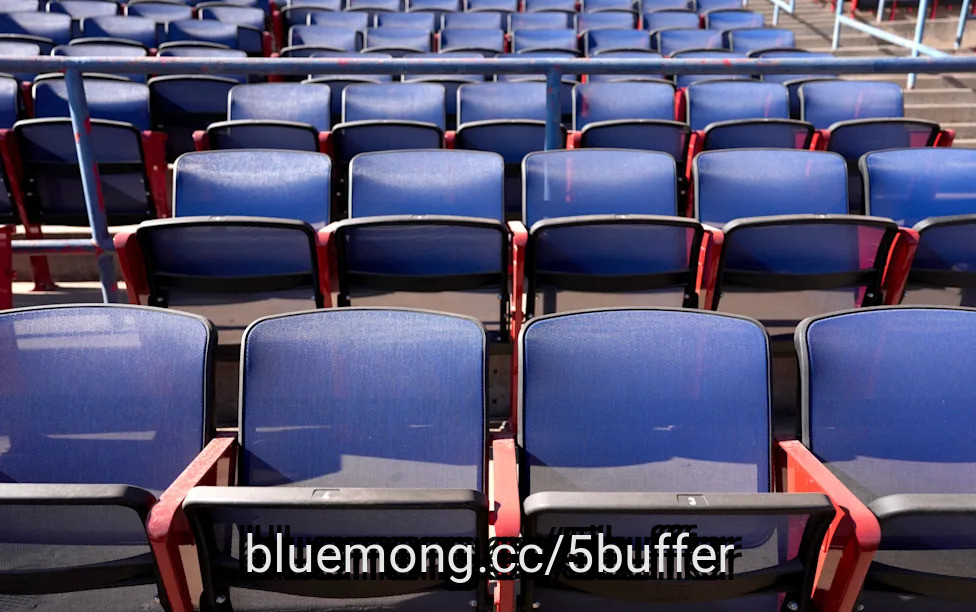
The $21 million project is funded through the OKC 2025 Bond. The Oklahoma Department of Commerce contributed $8 million for stadium improvements, including new chairback seating, improved practice fields, upgraded sound system and protective features.
"This will be a premier softball performance training facility that continues to grow the softball community nationally," Public Works Director Debbie Miller said in a news release. "Our goal is for this to be designated as a United States Olympic and Paralympic Committee training site and to help secure Oklahoma City as the home of the NCAA Women's College World Series beyond 2035."
#park
The 30,000-square-foot, split-level brick building is expected to help secure Devon Park as the home of the NCAA Women's College World Series beyond 2035, according to a news release
The facility will include two indoor practice infields, team locker rooms, and areas for sports medicine, player development and administration. An enclosed, climate-controlled connection will link the fieldhouse to the stadium, allowing staff, coaches and players to move between the buildings without exposure to weather.
The $21 million project is funded through the OKC 2025 Bond. The Oklahoma Department of Commerce contributed $8 million for stadium improvements, including new chairback seating, improved practice fields, upgraded sound system and protective features.
"This will be a premier softball performance training facility that continues to grow the softball community nationally," Public Works Director Debbie Miller said in a news release. "Our goal is for this to be designated as a United States Olympic and Paralympic Committee training site and to help secure Oklahoma City as the home of the NCAA Women's College World Series beyond 2035."
#park

2 months ago
Symbotic (NASDAQ: SYM), a developer of autonomous warehouse robots, went public through a merger with a special purpose acquisition company (SPAC) on June 8, 2022. It started trading at $10.51 per share, closed at a record high of $87.30 on Nov. 26, 2025, but now trades at $38.
Symbotic is still a divisive stock. The bulls are impressed by its robust revenue growth, its expanding margins, and its growing backlog -- which reached $22.5 billion in its latest quarter. But the bears will warn you that it's overly dependent on Walmart (NASDAQ: WMT) and that many investors overlook that customer concentration risk.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Walmart is Symbotic's largest customer and one of its top investors. The world's largest retailer accounted for 85% of its revenue in fiscal 2025 (which ended last September), driven by a long-term contract to automate all of its U.S. regional distribution centers through 2037.
Symbotic also acquired Walmart's own robotics division in early 2025, and the two companies have been co-developing automated micro-fulfillment systems for its brick-and-mortar stores. In other words, Symbotic wouldn't exist in its current form without Walmart's support.
#NVIDIA #walmart #flashing #revenue
Symbotic is still a divisive stock. The bulls are impressed by its robust revenue growth, its expanding margins, and its growing backlog -- which reached $22.5 billion in its latest quarter. But the bears will warn you that it's overly dependent on Walmart (NASDAQ: WMT) and that many investors overlook that customer concentration risk.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Walmart is Symbotic's largest customer and one of its top investors. The world's largest retailer accounted for 85% of its revenue in fiscal 2025 (which ended last September), driven by a long-term contract to automate all of its U.S. regional distribution centers through 2037.
Symbotic also acquired Walmart's own robotics division in early 2025, and the two companies have been co-developing automated micro-fulfillment systems for its brick-and-mortar stores. In other words, Symbotic wouldn't exist in its current form without Walmart's support.
#NVIDIA #walmart #flashing #revenue

2 months ago
Azariah Levells is back — and right on time, too.
A New Mexico district judge granted the Lobo cornerback's motion for an expedited temporary restraining order against the NCAA on Monday, allowing him to return to UNM for the time being.
While the fifth-year senior's restraining order is based only on preliminary findings, it made him eligible to rejoin UNM's roster ahead of Monday's cutoff date. Levells has since returned to practice and will be available to play Saturday in the Lobos' season opener against Central Michigan.
"The ordinary time required to notice and brief this motion would itself moot the relief sought and inflict the very harm (Levells) seeks to avoid," read the court order signed by Judge Beatrice Brickhouse of the 2nd Judicial District Court.
But unlike Brett Karhu — another Lobo granted a restraining order last week — Levells likely has more work to do. His motion was filed ex parte, meaning the NCAA has had no opportunity to respond.
#motion #lobo
A New Mexico district judge granted the Lobo cornerback's motion for an expedited temporary restraining order against the NCAA on Monday, allowing him to return to UNM for the time being.
While the fifth-year senior's restraining order is based only on preliminary findings, it made him eligible to rejoin UNM's roster ahead of Monday's cutoff date. Levells has since returned to practice and will be available to play Saturday in the Lobos' season opener against Central Michigan.
"The ordinary time required to notice and brief this motion would itself moot the relief sought and inflict the very harm (Levells) seeks to avoid," read the court order signed by Judge Beatrice Brickhouse of the 2nd Judicial District Court.
But unlike Brett Karhu — another Lobo granted a restraining order last week — Levells likely has more work to do. His motion was filed ex parte, meaning the NCAA has had no opportunity to respond.
#motion #lobo


2 months ago
CHICAGO — On the last day of June, the flags danced in a stiff wind above Wrigley Field and Moe Mullins arrived more than three hours before first pitch, just like usual. He set up his camping chair under the ash tree at the corner of Waveland and Kenmore, across the street from the back of the left-field bleachers, and the neighborhood slowly came to life.
In time, the street vendors appeared and the merchandise stands opened and the patio at Murphy's, a block away, started to fill in. Soon, the spectators gathered along the brick wall and waited for the bleacher gates to open. For a while, though, it was quiet, and the last refuge of old Wrigley, and its old neighborhood, belonged to Mullins.
He is the unofficial mayor of Waveland and Kenmore avenues, the elder statesman among the characters who give it character. The Chicago Cubs this weekend celebrated their 150th anniversary as a National League member. They've spent 110 of those years at Wrigley, where the corner just beyond left field remains old-school, a small throwback in the middle of ever-expanding change.
The Cubs have bought up many of the nearby buildings. The rooftops are a little less organically charming and a lot more expensive. Trendy bars and restaurants have moved in all over. Even Wrigley's iconic marquee comes with a corporate sponsor, and has for more than a decade.
The corner, though, remains the corner. Lawn chairs. Lifers. Good banter, some of which is even suitable for children. The most prominent ad there is handwritten, for the Gatorade that Dave Davison sells out of a cooler: $3 for Cubs fans and $4 for Cards fans, with the $5 for White Sox fans crossed out and replaced with "stay thirsty."
#wrigley #fans
In time, the street vendors appeared and the merchandise stands opened and the patio at Murphy's, a block away, started to fill in. Soon, the spectators gathered along the brick wall and waited for the bleacher gates to open. For a while, though, it was quiet, and the last refuge of old Wrigley, and its old neighborhood, belonged to Mullins.
He is the unofficial mayor of Waveland and Kenmore avenues, the elder statesman among the characters who give it character. The Chicago Cubs this weekend celebrated their 150th anniversary as a National League member. They've spent 110 of those years at Wrigley, where the corner just beyond left field remains old-school, a small throwback in the middle of ever-expanding change.
The Cubs have bought up many of the nearby buildings. The rooftops are a little less organically charming and a lot more expensive. Trendy bars and restaurants have moved in all over. Even Wrigley's iconic marquee comes with a corporate sponsor, and has for more than a decade.
The corner, though, remains the corner. Lawn chairs. Lifers. Good banter, some of which is even suitable for children. The most prominent ad there is handwritten, for the Gatorade that Dave Davison sells out of a cooler: $3 for Cubs fans and $4 for Cards fans, with the $5 for White Sox fans crossed out and replaced with "stay thirsty."
#wrigley #fans


2 months ago
On Tuesday, Lego posted a record first-half of 41.9 billion Danish kroner, or roughly $6.5 billion, in revenue — up 21% from the same period in 2025. In constant currency terms, revenue grew 26%.
The company said operating profit climbed 22% to reach 10.9 billion Danish kroner, equivalent to around $1.7 billion. Net profit climbed 32% to 8.6 billion Danish kroner. Consumer sales grew 22%, driven by demand across the product range. The company said it outpaced the global toy market and gained market share.
CEO Niels B. Christiansen said the results reflected broad appeal across the portfolio. "Our portfolio of products offers something for everyone, and culturally relevant brand experiences continue to drive demand across the globe," Christiansen said in a statement.
In the first half of the year, Lego introduced 332 new sets. Bestselling themes included Speed Champions, Botanicals, Technic, Icons and Star Wars. The company also introduced its LEGO SMART Play platform, which brings sensor-based interactive features to brick sets, and debuted a partnership with Pokémon. Sporting partnerships tied to Formula 1, the FIFA World Cup 2026 and K-pop property KPop Demon Hunters also contributed to consumer demand.
Christiansen told CNBC that new partnerships draw in consumers who had not previously found their interests represented in the Lego brand. "We've also seen that we retain consumers really, really well, and we're selling more to those we have," he said.
#danish #christiansen #kroner
The company said operating profit climbed 22% to reach 10.9 billion Danish kroner, equivalent to around $1.7 billion. Net profit climbed 32% to 8.6 billion Danish kroner. Consumer sales grew 22%, driven by demand across the product range. The company said it outpaced the global toy market and gained market share.
CEO Niels B. Christiansen said the results reflected broad appeal across the portfolio. "Our portfolio of products offers something for everyone, and culturally relevant brand experiences continue to drive demand across the globe," Christiansen said in a statement.
In the first half of the year, Lego introduced 332 new sets. Bestselling themes included Speed Champions, Botanicals, Technic, Icons and Star Wars. The company also introduced its LEGO SMART Play platform, which brings sensor-based interactive features to brick sets, and debuted a partnership with Pokémon. Sporting partnerships tied to Formula 1, the FIFA World Cup 2026 and K-pop property KPop Demon Hunters also contributed to consumer demand.
Christiansen told CNBC that new partnerships draw in consumers who had not previously found their interests represented in the Lego brand. "We've also seen that we retain consumers really, really well, and we're selling more to those we have," he said.
#danish #christiansen #kroner

2 months ago
Investors know that most dividend stocks dish out their payments on a quarterly basis. That's not a regulatory requirement, though. These companies can pay this money out at any cadence they like, including a monthly one. Some of them do so, in fact, including real estate investment trust Realty Income (NYSE: O).
To this end, how much monthly income would a $30,000 holding in Realty Income generate right now?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you're not familiar with it, like all other real estate investment trusts -- or REITs -- this one owns revenue-bearing real estate. However, even by REIT standards, Realty Income is unique. It specializes in serving as a landlord to the brick-and-mortar retailing industry. Its top tenants include Dollar General, Walgreens, and 7-Eleven.
The industry focus clearly works, too. Not only has the company paid a monthly dividend like clockwork for decades, but it has also raised its per-share payment for 31 consecutive years. Indeed, it's raised its dividend every quarter for almost 29 years.
#realty #signal #like #estate
To this end, how much monthly income would a $30,000 holding in Realty Income generate right now?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you're not familiar with it, like all other real estate investment trusts -- or REITs -- this one owns revenue-bearing real estate. However, even by REIT standards, Realty Income is unique. It specializes in serving as a landlord to the brick-and-mortar retailing industry. Its top tenants include Dollar General, Walgreens, and 7-Eleven.
The industry focus clearly works, too. Not only has the company paid a monthly dividend like clockwork for decades, but it has also raised its per-share payment for 31 consecutive years. Indeed, it's raised its dividend every quarter for almost 29 years.
#realty #signal #like #estate

2 months ago
This story was originally published on Payments Dive. To receive daily news and insights, subscribe to our free daily Payments Dive newsletter.
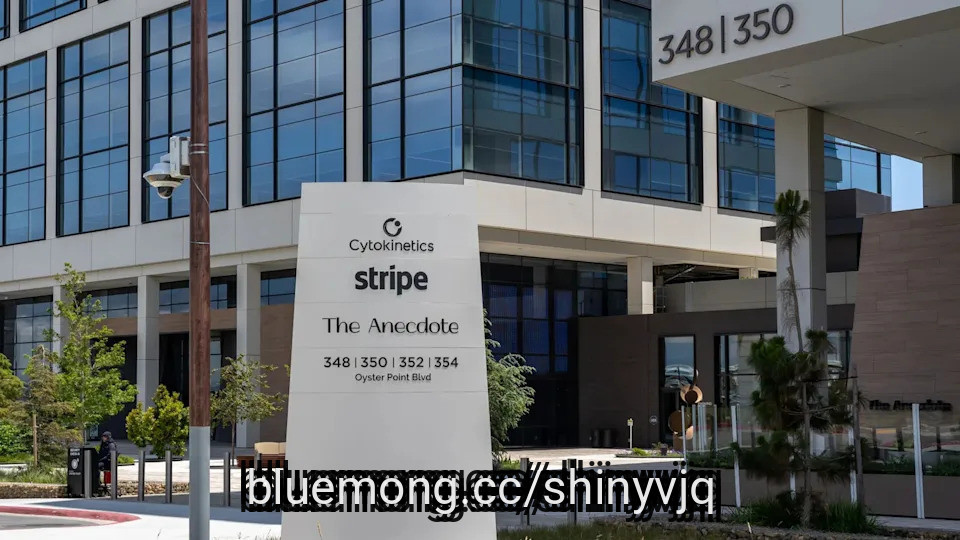
Stripe's top executives observe a "growing advantage" of remaining a privately held company, they said in a letter to investors last week.
This year marked the start of what Stripe executives called "a large inflection in long-run trends," fueled by artificial intelligence, wrote John and Patrick Collison, the Irish brothers who co-founded Stripe in 2010 and still lead it.
Being a private company offers "a growing advantage as we venture into the vicissitudes" of this era, they wrote on Wednesday. The letter was also signed by Will Gaybrick, Stripe's president of technology and business. Patrick Collison is the company's chief executive and John Collison is its president.
A Stripe spokesperson on Thursday confirmed the authenticity of the letter, which was first reported by Axios, the newsletter publisher.
#collison #letter #patrick #daily
Stripe's top executives observe a "growing advantage" of remaining a privately held company, they said in a letter to investors last week.
This year marked the start of what Stripe executives called "a large inflection in long-run trends," fueled by artificial intelligence, wrote John and Patrick Collison, the Irish brothers who co-founded Stripe in 2010 and still lead it.
Being a private company offers "a growing advantage as we venture into the vicissitudes" of this era, they wrote on Wednesday. The letter was also signed by Will Gaybrick, Stripe's president of technology and business. Patrick Collison is the company's chief executive and John Collison is its president.
A Stripe spokesperson on Thursday confirmed the authenticity of the letter, which was first reported by Axios, the newsletter publisher.
#collison #letter #patrick #daily

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Today's CD rates still hover well above the national average. The Federal Reserve reduced its target interest rate three times in 2025 and has left rates alone in 2026. This has had a ripple effect on deposit account rates, making now a great opportunity to lock in today's high rates with a certificate of deposit (CD). Here's a look at today's best CD rates and where you can find the best offers.
Today, Monday, August 24, 2026, the highest CD rate is 4.35%. This rate is offered by Sallie Mae on its 3-year CD.
Here is a look at some of the best CD rates available today from our verified partners.
If you're considering a CD, these rates are among the highest available, especially compared to the national average, which is significantly lower. It's also worth noting that online banks and credit unions generally offer more competitive rates than traditional brick-and-mortar banks.
#rate #average #deposit
Today's CD rates still hover well above the national average. The Federal Reserve reduced its target interest rate three times in 2025 and has left rates alone in 2026. This has had a ripple effect on deposit account rates, making now a great opportunity to lock in today's high rates with a certificate of deposit (CD). Here's a look at today's best CD rates and where you can find the best offers.
Today, Monday, August 24, 2026, the highest CD rate is 4.35%. This rate is offered by Sallie Mae on its 3-year CD.
Here is a look at some of the best CD rates available today from our verified partners.
If you're considering a CD, these rates are among the highest available, especially compared to the national average, which is significantly lower. It's also worth noting that online banks and credit unions generally offer more competitive rates than traditional brick-and-mortar banks.
#rate #average #deposit

2 months ago
Retailers' Walmart Inc. (NASDAQ:WMT) and Target Corporation (NYSE:TGT)'s shares are on two opposite spectrums when it comes to year-to-date performance. The latter's stock is down by 8% whole the latter is up by 64%. Cramer discussed the divergence between the two stocks and outlined that while he believed Walmart Inc. (NASDAQ:WMT)'s share price troubles had led to as tock that was too cheap, he didn't think the shares could drop further in terms of valuation:
"The one that I want to. . .I think Walmart is, I think you buy it and then you buy it after. Because we have not seen, Walmart does have a high PE, but I think it's worthy of it.
"I know that John Furner's unproven, as CEO. But I would say that Mr. McMillan, I love him and I think he's taught him well. And you still have John David Rainey there. I just feel like this is the stock that has already come down. I don't think it's going to get to a 20 PE ever again, I think it's got too much growth. But I recognize, it's unloved, it's only up 2.5%, everyone loves Target. And I do like the new management of Target and the comparisons are very easy. But Target's up 57%, 18 times earnings. . ."
Walmart Inc. (NASDAQ:WMT)'s shares haven't had a good week. They closed a painful 9% lower on August 20th after it reported its earnings in the morning. Had viewers bought the shares on Cramer's remarks, they would have missed an opportunity to utilize a major dip that occurred later in the week, as he had made the remarks on the 17th. The central theme for Walmart Inc. (NASDAQ:WMT), following the earnings, is whether the firm's gains in the online segment will transform into sustainable gains for the income statement. Starting from the basics, the firm beat ***** yst revenue and earnings estimates for its fiscal Q2.
While revenue in Q2 grew by 5.9%, Walmart Inc. (NASDAQ:WMT)'s global eCommerce sales jumped by 23% to significantly outpace revenue growth. More importantly, the firm also claimed that 50% US marketplace volume was through its fulfilment services. Additionally, media reports have also suggested that Walmart Inc. (NASDAQ:WMT) has managed to grow its digital advertising business by 26% annually to further complement its online growth. Yet, at the same time, the firm's status as a brick-and-mortar retailer generates worries about the impact of a consumer slowdown on the business. Walmart Inc. (NASDAQ:WMT)'s Q3 guidance for revenue growth and EPS undershot ***** yst estimates. Additionally, the firm also warned about $2 billion in incremental fuel costs in FY2027 and a dip in free cash flow.
#NASDAQ
"The one that I want to. . .I think Walmart is, I think you buy it and then you buy it after. Because we have not seen, Walmart does have a high PE, but I think it's worthy of it.
"I know that John Furner's unproven, as CEO. But I would say that Mr. McMillan, I love him and I think he's taught him well. And you still have John David Rainey there. I just feel like this is the stock that has already come down. I don't think it's going to get to a 20 PE ever again, I think it's got too much growth. But I recognize, it's unloved, it's only up 2.5%, everyone loves Target. And I do like the new management of Target and the comparisons are very easy. But Target's up 57%, 18 times earnings. . ."
Walmart Inc. (NASDAQ:WMT)'s shares haven't had a good week. They closed a painful 9% lower on August 20th after it reported its earnings in the morning. Had viewers bought the shares on Cramer's remarks, they would have missed an opportunity to utilize a major dip that occurred later in the week, as he had made the remarks on the 17th. The central theme for Walmart Inc. (NASDAQ:WMT), following the earnings, is whether the firm's gains in the online segment will transform into sustainable gains for the income statement. Starting from the basics, the firm beat ***** yst revenue and earnings estimates for its fiscal Q2.
While revenue in Q2 grew by 5.9%, Walmart Inc. (NASDAQ:WMT)'s global eCommerce sales jumped by 23% to significantly outpace revenue growth. More importantly, the firm also claimed that 50% US marketplace volume was through its fulfilment services. Additionally, media reports have also suggested that Walmart Inc. (NASDAQ:WMT) has managed to grow its digital advertising business by 26% annually to further complement its online growth. Yet, at the same time, the firm's status as a brick-and-mortar retailer generates worries about the impact of a consumer slowdown on the business. Walmart Inc. (NASDAQ:WMT)'s Q3 guidance for revenue growth and EPS undershot ***** yst estimates. Additionally, the firm also warned about $2 billion in incremental fuel costs in FY2027 and a dip in free cash flow.
#NASDAQ
3 months ago
With two races remaining in the regular season, the NASCAR Cup Series heads north this week for the Dollar Tree 301 at New Hampshire Motor Speedway.
The winner of five of the first nine races this season, Tyler Reddick is the pole-sitter for Sunday's race in Loudon, New Hampshire. It's Reddick's first pole win since April at Kansas, and he's aiming for his first victory since then as well. The driver of the No. 45 Toyota for 23XI Racing is fighting through a bit of a midseason slump as he's finished 25th or worse in six of the last 10 races.
Reddick has had some solid results mixed in there, running second at Pocono, finishing inside the top-10 at Atlanta and the Brickyard 400, and salvaging an 11th-place finish last weekend at Richmond after catching a caution at the right time. Reddick's team could use a victory this weekend to build some momentum ahead of the postseason Chase.
"We fight through those hard days very well as a team. When we get into the Chase — I mean, ideally on paper, you don't want to have a bad race, but when it does happen, you know it's important to respond the right way," Reddick told USA TODAY Sports this week. "And I feel like our team does that. When something goes wrong, we don't just throw our hands up in the air and start complaining. We get to work. We start figuring out ways that we can make the most of the day or get out of the hole completely and still try and win the race."
Josh Berry will join Reddick on the front row and is aiming for what would be his fourth consecutive top 10 finish — something the 35-year-old has never pulled off before in his Cup Series career. Berry, driving the No. 21 Ford for Wood Brothers, ran second at New Hampshire last season.
#reddick
The winner of five of the first nine races this season, Tyler Reddick is the pole-sitter for Sunday's race in Loudon, New Hampshire. It's Reddick's first pole win since April at Kansas, and he's aiming for his first victory since then as well. The driver of the No. 45 Toyota for 23XI Racing is fighting through a bit of a midseason slump as he's finished 25th or worse in six of the last 10 races.
Reddick has had some solid results mixed in there, running second at Pocono, finishing inside the top-10 at Atlanta and the Brickyard 400, and salvaging an 11th-place finish last weekend at Richmond after catching a caution at the right time. Reddick's team could use a victory this weekend to build some momentum ahead of the postseason Chase.
"We fight through those hard days very well as a team. When we get into the Chase — I mean, ideally on paper, you don't want to have a bad race, but when it does happen, you know it's important to respond the right way," Reddick told USA TODAY Sports this week. "And I feel like our team does that. When something goes wrong, we don't just throw our hands up in the air and start complaining. We get to work. We start figuring out ways that we can make the most of the day or get out of the hole completely and still try and win the race."
Josh Berry will join Reddick on the front row and is aiming for what would be his fourth consecutive top 10 finish — something the 35-year-old has never pulled off before in his Cup Series career. Berry, driving the No. 21 Ford for Wood Brothers, ran second at New Hampshire last season.
#reddick


3 months ago
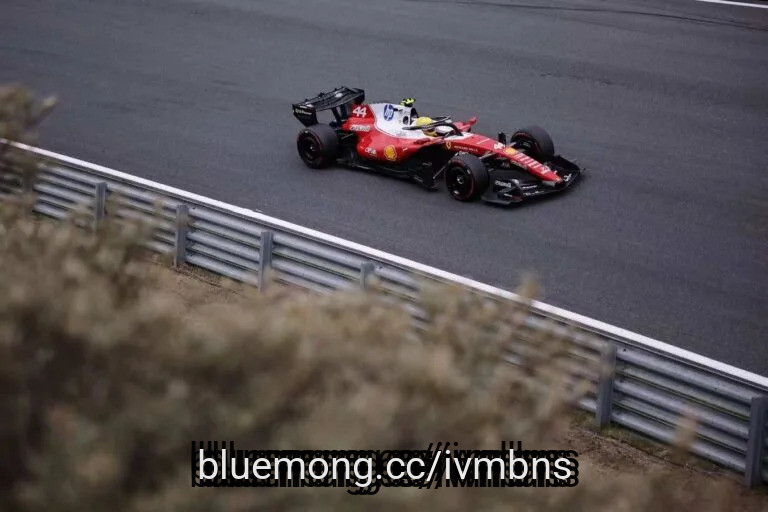
Lewis Hamilton felt much better in the car in the F1 Dutch Grand Prix qualifying, but confidence dented on Friday with tyres being the main culprit, as he struggled to work it and locked-up at Turn 1.
After a low-key return in both F1 Dutch GP sprint qualifying and also the race due to wrong set-up choice, Ferrari's Hamilton found something in the main qualifying but could only manage fifth in the end, behind both the McLaren and Mercedes pair.
He managed to beat teammate Charles Leclerc, but his confidence was dented on Friday itself, not giving him enough time to adjust to changes post-sprint as much. He is hopeful still of a better result, as he feels the race pace will be better than the one-lap pace was.
"Yeah, much, much happier with the car in quali, thankfully," said Hamilton to media after F1 Dutch GP qualifying. "But it's not that helpful when it comes to building confidence, it's like you're putting brick by brick, you're putting down building a wall, knock down that confidence that I had in FP1, didn't have it through sprint qualifying, and then I just basically was starting again building.
"But the car was much better and much happier with it. I'm excited for tomorrow." It was not easy especially in Q3 with the threat of rain. The Ferrari F1 cars were struggling to get temperature into the tyres. Hamilton kept on locking going into Turn 1 throughout qualifying.
#much #qualifying #hamilton #better
After a low-key return in both F1 Dutch GP sprint qualifying and also the race due to wrong set-up choice, Ferrari's Hamilton found something in the main qualifying but could only manage fifth in the end, behind both the McLaren and Mercedes pair.
He managed to beat teammate Charles Leclerc, but his confidence was dented on Friday itself, not giving him enough time to adjust to changes post-sprint as much. He is hopeful still of a better result, as he feels the race pace will be better than the one-lap pace was.
"Yeah, much, much happier with the car in quali, thankfully," said Hamilton to media after F1 Dutch GP qualifying. "But it's not that helpful when it comes to building confidence, it's like you're putting brick by brick, you're putting down building a wall, knock down that confidence that I had in FP1, didn't have it through sprint qualifying, and then I just basically was starting again building.
"But the car was much better and much happier with it. I'm excited for tomorrow." It was not easy especially in Q3 with the threat of rain. The Ferrari F1 cars were struggling to get temperature into the tyres. Hamilton kept on locking going into Turn 1 throughout qualifying.
#much #qualifying #hamilton #better
3 months ago
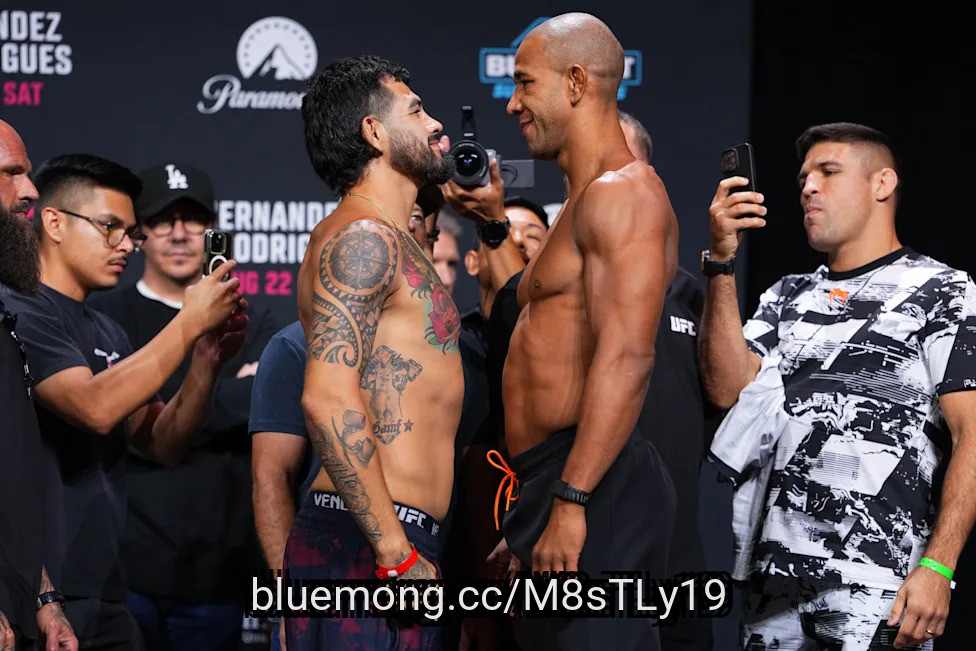
Uncrowned has UFC Sacramento live results, round-by-round updates, highlights and start time for the Anthony Hernandez vs. Gregory Rodrigues fight card on Saturday night at the Golden 1 Center in Sacramento, California. UFC middleweight veterans Anthony Hernandez and Gregory Rodrigues collide in the evening's five-round main event.
Hernandez (15-3, 1 NC) is hoping to get back on track after seeing his eight-fight win streak smash into the brick wall that was Sean Strickland in February. Prior to that setback, Hernandez scored big finishes of Roman Dolidze, Michel Pereira and Roman Kopylov, among others, to push his way to the precipice of **** le contention.
Rodrigues (19-6) returns to his second UFC main event on the heels of a three-fight run of victories over Jack Hermansson, Kopylov and Brunno Ferreira. "Robocop" has proven to be a ferocious finisher over his UFC tenure, ending seven of his 10 promotional victories via brutal knockouts.
UFC Sacramento starts at 5 p.m. ET with a seven-fight preliminary card on Paramount+. The six-fight main card kicks off at 8 p.m. ET on Paramount+.
Follow along with Uncrowned's live UFC Sacramento results, highlights and live blog below, including round-by-round play-by-play for the main event.
#live
Hernandez (15-3, 1 NC) is hoping to get back on track after seeing his eight-fight win streak smash into the brick wall that was Sean Strickland in February. Prior to that setback, Hernandez scored big finishes of Roman Dolidze, Michel Pereira and Roman Kopylov, among others, to push his way to the precipice of **** le contention.
Rodrigues (19-6) returns to his second UFC main event on the heels of a three-fight run of victories over Jack Hermansson, Kopylov and Brunno Ferreira. "Robocop" has proven to be a ferocious finisher over his UFC tenure, ending seven of his 10 promotional victories via brutal knockouts.
UFC Sacramento starts at 5 p.m. ET with a seven-fight preliminary card on Paramount+. The six-fight main card kicks off at 8 p.m. ET on Paramount+.
Follow along with Uncrowned's live UFC Sacramento results, highlights and live blog below, including round-by-round play-by-play for the main event.
#live
3 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Amazon.com, Inc. (NASDAQ:AMZN). Amazon.com, Inc. (NASDAQ:AMZN) is a multinational technology and retail company known for its leading online marketplace and cloud platform. On August 18, 2026, Amazon.com, Inc. (NASDAQ:AMZN) closed at $259.45 per share, reflecting a market capitalization of $2.8 trillion. Amazon.com, Inc. (NASDAQ:AMZN) posted a one‑month return of 5.96%, while its shares gained 15.92% over the past 52 weeks.
Eagle Capital Management stated the following regarding Amazon.com, Inc. (NASDAQ:AMZN) in its Q2 2026 investor letter:
"Amazon Web Services ("AWS"), Microsoft Azure, and Google Cloud Platform ("GCP") are highly profitable businesses with strong growth, margins, and returns on capital. We own positions in each. These businesses are growing faster and will be even bigger than we previously thought. However, there is little question that the industry structure they inhabit is worse than it was a few years ago.
Operating massive consumer platforms that aggregate demand for sellers and advertisers, Amazon.com, Inc. (NASDAQ:AMZN) has scale advantages, fast growth, and the ability to deploy AI to further press their leads. Amazon's retail business, Google Search and YouTube, and Meta are comparatively more mature, but they continue to grow at well above GDP rates with attractive margins. We believe AI is demonstrably helping Google Search and Meta's advertising business, both of which have accelerated as ad targeting and content capabilities have improved. Amazon and MercadoLibre should also benefit more than brick and mortar peers, which are unlikely to capture the same benefits from advertising, improvements in consumer search, or gains in wareh
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Amazon.com, Inc. (NASDAQ:AMZN). Amazon.com, Inc. (NASDAQ:AMZN) is a multinational technology and retail company known for its leading online marketplace and cloud platform. On August 18, 2026, Amazon.com, Inc. (NASDAQ:AMZN) closed at $259.45 per share, reflecting a market capitalization of $2.8 trillion. Amazon.com, Inc. (NASDAQ:AMZN) posted a one‑month return of 5.96%, while its shares gained 15.92% over the past 52 weeks.
Eagle Capital Management stated the following regarding Amazon.com, Inc. (NASDAQ:AMZN) in its Q2 2026 investor letter:
"Amazon Web Services ("AWS"), Microsoft Azure, and Google Cloud Platform ("GCP") are highly profitable businesses with strong growth, margins, and returns on capital. We own positions in each. These businesses are growing faster and will be even bigger than we previously thought. However, there is little question that the industry structure they inhabit is worse than it was a few years ago.
Operating massive consumer platforms that aggregate demand for sellers and advertisers, Amazon.com, Inc. (NASDAQ:AMZN) has scale advantages, fast growth, and the ability to deploy AI to further press their leads. Amazon's retail business, Google Search and YouTube, and Meta are comparatively more mature, but they continue to grow at well above GDP rates with attractive margins. We believe AI is demonstrably helping Google Search and Meta's advertising business, both of which have accelerated as ad targeting and content capabilities have improved. Amazon and MercadoLibre should also benefit more than brick and mortar peers, which are unlikely to capture the same benefits from advertising, improvements in consumer search, or gains in wareh

3 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Amazon.com, Inc. (NASDAQ:AMZN). Amazon.com, Inc. (NASDAQ:AMZN) is a multinational technology and retail company known for its leading online marketplace and cloud platform. On August 18, 2026, Amazon.com, Inc. (NASDAQ:AMZN) closed at $259.45 per share, reflecting a market capitalization of $2.8 trillion. Amazon.com, Inc. (NASDAQ:AMZN) posted a one‑month return of 5.96%, while its shares gained 15.92% over the past 52 weeks.
Eagle Capital Management stated the following regarding Amazon.com, Inc. (NASDAQ:AMZN) in its Q2 2026 investor letter:
"Amazon Web Services ("AWS"), Microsoft Azure, and Google Cloud Platform ("GCP") are highly profitable businesses with strong growth, margins, and returns on capital. We own positions in each. These businesses are growing faster and will be even bigger than we previously thought. However, there is little question that the industry structure they inhabit is worse than it was a few years ago.
Operating massive consumer platforms that aggregate demand for sellers and advertisers, Amazon.com, Inc. (NASDAQ:AMZN) has scale advantages, fast growth, and the ability to deploy AI to further press their leads. Amazon's retail business, Google Search and YouTube, and Meta are comparatively more mature, but they continue to grow at well above GDP rates with attractive margins. We believe AI is demonstrably helping Google Search and Meta's advertising business, both of which have accelerated as ad targeting and content capabilities have improved. Amazon and MercadoLibre should also benefit more than brick and mortar peers, which are unlikely to capture the same benefits from advertising, improvements in consumer search, or gains in wareh
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Amazon.com, Inc. (NASDAQ:AMZN). Amazon.com, Inc. (NASDAQ:AMZN) is a multinational technology and retail company known for its leading online marketplace and cloud platform. On August 18, 2026, Amazon.com, Inc. (NASDAQ:AMZN) closed at $259.45 per share, reflecting a market capitalization of $2.8 trillion. Amazon.com, Inc. (NASDAQ:AMZN) posted a one‑month return of 5.96%, while its shares gained 15.92% over the past 52 weeks.
Eagle Capital Management stated the following regarding Amazon.com, Inc. (NASDAQ:AMZN) in its Q2 2026 investor letter:
"Amazon Web Services ("AWS"), Microsoft Azure, and Google Cloud Platform ("GCP") are highly profitable businesses with strong growth, margins, and returns on capital. We own positions in each. These businesses are growing faster and will be even bigger than we previously thought. However, there is little question that the industry structure they inhabit is worse than it was a few years ago.
Operating massive consumer platforms that aggregate demand for sellers and advertisers, Amazon.com, Inc. (NASDAQ:AMZN) has scale advantages, fast growth, and the ability to deploy AI to further press their leads. Amazon's retail business, Google Search and YouTube, and Meta are comparatively more mature, but they continue to grow at well above GDP rates with attractive margins. We believe AI is demonstrably helping Google Search and Meta's advertising business, both of which have accelerated as ad targeting and content capabilities have improved. Amazon and MercadoLibre should also benefit more than brick and mortar peers, which are unlikely to capture the same benefits from advertising, improvements in consumer search, or gains in wareh

3 months ago
The price of the brick keeps going up. According to the Times of London, Tottenham Hotspur's pursuit of Brazilian winger Savinho could cost them as much as £85m. This particular transfer saga has now gone on for a year after Spurs expressed their interest and came close to signing Savinho last summer before City pulled the plug on negotiations.
The new £85m figure comes as almost a throwaway line in an article about City's overall transfer business and their continued attempt to refresh the squad under new head coach Enzo Maresco.
City are in talks with Tottenham Hotspur over the potential sale of Savinho for £85million while Nico González's situation is being monitored by several interested parties. The club also lost two of their top earners over the summer after Bernardo Silva and John Stones left for Real Madrid and Inter Milan respectively on free transfers.
I swear I can remember a time when the price for Savinho was rumored to be around £60m-65m. The delay in coming to an agreement appears to be mostly on the City side of negotiations — there are reports that Maresca has been delaying deciding whether Savinho is in his plans or not; meanwhile it's been clear for a while now that Savinho is of great interest to Spurs and is one of Roberto De Zerbi's top transfer targets, which no doubt has inflated the price. (This is why you don't tip your hand in negotiations.)
Meanwhile, rarely has a player made it so clear that he wants to leave and join Tottenham Hotspur. His social media has included commenting on and befriending numerous Spurs player accounts, and he's refused to train a couple of times now (though City has attributed this, plus his absence from the Community Shield squad, as "illness).
#negotiations #times
The new £85m figure comes as almost a throwaway line in an article about City's overall transfer business and their continued attempt to refresh the squad under new head coach Enzo Maresco.
City are in talks with Tottenham Hotspur over the potential sale of Savinho for £85million while Nico González's situation is being monitored by several interested parties. The club also lost two of their top earners over the summer after Bernardo Silva and John Stones left for Real Madrid and Inter Milan respectively on free transfers.
I swear I can remember a time when the price for Savinho was rumored to be around £60m-65m. The delay in coming to an agreement appears to be mostly on the City side of negotiations — there are reports that Maresca has been delaying deciding whether Savinho is in his plans or not; meanwhile it's been clear for a while now that Savinho is of great interest to Spurs and is one of Roberto De Zerbi's top transfer targets, which no doubt has inflated the price. (This is why you don't tip your hand in negotiations.)
Meanwhile, rarely has a player made it so clear that he wants to leave and join Tottenham Hotspur. His social media has included commenting on and befriending numerous Spurs player accounts, and he's refused to train a couple of times now (though City has attributed this, plus his absence from the Community Shield squad, as "illness).
#negotiations #times


3 months ago
Earlier this week, UCLA men's basketball alumnus Russell Westbrook retired from the NBA after 18 iconic seasons spent with seven franchises.
Since the Bruins legend called it a career, many professionals from across the sports world have reacted to the news, including a four-time NBA champion on his podcast, "The Draymond Green Show."
"Basketball fans, y'all suck. Basketball fans suck. And by the way, I am a basketball fan, so you can throw me in that category too. But basketball fans suck," Green proclaimed. "For the last eight to 10 years, all this guy has heard is how bad he sucks, how he don't shoot it well, how he stat pads and how he messes up teams.
"Make no mistake about it, 'Westbrick,' and all the things y'all said about him, and the moment he steps aside, 'Oh man, y'all did Russ wrong. Can't tell me he couldn't be on a team. Wow, how he played the game, gonna miss him.' All these great, beautiful things.
"Why we can't feel that when you gone? It's like when somebody die. Everybody's like, 'Oh man, best dude ever, best woman ever, would take the shirt off their back.' Everybody got all these great things to say, but when that person was living, you don't show that love.
#fans #green
Since the Bruins legend called it a career, many professionals from across the sports world have reacted to the news, including a four-time NBA champion on his podcast, "The Draymond Green Show."
"Basketball fans, y'all suck. Basketball fans suck. And by the way, I am a basketball fan, so you can throw me in that category too. But basketball fans suck," Green proclaimed. "For the last eight to 10 years, all this guy has heard is how bad he sucks, how he don't shoot it well, how he stat pads and how he messes up teams.
"Make no mistake about it, 'Westbrick,' and all the things y'all said about him, and the moment he steps aside, 'Oh man, y'all did Russ wrong. Can't tell me he couldn't be on a team. Wow, how he played the game, gonna miss him.' All these great, beautiful things.
"Why we can't feel that when you gone? It's like when somebody die. Everybody's like, 'Oh man, best dude ever, best woman ever, would take the shirt off their back.' Everybody got all these great things to say, but when that person was living, you don't show that love.
#fans #green


3 months ago
Networking equipment and software provider Arista Networks, Inc. (NYSE:ANET) is one of Cramer's favorite stocks. In fact, as far back as February 2025, the CNBC TV host remarked that going against Arista Networks, Inc. (NYSE:ANET) and its CEO meant an "invitation to your funeral." The shares are up by 49% over the past year and by 52% year-to-date. Over the month, they are up by 11.5% and closed 3.6% higher on August 5th, the day after Arista Networks, Inc. (NYSE:ANET)'s second quarter earnings report. Yet, as the shares dipped on the 6th, Cramer called the move profit taking:
"I was talking to Jayshree Ullal yesterday, for ANET, which is just a fantastic company, had an amazing quarter. And she's on the board of Snowflake. And I just said, no one noticed that Snowflake just goes up and up and up. That's the kind of thing that is coming up for profit taking taking today. As is ANET. As is Arista. And I just say, okay, wait a second, this is a take your breath moment. These companies are all doing really, really well. Or they have, like the long term agreement kind of thing with Western Digital. This is a profit taking thing, Carl. And I think that this is blessed. You want this."
Arista Networks, Inc. (NYSE:ANET) reported $3.04 billion in revenue and $1.02 in earnings per share for its second quarter and beat ***** yst estimates for both. The firm's third quarter revenue forecast of $3.3 billion also beat the estimates. With Arista Networks, Inc. (NYSE:ANET) counting tech giant such as Microsoft and Amazon, the healthy results indicated the strength of the ongoing AI buildout. The strength of the buildout and the firm's role in it is also key to the investment debate. With Arista Networks, Inc. (NYSE:ANET)'s competency in Ethernet networks, a faster switch to the technology can help the firm. Additionally, the firm also benefits from strong margins (63.4% non-GAAP gross margin in Q2) courtesy of its software model. Yet, at the same time, the fact that Arista Networks, Inc. (NYSE:ANET) relies on a few big-tech customers, which might switch to custom products creates risk that might not be reflected through the forward P/E of 46.73.
Snowflake Inc. (NYSE:SNOW), on the other hand, is a classic software-as-a-service (SaaS) firm. It enables data management and warehousing. Its data business benefits the firm in today's AI era, as it enables users to use their own data to create AI models. Consequently, Snowflake Inc. (NYSE:SNOW)'s net revenue retention (NRR) was 126% in its FY27Q1. Additionally, the firm had 779 customers with trailing 12-month product revenue greater than $1 million in the same quarter. While these figures point towards a robust business, if spending slows due to concerns about AI's returns or if platforms such as DataBricks and Google's BigQuery step up competition, the firm could struggle. For a firm with a forward. P/E of 169, there's little room for error.
#software
"I was talking to Jayshree Ullal yesterday, for ANET, which is just a fantastic company, had an amazing quarter. And she's on the board of Snowflake. And I just said, no one noticed that Snowflake just goes up and up and up. That's the kind of thing that is coming up for profit taking taking today. As is ANET. As is Arista. And I just say, okay, wait a second, this is a take your breath moment. These companies are all doing really, really well. Or they have, like the long term agreement kind of thing with Western Digital. This is a profit taking thing, Carl. And I think that this is blessed. You want this."
Arista Networks, Inc. (NYSE:ANET) reported $3.04 billion in revenue and $1.02 in earnings per share for its second quarter and beat ***** yst estimates for both. The firm's third quarter revenue forecast of $3.3 billion also beat the estimates. With Arista Networks, Inc. (NYSE:ANET) counting tech giant such as Microsoft and Amazon, the healthy results indicated the strength of the ongoing AI buildout. The strength of the buildout and the firm's role in it is also key to the investment debate. With Arista Networks, Inc. (NYSE:ANET)'s competency in Ethernet networks, a faster switch to the technology can help the firm. Additionally, the firm also benefits from strong margins (63.4% non-GAAP gross margin in Q2) courtesy of its software model. Yet, at the same time, the fact that Arista Networks, Inc. (NYSE:ANET) relies on a few big-tech customers, which might switch to custom products creates risk that might not be reflected through the forward P/E of 46.73.
Snowflake Inc. (NYSE:SNOW), on the other hand, is a classic software-as-a-service (SaaS) firm. It enables data management and warehousing. Its data business benefits the firm in today's AI era, as it enables users to use their own data to create AI models. Consequently, Snowflake Inc. (NYSE:SNOW)'s net revenue retention (NRR) was 126% in its FY27Q1. Additionally, the firm had 779 customers with trailing 12-month product revenue greater than $1 million in the same quarter. While these figures point towards a robust business, if spending slows due to concerns about AI's returns or if platforms such as DataBricks and Google's BigQuery step up competition, the firm could struggle. For a firm with a forward. P/E of 169, there's little room for error.
#software

3 months ago
Our picks for the best brick-and-mortar banks and credit unions in California include Chase Bank, Patelco Credit Union and Golden 1 Credit Union.
If you're comfortable banking fully online, check out the consistently excellent rates at Ally Bank.
Check out bank reviews, read the fine print and compare annual percentage yields to choose the best bank for you.
California is a large state, and so is your list of banking options in the Golden State. Truth is, there's no one "best" bank — the best option is the one that fits your specific needs. But we've done the research to give you some strong options. Whether you're looking for easy access to a branch, highly-rated customer service or the best yields, here's our list for the best banks and credit unions in California.
Best bank for customer satisfaction
#california
If you're comfortable banking fully online, check out the consistently excellent rates at Ally Bank.
Check out bank reviews, read the fine print and compare annual percentage yields to choose the best bank for you.
California is a large state, and so is your list of banking options in the Golden State. Truth is, there's no one "best" bank — the best option is the one that fits your specific needs. But we've done the research to give you some strong options. Whether you're looking for easy access to a branch, highly-rated customer service or the best yields, here's our list for the best banks and credit unions in California.
Best bank for customer satisfaction
#california


3 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Private software giant Databricks is now worth $190 billion thanks to a new funding round. The valuation jump is good news for early backers of the Snowflake (NYSE:SNOW) competitor, which includes Nancy Pelosi, NVIDIA Corporation (NASDAQ:NVDA) and Cathie Wood.
Former Speaker of the House Nancy Pelosi (D-Calif.) disclosed a holding in Databricks via Forge Investments on March 4, 2024. The investment, made by her husband and venture capitalist Paul Pelosi, was listed as being in a range of $1 million to $5 million.
The Forge Investments website shows a value of $73.50 per share for Databricks and a $43.4 billion valuation for the September 2023 funding round, and, in 2024, around the time the Pelosis invested.
While the exact valuation of the Pelosis' investment is unknown, the stake was likely made near the $43 billion mark.
#valuation #Investments #pelosis #round
Private software giant Databricks is now worth $190 billion thanks to a new funding round. The valuation jump is good news for early backers of the Snowflake (NYSE:SNOW) competitor, which includes Nancy Pelosi, NVIDIA Corporation (NASDAQ:NVDA) and Cathie Wood.
Former Speaker of the House Nancy Pelosi (D-Calif.) disclosed a holding in Databricks via Forge Investments on March 4, 2024. The investment, made by her husband and venture capitalist Paul Pelosi, was listed as being in a range of $1 million to $5 million.
The Forge Investments website shows a value of $73.50 per share for Databricks and a $43.4 billion valuation for the September 2023 funding round, and, in 2024, around the time the Pelosis invested.
While the exact valuation of the Pelosis' investment is unknown, the stake was likely made near the $43 billion mark.
#valuation #Investments #pelosis #round


3 months ago
The momentum behind artificial intelligence (AI)-linked nuclear energy stocks hit a brick wall in July, sending high-flying names like Oklo (NYSE: OKLO) into a nose-dive.
Shares of the nuclear energy start-up tumbled 25.8% last month, according to data provided by S&P Global Market Intelligence. By the end of July, the drop had wiped about 80% of the stock's value from its October 2025 peak of $193.84.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
For a company promising to fuel the AI build-out with fast-fission reactors, winning important approvals from the Department of Energy (DOE), and securing massive partnerships, the sudden mid-summer fallout left many investors asking where the power went.
Oklo is building fast-fission nuclear power plants called Aurora powerhouses and is still a pre-revenue company.
#oklo #company #called
Shares of the nuclear energy start-up tumbled 25.8% last month, according to data provided by S&P Global Market Intelligence. By the end of July, the drop had wiped about 80% of the stock's value from its October 2025 peak of $193.84.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
For a company promising to fuel the AI build-out with fast-fission reactors, winning important approvals from the Department of Energy (DOE), and securing massive partnerships, the sudden mid-summer fallout left many investors asking where the power went.
Oklo is building fast-fission nuclear power plants called Aurora powerhouses and is still a pre-revenue company.
#oklo #company #called



