

29 days ago
Investors aren't exactly short on reasons to worry.
The Shiller cyclically adjusted price-to-earnings (CAPE) ratio, which measures stock prices against 10-year inflation-adjusted earnings, and the Buffett indicator, the ratio of stock prices to GDP, show that the S&P 500 (SNPINDEX: ^GSPC) is historically expensive. Leadership has been extraordinarily concentrated in megacap tech stocks. Inflation is well above 3%. Long-term Treasury yields are at multidecade highs. And beneath the surface of the major indexes, market breadth has weakened considerably.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Any one of those could sound like a reason to prepare for the next market crash. But decades of stock market history suggest investors may be obsessing over the wrong things.
Instead of asking if and when stock prices will fall next, I'd ask a much simpler question: How long can you stay invested?
#earnings
The Shiller cyclically adjusted price-to-earnings (CAPE) ratio, which measures stock prices against 10-year inflation-adjusted earnings, and the Buffett indicator, the ratio of stock prices to GDP, show that the S&P 500 (SNPINDEX: ^GSPC) is historically expensive. Leadership has been extraordinarily concentrated in megacap tech stocks. Inflation is well above 3%. Long-term Treasury yields are at multidecade highs. And beneath the surface of the major indexes, market breadth has weakened considerably.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Any one of those could sound like a reason to prepare for the next market crash. But decades of stock market history suggest investors may be obsessing over the wrong things.
Instead of asking if and when stock prices will fall next, I'd ask a much simpler question: How long can you stay invested?
#earnings


30 days ago
Hay bales, bunnies, and big smiles set the scene as Brittany and Patrick Mahomes' kids welcomed autumn, engaged in outdoor activities, farm fun, and festive surprises. The family photos featuring their three little ones capture sweet moments enjoyed by the children.
Brittany Mahomes took to Instagram to share a carousel of her family in a fall mood. Her caption was simple: "It's fall y'all," followed by a leaf emoji. The pictures point to the family enjoying the outdoors at a pumpkin patch with farm animals and autumn décor. The couple shares three kids: Sterling, 5, Bronze, 3, and Golden Raye, 1.
The family of five also visited Kansas City's Power and Light District, which is a "walkable neighborhood featuring world-class restaurants, modern living," and premier entertainment facilities, according to the district's Instagram page.
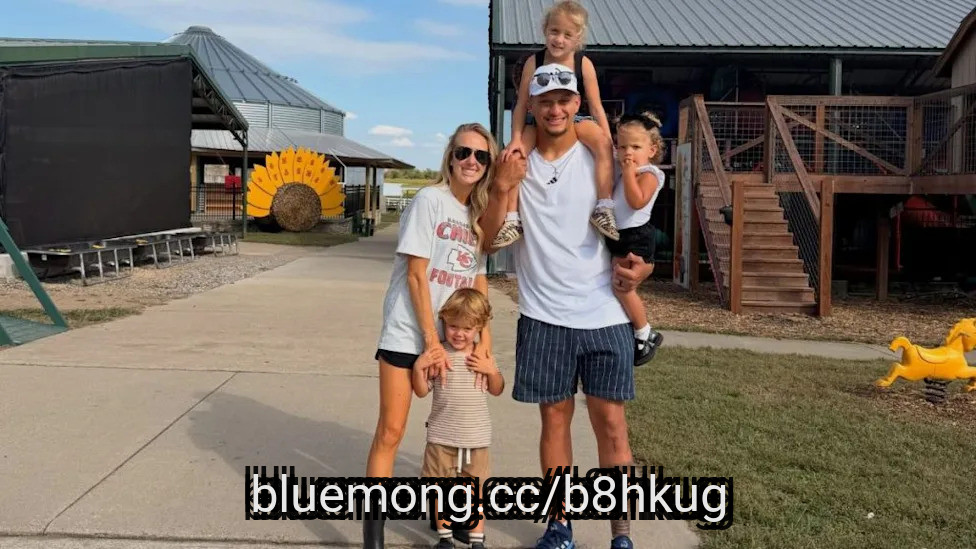
The opening photo of the carousel sets the tone for the outing. Patrick carries Sterling on his shoulders and holds Golden in one arm, while Bronze stands close by. Brittany smiles beside them in a Chiefs tee, sunglasses, and black rain boots.
Later frames show the quieter moments. Bronze and Golden hold hands on a hay bale in front of a wall of autumn leaves, with the name of the farm, "Johnson Farms," behind them. In other photos, Sterling grins while cradling a spotted rabbit, and at lunch, she hides behind a flatbread mask with eyeholes.
#brittany #sterling #golden
Brittany Mahomes took to Instagram to share a carousel of her family in a fall mood. Her caption was simple: "It's fall y'all," followed by a leaf emoji. The pictures point to the family enjoying the outdoors at a pumpkin patch with farm animals and autumn décor. The couple shares three kids: Sterling, 5, Bronze, 3, and Golden Raye, 1.
The family of five also visited Kansas City's Power and Light District, which is a "walkable neighborhood featuring world-class restaurants, modern living," and premier entertainment facilities, according to the district's Instagram page.
The opening photo of the carousel sets the tone for the outing. Patrick carries Sterling on his shoulders and holds Golden in one arm, while Bronze stands close by. Brittany smiles beside them in a Chiefs tee, sunglasses, and black rain boots.
Later frames show the quieter moments. Bronze and Golden hold hands on a hay bale in front of a wall of autumn leaves, with the name of the farm, "Johnson Farms," behind them. In other photos, Sterling grins while cradling a spotted rabbit, and at lunch, she hides behind a flatbread mask with eyeholes.
#brittany #sterling #golden

1 month ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


2 months ago
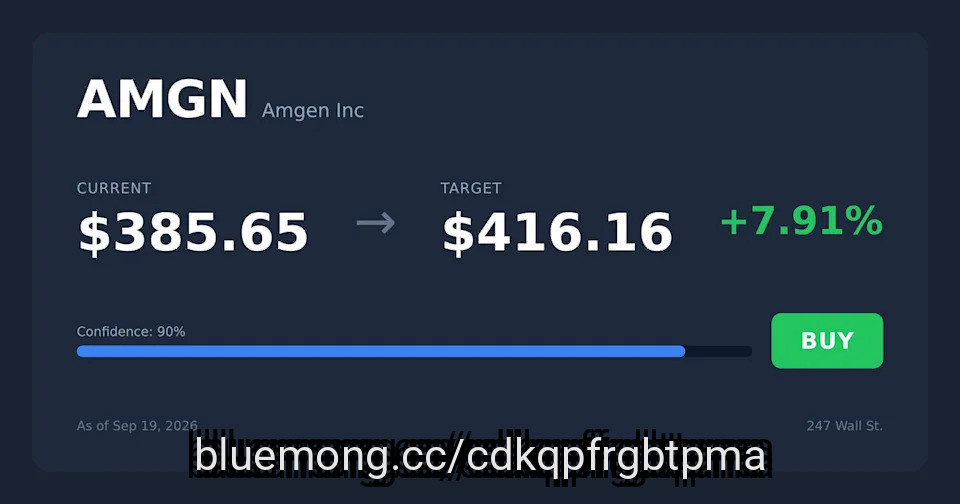
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen


2 months ago
In mid-September, stablecoins received a fresh injection of legitimacy when payments specialist MoneyGram introduced a new Visa-branded debit card backed by one. The product is somewhat unimaginatively called the MoneyGram Card, underpinned by the USDC (CRYPTO: USDC) stablecoin. In turn, Circle Internet Group (NYSE: CRCL) develops and manages the coin.
I believe this is a positive development not only for USDC and the company that co-developed and manages it but also for the wider stablecoin ecosystem. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
MoneyGram is the ideal company to offer such a card, as its bread and ***** er is remittances (i.e., cross-border payments, usually from people in economically advantaged countries to ***** ociates in less prosperous ones).
One of the great promises of cryptocurrencies is that transacting in them can be almost instantaneous and near-frictionless, anywhere in the world. So they're very suitable for remittances, as the facilitator behind them has less contact with challenges such as sharp exchange-rate moves, slow transaction settlement times, and other impediments to money transfers.
#usdc #signal #company #payments
I believe this is a positive development not only for USDC and the company that co-developed and manages it but also for the wider stablecoin ecosystem. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
MoneyGram is the ideal company to offer such a card, as its bread and ***** er is remittances (i.e., cross-border payments, usually from people in economically advantaged countries to ***** ociates in less prosperous ones).
One of the great promises of cryptocurrencies is that transacting in them can be almost instantaneous and near-frictionless, anywhere in the world. So they're very suitable for remittances, as the facilitator behind them has less contact with challenges such as sharp exchange-rate moves, slow transaction settlement times, and other impediments to money transfers.
#usdc #signal #company #payments
2 months ago
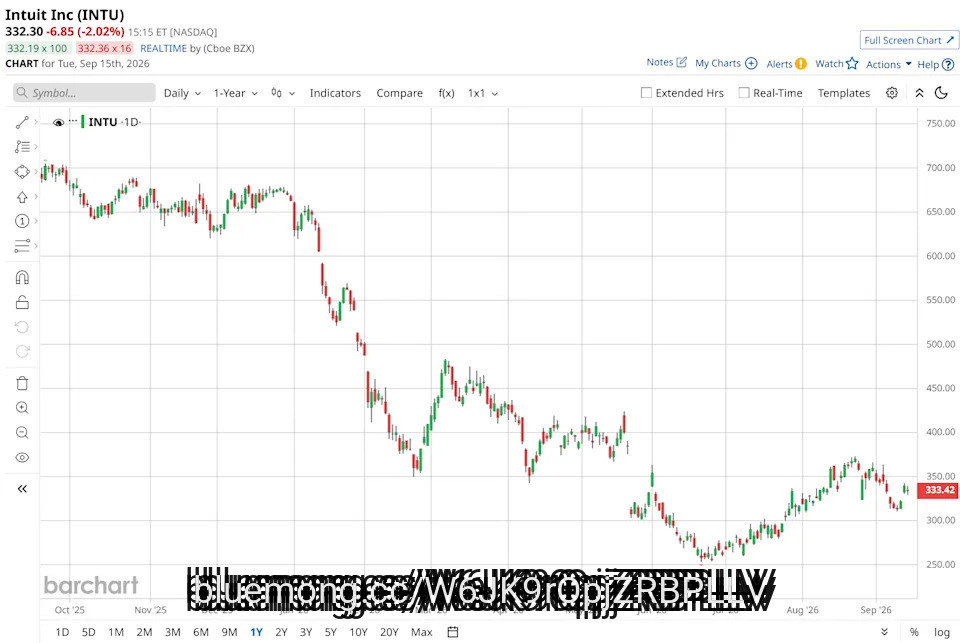
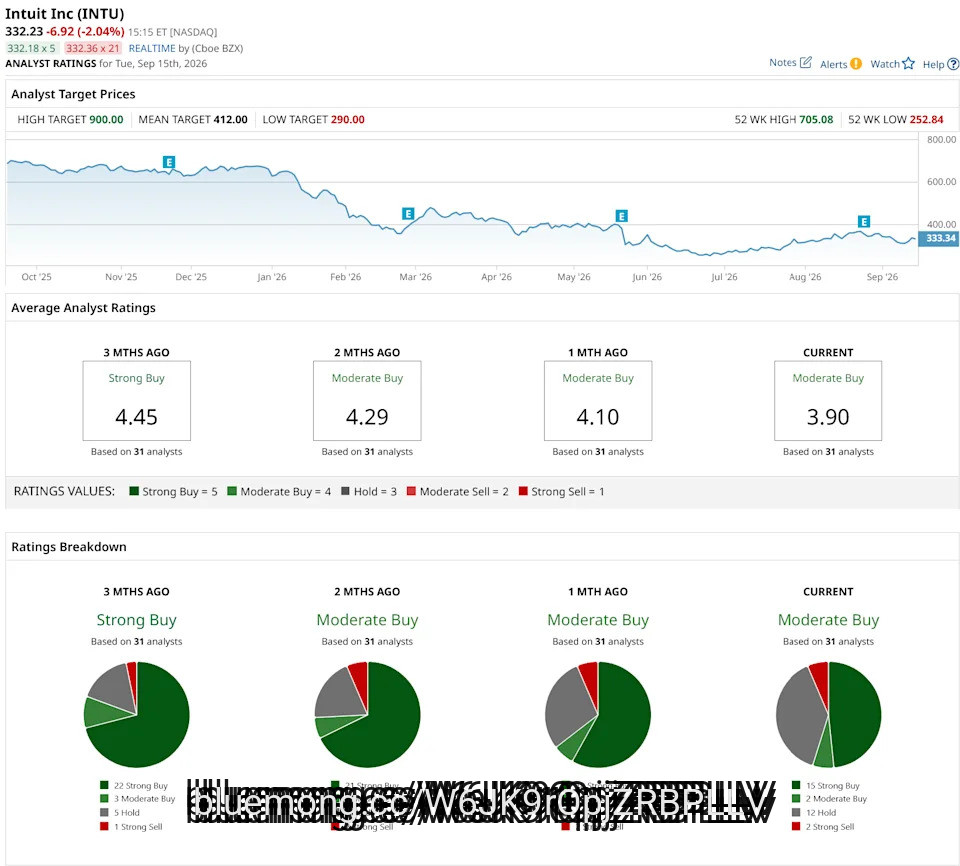
Intuit (INTU) remains a financial technology powerhouse, with roughly 100 million customers across its platforms. Its biggest advantage is the breadth of financial workflows it brings together, spanning everything from tax preparation to business software. But that strength has not protected the stock from a changing market narrative.
Wall Street is increasingly concerned that the rapid adoption and advancement of artificial intelligence (AI) could chip away at Intuit's core tax and business software offerings. These concerns intensified after Intuit delivered slightly disappointing FY2027 sales guidance with its Q4 FY2026 results.
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
A $90 Billion Reason to Buy Oracle Stock Now
This High-Yield Construction Stock Just Raised Its Dividend by 40%
#Dividend #yield #intu
Wall Street is increasingly concerned that the rapid adoption and advancement of artificial intelligence (AI) could chip away at Intuit's core tax and business software offerings. These concerns intensified after Intuit delivered slightly disappointing FY2027 sales guidance with its Q4 FY2026 results.
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
A $90 Billion Reason to Buy Oracle Stock Now
This High-Yield Construction Stock Just Raised Its Dividend by 40%
#Dividend #yield #intu


2 months ago
The Department of Homeland Security (DHS) said a California woman was fatally shot outside a Sacramento County Panera Bread Tuesday by an illegal immigrant who had stalked her for months and was subject to a restraining order.
Shalini Thakur, 38, was standing near her car when Rohit Rohit, an illegal immigrant from India, approached her, chased her when she tried to flee and shot her in the head before getting in a car and driving away, DHS said.
Responding police officers caught up to him, but Rohit took his own life with a gun, according to authorities.
Biden Admin Released Illegal Immigrant Accused Of Fatally Stabbing Fairfax County Mother
Rohit Rohit, an illegal immigrant from India, stalked a California woman for months before fatally shooting her in a parking lot this week and taking his own life. Rohit entered the United States illegally through Arizona and was released by the Biden administration, the Department of Homeland Security said.
#immigrant #department #India
Shalini Thakur, 38, was standing near her car when Rohit Rohit, an illegal immigrant from India, approached her, chased her when she tried to flee and shot her in the head before getting in a car and driving away, DHS said.
Responding police officers caught up to him, but Rohit took his own life with a gun, according to authorities.
Biden Admin Released Illegal Immigrant Accused Of Fatally Stabbing Fairfax County Mother
Rohit Rohit, an illegal immigrant from India, stalked a California woman for months before fatally shooting her in a parking lot this week and taking his own life. Rohit entered the United States illegally through Arizona and was released by the Biden administration, the Department of Homeland Security said.
#immigrant #department #India


2 months ago
It's been a long wait for this day to get here, but now we can finally turn the page to (I hope) more constructive play and move on from the UVA debacle. So what are we keeping our eyes on in the bigger picture tonight?
1.) Find at least the beginnings of an identity offensively. NC State's performance at Virginia was so bad as to look incoherent, and the offense wasn't on the field enough to develop a rhythm, much less discover its most important foundational aspects. Pretty much nothing worked, and what did—or could have—worked, often wasn't well-executed. The Pack has to take the opportunity presented by Richmond to start sorting itself out and establish concepts that work. Where's the bread and ***** er?
2.) To that end, who are the playmakers in this offense? We know that NC State would like to lean on Duke Scott and certainly he has better days ahead of him, but I'd like to see a more concerted effort to get Victor Snow the ball tonight. We learned next to nothing about the passing game in Week 0—well, nothing good, anyway—and still don't really know what we've got at receiver. It might end up essential for Snow to get 8-10 touches each week, and now's a good time to figure that out. I won't be surprised if Keenan Jackson is a focal point, either.
3.) What does this defense look like when it isn't in a bad position for 60 minutes? They were set up to fail by the offense in the first game, and Virginia never had to get out of its conservative comfort zone. Still the defense did some good things against actual handoffs, and needs to build on that. Richmond shouldn't have much of a downfield passing game to speak of, and I want to see how the defense performs against more regular passing downs.
#much #passing
1.) Find at least the beginnings of an identity offensively. NC State's performance at Virginia was so bad as to look incoherent, and the offense wasn't on the field enough to develop a rhythm, much less discover its most important foundational aspects. Pretty much nothing worked, and what did—or could have—worked, often wasn't well-executed. The Pack has to take the opportunity presented by Richmond to start sorting itself out and establish concepts that work. Where's the bread and ***** er?
2.) To that end, who are the playmakers in this offense? We know that NC State would like to lean on Duke Scott and certainly he has better days ahead of him, but I'd like to see a more concerted effort to get Victor Snow the ball tonight. We learned next to nothing about the passing game in Week 0—well, nothing good, anyway—and still don't really know what we've got at receiver. It might end up essential for Snow to get 8-10 touches each week, and now's a good time to figure that out. I won't be surprised if Keenan Jackson is a focal point, either.
3.) What does this defense look like when it isn't in a bad position for 60 minutes? They were set up to fail by the offense in the first game, and Virginia never had to get out of its conservative comfort zone. Still the defense did some good things against actual handoffs, and needs to build on that. Richmond shouldn't have much of a downfield passing game to speak of, and I want to see how the defense performs against more regular passing downs.
#much #passing


2 months ago
Usually, when a restaurant chain goes under, it happens in steps.
On The Border, for example, first closed a number of locations, then filed for Chapter 11 bankruptcy. It was purchased during that process and closed a few more locations. Then, its new owner filed for Chapter 7 bankruptcy for the brand, shutting down all but a handful of franchised locations.
It's rare that a company simply makes the decision to close all its restaurants and exit that business.
Whitbread, a company that operates a number of restaurant chains including Beefeater, Brewers Fayre, Bar + Block, Table Table, Whitbread Inns, and Cookhouse + Pub, plans to close all of its restaurants, a process that began in September.
More Restaurants:
#closed #bankruptcy
On The Border, for example, first closed a number of locations, then filed for Chapter 11 bankruptcy. It was purchased during that process and closed a few more locations. Then, its new owner filed for Chapter 7 bankruptcy for the brand, shutting down all but a handful of franchised locations.
It's rare that a company simply makes the decision to close all its restaurants and exit that business.
Whitbread, a company that operates a number of restaurant chains including Beefeater, Brewers Fayre, Bar + Block, Table Table, Whitbread Inns, and Cookhouse + Pub, plans to close all of its restaurants, a process that began in September.
More Restaurants:
#closed #bankruptcy


2 months ago
Palantir shares gained 7.7% on September 3, the same day PwC US expanded an alliance built around enterprise AI, M&A, and ERP modernization. The companies described an AI-native deals platform intended to execute transactions up to 50% faster and cut one-time costs by as much as 45%, but disclosed no new contract value. The same day, Globant introduced a MuleSoft AI Pod for Salesforce integration. Palantir Technologies Inc. (NASDAQ:PLTR) and Globant S.A. (NYSE:GLOB) are packaging expertise around software in very different ways.
Palantir's bull case is productized delivery. PwC can bring industry relationships and implementation capacity, while Foundry and AIP remain the recurring platform. Palantir's Q2 revenue rose 93% to $1.94 billion, including 149% growth in U.S. commercial revenue, so the alliance lands on real momentum. Arrowstreet Capital held 20,517,115 shares at June 30 after increasing its stake by 97%.
The valuation is the obvious counterweight. A partnership announcement without disclosed revenue cannot by itself justify a large daily move. Receivables concentration, stock-based compensation, and competition from clouds and consultants deserve attention. Hedge-fund breadth had already weakened: Insider Monkey counted 86 funds holding Palantir at June 30, down from 96 at March 31.
Globant's AI Pod offers a more explicit delivery unit. Configurations support roughly six, 12, or 24 integration flows or APIs per month, and the company cited benchmarks including up to 80% automation and 15% to 25% faster time to value. That makes capacity tangible. Twenty-three hedge funds held Globant S.A. (NYSE:GLOB) in Q2, down from 25 in Q1. Pzena Investment Management reported 3,859,718 shares after adding 31%.
Globant's problem is that reusable pods can still be labor businesses. The service remains on a waitlist, the benchmark outcomes are not guaranteed customer results, and AI may pressure billing rates even as it improves productivity.
#glob
Palantir's bull case is productized delivery. PwC can bring industry relationships and implementation capacity, while Foundry and AIP remain the recurring platform. Palantir's Q2 revenue rose 93% to $1.94 billion, including 149% growth in U.S. commercial revenue, so the alliance lands on real momentum. Arrowstreet Capital held 20,517,115 shares at June 30 after increasing its stake by 97%.
The valuation is the obvious counterweight. A partnership announcement without disclosed revenue cannot by itself justify a large daily move. Receivables concentration, stock-based compensation, and competition from clouds and consultants deserve attention. Hedge-fund breadth had already weakened: Insider Monkey counted 86 funds holding Palantir at June 30, down from 96 at March 31.
Globant's AI Pod offers a more explicit delivery unit. Configurations support roughly six, 12, or 24 integration flows or APIs per month, and the company cited benchmarks including up to 80% automation and 15% to 25% faster time to value. That makes capacity tangible. Twenty-three hedge funds held Globant S.A. (NYSE:GLOB) in Q2, down from 25 in Q1. Pzena Investment Management reported 3,859,718 shares after adding 31%.
Globant's problem is that reusable pods can still be labor businesses. The service remains on a waitlist, the benchmark outcomes are not guaranteed customer results, and AI may pressure billing rates even as it improves productivity.
#glob


2 months ago
Nvidia rose only 0.8% on September 4, while Astera Labs jumped 9.8% and Marvell gained 7.1%. The comparison was consistent with investors broadening the AI trade beyond accelerators into connectivity suppliers. Astera's rally also coincided with speculation that the company could be added to the S&P 500, although it was ultimately not selected in the September rebalance. Bigger accelerator clusters need retimers, switches, optical links, and custom silicon to move data without leaving expensive processors idle. Astera Labs, Inc. (NASDAQ:ALAB) and Marvell Technology, Inc. (NASDAQ:MRVL) monetize that connectivity bottleneck from different positions.
Photo from Astera Labs
Astera is the focused rack-scale connectivity play. Its second-quarter update said a Q3 production ramp of the Scorpio X-Series 320-lane fabric switch was expected to drive the next revenue inflection, alongside growth opportunities across Aries, Taurus, and Leo. The bull case is content growth: each new generation of AI rack can require more connectivity silicon and software. The bear case is dependence on a concentrated group of hyperscale customers, product-transition timing, and a valuation that ***** umes strong adoption before every design win becomes revenue.
Hedge-fund breadth strengthened before the rally. Insider Monkey counted 73 funds holding Astera Labs, Inc. (NASDAQ:ALAB) at June 30, up from 53 at March 31. Lee Ainslie's Maverick Capital disclosed 1,067,215 shares, 12% more than in Q1. The quarter-end filing cannot show whether Maverick participated in the September move.
Marvell is more diversified. Its data-center business spans custom compute, electro-optics, switching, and interconnect, giving it multiple ways to benefit as cloud companies redesign AI systems. That breadth is the bull case because one customer's architecture can pull several product families. It is also the risk: custom programs can be lumpy, development costs arrive before revenue, and investors may overestimate the near-term contribution of announced wins.
#september #alab
Photo from Astera Labs
Astera is the focused rack-scale connectivity play. Its second-quarter update said a Q3 production ramp of the Scorpio X-Series 320-lane fabric switch was expected to drive the next revenue inflection, alongside growth opportunities across Aries, Taurus, and Leo. The bull case is content growth: each new generation of AI rack can require more connectivity silicon and software. The bear case is dependence on a concentrated group of hyperscale customers, product-transition timing, and a valuation that ***** umes strong adoption before every design win becomes revenue.
Hedge-fund breadth strengthened before the rally. Insider Monkey counted 73 funds holding Astera Labs, Inc. (NASDAQ:ALAB) at June 30, up from 53 at March 31. Lee Ainslie's Maverick Capital disclosed 1,067,215 shares, 12% more than in Q1. The quarter-end filing cannot show whether Maverick participated in the September move.
Marvell is more diversified. Its data-center business spans custom compute, electro-optics, switching, and interconnect, giving it multiple ways to benefit as cloud companies redesign AI systems. That breadth is the bull case because one customer's architecture can pull several product families. It is also the risk: custom programs can be lumpy, development costs arrive before revenue, and investors may overestimate the near-term contribution of announced wins.
#september #alab

2 months ago
Palantir shares gained 7.7% on September 3, the same day PwC US expanded an alliance built around enterprise AI, M&A, and ERP modernization. The companies described an AI-native deals platform intended to execute transactions up to 50% faster and cut one-time costs by as much as 45%, but disclosed no new contract value. The same day, Globant introduced a MuleSoft AI Pod for Salesforce integration. Palantir Technologies Inc. (NASDAQ:PLTR) and Globant S.A. (NYSE:GLOB) are packaging expertise around software in very different ways.
Palantir's bull case is productized delivery. PwC can bring industry relationships and implementation capacity, while Foundry and AIP remain the recurring platform. Palantir's Q2 revenue rose 93% to $1.94 billion, including 149% growth in U.S. commercial revenue, so the alliance lands on real momentum. Arrowstreet Capital held 20,517,115 shares at June 30 after increasing its stake by 97%.
The valuation is the obvious counterweight. A partnership announcement without disclosed revenue cannot by itself justify a large daily move. Receivables concentration, stock-based compensation, and competition from clouds and consultants deserve attention. Hedge-fund breadth had already weakened: Insider Monkey counted 86 funds holding Palantir at June 30, down from 96 at March 31.
Globant's AI Pod offers a more explicit delivery unit. Configurations support roughly six, 12, or 24 integration flows or APIs per month, and the company cited benchmarks including up to 80% automation and 15% to 25% faster time to value. That makes capacity tangible. Twenty-three hedge funds held Globant S.A. (NYSE:GLOB) in Q2, down from 25 in Q1. Pzena Investment Management reported 3,859,718 shares after adding 31%.
Globant's problem is that reusable pods can still be labor businesses. The service remains on a waitlist, the benchmark outcomes are not guaranteed customer results, and AI may pressure billing rates even as it improves productivity.
#palantir #globant #shares #june
Palantir's bull case is productized delivery. PwC can bring industry relationships and implementation capacity, while Foundry and AIP remain the recurring platform. Palantir's Q2 revenue rose 93% to $1.94 billion, including 149% growth in U.S. commercial revenue, so the alliance lands on real momentum. Arrowstreet Capital held 20,517,115 shares at June 30 after increasing its stake by 97%.
The valuation is the obvious counterweight. A partnership announcement without disclosed revenue cannot by itself justify a large daily move. Receivables concentration, stock-based compensation, and competition from clouds and consultants deserve attention. Hedge-fund breadth had already weakened: Insider Monkey counted 86 funds holding Palantir at June 30, down from 96 at March 31.
Globant's AI Pod offers a more explicit delivery unit. Configurations support roughly six, 12, or 24 integration flows or APIs per month, and the company cited benchmarks including up to 80% automation and 15% to 25% faster time to value. That makes capacity tangible. Twenty-three hedge funds held Globant S.A. (NYSE:GLOB) in Q2, down from 25 in Q1. Pzena Investment Management reported 3,859,718 shares after adding 31%.
Globant's problem is that reusable pods can still be labor businesses. The service remains on a waitlist, the benchmark outcomes are not guaranteed customer results, and AI may pressure billing rates even as it improves productivity.
#palantir #globant #shares #june


2 months ago
Jim Cramer broke down Dell Technologies Inc.'s (NYSE:DELL) post-close earnings report on Mad Money's episode aired on September 1, as he declared it one of the best quarters he has ever witnessed. He stated:
You're getting a Dell, specifically, a blowout quarter from Dell Technologies. After the close, this iconic maker of tech hardware reported one of the best quarters I've ever seen thanks to the incredible strength of their AI server business. Dell's revenue grew 58% year-over-year, a 2 billion dollar beat. The company earned $7 and 4 cents per share. That's more than $2 above what Wall Street was looking for and more than triple what they made the year before. And the guidance was even better. They took their full-year earnings per share forecast from just under 18 bucks all the way up to $25.50. Stunning, definition of blowout.
The headline numbers show that the business is operating at extraordinary velocity. Dell Technologies Inc.'s (NYSE:DELL) total revenue reached a record $47 billion, marking a 58% increase year-over-year and beating estimates by more than $2 billion. Non-GAAP diluted earnings per share landed at $7.04, crushing expectations by $2.1. Management backed up the beat by raising full-year revenue guidance to $192 billion and lifted non-GAAP earnings expectations to $25.50 per share.
The main catalyst was the Infrastructure Solutions Group, where revenue surged 89% to $31.8 billion. Dell Technologies Inc. (NYSE:DELL) also booked $60.9 billion in AI-optimized server orders during the quarter, closing the period sitting on a staggering $95 billion AI backlog, proving that enterprise data centers are experiencing a broad modernization cycle. The company's COO and vice chairman, Jeff Clarke commented:
We're seeing broader revenue growth as well, with traditional servers and networking up 122%, storage up 26% and our client solutions up 20% year over year. Our second quarter results underscore the compounding benefits of our competitive advantages, the breadth of our portfolio and the strength of our operating model.
#year #billion #technologies #NYSE
You're getting a Dell, specifically, a blowout quarter from Dell Technologies. After the close, this iconic maker of tech hardware reported one of the best quarters I've ever seen thanks to the incredible strength of their AI server business. Dell's revenue grew 58% year-over-year, a 2 billion dollar beat. The company earned $7 and 4 cents per share. That's more than $2 above what Wall Street was looking for and more than triple what they made the year before. And the guidance was even better. They took their full-year earnings per share forecast from just under 18 bucks all the way up to $25.50. Stunning, definition of blowout.
The headline numbers show that the business is operating at extraordinary velocity. Dell Technologies Inc.'s (NYSE:DELL) total revenue reached a record $47 billion, marking a 58% increase year-over-year and beating estimates by more than $2 billion. Non-GAAP diluted earnings per share landed at $7.04, crushing expectations by $2.1. Management backed up the beat by raising full-year revenue guidance to $192 billion and lifted non-GAAP earnings expectations to $25.50 per share.
The main catalyst was the Infrastructure Solutions Group, where revenue surged 89% to $31.8 billion. Dell Technologies Inc. (NYSE:DELL) also booked $60.9 billion in AI-optimized server orders during the quarter, closing the period sitting on a staggering $95 billion AI backlog, proving that enterprise data centers are experiencing a broad modernization cycle. The company's COO and vice chairman, Jeff Clarke commented:
We're seeing broader revenue growth as well, with traditional servers and networking up 122%, storage up 26% and our client solutions up 20% year over year. Our second quarter results underscore the compounding benefits of our competitive advantages, the breadth of our portfolio and the strength of our operating model.
#year #billion #technologies #NYSE


2 months ago
Bloom Energy (BE) jumped 8% on momentum with no new catalyst, while FuelCell (FCEL) and Plug Power barely moved in the same risk-on session.
HYDR's 3% gain versus SPY's 1% rise largely reflects Bloom Energy's 15.5% fund weighting, masking weak breadth across hydrogen names.
KR Sridhar declared Bloom "the standard for AI onsite power" after Q2 revenue of $1.07 billion beat estimates and full-year guidance hit $4.2 billion.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
A risk-on tape is lifting high-beta fuel cell names on Thursday, but the group is splitting sharply on the way up. Bloom Energy (NYSE:BE) stock is up 8% to $233.69 in midday trading. That's a large single-session move against much more muted action from its two closest hydrogen and fuel cell peers.
#risk
HYDR's 3% gain versus SPY's 1% rise largely reflects Bloom Energy's 15.5% fund weighting, masking weak breadth across hydrogen names.
KR Sridhar declared Bloom "the standard for AI onsite power" after Q2 revenue of $1.07 billion beat estimates and full-year guidance hit $4.2 billion.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
A risk-on tape is lifting high-beta fuel cell names on Thursday, but the group is splitting sharply on the way up. Bloom Energy (NYSE:BE) stock is up 8% to $233.69 in midday trading. That's a large single-session move against much more muted action from its two closest hydrogen and fuel cell peers.
#risk

2 months ago
On August 18, Commvault (NASDAQ:CVLT) expanded its Cloud Rewind platform, tripling the number of Microsoft Azure resource types it can protect and recover after a cyberattack or outage. The move follows the company's fiscal first quarter 2027 results, reported on July 28, when subscription revenue rose 16% year over year to $267 million. Together, the two updates show a company betting on cloud recovery as its next growth engine, even as some of the underlying numbers complicate that story.
Cloud Rewind sits at the center of that bet. The August update makes it three times more capable on Azure, reaching 62% of the enterprise-relevant resource types available on that cloud. The tool continuously discovers cloud resources, maps how applications depend on each other, and orchestrates rebuilding the infrastructure and configurations an app needs, not just its files. New Protection Groups tie application data and cloud configuration into one recovery workflow, and policy-based protection can auto-enroll resources by tag, region, and type instead of onboarding each one by hand. Allcargo Group, a logistics customer, said the tool let it restore its operational environment in hours.
That kind of speed lines up with how fast Commvault itself is growing: subscription annualized recurring revenue reached $1,054 million in the quarter, up 22% year over year, while SaaS revenue crossed $100 million for the first time, up 39%, and free cash flow jumped 71% to $51 million. Commvault also struck a multi-year deal with Microsoft to sell its resilience tools as a native service on Azure, and Gartner named it a Magic Quadrant Leader in backup and data protection for the 15th straight year.
The numbers also show where the strain sits. Commvault's GAAP operating margin was just 8.2% in the quarter, far below the 22.8% non-GAAP margin the company highlights, a gap wide enough to suggest real costs are being adjusted away. Guidance points to more of the same rather than acceleration: management expects second-quarter subscription revenue of $264 million to $268 million, essentially flat against the $267 million just reported, and it guided full-year non-GAAP EBIT margin to about 21%, below the 22.8% just posted.
Even the marquee Cloud Rewind expansion has a gap built in. Tripling Azure coverage still leaves the platform reaching 62% of enterprise-relevant resource types, meaning well over a third of what enterprises run on Azure sits outside its recovery net, and the announcement says nothing about extending that coverage to AWS or Google Cloud. For a company competing on breadth of recovery, that is a real limitation until it is addressed.
#year #recovery
Cloud Rewind sits at the center of that bet. The August update makes it three times more capable on Azure, reaching 62% of the enterprise-relevant resource types available on that cloud. The tool continuously discovers cloud resources, maps how applications depend on each other, and orchestrates rebuilding the infrastructure and configurations an app needs, not just its files. New Protection Groups tie application data and cloud configuration into one recovery workflow, and policy-based protection can auto-enroll resources by tag, region, and type instead of onboarding each one by hand. Allcargo Group, a logistics customer, said the tool let it restore its operational environment in hours.
That kind of speed lines up with how fast Commvault itself is growing: subscription annualized recurring revenue reached $1,054 million in the quarter, up 22% year over year, while SaaS revenue crossed $100 million for the first time, up 39%, and free cash flow jumped 71% to $51 million. Commvault also struck a multi-year deal with Microsoft to sell its resilience tools as a native service on Azure, and Gartner named it a Magic Quadrant Leader in backup and data protection for the 15th straight year.
The numbers also show where the strain sits. Commvault's GAAP operating margin was just 8.2% in the quarter, far below the 22.8% non-GAAP margin the company highlights, a gap wide enough to suggest real costs are being adjusted away. Guidance points to more of the same rather than acceleration: management expects second-quarter subscription revenue of $264 million to $268 million, essentially flat against the $267 million just reported, and it guided full-year non-GAAP EBIT margin to about 21%, below the 22.8% just posted.
Even the marquee Cloud Rewind expansion has a gap built in. Tripling Azure coverage still leaves the platform reaching 62% of enterprise-relevant resource types, meaning well over a third of what enterprises run on Azure sits outside its recovery net, and the announcement says nothing about extending that coverage to AWS or Google Cloud. For a company competing on breadth of recovery, that is a real limitation until it is addressed.
#year #recovery

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Summary: Bread Savings, formerly known as Comenity Direct, is a division of Bread Financial — a financial services company that offers personal and business banking products.
The high-yield savings account from Bread currently offers a competitive 4% APY (interest is compounded daily and credited monthly) with no monthly fees. The minimum opening deposit is $100. Bread Savings offers free ACH transfers, free online statements, free incoming wire transfers, and unlimited deposits via mobile check capture and ACH transfer.
Bread Savings offers CDs with terms ranging from three months to five years, and rates up to 4.15% APY. The minimum opening deposit for CDs is $1,500. There are no monthly maintenance fees. Interest is compounded daily and credited monthly.
Bread Savings does not charge many fees. However, you may be charged the following fees for specific services:
#financial
Summary: Bread Savings, formerly known as Comenity Direct, is a division of Bread Financial — a financial services company that offers personal and business banking products.
The high-yield savings account from Bread currently offers a competitive 4% APY (interest is compounded daily and credited monthly) with no monthly fees. The minimum opening deposit is $100. Bread Savings offers free ACH transfers, free online statements, free incoming wire transfers, and unlimited deposits via mobile check capture and ACH transfer.
Bread Savings offers CDs with terms ranging from three months to five years, and rates up to 4.15% APY. The minimum opening deposit for CDs is $1,500. There are no monthly maintenance fees. Interest is compounded daily and credited monthly.
Bread Savings does not charge many fees. However, you may be charged the following fees for specific services:
#financial



2 months ago
David Eulitt / Getty Images
Jason Howard/Bauer-Griffin / Getty Images
Related: "Only True Swifties Can Match These Taylor Swift Lyrics To The Correct Album"
XNY/Star Max / Getty Images
I just gave a squirle a peice of bread and it straight smashed all of it!!!! I had no idea they ate bread like that!! Haha #crazy
#getty #howard
Jason Howard/Bauer-Griffin / Getty Images
Related: "Only True Swifties Can Match These Taylor Swift Lyrics To The Correct Album"
XNY/Star Max / Getty Images
I just gave a squirle a peice of bread and it straight smashed all of it!!!! I had no idea they ate bread like that!! Haha #crazy
#getty #howard

2 months ago
Billionaire Philippe Laffont made two of Coatue Management's most revealing second-quarter moves at opposite ends of the AI supply chain. The fund increased its Micron Technology, Inc. (NASDAQ:MU) position by 1,794% to 3.14 million shares and expanded its Amazon.com, Inc. (NASDAQ:AMZN) stake 49% to 11.83 million shares. Micron sells the high-bandwidth memory AI systems consume; Amazon turns those systems into cloud services. The paired positions give Coatue exposure to both the component bottleneck and the infrastructure owner, although the filing does not disclose Laffont's rationale.
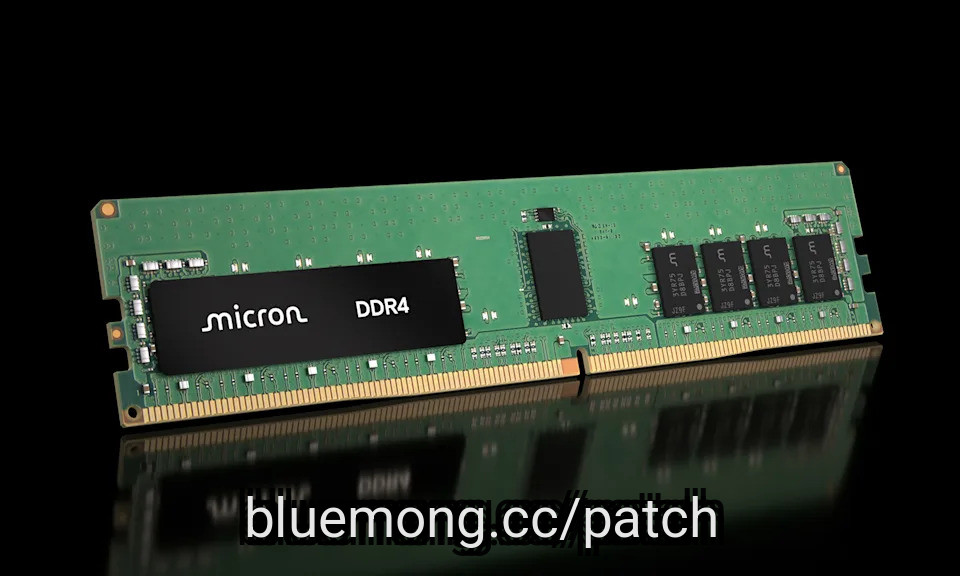
Source: Micron Technology
Micron Technology, Inc. (NASDAQ:MU) has direct exposure to scarcity. Its record fiscal third-quarter results reflected surging HBM demand, and every new accelerator requires large amounts of advanced memory. Tight supply and higher-value products can lift margins dramatically. The danger is that memory remains cyclical, although the traditional boom-and-bust framework may be getting outdated. See why here.
Micron plans more than $25 billion of capital spending, and competitors responding to shortages could eventually weaken pricing just as new factories become expensive to operate.
Amazon.com, Inc. (NASDAQ:AMZN) provides a more diversified route. AWS revenue grew 36.7% in the second quarter, and Amazon can monetize computing, storage, networking, models, and its own chips. That breadth reduces dependence on any single hardware cycle. It also requires roughly $220 billion of capital spending, however, creating a high return threshold. If customers optimize workloads or AI revenue develops more slowly than capacity, depreciation can outrun utilization.
#NASDAQ #amzn #second
Source: Micron Technology
Micron Technology, Inc. (NASDAQ:MU) has direct exposure to scarcity. Its record fiscal third-quarter results reflected surging HBM demand, and every new accelerator requires large amounts of advanced memory. Tight supply and higher-value products can lift margins dramatically. The danger is that memory remains cyclical, although the traditional boom-and-bust framework may be getting outdated. See why here.
Micron plans more than $25 billion of capital spending, and competitors responding to shortages could eventually weaken pricing just as new factories become expensive to operate.
Amazon.com, Inc. (NASDAQ:AMZN) provides a more diversified route. AWS revenue grew 36.7% in the second quarter, and Amazon can monetize computing, storage, networking, models, and its own chips. That breadth reduces dependence on any single hardware cycle. It also requires roughly $220 billion of capital spending, however, creating a high return threshold. If customers optimize workloads or AI revenue develops more slowly than capacity, depreciation can outrun utilization.
#NASDAQ #amzn #second

2 months ago
Hundreds of people gathered to watch the annual August bank holiday tradition of teams playing football matches in a shallow river.
The River Windrush football match, hosted by Bourton Rovers Football Club in Bourton-on-the-Water in Gloucestershire, involves players competing in ankle-deep water.
Those who were brave enough to stand on the edge of the riverbank came equipped with waterproof jackets and umbrellas to stay dry while the players contested the game, which finished 3-3.
The tradition is said to have started more than 100 years ago when drinkers in a riverside pub got bored and decided to stage an impromptu match in the water.
Why is folic acid being added to bread flour?
#river #august #windrush
The River Windrush football match, hosted by Bourton Rovers Football Club in Bourton-on-the-Water in Gloucestershire, involves players competing in ankle-deep water.
Those who were brave enough to stand on the edge of the riverbank came equipped with waterproof jackets and umbrellas to stay dry while the players contested the game, which finished 3-3.
The tradition is said to have started more than 100 years ago when drinkers in a riverside pub got bored and decided to stage an impromptu match in the water.
Why is folic acid being added to bread flour?
#river #august #windrush



2 months ago
On August 21, Flowers Foods (NYSE:FLO) held its second-quarter earnings call, and management didn't try to spin the results. Net sales fell 4% to $1.193 billion, as a 5.8% drop in volume overwhelmed the modest gains the company squeezed out on price. Branded retail volume fell even harder, down 7.6%, and net income sank 30.3% to $40.7 million. Underneath the weak quarter, though, is a company trying to reposition itself around where bread shoppers are actually headed, even as the next few months look no easier.
Even with volume sliding, Flowers Foods still pushed price and mix up 1.8% company wide, a sign its earlier pricing moves found at least some traction in a brutal bread aisle. Management also said its comprehensive organizational review is finished and the company has moved into executing the resulting cost initiatives, aimed at a structure that's been squeezed by labor and freight. CFO Anthony Scaglione pointed to $20 million in savings he expects those restructuring actions to deliver once fiscal 2027 arrives.
The bigger swing factor is where the company is putting its innovation dollars. Chairman and CEO Ryals McMullian pointed to sourdough, a $1.3 billion category where the company admits it's still underrepresented on shelves nationally, along with protein-enriched loaves, as the two ***** es where consumer tastes are actually moving. The relaunched Nature's Own line, now carrying Non-GMO Project Verified labeling, is getting encouraging early signals from retailers and shoppers alike. Executives also expect fresh customer wins already in the pipeline to help lift results later this year, and the company still generated $241.5 million in operating cash flow year to date, giving it room to fund the turnaround while it plays out.
The near-term numbers tell a rougher story. Volume fell 5.8% across the business as the fresh packaged bread category ran into an environment where household budgets are tighter, tastes are shifting and competitors are fighting hard on price. Branded retail net sales dropped 3.8% to $794.6 million, and the company's other segment, largely store-brand products, fell 4.4% as inflation pushed more shoppers toward cheaper private label. Profitability took the harder hit. Adjusted EBITDA dropped 19.2% to $111.3 million, just 9.3% of net sales, while adjusted diluted EPS fell nine cents to $0.21.
Management pointed to weaker output levels and rising labor costs behind a 40 basis point jump in production costs to 51.6% of sales, and higher spending on its workforce, freight and marketing pushed adjusted SD&A costs up 140 basis points to 39.1% of sales. McMullian also noted that rival bakers didn't follow Flowers Foods' price increases, leaving the company facing more aggressive promotions than it had planned for. Scaglione flagged oil, diesel and packaging resin costs as ongoing risks heading into next year. All of that led management to cut its full-year outlook, with net sales guidance now set at $5.070 billion
Even with volume sliding, Flowers Foods still pushed price and mix up 1.8% company wide, a sign its earlier pricing moves found at least some traction in a brutal bread aisle. Management also said its comprehensive organizational review is finished and the company has moved into executing the resulting cost initiatives, aimed at a structure that's been squeezed by labor and freight. CFO Anthony Scaglione pointed to $20 million in savings he expects those restructuring actions to deliver once fiscal 2027 arrives.
The bigger swing factor is where the company is putting its innovation dollars. Chairman and CEO Ryals McMullian pointed to sourdough, a $1.3 billion category where the company admits it's still underrepresented on shelves nationally, along with protein-enriched loaves, as the two ***** es where consumer tastes are actually moving. The relaunched Nature's Own line, now carrying Non-GMO Project Verified labeling, is getting encouraging early signals from retailers and shoppers alike. Executives also expect fresh customer wins already in the pipeline to help lift results later this year, and the company still generated $241.5 million in operating cash flow year to date, giving it room to fund the turnaround while it plays out.
The near-term numbers tell a rougher story. Volume fell 5.8% across the business as the fresh packaged bread category ran into an environment where household budgets are tighter, tastes are shifting and competitors are fighting hard on price. Branded retail net sales dropped 3.8% to $794.6 million, and the company's other segment, largely store-brand products, fell 4.4% as inflation pushed more shoppers toward cheaper private label. Profitability took the harder hit. Adjusted EBITDA dropped 19.2% to $111.3 million, just 9.3% of net sales, while adjusted diluted EPS fell nine cents to $0.21.
Management pointed to weaker output levels and rising labor costs behind a 40 basis point jump in production costs to 51.6% of sales, and higher spending on its workforce, freight and marketing pushed adjusted SD&A costs up 140 basis points to 39.1% of sales. McMullian also noted that rival bakers didn't follow Flowers Foods' price increases, leaving the company facing more aggressive promotions than it had planned for. Scaglione flagged oil, diesel and packaging resin costs as ongoing risks heading into next year. All of that led management to cut its full-year outlook, with net sales guidance now set at $5.070 billion


2 months ago
Download the Complete Report Here
Scaled ***** et-light appliance platform extending into commercial and health markets. HBB designs, markets and distributes branded household appliances, specialty housewares, commercial foodservice equipment and connected medication-management solutions, generating $606.9 million of revenue and shipping more than 25 million appliances in 2025. The company outsources substantially all manufacturing while retaining product development, engineering, quality ***** urance, marketing and distribution, keeping capex near 1% of revenue. This model combines a scaled consumer foundation with growing Commercial and Health platforms, while preserving capital for brand investment, innovation and adjacent growth opportunities.
A defensible business model built on reinforcing brand strength, category breadth, retailer access and repeatable innovation. Hamilton Beach, Proctor Silex and Weston provide broad mass-market reach, while Lotus and licensed CHI products extend into premium applications. HBB participates in more than 50 categories, ranked second among U.S. national small-kitchen-appliance brands by 2025 unit sales and draws on 300,000+ annual consumer touchpoints to support product development. Established retail relationships and an ***** et-light sourcing network reinforce the platform, making its competitive position broader than any single brand, product or patent.
Five growth pillars broaden mix across premium, commercial, digital and health markets. Recent initiatives include wider Lotus distribution, new core-product placements, Sunkist commercial products, foodservice-chain trials, AI-optimized content across 500 SKUs and expanding specialty-pharmacy partnerships; Health remained on track to grow 2026 sales 50%. Execution now hinges on converting these initiatives and incremental advertising into sustained revenue growth, better mix and profitable sell-through.
A large addressable market provides multiple growth pockets aligned with HBB's positioning. U.S. small-appliance sales grew 1.0% in 2025, while kitchen electrics increased 4.1% and replacement accounted for 52% of 4Q25 purchases. HBB's strong unit position and accessible price points support replacement demand, while its lower dollar share and roughly 1% position in an estimated $4.2 billion premium TAM leave meaningful premiumization headroom. Commercial automation, home-administered therapies and AI-mediated discovery add further growth avenues.
#Growth #Health #appliance
Scaled ***** et-light appliance platform extending into commercial and health markets. HBB designs, markets and distributes branded household appliances, specialty housewares, commercial foodservice equipment and connected medication-management solutions, generating $606.9 million of revenue and shipping more than 25 million appliances in 2025. The company outsources substantially all manufacturing while retaining product development, engineering, quality ***** urance, marketing and distribution, keeping capex near 1% of revenue. This model combines a scaled consumer foundation with growing Commercial and Health platforms, while preserving capital for brand investment, innovation and adjacent growth opportunities.
A defensible business model built on reinforcing brand strength, category breadth, retailer access and repeatable innovation. Hamilton Beach, Proctor Silex and Weston provide broad mass-market reach, while Lotus and licensed CHI products extend into premium applications. HBB participates in more than 50 categories, ranked second among U.S. national small-kitchen-appliance brands by 2025 unit sales and draws on 300,000+ annual consumer touchpoints to support product development. Established retail relationships and an ***** et-light sourcing network reinforce the platform, making its competitive position broader than any single brand, product or patent.
Five growth pillars broaden mix across premium, commercial, digital and health markets. Recent initiatives include wider Lotus distribution, new core-product placements, Sunkist commercial products, foodservice-chain trials, AI-optimized content across 500 SKUs and expanding specialty-pharmacy partnerships; Health remained on track to grow 2026 sales 50%. Execution now hinges on converting these initiatives and incremental advertising into sustained revenue growth, better mix and profitable sell-through.
A large addressable market provides multiple growth pockets aligned with HBB's positioning. U.S. small-appliance sales grew 1.0% in 2025, while kitchen electrics increased 4.1% and replacement accounted for 52% of 4Q25 purchases. HBB's strong unit position and accessible price points support replacement demand, while its lower dollar share and roughly 1% position in an estimated $4.2 billion premium TAM leave meaningful premiumization headroom. Commercial automation, home-administered therapies and AI-mediated discovery add further growth avenues.
#Growth #Health #appliance



2 months ago
Target Corporation (NYSE:TGT) enters its fiscal second-quarter report with its shares up significantly in 2026. Consensus estimates call for revenue to increase 3.5% to $26.09 billion, adjusted earnings to rise 14% to $2.34 per share, and comparable sales to grow 2.4%. That follows a first quarter in which net sales increased 6.7%, comparable sales rose 5.6%, and traffic grew 4.4%. With the stock's recovery already well advanced, another sales beat may not be enough.
The central test is profitability. Target Corporation (NYSE:TGT) improved its adjusted operating margin to 4.5% from 3.7%, but the adjusted SG&A expense rate increased to 21.9% from 21.7%. Gross margin expanded 80 basis points to 29%. Management expects the full-year operating margin to exceed the 2025 adjusted rate of 4.6% by more than 20 basis points.
Target Corporation (NYSE:TGT) reported higher sales across all six core merchandise categories during the first quarter. Digital comparable sales grew 8.9%, led by more than 27% growth in same-day delivery. Non-merchandise sales increased nearly 25% as Roundel advertising, Target Circle 360 membership revenue and the Target+ marketplace expanded.
That breadth matters because Target Corporation (NYSE:TGT) is not relying on one category or sales channel to restore growth. Higher traffic, positive average transaction growth, and gains across stores and digital channels indicate that the retailer is becoming more relevant to shoppers.
Target Corporation (NYSE:TGT) also showed early margin progress. Supply-chain productivity, lower markdowns, and growth in advertising and other non-merchandise revenue helped expand gross margin despite higher product costs. Sustained traffic growth would give the retailer a larger sales base over which to spread its store and fulfillment expenses.
#target #Margin #quarter
The central test is profitability. Target Corporation (NYSE:TGT) improved its adjusted operating margin to 4.5% from 3.7%, but the adjusted SG&A expense rate increased to 21.9% from 21.7%. Gross margin expanded 80 basis points to 29%. Management expects the full-year operating margin to exceed the 2025 adjusted rate of 4.6% by more than 20 basis points.
Target Corporation (NYSE:TGT) reported higher sales across all six core merchandise categories during the first quarter. Digital comparable sales grew 8.9%, led by more than 27% growth in same-day delivery. Non-merchandise sales increased nearly 25% as Roundel advertising, Target Circle 360 membership revenue and the Target+ marketplace expanded.
That breadth matters because Target Corporation (NYSE:TGT) is not relying on one category or sales channel to restore growth. Higher traffic, positive average transaction growth, and gains across stores and digital channels indicate that the retailer is becoming more relevant to shoppers.
Target Corporation (NYSE:TGT) also showed early margin progress. Supply-chain productivity, lower markdowns, and growth in advertising and other non-merchandise revenue helped expand gross margin despite higher product costs. Sustained traffic growth would give the retailer a larger sales base over which to spread its store and fulfillment expenses.
#target #Margin #quarter

2 months ago
On August 14, 2026, Reuters reported that Alphabet Inc. (NASDAQ:GOOGL) disclosed that its stake in ******* e Exploration Technologies Corp. (NASDAQ:SPCX) was worth about $94 billion as of June 30, 2026, more than 100 times its original $900 million investment from 2015. It is making Alphabet by far ******* eX's largest single institutional shareholder following the company's June initial public offering.
Alphabet Inc. (NASDAQ:GOOGL)'s ******* eX stake is now one of the most lucrative early-stage bets in tech history. A $900 million check from 2015 is worth roughly $94 billion, a gain that dwarfs Alphabet's next-largest disclosed rival holder, Saudi Arabia's Public Investment Fund, whose 154.1 million shares were worth $26.3 billion at the same date. That scale validates Alphabet's willingness to make patient, outsized bets outside its core search business, a track record that could matter the next time Alphabet weighs a similarly bold bet.
Space Exploration Technologies Corp. (NASDAQ:SPCX)'s trading action suggests institutional demand is holding up despite the pullback. The stock got "a fresh jolt of buying" when fears about its first lockup expiry proved unfounded, Interactive Brokers strategist Steve Sosnick told Reuters. It remains one of the most actively traded names among the firm's customers. That kind of resilience right after a lockup, often a moment when early holders dump shares, signals ******* eX's shareholder base isn't rushing for the exits.
SpaceX's ownership base extends well beyond Alphabet, which reduces reliance on any single backer's continued conviction. Reuters' filing review found Fidelity, Saudi Arabia's PIF, Hancock Prospecting, Brookfield, and other major institutions all disclosing sizable stakes. That breadth shows professional investors broadly, not just Alphabet, are underwriting ******* eX's valuation.
Alphabet Inc. (NASDAQ:GOOGL)'s headline number is already stale and shrinking. The stake would be worth about $77.9 billion at ******* eX's August 13 price, Reuters reported, roughly $16 billion below the June 30 figure used in the disclosure, since regulatory filings run on a 45-day lag. Now that ******* eX is public, Alphabet's stake must be marked to market. It means ******* eX's own stock swings could show up as real volatility in Alphabet's reported earnings going forward, a new risk that did not exist while the investment sat private.
#reuters #worth #public
Alphabet Inc. (NASDAQ:GOOGL)'s ******* eX stake is now one of the most lucrative early-stage bets in tech history. A $900 million check from 2015 is worth roughly $94 billion, a gain that dwarfs Alphabet's next-largest disclosed rival holder, Saudi Arabia's Public Investment Fund, whose 154.1 million shares were worth $26.3 billion at the same date. That scale validates Alphabet's willingness to make patient, outsized bets outside its core search business, a track record that could matter the next time Alphabet weighs a similarly bold bet.
Space Exploration Technologies Corp. (NASDAQ:SPCX)'s trading action suggests institutional demand is holding up despite the pullback. The stock got "a fresh jolt of buying" when fears about its first lockup expiry proved unfounded, Interactive Brokers strategist Steve Sosnick told Reuters. It remains one of the most actively traded names among the firm's customers. That kind of resilience right after a lockup, often a moment when early holders dump shares, signals ******* eX's shareholder base isn't rushing for the exits.
SpaceX's ownership base extends well beyond Alphabet, which reduces reliance on any single backer's continued conviction. Reuters' filing review found Fidelity, Saudi Arabia's PIF, Hancock Prospecting, Brookfield, and other major institutions all disclosing sizable stakes. That breadth shows professional investors broadly, not just Alphabet, are underwriting ******* eX's valuation.
Alphabet Inc. (NASDAQ:GOOGL)'s headline number is already stale and shrinking. The stake would be worth about $77.9 billion at ******* eX's August 13 price, Reuters reported, roughly $16 billion below the June 30 figure used in the disclosure, since regulatory filings run on a 45-day lag. Now that ******* eX is public, Alphabet's stake must be marked to market. It means ******* eX's own stock swings could show up as real volatility in Alphabet's reported earnings going forward, a new risk that did not exist while the investment sat private.
#reuters #worth #public

2 months ago
Pfizer Inc. (NYSE:PFE) and Abbott Laboratories (NYSE:ABT) offer investors two very different dividend stories. Pfizer (NYSE:PFE) is working to rebuild growth before major patent expirations arrive, while Abbott (NYSE:ABT) is combining a long dividend-growth record with a more diversified healthcare portfolio. Pfizer (NYSE:PFE) may offer turnaround potential, but Abbott's (NYSE:ABT) latest results present the steadier investment case.
Pfizer's (NYSE:PFE) non-COVID portfolio is beginning to carry more of the business. Revenue excluding Comirnaty and Paxlovid grew 5% operationally in fiscal Q2 2026, while launched and acquired products generated $3.2 billion and increased 18% operationally. Padcev revenue rose 23% operationally to $667 million, supported by increased market share in first-line locally advanced or metastatic urothelial cancer and uptake in muscle-invasive bladder cancer. The Vyndaqel family generated $1.76 billion, up 8% operationally, while Lorbrena grew 37% operationally. This broader contribution is encouraging because Pfizer needs several products to offset declining COVID revenue and future patent losses.
Stronger non-COVID performance allowed Pfizer (NYSE:PFE) to raise the midpoint of its 2026 revenue guidance by $500 million, despite reducing its COVID-product forecast from approximately $5 billion to $4 billion. Its cost programs should provide further support, as management expects combined savings of approximately $9.7 billion through 2029 across its cost-realignment and manufacturing-optimization initiatives.
Abbott's (NYSE:ABT) advantage is the breadth of its growth. Second-quarter sales increased 13% on a reported basis and 4.8% on a comparable basis, while adjusted EPS rose 4% to $1.31. Medical Devices remained Abbott's (NYSE:ABT) largest segment and an important growth contributor, with sales rising 8.4% on a comparable basis. Growth was led by electrophysiology, rhythm management, heart failure, and diabetes care, with continuous-glucose-monitor sales increasing 9.5% comparably.
The Exact Sciences acquisition also expanded Abbott's (NYSE:ABT) diagnostics business. Diagnostics revenue reached $3.09 billion, rising 42.3% reported and 2.9% comparably. Within the segment, Cancer Diagnostics delivered 13.3% comparable growth as Cologuard benefited from increasing numbers of new and repeat users.
#Growth #billion #covid #revenue
Pfizer's (NYSE:PFE) non-COVID portfolio is beginning to carry more of the business. Revenue excluding Comirnaty and Paxlovid grew 5% operationally in fiscal Q2 2026, while launched and acquired products generated $3.2 billion and increased 18% operationally. Padcev revenue rose 23% operationally to $667 million, supported by increased market share in first-line locally advanced or metastatic urothelial cancer and uptake in muscle-invasive bladder cancer. The Vyndaqel family generated $1.76 billion, up 8% operationally, while Lorbrena grew 37% operationally. This broader contribution is encouraging because Pfizer needs several products to offset declining COVID revenue and future patent losses.
Stronger non-COVID performance allowed Pfizer (NYSE:PFE) to raise the midpoint of its 2026 revenue guidance by $500 million, despite reducing its COVID-product forecast from approximately $5 billion to $4 billion. Its cost programs should provide further support, as management expects combined savings of approximately $9.7 billion through 2029 across its cost-realignment and manufacturing-optimization initiatives.
Abbott's (NYSE:ABT) advantage is the breadth of its growth. Second-quarter sales increased 13% on a reported basis and 4.8% on a comparable basis, while adjusted EPS rose 4% to $1.31. Medical Devices remained Abbott's (NYSE:ABT) largest segment and an important growth contributor, with sales rising 8.4% on a comparable basis. Growth was led by electrophysiology, rhythm management, heart failure, and diabetes care, with continuous-glucose-monitor sales increasing 9.5% comparably.
The Exact Sciences acquisition also expanded Abbott's (NYSE:ABT) diagnostics business. Diagnostics revenue reached $3.09 billion, rising 42.3% reported and 2.9% comparably. Within the segment, Cancer Diagnostics delivered 13.3% comparable growth as Cologuard benefited from increasing numbers of new and repeat users.
#Growth #billion #covid #revenue


2 months ago
A popular sports bar and grill chain has abruptly closed four restaurants, cutting its footprint by 20%, less than two years after a new owner acquired the brand.
The closures come as restaurant chains across the country continue to deal with severe challenges stemming from rising food and labor costs, shifting consumer habits, and aggressive competition for diners.
Full-service restaurants are feeling more pressure as they rely heavily on front-of-house staffing, table service, and bar staff. Moreover, full-service restaurants earn 3%-5% net, versus 6%-9% for fast-casual concepts and quick-service restaurants, on a scale where net margin above 6% is considered strong, according to data from Bloom Intelligence.
Founded in 1997 in Hickory, North Carolina, Hickory Tavern is a sports bar and grill family restaurant chain popular for its saucy wings, flatbreads, loaded nachos, and mozzarella sticks. Aside from food, the bar was often seen as a popular neighborhood gathering place.
Hickory Tavern abruptly closed four locations, leaving the chain with 16 remaining across the Carolinas, reported FSR Magazine.
#restaurants #hickory #chain #grill
The closures come as restaurant chains across the country continue to deal with severe challenges stemming from rising food and labor costs, shifting consumer habits, and aggressive competition for diners.
Full-service restaurants are feeling more pressure as they rely heavily on front-of-house staffing, table service, and bar staff. Moreover, full-service restaurants earn 3%-5% net, versus 6%-9% for fast-casual concepts and quick-service restaurants, on a scale where net margin above 6% is considered strong, according to data from Bloom Intelligence.
Founded in 1997 in Hickory, North Carolina, Hickory Tavern is a sports bar and grill family restaurant chain popular for its saucy wings, flatbreads, loaded nachos, and mozzarella sticks. Aside from food, the bar was often seen as a popular neighborhood gathering place.
Hickory Tavern abruptly closed four locations, leaving the chain with 16 remaining across the Carolinas, reported FSR Magazine.
#restaurants #hickory #chain #grill
2 months ago
NASCAR "driver appearances" were once so common, you couldn't avoid them on any milk-and-bread run, not to mention a swing by the local auto parts store.
Well, this week in Daytona, you can meet two former champions as well as the two best NASCAR racers to win everything BUT a championship.
Along the way, you can meet a driver at a pool party.
NASCAR Hall of Famer Mark Martin, who recently released an autobiography — "Never Lift" — will be among the big names you can find Thursday at one of the old staples of NASCAR partnerships: Winn-Dixie.
His fellow famous non-champ, Denny Hamlin, can also be found there.
#well #driver #meet #famer
Well, this week in Daytona, you can meet two former champions as well as the two best NASCAR racers to win everything BUT a championship.
Along the way, you can meet a driver at a pool party.
NASCAR Hall of Famer Mark Martin, who recently released an autobiography — "Never Lift" — will be among the big names you can find Thursday at one of the old staples of NASCAR partnerships: Winn-Dixie.
His fellow famous non-champ, Denny Hamlin, can also be found there.
#well #driver #meet #famer



2 months ago
Orbis Investment Management, an investment management company, released its Q2 2026 investor letter for "Orbis Global Equity Strategy". The letter can be downloaded here. In the first half of 2026, the Global Equity Strategy returned 19.9%, surpassing the MSCI All Country World Index by 7.8%. The market faced narrow breadth in the quarter. The strategy focuses on AI investments categorized into four groups: "Core" (direct exposure), "Enablers" (supporting businesses), "AI Powered" (companies enhanced by AI), and "Overlooked" (misjudged resilient companies). The firm emphasizes maintaining strong but flexible convictions in a fluctuating market, prioritizing disciplined, evidence-based investment over emotional decision-making. Also, check the fund's top five holdings to see its best picks in 2026.
In its Q2 2026 investor letter, Orbis Global Equity Strategy highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On August 24, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $44.34 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -3.63%, and its shares lost 23.17% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $17.29 billion.
Orbis Global Equity Strategy stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"The biggest winners have been concentrated in AI. But not all AI exposure is equal. We frame ours in four groups. The first is the "Core", the second is "Enablers", the third is AI "Powered" and the fourth is the "Overlooked": resilient businesses the market has mispriced as AI casualties. The first three are widely understood. The fourth is where we believe the market is most wrong, and where we are hunting.
Take insurance brokerage. Brown & Brown and Ryan Specialty Holdings, Inc. (NYSE:RYAN) are brokers: they sit between companies and insurers, matching clients to the right coverage and placing it for a fee, without carrying the risk themselves. Both are priced as AI casualties. Two fears weigh on the stocks: a softening pricing cycle and AI disintermediation. The pricing cycle is already in the price. On AI, we disagree. Ryan Specialty makes the case from the other end of the market: a leading specialist in excess and surplus, the part of insurance built for complex, hard-to-place, and emerging risk. That market is structurally expanding, and we view Ryan as its most capable navigator. The pattern holds across the Overlooked. We are not buying businesses AI leaves alone. We are buying businesses that put AI to work. Scaled brokers with proprietary data are sharpened by it, not replaced."
#NYSE #strategy #orbis
In its Q2 2026 investor letter, Orbis Global Equity Strategy highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On August 24, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $44.34 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -3.63%, and its shares lost 23.17% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $17.29 billion.
Orbis Global Equity Strategy stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"The biggest winners have been concentrated in AI. But not all AI exposure is equal. We frame ours in four groups. The first is the "Core", the second is "Enablers", the third is AI "Powered" and the fourth is the "Overlooked": resilient businesses the market has mispriced as AI casualties. The first three are widely understood. The fourth is where we believe the market is most wrong, and where we are hunting.
Take insurance brokerage. Brown & Brown and Ryan Specialty Holdings, Inc. (NYSE:RYAN) are brokers: they sit between companies and insurers, matching clients to the right coverage and placing it for a fee, without carrying the risk themselves. Both are priced as AI casualties. Two fears weigh on the stocks: a softening pricing cycle and AI disintermediation. The pricing cycle is already in the price. On AI, we disagree. Ryan Specialty makes the case from the other end of the market: a leading specialist in excess and surplus, the part of insurance built for complex, hard-to-place, and emerging risk. That market is structurally expanding, and we view Ryan as its most capable navigator. The pattern holds across the Overlooked. We are not buying businesses AI leaves alone. We are buying businesses that put AI to work. Scaled brokers with proprietary data are sharpened by it, not replaced."
#NYSE #strategy #orbis
2 months ago
Orbis Investment Management, an investment management company, released its Q2 2026 investor letter for "Orbis Global Equity Strategy". The letter can be downloaded here. In the first half of 2026, the Global Equity Strategy returned 19.9%, surpassing the MSCI All Country World Index by 7.8%. The market faced narrow breadth in the quarter. The strategy focuses on AI investments categorized into four groups: "Core" (direct exposure), "Enablers" (supporting businesses), "AI Powered" (companies enhanced by AI), and "Overlooked" (misjudged resilient companies). The firm emphasizes maintaining strong but flexible convictions in a fluctuating market, prioritizing disciplined, evidence-based investment over emotional decision-making. Also, check the fund's top five holdings to see its best picks in 2026.
In its Q2 2026 investor letter, Orbis Global Equity Strategy highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On August 24, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $74.62 per share, reflecting a market capitalization of $24.97 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of 1.32%, while its shares lost 22.31% over the past 52 weeks.
Orbis Global Equity Strategy stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"The biggest winners have been concentrated in AI. But not all AI exposure is equal. We frame ours in four groups. The first is the "Core": direct exposure through companies like Samsung Electronics, Taiwan Semiconductor, and SK Square. The second is "Enablers": the businesses providing the power, materials, and real estate that hyperscalers need to operate. The third is AI "Powered": companies where AI accelerates an already compelling model, like Alphabet. The fourth is the "Overlooked": resilient businesses the market has mispriced as AI casualties. The first three are widely understood. The fourth is where we believe the market is most wrong, and where we are hunting.
Take insurance brokerage. Brown & Brown, Inc. (NYSE:BRO) and Ryan Specialty are brokers: they sit between companies and insurers, matching clients to the right coverage and placing it for a fee, without carrying the risk themselves. Both are priced as AI casualties. Two fears weigh on the stocks: a softening pricing cycle and AI disintermediation. The pricing cycle is already in the price. On AI, we disagree. AI may automate commodity cover like personal auto, but that is under 5% of Brown & Brown's book. The rest is commercial and specialty insurance, where the broker exercises judgement and answers for a denied claim. It is a people business, and Brown & Brown has spent more than eighty years serving mid sized companies that lack the in-house expertise in insurance."
#strategy #Equity
In its Q2 2026 investor letter, Orbis Global Equity Strategy highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On August 24, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $74.62 per share, reflecting a market capitalization of $24.97 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of 1.32%, while its shares lost 22.31% over the past 52 weeks.
Orbis Global Equity Strategy stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"The biggest winners have been concentrated in AI. But not all AI exposure is equal. We frame ours in four groups. The first is the "Core": direct exposure through companies like Samsung Electronics, Taiwan Semiconductor, and SK Square. The second is "Enablers": the businesses providing the power, materials, and real estate that hyperscalers need to operate. The third is AI "Powered": companies where AI accelerates an already compelling model, like Alphabet. The fourth is the "Overlooked": resilient businesses the market has mispriced as AI casualties. The first three are widely understood. The fourth is where we believe the market is most wrong, and where we are hunting.
Take insurance brokerage. Brown & Brown, Inc. (NYSE:BRO) and Ryan Specialty are brokers: they sit between companies and insurers, matching clients to the right coverage and placing it for a fee, without carrying the risk themselves. Both are priced as AI casualties. Two fears weigh on the stocks: a softening pricing cycle and AI disintermediation. The pricing cycle is already in the price. On AI, we disagree. AI may automate commodity cover like personal auto, but that is under 5% of Brown & Brown's book. The rest is commercial and specialty insurance, where the broker exercises judgement and answers for a denied claim. It is a people business, and Brown & Brown has spent more than eighty years serving mid sized companies that lack the in-house expertise in insurance."
#strategy #Equity


2 months ago
LAS VEGAS — From a fry bread pot roast taco created for the Kansas City Chiefs' visit to A5 Wagyu tomahawks and caviar service in premium areas, Allegiant Stadium is expanding its food and beverage lineup for the 2026 Las Vegas Raiders season.
Silver & Black Hospitality, the stadium's culinary and hospitality provider, unveiled a collection of new concessions, opponent-themed dishes, specialty ***** tails, desserts and premium offerings Tuesday. The additions follow Allegiant Stadium's second-place finishes in nationwide voting for both the AFC's Best NFL Stadium and Best NFL Stadium Food in the 2026 USA TODAY 10 Best Readers' Choice Awards.
"This year we have a lot of new and kind of fun items that we're showcasing and just continuing to elevate our food and beverage program," said Dillon Schoell, senior executive chef at Allegiant Stadium.
New featured concession items include a Fry Bread Pot Roast Taco topped with lettuce, tomato, queso fresco, salsa verde and chipotle crema; a Street Dog Torta with a Sabrett hot dog, pork belly, refried beans and avocado aioli; and a Chile Relleno Burger topped with avocado and crema. The lineup also includes a Focaccia and Lox Sandwich and Really Big Chicken & Waffles served with pickles, hot honey and chives.
Other new items available throughout the season include Buffalo Chicken Wontons, Potato Tacos, an XL Chicken Club Sandwich and a Korean Philly Cheesesteak made with shaved beef, kimchi, mozzarella, provolone, green onions and gochujang aioli.
#items
Silver & Black Hospitality, the stadium's culinary and hospitality provider, unveiled a collection of new concessions, opponent-themed dishes, specialty ***** tails, desserts and premium offerings Tuesday. The additions follow Allegiant Stadium's second-place finishes in nationwide voting for both the AFC's Best NFL Stadium and Best NFL Stadium Food in the 2026 USA TODAY 10 Best Readers' Choice Awards.
"This year we have a lot of new and kind of fun items that we're showcasing and just continuing to elevate our food and beverage program," said Dillon Schoell, senior executive chef at Allegiant Stadium.
New featured concession items include a Fry Bread Pot Roast Taco topped with lettuce, tomato, queso fresco, salsa verde and chipotle crema; a Street Dog Torta with a Sabrett hot dog, pork belly, refried beans and avocado aioli; and a Chile Relleno Burger topped with avocado and crema. The lineup also includes a Focaccia and Lox Sandwich and Really Big Chicken & Waffles served with pickles, hot honey and chives.
Other new items available throughout the season include Buffalo Chicken Wontons, Potato Tacos, an XL Chicken Club Sandwich and a Korean Philly Cheesesteak made with shaved beef, kimchi, mozzarella, provolone, green onions and gochujang aioli.
#items
2 months ago
Orbis Investment Management, an investment management company, released its Q2 2026 investor letter for "Orbis Global Equity Strategy". The letter can be downloaded here. In the first half of 2026, the Global Equity Strategy returned 19.9%, surpassing the MSCI All Country World Index by 7.8%. The market faced narrow breadth in the quarter. The strategy focuses on AI investments categorized into four groups: "Core" (direct exposure), "Enablers" (supporting businesses), "AI Powered" (companies enhanced by AI), and "Overlooked" (misjudged resilient companies). The firm emphasizes maintaining strong but flexible convictions in a fluctuating market, prioritizing disciplined, evidence-based investment over emotional decision-making. Also, check the fund's top five holdings to see its best picks in 2026.
In its Q2 2026 investor letter, Orbis Global Equity Strategy highlighted QXO, Inc. (NYSE:QXO). QXO, Inc. (NYSE:QXO) is a leading US-based roofing, waterproofing, and complementary building products distributor. On August 24, 2026, QXO, Inc. (NYSE:QXO) closed at $13.41 per share, reflecting a market capitalization of $13.91 billion. QXO, Inc. (NYSE:QXO) posted a one-month return of -5.89%, while its shares lost 35.93% over the past 52 weeks.
Orbis Global Equity Strategy stated the following regarding QXO, Inc. (NYSE:QXO) in its Q2 2026 investor letter:
"We think about AI through the same lens. Most early corporate AI adoption is a motor swap: existing workflows, existing structures, existing ***** umptions, with AI bolted on. The companies that compound the most value are those willing to redesign the floor. This is a question I ask of every management team I invest behind. QXO, Inc. (NYSE:QXO) is doing exactly that. As it consolidates the prosaic, low-tech business of building products distribution, it is rebuilding the operating model itself, from pricing and procurement to inventory and branch data, rather than bolting technology onto the old way of working."
QXO, Inc. (NYSE:QXO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 83 hedge fund portfolios held QXO, Inc. (NYSE:QXO) at the end of the second quarter, up from 65 in the previous quarter. While we acknowledge the potential of QXO, Inc. (NYSE:QXO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#strategy
In its Q2 2026 investor letter, Orbis Global Equity Strategy highlighted QXO, Inc. (NYSE:QXO). QXO, Inc. (NYSE:QXO) is a leading US-based roofing, waterproofing, and complementary building products distributor. On August 24, 2026, QXO, Inc. (NYSE:QXO) closed at $13.41 per share, reflecting a market capitalization of $13.91 billion. QXO, Inc. (NYSE:QXO) posted a one-month return of -5.89%, while its shares lost 35.93% over the past 52 weeks.
Orbis Global Equity Strategy stated the following regarding QXO, Inc. (NYSE:QXO) in its Q2 2026 investor letter:
"We think about AI through the same lens. Most early corporate AI adoption is a motor swap: existing workflows, existing structures, existing ***** umptions, with AI bolted on. The companies that compound the most value are those willing to redesign the floor. This is a question I ask of every management team I invest behind. QXO, Inc. (NYSE:QXO) is doing exactly that. As it consolidates the prosaic, low-tech business of building products distribution, it is rebuilding the operating model itself, from pricing and procurement to inventory and branch data, rather than bolting technology onto the old way of working."
QXO, Inc. (NYSE:QXO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 83 hedge fund portfolios held QXO, Inc. (NYSE:QXO) at the end of the second quarter, up from 65 in the previous quarter. While we acknowledge the potential of QXO, Inc. (NYSE:QXO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#strategy


