9 hours ago
Michael Douglas has finally revealed why he refused to appear on David Letterman's talk show for almost two decades.
In his new memoir One ****** uva Ride, the Wall Street actor recounted how he had promoted various projects on the Late Show with David Letterman.
"I had been a regular guest on Letterman's show earlier in my career, but the last time I was on, I felt David went too far," he shared.
Douglas went on to recall how Letterman had played "without warning" a TV commercial that his actress mother, Diana Dill, had appeared in.
"(Letterman) started grilling me about it. It felt like he was making fun of my mother," the 82-year-old continued. "(That appearance) left me feeling like he had a real nasty sense of humour... After that, whenever the producers of the show requested to have me back on, I always refused. I said no for 18 straight years. Dave wrote me personal letters to apologise, but my feelings didn't change. He had crossed a line."
However, Douglas decided to "bury the hatchet" and announce that he was battling advanced tongue cancer during an interview on the Late Show with David Letterman while promoting his movie Wall Street: Money Never Sleeps in 2010. He has since recovered from the cancer after undergoing chemotherapy and radiation treatments.
#letterman #late #refused #felt


1 day ago
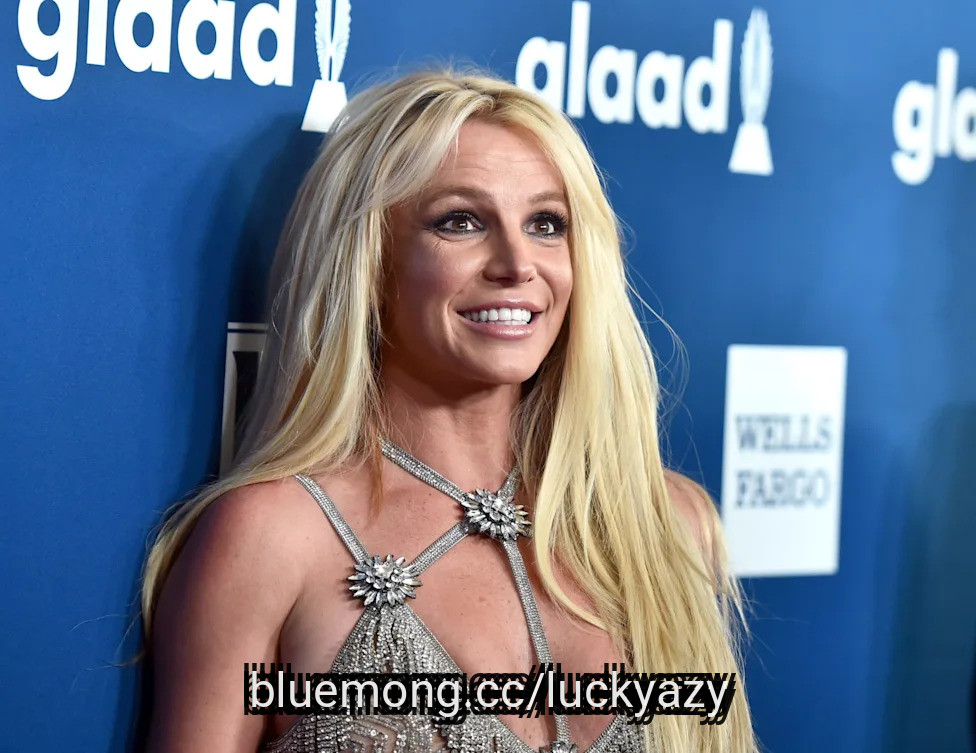
Britney Spears shared pictures and video from a rare public outing with her two adult sons, Sean Preston Federline, 21, and Jayden James Federline, 20, on her Instagram on Wednesday (Oct. 7). In a sweet pic, Spears can be seen posing between the two young men, who tower over her, in front of the sign at Dolly Parton's beloved Dollywood resort in Pigeon Forge, Tenn.
"Wow wow!!! I didn't know this place existed, so incredibly cool and exciting," Spears, 44, wrote of the 165-acre amusement park and resort the late country icon took over and rebranded in 1986. The singer was pictured wearing a short blue skirt, flip-flops, a red-and-white striped shirt and a white surgical mask, while the boys rocked baggy jeans and white T-shirts, with Britney lamenting that it was "extremely hot and my skirt is too big for me."
More from Billboard
Britney Spears' Son Jayden James On Being Chip Off the Pop Block: 'Expressing Myself Through Music Has Always Been My Best Therapy'
Dollywood to Celebrate Dolly Parton With New Installations & Experiences: 'We Will Carry Her Dreams Forward'
#britney #white
1 day ago
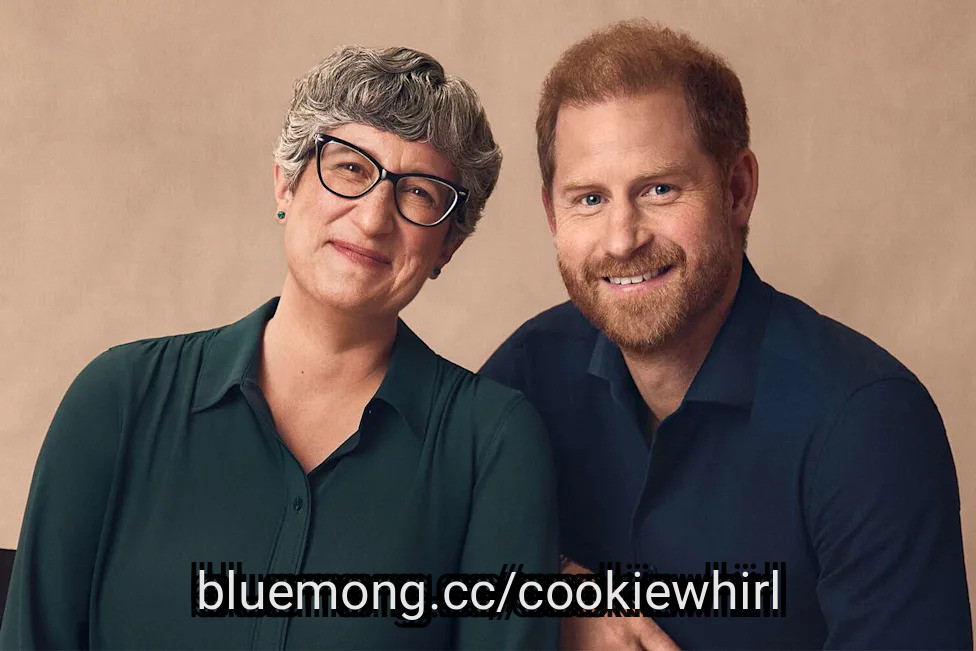
Prince Harry is opening up like never before about grief and what losing his mother, Princess Diana, at age 12 has meant for nearly every chapter of his life since.
In Redefining Grief: Building Resilience Through Loss, a new MasterClass available Oct. 8, the Duke of Sussex, 42, sits down with neuroscientist and grief expert Dr. Mary-Frances O'Connor for an intimate and at times deeply emotional conversation about loss, trauma and the ways grief can affect both the brain and body.
Rather than a traditional interview, the class — timed ahead of World Mental Health Day on Oct. 10 — unfolds as a candid exchange between Harry and O'Connor, a professor of clinical psychology and psychiatry at the University of Arizona whose research focuses on the psychological and physiological effects of bereavement. Together, they explore the science of grief and resilience while Harry draws extensively on his own life — from losing Diana and serving in Afghanistan to therapy, panic attacks, his marriage to Meghan Markle and life as a father.
"I didn't cry when I was told my mom died, only at her burial, and then not again for nearly two decades," he says near the start of the class. "I was convinced that was strength, but it wasn't. It was a 12-year-old boy with no permission to fall apart and no roadmap for how to heal."
"You would think I had the best help in the world. I'm a prince for God's sake, but I was still grieving and didn't have any place to put those feelings," he continues.
#harry #diana #loss #World
2 days ago
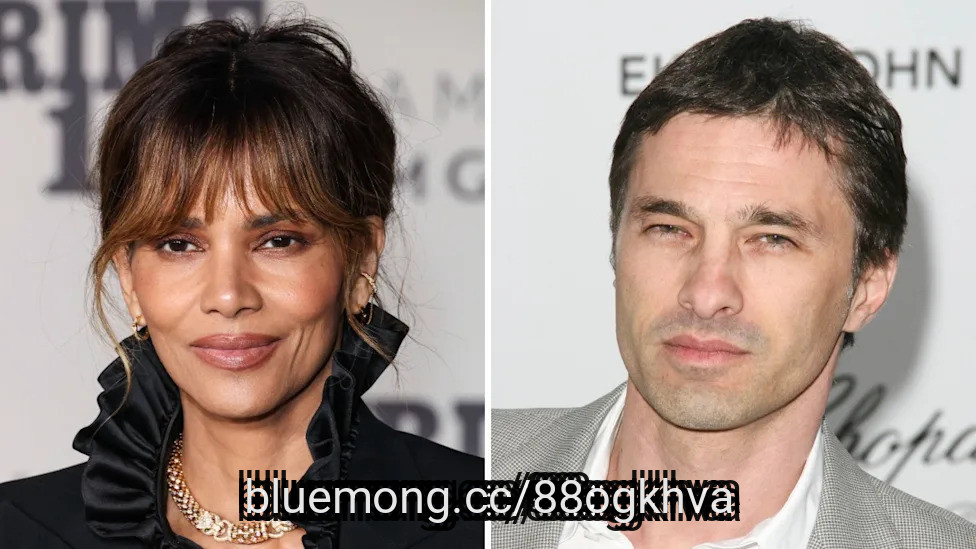
There's zero chance that Halle Berry and ex-husband Olivier Martinez will reach a compromise amid their battle over 13-year-old son Maceo, a source tells Star.
"The hatred between these two is off the charts," reveals the source. "There's years and years of ugly history."
On Thursday, October 1, People reported that the Unfaithful actor, 60, was granted a temporary restraining order against the Oscar-winning actress, 60, as well as modified visitation after he accused her of physically abusing Maceo.
"Olivier's accusing Halle of being dangerous and saying he needs to protect their son from her, which is something she vehemently denies," reveals the source. "She's furious and says all Olivier is doing is trying to alienate her son from her."
In documents obtained by Star, the Monster's Ball actress asked that their former custody agreement, which grants her 50/50 custody and tie-breaking authority, be reinstated and that Martinez be forced to attend court-ordered therapy sessions.
#star #actress
4 days ago
Halle Berry is asking a Los Angeles court to restore the 50/50 custody arrangement she previously shared with ex-husband Olivier Martinez, alleging that their 12-year-old son, Maceo, returns from time with his father "angry and combative."
She is also asking to regain the tie-breaking authority she held under the 2023 agreement and wants the court to require Martinez to attend their ordered therapy sessions. Those requests put decision-making power and the stalled co-parenting process back at the center of the dispute.
Berry's filing arrives days after Martinez sought sole custody and obtained a temporary restraining order against her over allegations that she physically abused their son. Berry has strongly denied those accusations, turning the former couple's long-running co-parenting dispute into an even more complicated court battle.
ZUMAPRESS.com / MEGA
According to PEOPLE, Berry alleged that Martinez has repeatedly tried to align Maceo with him and against her when disagreements arise over their son's life.
#martinez #custody #parenting
4 days ago
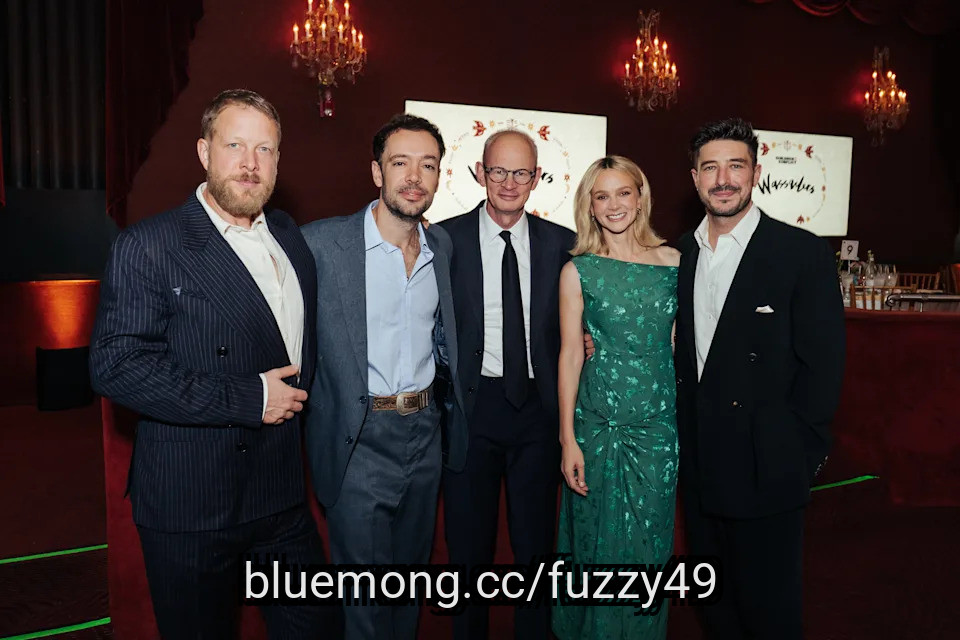
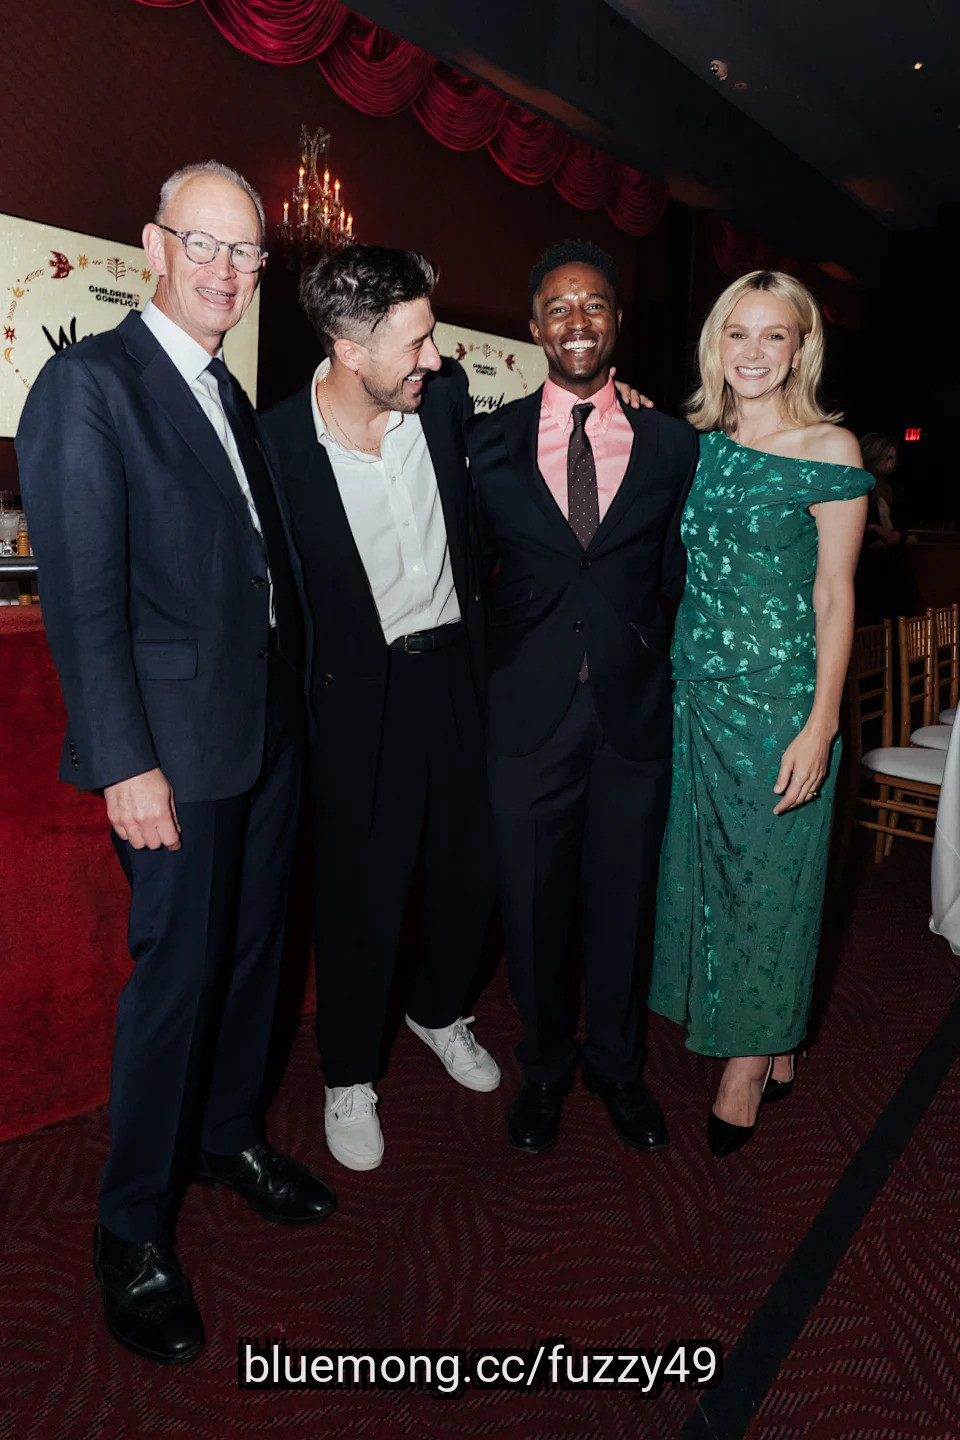
Carey Mulligan and Marcus Mumford raised $7.65 million on Sunday night in Los Angeles for Children in Conflict, a nonprofit organization dedicated to protecting, educating and providing mental health support to children living in war zones and high-conflict areas.
The couple hosted their annual star-studded Wassail benefit for the first time in Los Angeles. Previously held in London and New York, the evening took place at the El Rey Theatre.
More from Variety
Marisa Tomei and Rosanna Arquette to Star in 'This Is Crazy' NAMI Benefit in Memory of Chris Huvane
Riley Keough and Director Clay Tweel Board First Responder Psychedelic Therapy Doc 'Under Fire' as Executive Producers (EXCLUSIVE)
#conflict #first #carey #mulligan
4 days ago
Marc Summers has lived with chronic lymphocytic leukemia for 15 years and takes daily medication after chemotherapy stopped working
The 75-year-old still enjoys long walks and recently logged 13 miles in one day
Summers is celebrating Double Dare's 40th anniversary and says he's lucky to do what he loves, and to be alive and healthy
Former Double Dare and Unwrapped host Marc Summers says he's more than lucky to be alive after cheating death not once, but twice.
In 2010, Summers was diagnosed with chronic lymphocytic leukemia, which he tells PEOPLE he's managed for 15 years.
#chronic

4 days ago
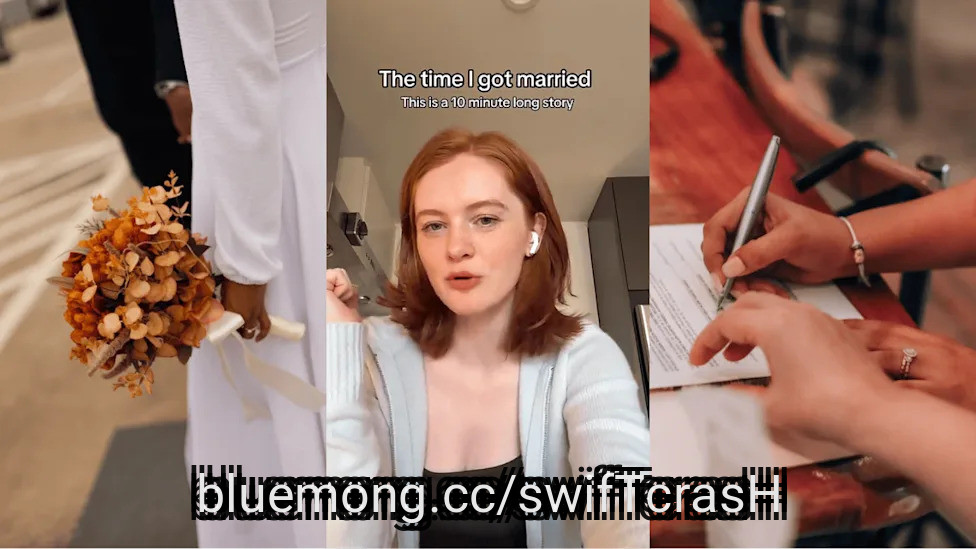
Internet personality and streamer Meep (meepiosaurus) revealed that she was married at 19. It wasn't a fairy tale, and she told TikTok about the red flags leading up to her wedding.
"At this moment, I was separating myself from my family," Meep prefaced her story. Now divorced, she claimed her husband "wasn't the best" in terms of character. Furthermore, she alleged that he had been physically abusive but didn't go into detail about it.
"The beginning of that pattern starts with them taking you away from your family and your friends, kind of ostracizing you from your support system," she alleged. A former prosecutor has also described dangerous men and the characteristics they have in common. Meep now recognizes the pattern, but couldn't when she was 19.
"So, I remember my dad and I were besties at the time, and I started really detaching myself from him. Stopped going to therapy," Meep said. At the time, she was supposed to be tested for bipolar disorder, but didn't push through. She told her dad she was getting married the next day while they were in a parking lot.
"I remember it was one of those conversations that was heavy, okay? And I could tell there was something more happening in that conversation, and it was something I wasn't picking up on," Meep recalled. She said she knew she was making a mistake, and her father also advised her. He allegedly told her not to sign any contract that indicated she was married to her then-boyfriend. Meep believes her dad saw through her boyfriend and thought he was taking advantage of her.
#myself
8 days ago
Halle Berry and ex-husband Olivier Martinez attended "co-parenting therapy" for their son Maceo in 2024, PEOPLE can confirm
Court documents outlined individual meetings followed by six joint sessions with a coach selected by the former couple
Berry's fiancé Van Hunt was permitted to participate in the sessions, which came years ahead of Martinez filing for sole custody of Maceo and alleging abuse
Halle Berry and ex-husband Olivier Martinez attended "co-parenting therapy" two years ago.
In May 2024, the Crime 101 actress and Martinez, both 60, agreed to "co-parenting therapy" with a coach to "resolve disputes and conflicts between them in an effort to successfully co-parent" their then-9-year-old son Maceo, according to court documents obtained by PEOPLE.
#parenting #husband


8 days ago
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of Hollywood because his fellow A-listers would "make fun" of him—while opening up about the very different life he has built away from Los Angeles.
The 53-year-old "Ransom Canyon" star recently spoke about his experience with testosterone replacement therapy, revealing that his former representatives had warned him that publicly attaching himself to the treatment could damage his image and career.
Duhamel, who co-founded men's health company Gatlan, said during an appearance on Dave Asprey's "The Human Upgrade" podcast that he initially had reservations about becoming so publicly involved with the company because of the potential response in Hollywood.
"I won't tell you the agency that I'm no longer with, but they said, 'Don't do it. It's bad for your image,'" he recalled. "And I was like, 'All right, watch.'"
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of town in Hollywood—while opening up about the very different life he has built away from Los Angeles. (CBS Mornings)
#duhamel #left


8 days ago
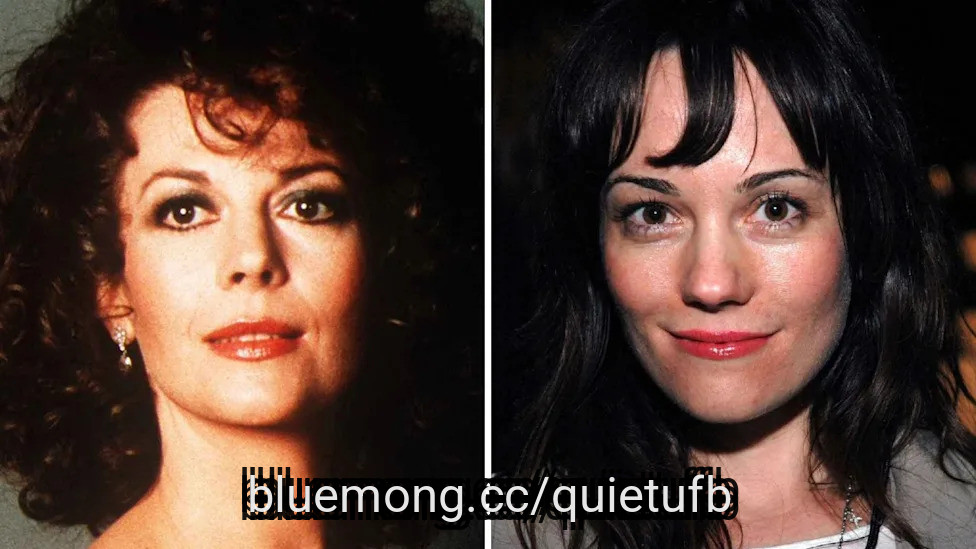
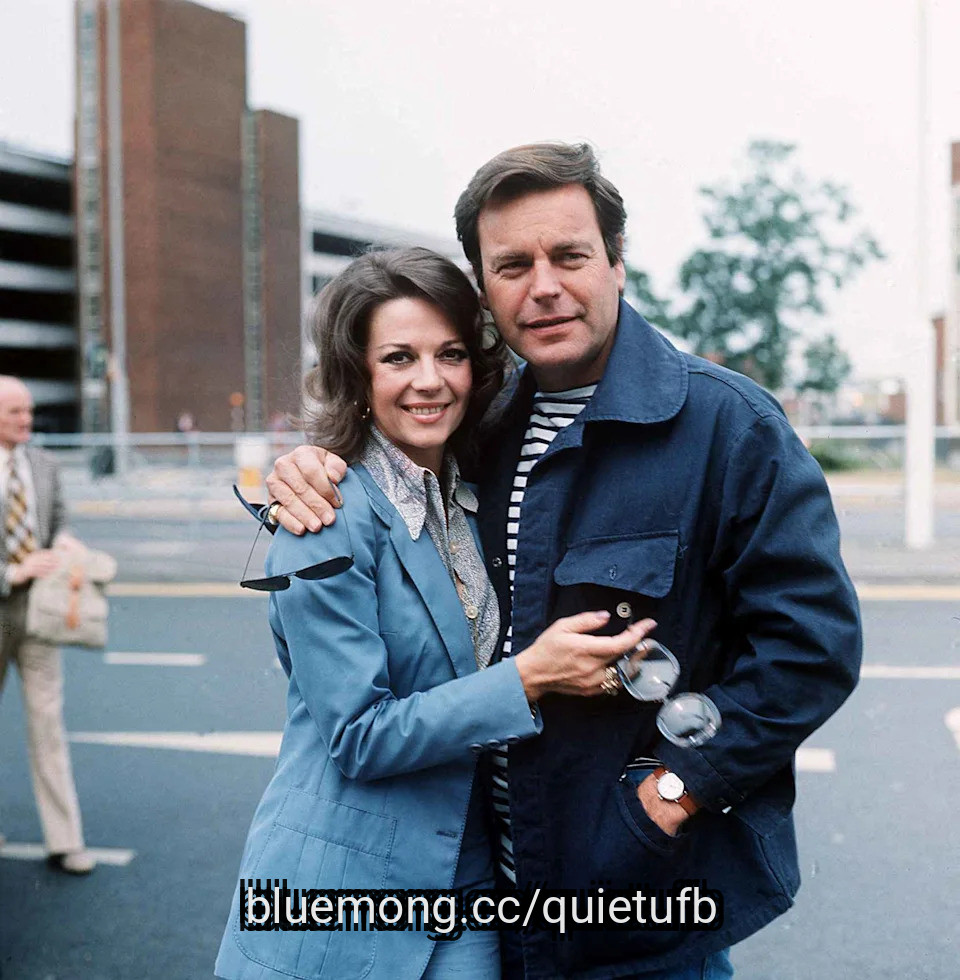
Natasha Gregson Wagner, the eldest daughter of late actress Natalie Wood, opened up about growing up without her mother, calling herself a "self-preservationist."
Natasha, 56, was raised by her father, movie producer Richard Gregson, and stepfather, actor Robert Wagner, after the West Side Story star drowned after falling off of Robert's yacht near California's Catalina Island in November 1981.
"Luckily I had these two men, Daddy Gregson and Daddy Wagner, who came together and rose to the occasion and completely put me first," Natasha told Daily Mail on Thursday, October 1. "They got me into therapy right [after my mom died] and I had that same amazing therapist here in Beverly Hills until my twenties."
J Jarrett / Mirrorpix/Newscom/The Mega Agency
"I'm not saying I haven't had very, very painful things in my life," she continued. "My life was dramatic in that my parents were famous, and dressed up, glamorous — but in the home, it was all very safe and secure and warm, so I got lucky in that way."
#richard #robert #west

8 days ago
Busy Philipps tells PEOPLE her oncologist confirmed her latest scan was clear after she was diagnosed with a brain tumor
Doctors discovered the rare tumor during a full-body MRI in February
Philipps underwent two surgeries and did not need chemotherapy or radiation
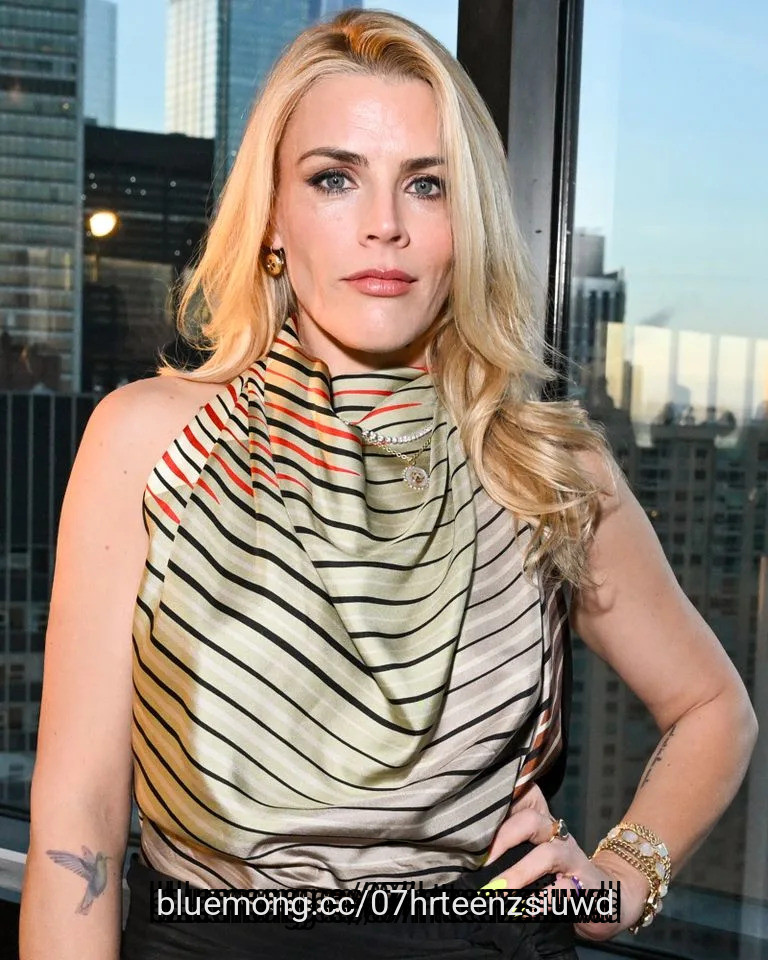
Busy Philipps shared a positive update amid her ongoing health journey after she was diagnosed with a brain tumor earlier this year.
"I chatted with my oncologist today," the Cupertino star, 47, tells PEOPLE exclusively at the Wednesday, Sept. 30, premiere of the CBS show in New York City. The Silicon Valley-set legal drama was her doctor's preferred topic of conversation, Philipps shars.
#tumor #people


8 days ago
Bringing Up Bates alum Gil Bates suffered a heart attack after experiencing unusual chest sensations and occasional jaw pain for two weeks
Doctors discovered an 80% blockage in his LAD artery and a 95% blockage in his RCA artery, leading to the placement of two stents
Gil's wife, Kelly Jo Bates, said he is heading home and will begin cardiac therapy next week
Gil Bates is recovering after suffering a heart attack.
The Bringing Up Bates alum, 61, was hospitalized earlier this week after experiencing an unusual sensation in his chest for approximately two weeks, his wife, Kelly Jo Bates, revealed in an Instagram post on Wednesday, Sept. 30.
#chest #weeks

19 days ago
ResMed Inc. (NYSE:RMD) is well positioned to benefit from the long-term growth of the global obstructive sleep apnea (OSA) treatment market. Likewise, the company remains well positioned to benefit from growing awareness and penetration in the global market, backed by a robust product portfolio.
The company's OSA portfolio includes CPAP and APAP machines, led by the AirSense platform. The AirSense 10 series is one of the most widely used CPAP and APAP machine series. Beyond sleep therapy machines, it also offers nasal, nasal-pillow, and full-face masks, along with a wide range of accessories and related products.
The broad product portfolio offers multiple avenues for generating recurring revenue beyond the initial sale of a sleep therapy device.
Monkey Business Images/Shutterstock.com
In the fourth quarter of fiscal 2026, ResMed's revenue increased 9% year over year to $1.5 billion, supported by strong demand for sleep devices, masks, and accessories. Americas device revenue increased 6%, while total Americas Sleep and Breathing Health revenue rose 8%. Americas masks and other revenue increased 10%. The stronger performance is particularly important as it highlights the ability to monetize the installed patient base beyond the initial device purchase.
#sleep #increased
20 days ago
Johnson & Johnson (JNJ) stock has returned about 57% over the past year, against about 17% for the S&P 500. On the earnings it has already banked, that price looks expensive. But those earnings carry STELARA, which is losing share to biosimilar competition. What looks dear on earnings already reported comes down sharply on the earnings ***** ysts expect.
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings
20 days ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta

20 days ago
On September 8, 2026, CNBC reported that Novartis AG (NYSE:NVS) shares fell about 10% after the company said its experimental drug del-desiran failed to meet its primary goal in a late-stage trial for myotonic dystrophy type 1.
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib
21 days ago
Ascendis Pharma A/S (NASDAQ:ASND) announced on September 14 that it will regain exclusive rights to develop, manufacture, and commercialize TransCon products in metabolic and cardiovascular diseases following the termination of its collaboration with Novo Nordisk A/S (NYSE:NVO).
The rights include once-monthly TransCon Semaglutide, an investigational long-acting prodrug of semaglutide intended for obesity and type 2 diabetes. Neither party will have continuing financial obligations to the other. Once termination becomes effective and the rights revert, management plans to initiate multiple programs across rare and large indications.
The investment question is whether greater control over future products can justify the resources needed to develop them.
Ascendis Pharma A/S (NASDAQ:ASND) would regain flexibility over which indications to pursue, how quickly to advance candidates, and whether to seek another partner. Successful independent development could retain more of a product's commercial economics, while a new collaboration could provide another way to share costs and risk.
Monthly dosing offers a clear development objective. If clinical studies demonstrate effective treatment with acceptable tolerability, fewer injections could make long-term therapy more convenient. That potential benefit would matter most if it helps patients stay on treatment without sacrificing outcomes.
#ascendis #pharma #asnd #regain

22 days ago
Merck (MRK) was at the center of a major cancer-treatment update in August. Specifically, the drugmaker and Moderna (MRNA) said their personalized mRNA cancer therapy, intismeran autogene, delivered positive results in a Phase 3 study involving 1,137 patients with high-risk melanoma.
Used with Keytruda, the treatment reduced the risk of cancer returning or causing death and improved distant metastasis-free survival compared with Keytruda alone. Merck shares jumped 11% on the news. That was a big move for the stock, which had posted only five single-day gains of more than 5% over the past year.
This High-Yield Construction Stock Just Raised Its Dividend by 40%
Dear Intuit Stock Fans, Mark Your Calendars for September 17
This Dividend Stock Is Staging a Turnaround in 2026 and Pays More Than 2.4%
#Dividend #high #treatment #risk


23 days ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival

23 days ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ***** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#biontech #survival

25 days ago
Amgen Inc. (NASDAQ:AMGN) shed roughly $12 billion in market value after hours on September 4, 2026. The stock declined by about 5% to $415. The reason, as strange as it sounds, is a drug it does not own. Novartis announced that pelacarsen, an Lp(a)-lowering therapy, missed its Phase 3 cardiovascular-outcomes trial, Lp(a)HORIZON. And since Amgen's late-stage ******* et olpasiran relies on the same biological premise, investors immediately marked down Amgen on the negative read-through.
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen
28 days ago
The pharmaceutical sector was hit with major pipeline news on September 1 when Novartis AG (NYSE:NVS) paused eight clinical trials of rap-cel, its experimental CAR-T cell therapy targeting autoimmune and neurological disorders. The suspension, effective August 24, followed three patient deaths caused by severe, life-threatening immune reactions (immune effector cell-associated hemophagocytic syndrome). Novartis is currently conducting a safety review alongside independent monitoring boards. Following the news, Bristol-Myers Squibb Company (NYSE:BMY) voluntarily paused trials for its competing CAR-T treatment, zola-cel, as a precautionary measure after detecting transient inflammatory side effects.
Looking at Q2 2026 earnings, Bristol Myers Squibb is currently demonstrating stronger financial momentum. Bristol-Myers Squibb Company (NYSE:BMY) reported total revenue of $13.0 billion, up 6% year over year, driven by a 15% increase in its Growth Portfolio to $7.6 billion, led by Opdivo, Qvantig, Reblozyl, and Camzyos. Non-GAAP EPS reached $2.04, while net income totaled $3.3 billion, or $4.2 billion on a non-GAAP basis. The company also raised its full-year 2026 revenue guidance from approximately $46.0–$47.5 billion to $49.0–$50.0 billion and increased its non-GAAP EPS outlook to $6.75–$7.00.
Novartis AG (NYSE:NVS), meanwhile, reported Q2 net sales of $14.4 billion, up 3% in U.S. dollars and 1% at constant currencies, supported by Kisqali and Kesimpta, which grew 43% and 32% at constant currencies, respectively. However, generic competition reduced growth by 14 percentage points, while core operating income remained flat at $5.9 billion and GAAP net income fell 19% to $3.3 billion. Novartis reaffirmed rather than raised its full-year guidance, calling for low single-digit sales growth and a low single-digit decline in core operating income.
Overall, Bristol Myers stands out as the stronger financial story this quarter, with its Growth Portfolio offsetting legacy patent-cliff pressures and supporting a guidance increase, while Novartis continues to contend with generic erosion weighing on earnings.
Novartis' bull case rests on strong double-digit growth from high-margin blockbusters such as Kisqali, Kesimpta, and Scemblix, supporting robust Q2 free cash flow of $5.6 billion. However, CAR-T safety setbacks could threaten a key pipeline platform, while intense generic competition has already reduced top-line growth by 14 percentage points.
#billion #novartis

28 days ago
Interested in AbbVie Inc.? Here are five stocks we like better.
SKYRIZI and RINVOQ remain AbbVie's main growth drivers, with additional opportunities in inflammatory bowel disease, vitiligo, alopecia and hidradenitis suppurativa. The company expects a subcutaneous SKYRIZI induction approval for Crohn's disease in the fourth quarter and plans further combination-therapy data.
AbbVie is advancing a broad pipeline, including the BCMA-directed cancer therapy etentamig, which showed strong early multiple-myeloma results and could support a rapid regulatory filing. Neuroscience programs such as bretisilocin for depression are also expected to deliver additional data this year.
The company is taking a selective approach to acquisitions and partnerships, having invested about $20 billion in roughly 30 transactions while increasing annual R&D spending toward $10 billion. Management maintained its outlook for high-single-digit annual revenue growth through the decade.
Moderna Just Doubled Overnight, and 2 More Healthcare Stocks Could Follow It
#disease #company #Therapy

29 days ago
Puka Nacua has opened up about his struggles with alcohol, therapy and rehabilitation ahead of the Los Angeles Rams' season opener against the San Francisco 49ers in Melbourne.
Speaking to Netflix's Elle Duncan, Nacua admitted he had used alcohol to escape the pressure building around him as his NFL career took off.
Nacua's rise has been remarkably quick. The former fifth-round pick became a star almost immediately, while last season he led the NFL with 129 receptions and finished with 1,715 receiving yards.
Photo by Robert Cianflone/Getty Images
The Rams receiver said becoming a public figure, maintaining a high level of performance and becoming a father all contributed to the stress he was carrying.
#Rams #season #angeles #francisco


1 month ago
On August 5, Protagonist Therapeutics (NASDAQ:PTGX) reported second-quarter 2026 results that flipped the company from red ink to a $162.8 million profit, or $2.29 per diluted share, compared with a $34.8 million loss a year earlier. The swing came as the company banked payments tied to two drugs moving from the lab bench to the pharmacy counter: ICOTYDE, an oral psoriasis treatment, and rusfertide, an injectable now awaiting an FDA decision. Cash and marketable securities climbed to $849.5 million. Here's what's fueling the optimism, and what could complicate it.
The quarter marked the first full three months of commercial sales for ICOTYDE, which won FDA approval on March 18 for moderate-to-severe plaque psoriasis in patients 12 and older weighing at least 40 kg. That approval triggered a $50 million milestone payment and made ICOTYDE, according to the company, the first and only FDA-approved targeted oral peptide for the condition. Protagonist can still collect up to $580 million more in milestones from partner Johnson & Johnson, plus royalties that average around 7.25 percent at $4 billion in annual sales.
Rusfertide carries even more weight. Its new drug application sits under Priority Review with a PDUFA goal date in August, backed by Breakthrough Therapy, Orphan Drug, and Fast Track designations for polycythemia vera. Partner Takeda already paid Protagonist $200 million on an opt-out election in April, with another $200 million and a $75 million approval milestone still due, on top of royalties that can reach 29 percent of sales above $1.5 billion. Behind both drugs, PN-881, an oral IL-17 antagonist, is heading into a Phase 2b psoriasis program in early 2027 after Phase 1 data showed drug levels beating their pharmacokinetic targets, and a Phase 1 study just began for PN-477sc, an injectable obesity peptide.
Look closer at that $213.5 million in license and collaboration revenue, and $192.4 million of it traces to the proportional recognition of Takeda's initial opt-out payment, not repeatable product sales. A year earlier, the same line item was just $5.5 million, so the growth reflects a single deal event more than an operating business scaling up. And that opt-out itself cuts both ways: Protagonist gave up its right to develop and commercialize rusfertide on its own, trading full ownership for royalties and milestones that depend on Takeda's execution rather than Protagonist's.
Spending is also set to climb. Management expects research and development costs to increase significantly in the second half of 2026 versus the first half, driven by the new PN-881 Phase 2b program, manufacturing investments, and added headcount. General and administrative costs are rising too, largely on stock-based compensation. And rusfertide's fate still hinges on an FDA decision that hasn't happened yet, priority review or not.
#protagonist
1 month ago
Starting statin therapy shortly after a type 2 diabetes diagnosis may not only protect the heart — it may also be linked to a lower dementia risk.
A large study presented at the European Society of Cardiology Congress in Munich on Aug. 30 found that adults who began taking a statin within one year of their type 2 diabetes diagnosis had a 15% lower relative risk of developing dementia over 10 years compared to those who did not take the medication within five years.
Even for those who delayed starting a statin for one to five years, there was still a 10% lower relative risk, according to the findings, which were published in The Lancet Regional Health – Europe.
3 Things To Avoid In Middle Age Could Mean 13 More Years Without Dementia, Study Finds
A statin is a prescription medication that lowers "bad" LDL cholesterol and helps reduce the risk of heart attack and stroke.
#risk #lower #study #diagnosis

1 month ago
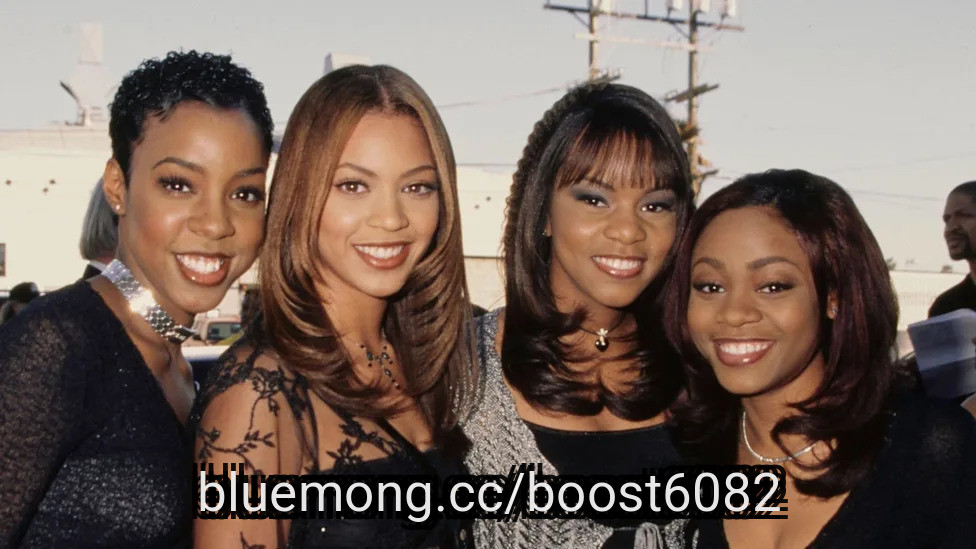
Destiny's Child was one of the biggest girl groups in the world, but high-profile line-up changes and lawsuits plagued their early success.
Two of the founding members, LeToya Luckett and LaTavia Roberson, filed a lawsuit against manager Mathew Knowles, Beyoncé's dad, for breach of contract, defamation, libel, and fraud, according to Rolling Stone, after claiming he favored Beyoncé and distributed the group's earnings somewhat creatively.
LeToya and LaTavia were then replaced by Michelle Williams and Farrah Franklin, who left the group after six months, and Destiny's Child became a trio.
LeToya and LaTavia were part of the original Destiny's Child lineup (@ Getty Images)
The lawsuit was settled out of court in 2002, and LeToya claimed in 2023 that all was forgiven. "Things happened the way they were supposed to happen," she said. "Baby, everybody's fine. We've done our therapy."
#letoya #beyonc #mathew #knowles

1 month ago
On August 3, Ocular Therapeutix (NASDAQ:OCUL) reported second-quarter 2026 financial results that read as much like a regulatory update as an earnings report. Management confirmed that AXPAXLI, its lead retinal disease candidate, remains on track for a new drug application submission for wet age-related macular degeneration in the fourth quarter of 2026, a plan the FDA effectively signed off on during a Type C meeting held in May. That timeline, paired with new data suggesting patients could need far fewer injections, is the headline. The rest of the report shows what it costs to get there.
AXPAXLI's case rests on the SOL-1 trial, which Ocular describes as the first successful superiority study of a new agent against an approved anti-VEGF therapy since that drug class arrived two decades ago. The FDA's May 2026 meeting minutes confirmed that SOL-1's efficacy and safety data, along with an interim safety look at the SOL-R trial and supporting evidence on axitinib, will be enough to support the NDA filing, and Ocular plans to file under the 505(b)(2) pathway, which could shave up to 60 days off a standard review.
A post hoc ***** ysis of SOL-1 adds a practical argument for the drug: applying SOL-R's stricter rescue criteria, Ocular estimates patients could need up to 72% fewer injections through 60 weeks, or 56% once the two loading doses are counted, than a patient on a typical every-eight-week aflibercept regimen, a gap that matters given that up to 40% of wet AMD patients quit treatment within their first year.
Early market research backs that pitch: about 80% of surveyed retina specialists said they would likely prescribe a drug with AXPAXLI's profile, and more than 90% expect to adopt it within a year of approval. The company says every Tier 1 payer it has engaged, across Medicare Advantage and commercial plans, has floated premium pricing for a more durable option. Underpinning all of it is a cash balance of $598.6 million as of June 30, which management expects to last into 2028.
Getting AXPAXLI to market is expensive, and the quarter showed it. Research and development spending rose to $54.1 million from $51.1 million a year earlier, selling and marketing costs climbed to $17.3 million from $13.7 million, and general and administrative expenses jumped to $22.2 million from $14.3 million, all tied to trial costs and a growing commercial team ahead of a launch that still is not approved. Net loss widened to $78.8 million from $67.8 million in the same quarter of 2025.
#quarter #costs

1 month ago
On August 25, Electromed (NASDAQ:ELMD) reported fiscal fourth-quarter results that extended a streak few small-cap medical device companies can claim: fifteen consecutive quarters of year-over-year revenue and profit growth. Net revenue hit a record $19.4 million, up 11.6% from a year earlier, and diluted earnings per share climbed to $0.39 from $0.25. Those headline numbers look clean, but they arrive alongside a leadership change and a hospital business moving in the opposite direction, which makes the quarter more complicated than the growth streak suggests.
Home care is still the whole story here. Home care revenue reached $17.7 million in the quarter, up 15.2% year over year, and for the full fiscal year it grew 16.3% to $66.6 million. That growth is coming from efficiency, not just headcount: on an annualized basis, home care revenue worked out to $1,145,000 per rep, above the company's own target range of $1 million to $1.1 million. Electromed ended the year with 64 direct sales reps and is targeting 67 filled territories for fiscal 2027, including two hospital account liaisons meant to catch patients as they move from acute care into home-based therapy.
The addressable market behind that growth still looks large. Management estimates roughly 1 million people in the U.S. carry a bronchiectasis diagnosis, yet only about 16% currently use high-frequency chest wall oscillation therapy, leaving close to 800,000 diagnosed patients untreated, plus more than 4 million additional people who may have the condition without a diagnosis at all. Payer access has kept pace with that opportunity.
Electromed closed the fiscal year with 87% of US covered lives under contract after signing 40 new payer agreements and adding 6 million covered lives. Its Smart Order e-prescribing tool handled 45% of fourth-quarter orders and shipped them noticeably faster than fax submissions, which matters as CMS rules phase out fax-based ordering by May 2028. All of this sits on a debt-free balance sheet, with cash growing to $20.5 million even after $3.9 million in share repurchases during the year.
The weaker spots are easy to miss next to those numbers. Hospital revenue fell 29% in the fourth quarter, which CEO James Cunniff attributed to a sales cycle that is "inherently less predictable than our other channels." The distributor channel grew just 2% in the quarter, and combined, the non-home care business grew only 6.7% for the full year versus 16.3% in home care, meaning nearly all of Electromed's growth is coming from one channel. SG&A expenses rose 8.7% to $42.7 million for the year, driven mainly by higher sales, marketing, and reimbursement compensation, and accounts receivable climbed to $29.8 million from $24.7 million as the business scaled up.
#quarter #Growth #electromed #hospital