27 days ago
Johnson & Johnson (JNJ) stock has returned about 57% over the past year, against about 17% for the S&P 500. On the earnings it has already banked, that price looks expensive. But those earnings carry STELARA, which is losing share to biosimilar competition. What looks dear on earnings already reported comes down sharply on the earnings ***** ysts expect.
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings
29 days ago
Johnson & Johnson (JNJ) has been a rewarding stock to hold, up about 53% over the past year against about 17% for the S&P 500. The change worth noticing over that stretch is quieter than the price. Management said sales still rose 5.6% despite a STELARA drag of about 460 basis points. Management is encouraging investors to evaluate the company's underlying momentum by presenting growth rates that exclude STELARA alongside its reported figures.
A year and a half ago, that drag was the headline. Management's own framing of the first quarter of 2025 noted an approximate 810 basis point headwind on Innovative Medicine sales.
By the second quarter of 2026, that segment-level drag remained heavy at roughly 760 basis points (or about 460 basis points across the total enterprise), yet management's emphasis shifted to highlighting double-digit operational growth excluding STELARA
The exclusion is not a rounding adjustment. STELARA sales fell 55.7% in the second quarter of 2026, and management put that drag at about 460 basis points of the whole company's 5.6% operational sales growth.
Two products show what the replacement looks like. TREMFYA booked $2 billion of sales in the second quarter of 2026, up over 70%, and management says ulcerative colitis and Crohn's disease are the major drivers of that growth. ICOTYDE, a recently launched once-daily pill for psoriasis, is the second, which leadership has highlighted as a key pipeline priority for the immunology business.
#sales #basis #drag #quarter

1 month ago
On August 12, Royalty Pharma (NASDAQ:RPRX) agreed to pay Zealand Pharma $100 million for the rights to future royalties on rusfertide, an experimental treatment for a rare blood disorder called polycythemia vera. It is Royalty Pharma's second collaboration with Zealand, and it arrives just as rusfertide awaits a decision from the FDA. For a company that makes its living buying pieces of other companies' drugs, the timing says a lot about how it weighs risk against reward before a regulatory verdict even lands.
Royalty Pharma's business depends on picking the right moment to buy into a drug's future, and this deal fits that pattern. Under the agreement, $50 million changes hands at closing and the remaining $50 million arrives on the first anniversary, in exchange for a 1% royalty on rusfertide's global sales plus any regulatory and commercial milestones. Rusfertide, a once-weekly self-injected therapy that mimics the hormone hepcidin to control iron levels in polycythemia vera patients, already has an FDA goal date set for the third quarter of 2026, with Takeda lined up to handle commercialization worldwide. That is a near-term catalyst most royalty purchases do not carry.
The broader portfolio backs up the confidence. Royalty Receipts grew 14% to $768 million in the second quarter of 2026, lifted by Tremfya, Voranigo, Imdelltra and Evrysdi, and the company raised its full-year 2026 guidance for Portfolio Receipts to a range of $3.4 billion to $3.5 billion, the second increase this year. Capital deployment has already topped $1 billion in 2026, including a July 2026 royalty purchase tied to AstraZeneca's cliramitug, pushing the development-stage pipeline to 19 potential therapies. Even after repaying a $380 million term loan in July 2026, Royalty Pharma still paid a quarterly dividend of $0.235 per share and bought back $45 million of stock in the second quarter alone.
Not every royalty ages well, and Royalty Pharma's own numbers show it. Promacta royalties fell 75% in the second quarter of 2026 to just $8 million as US generic competition took hold, and Imbruvica payments slipped 16% to $36 million, a reminder that patent cliffs eventually catch up to even the steadiest cash flows. That same risk sits underneath every new deal the company signs, including the one with Zealand.
The rusfertide agreement carries its own strings. Royalty Pharma's 1% royalty stops scaling once global sales pass $1.5 billion, at which point Zealand keeps a 0.25% cut and Royalty Pharma only 0.75%, so the largest commercial outcomes get split rather than fully captured. And rusfertide still has not cleared the FDA. The agency's goal date only falls in the third quarter of 2026, meaning the second $50 million payment is committed before regulators finish their review. Layer that onto a balance sheet carrying $9.2 billion in total debt principal against $812 million of cash as of June 30, 2026, and it becomes clear this is a company funding new bets with borrowed as w
2 months ago
Pharmaceutical giant Johnson & Johnson (NYSE:JNJ) is one of Jim Cramer's favorite stocks in the sector. Over the course of this year, the CNBC TV host has praised the firm on multiple occasions. Among the reasons that he has been optimistic about Johnson & Johnson (NYSE:JNJ) include the firm's cancer drug portfolio and its Triple A balance sheet. For instance, in his July 6th appearance on Mad Money, Cramer remarked that "P&Gs and the J&Js in your portfolio allow you to safely own the techs." With tech stocks struggling recent due to concerns about the data center buildout, it was unsurprising that Johnson & Johnson (NYSE:JNJ) popped up on his radar once again on August 24th:
"I've been using that one stock JNJ to be able to [example] becuase it has a better balance sheet at this point than the US government, it doesn't need money, it's got very good science. It's not hostage to the government right now. It's got more new drugs than any of the, 18 new compounds, could be a billion dollars. And I come back and say, all right, well that's the treasury, plus the upside."
Johnson & Johnson (NYSE:JNJ)'s shares are up by more than 50% over the past year. Cramer's optimism about the firm covers several, but not all, aspects of the debate surrounding the firm. While Johnson & Johnson (NYSE:JNJ) has raised its full-year revenue guidance to a midpoint of $101 billion, removed headwinds related to its longstanding talcum powder lawsuits and posted strong growth with its Darzalex and Tremfya drugs for myeloma and psoriasis, concerns about its MedTech growth, flat profits growth and a 55.7% sales hit to its immune system disorders drug Stelara continue to raise the potential for headwinds.
For instance, Johnson & Johnson (NYSE:JNJ)'s MedTech business grew by a mere 3.6% in the second quarter as it was impacted by a slowdown in sales of heart-recovery devices following a study in the United Kingdom. Additionally, for a firm that's struggling on the net income growth front, $5.5 billion in talc powder settlements will continue to be a headwind to the cash flow. Johnson & Johnson (NYSE:JNJ) is due to pay $3 billion out of the $5.5 billion in 2027. Yet, at the same time, the diversified business nature means that some segments are growing. One example is the Innovative Medicine Business, which grew by 6.8% to $16.4 billion revenue, due to Darzalex and Tremfya.
Looking at hedge fund sentiment, while 113 out of the 1,022 funds part of Insider Monkey's Q1 database had held a stake in Johnson & Johnson (NYSE:JNJ), the figure jumped to 117 out of 1,006 funds in Q2. Among the notable additions was Polar Capital's $199 million stake, while Fisher ****** et Management ****** ped its stake by 44% to $3.3 billion. On the valuation front, Johnson & Johnson (NYSE:JNJ) trades at a forward P/E ratio of 23.4,2 which is lower than MRK's 56.82 and higher than AbbVie's 18.83. Shares short as a percentage of float are negligible at roughly 1%.
#billion #tremfya


2 months ago
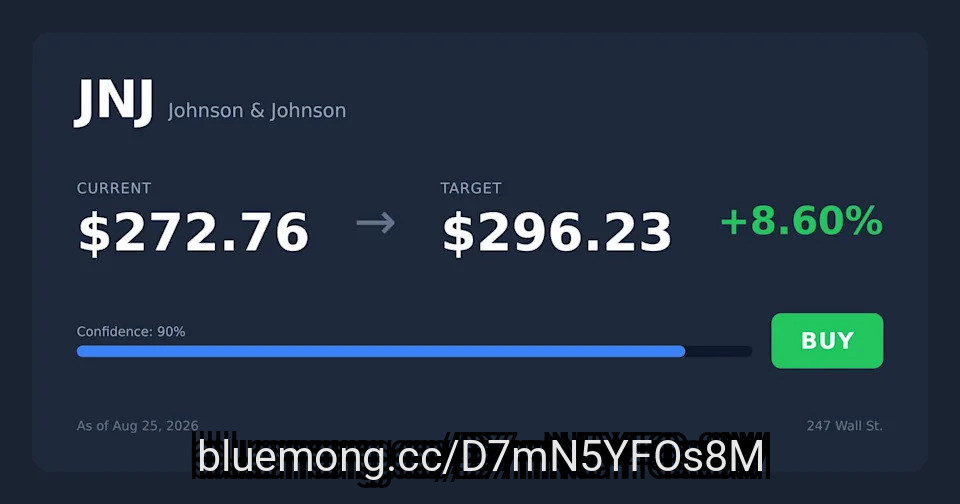
JNJ trades at $270, inches from its $276 52-week high, with raised guidance and FDA robotic approval already priced into **** yst consensus.
JNJ's 32% YTD gain nearly triples SPY's 12% return, yet a trailing P/E of 31 leaves little margin for earnings disappointment.
Tremfya surged 71% and Darzalex topped $4 billion in Q2, but Stelara's 56% decline continues to pressure free cash flow toward a $21 billion target.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Johnson & Johnson didn't make the cut. Grab the names FREE today.
At $270.24, Johnson & Johnson (NYSE:JNJ) is a hold. The stock has run to within striking distance of its 52-week high of $276.47 after a raised guide and robotics approval, and the setup at this price deserves careful consideration rather than a reflexive chase.
#raised #analyst


2 months ago
Healthcare investors looking for long-term growth don't always have to choose between fast-growing companies and defensive businesses. Sometimes the more interesting decision is between two high-quality companies that are growing for entirely different reasons. Johnson & Johnson (NYSE:JNJ) continues to benefit from the breadth of its pharmaceutical and medical technology businesses, while Thermo Fisher's (NYSE:TMO) outlook increasingly depends on a recovery in life sciences spending after several difficult years.
Both companies reported encouraging results, but does steady diversification or an improving industry cycle offer the stronger long-term opportunity for investors? Let's take a look.
Johnson & Johnson's (NYSE:JNJ) pharmaceutical business was arguably the biggest contributor to its strong quarter, as it helped increase total sales, generating $16.38 billion in quarterly sales and exceeding **** ysts' estimate of $16.1 billion. The healthcare giant now expects its annual sales to be around $101.1 billion at the midpoint, compared with $100.8 billion previously. In another optimistic feat, it raised its adjusted earnings per share forecast to $11.68 at the midpoint, from a previous $11.55 per share.
The most impressive aspect for Johnson & Johnson (NYSE:JNJ), however, wasn't simply pharmaceutical growth but rather the company's ability to offset one of the largest patent cliffs in its portfolio, as it absorbed a significant patent-related decline in Stelara sales while still raising its full-year outlook. Revenue from Johnson & Johnson's (NYSE:JNJ) Stelara, which treats psoriasis, Crohn's disease, and other autoimmune conditions, dropped over 55% in the quarter to $740 million due to patent loss.
However, the company's cancer and newer immunology drugs can be seen countering this loss, as sales of Tremfya, its psoriasis and inflammatory bowel disease drug, rose 72.5% to $2 billion, considerably exceeding the estimate of $1.74 billion. Strong performance from newer drugs such as Tremfya suggests the company's pipeline is successfully offsetting losses from older products.
#billion #tremfya

3 months ago
JNJ's 23x forward P/E for double-digit oncology growth undercuts KO's 26x multiple, making JNJ the stronger risk-reward defensive anchor right now.
KO's 12% revenue surge masks thin fundamentals, given that only 3% volume growth means most gains came from pricing that could reverse.
Polymarket traders price a 92% chance JNJ beats its next earnings, fueled by DARZALEX and TREMFYA absorbing STELARA's biosimilar erosion.
This lithium producer surpassed a $1B private valuation, joining some of America's most powerful startups. Now you can invest in EnergyX alongside global giants like General Motors, but only through July 16. (sponsor)
Johnson & Johnson (NYSE:JNJ) and Coca-Cola (NYSE:KO) both delivered Q1 2026 beats and both are being crowded into by capital rotating out of tech. JNJ has broken out past $259, while KO just tagged an all-time high near $84.14. That backdrop makes this a real premium-defensive showdown.

4 months ago
Johnson & Johnson (NYSE: JNJ) stock jumped 3.4% through 12:20 p.m. ET Friday after Guggenheim ***** yst Vamil Divan raised his price target on the already buy-rated stock to $270 per share.
Johnson & Johnson stock closed below $245 yesterday, suggesting Divan sees potential for the biopharmaceutical company to gain another 10.2% over the next 12 months. Add a 2.2% dividend yield, and that's a respectable 12.4% potential profit in a year.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Divan updated his numbers ahead of JNJ's Q2 earnings release due July 15. Going over the numbers, he predicts modest top- and bottom-line "beats" for the company, with revenue coming in around $25.5 billion and profits of perhaps $2.87 per share.
On guidance, Divan advises investors to focus on two key areas for JNJ: immunology and oncology. On the former, Tremfya, Caplyta, and Erleada prescriptions are doing better than expected, and he's thinking this trend could continue, especially for Tremfya (an anti-inflammatory).