

22 days ago
Burry is mitigating near-term tax selling in underperforming holdings.
The investor foresees an early end to the artificial intelligence boom, positioning for a 2000–2003 style value equity revival.
Significant capital is being directed into discounted Chinese equities like BYD, while maintaining a cautious stance on Alibaba amidst its infrastructure spending.
Renowned value investor Michael Burry outlined his fourth-quarter portfolio maneuvers in an update on his Cassandra Unchained Substack platform on Monday, revealing how he is positioning around tax-loss harvesting headwinds while building long-term exposure to deeply discounted sectors.
Burry noted that the final quarter routinely brings heightened selling pressure on underperforming equities as investors sell underperforming ***** ets at a loss to offset capital gains.
#burry #positioning #capital #equities

1 month ago
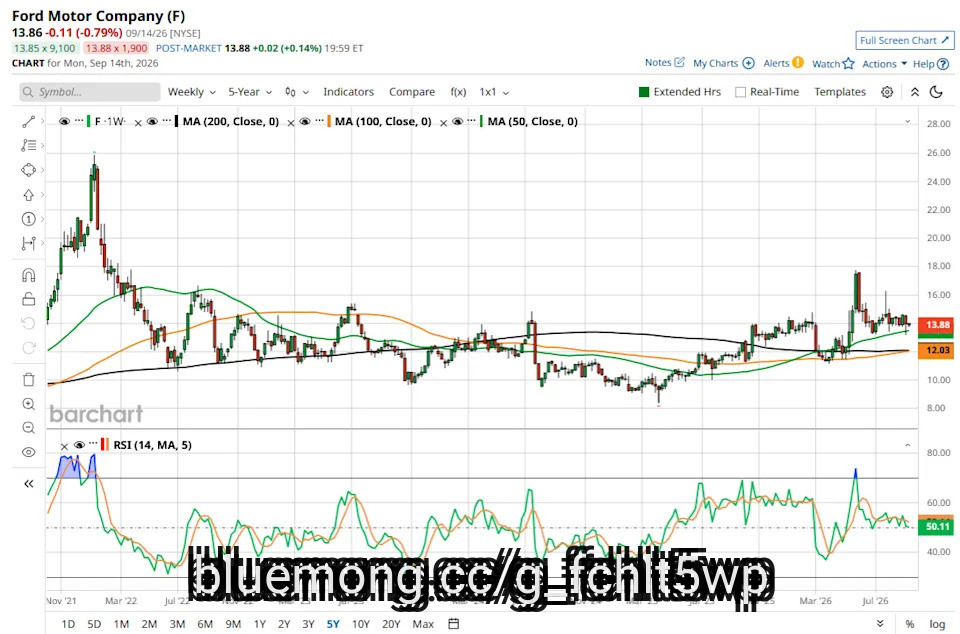
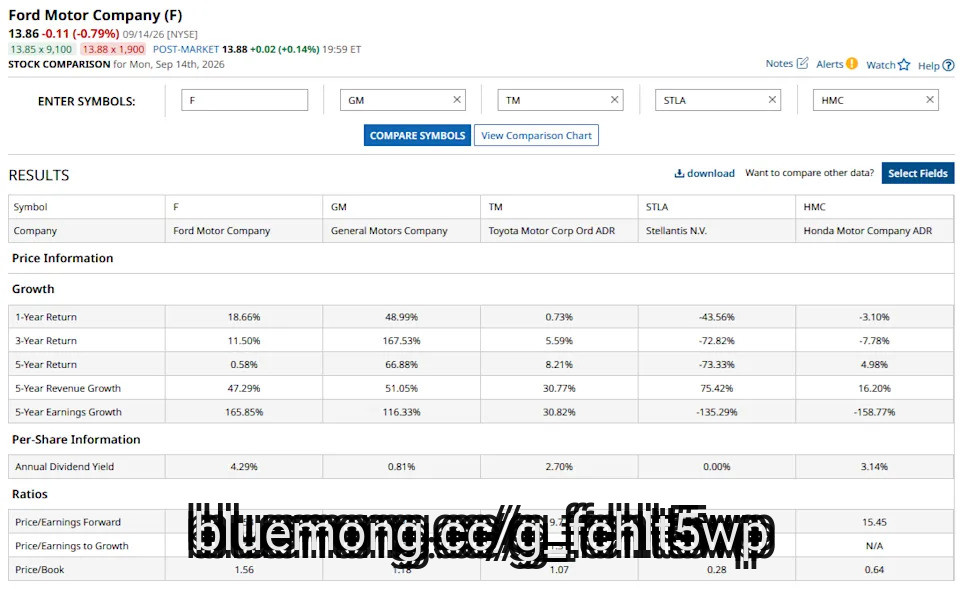
With a dividend yield of 4.3%, Ford (F) is among the highest-yielding constituents of the S&P 500 Index ($SPX). That number would look even more compelling considering Ford's dividend yield is over four times what an average S&P 500 Index constituent pays.
However, a bit of number-crunching tells a different picture. Dividend yield is basically a function of the per-share dividend, which is the numerator in the equation, and the stock price, which is the denominator. Dividend yield rises when the company raises its dividends or the share price falls. More often than not, the latter is true for companies that have a very high dividend yield.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ****** ysis you won't find anywhere else.
The S&P 500's dividend yield is near its historical lows. Two factors can be blamed for the dip in the world's most popular index's dividend yield. First, tech companies' share in the market-cap-weighted index has soared amid the artificial intelligence (AI) driven rally. Mega-cap tech companies are known to be frugal with dividends, and their rising weightage in the index pulls down its dividend yield. Second, while the annualized dividend per share of the S&P 500 has continued to rise over the years, the increase has been much lower compared to the surge in stock prices.
In contrast, Ford's quarterly dividend has been static since July 2022, when the company raised the payout by 50% to $0.15. Notably, while Ford paid special dividends in the preceding three years to reach its payout targets, it hasn't raised its payout for over four years. Its dividend yield is still high because of its underperforming stock, which has essentially gone nowhere in the last five years and trades 46% below its October 2022 highs.
#Dividend #yield #Share #dividends


1 month ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa

1 month ago
The casual Mexican restaurant sector has faced a challenging year in 2026, as dining chains have closed underperforming locations, filed for Chapter 11 bankruptcy protection to reorganize their businesses, and in at least one case, filed for Chapter 7 liquidation to shut down all operations.
Once popular Mexican chain On the Border ceased operations in 2026, after closing all of its locations before its operating company, OTB Hospitality, filed for Chapter 7 liquidation on June 19, 2026, the company shared in a press release.
Another chain facing financial distress is Session Taco, a St. Louis-based casual Mexican dining chain, which closed one of its restaurant locations for the second time in seven months. The chain has not filed for bankruptcy.
The Mexican chain, originally branded Mission Taco Joint until a 2023 name change, closed its Sobremesa restaurant in St. Charles, Mo., on Sept. 13 after only three months of operation, according to its Facebook page.
The St. Charles location was previously branded as Session Taco until the company closed the restaurant on Feb. 13 to redesign and rebrand the restaurant as Sobremesa before reopening in June 2026.
#mexican #locations


1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor


1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor


1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter


1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#multi #investment

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#charter #multi #investor

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Equity


1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Equity #fund #weitz

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund

1 month ago
As of 11:38 AM ET, the S&P 500 (SNPINDEX:^GSPC) is down 0.44% to 7,623, the Nasdaq Composite (NASDAQINDEX:^IXIC) has fallen 0.44% to 26,217 as cooling artificial intelligence sentiment weighs on growth stocks, and the Dow Jones Industrial Average (DJINDICES:^DJI) is trading 0.36% lower to 52,422.
Gold is down 1.88% to $4,325.10, and the 10-Year Treasury yield has slipped 0.02% to 4.96%, after reaching 5% for the first time since 2023. Communication stocks and healthcare are leading sector gains, while basic materials and industrials are underperforming.
Meta Platforms is climbing today after Goldman Sachs maintained a Buy rating, stressing the potential upside from its Muse AI agent. Micron Technology tumbled over 5% following warnings about the risks of rapid AI development. Those same concerns drove gains in cybersecurity stocks -- CrowdStrike Holdings soared 15%.
Tech leaders have issued dire warnings about the risks of rapid artificial intelligence (AI) development in recent days, prompting an industrywide pullback. Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman both highlighted the dangers that advanced systems could quickly move beyond human control and called for a slower pace of development.
Investors fear any slowdown could impact demand for AI infrastructure, pressuring some of this year's outperformers, such as Marvell Technology, CoreWeave, and Intel. Those worries are understandable, but it is important think about how any controls on AI development might impact long-term growth. Near-term sentiment may slip, but AI isn't going to disappear, and there is a chance that a slower build-out could actually strengthen the industry in the long term.
#down
2 months ago
Chinese e-commerce giants such as Shein and Temu have reshaped the retail landscape amid economic uncertainty, higher prices, and cautious consumer spending by offering shoppers a wide range of products at extremely low prices.
Their growth has prompted established companies such as Amazon, Target, and Walmart to invest in strategies like third-party marketplaces, supply chain infrastructure, and digital tools to keep pace with changing consumer habits.
Now, one online-first fashion retailer is taking a different approach. While many established brands have been reassessing their physical footprints and closing underperforming stores, this e-commerce fashion company is moving in the opposite direction by expanding its brick-and-mortar presence in the U.S.
Founded in 2020 as an online-first womenswear brand, Cider has built its business around affordable, trend-driven fashion and a digital-focused shopping experience.
Cider opened its second permanent U.S. retail location on September 4, 2026, at Westfield Valley Fair in San Jose, California. The 11,269-square-foot store is located at 2855 Stevens Creek Blvd., ****** e No. 2411.
#fashion #cider #prices #first

2 months ago
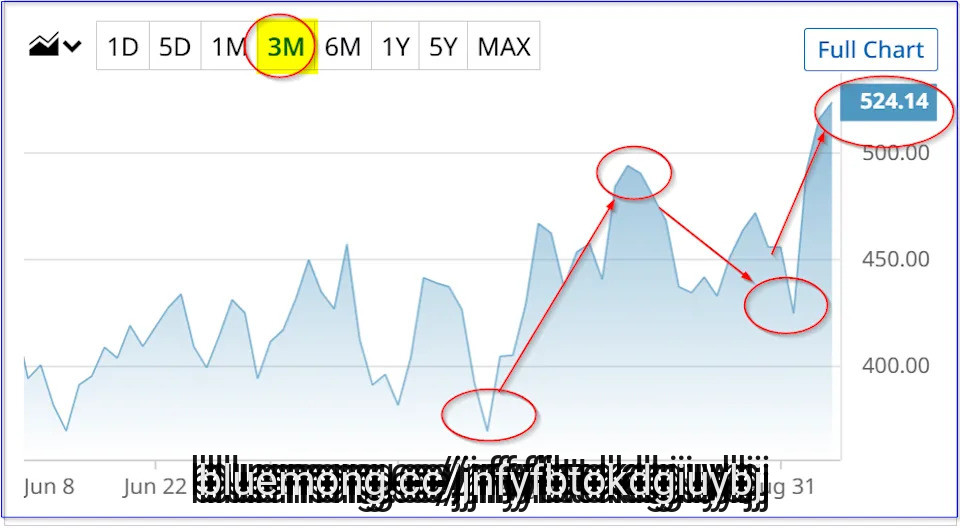
Dell Technologies (DELL) stock spiked almost $100 this week after its Sept. 1 Q2 earnings release, following strong earnings and free cash flow (FCF) performance. But it's near my prior FCF-based price target ($525.71) from a month ago. Moreover, ***** ysts' PTs are only slightly higher (+7.6%).
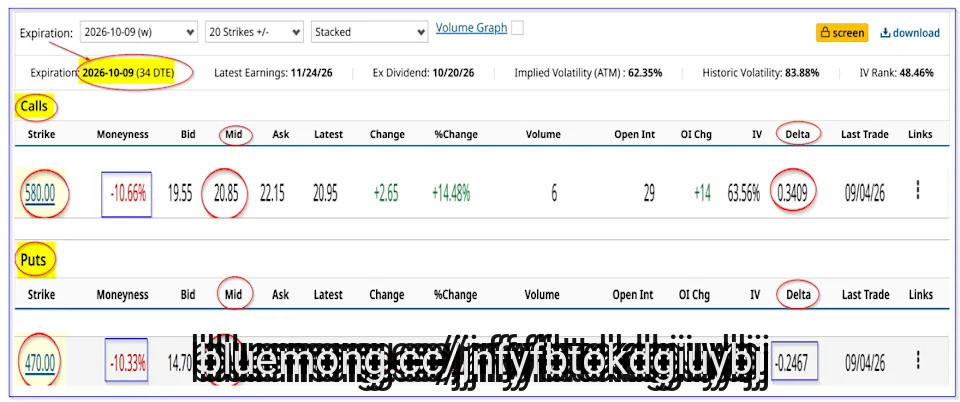
As a result, instead of buying DELL stock here, shorting out-of-the-money options may be a better play. That way, an investor can collect a premium while waiting to buy in (i.e., a short-put play) lower or sell at a higher price (a covered call play). This article will show how these work.
Meta Is Underperforming Every Trillion-Dollar Stock but Tesla. This Trade Pays You While Wall Street Waits It Out.
Markets move fast. Keep up by reading our FREE midday Barchart Brief newsletter for exclusive charts, ***** ysis, and headlines.
DELL closed at $524.14 on Friday, Sept. 4, up +23.3% from its pre-earnings close on Sept. 1 of $425.00. In fact, it's been quite volatile, as seen in the Barchart chart below. In fact, its implied volatility (IV) is relatively high at 62.50%, according to Barchart.
#earnings

2 months ago
If it's strong capital appreciation that you're after, then Procter & Gamble (NYSE: PG) isn't the best investment candidate. Its shares are up just 67% in the past decade (as of Sept. 3), drastically underperforming the S&P 500 index.
But if you're seeking a blue chip dividend stock, then Procter & Gamble is hard to beat. Its dividend yield of nearly 3% is almost triple the benchmark average.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Here's how many shares of this company you'd need for $15,000 in yearly dividends.
Procter & Gamble currently pays an annual dividend of about $4.34 per share. This means you would have to own 3,456 shares to generate $15,000 in yearly passive income. Based on the stock price of $147.51, investors would be required to pay $510,000 to buy enough shares.
#NVIDIA #Stock #company
2 months ago
On August 26, JinkoSolar (NASDAQ:JKS) reported a quarter that looked rough on the surface but revealed a company quietly rebuilding itself underneath. Revenue fell 31.3% year over year to $1.82 billion, and the net loss widened to RMB 697.3 million from RMB 463.5 million in the prior quarter. Yet the same earnings call showed a business leaning harder into storage, high-efficiency manufacturing and a growing side portfolio of outside investments, all while its core panel business absorbs a brutal pricing environment.
Module shipments climbed 16.7% sequentially to 15,961 megawatts, and overseas markets made up more than 70% of first-half 2026 volume. Its Tiger Neo 3.0 line still commands roughly a $0.10 per watt premium over conventional panels, and the newer Tiger Neo 5.0 modules reached 25.91% mass-production efficiency with output topping 700 watts. JinkoSolar expects 40 gigawatts of TOPCon 3.0 capacity by year-end, built to clear the toughest efficiency tier under China's new national standard taking effect in January 2027, a rule under which underperforming products "will not be permitted for production or sales," according to CEO Du.
Energy storage is scaling too. Shipments hit 3.1 gigawatt-hours in the first half of 2026, a sharp increase from a year earlier, with 1.5 gigawatt-hours already recognized as revenue, including more than 1 gigawatt-hour in the second quarter alone. Beyond the core business, JinkoSolar's strategic investment arm now holds stakes in more than 40 companies spanning solar, storage and artificial intelligence, worth RMB 1.99 billion in fair value and generating RMB 490 million in first-half gains. That included a divestment of its LAPLACE Renewable Energy Technology stake for more than RMB 300 million in cash and a ***** ulative realized gain topping RMB 250 million, plus a sale of its U.S. subsidiary that brought in RMB 1.31 billion in cash. The board still declared a $1.50 per ADS dividend in June 2026.
The core problem is that panels are getting cheaper to sell and more expensive to make. Gross margin slid to 4.2% from 8.3% in the first quarter of 2026 as average selling prices dropped, while the cost of ramping up high-efficiency production stayed elevated. Operating loss margin widened to 11.6% from 4.8% a quarter earlier, and total operating expenses rose 21.3% sequentially to $287.3 million on higher expected credit losses. Cash on hand fell to $2.5 billion from $3.3 billion in a single quarter, and JinkoSolar cut its full-year shipment guidance to a range of 60 to 70 gigawatts.
#efficiency
2 months ago
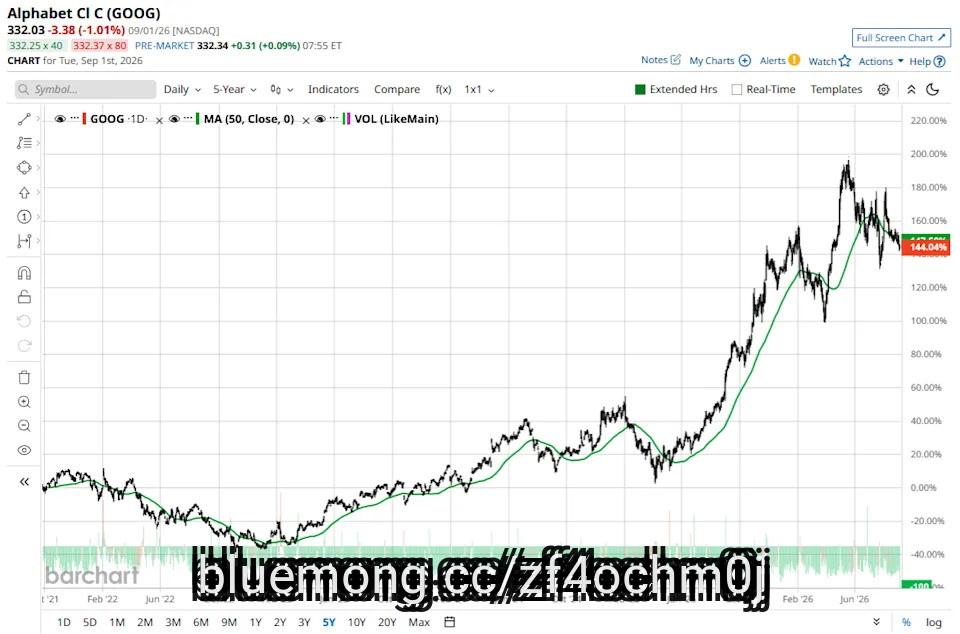
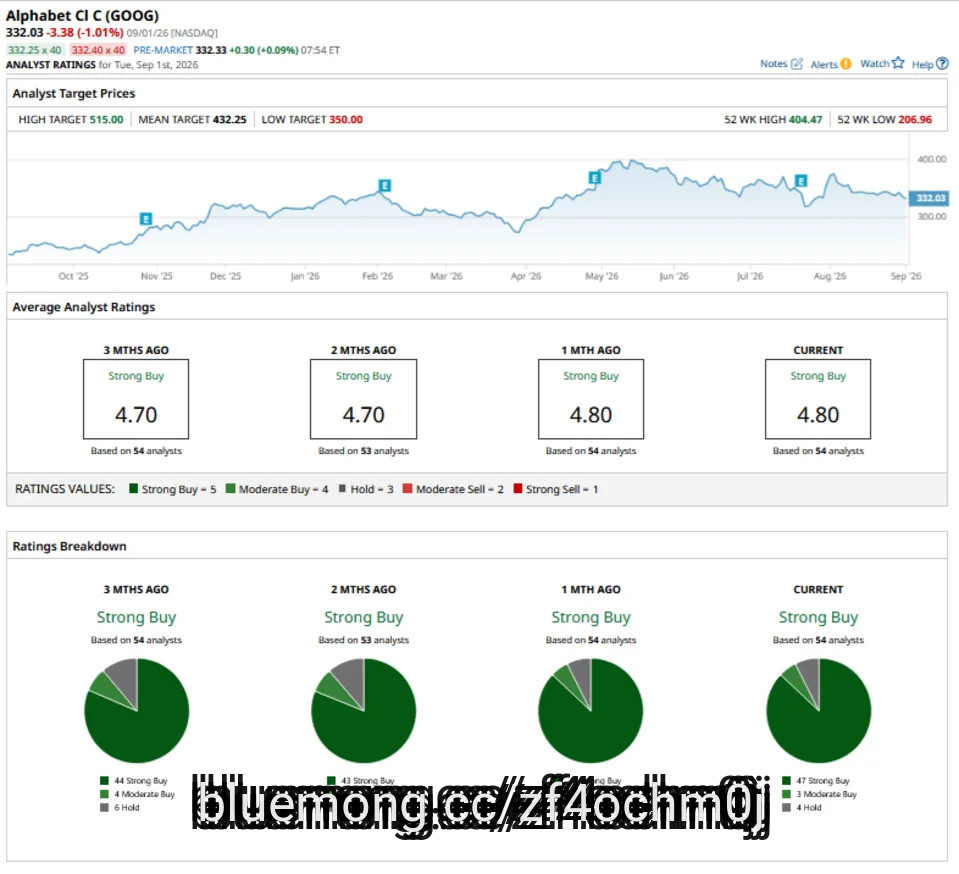
Alphabet (GOOG) (GOOGL) has seen a reversal of fortunes this year after gaining nearly 65% in 2025 to clock its second-best year ever. The stock was the best-performing Magnificent 7 stock last year by a fairly good margin, but 2026 has been a different ballgame.
Alphabet is up just 6.5% this year and is underperforming the S&P 500 Index ($SPX). The stock peaked above $400 in May and has since plunged almost 18%. It is now nearing a bear market, which, by definition, is a drawdown of 20% from recent highs. As I noted in my article in January, I did not expect GOOG to repeat its stellar 2025 performance this year. In this article, we'll explore whether the stock's valuations are now attractive enough to make it a "buy" or whether investors should continue to stay on the sidelines.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ****** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#alphabet #best #article #magnificent

2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted DPC Holdings PLC (NYSE:DPC) as a new addition. DPC Holdings PLC (NYSE:DPC) manufacturers engine products, including complex precision cast components and nickel- and cobalt-based superalloys for aerospace, industrial gas turbine and transportation industries. On September 1, 2026, DPC Holdings PLC (NYSE:DPC) closed at $41.48 per share. Over the past month, DPC Holdings PLC (NYSE:DPC) declined 20.69%. DPC Holdings PLC (NYSE:DPC) has a market capitalization of $6.02 billion.
Baron Global Opportunity Fund stated the following regarding DPC Holdings PLC (NYSE:DPC) in its Q2 2026 investor letter:
We also initiated a new position in DPC Holdings PLC (NYSE:DPC), a leading manufacturer of precision-cast superalloy components – the turbine blades, vanes, and structural castings that must perform under very harsh operating conditions including very high temperatures (1000c) and high pressure. These parts go into both commercial aircraft engines and industrial gas turbines (IGT) that generate electricity. The company occupies a hard-to-replicate market positioning as a critical supplier of the inner parts of an engine that only a handful of qualified manufacturers in the world are capable of producing.
Since the company began its turnaround in 2020 after over a decade under poor ownership, with the leadership of CEO Mike Quinn, who spent over a decade at Precision Castparts, and Co Chairperson of the Board Dirkson Charles, who built and currently is CEO of aerospace and defense proprietary parts provider

2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted CrowdStrike Holdings, Inc. (NASDAQ:CRWD). CrowdStrike Holdings, Inc. (NASDAQ:CRWD), a leading cybersecurity technology company, contributed 2.23% to the fund's performance this quarter. On September 1, 2026, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) closed at $215.07 per share. Over the past month, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) declined 2.01%, but its shares are up 99.08% over the past year. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) has a market capitalization of $220.22 billion.
Baron Global Opportunity Fund stated the following regarding CrowdStrike Holdings, Inc. (NASDAQ:CRWD) in its Q2 2026 investor letter:
"Leading cloud-native cybersecurity platform CrowdStrike Holdings, Inc. (NASDAQ:CRWD) contributed to performance during the quarter with the stock up 95.6% as the market increasingly recognized the company as one of the primary beneficiaries of enterprise AI adoption. As organizations increasingly adopt AI, cybersecurity has moved to the forefront of C-suite concerns, and CrowdStrike is well positioned to potentially benefit as a leading platform with unmatched data and a large installed base that helps it defend better against breaches. That standing was reinforced when CrowdStrike was named a launch partner in major AI-industry security collaborations, including Anthropic's Project Glasswing and OpenAI's Trusted Access for Cyber program, underscoring its role in addressing new security challenges created by AI. This is already translating into demand. CrowdStrike's AI detection

2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted Nu Holdings Ltd. (NYSE:NU). Nu Holdings Ltd. (NYSE:NU) is a leading digital banking platform, which detracted from the fund's performance this quarter. On September 01, 2026, Nu Holdings Ltd. (NYSE:NU) closed at $14.46 per share. Over the past month, Nu Holdings Ltd. (NYSE:NU) returned 3.21%, but its shares are up 0.30% over the past year. Nu Holdings Ltd. (NYSE:NU) has a market capitalization of $69.85 billion.
Baron Global Opportunity Fund stated the following regarding Nu Holdings Ltd. (NYSE:NU) in its Q2 2026 investor letter:
"Shares of Nu Holdings Ltd. (NYSE:NU) underperformed during the quarter, declining 7.1% following a weaker-than-expected 1Q26 earnings release. Provisions exceeded expectations by 37%, resulting in a 7% earnings miss and raising investor concerns about the near term outlook for credit costs and profitability. The unexpected departure of the CFO also weighed on sentiment. Concerns were further compounded by management's ambitions in the U.S., where the competitive landscape is materially more mature and the long-term returns on incremental investment remain less certain. That said, the CEO subsequently outlined a more measured approach to U.S. expansion (limiting investment to 1% of revenues over 2026-2027) and capital deployment, which provided us with greater comfort regarding execution and resource allocation. We viewed the market's reaction as an attractive opportunity to increase our position, taking advantage of the pullback in the share price. While these developm

2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted Wix.com Ltd. (NASDAQ:WIX). Wix.com Ltd. (NASDAQ:WIX), a cloud-based web development platform for registered users and creators, detracted from the fund's performance this quarter. On September 1, 2026, Wix.com Ltd. (NASDAQ:WIX) closed at $88.38 per share. Over the past month, Wix.com Ltd. (NASDAQ:WIX) returned 40.93%, and its shares are down 37.09% over the past year. Wix.com Ltd. (NASDAQ:WIX) has a market capitalization of $3.7 billion.
Baron Global Opportunity Fund stated the following regarding Wix.com Ltd. (NASDAQ:WIX) in its Q2 2026 investor letter:
"Shares of Wix.com Ltd. (NASDAQ:WIX), a cloud-based platform for building and managing websites and online businesses, declined 51.0% during the second quarter. The stock came under pressure as growth in the company's core business decelerated, with bookings and new user cohorts softening relative to prior quarters. While the newer AI-driven offering (Base 44) continued to grow, it was not enough to offset slowing momentum in the established core business, raising questions about the durability of the overall growth algorithm. We had valued Wix for its combination of durable subscription revenue, expanding free cash flow, and disciplined capital returns, but the deceleration in the core business undermined a central pillar of our thesis. We have therefore exited the position during the quarter, redeploying capital toward opportunities with clearer growth trajectories."
#quarter
2 months ago
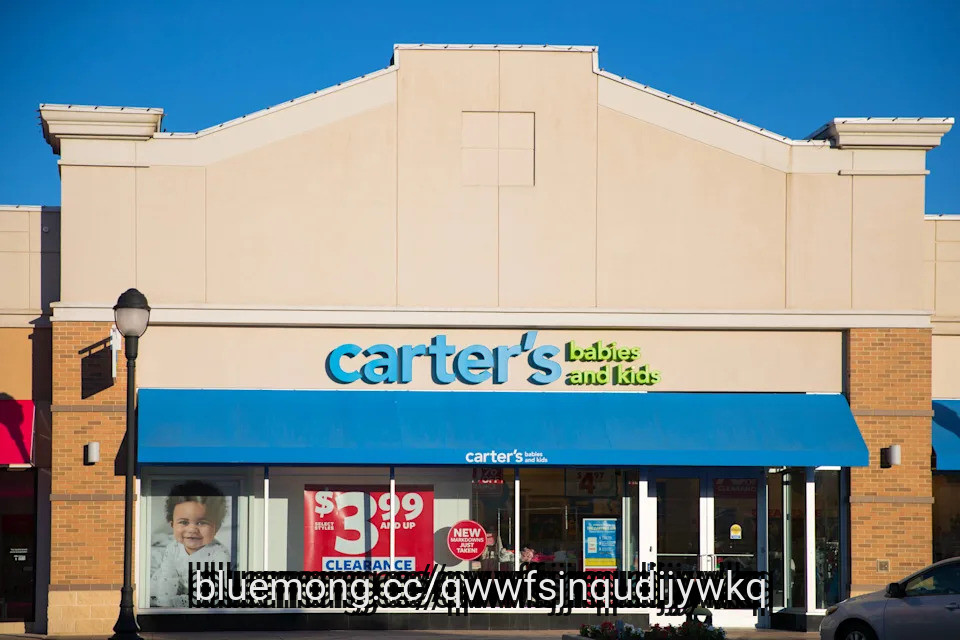
As parents continue to feel pressures on their household budgets, increasingly skipping specialty clothing stores in favor of one-stop shopping at big-box giants like Target and Walmart, another children's apparel retailer is closing stores.
Industry data confirms this shift, revealing that mass merchants now capture 80% of planned spending in the back-to-school category, according to Deloitte.
This shift in consumer spending habits, paired with the shrinking malls data, including projection from Capital One Shopping suggesting that up to 87% of traditional shopping malls could close over the next decade, has forced a number of mall clothing retailers to shut a number of underperforming locations.
A mall staple The Children's Place has shuttered hundreds of locations in recent years as part of a major restructuring plan to shed costly real estate, and legacy specialty chain, Carter's, has started its wave of planned closures in 2025.
Founded in 1865, Carter's grew from a modest Massachusetts knitting mill into North America's largest children's clothing maker by continually expanding its footprint and acquiring legacy brands like OshKosh B'gosh.
#like #data #shift

2 months ago
As parents continue to feel pressures on their household budgets, increasingly skipping specialty clothing stores in favor of one-stop shopping at big-box giants like Target and Walmart, another children's apparel retailer is closing stores.
Industry data confirms this shift, revealing that mass merchants now capture 80% of planned spending in the back-to-school category, according to Deloitte.
This shift in consumer spending habits, paired with the shrinking malls data, including projection from Capital One Shopping suggesting that up to 87% of traditional shopping malls could close over the next decade, has forced a number of mall clothing retailers to shut a number of underperforming locations.
A mall staple The Children's Place has shuttered hundreds of locations in recent years as part of a major restructuring plan to shed costly real estate, and legacy specialty chain, Carter's, has started its wave of planned closures in 2025.
Founded in 1865, Carter's grew from a modest Massachusetts knitting mill into North America's largest children's clothing maker by continually expanding its footprint and acquiring legacy brands like OshKosh B'gosh.
#spending


2 months ago
As parents continue to feel pressures on their household budgets, increasingly skipping specialty clothing stores in favor of one-stop shopping at big-box giants like Target and Walmart, another children's apparel retailer is closing stores.
Industry data confirms this shift, revealing that mass merchants now capture 80% of planned spending in the back-to-school category, according to Deloitte.
This shift in consumer spending habits, paired with the shrinking malls data, including projection from Capital One Shopping suggesting that up to 87% of traditional shopping malls could close over the next decade, has forced a number of mall clothing retailers to shut a number of underperforming locations.
A mall staple The Children's Place has shuttered hundreds of locations in recent years as part of a major restructuring plan to shed costly real estate, and legacy specialty chain, Carter's, has started its wave of planned closures in 2025.
Founded in 1865, Carter's grew from a modest Massachusetts knitting mill into North America's largest children's clothing maker by continually expanding its footprint and acquiring legacy brands like OshKosh B'gosh.
#shopping #specialty #like
2 months ago
Underperforming store locations have been a major problem for various retail sectors, such as supermarkets, apparel shops, and drugstore chains, forcing retailers to close shops to eliminate a drain on liquidity.
Restaurants have also closed struggling locations to cut their losses, and now manufacturers are also closing underperforming facilities as well.
Giant tool company Stanley Black & Decker Inc. plans to close its underperforming Hampstead, Md., factory and lay off 55 workers, according to a Worker Adjustment and Retraining Notification Act notice filed with the Maryland Department of Labor on Aug. 19.
Layoffs at the factory are set to begin on Oct. 23, 2026, and continue through the facility's closing by March 26, 2027, according to the WARN notice.
"Over the past few years, we have seen a steady decline in volume in the materials produced at our Hampstead, Maryland, manufacturing facility," Stanley Black & Decker spokesperson Debora Raymond told the Baltimore Sun.
#underperforming #black


2 months ago
On August 3, TotalEnergies SE (NYSE:TTE) signed an agreement to acquire Shell plc (NYSE:SHEL)'s entire onshore renewables business in Europe. The acquisition includes 500 MW of operational or under-construction solar and wind ******* ets primarily in Italy and the Netherlands, alongside a 3.5 GW pipeline of solar, wind, and battery storage projects across Italy, the UK, and Spain. Set for completion by late 2026 pending regulatory approval, the deal directly advances TotalEnergies' European Integrated Power strategy, bolstering its existing portfolio of roughly 10 GW in gross capacity/construction and 27 GW under development. Following the news on August 3, Piper Sandler ******* yst John Royall raised Shell's price target from $88 to $89 while maintaining a Neutral rating, citing strong Q2 trading beats.
Both Big Oil majors reported robust Q2 2026 results driven by operational efficiency, yet distinct financial profiles emerge. TotalEnergies SE (NYSE:TTE) generated adjusted net income of $6.0 billion and cash flow from operations (CFFO) of $9.8 billion on 2.395 Mboe/d production, keeping Upstream operating costs down to $5/b despite Middle East transit disruptions. Shell outperformed on sheer cash generation, posting $9.8 billion in Adjusted Earnings and CFFO of $21.4 billion, supported by record upstream production in Brazil, record refinery utilization, and a $3.4 billion working capital inflow.
TotalEnergies retains a leaner debt profile with a gearing ratio of 13.1% ($3.3 billion net debt reduction), whereas Shell holds a 19% gearing ratio with $42 billion in net debt ($12 billion excluding leases). While Shell plc (NYSE:SHEL) leads on top-line cash generation, TotalEnergies displays superior balance sheet leverage and higher quarter-over-quarter cash flow growth (+15%).
TotalEnergies' bull case is supported by strong execution of its Integrated Power strategy, with expanding high-margin renewable power capacity alongside low Upstream costs of approximately $5 per barrel. Its healthy balance sheet, reflected in 13.1% gearing, provides financial flexibility to support a 5.9% dividend increase to €0.90 per share while continuing $1.5 billion in quarterly share buybacks. However, the bear case centers on weakness in Integrated LNG, particularly from underperforming European gas trading. Continued exposure to geopolitical disruptions along Middle Eastern transit corridors could also restrict physical oil liftings and weigh on operations.
#TotalEnergies #shell #upstream

2 months ago
Underperforming store locations have been a major problem for various retail sectors, such as supermarkets, apparel shops, and drugstore chains, forcing retailers to close shops to eliminate a drain on liquidity.
Restaurants have also closed struggling locations to cut their losses, and now manufacturers are also closing underperforming facilities as well.
Giant tool company Stanley Black & Decker Inc. plans to close its underperforming Hampstead, Md., factory and lay off 55 workers, according to a Worker Adjustment and Retraining Notification Act notice filed with the Maryland Department of Labor on Aug. 19.
Layoffs at the factory are set to begin on Oct. 23, 2026, and continue through the facility's closing by March 26, 2027, according to the WARN notice.
"Over the past few years, we have seen a steady decline in volume in the materials produced at our Hampstead, Maryland, manufacturing facility," Stanley Black & Decker spokesperson Debora Raymond told the Baltimore Sun.
#maryland #close




