59 mins. ago
This is one of the best letters that I have read in my lifetime ("We lived within our means: I earned $30,000 as a pastor and still retired comfortably"). I used to be a mortgage-loan officer; I would get a couple that each made six figures, but would have difficulty qualifying them for a loan amount they wanted because of their consumer-debt load.
Conversely, I would have a blue-collar "Joe Sixpack" that made substantially less but saved and saved and saved, and who got the loan he needed for a house. People in the U.S. need to wake up and not be compulsive: Quit buying things you really don't need. It's that way with the federal government as well, and based on that.
My wife never went back to work after raising our kids. Do I have to share my retirement savings 50/50?
Go ahead and get that poetry degree. Republican law won't prevent people with humanities majors from getting student loans.
We'd better get real quick or we're going to have a financial crisis that makes the Great Recession of 2008 look like a picnic.
#conversely

19 days ago
The choice between established ****** ans and digital-first challengers defines many modern portfolios. In the financial realm, investors must decide if JPMorgan Chase (NYSE:JPM) or SoFi Technologies (NASDAQ:SOFI) is the better buy for long-term growth.
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term

1 month ago
It's such an exciting time here at SB Nation with our launch of a brand-new, free app!
You've probably seen the links at the bottom of your screen, with availability on both iOS and Android, but I want to explain a little about why the app is going to be a daily read for you. Firstly, the home screen, which is a rolling feed of everything you tell us you want to see. We understand fans, and that being hyper-focused on just your city is what a lot of you care about, so this strips out all the extra stuff to only show you what you want to see.
Conversely, some of you like a broader picture of the entire league. Here you can follow NFL as an entire community, where we'll break down stories with national significance and importantly, allow you to find like-minded, engaged sports fans who want to talk about the big stories in football every day. Community is at the heart of this, as we bring together our vast network of team sites and national coverage all into one place.
With the app you'll see fewer ads, which everyone loves, and it's also a snappier experience that makes swiping through all your favorite team sites a breeze. Easily one of my favorite features (and one I think you'll love too) are our "Game Chats." Here you'll automatically find live chats during every single game for the teams and leagues you follow, putting you in contact with every other fan in our network. We know open threads are a favorite part of everyone's team site, and they have been seamlessly integrated into the app to make it easy to jump in, fire off some comments, and get notified when another fan has replied to you. Celebrate together, cry together, experience together — that's the best part of sports.
For years the SB Nation motto has been "Come Fan With Us," and now with the SB Nation app that's going to be easier than ever.
#favorite

1 month ago
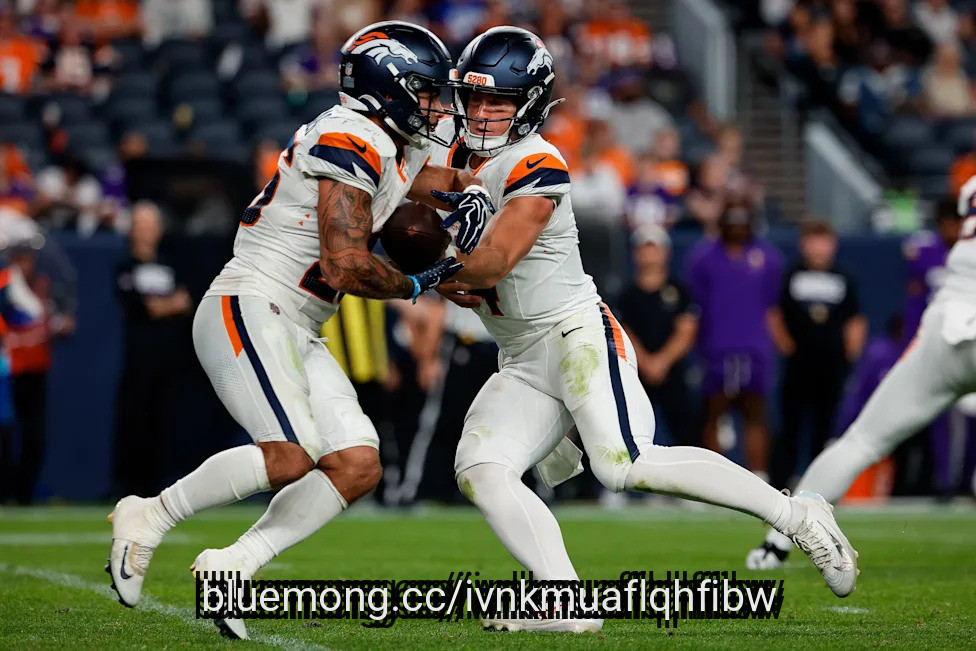
The Denver Broncos' initial 53-man roster came down to the wire, having cut down from 91 players to 53 on Sunday afternoon. There were several surprises from the initial roster, from cutting fan-favorite draft picks to veteran playmakers. We take a more in-depth look at the winners and losers from the first iteration of the 53-man roster.
Ehlinger made a push for the backup quarterback position against Jarrett Stidham this summer. Stidham ended up starting two of Denver's preseason contests, giving him a leg up on Ehlinger. What sealed Ehlinger's spot on the 53-man roster was his performance on Friday against the Minnesota Vikings. Ehlinger went 15-of-20 for 233 yards, three touchdowns and one interception. General manager George Paton said that the team "didn't want to lose him" after a very competitive summer.
McLaughlin was the "last decision we made," according to Paton in a post-cut presser. The writing began to be on the wall when the Broncos put McLaughlin on the practice squad in 2025. McLaughlin became expendable when the Broncos drafted Jonah Coleman in the third round of the 2026 NFL draft.
Conversely, Badie was named to the 53-man roster ahead of McLaughlin. Badie struggled in the preseason, but was one of those players who coach Sean Payton apparently couldn't live without. Badie saw action in 15 of Denver's games, so the trust is there. The fact that Badie made the roster in place of McLaughlin tells a story of the skill set difference between the players.
"Mr. Irrelevant" showed his potential throughout the preseason, making tackles and even forcing a fumble. One could have made a strong case for Murdock, who played his ***** off in camp and the preseason. He was calling plays for Vance Joseph's defense and was one of the biggest surprises of the entire cut process. Hopefully Murdock clears waivers and will be on the practice squad. He was a likeable player, with an even better story.
#made #players #paton
1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted Cintas Corporation (NASDAQ:CTAS). Cintas Corporation (NASDAQ:CTAS) engages in the provision of corporate identity uniforms and related business services. On August 21, 2026, Cintas Corporation (NASDAQ:CTAS) closed at $203.79 per share, reflecting a market capitalization of $81.55 billion. Cintas Corporation (NASDAQ:CTAS) posted a one‑month return of -3.41%, while its shares lost 3.81% over the past 52 weeks.
Aoris Investment Management stated the following regarding Cintas Corporation (NASDAQ:CTAS) in its Q2 2026 investor letter:
"Cintas Corporation (NASDAQ:CTAS) is America's largest uniform rental company. It earns 40% of its revenue from collecting, laundering and replacing uniforms for customers in industries such as hospitality, entertainment, manufacturing and healthcare. It also offers other facility services like the laundering of entrance mats, replenishment of restroom supplies, and monitoring of first aid kits and fire protection equipment.
Cintas has long used technology to improve service and efficiency, such as the SmartTruck system, which optimises its technicians' workday routes, and garment-tracking technology to reduce the likelihood of lost uniforms. AI should be another tool for Cintas to improve its logistics, service quality, sales effectiveness and cost control…" (Click here to read the full text)
#aoris #investor

1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted SAP SE (NYSE:SAP). Headquartered in Walldorf, Germany, SAP SE (NYSE:SAP) is a leading enterprise application and business solutions provider. On August 21, 2026, SAP SE (NYSE:SAP) closed at $218.68 per share, reflecting a market capitalization of $256.39 billion. SAP SE (NYSE:SAP) posted a one-month return of 27.88%, while its shares lost 19.09% over the past 52 weeks.
Aoris Investment Management stated the following regarding SAP SE (NYSE:SAP) in its Q2 2026 investor letter:
"SAP SE (NYSE:SAP) is the world's leading enterprise resource planning (ERP) software company. ERP systems run core business processes such as finance, human resources, manufacturing, supply chain management and customer relationship management. SAP is a core system of record for many of the world's largest organisations. Of the world's 100 largest organisations, 99 use SAP's solutions, and 80% of all the world's transactions touch an SAP system.
The value of SAP's systems should increase, because AI is only useful when it can access accurate data, business context and established workflows. AI is providing opportunities for SAP to layer on additional services which the company believes can add 20% or more to a customer's spending. Examples include its Business Data Cloud, which brings together SAP and non-SAP data for real-time ******* ysis, and its Joule AI agent, which can automate work with an understanding of customers' existing data structures and processes…" (Click here to read the full text)
#NYSE
1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted InterContinental Hotels Group PLC (NYSE:IHG). InterContinental Hotels Group PLC (NYSE:IHG) is a leading hospitality company owns, manages, franchises, and leases hotels globally. On August 21, 2026, InterContinental Hotels Group PLC (NYSE:IHG) closed at $159.91 per share, reflecting a market capitalization of $23.55 billion. InterContinental Hotels Group PLC (NYSE:IHG) posted a one‑month return of 0.25%, while its shares gained 32.18% over the past 52 weeks.
Aoris Investment Management stated the following regarding InterContinental Hotels Group PLC (NYSE:IHG) in its Q2 2026 investor letter:
"InterContinental Hotels Group PLC (NYSE:IHG) is a brand owner and franchisor of global hotel chains, including Holiday Inn, InterContinental and Crowne Plaza. Hotel owners pay IHG a franchise fee in exchange for access to its brands, loyalty program, and IT systems to help manage their properties, reservations and pricing. IHG franchisees earn better economics than independent hotels, which is why an increasing share of new and existing hotels are choosing to partner with IHG.
IHG's technology systems are a core advantage over smaller chains and independent hotels. AI can widen this gap through improvements in its search functions, booking process, customer service, pricing, marketing, and operational efficiency. For example, IHG is developing AI-powered conversational search to help guests book properties and receive more detailed information about its franchisees' rooms and services.…" (Click here to read the full text)
#NYSE

1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted RELX PLC (NYSE:RELX). RELX PLC (NYSE:RELX) is a British-based information ****** ytics and decision solutions provider for professional and business customers. On August 21, 2026, RELX PLC (NYSE:RELX) stock closed at $35.91 per share. One-month return of RELX PLC (NYSE:RELX) was 0.73%, and its shares lost 24.86% over the past 52 weeks. RELX PLC (NYSE:RELX) has a market capitalization of $62.03 billion.
Aoris Investment Management stated the following regarding RELX PLC (NYSE:RELX) in its Q2 2026 investor letter:
"RELX PLC (NYSE:RELX) provides data, ****** ytics and decision-making tools for professional users in the science, academia, legal, risk and insurance industries. One-third of its revenue comes from scientific content and research tools, one-third comes from risk management solutions like identity verification and anti-money laundering, 20% comes from content and tools for the legal industry, and 10% comes from running trade exhibitions.
RELX owns and curates large bodies of proprietary and authoritative content, which has become more valuable as the internet is largely exhausted as a training resource for AI models. Legal work is especially well-suited to generative AI because it's language-intensive, but also an area where accuracy matters. RELX's AI products help lawyers research, draft and conduct due diligence faster, while remaining anchored to trusted legal content. Just two and a half years after launch, around half of its legal customers have subscribed to its premium AI offering. AI is also making frau
1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On August 21, 2026, Visa Inc. (NYSE:V) closed at $371.04 per share, reflecting a market capitalization of $692.74 billion. Visa Inc. (NYSE:V) posted a one‑month return of 2.35%, while its shares gained 6.37% over the past 52 weeks.
Aoris Investment Management stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor letter:
"Visa Inc. (NYSE:V) is the world's largest payment network, enabling consumers and businesses to transact with over 130 million merchants globally in a convenient and secure way. It earns 70% of its revenue by charging fixed and percentage-based fees on transactions processed over its network. The other 30% comes from a range of payment-related services that help financial institutions and merchants to reduce fraud, improve back-office efficiency, increase sales and deepen customer loyalty.
If AI agents start making purchases on behalf of consumers and businesses, which is known as agentic commerce, then Visa's secure credentials, fraud controls, acceptance, dispute resolution and trusted network rules will become increasingly important. More digital commerce usually means more transactions, which would benefit Visa's transaction-based fees. Agentic commerce may also accelerate Visa's market share gains against domestic card networks like Eftpos, many of which still aren't accepted for onl

1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted InterContinental Hotels Group PLC (NYSE:IHG). InterContinental Hotels Group PLC (NYSE:IHG) is a leading hospitality company owns, manages, franchises, and leases hotels globally. On August 21, 2026, InterContinental Hotels Group PLC (NYSE:IHG) closed at $159.91 per share, reflecting a market capitalization of $23.55 billion. InterContinental Hotels Group PLC (NYSE:IHG) posted a one‑month return of 0.25%, while its shares gained 32.18% over the past 52 weeks.
Aoris Investment Management stated the following regarding InterContinental Hotels Group PLC (NYSE:IHG) in its Q2 2026 investor letter:
"InterContinental Hotels Group PLC (NYSE:IHG) is a brand owner and franchisor of global hotel chains, including Holiday Inn, InterContinental and Crowne Plaza. Hotel owners pay IHG a franchise fee in exchange for access to its brands, loyalty program, and IT systems to help manage their properties, reservations and pricing. IHG franchisees earn better economics than independent hotels, which is why an increasing share of new and existing hotels are choosing to partner with IHG.
IHG's technology systems are a core advantage over smaller chains and independent hotels. AI can widen this gap through improvements in its search functions, booking process, customer service, pricing, marketing, and operational efficiency. For example, IHG is developing AI-powered conversational search to help guests book properties and receive more detailed information about its franchisees' rooms and services.…" (Click here to read the full text)
#inves

1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On August 21, 2026, Visa Inc. (NYSE:V) closed at $371.04 per share, reflecting a market capitalization of $692.74 billion. Visa Inc. (NYSE:V) posted a one‑month return of 2.35%, while its shares gained 6.37% over the past 52 weeks.
Aoris Investment Management stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor letter:
"Visa Inc. (NYSE:V) is the world's largest payment network, enabling consumers and businesses to transact with over 130 million merchants globally in a convenient and secure way. It earns 70% of its revenue by charging fixed and percentage-based fees on transactions processed over its network. The other 30% comes from a range of payment-related services that help financial institutions and merchants to reduce fraud, improve back-office efficiency, increase sales and deepen customer loyalty.
If AI agents start making purchases on behalf of consumers and businesses, which is known as agentic commerce, then Visa's secure credentials, fraud controls, acceptance, dispute resolution and trusted network rules will become increasingly important. More digital commerce usually means more transactions, which would benefit Visa's transaction-based fees. Agentic commerce may also accelerate Visa's market share gains against domestic card networks like Eftpos, many of which still aren't accepted for onl

1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted RELX PLC (NYSE:RELX). RELX PLC (NYSE:RELX) is a British-based information ****** ytics and decision solutions provider for professional and business customers. On August 21, 2026, RELX PLC (NYSE:RELX) stock closed at $35.91 per share. One-month return of RELX PLC (NYSE:RELX) was 0.73%, and its shares lost 24.86% over the past 52 weeks. RELX PLC (NYSE:RELX) has a market capitalization of $62.03 billion.
Aoris Investment Management stated the following regarding RELX PLC (NYSE:RELX) in its Q2 2026 investor letter:
"RELX PLC (NYSE:RELX) provides data, ****** ytics and decision-making tools for professional users in the science, academia, legal, risk and insurance industries. One-third of its revenue comes from scientific content and research tools, one-third comes from risk management solutions like identity verification and anti-money laundering, 20% comes from content and tools for the legal industry, and 10% comes from running trade exhibitions.
RELX owns and curates large bodies of proprietary and authoritative content, which has become more valuable as the internet is largely exhausted as a training resource for AI models. Legal work is especially well-suited to generative AI because it's language-intensive, but also an area where accuracy matters. RELX's AI products help lawyers research, draft and conduct due diligence faster, while remaining anchored to trusted legal content. Just two and a half years after launch, around half of its legal customers have subscribed to its premium AI offering. AI is also making frau


1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted SAP SE (NYSE:SAP). Headquartered in Walldorf, Germany, SAP SE (NYSE:SAP) is a leading enterprise application and business solutions provider. On August 21, 2026, SAP SE (NYSE:SAP) closed at $218.68 per share, reflecting a market capitalization of $256.39 billion. SAP SE (NYSE:SAP) posted a one-month return of 27.88%, while its shares lost 19.09% over the past 52 weeks.
Aoris Investment Management stated the following regarding SAP SE (NYSE:SAP) in its Q2 2026 investor letter:
"SAP SE (NYSE:SAP) is the world's leading enterprise resource planning (ERP) software company. ERP systems run core business processes such as finance, human resources, manufacturing, supply chain management and customer relationship management. SAP is a core system of record for many of the world's largest organisations. Of the world's 100 largest organisations, 99 use SAP's solutions, and 80% of all the world's transactions touch an SAP system.
The value of SAP's systems should increase, because AI is only useful when it can access accurate data, business context and established workflows. AI is providing opportunities for SAP to layer on additional services which the company believes can add 20% or more to a customer's spending. Examples include its Business Data Cloud, which brings together SAP and non-SAP data for real-time ******* ysis, and its Joule AI agent, which can automate work with an understanding of customers' existing data structures and processes…" (Click here to read the full text)
#aoris #investor #return

1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted Cintas Corporation (NASDAQ:CTAS). Cintas Corporation (NASDAQ:CTAS) engages in the provision of corporate identity uniforms and related business services. On August 21, 2026, Cintas Corporation (NASDAQ:CTAS) closed at $203.79 per share, reflecting a market capitalization of $81.55 billion. Cintas Corporation (NASDAQ:CTAS) posted a one‑month return of -3.41%, while its shares lost 3.81% over the past 52 weeks.
Aoris Investment Management stated the following regarding Cintas Corporation (NASDAQ:CTAS) in its Q2 2026 investor letter:
"Cintas Corporation (NASDAQ:CTAS) is America's largest uniform rental company. It earns 40% of its revenue from collecting, laundering and replacing uniforms for customers in industries such as hospitality, entertainment, manufacturing and healthcare. It also offers other facility services like the laundering of entrance mats, replenishment of restroom supplies, and monitoring of first aid kits and fire protection equipment.
Cintas has long used technology to improve service and efficiency, such as the SmartTruck system, which optimises its technicians' workday routes, and garment-tracking technology to reduce the likelihood of lost uniforms. AI should be another tool for Cintas to improve its logistics, service quality, sales effectiveness and cost control…" (Click here to read the full text)
#letter

1 month ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted W.W. Grainger, Inc. (NYSE:GWW). W.W. Grainger, Inc. (NYSE:GWW) is leading supplier of maintenance, repair, and operating products and services, serving customers across industries. On August 21, 2026, W.W. Grainger, Inc. (NYSE:GWW) closed at $1,312.24 per share, reflecting a market capitalization of $61.81 billion. W.W. Grainger, Inc. (NYSE:GWW) posted a one‑month return of -6.20%, while its shares gained 29.48% over the past 52 weeks.
Aoris Investment Management stated the following regarding W.W. Grainger, Inc. (NYSE:GWW) in its Q2 2026 investor letter:
"W.W. Grainger, Inc. (NYSE:GWW) is a leading distributor of maintenance, repair and operating (MRO) supplies in North America and ******* an. Around 80% of its revenue comes from high-touch service for large and complex organisations, while the remainder comes from an online-only offering for smaller purchases.
Grainger is using AI to improve the search functionality and depth of product information on its e-commerce platform, helping customers find the right part faster and with more certainty. Internally it's using AI to improve the speed and resolution of customer service queries and the effectiveness of its salespeople.…" (Click here to read the full text)
#NYSE #aoris #letter #management
2 months ago
Is Sandisk (NASDAQ: SNDK) stock overbought... and overpriced?
Worries over a Morgan Stanley report yesterday, which compared the percentage of the S&P 500 index that is Sandisk stock versus the percentage Sandisk occupies in the portfolios of large institutional investors -- and concluded Sandisk is "over-owned" -- spooked investors yesterday. By close of trading, Sandisk stock had fallen 9%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
As we approach the mid-day mark Wednesday, Sandisk stock continues to drift lower -- down 2.2% as of 11:30 a.m. ET.
Morgan Stanley's number-crunchers did what they do, calculating percentages and concluding that certain tech stocks, including Apple, Microsoft, and Amazon, are all "under-owned" (because institutions don't own as much of them as S&P does). Other stocks, and Sandisk in particular, are conversely "over-owned" -- because they're more popular on Wall Street.
#NVIDIA
2 months ago
Is Sandisk (NASDAQ: SNDK) stock overbought... and overpriced?
Worries over a Morgan Stanley report yesterday, which compared the percentage of the S&P 500 index that is Sandisk stock versus the percentage Sandisk occupies in the portfolios of large institutional investors -- and concluded Sandisk is "over-owned" -- spooked investors yesterday. By close of trading, Sandisk stock had fallen 9%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
As we approach the mid-day mark Wednesday, Sandisk stock continues to drift lower -- down 2.2% as of 11:30 a.m. ET.
Morgan Stanley's number-crunchers did what they do, calculating percentages and concluding that certain tech stocks, including Apple, Microsoft, and Amazon, are all "under-owned" (because institutions don't own as much of them as S&P does). Other stocks, and Sandisk in particular, are conversely "over-owned" -- because they're more popular on Wall Street.
#sandisk #NVIDIA #signal #flashing

2 months ago
The San Francisco 49ers' short-term future doesn't look great, according to ESPN. An expert panel consisting of ****** ysts Louis Riddick, Aaron Schatz, Ben Solak, and Seth Walder ranked the 49ers No. 14 in ESPN's Future Power Rankings.
ESPN's methodology evaluates how well all 32 NFL franchises are set up for sustained success over a three-year window spanning the 2027 through 2029 seasons. The panel rated each team's quarterback situation, non-QB roster makeup, front office, and coaching staff on a 1–100 scale. Those grades were then calculated into a weighted overall score: roster makeup (30%), coaching staff (25%), front office (25%), and quarterback (20%).
The 49ers earned an overall score of 82.4, placing them behind NFC West rivals Seattle (No. 1, 88.7) and Los Angeles (No. 5, 85.3). San Francisco's category breakdown features elite respect for their coaching staff (93.5 score, second in NFL) and a top-10 quarterback rating (87.0 score, 10th in NFL). However, lower marks for their non-QB roster (77.0 score, 16th in NFL) and front office (74.0 score, 23rd in NFL) pulled down their overall grade.
The primary reason for optimism centers around head coach Kyle Shanahan's play-calling brilliance and a young defense. Solak noted that as long as Shanahan remains at the helm printing high-caliber offensive schemes, San Francisco will stay dangerous regardless of offensive line inconsistencies or playmaker injuries.
Conversely, Riddick highlighted roster age and durability as major causes for concern. Crucial veterans like Trent Williams (38), Kyle Juszczyk (35), Mike Evans (32), and George Kittle (32, returning from an Achilles tear) face steep longevity questions. Paired with a history of significant annual injury bug issues, the 49ers will lean heavily on Shanahan and his staff to continuously develop unheralded talent to remain in contention over the next three-year cycle.
#overall

2 months ago
The Vanderbilt Commodores started the 2026 season with a win that left a "bitter" taste in Coach Darren Ambrose's mouth according to his post-game interview. He used the words sluggish, lethargic, and choreographed to describe the performance. Coach Ambrose harped on being proud and happy with the victory, but he kept focusing on different flaws in the performance. If you saw my comments during and after the match, I am proud to say Coach and I are on the same wavelength.
The pushback that I got was that it was just game 1. It was. I am not panicking. My predictions for the season have not changed. My thoughts about the talent on the team have not changed, except for some concern about one particular position. Armas in goal was not very convincing. Again, it was match 1. I am not going to react too strongly yet.
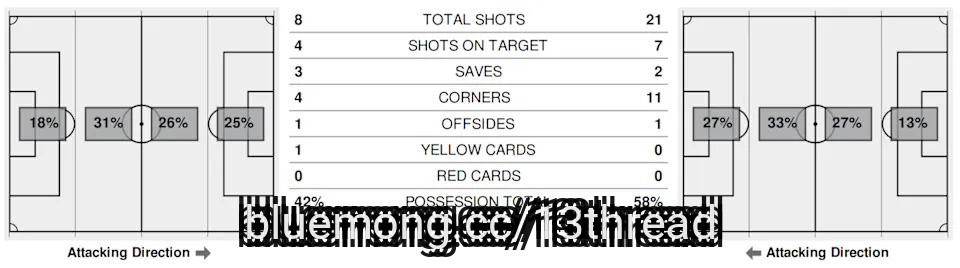
The Commodores had plenty of possession and tons of shot attempts. They spent more than a third of the match (35%) in possession in the attacking half. Attempting 21 shots but with only 7 on target is where the sharpness and intensity that Ambrose found lacking came into play. They generated 11 corners yet did not score off one. Conversely, SMU was able to turn 21% attacking possession and 8 shot attempts into 4 shots on target and 3 goals. Granted, 1 goal for the Mustangs was a cross that deflected off Grace Freeman's leg in a truly unfortunate moment where Armas was diving out to claim the cross.
The number of players used is really intriguing to me. Typically, Coach Ambrose has gone deep into the bench early in seasons. It normally is paired down to 14 to 16 by the time SEC play starts, but early season matches often see 20 or more players. The tightness of the match and dissatisfaction with the performance may have been why the starters played more as they tried to work out the kinks.
Courtney Jones, Olivia Stafford, and Sydney Watts all have 4 shot attempts and a goal is not particularly surprising. I would have expected Pentz to get off more shots, but she had the early goal on her only attempt. I do not think Fullerton at CAM and Pentz at striker beside Watts is the best lineup for this squad based on natural inclinations of the players and how that effects ******* ing.
#goal #performance #possession

2 months ago
The opening week of the NFL preseason comes to a close on Saturday, with seven games punctuating the first sweep of exhibitions.
There are a bevy of storylines to follow, perhaps most notably the Cleveland Browns' position battle under center that will take center stage in Chicago, where the Bears conversely will be resting their QB1, Caleb Williams.
Play Yahoo's new College Fantasy Football game: Create or join a league now!
Here's a look at who's in and who's out for the first portion of Saturday's NFL preseason schedule:
Panthers: Starters, including QB Bryce Young, WR Tetairoa McMillan, LB Devin Lloyd, LB Jaelan Phillips
#center #Browns #bears

2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
U.S. stock futures were mixed heading into Friday morning as Wall Street digested an impending batch of retail and consumer data against a backdrop of escalating tensions in the Middle East.
The Polymarket (CRYPTO: POL) crowd is leaning bullish for the Aug. 14 trading session. The "S&P 500 (SPX) Up or Down on August 14?" contract currently reflects a 57% chance of a higher open.
Traders are balancing domestic economic indicators against intense geopolitical frictions and yield pressures:
Mixed Index Futures: Equity futures are pointing to a mixed open. S&P 500 futures ticked up 0.01%, and Dow Jones futures advanced 0.06%. Conversely, Nasdaq 100 futures dipped 0.15% and Russell 2000 futures dropped 0.08%.
#futures #Friday


2 months ago
Recent seasons have brought notable highs and lows for Lazio, which become clearer when reviewing more than just scores or headlines. Fans and football betting enthusiasts often study long-term trends, such as league position consistency, scoring stats, and defensive markers, to understand where the club excels or faces challenges. This article summarizes those patterns and fluctuations, drawing out areas of strength and inconsistency.
Lazio's final league positions over recent seasons display a mix of promising campaigns and tough stretches. Reviewing points totals and table standing each year marks out when the team achieved stability or experienced setbacks. Seasons with a stable squad typically brought better finishes, while years with major management changes or player turnover saw drops in points and position.
A settled core often correlated with higher league placements, while instability in the roster or tactics could result in a slide down the table. These shifts indicate the importance of squad cohesion and leadership continuity for Lazio's consistency.
The gap between Lazio's best and worst finishes in recent years demonstrates how volatile their campaigns can be. In their stronger seasons, the team managed to secure European qualification spots, sometimes even challenging for Champions League positions with point totals exceeding 70. Conversely, mid-table finishes around 6th to 8th place reflected campaigns where early promise faded due to poor form in the second half of the season. ****** yzing the points-per-game average across different phases of each campaign reveals that Lazio often starts strongly but struggles to maintain momentum after the winter break, suggesting potential issues with squad depth or physical conditioning during the demanding latter stages of the season.
Lazio's effectiveness in attack varies between seasons. Their goals per game ratio reveals when the team was most capable of breaking down defences, while instances of multi-goal matches point to notable offensive spells. However, some campaigns featured high shot counts but low conversion rates, underlining occasional struggles to turn opportunities into goals.
#seasons #league #often

2 months ago
With the first week of NFL preseason kicking off this week, Nate Davis of USA TODAY Sports has released his updated NFL power rankings.
Davis is giving the Denver Broncos a lot of respect, ranking them third overall, only trailing the Los Angeles Rams (No. 1) and Seattle Seahawks (No. 2). By his estimation, Denver's the team to beat in the AFC this fall.
"You can make a legitimate case that at least half of the AFC's teams have a bona fide shot to reach the Super Bowl − which, conversely, also suggests none of them exactly seem like heavyweights well positioned to compete with the NFC's elite," Davis wrote for USA TODAY. "But the Broncos were probably one key injury away from going to Super Bowl 60 and might be even better in Year 3 of the Sean Payton-Bo Nix era, the latter healthy once again.
Elsewhere in the AFC West, the Kansas City Chiefs are ranked No. 14, the Los Angeles Chargers are ranked No. 16 and the Las Vegas Raiders are ranked No. 28. To view the complete power rankings, visit USATODAY.com.
Social: Follow Broncos Wire on Facebook and Twitter/X! Did you know: These 25 celebrities are Broncos fans.
#today

2 months ago
Meta Platforms (META) continues to grow rapidly, and evidence suggests that artificial intelligence (AI) is making its ads more effective. Still, the company's financial results appear unlikely to get a huge boost from AI in the bigger picture, while Meta also does not appear to have many imminent positive catalysts on the way. Meta's core ad business is also quite vulnerable to a potential drop in consumer spending, which could eventually be triggered by elevated oil prices and tariffs.
Conversely, Amazon (AMZN) is benefiting tremendously from the AI boom and appears likely to continue to do so. Amazon has multiple, needle-moving businesses working for it as well, making the case for AMZN stock even stronger.
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and ****** eX Earnings on Tap
#amzn #continues #boost #still

2 months ago
Lenni Hameenaho had quite the season for his first campaign in North America in 2025-26. Starting the season in the AHL with the Utica Comets, Hameenaho initially got off to a slow start with no points in his first nine games. He would come on strong after an that initial adjustment period to post 22 points in his next 25 games, earning himself a spot in the NHL for much of the remainder of the Devils' season. His 33 NHL appearances would see him post just eight points (two goals and six ***** ists) while mostly being used in the Bottom Six. The Devils would send Lenni back down for the final push for the Comets to make the postseason; while they came up just short, Hameenaho contibuted four points in those three games.
2025-26 was a good start for a 21 year old rookie; while you might be disappointed in his NHL point totals, keep in mind his deployment, He was typically playing on the fourth line with little to no time on special teams. He wasn't consistently put with teammates who could help him generate offense. He did make a number of mistakes as young players often do, but by the end of the season I would argue Hameenaho was a more complete player in game 33 in New Jersey than he was in game one. This upcoming season will be a good opportunity for him to take another step forward. The only question has to be where in the organization will that be?
For 2026-27, the Devils have added to their forward depth, so much so that if Hameenaho were to be on the NHL roster alongside everyone else listed on PuckPedia, he would be one of 14 forwards. While the Devils carried 14 forwards for a portion of last season, I don't think the argument could be made that all of them belonged at the NHL level. This season, while you could argue their role and deployment, each of the other 13 forwards is at least an NHL player. The Devils are trying to ensure future success, but also want to win now; if there's players better than Lenni, that means 12 other Devils will be on the ice nightly, and at the same time you don't want one of your better prospects sitting in the press box on a nightly or almost nightly basis. So is Hameenaho destined for a full season with Utica?
I think a lot of it is going to depend on how much he's learned from last season and what he has done this summer. If Lenni spent the offseason looking over game footage, furthering his understanding of Sheldon Keefe's system, adding muscle to his frame and continuing to improve his skills, then there's a chance he could leap over a number of the lower tier Devils forwards and work his way onto the opening night roster. If that were the case, then the Devils would probably have to send a goaltender or fringe forward down, but hey, would the Devils really be that much worse without one of Nico Daws/David Rittich or Jesper Boqvist/Nick Bjugstad?
Conversely, Hameenaho is still a very young player, as he will just be turning 22 shortly into the upcoming season. It wouldn't be a bad thing if the Devi

2 months ago
Pfizer has upgraded the bottom-end of its full-year (FY) revenue outlook by $500m as performance from the drugmaker's lead products more than compensated for weaker Covid-19-related sales.
Pfizer now expects 2026 revenue to land between $60.5bn and $62.5bn, up from the $59.5bn to $62.5bn range it previously forecast.
According to the big pharma company, the revised outlook reflects a $1.5bn better-than-expected performance from its non-Covid products. Sales for Covid-19 products, which include antiviral Paxlovid and mRNA vaccine Comirnaty, are conversely expected to bring in $1bn less. The former's sales were down 95% in Q2, while the latter dropped 34%.
Pfizer emerged as a pharmaceutical powerhouse during the pandemic, but lower infection rates and narrower use cases mean its Covid-19 brands are impacting the company's bottom line.
Pfizer still recorded revenues of $15bn in Q2, up 3% from the same quarter in 2025, meaning its non-Covid products more than offset headwinds. This figure beat consensus estimates, as per Citi ******* ysts.
#covid #sales #bottom #performance


2 months ago
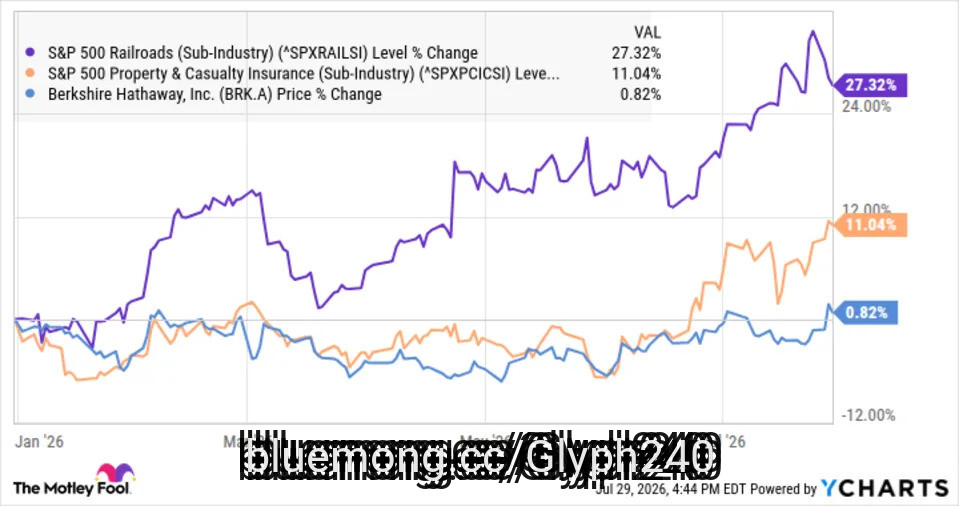
Earlier this year, CEO Greg Abel announced that Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) resumed its share repurchase program in March. But much to investors' disappointment, the company's first-quarter earnings report revealed just $235 million in total share repurchases that month. That's practically unnoticeable for a company with a market cap of more than $1 trillion.
It looks like Abel stepped up the repurchase activity in the second quarter. A Barron's **** ysis of Warren Buffett's SEC filings in July indicates Berkshire Hathaway's Class A share count declined by around 11,000 between April 14 and July 14. Due to rounding and estimating the average share price of repurchases, the actual amount spent buying back shares won't be known until Berkshire releases its Q2 earnings results. However, Barron's suggests the amount could be as high as $11 billion.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That's a bullish sign for shareholders.
When Berkshire Hathaway buys back its own shares, it's usually a good sign that management believes its shares are undervalued. Chairman Warren Buffett has decried companies that repurchase shares without regard for their stock's price or value. Conversely, Berkshire's share repurchase authorization permits repurchases only when "Berkshire's Chief Executive Officer, after consultation with the Chairman of the Board, believes that the repurchase price is below Berkshire's intrinsic value, conservatively determined."
#berkshire


2 months ago
As of 11:38 AM ET, the Dow Jones Industrial Average (DJINDICES:^DJI) is up 0.13% to 52,017.19, while the S&P 500 (SNPINDEX:^GSPC) is down 0.33% to 7,387.76, and the Nasdaq Composite (NASDAQINDEX:^IXIC) has slipped 0.44% to 24,840.43 as tech pressure offsets optimism from cooling geopolitical tensions.
Gold is up 0.45% to $4,074.30, and the 10-Year Treasury yield is down 0.03% to 4.65%. Communications and consumer defensive stocks are this morning's top-performing sectors while technology and energy sectors are in the red.
RTX Corp climbed 2.61% to $218.28 on strong Q2 earnings. SAP surged 7.4% to $171.79, extending last week's gains after the software company beat earnings expectations. Conversely, Nvidia is trading lower amid concerns about Chinese competition. Reddit is up 6.7% to 171.79 on optimism about its upcoming earnings.
Oil prices fell this morning on news of a pause in strikes between the U.S. and Iran. WTI crude oil fell almost 7% to $83.15 a barrel, boosting market sentiment and lifting the Dow slightly. However, investors are braced for further volatility and will be watching the Federal Reserve meeting this week. The Fed is widely expected to leave rates unchanged in July, but inflationary pressures caused by ongoing tensions in the Middle East and high spending by tech companies could prompt it to raise rates before the end of the year.
On the other side, renewed artificial intelligence (AI) valuation concerns weighed on markets. This week will bring earnings from Microsoft, Meta Platforms, Apple, and Amazon, and investors will be paying close attention to capital expenditure plans. The high concentration in the Nasdaq and the S&P 500 means any drop in their share prices will have an outsized impact on these major indexes.
#earnings

2 months ago
The Diamondbacks dropped the opener of The Most Important Series of the Season™, losing 3-2 in ten innings to the Pirates. Merrill Kelly pitched well, and Max Kepler gave Arizona a 2-0 lead. But a throwing error by Kelly allowed a key Pittsburgh run, and Juan Morillo then gave up the tying score, which pushed the contest into extras. The Diamondbacks were unable to take advantage of a major Pirates gaffe, stranding the Manfred Man. A ball which was clanked off the glove of Ildemaro Vargas let the home team walk off, but the key stat tonight was the D-backs going just 2-for-14 with runners in scoring position. And one of those hits didn't score a run either.
But to focus on the positives. Merrill Kelly continued his resurgence. He finished June with an ERA above six (6.11, to be precise). But since the calendar turned to July, he has been much improved. Tonight, he allowed only an unearned run over 5.2 innings, on four hits – all of which were singles. He walked one and struck out six. [That is still an area of concern. Through nineteen starts last year, he had 7 or more K's eight times: he hasn't gone past six at all this year] He did hit a batter, Pirates' rookie Esmerlyn Valdez wearing a pitch around the wrist area, and having to leave the game in obvious discomfort. Hopefully, there's no serious damage there.
Through five innings, both Kelley and his opposite number – confusingly, called M. Keller – were basically cruising. Each side has managed to advance only one runner past first-base to that point. In the top of the second, Max Kepler led off with a single, advanced to third on a pair of outs, but was stranded there when Ildemaro Vargas grounded out. For the Pirates, they got a two-out single in the bottom of the fifth, and the runner stole second before being left there. Kelly even got a pick-off, ending the fourth by nailing the pinch-runner who had come in to replace Valdez. Rather embarrassing for them, I imagine.
Both pitchers were also being highly efficient. Through five innings, Keller had needed just 63 pitches, and Kelly less than a handful more at 67. I particularly enjoyed this strikeout by Kelly which ended the fifth inning. None of the six pitches in the zone, and zero contact by the batter on his three swings. However, my hopes of a quick recap foundered thereafter, as neither starting pitcher would make it through the sixth. Corbin Carroll and Geraldo Perdomo singled to lead off the top of the frame, though Gabriel Moreno would strike out looking, on a master-class of ABS by the Pirates catcher, which reversed two ******* to strikes, by very narrow margins.
[Conversely, Moreno was 0-for-2 in his challenges tonight. Though it is worth noting that the team's overall challenge rate when on defense is still 66.7%, significantly better than the MLB average of 58.1%.]
#innings #tonight #runner


3 months ago
The NFL draft is the lifeblood of your football team. Selecting and developing young talent is the number one job of an NFL general manager.
Adam Peters has been criticized a bit over his first two years in Washington for some of his higher draft picks. Some of those guys were expected to have a MUCH bigger impact on the team than they have had to date.
Conversely, some players who were picked a bit later shined early on. While we can make our voices heard in displeasure about some of Peter’s top 100 picks not preforming, we must be just as complementary of some guys who may have been overlooked in the draft, but came to Washington and did well. And, yes, I’m taking about BILL!
Fans want to see players perform well. Some players take more time than others to develop, but the key to success is whether said player eventually gets to that “expected” level.
With that said, below are my offensive and defensive breakout candidates for the upcoming season.
#picks #expected