26 days ago
Jamie Dimon has spent much of this year warning that the bond market is a problem waiting to happen. On April 28, at a conference hosted by Norway's sovereign wealth fund, the JPMorgan Chase CEO said there would be "some kind of bond crisis," according to TheStreet.
The debt he had in mind was mostly owed by governments. But Dimon has long argued that the pain lands somewhere else.
In a 2025 Fox Business interview, he said bond market volatility hurts the people raising money, small businesses included. He admitted he could not tell whether trouble was six months or six years away. This time, he named the next group in line.
Also read: Scott Bessent just made a bold move on the bond market
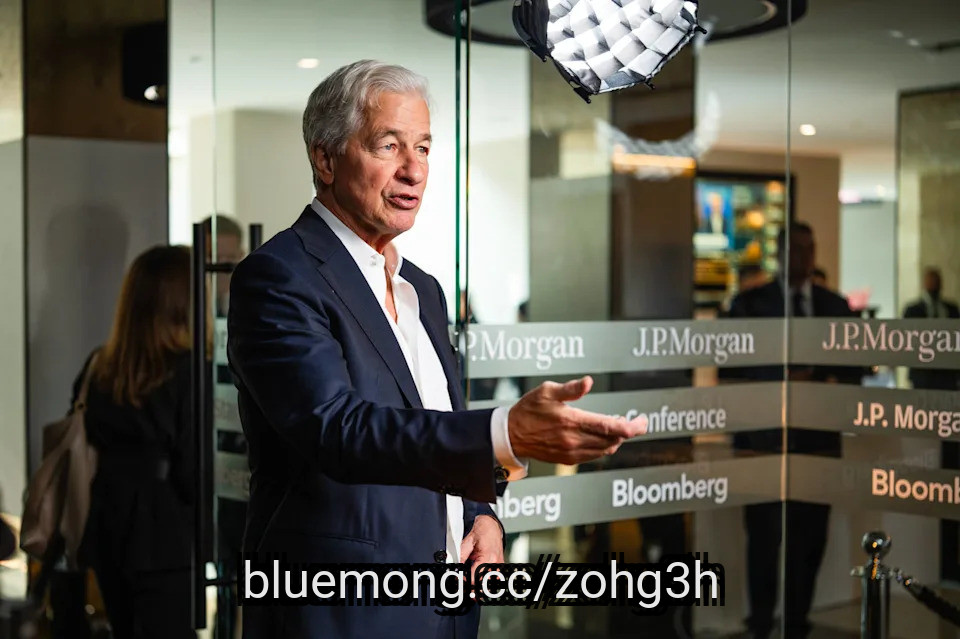
Speaking on the sidelines of a JPMorgan event in London on Oct. 6, Dimon said the worldwide scramble for capital could begin to squeeze corporate borrowers, Bloomberg reported. Investors will keep asking for more, he said. At some point, that feeds into corporate debt and credit spreads.
#debt
The debt he had in mind was mostly owed by governments. But Dimon has long argued that the pain lands somewhere else.
In a 2025 Fox Business interview, he said bond market volatility hurts the people raising money, small businesses included. He admitted he could not tell whether trouble was six months or six years away. This time, he named the next group in line.
Also read: Scott Bessent just made a bold move on the bond market
Speaking on the sidelines of a JPMorgan event in London on Oct. 6, Dimon said the worldwide scramble for capital could begin to squeeze corporate borrowers, Bloomberg reported. Investors will keep asking for more, he said. At some point, that feeds into corporate debt and credit spreads.
#debt

27 days ago
JPMorgan Chase (JPM) CEO Jamie Dimon sharpened his warning about the risks of a global bond sell-off on Tuesday, saying the world's massive competition for capital could begin squeezing corporate borrowers.
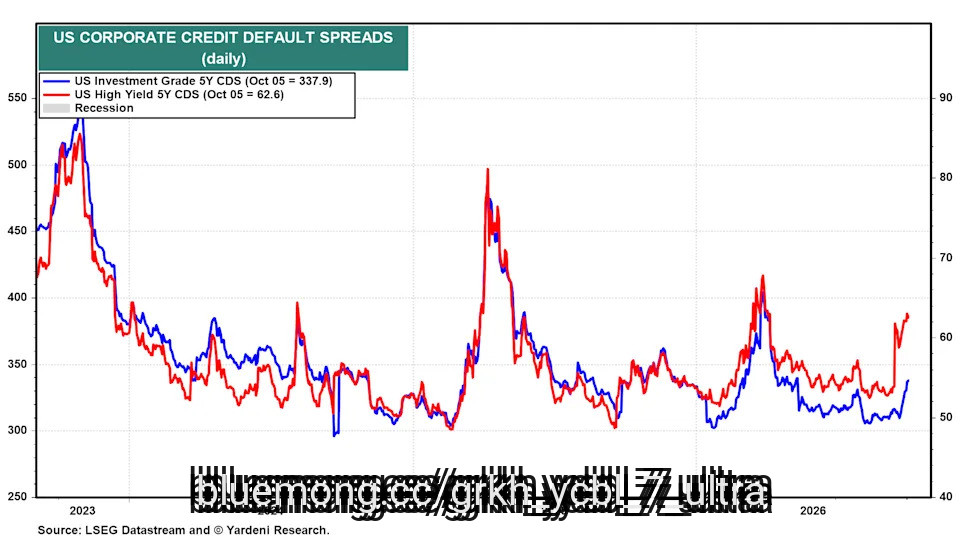
Dimon warned that the combination of rising government borrowing costs and spending on the AI boom could spill into corporate credit markets, pushing up the costs for companies to refinance or raise new debt.
"There will be a point where the market will ask for more and more and more, and yeah, at one point that'll feed into corporate debt, corporate credit spreads, and things like that, which is how it normally happens," Dimon said in a Bloomberg interview on the sidelines of a JPMorgan event in London.
"The best thing to do with any of these things is deal with it before it becomes a crisis. If it becomes a crisis, we will deal with it. It just will be in a much less pleasant way," he added.
The warning comes as a global rout in bonds has pushed longer-term borrowing costs sharply higher in recent weeks, with the benchmark US 10-year Treasury yield recently surpassing heights not seen since 2002.
#credit
Dimon warned that the combination of rising government borrowing costs and spending on the AI boom could spill into corporate credit markets, pushing up the costs for companies to refinance or raise new debt.
"There will be a point where the market will ask for more and more and more, and yeah, at one point that'll feed into corporate debt, corporate credit spreads, and things like that, which is how it normally happens," Dimon said in a Bloomberg interview on the sidelines of a JPMorgan event in London.
"The best thing to do with any of these things is deal with it before it becomes a crisis. If it becomes a crisis, we will deal with it. It just will be in a much less pleasant way," he added.
The warning comes as a global rout in bonds has pushed longer-term borrowing costs sharply higher in recent weeks, with the benchmark US 10-year Treasury yield recently surpassing heights not seen since 2002.
#credit

1 month ago
Around 57% of households have some type of unsecured debt, including credit cards and personal loans. This debt can be a financial burden because borrowers must make monthly payments and cover interest.
Once you've taken on debt, you're committed to paying it back. Otherwise, you could hurt your credit score and face collection activity. But what happens if the company you borrowed from runs into financial trouble and goes out of business? Does that mean your debt disappears?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#around #once #otherwise
Once you've taken on debt, you're committed to paying it back. Otherwise, you could hurt your credit score and face collection activity. But what happens if the company you borrowed from runs into financial trouble and goes out of business? Does that mean your debt disappears?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#around #once #otherwise


1 month ago
Around 57% of households have some type of unsecured debt, including credit cards and personal loans. This debt can be a financial burden because borrowers must make monthly payments and cover interest.
Once you've taken on debt, you're committed to paying it back. Otherwise, you could hurt your credit score and face collection activity. But what happens if the company you borrowed from runs into financial trouble and goes out of business? Does that mean your debt disappears?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#around
Once you've taken on debt, you're committed to paying it back. Otherwise, you could hurt your credit score and face collection activity. But what happens if the company you borrowed from runs into financial trouble and goes out of business? Does that mean your debt disappears?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#around


1 month ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
A mind is a terrible thing to waste, but college is awfully expensive.
Depending on where someone goes to school, they can be left with a lot of debt — an albatross that can hang around their neck for decades. Among 401(k) plan participants in their 40s, those with student loan debt had median retirement account balances roughly 45% lower than those without, according to a new report from the Employee Benefit Research Institute.
The best option is to figure out scholarships, financial aid, debt timelines and what school makes financial sense before going to college. But that's not reality for many clients, leaving advisors to help fit student debt into a financial plan that balances both loans and savings. "The biggest mistake I see is treating student loans as an all-or-nothing problem," said Corinna Rose, a CFP with Bell Investment Advisors. "Many borrowers think they need to eliminate every dollar of debt before they can start investing."
Sign up for The Daily Upside at no cost for premium ******* ysis on all your favorite stocks.
#student #sign #many
A mind is a terrible thing to waste, but college is awfully expensive.
Depending on where someone goes to school, they can be left with a lot of debt — an albatross that can hang around their neck for decades. Among 401(k) plan participants in their 40s, those with student loan debt had median retirement account balances roughly 45% lower than those without, according to a new report from the Employee Benefit Research Institute.
The best option is to figure out scholarships, financial aid, debt timelines and what school makes financial sense before going to college. But that's not reality for many clients, leaving advisors to help fit student debt into a financial plan that balances both loans and savings. "The biggest mistake I see is treating student loans as an all-or-nothing problem," said Corinna Rose, a CFP with Bell Investment Advisors. "Many borrowers think they need to eliminate every dollar of debt before they can start investing."
Sign up for The Daily Upside at no cost for premium ******* ysis on all your favorite stocks.
#student #sign #many

1 month ago
Federal student loans are, for many students, the best option for covering postsecondary education and related expenses.
With fixed interest rates, clear grace periods and forbearance options, federal loans offer predictable repayment schedules.
Some borrowers may even qualify for loan forgiveness under Public Service Loan Forgiveness, income-driven repayment plans or the Teacher Loan Forgiveness program.
Though federal student loans have benefits compared to private loans, consider any borrowing carefully before committing to a debt.
If you don't have cash on hand to completely cover the cost of attendance for college — around $38,000 per year on average, according to the Education Data Initiative — you're not alone. More than 42 million borrowers have federal student loan debt.
#loan #debt
With fixed interest rates, clear grace periods and forbearance options, federal loans offer predictable repayment schedules.
Some borrowers may even qualify for loan forgiveness under Public Service Loan Forgiveness, income-driven repayment plans or the Teacher Loan Forgiveness program.
Though federal student loans have benefits compared to private loans, consider any borrowing carefully before committing to a debt.
If you don't have cash on hand to completely cover the cost of attendance for college — around $38,000 per year on average, according to the Education Data Initiative — you're not alone. More than 42 million borrowers have federal student loan debt.
#loan #debt

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#federal #rates #loans
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#federal #rates #loans

2 months ago
While the average personal loan interest rate is 12.44%, borrowers with excellent credit may have access to rates as low as 5.96%.
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.64% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting just below 6%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#average #rates #lowest #borrowing
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.64% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting just below 6%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#average #rates #lowest #borrowing
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#Consumer
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#Consumer


2 months ago
As high mortgage rates and elevated home prices continue to crimp housing affordability, Federal Housing Finance Agency's Bill Pulte is seeking cuts to a common "hidden cost" of homeownership.
Targeting private mortgage insurance, which around 800,000 borrowers used to buy homes last year, Pulte is aligning policies between mortgage giants Fannie Mae and Freddie Mac to allow loan servicers to proactively call borrowers when they're eligible to drop their mortgage insurance. Previously, only Freddie Mac allowed servicers to do so.
"If your Home is worth more, or you have paid the loan down far enough, you should be able to drop EXTRA Mortgage Insurance," Pulte wrote in a post on X on Tuesday.
"Right now Fannie Mae will not let your loan company call and tell you that you may qualify because your home has gone up in value! You have to know to ask. Freddie Mac will let them call. That is crazy. We are fixing that. Fannie Mae will follow Freddie's rule: if you may qualify to drop unnecessary extra insurance because your home has gained value, they can contact you and walk you through how to cancel your PMI. You can stop paying for coverage you do not need and keep the money."
Read more: What is private mortgage insurance (PMI)? Definition, cost, and how to avoid it
#freddie #loan #call
Targeting private mortgage insurance, which around 800,000 borrowers used to buy homes last year, Pulte is aligning policies between mortgage giants Fannie Mae and Freddie Mac to allow loan servicers to proactively call borrowers when they're eligible to drop their mortgage insurance. Previously, only Freddie Mac allowed servicers to do so.
"If your Home is worth more, or you have paid the loan down far enough, you should be able to drop EXTRA Mortgage Insurance," Pulte wrote in a post on X on Tuesday.
"Right now Fannie Mae will not let your loan company call and tell you that you may qualify because your home has gone up in value! You have to know to ask. Freddie Mac will let them call. That is crazy. We are fixing that. Fannie Mae will follow Freddie's rule: if you may qualify to drop unnecessary extra insurance because your home has gained value, they can contact you and walk you through how to cancel your PMI. You can stop paying for coverage you do not need and keep the money."
Read more: What is private mortgage insurance (PMI)? Definition, cost, and how to avoid it
#freddie #loan #call


2 months ago
An AI approval in minutes means nothing if you retire before closing. Lenders must re-verify employment within 10 business days of the note date.
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval


2 months ago
Carlyle Global Head of Liquid Credit Lauren Basmadjian spoke with Bloomberg's Dani Burger from the sidelines of Carlyle's Global Investor Conference and talked about the health of corporate borrowers, the loan market moving toward equilibrium, data centers as an emerging source of loan supply, and more.
#liquid #credit
#liquid #credit


2 months ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ******* ysis delivered straight to their inbox with the free CRE Daily newsletter.
A $420 million CMBS loan backed by the 893,000-square-foot office tower at 51 West 52nd Street will exit special servicing after Harbor Group closed a negotiated extension.
Morningstar reported occupancy fell from 99% to 86% and cash flow dropped 37% below underwritten levels, though a source close to the deal says the building is now fully leased.
Harbor Group bought the Midtown tower from ViacomCBS for $760 million in 2021, the largest investment sale that year, and has since invested $150 million in upgrades.
A $420 million CMBS loan backed by 51 West 52nd Street, a 38-story, 893,000-square-foot Midtown office tower, will exit special servicing after sponsor Harbor Group International closed a negotiated loan extension, according to Commercial Observer. The loan, which backs the single-asset, single-borrower DBGS 2021-W52 deal, was transferred to special servicing ahead of its October 2026 maturity even though it still carried a 12-month extension option, per an alert from Morningstar Credit ******* ytics.
#group #extension
A $420 million CMBS loan backed by the 893,000-square-foot office tower at 51 West 52nd Street will exit special servicing after Harbor Group closed a negotiated extension.
Morningstar reported occupancy fell from 99% to 86% and cash flow dropped 37% below underwritten levels, though a source close to the deal says the building is now fully leased.
Harbor Group bought the Midtown tower from ViacomCBS for $760 million in 2021, the largest investment sale that year, and has since invested $150 million in upgrades.
A $420 million CMBS loan backed by 51 West 52nd Street, a 38-story, 893,000-square-foot Midtown office tower, will exit special servicing after sponsor Harbor Group International closed a negotiated loan extension, according to Commercial Observer. The loan, which backs the single-asset, single-borrower DBGS 2021-W52 deal, was transferred to special servicing ahead of its October 2026 maturity even though it still carried a 12-month extension option, per an alert from Morningstar Credit ******* ytics.
#group #extension


2 months ago
Kansas City, Missouri — Vice President JD Vance announced Monday the Trump administration will suspend roughly 870,000 people suspected of defrauding pandemic-era small business programs from receiving future federal loans.
The vice president contended that borrowers who stole taxpayer money should no longer be eligible to receive loans from government-backed programs.
"If you screwed the American taxpayer, the federal government is now going to say you're cut off, no more," Vance told reporters. "You shouldn't be applying anymore, and if you do apply, you're no longer able to get those benefits."
His remarks came as the Justice Department announced a slew of cases in a nationwide crackdown on fraud involving the COVID-19-era Paycheck Protection Program.
The department's enforcement push, which ran from June 12 through Sept. 1 and was dubbed "Heartland fraud surge," resulted in actions involving more than 160 defendants and approximately $245 million in intended losses to taxpayers. The operation was put into action more than five years after the government pushed emergency loans to businesses nationwide that were struggling as a result of the coronavirus pandemic.
#president #pandemic #federal
The vice president contended that borrowers who stole taxpayer money should no longer be eligible to receive loans from government-backed programs.
"If you screwed the American taxpayer, the federal government is now going to say you're cut off, no more," Vance told reporters. "You shouldn't be applying anymore, and if you do apply, you're no longer able to get those benefits."
His remarks came as the Justice Department announced a slew of cases in a nationwide crackdown on fraud involving the COVID-19-era Paycheck Protection Program.
The department's enforcement push, which ran from June 12 through Sept. 1 and was dubbed "Heartland fraud surge," resulted in actions involving more than 160 defendants and approximately $245 million in intended losses to taxpayers. The operation was put into action more than five years after the government pushed emergency loans to businesses nationwide that were struggling as a result of the coronavirus pandemic.
#president #pandemic #federal


2 months ago
Vale S.A. (NYSE:VALE) is considering making its debut in China's domestic bond market as soon as this year, with CFO Marcelo Bacci saying the company is preparing for a potential Panda bond issuance. The move would be strategically significant because China accounts for roughly half of Vale's revenue, making renminbi financing a natural extension of its relationship with its largest market. Bloomberg reported that Vale is still ****** sing the market, including whether it can obtain a maturity longer than the typical two-, three-, or five-year terms available to international issuers.
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China
The timing is also favorable for Vale because China's Panda bond market is expanding rapidly. Reuters reported that foreign issuers have increasingly turned to Asian bond markets to diversify funding sources, while Chinese yuan bond issuance has reached record levels in 2026. For Vale S.A. (NYSE:VALE), the potential transaction therefore looks less like a necessity for raising capital and more like an effort to diversify its investor base, potentially lower funding costs, and build a longer-term financing relationship with Chinese investors.
The strongest bullish argument is that Vale S.A. (NYSE:VALE) could potentially lower and diversify its cost of capital by accessing a large pool of Chinese investors at a time when renminbi funding remains relatively inexpensive. Reuters noted that Chinese onshore and offshore yuan bond markets have experienced record issuance this year, with foreign borrowers increasingly using these markets to diversify away from traditional funding currencies. If Vale can achieve competitive pricing, a Panda bond could provide an additional funding channel alongside its established dollar financing, reducing its dependence on a single market.
The move could also create a better natural match between Vale's revenues and its financing currency. Because China represents approximately half of Vale's revenue, raising at least some debt in renminbi could provide a degree of currency alignment with its Chinese business exposure. More importantly, establishing itself as a repeat issuer could strengthen Vale's relationships with Chinese banks and institutional investors, potentially giving it access to another source of capital when global dollar markets become less attractive.
There is also a broader strategic benefit. China is actively expanding the Panda bond market and encouraging international companies to use it. Official Chinese data showed that more than 160 billion yuan of Panda bonds were issued during the first half of 2026, up 69% year over year, demonstrating that the market is becoming more established and liquid. Vale entering this market could therefore position the company early in a growing financing ecosystem rather than waiting until it becomes more crowded.
#chinese #bond #panda #China

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates

2 months ago
If you are looking for yield today, rising interest rates have increased your options. For example, the 30-year Treasury bond's yield is around 5.3% as of this writing. By comparison, the S&P 500 index (SNPINDEX: ^GSPC) is only yielding around 1%. But there are still two big reasons why investors may want to buy a high-yield dividend stock like Coca-Cola (NYSE: KO), even though its 2.4% yield isn't even close to the 30-year Treasury yield.
A bond is an agreement between the lender and the borrower. The lender provides a fixed amount of cash, while the borrower pays interest at a fixed rate until the loan matures. When the loan matures, the borrower repays the bond's principal. Everything is fixed, and both the value of the interest collected and the bond's principal are slowly eroded by inflation. It doesn't matter that 30-year Treasuries are considered safe because they are backed by the U.S. government. The big inflation risk is still the same.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you have a short investment time horizon, inflation may not be a big issue for you. In which case, the 5.3% yield of a 30-year Treasury would probably be more attractive than Coca-Cola's 2.4% yield. However, if you have a long time horizon, Coca-Cola's yield comes with something that a Treasury doesn't: Growth.
Coca-Cola is one of the world's largest consumer staples companies. It has an incredible history of growth, highlighted by 64 annual dividend increases. That makes the company a Dividend King. But think about that for a second, you can collect 30 years of the same income from a bond or 30 years of increasing income from Coca-Cola. Since the start of 1996, roughly 30 years ago, the company's dividend has increased by nearly 750%. That dividend growth was driven by the company's growth, which also led to an over 300% increase in the stock price. If you hold a bond to maturity, all you get back is the principal.
#coca
A bond is an agreement between the lender and the borrower. The lender provides a fixed amount of cash, while the borrower pays interest at a fixed rate until the loan matures. When the loan matures, the borrower repays the bond's principal. Everything is fixed, and both the value of the interest collected and the bond's principal are slowly eroded by inflation. It doesn't matter that 30-year Treasuries are considered safe because they are backed by the U.S. government. The big inflation risk is still the same.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you have a short investment time horizon, inflation may not be a big issue for you. In which case, the 5.3% yield of a 30-year Treasury would probably be more attractive than Coca-Cola's 2.4% yield. However, if you have a long time horizon, Coca-Cola's yield comes with something that a Treasury doesn't: Growth.
Coca-Cola is one of the world's largest consumer staples companies. It has an incredible history of growth, highlighted by 64 annual dividend increases. That makes the company a Dividend King. But think about that for a second, you can collect 30 years of the same income from a bond or 30 years of increasing income from Coca-Cola. Since the start of 1996, roughly 30 years ago, the company's dividend has increased by nearly 750%. That dividend growth was driven by the company's growth, which also led to an over 300% increase in the stock price. If you hold a bond to maturity, all you get back is the principal.
#coca


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Mortgage rates have been slowly rising over the past seven months, from just below 6% before the Middle East conflict began in late February to near 7% this week (with some surveys reporting rates already above 7%).
However, it's still possible to lock in a rate below the national average. Borrowers need to shop diligently and deploy one or more of the following strategies to earn the lowest mortgage rate possible in the 2026 housing market.
See the average mortgage rate in your state.
Analysis by Yahoo Finance of nearly 5,000 mortgage lenders reporting 2026 loan information under the Home Mortgage Disclosure Act reveals the surprising truth: the lenders offering the absolute lowest mortgage rates. In 2026, the largest national banks, credit unions, and homebuilders that finance their own construction offered the most favorable home loan rates to the widest variety of borrowers.
#rates #finance #reporting
Mortgage rates have been slowly rising over the past seven months, from just below 6% before the Middle East conflict began in late February to near 7% this week (with some surveys reporting rates already above 7%).
However, it's still possible to lock in a rate below the national average. Borrowers need to shop diligently and deploy one or more of the following strategies to earn the lowest mortgage rate possible in the 2026 housing market.
See the average mortgage rate in your state.
Analysis by Yahoo Finance of nearly 5,000 mortgage lenders reporting 2026 loan information under the Home Mortgage Disclosure Act reveals the surprising truth: the lenders offering the absolute lowest mortgage rates. In 2026, the largest national banks, credit unions, and homebuilders that finance their own construction offered the most favorable home loan rates to the widest variety of borrowers.
#rates #finance #reporting


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Adjustable-rate mortgages (ARMs) can allow you to land a lower interest rate in today's high-rate environment. However, ARMs aren't without risk, and they're only right for certain borrowers in certain situations. Find out how ARMs work and whether this type of home loan is right for you.
ARMs behave like two different mortgages rolled into one loan agreement. It begins with a fixed-rate term, usually between five and 10 years. During this period, your interest rate and payment will remain the same.
After that, it converts to a variable-rate loan with an interest rate that can change (up or down) every six months or annually. This means your monthly mortgage payment also changes.
To fully understand how ARMs work, you need to understand what their formulas mean. For example, let's examine the "5/1" ARM:
#rate
Adjustable-rate mortgages (ARMs) can allow you to land a lower interest rate in today's high-rate environment. However, ARMs aren't without risk, and they're only right for certain borrowers in certain situations. Find out how ARMs work and whether this type of home loan is right for you.
ARMs behave like two different mortgages rolled into one loan agreement. It begins with a fixed-rate term, usually between five and 10 years. During this period, your interest rate and payment will remain the same.
After that, it converts to a variable-rate loan with an interest rate that can change (up or down) every six months or annually. This means your monthly mortgage payment also changes.
To fully understand how ARMs work, you need to understand what their formulas mean. For example, let's examine the "5/1" ARM:
#rate



2 months ago
While the average personal loan interest rate is 12.21%, borrowers with excellent credit may have access to rates as low as 6.20%.
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.72% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting at 6.20%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12.06%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#loan
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.72% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting at 6.20%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12.06%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#loan

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Adjustable-rate mortgages (ARMs) can allow you to land a lower interest rate in today's high-rate environment. However, ARMs aren't without risk, and they're only right for certain borrowers in certain situations. Find out how ARMs work and whether this type of home loan is right for you.
ARMs behave like two different mortgages rolled into one loan agreement. It begins with a fixed-rate term, usually between five and 10 years. During this period, your interest rate and payment will remain the same.
After that, it converts to a variable-rate loan with an interest rate that can change (up or down) every six months or annually. This means your monthly mortgage payment also changes.
To fully understand how ARMs work, you need to understand what their formulas mean. For example, let's examine the "5/1" ARM:
#interest #right #understand
Adjustable-rate mortgages (ARMs) can allow you to land a lower interest rate in today's high-rate environment. However, ARMs aren't without risk, and they're only right for certain borrowers in certain situations. Find out how ARMs work and whether this type of home loan is right for you.
ARMs behave like two different mortgages rolled into one loan agreement. It begins with a fixed-rate term, usually between five and 10 years. During this period, your interest rate and payment will remain the same.
After that, it converts to a variable-rate loan with an interest rate that can change (up or down) every six months or annually. This means your monthly mortgage payment also changes.
To fully understand how ARMs work, you need to understand what their formulas mean. For example, let's examine the "5/1" ARM:
#interest #right #understand


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Pre-approval signals you likely qualify, but no underwriter has verified your income, debts, or employment, so it is far from a guaranteed loan.
Full underwriting approval verifies income, employment, credit, and ***** ets, but can still carry conditions that must be resolved before closing.
Even after full approval, taking on new debt, switching jobs, or a failed appraisal can derail your mortgage before closing day.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Getting approved for a mortgage is one of the first major steps in the home-buying process. But it's not always so easy and usually comes with a lot of paperwork. Lenders need to know you are a reliable borrower. They want to review your finances to make sure you can comfortably afford the loan. This means you need to provide documented proof of your income, employment history, savings, and existing debt. Having these documents ready ahead of time can make the mortgage process faster and more manageable. While every lender will have slightly different requirements, these are the most common documents a lender will ask for.
#income
Full underwriting approval verifies income, employment, credit, and ***** ets, but can still carry conditions that must be resolved before closing.
Even after full approval, taking on new debt, switching jobs, or a failed appraisal can derail your mortgage before closing day.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Getting approved for a mortgage is one of the first major steps in the home-buying process. But it's not always so easy and usually comes with a lot of paperwork. Lenders need to know you are a reliable borrower. They want to review your finances to make sure you can comfortably afford the loan. This means you need to provide documented proof of your income, employment history, savings, and existing debt. Having these documents ready ahead of time can make the mortgage process faster and more manageable. While every lender will have slightly different requirements, these are the most common documents a lender will ask for.
#income

2 months ago
Pre-approval signals you likely qualify, but no underwriter has verified your income, debts, or employment, so it is far from a guaranteed loan.
Full underwriting approval verifies income, employment, credit, and ******* ets, but can still carry conditions that must be resolved before closing.
Even after full approval, taking on new debt, switching jobs, or a failed appraisal can derail your mortgage before closing day.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Getting approved for a mortgage is one of the first major steps in the home-buying process. But it's not always so easy and usually comes with a lot of paperwork. Lenders need to know you are a reliable borrower. They want to review your finances to make sure you can comfortably afford the loan. This means you need to provide documented proof of your income, employment history, savings, and existing debt. Having these documents ready ahead of time can make the mortgage process faster and more manageable. While every lender will have slightly different requirements, these are the most common documents a lender will ask for.
#approval #loan #stocks
Full underwriting approval verifies income, employment, credit, and ******* ets, but can still carry conditions that must be resolved before closing.
Even after full approval, taking on new debt, switching jobs, or a failed appraisal can derail your mortgage before closing day.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Getting approved for a mortgage is one of the first major steps in the home-buying process. But it's not always so easy and usually comes with a lot of paperwork. Lenders need to know you are a reliable borrower. They want to review your finances to make sure you can comfortably afford the loan. This means you need to provide documented proof of your income, employment history, savings, and existing debt. Having these documents ready ahead of time can make the mortgage process faster and more manageable. While every lender will have slightly different requirements, these are the most common documents a lender will ask for.
#approval #loan #stocks
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
A college education is probably one of the most expensive purchases you'll make in your lifetime.
The average cost of college today ranges from more than $25,000 to $60,000 per year. With prices that high, it's inevitable that many students will rely on student loans to help fund their education, in addition to their own savings, contributions from family, scholarships, and grants.
Federal student loans are a great first place to start. They typically offer the most competitive rates with fixed APRs and borrower protections. But some students aren't eligible for federal loans, or can't get the full amount they need for school.
As a result, you may turn to private student loans to fill the gap. Here's what you need to know before you apply for a private loan, and some of the top lenders to consider today.
#loans #federal #private
A college education is probably one of the most expensive purchases you'll make in your lifetime.
The average cost of college today ranges from more than $25,000 to $60,000 per year. With prices that high, it's inevitable that many students will rely on student loans to help fund their education, in addition to their own savings, contributions from family, scholarships, and grants.
Federal student loans are a great first place to start. They typically offer the most competitive rates with fixed APRs and borrower protections. But some students aren't eligible for federal loans, or can't get the full amount they need for school.
As a result, you may turn to private student loans to fill the gap. Here's what you need to know before you apply for a private loan, and some of the top lenders to consider today.
#loans #federal #private


2 months ago
On August 25, Qfin Holdings (NASDAQ:QFIN) reported second-quarter results that tell two very different stories at once. Total loan volume fell 25.1% year over year to RMB63,377 million, and non-GAAP net income dropped to RMB454.9 million from RMB946 million just one quarter earlier. Non-GAAP earnings per diluted ADS sank to RMB3.72 from RMB7.70. But buried in the same release, revenue from the company's technology solutions business jumped more than sixfold, and management laid out plans to turn Qfin into what it calls an AI-native lender. Investors have to weigh both halves of that picture.
The clearest growth story sits inside Qfin's tech solutions arm. Loan volume tied to that unit hit RMB10.5 billion for the quarter, up 515% from a year earlier, while the outstanding balance climbed to roughly RMB16.1 billion, up 313%. Through its FocusPRO platform, Qfin now helps banks serve borrowers priced between 3% and 12%, a segment its own consumer lending rarely touches. During the quarter, the company signed two new AI agent projects with banking partners, one built to support loan officers from lead identification through conversion, the other aimed at SME credit review and approval. CEO Wu Haisheng framed the effort as an organizational shift, saying it is "about turning individual and team experience into shared reusable organizational capabilities."
Risk metrics also moved in the right direction during the quarter itself. The 30-day collection rate rose to 88.1%, up 2.3 percentage points sequentially, while the C-M2 delinquency ratio fell 17% sequentially to 0.66%, nearing year-ago levels. The 90-day delinquency rate dropped to 2.83% from 3.5%. On the funding side, ABS issuance jumped 90% sequentially to RMB5.5 billion while issuance costs fell roughly 20 basis points, and overall funding costs eased about 10 basis points as the company leaned on a track record of stable ******* et performance. Qfin also paid a semiannual dividend of $0.46 per ADS, a payout ratio near 30%, and had repurchased $7 million of stock before pausing the buyback program.
Every one of those quarterly improvements sits next to a much rougher backdrop. Sales and marketing spending fell 13% sequentially as Qfin pulled back on growth, and new credit line users fell to 830,000, down from 1.19 million a quarter earlier. New loan provisions hit RMB1.72 billion, a booking ratio of 5.36%, the highest on record. A one-off RMB500 million tax expense tied to a change in tax treatment pushed the effective tax rate to 60.3%, though management expects it to settle near 20% going forward.
#earlier
The clearest growth story sits inside Qfin's tech solutions arm. Loan volume tied to that unit hit RMB10.5 billion for the quarter, up 515% from a year earlier, while the outstanding balance climbed to roughly RMB16.1 billion, up 313%. Through its FocusPRO platform, Qfin now helps banks serve borrowers priced between 3% and 12%, a segment its own consumer lending rarely touches. During the quarter, the company signed two new AI agent projects with banking partners, one built to support loan officers from lead identification through conversion, the other aimed at SME credit review and approval. CEO Wu Haisheng framed the effort as an organizational shift, saying it is "about turning individual and team experience into shared reusable organizational capabilities."
Risk metrics also moved in the right direction during the quarter itself. The 30-day collection rate rose to 88.1%, up 2.3 percentage points sequentially, while the C-M2 delinquency ratio fell 17% sequentially to 0.66%, nearing year-ago levels. The 90-day delinquency rate dropped to 2.83% from 3.5%. On the funding side, ABS issuance jumped 90% sequentially to RMB5.5 billion while issuance costs fell roughly 20 basis points, and overall funding costs eased about 10 basis points as the company leaned on a track record of stable ******* et performance. Qfin also paid a semiannual dividend of $0.46 per ADS, a payout ratio near 30%, and had repurchased $7 million of stock before pausing the buyback program.
Every one of those quarterly improvements sits next to a much rougher backdrop. Sales and marketing spending fell 13% sequentially as Qfin pulled back on growth, and new credit line users fell to 830,000, down from 1.19 million a quarter earlier. New loan provisions hit RMB1.72 billion, a booking ratio of 5.36%, the highest on record. A one-off RMB500 million tax expense tied to a change in tax treatment pushed the effective tax rate to 60.3%, though management expects it to settle near 20% going forward.
#earlier

2 months ago
Garn-St Germain bars lenders from calling a parent's mortgage due at death, letting heirs keep a 3% rate locked against today's 6.73% average.
Heirs must file a death certificate or probate order with the servicer to establish successor-in-interest status before making payments on the inherited loan.
Reverse mortgages fall outside Garn-St Germain, and a HECM becomes due at the borrower's death, forcing heirs to pay off, sell, or surrender the property.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
If your parent still holds a mortgage locked in near 3% from the refinancing wave earlier this decade, that loan itself has become an ****** et worth considering. With the 30-year fixed averaging 6.73% at the end of August 2026 and the 10-year Treasury yield at 4.75% as of August 31, 2026, a below-market fixed rate is effectively something you inherit along with the house. A federal law passed back in 1982 says that when a homeowner dies and the property passes to a relative, the lender cannot use the death as an excuse to call the loan due. The kids can keep both the house and the rate.
#heirs
Heirs must file a death certificate or probate order with the servicer to establish successor-in-interest status before making payments on the inherited loan.
Reverse mortgages fall outside Garn-St Germain, and a HECM becomes due at the borrower's death, forcing heirs to pay off, sell, or surrender the property.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
If your parent still holds a mortgage locked in near 3% from the refinancing wave earlier this decade, that loan itself has become an ****** et worth considering. With the 30-year fixed averaging 6.73% at the end of August 2026 and the 10-year Treasury yield at 4.75% as of August 31, 2026, a below-market fixed rate is effectively something you inherit along with the house. A federal law passed back in 1982 says that when a homeowner dies and the property passes to a relative, the lender cannot use the death as an excuse to call the loan due. The kids can keep both the house and the rate.
#heirs

2 months ago
Personal loans are dangerously easy to get. You can have cash in your account the same day you apply — no collateral, minimal friction, maximum temptation. And that's exactly the problem. Just because you can borrow doesn't mean you should. The difference between a smart financial move and a debt spiral often comes down to one thing: understanding why you're borrowing in the first place.
Personal loans aren't inherently good or bad. They're a tool. And like any tool, they can either solve your problem or make it worse. Below, we break down the situations where borrowing actually makes sense and the ones where walking away is the smarter play.
Personal loans hover around 12% APR for borrowers with solid credit. Credit cards? Try 20%. If you're juggling multiple cards with balances, rolling that debt into a single personal loan can save you serious money on interest. Plus, you get one predictable payment instead of the payment shuffle.
But the catch is that you actually have to stop using your credit cards. Too many people consolidate their debt, feel relieved and then rack up new balances within a year. Now they've got two problems instead of one. So, before you borrow, compare rates, map out your payoff timeline and be honest about your spending habits. If you know you'll just max out those cards again, a personal loan won't save you. It'll only bury you deeper.
Your credit utilization ratio — basically, how much of your available credit you're actually using — accounts for 30% of your FICO credit score. Since personal loans are installment debt, they don't count toward that ratio the way credit cards do.
#debt #borrow #down
Personal loans aren't inherently good or bad. They're a tool. And like any tool, they can either solve your problem or make it worse. Below, we break down the situations where borrowing actually makes sense and the ones where walking away is the smarter play.
Personal loans hover around 12% APR for borrowers with solid credit. Credit cards? Try 20%. If you're juggling multiple cards with balances, rolling that debt into a single personal loan can save you serious money on interest. Plus, you get one predictable payment instead of the payment shuffle.
But the catch is that you actually have to stop using your credit cards. Too many people consolidate their debt, feel relieved and then rack up new balances within a year. Now they've got two problems instead of one. So, before you borrow, compare rates, map out your payoff timeline and be honest about your spending habits. If you know you'll just max out those cards again, a personal loan won't save you. It'll only bury you deeper.
Your credit utilization ratio — basically, how much of your available credit you're actually using — accounts for 30% of your FICO credit score. Since personal loans are installment debt, they don't count toward that ratio the way credit cards do.
#debt #borrow #down


2 months ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ***** ysis delivered straight to their inbox with the free CRE Daily newsletter.
National Resources, Great Point Studios, and Lindsay Goldberg refinanced their 719,943-square-foot "Hollywood on the Hudson" studio portfolio in Yonkers for $435 million.
The floating-rate loan from Bank of Montreal, Starwood Mortgage Capital, and Bank of America replaces $376.8 million in debt and funds tenant improvements.
The portfolio is 98.9% leased with Lionsgate Studio Corp. alone occupying 52.5% of the ***** e, underscoring strong demand for film and TV production real estate.
A four-building Yonkers film studio and office portfolio has landed a $435 million refinancing, according to Commercial Property Executive. The borrower, a joint venture between National Resources, Great Point Studios Operations, and Lindsay Goldberg, used the floating-rate loan to retire $376.8 million in prior debt on the 719,943-square-foot "Hollywood on the Hudson" portfolio, with the balance covering closing costs, equity returns, and tenant improvements.
#Portfolio #national #point #lindsay
National Resources, Great Point Studios, and Lindsay Goldberg refinanced their 719,943-square-foot "Hollywood on the Hudson" studio portfolio in Yonkers for $435 million.
The floating-rate loan from Bank of Montreal, Starwood Mortgage Capital, and Bank of America replaces $376.8 million in debt and funds tenant improvements.
The portfolio is 98.9% leased with Lionsgate Studio Corp. alone occupying 52.5% of the ***** e, underscoring strong demand for film and TV production real estate.
A four-building Yonkers film studio and office portfolio has landed a $435 million refinancing, according to Commercial Property Executive. The borrower, a joint venture between National Resources, Great Point Studios Operations, and Lindsay Goldberg, used the floating-rate loan to retire $376.8 million in prior debt on the 719,943-square-foot "Hollywood on the Hudson" portfolio, with the balance covering closing costs, equity returns, and tenant improvements.
#Portfolio #national #point #lindsay

2 months ago
There's a famous line in The Big Short when a baffled Mark Baum, after hearing some finance bros casually admit to issuing fraudulent, high-risk loans to unqualified borrowers, asks his colleagues: "I don't get it. Why are they confessing?"
"They're not confessing. They're bragging," comes the response.
Naturally, people thought of this when ex-Premier League referee Mike Dean made his latest attempt to shove himself into the spotlight. On Jamie Vardy's Having a Party podcast, he "admitted" to playing secret mini-games while officiating top-flight matches.
He claimed: "We used to say, 'Right, we'll kick off now, right? See how long we can go without blowing a whistle.' Done that a few times in the Premier [League], before VAR obviously. Went 20-25 minutes without blowing a whistle a few times. Let it go, let it go, let it go." He also said he would try and stay within the confines of the centre circle for as long as possible, once reaching the 15-minute mark on that particular side-quest.
Mike Dean's claim that he played secret mini-games during matches has sparked outrage (PA Archive)
#mike #mark #secret #games
"They're not confessing. They're bragging," comes the response.
Naturally, people thought of this when ex-Premier League referee Mike Dean made his latest attempt to shove himself into the spotlight. On Jamie Vardy's Having a Party podcast, he "admitted" to playing secret mini-games while officiating top-flight matches.
He claimed: "We used to say, 'Right, we'll kick off now, right? See how long we can go without blowing a whistle.' Done that a few times in the Premier [League], before VAR obviously. Went 20-25 minutes without blowing a whistle a few times. Let it go, let it go, let it go." He also said he would try and stay within the confines of the centre circle for as long as possible, once reaching the 15-minute mark on that particular side-quest.
Mike Dean's claim that he played secret mini-games during matches has sparked outrage (PA Archive)
#mike #mark #secret #games


2 months ago
A loan estimate looks like a done deal. It isn't. Some of the numbers on it can legally change by up to 10% before closing, and a few can change by any amount.
Shopping around for a mortgage is crucial, and it starts with the loan estimate, a three-page document detailing the interest rate, estimated costs and other loan terms.
87% of 2025 borrowers paid above the most competitive rate available to them simply because they didn't compare offers, according to Bankrate's Hidden Homeownership Tax research. The typical cost of not shopping: $3,343 a year, or $278 a month.
A mortgage loan estimate is a standardized, three-page document that a lender must send you within three business days of receiving your mortgage application. It lists your rate, monthly payment, closing costs and other terms — but none of these numbers are final. Think of it as a detailed price quote: close enough to compare lenders and build an accurate budget, but not enough to guarantee what you'll actually pay at closing.
When you compare loan estimates from more than one lender, you're more likely to uncover the lowest rate you actually qualify for. Freddie Mac found that borrowers who obtained two rate quotes during the high-rate months of October and November 2022, when average rates topped 7%, could have saved up to $600 a year. Borrowers who obtained at least four quotes could have saved more than $1,200 a year.
#estimate #compare #year
Shopping around for a mortgage is crucial, and it starts with the loan estimate, a three-page document detailing the interest rate, estimated costs and other loan terms.
87% of 2025 borrowers paid above the most competitive rate available to them simply because they didn't compare offers, according to Bankrate's Hidden Homeownership Tax research. The typical cost of not shopping: $3,343 a year, or $278 a month.
A mortgage loan estimate is a standardized, three-page document that a lender must send you within three business days of receiving your mortgage application. It lists your rate, monthly payment, closing costs and other terms — but none of these numbers are final. Think of it as a detailed price quote: close enough to compare lenders and build an accurate budget, but not enough to guarantee what you'll actually pay at closing.
When you compare loan estimates from more than one lender, you're more likely to uncover the lowest rate you actually qualify for. Freddie Mac found that borrowers who obtained two rate quotes during the high-rate months of October and November 2022, when average rates topped 7%, could have saved up to $600 a year. Borrowers who obtained at least four quotes could have saved more than $1,200 a year.
#estimate #compare #year