

1 month ago
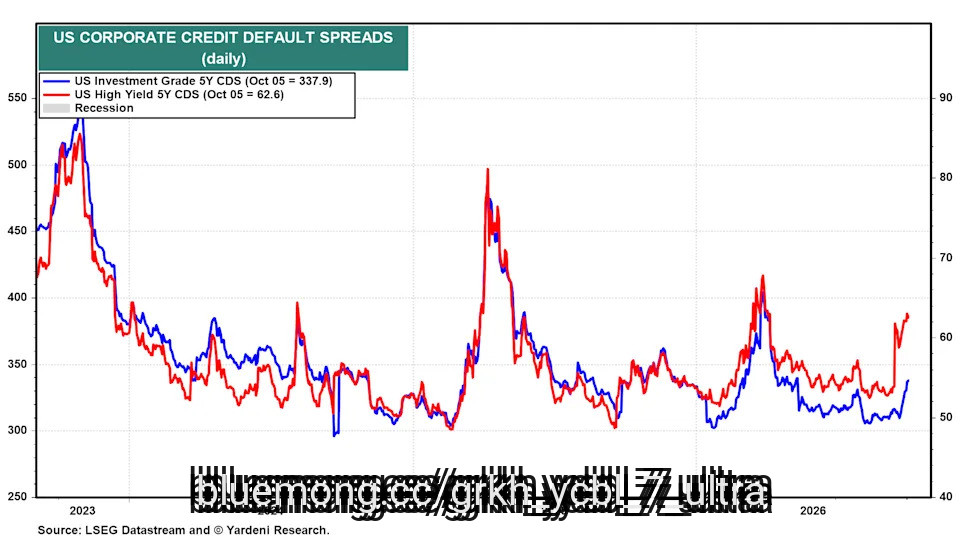
JPMorgan Chase (JPM) CEO Jamie Dimon sharpened his warning about the risks of a global bond sell-off on Tuesday, saying the world's massive competition for capital could begin squeezing corporate borrowers.
Dimon warned that the combination of rising government borrowing costs and spending on the AI boom could spill into corporate credit markets, pushing up the costs for companies to refinance or raise new debt.
"There will be a point where the market will ask for more and more and more, and yeah, at one point that'll feed into corporate debt, corporate credit spreads, and things like that, which is how it normally happens," Dimon said in a Bloomberg interview on the sidelines of a JPMorgan event in London.
"The best thing to do with any of these things is deal with it before it becomes a crisis. If it becomes a crisis, we will deal with it. It just will be in a much less pleasant way," he added.
The warning comes as a global rout in bonds has pushed longer-term borrowing costs sharply higher in recent weeks, with the benchmark US 10-year Treasury yield recently surpassing heights not seen since 2002.
#credit
Dimon warned that the combination of rising government borrowing costs and spending on the AI boom could spill into corporate credit markets, pushing up the costs for companies to refinance or raise new debt.
"There will be a point where the market will ask for more and more and more, and yeah, at one point that'll feed into corporate debt, corporate credit spreads, and things like that, which is how it normally happens," Dimon said in a Bloomberg interview on the sidelines of a JPMorgan event in London.
"The best thing to do with any of these things is deal with it before it becomes a crisis. If it becomes a crisis, we will deal with it. It just will be in a much less pleasant way," he added.
The warning comes as a global rout in bonds has pushed longer-term borrowing costs sharply higher in recent weeks, with the benchmark US 10-year Treasury yield recently surpassing heights not seen since 2002.
#credit

2 months ago
On August 20, Royal Caribbean Group (NYSE:RCL) said it had completed a sale of $1.25 billion of notes that carry a 5.55% coupon and come due on January 20, 2034. The money is earmarked first for floating-rate term loans, with anything left over used to repay or refinance other debt, and the offering rode on a shelf registration filed on February 29, 2024. That sounds like routine upkeep. But next to an earnings beat and a flat third-quarter pricing outlook, the deal gives you a handy lens on where the company stands.
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year

2 months ago
American Tower Corporation (NYSE:AMT) priced $1.6 billion of senior notes on September 9: $500 million at 5.300% due 2031, $500 million at 5.560% due 2033, and $600 million at 5.750% due 2036. Once issued, the three tranches would carry combined annual coupons of $88.8 million, equivalent to a weighted average coupon of 5.55%.
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower
American Tower Corporation (NYSE:AMT) expects approximately $1.580 billion in net proceeds. It intends to use $600 million to repay 1.450% notes due in 2026, with additional proceeds designated for revolving-credit debt and general corporate purposes. The financing exchanges a near-term repayment requirement and some revolving debt for longer fixed-rate obligations.
The investment question is whether greater funding certainty compensates for the higher cash-interest commitment.
American Tower Corporation (NYSE:AMT) would remove a $600 million maturity falling due this year once the planned repayment occurs. That reduces exposure to having to refinance the obligation closer to its deadline, when borrowing conditions could be less favorable.
The new maturities also distribute principal repayments across 2031, 2033 and 2036. For American Tower Corporation (NYSE:AMT), a spread of repayment dates can support financial planning across its communications-site and data-center portfolio. Fixed coupons make the cost of this funding predictable.
#tower


2 months ago
The best time to refinance is when your credit score or overall financial situation has improved.
Generally, you should aim to either lower your interest rate or your monthly payment — preferably both.
Avoid refinancing when auto loan rates are high or if you won't be able to save money by switching lenders.
It makes sense to consider refinancing your auto loan if you can lower your interest rate and monthly payment. The refinancing process involves swapping your current loan for a new loan with different — and ideally better — terms.
However, refinancing is not always a wise financial move. If interest rates are high, or if you're close to paying off your loan, then it may make more sense to stick with your current lender. Knowing the ins and outs of when to refinance and when to wait will help you make the best decision for refinancing your auto loan.
#financial #lower
Generally, you should aim to either lower your interest rate or your monthly payment — preferably both.
Avoid refinancing when auto loan rates are high or if you won't be able to save money by switching lenders.
It makes sense to consider refinancing your auto loan if you can lower your interest rate and monthly payment. The refinancing process involves swapping your current loan for a new loan with different — and ideally better — terms.
However, refinancing is not always a wise financial move. If interest rates are high, or if you're close to paying off your loan, then it may make more sense to stick with your current lender. Knowing the ins and outs of when to refinance and when to wait will help you make the best decision for refinancing your auto loan.
#financial #lower


2 months ago
Monthly car payments continue to hit record levels for both new and used cars.
The overall cost of car ownership remains elevated due to steep insurance and car maintenance prices in addition to the cost of a loan.
Good credit scores are key to qualifying for the best auto loan rates and driving away with a competitive monthly payment.
New car prices remain steep, with monthly payments for new cars soaring to the highest levels ever recorded. Amid this environment, buyers are taking on increasingly larger loans to make vehicle purchases, and some are also stretching repayment over a longer timeline — in some cases, up to seven years.
Whether you have poor credit or are looking to refinance your current loan, it's important to understand typical monthly payments and rates so you can feel confident that you are getting the best deal. While auto loan rates in 2026 are projected to lower slightly, it won't be enough to put a serious dent in the many factors that are driving up the cost of car ownership, including continued high cost of auto insurance and maintenance expenses.
#payments #rates #levels #ownership
The overall cost of car ownership remains elevated due to steep insurance and car maintenance prices in addition to the cost of a loan.
Good credit scores are key to qualifying for the best auto loan rates and driving away with a competitive monthly payment.
New car prices remain steep, with monthly payments for new cars soaring to the highest levels ever recorded. Amid this environment, buyers are taking on increasingly larger loans to make vehicle purchases, and some are also stretching repayment over a longer timeline — in some cases, up to seven years.
Whether you have poor credit or are looking to refinance your current loan, it's important to understand typical monthly payments and rates so you can feel confident that you are getting the best deal. While auto loan rates in 2026 are projected to lower slightly, it won't be enough to put a serious dent in the many factors that are driving up the cost of car ownership, including continued high cost of auto insurance and maintenance expenses.
#payments #rates #levels #ownership

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Treasury Department's $6 billion bond buyback, an effort to stem rising yields, fell far short of expectations Thursday. The repurchase of government debt led to Treasury yields continuing to climb, with the 10-year note topping a three-year high. Potential home buyers and refinancers hoping for some mortgage rate relief instead saw rates creep toward, and in some reports, top 7%.
Yields were mixed Friday, with the 10-year Treasury remaining just below 5%.
In an interview Thursday evening with conservative strategist Steve Bannon on "War Room," Treasury Secretary Scott Bessent disputed the talk that the buyback program failed.
"This whole nonsense today that our operation didn't work — well, our operation didn't work, because we only had $10 billion of offers for our buyback program," Bessent said. "Normally, we get $20 billion, and we only buy the bonds back cheap. People seem to want to keep their long-term bonds, because we only had half as many offers. So, it's a bunch of noise, and in my career, I made money ignoring the noise."
#yields #offers #year
The Treasury Department's $6 billion bond buyback, an effort to stem rising yields, fell far short of expectations Thursday. The repurchase of government debt led to Treasury yields continuing to climb, with the 10-year note topping a three-year high. Potential home buyers and refinancers hoping for some mortgage rate relief instead saw rates creep toward, and in some reports, top 7%.
Yields were mixed Friday, with the 10-year Treasury remaining just below 5%.
In an interview Thursday evening with conservative strategist Steve Bannon on "War Room," Treasury Secretary Scott Bessent disputed the talk that the buyback program failed.
"This whole nonsense today that our operation didn't work — well, our operation didn't work, because we only had $10 billion of offers for our buyback program," Bessent said. "Normally, we get $20 billion, and we only buy the bonds back cheap. People seem to want to keep their long-term bonds, because we only had half as many offers. So, it's a bunch of noise, and in my career, I made money ignoring the noise."
#yields #offers #year


2 months ago
In 2024, Catalent tapped direct lenders for a $4.2 billion term loan to fund its acquisition by Novo Holdings. Last month, the drug manufacturer refinanced with a $4.1 billion syndicated loan that it says will cut its annual interest expense by about $100 million.
Catalent's move captures a shift under way in the leveraged finance market, according to a new report from DC Advisory. Redemptions from retail investors are contributing to the erosion of private credit's pricing advantage, creating an opening for banks to win refinancing business.
The problems in the retail private credit market show few signs of abating.
All the largest direct lenders, such as Ares, Apollo and KKR, also run business development companies, the most common form of credit fund aimed at individual investors, all under varying degrees of pressure to redeem investors.
PitchBook LCD reported on Wednesday that investors in Cliffwater's direct lending interval fund sought to redeem 16% of shares outstanding in the third quarter, down from 17% in the prior quarter.
#billion #private
Catalent's move captures a shift under way in the leveraged finance market, according to a new report from DC Advisory. Redemptions from retail investors are contributing to the erosion of private credit's pricing advantage, creating an opening for banks to win refinancing business.
The problems in the retail private credit market show few signs of abating.
All the largest direct lenders, such as Ares, Apollo and KKR, also run business development companies, the most common form of credit fund aimed at individual investors, all under varying degrees of pressure to redeem investors.
PitchBook LCD reported on Wednesday that investors in Cliffwater's direct lending interval fund sought to redeem 16% of shares outstanding in the third quarter, down from 17% in the prior quarter.
#billion #private


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
According to rates from the Zillow lender marketplace, current purchase mortgage rates are lower than refinance rates as of Monday, September 7, 2026.
Today, the 30-year fixed purchase rate is 6.67%, 6 basis points lower than the current refinance rate. The 15-year fixed purchase rate of 6.04% is 7 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.64% is 14 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Minor pricing changes
Here are the current mortgage rates today, Monday, September 7, 2026, according to the latest Zillow data:
#rates #year #basis
According to rates from the Zillow lender marketplace, current purchase mortgage rates are lower than refinance rates as of Monday, September 7, 2026.
Today, the 30-year fixed purchase rate is 6.67%, 6 basis points lower than the current refinance rate. The 15-year fixed purchase rate of 6.04% is 7 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.64% is 14 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Minor pricing changes
Here are the current mortgage rates today, Monday, September 7, 2026, according to the latest Zillow data:
#rates #year #basis



2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're not able to move to a new home or refinance to take advantage of the equity you have built up in your home, you're likely considering a home equity loan or a home equity line of credit. But besides interest rates, how do you choose between a HELOC or a home equity loan?
The average HELOC adjustable rate is 7.16%, a new 2026 low, according to real estate data ******* ytics company Curinos.
The national average rate on a fixed-rate home equity loan is 7.35%, up slightly from its 2026 low of 7.31% in late June.
Both rates are based on applicants with a minimum credit score of 780 and a maximum combined loan-to-value ratio (CLTV) of less than 70%.
#home #rate #heloc #advertiser
If you're not able to move to a new home or refinance to take advantage of the equity you have built up in your home, you're likely considering a home equity loan or a home equity line of credit. But besides interest rates, how do you choose between a HELOC or a home equity loan?
The average HELOC adjustable rate is 7.16%, a new 2026 low, according to real estate data ******* ytics company Curinos.
The national average rate on a fixed-rate home equity loan is 7.35%, up slightly from its 2026 low of 7.31% in late June.
Both rates are based on applicants with a minimum credit score of 780 and a maximum combined loan-to-value ratio (CLTV) of less than 70%.
#home #rate #heloc #advertiser


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
According to rates from the Zillow lender marketplace, current purchase mortgage rates are lower than refinance rates as of Monday, September 7, 2026.
Today, the 30-year fixed purchase rate is 6.67%, 6 basis points lower than the current refinance rate. The 15-year fixed purchase rate of 6.04% is 7 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.64% is 14 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Minor pricing changes
Here are the current mortgage rates today, Monday, September 7, 2026, according to the latest Zillow data:
#rate #year #basis #points
According to rates from the Zillow lender marketplace, current purchase mortgage rates are lower than refinance rates as of Monday, September 7, 2026.
Today, the 30-year fixed purchase rate is 6.67%, 6 basis points lower than the current refinance rate. The 15-year fixed purchase rate of 6.04% is 7 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.64% is 14 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Minor pricing changes
Here are the current mortgage rates today, Monday, September 7, 2026, according to the latest Zillow data:
#rate #year #basis #points


2 months ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ***** ysis delivered straight to their inbox with the free CRE Daily newsletter.
National Resources, Great Point Studios, and Lindsay Goldberg refinanced their 719,943-square-foot "Hollywood on the Hudson" studio portfolio in Yonkers for $435 million.
The floating-rate loan from Bank of Montreal, Starwood Mortgage Capital, and Bank of America replaces $376.8 million in debt and funds tenant improvements.
The portfolio is 98.9% leased with Lionsgate Studio Corp. alone occupying 52.5% of the ***** e, underscoring strong demand for film and TV production real estate.
A four-building Yonkers film studio and office portfolio has landed a $435 million refinancing, according to Commercial Property Executive. The borrower, a joint venture between National Resources, Great Point Studios Operations, and Lindsay Goldberg, used the floating-rate loan to retire $376.8 million in prior debt on the 719,943-square-foot "Hollywood on the Hudson" portfolio, with the balance covering closing costs, equity returns, and tenant improvements.
#Portfolio #national #point #lindsay
National Resources, Great Point Studios, and Lindsay Goldberg refinanced their 719,943-square-foot "Hollywood on the Hudson" studio portfolio in Yonkers for $435 million.
The floating-rate loan from Bank of Montreal, Starwood Mortgage Capital, and Bank of America replaces $376.8 million in debt and funds tenant improvements.
The portfolio is 98.9% leased with Lionsgate Studio Corp. alone occupying 52.5% of the ***** e, underscoring strong demand for film and TV production real estate.
A four-building Yonkers film studio and office portfolio has landed a $435 million refinancing, according to Commercial Property Executive. The borrower, a joint venture between National Resources, Great Point Studios Operations, and Lindsay Goldberg, used the floating-rate loan to retire $376.8 million in prior debt on the 719,943-square-foot "Hollywood on the Hudson" portfolio, with the balance covering closing costs, equity returns, and tenant improvements.
#Portfolio #national #point #lindsay

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
With the SAVE program ending and major changes for federal student loan borrowers this year, now could be a good time to review your repayment plan — which may also include refinancing.
Refinancing your student loans can help you score a lower interest rate or consolidate multiple monthly payments into one. But if you're refinancing federal student loans, you could also lose some valuable protections and forgiveness opportunities.
The first step is finding a student loan refinance lender that works with your budget and timeline. To help you get started, here are some top options today.
Read more: How to refinance your student loans
#refinancing #federal #disclosure
With the SAVE program ending and major changes for federal student loan borrowers this year, now could be a good time to review your repayment plan — which may also include refinancing.
Refinancing your student loans can help you score a lower interest rate or consolidate multiple monthly payments into one. But if you're refinancing federal student loans, you could also lose some valuable protections and forgiveness opportunities.
The first step is finding a student loan refinance lender that works with your budget and timeline. To help you get started, here are some top options today.
Read more: How to refinance your student loans
#refinancing #federal #disclosure
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
According to rates from the Zillow lender marketplace, current purchase mortgage rates are higher than refinance rates as of Monday, August 31, 2026.
Today, the 30-year fixed purchase rate is 6.55%, 4 basis points higher than the current refinance rate. The 15-year fixed purchase rate of 5.91% is 2 basis points higher than the 15-year refi rate. The 5/1 ARM purchase rate of 6.26% is 7 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Holding firm in the mid-6s
Here are the current mortgage rates today, Monday, August 31, 2026, according to the latest Zillow data:
#rate #current #mortgage #zillow
According to rates from the Zillow lender marketplace, current purchase mortgage rates are higher than refinance rates as of Monday, August 31, 2026.
Today, the 30-year fixed purchase rate is 6.55%, 4 basis points higher than the current refinance rate. The 15-year fixed purchase rate of 5.91% is 2 basis points higher than the 15-year refi rate. The 5/1 ARM purchase rate of 6.26% is 7 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Holding firm in the mid-6s
Here are the current mortgage rates today, Monday, August 31, 2026, according to the latest Zillow data:
#rate #current #mortgage #zillow



2 months ago
In 2025, 87% of all mortgage borrowers paid above the most competitive rate available to them, and 78.7% of refinance borrowers overpaid, typically costing them $3,343 a year, or $278 a month, according to Bankrate's Hidden Homeownership Tax research.
Refinancing isn't free. Expect closing costs of 2% to 5% of your new loan amount, and the savings only outweigh that cost once you cross your break-even point.
While a lower interest rate sounds tempting, keep an eye on fees – they can overwhelm your savings from lower monthly payments.
Despite the rise in interest rates in the last few years, refinancing may still make sense for some homeowners. If you're a first-time refinancer, though, you might have a lot of questions about what the process is like — and might also have picked up some misinformation. Let's dispel some common myths about mortgage refinancing.
Myth
#savings
Refinancing isn't free. Expect closing costs of 2% to 5% of your new loan amount, and the savings only outweigh that cost once you cross your break-even point.
While a lower interest rate sounds tempting, keep an eye on fees – they can overwhelm your savings from lower monthly payments.
Despite the rise in interest rates in the last few years, refinancing may still make sense for some homeowners. If you're a first-time refinancer, though, you might have a lot of questions about what the process is like — and might also have picked up some misinformation. Let's dispel some common myths about mortgage refinancing.
Myth
#savings

2 months ago
Better Mortgage and Coinbase (NASDAQ: $COIN) have moved their token-backed conforming mortgage into general availability, taking a product that closed its first Bitcoin-backed Fannie Mae loan in June into a broader nationwide offering for Coinbase One members.
The mortgages are originated and serviced by Better and powered by Coinbase, with the first lien structured under Fannie Mae guidelines as a standard conforming home loan. The crypto-backed portion sits alongside that mortgage, allowing qualified borrowers to pledge digital **** ets toward the down payment without first selling their holdings.
Coinbase One members approved for a Better loan can also receive a lender-funded credit equal to 1% of the mortgage value, capped at $10,000. Better said the credit now extends beyond the token-backed product to standard mortgages, home equity lines of credit and refinances.
More From Cryptoprowl:
MEXC TradFi Gala Concludes With Over 170,000 Registrations and $4.3 Billion in Daily Trading Volume
#Coinbase #first #loan
The mortgages are originated and serviced by Better and powered by Coinbase, with the first lien structured under Fannie Mae guidelines as a standard conforming home loan. The crypto-backed portion sits alongside that mortgage, allowing qualified borrowers to pledge digital **** ets toward the down payment without first selling their holdings.
Coinbase One members approved for a Better loan can also receive a lender-funded credit equal to 1% of the mortgage value, capped at $10,000. Better said the credit now extends beyond the token-backed product to standard mortgages, home equity lines of credit and refinances.
More From Cryptoprowl:
MEXC TradFi Gala Concludes With Over 170,000 Registrations and $4.3 Billion in Daily Trading Volume
#Coinbase #first #loan


2 months ago
Canada-headquartered Revolve Renewable Power Corp., a North American owner, operator and developer of power generation and digital infrastructure projects, announced it has entered into a MXN$450 million ($24 million) project-level, non-recourse-style financing facility with Banco Multiva, S.A., Institución de Banca Múltiple, Grupo Financiero Multiva. The facility is secured by project cash flows and contracted revenues and is expected to support the continued expansion of Revolve's distributed generation business in Mexico while enabling the company to recycle capital from existing operating and construction-stage ****** ets into future growth opportunities.Concurrent with the signing of the facility, Revolve expects to complete an initial drawdown of about MXN$128.8 million ($7.7 million) backed by operating ****** ets and projects currently under construction. This drawdown is anticipated to refinance a portion of Revolve's investment in these ****** ets and return capital to the corporate level, while maintaining ownership of the underlying projects and their long-term contracted revenue streams.Tania Ontiveros, CFO of Revolve, stated that the financing with Banco Multiva is a significant milestone and validation of the company's growing distributed generation business in Mexico. She expressed gratitude to the Banco Multiva team for their work and vision. Ontiveros highlighted that the facility provides the $24 million in long-term project-level capital for growth, and the initial drawdown of $7.7 million demonstrates the effectiveness of Revolve's capital recycling strategy. This involves recovering invested capital from developed and constructed ****** ets while retaining ownership and future cash flows.Tamara Caballero, CEO of Banco Multiva, noted that this financing marks a significant milestone for Multiva in advancing energy projects and reinforces its ability to deliver long-term financing solutions. She added that the institution is proud to contribute to the sector's growth through investment-encouraging structures that support innovative companies and create sustainable value for Mexico.The Multiva Facility is structured as a 14-year project financing facility, providing Revolve with access to long-term, non-dilutive capital. This capital is intended for the construction of new distributed generation (DG) projects, refinancing of operating ****** ets, and expansion of its portfolio of commercial and industrial solar projects in Mexico. The facility is structured through Revolve's Mexican subsidiaries, EPM Solar, S.A. de C.V. and RRP Business Solutions, S.A. de C.V., and comprises two equal MXN$225 million ($13.3 million) tranches.Key terms of the credit facility include a total size of MXN$450 million ($24 million), a term of 168 months (14 years) from drawdown, and a 24-month availability period. The facility's purpose is project-level debt financing of up to 75% of eligible distributed generation project expenditures, including de

2 months ago
Home equity loans, HELOCs and cash-out refinances are three popular ways to borrow money, using your home as collateral.
A cash-out refinance replaces your existing mortgage at today's rate, while home equity loans and HELOCs involve taking on a separate debt that leaves your current mortgage rate untouched.
With all three, the amount you can borrow will depend on the amount of equity (ownership stake) you have in your home.
If you bought or refinanced between 2020 and 2022 and locked in a primary mortgage rate below where rates sit today, a HELOC or home equity loan can protect that low rate. If your rate is at or above today's average, a cash-out refinance may actually improve your terms.
Homeowners are sitting on a record $18 trillion in home equity, but which option makes sense — and at what rate — depends on one thing: whether your current mortgage rate is better or worse than what's available today. "Choosing between a home equity loan, HELOC or cash-out refinance isn't a one-size-fits-all decision," says Tim Choate, founder and CEO of Red Awning, a platform for short-term vacation rental owners and property managers. "Each option has unique characteristics that align with different financial needs, risk profiles, and flexibility requirements."
#mortgage
A cash-out refinance replaces your existing mortgage at today's rate, while home equity loans and HELOCs involve taking on a separate debt that leaves your current mortgage rate untouched.
With all three, the amount you can borrow will depend on the amount of equity (ownership stake) you have in your home.
If you bought or refinanced between 2020 and 2022 and locked in a primary mortgage rate below where rates sit today, a HELOC or home equity loan can protect that low rate. If your rate is at or above today's average, a cash-out refinance may actually improve your terms.
Homeowners are sitting on a record $18 trillion in home equity, but which option makes sense — and at what rate — depends on one thing: whether your current mortgage rate is better or worse than what's available today. "Choosing between a home equity loan, HELOC or cash-out refinance isn't a one-size-fits-all decision," says Tim Choate, founder and CEO of Red Awning, a platform for short-term vacation rental owners and property managers. "Each option has unique characteristics that align with different financial needs, risk profiles, and flexibility requirements."
#mortgage
3 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
According to rates from the Zillow lender marketplace, current purchase mortgage rates are a mixed bag when compared to current refinance rates for Monday, August 24, 2026 — one is higher, one lower, and one is exactly the same. Shopping rates really matters.
The current 30-year fixed purchase rate is 6.64%, equal to the current refinance rate. The 15-year fixed purchase rate of 5.88% is 11 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.74% is 24 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Small moves in rates and fees
Here are the current mortgage rates today, Monday, August 24, 2026, according to the latest Zillow data:
#Monday
According to rates from the Zillow lender marketplace, current purchase mortgage rates are a mixed bag when compared to current refinance rates for Monday, August 24, 2026 — one is higher, one lower, and one is exactly the same. Shopping rates really matters.
The current 30-year fixed purchase rate is 6.64%, equal to the current refinance rate. The 15-year fixed purchase rate of 5.88% is 11 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.74% is 24 basis points higher than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Small moves in rates and fees
Here are the current mortgage rates today, Monday, August 24, 2026, according to the latest Zillow data:
#Monday


3 months ago
On August 11, Venture Global (NYSE:VG) reported its Q2 2026 earnings. While the text implies an established corporate history, Venture Global completed its IPO in January 2025, making this only its second Q2 report as a publicly traded company. The company posted its largest quarterly EBITDA ever, raised its full-year guidance for the second time this year, and lifted its dividend by triple digits. But the stock still carries one of the most lopsided sentiment profiles on the market, and that gap between the fundamentals and the trading floor is the real story here.
The headline number was $2.5 billion in consolidated adjusted EBITDA for the second quarter of 2026, a 79% jump from the $1.4 billion posted in the same quarter of 2025. Revenue followed the same trajectory, climbing 48% year over year to $4.6 billion, with $1.3 billion of that increase coming from higher sales volumes and the rest from better pricing. Venture Global shipped 466 TBtu of LNG in the quarter, up from 329 TBtu a year earlier, and net income attributable to common stockholders came in at $1.3 billion, up 266% from $368 million.
That kind of operating leverage let management raise 2026 EBITDA guidance to a range of $8.7 billion to $9.1 billion, up from the $8.2 billion to $8.5 billion range given back in May. The company also exported its 1,000th cargo, just four years after its first shipment in March 2022, while keeping 91% of its 2026 volumes contracted, up from 84% at the start of the year. On the balance sheet side, Venture Global refinanced $5.3 billion of debt and preferred equity during the quarter, part of more than $103 billion raised or refinanced since the company's founding, a move management says will cut annual interest and coupon costs by more than $100 million. The board followed that up by raising the quarterly dividend 122% to $0.04 per share.
Not everything in the release points in one direction. Management kept its EBITDA guidance range wider than usual, citing LNG price volatility tied to events in the Middle East, and said it would only narrow that range after the third quarter. The current guidance ****** umes a liquefaction fee of $12.50 to $13.50 per MMBtu for uncontracted 2026 cargoes, and every $1 swing in that fee moves EBITDA by $180 million to $210 million, a reminder of how exposed results still are to global gas prices.
Much of the company's future growth also sits years out. A final investment decision on the 10 MTPA CP2 expansion isn't expected until early 2027, with first production not until late 2028, while the Plaquemines expansion is targeting an FID in the first half of 2027 and Phase 1 output only starting in 2029. Of the roughly 85 MTPA of run-rate production expected once all three projects and their bolt-ons are online, only about 53 MTPA is currently committed under long- and medium-term contracts, leaving 32 MTPA still to be marketed. And despite the dividend increase, the payout remains modest at $0.04 per share, even as t
The headline number was $2.5 billion in consolidated adjusted EBITDA for the second quarter of 2026, a 79% jump from the $1.4 billion posted in the same quarter of 2025. Revenue followed the same trajectory, climbing 48% year over year to $4.6 billion, with $1.3 billion of that increase coming from higher sales volumes and the rest from better pricing. Venture Global shipped 466 TBtu of LNG in the quarter, up from 329 TBtu a year earlier, and net income attributable to common stockholders came in at $1.3 billion, up 266% from $368 million.
That kind of operating leverage let management raise 2026 EBITDA guidance to a range of $8.7 billion to $9.1 billion, up from the $8.2 billion to $8.5 billion range given back in May. The company also exported its 1,000th cargo, just four years after its first shipment in March 2022, while keeping 91% of its 2026 volumes contracted, up from 84% at the start of the year. On the balance sheet side, Venture Global refinanced $5.3 billion of debt and preferred equity during the quarter, part of more than $103 billion raised or refinanced since the company's founding, a move management says will cut annual interest and coupon costs by more than $100 million. The board followed that up by raising the quarterly dividend 122% to $0.04 per share.
Not everything in the release points in one direction. Management kept its EBITDA guidance range wider than usual, citing LNG price volatility tied to events in the Middle East, and said it would only narrow that range after the third quarter. The current guidance ****** umes a liquefaction fee of $12.50 to $13.50 per MMBtu for uncontracted 2026 cargoes, and every $1 swing in that fee moves EBITDA by $180 million to $210 million, a reminder of how exposed results still are to global gas prices.
Much of the company's future growth also sits years out. A final investment decision on the 10 MTPA CP2 expansion isn't expected until early 2027, with first production not until late 2028, while the Plaquemines expansion is targeting an FID in the first half of 2027 and Phase 1 output only starting in 2029. Of the roughly 85 MTPA of run-rate production expected once all three projects and their bolt-ons are online, only about 53 MTPA is currently committed under long- and medium-term contracts, leaving 32 MTPA still to be marketed. And despite the dividend increase, the payout remains modest at $0.04 per share, even as t

3 months ago
In 2025, 87% of borrowers paid higher than the best available mortgage rate for their credit profile — often because they didn't shop around, according to Bankrate's Hidden Homeownership Tax research.
Refinancing can lower your interest rate and cut thousands of dollars off the total cost of your loan.
Staying with your current lender out of convenience can mean paying a hidden "loyalty tax." Below, we break down when sticking with your lender pays off and when it costs you.
You can refinance with your current lender or switch to a new one — there's no rule requiring you to do either. The real question isn't whether you're allowed to change lenders (you are); it's whether it's the smarter move for your finances.
That decision comes down to more than just comparing your current lender's offer against the competition. Whether you're thinking of refinancing to tap into home equity or snag a lower rate, here's how to weigh the convenience of staying put against what you might be leaving on the table by not shopping around.
#rate #current #lender
Refinancing can lower your interest rate and cut thousands of dollars off the total cost of your loan.
Staying with your current lender out of convenience can mean paying a hidden "loyalty tax." Below, we break down when sticking with your lender pays off and when it costs you.
You can refinance with your current lender or switch to a new one — there's no rule requiring you to do either. The real question isn't whether you're allowed to change lenders (you are); it's whether it's the smarter move for your finances.
That decision comes down to more than just comparing your current lender's offer against the competition. Whether you're thinking of refinancing to tap into home equity or snag a lower rate, here's how to weigh the convenience of staying put against what you might be leaving on the table by not shopping around.
#rate #current #lender


3 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're not able to move to a new home or refinance to take advantage of the equity you have built up in your home, you're likely considering a home equity loan or a home equity line of credit. But, besides interest rates, how do you choose between a HELOC or a home equity loan?
The average HELOC adjustable rate is 7.16%, a new 2026 low, according to real estate data ******* ytics company Curinos.
The national average rate on a fixed-rate home equity loan is 7.35%, up slightly from its 2026 low of 7.31% in late June.
Both rates are based on applicants with a minimum credit score of 780 and a maximum combined loan-to-value ratio (CLTV) of less than 70%.
#heloc #you 're #rates
If you're not able to move to a new home or refinance to take advantage of the equity you have built up in your home, you're likely considering a home equity loan or a home equity line of credit. But, besides interest rates, how do you choose between a HELOC or a home equity loan?
The average HELOC adjustable rate is 7.16%, a new 2026 low, according to real estate data ******* ytics company Curinos.
The national average rate on a fixed-rate home equity loan is 7.35%, up slightly from its 2026 low of 7.31% in late June.
Both rates are based on applicants with a minimum credit score of 780 and a maximum combined loan-to-value ratio (CLTV) of less than 70%.
#heloc #you 're #rates



3 months ago
Radian Group (NYSE:RDN) delivered its Q2 2026 earnings on August 6, and the numbers marked a turning point. Total revenue jumped 93% year-over-year to $575 million, while net earned premiums more than doubled to $504 million, as the company's first full quarter with newly acquired specialty insurer Inigo showed up in the results. Book value per share climbed 8.5% to $36. With a forward P/E of just 7.19, the market doesn't seem convinced the growth will stick.
Radian's legacy mortgage insurance operation kept humming along on its own. New insurance written rose 14% year-over-year to $16.3 billion, and persistency held at 82%, pushing primary insurance in force to a record $284 billion. About half of that portfolio carries a mortgage rate of 5.5% or lower, so those borrowers have little reason to refinance away, which supports future premium income. Credit quality kept improving too. New defaults fell 9% from the prior quarter to roughly 12,400, and cures kept outpacing new defaults, dropping the portfolio default rate to 2.47%. That trend produced $20 million of favorable reserve development in the quarter, while the mortgage segment's expense ratio improved to 23% from 25% a year earlier.
The Inigo deal changed Radian's shape almost overnight. Specialty insurance now makes up roughly 50% of total revenue and 53% of net premiums earned, giving Radian a second, meaningfully sized engine. Capital returns kept flowing at the same time. Radian repurchased $76 million of stock in the quarter and about $50 million more so far in the third quarter, pushing year-to-date buybacks to $176 million, while Radian Guaranty sent a $200 million dividend up to the parent company.
The newly acquired specialty business is running into a tougher market. Management said competition is intensifying in property insurance and reinsurance and that rates continue to soften, a cyclical dynamic it says it expected when it underwrote the Inigo deal. The segment's net combined ratio came in at 98% for the quarter and 93% for the first half of 2026, elevated in part because Radian set aside reserves tied to the ongoing conflict in the Middle East, covering both expected and potential claims plus updated inflation **** umptions across the insured portfolio. Management now expects a combined ratio in the low 90s going forward as softer pricing works its way into results, versus the high 80s it had been tracking toward before the reserve charge. Radian is also mid-transition at the top, with CEO-elect Mike Weinbach set to take over from longtime CEO Rick Thornberry, and it still had $75 million outstanding on its revolving credit facility at quarter-end.
#million #quarter #specialty #Portfolio
Radian's legacy mortgage insurance operation kept humming along on its own. New insurance written rose 14% year-over-year to $16.3 billion, and persistency held at 82%, pushing primary insurance in force to a record $284 billion. About half of that portfolio carries a mortgage rate of 5.5% or lower, so those borrowers have little reason to refinance away, which supports future premium income. Credit quality kept improving too. New defaults fell 9% from the prior quarter to roughly 12,400, and cures kept outpacing new defaults, dropping the portfolio default rate to 2.47%. That trend produced $20 million of favorable reserve development in the quarter, while the mortgage segment's expense ratio improved to 23% from 25% a year earlier.
The Inigo deal changed Radian's shape almost overnight. Specialty insurance now makes up roughly 50% of total revenue and 53% of net premiums earned, giving Radian a second, meaningfully sized engine. Capital returns kept flowing at the same time. Radian repurchased $76 million of stock in the quarter and about $50 million more so far in the third quarter, pushing year-to-date buybacks to $176 million, while Radian Guaranty sent a $200 million dividend up to the parent company.
The newly acquired specialty business is running into a tougher market. Management said competition is intensifying in property insurance and reinsurance and that rates continue to soften, a cyclical dynamic it says it expected when it underwrote the Inigo deal. The segment's net combined ratio came in at 98% for the quarter and 93% for the first half of 2026, elevated in part because Radian set aside reserves tied to the ongoing conflict in the Middle East, covering both expected and potential claims plus updated inflation **** umptions across the insured portfolio. Management now expects a combined ratio in the low 90s going forward as softer pricing works its way into results, versus the high 80s it had been tracking toward before the reserve charge. Radian is also mid-transition at the top, with CEO-elect Mike Weinbach set to take over from longtime CEO Rick Thornberry, and it still had $75 million outstanding on its revolving credit facility at quarter-end.
#million #quarter #specialty #Portfolio


3 months ago
Sam Altman's push for a $1 trillion OpenAI IPO is on a collision course with SoftBank's need to repay a $40 billion bridge loan early next year, creating real tension around the deal's timing and valuation. All this tension matters for Microsoft (NASDAQ: MSFT) and Nvidia (NASDAQ: NVDA) shareholders, because both companies have meaningful OpenAI exposure on their balance sheets and in their narratives.
OpenAI filed a confidential S‑1 with the Securities and Exchange Commission in June and sits at a private post‑money valuation of around $852 billion after its March 2026 funding round. Reports put its 2025 revenue near $13 billion and its 2026 revenue near $2 billion per month, numbers that support a high valuation multiple, but not a stress‑free one. Altman has told investors he will not take the company public below $1 trillion, so the IPO must clear that bar, or the listing will stay on hold.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
To fund its expanded stake in OpenAI, SoftBank arranged an unsecured $40 billion bridge loan that matures in March 2027. Bridge paper exists to carry a borrower into a specific liquidity moment, which in this case lines up with a fourth-quarter 2026 or first-quarter 2027 window for OpenAI's IPO. If public markets balk at putting a $1 trillion valuation on the ChatGPT developer, SoftBank will either have to refinance at tougher terms or the company will have to accept a lower market cap -- an outcome that could ripple through its broader AI story.
Microsoft owns roughly 27% of OpenAI after committing about $13 billion to it a few years ago, and it's in talks to add a bit under $10 billion more to its stake in the new funding round. A trillion-dollar IPO would turn that stake into one of the most valuable strategic holdings in corporate history, which supports the long‑term AI infrastructure thesis around Azure and Copilot. The risk here is that SoftBank's need for speed will push OpenAI to go public before the economics of enterprise AI are stable, leaving Microsoft with headline valuation gains but more scrutiny on capital intensity and on an AI partner whose stock could swing hard.
#bridge #signal
OpenAI filed a confidential S‑1 with the Securities and Exchange Commission in June and sits at a private post‑money valuation of around $852 billion after its March 2026 funding round. Reports put its 2025 revenue near $13 billion and its 2026 revenue near $2 billion per month, numbers that support a high valuation multiple, but not a stress‑free one. Altman has told investors he will not take the company public below $1 trillion, so the IPO must clear that bar, or the listing will stay on hold.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
To fund its expanded stake in OpenAI, SoftBank arranged an unsecured $40 billion bridge loan that matures in March 2027. Bridge paper exists to carry a borrower into a specific liquidity moment, which in this case lines up with a fourth-quarter 2026 or first-quarter 2027 window for OpenAI's IPO. If public markets balk at putting a $1 trillion valuation on the ChatGPT developer, SoftBank will either have to refinance at tougher terms or the company will have to accept a lower market cap -- an outcome that could ripple through its broader AI story.
Microsoft owns roughly 27% of OpenAI after committing about $13 billion to it a few years ago, and it's in talks to add a bit under $10 billion more to its stake in the new funding round. A trillion-dollar IPO would turn that stake into one of the most valuable strategic holdings in corporate history, which supports the long‑term AI infrastructure thesis around Azure and Copilot. The risk here is that SoftBank's need for speed will push OpenAI to go public before the economics of enterprise AI are stable, leaving Microsoft with headline valuation gains but more scrutiny on capital intensity and on an AI partner whose stock could swing hard.
#bridge #signal

3 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
According to rates from the Zillow lender marketplace, current purchase mortgage rates are lower than current refinance rates for Monday, August 10, 2026.
The current 30-year purchase fixed rate today is 6.51%, 13 basis points lower than the current refinance rate. The 15-year fixed purchase rate of 6.01% is 2 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.37% is 13 basis points lower than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Revealing the wide gaps among rates and fees
Here are the current mortgage rates today, Monday, August 10, 2026, according to the latest Zillow data:
#current #purchase #lower #points
According to rates from the Zillow lender marketplace, current purchase mortgage rates are lower than current refinance rates for Monday, August 10, 2026.
The current 30-year purchase fixed rate today is 6.51%, 13 basis points lower than the current refinance rate. The 15-year fixed purchase rate of 6.01% is 2 basis points lower than the 15-year refi rate. The 5/1 ARM purchase rate of 6.37% is 13 basis points lower than the 5/1 refi rate.
Read more: Weekly survey of mortgage lenders with the lowest rates: Revealing the wide gaps among rates and fees
Here are the current mortgage rates today, Monday, August 10, 2026, according to the latest Zillow data:
#current #purchase #lower #points



3 months ago
Household affordability challenges are leading some consumers to consider refinancing their auto loans to save money on monthly payments.
Stephanie Roberts, director of auto products at PenFed Credit Union, told FOX Business that expanded access to credit terms has allowed consumers to more easily check the rates available to them as they consider refinancing.
"I think consumers from a credit education standpoint are more educated than ever on the health of their credit, so they're taking out those refinances," Roberts said, noting that many banking and personal finance apps give consumers access to their credit scores.
"A lot of lenders, PenFed included, are allowing for consumers to check their rate by way of soft pull … without any impact to their credit score or promises that I'm going to go through this process. And I think that's why a lot of people are now seeing that refinance is a fruitful option for them, where it hadn't been like that in the past."
Average New Car Payment Reaches All-time High As Affordability Issues Persist
#affordability #consider #check
Stephanie Roberts, director of auto products at PenFed Credit Union, told FOX Business that expanded access to credit terms has allowed consumers to more easily check the rates available to them as they consider refinancing.
"I think consumers from a credit education standpoint are more educated than ever on the health of their credit, so they're taking out those refinances," Roberts said, noting that many banking and personal finance apps give consumers access to their credit scores.
"A lot of lenders, PenFed included, are allowing for consumers to check their rate by way of soft pull … without any impact to their credit score or promises that I'm going to go through this process. And I think that's why a lot of people are now seeing that refinance is a fruitful option for them, where it hadn't been like that in the past."
Average New Car Payment Reaches All-time High As Affordability Issues Persist
#affordability #consider #check


3 months ago
When longtime mortgage loan officer Hillary Moussali worked at a local Chase bank branch, an elderly man walked in holding a mail advertisement with the bank's name, promising "super low" refinancing rates. Moussali took one look at the mailer and knew it wasn't sent from Chase.
"I read the fine print, which he probably couldn't even see," said Moussali, who worked as a loan officer for Chase from 2016 to 2021. "If he had just called the 1-800 number, who knows what they would have charged him."
There's a good chance they would've charged him thousands of extra dollars in unnecessary costs, according to new Bankrate research that finds a costly "Seniority Tax" is consistently imposed on older refinancers. The Seniority Tax is a targeted example of a wider Hidden Homeownership Tax revealed by our research — the systemic overpayment by American mortgage borrowers.
Read more about how the Seniority Tax plays out, along with similar overpayment consequences for other groups of people.
Full report
#worked #charged
"I read the fine print, which he probably couldn't even see," said Moussali, who worked as a loan officer for Chase from 2016 to 2021. "If he had just called the 1-800 number, who knows what they would have charged him."
There's a good chance they would've charged him thousands of extra dollars in unnecessary costs, according to new Bankrate research that finds a costly "Seniority Tax" is consistently imposed on older refinancers. The Seniority Tax is a targeted example of a wider Hidden Homeownership Tax revealed by our research — the systemic overpayment by American mortgage borrowers.
Read more about how the Seniority Tax plays out, along with similar overpayment consequences for other groups of people.
Full report
#worked #charged

3 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
When you refinance your mortgage, you replace your existing home loan with a new one for the same property. There are many reasons to refinance your home loan, from locking in a lower mortgage interest rate to tapping into your equity. Understanding the process can help you prepare and save money along the way.
First things first: Ensure you're financially prepared to refinance.
Check your credit score and see if there are ways to improve it before refinancing. Your credit score plays a big role in your ability to get approved and will influence your interest rate.
You should also calculate your debt-to-income ratio (DTI) and consider paying down some debts, because a lower DTI can help you more easily qualify for your loan.
#loan #first #lower #interest
When you refinance your mortgage, you replace your existing home loan with a new one for the same property. There are many reasons to refinance your home loan, from locking in a lower mortgage interest rate to tapping into your equity. Understanding the process can help you prepare and save money along the way.
First things first: Ensure you're financially prepared to refinance.
Check your credit score and see if there are ways to improve it before refinancing. Your credit score plays a big role in your ability to get approved and will influence your interest rate.
You should also calculate your debt-to-income ratio (DTI) and consider paying down some debts, because a lower DTI can help you more easily qualify for your loan.
#loan #first #lower #interest


3 months ago
If you bought a home within the last few years, you might face some mortgage rate regrets. But as everyday people have told me, life doesn't wait for the market. You needed a home at the time you bought it, not before or after when rates were different.
While rates are still relatively high, they've fallen from their peak a few years ago. And if you're looking for a lower monthly payment, it's worth checking if you're paying more than today's average mortgage rate. If you are, a refinance may be on the table.
The math can be complicated, with interest rates, closing costs and amortization schedules to consider. And you can't always count on your lender to do this math for you.
But crunching the numbers is key to making the right refi move. Here's how three homeowners decided it was worth it for them.
When Bob Bradley, a 44-year-old publicist based in Orange County, Calif., married his wife, Kristy Andre, they needed a house to fit their blended family. He sold his 2%-rate condominium to fund a down payment on their family home. The couple bought at a 6.125% rate in June 2024.
#bought #payment
While rates are still relatively high, they've fallen from their peak a few years ago. And if you're looking for a lower monthly payment, it's worth checking if you're paying more than today's average mortgage rate. If you are, a refinance may be on the table.
The math can be complicated, with interest rates, closing costs and amortization schedules to consider. And you can't always count on your lender to do this math for you.
But crunching the numbers is key to making the right refi move. Here's how three homeowners decided it was worth it for them.
When Bob Bradley, a 44-year-old publicist based in Orange County, Calif., married his wife, Kristy Andre, they needed a house to fit their blended family. He sold his 2%-rate condominium to fund a down payment on their family home. The couple bought at a 6.125% rate in June 2024.
#bought #payment


4 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
With the SAVE program ending and major changes for federal student loan borrowers this year, now could be a good time to review your repayment plan — which may also include refinancing.
Refinancing your student loans can help you score a lower interest rate or consolidate multiple monthly payments into one. But if you're refinancing federal student loans, you could also lose some valuable protections and forgiveness opportunities.
The first step is finding a student loan refinance lender that works with your budget and timeline. To help you get started, here are some top options today.
Read more: How to refinance your student loans
#refinance
With the SAVE program ending and major changes for federal student loan borrowers this year, now could be a good time to review your repayment plan — which may also include refinancing.
Refinancing your student loans can help you score a lower interest rate or consolidate multiple monthly payments into one. But if you're refinancing federal student loans, you could also lose some valuable protections and forgiveness opportunities.
The first step is finding a student loan refinance lender that works with your budget and timeline. To help you get started, here are some top options today.
Read more: How to refinance your student loans
#refinance



