7 hours ago
Amanda Peet noticed something unusual months before learning she had breast cancer.
During an interview on Today on Thursday, October 1, Peet, 54, described the change she first felt about six months before her diagnosis.
"I was in my closet, I was probably putting something on and I felt a weird — it just didn't feel like normal skin, but it wasn't the frozen pea that everybody talks about," The Whole Nine Yards star said during her conversation with the show's coanchor Savannah Guthrie.
That unfamiliar feeling prompted Peet to seek medical attention. At the time, she believed the results meant everything was fine.
"I went and I even got an MRI and then they sent me away," she said. "So I thought I had a clean bill of health, but they were actually watching it."
#felt



8 hours ago
Bringing Up Bates alum Gil Bates suffered a heart attack after experiencing unusual chest sensations and occasional jaw pain for two weeks
Doctors discovered an 80% blockage in his LAD artery and a 95% blockage in his RCA artery, leading to the placement of two stents
Gil's wife, Kelly Jo Bates, said he is heading home and will begin cardiac therapy next week
Gil Bates is recovering after suffering a heart attack.
The Bringing Up Bates alum, 61, was hospitalized earlier this week after experiencing an unusual sensation in his chest for approximately two weeks, his wife, Kelly Jo Bates, revealed in an Instagram post on Wednesday, Sept. 30.
#chest #weeks


9 hours ago
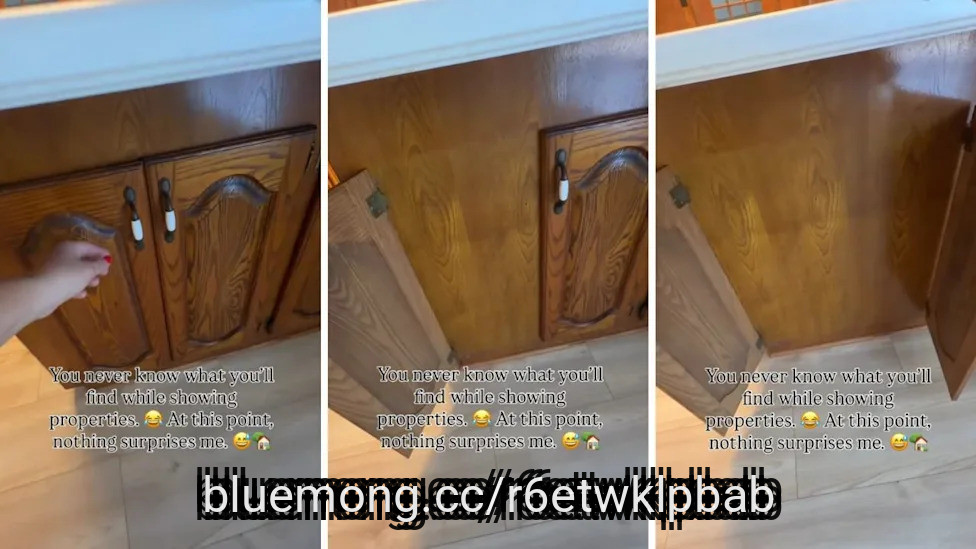
A realtor from Texas is having a viral moment on Instagram for showing that there was nothing behind the kitchen cabinet doors of a house that she was selling.
The video also uses the trending "I hope you're hungry, for nothing!" audio, adding to the post's humor, with commenters making various puns and jokes about the peculiar lack of a cabinet on the post.
Heather Kerr is a Houston-based realtor who also creates content on social media. A lot of her content is related to her work as a realtor, but she also posts about her life and religion.
Her first viral moment happened recently, thanks to a video in which she showed the very unusual kitchen cabinet door with no actual cabinet behind it in a Pasadena house that she was selling.
The video, posted on September 22nd, has since garnered nearly 2 million views on Instagram, as well as 100,000 likes and over 500 comments.
#Instagram #viral #nothing #behind


11 days ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
11 days ago
Marathon Petroleum Corporation (NYSE:MPC) has substantially outperformed the wider market this year, supported by an unusually sharp surge in global refining margins as the prolonged Iran crisis has significantly tightened global refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle
11 days ago
Valero Energy Corporation (NYSE:VLO) has been on a strong rally, posting gains of over 140% since the beginning of 2026. The strong performance is fuelled by an unusually sharp surge in global refining margins as the ongoing disruptions have significantly reduced the world's refining capacity and tightened supplies of gasoline, diesel, and jet fuel.
While there are now investor concerns that the stock may have topped out, Wall Street sees further upside ahead. On September 14, Morgan Stanley ******* yst Joe Laetsch significantly boosted the firm's price target on VLO from $255 to $411, while maintaining an 'Equal Weight' rating on the shares. The revised target implies an upside of almost 4% from the current levels and even exceeds the stock's all-time high of just under $400 per share.
The higher price objective is supported by the possibility that Valero can translate the favorable refining environment into material earnings and cash flows. The company did exactly that in the second quarter, when it posted its highest-ever Q2 profit and topped Wall Street expectations.
It seems like the high-margin environment is here to stay following a fresh wave of attacks between the US and Iran. Even if the attacks stop and a potential peace agreement is achieved, the damaged or idled refineries in the Middle East are likely to take some time to return to full operations, keeping refined-fuel markets relatively tight. Notably, the supply disruptions also extend beyond the troubled region, as a recent series of Ukrainian strikes on Russian refineries has further constrained global refining capacity.
Valero's FCC Unit optimization project at its St. Charles Refinery will allow it to capitalize even further on the high-priced environment. Expected to be completed in the third quarter, the $230 million initiative will help enhance the facility's ability to produce high-value products.
#even #environment #wall #strong

12 days ago
TIPS held in taxable brokerage accounts generate phantom income from inflation-adjusted principal, potentially pushing up to 85% of Social Security benefits into taxable income.
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable
12 days ago
Interested in Cardinal Health, Inc.? Here are five stocks we like better.
Cardinal Health expects growth to normalize in fiscal 2027 after fiscal 2026 benefited from unusually strong specialty growth, customer onboarding, acquisitions and solid healthcare utilization. Management said all five operating segments delivered double-digit earnings growth in fiscal 2026.
The company is expanding its specialty and at-home healthcare strategy through MSO platforms, bolt-on acquisitions and diabetes-related deals. Strive Medical has closed, while the AdaptHealth diabetes acquisition is expected to close in the second half of fiscal 2027, strengthening Cardinal's continuous glucose monitoring business.
Cardinal is prioritizing automated, small-parcel distribution of higher-value at-home products and plans to add three more automated distribution centers. Management also said cash flow was strong in fiscal 2026, putting the company about 90% of the way toward its previously announced $10 billion objective.
Cardinal Health Earnings: Can Perfection Get Priced In Twice?
#acquisitions

13 days ago
This story was originally published on Supply Chain Dive. To receive daily news and insights, subscribe to our free daily Supply Chain Dive newsletter.
TJX Companies is confident in navigating weather-related events such as El Niño due to its warehouse distribution model, CEO Ernie Herrman said in a Q2 earnings call on Aug. 19.
Herrman said since the company keeps its liquidity and shipping out of its warehouses, it has better control than traditional retailers. Inventory doesn't need to go straight to the stores if the off-price retailer thinks there's going to be an unusual weather pattern in a certain region, he added.
"[T]his is a benefit of our model where we stage goods in our warehouses versus goods at most brick-and-mortar retailers come into the warehouse and have to go out," Herrman told **** ysts. He added that the company's "planning organization is really good at reacting to any wild swings in weather or natural disasters or any of those red flags."
Off-price retailers and classic retailers tend to have different supply chain models when it comes to how they manage their inventory, but it's not one-size fits all, Dheera Anand, a partner at Bain and Co., told Supply Chain Dive in an interview. The supply chain strategy Hermann described in TJX's earnings call is known as the hold and flow, or staged, model, Anand said.
#supply

13 days ago
SEIC provides investment processing, management, and operational platforms for private banks, financial advisors, institutional investors, and financial managers. SEIC's second-quarter fiscal 2026 report showed revenue of $641.6 million (a 14.7% year-over-year gain), adjusted per-share earnings of $1.66 (a 38% rise), $207 million in operating income (a 36% jump) – all of which were quarterly records – and the company has nearly $400 million in cash for more growth ahead.
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock


13 days ago
There are plenty of tried-and-true strategies one can follow to build wealth, like staying debt-free and investing early for retirement. But sometimes it's worth it to go off the beaten path and try quirky money habits.
Are these habits kind of unusual? Yes. Will everyone else practice them? Probably not. Do they work? Also, yes.
An episode of Smart Money Happy Hour hosted by financial experts Rachel Cruze and George Kamel took a closer look at the most unusual money habits worth trying out to get ahead financially.
Here are 10 weird habits that can help you become rich.
This approach is not likely to be popular with most people, but Kamel said working more hours every week is something you can control especially if you're trying to get out of debt.
#money #unusual #happy
14 days ago
Oddity Tech Ltd. (NASDAQ:ODD) reported second-quarter revenue of approximately $181 million on September 9, down 25% from $241 million a year earlier. Company-defined non-GAAP adjusted EBITDA fell to $13 million from $70 million. This measure excludes net financial income, income taxes, depreciation and amortization, share-based compensation, and certain unusual or nonrecurring items from net income.
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects


14 days ago
Heavy volume in Apple Inc. (AAPL) puts expiring in one year with a strike price 4% lower shows that institutional investors are bullish on AAPL. In addition, this short-put play provides a 6.76% one-year yield.
AAPL is trading at $322.96 midday on Wednesday, Sept. 16. This is off a recent peak of $340.08 on July 28, but up from a trough of $302.25 on Aug. 12.
Adobe Stock is Dirt Cheap After Its Recent Results - What's the Best Way to Play ADBE?
Why Wall Street Could Be Pricing This GE Stock Option Spread Incorrectly
Unusual Out-of-the-Money Put Option Volume in Amazon Shows Investors Bullish on AMZN
#bullish #play #recent #year

14 days ago
By Michael S. Derby
Sept 16 (Reuters) - Surging government bond yields are raising credit costs across the U.S. economy and could factor into Federal Reserve monetary policy deliberations, but ***** ysts see the central bank resisting any explicit call from the Trump administration to bail out the market.
The focus on the Fed's possible involvement comes as Treasury Secretary Scott Bessent has taken an unusually activist role in trying to tamp down rising yields he considers to be misaligned with the U.S. economic outlook.
Bessent's campaign, which saw the expansion of a key debt buyback operation last week, is foundering, as the 10-year Treasury note rose above 5% to its highest since 2007. He shrugged the move off as owing to "global issues" on Tuesday as he arrived for a congressional hearing.
Treasury's bond market travails are raising questions whether the Fed might be requested to buy government debt to reduce supply, which could cap or lower yields, in turn easing government and private sector borrowing costs.
#government #treasury #bond #debt
14 days ago
With the market coming into a seasonally weak time of year, Bear Call Spreads could be an interesting trade to consider.
A bear call spread is a type of vertical spread, meaning that two options within the same expiry month are being traded.
Adobe Stock is Dirt Cheap After Its Recent Results - What's the Best Way to Play ADBE?
Why Wall Street Could Be Pricing This GE Stock Option Spread Incorrectly
Unusual Out-of-the-Money Put Option Volume in Amazon Shows Investors Bullish on AMZN
#spread #option #bear #call

14 days ago
Britain's royal family has taken the unusual step of publicly challenging claims made by Princess Diana's brother, Earl Spencer, in his upcoming memoir.
Departing from the monarchy's traditional "never complain, never explain" approach, Buckingham Palace responded Wednesday to Spencer's recollection of a phone call between himself and King Charles, in the wake of Diana's death in 1997. According to Spencer, the call took place after Spencer objected to Prince William and Prince Harry, then 15 and 12, walking behind their mother's coffin at her funeral.
In an excerpt from the book Swan Song: Diana, My Sister published by Britain's Daily Mail, Spencer wrote, "He unleashed down the phone what I have always taken to be his pent-up contempt for Diana, and his horror that the world was so bowled over by her death. 'Rest ****** ured,' he hissed, 'we'll forget her soon enough.'"
While the palace didn't directly address whether the comment was made, the statement questioned the reliability of Spencer's recollection, saying, "While we do not comment on books as a matter of principle, His Majesty is mindful that the pain of fraternal grief can cloud reason, affect judgment and color memory in ways others do not recognize, even many years after such a loss."
The statement echoes the palace's reaction to claims made by Harry and Meghan Markle during their 2021 interview with Oprah Winfrey that an unnamed royal had made a remark about their son's skin color before he was born and that the monarchy failed to help a suicidal Meghan. A response issued on behalf of Queen Elizabeth II at that time said that "recollections may vary."
#spencer #meghan #palace #taken

15 days ago
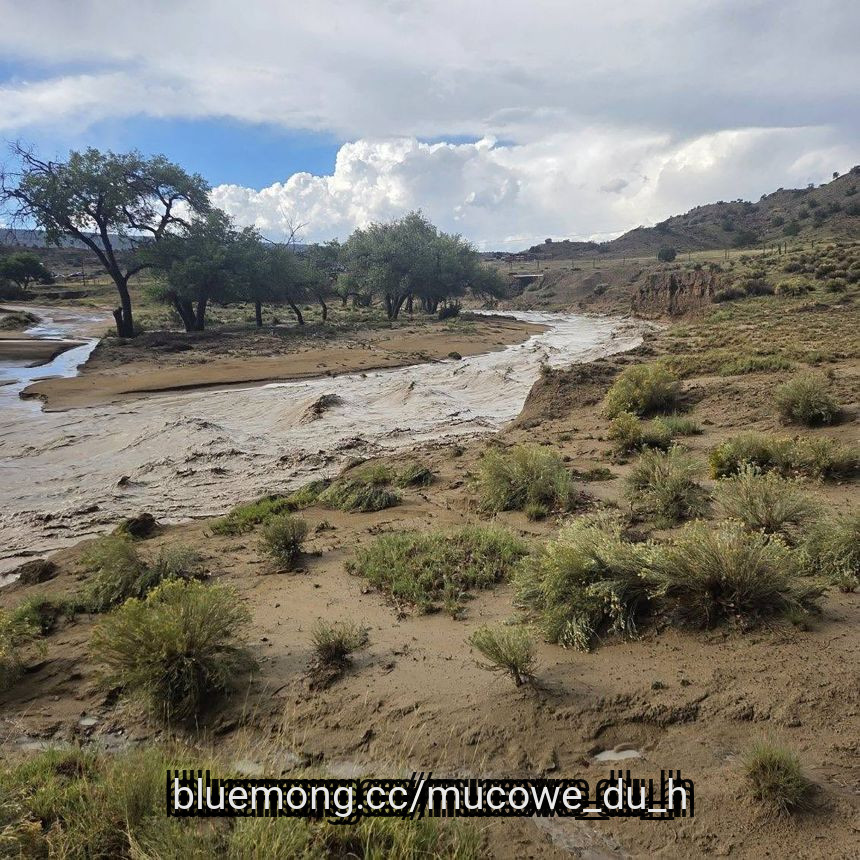
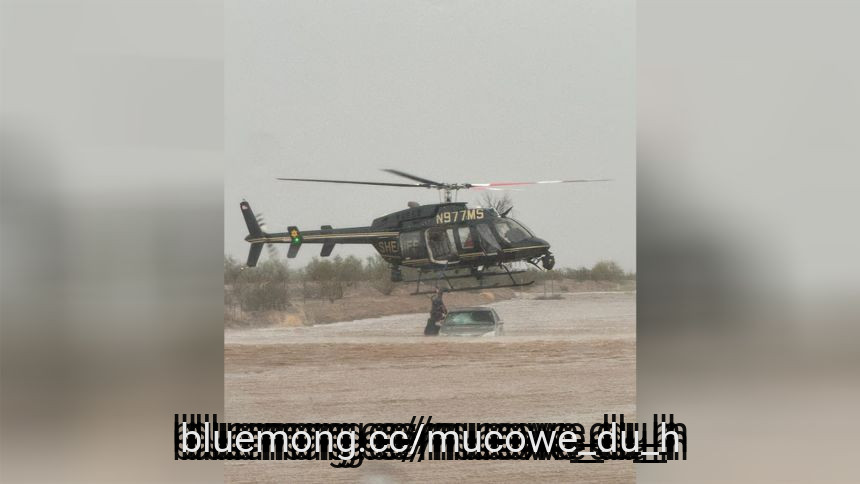
The Southwest faces a barrage of intense rain this week as rounds of storms are tapping into unusually moisture-rich air being pulled north from Baja California, after flash flooding in New Mexico killed three people early Wednesday.
Officers responded at around 12:30 a.m. local time to a report of three people washed away by flooding near Newcomb, New Mexico, on the Navajo Nation. Police discovered two adults and one juvenile on scene, the Navajo Police Department said in a statement. All three were ****** ounced dead. The department declined to provide further details about the deaths when contacted by CNN, citing concern for the family’s privacy.
🌧️ Get your local forecast from the CNN Weather app
Rainfall over Newcomb began Tuesday afternoon around 4:30 p.m. and lingered intermittently until just after midnight. The area saw around 0.5 inches to 1 inch of rain in total, with most of it falling within an hour Tuesday evening.
Wednesday’s storms prompted a rare Level 3 of 4 risk of flooding rainfall for parts of Arizona and New Mexico, including Phoenix and Tucson. Phoenix had not faced a flood risk that high since 2022.
#flooding #around #wednesday #navajo

15 days ago
Netflix (NFLX) trades at about $80, and its own options put a price on how far that can travel over the twelve months ahead: a floor near $54.21 and a ceiling near $119. The options market is charging nothing unusual for that range. Ordinary, for Netflix, already means a range wide enough to take a third of your money.
Your $10,000 Stake Could Be Worth $6,750 Or $14,800 A Year Out
From today's price the ceiling is about 48% higher and the floor about 33% lower. A $10,000 stake could end the year near $6,750 or near $14,800. The upside is larger in dollars for a mechanical reason: a share price stops at zero and has no top.
Those bounds are odds rather than a forecast: roughly a two-in-three chance of finishing between them, and about a 16% chance of ending beyond each one. Nothing in that says which way. It says how much room a holder has to give, and Netflix has needed that room before.
Netflix Just Had A Year Almost This Volatile
#year #price #floor #ceiling

15 days ago
Today, Amazon Inc. (AMZN) put options at a $220 strike expiring in 45 days (Oct. 30) have had unusually heavy volume. That strike is 11.5% below today's trading price, and investors collect a 1.45% short-put yield, a bullish play.
AMZN is trading at $248.77 in midday trading on Tuesday, Sept. 15. That's well off its recent peak of $284.02 on Aug. 3, just after its July 30 Q2 earnings release.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#week #strike


15 days ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total ******* ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#quarter #spending #bought #engine

15 days ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather

15 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
15 days ago
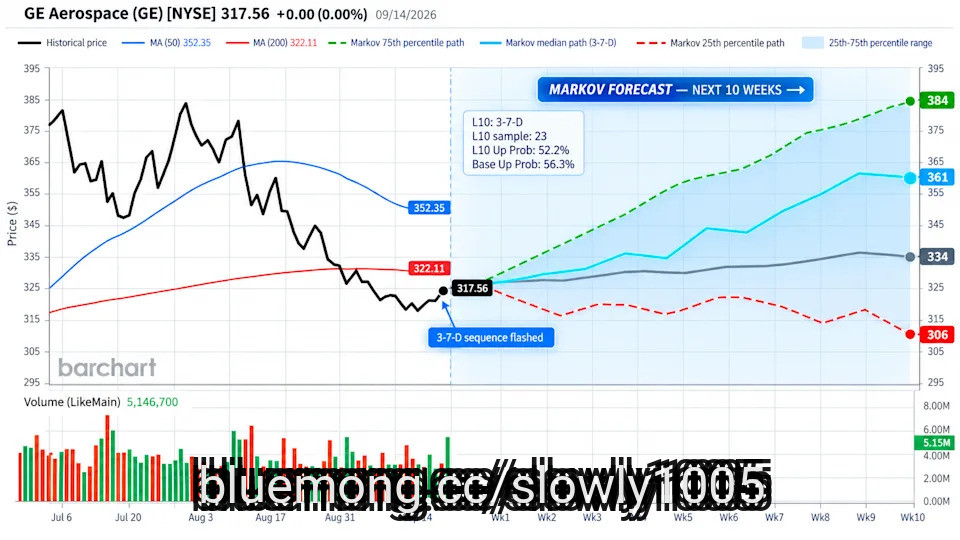
Browsing through the available strike selections for month-of-October bull call spreads, it's impossible to ignore one glaring idea for GE Aerospace (GE). With a maximum payout of 222.58% in exchange for a net debit (cash outlay) of $310, the risk-reward profile seems unusually favorable. Of course, Wall Street isn't in the business of giving traders a free lunch — and that's where the problem with GE stock lies.
While the breakeven price of $333.10 represents "only" a 5% lift from the current spot price, the implied probability of this threshold (derived from the Black-Scholes family of calculations) sits at 29.6%. Again, that's just to break even. If you want to be fully profitable, GE Aerospace stock must trigger the $340 second-leg strike price.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart **** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#price #call #unusually #browsing
15 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
15 days ago
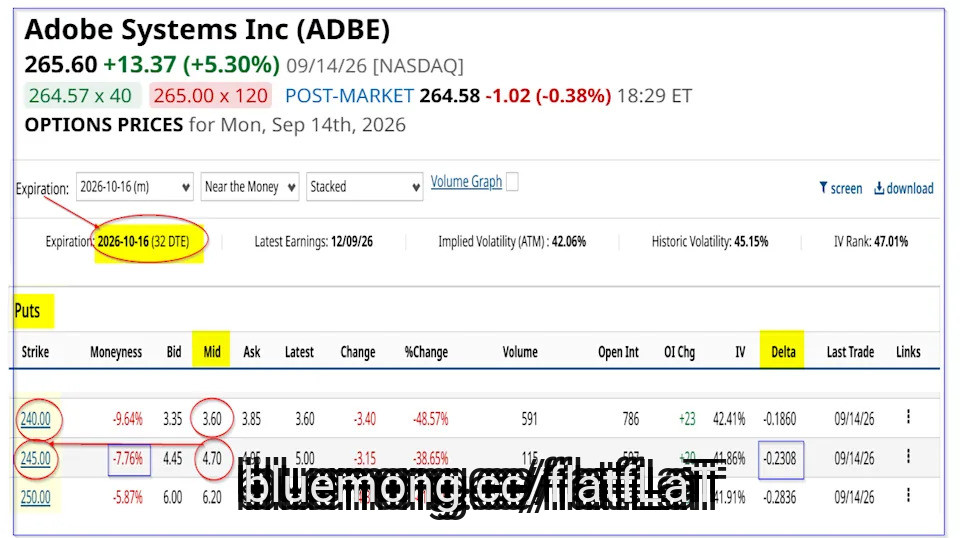
Adobe Systems (ADBE) reported strong revenue and free cash flow results for fiscal Q3 on Sept. 10. Free cash flow (FCF) margins were over 40% over the past year. ADBE stock is dirt cheap now at less than 10x earnings and 10x trailing 12-month (TTM) FCF. As a result, shorting ADBE puts and put credit spreads work well for value investors.
ADBE closed at $265.60 on Monday, Sept. 14, up from a recent trough of $248.83 on Sept. 10 before the earnings release. However, the chart below from Barchart shows ADBE has been flat for the past month and a half.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
What Old-School Chart ****** ysis and Gamma Exposure Tell Us About QQQ This Fed Week
Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT
#week #cash #flow


15 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na

15 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st

15 days ago
If you bought Meta Platforms (META) for its advertising engine, the engine still runs: revenue rose 28% year over year in the June 2026 quarter, and its Advantage+ automated campaigns keep growing. What has changed is where the cash goes afterward. The question for a holder is whether Meta is still the business you bought.
Over the twelve months through the June 2026 quarter, capital spending took 39.1% of revenue, against 18.5% across Meta's history. That money buys servers, data centers and network infrastructure. In late July 2026, Meta also announced a venture with BlackRock to develop a 1 gigawatt data center in El Paso, Texas. The plan is to keep going: management narrowed its 2026 capital-spending range by lifting the bottom of it.
Less cash is left over. TTM free-cash-flow margin is 18.0%, against 32.8% across its history, so on each dollar of sales Meta keeps a little more than half the free cash it used to.
Borrowing fills part of the gap. Debt has risen to 25.0% of total **** ets, against a historical 7.0%, and the CFO says Meta is adding more debt to lower its cost of capital. Meta still holds more cash and marketable securities than debt.
Together, those three readings are the most unusual combination Meta has shown in 14 years. Taken with the 2026 spending floor that management has raised, the combination reads as a change in the business rather than one quarter of noise.
#meta #cash

15 days ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year
15 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi