1 day ago
Trump’s political lieutenants are trying to shift the blame onto lazy candidates, but Republicans on Capitol Hill and beyond are not buying it.
Attendees react at the conclusion of concession speeches during a midterm election night watch party with Ohio Republican candidates in Columbus, Ohio, on Nov. 3, 2026. | Jon Cherry/Getty Images
11/04/2026 5:55 AM EST
#ohio #republican #cherry
Attendees react at the conclusion of concession speeches during a midterm election night watch party with Ohio Republican candidates in Columbus, Ohio, on Nov. 3, 2026. | Jon Cherry/Getty Images
11/04/2026 5:55 AM EST
#ohio #republican #cherry

2 days ago
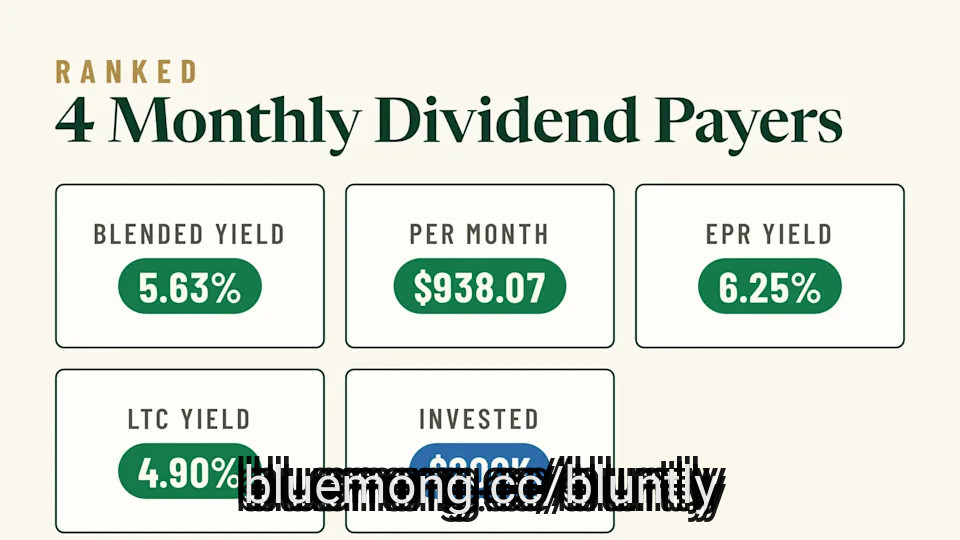
LTC and Realty Income pay monthly dividends yielding 4.90% and 5.61%, generating roughly $204 and $234 per month on a $50,000 investment.
EPR Properties yields 6.25% with an AFFO payout ratio of just 60%, but its top 10 tenants control 68% of base rent.
Across all four holdings, $200,000 invested produces about $938 a month, aligning paydays with recurring household bills.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Rent, utilities, insurance premiums, and groceries all come due every month, but most dividend stocks pay only four times a year. If you live off a portfolio, that gap means holding extra cash or selling shares to cover the months with no payment. Monthly-paying stocks line up payments with bills.
#income #monthly #bills
EPR Properties yields 6.25% with an AFFO payout ratio of just 60%, but its top 10 tenants control 68% of base rent.
Across all four holdings, $200,000 invested produces about $938 a month, aligning paydays with recurring household bills.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Rent, utilities, insurance premiums, and groceries all come due every month, but most dividend stocks pay only four times a year. If you live off a portfolio, that gap means holding extra cash or selling shares to cover the months with no payment. Monthly-paying stocks line up payments with bills.
#income #monthly #bills

28 days ago
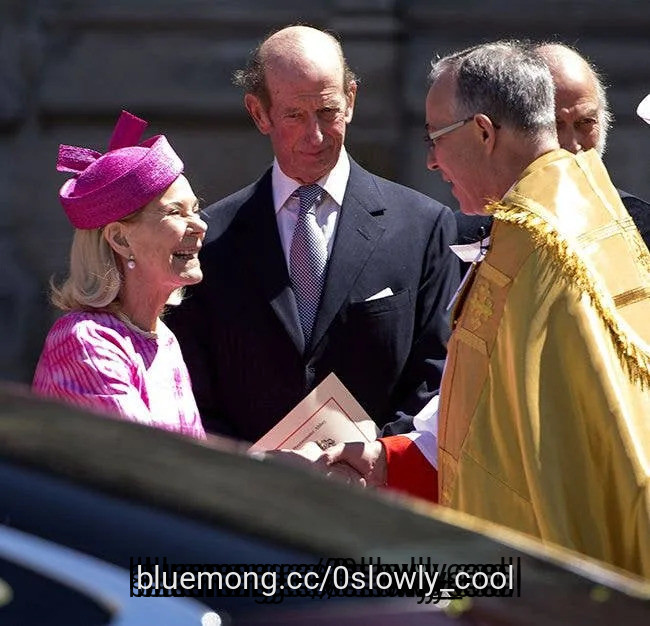
The Duke Of Kent is mourning a tragic personal loss ahead of his birthday.
The late Queen's cousin Prince Edward, who turns 91 on Friday, is grieving the loss of Nicholas Turnbull, who died on 16 September aged 63.
He had been appointed a Lieutenant of the Royal Victorian Order by King Charles just two days earlier.
Nicholas started working for the Duke in 2019, according to reports, and joined him in the Royal Box at Wimbledon in July.
The Duke of Kent at Wimbledon earlier this year (@ Getty)
#nicholas #earlier
The late Queen's cousin Prince Edward, who turns 91 on Friday, is grieving the loss of Nicholas Turnbull, who died on 16 September aged 63.
He had been appointed a Lieutenant of the Royal Victorian Order by King Charles just two days earlier.
Nicholas started working for the Duke in 2019, according to reports, and joined him in the Royal Box at Wimbledon in July.
The Duke of Kent at Wimbledon earlier this year (@ Getty)
#nicholas #earlier
29 days ago
When a caller mentioned that they are thinking about adding to their position in Simon Property Group, Inc. (NYSE:SPG) during the October 2 episode of Mad Money, Jim Cramer commented:
I think you're absolutely right... I want you to add to the Simon Property Group... What a great man he (David Simon, previous CEO) was, and he built a fabulous company, and you should buy more of it.
A September 8 question about buying Simon Property Group led Cramer to bring another real estate stock into the conversation.
Simon Property Group, Inc. (NYSE:SPG) reported second-quarter real estate funds from operations of $3.29 per diluted share, up 7.9% year-over-year. Domestic property net operating income increased 8.5%. Occupancy at its U.S. malls and premium outlets remained at 96%, while base minimum rent increased 6.3% to $62.42 per square foot. Management raised its full-year real estate funds from operations outlook to $13.20 - $13.30 per share. These figures show rent and property-income growth without requiring an increase in occupancy. Leasing activity also remained substantial. During the earnings call, management reported signing approximately 1,200 leases covering more than 4.8 million square feet, with new-deal volume increasing more than 20%.
Stable occupancy does not mean every tenant is healthy. Simon Property Group, Inc. (NYSE:SPG) absorbed approximately one million square feet of ****** e returned through retailer bankruptcies during the quarter. Management said it successfully re-leased the ****** e, helping maintain occupancy. That shows leasing strength, but also a reminder of the work required to preserve rental income. Additional retailer failures could bring more vacancies and replacement costs, even when demand for the properties remains sound.
#occupancy #NYSE #management #estate
I think you're absolutely right... I want you to add to the Simon Property Group... What a great man he (David Simon, previous CEO) was, and he built a fabulous company, and you should buy more of it.
A September 8 question about buying Simon Property Group led Cramer to bring another real estate stock into the conversation.
Simon Property Group, Inc. (NYSE:SPG) reported second-quarter real estate funds from operations of $3.29 per diluted share, up 7.9% year-over-year. Domestic property net operating income increased 8.5%. Occupancy at its U.S. malls and premium outlets remained at 96%, while base minimum rent increased 6.3% to $62.42 per square foot. Management raised its full-year real estate funds from operations outlook to $13.20 - $13.30 per share. These figures show rent and property-income growth without requiring an increase in occupancy. Leasing activity also remained substantial. During the earnings call, management reported signing approximately 1,200 leases covering more than 4.8 million square feet, with new-deal volume increasing more than 20%.
Stable occupancy does not mean every tenant is healthy. Simon Property Group, Inc. (NYSE:SPG) absorbed approximately one million square feet of ****** e returned through retailer bankruptcies during the quarter. Management said it successfully re-leased the ****** e, helping maintain occupancy. That shows leasing strength, but also a reminder of the work required to preserve rental income. Additional retailer failures could bring more vacancies and replacement costs, even when demand for the properties remains sound.
#occupancy #NYSE #management #estate

30 days ago
American Tower Corporation (NYSE:AMT) traded at around $165 on October 6, within five dollars of its 52-week low of $160.06.
The company keeps 45.41% of revenue as operating profit on a portfolio of communications towers leased to wireless carriers. A business that profitable sitting at a 52-week low is usually a disagreement about the future rather than the present.
READ ALSO: What is eBay's (EBAY) Economic Moat, and is it Widening or Narrowing?
A tower is difficult to replicate for reasons that have nothing to do with engineering. Local authorities restrict where new structures can go, so an existing site near a highway or a dense suburb cannot simply be copied next door.
The economics follow from that scarcity. The first tenant on a tower covers the construction and the ground lease, and each additional tenant is close to pure margin. Gross margin of 73.77% is what that layering produces, and the 45.41% operating margin is what survives after the overheads.
#NYSE
The company keeps 45.41% of revenue as operating profit on a portfolio of communications towers leased to wireless carriers. A business that profitable sitting at a 52-week low is usually a disagreement about the future rather than the present.
READ ALSO: What is eBay's (EBAY) Economic Moat, and is it Widening or Narrowing?
A tower is difficult to replicate for reasons that have nothing to do with engineering. Local authorities restrict where new structures can go, so an existing site near a highway or a dense suburb cannot simply be copied next door.
The economics follow from that scarcity. The first tenant on a tower covers the construction and the ground lease, and each additional tenant is close to pure margin. Gross margin of 73.77% is what that layering produces, and the 45.41% operating margin is what survives after the overheads.
#NYSE


1 month ago
SK Hynix is exploring something it has never done before: manufacturing memory chips in the United States.
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long

2 months ago
On August 10, Simon Property Group (NYSE:SPG) reported results for the three months through June 30 and raised its full-year profit outlook once again. Real estate funds from operations (FFO), a cash-flow measure suited to landlords, hit $3.29 per share. Tenants are earning more from their stores, and management is confident enough to lift its guidance again. Yet the professionals who own the stock are heading the other way.
Start with the tenants, because they pay the rent. Reported retailer sales reached $838 per square foot over the year through June 30, up from $736 a year earlier, on June 30, 2025. Stronger sales tend to make higher rent easier to swallow, and base minimum rent per square foot did climb to $62.42 from $58.70.
That demand flowed through to profit. Real estate FFO rose to $3.29 per diluted share from $3.05, and net operating income at Simon's domestic properties grew 8.5%. Management responded by lifting its full-year real estate FFO range to $13.20 to $13.30 per share, moving the midpoint up by $0.08.
Shareholders get paid while they wait. The board declared a third-quarter dividend of $2.25 per share, $0.10 more than a year ago, to be paid on September 30 to anyone on the books by September 9. Simon also put $211.4 million into buying back stock at an average of $205.10 per share, and it finished June with about $9.3 billion of liquidity.
Now the less flattering side. Net income for common stockholders was $483.1 million, or $1.49 per diluted share, versus $1.70 a year earlier. The 2025 quarter included a non-cash gain of $0.21 per share from investment activity, which flatters that comparison. Still, plain FFO followed the same path, slipping to $3.12 from $3.15.
#Share #year #june #estate
Start with the tenants, because they pay the rent. Reported retailer sales reached $838 per square foot over the year through June 30, up from $736 a year earlier, on June 30, 2025. Stronger sales tend to make higher rent easier to swallow, and base minimum rent per square foot did climb to $62.42 from $58.70.
That demand flowed through to profit. Real estate FFO rose to $3.29 per diluted share from $3.05, and net operating income at Simon's domestic properties grew 8.5%. Management responded by lifting its full-year real estate FFO range to $13.20 to $13.30 per share, moving the midpoint up by $0.08.
Shareholders get paid while they wait. The board declared a third-quarter dividend of $2.25 per share, $0.10 more than a year ago, to be paid on September 30 to anyone on the books by September 9. Simon also put $211.4 million into buying back stock at an average of $205.10 per share, and it finished June with about $9.3 billion of liquidity.
Now the less flattering side. Net income for common stockholders was $483.1 million, or $1.49 per diluted share, versus $1.70 a year earlier. The 2025 quarter included a non-cash gain of $0.21 per share from investment activity, which flatters that comparison. Still, plain FFO followed the same path, slipping to $3.12 from $3.15.
#Share #year #june #estate
2 months ago
CleanSpark just announced a Mag 7 tenant for its first AI site, in a bullish disclosure for the former bitcoin miner as it seeks $2B in financing for its first AI site at a time when capital could get more expensive following the Fed's rate hike yesterday.
CleanSpark announced its first-ever AI lease on July 14 – a 20-year, $6.6B deal for 175 critical IT MWs at its Sandersville, Georgia, facility. But at the time, CleanSpark didn't disclose the tenant.
An SEC filing from today reveals that tenant is Meta, the social-media stalwart turned digital marketing giant and burgeoning AI lab, by way of its wholly owned subsidiary, Anviran. But that's not even the most interesting part – this ******* ociation also means that Meta holds an LOI for 885 MW from CleanSpark's Sealy and Brazoria, Texas, sites, since CleanSpark in July said the Sandersville counterparty also signed an exclusivity agreement for those sites.
The filing says that Meta will serve as "guarantor of rent and operating expenses," with the parent company backstopping Anviran.
And this backstop is more important now than ever. As we covered on the show yesterday, the Fed's 25-basis-point rate hike could lead to not just higher borrowing costs but also tightened credit access for non-investment-grade companies.
#tenant
CleanSpark announced its first-ever AI lease on July 14 – a 20-year, $6.6B deal for 175 critical IT MWs at its Sandersville, Georgia, facility. But at the time, CleanSpark didn't disclose the tenant.
An SEC filing from today reveals that tenant is Meta, the social-media stalwart turned digital marketing giant and burgeoning AI lab, by way of its wholly owned subsidiary, Anviran. But that's not even the most interesting part – this ******* ociation also means that Meta holds an LOI for 885 MW from CleanSpark's Sealy and Brazoria, Texas, sites, since CleanSpark in July said the Sandersville counterparty also signed an exclusivity agreement for those sites.
The filing says that Meta will serve as "guarantor of rent and operating expenses," with the parent company backstopping Anviran.
And this backstop is more important now than ever. As we covered on the show yesterday, the Fed's 25-basis-point rate hike could lead to not just higher borrowing costs but also tightened credit access for non-investment-grade companies.
#tenant


2 months ago
Digital Realty Trust, Inc. (NYSE:DLR) announced a joint venture with Rönesans Infrastructure on September 14 to develop and operate data centers in Türkiye. The first Ankara campus is designed for more than 22 megawatts of IT capacity. Land, power and permits are secured, early construction has begun, and the first facility is scheduled for completion in 2028.
Digital Realty Trust, Inc. (NYSE:DLR) has established credible development foundations. The investment question is whether those foundations can support attractive returns once construction spending, customer contracts, and operating costs enter the calculation.
For Digital Realty Trust, Inc. (NYSE:DLR), securing land, electricity and permits reduces uncertainty around whether development can proceed. That matters because customer interest has limited commercial value when a developer cannot offer a credible delivery schedule. Construction progress can make discussions with prospective tenants more concrete.
Digital Realty Trust, Inc. (NYSE:DLR) also combines its global customer relationships and operating experience with Rönesans Infrastructure's local development and construction capabilities. The potential benefit is practical: a partner familiar with local execution can help deliver the buildings, while an established data-center operator can help attract customers and manage their deployments.
Digital Realty Trust, Inc. (NYSE:DLR) is entering through a venture that also plans an additional Istanbul facility. A presence in both cities could appeal to customers seeking multiple locations for resilience and connectivity. Success in Ankara could therefore create a commercial foundation for further expansion, provided demand supports additional investment.
#digital #construction #development #venture
Digital Realty Trust, Inc. (NYSE:DLR) has established credible development foundations. The investment question is whether those foundations can support attractive returns once construction spending, customer contracts, and operating costs enter the calculation.
For Digital Realty Trust, Inc. (NYSE:DLR), securing land, electricity and permits reduces uncertainty around whether development can proceed. That matters because customer interest has limited commercial value when a developer cannot offer a credible delivery schedule. Construction progress can make discussions with prospective tenants more concrete.
Digital Realty Trust, Inc. (NYSE:DLR) also combines its global customer relationships and operating experience with Rönesans Infrastructure's local development and construction capabilities. The potential benefit is practical: a partner familiar with local execution can help deliver the buildings, while an established data-center operator can help attract customers and manage their deployments.
Digital Realty Trust, Inc. (NYSE:DLR) is entering through a venture that also plans an additional Istanbul facility. A presence in both cities could appeal to customers seeking multiple locations for resilience and connectivity. Success in Ankara could therefore create a commercial foundation for further expansion, provided demand supports additional investment.
#digital #construction #development #venture


2 months ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ***** ysis delivered straight to their inbox with the free CRE Daily newsletter.
Tech leased 1.1 million square feet of New York office ***** e in Q3 so far, surpassing legal to become the market's second-largest leasing sector behind finance.
AI companies are driving roughly 60% of tech leasing this quarter, competing for ***** e as Manhattan office supply hits its lowest point since 2020.
Flatiron remains the top tech submarket, while Hudson Square, the Penn District and Downtown are emerging as alternatives for ***** e-constrained tenants.
New York's tech sector has overtaken legal to become the city's second-largest office sector, trailing only finance, according to a September JLL report cited by GlobeSt.com. Tech tenants have leased 1.1 million square feet across the metro so far in the third quarter, a pace JLL Managing Director Joe Sipala called one of the "busiest summers" for office leasing the brokerage has seen in some time.
#daily #square #sector
Tech leased 1.1 million square feet of New York office ***** e in Q3 so far, surpassing legal to become the market's second-largest leasing sector behind finance.
AI companies are driving roughly 60% of tech leasing this quarter, competing for ***** e as Manhattan office supply hits its lowest point since 2020.
Flatiron remains the top tech submarket, while Hudson Square, the Penn District and Downtown are emerging as alternatives for ***** e-constrained tenants.
New York's tech sector has overtaken legal to become the city's second-largest office sector, trailing only finance, according to a September JLL report cited by GlobeSt.com. Tech tenants have leased 1.1 million square feet across the metro so far in the third quarter, a pace JLL Managing Director Joe Sipala called one of the "busiest summers" for office leasing the brokerage has seen in some time.
#daily #square #sector

2 months ago
Investors continue to ask for more timely information, even as the volume available to them expands. A 2026 CFA Institute survey of 2,500 **** ysts and portfolio managers found that 62% opposed replacing quarterly reporting with semiannual reporting. Nearly 85% expressed concern about comparability if companies and investment managers could determine their own reporting frequency and format. Access remains important, while interpretation requires a separate discipline.
The demand also concerns the quality of disclosure. PwC's 2025 Global Investor Survey, covering 1,074 investment professionals across 26 countries and territories, found that only 37% believed companies disclosed enough about artificial intelligence strategies and policies. Respondents wanted greater transparency around innovation strategies, AI investment, and expected returns. These findings suggest that investors can face abundant commentary while still lacking the evidence needed to **** s a thesis.
Commercial incentives add another layer. A 2025 CFA Institute report examined continuation funds, in which a manager can oversee both the vehicle selling an **** et and the vehicle buying it. The report recognized the structure's liquidity role and identified conflicts requiring fair processes and governance. The example illustrates why informed **** ysis and aligned incentives are separate considerations.
That distinction applies beyond any single investment structure. Managers often possess valuable operational knowledge because they work directly with **** ets, tenants and financing markets. They may also be raising capital for the strategies they discuss. Their commercial interest becomes additional context for investors weighing forecasts, market narratives and recommendations alongside independently produced evidence. That context can help an investment committee separate a source's knowledge of the market from the confidence it should place in the source's preferred outcome during capital allocation.
Geoffrey Dohrmann, chairman, CEO and editor-in-chief of Institutional Real Estate, Inc., has watched those narratives develop across several market cycles. IREI is a media and market intelligence company covering institutional real estate and infrastructure through publications, research, data, events and consulting. Dohrmann explains its editorial role as independently recording where real-asset capital is moving and examining the explanations offered for those decisions.
#real #institute
The demand also concerns the quality of disclosure. PwC's 2025 Global Investor Survey, covering 1,074 investment professionals across 26 countries and territories, found that only 37% believed companies disclosed enough about artificial intelligence strategies and policies. Respondents wanted greater transparency around innovation strategies, AI investment, and expected returns. These findings suggest that investors can face abundant commentary while still lacking the evidence needed to **** s a thesis.
Commercial incentives add another layer. A 2025 CFA Institute report examined continuation funds, in which a manager can oversee both the vehicle selling an **** et and the vehicle buying it. The report recognized the structure's liquidity role and identified conflicts requiring fair processes and governance. The example illustrates why informed **** ysis and aligned incentives are separate considerations.
That distinction applies beyond any single investment structure. Managers often possess valuable operational knowledge because they work directly with **** ets, tenants and financing markets. They may also be raising capital for the strategies they discuss. Their commercial interest becomes additional context for investors weighing forecasts, market narratives and recommendations alongside independently produced evidence. That context can help an investment committee separate a source's knowledge of the market from the confidence it should place in the source's preferred outcome during capital allocation.
Geoffrey Dohrmann, chairman, CEO and editor-in-chief of Institutional Real Estate, Inc., has watched those narratives develop across several market cycles. IREI is a media and market intelligence company covering institutional real estate and infrastructure through publications, research, data, events and consulting. Dohrmann explains its editorial role as independently recording where real-asset capital is moving and examining the explanations offered for those decisions.
#real #institute


2 months ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still


2 months ago
Welltower and Ventas posted SHOP NOI growth of 20.5% and 16.3%, respectively, as senior occupancy rates climb and new supply starts remain at record lows.
Roughly 2 million people turn 80 in 2026, and Ventas CEO Debra Cafaro says the senior population growth rate will more than double over the next decade.
OHI's 5.68% yield carries real tenant risk: Genesis Healthcare is in Chapter 11 with $148 million in loans outstanding and the CEO is retiring.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing and skilled nursing REITs are riding a demographic tide that shows up in the operating data. Roughly two million people will turn 80 in 2026 alone, and Ventas Chair and CEO Debra A. Cafaro told investors that "the leading edge of the nearly 70 million baby boomers has just begun turning 80 this year, ushering in a decade where the growth rate of the senior population more than doubles, yet new starts remain at record lows." Four US-listed equity REITs sit squarely in that trade. Dividend safety leads the **** ysis, so every payout is measured against FFO or AFFO, not GAAP earnings.
#ventas #welltower
Roughly 2 million people turn 80 in 2026, and Ventas CEO Debra Cafaro says the senior population growth rate will more than double over the next decade.
OHI's 5.68% yield carries real tenant risk: Genesis Healthcare is in Chapter 11 with $148 million in loans outstanding and the CEO is retiring.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Welltower didn't make the cut. Enter your email to see the names that beat WELL. The report is free. Enter your email and see if any of your stocks made the cut.
Senior housing and skilled nursing REITs are riding a demographic tide that shows up in the operating data. Roughly two million people will turn 80 in 2026 alone, and Ventas Chair and CEO Debra A. Cafaro told investors that "the leading edge of the nearly 70 million baby boomers has just begun turning 80 this year, ushering in a decade where the growth rate of the senior population more than doubles, yet new starts remain at record lows." Four US-listed equity REITs sit squarely in that trade. Dividend safety leads the **** ysis, so every payout is measured against FFO or AFFO, not GAAP earnings.
#ventas #welltower
2 months ago
Intel and SK Hynix each jumped roughly 3% after Reuters reported talks to produce memory chips at Intel's $100B Ohio campus, with plants not due until 2030.
Semiconductor ETF SOXX gained 2%, tripling QQQ's advance, while Micron risks losing its CHIPS Act home-market edge if SK Hynix secures U.S. soil production.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Intel didn't make the cut. Enter your email to see the names that beat INTC. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Intel (NASDAQ:INTC) are trading higher early Wednesday after Reuters reported the chipmaker is in talks with a Korean memory partner about producing memory chips at Intel's Ohio campus. Intel stock is up 4% to $100.55 in early Wednesday trading, extending a run that has the shares up 171% year to date. The move points to a paying tenant on the same site Intel has been funding on its own.
SK Hynix (NASDAQ:SKHY) is the reported counterparty, and its U.S.-listed shares are climbing on the same story. SK Hynix stock is up 3.3% to $180.52. The Korean memory leader is in the middle of a wider U.S. build-out that already includes a groundbreaking last month on a high-bandwidth memory (HBM) production base in Indiana.
#Intel #Stock #reuters
Semiconductor ETF SOXX gained 2%, tripling QQQ's advance, while Micron risks losing its CHIPS Act home-market edge if SK Hynix secures U.S. soil production.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Intel didn't make the cut. Enter your email to see the names that beat INTC. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Intel (NASDAQ:INTC) are trading higher early Wednesday after Reuters reported the chipmaker is in talks with a Korean memory partner about producing memory chips at Intel's Ohio campus. Intel stock is up 4% to $100.55 in early Wednesday trading, extending a run that has the shares up 171% year to date. The move points to a paying tenant on the same site Intel has been funding on its own.
SK Hynix (NASDAQ:SKHY) is the reported counterparty, and its U.S.-listed shares are climbing on the same story. SK Hynix stock is up 3.3% to $180.52. The Korean memory leader is in the middle of a wider U.S. build-out that already includes a groundbreaking last month on a high-bandwidth memory (HBM) production base in Indiana.
#Intel #Stock #reuters

2 months ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed

2 months ago
Walmart (WMT) recently took another step into restaurant delivery, announcing a national partnership with Inspire Brands that puts it more directly in competition with DoorDash (DASH) and Uber Technologies' (UBER) Uber Eats. But the expansion announced recently is still largely limited to restaurants operating as tenants inside Walmart stores, where the logistics are considerably easier to manage. The bigger question is what happens when the company moves beyond these in-store tenants and takes on the more difficult parts of the restaurant delivery market. Until then, the current expansion says more about Walmart's ambition than its ability to become a structural competitor to the established players.
Walmart is expanding its restaurant delivery strategy through a new collaboration with Inspire Brands, whose portfolio includes Arby's, Jimmy John's, Dunkin, Baskin-Robbins, and Sonic. The partnership will bring restaurant delivery into Walmart's app. Dunkin' will be the first brand to launch, starting with 150 in-store tenant locations. Walmart and Dunkin' then plan to expand the offering to most of Dunkin's roughly 10,000 U.S. restaurants, including locations outside Walmart's stores. The broader opportunity is built around Walmart's existing physical footprint. A customer could place a restaurant order alongside a Walmart purchase and receive both through the same delivery. The retail giant says its footprint is located within 10 miles of about 90% of the U.S. population.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#uber #Stock #inspire #launch
Walmart is expanding its restaurant delivery strategy through a new collaboration with Inspire Brands, whose portfolio includes Arby's, Jimmy John's, Dunkin, Baskin-Robbins, and Sonic. The partnership will bring restaurant delivery into Walmart's app. Dunkin' will be the first brand to launch, starting with 150 in-store tenant locations. Walmart and Dunkin' then plan to expand the offering to most of Dunkin's roughly 10,000 U.S. restaurants, including locations outside Walmart's stores. The broader opportunity is built around Walmart's existing physical footprint. A customer could place a restaurant order alongside a Walmart purchase and receive both through the same delivery. The retail giant says its footprint is located within 10 miles of about 90% of the U.S. population.
Dear ****** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#uber #Stock #inspire #launch


2 months ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ***** ysis, subscribe to Bisnow's free suite of newsletters.
Despite office vacancy falling in most major cities, most landlords are still watching their margins shrink a half-decade after tenants embraced remote work.
Median total operating expense growth has exceeded revenue every year from 2021 through 2025, according to a Trepp ***** ysis of office properties backing CMBS loans.
Operating expenses have increased 2.7% annually, compared with a 1.3% growth rate for revenues. Net operating income has been squeezed to just a 0.2% uptick annually as a result.
Overall, the implied five-year growth rate is 14.3% for operating expenses and 6.7% for revenues. NOI was up just 1% during the period, according to Trepp's model.
#year #expenses
Despite office vacancy falling in most major cities, most landlords are still watching their margins shrink a half-decade after tenants embraced remote work.
Median total operating expense growth has exceeded revenue every year from 2021 through 2025, according to a Trepp ***** ysis of office properties backing CMBS loans.
Operating expenses have increased 2.7% annually, compared with a 1.3% growth rate for revenues. Net operating income has been squeezed to just a 0.2% uptick annually as a result.
Overall, the implied five-year growth rate is 14.3% for operating expenses and 6.7% for revenues. NOI was up just 1% during the period, according to Trepp's model.
#year #expenses


2 months ago
Interested in American Tower Corporation? Here are five stocks we like better.
2026 is expected to be American Tower's organic growth trough, with tenant billings growth projected to accelerate in 2027 as Dish Network churn fades and carrier network investment improves.
Future demand could be supported by 5G capacity expansion, higher-band spectrum, AI-driven uplink traffic and eventual 6G deployments. CoreSite's data-center business is also benefiting from rising bandwidth and cloud-interconnection demand.
American Tower is targeting 200–300 basis points of tower-business margin expansion and mid- to upper-mid-single-digit long-term AFFO-per-share growth, while Dish litigation and a Mexico arbitration could provide additional upside if resolved favorably.
AST ****** eMobile Looks to Extend Its 30-Day FCC Satellite Testing Window
#Growth #expansion #interested
2026 is expected to be American Tower's organic growth trough, with tenant billings growth projected to accelerate in 2027 as Dish Network churn fades and carrier network investment improves.
Future demand could be supported by 5G capacity expansion, higher-band spectrum, AI-driven uplink traffic and eventual 6G deployments. CoreSite's data-center business is also benefiting from rising bandwidth and cloud-interconnection demand.
American Tower is targeting 200–300 basis points of tower-business margin expansion and mid- to upper-mid-single-digit long-term AFFO-per-share growth, while Dish litigation and a Mexico arbitration could provide additional upside if resolved favorably.
AST ****** eMobile Looks to Extend Its 30-Day FCC Satellite Testing Window
#Growth #expansion #interested

2 months ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ******* ysis, subscribe to Bisnow's free suite of newsletters.
CBRE's investment management arm has acquired a 5-year-old net lease company with ******* ets totaling 12M SF across the U.S.
CBRE Investment Management purchased Cerberus Capital Management's Tenet Equity business for $1.6B, both sides of the transaction announced in separate news releases Tuesday. CBRE said it made the investment on behalf of several of its investment strategies but didn't disclose which ones.
Net leases are real estate arrangements in which tenants are responsible for fees typically ******* ociated with ownership, like insurance, maintenance and taxes. This is often executed through leaseback deals, in which a business sells its property for a cash infusion and then leases it back to remain a tenant.
Along with the acquisition, CBRE is launching a new strategy to further invest in net lease properties. Akash Shivashankara, a CBRE IM senior portfolio manager, will be heading that strategy.
#management
CBRE's investment management arm has acquired a 5-year-old net lease company with ******* ets totaling 12M SF across the U.S.
CBRE Investment Management purchased Cerberus Capital Management's Tenet Equity business for $1.6B, both sides of the transaction announced in separate news releases Tuesday. CBRE said it made the investment on behalf of several of its investment strategies but didn't disclose which ones.
Net leases are real estate arrangements in which tenants are responsible for fees typically ******* ociated with ownership, like insurance, maintenance and taxes. This is often executed through leaseback deals, in which a business sells its property for a cash infusion and then leases it back to remain a tenant.
Along with the acquisition, CBRE is launching a new strategy to further invest in net lease properties. Akash Shivashankara, a CBRE IM senior portfolio manager, will be heading that strategy.
#management

2 months ago
Prince Harry and Meghan Markle's relationship with the royal family will reportedly face renewed tension. The shift follows a pointed letter from King Charles. According to a royal expert, the Duke of Sussex will be left "angered" by official guidance clarifying his standing in the monarchy. The Sussexes previously sparked fresh speculation after returning to Britain with their family. While speculation remains about their future ties, Charles allegedly handed the couple a blunt statement confirming they remain non-working royals.
The firm directive from Buckingham Palace has reportedly dashed any lingering hopes of a hybrid role for the Sussexes. King Charles' official instruction to government and military officials could reportedly keep the Sussexes sidelined in the long run. Royal commentators writing for iNews recently revealed that the King issued a formal statement to establish clear boundaries.
According to reports, the letter was sent by the Lord Chamberlain on behalf of the King to government departments, military officials, lord lieutenants across Britain, and Harry and Meghan themselves. Although Harry is the King's son, the Palace allegedly wants no confusion about his non-working status moving forward.
Reports claimed that official guidance serves as a shut-down against rumors of a half-in, half-out royal plan. "Not a quiet word in your ear, not a private memo: no, this was a formal, blunt statement of fact sent to Harry on his father's orders," the report noted. The expert revealed that Palace officials strictly designed the public directive to shut down speculation.
Furthermore, the directive stated that Harry and Meghan's "HRH" ******* les remain in abeyance, preventing the couple from using them in any official capacity. Harry might hope to continue his charitable work in Britain. However, Buckingham Palace has completely ruled out official royal backing.
#harry #sussexes
The firm directive from Buckingham Palace has reportedly dashed any lingering hopes of a hybrid role for the Sussexes. King Charles' official instruction to government and military officials could reportedly keep the Sussexes sidelined in the long run. Royal commentators writing for iNews recently revealed that the King issued a formal statement to establish clear boundaries.
According to reports, the letter was sent by the Lord Chamberlain on behalf of the King to government departments, military officials, lord lieutenants across Britain, and Harry and Meghan themselves. Although Harry is the King's son, the Palace allegedly wants no confusion about his non-working status moving forward.
Reports claimed that official guidance serves as a shut-down against rumors of a half-in, half-out royal plan. "Not a quiet word in your ear, not a private memo: no, this was a formal, blunt statement of fact sent to Harry on his father's orders," the report noted. The expert revealed that Palace officials strictly designed the public directive to shut down speculation.
Furthermore, the directive stated that Harry and Meghan's "HRH" ******* les remain in abeyance, preventing the couple from using them in any official capacity. Harry might hope to continue his charitable work in Britain. However, Buckingham Palace has completely ruled out official royal backing.
#harry #sussexes

2 months ago
On August 3, Alexandria Real Estate Equities (NYSE:ARE) reported a Q2 2026 net loss of $0.43 per diluted share, narrower than the $0.64 loss posted a year earlier, while first-half net income swung to $1.68 per share from a loss of $0.71 in H1 2025. Funds from operations, the metric real estate investors watch most closely, moved the other way. Second-quarter FFO per share, as adjusted, fell to $1.73 from $2.33, and first-half FFO per share dropped to $3.46 from $4.63.
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased ******* e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 m
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased ******* e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 m
2 months ago
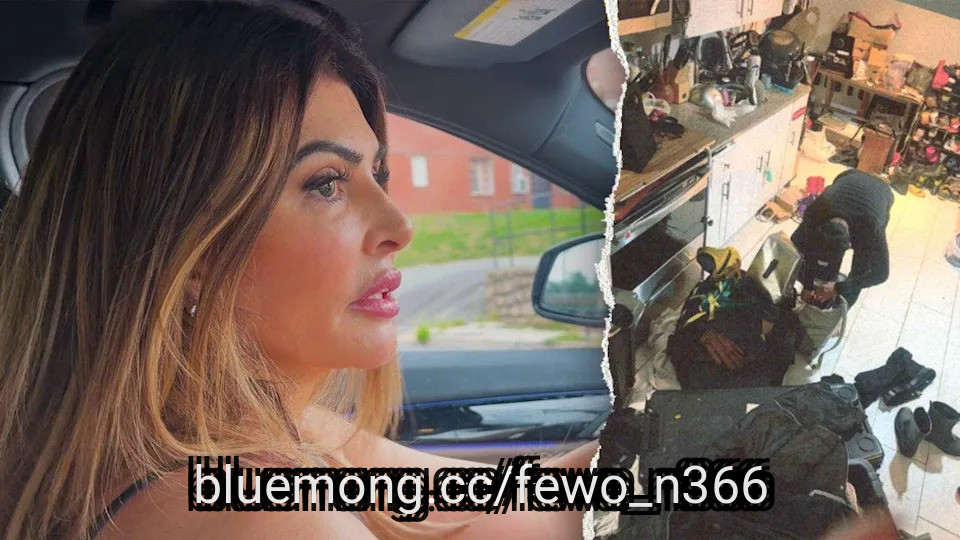
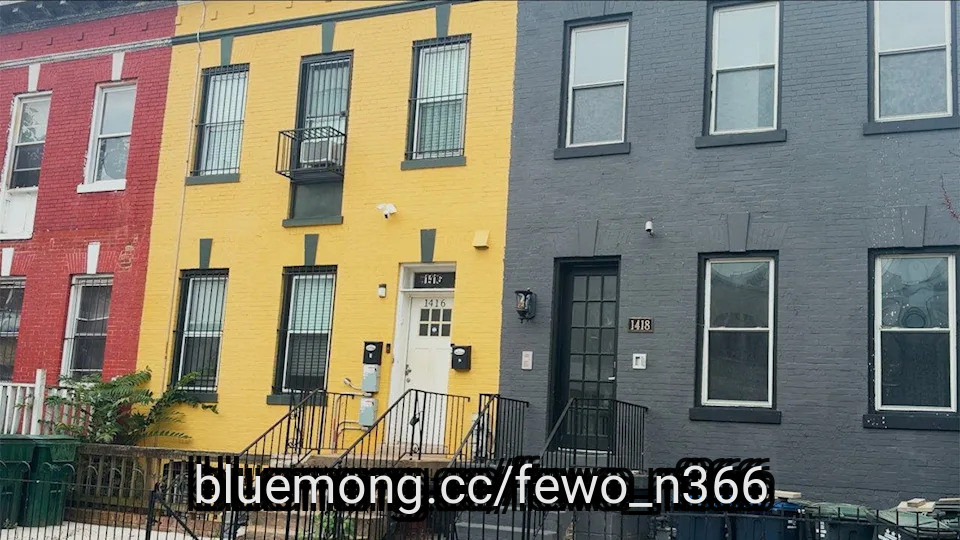
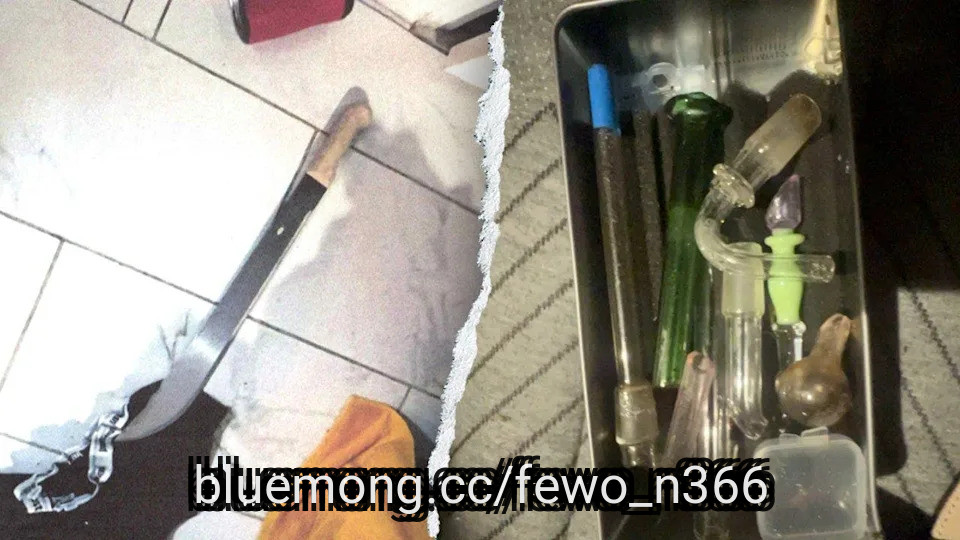
WASHINGTON, D.C. — FIRST ON FOX: As Washington, D.C., grapples with a persistent squatting problem, one resident in the nation's capital is speaking out about how unwelcome tenants have turned her life upside down, terrorizing her neighborhood while the city stands by and does nothing.
"I lived in several countries, including Third World countries, but it seems to me that I'm living in a Fourth World country in D.C.," Tatyana Day Velasquez, who owns a small three-unit building in Columbia Heights, told Fox News Digital.
"I've never seen something like it. There's no accountability for what goes on. Everybody just throws the ball to each other, and there's no help. So how can somebody resolve a problem like mine if you don't get help?"
For a tumultuous eight months, Velasquez said her property's basement apartment has been overrun by strangers who refuse to leave and live rent-free with no consequences in sight.
Homeowners Terrorized By Pro Squatters Turning Dreams Into Nightmares In Palm-lined Paradise, Experts Say
#World #velasquez #like #first
"I lived in several countries, including Third World countries, but it seems to me that I'm living in a Fourth World country in D.C.," Tatyana Day Velasquez, who owns a small three-unit building in Columbia Heights, told Fox News Digital.
"I've never seen something like it. There's no accountability for what goes on. Everybody just throws the ball to each other, and there's no help. So how can somebody resolve a problem like mine if you don't get help?"
For a tumultuous eight months, Velasquez said her property's basement apartment has been overrun by strangers who refuse to leave and live rent-free with no consequences in sight.
Homeowners Terrorized By Pro Squatters Turning Dreams Into Nightmares In Palm-lined Paradise, Experts Say
#World #velasquez #like #first
2 months ago
On August 3, Alexandria Real Estate Equities (NYSE:ARE) reported a Q2 2026 net loss of $0.43 per diluted share, narrower than the $0.64 loss posted a year earlier, while first-half net income swung to $1.68 per share from a loss of $0.71 in H1 2025. Funds from operations, the metric real estate investors watch most closely, moved the other way. Second-quarter FFO per share, as adjusted, fell to $1.73 from $2.33, and first-half FFO per share dropped to $3.46 from $4.63.
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased **** e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 mill
Leasing activity picked up meaningfully in the second quarter. Alexandria signed 1,038,917 rentable square feet of leases in Q2 2026, a 60% jump from the first quarter and roughly 87,000 square feet above its trailing quarterly average. Three-quarters of that leasing activity over the trailing twelve months came from existing tenants, and once executed leases with future occupancy are counted, total occupancy climbs to 90.9% from the reported 86.9%. Tenant quality remains a selling point too: 80% of annual rental revenue comes from the company's Megacampus platform, and 57% comes from investment-grade or publicly traded large-cap tenants, with 99.9% of second-quarter rents and receivables collected as of August 3.
The balance sheet backs that stability up. Alexandria holds $3.60 billion in liquidity and just extended its $5.0 billion unsecured line of credit to 2032 at a lower borrowing rate of SOFR plus 0.725%, down from SOFR plus 0.835%. Only 6% of total debt matures through 2028, and the company's 9.7-year weighted-average remaining debt term is the longest among S&P 500 REITs. General and administrative expenses fell 17.4% from Q2 2024, even after a year-over-year uptick, and the company maintained its $0.72 per share quarterly dividend, a 5.4% yield as of June 30.
The numbers behind the improved per-share figures are less reassuring on closer look. Same-property net operating income fell 10.6% in the second quarter and 11.5% for the first half, driven largely by occupancy declines tied to lease expirations. Operating occupancy slipped from 87.7% at the end of March to 86.9% at the end of June, and the current-period average occupancy of 87.1% compares with 92.6% a year earlier. Lease renewals aren't helping much either: rental rate changes on renewed and re-leased **** e fell 0.7% in the second quarter and 15.0% in the first quarter, with cash-basis declines of 4.3% and 15.8%, respectively.
Leverage remains elevated in the near term. Net debt and preferred stock to Adjusted EBITDA stood at 7.0x on a Q2 2026 annualized basis, well above the company's 5.6x to 6.2x target for the fourth quarter, which depends on completing $2.9 billion in planned dispositions and other capital sources. General and administrative expenses rose 26.5% from Q2 2025 to $36.9 million. The company also recorded $222.5 million of real estate impairment charges in the quarter and continues to evaluate the business and financial strategy for five development and redevelopment projects totaling 1.4 mill

2 months ago
Former Ohio State Head Football Coach and current Lieutenant Governor of Ohio, Jim Tressel, has been enshrined in the Ring of Honor at Ohio Stadium.
[DOWNLOAD: Free WHIO-TV News app for alerts as news breaks]
Tressel's plaque on the C-Deck of Ohio Stadium was unveiled during Ohio State's season opener against Ball State.
TRENDING STORIES:
'Teen takeover' trend hits AlterFest, prompts new curfew
#state #former #Football #governor
[DOWNLOAD: Free WHIO-TV News app for alerts as news breaks]
Tressel's plaque on the C-Deck of Ohio Stadium was unveiled during Ohio State's season opener against Ball State.
TRENDING STORIES:
'Teen takeover' trend hits AlterFest, prompts new curfew
#state #former #Football #governor


2 months ago
There aren't too many dividend stocks that yield more than 5%. Those that do can be separated into high- and low-risk categories, and most investors, especially those who rely on passive income, are looking for low-risk options.
Realty Income (NYSE: O) boasts a 5.3% dividend yield, and it's as reliable as they come. Here's why it's my pick for the top S&P 500 (SNPINDEX: ^GSPC) stock with a yield above 5%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Realty Income is a real estate investment trust (REIT), a structure that pays out 90% of earnings as dividends. REITs often play a big role in a dividend-focused portfolio, although there are all sorts of REITs, some of which are high-risk and some that don't pay high yields.
REITs buy and lease properties, and they typically have an industry focus. Realty Income is a retail REIT, meaning it predominantly leases its properties to retailers. Its tenant roster includes some of the largest and most stable retailers in the U.S., such as Walmart and Home Depot. Grocery and convenience stores make up more than 20% of its total portfolio, and it services other essential retail categories like pharmacy and home improvement, which is why its tenant base is so reliable.
#realty #yield #high
Realty Income (NYSE: O) boasts a 5.3% dividend yield, and it's as reliable as they come. Here's why it's my pick for the top S&P 500 (SNPINDEX: ^GSPC) stock with a yield above 5%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Realty Income is a real estate investment trust (REIT), a structure that pays out 90% of earnings as dividends. REITs often play a big role in a dividend-focused portfolio, although there are all sorts of REITs, some of which are high-risk and some that don't pay high yields.
REITs buy and lease properties, and they typically have an industry focus. Realty Income is a retail REIT, meaning it predominantly leases its properties to retailers. Its tenant roster includes some of the largest and most stable retailers in the U.S., such as Walmart and Home Depot. Grocery and convenience stores make up more than 20% of its total portfolio, and it services other essential retail categories like pharmacy and home improvement, which is why its tenant base is so reliable.
#realty #yield #high
2 months ago
Soluna Holdings reported second-quarter revenue of $15.1 million, up 145% year over year. That headline needs an important qualification. A change in accounting presentation moved roughly $4.4 million of pass-through electricity costs from a net presentation to both revenue and cost of revenue, without changing profit or loss. Excluding that change, revenue grew 73% year over year and 13% sequentially. Soluna Holdings, Inc. (NASDAQ:SLNH) therefore delivered substantial growth, but not all of the reported increase reflected new economic activity.
The quarter also should not be treated as proof that the AI pivot is already producing revenue. Project Dorothy 1A generated $2.9 million of revenue, up 31% sequentially, and $795,000 of gross profit at a 28% margin, but that improvement came from Bitcoin-mining customers, including Blockware and Canaan. Management said Bitcoin-miner hosting remains its largest business today. The AI and high-performance-computing opportunity is prospective. That distinction matters because AI leases can carry different capital needs, construction schedules, and customer requirements from cryptocurrency hosting.
That opportunity is nevertheless large. As of August 1, Soluna reported a roughly 6.3-gigawatt overall pipeline, including more than 1.6 gigawatts of AI data-center capacity in development. It said Hedy, Ellen, and Fei were advancing under term sheets toward a combined 583 megawatts designated for AI and HPC. The 583-megawatt figure describes their combined planned capacity, not entirely new capacity. Based on the project updates, their capacities rose by 243 megawatts in aggregate, from 340 to 583 megawatts.
A pipeline is not contracted revenue. Projects still require land, permits, interconnection, financing, equipment, and tenants before generating cash. Soluna Holdings, Inc. (NASDAQ:SLNH) remains a small company pursuing capital-intensive facilities, so delays or unfavorable funding could overwhelm operating progress. AI customers may also demand stronger balance sheets and long construction guarantees, while rapid share issuance could dilute per-share gains.
Hedge-fund interest increased but remained limited. Insider Monkey counted nine hedge funds holding the shares in Q2, up from six in Q1. Separately, Vident Advisory, an institutional investment adviser rather than a hedge fund, expanded its reported position by 7,772% to 5,227,200 shares. The percentage is dramatic because its prior position was small and should not be mistaken for broad sponsorship.
#soluna #holdings #NASDAQ
The quarter also should not be treated as proof that the AI pivot is already producing revenue. Project Dorothy 1A generated $2.9 million of revenue, up 31% sequentially, and $795,000 of gross profit at a 28% margin, but that improvement came from Bitcoin-mining customers, including Blockware and Canaan. Management said Bitcoin-miner hosting remains its largest business today. The AI and high-performance-computing opportunity is prospective. That distinction matters because AI leases can carry different capital needs, construction schedules, and customer requirements from cryptocurrency hosting.
That opportunity is nevertheless large. As of August 1, Soluna reported a roughly 6.3-gigawatt overall pipeline, including more than 1.6 gigawatts of AI data-center capacity in development. It said Hedy, Ellen, and Fei were advancing under term sheets toward a combined 583 megawatts designated for AI and HPC. The 583-megawatt figure describes their combined planned capacity, not entirely new capacity. Based on the project updates, their capacities rose by 243 megawatts in aggregate, from 340 to 583 megawatts.
A pipeline is not contracted revenue. Projects still require land, permits, interconnection, financing, equipment, and tenants before generating cash. Soluna Holdings, Inc. (NASDAQ:SLNH) remains a small company pursuing capital-intensive facilities, so delays or unfavorable funding could overwhelm operating progress. AI customers may also demand stronger balance sheets and long construction guarantees, while rapid share issuance could dilute per-share gains.
Hedge-fund interest increased but remained limited. Insider Monkey counted nine hedge funds holding the shares in Q2, up from six in Q1. Separately, Vident Advisory, an institutional investment adviser rather than a hedge fund, expanded its reported position by 7,772% to 5,227,200 shares. The percentage is dramatic because its prior position was small and should not be mistaken for broad sponsorship.
#soluna #holdings #NASDAQ


2 months ago
We ran an **** ysis based on Insider Monkey's proprietary database to see which real estate stocks billionaire-led funds held at the end of the second quarter. We narrowed the list to names paying dividend yields above 5%. Two stood out.
VICI Properties Inc. (NYSE:VICI) came in first. A total of 22 billionaire-led funds held stakes in the company at the end of the second quarter. VICI owns casino and gaming real estate and leases the properties back to operators under triple-net agreements, which means tenants cover taxes, insurance and maintenance. It has a dividend yield of about 7%.
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) was in about 19 billionaire-led fund portfolios as of the end of the June quarter, up from 16 in the first quarter. The stock has a dividend yield of about 7.5%. In this article, we will focus on Gaming and Leisure Properties, Inc. (NASDAQ:GLPI).
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) is a REIT focusing on casino properties. In the most recent quarter, its revenue rose about 9% year over year and beat estimates. Management raised its full-year fiscal 2026 outlook for adjusted funds from operations.
Photo by Breno **** is on Unsplash
#quarter #NASDAQ #Dividend
VICI Properties Inc. (NYSE:VICI) came in first. A total of 22 billionaire-led funds held stakes in the company at the end of the second quarter. VICI owns casino and gaming real estate and leases the properties back to operators under triple-net agreements, which means tenants cover taxes, insurance and maintenance. It has a dividend yield of about 7%.
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) was in about 19 billionaire-led fund portfolios as of the end of the June quarter, up from 16 in the first quarter. The stock has a dividend yield of about 7.5%. In this article, we will focus on Gaming and Leisure Properties, Inc. (NASDAQ:GLPI).
Gaming and Leisure Properties, Inc. (NASDAQ:GLPI) is a REIT focusing on casino properties. In the most recent quarter, its revenue rose about 9% year over year and beat estimates. Management raised its full-year fiscal 2026 outlook for adjusted funds from operations.
Photo by Breno **** is on Unsplash
#quarter #NASDAQ #Dividend

2 months ago
Boston, Massachusetts-based American Tower Corporation (AMT) is a leading global real estate investment trust (REIT) focused on communications infrastructure, primarily owning and operating wireless communications towers and other critical telecom ******* ets. With a market cap of $87.1 billion, the company leases antenna sites on multi-tenant towers for a diverse range of wireless communications industries, including personal communications services, paging, and cellular.
Companies worth $10 billion or more are generally described as "large-cap stocks," and AMT perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty REIT industry. With a large, geographically diversified portfolio of communications sites, American Tower benefits from the growing demand for wireless connectivity and data consumption. Its ******* et-heavy infrastructure business also generates recurring, long-term rental revenue, making AMT a key player in the global digital infrastructure ecosystem.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ******* eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#wireless #tower #business
Companies worth $10 billion or more are generally described as "large-cap stocks," and AMT perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the specialty REIT industry. With a large, geographically diversified portfolio of communications sites, American Tower benefits from the growing demand for wireless connectivity and data consumption. Its ******* et-heavy infrastructure business also generates recurring, long-term rental revenue, making AMT a key player in the global digital infrastructure ecosystem.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ******* eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#wireless #tower #business



2 months ago
NNN and ADC both carry ~70% AFFO payout ratios, but Agree's two-thirds investment-grade tenant mix and 3.7x net debt ratio outshine NNN's 5.7x.
NNN's 37-year consecutive dividend increase streak impresses, but its non-investment-grade tenant roster creates meaningful tail risk that Agree's portfolio avoids.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Two of the largest net lease REITs cut checks to shareholders on the same day. NNN REIT (NYSE:NNN) sent out $0.62 per share on August 14, 2026, its first payment at a raised quarterly rate. Agree Realty (NYSE:ADC) delivered $0.267 per share on August 14, 2026 as part of its monthly payout schedule. Same date, same sector, and remarkably similar payout ratios. The grades diverge on what backs each dollar.
The August payment marked NNN's 37th consecutive annual dividend increase, one of the longest streaks in the REIT universe. The 3.3% increase in the quarterly rate lifted the annualized dividend to $2.48 per share.
#same #payout #increase #investment
NNN's 37-year consecutive dividend increase streak impresses, but its non-investment-grade tenant roster creates meaningful tail risk that Agree's portfolio avoids.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Two of the largest net lease REITs cut checks to shareholders on the same day. NNN REIT (NYSE:NNN) sent out $0.62 per share on August 14, 2026, its first payment at a raised quarterly rate. Agree Realty (NYSE:ADC) delivered $0.267 per share on August 14, 2026 as part of its monthly payout schedule. Same date, same sector, and remarkably similar payout ratios. The grades diverge on what backs each dollar.
The August payment marked NNN's 37th consecutive annual dividend increase, one of the longest streaks in the REIT universe. The 3.3% increase in the quarterly rate lifted the annualized dividend to $2.48 per share.
#same #payout #increase #investment


2 months ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ***** ysis delivered straight to their inbox with the free CRE Daily newsletter.
National Resources, Great Point Studios, and Lindsay Goldberg refinanced their 719,943-square-foot "Hollywood on the Hudson" studio portfolio in Yonkers for $435 million.
The floating-rate loan from Bank of Montreal, Starwood Mortgage Capital, and Bank of America replaces $376.8 million in debt and funds tenant improvements.
The portfolio is 98.9% leased with Lionsgate Studio Corp. alone occupying 52.5% of the ***** e, underscoring strong demand for film and TV production real estate.
A four-building Yonkers film studio and office portfolio has landed a $435 million refinancing, according to Commercial Property Executive. The borrower, a joint venture between National Resources, Great Point Studios Operations, and Lindsay Goldberg, used the floating-rate loan to retire $376.8 million in prior debt on the 719,943-square-foot "Hollywood on the Hudson" portfolio, with the balance covering closing costs, equity returns, and tenant improvements.
#Portfolio #national #point #lindsay
National Resources, Great Point Studios, and Lindsay Goldberg refinanced their 719,943-square-foot "Hollywood on the Hudson" studio portfolio in Yonkers for $435 million.
The floating-rate loan from Bank of Montreal, Starwood Mortgage Capital, and Bank of America replaces $376.8 million in debt and funds tenant improvements.
The portfolio is 98.9% leased with Lionsgate Studio Corp. alone occupying 52.5% of the ***** e, underscoring strong demand for film and TV production real estate.
A four-building Yonkers film studio and office portfolio has landed a $435 million refinancing, according to Commercial Property Executive. The borrower, a joint venture between National Resources, Great Point Studios Operations, and Lindsay Goldberg, used the floating-rate loan to retire $376.8 million in prior debt on the 719,943-square-foot "Hollywood on the Hudson" portfolio, with the balance covering closing costs, equity returns, and tenant improvements.
#Portfolio #national #point #lindsay