
5 days ago
Miesha Shakes wants to question Montia Sabbag about the recording and its investigation in her ongoing legal dispute with Hart.
Kevin Hart's former ****** istant Miesha Shakes wants Montia Sabbag, the woman involved in his 2017 ****** tape scandal, to testify in the comedian's lawsuit against her.
In court documents obtained by TMZ, Shakes said she wants to question Sabbag about the recording and the investigation that followed. She also plans to testify herself and call Hart as a witness.
Hart sued Shakes in December 2023 after she discussed his private life during an interview with blogger Tasha K, whose real name is Latasha Kebe. Shakes worked for Hart's company from August 2017 to October 2020. His complaint accused her of defamation and breaching a nondisclosure agreement. Hart denied her claims that he recorded a ****** ual encounter and faced criminal charges over it.
Shakes argues the agreement is invalid because Hart failed to meet obligations under it. Hart disputes that argument and says her comments damaged his reputation. In June 2026, he asked a judge to order Shakes to pay $50,000, citing the damages provision in their agreement.
#shakes #sabbag #wants #montia

7 days ago
Options traders price NVDA at 50% odds of hitting $6 trillion by Oct. 30, needing just a 4% gain to roughly $249 a share.
Morgan Stanley restored NVDA as its top chip pick with a $300 target, while TSM's Oct. 15 earnings give the first read on AI foundry demand.
NVDA's revenue surged 106% and net income rose 126% last quarter, yet the stock's 28% year-to-date gain trails the semiconductor sector's 96% return.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
No company has ever been worth $6 trillion, yet a CNBC options-pricing ****** ysis put the odds of NVIDIA (NASDAQ:NVDA) reaching that level by the end of October at about 50%. The same pricing gave it about 13% odds of crossing within the week of Oct. 5.
#odds #options #trillion #morgan


8 days ago
Justin Bieber is sharing another rare glimpse of his baby boy.
The "Daisies" singer, 32, brought fans along for a recent family outing with his wife, Hailey Bieber, featuring two sweet (albeit faceless) cameos from their 2-year-old son, Jack Blues. Bieber took to Instagram on Oct. 3 with a carousel of photos showing him and the toddler visiting some furry friends during their outdoor adventure.
In one photo, baby Jack holds his dad's hand while hanging out with kangaroos; another shows him reaching to offer a leafy snack to a giraffe with his runway-star mom, 29.
The two-time Grammy winner wore a white T-shirt, camouflage bucket hat and dark sunglasses for their family time, with the toddler sporting a white tank top and white-striped green track pants.
#toddler

8 days ago
WASHINGTON (AP) — The U.S. military said it attacked a boat suspected of being used to smuggle drugs in the Caribbean Sea on Sunday, killing four people, as the Trump administration continues its yearlong campaign against alleged traffickers in Latin America.
The latest attack brings the number of people who have been killed in boat strikes by the U.S. military to at least 235 in 70 strikes since the Trump administration began targeting those it calls "narcoterrorists" in September 2025. As with most of the military's statements on strikes in the eastern Pacific Ocean and Caribbean Sea, U.S. Southern Command said it targeted the alleged drug traffickers along known smuggling routes.
The military did not provide evidence that the vessel was ferrying drugs. A video posted on X showed what appeared to be an explosion destroying a moving boat, which the military said was a go-fast vessel.
The Trump administration is pursuing deals with allied nations to extend its offensive to land across multiple Latin American countries. Defense Secretary Pete Hegseth said during a visit to Panama in August that Colombia, Guatemala and Honduras had agreed to allow the U.S. to carry out joint military operations against criminal groups on their soil. Guatemala denied reaching such a deal. Ecuador launched similar missions with the U.S. in March.
President Donald Trump has said the U.S. is in "armed conflict" with cartels in Latin America and has justified the attacks as a necessary escalation to stem the flow of drugs into the United States and fatal overdoses claiming American lives. But his administration has offered little evidence to support its claims of killing smugglers.
#boat #caribbean


10 days ago
Harvey Weinstein allegedly tried to spend $1.75 million from behind bars to influence the jury pool in his New York ****** crimes case, according to prosecutors, who say they have recordings of the disgraced Hollywood producer discussing the offer with a podcaster.
The stunning allegation emerged via The New York Post during Weinstein's sentencing for ****** ually ****** aulting former Project Runway production ****** istant Miriam "Mimi" Haley. Manhattan ****** istant District Attorney Nicole Blumberg told the court that Weinstein offered the money during a jailhouse phone call in an effort to release videos that could reach potential jurors—and even people already seated on the case.
According to Blumberg, the material was intended to help Weinstein's defense by "contaminating the jury pool and reaching the seated jurors before and after the trials." She accused Weinstein of engaging in a "scheme to disrupt the trial and instill fear in his victims."
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
Prosecutors did not publicly identify the allegedly involved podcaster. Candace Owens, however, released a 2025 podcast series ****** led Harvey Speaks that featured jailhouse videos of Weinstein, leading to speculation that she was the podcaster offered the handsome payout.
#according


10 days ago
George Armstrong, a fitness influencer who is known for preaching against cheating, found himself accused of the very thing on Friday when his account was accused of doing just that.
The posts came from his wife, Bailey Scarlett, who accessed his account and released a series of slides that appeared to be Armstrong confessing to cheating on her with Indonesian prostitutes and Dubai escorts. The posts were taken down quickly after they were published, and Scarlett later apologized, explaining that the behavior described in the slides did not take place during their relationship.
Each slide was written from Armstrong's point of view and addressed his followers, who are used to seeing him share fitness tips. The first slide was rather harsh.
Published on his Instagram, it said: "I like to cheat on the mother of my child and wife bailey.scarlett with Indonesian Prostitutes. And I definitely don't practice what I preach on Instagram, I also w**k to p**n and frequently get escorts in Dubai. But I will act like it's the most weakest thing in the world on Instagram to other men and shame them for it! I have no respect for the mother of my child or my wife. I am no outstanding father anyone should look up to. I am nothing more than a cheat who has portrayed this image for Instagram but sadly that's all it is. An image:)"
The slide was a direct hit on Armstrong's carefully constructed image.
#Dubai #prostitutes

11 days ago
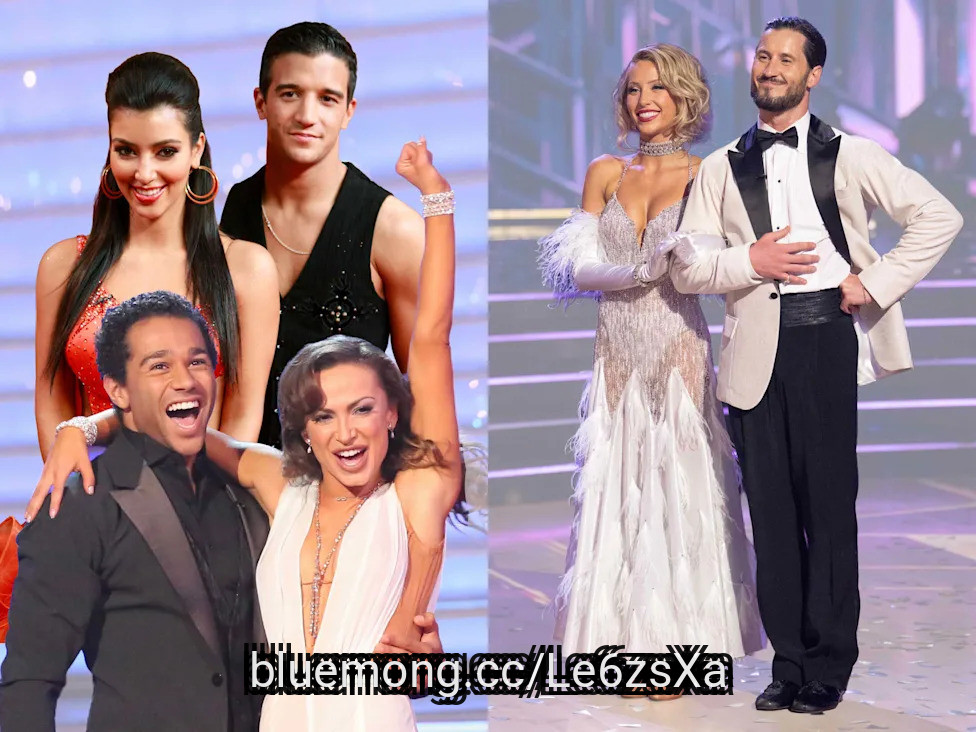
Season 35 of Dancing With the Stars premiered on September 15, 2026.
Each week, the stars and their pro partners collaborate on costumes that complement the theme and style of their dances.
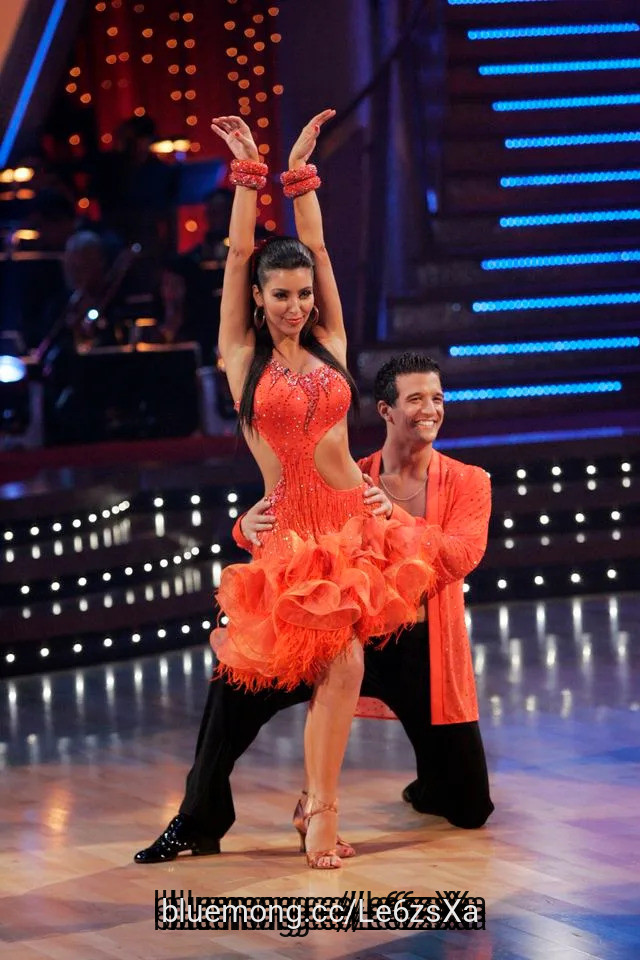
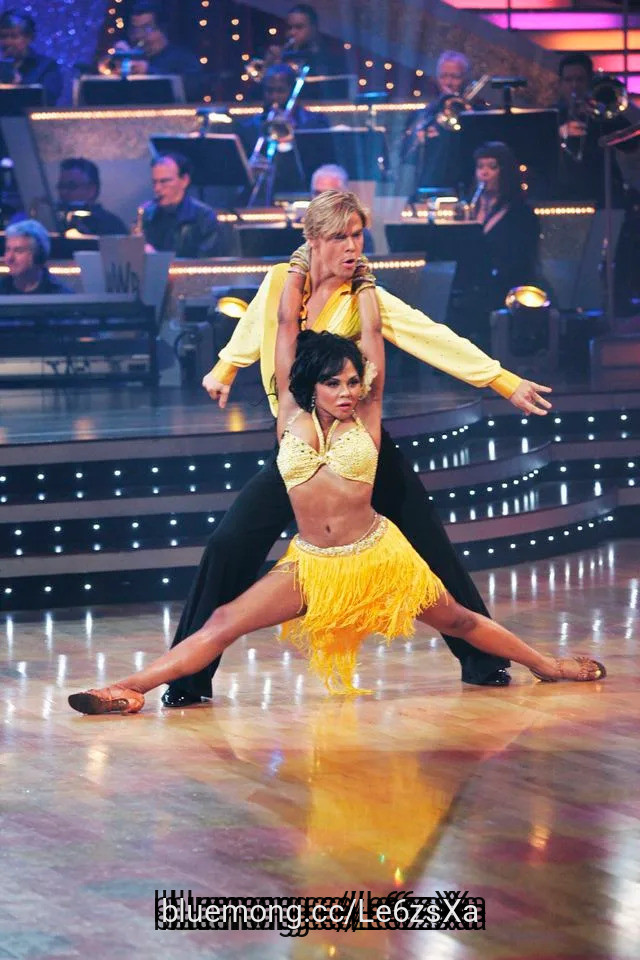
InStyle looks back at 13 of the best Dancing With the Stars fashion moments throughout the years.
You may think you're simply reaching the age when Dancing With the Stars starts catering to you, but the long-running competition series is having a major moment in general. So, no matter your age, it makes sense if you've suddenly found yourself completely engrossed in the celebrity-meets-dance-pro spectacle (and keeping who's delivering a perfect 10 each week).
Of course, the choreography is only part of the fun. The themed costumes are often just as entertaining as the dances themselves, with every performance bringing a new opportunity for sequins, fringe, feathers, sheer fabrics, and plenty of sparkle. And when Disney Night, Halloween Night, or the freestyle round rolls around, you can pretty much count on the wardrobe department pulling out all the stops. Depending on the dance and its theme, contestants can transform from Old Hollywood starlets in sweeping gowns to disco divas dripping in rhinestones—and sometimes undergo multiple transitions in a single episode.
#dancing #costumes #season
12 days ago
Jelly Roll and Bunnie XO are putting one of their Nashville-area homes up for sale after finalizing their divorce. The Franklin, Tennessee, estate now carries a price of just under $7 million. The former couple listed the property after reaching a settlement over their ******* ets.
Real estate sources told TMZ that the couple listed the home on Wednesday. The estate was custom-built and features over 10 acres and over 7,000 square feet of living area. The property has five bedrooms and seven bathrooms. It also offers views of the Tennessee countryside.
The home includes a chef's kitchen and a media den that looks over a glass-walled automotive showroom. On the outside, the estate has a covered porch and an outdoor kitchen. It also has outdoor dining and living ******* es. The outdoor ******* e is completed by a resort-style pool.
The listing is held by Erik Levin of Benchmark Realty and Greg Sanford of Greg Sanford Real Estate. The sale comes after Jelly Roll and Bunnie finalized their divorce in July. Court documents obtained by TMZ show that the former couple reached a settlement covering their aircraft, cars, homes, and intellectual property. Jelly Roll also agreed to give Bunnie a one-time lump-sum payment.
It was previously reported that movers appeared at the property in June. Exclusive photos showed a large moving truck outside while workers appeared to remove items from the home. Jelly Roll filed for divorce in May, and sources with direct knowledge said the split came from a mutual decision handled privately. Jelly Roll and Bunnie married in August 2016 after meeting the year before.
#bunnie #property #tennessee
12 days ago
"Hearst Magazines and Yahoo may earn commission or revenue on some items through these links."
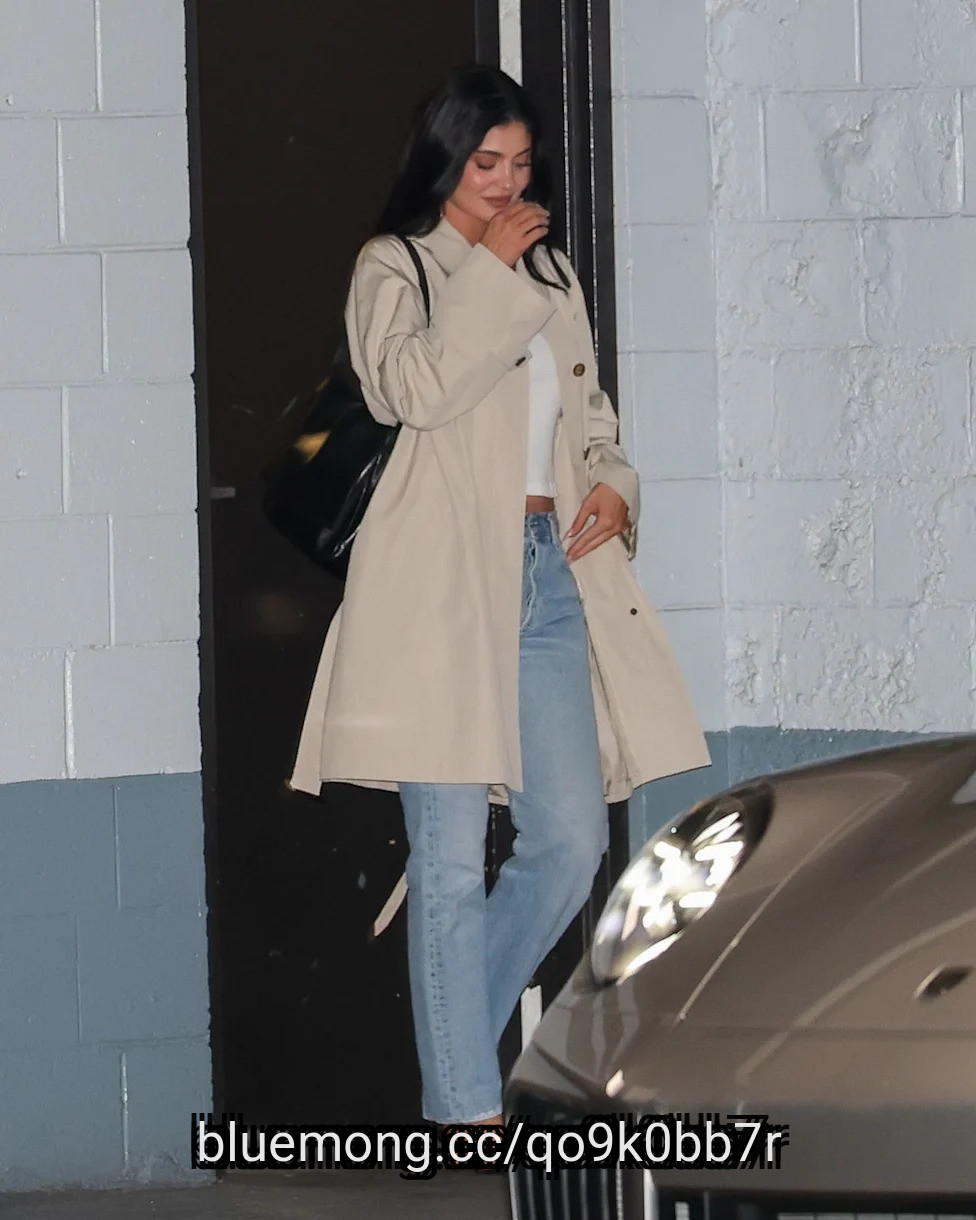
Coat season is here, and while autumn may have some reaching for their trench coats, Kylie Jenner just put her stamp of approval on another trending outerwear style: the car coat.
The it-girl approved staple has been having quite a moment. With its easy, light fit, mid-length design, and sleek silhouette, it makes for a totally versatile piece that goes well with just about anything. The style was born in the 1900s, and its name came as it was designed to allow easy movement for its wearer while driving or using transportation.
Now, decades later, the car coat has found its way to the hottest runways: Prada, Dries Van Noten, Lemaire, Meryll Rogge, and Tory Burch, to name a few. Even Burberry, best known for its polished khaki trenches, has reimagined the car coat with funky prints for the modern It girl (or It boy).
All this to say that Jenner's seemingly trivial outerwear choice—for her girls' night with Stas Karanikolaou at Sushi Park in Los Angeles—actually has a long and rich fashion history behind it. (Her sister Kendall Jenner is also a fan of the staple.)
The Khy founder styled her sharp beige car coat with a little white tee and straight-leg blue jeans in a light wash. For footwear, she traded her go-to thong sandals for a pair of strappy black heels. And to match, she carried a slouchy black leather tote. Rosy blush, paired with a bronze eye and lip, completed her effortless look.
#outerwear #name #black
15 days ago
SK Hynix is exploring something it has never done before: manufacturing memory chips in the United States.
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long
22 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
22 days ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue

23 days ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services

24 days ago
Meta Platforms (META) has spent most of 2026 trading near $648 while the business behind it delivered record quarterly revenue. That growing mismatch has drawn a wave of ******* ysts who believe the stock is meaningfully underpriced.
Second-quarter revenue reached $60.8 billion, up 28% year over year, with a 31% operating margin, Meta's earnings press release confirmed.
At a forward price-to-earnings (P/E) ratio of 19, the stock trades below the S&P 500's approximately 22 times forward earnings.
Reaching $900 would require roughly 39% upside from current levels. Whether the target is realistic depends on how quickly Meta's artificial intelligence spending produces revenue beyond its advertising business.
Meta's advertising technology is producing gains that rival any growth story in big tech. Internal model upgrades drove an 8.3% lift in ad clicks and a 15.7% conversion gain on Facebook last quarter, 24/7 Wall St reported.
#business #year

24 days ago
The ******* e Exploration Technologies (NASDAQ: SPCX) IPO was one of the most highly anticipated public offerings in years. Within a few days of going public, ******* eX had a valuation of $2.7 trillion after raising nearly $86 billion in funding.
Then things started going sideways. The stock began falling amid fears that ******* eX is spending too much on artificial intelligence (AI) infrastructure, and shares still trade below their opening price of $150 as of this writing. At one point, the share price fell enough to wipe out more than $1 trillion from ******* eX's valuation over a one-month span.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Another AI company, Anthropic, could go public as soon as next month. Like ******* eX, it's a highly anticipated IPO. But investors would be wise to take the recent ******* eX sell-off as a warning that buying IPO stocks when they first go public is rarely a good move. History shows it's far better to wait before buying -- here's why.
While there was an initial surge in interest for ******* eX, investors quickly turned their attention to the company's massive AI spending spree. The company's capital expenditures (capex) jumped 308% in the first six months of this year, compared to 2025, reaching $28.5 billion. That's a hefty sum, especially when you consider that ******* eX sales were just $12.5 billion over that same period.
#billion #first

24 days ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth

24 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax

24 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Silver (SI=F) December futures opened at $65.76 per ounce on Friday, September 18, 2026, down 0.5% from Thursday's close but more than $2 higher than yesterday's opening price. Silver prices surged this morning, reaching $67.47 as of 7:05 a.m. ET.
Until today, silver prices bounced around the $63 to $64 range, but broke out of those bookends by a wide margin this morning. Today's opening price set the highest opening price of the week, and silver is surging this morning, hitting a high of $67.89.
The Fed's decision to raise rates for the first time in three years, combined with the ongoing restoration of Saudi Arabia's key East-West pipeline, has prompted inflation concerns to fade among investors.
And oil prices are responding as well. Wednesday morning, Brent crude (BZ=F) prices were over $107 a barrel. Yesterday at this time, prices were at over $99 a barrel, and this morning, they're $98.51 as of 7:05 a.m. ET.
#disclosure


24 days ago
Picture a snowy mountain slope in France or an elite tennis court during a grand slam. Whether it is an Arc'teryx jacket designed for the harshest alpine conditions or a Wilson racket in the hands of a professional, Amer Sports (NYSE:AS) equips the world's most demanding athletes. The company functions as a global powerhouse in athletic gear and apparel, operating a premium multi-brand platform that spans from high-end technical clothing to specialized sports equipment. With its current stock price at $27.26 as of Sept. 16, 2026, the company has seen the stock decline 26% over the past year, reflecting the market's digestion of its rapid post-IPO scaling.
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium

24 days ago
Coinbase (COIN) dropped sharply when the CLARITY Act failed its Senate vote as Bitcoin barely moved, proving the bill served exchanges, not the coin.
Circle (CRCL) sold off alongside COIN while Polymarket prices Bitcoin reaching $95,000 by December at just 26%, well below Wall Street's bullish targets.
Grok flags October's Fed hike as Bitcoin's real gate, arguing that if it proves to be the last, returning ETF inflows could bring $100,000 within reach as a stretch target.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Coinbase (NASDAQ:COIN) and Circle (NYSE:CRCL) both fell sharply after the September 15 Senate cloture vote failed to advance the CLARITY Act, while Bitcoin (CRYPTO:BTC) barely moved.
#Coinbase #circle


24 days ago
VYMI outran SCHY 29% to 23% over the past year while charging a lower 0.07% fee and covering both developed and emerging markets.
IDV delivers the highest yield at 5%, but its 0.50% expense ratio is seven times VYMI's fee, eroding long-term accumulation returns.
SCHY holders switching to VYMI in taxable accounts should check cost basis first, since many carry embedded gains after 2026's international rally.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
SCHD holders reaching for international diversification usually land on one name first: Schwab International Dividend Equity ETF (NYSEARCA:SCHY), built on the same Dow Jones dividend-quality methodology that made the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) a portfolio staple. SCHY looks like SCHD's international twin because Schwab designed it that way. However, three deep-pocketed rivals from Vanguard, Fidelity, and BlackRock now compete for the same wallet share, and one has quietly outrun SCHY on nearly every metric that matters to a SCHD-style investor.
#international #schwab

24 days ago
Space Exploration Technologies Corp. (NASDAQ:SPCX) is increasingly confident it can reach a $100 billion annual revenue run rate by year-end. The company's CFO said there is now "even more conviction" around the target. A new AI hosting agreement worth $13 billion on an annualized basis adds significant support to that outlook and reflects how quickly ***** eX's compute business is scaling. But the financial picture behind that growth is less straightforward. The same AI division that management is relying on to help reach that target posted a $1.3 billion loss in the latest quarter alone. The loss wiped out what would have otherwise been a profitable quarter, while the company generated roughly negative $25 billion in free cash flow during the first half of 2026.
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly

25 days ago
AI poster-child Nvidia (NVDA) has jumped 14% year to date, but the ride's been noticeably ******* py according to Seeking Alpha data.
The stock's down nearly 6% in just one week and around the same amount over the past month, a pullback that has coincided with fresh questions over whether the breakneck AI buildout could finally lose momentum.
Consequently, that debate followed calls from some of the biggest names in AI to slow the development of frontier models for safety reasons. But on his latest "Mad Money" broadcast from Dreamforce, veteran ******* yst Jim Cramer made clear he's viewing Nvidia stock through a very different lens.
That's not hard to fathom because Nvidia continues giving bulls ammunition. Fiscal Q2 revenue more than doubled to $96.2 billion, with its Data Center business reaching $89 billion, as it pushes deeper into enterprise AI, including Salesforce's (CRM) new Koa reasoning model built on Nvidia Nemotron.
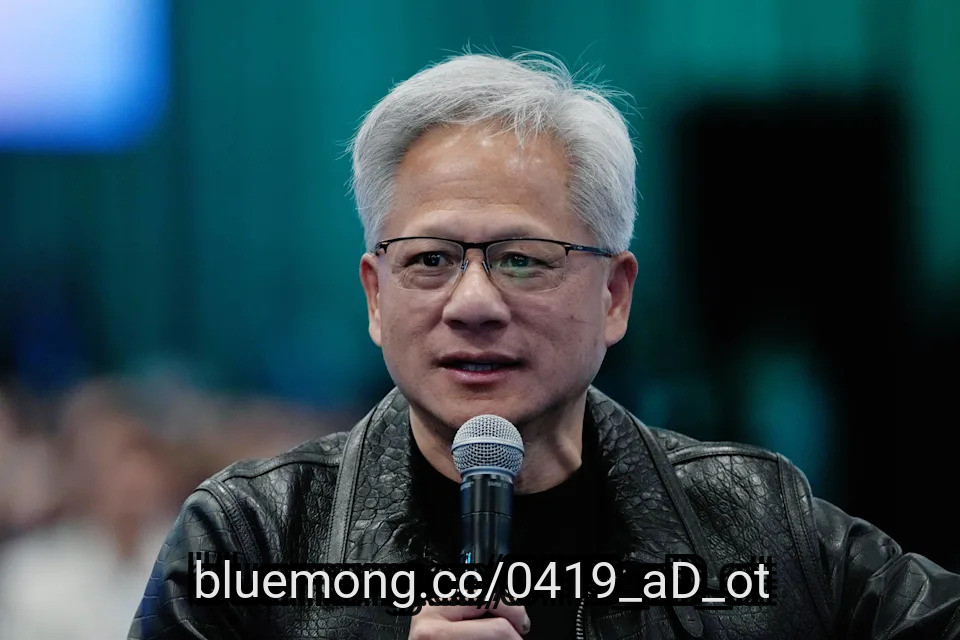
Cramer's takeaway after a sit-down with CEO Jensen Huang was hardly cautious, though. Instead of treating the latest AI scare as a reason to jump in and out of Nvidia, he framed the stock as something investors need to hold through the noise instead of trade.
#down #latest #billion
25 days ago
MercadoLibre, Inc. (NASDAQ:MELI) priced $1 billion of senior unsecured notes on September 9, 2026, with settlement scheduled for September 14 and maturity on September 14, 2036. As of September 10, the transaction had not settled.
The notes carry a 5.85% coupon, with proceeds intended for general corporate purposes. Once settled, they would require $58.5 million in annual coupon payments on the full principal outstanding, alongside repayment of $1 billion at maturity.
Management retains discretion over deployment. Logistics, payments, credit and commerce represent potential uses within the business, rather than disclosed allocations of this particular offering.
Ten-year funding can better match investments whose benefits emerge over several years. Logistics facilities need time to attract shipment volume, while financial-services products require investment in technology, customer acquisition and risk management before reaching scale.
For MercadoLibre, Inc. (NASDAQ:MELI), that longer horizon could reduce dependence on repeated short-term refinancing. A fixed coupon also makes contractual dollar interest payments more predictable if market borrowing rates rise.
#payments

25 days ago
October WTI crude oil (CLV26) closed down -3.40 (-3.21%) on Wednesday, and October RBOB gasoline (RBV26) closed up +0.0198 (+0.57%).
Crude oil and gasoline prices settled mixed on Wednesday, with gasoline climbing to a 3-week nearest-futures high. Crude prices fell sharply on Wednesday as signs emerged that more crude supplies are reaching the market, easing supply concerns. Losses in crude accelerated on Wednesday after weekly EIA crude inventories fell less than expected and gasoline and distillate supplies rose more than expected. Also, Wednesday's rally in the dollar index ($DXY) to a 1.5-month high undercut energy prices.
Crude Oil Prices Retreat as Supply Fears Ease
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#crude #wednesday #supply #high
26 days ago
The choice between established ****** ans and digital-first challengers defines many modern portfolios. In the financial realm, investors must decide if JPMorgan Chase (NYSE:JPM) or SoFi Technologies (NASDAQ:SOFI) is the better buy for long-term growth.
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term

26 days ago
MINNEAPOLIS (AP) — The man who sprayed vinegar at Democratic U.S. Rep. Ilhan Omar during a Minneapolis town hall was sentenced Thursday to 14 months in prison after reaching a deal with prosecutors.
Anthony Kazmierczak, 56, was sentenced nearly eight months after the Jan. 27 ******* ault. At the time, Minneapolis-St. Paul was subject to an immigration crackdown that led to angry protests, arrests and the deaths of two U.S. citizens. Prosecutors had recommended a 14-month prison term.
He was also sentenced to three years of supervised release, which includes no contact with Omar. U.S. marshals escorted him from the courtroom after the hearing.
During an earlier hearing, Kazmierczak was unable to explain his actions.
"It's fuzzy," he told U.S. District Judge Joan N. Ericksen when asked what he remembered.
#ilhan


26 days ago
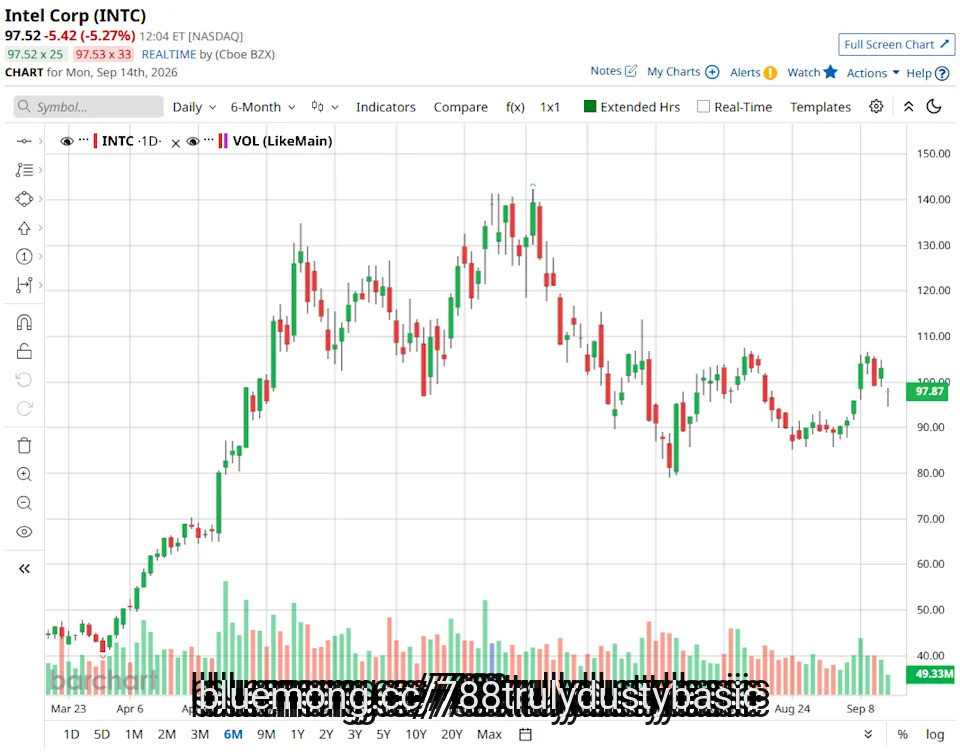
Mizuho has identified four clear tailwinds for Intel (INTC): ongoing CPU supply shortages, a stronger PC refresh cycle, accelerating demand for agentic AI, and growth in advanced packaging. Normally, such a setup would provide a reason to raise a price target. Instead, the firm cut its price target from $109 to $92, citing short-term multiple compression across Agentic AI stocks, and maintained a "Neutral" rating. The contradiction becomes more important because Intel's re-rating still depends on a foundry turnaround that has yet to prove itself.
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four

26 days ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
26 days ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry


