12 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
12 days ago
On September 17, B. Riley initiated coverage of Nokia Oyj (NYSE:NOK), giving the stock a Buy rating and setting the price target at $15. The firm pointed to the company's position in telecom infrastructure, cloud software, and hardware networking solutions.
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm

12 days ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
12 days ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional
12 days ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
12 days ago
Transocean Ltd. (NYSE:RIG) received a boost on September 15 when the company announced that it had secured an approximately $80 million contract for its Deepwater Conqueror ultra-deepwater drillship in Equatorial Guinea. The estimated 170-day campaign with an undisclosed operator is expected to begin next year, directly following the rig's current contract in the US Gulf.
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial
12 days ago
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
13 days ago
The first full week of trading in September didn't give Zscaler (NASDAQ: ZS) investors much to celebrate. During the shortened trading week that followed Labor Day, Zscaler dropped about 3%. This week, however, is a very different story, thanks to a firm providing an auspicious outlook for the cybersecurity stock.
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week
13 days ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment

14 days ago
Saving for retirement is hard. For starters, humans aren't very good at delaying gratification. And saving is basically choosing not to spend today so you can spend, hopefully even more, in the future. But there's another problem with saving for retirement: it is hard to set a goal. There's one popular retirement rule that can help with that. Here it is.
When you think about money, the gut reaction is to compare yourself to other people. That's understandable, but it can lead you into troubling waters. For example, the average 65 to 74-year-old has a net worth of nearly $1.8 million. So, you could argue that by 67 you should have that much money saved up. But that figure mashes together the very rich with people who aren't as fortunate. The median net worth, with half of all people above and half below, is roughly $410,000, which is a lot lower. Which one is the better target?
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
That doesn't even consider the fact that net worth includes ***** ets like a home, which isn't something you can easily tap for cash. Sure, you could sell your home and move into a small residence, but you still need to live somewhere. And you aren't average or median. You are you, and your earnings and savings numbers are unique.
That's where a simple savings rule comes in, based on your salary. Essentially, you are creating a personalized saving goal for retirement. To cut to the end of the story, the rule is that you should have 10x your salary saved by age 67. But that's just the final step in the process, because the rule provides benchmarks all along the way to keep you on track.
#spend

14 days ago
Owning a $400,000 Villages home costs owners roughly 4.5% annually in forgone investment income alone, before taxes, insurance, or CDD bond payments.
Annual rentals run between $2,200 and $3,000 a month, but renting beats owning only for stays under eight years once all costs are counted.
A 75-year-old facing a forced sale in a narrow buyer pool at 3.98 million existing home sales risks losing the flexibility a lease ending provides.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
At the end of the day, renting versus buying in The Villages comes down to one thing: math. More owners are running the numbers and finding that renting wins on the spreadsheet, so here is what the comparison actually looks like when every line is filled in.
#income

14 days ago
Des Moines, Iowa-based Principal Financial Group, Inc. (PFG) provides retirement, ******* et management, and insurance products and services to businesses, individuals, and institutional clients worldwide. The company has a market cap of $25 billion and operates through Retirement and Income Solutions, Principal ******* et Management, and Benefits and Protection segments.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." PFG fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the ******* et management industry.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#asset #management #market #moines

14 days ago
SEIC provides investment processing, management, and operational platforms for private banks, financial advisors, institutional investors, and financial managers. SEIC's second-quarter fiscal 2026 report showed revenue of $641.6 million (a 14.7% year-over-year gain), adjusted per-share earnings of $1.66 (a 38% rise), $207 million in operating income (a 36% jump) – all of which were quarterly records – and the company has nearly $400 million in cash for more growth ahead.
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock


14 days ago
This story was originally published on Trucking Dive. To receive daily news and insights, subscribe to our free daily Trucking Dive newsletter.
Truckload LLC, doing business as Expedite Express, filed for Chapter 11 bankruptcy last week, a process typically done to reorganize operations.
The Southwest Florida-based carrier estimated its **** ets between $100,000 and $500,000 with estimated liabilities of $50,000 or less, per a voluntary petition in court. The business also suggested it had at least 50 creditors.
The business has four power units and eight drivers, according to a federal database as of early June, and provides services across North America, per its website.
Expedite Express joins a list of trucking companies declaring bankruptcy in 2026 as financial and operational challenges continue to batter the industry.
#dive #estimated #chapter

14 days ago
On September 8, 2026, CNBC reported that Novartis AG (NYSE:NVS) shares fell about 10% after the company said its experimental drug del-desiran failed to meet its primary goal in a late-stage trial for myotonic dystrophy type 1.
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib

14 days ago
Tesla's (NASDAQ: TSLA) business is in an interesting spot. The company saw a significant sales rebound in the second quarter, with revenue rising 26% year over year to reach $22.5 billion. Recent reports also suggest that the company's share of the U.S. electric vehicle (EV) market has risen sharply amid a substantial sales contraction for the overall industry. And while the company's net income fell 5% annually in the second quarter, the business still recorded net income of $1.11 billion in the period.
On the other hand, positive net income doesn't tell the whole story because the metric doesn't include capital expenditures (capex) that are recorded as ****** ets on the balance sheet. With Tesla betting big on its robotaxi project, Optimus humanoid robots, and other potential growth drivers, the company recorded $5.79 billion in capex in Q2. As a result, the business posted -$1.1 billion in free cash flow (FCF) in the period. With FCF coming up negative lately, the company's $43.5 billion cash position provides a valuable cushion.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Tesla posted substantial sales growth in the second quarter as some of the pressures facing the brand eased, higher gas prices encouraged EV purchases, and price cuts helped spur demand. On the other hand, it remains to be seen whether this sales growth momentum is sustainable -- and banking on the core EV business to be an earnings driver that can support the company's highly growth-dependent valuation seems unwise.
While Tesla has seen competitors based in the U.S., ****** an, and South Korea reduce their focus on the EV market, BYD and other China-based rivals are making inroads in the market and continue to bet heavily on long-term growth in the category. CEO Elon Musk appears to have a good grasp on the challenging competitive landscape and has been positioning robotaxis, humanoid robots, and semiconductor projects as the core elements of his company's growth strategy.
#NVIDIA
14 days ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas
14 days ago
Logistic Properties of the Americas (NYSEAMERICAN:LPA) moved closer to selling Parque Logístico Lima Sur after Peru's antitrust authority, INDECOPI, approved the transaction on September 11. FIBRA Prime would acquire the entire 1.3-million-square-foot logistics park for $145 million. Customary administrative closing matters remain outstanding.
Management expects approximately $85 million of net proceeds after debt repayment and before taxes, with Mexico the intended destination. Approval advances the financing of that expansion, while the investment case rests on replacing an established income stream.
Lima Sur generated $10.3 million of cash net operating income, or cash NOI, during the 12 months ended March 31, 2026. Cash NOI is a company-defined non-IFRS measure of property income after operating expenses, adjusted to remove straight-line rental accounting. It excludes corporate overhead, financing costs, income taxes, and other non-property items.
Logistic Properties of the Americas (NYSEAMERICAN:LPA) has demonstrated an ability to develop, lease and operate logistics ***** ets. Second-quarter revenue increased 26.1% to $14.7 million, while stabilized portfolio occupancy reached 100% as of June 30.
Mexico already contributes revenue. Two properties acquired in Puebla in August 2025 generated approximately $0.5 million during the second quarter. That provides an operating foothold for deploying proceeds.
#cash #logistic #nyseamerican #Mexico
15 days ago
Fenimore ***** et Management, an investment management company, released its Q2 2026 investor letter. The letter can be downloaded here. U.S. equity markets saw broad gains in Q2, driven by strong corporate earnings, economic resilience, and enthusiasm for artificial intelligence (AI). Major indices reached all-time highs, though the energy sector declined. Continued earnings growth, especially among AI-related investments, supported the rally. Technology, particularly semiconductors, led performance as demand for AI infrastructure surged. Despite macroeconomic uncertainties and interest rate influences, Fenimore remains committed to investing in high-quality businesses. The Fenimore Small Cap Strategy returned 9.51% in the quarter, lagging the Russell 2000 Index's 21.49% gain. The underperformance was largely driven by avoiding lower-quality tech stocks linked to data center expansions. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Fenimore ***** et Management highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On September 17, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $40.03 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -8.32%, and its shares lost 25.53% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $10.15 billion.
Fenimore ***** et Management stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"We initiated a position in Ryan Specialty Holdings, Inc. (NYSE:RYAN), which we had previously owned after its initial public offering. The insurance industry has seen softness in rates. While RYAN's model differs from traditional retail brokerage, the company released results citing a volatile environment which led to a decrease in their earnings outlook for the year. We're encouraged by the business's long-term prospects and, in our opinion, its legendary leader Pat Ryan. He is also purchasing shares of RYAN's stock during this weakness."
Ryan Specialty Holdings, Inc. (NYSE:RYAN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 32 hedge fund portfolios held Ryan Specialty Holdings, Inc. (NYSE:RYAN) at the end of the second quarter, compared to 35 in the previous quarter. While we acknowledge the potential of Ryan Specialty Holdings, Inc. (NYSE:RYAN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.

15 days ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange

15 days ago
AeroVironment, Inc. (NASDAQ:AVAV) reported on September 9, 2026, that revenue for fiscal Q1 2027, ended August 1, 2026, increased 6% to $480.5 million. Funded backlog reached approximately $1.5 billion at quarter-end, up from $1.2 billion at April 30, 2026. This represents remaining work under firm customer orders with funding already appropriated, providing a concrete base for future revenue.
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity

15 days ago
Fox Corporation (NASDAQ:FOXA) disclosed on September 9 that the U.S. Department of Justice issued a second request for information concerning the proposed acquisition of Roku, Inc. (NASDAQ:ROKU). Cooperation with the review continues, and the expected closing remains in the first half of 2027, according to The Wall Street Journal.
A second request extends the premerger waiting period while regulators seek additional documents and data. For investors, the question is whether Fox Corporation (NASDAQ:FOXA) can preserve the acquisition's streaming benefits through a potentially longer review and any conditions attached to clearance.
The strategic fit centers on combining content with distribution. Roku, Inc. (NASDAQ:ROKU) reaches more than 100 million households globally and would provide Fox Corporation (NASDAQ:FOXA) with an established connected-television platform, advertising technology and direct consumer relationships.
That reach could create additional opportunities to promote live news, sports and streaming services. For advertisers, a broader combination of content, audience data and campaign tools could make the combined offering more useful, provided integration improves targeting and measurement.
The commercial opportunity also extends beyond audience growth. Better advertising monetization and more efficient promotion of streaming services could improve the value generated from existing viewers. Household reach provides the starting point; advertising revenue, engagement and customer acquisition costs would determine the financial payoff.
#advertising #second #request #review


15 days ago
Circle Internet Group, Inc. (NYSE:CRCL), issuer of the dollar-backed USDC stablecoin, announced on September 8 an agreement to acquire Singapore-based Tazapay, which serves payment providers and financial institutions.
Circle Internet Group, Inc. (NYSE:CRCL) agreed to pay approximately $400 million in Class A common stock, subject to adjustments for debt, cash, and transaction expenses. Separately, the agreement provides for $25 million of post-closing employee restricted stock unit awards.
As of July 31, 2026, Tazapay had more than $25 billion of annualized payment volume, over 60 banking and fintech partners, and payout capabilities across more than 100 markets. Approximately 60% of transaction volume involves stablecoins; USDC's share was not specified. Payment volume represents funds processed, not revenue.
Closing is expected in 2027, subject to customary conditions and regulatory approvals, including approval from the Monetary Authority of Singapore.
Tazapay would strengthen the connections between digital dollars and local bank payments. Within the Circle Payments Network, originating institutions can convert funds into stablecoins for settlement, while receiving institutions convert them into local currency and pay recipients. Merchants can benefit without requiring every customer or supplier to hold tokens.
#tazapay

15 days ago
Heavy volume in Apple Inc. (AAPL) puts expiring in one year with a strike price 4% lower shows that institutional investors are bullish on AAPL. In addition, this short-put play provides a 6.76% one-year yield.
AAPL is trading at $322.96 midday on Wednesday, Sept. 16. This is off a recent peak of $340.08 on July 28, but up from a trough of $302.25 on Aug. 12.
Adobe Stock is Dirt Cheap After Its Recent Results - What's the Best Way to Play ADBE?
Why Wall Street Could Be Pricing This GE Stock Option Spread Incorrectly
Unusual Out-of-the-Money Put Option Volume in Amazon Shows Investors Bullish on AMZN
#bullish #play #recent #year

15 days ago
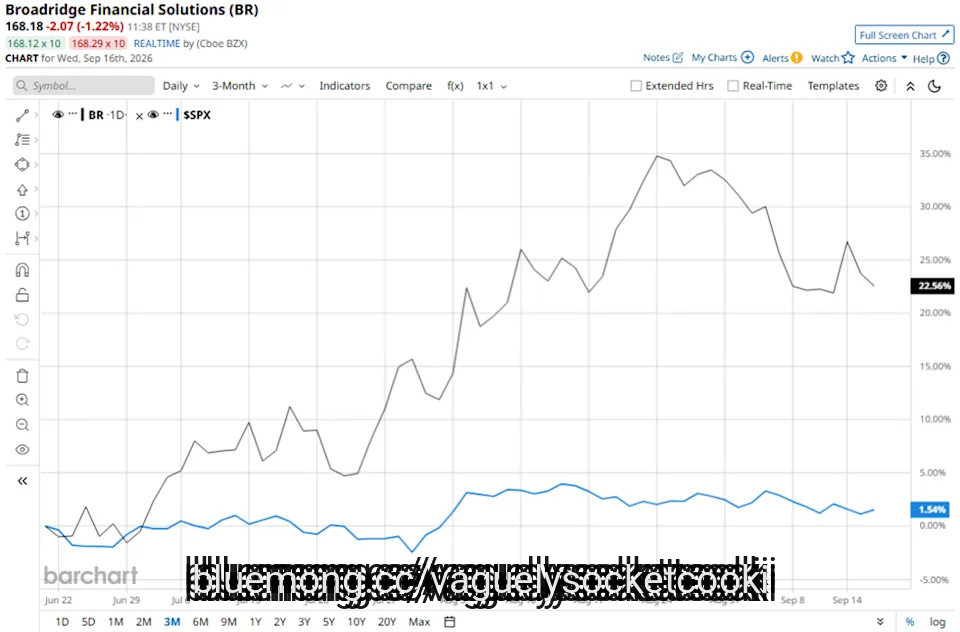
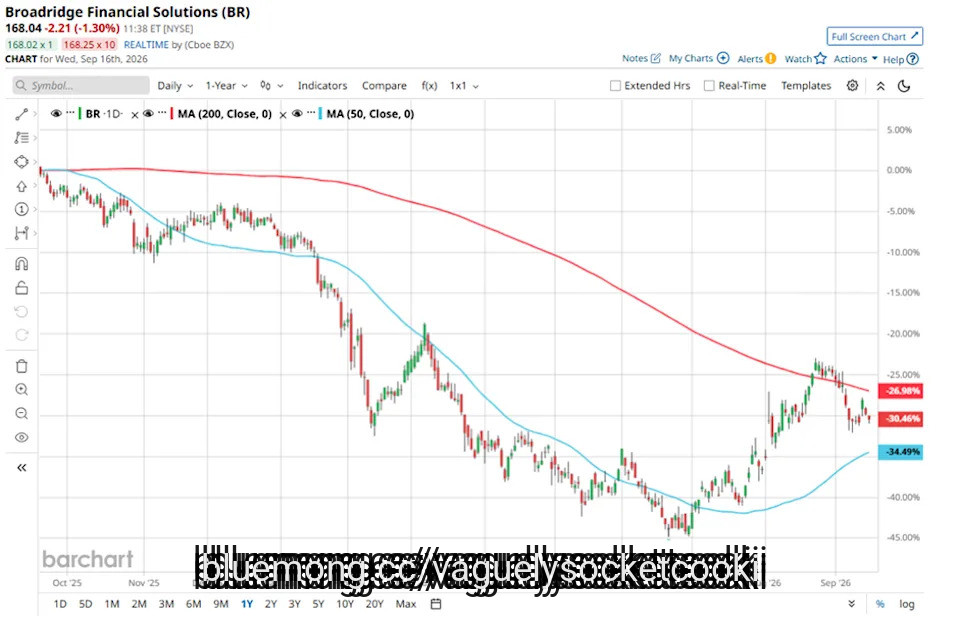
With a market cap of $19.4 billion, Broadridge Financial Solutions, Inc. (BR) is a global financial technology leader that provides investor communications and technology-driven solutions to banks, broker-dealers, ***** et managers, corporate issuers, and other financial institutions. Broadridge plays a critical role in enhancing transparency, efficiency, and engagement across the financial services industry.
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Broadridge Financial fits this criterion perfectly. Through its two segments: Investor Communication Solutions and Global Technology & Operations, the company delivers services ranging from regulatory and shareholder communications to front-to-back securities processing and data-driven solutions.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#financial #broadridge
15 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre

15 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
15 days ago
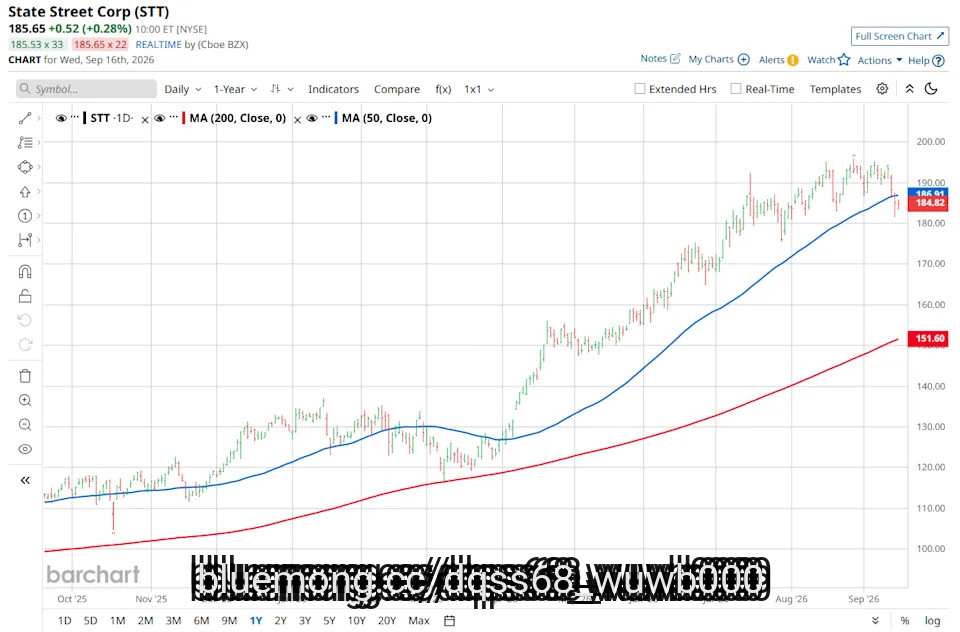
Boston, Massachusetts-based State Street Corporation (STT) provides a range of financial products and services to institutional investors. Valued at a market cap of $50.9 billion, it offers custody, accounting, and fund administration services for traditional and alternative ****** ets, as well as multi-asset-class investments, recordkeeping, client reporting, and more.
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." STT fits squarely in that category, with a market cap above this threshold that reflects its size and influence in the ****** et management industry.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#market #street

15 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

15 days ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor