16 days ago
Troy Aikman and his girlfriend, Marisa Howard, celebrated a milestone in style this week, enjoying an intimate birthday dinner at an upscale Dallas restaurant.
Howard, 40, took to her Instagram Story to share a snapshot of the 59-year-old Pro Football Hall of Famer with his arm wrapped around her and captioned the post, "Best night." Aikman reposted the image before sharing a rare photo set go photos on Instagram with the caption, "Happy Birthday Beautiful."
View this post on Instagram
A post shared by troy aikman (troyaikman)
The romance between the pair first captured public attention when D Magazine reported last year that they were spotted taking hot yoga classes together in Dallas. At the time, Howard was going through a divorce from her ex-husband, Frank Howard Jr., whom she filed to split from in July 2024. Howard shares two daughters with her ex and previously worked as the director of communications for his company, GeneIQ, a molecular diagnostic laboratory.
#Instagram #aikman
25 days ago
Westinghouse Air Brake Technologies Corporation (NYSE:WAB) announced on September 21 a services agreement worth more than $700 million with La Compagnie du TransGuinéen. Combined with locomotive orders placed in 2024, announced agreements for the Simandou project now exceed $1.2 billion.
The railway stretches more than 600 kilometers between the Simandou mine and Guinea's Port of Morebaya. The new agreement extends the relationship beyond locomotive delivery into ongoing fleet support. For investors, the opportunity is to earn revenue throughout the equipment's operating life.
Westinghouse Air Brake Technologies Corporation (NYSE:WAB) will provide scheduled and unscheduled maintenance, parts, component overhauls, logistics support, remote diagnostics, and training. These activities create multiple opportunities to serve the same fleet after the initial equipment sale.
That is an attractive business model when maintenance needs translate into repeat orders and efficient service delivery. Familiarity with the locomotives should help technicians diagnose problems and plan repairs. Remote monitoring could also help identify faults before they cause prolonged downtime, strengthening the customer's incentive to maintain the relationship.
Local workforce development and partnerships with Guinean businesses could improve responsiveness as the operation matures. Over time, an experienced local team could reduce dependence on specialists traveling to the site and make parts planning more efficient.
#westinghouse #brake #agreement
1 month ago
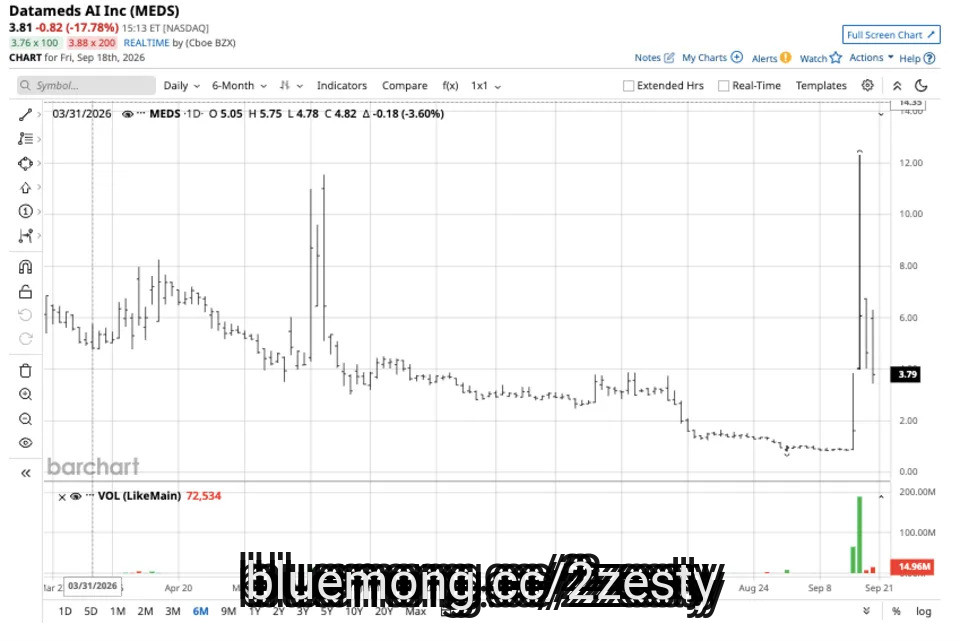
DataMEDS AI (MEDS) announced on Sept. 15 that it acquired Helomics and a lab services business, sparking a huge rally in MEDS stock. Shares of MEDS stock gained 87% on Sept. 15 and 275% in the following session. Like the lab services unit, Helomics was sold by Axe Compute (AGPU) and utilizes artificial intelligence (AI) for cancer diagnostics and treatment.
Generally, I'm a big fan of using AI in medicine, and a fan of the companies that do so. In fact, I own two stocks — Schrodinger (SDGR) and Radnet (RDNT) — that specialize in this area; Schrodinger uses AI to help speed up the drug-discovery process, while many of Radnet's diagnostic medical devices utilize AI.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#meds #shares

1 month ago
On September 16, IDEXX Laboratories (NASDAQ:IDXX) announced it had bought CoVetAI, a fast-growing veterinary software company whose tool listens during appointments and organizes what gets said and done. It sounds like a productivity gadget. But IDEXX is pitching it as a way to put the right patient details in front of a vet at the moment they decide what to test. The price was not disclosed, so the strategy is the story.
Start with the customer base IDEXX already has. More than 10,000 clinics worldwide run on its cloud practice software, and CoVet will plug into that system, including a link to IDEXX VetConnect PLUS. That hands a new product a ready audience. CoVet also works with practice systems IDEXX does not make, and IDEXX plans to keep supporting rival scribes, so the tool can reach clinics and regions the company does not serve today.
Then there is the engine this could feed. On August 4, IDEXX reported second-quarter revenue growth of 10%, and its recurring diagnostics business grew 11%, powered by higher volumes. That says vets are already running more tests, which is the behavior a smarter workflow tool is meant to encourage. The company also placed more than 1,600 inVue Dx ****** yzers in the quarter, lifting the installed base past 9,000, and it counts that instrument among its AI-driven products. Software and hardware are pointing in the same direction.
The biggest problem is what we can't see. Without deal terms, there is no way to judge what IDEXX paid or how much CoVet matters to earnings. And the company describes the payoff in future tense, saying these capabilities can raise diagnostic use over time. That is a hope, not a result yet. CoVet's openness to other systems cuts both ways too. It widens reach, but it also means a clinic can use CoVet without going deeper into IDEXX's ecosystem.
The second quarter also needs a careful read. Earnings per share rose 18%, but that included tax benefits from stock-based pay and a currency boost, and growth on a comparable basis was 15%. Some of the gain, in other words, did not come from selling more to vets. IDEXX also says it is spending more on commercial and innovation priorities, so its higher full-year earnings outlook comes with added costs attached.
#company #software #earnings #already

1 month ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Revolution Medicines, Inc. (NASDAQ:RVMD) as a new addition. Revolution Medicines, Inc. (NASDAQ:RVMD) is a clinical-stage precision oncology company that develops novel targeted therapies for RAS-addicted cancers. On September 15, 2026, Revolution Medicines, Inc. (NASDAQ:RVMD) closed at $204.86 per share. Over the past month, Revolution Medicines, Inc. (NASDAQ:RVMD) declined 6.53% and its shares gained 358.00% over the past 52 weeks. Revolution Medicines, Inc. (NASDAQ:RVMD) has a market capitalization of $43.91 billion.
Parnassus Growth Equity Fund stated the following regarding Revolution Medicines, Inc. (NASDAQ:RVMD) in its Q2 2026 investor letter:
"In the Health Care sector, we see compelling long-term idiosyncratic growth opportunities in drug discovery, diagnostics and medical innovation. During the quarter, we added Revolution Medicines, Inc. (NASDAQ:RVMD), developer of a promising new drug for pancreatic cancer. Revolution Medicines' lead drug candidate, daraxonrasib, has delivered strong late-stage clinical results in pancreatic cancer, with data suggesting it could become a new standard of care and support significant commercial potential, alongside additional opportunities in other cancers over time."
Revolution Medicines, Inc. (NASDAQ:RVMD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 105 hedge fund portfolios held Revolution Medicines, Inc. (NASDAQ:RVMD) at the end of the second quarter, compared to 106 in the previous quarter. While we acknowledge the potential of Revolution Medicines, Inc. (NASDAQ:RVMD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Tr
1 month ago
Stanley Druckenmiller has quite a long and distinguished career as an investor. Much of this has to do with high-risk bets that have paid off enormously, such as when he and his boss, George Soros at Quantum Fund, shorted the U.K. pound for a handsome profit of what was reported to be around $1 billion.
For that reason, the trades Druckenmiller makes with his Duquesne family office matter, and his picks are taken seriously. One of the more intriguing ones is Duquesne's largest holding currently -- and for eight quarters now. It's not a famous name; rather, it's a next-generation healthcare diagnostics company that was once something of a sleeper. Here's a bit more about it.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This huge bet on the future is Natera (NASDAQ: NTRA), a medical diagnostics company that uses unique, state-of-the-art technology to evaluate a patient's blood sample. Natera isn't the only business providing these liquid biopsies, as they're known, but its personalized, tumor-informed approach makes it a best-in-class screener in numerous use cases.
The major one is oncology, which is hardly surprising given the prevalence of cancer. Natera has a set of tests for this, led by Signatera, a highly personalized one constructed from the patient's tumor profile. With this, it detects circulating tumor DNA in the blood. To say this is useful in cancer detection is an understatement, so it's hardly surprising that Natera processed roughly 296,700 oncology tests in the company's second quarter. That was up a highly impressive 57% year over year.
#tumor

1 month ago
Durham, North Carolina-based IQVIA Holdings Inc. (IQV) provides healthcare research services. Valued at $42.3 billion by market cap, the company offers ******* ytics, technology solutions, and clinical research services to the life sciences industry which helps them in the clinical development and commercialization of medical treatments that improve healthcare outcomes for patients.
Companies worth $10 billion or more are generally described as "large-cap stocks," and IQV perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the diagnostics & research industry. With strong revenue growth and a global presence in over 100 countries, IQVIA's expertise and scale provide a competitive edge that is hard to replicate.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#Research #Stock #healthcare


1 month ago
IDEXX Laboratories, Inc. (IDXX) is a leading animal-health diagnostics and technology company best known for providing veterinarians with diagnostic testing, laboratory services, software, and imaging solutions. Valued at a market cap of $45.7 billion, the company develops and supplies diagnostic instruments, test kits, software, and laboratory services that help veterinarians, farmers, and laboratories detect diseases and monitor animal health.
Companies worth between $10 billion and $200 billion are typically classified as "large-cap stocks," and IDXX fits the label perfectly. The company is widely recognized as a market leader in veterinary diagnostics, supported by strong brand recognition, a large installed base of diagnostic instruments across veterinary practices, and a recurring revenue model fueled by consumables and testing services. With its solutions used by veterinary practices in more than 175 countries, the company has built a strong global presence and a broad, highly recurring customer base.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#Services #Stock #laboratories


1 month ago
CVS Health (NYSE: CVS) dealt with significant headwinds after the COVID-19 pandemic. The company's financial results suffered as sales of coronavirus-related products (such as diagnostic tests) declined, while expenses in its insurance business rose substantially, resulting in lower profits and margins. However, CVS Health has done a good job of addressing those problems, and the stock has rebounded. Shares are up 31% over the past 12 months. Wall Street thinks there may be even more upside on the horizon. CVS Health's average price target is $116.04 (according to Yahoo! Finance), implying a meaningful 20% upside from current levels. Is now a great time to buy the stock?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past 18 months (or so), CVS Health has implemented several initiatives that have helped improve its business. For instance, the company closed dozens of stores, many of which were unprofitable. The pharmacy chain specialist also scaled back its insurance division, notably by exiting the Affordable Care Act marketplace. The results have been pretty impressive. Consider the company's second-quarter results. CVS Health's revenue increased by a healthy 7.3% year over year to $106.1 billion.
Adjusted earnings per share were $2.58, 42.5% higher than the year-ago period. Note the improvement in CVS Health's healthcare benefits segment, which offers health insurance services. Operating expenses as a percentage of revenue declined slightly to 12.4%, down from 12.5% in the prior-year quarter, even as revenue grew 3.5% year over year. And operating margins within this unit came in at 5.8%, up from the 2.8% reported in the year-ago period. Also, CVS Health's medical benefits ratio -- the percentage of insurance premiums the company spent on medical care (the lower the better) -- declined to 87.4% in the second quarter, down from 89.9% in Q2 2025.
CVS Health also increased its guidance for the full fiscal year 2026. The company now expects its adjusted EPS to fall between $7.90 and $8.10, up from its previous range of between $7.30 to $7.50. The company is also now projecting cash flow from operations of at least $11.5 billion, up from the previous lower bound of $9.5 billion. These are signs of a much-improved business.
#insurance
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Impax ***** et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Zoetis Inc. (NYSE:ZTS). Zoetis Inc. (NYSE:ZTS), an animal health company focused on animal health medications, vaccines, and diagnostic products, detracted from the Fund's performance during the quarter. On September 04, 2026, Zoetis Inc. (NYSE:ZTS) closed at $75.81 per share. Over the past month, Zoetis Inc. (NYSE:ZTS) returned 1.31%, but its shares are down 50.04% over the past year. Zoetis Inc. (NYSE:ZTS) has a market capitalization of $31.33 billion.
Impax US Sustainable Economy Fund stated the following regarding Zoetis Inc. (NYSE:ZTS) in its Q2 2026 investor letter:
"Zoetis Inc. (NYSE:ZTS) (Pharmaceuticals, Health Care) is owned for its attractive sustainability opportunity profile in areas including Wellbeing and Evolving Health Care Challenge, as well as its strong governance profile. The stock declined sharply in the quarter following a downward revision to near-term earnings guidance. Sales of Librela, the company's key canine arthritis pain management product, continued to face headwinds from safety perception concerns among some veterinarians, and management indicated that the ramp-up of next-generation product launches would extend into the following year."
#economy #Health

2 months ago
On August 5, OraSure Technologies (NASDAQ:OSUR) reported second-quarter 2026 results that included its first GAAP net income in years, a headline number of $6.2 million versus a $19.7 million loss a year earlier. Revenue of $30.6 million beat the company's own guidance range and climbed 9.7% from the prior quarter. But look past the top line and the story splits in two, one part driven by real operating progress, the other by an accounting adjustment tied to a regulatory setback.
Some of this quarter's improvement came from actual operations. Gross margin expanded to 43.5% on a GAAP basis, up from 42.1% a year earlier, and non-GAAP gross margin rose to 44.2% from 43.2%. Diagnostics revenue grew 1% year over year to $19.4 million, helped by higher syphilis test sales and the addition of BioMedomics' Sickle SCAN product line. OraSure also picked up two regulatory wins during the quarter. In June 2026, the FDA cleared its Colli-Pee Dx urine collection kit for use with Roche's **** ually transmitted infection tests, letting patients collect samples at home instead of in a clinic.
The following month, the FDA granted Emergency Use Authorization for the second-generation OraQuick Ebola 2.0 Rapid Antigen Test, which can detect all four Ebola virus strains known to cause disease in humans. Cash used in operating activities improved to $23.8 million over the first six months of 2026, down from $30 million a year earlier, a sign the cash burn is easing. The company also kept buying back stock, repurchasing $22 million of shares, or 7.7 million shares, against its $40 million authorization, retiring more than 10% of shares outstanding.
The GAAP profit that headlines this quarter didn't come from the business getting more profitable. It came almost entirely from a $22.6 million reduction in a contingent consideration liability, an accounting entry triggered when OraSure updated its regulatory submission plan for the CT/NG test on its Sherlock platform. Strip that adjustment out and the underlying trend looks different. Non-GAAP operating loss widened to $14.7 million from $13.2 million a year earlier, and non-GAAP net loss came in at $13.8 million, roughly in line with last year's $14.2 million loss. The regulatory event behind that accounting gain is itself a setback.
In July, OraSure withdrew its InteliQuick CT/NG molecular self-test submission after receiving FDA feedback, meaning the product's path to market is now delayed while the company prepares a future resubmission. Total revenue for the quarter was still down 2% year over year, and core revenue, which excludes COVID-19 and Risk **** sment Testing, was flat. Six-month revenue fell 4% to $58.6 million. Sample Management Solutions revenue stayed flat year over year at $9.9 million, showing no growth driver of its own. Cash and equivalents fell to $161 million at quarter-end from $199.3 million at the end of 2025, pulled down by continued buybacks and cash used in operations.
#year #gaap #reven
2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ***** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Danaher Corporation (NYSE:DHR). Danaher Corporation (NYSE:DHR) is a healthcare and life science tools company operating through Biotechnology, Life Sciences, and Diagnostics segments. On September 02, 2026, Danaher Corporation (NYSE:DHR) closed at $209.91 per share. Over the past month, Danaher Corporation (NYSE:DHR) returned 4.97%, and its shares gained 5.47% over the past 52 weeks. Danaher Corporation (NYSE:DHR) has a market capitalization of $147.56 billion.
Eagle Capital Management stated the following regarding Danaher Corporation (NYSE:DHR) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher Corporation (NYSE:DHR), S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ***** ets, network effects, or regulatory moats. Danaher is a leading life sciences company, selling a broad mix of consumables and tooling for biological R&D and drug production.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. However, as earnings in the economy nor
2 months ago
Revolution Medicines, Inc. (NASDAQ:RVMD) received FDA approval for Rasonque, or daraxonrasib, following an expedited review. The once-daily oral RAS inhibitor is approved for adults with metastatic pancreatic adenocarcinoma who have received at least one prior systemic therapy or are not candidates for multiagent systemic therapy.
Revolution Medicines, Inc. (NASDAQ:RVMD) set a wholesale acquisition cost (WAC) of $39,800 for a 30-day supply. Twelve 30-day supplies would total $477,600 at WAC before discounts, rebates, or ******* istance. Rasonque is available in the United States, with (ON)Path offering insurance navigation and financial-assistance resources, including copay support for eligible commercially insured patients.
The approval was based on RASolute 302, a randomized Phase 3 trial involving 500 patients with previously treated metastatic pancreatic adenocarcinoma. In the overall population, median overall survival reached 13.2 months with Rasonque versus 6.7 months with chemotherapy. The hazard ratio of 0.40 represented a 60% lower hazard of death during trial follow-up. Median progression-free survival was 7.2 months versus 3.6 months, while objective response rates were 30% and 11%, respectively.
The survival benefit gives Rasonque a strong clinical argument for reimbursement. Pancreatic cancer is aggressive, treatment options after progression are limited, and Rasonque improved overall survival, progression-free survival, and response rates in a randomized comparison. Oral dosing may also reduce the burden of intravenous chemotherapy.
The approved population is broader than a single mutation-defined subgroup. Rasonque can be prescribed with or without an identified RAS tumor mutation and does not require a companion diagnostic. That reduces testing friction within the approved treatment setting.
#months #pancreatic #progression #medicines
2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#stevanato #partners #investor
2 months ago
NFL players diagnosed with advanced CTE after death who also demonstrated cognitive impairment in testing during their life still did not meet the requirements for financial compensation under the NFL Concussion Settlement, according to a Boston University study published Wednesday.
Researchers examined 33 NFL players diagnosed with CTE after an autopsy who had completed the baseline ****** sment program (BAP) stipulated by the 2014 settlement – that ended a years-long class-action lawsuit – in what researchers called the largest study to date linking cognitive testing performance during life with CTE confirmed posthumously.
The results, published in JAMA Network Open, found that seven participants had advanced (Stage 3 or 4) CTE. Six of those seven showed measurable cognitive impairment on testing, yet all seven received the lowest impairment rating (Level 0) on the BAP's system, according to documentation provided to researchers by players' families.
"The BAP's diagnostic criteria might miss cases of cognitive impairment that are objectively measurable and ****** ociated with confirmed CTE pathology," Michael Alosco, PhD, co-director of clinical research at the BU CTE Center said in a statement. "This has important implications for former players seeking diagnosis and potential compensation through the NFL Concussion Settlement."
The participants' average age at the time of testing was 63, and their average age of death was 65. The most-common problem was memory, particularly short-term, with 63% of the participants affected. Executive function (52%) and language (41%) were other common impairments.
#cognitive #testing #settlement #participants

2 months ago
Washington, the District Of Columbia-based Danaher Corporation (DHR) designs, manufactures, and markets professional, medical, research, and industrial products and services. The company is valued at $151.9 billion by market cap.
Companies worth $10 billion or more are generally described as "large-cap stocks," and DHR definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the diagnostics & research industry. DHR's competitive strengths come from its portfolio of high-margin, mission-critical tools in biotech, diagnostics, and life sciences. Strong positions in regulated, R&D-heavy markets give it pricing power and resilience, even in downturns.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#palantir


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#NYSE #strategy #market #riverwater
2 months ago
Qiagen N.V. (NYSE:QGEN) announced on August 10 that the U.S. FDA cleared its QIAstat-Dx BCID GPF Plus AMR Panel, marking the company's first entry into the U.S. bloodstream infection testing market. Operating on the QIAstat-Dx platform, which boasts over 5,200 global placements, the automated panel detects 20 gram-positive bacterial and fungal targets, alongside 10 genetic antimicrobial resistance markers, in about one hour.
This regulatory milestone comes shortly after Qiagen N.V. (NYSE:QGEN) reported solid Q2 2026 financial results on August 5. Net sales reached $535 million (flat YoY at constant exchange rates), beating guidance for a 2% decline. Adjusted diluted EPS rose 3% YoY to $0.62, topping expectations. Performance across core growth pillars (+5% CER), including Sample Technologies (+9% CER) and QIAcuity digital PCR, helped offset a 7% drop in QIAstat-Dx respiratory testing sales. QGEN reaffirmed its full-year 2026 outlook for 1%–2% CER net sales growth and adjusted EPS of at least $2.43.
Additionally, Qiagen announced that Jonathan Pratt will take over as CEO effective September 1, succeeding Thierry Bernard. Joining at a pivotal time, Pratt will lead executive execution following an intensive portfolio evaluation and ongoing corporate efficiency programs.
This brings up a key question: Does the FDA clearance and steady execution under incoming leadership position Qiagen N.V. (NYSE:QGEN) for a valuation rerating, or will soft regional demand and product mix headwinds keep shares range-bound?
Bulls argue that Qiagen's high-margin, consumable-driven business model (comprising 90% of total Q2 sales) provides defensive recurring cash flow, generating $301 million in H1 operating cash flow. The new FDA approval expands QIAstat-Dx into its fourth major infectious disease area in the U.S., unlocking higher-margin hospital diagnostic channels. Furthermore, solid growth across core pillars like Sample Technologies and QIAcuity demonstrates fundamental demand. Strong internal cash generation also gives incoming CEO Jonathan Pratt ample balance sheet capacity to pursue disciplined capital deployment and portfolio innovation.
#qiagen


2 months ago
Aristotle Capital Management, LLC, an investment management company, released its "Value Equity Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund delivered a 4.32% total return in Q2 2026, underperforming the 13.87% gain for the Russell 1000 Value Index and the 15.20% return for the S&P 500, while its 1.99% year-to-date return also lagged the Russell 1000 Value Index's 16.26% and the S&P 500's 10.21%. The Fund attributed the performance gap largely to limited exposure to the AI infrastructure spending boom, noting that the U.S. has about 4,000 existing data centers and nearly 3,000 more planned or under construction, while AI-related demand has created bottlenecks in processors and memory. The letter highlighted the scale of the cycle, with industry cash flows in key AI hardware areas rising sharply, while the Russell 1000 Value Index's top 10 contributors gained an average 182% year to date and accounted for 9.29 percentage points of the index's 16.23% return. Looking ahead, the fund expects investors to eventually reassess the sustainability of current AI infrastructure earnings and valuations. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Aristotle Value Equity Fund highlighted stocks like Danaher Corporation (NYSE:DHR). Danaher Corporation (NYSE:DHR) develops life sciences, diagnostics, and biotechnology products and technologies used across healthcare and research markets. The one-month return of Danaher Corporation (NYSE:DHR) was 10.62% while its shares traded between $160.93 and $242.80 over the last 52 weeks. On August 27, 2026, Danaher Corporation (NYSE:DHR) stock closed at approximately $215.36 per share, with a market capitalization of about $155.62 billion.
Aristotle Value Equity Fund stated the following regarding Danaher Corporation (NYSE:DHR) in its Q2 2026 investor letter:
We first invested in Danaher Corporation (NYSE:DHR), a company focused on biotechnology, life sciences and diagnostics, in the second quarter of 2016, attracted by its disciplined capital allocation, differentiated operating culture and consistent FREE cash flow generation. The business is distinguished by a portfolio of market-leading franchises and a high mix of recurring consumables revenue tied to a large installed base. Its differentiated operating culture, anchored by the Danaher Business System, has historically enabled the company to be a highly effective acquirer, consistently integrating new businesses, expanding margins and driving strong FREE cash flow generation. Over our decade-long holding period, Danaher successfully transformed itself from a diversified industrial company into a more focused healthcare business. This evolution included the spinoffs of Fortive, Envista, and Veralto, as well as the acquisition and integration of key ***** ets such as Pall, Cepheid and Cytiva. The company also increased the contribution from re

2 months ago
Pfizer Inc. (NYSE:PFE) and Abbott Laboratories (NYSE:ABT) offer investors two very different dividend stories. Pfizer (NYSE:PFE) is working to rebuild growth before major patent expirations arrive, while Abbott (NYSE:ABT) is combining a long dividend-growth record with a more diversified healthcare portfolio. Pfizer (NYSE:PFE) may offer turnaround potential, but Abbott's (NYSE:ABT) latest results present the steadier investment case.
Pfizer's (NYSE:PFE) non-COVID portfolio is beginning to carry more of the business. Revenue excluding Comirnaty and Paxlovid grew 5% operationally in fiscal Q2 2026, while launched and acquired products generated $3.2 billion and increased 18% operationally. Padcev revenue rose 23% operationally to $667 million, supported by increased market share in first-line locally advanced or metastatic urothelial cancer and uptake in muscle-invasive bladder cancer. The Vyndaqel family generated $1.76 billion, up 8% operationally, while Lorbrena grew 37% operationally. This broader contribution is encouraging because Pfizer needs several products to offset declining COVID revenue and future patent losses.
Stronger non-COVID performance allowed Pfizer (NYSE:PFE) to raise the midpoint of its 2026 revenue guidance by $500 million, despite reducing its COVID-product forecast from approximately $5 billion to $4 billion. Its cost programs should provide further support, as management expects combined savings of approximately $9.7 billion through 2029 across its cost-realignment and manufacturing-optimization initiatives.
Abbott's (NYSE:ABT) advantage is the breadth of its growth. Second-quarter sales increased 13% on a reported basis and 4.8% on a comparable basis, while adjusted EPS rose 4% to $1.31. Medical Devices remained Abbott's (NYSE:ABT) largest segment and an important growth contributor, with sales rising 8.4% on a comparable basis. Growth was led by electrophysiology, rhythm management, heart failure, and diabetes care, with continuous-glucose-monitor sales increasing 9.5% comparably.
The Exact Sciences acquisition also expanded Abbott's (NYSE:ABT) diagnostics business. Diagnostics revenue reached $3.09 billion, rising 42.3% reported and 2.9% comparably. Within the segment, Cancer Diagnostics delivered 13.3% comparable growth as Cologuard benefited from increasing numbers of new and repeat users.
#Growth #billion #covid #revenue

2 months ago
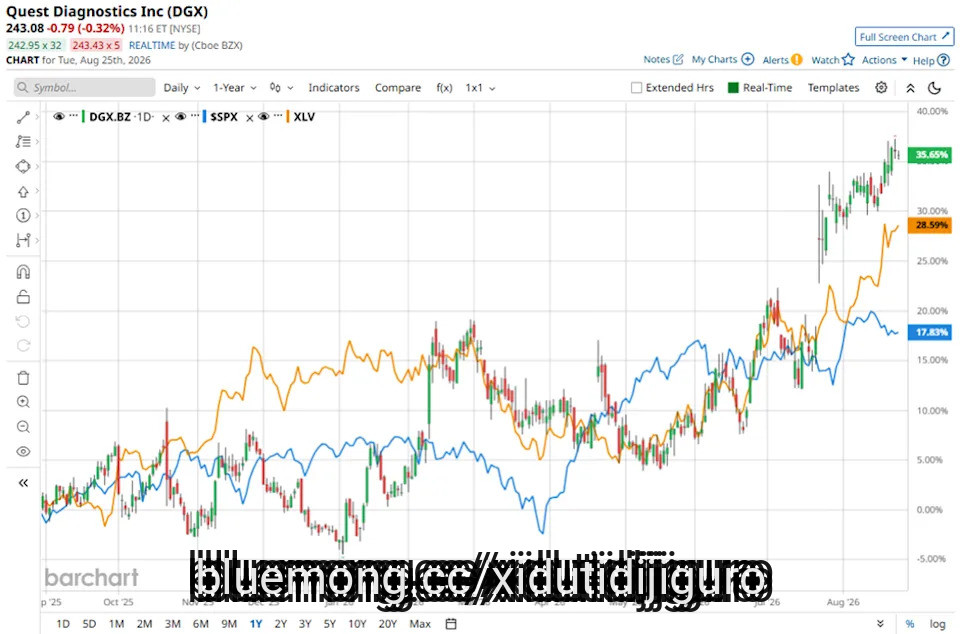
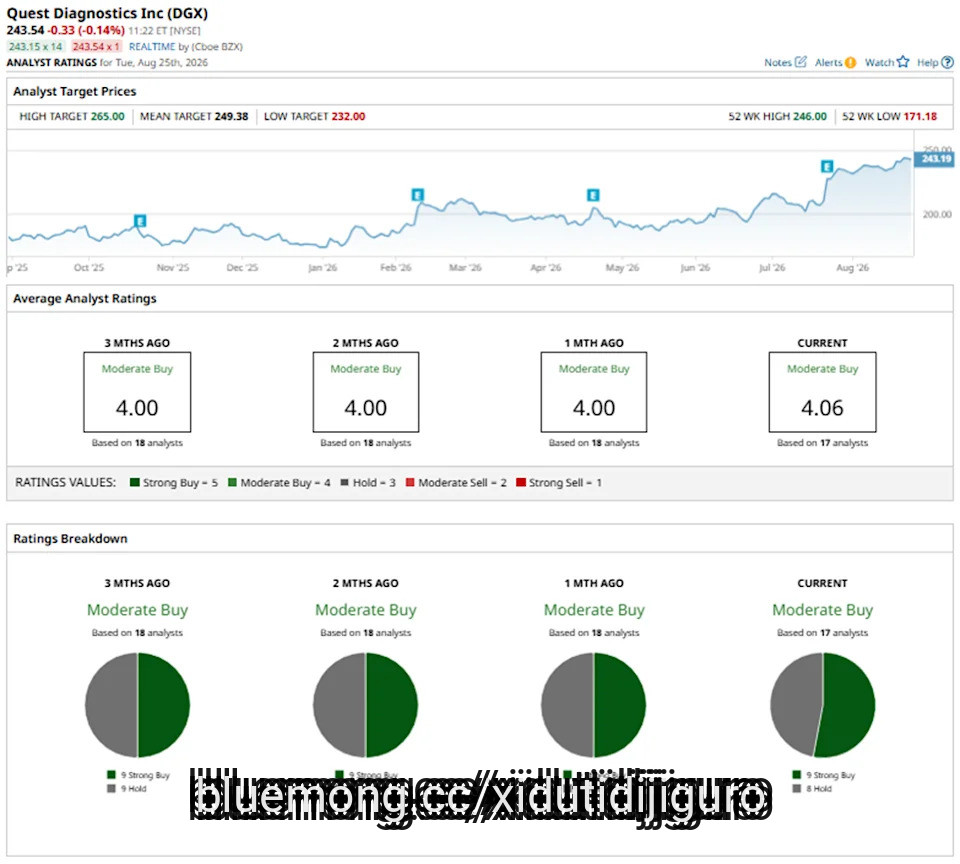
With a market cap of $26.9 billion, Quest Diagnostics Incorporated (DGX) is a leading provider of diagnostic testing services in the United States and internationally. The company delivers a wide range of routine and advanced diagnostic information services through its brands and network of laboratories, serving healthcare providers, insurers, employers, and government institutions.
Shares of the Secaucus, New Jersey-based company have outperformed the broader market over the past 52 weeks. DGX stock has returned 36.3% over this time frame, while the broader S&P 500 Index ($SPX) has gained 19.1%. Moreover, the stock has soared 40.4% on a YTD basis, compared to SPX's 12% increase.
IonQ vs. Rigetti: The Better Quantum Computing Stock for Long-Term Investors
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
IBM Just Hit a New Quantum Computing Milestone. How to Play IBM Stock Now.
#quantum #computing #market #quest
2 months ago
Revvity, Inc. (RVTY), headquartered in Waltham, Massachusetts, is a leading provider of health sciences solutions, technologies, and diagnostic services. Valued at $13.9 billion by market cap, the company focuses on translational multi-omics technologies, biomarker identification, imaging, prediction, screening, detection, diagnosis, informatics, and other areas.
Shares of this leading research and diagnostic firm have outperformed the broader market over the past year. RVTY has gained 39.1% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 20.5%. In 2026, RVTY's stock rose 28.9%, surpassing the SPX's 12.1% rise on a YTD basis.
Soros Fund Management Opened a New Position in Nebius During Q2. What This Means for NBIS Stock.
Nvidia Earnings, Jackson Hole and Other Key Things to Watch this Week
Ahead of Nvidia Earnings, Here's What Barchart Data Says Comes Next for NVDA Stock
#Stock #rvty #diagnostic #revvity

2 months ago
Healthcare investors are often faced with a choice between companies that generate steady growth across diversified businesses and those positioned to benefit from improving industry conditions. Abbott Laboratories (NYSE:ABT) and Thermo Fisher Scientific (NYSE:TMO) represent those two approaches. Abbott (NYSE:ABT) continues to deliver broad-based growth across diagnostics, medical devices, and nutrition, while Thermo Fisher (NYSE:TMO) is showing early signs that the life sciences downturn may finally be easing.
Both companies reported encouraging results, but the question for investors is whether consistent execution or a cyclical recovery offers the stronger long-term opportunity.
Abbott's (NYSE:ABT) strongest growth driver this quarter came from diagnostics, reinforcing the company's ability to generate meaningful growth across multiple business segments. The company's cancer diagnostics business, which was recently integrated through the Exact Sciences buyout, is benefiting from an expanding base that comprises both new and repeat users of the colorectal cancer screening test, Cologuard.
The quarter's earnings report corroborates this, as sales in its diagnostics segment rose 42% to $3.09 billion in fiscal Q2, surpassing the estimate of $3.02 billion, emerging as one of the company's strongest performers during the quarter. The continued strength in diagnostics is particularly important because it adds another major growth engine alongside Abbott's (NYSE:ABT) medical device business, making the company's earnings profile more balanced.
While Abbott's (NYSE:ABT) investment case is built on factors like diversification, Thermo Fisher's (NYSE:TMO) outlook increasingly depends on improving conditions across the life sciences industry. The company's quarter suggests that the recovery in life sciences spending is becoming increasingly broad-based. Management highlighted improving customer activity across pharmaceutical and biotechnology markets, while multiple operating segments returned to healthy growth. That is an important distinction because broader participation across business segments suggests customer spending is becoming healthier rather than merely stabilizing in one niche.
#Growth #thermo
2 months ago
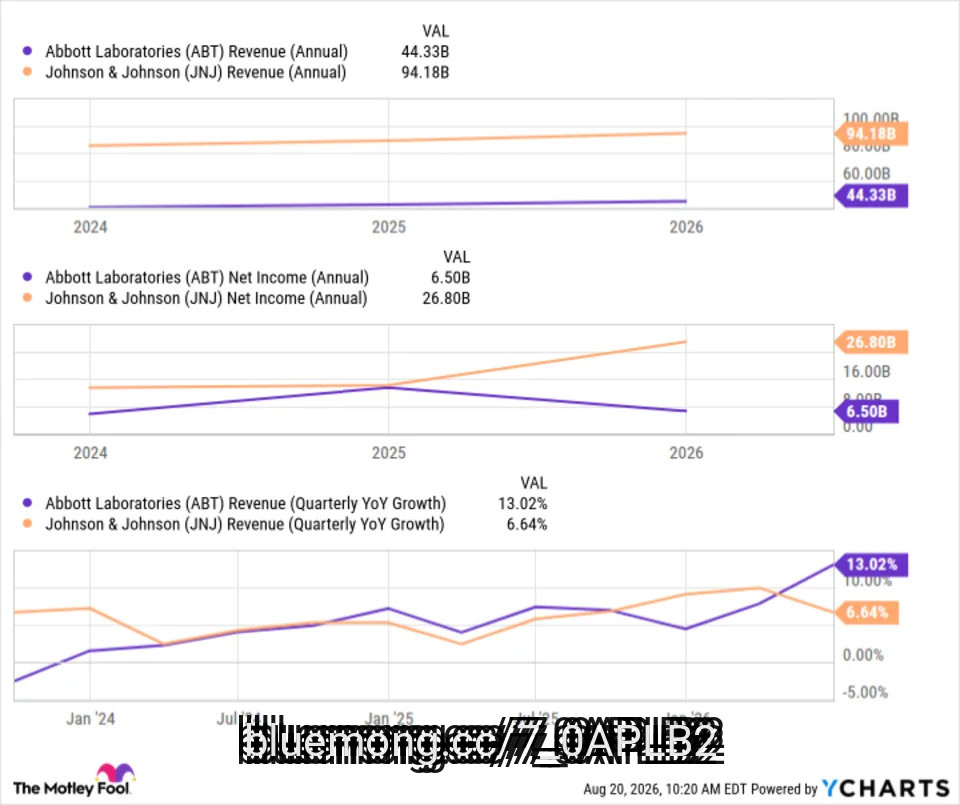
Investors looking for rock-solid dividend stocks can hardly do better than turning to Dividend Kings. This refers to a group of corporations that have raised their payouts for at least 50 consecutive years, an impressive accomplishment. However, not all Dividend Kings are created equal. Take Abbott Laboratories (NYSE: ABT) and Johnson & Johnson (NYSE: JNJ). Both healthcare giants belong to that group, and they have moved in opposite directions this year: Johnson & Johnson has beaten broader equities, while Abbott Laboratories has been a market laggard. Which of them is a better buy today?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Abbott has faced several challenges over the past couple of years. First, revenue and earnings growth haven't been strong, particularly in its diagnostics and nutrition segments. Second, the medical device specialist has faced some legal and regulatory headwinds. For instance, it has dealt with lawsuits claiming that its baby formula caused health issues in premature babies.
These have somewhat tarnished the company's public image. However, the healthcare leader is looking to turn things around. It can still count on its core medical device segment, particularly its diabetes care unit, which remains one of its main growth drivers. Abbott's FreeStyle Libre, a line of continuous glucose monitoring (CGM) systems that help patients with diabetes track their blood sugar levels, continues to perform well.
Also important, the company acquired Exact Sciences earlier this year in a cash transaction valued at $21 billion. This deal brings Cologuard, a leading non-invasive diagnostic test for colorectal cancer, under Abbott's umbrella. It will help the company tap into the large and growing cancer diagnostic market and boost sales within its diagnostic division. So, Abbott could bounce back, and in the meantime, its dividend program remains intact. It has increased its payouts for 54 consecutive years.
#johnson #Dividend

2 months ago
Zoetis Inc. (NYSE:ZTS) entered 2026 as a leader in animal health, but its latest earnings show that even a strong market position cannot fully insulate the company from weaker consumer demand. Fiscal Q2 2026 revenue remained flat at $2.5 billion and declined 1% on an organic operational basis, as pressure in the U.S. companion-animal market offset growth in livestock and international markets.
The quarter therefore presents investors with two different versions of Zoetis (NYSE:ZTS), as an established companion-animal business facing near-term pressure and a diversified animal-health platform still investing in its next generation of products.
Zoetis's (NYSE:ZTS) diversification provided an important source of resilience during the quarter. Livestock revenue increased 12% on a reported basis, supported by cattle and poultry products. In the United States, livestock sales grew 23% on both a reported and organic operational basis in the quarter, benefiting from favorable beef-cattle economics, supply timing, and increased poultry-vaccine sales **** ociated with disease outbreaks.
International performance was also encouraging. Revenue outside the United States rose 8% on a reported basis and 6% organically to $1.2 billion. International companion-animal sales grew 5% organically, supported by parasiticides such as Simparica Trio, Revolution and Stronghold, as well as diagnostics and newer osteoarthritis treatments. This geographic contrast demonstrates that the weakness was not uniform across Zoetis's (NYSE:ZTS) business. Demand for its products remains healthy in several markets, even as U.S. pet owners become more price-sensitive.
However, innovation could provide another route back to growth, as Zoetis (NYSE:ZTS) says that its pipeline contains more than 12 potential blockbuster candidates across chronic kidney disease, oncology, cardiology, anxiety, and obesity. The company also launched Lenivia and Portela, long-acting osteoarthritis treatments offering dogs and cats up to three months of pain relief from one injection.
#revenue #quarter

2 months ago
Aug 24 (Reuters) - The U.S. Food and Drug Administration has cleared Roche and partner Eli Lilly's blood test to help identify signs of Alzheimer's disease in people aged 55 and older with cognitive decline.
The test, Elecsys pTau217, is a biomarker blood test that can help doctors identify patients who are likely or unlikely to have Alzheimer's-related brain changes, Roche said on Monday.
The FDA clearance follows European approval for the test in May.
The test can be run on more than 4,500 Roche laboratory ******* yzers already installed across the United States, which the company said could help broaden access.
Separately, Labcorp and Quest Diagnostics said that they plan to offer the test through their laboratory networks, potentially expanding availability across the United States.
#test

2 months ago
Baron Capital, an investment management company, released its Q2 2026 investor letter for the "Baron Focused Growth Fund". A copy of the letter can be downloaded here. In the second quarter, the Baron Focused Growth Fund achieved a 13.26% gain, still trailing the Russell 2500 Growth Index's 24.02% return. The underperformance was driven by ongoing concerns about AI's impact on portfolio businesses and underexposure to AI infrastructure. The IPO of ****** eX provided a boost, but overall, the Fund's companies are generating robust revenue growth and strengthening margins through enhanced client engagement and product offerings. Many stocks remain historically undervalued, and companies are beginning accelerated share repurchases, bolstering investor confidence. The Fund is perceived as compelling, benefiting from favorable market conditions and strong balance sheets, while inflation and interest rates are expected to remain stable. The Fund has outperformed its Benchmark over the past 3, 5, and 10 years, showing significant excess returns with lower market risk, attributed to a research-driven investment approach. The Fund maintains a commitment to long-term investing in growth-oriented businesses, utilizing a balanced portfolio to mitigate risk and potentially enhance returns. Please review the Fund's top five holdings to gain insights into their key selections for 2026.
In its Q2 2026 investor letter, Baron Focused Growth Fund highlighted IDEXX Laboratories, Inc. (NASDAQ:IDXX). IDEXX Laboratories, Inc. (NASDAQ:IDXX) develops, manufactures, and distributes products for the companion animal veterinary, livestock and poultry, dairy, and water testing industries. On August 19, 2026, IDEXX Laboratories, Inc. (NASDAQ:IDXX) closed at $562.20 per share, reflecting a market capitalization of $44.29 billion. IDEXX Laboratories, Inc. (NASDAQ:IDXX) posted a one‑month return of 4.23%, while its shares lost 11.19% over the past 52 weeks.
Baron Focused Growth Fund stated the following regarding IDEXX Laboratories, Inc. (NASDAQ:IDXX) in its Q2 2026 investor letter:
"In Health Care, we invest in competitively advantaged companies that are leaders in their industries such as IDEXX Laboratories, Inc. (NASDAQ:IDXX), the leading provider of diagnostics to the veterinary industry and who is benefiting from the increase in pets that people acquired during the COVID pandemic, especially as these pets age. The Fund is further diversified by investments in businesses at different stages of growth and development."
#idxx #baron
2 months ago
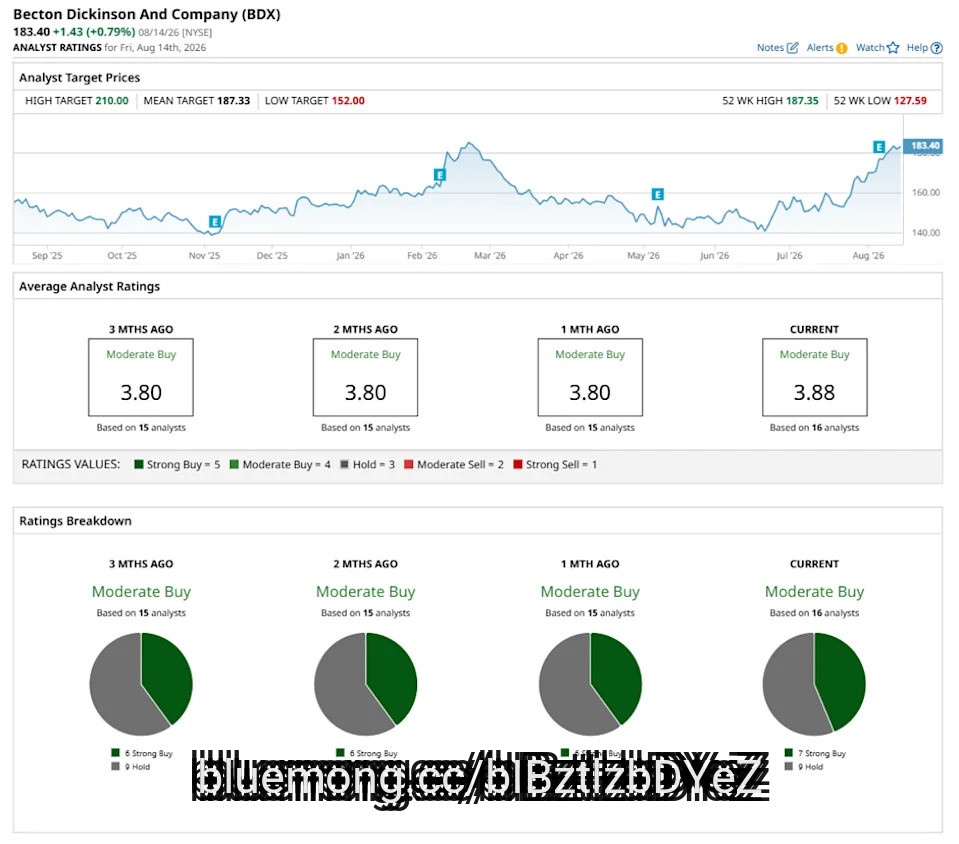
Becton, **** inson and Company (BDX) develops, manufactures, and sells medical supplies, devices, laboratory equipment, and diagnostic products. Valued at $50.5 billion by market cap, the company offers solutions that help advance medical research and genomics, enhance the diagnosis of infectious disease and cancer, improve medication management, and promote infection prevention.
Shares of this global medical technology giant have underperformed the broader market over the past year. BDX has gained 19.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 20.4%. However, in 2026, BDX stock is up 20.2%, surpassing the SPX's 13.7% rise on a YTD basis.
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
A $210 Billion Reason to Buy AMD Stock Here
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#medical #billion

2 months ago
Waltham, Massachusetts-based Thermo Fisher Scientific Inc. (TMO) provides life sciences solutions, ****** ytical instruments, specialty diagnostics, and laboratory products and biopharma services internationally. The company has a market cap of $217.5 billion and operates through four segments: Life Sciences Solutions, ****** ytical Instruments, Specialty Diagnostics, and Laboratory Products and Biopharma Services.
Shares of Thermo Fisher have slightly lagged behind the broader market over the past year, surging 20.3% compared to the S&P 500 Index's ($SPX) 20.4% surge. Moreover, in 2026, the stock has grown by nearly 1.5%, also underperforming SPX's 13.7% gain.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#specialty


2 months ago
On August 6, 10x Genomics (NASDAQ:TXG) reported second-quarter revenue of $151 million, boosted by a $1.6 million settlement payment from Takara. Strip that out and revenue grew just 3% year-over-year to $149.4 million, a modest number next to the real headline of the quarter: a brand-new instrument platform called Atera, where booked orders have exceeded full-year planned shipments.
By the end of the second quarter, booked orders for Atera already exceeded the roughly 40 units 10x had planned to ship for all of 2026. Demand also showed up in Catalyst Research Services, the program that lets customers run samples on Atera in 10x's own lab before committing to buy a unit. Away from Atera, the existing consumables business kept growing, up 7% overall, with spatial consumables climbing 16% on continued strength in the Xenium platform. During the quarter, 10x acquired Proteintech Genomics, adding single-cell protein panels that management says will let Atera measure proteins alongside gene expression from the same cell.
The balance sheet backed up the story. Cash and marketable securities rose to $552 million, up $105 million from a year earlier, and gross margin expanded to 74% from 72%. Management raised full-year revenue guidance to a range of $610 million to $630 million. New research partnerships with Cleveland Clinic and Lausanne University Hospital, aimed at finding biomarkers of treatment response in oncology, point to where 10x hopes this technology eventually leads: clinical diagnostics.
The flip side of Atera's launch showed up in the instrument line. Total instrument revenue fell 47% year over year, with Chromium instruments down 46% and spatial instruments down 48%, as customers held off on buying older spatial systems while waiting for the new platform. Management expects that pause to continue, guiding for a sequential revenue step down in the third quarter before a bigger jump in the fourth. Even though booked Atera orders already exceed the year's full production plan, 10x kept its shipment target at about 40 units, weighted mostly toward the fourth quarter, a sign the company is still constrained on how fast it can build the machine.
Regionally, APAC revenue fell 19%, partly because customers in China had pulled purchases forward a year earlier ahead of anticipated tariffs. Operating expenses rose to $132.1 million from $95 million, though the comparison is skewed by a $40.7 million patent settlement gain booked in the prior year versus $3.4 million this year.
#year #quarter