

1 month ago
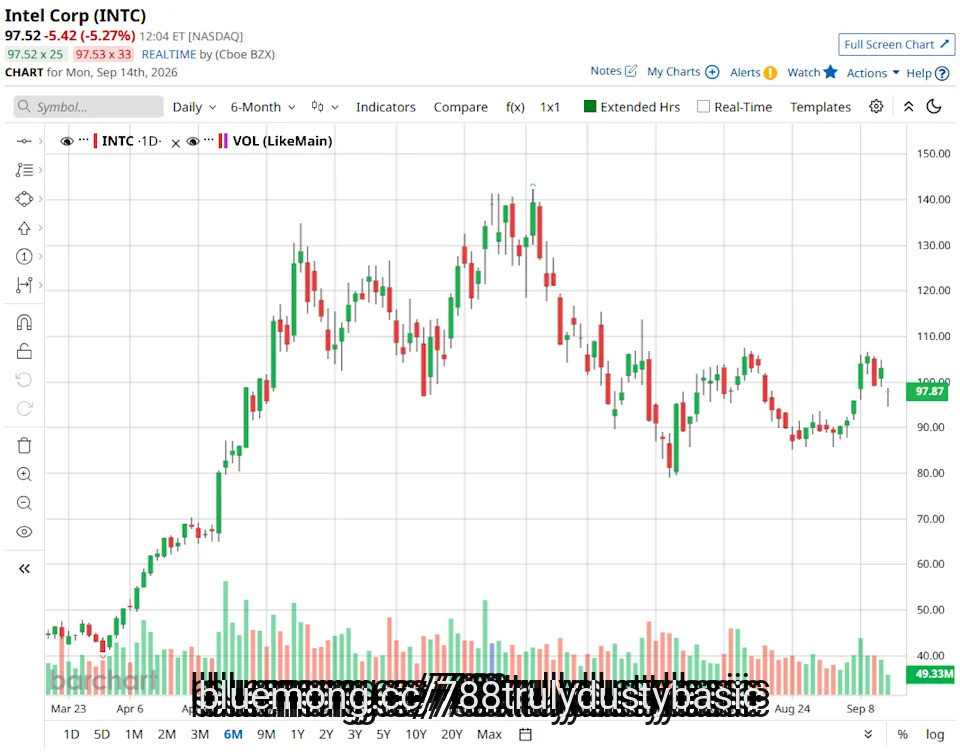
Mizuho has identified four clear tailwinds for Intel (INTC): ongoing CPU supply shortages, a stronger PC refresh cycle, accelerating demand for agentic AI, and growth in advanced packaging. Normally, such a setup would provide a reason to raise a price target. Instead, the firm cut its price target from $109 to $92, citing short-term multiple compression across Agentic AI stocks, and maintained a "Neutral" rating. The contradiction becomes more important because Intel's re-rating still depends on a foundry turnaround that has yet to prove itself.
Mizuho remains cautious on INTC stock despite outlining four separate tailwinds that could support the company's growth. The firm lowered its price target from $109 to $92 on Sept. 3, pointing to short-term multiple compression across agentic AI companies while keeping its "Neutral" rating unchanged. Mizuho **** yst Vijay Rakesh highlighted four developments that could support Intel's outlook. According to the **** yst, accelerating agentic AI demand could improve CPU-to-GPU ratios and drive additional server refreshers. Ongoing CPU supply constraints could also leave the company unable to fully meet demand through 2027. In addition, advanced packaging revenue is expected to reach $3.5 billion by 2029, with external foundry revenue potentially reaching a similar level through the 14A node. Finally, a stronger PC cycle could extend the upgrade cycle as corporate refreshes combine with ongoing memory tightness.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#four


1 month ago
On September 10, Shoe Station Group (NASDAQ:SHOE) held its first earnings call under its new name, and the numbers told a story of a company still finding its footing. Second quarter net sales fell 7.2% to $284.3 million from $306.4 million a year earlier, with comparable sales down 7.1%. But buried in the report was a sharper signal: August comparable sales improved to a 2.7% decline, a real jump from the second quarter's pace, and management is pointing to store-by-store product changes as the reason why.
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha


2 months ago
On September 8, a caller inquired if Trinity Industries, Inc. (NYSE:TRN) is worth looking at after its recent pullback. Mad Money host Jim Cramer replied:
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity

2 months ago
Tamboran Resources Corporation (NYSE:TBN) announced September 7 that it and Daly Waters Energy, LP had begun gas sales from the Shenandoah South Pilot Project into Australia's Northern Territory network. The deliveries mark the Beetaloo Basin's first gas sales and move the project into revenue generation.
The Sturt Plateau Compression Facility has a capacity of approximately 48.5 million cubic feet per day. Contracted supply of approximately 38.8 million cubic feet per day is expected by early 2027 under a long-term take-or-pay agreement with the Northern Territory Government. These are gross project volumes. Commissioning gas receives a discounted price because supply remains interruptible.
Tamboran Resources Corporation (NYSE:TBN) now has a working route from wells through processing infrastructure to a customer. All five wells on the Shenandoah South 2 pad have been drilled, stimulated and connected to the facility. Initial deliveries reduce uncertainty around the physical connection between the resource and its market.
Contracted demand equals 80% of stated processing capacity, providing a substantial foundation for utilization once production reaches the target. Take-or-pay agreements generally require buyers to pay for committed volumes even if they do not take delivery, subject to contractual conditions.
The gas sales agreement specifies a fixed price with annual adjustments linked to Australia's Consumer Price Index. That structure provides more revenue visibility than relying entirely on spot-market demand, although the price remains confidential.
#corporation


2 months ago
During the episode aired on September 8, Mad Money host Jim Cramer turned his focus to Apple Inc. (NASDAQ:AAPL), breaking down why the tech giant remains his ultimate "fantasy football" quarterback for steady, reliable portfolio performance. He stated:
We know how to draft on Mad Money so, break out your pen and paper and let's get started. Now, we got to start with our quarterback in fantasy… You're typically only playing one quarterback per week. And what you want here is consistent production. That's why for the past several years, I've picked Apple as my fantasy stock football QB. As always, own it, don't trade it. Not only does Apple make the most beloved products in the world, they're playing a very different game from their mega cap peers. Everybody else is spending hundreds of billions of dollars on AI. Apple's spending next to nothing, just partnering with AI companies. They desperately want access to Apple's massive user base.
To me, that makes Apple a lot less risky than the other members of the Magnificent Seven. To put that in NFL terms, Apple reminds me of Josh Allen, the quarterback for the Buffalo Bills. Allen's a known quantity. He was the league MVP two years ago. Then last year, he had 25 passing touchdowns, 14 rushing touchdowns, which, well, it gives you more points in fantasy football. But the main parallel is that both Apple and Allen are now under new management. For the first time in 15 years, Apple has a new CEO, John Ternus, who officially took over from Tim Cook last week. Similarly, at the end of last season, the Buffalo Bills let go of former head coach Sean McDermott, nine seasons, promoting former offensive coordinator Joe Brady to the position.
Cramer's comparison highlights Apple Inc.'s (NASDAQ:AAPL) distinct structural advantage within the Magnificent Seven. While rival mega-cap tech peers sink hundreds of billions of dollars into capital-intensive data center builds and proprietary AI infrastructure, the company has adopted a resource-efficient model. By integrating third-party AI capabilities while guarding its massive, high-intent global user base, the company limits its exposure to heavy upfront capital expenditure and margin compression.
Apple Inc.'s (NASDAQ:AAPL) high user retention continues to drive significant cash flow generation. Its hardware and premium services loop creates deep consumer loyalty, allowing the company to maintain pricing power and high profitability without taking on the aggressive infrastructure risk carried by other major technology players.
#Apple #aapl #last


2 months ago
Tyson Foods lowered its fiscal 2026 revenue growth forecast to 1.5%-2.0%, down from 2.5%-3.5%.
The company expects significant losses in its beef segment due to volatile cattle prices and shortages.
Tyson Foods shares dropped 7% after the revised outlook and are down 11% year-to-date.
Tyson Foods updated its fiscal 2026 outlook Thursday. Investors aren't too pleased.
Shares of Tyson Foods (TSN) sank roughly 7% in morning trading after the meat giant reduced its full-year revenue growth and adjusted operating income projections, "primarily driven by significant margin compression amid volatile cattle prices and one of the most severe cattle shortages in U.S. history, as well as the expected impact of lower cattle prices on the value of live cattle inventories."
#foods #prices #shares



2 months ago
On August 24, ePlus (NASDAQ:PLUS) announced it had completed the acquisition of the **** ets of Daymark Solutions, a Massachusetts-based IT services provider, with the deal having closed three days earlier on August 21. The announcement landed three weeks after the company posted first-quarter fiscal 2027 results on August 4, showing sales climbing even as profit slipped. Together, the two headlines capture where ePlus stands right now: reaching for new growth in cloud and security while working through pressure on its existing business.
Daymark, founded in 2001, built its business serving highly regulated, data-intensive industries including energy and utilities, healthcare, life sciences, defense, and financial services. Its core capabilities span modern data center infrastructure, cloud, Microsoft 365, Microsoft 365 Copilot, and cybersecurity, and its status as a Microsoft Tier 1 Cloud Solution Provider slots directly alongside ePlus' existing Azure and Microsoft 365 professional and managed services work. The acquisition also gives ePlus a deeper foothold in the New England region, particularly metropolitan Boston. CEO Mark Marron framed it as a way to gain a specialized Microsoft team that could serve as a catalyst for growth across Azure, Microsoft 365, security, and Copilot.
The timing lines up with what was already ePlus' fastest-growing segment. Managed services revenue rose 15.1% to $51.3 million in the first quarter, the segment's first quarter above $50 million, with gross profit up 11.3% on that growth. The balance sheet backs further moves like this one: cash and equivalents reached $448.9 million as of June 30, up from $410.8 million three months earlier, giving ePlus room for additional acquisitions, dividends, and buybacks. Management also pointed to record sales and a significant rise in booked and open orders, positioning the company for what it called a stronger second half.
The first quarter numbers show a company growing on top but shrinking underneath. Net earnings from continuing operations fell 5.4% to $30.3 million, adjusted EBITDA dropped 9.2% to $47.8 million, and operating income declined 9.6% to $38.8 million. Gross margin slipped to 23.3% from 23.9% a year earlier, with margin compression showing up across all three business segments rather than just one.
The professional services segment, the part of the business closest to the consulting and implementation work Daymark specializes in, fell 5.1% to $68.1 million, and its margin dropped to 36.9% from 39.2%. The product segment saw its own margin decline, to 21.0% from 21.3%, as an ongoing memory chip shortage extended lead times and delayed shipments. Terms of the Daymark transaction were not disclosed, leaving no visibility into what ePlus paid or how the deal affects near-term results.
#Microsoft #million #august #first


2 months ago
During the August 31 episode of Mad Money, Jim Cramer examined the sharp rotation back into enterprise software following the forced unwinding of bearish hedge fund positions. Mentioning Veeva Systems Inc. (NYSE:VEEV) and Salesforce, Inc. (NYSE:CRM) as examples of sector leaders, he commented:
Situational Awareness just despised enterprise software and Veeva Systems, number three, up 40%, is enterprise software writ large for the healthcare industry. I think it's bounced back in conjunction with all the other enterprise software companies that Situational Awareness believed would be destroyed by AI that haven't been. Once that hedge fund blew up, the whole group came roaring back as Situational was no longer there to put pressure on them. Hey, Salesforce had a similar rally, up nearly 40%. Now, here's one that openly took on the short sellers first with rhetoric and then with numbers which have not been hurt at all by… the SaaS-pocalypse. His blowout quarter obliterated the shorts. I don't think they still know what hit them.
For months, bearish macro funds aggressively shorted enterprise software providers, on the belief that emerging artificial intelligence platforms would easily replicate proprietary workflows and trigger severe pricing compression.
Salesforce, Inc. (NYSE:CRM) and Veeva Systems Inc. (NYSE:VEEV) proved the exact opposite. Salesforce showed that autonomous enterprise features act as expansion engines. Similarly, Veeva Systems, which powers critical clinical and commercial operations for the heavily regulated life sciences sector, integrated advanced data capabilities directly into its platform. Rather than cannibalizing software licenses, artificial intelligence features reinforced the massive switching costs embedded in both platforms.
Despite solid execution, market skeptics continue to scrutinize the growth limits and valuation multiples of both companies. Salesforce, Inc. (NYSE:CRM) trades at a forward P/E of 19x, showing market hesitation over macroeconomic budget tightening and the necessity for the company to rapidly monetize its heavy artificial intelligence investments.
#salesforce #situational #artificial #intelligence


2 months ago
Wall Street experts believe that AI adoption continues to create a cybersecurity spending cycle, with companies increasingly needing to secure AI agents, applications, and cloud workloads. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) is benefiting from this trend, posting record net new ARR of $333 million in Q2 2027, up 51% year-over-year, and upgrading FY27 net new ARR growth guidance by 630 bps to 34%. Revenue also rose 26% to $1.47 billion, driven by elevated demand.
Scotiabank lifted its price objective on CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s stock to $250 from $227 on August 27, while maintaining a "Sector Outperform" rating. The firm sees broad-based enterprise demand and increased spending on AI security for CRWD. The firm also tagged the company as a medium-term compounder even though it commands a premium valuation.
Wall Street ***** ysts believe that the upside case for CRWD revolves around platform expansion and AI security. Falcon Flex ARR crossed $2.29 billion, implying a rise of 101% YoY. Notably, 51% of subscription customers are now using six or more modules. Moving forward, growth is expected to be backed by cross-selling, AI security adoption, and record FCF.
However, bears highlight valuation as the biggest risk. Since expectations for high growth remain elevated, this leaves room for multiple compression if ARR growth slows, module adoption disappoints, or competition intensifies. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) trades at a forward P/E of ~172.4x, significantly higher than that of competitor Palo Alto Networks, Inc. (NASDAQ:PANW)'s forward P/E of ~87.7x.
CrowdStrike's strong ARR growth and expanding Falcon platform provide the company with a strong growth profile. On the other hand, Palo Alto Networks, Inc. (NASDAQ:PANW) is benefiting from broader network-security exposure. Overall, CrowdStrike's strong presence across endpoint, cloud, identity, SIEM, and AI security cements its position as the consolidated cybersecurity platform.
#adoption


2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Intercontinental Exchange, Inc. (NYSE:ICE), a US-based financial services company that provides technology, data, and market infrastructure to financial institutions, corporations, and government entities. On September 1, 2026, Intercontinental Exchange, Inc. (NYSE:ICE) closed at $159.60 per share. Over the past month, Intercontinental Exchange, Inc. (NYSE:ICE) returned 4.85%, while its shares have declined 10.30% in the last 52 weeks. Intercontinental Exchange, Inc. (NYSE:ICE) has a market capitalization of $89.6 billion, and its stock has traded within a 52-week range of $121.79 to $177.00.
Sands Capital Select Growth Fund stated the following regarding Intercontinental Exchange, Inc. (NYSE:ICE) in its Q2 2026 investor letter:
"Intercontinental Exchange, Inc. (NYSE:ICE) is one of the world's largest operators of financial exchanges and clearinghouses. Shares declined as investor concerns around AI disruption in ICE's Mortgage business and potential competition from perpetual futures contracts weighed on the stock. Much of the underperformance appears to reflect multiple compression rather than a weakening of fundamentals, which remain solid. In our view, the market is overestimating the risk that AI will displace ICE Mortgage. The business is not simply a workflow solution; it is a platform that connects lenders, data vendors, and other participants required to originate, sell, and service mortgages, while also serving as a system of record for a significant portion of the U.S. mortgage ecosystem. We also believe concerns around perpetual futures competition are overstated, as the structure of these products may limit their use in institutional hedging and risk management, particularly before accounting for liquidity. As such, we believe the recent sell-off more than discounts these risks."
#investor


2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On August 31, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $147.37 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) returned 19.52%, but its shares are up 5.99% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $189.59 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Baron Fifth Avenue Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP), a leading global commerce platform serving merchants across online and offline channels, detracted from performance in the second quarter with the stock down 3.7%. The decline was driven by multiple compression (its P/E was down 8.5%11) rather than any deterioration in the underlying business or fundamental outlook. Shopify continued to post healthy growth in gross merchandise volume and revenue, which were up 30% and 32% year-on-year, respectively. Instead, the pressure reflected investor concerns about the company's long-term positioning in a future state of e-commerce that may rely more heavily on AI-driven applications than traditional websites. We view those concerns as misplaced and see Shopify as an AI winner. Two decades of proprietary data across millions of merchants provide Shopify with a strong foundation for AI tools that improve merchant outcomes. Recent product releases also embed the platform more deeply within the emerging agentic commerce ecosystem while creating new monetization opportunities. We continue to believe that Shopify is the category-defining platform for modern commerce, benefiting from durable secular growth
2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On August 31, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $147.37 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) returned 19.52%, but its shares are up 5.99% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $189.59 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Baron Fifth Avenue Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP), a leading global commerce platform serving merchants across online and offline channels, detracted from performance in the second quarter with the stock down 3.7%. The decline was driven by multiple compression (its P/E was down 8.5%11) rather than any deterioration in the underlying business or fundamental outlook. Shopify continued to post healthy growth in gross merchandise volume and revenue, which were up 30% and 32% year-on-year, respectively. Instead, the pressure reflected investor concerns about the company's long-term positioning in a future state of e-commerce that may rely more heavily on AI-driven applications than traditional websites. We view those concerns as misplaced and see Shopify as an AI winner. Two decades of proprietary data across millions of merchants provide Shopify with a strong foundation for AI tools that improve merchant outcomes. Recent product releases also embed the platform more deeply within the emerging agentic commerce ecosystem while creating new monetization opportunities. We continue to believe that Shopify is the category-defining platform for modern commerce, benefiting from durable secular growth
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On August 31, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $147.37 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) returned 19.52%, but its shares are up 5.99% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $189.59 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Baron Fifth Avenue Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP), a leading global commerce platform serving merchants across online and offline channels, detracted from performance in the second quarter with the stock down 3.7%. The decline was driven by multiple compression (its P/E was down 8.5%11) rather than any deterioration in the underlying business or fundamental outlook. Shopify continued to post healthy growth in gross merchandise volume and revenue, which were up 30% and 32% year-on-year, respectively. Instead, the pressure reflected investor concerns about the company's long-term positioning in a future state of e-commerce that may rely more heavily on AI-driven applications than traditional websites. We view those concerns as misplaced and see Shopify as an AI winner. Two decades of proprietary data across millions of merchants provide Shopify with a strong foundation for AI tools that improve merchant outcomes. Recent product releases also embed the platform more deeply within the emerging agentic commerce ecosystem while creating new monetization opportunities. We continue to believe that Shopify is the category-defining platform for modern commerce, benefiting from durable secular growth

2 months ago
Sophie Cunningham is one of the most talked about players in the WNBA right now. She is one of the stars of the league, and leads the Indiana Fever. She is a very resourceful player on the court and is known for her fiery attitude on to as well.
The Fever star has also become one of the most outspoken voices in the league. She recently attracted attention for a daring action before a game.
Cunningham has been one of the WNBA's most talked about athletes in recent times. She has begun a debate over whether transgender athletes can be allowed to play in the league that is still ongoing. Other than that, she is not scared to talk about, or portray herself as she wishes.
Jun 20, 2026; Atlanta, Georgia, USA; Indiana Fever guard Sophie Cunningham (8) reacts to a foul call during the game against the Atlanta Dream during the second quarter at State Farm Arena. Mandatory Credit: Jordan Godfree-Imagn Images
Cunningham recently caused another light-hearted moment, during the pregame shootaround. It was before the game against the Dallas Wings. When a team staff member was filming her from the bench, she initially pretended not to notice. She then lowered casually pulled down her sweatpants as a fun moment, before pulling them up, turning around and smiling while pointing directly at the camera. She was wearing her compression shorts underneath, so no serious harm was done.
#athletes


2 months ago
Nvidia (NVDA) being more generous with dividends and stock buybacks could be a nice catalyst for the stock, just as it has been for Apple (AAPL).
The AI chip darling returned a record $26 billion to shareholders in its second fiscal quarter, $20 billion through share repurchases and $6 billion by way of a $0.25 a share quarterly dividend. Relative to its plan to return 50% or more of free cash flow to shareholders, Nvidia has returned 60% year to date.
Executives said the company intends to increase capital returns going forward.
"We forecast Nvidia to return $115 billion in cash to shareholders in 2026 and $230b billion in 2027, which we expect will translate to P/E multiple expansion, similar to what happened to Apple in 2015," Evercore ISI ******* yst Mark Lipacis wrote in a note on Thursday.
Lipacis pointed out in the chart below that after five years of compression, Apple's price-to-earnings ratio began expanding with increases in its capital returns program.
#billion #lipacis #returned #cash


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Linde plc (NASDAQ:LIN) as a new holding. Linde plc (NASDAQ:LIN) operates as the world's leading industrial gas company. On August 21, 2026, Linde plc (NASDAQ:LIN) closed at $487.57 per share. The one-month return of Linde plc (NASDAQ:LIN) was -3.84%, and its shares gained 2.03% over the past 52 weeks. Linde plc (NASDAQ:LIN) has a market capitalization of $224.76 billion.
SGA Global Growth Strategy stated the following regarding Linde plc (NASDAQ:LIN) in its Q2 2026 investor letter:
"Linde plc (NASDAQ:LIN), the world's largest industrial gas company, was added to the portfolio in April. We had previously exited the position in 2024 due to valuation considerations and forced attrition; since then, the stock price has consolidated while fundamentals continued to progress. Linde remains an attractive long-term investment, supported by a highly durable business model and meaningful structural advantages. A large share of revenue is generated from long-term, recurring customer contracts in essential end markets, providing strong pricing power and cash flow visibility even in a slower growth environment. The company's strengths are rooted in its production efficiency and broad exposure across diverse end markets, including healthcare, manufacturing, electronics, chemicals, and energy.
Looking ahead, Linde is well-positioned to benefit from structural improvements and a potential acceleration in global growth across several of its core markets over the medium term. The U.S., which accounts for roughly 45% of revenue, is likely to see improved growth driven by an industrial recovery, increased semiconductor manufacturing, and higher refinery utilization. Europe (approximately 25% of revenue) has been a headwind in recent years due to negative volume growth, but is expected to stabilize over the medium term, with the potential for mo

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted ServiceNow, Inc. (NYSE:NOW). ServiceNow, Inc. (NYSE:NOW) is a cloud-based software company that provides a platform for automating and managing digital workflows. On August 21, 2026, ServiceNow, Inc. (NYSE:NOW) closed at $128.48 per share. The one-month return of ServiceNow, Inc. (NYSE:NOW) was 21.64%, and its shares lost 27.04% over the past 52 weeks. ServiceNow, Inc. (NYSE:NOW) has a market capitalization of $132.85 billion.
SGA Global Growth Strategy stated the following regarding ServiceNow, Inc. (NYSE:NOW) in its Q2 2026 investor letter:
"As part of our ongoing dialogue with ServiceNow, Inc. (NYSE:NOW), we met with President and Chief Legal Officer Hossein Nowbar and members of the company's legal, compensation and, human resources teams. A significant portion of the discussion focused on the company's recent acquisition activity and the importance of maintaining transparency with shareholders regarding strategic decision-making. Management disagreed with our characterization that its acquisition strategy had become more aggressive, describing the recent transactions as an unusual convergence of several deals rather than a fundamental change in approach. We emphasized that, regardless of management's intent, the lack of timely communication surrounding these transactions contributed to investor uncertainty and undermined shareholder confidence. We encouraged the company to provide clearer and more proactive disclosure around significant strategic decisions to help investors develop a better understanding of the rationale and risks ***** ociated with future acquisitions....." (Click here to read the full text)
#holdings

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Arm Holdings plc (NASDAQ:ARM) as a leading contributor. Arm Holdings plc (NASDAQ:ARM) is a UK-based technology company that develops and licenses central processing unit designs and related technologies for semiconductor companies and original equipment manufacturers. On August 21, 2026, Arm Holdings plc (NASDAQ:ARM) closed at $243.32 per share. The one-month return of Arm Holdings plc (NASDAQ:ARM) was -8.64%, and its shares gained 76.60% over the past 52 weeks. Arm Holdings plc (NASDAQ:ARM) has a market capitalization of $259.87 billion.
SGA Global Growth Strategy stated the following regarding Arm Holdings plc (NASDAQ:ARM) in its Q2 2026 investor letter:
"Arm Holdings plc (NASDAQ:ARM), leading designer and licensor of CPU architectures and related subsystems, was a top contributor to performance again this quarter. The company delivered solid quarterly results, including 20% revenue growth and 12% profit growth, with continued strength in licensing activity and sustained royalty expansion despite a tougher comparison period. Management guidance reinforced confidence in maintaining roughly 20% revenue growth, supported by increasing demand for Arm-based CPUs and expanding adoption across data center and AI workloads, which helped offset expected weakness in handset markets. Confidence was further supported by evidence of strong CPU demand, improving share gains versus x86 architectures, and growing customer traction, including an expanding roster of signed partners and management's confidence in achieving long-term revenue targets. With strong pricing power, highly recurring revenues, and expanding royalty rates as Arm captures more value across the compute stack, we continue to view the company as a high-quality, long-term compounder well-positioned to benefit from the proliferation of AI and power efficient computing. We

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Alcon Inc. (NYSE:ALC). Alcon Inc. (NYSE:ALC) is a Swiss-based healthcare and medical technology company focused on eye care products. On August 21, 2026, Alcon Inc. (NYSE:ALC) closed at $73.63 per share. The one-month return of Alcon Inc. (NYSE:ALC) was 9.44% and its shares lost 8.83% over the past 52 weeks. Alcon Inc. (NYSE:ALC) has a market capitalization of $36.68 billion.
SGA Global Growth Strategy stated the following regarding Alcon Inc. (NYSE:ALC) in its Q2 2026 investor letter:
"During the quarter, we exited our position in Alcon Inc. (NYSE:ALC). Alcon remains a leader in eye care with exposure to increasing secular demand driven by aging and myopia, with market leadership across multiple categories. Strong launches in new equipment and eye drops drove topline growth of 6% constant currency and earnings per share growth of 16%+ in Q1. This was slightly below expectations of 7% growth, as the market for cataracts and contact lenses remains subdued. Additionally, the premium intraocular lens for cataracts is getting more competitive, with Alcon remaining the leader but expected to continue to cede share from the highs of 80%+ as competitors are catching up. Management continues to execute well on product launches to offset pressures in intraocular lens, which accounts for 17% of total sales. However, to account for the increased competition and subdued market conditions overall, we gradually reduced the position before ultimately redeploying the capital into a higher growth opportunity in Schneider Electric."
#strategy

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy added Equinix, Inc. (NASDAQ:EQIX) to its portfolio. Equinix, Inc. (NASDAQ:EQIX) is a leading digital infrastructure company that operates a global network of data centers and interconnected ecosystems, enabling seamless delivery of digital experiences and cutting-edge AI quickly and efficiently. On August 21, 2026, Equinix, Inc. (NASDAQ:EQIX) closed at $1,065.39 per share. The one-month return of Equinix, Inc. (NASDAQ:EQIX) was 1.78% and its shares gained 36.17% over the past 52 weeks. Equinix, Inc. (NASDAQ:EQIX) has a market capitalization of $105.12 billion.
SGA Global Growth Strategy stated the following regarding Equinix, Inc. (NASDAQ:EQIX) in its Q2 2026 investor letter:
"A position in Equinix, a leading global data center provider, was initiated during the quarter. The company sells ******* e, power, and connectivity services across a global footprint, binding strategic clients to its facilities through interconnection and coplacement for low-latency and high-bandwidth services. Equinix is a familiar name for SGA, having been a portfolio holding for ten years before being sold in 2024 as the growth rate had slowed and management was in the midst of a leadership transition. Both dynamics have since reversed, with growth re-accelerating as AI inferencing ramps and power demand remains high, and with new leaders now announced and in place." (Click here to read the full text)
#Growth #eqix #letter


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Salesforce, Inc. (NYSE:CRM). Salesforce, Inc. (NYSE:CRM) is a cloud computing company that offers Customer Relationship Management (CRM) technology that brings companies and customers together. On August 21, 2026, Salesforce, Inc. (NYSE:CRM) closed at $209.17 per share. The one-month return of Salesforce, Inc. (NYSE:CRM) is 21.95%, while its shares lost 14.59% over the past 52 weeks. Salesforce, Inc. (NYSE:CRM) has a market capitalization of $171.31 billion.
SGA Global Growth Strategy stated the following regarding Salesforce, Inc. (NYSE:CRM) in its Q2 2026 investor letter:
"Salesforce was a detractor from performance during the quarter as investor sentiment remained cautious following another quarter that merely met its guidance targets. Current remaining performance obligations (cRPO) growth were in line at roughly 9% rather than the historical pattern of beating by about a point, and the forward quarter guide was modest. Management acknowledged continued weakness in Marketing, Commerce, and Tableau (roughly 20% of revenue), partially offset by strength in Sales Cloud, Service Cloud, Slack, and Data Cloud (roughly 75% to 80% of revenue), with Sales and Service Cloud each posting seat growth in the quarter. Additionally, Agentforce annualized recurring revenue reached $1.2 billion, growing 205%. Management reiterated full-year guidance and a second-half reacceleration based on bookings strength and lower attrition, alongside a long-term double-digit organic growth target through CY29 with about 100 basis points of annual margin expansion. Despite concerns around AI‑driven competition, we believe Salesforce's integration into customer business processes, large installed base, and wide product set position it well to compete effectively in the Agentic AI era, supporting low-teens earnings growth over the next three years. We


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) as a top contributor to the performance. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's leading contract chip manufacturer, producing advanced semiconductors for major global technology companies. On August 21, 2026, Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) closed at $418.95 per share. The one-month return of Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) was 2.34%, and its shares gained 73.37% over the past 52 weeks. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) has a market capitalization of $1.9 trillion with a 52-week trading range between $223.70 - $479.00.
SGA Global Growth Strategy stated the following regarding Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) in its Q2 2026 investor letter:
"Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM), the world's leading semiconductor foundry, was a top contributor to performance during the quarter. Shares were supported by sustained strength in demand for advanced logic and compute, with customers across AI accelerators and CPUs continuing to require additional capacity. TSMC remains firmly positioned at the leading edge of semiconductor manufacturing, benefiting from secular demand across high performance computing, smartphones, automotive, and AI applications. Its technology leadership and scale support sustained double digit growth, with revenue increasingly driven by recurring and repeatable categories that reduce cyclicality. Given TSMC's dominant competitive position, deep customer entrenchment, and the continued global need for advanced compute, TSMC remains well-positioned to deliver strong double-digit revenue and earnings growth over the coming years. We maintained an above average weight position du


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Netflix, Inc. (NASDAQ:NFLX). Netflix, Inc. (NASDAQ:NFLX), a leading subscription-based streaming entertainment platform, detracted from performance during the quarter. On August 21, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $79.59 per share, reflecting a market capitalization of $331.41 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of 13.05%, while its shares lost 34.66% over the past 52 weeks.
SGA Global Growth Strategy stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX) was a detractor from returns during the quarter after the stock came under pressure despite reporting solid first quarter results in April. Revenue grew 16% year-over-year, or 14% excluding FX, and operating income rose 18%, supported by strong growth in APAC and Latin America. Second quarter revenue guidance came in roughly 1% below expectations and EBIT guidance was 5% light due to content amortization timing. Management maintained full-year guidance of 11% to 13% revenue growth (excluding FX) and approximately 20% profit growth rather than raising it, which disappointed some investors who had anticipated a lift following the recent price hike and the removal of the Warner Bros. Discovery deal overhang. With the Warner Bros. Discovery acquisition now behind it, management can refocus on the core business and deploy excess free cash flow toward AI investment and buybacks, including a new $25 billion authorization. The company continues to expand its mobile and content initiatives, while evaluating longer-term opportunities in advertising and AI-driven production tools. Over the long term, Netflix benefits from a recurring subscription model with low churn and demonstrated pricing power, supported by a broad and growing content library and meaningful global growth opportu

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Intuit Inc. (NASDAQ:INTU). Intuit Inc. (NASDAQ:INTU) provides financial management, payments and capital, compliance, and marketing products and services. On August 21, 2026, Intuit Inc. (NASDAQ:INTU) closed at $367.00 per share. The one-month return of Intuit Inc. (NASDAQ:INTU) was 20.76%, and its shares lost 44.14% over the past 52 weeks. Intuit Inc. (NASDAQ:INTU) has a market capitalization of $100.4 billion.
SGA Global Growth Strategy stated the following regarding Intuit Inc. (NASDAQ:INTU) in its Q2 2026 investor letter:
"We liquidated our position in Intuit Inc. (NASDAQ:INTU) during the quarter. Following the company's fiscal third quarter results, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. As a result, we exited the position and reallocated the capital to a new position in Arista Networks.
Intuit was a detractor from performance during the quarter. The company reported fiscal third quarter results that included a modest revenue beat and a full-year guidance increase, though results were overshadowed by weaker than expected Consumer Tax performance. TurboTax revenue grew 7%, below guidance, with notable weakness in the DIY segment. Management cited pressure among lower income, price sensitive filers and a contraction in total IRS filers of roughly 30 basis points. Despite double-digit revenue growth and ongoing margin expansion above 40%, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. Given these factors, we chose to exit the position and


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Alphabet Inc. (NASDAQ:GOOG) as a leading performance contributor. Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On August 21, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.75 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of 4.65%, while its shares gained 63.39% over the past 52 weeks.
SGA Global Growth Strategy stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was a contributor to performance during the quarter supported by the continued narrative that the company is a well-positioned beneficiary of the AI investment cycle. Its full‑stack exposure spans infrastructure, foundational models, developer tools, and scaled consumer applications, providing broad participation in AI adoption. The stock benefited from the company's Q1 report which highlighted robust ongoing demand for the company's AI compute resources. We continue to view Alphabet as a high-quality, long-term compounder. Its leading global platforms, supported by strong network effects, direct user relationships, and scaled infrastructure, underpin durable pricing power and highly recurring revenue streams. The company remains well-positioned to benefit from sustained growth drivers, including the ongoing shift toward digital advertising and cloud computing, while its continued investment in AI and innovation supports its ability to reinforce its competitive position over time. We raised the position target, maintaining an above-average weight."
#alphabet #strategy #investment


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Canadian Pacific Kansas City Limited (NYSE:CP). Canadian Pacific Kansas City Limited (NYSE:CP) owns and operates a transcontinental freight railway in Canada and internationally. On August 24, 2026, Canadian Pacific Kansas City Limited (NYSE:CP) closed at $94.68 per share. The one-month return of Canadian Pacific Kansas City Limited (NYSE:CP) was 3.25%, and its shares gained 24.17% over the past 52 weeks. Canadian Pacific Kansas City Limited (NYSE:CP) has a market capitalization of $83.25 billion.
SGA Global Growth Strategy stated the following regarding Canadian Pacific Kansas City Limited (NYSE:CP) in its Q2 2026 investor letter:
"We engaged with management of Canadian Pacific Kansas City Limited (NYSE:CP) in advance of the company's annual meeting to discuss its climate strategy and a proposal on climate-related disclosures. A key topic of discussion was the company's decision to defer establishing a Science Based Targets initiative (SBTi)-validated 1.5°C-aligned emissions reduction target. While the ISS Sustainability policy recommended voting against the climate proposal due to the absence of intermediate and long-term emissions targets, management explained that the delay stemmed from the lack of a finalized intensity-based methodology from SBTi appropriate for the freight rail industry, emphasizing that CPKC remains committed to its existing goal of reducing locomotive well-to-wheel emissions intensity by 36.9% by 2030 and continues to work with SBTi as industryspecific frameworks evolve. Management highlighted continued spending on locomotive fleet modernization, including investment in new Tier 4 locomotives, expansion of its hydrogen locomotive program, and trials of renewable fuels. After reviewing the company's disclosures, proxy materials, and feedback from management, we concluded that the company is making goo

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Yum! Brands, Inc. (NYSE:YUM). Yum! Brands, Inc. (NYSE:YUM) develops, operates, and franchises traditional and non-traditional quick service restaurants in the United States and internationally. On August 24, 2026, Yum! Brands, Inc. (NYSE:YUM) closed at $157.35 per share. The one-month return of Yum! Brands, Inc. (NYSE:YUM) was 4.4%, and its shares gained 6.7% over the past 52 weeks. Yum! Brands, Inc. (NYSE:YUM) has a market capitalization of $42.84 billion.
SGA Global Growth Strategy stated the following regarding Yum! Brands, Inc. (NYSE:YUM) in its Q2 2026 investor letter:
"We met with Jon Hixon, Yum! Brands, Inc.'s (NYSE:YUM) Chief Sustainability Officer, as well as members of legal and human resources teams to discuss several topics relevant to our investment thesis, including human capital management, geopolitical and reputational risks, corporate governance, and sustainability reporting. During the discussion, we were pleased to hear that Yum's next sustainability report would include, for the first time, disclosures aligned with the Taskforce on Nature-related Financial Disclosures (TNFD) framework, alongside its existing climate-related reporting. The addition of TNFD reporting reflects the company's ongoing efforts to ******* s and disclose nature-related dependencies, impacts, risks, and opportunities across its agricultural supply chain. A key focus of the engagement was Pizza Hut's ongoing strategic review and the ******* ociated human capital implications. Management outlined several retention initiatives designed to support workforce stability during the review process, including broad-based retention bonuses for employees and targeted retention awards for critical leadership and operational roles. While the company had experienced a modest increase in employee turnover, management indicated that attrition remai


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Linde plc (NASDAQ:LIN) as a new holding. Linde plc (NASDAQ:LIN) operates as the world's leading industrial gas company. On August 21, 2026, Linde plc (NASDAQ:LIN) closed at $487.57 per share. The one-month return of Linde plc (NASDAQ:LIN) was -3.84%, and its shares gained 2.03% over the past 52 weeks. Linde plc (NASDAQ:LIN) has a market capitalization of $224.76 billion.
SGA Global Growth Strategy stated the following regarding Linde plc (NASDAQ:LIN) in its Q2 2026 investor letter:
"Linde plc (NASDAQ:LIN), the world's largest industrial gas company, was added to the portfolio in April. We had previously exited the position in 2024 due to valuation considerations and forced attrition; since then, the stock price has consolidated while fundamentals continued to progress. Linde remains an attractive long-term investment, supported by a highly durable business model and meaningful structural advantages. A large share of revenue is generated from long-term, recurring customer contracts in essential end markets, providing strong pricing power and cash flow visibility even in a slower growth environment. The company's strengths are rooted in its production efficiency and broad exposure across diverse end markets, including healthcare, manufacturing, electronics, chemicals, and energy.
Looking ahead, Linde is well-positioned to benefit from structural improvements and a potential acceleration in global growth across several of its core markets over the medium term. The U.S., which accounts for roughly 45% of revenue, is likely to see improved growth driven by an industrial recovery, increased semiconductor manufacturing, and higher refinery utilization. Europe (approximately 25% of revenue) has been a headwind in recent years due to negative volume growth, but is expected to stabilize over the medium term, with the potential for mo

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Salesforce, Inc. (NYSE:CRM). Salesforce, Inc. (NYSE:CRM) is a cloud computing company that offers Customer Relationship Management (CRM) technology that brings companies and customers together. On August 21, 2026, Salesforce, Inc. (NYSE:CRM) closed at $209.17 per share. The one-month return of Salesforce, Inc. (NYSE:CRM) is 21.95%, while its shares lost 14.59% over the past 52 weeks. Salesforce, Inc. (NYSE:CRM) has a market capitalization of $171.31 billion.
SGA Global Growth Strategy stated the following regarding Salesforce, Inc. (NYSE:CRM) in its Q2 2026 investor letter:
"Salesforce was a detractor from performance during the quarter as investor sentiment remained cautious following another quarter that merely met its guidance targets. Current remaining performance obligations (cRPO) growth were in line at roughly 9% rather than the historical pattern of beating by about a point, and the forward quarter guide was modest. Management acknowledged continued weakness in Marketing, Commerce, and Tableau (roughly 20% of revenue), partially offset by strength in Sales Cloud, Service Cloud, Slack, and Data Cloud (roughly 75% to 80% of revenue), with Sales and Service Cloud each posting seat growth in the quarter. Additionally, Agentforce annualized recurring revenue reached $1.2 billion, growing 205%. Management reiterated full-year guidance and a second-half reacceleration based on bookings strength and lower attrition, alongside a long-term double-digit organic growth target through CY29 with about 100 basis points of annual margin expansion. Despite concerns around AI‑driven competition, we believe Salesforce's integration into customer business processes, large installed base, and wide product set position it well to compete effectively in the Agentic AI era, supporting low-teens earnings growth over the next three years. We


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy added Equinix, Inc. (NASDAQ:EQIX) to its portfolio. Equinix, Inc. (NASDAQ:EQIX) is a leading digital infrastructure company that operates a global network of data centers and interconnected ecosystems, enabling seamless delivery of digital experiences and cutting-edge AI quickly and efficiently. On August 21, 2026, Equinix, Inc. (NASDAQ:EQIX) closed at $1,065.39 per share. The one-month return of Equinix, Inc. (NASDAQ:EQIX) was 1.78% and its shares gained 36.17% over the past 52 weeks. Equinix, Inc. (NASDAQ:EQIX) has a market capitalization of $105.12 billion.
SGA Global Growth Strategy stated the following regarding Equinix, Inc. (NASDAQ:EQIX) in its Q2 2026 investor letter:
"A position in Equinix, a leading global data center provider, was initiated during the quarter. The company sells **** e, power, and connectivity services across a global footprint, binding strategic clients to its facilities through interconnection and coplacement for low-latency and high-bandwidth services. Equinix is a familiar name for SGA, having been a portfolio holding for ten years before being sold in 2024 as the growth rate had slowed and management was in the midst of a leadership transition. Both dynamics have since reversed, with growth re-accelerating as AI inferencing ramps and power demand remains high, and with new leaders now announced and in place." (Click here to read the full text)
#Growth #eqix #letter #strategy
2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Alcon Inc. (NYSE:ALC). Alcon Inc. (NYSE:ALC) is a Swiss-based healthcare and medical technology company focused on eye care products. On August 21, 2026, Alcon Inc. (NYSE:ALC) closed at $73.63 per share. The one-month return of Alcon Inc. (NYSE:ALC) was 9.44% and its shares lost 8.83% over the past 52 weeks. Alcon Inc. (NYSE:ALC) has a market capitalization of $36.68 billion.
SGA Global Growth Strategy stated the following regarding Alcon Inc. (NYSE:ALC) in its Q2 2026 investor letter:
"During the quarter, we exited our position in Alcon Inc. (NYSE:ALC). Alcon remains a leader in eye care with exposure to increasing secular demand driven by aging and myopia, with market leadership across multiple categories. Strong launches in new equipment and eye drops drove topline growth of 6% constant currency and earnings per share growth of 16%+ in Q1. This was slightly below expectations of 7% growth, as the market for cataracts and contact lenses remains subdued. Additionally, the premium intraocular lens for cataracts is getting more competitive, with Alcon remaining the leader but expected to continue to cede share from the highs of 80%+ as competitors are catching up. Management continues to execute well on product launches to offset pressures in intraocular lens, which accounts for 17% of total sales. However, to account for the increased competition and subdued market conditions overall, we gradually reduced the position before ultimately redeploying the capital into a higher growth opportunity in Schneider Electric."
#market #strategy #Portfolio #quarter



