

8 days ago
The S&P 500 (SNPINDEX: ^GSPC) has spent most of 2026 at or near record highs. While that's been good news for anyone invested in the index, a problem is developing beneath the surface.
As of Oct. 5, the S&P 500 was trading at less than 1% below its all-time high, yet only 42% of its components were trading above their 200-day moving average. According to Dow Jones Market Data, the last time the S&P 500 was within 1% of a record high while more than half of its stocks traded below their 200-day moving averages was March 2000.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Clearly, no one likes to see comparisons to the peak of the tech bubble. But this isn't a signal to sell stocks. Rather, it's time to rethink what you're actually owning when you buy the S&P 500.
Obviously, the S&P 500 is historically top-heavy right now. Tech stocks account for roughly 38% of the index, while the top 10 holdings also account for approximately 38%.
#time #Tech #record
9 days ago
The US trade deficit jumped to more than $100 billion in August as importers wrestled with a new round of President Trump's tariffs and continued to bring in billions of dollars' worth of components for AI data centers.
The total gap: $105.6 billion, a 13.8% increase from July's revised $92.8 billion deficit, the highest level since early 2025, when importers stocked up ahead of Trump's "Liberation Day" and a later four-month surge in imports that pushed average monthly trade deficits north of $120 billion.
Imports rose in August by 4.3%, compared with a 1.4% increase in exports. The US brought in $420.8 billion in total imports in August against $315.2 billion in exports.
In an **** ysis, Capital Economics said the "sharp rise in imports suggests third quarter GDP growth will be well below our current forecast of 4.0%," suggesting that the final annualized figure could be closer to 2.5%."
"The relatively broad-based rise in goods imports mean net trade was still a drag overall," the group added.
#billion #imports #total #increase
17 days ago
When AI stocks rebounded last week, optical networking companies did not rebound equally.
Lumentum Holdings Inc. (NASDAQ:LITE) jumped nearly 10% in Wednesday trading and led the S&P 500, while Coherent rose 6.9%. Corning Incorporated (NYSE:GLW) managed only a 0.4% gain and remained down sharply for the week.
All three sit inside the same broad AI-connectivity buildout. The divergence suggests investors are beginning to distinguish between different pieces of that infrastructure rather than buying every optics name together.
Photo from Lumentum Holdings website
AI clusters increasingly need optical connections as more accelerators communicate across larger physical distances. That drives demand for high-speed transceivers, lasers and other photonic components.
#NASDAQ #lite #wednesday #coherent
17 days ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ
25 days ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily


26 days ago
On September 15, Guggenheim ****** yst Michael Ciarmoli initiated coverage of almost two dozen defense stocks, with a bullish, sector-wide buy-the-pullback call.
He issued 13 Buy ratings with an average upside of roughly 50%, with the standout being Applied Aerospace & Defense, Inc. (NYSE:AADX). The ****** yst sees the stock around $30, up by about 150% from the share's closing price that day.
Ciarmoli described AADX as a "merchant supplier of established and proven military subsystems and components". The ****** yst believes the company is well positioned to benefit from favorable growth trends across the aerospace, defense, and ****** e industries.
Several defense stocks have struggled since the advent of the Iran war. Investors are also concerned about the possibility of a split Congress after the midterm elections, which could result in a spending gridlock.
However, Ciarmoli says the fears are overblown. The Guggenheim ****** yst is urging investors to be buyers on the pullback. He expects the current trend of increased spending on autonomous systems, ****** e, and replenishing depleted stockpiles to sustain.
#pullback


26 days ago
On September 4, RTX Corporation (NYSE:RTX) announced that its Pratt & Whitney business was investing $25 million to expand its manufacturing facility in Niepołomice, Poland.
The site produces complex tubular ****** emblies for both military and commercial engines. The expanded facility will begin operations in 2028 and create over 120 jobs.
Niepołomice already delivers precision components for several engines, including the F135, Pratt & Whitney GTF, and the PW800. The initiative complements the $100 million investment announced in April to boost production and enhance capabilities at the company's facility in Rzeszów, Poland.
The capacity expansion reflects the company's confidence in sustained demand for both commercial and military engine production over the coming years, which is supported by a record backlog of $289 billion at the end of Q2, increasing 22% year-over-year.
This further strengthens RTX Corporation (NYSE:RTX)'s manufacturing footprint in Europe, especially in Poland – which is already the company's largest presence outside the U.S. with more than 9,500 employees. The expansion will enhance its regional supply chain capabilities.
#Manufacturing
26 days ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply
26 days ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas

26 days ago
The intelligence report, circulated across the US military this spring in the midst of the war with Iran, immediately set off alarm bells: A Chinese ship in the Middle East was transporting components of a nuclear weapons program.
The US military swung into action with plans to intercept the vessel, according to four sources familiar with the episode. According to two of the sources, armed members of the US military were preparing to board the ship. Military planes were in the air, one of those sources and another source familiar with the incident said.
It was only just before the planned operation that officials dug deeper into the report put together by a special operations command ****** yst and found it had been generated with the help of artificial intelligence (AI) — and that a chatbot the ****** yst had used inaccurately identified the material the ship was carrying. CNN was not able to learn what the misidentified cargo was.
The report, according to one of the sources, was “entirely false.” But it also “almost started a war,” the source said. Any US operation against a Chinese vessel could have risked spiraling into an armed conflict between the two nations.
Across the US military and the intelligence community, officials are pushing to weave AI into nearly every facet of their work, from ****** yzing the huge volumes of raw intelligence the US collects and selecting targets for strikes, to more mundane applications like managing budgeting, logistics and supply chains.
#intelligence #ship #familiar
27 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
27 days ago
It seems too early to read this yet, with a major Fed catalyst due out this afternoon, but as of Tuesday, Sept. 15, roughly over half of the Russell 3000 Index – some 1,613 components! – have a "sell" signal from Barchart's TrendSeeker® indicator.
The broad-based Russell 3000 seeks to measure roughly 3,000 of the largest publicly traded U.S. companies, and it represents about $80 trillion in market cap as of the June 2026 annual rebalancing. That's 98% of the publicly traded market, give or take.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
The Case for Selling CrowdStrike Stock
#russell #Stock #publicly #traded


27 days ago
Exton, Pennsylvania-based West Pharmaceutical Services, Inc. (WST) designs, manufactures, and sells containment and delivery systems for injectable drugs and healthcare products. Valued at $25.7 billion by market cap, the company's technologies include the design and manufacture of packaging components, research and development of drug delivery systems, and contract laboratory services and other services.
Companies worth $10 billion or more are generally described as "large-cap stocks," and WST perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical instruments & supplies industry. WST stands out as a market leader with a diversified portfolio serving pharma and healthcare.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#Stock #billion


28 days ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
28 days ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#Dividend

28 days ago
Dover Corporation (DOV) is a diversified global manufacturer and solutions provider based in Downers Grove, Illinois. It produces equipment, components, consumables, aftermarket parts, software and digital solutions across five operating segments, serving customers worldwide. The company has a market capitalization of approximately $25.5 billion.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and Dover comfortably fits this category. Dover's market leadership comes from making specialized industrial products that serve a wide range of markets worldwide. Its diversified portfolio reduces dependence on any single market, while strategic acquisitions and divestitures sharpen its focus on profitable businesses. Its growing exposure to clean energy and fueling technologies adds further growth potential.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #worldwide #downers #grove


28 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
28 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#na

28 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Dolby Laboratories, Inc. (NYSE:DLB). Dolby Laboratories, Inc. (NYSE:DLB) is a US-based technology company that designs and manufactures audio, imaging, accessibility, and other hardware and software solutions for television, broadcast, and live entertainment industries. On September 14, 2026, Dolby Laboratories, Inc. (NYSE:DLB) closed at $61.91 per share. Over the past month, Dolby Laboratories, Inc. (NYSE:DLB) returned 1.33%, and its shares lost 14.24% over the past 52 weeks. Dolby Laboratories, Inc. (NYSE:DLB) has a market capitalization of $5.79 billion, and its stock has traded within a 52-week range of $48.26 and $73.01.
Prosper Stars & Stripes stated the following regarding Dolby Laboratories, Inc. (NYSE:DLB) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories, Inc. (NYSE:DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to st


28 days ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket

28 days ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Advanced Micro Devices, Inc. (NASDAQ:AMD). Advanced Micro Devices, Inc. (NASDAQ:AMD) is a leading semiconductor company that designs and manufactures AI accelerators, microprocessors, and graphics processing units. On September 14, 2026, Advanced Micro Devices, Inc. (NASDAQ:AMD) closed at $493.41 per share, reflecting a market capitalization of $805.61 billion. Over the past month, Advanced Micro Devices, Inc. (NASDAQ:AMD) returned 7.72%, but its shares are up 226.08% over the past year.
Fidelity Dividend Growth Fund stated the following regarding Advanced Micro Devices, Inc. (NASDAQ:AMD) in its Q2 2026 investor letter:
"On the other hand, security selection in industrials and materials meaningfully detracted for the quarter, along with a large overweight in the lagging energy sector. The five largest relative detractors were all strong-performing benchmark components in the technology sector that the fund didn't own during the quarter. For example, Advanced Micro Devices, Inc. (NASDAQ:AMD) (+186%) was the largest relative detractor for the period. AMD competes in many markets with Nvidia, which we preferred and has outperformed AMD in many recent quarters. Also, AMD pays no dividend, whereas Nvidia does. The past three months, though, AMD had by far the better return, aided by better-than-expected earnings for Q1 that were driven by accelerating demand for AI infrastructure."
#devices #NASDAQ #letter
28 days ago
ASML Holding N.V. (NASDAQ:ASML) is examining ways to produce more than 110 EUV lithography systems in 2028, according to JPMorgan ***** ysts following a meeting with CFO Roger Dassen. The company is already nearly sold out for 2027 and expects to produce at least 80 EUV systems that year, meaning output above 110 in 2028 would represent at least a 37.5% increase from the 2027 level. JPMorgan said the main constraint has shifted toward ***** embly speed rather than the availability of critical components, suggesting ASML believes additional capacity can be unlocked through manufacturing and ***** embly improvements.
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company

28 days ago
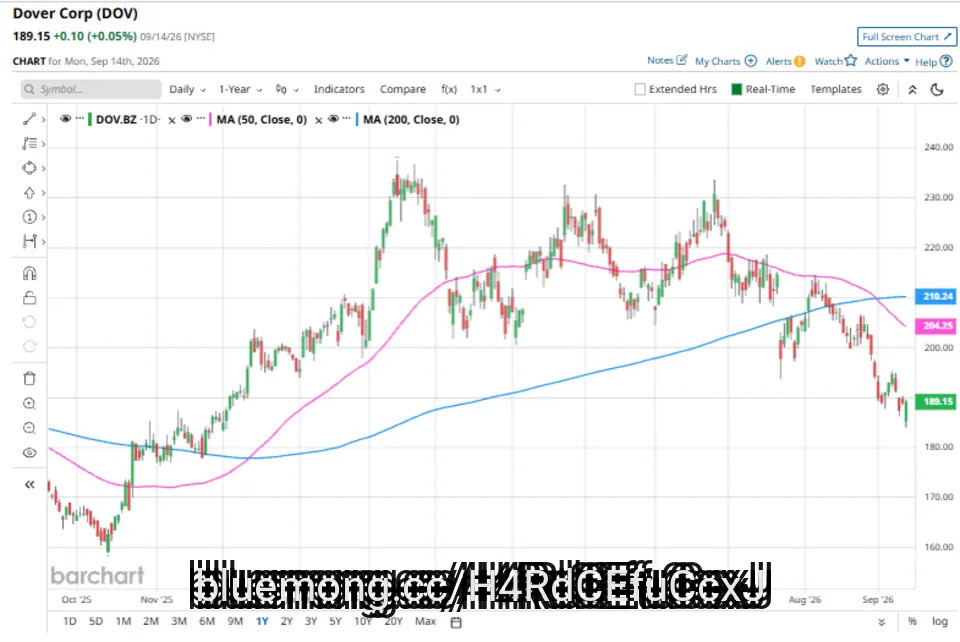
Dover Corporation (DOV) is a diversified global manufacturer and solutions provider based in Downers Grove, Illinois. It produces equipment, components, consumables, aftermarket parts, software and digital solutions across five operating segments, serving customers worldwide. The company has a market capitalization of approximately $25.5 billion.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and Dover comfortably fits this category. Dover's market leadership comes from making specialized industrial products that serve a wide range of markets worldwide. Its diversified portfolio reduces dependence on any single market, while strategic acquisitions and divestitures sharpen its focus on profitable businesses. Its growing exposure to clean energy and fueling technologies adds further growth potential.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#corporation #downers #grove


28 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Logitech International S.A. (NASDAQ:LOGI). Logitech International S.A. (NASDAQ:LOGI) is a Swiss technology company that designs, manufactures, and markets software-enabled hardware solutions. On September 14, 2026, Logitech International S.A. (NASDAQ:LOGI) closed at $100.36 per share. Over the past month, Logitech International S.A. (NASDAQ:LOGI) returned 2.09%, and its shares lost 10.65% over the past 52 weeks. Logitech International S.A. (NASDAQ:LOGI) has a market capitalization of $14.14 billion; its stock has traded within a 52-week trading range of $83.32 to $129.66.
Prosper Stars & Stripes stated the following regarding Logitech International S.A. (NASDAQ:LOGI) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corp (OLED), Dolby Laboratories (DLB), and Logitech International S.A. (NASDAQ:LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nearly impossible to use discounts to stimulate sales, compounding the pressure."
#pr

28 days ago
Prosper Stars & Stripes, a long/short equity fund, recently released its second-quarter 2026 investor letter. The letter can be downloaded here. In Q2 2026, the portfolio delivered a strong net return of +30.1% compared to the Russell 2000 Index's +21.5% return and the HFRX Equity Hedge Index's +10.3% return. The long book drove performance, generating a 43.2% gross contribution, while average net exposure remained relatively modest at 47%. U.S. economic growth remained resilient despite inflation concerns, elevated energy prices, and geopolitical uncertainty. Markets rallied sharply after easing U.S.-Iran tensions pushed oil prices lower, supporting renewed risk appetite. Small-cap equities benefited significantly, with Information Technology, Industrials, and Health Care leading gains, while Energy declined as crude prices fell. Year to date, the Composite returned +23.7%, slightly ahead of the Russell 2000's +22.6% and well above the HFRI Equity Hedge Index's +9.7%. Additionally, you can review the Portfolio's top 5 holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Prosper Stars & Stripes highlighted Universal Display Corporation (NASDAQ:OLED). Universal Display Corporation (NASDAQ:OLED) is an American technology company that develops and commercializes organic light-emitting diode (OLED) technologies and materials for use in display and solid-state lighting applications. On September 14, 2026, Universal Display Corporation (NASDAQ:OLED) closed at $76.62 per share. Over the past month, Universal Display Corporation (NASDAQ:OLED) declined 9.27%, and its shares lost 44.06% over the past 52 weeks. Universal Display Corporation (NASDAQ:OLED) has a market capitalization of $3.52 billion, and its stock traded within a 52-week range of $76.42 to $153.38.
Prosper Stars & Stripes stated the following regarding Universal Display Corporation (NASDAQ:OLED) in its Q2 2026 investor letter:
"This year's market rally has pressured short returns and narrowed the windows to successfully monetize shorts, as we would expect. Certain themes and short ideas do continue to resonate, however. One theme that has had success is the ongoing pressure caused by the investment boom in AI crowding out spending in other areas. We have shorted Universal Display Corporation (NASDAQ:OLED), Dolby Laboratories (DLB), and Logitech International (LOGI) on this theme. We believe cost pressures on technology components such as DRAM to result in higher prices for consumer electronics. This would have a significant impact on back-to-school and holiday spending, the key periods for these companies' end markets. We expect the forecasts that these companies are providing at this time of the year to prove optimistic, as tech cost inflation is unusual. Further, we believe the so-called K-shaped economy, where consumers have felt the pressure of rising costs of living, will continue to squeeze discretionary purchases like these. Rising prices make it nea
29 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#lumentum #lite #Growth #investor
1 month ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
1 month ago
On August 6, The RealReal (NASDAQ:REAL) reported second quarter results that beat its own outlook and pushed the resale luxury marketplace to raise its full year guidance. Gross merchandise value hit an all time high of $617 million, up 22% from a year earlier, and management pointed to four straight quarters of GMV growth above 20%. But a wider net loss sitting next to those record numbers complicates the story for anyone weighing the stock today.
The headline number is GMV of $617 million for the quarter ended June 30, up 22% year over year, with total revenue climbing 17% to $193 million. Consignment revenue grew 15% while Direct Revenue, the company's owned inventory channel, grew 26%, showing both sides of the business contributing to the acceleration. Profitability moved in the same direction. Gross margin reached 74.4%, up 10 basis points from a year ago, and Adjusted EBITDA margin jumped to 7%, a 290 basis point improvement that management called nearly 300 basis points of expansion.
The buyer base backs up the growth story rather than just the pricing. Trailing twelve-month active buyers rose 11% to 1,107,000, and average order value climbed 13% to $659, meaning existing shoppers are spending meaningfully more per transaction, not just showing up more often. That combination gave management enough confidence to raise full-year guidance to $2.54 billion to $2.57 billion in GMV and $788 million to $797 million in total revenue, alongside third-quarter Adjusted EBITDA guidance of $13.5 million to $14.5 million.
Despite the operating improvements, GAAP losses widened. Net loss came in at $27 million, or 14.1% of total revenue, compared to $11 million, or 6.9% of total revenue, a year earlier. GAAP basic net loss per share was $0.23 versus $0.10 in the prior year period, and diluted net loss per share was $0.23 versus $0.13. Much of that swing traces to a $(18.6) million non-cash adjustment tied to the change in fair value of warrant liability, a factor unrelated to how the underlying business performed. On a non-GAAP basis, basic and diluted net loss per share actually narrowed to $0.01 from $0.06, underscoring how much of the GAAP gap is accounting rather than operations.
There is also a transparency wrinkle in the guidance itself. The RealReal said it has not reconciled its forward-looking Adjusted EBITDA figures to GAAP net income or loss, citing components like payroll tax expense on employee stock transactions that it cannot predict with reasonable certainty. That leaves investors trusting a non-GAAP target without the usual bridge back to the bottom line.
#adjusted

1 month ago
On September 10, LightPath Technologies (NASDAQ:LPTH) reported fiscal fourth-quarter and full-year results that turned a multiyear strategic bet into a financial statement. Revenue nearly doubled for the year, margins expanded, and the company walked away from its last manufacturing ties to China. For a small-cap optics supplier that spent years explaining a strategy, this was the quarter the strategy started explaining itself.
Annual revenue climbed 92.7% to $71.7 million from $37.2 million, and the fourth quarter alone hit a record $21.2 million, up 73.8% year over year. That growth is not just volume. Full-year gross margin expanded to 36% from 27.2%, and the fourth quarter came in even higher at 39.4%, because ****** emblies, modules and cameras now make up 44% of annual sales instead of being sold as raw components.
CEO Sam Rubin said the shift reflects both a change in what LightPath sells and better execution on what it already made, noting every one of its four product groups improved margin for the year. Backlog finished at $110.9 million, up 197% from $37.4 million a year earlier, with $85.6 million of it scheduled for delivery within 12 months. Weeks after the fiscal year closed, the company booked another $24 million in counter-UAS orders, and some of those programs have already moved to monthly delivery cadences of tens of units.
LightPath also completed its exit from China, selling its subsidiary there for $4.5 million paid out over five years, leaving the company with no manufacturing footprint in a country that increasingly can't supply the defense primes it depends on. That matters because defense programs face a deadline this decade to source optics away from covered nations, and qualification cycles run two to three years, meaning the sourcing decisions being made now will determine who wins contracts in 2029 and 2030.
The company's fourth-quarter net loss narrowed to $4.1 million from $7.1 million a year earlier, but full-year operating expenses jumped to $45.5 million from $22 million, and $15.6 million of that was a noncash charge tied to G5 Infrared outperforming the earnout targets set at acquisition. Management called that charge mostly behind the business now that the final G5 payout has been accrued for January 2027, but it is a reminder that acquisition accounting can swing the income statement even when operations are healthy.
#year #quarter #China
1 month ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial


