

1 day ago
Interested in Johnson & Johnson? Here are five stocks we like better.
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested


4 days ago
Investors hammered Cooper Companies (COO) on Thursday after the medtech's fiscal third-quarter sales lagged Wall Street's expectations, leading to a guidance cut.
Specifically, the CooperVision segment — which sells contact lenses — missed expectations by 4.5%, William Blair **** yst Steven Lichtman said in a report. The miss was due to destocking. Further, the company opted against selling its CooperSurgical business following a strategic review.
"The 'no sale' is a surprise after management highlighted prospective buyers on the last earnings call," he said. "With CVI (CooperVision) results also disappointing, the stock moves back into the penalty box."
On today's stock market, Cooper Companies shares toppled 14.7%, closing at 54.17. Shares are already trading well below their key moving averages, IBD MarketSurge charts show.
Cooper said it couldn't sell the surgical division due to competition for its implantable contraceptive, Paragard, an intrauterine device. In June, Organon (OGN) licensed Miudella, a rival to Cooper's non-hormonal IUD. Cooper is also facing fertility litigation, BofA Securities **** yst Travis Steed said in a note to clients.
#Companies #expectations #investors #wall
Specifically, the CooperVision segment — which sells contact lenses — missed expectations by 4.5%, William Blair **** yst Steven Lichtman said in a report. The miss was due to destocking. Further, the company opted against selling its CooperSurgical business following a strategic review.
"The 'no sale' is a surprise after management highlighted prospective buyers on the last earnings call," he said. "With CVI (CooperVision) results also disappointing, the stock moves back into the penalty box."
On today's stock market, Cooper Companies shares toppled 14.7%, closing at 54.17. Shares are already trading well below their key moving averages, IBD MarketSurge charts show.
Cooper said it couldn't sell the surgical division due to competition for its implantable contraceptive, Paragard, an intrauterine device. In June, Organon (OGN) licensed Miudella, a rival to Cooper's non-hormonal IUD. Cooper is also facing fertility litigation, BofA Securities **** yst Travis Steed said in a note to clients.
#Companies #expectations #investors #wall


11 days ago
On August 3, UFP Technologies (NASDAQ:UFPT) reported second-quarter net income of $20.9 million, up 21.4% from $17.2 million a year earlier, alongside net sales of $174.0 million, a 15.1% jump from $151.2 million. Both figures, along with adjusted earnings per share of $2.92, marked the best quarter in the company's history. For the six months ended June 30, net income reached $38.3 million on sales of $328.2 million, up from $34.4 million and $299.3 million, respectively, in the same period of 2025. The headline numbers look clean. What sits underneath them is less tidy.
The quarter's strength did not come from one customer or one product line carrying the rest. UFP Technologies' top five customers grew 14.7%, and the remainder of its MedTech business grew even faster, at 19.7%. Organic sales growth, stripping out acquisitions, still ran at 12.4% for the quarter and 6.8% for the first half, which means the base business is expanding on its own rather than relying on deals to pad the numbers. Gross margin climbed to 29.3% from 28.8% a year earlier, and operating income rose 15.5% to $28.1 million, outpacing revenue growth. Adjusted EBITDA followed the same pattern, up 14.3% to $36.4 million for the quarter.
The balance sheet moved in a healthy direction too. Long-term debt, excluding current installments, fell to $104.8 million from $122.9 million at the end of 2025, while total equity grew to $462.4 million from $423.9 million over the same stretch. UFP Technologies also added executives in business development, operations, and legal during the quarter, a sign that management is building out the organization to support the growth it is already seeing rather than reacting to it after the fact.
The same earnings release that touted record results also flagged where the strain is showing. CEO Mitch Rock said the company's ongoing investment in its Dominican Republic operations is "taking longer than anticipated" to pay off and is creating "near-term mix and margin pressure" within the U.S. business. That is a direct admission that the expansion driving future capacity is costing money today. Selling, general and administrative expenses grew 21.8% to $22.8 million, faster than the 15.1% sales growth, pushing SG&A as a percentage of sales up to 13.1% from 12.4%. On an adjusted basis, SG&A crept up to 11.7% of sales from 10.8%.
Not every part of the business is contributing to the growth story either. While MedTech surged, the non-medical segment was flat for the quarter, leaving the entire growth burden on one part of the portfolio. Cash on hand also dropped sharply, falling to $9.0 million from $20.3 million at the end of 2025, even as receivables grew to $113.2 million from $82.9 million and inventories rose to $100.1 million from $86.9 million, a combination that suggests working capital is absorbing more cash than it used to.
#sales
The quarter's strength did not come from one customer or one product line carrying the rest. UFP Technologies' top five customers grew 14.7%, and the remainder of its MedTech business grew even faster, at 19.7%. Organic sales growth, stripping out acquisitions, still ran at 12.4% for the quarter and 6.8% for the first half, which means the base business is expanding on its own rather than relying on deals to pad the numbers. Gross margin climbed to 29.3% from 28.8% a year earlier, and operating income rose 15.5% to $28.1 million, outpacing revenue growth. Adjusted EBITDA followed the same pattern, up 14.3% to $36.4 million for the quarter.
The balance sheet moved in a healthy direction too. Long-term debt, excluding current installments, fell to $104.8 million from $122.9 million at the end of 2025, while total equity grew to $462.4 million from $423.9 million over the same stretch. UFP Technologies also added executives in business development, operations, and legal during the quarter, a sign that management is building out the organization to support the growth it is already seeing rather than reacting to it after the fact.
The same earnings release that touted record results also flagged where the strain is showing. CEO Mitch Rock said the company's ongoing investment in its Dominican Republic operations is "taking longer than anticipated" to pay off and is creating "near-term mix and margin pressure" within the U.S. business. That is a direct admission that the expansion driving future capacity is costing money today. Selling, general and administrative expenses grew 21.8% to $22.8 million, faster than the 15.1% sales growth, pushing SG&A as a percentage of sales up to 13.1% from 12.4%. On an adjusted basis, SG&A crept up to 11.7% of sales from 10.8%.
Not every part of the business is contributing to the growth story either. While MedTech surged, the non-medical segment was flat for the quarter, leaving the entire growth burden on one part of the portfolio. Cash on hand also dropped sharply, falling to $9.0 million from $20.3 million at the end of 2025, even as receivables grew to $113.2 million from $82.9 million and inventories rose to $100.1 million from $86.9 million, a combination that suggests working capital is absorbing more cash than it used to.
#sales

18 days ago
Pharmaceutical giant Johnson & Johnson (NYSE:JNJ) is one of Jim Cramer's favorite stocks in the sector. Over the course of this year, the CNBC TV host has praised the firm on multiple occasions. Among the reasons that he has been optimistic about Johnson & Johnson (NYSE:JNJ) include the firm's cancer drug portfolio and its Triple A balance sheet. For instance, in his July 6th appearance on Mad Money, Cramer remarked that "P&Gs and the J&Js in your portfolio allow you to safely own the techs." With tech stocks struggling recent due to concerns about the data center buildout, it was unsurprising that Johnson & Johnson (NYSE:JNJ) popped up on his radar once again on August 24th:
"I've been using that one stock JNJ to be able to [example] becuase it has a better balance sheet at this point than the US government, it doesn't need money, it's got very good science. It's not hostage to the government right now. It's got more new drugs than any of the, 18 new compounds, could be a billion dollars. And I come back and say, all right, well that's the treasury, plus the upside."
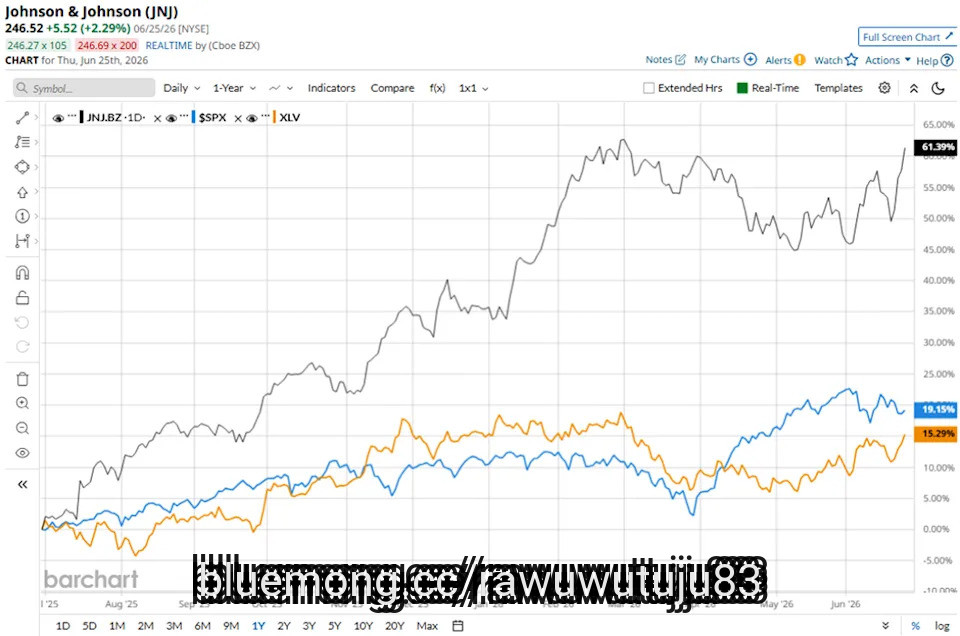
Johnson & Johnson (NYSE:JNJ)'s shares are up by more than 50% over the past year. Cramer's optimism about the firm covers several, but not all, aspects of the debate surrounding the firm. While Johnson & Johnson (NYSE:JNJ) has raised its full-year revenue guidance to a midpoint of $101 billion, removed headwinds related to its longstanding talcum powder lawsuits and posted strong growth with its Darzalex and Tremfya drugs for myeloma and psoriasis, concerns about its MedTech growth, flat profits growth and a 55.7% sales hit to its immune system disorders drug Stelara continue to raise the potential for headwinds.
For instance, Johnson & Johnson (NYSE:JNJ)'s MedTech business grew by a mere 3.6% in the second quarter as it was impacted by a slowdown in sales of heart-recovery devices following a study in the United Kingdom. Additionally, for a firm that's struggling on the net income growth front, $5.5 billion in talc powder settlements will continue to be a headwind to the cash flow. Johnson & Johnson (NYSE:JNJ) is due to pay $3 billion out of the $5.5 billion in 2027. Yet, at the same time, the diversified business nature means that some segments are growing. One example is the Innovative Medicine Business, which grew by 6.8% to $16.4 billion revenue, due to Darzalex and Tremfya.
Looking at hedge fund sentiment, while 113 out of the 1,022 funds part of Insider Monkey's Q1 database had held a stake in Johnson & Johnson (NYSE:JNJ), the figure jumped to 117 out of 1,006 funds in Q2. Among the notable additions was Polar Capital's $199 million stake, while Fisher ****** et Management ****** ped its stake by 44% to $3.3 billion. On the valuation front, Johnson & Johnson (NYSE:JNJ) trades at a forward P/E ratio of 23.4,2 which is lower than MRK's 56.82 and higher than AbbVie's 18.83. Shares short as a percentage of float are negligible at roughly 1%.
#billion #tremfya
"I've been using that one stock JNJ to be able to [example] becuase it has a better balance sheet at this point than the US government, it doesn't need money, it's got very good science. It's not hostage to the government right now. It's got more new drugs than any of the, 18 new compounds, could be a billion dollars. And I come back and say, all right, well that's the treasury, plus the upside."
Johnson & Johnson (NYSE:JNJ)'s shares are up by more than 50% over the past year. Cramer's optimism about the firm covers several, but not all, aspects of the debate surrounding the firm. While Johnson & Johnson (NYSE:JNJ) has raised its full-year revenue guidance to a midpoint of $101 billion, removed headwinds related to its longstanding talcum powder lawsuits and posted strong growth with its Darzalex and Tremfya drugs for myeloma and psoriasis, concerns about its MedTech growth, flat profits growth and a 55.7% sales hit to its immune system disorders drug Stelara continue to raise the potential for headwinds.
For instance, Johnson & Johnson (NYSE:JNJ)'s MedTech business grew by a mere 3.6% in the second quarter as it was impacted by a slowdown in sales of heart-recovery devices following a study in the United Kingdom. Additionally, for a firm that's struggling on the net income growth front, $5.5 billion in talc powder settlements will continue to be a headwind to the cash flow. Johnson & Johnson (NYSE:JNJ) is due to pay $3 billion out of the $5.5 billion in 2027. Yet, at the same time, the diversified business nature means that some segments are growing. One example is the Innovative Medicine Business, which grew by 6.8% to $16.4 billion revenue, due to Darzalex and Tremfya.
Looking at hedge fund sentiment, while 113 out of the 1,022 funds part of Insider Monkey's Q1 database had held a stake in Johnson & Johnson (NYSE:JNJ), the figure jumped to 117 out of 1,006 funds in Q2. Among the notable additions was Polar Capital's $199 million stake, while Fisher ****** et Management ****** ped its stake by 44% to $3.3 billion. On the valuation front, Johnson & Johnson (NYSE:JNJ) trades at a forward P/E ratio of 23.4,2 which is lower than MRK's 56.82 and higher than AbbVie's 18.83. Shares short as a percentage of float are negligible at roughly 1%.
#billion #tremfya


19 days ago
Boston Scientific (NYSE:BSX), a global medical device maker, closed at $48.17, down 3.38%. Premarket reports said a cybersecurity incident disrupted global operations and shipping. The company also announced a product recall for certain types of its percutaneous catheters, further weighing on the stock. Investors are watching how quickly the company restores its systems and whether the recall exacerbates the interruption. Trading volume reached 31.8M shares, coming in about 48% above its three-month average of 21.4M shares.
S&P 500 (SNPINDEX:^GSPC) fell 0.04% to 7,675, and the Nasdaq Composite (NASDAQINDEX:^IXIC) slipped 0.08% to 26,130. Among medical devices and interventional medtech peers, Abbott Laboratories (NYSE:ABT) closed at $114.10, down 1.75%, while Medtronic (NYSE:MDT) finished at $92.01, up 0.95%, as Boston Scientific's cyber disruption stood out.
Boston Scientific has seen its stock drop 55% over the last year, and today's double dose of bad news didn't help things. The product recall is tied to the company's ENROUTE Transcarotid Neuroprotection System (NPS) following the FDA's concerns about the potential separation of the product's arterial sheath tip.
Making matters worse, the company also disclosed a cybersecurity incident that disrupted its global operations, potentially disrupting the processing and shipping of customers' orders. Management noted that it was working to restore lost functions but couldn't yet determine whether the event would have a material impact on BSX shares.
Following several quarters of weaker-than-expected earnings results, disappointing Watchman sales, slashed guidance, and a major acquisition now weighing on Boston Scientific's balance sheet, the stock has shifted from a steady compounder to more of a turnaround or value type of stock -- especially after today's news. While BSX stock is on my watch list, I'd need to see some type of positive developments before I consider buying.
#boston #NYSE #global #following
S&P 500 (SNPINDEX:^GSPC) fell 0.04% to 7,675, and the Nasdaq Composite (NASDAQINDEX:^IXIC) slipped 0.08% to 26,130. Among medical devices and interventional medtech peers, Abbott Laboratories (NYSE:ABT) closed at $114.10, down 1.75%, while Medtronic (NYSE:MDT) finished at $92.01, up 0.95%, as Boston Scientific's cyber disruption stood out.
Boston Scientific has seen its stock drop 55% over the last year, and today's double dose of bad news didn't help things. The product recall is tied to the company's ENROUTE Transcarotid Neuroprotection System (NPS) following the FDA's concerns about the potential separation of the product's arterial sheath tip.
Making matters worse, the company also disclosed a cybersecurity incident that disrupted its global operations, potentially disrupting the processing and shipping of customers' orders. Management noted that it was working to restore lost functions but couldn't yet determine whether the event would have a material impact on BSX shares.
Following several quarters of weaker-than-expected earnings results, disappointing Watchman sales, slashed guidance, and a major acquisition now weighing on Boston Scientific's balance sheet, the stock has shifted from a steady compounder to more of a turnaround or value type of stock -- especially after today's news. While BSX stock is on my watch list, I'd need to see some type of positive developments before I consider buying.
#boston #NYSE #global #following


22 days ago
Medtronic plc (NYSE:MDT) and Tenet Healthcare Corporation (NYSE:THC) offer investors two very different healthcare growth stories. Medtronic's (NYSE:MDT) thesis rests on whether a new generation of medical devices can produce a durable turnaround across its enormous portfolio. Tenet (NYSE:THC), meanwhile, is generating stronger earnings by improving hospital profitability and focusing its ambulatory business on higher-acuity procedures.
The comparison ultimately comes down to whether investors prefer Medtronic's (NYSE:MDT) innovation-led recovery or Tenet's (NYSE:THC) stronger operating leverage.
Medtronic (NYSE:MDT) reported its highest annual revenue growth in a decade in its fiscal Q4 and full-year 2026 results, suggesting that years of investment in faster-growing technologies are beginning to produce meaningful results. Growth opportunities including Affera, Symplicity, Hugo, Altaviva, and Stealth AXiS give the company several potential drivers rather than leaving its recovery dependent on a single product.
Cardiac Ablation Solutions has emerged as a particularly important contributor. Revenue increased 78% globally, including 124% growth in the United States, as newer products strengthened Medtronic's (NYSE:MDT) position in the expanding cardiac-ablation market. The company is also investing in innovation and acquisitions, including targeted investments in intracardiac echocardiography catheter technology.
The breadth of Medtronic's (NYSE:MDT) pipeline supports the possibility that its recent acceleration can spread across more of the portfolio. Improving sentiment toward the wider medical-technology sector could provide an additional catalyst if the company maintains its execution. BTIG has argued that MedTech may be stabilizing following a period of underperformance, although company-specific results will ultimately matter more than broader sector sentiment.
#results #medtronic #healthcare
The comparison ultimately comes down to whether investors prefer Medtronic's (NYSE:MDT) innovation-led recovery or Tenet's (NYSE:THC) stronger operating leverage.
Medtronic (NYSE:MDT) reported its highest annual revenue growth in a decade in its fiscal Q4 and full-year 2026 results, suggesting that years of investment in faster-growing technologies are beginning to produce meaningful results. Growth opportunities including Affera, Symplicity, Hugo, Altaviva, and Stealth AXiS give the company several potential drivers rather than leaving its recovery dependent on a single product.
Cardiac Ablation Solutions has emerged as a particularly important contributor. Revenue increased 78% globally, including 124% growth in the United States, as newer products strengthened Medtronic's (NYSE:MDT) position in the expanding cardiac-ablation market. The company is also investing in innovation and acquisitions, including targeted investments in intracardiac echocardiography catheter technology.
The breadth of Medtronic's (NYSE:MDT) pipeline supports the possibility that its recent acceleration can spread across more of the portfolio. Improving sentiment toward the wider medical-technology sector could provide an additional catalyst if the company maintains its execution. BTIG has argued that MedTech may be stabilizing following a period of underperformance, although company-specific results will ultimately matter more than broader sector sentiment.
#results #medtronic #healthcare


29 days ago
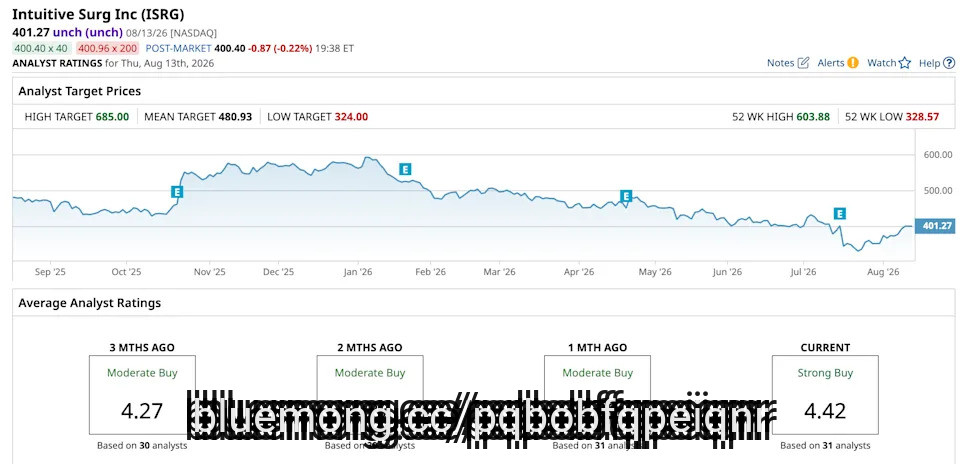
Analysts at Oppenheimer recently upgraded the medtech company Intuitive Surgical (ISRG) from "Perform" to "Outperform" and set a $500 price target, implying a 24.6% upside from current levels. Expecting the company to benefit from the growth in robotic surgery, Oppenheimer **** ysts expect Intuitive to maintain a leading position in the market despite increasing competition.
Intuitive also has a vision regarding the usage of artificial intelligence (AI) in such surgeries, helping medical personnel achieve better outcomes. The company is developing AI as a capability stack that leverages real-world surgical data to build advanced vision-language and reasoning models capable of answering complex surgical questions.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#Stock #analysts
Intuitive also has a vision regarding the usage of artificial intelligence (AI) in such surgeries, helping medical personnel achieve better outcomes. The company is developing AI as a capability stack that leverages real-world surgical data to build advanced vision-language and reasoning models capable of answering complex surgical questions.
A $210 Billion Reason to Buy AMD Stock Here
CoreWeave vs Nebius: Both Companies Reported Strong Earnings, But Here's the Stock You Should Buy
As Oracle Deepens Its Partnership with AWS, Here's How You Should Play ORCL Stock
#Stock #analysts


1 month ago
Johnson & Johnson (NYSE:JNJ) has officially entered the U.S. soft-tissue robotic surgery market after receiving FDA De Novo authorization for its OTTAVA robotic surgical system. The authorization represents an important milestone for J&J's MedTech ambitions, but the company is entering a market in which Intuitive Surgical (NASDAQ:ISRG) already has an extensive installed base, established surgeon relationships, and a rapidly expanding da Vinci 5 platform.
The question for investors is not whether OTTAVA can become a viable product, but whether Johnson & Johnson (NYSE:JNJ) can convert its differentiated design and broader surgical portfolio into meaningful market share, and even challenge Intuitive Surgical (ISRG) in the process.
OTTAVA's most compelling feature is its table-integrated architecture. Johnson & Johnson (NYSE:JNJ) stated that the robotic arms are incorporated directly into the operating table, which allows the system to occupy 30% to 50% less ****** e than traditional boom- and cart-mounted systems. The company believes this design could make robotic surgery accessible to operating rooms that previously could not accommodate a larger platform. That gives Johnson & Johnson (NYSE:JNJ) a potentially differentiated selling point among hospitals focused on operating-room capacity and workflow efficiency.
The FDA authorized OTTAVA for multiple upper-abdominal general surgery procedures, including gastric bypass, gastrectomy, cholecystectomy, gastric sleeve surgery, appendectomy, and hiatal hernia repair. Johnson & Johnson (NYSE:JNJ) will commercially launch the OTTAVA system with select customers in the United States to focus on early customer success and simultaneously advance the technology into additional regulatory jurisdictions and indications gradually. In addition, it has an ongoing U.S. clinical trial for OTTAVA in inguinal hernia procedures.
The selective launch is strategically sensible because robotic surgery systems require several factors for their smooth functioning in addition to regulatory authorization, including training for surgeons and operating-room staff, integration of the system into existing workflows, and establishing procedure volumes sufficient to justify the investment. With such a measured rollout, Johnson & Johnson (NYSE:JNJ) has time to collect real-world feedback, improve training, and refine the platform before attempting a broader commercial expansion.
#ottava #operating #market
The question for investors is not whether OTTAVA can become a viable product, but whether Johnson & Johnson (NYSE:JNJ) can convert its differentiated design and broader surgical portfolio into meaningful market share, and even challenge Intuitive Surgical (ISRG) in the process.
OTTAVA's most compelling feature is its table-integrated architecture. Johnson & Johnson (NYSE:JNJ) stated that the robotic arms are incorporated directly into the operating table, which allows the system to occupy 30% to 50% less ****** e than traditional boom- and cart-mounted systems. The company believes this design could make robotic surgery accessible to operating rooms that previously could not accommodate a larger platform. That gives Johnson & Johnson (NYSE:JNJ) a potentially differentiated selling point among hospitals focused on operating-room capacity and workflow efficiency.
The FDA authorized OTTAVA for multiple upper-abdominal general surgery procedures, including gastric bypass, gastrectomy, cholecystectomy, gastric sleeve surgery, appendectomy, and hiatal hernia repair. Johnson & Johnson (NYSE:JNJ) will commercially launch the OTTAVA system with select customers in the United States to focus on early customer success and simultaneously advance the technology into additional regulatory jurisdictions and indications gradually. In addition, it has an ongoing U.S. clinical trial for OTTAVA in inguinal hernia procedures.
The selective launch is strategically sensible because robotic surgery systems require several factors for their smooth functioning in addition to regulatory authorization, including training for surgeons and operating-room staff, integration of the system into existing workflows, and establishing procedure volumes sufficient to justify the investment. With such a measured rollout, Johnson & Johnson (NYSE:JNJ) has time to collect real-world feedback, improve training, and refine the platform before attempting a broader commercial expansion.
#ottava #operating #market


1 month ago
Throughout 2026, tariffs, inflation, and shifting geopolitical dynamics have added additional pressure to medtech supply chains, with the diabetes technology supply chain being no exception.
For diabetes technology, these factors are reshaping where devices are made, how they're priced, and ultimately, which products reach patients. On 18 August, GlobalData Healthcare ***** ysts Dr Andrew Thompson, director of therapy research and ***** ysis, medical devices, and Charlie Whelan, senior director of consulting, medical devices, will host a webinar ***** sing the impact these challenges.
During the "Lifting the Lid on the Diabetes Tech Supply Chain" webinar, Thompson and Whelan will draw on revenue and volume data across the diabetes device market to show how macroeconomic forces translate into real commercial and patient-level outcomes.
Topics under ***** sment will include how globalised manufacturing across the diabetes device market creates exposure to tariff and inflation risk, where revenue and volume flows sit today, and the relationship between gate pricing and macroeconomics, with Thompson and Whelan ***** sing what these factors mean for manufacturers, payers, and patients as geopolitical uncertainty continues.
Keen to learn more about how market challenges are impacting pricing and production dynamics in the diabetes technology supply chain?
#diabetes #supply #technology
For diabetes technology, these factors are reshaping where devices are made, how they're priced, and ultimately, which products reach patients. On 18 August, GlobalData Healthcare ***** ysts Dr Andrew Thompson, director of therapy research and ***** ysis, medical devices, and Charlie Whelan, senior director of consulting, medical devices, will host a webinar ***** sing the impact these challenges.
During the "Lifting the Lid on the Diabetes Tech Supply Chain" webinar, Thompson and Whelan will draw on revenue and volume data across the diabetes device market to show how macroeconomic forces translate into real commercial and patient-level outcomes.
Topics under ***** sment will include how globalised manufacturing across the diabetes device market creates exposure to tariff and inflation risk, where revenue and volume flows sit today, and the relationship between gate pricing and macroeconomics, with Thompson and Whelan ***** sing what these factors mean for manufacturers, payers, and patients as geopolitical uncertainty continues.
Keen to learn more about how market challenges are impacting pricing and production dynamics in the diabetes technology supply chain?
#diabetes #supply #technology


1 month ago
Conestoga Capital Advisors, an ****** et management company, released its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The letter reports a positive market shift towards Small Caps, with the Russell 2000 Index achieving its best first half since 1991 and the Russell 2000 Growth Index up 25.7% in Q2, fueled by AI enthusiasm and semiconductor stocks. However, market leadership was uneven, mirroring the Tech Bubble, as high-beta stocks outperformed while high-quality companies lagged, impacting Conestoga's quality-focused strategies. Management expressed confidence in long-term outcomes, noting that speculative leadership won't last as monetary policy tightens and market breadth improves. The firm remains committed to high-quality growth businesses, expecting these to regain favor as leadership broadens. The Conestoga Small Cap Composite returned 14.32% net-of-fees in the second quarter, with 25.71% for the Russell 2000 Growth Index. Narrow Index leadership hurt the relative results, but it also hid Composite improvements. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Conestoga Capital Advisors highlighted Knowles Corporation (NYSE:KN) as a newly added position in the Small Cap Composite. Knowles Corporation (NYSE:KN) is a specialty electronic components manufacturer that offers capacitors, radio frequency (RF) and microwave filters, balanced armature speakers, and medtech microphones. On August 4, 2026, Knowles Corporation (NYSE:KN) closed at $40.40 per share, reflecting a market capitalization of $3.45 billion. Knowles Corporation (NYSE:KN) posted a one-month return of 14.25%, while its shares gained 105.03% over the past 52 weeks.
Conestoga Capital Advisors stated the following regarding Knowles Corporation (NYSE:KN) in its Q2 2026 investor letter:
"Knowles Corporation (NYSE:KN) designs highly engineered components used in medical, defense, industrial, and electrification applications. We were attracted to the company's accelerating organic growth, expanding margins, and exposure to several attractive long-term secular trends. Management highlighted strong order activity across its Precision Devices business, with a sixth consecutive quarter of book-to-bill above 1.0x supporting confidence in continued growth."
Knowles Corporation (NYSE:KN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. As per our database, 26 hedge fund portfolios held Knowles Corporation (NYSE:KN) at the end of the first quarter, which was 30 in the previous quarter. While we acknowledge the risk and potential of Knowles Corporation (NYSE:KN) as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than Knowles Corporation (NYSE:KN) and that has 10,000% upside pote
In its Q2 2026 investor letter, Conestoga Capital Advisors highlighted Knowles Corporation (NYSE:KN) as a newly added position in the Small Cap Composite. Knowles Corporation (NYSE:KN) is a specialty electronic components manufacturer that offers capacitors, radio frequency (RF) and microwave filters, balanced armature speakers, and medtech microphones. On August 4, 2026, Knowles Corporation (NYSE:KN) closed at $40.40 per share, reflecting a market capitalization of $3.45 billion. Knowles Corporation (NYSE:KN) posted a one-month return of 14.25%, while its shares gained 105.03% over the past 52 weeks.
Conestoga Capital Advisors stated the following regarding Knowles Corporation (NYSE:KN) in its Q2 2026 investor letter:
"Knowles Corporation (NYSE:KN) designs highly engineered components used in medical, defense, industrial, and electrification applications. We were attracted to the company's accelerating organic growth, expanding margins, and exposure to several attractive long-term secular trends. Management highlighted strong order activity across its Precision Devices business, with a sixth consecutive quarter of book-to-bill above 1.0x supporting confidence in continued growth."
Knowles Corporation (NYSE:KN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. As per our database, 26 hedge fund portfolios held Knowles Corporation (NYSE:KN) at the end of the first quarter, which was 30 in the previous quarter. While we acknowledge the risk and potential of Knowles Corporation (NYSE:KN) as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than Knowles Corporation (NYSE:KN) and that has 10,000% upside pote


1 month ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by a 45% increase in printer sales, signaling a return of customer capital spending and the successful refresh of the product portfolio.
The company is shifting focus toward four key high-growth markets: medtech, dental, aerospace and defense, and data center infrastructure, which are adopting additive manufacturing for production.
Healthcare remains the largest segment, bolstered by strong demand for orthopedic implants and the successful launch of the NextDent 300 denture system.
Industrial segment revenue was modestly lower year-over-year as growth in aerospace, defense, and data center infrastructure was offset by the replacement of older systems and competition in consumer-facing markets.
#successful #Growth #data
Performance was driven by a 45% increase in printer sales, signaling a return of customer capital spending and the successful refresh of the product portfolio.
The company is shifting focus toward four key high-growth markets: medtech, dental, aerospace and defense, and data center infrastructure, which are adopting additive manufacturing for production.
Healthcare remains the largest segment, bolstered by strong demand for orthopedic implants and the successful launch of the NextDent 300 denture system.
Industrial segment revenue was modestly lower year-over-year as growth in aerospace, defense, and data center infrastructure was offset by the replacement of older systems and competition in consumer-facing markets.
#successful #Growth #data


1 month ago
Ariel Investments, an investment management company, released its "Small Cap Value Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. Ariel Investments said its Small Cap Value Tax-Exempt Composite gained 17.19% gross and 17.04% net in the second quarter of 2026, matching the Russell 2000 Value Index but trailing the Russell 2000's 21.49% return. The rebound was supported by easing geopolitical tensions, lower oil prices, resilient earnings, and renewed strength in technology and AI-related stocks, with strong stock selection also aiding performance. The fund enters the second half with a measured outlook, citing uneven global growth, geopolitical risks, persistent inflation, and elevated borrowing costs as potential sources of volatility. The firm remains focused on long-term value creation through disciplined, bottom-up research and investments in durable businesses with strong balance sheets, capable management, and sustainable competitive advantages. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Ariel Small Cap Value Fund highlighted stocks like Knowles Corporation (NYSE:KN). Knowles Corporation (NYSE:KN) is an electronic components company providing advanced audio, communications, and connectivity solutions for consumer and industrial applications. The one-month return of Knowles Corporation (NYSE:KN) was -0.49% while its shares traded between $19.29 and $42.93 over the last 52 weeks. On July 31, 2026, Knowles Corporation (NYSE:KN) stock closed at approximately $36.08 per share, with a market capitalization of about $3.125 billion.
Ariel Small Cap Value Fund stated the following regarding Knowles Corporation (NYSE:KN) in its Q2 2026 investor letter:
Leading provider of audio components and precision electronic devices, Knowles Corporation (NYSE:KN) also advanced following a strong earnings report that exceeded revenue and profit expectations. Performance was propelled by solid execution across segments, with Precision Devices benefiting from robust demand across diverse applications and its positioning for accelerated growth. MedTech & Specialty Audio also delivered steady results with attractive margins, underscoring the resilience and quality of the business. Meanwhile, KN continued to return capital to shareholders through share repurchases. We believe the company remains well positioned due to its focus on high-value, niche markets where it holds leading positions, supported by favorable end-market dynamics and improving operational execution that provide a compelling path for sustained growth.
#fund
In its second-quarter 2026 investor letter, Ariel Small Cap Value Fund highlighted stocks like Knowles Corporation (NYSE:KN). Knowles Corporation (NYSE:KN) is an electronic components company providing advanced audio, communications, and connectivity solutions for consumer and industrial applications. The one-month return of Knowles Corporation (NYSE:KN) was -0.49% while its shares traded between $19.29 and $42.93 over the last 52 weeks. On July 31, 2026, Knowles Corporation (NYSE:KN) stock closed at approximately $36.08 per share, with a market capitalization of about $3.125 billion.
Ariel Small Cap Value Fund stated the following regarding Knowles Corporation (NYSE:KN) in its Q2 2026 investor letter:
Leading provider of audio components and precision electronic devices, Knowles Corporation (NYSE:KN) also advanced following a strong earnings report that exceeded revenue and profit expectations. Performance was propelled by solid execution across segments, with Precision Devices benefiting from robust demand across diverse applications and its positioning for accelerated growth. MedTech & Specialty Audio also delivered steady results with attractive margins, underscoring the resilience and quality of the business. Meanwhile, KN continued to return capital to shareholders through share repurchases. We believe the company remains well positioned due to its focus on high-value, niche markets where it holds leading positions, supported by favorable end-market dynamics and improving operational execution that provide a compelling path for sustained growth.
#fund


2 months ago
This story was originally published on MedTech Dive. To receive daily news and insights, subscribe to our free daily MedTech Dive newsletter.
Robot developer Vicarious Surgical, which raised more than $425 million from investors including Bill Gates before its 2021 initial public offering, has obtained approval from shareholders to wind down and liquidate the business.
Shareholders voted at a special meeting Tuesday to enter into an ******* ignment for the benefit of creditors, an alternative to bankruptcy. The process transfers a company's ******* ets into a trust for distribution to creditors.
Vicarious was working to develop a single-port surgical robot that "shrinks the surgeon" to perform procedures inside the patient's abdomen but faced a series of delays in bringing the device to market and last year canceled plans for a clinical trial as it pushed to finish the design for the commercial version of the system.
Vicarious is shutting down 12 years after it was formed with the ambitious goals of improving patient outcomes, increasing surgical efficiency and addressing what its founders saw as significant limitations to legacy robotic platforms. Its 2021 merger with D8 Holdings, a special purpose acquisition company, or ******* , valued the company at $1.1 billion.
#medtech #shareholders #down #special
Robot developer Vicarious Surgical, which raised more than $425 million from investors including Bill Gates before its 2021 initial public offering, has obtained approval from shareholders to wind down and liquidate the business.
Shareholders voted at a special meeting Tuesday to enter into an ******* ignment for the benefit of creditors, an alternative to bankruptcy. The process transfers a company's ******* ets into a trust for distribution to creditors.
Vicarious was working to develop a single-port surgical robot that "shrinks the surgeon" to perform procedures inside the patient's abdomen but faced a series of delays in bringing the device to market and last year canceled plans for a clinical trial as it pushed to finish the design for the commercial version of the system.
Vicarious is shutting down 12 years after it was formed with the ambitious goals of improving patient outcomes, increasing surgical efficiency and addressing what its founders saw as significant limitations to legacy robotic platforms. Its 2021 merger with D8 Holdings, a special purpose acquisition company, or ******* , valued the company at $1.1 billion.
#medtech #shareholders #down #special


2 months ago
Intuitive Surgical, Inc. (NASDAQ:ISRG) is one of the 8 Worst Blue Chip Stocks to Buy Now.
On July 9, 2026, BMO Capital ****** yst Vik Chopra initiated coverage of Intuitive Surgical, Inc. (NASDAQ:ISRG) with an Outperform rating and $518 price target. Chopra said the da Vinci 5 upgrade cycle remains in the early innings, procedure growth is broadening into new specialties and geographies, and the earnings stream is "durable and visible."
On July 6, Evercore ISI lowered the firm's price target on Intuitive Surgical to $430 from $480 and kept an In Line rating on the shares. Evercore ISI said its Q2 preview for MedTech, Life Sciences Tools, and Diagnostics highlights generally healthy procedure volumes and capital expenditure trends across the sector.
Last month, BofA ****** yst Travis Steed lowered the firm's price target on Intuitive Surgical to $515 from $520 and kept a Buy rating on the shares. Steed noted that BofA's services team continues to highlight a lower utilization environment and took a more conservative view on 2027 medtech company estimates, given that valuations already reflect utilization risk. Steed also ****** umed inflation will be more of a headwind in 2027, with less margin expansion for medtech, and lowered 2027 estimates across the firm's larger-cap coverage with exposure to utilization and inflation.
Intuitive Surgical, Inc. (NASDAQ:ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care in the United States and internationally.
On July 9, 2026, BMO Capital ****** yst Vik Chopra initiated coverage of Intuitive Surgical, Inc. (NASDAQ:ISRG) with an Outperform rating and $518 price target. Chopra said the da Vinci 5 upgrade cycle remains in the early innings, procedure growth is broadening into new specialties and geographies, and the earnings stream is "durable and visible."
On July 6, Evercore ISI lowered the firm's price target on Intuitive Surgical to $430 from $480 and kept an In Line rating on the shares. Evercore ISI said its Q2 preview for MedTech, Life Sciences Tools, and Diagnostics highlights generally healthy procedure volumes and capital expenditure trends across the sector.
Last month, BofA ****** yst Travis Steed lowered the firm's price target on Intuitive Surgical to $515 from $520 and kept a Buy rating on the shares. Steed noted that BofA's services team continues to highlight a lower utilization environment and took a more conservative view on 2027 medtech company estimates, given that valuations already reflect utilization risk. Steed also ****** umed inflation will be more of a headwind in 2027, with less margin expansion for medtech, and lowered 2027 estimates across the firm's larger-cap coverage with exposure to utilization and inflation.
Intuitive Surgical, Inc. (NASDAQ:ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care in the United States and internationally.

2 months ago
Intuitive Surgical (ISRG) stock tumbled Tuesday, alongside shares of other medtech leaders like Abbott Laboratories (ABT), Stryker (SYK) and Medtronic (MDT), after HCA Healthcare trimmed its full-year earnings outlook, suggesting a drop in surgical procedures.
HCA Healthcare, the largest for-profit hospital operator, said inpatient surgeries declined 2.3% while outpatient procedures fell 3.4% in the second quarter compared with the year-ago period.
As a result, HCA now projects $6.3 billion to $6.7 billion in net income and adjusted earnings before interest, taxes, depreciation and amortization, or EBITDA, of $15.4 billion to $16.1 billion. That's down from the prior outlook for roughly $6.5 billion to $7.04 billion in net income and adjusted EBITDA of $15.55 billion to $16.45 billion.
HCA also narrowed its sales guidance, now projecting $77 billion to $79.5 billion. The midpoint of the new outlook, $78.25 billion, matches the company's prior view.
HCA Healthcare, the largest for-profit hospital operator, said inpatient surgeries declined 2.3% while outpatient procedures fell 3.4% in the second quarter compared with the year-ago period.
As a result, HCA now projects $6.3 billion to $6.7 billion in net income and adjusted earnings before interest, taxes, depreciation and amortization, or EBITDA, of $15.4 billion to $16.1 billion. That's down from the prior outlook for roughly $6.5 billion to $7.04 billion in net income and adjusted EBITDA of $15.55 billion to $16.45 billion.
HCA also narrowed its sales guidance, now projecting $77 billion to $79.5 billion. The midpoint of the new outlook, $78.25 billion, matches the company's prior view.


2 months ago
Abbott Laboratories (NYSE:ABT) is one of the Best Monopoly Stocks to Buy According to Hedge Funds. On June 30, Baird initiated coverage on the company's stock with an "Outperform" rating, setting a price objective of $121.00. The firm sees Abbott Laboratories (NYSE:ABT)'s portfolio as delivering steady top-line and earnings growth over the upcoming several years. As per the firm, the company's medical device segment is expected to see an above-peer growth trajectory.
The company's diagnostics, nutrition, and established pharmaceutical offerings enhance Abbott Laboratories (NYSE:ABT)'s reach throughout the healthcare spectrum. As per the firm, there is a clearer path to upside in FY 2027 and FY 2028, with new products and indication opportunities layering in, and Exact Sciences integration and synergies contributing to the results.
In a different update, Evercore ISI **** yst Vijay **** ar reduced the firm's price objective on Abbott Laboratories (NYSE:ABT)'s stock to $112 from $120 and maintained an "Outperform" rating. The firm's Q2 preview for MedTech, Life Sciences Tools, and Diagnostics demonstrates healthy procedure volumes as well as capex trends throughout the sector.
Abbott Laboratories (NYSE:ABT) is engaged in discovering, developing, manufacturing, and selling health care products.
While we acknowledge the potential of ABT as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
The company's diagnostics, nutrition, and established pharmaceutical offerings enhance Abbott Laboratories (NYSE:ABT)'s reach throughout the healthcare spectrum. As per the firm, there is a clearer path to upside in FY 2027 and FY 2028, with new products and indication opportunities layering in, and Exact Sciences integration and synergies contributing to the results.
In a different update, Evercore ISI **** yst Vijay **** ar reduced the firm's price objective on Abbott Laboratories (NYSE:ABT)'s stock to $112 from $120 and maintained an "Outperform" rating. The firm's Q2 preview for MedTech, Life Sciences Tools, and Diagnostics demonstrates healthy procedure volumes as well as capex trends throughout the sector.
Abbott Laboratories (NYSE:ABT) is engaged in discovering, developing, manufacturing, and selling health care products.
While we acknowledge the potential of ABT as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


2 months ago
Johnson & Johnson (NYSE:JNJ) is one of billionaire Cliff Asness' top 10 healthcare stock picks. On June 25, Johnson & Johnson (NYSE:JNJ) announced the commercial launch of the Dual Energy THERMOCOOL SMARTTOUCH SF (DE STSF) Platform in Europe. That means the platform is now commercially available to electrophysiologists across the EMEA region for the treatment of cardiac arrhythmias, including atrial fibrillation.
Copyright: moovstock / 123RF Stock Photo
The company said that the platform is the first of its kind to combine two distinct energy sources in a single catheter-based solution. It combines radiofrequency (RF) and pulsed field (PF) energy to allow physicians to switch between the two during the same procedure without having to change equipment. This is clinically significant because RF and PF ablation each have different tissue effects and safety profiles, said Nicolas Derval, M.D., a consultant for Johnson & Johnson based in Bordeaux, France. Derval added that the ability to use both gives doctors more flexibility to tailor treatment to individual patient anatomy and disease patterns.
Johnson & Johnson explained that the platform consists of the DE STSF Catheter, which is an irrigated, contact-force sensing catheter that physically delivers energy to heart tissue. The other half consists of the TRUPULSE Generator, which controls and powers the delivery of both RF and PF energy. The company said the system is fully integrated with its CARTO 3 System, which is an electro-anatomical mapping platform. This combination enables real-time 3D visualization, contact-force feedback, and index-guided ablation during live procedures.
Johnson & Johnson (NYSE:JNJ) is a healthcare conglomerate. It operates through two segments: Innovative Medicine, which develops and markets prescription drugs in oncology, immunology, neuroscience, and infectious disease, and MedTech, which manufactures medical devices for surgery, orthopedics, and interventional solutions.
Copyright: moovstock / 123RF Stock Photo
The company said that the platform is the first of its kind to combine two distinct energy sources in a single catheter-based solution. It combines radiofrequency (RF) and pulsed field (PF) energy to allow physicians to switch between the two during the same procedure without having to change equipment. This is clinically significant because RF and PF ablation each have different tissue effects and safety profiles, said Nicolas Derval, M.D., a consultant for Johnson & Johnson based in Bordeaux, France. Derval added that the ability to use both gives doctors more flexibility to tailor treatment to individual patient anatomy and disease patterns.
Johnson & Johnson explained that the platform consists of the DE STSF Catheter, which is an irrigated, contact-force sensing catheter that physically delivers energy to heart tissue. The other half consists of the TRUPULSE Generator, which controls and powers the delivery of both RF and PF energy. The company said the system is fully integrated with its CARTO 3 System, which is an electro-anatomical mapping platform. This combination enables real-time 3D visualization, contact-force feedback, and index-guided ablation during live procedures.
Johnson & Johnson (NYSE:JNJ) is a healthcare conglomerate. It operates through two segments: Innovative Medicine, which develops and markets prescription drugs in oncology, immunology, neuroscience, and infectious disease, and MedTech, which manufactures medical devices for surgery, orthopedics, and interventional solutions.

2 months ago
Intuitive Surgical, Inc. (NASDAQ:ISRG) has declined more than 29% over the past 6 months and is now trading close to its 52-week lows. The downward pressure stems from regulatory scrutiny regarding instrument reuse and concerns over Chinese competition.
However, the Street expects the stock to rebound, with ******* ysts' 12-month average price target suggesting more than 42% upside, making Intuitive Surgical, Inc. (NASDAQ:ISRG) one of the Top Large Cap Stocks to Invest In At 52-Week Lows.
Recently, on June 23, BTIG ******* yst Ryan Zimmerman reiterated a Buy rating on the stock with a price target of $574. Earlier on June 12, Bank of America Securities had reiterated a Buy rating on the stock with a price target of $515, down slightly from the previous target of $520. The adjustment reflects a more cautious stance on 2027 estimates across BofA's broader medtech coverage.
BofA noted that its services team has flagged a lower utilization environment, suggesting hospitals and surgical centers are using robotic surgery systems less intensively than previously expected. Moreover, the firm's ******* yst Steed also noted that factoring in inflation as a growing headwind in 2027, with less room for margin expansion across the medtech sector.
Intuitive Surgical Inc. (NASDAQ:ISRG) engages in the development, manufacturing, and marketing of da Vinci surgical systems and Ion endoluminal system.
However, the Street expects the stock to rebound, with ******* ysts' 12-month average price target suggesting more than 42% upside, making Intuitive Surgical, Inc. (NASDAQ:ISRG) one of the Top Large Cap Stocks to Invest In At 52-Week Lows.
Recently, on June 23, BTIG ******* yst Ryan Zimmerman reiterated a Buy rating on the stock with a price target of $574. Earlier on June 12, Bank of America Securities had reiterated a Buy rating on the stock with a price target of $515, down slightly from the previous target of $520. The adjustment reflects a more cautious stance on 2027 estimates across BofA's broader medtech coverage.
BofA noted that its services team has flagged a lower utilization environment, suggesting hospitals and surgical centers are using robotic surgery systems less intensively than previously expected. Moreover, the firm's ******* yst Steed also noted that factoring in inflation as a growing headwind in 2027, with less room for margin expansion across the medtech sector.
Intuitive Surgical Inc. (NASDAQ:ISRG) engages in the development, manufacturing, and marketing of da Vinci surgical systems and Ion endoluminal system.

3 months ago
Boston Scientific Corporation (NYSE:BSX) is one of the best low volatility stocks to buy under $50. BofA cut the price target on Boston Scientific Corporation (NYSE:BSX) to $61 from $68 on June 12 and maintained a Buy rating on the shares. It noted that the firm's services team continues to highlight a lower utilization environment, and Barclays wants to take a more conservative view on 2027 medtech company estimates, given valuations are already reflecting utilization risk. It further told investors that the firm is lowering 2027 estimates across its larger-cap coverage where there's exposure to utilization and inflation.
Boston Scientific Corporation (NYSE:BSX) also received a rating update from Canaccord on June 1. The firm lowered the price target on the stock to $70 from $71, reiterating a Buy rating on the shares. Canaccord stated that it updated its model on the stock to take into account slowdowns in the U.S. Watchman business in 2026 and 2027, which have negative implications on its revenue and EPS estimates.
Boston Scientific Corporation (NYSE:BSX) manufactures, develops, and markets medical devices used in interventional medical procedures. Its operations are divided into Cardiovascular and MedSurg segments. The Cardiovascular segment covers Cardiology and Peripheral Interventions, while the MedSurg segment comprises Urology, Endoscopy, and Neuromodulation.
While we acknowledge the potential of BSX as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.
Boston Scientific Corporation (NYSE:BSX) also received a rating update from Canaccord on June 1. The firm lowered the price target on the stock to $70 from $71, reiterating a Buy rating on the shares. Canaccord stated that it updated its model on the stock to take into account slowdowns in the U.S. Watchman business in 2026 and 2027, which have negative implications on its revenue and EPS estimates.
Boston Scientific Corporation (NYSE:BSX) manufactures, develops, and markets medical devices used in interventional medical procedures. Its operations are divided into Cardiovascular and MedSurg segments. The Cardiovascular segment covers Cardiology and Peripheral Interventions, while the MedSurg segment comprises Urology, Endoscopy, and Neuromodulation.
While we acknowledge the potential of BSX as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.


3 months ago
Boston Scientific Corporation (NYSE:BSX) is one of the best low volatility stocks to buy under $50. BofA cut the price target on Boston Scientific Corporation (NYSE:BSX) to $61 from $68 on June 12 and maintained a Buy rating on the shares. It noted that the firm's services team continues to highlight a lower utilization environment, and Barclays wants to take a more conservative view on 2027 medtech company estimates, given valuations are already reflecting utilization risk. It further told investors that the firm is lowering 2027 estimates across its larger-cap coverage where there's exposure to utilization and inflation.
Boston Scientific Corporation (NYSE:BSX) also received a rating update from Canaccord on June 1. The firm lowered the price target on the stock to $70 from $71, reiterating a Buy rating on the shares. Canaccord stated that it updated its model on the stock to take into account slowdowns in the U.S. Watchman business in 2026 and 2027, which have negative implications on its revenue and EPS estimates.
Boston Scientific Corporation (NYSE:BSX) manufactures, develops, and markets medical devices used in interventional medical procedures. Its operations are divided into Cardiovascular and MedSurg segments. The Cardiovascular segment covers Cardiology and Peripheral Interventions, while the MedSurg segment comprises Urology, Endoscopy, and Neuromodulation.
While we acknowledge the potential of BSX as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.
Boston Scientific Corporation (NYSE:BSX) also received a rating update from Canaccord on June 1. The firm lowered the price target on the stock to $70 from $71, reiterating a Buy rating on the shares. Canaccord stated that it updated its model on the stock to take into account slowdowns in the U.S. Watchman business in 2026 and 2027, which have negative implications on its revenue and EPS estimates.
Boston Scientific Corporation (NYSE:BSX) manufactures, develops, and markets medical devices used in interventional medical procedures. Its operations are divided into Cardiovascular and MedSurg segments. The Cardiovascular segment covers Cardiology and Peripheral Interventions, while the MedSurg segment comprises Urology, Endoscopy, and Neuromodulation.
While we acknowledge the potential of BSX as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.

3 months ago
With a market cap of $580.1 billion, Johnson & Johnson (JNJ) is a global healthcare company engaged in the research, development, manufacture, and sale of a broad range of medical products and solutions through its Innovative Medicine and MedTech segments. It serves healthcare providers, hospitals, retailers, and patients worldwide across areas including pharmaceuticals, surgery, orthopedics, cardiovascular care, and vision health.
The New Brunswick, New Jersey-based company is expected to unveil its fiscal Q2 2026 results before the market opens on Wednesday, Jul. 15. Ahead of the event, ****** ysts forecast JNJ to post an adjusted EPS of $2.83, a growth of 2.2% from $2.77 in the same quarter last year. It has surpassed Wall Street's bottom-line projections in the past four quarters.
Palantir Stock Crashes to a 52-Week Low: Why It's Time to Buy the Dip.
Corning Stock Skyrockets on AI-Related Demand, Spurring Unusual Call Option Buying
AMD's MEXT Acquisition Is More Important Than Markets Realize. Here's How It Solves the Memory Bottleneck.
The New Brunswick, New Jersey-based company is expected to unveil its fiscal Q2 2026 results before the market opens on Wednesday, Jul. 15. Ahead of the event, ****** ysts forecast JNJ to post an adjusted EPS of $2.83, a growth of 2.2% from $2.77 in the same quarter last year. It has surpassed Wall Street's bottom-line projections in the past four quarters.
Palantir Stock Crashes to a 52-Week Low: Why It's Time to Buy the Dip.
Corning Stock Skyrockets on AI-Related Demand, Spurring Unusual Call Option Buying
AMD's MEXT Acquisition Is More Important Than Markets Realize. Here's How It Solves the Memory Bottleneck.



1 yr. ago
News is everywhere. But can you trust it? How can you leverage it to gain a competitive edge? Start your free trial: https://ow.ly/KKEz50TTwo6.
Unlock expert ****** ysis of the pharma, biotech, medtech, and consumer health with 1-week’s access to our award-winning publications.
Unlock expert ****** ysis of the pharma, biotech, medtech, and consumer health with 1-week’s access to our award-winning publications.
1 yr. ago
Wonderful news,
JNJMedTech
JNJNews
JNJInnovation
we have some excellent imaging enterprise portfolio **** ets on our official business networks.
_smartgxp
Thanks
JNJMedTech
JNJNews
JNJInnovation
we have some excellent imaging enterprise portfolio **** ets on our official business networks.
_smartgxp
Thanks



