2 months ago
SPX Technologies, Inc. (NYSE:SPXC) announced on September 15 that it completed the acquisition of FIS Water, LLC for approximately $410 million in cash, including certain tax attributes. The acquired business is expected to generate approximately $105 million of revenue in 2026.
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE

2 months ago
RF Industries, Ltd. (NASDAQ:RFIL) reported stronger fiscal third-quarter results on September 14. Revenue increased 21% to $23.96 million for the quarter ended July 31, 2026, while operating income reached approximately $1.8 million, compared with $720,000 a year earlier.
The next question is whether new orders can sustain that performance. Quarterly bookings totaled $22.5 million, below revenue. Backlog stood at $18.6 million at quarter-end and increased to $19.8 million by September 14.
Bookings measure new orders, including modifications or cancellations of earlier orders. Backlog represents orders received for which revenue has yet to be recognized.
RF Industries, Ltd. (NASDAQ:RFIL) improved both sales and profitability. Gross margin increased to 35.6% from 34% a year earlier, helping operating income grow much faster than revenue.
Management attributes the margin expansion to a shift toward customized cabling and integrated systems. These offerings involve more engineering and larger projects than traditional component sales. Competing on technical capability and customer requirements could support stronger relationships and repeat business.
#earlier
The next question is whether new orders can sustain that performance. Quarterly bookings totaled $22.5 million, below revenue. Backlog stood at $18.6 million at quarter-end and increased to $19.8 million by September 14.
Bookings measure new orders, including modifications or cancellations of earlier orders. Backlog represents orders received for which revenue has yet to be recognized.
RF Industries, Ltd. (NASDAQ:RFIL) improved both sales and profitability. Gross margin increased to 35.6% from 34% a year earlier, helping operating income grow much faster than revenue.
Management attributes the margin expansion to a shift toward customized cabling and integrated systems. These offerings involve more engineering and larger projects than traditional component sales. Competing on technical capability and customer requirements could support stronger relationships and repeat business.
#earlier

2 months ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#quarter


2 months ago
Rocket Lab (RKLB) stock has traded between $39.48 and $150.23 over the past 52 weeks. It now sits about 58% below its 52-week high, and anyone who bought twelve months ago is still up about 19%. None of that tells you what you would be buying today. Rocket Lab sells two quite different things, and the one its name points at is the smaller of them.
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue
In Q2 2026 the ****** e Systems segment brought in $189.5 million. Launch Services brought in $44.6 million, down 30% from the previous quarter despite a similar number of launches. Management attributes that drop to accounting rather than lost work, because revenue from those launches is recognized over time and much of it had already been booked.
So Rocket Lab earns most of its revenue building satellites and their parts. Electron flew its 16th mission of 2026 in September. Launch is a real franchise, and it is not where most of the money comes from.
The stock trades at 52 times sales, against 3.1 for the S&P 500, on revenue of about $0.8 billion over the trailing twelve months. At this valuation, investors are largely pricing in future execution on the Neutron medium-lift rocket and the financial impact of the pending Iridium acquisition, rather than current satellite production alone. Management targets delivery to the pad in Q4 2026, and says the window for a launch before the end of 2026 is narrowing.
And you are paying for Iridium, which Rocket Lab has agreed to buy and expects to close in mid-2027. Iridium, a global satellite communications network, serves more than 2.5 million subscribers and delivered over $870 million of revenue in its past year. That is more than Rocket Lab's whole trailing twelve months. Management calls it a relatively slow-growing business that brings profit rather than a hole in the income statement.
#million #management #revenue


2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Revenue growth of 60% year-over-year was driven by a combination of competitive share gains, market expansion, and a higher mix of in-network patients.
Management attributes the 11th consecutive quarter of gross margin expansion to attractive unit economics and volume leverage inherent in the rental business model.
The 'integrated care model' is cited as a key differentiator, where therapeutic protection is paired with responsive support services to convert clinical insights into urgent patient care.
Strategic territory management, including splitting high-volume 'platinum' territories and adding clinical specialists, is compounding growth by deepening penetration in existing accounts.
#Growth #tell
Revenue growth of 60% year-over-year was driven by a combination of competitive share gains, market expansion, and a higher mix of in-network patients.
Management attributes the 11th consecutive quarter of gross margin expansion to attractive unit economics and volume leverage inherent in the rental business model.
The 'integrated care model' is cited as a key differentiator, where therapeutic protection is paired with responsive support services to convert clinical insights into urgent patient care.
Strategic territory management, including splitting high-volume 'platinum' territories and adding clinical specialists, is compounding growth by deepening penetration in existing accounts.
#Growth #tell


2 months ago
On August 5, Kinetik Holdings Inc. (NYSE:KNTK) reported the strongest quarterly results in company history and raised its full-year 2026 guidance. The Permian-focused midstream operator posted net income, including noncontrolling interest, of $123.1 million for the quarter ended June 30, while Adjusted EBITDA climbed to $280.8 million. Management didn't stop at celebrating the number. It used the quarter as the launchpad for a string of expansion decisions that stretch out to 2028.
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#natural
The Midstream Logistics segment, Kinetik's largest, grew Adjusted EBITDA 35% year over year to $204.8 million in the second quarter, even though processed natural gas volumes held flat at 1.74 Bcf/d. That flat number actually undersells the quarter. It came despite roughly 250 million cubic feet per day of gas that had been shut in because of weak Waha-area pricing, with stronger natural gas liquid recoveries, condensate yields, and favorable commodity spreads carrying the segment instead.
Management is betting the growth continues well past 2026. In May, Kinetik reached a final investment decision on Kings Landing II, a roughly $260 million project that will lift sour gas processing capacity across the company's Delaware North complex above 700 MMcf/d and push total system capacity to 2.7 Bcf/d when it comes online in mid-2028, earlier than previously communicated. The ECCC Pipeline, which links the system's northern and southern halves between Eddy and Culberson Counties, is now in service, and right-of-way work has already begun on a follow-on expansion for 2027.
Kinetik also locked in new firm Gulf Coast access for residue gas starting in 2027 and signed fresh natural gas liquids transport agreements, both aimed at getting better prices for the gas it moves. On the back of that momentum, Kinetik raised its full-year 2026 Adjusted EBITDA guidance to a range of $1.04 billion to $1.1 billion, a 7% ***** p from the guidance it issued in February.
Not every part of the business is moving in the same direction. The Pipeline Transportation segment posted Adjusted EBITDA of $83.0 million in the quarter, down 14% year over year, a decline the company attributes to last year's divestiture of its equity stake in EPIC Crude Holdings. That sale removed a source of cash flow the rest of the business now has to make up for. Kinetik also expects gas curtailments to keep running at an average of 25 million cubic feet per day through the second half of 2026, on top of the Waha-driven shut-ins that already weighed on the quarter. Its own pricing ***** umptions underline the regional problem: the company is now modeling Waha Hub natural gas at negative $0.26 per MMBtu for the full year, meaning gas in parts of the Permian is priced so low that moving it out of the basin is the whole game.
#natural


2 months ago
On August 6, PureCycle Technologies (NASDAQ:PCT) reported second-quarter results for the period ended June 30, and buried in the numbers was something the plastics recycler has chased for years: an actual branded product on store shelves. Select Downy detergent caps made with PureCycle's PureFive resin entered commercial production for Procter & Gamble during the quarter, the first tangible sign the company's purification technology can clear a major consumer brand's supply chain. Revenue came in at $4.5 million, up roughly 173% from a year earlier and the sixth straight quarter of sequential growth.
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss
The Downy win was not an isolated event. PureCycle said select Tide caps are scheduled for retail production in the third quarter, with Vicks ZzzQuil PURE Zzzs child-resistant lids targeted for the fourth quarter of 2026. Seven customer conversions took place during the quarter, alongside six new commercial partnerships spanning closures, automotive, film, and food packaging, including Amcor, Motherson, and Innovia Films. Regulation is doing real work here too. New Jersey's Department of Environmental Protection approved PureFive as post-consumer recycled content, a decision that arrives as the state's food contact exemption expires in January 2027 and its recycled content requirement climbs to 20%, while California's SB54 is already in effect.
Operationally, the Ironton facility's planned turnaround finished ahead of schedule and under budget, with more than 170 reliability and rate projects completed and inspections showing no corrosion on major equipment. On-site compounding, commissioned in April, is now running 24 hours a day, five days a week, with plans to expand to seven by the fourth quarter. PureCycle also picked up ISO 9001:2015 certification in May and closed the quarter with $236.9 million in total liquidity after a June capital raise.
The other side of the ledger is harder to ignore. PureCycle posted a net loss of $142.2 million for the quarter, and adjusted EBITDA actually widened to a loss of $31.7 million from a loss of $27.8 million a year earlier, a shift the company attributes to smaller non-cash addbacks rather than weaker operations. PureFive production fell to 4.5 million pounds for the quarter, a direct result of the planned turnaround, even though output was still up about 32% from a year ago. Growth is not coming cheap either. Full-year 2026 project spending guidance was raised to a range of $45 million to $50 million, up from the prior $39 million to $45 million.
#year #loss


2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Net sales growth of 22% was primarily driven by sustained demand across enterprise, data center, and specialty market sectors, including military applications.
Gross profit margin expansion to 37.4% demonstrates significant manufacturing operating leverage, where fixed costs are distributed over higher production volumes.
Management attributes margin improvements to increased manufacturing efficiencies that naturally occur as production volumes scale.
The company is navigating industry-wide optical fiber shortages and raw material lead time extensions by actively managing supply chain dynamics to protect customer deliveries.
#Margin #Manufacturing #volumes #management
Net sales growth of 22% was primarily driven by sustained demand across enterprise, data center, and specialty market sectors, including military applications.
Gross profit margin expansion to 37.4% demonstrates significant manufacturing operating leverage, where fixed costs are distributed over higher production volumes.
Management attributes margin improvements to increased manufacturing efficiencies that naturally occur as production volumes scale.
The company is navigating industry-wide optical fiber shortages and raw material lead time extensions by actively managing supply chain dynamics to protect customer deliveries.
#Margin #Manufacturing #volumes #management

2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the sequential improvement in comparable sales to enhanced digital conversion and the successful scaling of private brand franchises like THERMACHILL.
The company is navigating a structural shift in customer behavior driven by GLP-1 medication adoption, which has led to temporary pauses in apparel purchasing during weight loss journeys.
Performance was significantly bolstered by a $4.6 million IEEPA tariff refund, which masked a 70 basis point decline in underlying merchandise margins caused by higher markdowns and shipping surcharges.
Strategic focus has shifted toward 'Fit Authority' through the FITMAP initiative, which has scanned 150,000 customers and resulted in higher average order values and lower return rates.
#performance
Management attributes the sequential improvement in comparable sales to enhanced digital conversion and the successful scaling of private brand franchises like THERMACHILL.
The company is navigating a structural shift in customer behavior driven by GLP-1 medication adoption, which has led to temporary pauses in apparel purchasing during weight loss journeys.
Performance was significantly bolstered by a $4.6 million IEEPA tariff refund, which masked a 70 basis point decline in underlying merchandise margins caused by higher markdowns and shipping surcharges.
Strategic focus has shifted toward 'Fit Authority' through the FITMAP initiative, which has scanned 150,000 customers and resulted in higher average order values and lower return rates.
#performance


2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by the compounding power of the identity security platform and rapid adoption of SaaS, which accounted for 97% of net new ARR in Q2.
Management attributes growth to the strategic elevation of identity governance to CISO and Board-level priorities, unlocking larger enterprise budget opportunities.
The acquisition of Entro Security accelerated the product roadmap by expanding discovery capabilities to over 1,200 non-human identity types, providing critical lineage context.
Strategic positioning focuses on a unified control plane, arguing that monitoring alone is insufficient and that proactive governance must link autonomous agents to accountable humans.
#performance #management
Performance was driven by the compounding power of the identity security platform and rapid adoption of SaaS, which accounted for 97% of net new ARR in Q2.
Management attributes growth to the strategic elevation of identity governance to CISO and Board-level priorities, unlocking larger enterprise budget opportunities.
The acquisition of Entro Security accelerated the product roadmap by expanding discovery capabilities to over 1,200 non-human identity types, providing critical lineage context.
Strategic positioning focuses on a unified control plane, arguing that monitoring alone is insufficient and that proactive governance must link autonomous agents to accountable humans.
#performance #management


2 months ago
Microsoft (MSFT) is coming off the most profitable stretch it has posted in years, and its stock trades at $493.95, about 92% of its 52-week high. Nothing here is broken. The risk is quieter than that. The spending that came with those margins is still climbing, and the company has already told shareholders what it expects that to do to fiscal 2027.
Net margin over the trailing twelve months is 40.3%, the highest in at least five years and well above a 36.8% three-year average. Operating margin runs 46.8% against a 45.3% three-year average, near the top of its multi-year range. Revenue of $331.8 billion grew 17.8% year over year, so none of this came from a shrinking business.
Margins at a peak rarely stay there. This peak arrives with a specific and growing bill, and that bill is the Azure build-out.
Azure revenue grew 43% in fiscal Q4 2026, and management says customer demand still exceeds available capacity. Company-wide, the build-out took $41 billion of capital expenditure in that one quarter (including equipment acquired under leases), roughly two-thirds of it on what management calls short-lived **** ets, primarily CPUs and GPUs. Against $55.4 billion in cash from operations, cash actually paid for property and equipment was $35.8 billion, yielding $19.6 billion in free cash flow.
The bill is already visible in the margin. The company's gross margin was 67% in fiscal Q4 2026, down year over year, and management attributes the decline to the sales mix shift toward Azure and the AI infrastructure spending behind it, offset only partly by efficiency gains. Capital expenditure is guided higher again in fiscal 2027.
#azure #bill #cash
Net margin over the trailing twelve months is 40.3%, the highest in at least five years and well above a 36.8% three-year average. Operating margin runs 46.8% against a 45.3% three-year average, near the top of its multi-year range. Revenue of $331.8 billion grew 17.8% year over year, so none of this came from a shrinking business.
Margins at a peak rarely stay there. This peak arrives with a specific and growing bill, and that bill is the Azure build-out.
Azure revenue grew 43% in fiscal Q4 2026, and management says customer demand still exceeds available capacity. Company-wide, the build-out took $41 billion of capital expenditure in that one quarter (including equipment acquired under leases), roughly two-thirds of it on what management calls short-lived **** ets, primarily CPUs and GPUs. Against $55.4 billion in cash from operations, cash actually paid for property and equipment was $35.8 billion, yielding $19.6 billion in free cash flow.
The bill is already visible in the margin. The company's gross margin was 67% in fiscal Q4 2026, down year over year, and management attributes the decline to the sales mix shift toward Azure and the AI infrastructure spending behind it, offset only partly by efficiency gains. Capital expenditure is guided higher again in fiscal 2027.
#azure #bill #cash

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the 25% revenue decline primarily to a technical 'algorithm dislocation' with its largest advertising partner, causing an audience drift that sharply increased customer acquisition costs (CPA) for IL MAKIAGE.
The company is prioritizing technical remediation over immediate growth for IL MAKIAGE, shifting resources toward intensive testing to retrain the ad algorithm rather than executing its planned product pipeline.
SpoiledChild is demonstrating operational resilience, on track for $350 million in 2026 revenue by maintaining strong unit economics and 12-month net revenue repeat rates exceeding 100% despite broader platform headwinds.
The launch of METHODIQ signals a strategic pivot toward the 'beauty and medicine' convergence, leveraging computer vision and ODDITY Labs' patented molecules to capture higher-intent medical-grade customers.
#tell #management
Management attributes the 25% revenue decline primarily to a technical 'algorithm dislocation' with its largest advertising partner, causing an audience drift that sharply increased customer acquisition costs (CPA) for IL MAKIAGE.
The company is prioritizing technical remediation over immediate growth for IL MAKIAGE, shifting resources toward intensive testing to retrain the ad algorithm rather than executing its planned product pipeline.
SpoiledChild is demonstrating operational resilience, on track for $350 million in 2026 revenue by maintaining strong unit economics and 12-month net revenue repeat rates exceeding 100% despite broader platform headwinds.
The launch of METHODIQ signals a strategic pivot toward the 'beauty and medicine' convergence, leveraging computer vision and ODDITY Labs' patented molecules to capture higher-intent medical-grade customers.
#tell #management

2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Total software revenue grew 21% year-over-year, significantly outstripping total revenue growth as the company executes a deliberate shift toward higher-quality, scalable revenue streams.
Management attributes strong performance to a healthy demand environment where governments are prioritizing national security, border security, and public safety through enhanced intelligence capabilities.
The platform's competitive advantage is driven by 'sovereign AI,' allowing agencies to maintain full control over data and infrastructure while utilizing AI that is explainable rather than a 'black box.'
Domain expertise is cited as the primary differentiator against general-purpose AI models, as intelligence work focuses on rare and obscure data rather than common cases.
#year #security #data #rather
Total software revenue grew 21% year-over-year, significantly outstripping total revenue growth as the company executes a deliberate shift toward higher-quality, scalable revenue streams.
Management attributes strong performance to a healthy demand environment where governments are prioritizing national security, border security, and public safety through enhanced intelligence capabilities.
The platform's competitive advantage is driven by 'sovereign AI,' allowing agencies to maintain full control over data and infrastructure while utilizing AI that is explainable rather than a 'black box.'
Domain expertise is cited as the primary differentiator against general-purpose AI models, as intelligence work focuses on rare and obscure data rather than common cases.
#year #security #data #rather


2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by the disciplined execution of a value creation strategy, resulting in 27% full-year adjusted EBITDA growth despite reported sales declines from network optimization.
Management attributes underlying sales growth to the $90 billion target addressable market of differentiated retailers, who increased their grocery industry share by 30 basis points.
Operational efficiency improved through the deployment of 'Lean' daily management to 44 distribution centers, resulting in four consecutive quarters of fill rate and throughput gains.
The natural product segment continues to outperform the broader market, reflecting enduring consumer demand for health-forward and specialty products.
#resulting #performance #ebitda #operational
Performance was driven by the disciplined execution of a value creation strategy, resulting in 27% full-year adjusted EBITDA growth despite reported sales declines from network optimization.
Management attributes underlying sales growth to the $90 billion target addressable market of differentiated retailers, who increased their grocery industry share by 30 basis points.
Operational efficiency improved through the deployment of 'Lean' daily management to 44 distribution centers, resulting in four consecutive quarters of fill rate and throughput gains.
The natural product segment continues to outperform the broader market, reflecting enduring consumer demand for health-forward and specialty products.
#resulting #performance #ebitda #operational

2 months ago
The Los Angeles Rams have historically been OK with a lack of size at the cornerback position. Their last few draft picks—although rare—have demonstrated this from Cobie Durant and Derion Kendrick to the likes of Tre Tomlinson.
But the Rams did something very out of character this offseason: they made a major free agent signing and brought in a player with real size attributes. Jaylen Watson is listed at 6-2 and 197 lbs.
The addition of Watson got lost in the shuffle during the aftermath of LA's trade for higher profile corner Trent McDuffie, his Kansas City teammate. McDuffie also fits the Rams' preference or accommodation of smaller defenders, although he has a strong lower half and is a willing tackler out of the slot.
However, in Week 1 against the San Francisco 49ers, Watson may be the more important contributor out of the two.
The San Francisco 49ers' biggest offseason addition was receiver Mike Evans. It wouldn't be wise for the Rams to ask McDuffie to cover one of the most physical receivers in the NFL—this is a job for Watson.
#mcduffie #francisco #addition #angeles
But the Rams did something very out of character this offseason: they made a major free agent signing and brought in a player with real size attributes. Jaylen Watson is listed at 6-2 and 197 lbs.
The addition of Watson got lost in the shuffle during the aftermath of LA's trade for higher profile corner Trent McDuffie, his Kansas City teammate. McDuffie also fits the Rams' preference or accommodation of smaller defenders, although he has a strong lower half and is a willing tackler out of the slot.
However, in Week 1 against the San Francisco 49ers, Watson may be the more important contributor out of the two.
The San Francisco 49ers' biggest offseason addition was receiver Mike Evans. It wouldn't be wise for the Rams to ask McDuffie to cover one of the most physical receivers in the NFL—this is a job for Watson.
#mcduffie #francisco #addition #angeles


2 months ago
Nike has just released a new video campaign in honor of Carlos Alcaraz, who's set to defend his US Open crown at Arthur Ashe Stadium in New York today.
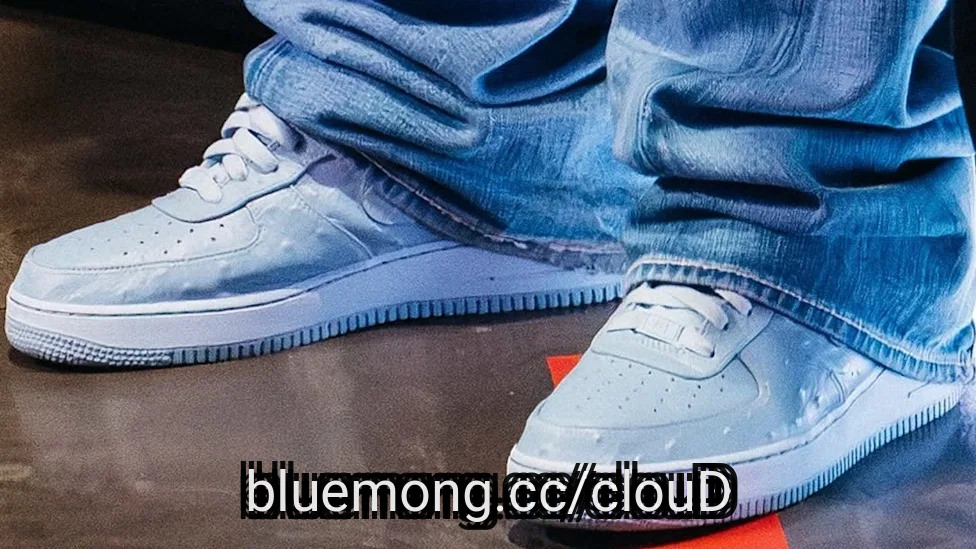
Just moments ago, Alcaraz's new US Open campaign was shared on the Swoosh's and Alcaraz's Instagram accounts. The ad is narrated by fellow Nike endorser Travis Scott, who is seen wearing his unreleased Air Force 1 collab. Throughout the video, Travis breaks down Alcaraz's impressive tennis attributes while the reigning US Open champion returns several volleys. The ad ends with both Travis' "Cactus Jack" logo and the reverse Swoosh appearing.
Despite the teaser, release details for the new Travis Scott x Nike Air Force 1 collab have yet to be announced by either of the parties involved. Alcaraz's US Open **** le defense begins this afternoon with his first-round matchup against Roman Safiullin.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
Travis Scott's Nike Air Force 1 'Ice Blue' Is Releasing This Fall
#open #shop #carlos #alcaraz
Just moments ago, Alcaraz's new US Open campaign was shared on the Swoosh's and Alcaraz's Instagram accounts. The ad is narrated by fellow Nike endorser Travis Scott, who is seen wearing his unreleased Air Force 1 collab. Throughout the video, Travis breaks down Alcaraz's impressive tennis attributes while the reigning US Open champion returns several volleys. The ad ends with both Travis' "Cactus Jack" logo and the reverse Swoosh appearing.
Despite the teaser, release details for the new Travis Scott x Nike Air Force 1 collab have yet to be announced by either of the parties involved. Alcaraz's US Open **** le defense begins this afternoon with his first-round matchup against Roman Safiullin.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
Travis Scott's Nike Air Force 1 'Ice Blue' Is Releasing This Fall
#open #shop #carlos #alcaraz

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record Q3 revenue of $1.7 billion and 22.5% operating margin, driven by an accelerating industry demand environment for data center infrastructure.
Management attributes the performance to Ciena's role in re-architecting networks for AI, which requires high-speed, low-latency optical connectivity for both training and inferencing workloads.
The company is seeing a fundamental shift where optics have become the 'indispensable element' for next-generation AI architectures across traditional WAN, AI-specific WAN, and intra-data center fabrics.
Market share gains are being driven by the WaveLogic 6 Extreme platform, which remains the only 1.6 terabit high-performance modem available after 18 months on the market.
#market #next
Achieved record Q3 revenue of $1.7 billion and 22.5% operating margin, driven by an accelerating industry demand environment for data center infrastructure.
Management attributes the performance to Ciena's role in re-architecting networks for AI, which requires high-speed, low-latency optical connectivity for both training and inferencing workloads.
The company is seeing a fundamental shift where optics have become the 'indispensable element' for next-generation AI architectures across traditional WAN, AI-specific WAN, and intra-data center fabrics.
Market share gains are being driven by the WaveLogic 6 Extreme platform, which remains the only 1.6 terabit high-performance modem available after 18 months on the market.
#market #next

2 months ago
Millwall have completed the signing of Montpellier winger Yanis Issoufou after FIFA confirmed the player's international clearance could be granted.
The 19-year-old has joined the Lions on a long-term contract and becomes the club's 13th signing of the summer transfer window.
The winger progressed through Montpellier's academy, featuring for the club's Under-19 and B teams before breaking into the first team.
Issoufou scored six goals last season and has already made four appearances in the 2026-27 campaign, finding the net once.
Millwall's director of football Steve Gallen believes the young winger has the attributes to develop into an important player for the club.
#winger #montpellier #yanis #gallen
The 19-year-old has joined the Lions on a long-term contract and becomes the club's 13th signing of the summer transfer window.
The winger progressed through Montpellier's academy, featuring for the club's Under-19 and B teams before breaking into the first team.
Issoufou scored six goals last season and has already made four appearances in the 2026-27 campaign, finding the net once.
Millwall's director of football Steve Gallen believes the young winger has the attributes to develop into an important player for the club.
#winger #montpellier #yanis #gallen

2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Total revenue growth accelerated to 30%, the highest rate since fiscal 2024, driven by broad-based strength across both Atlas and Enterprise Advanced (EA).
Management attributes the 36% growth in EA to the strategic launch of search and vector search capabilities, allowing regulated industries to build AI agents within governed, self-managed environments.
The 'run-anywhere' strategy is serving as a key differentiator, with customers increasingly adopting hybrid deployments across multiple clouds and on-premises to satisfy regulatory and operational resilience requirements.
Atlas momentum is being fueled by large enterprise customers and 'AI natives' who migrate to MongoDB after hitting scaling limits with legacy relational databases like Postgres.
#search
Total revenue growth accelerated to 30%, the highest rate since fiscal 2024, driven by broad-based strength across both Atlas and Enterprise Advanced (EA).
Management attributes the 36% growth in EA to the strategic launch of search and vector search capabilities, allowing regulated industries to build AI agents within governed, self-managed environments.
The 'run-anywhere' strategy is serving as a key differentiator, with customers increasingly adopting hybrid deployments across multiple clouds and on-premises to satisfy regulatory and operational resilience requirements.
Atlas momentum is being fueled by large enterprise customers and 'AI natives' who migrate to MongoDB after hitting scaling limits with legacy relational databases like Postgres.
#search

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Record revenue and EPS were driven by the compounding benefits of a modernized operating model, enabling earnings to grow faster than revenue through significant operating leverage.
Management attributes the 122% growth in traditional servers to a structural shift where customers view IT as a value driver rather than a cost center, accelerating the refresh of an aged installed base.
AI server momentum is broadening across Neoclouds, sovereigns, and enterprise customers, with the customer count surpassing 6,500 as organizations move from design to production.
Storage returned to growth and share gains, fueled by strong demand for Dell IP products and early tailwinds from AI workloads requiring massive data movement and protection.
#Growth #management #storage
Record revenue and EPS were driven by the compounding benefits of a modernized operating model, enabling earnings to grow faster than revenue through significant operating leverage.
Management attributes the 122% growth in traditional servers to a structural shift where customers view IT as a value driver rather than a cost center, accelerating the refresh of an aged installed base.
AI server momentum is broadening across Neoclouds, sovereigns, and enterprise customers, with the customer count surpassing 6,500 as organizations move from design to production.
Storage returned to growth and share gains, fueled by strong demand for Dell IP products and early tailwinds from AI workloads requiring massive data movement and protection.
#Growth #management #storage
2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Organic revenue growth of 13.7% was driven by strong underlying market demand and execution across the 'Big 3' businesses: CRM, CST, and Surgical.
Cardiac Ablation Solutions (CAS) delivered 88% growth, fueled by Sphere-9 share gains and the Affera mapping platform reaching a $2 billion trailing 12-month revenue milestone.
The AiBLE ecosystem in Cranial & Spinal Technologies is driving growth by connecting AI-driven planning, robotics, and navigation, which traditionally operated in silos.
Management attributes the broad-based performance to the compounding impact of multi-year strategic, operational, and cultural changes aimed at commercial consistency.
#Growth #driven #solutions
Organic revenue growth of 13.7% was driven by strong underlying market demand and execution across the 'Big 3' businesses: CRM, CST, and Surgical.
Cardiac Ablation Solutions (CAS) delivered 88% growth, fueled by Sphere-9 share gains and the Affera mapping platform reaching a $2 billion trailing 12-month revenue milestone.
The AiBLE ecosystem in Cranial & Spinal Technologies is driving growth by connecting AI-driven planning, robotics, and navigation, which traditionally operated in silos.
Management attributes the broad-based performance to the compounding impact of multi-year strategic, operational, and cultural changes aimed at commercial consistency.
#Growth #driven #solutions

2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Revenue growth of approximately 1,970% in H1 2026 was driven by the rapid expansion of the customer base to over 1,640 enterprise clients.
The company is pivoting from a conventional direct sales model to a partner-led distribution strategy leveraging Microsoft, Google, TCS, and Tech Mahindra to access global enterprise markets.
Management attributes the successful scaling to their 'Agentic' commerce suite, which provides the data, intelligence, and payment rails required for AI agents to execute transactions.
The selection of Rezolve's distributed database technology by Google Cloud validates the company's strategy to license its underlying infrastructure independently of its commerce applications.
#mahindra
Revenue growth of approximately 1,970% in H1 2026 was driven by the rapid expansion of the customer base to over 1,640 enterprise clients.
The company is pivoting from a conventional direct sales model to a partner-led distribution strategy leveraging Microsoft, Google, TCS, and Tech Mahindra to access global enterprise markets.
Management attributes the successful scaling to their 'Agentic' commerce suite, which provides the data, intelligence, and payment rails required for AI agents to execute transactions.
The selection of Rezolve's distributed database technology by Google Cloud validates the company's strategy to license its underlying infrastructure independently of its commerce applications.
#mahindra

2 months ago
The night before the transfer window shut, it seemed it would close with Enzo Fernandez still at Stamford Bridge. Chelsea were asking for £135m. It was more than Manchester City were prepared to pay. It took negotiations on 1 September to bring the price down to £125m, still a joint British transfer record and a deal that took the amount committed to buying players either to or from City this summer to around three quarters of a billion.
Had Chelsea not reduced their demands – which may be seen as an indication of their willingness to get rid of Fernandez, especially when their attempt to replace him with Monaco's Lamine Camara broke down – City might not have signed a third midfielder.
Instead, they completed a £326m revamp in the centre of the pitch. There were several pertinent elements. The £116m buy Elliot Anderson was always their first choice to replace captain Bernardo Silva, who was leaving when his contract expired and who then joined Real Madrid. City took added satisfaction from knowing some of their rivals wanted Anderson, including Manchester United.
Enzo Fernandez completed a £125m move to Manchester City on deadline day (Reuters)
The £85m arrival Ayyoub Bouaddi is seen as a player with the attributes to be world class and who, despite being only 18, is expected to play a lot of games this season. The Morocco international, who is studying for a maths degree, is regarded as belonging to the tradition of intelligent midfielders at City. Significantly, perhaps, City feel he is the only specialist No 6 in their squad.
#fernandez #took #Chelsea #anderson
Had Chelsea not reduced their demands – which may be seen as an indication of their willingness to get rid of Fernandez, especially when their attempt to replace him with Monaco's Lamine Camara broke down – City might not have signed a third midfielder.
Instead, they completed a £326m revamp in the centre of the pitch. There were several pertinent elements. The £116m buy Elliot Anderson was always their first choice to replace captain Bernardo Silva, who was leaving when his contract expired and who then joined Real Madrid. City took added satisfaction from knowing some of their rivals wanted Anderson, including Manchester United.
Enzo Fernandez completed a £125m move to Manchester City on deadline day (Reuters)
The £85m arrival Ayyoub Bouaddi is seen as a player with the attributes to be world class and who, despite being only 18, is expected to play a lot of games this season. The Morocco international, who is studying for a maths degree, is regarded as belonging to the tradition of intelligent midfielders at City. Significantly, perhaps, City feel he is the only specialist No 6 in their squad.
#fernandez #took #Chelsea #anderson


2 months ago
The transfer window slammed shut last night, but there are always a few late deals that only get announced the following morning. Unfortunately, a new midfielder is not one of those despite some speculation today about veteran free agent Georginio Wijnaldum.
The three confirmed moves are loans for Academy standouts Landon Emenalo, 18, Shim Mheuka, 18, and Kiano Dyer, 19 — the two 18-year-olds both going to Celtic in Scotland and Dyer joining League Two side Chesterfield FC. Dyer and Mheuka already have at least one senior appearance to their name while Emenalo (son of our former sporting director Michael Emenalo) was with the first-team on our preseason tour this summer and caught the eye of many observers.
It's certainly a bold move for both Emenalo and Mheuka to be joining the Scottish champions, where they will be competing for minutes against seasoned internationals like former ****** nal left back Kieran Tierney or Denmark striker Kasper Høgh. Celtic manager Martin O'Neill spoke highly of the two teenagers upon their arrival, but we'll just have to wait and see how that translates to minutes at the top level.
"Landon is a very good player we have followed for some time, he will give us some real quality. He has many attributes which I think can benefit us, he is very quick and athletic but also very composed on the ball and while he can defend he certainly gets up the pitch into attacking positions too. I know he has a real desire to do well for us and I am sure he will, as he adds strong competition and support on our left side."
"Shim has great quality, hence Chelsea extending his contract, however I think this period of his career, spent with us, will be beneficial to him and obviously to us. I look forward to working with him, he is a player who I think can give us another great attacking dimension and I'm sure he will make an important contribution to Celtic."
#mheuka #side
The three confirmed moves are loans for Academy standouts Landon Emenalo, 18, Shim Mheuka, 18, and Kiano Dyer, 19 — the two 18-year-olds both going to Celtic in Scotland and Dyer joining League Two side Chesterfield FC. Dyer and Mheuka already have at least one senior appearance to their name while Emenalo (son of our former sporting director Michael Emenalo) was with the first-team on our preseason tour this summer and caught the eye of many observers.
It's certainly a bold move for both Emenalo and Mheuka to be joining the Scottish champions, where they will be competing for minutes against seasoned internationals like former ****** nal left back Kieran Tierney or Denmark striker Kasper Høgh. Celtic manager Martin O'Neill spoke highly of the two teenagers upon their arrival, but we'll just have to wait and see how that translates to minutes at the top level.
"Landon is a very good player we have followed for some time, he will give us some real quality. He has many attributes which I think can benefit us, he is very quick and athletic but also very composed on the ball and while he can defend he certainly gets up the pitch into attacking positions too. I know he has a real desire to do well for us and I am sure he will, as he adds strong competition and support on our left side."
"Shim has great quality, hence Chelsea extending his contract, however I think this period of his career, spent with us, will be beneficial to him and obviously to us. I look forward to working with him, he is a player who I think can give us another great attacking dimension and I'm sure he will make an important contribution to Celtic."
#mheuka #side

2 months ago
Summers Value Partners, a boutique investment firm, noted in its Q2 2026 investor update that The Summers Value Fund delivered strong results in the quarter, returning 41.7% net, outperforming the Russell 2000 Index ETF (IWM), which returned 21.4%, and the Russell 2000 Value Index ETF (IWN), which returned 17.1%. The letter can be downloaded here. The Fund experienced its best quarter since inception, achieving profitability on both long and short positions. Favorable market conditions, particularly in small-cap and healthcare stocks, led to attractive investment opportunities. The Fund maintained a cash position of approximately 13%. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, The Summers Value Fund highlighted Consensus Cloud Solutions, Inc. (NASDAQ:CCSI). Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) is a leading information delivery services provider through a software-as-a-service platform. On August 31, 2026, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) closed at $38.25 per share. Over the past month, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) declined 0.65%, but its shares are up 44.39% over the past year. Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) has a market capitalization of $700.93 million.
The Summers Value Fund stated the following regarding Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) in its Q2 2026 investor letter:
Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) - $695 million market cap. Consensus Cloud Solutions is a leading provider of cloud-based fax services to the healthcare sector under its well-recognized eFax brand. Faxing remains an important means of communication in the healthcare ecosystem with billions of pages sent each year. Faxing, while a legacy technology, allows industry participants to communicate in a HIPAA-compliant manner. Many hospitals and clinics still rely on physical fax machines while Consensus' cloud-based service feels more like sending an email.
Consensus was a busted spin-off from J2 Global when we started buying shares two years ago. The stock had declined from $65 to a low of $12 following missed expectations and an accounting restatement. At its low, the stock traded at 2.5x GAAP earnings. We began building our position at $16, or 3.5x GAAP earnings. Despite selling legacy technology into an industry in secular decline, the company had several attributes we found appealing: high margins, low customer churn, and strong free cash flow generation. After years of a declining share price, investor expectations and sell-side coverage were almost non-existent, which helped create the mispricing..." (Click here to read the full text)
#solutions
In its second-quarter 2026 investor letter, The Summers Value Fund highlighted Consensus Cloud Solutions, Inc. (NASDAQ:CCSI). Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) is a leading information delivery services provider through a software-as-a-service platform. On August 31, 2026, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) closed at $38.25 per share. Over the past month, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) declined 0.65%, but its shares are up 44.39% over the past year. Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) has a market capitalization of $700.93 million.
The Summers Value Fund stated the following regarding Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) in its Q2 2026 investor letter:
Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) - $695 million market cap. Consensus Cloud Solutions is a leading provider of cloud-based fax services to the healthcare sector under its well-recognized eFax brand. Faxing remains an important means of communication in the healthcare ecosystem with billions of pages sent each year. Faxing, while a legacy technology, allows industry participants to communicate in a HIPAA-compliant manner. Many hospitals and clinics still rely on physical fax machines while Consensus' cloud-based service feels more like sending an email.
Consensus was a busted spin-off from J2 Global when we started buying shares two years ago. The stock had declined from $65 to a low of $12 following missed expectations and an accounting restatement. At its low, the stock traded at 2.5x GAAP earnings. We began building our position at $16, or 3.5x GAAP earnings. Despite selling legacy technology into an industry in secular decline, the company had several attributes we found appealing: high margins, low customer churn, and strong free cash flow generation. After years of a declining share price, investor expectations and sell-side coverage were almost non-existent, which helped create the mispricing..." (Click here to read the full text)
#solutions

2 months ago
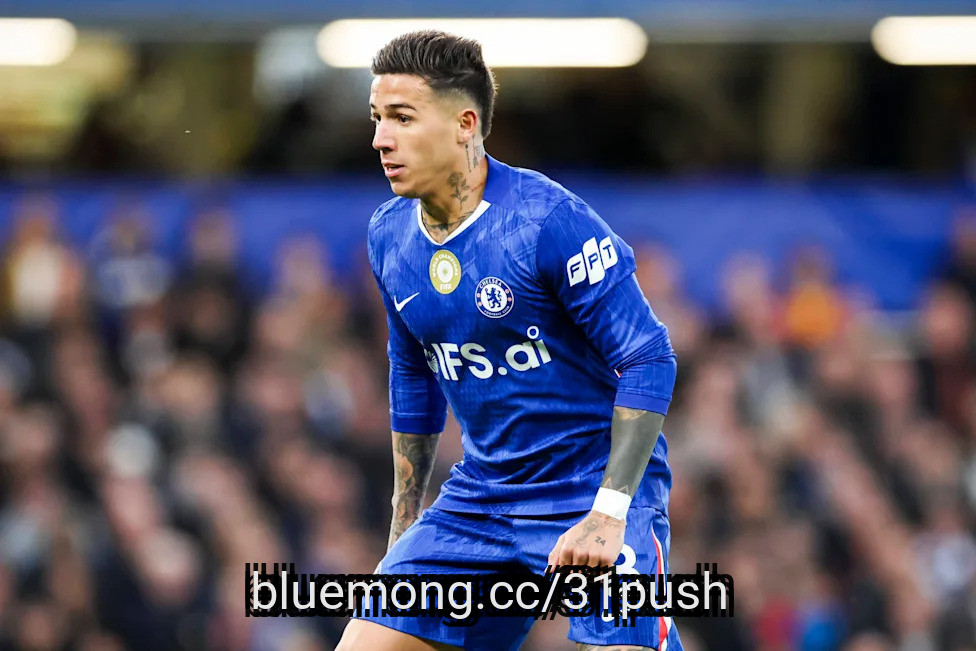
Chelsea's handling of Enzo Fernandez's move to Manchester City has emerged as one of the standout stories of deadline day, with the London club choosing to honour an agreement despite late complications in the market.
As the window reached its conclusion, Chelsea had scope to revisit the situation. After issues surrounding Lamine Camara and the failed pursuit of a replacement, there was an opening to step back and inform Manchester City that Fernandez would no longer be available. Instead, Chelsea pressed ahead and sanctioned the transfer.
The key detail in this Enzo Fernandez deal is not only that Manchester City secured their target, but that Chelsea stayed consistent when circumstances changed. In a market often shaped by sudden reversals, that decision has been viewed internally and externally as significant.
One widely shared ***** sment of Chelsea's stance summed it up clearly: "Chelsea were class this deadline day. Chelsea had this possibility after the drama to Lamine Camara to say to Manchester City 'Sorry, we lost our replacement, Enzo can't come to to Manchester City anymore', But Chelsea decided to maintain their word to Enzo Fernandez. Maintain their word to Manchester City. Maintain their word regarding the deal and to still give the green light for Enzo to go to Manchester City Because, Chelsea behave as a serious club."
For Manchester City, the arrival of Fernandez adds another high-level option in midfield and reflects a decisive end to their transfer business. The Argentina international brings technical quality, control in possession and proven experience at elite level, attributes that will be expected to enhance the champions' engine room immediately.
#fernandez #lamine #deadline
As the window reached its conclusion, Chelsea had scope to revisit the situation. After issues surrounding Lamine Camara and the failed pursuit of a replacement, there was an opening to step back and inform Manchester City that Fernandez would no longer be available. Instead, Chelsea pressed ahead and sanctioned the transfer.
The key detail in this Enzo Fernandez deal is not only that Manchester City secured their target, but that Chelsea stayed consistent when circumstances changed. In a market often shaped by sudden reversals, that decision has been viewed internally and externally as significant.
One widely shared ***** sment of Chelsea's stance summed it up clearly: "Chelsea were class this deadline day. Chelsea had this possibility after the drama to Lamine Camara to say to Manchester City 'Sorry, we lost our replacement, Enzo can't come to to Manchester City anymore', But Chelsea decided to maintain their word to Enzo Fernandez. Maintain their word to Manchester City. Maintain their word regarding the deal and to still give the green light for Enzo to go to Manchester City Because, Chelsea behave as a serious club."
For Manchester City, the arrival of Fernandez adds another high-level option in midfield and reflects a decisive end to their transfer business. The Argentina international brings technical quality, control in possession and proven experience at elite level, attributes that will be expected to enhance the champions' engine room immediately.
#fernandez #lamine #deadline
2 months ago
Summers Value Partners, a boutique investment firm, noted in its Q2 2026 investor update that The Summers Value Fund delivered strong results in the quarter, returning 41.7% net, outperforming the Russell 2000 Index ETF (IWM), which returned 21.4%, and the Russell 2000 Value Index ETF (IWN), which returned 17.1%. The letter can be downloaded here. The Fund experienced its best quarter since inception, achieving profitability on both long and short positions. Favorable market conditions, particularly in small-cap and healthcare stocks, led to attractive investment opportunities. The Fund maintained a cash position of approximately 13%. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, The Summers Value Fund highlighted Consensus Cloud Solutions, Inc. (NASDAQ:CCSI). Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) is a leading information delivery services provider through a software-as-a-service platform. On August 31, 2026, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) closed at $38.25 per share. Over the past month, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) declined 0.65%, but its shares are up 44.39% over the past year. Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) has a market capitalization of $700.93 million.
The Summers Value Fund stated the following regarding Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) in its Q2 2026 investor letter:
Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) - $695 million market cap. Consensus Cloud Solutions is a leading provider of cloud-based fax services to the healthcare sector under its well-recognized eFax brand. Faxing remains an important means of communication in the healthcare ecosystem with billions of pages sent each year. Faxing, while a legacy technology, allows industry participants to communicate in a HIPAA-compliant manner. Many hospitals and clinics still rely on physical fax machines while Consensus' cloud-based service feels more like sending an email.
Consensus was a busted spin-off from J2 Global when we started buying shares two years ago. The stock had declined from $65 to a low of $12 following missed expectations and an accounting restatement. At its low, the stock traded at 2.5x GAAP earnings. We began building our position at $16, or 3.5x GAAP earnings. Despite selling legacy technology into an industry in secular decline, the company had several attributes we found appealing: high margins, low customer churn, and strong free cash flow generation. After years of a declining share price, investor expectations and sell-side coverage were almost non-existent, which helped create the mispricing..." (Click here to read the full text)
#cloud #solutions #quarter
In its second-quarter 2026 investor letter, The Summers Value Fund highlighted Consensus Cloud Solutions, Inc. (NASDAQ:CCSI). Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) is a leading information delivery services provider through a software-as-a-service platform. On August 31, 2026, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) closed at $38.25 per share. Over the past month, Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) declined 0.65%, but its shares are up 44.39% over the past year. Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) has a market capitalization of $700.93 million.
The Summers Value Fund stated the following regarding Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) in its Q2 2026 investor letter:
Consensus Cloud Solutions, Inc. (NASDAQ:CCSI) - $695 million market cap. Consensus Cloud Solutions is a leading provider of cloud-based fax services to the healthcare sector under its well-recognized eFax brand. Faxing remains an important means of communication in the healthcare ecosystem with billions of pages sent each year. Faxing, while a legacy technology, allows industry participants to communicate in a HIPAA-compliant manner. Many hospitals and clinics still rely on physical fax machines while Consensus' cloud-based service feels more like sending an email.
Consensus was a busted spin-off from J2 Global when we started buying shares two years ago. The stock had declined from $65 to a low of $12 following missed expectations and an accounting restatement. At its low, the stock traded at 2.5x GAAP earnings. We began building our position at $16, or 3.5x GAAP earnings. Despite selling legacy technology into an industry in secular decline, the company had several attributes we found appealing: high margins, low customer churn, and strong free cash flow generation. After years of a declining share price, investor expectations and sell-side coverage were almost non-existent, which helped create the mispricing..." (Click here to read the full text)
#cloud #solutions #quarter

2 months ago
On August 28, Pinterest (NYSE:PINS) said that the Chief Financial Officer, Julia Donnelly, will leave the company on October 30, kicking off an external search for her replacement. Vikram Naidu, the company's vice president of finance and business operations, will serve as interim principal financial officer in the meantime. Donnelly is departing to join a private, early-stage company after roughly three years in the role, a stretch CEO Bill Ready credited with 11 consecutive quarters of double-digit revenue growth. The timing puts a spotlight on whether Pinterest can keep that momentum going without her.
The financial picture Donnelly leaves behind is a strong one. In the second quarter of 2026, Pinterest generated $1.18 billion in revenue, up 18% year over year and the fourth straight quarter above $1 billion. Global monthly active users climbed to 640 million, an 11% increase and the eleventh consecutive quarter of double-digit user growth, with Gen Z now making up more than half the platform's user base.
The United States and Canada region, Pinterest's most lucrative market, shows the acceleration most clearly. Revenue there grew 18%, a five-point jump from the prior quarter, helped by a restructured sales team and tighter account coverage for mid-market advertisers. Average revenue per user in that region rose 14% to $8.30. Management has also leaned hard into artificial intelligence, rolling its conversational Pinterest ****** istant out to most US users by the end of July and pointing to open-source models that run at less than 8% of the cost of comparable closed systems.
Profitability improved alongside growth. Adjusted EBITDA reached $311 million, a 26% margin that expanded 130 basis points from a year earlier, and free cash flow totaled $1.3 billion over the trailing twelve months. Pinterest used some of that cash to retire nearly 111 million shares this year, spending more than $2 billion on buybacks.
Donnelly's exit adds a layer of uncertainty to a company that just forecast a deceleration. Pinterest's own guidance calls for third-quarter revenue growth of 13% to 15%, down from 18% in the second quarter, a slowdown management attributes to the shift in when Prime Day fell, a smaller currency tailwind, and continued pressure from Asia-based cross-border retailers hit by regulatory actions in Europe. Competition from Meta's Instagram for digital advertising dollars is compounding the squeeze.
#revenue #year #company
The financial picture Donnelly leaves behind is a strong one. In the second quarter of 2026, Pinterest generated $1.18 billion in revenue, up 18% year over year and the fourth straight quarter above $1 billion. Global monthly active users climbed to 640 million, an 11% increase and the eleventh consecutive quarter of double-digit user growth, with Gen Z now making up more than half the platform's user base.
The United States and Canada region, Pinterest's most lucrative market, shows the acceleration most clearly. Revenue there grew 18%, a five-point jump from the prior quarter, helped by a restructured sales team and tighter account coverage for mid-market advertisers. Average revenue per user in that region rose 14% to $8.30. Management has also leaned hard into artificial intelligence, rolling its conversational Pinterest ****** istant out to most US users by the end of July and pointing to open-source models that run at less than 8% of the cost of comparable closed systems.
Profitability improved alongside growth. Adjusted EBITDA reached $311 million, a 26% margin that expanded 130 basis points from a year earlier, and free cash flow totaled $1.3 billion over the trailing twelve months. Pinterest used some of that cash to retire nearly 111 million shares this year, spending more than $2 billion on buybacks.
Donnelly's exit adds a layer of uncertainty to a company that just forecast a deceleration. Pinterest's own guidance calls for third-quarter revenue growth of 13% to 15%, down from 18% in the second quarter, a slowdown management attributes to the shift in when Prime Day fell, a smaller currency tailwind, and continued pressure from Asia-based cross-border retailers hit by regulatory actions in Europe. Competition from Meta's Instagram for digital advertising dollars is compounding the squeeze.
#revenue #year #company

2 months ago
21-year-old centre-back extends deal until 2031
Jeremiaha Maluze has agreed a contract extension at Eintracht Frankfurt. The 21-year-old is now in his second season on the Main and recently made his first-team debut for the Eagles in the DFB-Pokal first-round tie at SC St. Tönis.
Following spells in the youth set-ups at Rot-Weiß Oberhausen, KFC Uerdingen and MSV Duisburg, Maluze took his first steps in senior football during the 2023/24 campaign for SV Straelen and Mühlheimer FC, both in the Oberliga Niederrhein (fifth tier). That was followed by a year at Regionalliga Nordost (fourth tier) clubFC Rot-Weiß Erfurt, where he became a key player.
Maluze then signed a first-team contract with Eintracht in summer 2025 but was initially part of the U21 squad. He scored three goals and **** isted another 10 in 26 appearances in the Hessenliga (fifth tier) – nine of them in the second half of the campaign, playing a major role in the side's promotion to the Regionalliga. Maluze was regularly involved in the first team's preparations for this season and made his first competitive appearance in the cup last Friday, replacing captain Robin Koch midway through the second half.
"Jeremiaha has made great progress in recent months and shown that he's ready for the next step with his performances in the U21s," said sporting director Timmo Hardung. "He's quickly adapted to the higher level and made a good impression with the first team. He's willing to learn, works on himself in a very focused way and as such, he has the attributes to continue on his path in professional football. We're pleased to have tied him to Eintracht Frankfurt for the long term."
#first #made
Jeremiaha Maluze has agreed a contract extension at Eintracht Frankfurt. The 21-year-old is now in his second season on the Main and recently made his first-team debut for the Eagles in the DFB-Pokal first-round tie at SC St. Tönis.
Following spells in the youth set-ups at Rot-Weiß Oberhausen, KFC Uerdingen and MSV Duisburg, Maluze took his first steps in senior football during the 2023/24 campaign for SV Straelen and Mühlheimer FC, both in the Oberliga Niederrhein (fifth tier). That was followed by a year at Regionalliga Nordost (fourth tier) clubFC Rot-Weiß Erfurt, where he became a key player.
Maluze then signed a first-team contract with Eintracht in summer 2025 but was initially part of the U21 squad. He scored three goals and **** isted another 10 in 26 appearances in the Hessenliga (fifth tier) – nine of them in the second half of the campaign, playing a major role in the side's promotion to the Regionalliga. Maluze was regularly involved in the first team's preparations for this season and made his first competitive appearance in the cup last Friday, replacing captain Robin Koch midway through the second half.
"Jeremiaha has made great progress in recent months and shown that he's ready for the next step with his performances in the U21s," said sporting director Timmo Hardung. "He's quickly adapted to the higher level and made a good impression with the first team. He's willing to learn, works on himself in a very focused way and as such, he has the attributes to continue on his path in professional football. We're pleased to have tied him to Eintracht Frankfurt for the long term."
#first #made
2 months ago
Brentford boss Keith Andrews has been speaking to the media before Sunday's Premier League game against Leeds United at Elland Road (kick-off 14:00 BST).
Here are the key lines from his news conference:
Andrews said there are no injuries to his squad and the team "came through midweek really well".
New defender El Hadji Malick Diouf is a "very good player". Andrews said: "I thought he had some eye-catching performances [last season at West Ham]. He fits what we are about, age profile, attributes and he comes into it in an already competitive squad."
On 25-year-old Keane Lewis-Potter: "He is versatile, it is a super strength. Before we signed Malick I said we could play Keano in different positions throughout the season. I don't think that will change."
#squad #leeds
Here are the key lines from his news conference:
Andrews said there are no injuries to his squad and the team "came through midweek really well".
New defender El Hadji Malick Diouf is a "very good player". Andrews said: "I thought he had some eye-catching performances [last season at West Ham]. He fits what we are about, age profile, attributes and he comes into it in an already competitive squad."
On 25-year-old Keane Lewis-Potter: "He is versatile, it is a super strength. Before we signed Malick I said we could play Keano in different positions throughout the season. I don't think that will change."
#squad #leeds