

20 days ago
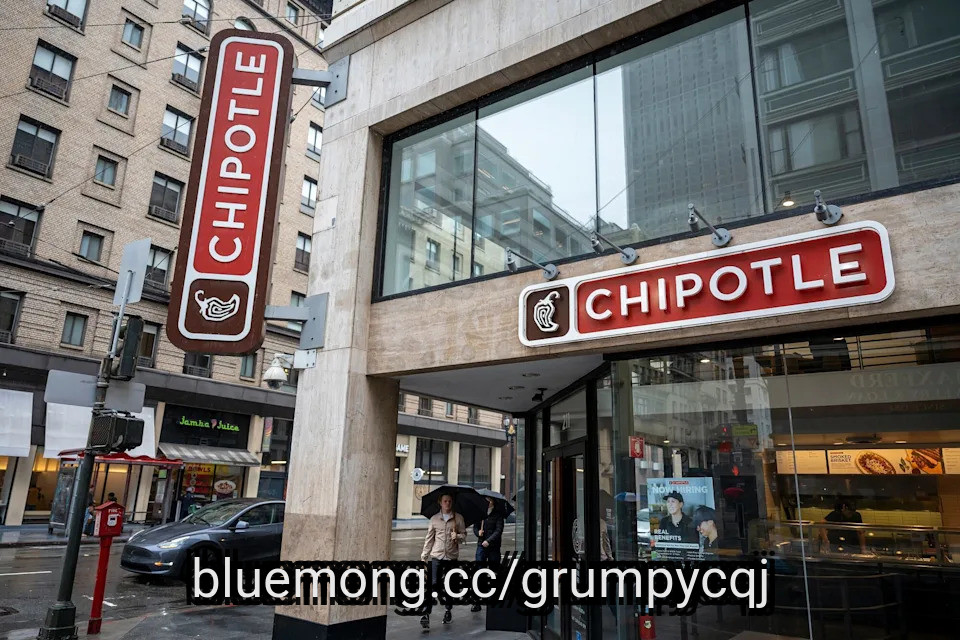
(Bloomberg) -- Chipotle Mexican Grill Inc. (CMG) shares jumped after the Financial Times reported that Starbucks Corp. has worked with advisers in recent months on a takeover proposal for the burrito chain.
Most Read from Bloomberg
UPS Worker Missed Email, Letting China Get F-35 Parts
Apple to Launch Doorbell, Lock, Thermostat Developed With LG
Dalio Says We're Nearing Point Where AI Bubble May Burst
#missed
Most Read from Bloomberg
UPS Worker Missed Email, Letting China Get F-35 Parts
Apple to Launch Doorbell, Lock, Thermostat Developed With LG
Dalio Says We're Nearing Point Where AI Bubble May Burst
#missed

20 days ago
Investing.com -- Shares of Chipotle Mexican Grill (NYSE: CMG) and Starbucks (NASDAQ: SBUX) swung sharply Thursday following a Financial Times report that Starbucks has explored a potential acquisition of the burrito chain.
Before you buy NVIDIA: our AI model's stock picks are beating the market by 120%+. See the list now »
Chipotle shares initially jumped as much as 8% following the report, while Starbucks fell as much as 6%. Both stocks later pared those moves as investors weighed the potential implications of a deal.
Whispers of a potential tie-up had circulated previously, including a report from Semafor, but the speculation was largely dismissed by the market at the time. The Financial Times report carries greater weight, indicating that Starbucks has worked with advisers in recent months on a potential proposal for Chipotle, which currently has a market value of nearly $39 billion.
The sharp divergence in the stocks, however, could complicate the financial mechanics of a potential transaction. Starbucks' declining share price would reduce the value of any equity used as consideration, while Chipotle's rally increases the price Starbucks would need to pay for the company. The status of Starbucks' plans, including whether it has made a formal offer, remains unclear.
#starbucks #market #shares


24 days ago
Updated on: October 4, 2026 / 8:06 PM EDT / CBS News
As Sen. Thom Tillis exits the Senate, he's blasting many of the advisers President Trump has surrounded himself with as "sycophants, and calling on his colleagues to stand up to executive power like the co-equal branch of government they are."
The 66-year-old senior senator from North Carolina unloads on what he calls the "WTF moments" of the second Trump Administration in a new book, "How to Lose Friends and Antagonize Presidents." Having served in the Senate during the Barack Obama, Joe Biden and both Trump presidencies, Tillis said he's increasingly worried about how the nation's system of checks and balances is being tested by the outsized influence of the executive branch.
"We will have a sort of dictator king if we're not careful," he said.
Every recent White House has been eager to govern by executive order, something that's been especially true during the current Trump administration, Tillis said. Presidents, he said, fail to understand that Congress is a coequal branch that should be treated as a peer, and that Congress needs to act as such.
#tillis #congress #updated #october



1 month ago
Former President Obama on Friday slammed President Trump over his handling of how to approach artificial intelligence amid “doomsday” warnings coming from some in the tech industry about the technology’s potential existential threat to humanity.
Obama said during an interview at Colgate University in New York that the federal government must regulate AI, before referring to comments made by one Trump adviser.
“I heard one of Donald Trump’s main advisers on this make the argument that, ‘The market will take care of AI,'” the former president said. “‘These companies will solve the safety issues because they have every incentive to do so — if it turns out to be dangerous, people will just sue them, and they’re worried about financial liability.'”
“That’s not how we treat airlines,” Obama added. “Or drug companies, or food companies.”
Obama continued to say that AI could become a threat at a human level if it falls into the clutches of “bad humans” and if self-improving AI models realize they no longer need humans. He referred to Trump again in that his successor has said regulations on AI are “for losers.”
#obama #president #university


1 month ago
On September 8, 2026, Reuters reported that NIKE, Inc. (NYSE:NKE) shareholders rejected a proposal urging greater transparency on how the company plans to meet its 2030 emissions-reduction targets, despite support from Norway's sovereign wealth fund, Nike's 11th-largest shareholder.
Nike's board had urged a "no" vote, arguing management is "best positioned to determine the targets and related disclosures that are appropriate." Shareholders separately approved the company's executive compensation proposal, including pay for CEO Elliott Hill, in a vote that had faced some opposition.
The failed climate proposal gives NIKE, Inc. (NYSE:NKE)'s management more flexibility to focus on its operational turnaround. Shareholders rejected the request for greater disclosure on how Nike plans to meet its 2030 emissions targets. It allows CEO Elliott Hill and his team to prioritize product innovation, sales recovery, and market-share gains. Nike faces significant operational challenges. So management could benefit from directing more resources toward restoring growth and profitability.
Nike has already made measurable progress toward its environmental targets. It limits the immediate financial impact of the rejected proposal. The company reported an 11% reduction in supply-chain emissions from its 2015 baseline in fiscal 2024, while its 2030 targets call for a 65% reduction in operational emissions and a 30% reduction across its supply chain. This progress gives Nike evidence that it is chasing its climate goals even without expanding its current disclosure.
Shareholders' approval of Elliott Hill's compensation package shows support for Nike's leadership despite the difficult turnaround. Investors approved more than $36 million in total compensation for Hill for fiscal 2026, even though Norway's wealth fund and major proxy advisers opposed the package. Shareholder support gives Hill greater room to execute his strategy as Nike works to stabilize sales, rebuild its market position, and restore long-term earnings growth.
#reduction #elliott #greater


1 month ago
The Federal Reserve's interest rate hike — the first in three years — is a policy shift that will have a domino effect for retirees.
Those in retirement and those nearing retirement need to factor interest rates into their investment decisions. To explain what the Fed hike might mean, Yahoo Finance talked to several wealth management advisers and finance professionals.
First off, it's important to keep in mind that one quarter-point rate hike won't drastically alter anyone's fortunes.
"A single rate hike rarely helps or hurts a retiree outright," said Michael Cochran, chief investment officer at BentOak Capital in Fort Worth, Texas. "It reshuffles the deck where there are benefits, but also some pressures."
A rate hike could be good news because it means that savings yields will likely rise, said LendingTree chief consumer finance **** yst Matt Schulz.
#first #Retirement #chief #michael

1 month ago
The White House said Tuesday that banning yield on stablecoins would do little to increase bank lending, pushing back against estimates that stablecoin rewards could result in large amounts of deposits leaving the traditional banking system.
In an update to an April ****** ysis by the Council of Economic Advisers (CEA), the White House said eliminating stablecoin yield would increase bank lending by about $2.1 billion under its baseline ****** umptions. That represents just 0.02% of outstanding bank loans.
Community banks would account for roughly $500 million of the additional lending, or about 0.03% of their loan books, according to the ****** ysis.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#yield #increase #tuesday


2 months ago
Private equity advisers are racing to leverage AI and automate the services they provide to fund managers and their investors. Law firms, such as Kirkland & Ellis, have been among the most active adopters.
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private


2 months ago
Leading U.S. medical groups are urging people to get updated flu and COVID-19 vaccinations this fall, banding together Wednesday to issue shot guidelines — and highlight the science behind them — saying they hope to ease confusion caused by the Trump administration's changing advice.
Flu vaccinations are beginning and COVID-19 shots are starting to arrive after the Food and Drug Administration approved this year's updated versions last week. Winter also brings another vaccine-preventable risk called RSV. Exactly who should get one or all of these vaccines, and when?
That advice usually comes from the Centers for Disease Control and Prevention, with help from its independent advisers. But despite no new scientific evidence, Trump health officials last year began pulling back on some longstanding recommendations for fall virus protection and routine children's vaccinations. And that advisory panel, which influences state and insurance vaccine policies, is caught in a court battle. The CDC didn't respond to questions about any new fall guidance but suggested on its website that doctors follow last year's flu recommendations.
Doctors' groups are filling the gap: the American Academy of Pediatrics, American Academy of Family Physicians, American College of Obstetricians and Gynecologists, and the Infectious Diseases Society of America each released vaccination guidelines for their patient populations.
"There's been a lot of confusion and chaos regarding vaccine recommendations," said Dr. Sandra Fryhofer, of the American Medical **** ociation.
#vaccinations #medical

2 months ago
On August 27, CIBC (NYSE:CM) reported third-quarter results that pushed adjusted earnings per share to $2.73, up 26% from a year earlier and marking the ninth consecutive quarter of double-digit EPS growth. Adjusted net income climbed to $2,648 million on revenue of $8,368 million, up 15% year over year, and return on equity reached 16.8%, up 260 basis points from the same quarter last year. The headline numbers describe a bank firing on multiple cylinders at once, even as management flagged pockets of strain underneath.
Capital Markets net income grew 34% year over year to $722 million, powered by equity trading and financing activity. Canadian Personal and Business Banking delivered $948 million in net income, up 17% from a year ago, while net interest margin climbed to 304 basis points, up 3 basis points sequentially on higher loan and deposit margins. In the US segment, net income rose 23% to $320 million, helped by lower provisions for loan losses and a revenue increase, even as net interest margin slipped 14 basis points sequentially to 3.76%. CIBC's efficiency ratio tightened by 200 basis points from a year earlier, the 12th straight quarter the bank has generated positive operating leverage, a sign revenue is outrunning costs rather than expenses eating into the gains.
Wealth Management showed similar strength, with ******* ets under administration and ******* ets under management both up more than 20% year over year and credit fees rising 25% on strong corporate lending and financing activity. Investor's Edge, the bank's self-directed investing platform, posted 34% growth in new account openings, and the managed mass affluent client base grew 4%, supporting a 12% increase in money-in balances. CIBC also returned capital to shareholders through 7.5 million shares repurchased during the quarter, and CEO Harry Culham pointed to the newly launched CIBC AI 2.0 agentic workspace and the CIBC AdvisorAssist platform, which he said cuts advisers' administrative documentation time by up to 50%.
Not every line moved in CIBC's favor. The Common Equity Tier 1 ratio slipped 19 basis points sequentially to 13.4%, as organic capital generation was offset by share buybacks and a $269 million charge, $232 million after tax, related to CIBC's planned sale of its Caribbean banking unit, CIBC Caribbean Bank Limited. Provisions on impaired loans climbed $64 million sequentially to $612 million, which CIBC linked to a handful of one-off credit issues inside its Canadian Commercial Banking and Capital Markets books rather than any broader deterioration. Total deposits fell 1% year over year, and GIC balances dropped 10% as clients shifted funds into higher-margin managed mutual fund products.
#income #banking


2 months ago
At this point more than two months before the midterm elections, Democrats retaking control of Congress and its subpoena power is far from certain. But President Donald Trump is already laying down legal markers for how he'll fight any attempt by lawmakers to investigate him.
In a Justice Department memo and legal filings, the Trump administration is arguing that the president can keep secret not just the conversations he has with his advisers within the White House, but that his dealings with individuals outside the government can be shielded as well. The White House is also saying in court that even disclosing the identities of the people who worked on significant policy efforts would infringe upon the presidential confidentiality to which Trump is entitled. And the administration has taken the stance that it can ignore a Watergate-era law prohibiting the destruction of White House documents.
The posturing comes as Trump, in his second term, has been notably reliant on a constellation of business moguls, non-government attorneys and old friends to help shape his agenda.
"There has been an unprecedented amount of interaction between the Executive Branch — particularly the White House — and the private sector that Congress has made clear is going to be the subject of oversight," said Jamie Bair, a partner and head of congressional investigations at the law firm Crowell & Moring.
Congressional Democrats are already probing the administration's interactions with FIFA, how Trump's ties to the crypto-industry are affecting federal policy, and other examples of Trump family business maneuverings that Democrats say can be tied to government policies.
#congressional

2 months ago
Two US-based holders of Aston Martin bonds have asked a New York court to authorise evidence-gathering ahead of a UK legal claim against the carmaker's debt restructuring.
According to Bloomberg, Arini Capital Management and Tresidor Investment Management lodged the application with the Southern District of New York.
The filing asks the court to compel BlackRock-owned HPS Investment Partners, the UK arm of Authentic Brands Group, and advisers Moelis & Co and Lazard to produce documents and give testimony.
Pallas Partners, representing the bondholders, plans to use the evidence in a UK claim now being drafted against the deal.
At issue is the arrangement between Aston Martin, HPS and Authentic Brands that raised £450m in debt – an arrangement the bondholders say left existing creditors worse off.
#aston #martin #management #authentic

2 months ago
Vanguard Group agreed to acquire Altruist, a wealth technology and custody platform serving independent financial advisers, the companies announced Wednesday. The transaction is worth around $4 billion, according to The Wall Street Journal.
Altruist's platform combines a self-clearing brokerage with tools covering account opening, trading, portfolio management, billing, and reporting for independent wealth-management firms. The company competes with Charles Schwab and Fidelity Investments in providing custodial and administrative services to independent financial advisers, according to the Wall Street Journal.
Following the close of the deal, Altruist is expected to operate as a standalone business, retaining its leadership, brand, and distinct operating model, the companies said. The transaction is subject to customary closing conditions, including regulatory approvals, and is expected to close later this year. Financial terms were not disclosed by the companies.
Vanguard first invested in Altruist in 2020, according to the company. The acquisition advances Vanguard chief executive officer Salim Ramji's broader effort to diversify the firm's revenue streams beyond its low-fee index funds by building out a financial advice business. Vanguard itself plans to become an anchor client for parts of the Altruist platform.
"Altruist's mission to make financial advice more accessible, more affordable, and help advisers scale their practices, that very much rhymes with what we're trying to do here at Vanguard," Ramji said. "That's really how this acquisition was born."
#platform #advisers #Companies

2 months ago
T. Rowe Price Group, Inc. (NASDAQ:TROW) is making a bigger move into fixed-income ETFs through its agreement to acquire F/m Investments, a fixed-income **** et manager with about $19 billion in **** ets. The deal would add 20 ETFs covering Treasuries, TIPS, corporate bonds and municipal securities. It would also increase T. Rowe Price's fixed-income **** ets by nearly 9% and more than double its fixed-income ETF **** ets from around $6.5 billion.
The deal comes as ETFs become a more important part of the **** et-management industry. T. Rowe Price Group, Inc. (NASDAQ:TROW) has traditionally been better known for active investing, so F/m gives it an established ETF platform and a team with experience developing fixed-income products. The transaction is expected to close in early 2027, although T. Rowe Price has not disclosed how much it will pay for F/m.
Photo by Scott Graham on Unsplash
The biggest positive for T. Rowe Price Group, Inc. (NASDAQ:TROW) is that it is getting an established fixed-income ETF business rather than having to build one from scratch. The company already manages about $220 billion in fixed income, so F/m fits naturally into a business T. Rowe Price already knows well.
Distribution could be another major opportunity. F/m has built a portfolio of ETFs, but T. Rowe has a much larger network and deeper relationships with financial advisers, institutions and other investors. If the company can put F/m's products in front of more customers, the $19 billion **** et base could have room to grow. F/m also brings experience in developing new ETF structures and products. T. Rowe Price, meanwhile, has the scale and resources of a much larger **** et manager. Bringing those strengths together could help expand its fixed-income ETF offering as more investors turn to ETFs for bond exposure.
#income #group #trow
2 months ago
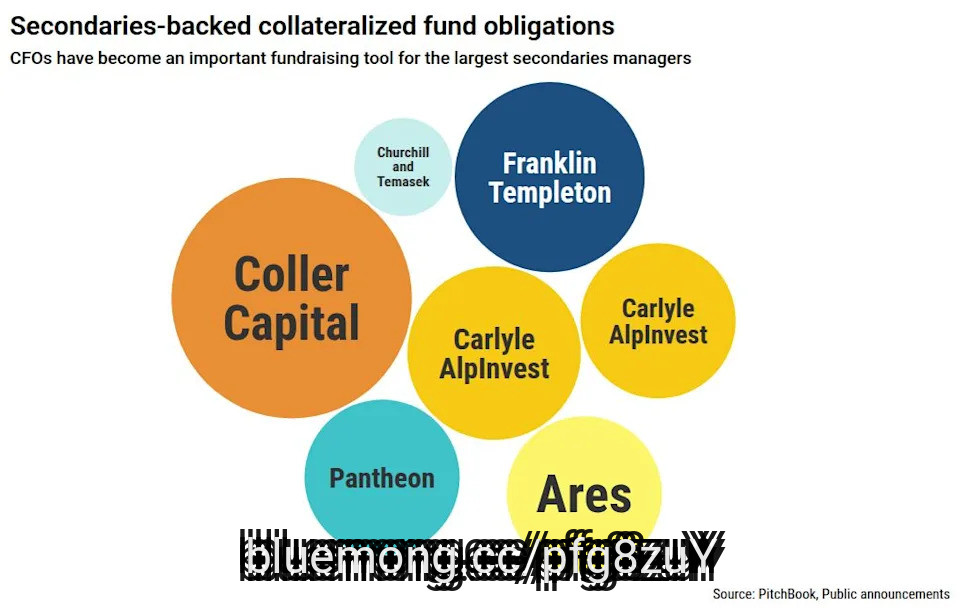
Collateralized fund obligations have quietly become an important fundraising tool for some of the largest managers of secondaries funds.
Last week, Franklin Templeton got in on the act by raising a $1.5 billion CFO, allowing the ****** et manager to issue tranches of rated debt secured against cash flows generated by a pool of private ****** ets it manages.
Structured Solutions 2026, as the CFO is known, gives investors, including registered investment advisers, family offices and insurance companies, exposure to the returns of a diversified portfolio of private equity fund stakes and continuation funds managed by Franklin Templeton's secondary-investing affiliate, Lexington Partners.
A portfolio of US middle-market loans managed by Benefit Street Partners, a direct-lending subsidiary of the $1.8 trillion ****** et manager, is also included in the CFO, according to a statement.
Franklin Templeton did not respond to further questions.
#private #Portfolio

2 months ago
(Bloomberg) -- JPMorgan Chase & Co. and Morgan Stanley are among banks shareholders are suing over their roles on multibillion-dollar buyout deals after a recent corporate-law overhaul failed to protect financial advisers from potential liability.
Most Read from Bloomberg
Canada Sees Long Trade War With US That May Last Beyond Midterms
Canadians Brace for Economic Pain as 50% US Tariffs Take Effect
Bessent Has No Easy Fix for What's Really Driving Yields Up
#chase #canada
Most Read from Bloomberg
Canada Sees Long Trade War With US That May Last Beyond Midterms
Canadians Brace for Economic Pain as 50% US Tariffs Take Effect
Bessent Has No Easy Fix for What's Really Driving Yields Up
#chase #canada

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Linde plc (NASDAQ:LIN) as a new holding. Linde plc (NASDAQ:LIN) operates as the world's leading industrial gas company. On August 21, 2026, Linde plc (NASDAQ:LIN) closed at $487.57 per share. The one-month return of Linde plc (NASDAQ:LIN) was -3.84%, and its shares gained 2.03% over the past 52 weeks. Linde plc (NASDAQ:LIN) has a market capitalization of $224.76 billion.
SGA Global Growth Strategy stated the following regarding Linde plc (NASDAQ:LIN) in its Q2 2026 investor letter:
"Linde plc (NASDAQ:LIN), the world's largest industrial gas company, was added to the portfolio in April. We had previously exited the position in 2024 due to valuation considerations and forced attrition; since then, the stock price has consolidated while fundamentals continued to progress. Linde remains an attractive long-term investment, supported by a highly durable business model and meaningful structural advantages. A large share of revenue is generated from long-term, recurring customer contracts in essential end markets, providing strong pricing power and cash flow visibility even in a slower growth environment. The company's strengths are rooted in its production efficiency and broad exposure across diverse end markets, including healthcare, manufacturing, electronics, chemicals, and energy.
Looking ahead, Linde is well-positioned to benefit from structural improvements and a potential acceleration in global growth across several of its core markets over the medium term. The U.S., which accounts for roughly 45% of revenue, is likely to see improved growth driven by an industrial recovery, increased semiconductor manufacturing, and higher refinery utilization. Europe (approximately 25% of revenue) has been a headwind in recent years due to negative volume growth, but is expected to stabilize over the medium term, with the potential for mo

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted ServiceNow, Inc. (NYSE:NOW). ServiceNow, Inc. (NYSE:NOW) is a cloud-based software company that provides a platform for automating and managing digital workflows. On August 21, 2026, ServiceNow, Inc. (NYSE:NOW) closed at $128.48 per share. The one-month return of ServiceNow, Inc. (NYSE:NOW) was 21.64%, and its shares lost 27.04% over the past 52 weeks. ServiceNow, Inc. (NYSE:NOW) has a market capitalization of $132.85 billion.
SGA Global Growth Strategy stated the following regarding ServiceNow, Inc. (NYSE:NOW) in its Q2 2026 investor letter:
"As part of our ongoing dialogue with ServiceNow, Inc. (NYSE:NOW), we met with President and Chief Legal Officer Hossein Nowbar and members of the company's legal, compensation and, human resources teams. A significant portion of the discussion focused on the company's recent acquisition activity and the importance of maintaining transparency with shareholders regarding strategic decision-making. Management disagreed with our characterization that its acquisition strategy had become more aggressive, describing the recent transactions as an unusual convergence of several deals rather than a fundamental change in approach. We emphasized that, regardless of management's intent, the lack of timely communication surrounding these transactions contributed to investor uncertainty and undermined shareholder confidence. We encouraged the company to provide clearer and more proactive disclosure around significant strategic decisions to help investors develop a better understanding of the rationale and risks ***** ociated with future acquisitions....." (Click here to read the full text)
#holdings
2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Arm Holdings plc (NASDAQ:ARM) as a leading contributor. Arm Holdings plc (NASDAQ:ARM) is a UK-based technology company that develops and licenses central processing unit designs and related technologies for semiconductor companies and original equipment manufacturers. On August 21, 2026, Arm Holdings plc (NASDAQ:ARM) closed at $243.32 per share. The one-month return of Arm Holdings plc (NASDAQ:ARM) was -8.64%, and its shares gained 76.60% over the past 52 weeks. Arm Holdings plc (NASDAQ:ARM) has a market capitalization of $259.87 billion.
SGA Global Growth Strategy stated the following regarding Arm Holdings plc (NASDAQ:ARM) in its Q2 2026 investor letter:
"Arm Holdings plc (NASDAQ:ARM), leading designer and licensor of CPU architectures and related subsystems, was a top contributor to performance again this quarter. The company delivered solid quarterly results, including 20% revenue growth and 12% profit growth, with continued strength in licensing activity and sustained royalty expansion despite a tougher comparison period. Management guidance reinforced confidence in maintaining roughly 20% revenue growth, supported by increasing demand for Arm-based CPUs and expanding adoption across data center and AI workloads, which helped offset expected weakness in handset markets. Confidence was further supported by evidence of strong CPU demand, improving share gains versus x86 architectures, and growing customer traction, including an expanding roster of signed partners and management's confidence in achieving long-term revenue targets. With strong pricing power, highly recurring revenues, and expanding royalty rates as Arm captures more value across the compute stack, we continue to view the company as a high-quality, long-term compounder well-positioned to benefit from the proliferation of AI and power efficient computing. We


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Alcon Inc. (NYSE:ALC). Alcon Inc. (NYSE:ALC) is a Swiss-based healthcare and medical technology company focused on eye care products. On August 21, 2026, Alcon Inc. (NYSE:ALC) closed at $73.63 per share. The one-month return of Alcon Inc. (NYSE:ALC) was 9.44% and its shares lost 8.83% over the past 52 weeks. Alcon Inc. (NYSE:ALC) has a market capitalization of $36.68 billion.
SGA Global Growth Strategy stated the following regarding Alcon Inc. (NYSE:ALC) in its Q2 2026 investor letter:
"During the quarter, we exited our position in Alcon Inc. (NYSE:ALC). Alcon remains a leader in eye care with exposure to increasing secular demand driven by aging and myopia, with market leadership across multiple categories. Strong launches in new equipment and eye drops drove topline growth of 6% constant currency and earnings per share growth of 16%+ in Q1. This was slightly below expectations of 7% growth, as the market for cataracts and contact lenses remains subdued. Additionally, the premium intraocular lens for cataracts is getting more competitive, with Alcon remaining the leader but expected to continue to cede share from the highs of 80%+ as competitors are catching up. Management continues to execute well on product launches to offset pressures in intraocular lens, which accounts for 17% of total sales. However, to account for the increased competition and subdued market conditions overall, we gradually reduced the position before ultimately redeploying the capital into a higher growth opportunity in Schneider Electric."
#strategy
2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy added Equinix, Inc. (NASDAQ:EQIX) to its portfolio. Equinix, Inc. (NASDAQ:EQIX) is a leading digital infrastructure company that operates a global network of data centers and interconnected ecosystems, enabling seamless delivery of digital experiences and cutting-edge AI quickly and efficiently. On August 21, 2026, Equinix, Inc. (NASDAQ:EQIX) closed at $1,065.39 per share. The one-month return of Equinix, Inc. (NASDAQ:EQIX) was 1.78% and its shares gained 36.17% over the past 52 weeks. Equinix, Inc. (NASDAQ:EQIX) has a market capitalization of $105.12 billion.
SGA Global Growth Strategy stated the following regarding Equinix, Inc. (NASDAQ:EQIX) in its Q2 2026 investor letter:
"A position in Equinix, a leading global data center provider, was initiated during the quarter. The company sells ******* e, power, and connectivity services across a global footprint, binding strategic clients to its facilities through interconnection and coplacement for low-latency and high-bandwidth services. Equinix is a familiar name for SGA, having been a portfolio holding for ten years before being sold in 2024 as the growth rate had slowed and management was in the midst of a leadership transition. Both dynamics have since reversed, with growth re-accelerating as AI inferencing ramps and power demand remains high, and with new leaders now announced and in place." (Click here to read the full text)
#Growth #eqix #letter

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Salesforce, Inc. (NYSE:CRM). Salesforce, Inc. (NYSE:CRM) is a cloud computing company that offers Customer Relationship Management (CRM) technology that brings companies and customers together. On August 21, 2026, Salesforce, Inc. (NYSE:CRM) closed at $209.17 per share. The one-month return of Salesforce, Inc. (NYSE:CRM) is 21.95%, while its shares lost 14.59% over the past 52 weeks. Salesforce, Inc. (NYSE:CRM) has a market capitalization of $171.31 billion.
SGA Global Growth Strategy stated the following regarding Salesforce, Inc. (NYSE:CRM) in its Q2 2026 investor letter:
"Salesforce was a detractor from performance during the quarter as investor sentiment remained cautious following another quarter that merely met its guidance targets. Current remaining performance obligations (cRPO) growth were in line at roughly 9% rather than the historical pattern of beating by about a point, and the forward quarter guide was modest. Management acknowledged continued weakness in Marketing, Commerce, and Tableau (roughly 20% of revenue), partially offset by strength in Sales Cloud, Service Cloud, Slack, and Data Cloud (roughly 75% to 80% of revenue), with Sales and Service Cloud each posting seat growth in the quarter. Additionally, Agentforce annualized recurring revenue reached $1.2 billion, growing 205%. Management reiterated full-year guidance and a second-half reacceleration based on bookings strength and lower attrition, alongside a long-term double-digit organic growth target through CY29 with about 100 basis points of annual margin expansion. Despite concerns around AI‑driven competition, we believe Salesforce's integration into customer business processes, large installed base, and wide product set position it well to compete effectively in the Agentic AI era, supporting low-teens earnings growth over the next three years. We


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) as a top contributor to the performance. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's leading contract chip manufacturer, producing advanced semiconductors for major global technology companies. On August 21, 2026, Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) closed at $418.95 per share. The one-month return of Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) was 2.34%, and its shares gained 73.37% over the past 52 weeks. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) has a market capitalization of $1.9 trillion with a 52-week trading range between $223.70 - $479.00.
SGA Global Growth Strategy stated the following regarding Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) in its Q2 2026 investor letter:
"Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM), the world's leading semiconductor foundry, was a top contributor to performance during the quarter. Shares were supported by sustained strength in demand for advanced logic and compute, with customers across AI accelerators and CPUs continuing to require additional capacity. TSMC remains firmly positioned at the leading edge of semiconductor manufacturing, benefiting from secular demand across high performance computing, smartphones, automotive, and AI applications. Its technology leadership and scale support sustained double digit growth, with revenue increasingly driven by recurring and repeatable categories that reduce cyclicality. Given TSMC's dominant competitive position, deep customer entrenchment, and the continued global need for advanced compute, TSMC remains well-positioned to deliver strong double-digit revenue and earnings growth over the coming years. We maintained an above average weight position du


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Netflix, Inc. (NASDAQ:NFLX). Netflix, Inc. (NASDAQ:NFLX), a leading subscription-based streaming entertainment platform, detracted from performance during the quarter. On August 21, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $79.59 per share, reflecting a market capitalization of $331.41 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of 13.05%, while its shares lost 34.66% over the past 52 weeks.
SGA Global Growth Strategy stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX) was a detractor from returns during the quarter after the stock came under pressure despite reporting solid first quarter results in April. Revenue grew 16% year-over-year, or 14% excluding FX, and operating income rose 18%, supported by strong growth in APAC and Latin America. Second quarter revenue guidance came in roughly 1% below expectations and EBIT guidance was 5% light due to content amortization timing. Management maintained full-year guidance of 11% to 13% revenue growth (excluding FX) and approximately 20% profit growth rather than raising it, which disappointed some investors who had anticipated a lift following the recent price hike and the removal of the Warner Bros. Discovery deal overhang. With the Warner Bros. Discovery acquisition now behind it, management can refocus on the core business and deploy excess free cash flow toward AI investment and buybacks, including a new $25 billion authorization. The company continues to expand its mobile and content initiatives, while evaluating longer-term opportunities in advertising and AI-driven production tools. Over the long term, Netflix benefits from a recurring subscription model with low churn and demonstrated pricing power, supported by a broad and growing content library and meaningful global growth opportu

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Intuit Inc. (NASDAQ:INTU). Intuit Inc. (NASDAQ:INTU) provides financial management, payments and capital, compliance, and marketing products and services. On August 21, 2026, Intuit Inc. (NASDAQ:INTU) closed at $367.00 per share. The one-month return of Intuit Inc. (NASDAQ:INTU) was 20.76%, and its shares lost 44.14% over the past 52 weeks. Intuit Inc. (NASDAQ:INTU) has a market capitalization of $100.4 billion.
SGA Global Growth Strategy stated the following regarding Intuit Inc. (NASDAQ:INTU) in its Q2 2026 investor letter:
"We liquidated our position in Intuit Inc. (NASDAQ:INTU) during the quarter. Following the company's fiscal third quarter results, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. As a result, we exited the position and reallocated the capital to a new position in Arista Networks.
Intuit was a detractor from performance during the quarter. The company reported fiscal third quarter results that included a modest revenue beat and a full-year guidance increase, though results were overshadowed by weaker than expected Consumer Tax performance. TurboTax revenue grew 7%, below guidance, with notable weakness in the DIY segment. Management cited pressure among lower income, price sensitive filers and a contraction in total IRS filers of roughly 30 basis points. Despite double-digit revenue growth and ongoing margin expansion above 40%, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. Given these factors, we chose to exit the position and


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Alphabet Inc. (NASDAQ:GOOG) as a leading performance contributor. Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On August 21, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.75 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of 4.65%, while its shares gained 63.39% over the past 52 weeks.
SGA Global Growth Strategy stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was a contributor to performance during the quarter supported by the continued narrative that the company is a well-positioned beneficiary of the AI investment cycle. Its full‑stack exposure spans infrastructure, foundational models, developer tools, and scaled consumer applications, providing broad participation in AI adoption. The stock benefited from the company's Q1 report which highlighted robust ongoing demand for the company's AI compute resources. We continue to view Alphabet as a high-quality, long-term compounder. Its leading global platforms, supported by strong network effects, direct user relationships, and scaled infrastructure, underpin durable pricing power and highly recurring revenue streams. The company remains well-positioned to benefit from sustained growth drivers, including the ongoing shift toward digital advertising and cloud computing, while its continued investment in AI and innovation supports its ability to reinforce its competitive position over time. We raised the position target, maintaining an above-average weight."
#alphabet #strategy #investment


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Canadian Pacific Kansas City Limited (NYSE:CP). Canadian Pacific Kansas City Limited (NYSE:CP) owns and operates a transcontinental freight railway in Canada and internationally. On August 24, 2026, Canadian Pacific Kansas City Limited (NYSE:CP) closed at $94.68 per share. The one-month return of Canadian Pacific Kansas City Limited (NYSE:CP) was 3.25%, and its shares gained 24.17% over the past 52 weeks. Canadian Pacific Kansas City Limited (NYSE:CP) has a market capitalization of $83.25 billion.
SGA Global Growth Strategy stated the following regarding Canadian Pacific Kansas City Limited (NYSE:CP) in its Q2 2026 investor letter:
"We engaged with management of Canadian Pacific Kansas City Limited (NYSE:CP) in advance of the company's annual meeting to discuss its climate strategy and a proposal on climate-related disclosures. A key topic of discussion was the company's decision to defer establishing a Science Based Targets initiative (SBTi)-validated 1.5°C-aligned emissions reduction target. While the ISS Sustainability policy recommended voting against the climate proposal due to the absence of intermediate and long-term emissions targets, management explained that the delay stemmed from the lack of a finalized intensity-based methodology from SBTi appropriate for the freight rail industry, emphasizing that CPKC remains committed to its existing goal of reducing locomotive well-to-wheel emissions intensity by 36.9% by 2030 and continues to work with SBTi as industryspecific frameworks evolve. Management highlighted continued spending on locomotive fleet modernization, including investment in new Tier 4 locomotives, expansion of its hydrogen locomotive program, and trials of renewable fuels. After reviewing the company's disclosures, proxy materials, and feedback from management, we concluded that the company is making goo

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Yum! Brands, Inc. (NYSE:YUM). Yum! Brands, Inc. (NYSE:YUM) develops, operates, and franchises traditional and non-traditional quick service restaurants in the United States and internationally. On August 24, 2026, Yum! Brands, Inc. (NYSE:YUM) closed at $157.35 per share. The one-month return of Yum! Brands, Inc. (NYSE:YUM) was 4.4%, and its shares gained 6.7% over the past 52 weeks. Yum! Brands, Inc. (NYSE:YUM) has a market capitalization of $42.84 billion.
SGA Global Growth Strategy stated the following regarding Yum! Brands, Inc. (NYSE:YUM) in its Q2 2026 investor letter:
"We met with Jon Hixon, Yum! Brands, Inc.'s (NYSE:YUM) Chief Sustainability Officer, as well as members of legal and human resources teams to discuss several topics relevant to our investment thesis, including human capital management, geopolitical and reputational risks, corporate governance, and sustainability reporting. During the discussion, we were pleased to hear that Yum's next sustainability report would include, for the first time, disclosures aligned with the Taskforce on Nature-related Financial Disclosures (TNFD) framework, alongside its existing climate-related reporting. The addition of TNFD reporting reflects the company's ongoing efforts to ******* s and disclose nature-related dependencies, impacts, risks, and opportunities across its agricultural supply chain. A key focus of the engagement was Pizza Hut's ongoing strategic review and the ******* ociated human capital implications. Management outlined several retention initiatives designed to support workforce stability during the review process, including broad-based retention bonuses for employees and targeted retention awards for critical leadership and operational roles. While the company had experienced a modest increase in employee turnover, management indicated that attrition remai


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Linde plc (NASDAQ:LIN) as a new holding. Linde plc (NASDAQ:LIN) operates as the world's leading industrial gas company. On August 21, 2026, Linde plc (NASDAQ:LIN) closed at $487.57 per share. The one-month return of Linde plc (NASDAQ:LIN) was -3.84%, and its shares gained 2.03% over the past 52 weeks. Linde plc (NASDAQ:LIN) has a market capitalization of $224.76 billion.
SGA Global Growth Strategy stated the following regarding Linde plc (NASDAQ:LIN) in its Q2 2026 investor letter:
"Linde plc (NASDAQ:LIN), the world's largest industrial gas company, was added to the portfolio in April. We had previously exited the position in 2024 due to valuation considerations and forced attrition; since then, the stock price has consolidated while fundamentals continued to progress. Linde remains an attractive long-term investment, supported by a highly durable business model and meaningful structural advantages. A large share of revenue is generated from long-term, recurring customer contracts in essential end markets, providing strong pricing power and cash flow visibility even in a slower growth environment. The company's strengths are rooted in its production efficiency and broad exposure across diverse end markets, including healthcare, manufacturing, electronics, chemicals, and energy.
Looking ahead, Linde is well-positioned to benefit from structural improvements and a potential acceleration in global growth across several of its core markets over the medium term. The U.S., which accounts for roughly 45% of revenue, is likely to see improved growth driven by an industrial recovery, increased semiconductor manufacturing, and higher refinery utilization. Europe (approximately 25% of revenue) has been a headwind in recent years due to negative volume growth, but is expected to stabilize over the medium term, with the potential for mo

2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Salesforce, Inc. (NYSE:CRM). Salesforce, Inc. (NYSE:CRM) is a cloud computing company that offers Customer Relationship Management (CRM) technology that brings companies and customers together. On August 21, 2026, Salesforce, Inc. (NYSE:CRM) closed at $209.17 per share. The one-month return of Salesforce, Inc. (NYSE:CRM) is 21.95%, while its shares lost 14.59% over the past 52 weeks. Salesforce, Inc. (NYSE:CRM) has a market capitalization of $171.31 billion.
SGA Global Growth Strategy stated the following regarding Salesforce, Inc. (NYSE:CRM) in its Q2 2026 investor letter:
"Salesforce was a detractor from performance during the quarter as investor sentiment remained cautious following another quarter that merely met its guidance targets. Current remaining performance obligations (cRPO) growth were in line at roughly 9% rather than the historical pattern of beating by about a point, and the forward quarter guide was modest. Management acknowledged continued weakness in Marketing, Commerce, and Tableau (roughly 20% of revenue), partially offset by strength in Sales Cloud, Service Cloud, Slack, and Data Cloud (roughly 75% to 80% of revenue), with Sales and Service Cloud each posting seat growth in the quarter. Additionally, Agentforce annualized recurring revenue reached $1.2 billion, growing 205%. Management reiterated full-year guidance and a second-half reacceleration based on bookings strength and lower attrition, alongside a long-term double-digit organic growth target through CY29 with about 100 basis points of annual margin expansion. Despite concerns around AI‑driven competition, we believe Salesforce's integration into customer business processes, large installed base, and wide product set position it well to compete effectively in the Agentic AI era, supporting low-teens earnings growth over the next three years. We



