

10 days ago
C3.ai's fiscal first-quarter results replaced a speculative earnings setup with a mixed turnaround test. The company reported $52.4 million of revenue, within its $50 million to $54 million guidance but down 25% from $70.3 million a year earlier. Subscription revenue was $49.2 million, or 94% of total revenue, compared with $60.3 million in the prior-year quarter. C3.ai, Inc. (NYSE:AI) therefore stabilized within management's lowered expectations, without yet returning to growth.
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE
There were encouraging operating signals. Bookings increased 73% sequentially, the company signed 22 agreements, and free cash flow improved to positive $2.1 million from negative $34.3 million a year earlier. Its non-GAAP operating loss narrowed 33% sequentially to $36.2 million. Management guided fiscal second-quarter revenue to $51 million to $55 million and maintained full-year revenue guidance of $210 million to $240 million. Still, both ranges imply that a rapid return to the prior year's scale is unlikely.
Those figures complicate, rather than erase, DA Davidson ***** yst Lucky Schreiner's bearish case. In a September 1 note, Schreiner reiterated an Underperform rating and a $7 target, while seeing possible professional-services upside and stabilization in subscription trends. Revenue landed near the middle of guidance, and subscription revenue represented a larger share of the mix. However, stabilization at a much lower level is not the same as renewed expansion.
The bearish evidence remains substantial. GAAP gross margin was only 32%, and the company posted a $92.8 million GAAP net loss, or $0.60 per share. C3.ai, Inc. (NYSE:AI) still competes against cloud providers, data platforms, and customers building applications internally. Better bookings and cash flow must translate into durable subscription growth and improving margins before the results demonstrate an economic turnaround.
Hedge funds showed cautious improvement rather than conviction. Insider Monkey counted 29 hedge funds holding the shares in Q2, up from 25 in Q1. Point72 ***** et Management increased its position 154% to 568,406 shares. That is notable, but 13F filings reveal positions rather than investment rationales.
#gaap #company #guidance #NYSE
10 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved a debt-free balance sheet following $350 million in prepayments since 2023, significantly reducing cash flow breakeven points and enhancing financial flexibility.
Maintained high profitability with a 40% margin, driven by efficient cost structures and increased interest income from a growing cash position.
Executed a fleet optimization strategy by selling 13 older vessels since 2023 to crystallize returns and improve the average age of the fleet.
Shifted vessel allocation to the West of Suez (Europe and Med) where spot rates are approximately 30% higher than in Eastern markets.
#achieved #shifted
Achieved a debt-free balance sheet following $350 million in prepayments since 2023, significantly reducing cash flow breakeven points and enhancing financial flexibility.
Maintained high profitability with a 40% margin, driven by efficient cost structures and increased interest income from a growing cash position.
Executed a fleet optimization strategy by selling 13 older vessels since 2023 to crystallize returns and improve the average age of the fleet.
Shifted vessel allocation to the West of Suez (Europe and Med) where spot rates are approximately 30% higher than in Eastern markets.
#achieved #shifted
13 days ago
First Phosphate Corp. (CSE:PHOS, NASDAQ:PHOS, FRA:KD0, OTCQX:FRSPF) said shareholders re-elected all five board nominees and approved an advance notice policy at its Annual General and Special Meeting, as the company's registered shareholder base grew 861% over the past year.
The company reported voter turnout of more than 34% at the meeting, held August 28, 2026, with all board nominees receiving support above 95%.
First Phosphate said its shareholder count reached 12,501 as of the record date for the 2026 meeting, up from 1,301 a year earlier, an increase of 861%. The figures, drawn from the company's transfer agent registrar and beneficial shareholder data from Broadridge, do not include any growth since the company's recent Nasdaq listing.
The company said the growth in its shareholder base reflects a positive sign of maturation in its corporate development, which it attributed to successful financings, management's commitment to results, and a broader understanding and appreciation of the company's vision, initiatives and opportunities among both retail and institutional investors.
Shareholders also approved fixing the board at five directors, the appointment of Davidson & Company LLP as auditor, and the re-approval of the company's omnibus equity incentive plan, each drawing support above 96%.
#shareholder #company
The company reported voter turnout of more than 34% at the meeting, held August 28, 2026, with all board nominees receiving support above 95%.
First Phosphate said its shareholder count reached 12,501 as of the record date for the 2026 meeting, up from 1,301 a year earlier, an increase of 861%. The figures, drawn from the company's transfer agent registrar and beneficial shareholder data from Broadridge, do not include any growth since the company's recent Nasdaq listing.
The company said the growth in its shareholder base reflects a positive sign of maturation in its corporate development, which it attributed to successful financings, management's commitment to results, and a broader understanding and appreciation of the company's vision, initiatives and opportunities among both retail and institutional investors.
Shareholders also approved fixing the board at five directors, the appointment of Davidson & Company LLP as auditor, and the re-approval of the company's omnibus equity incentive plan, each drawing support above 96%.
#shareholder #company
19 days ago
Cybersecurity has been a hot industry for several years, with Grand View Research projecting an 11.9% compound annual growth rate (CAGR) through 2033. However, artificial intelligence (AI) is heating up the need for cybersecurity.
Each AI agent and model needs cybersecurity. Furthermore, hackers can use AI to hack more targets, and cybersecurity companies use AI to deter those attackers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Cloudflare (NYSE: NET) and Palo Alto Networks (NASDAQ: PANW) are at the forefront of this opportunity. They both generate annual recurring revenue from leading companies, but there are a few things to consider when comparing these stocks.
Palo Alto Networks is the most established cybersecurity platform. It earned $3 billion in its fiscal 2026 third quarter, ended April 30, while Cloudflare only generated $696.1 million in the second quarter. It is also profitable, while Cloudflare is still burning through cash. Although its fiscal 2026 third quarter wasn't profitable, that was mainly due to merger and acquisition (M&A) expenses. It had been profitable in the first and second quarters of its fiscal 2026.
#signal #fiscal #quarter #networks
Each AI agent and model needs cybersecurity. Furthermore, hackers can use AI to hack more targets, and cybersecurity companies use AI to deter those attackers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Cloudflare (NYSE: NET) and Palo Alto Networks (NASDAQ: PANW) are at the forefront of this opportunity. They both generate annual recurring revenue from leading companies, but there are a few things to consider when comparing these stocks.
Palo Alto Networks is the most established cybersecurity platform. It earned $3 billion in its fiscal 2026 third quarter, ended April 30, while Cloudflare only generated $696.1 million in the second quarter. It is also profitable, while Cloudflare is still burning through cash. Although its fiscal 2026 third quarter wasn't profitable, that was mainly due to merger and acquisition (M&A) expenses. It had been profitable in the first and second quarters of its fiscal 2026.
#signal #fiscal #quarter #networks
20 days ago
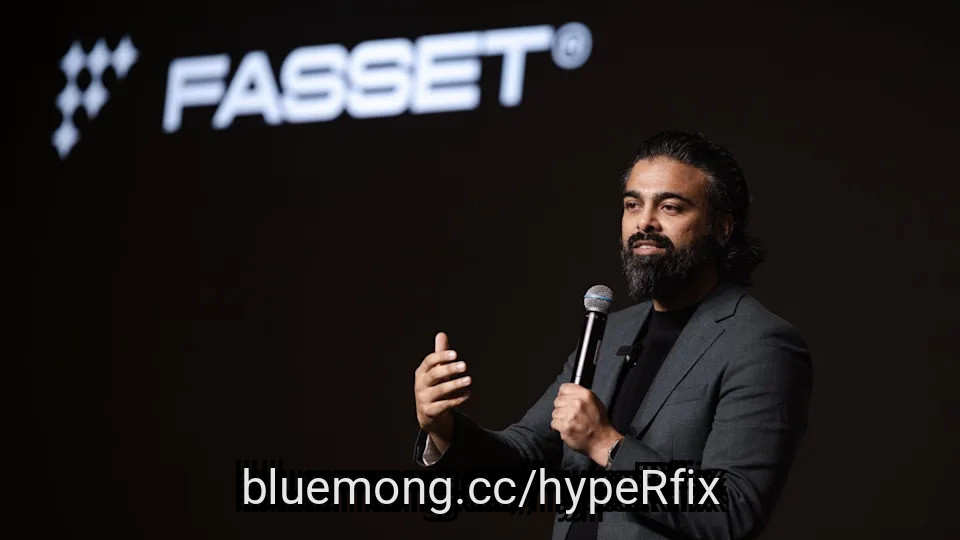
Fasset, a stablecoin-powered neobank, has achieved unicorn status following its latest funding round led by ******* an's SBI Group.
The platform raised $68m in Series C to hit $1bn valuation.
The funding follows Fasset's $51m Series B announced in May. The company said Speedinvest joined the cap table in that round alongside strategic investors.
Overall, Fasset has raised $119m this year.
SBI Holdings chairman, president and CEO, and representative director Yoshitaka Kitao said: "Fasset's vision of a world in which money moves across borders as easily as information does point in the same direction as the on-chain economic zone that the SBI Group seeks to realise through digital finance.
#group #series #raised
The platform raised $68m in Series C to hit $1bn valuation.
The funding follows Fasset's $51m Series B announced in May. The company said Speedinvest joined the cap table in that round alongside strategic investors.
Overall, Fasset has raised $119m this year.
SBI Holdings chairman, president and CEO, and representative director Yoshitaka Kitao said: "Fasset's vision of a world in which money moves across borders as easily as information does point in the same direction as the on-chain economic zone that the SBI Group seeks to realise through digital finance.
#group #series #raised
24 days ago
Apple and Alphabet are two of the largest holdings within Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB)'s portfolio. Those tech giants are also among the most valuable stocks in the world, with market caps in excess of $4 trillion.
Historically, under former CEO Warren Buffett, Berkshire hasn't been all that big on tech stocks, but that appears to be changing. Apple has been a big exception, largely because of the success of its iPhones, and it has effectively become a massive consumer brand. Consumer goods stocks are investments that certainly aren't foreign to Buffett or Berkshire's portfolio.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Greg Abel has taken over as CEO of Berkshire, and while Buffett claims to have initiated the recent position in Alphabet, Abel has added to it. And it begs the question of whether another top tech giant might end up in Berkshire's portfolio.
Could Nvidia (NASDAQ: NVDA) be the next big tech stock that Berkshire invests in?
#berkshire #alphabet #NYSE
Historically, under former CEO Warren Buffett, Berkshire hasn't been all that big on tech stocks, but that appears to be changing. Apple has been a big exception, largely because of the success of its iPhones, and it has effectively become a massive consumer brand. Consumer goods stocks are investments that certainly aren't foreign to Buffett or Berkshire's portfolio.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Greg Abel has taken over as CEO of Berkshire, and while Buffett claims to have initiated the recent position in Alphabet, Abel has added to it. And it begs the question of whether another top tech giant might end up in Berkshire's portfolio.
Could Nvidia (NASDAQ: NVDA) be the next big tech stock that Berkshire invests in?
#berkshire #alphabet #NYSE
25 days ago
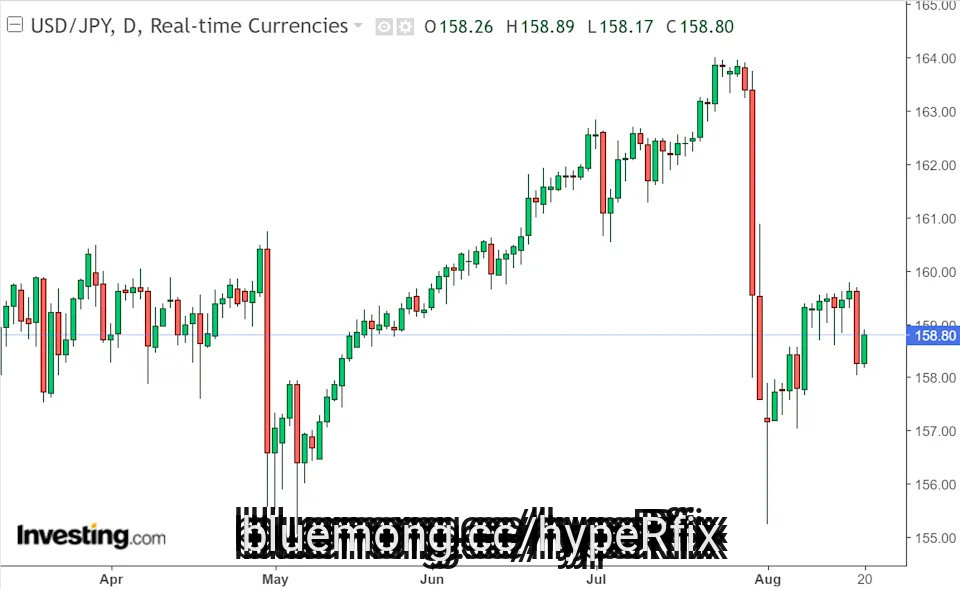
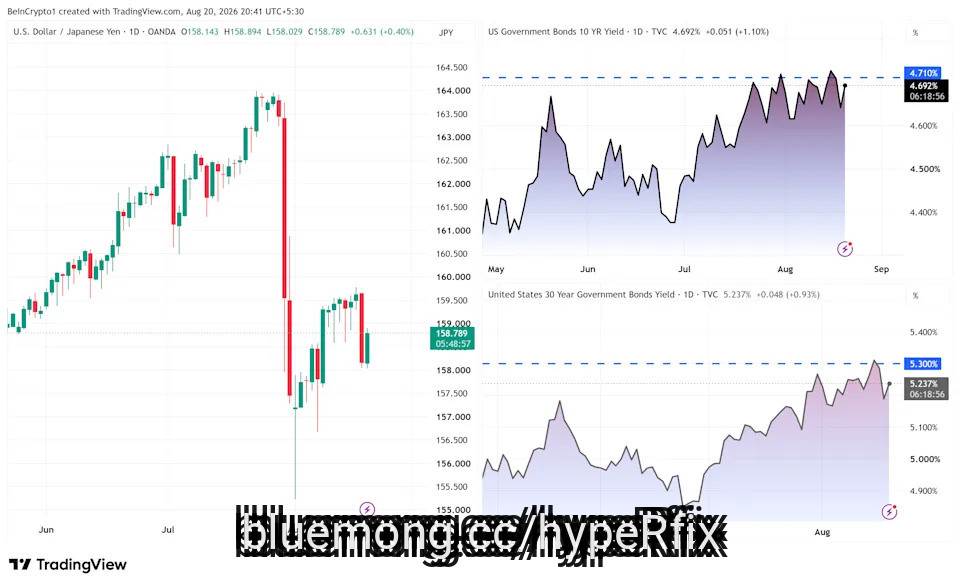
Bitcoin (BTC) has traded through two US market interventions in under three weeks. It moved the opposite way each time. Support for the yen pushed it down. An attack on long yields lifted it 8.8%.
Treasury Secretary Scott Bessent went further on Thursday. He said buybacks could exceed $4 billion per issue and would become routine, while denying that rates drove the decision.
Follow us on X to get the latest news as it happens
The pattern is narrower than it looks. Bitcoin does not reward intervention itself. It rewards the intervention that lowers long-dated US borrowing costs.
The first landed at the start of August. ****** an bought its own currency with an estimated $53 billion. The New York Fed then bought yen for the Treasury on August 1.
#august #intervention #bought #secretary
Treasury Secretary Scott Bessent went further on Thursday. He said buybacks could exceed $4 billion per issue and would become routine, while denying that rates drove the decision.
Follow us on X to get the latest news as it happens
The pattern is narrower than it looks. Bitcoin does not reward intervention itself. It rewards the intervention that lowers long-dated US borrowing costs.
The first landed at the start of August. ****** an bought its own currency with an estimated $53 billion. The New York Fed then bought yen for the Treasury on August 1.
#august #intervention #bought #secretary
25 days ago
(Bloomberg) -- Meta Platforms Inc. has deceived the public for years by targeting children on Facebook and Instagram with technology designed to turn them into compulsive users and drive up advertising revenue, a lawyer at the California attorney general's office told a jury.
Most Read from Bloomberg
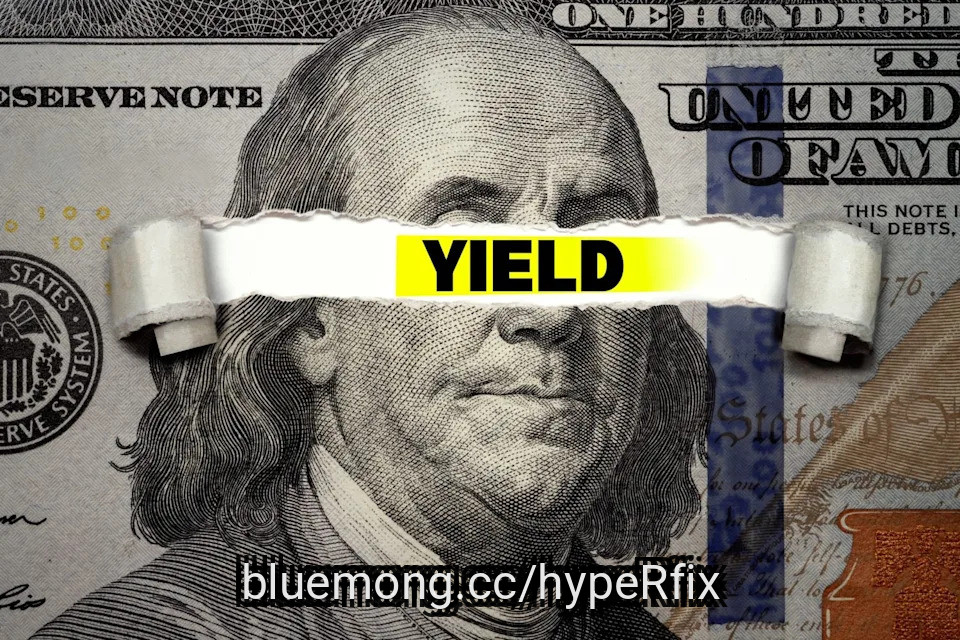
US Bond Selloff Drives 30-Year Yields to Highest Since 2007
US-Iran Peace Prospects Dim as Trump Rejects Truce Extension
Anthropic's Annualized Revenue Tops $65 Billion Before IPO
#selloff
Most Read from Bloomberg
US Bond Selloff Drives 30-Year Yields to Highest Since 2007
US-Iran Peace Prospects Dim as Trump Rejects Truce Extension
Anthropic's Annualized Revenue Tops $65 Billion Before IPO
#selloff

1 month ago
A $100,000 stake in QYLD returned 170% over 12 years while QQQ gained 652%, leaving holders with a six-figure gap in realized wealth.
JEPQ and GPIQ use partial option coverage instead of QYLD's 100% overlay, preserving more NAV while sacrificing some monthly income.
QYLD's distributions have dropped 24% since 2021 and its NAV has gone sideways for a decade, quietly undermining the 12% headline yield.
It sounds nuts, but SoFi1 is giving new Active Invest users up to $3,000 in stock for a limited time, and all it takes is a $50 deposit to get started.2 See for yourself (Sponsor)
Twelve years of monthly distributions and a double-digit yield sound attractive. But for long-term holders of the Global X NASDAQ 100 Covered Call ETF (NASDAQ:QYLD), that income has come at a significant cost. The fund has generated plenty of cash, but its share price has barely moved. Compared with simply owning a plain Nasdaq-100 index fund, the opportunity cost now stretches well into six figures on a $100,000 investment.
#qyld #years
JEPQ and GPIQ use partial option coverage instead of QYLD's 100% overlay, preserving more NAV while sacrificing some monthly income.
QYLD's distributions have dropped 24% since 2021 and its NAV has gone sideways for a decade, quietly undermining the 12% headline yield.
It sounds nuts, but SoFi1 is giving new Active Invest users up to $3,000 in stock for a limited time, and all it takes is a $50 deposit to get started.2 See for yourself (Sponsor)
Twelve years of monthly distributions and a double-digit yield sound attractive. But for long-term holders of the Global X NASDAQ 100 Covered Call ETF (NASDAQ:QYLD), that income has come at a significant cost. The fund has generated plenty of cash, but its share price has barely moved. Compared with simply owning a plain Nasdaq-100 index fund, the opportunity cost now stretches well into six figures on a $100,000 investment.
#qyld #years
1 month ago
Interested in MP Materials Corp.? Here are five stocks we like better.
Q2 performance improved sharply: Revenue and PPA income more than doubled year over year to $126.1 million, while adjusted EBITDA rose by $41 million to $28.5 million. NdPr sales volumes increased 127%, supported by stronger production and materials-segment profitability.
Rare-earth expansion is advancing: MP Materials completed its first heavy rare-earth separation circuit and expects to begin producing terbium and dysprosium later this year. It also secured a sizable, multiyear gadolinium oxide supply agreement with a U.S. aerospace and defense customer.
Magnet manufacturing is nearing commercialization: The Independence facility delivered magnets to General Motors for qualification testing, with initial commercial shipments still expected in Q4. Construction has begun at the larger 10X facility, and the company maintained 2026 capital-expenditure guidance of $500 million to $600 million.
Why Rare Earth Processing Could Be the Real 2027 Opportunity
#materials #revenue
Q2 performance improved sharply: Revenue and PPA income more than doubled year over year to $126.1 million, while adjusted EBITDA rose by $41 million to $28.5 million. NdPr sales volumes increased 127%, supported by stronger production and materials-segment profitability.
Rare-earth expansion is advancing: MP Materials completed its first heavy rare-earth separation circuit and expects to begin producing terbium and dysprosium later this year. It also secured a sizable, multiyear gadolinium oxide supply agreement with a U.S. aerospace and defense customer.
Magnet manufacturing is nearing commercialization: The Independence facility delivered magnets to General Motors for qualification testing, with initial commercial shipments still expected in Q4. Construction has begun at the larger 10X facility, and the company maintained 2026 capital-expenditure guidance of $500 million to $600 million.
Why Rare Earth Processing Could Be the Real 2027 Opportunity
#materials #revenue
1 month ago
The commercial **** e sector is one of the most volatile themes in the market. Because **** e stocks often move up and down together, thanks to macro liquidity, launch successes, or sector-wide risk-on sentiment, how an ETF constructs its holdings matters significantly.
Different **** e-focused ETFs offer different edges and also weaknesses versus their peers. That beauty, or lack thereof, is in the eyes of the beholder. It often comes down to how concentrated an ETF is. In other words, how few stock holdings it includes. Here are four ETFs I am comparing below:
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and **** eX Earnings on Tap
#holdings
Different **** e-focused ETFs offer different edges and also weaknesses versus their peers. That beauty, or lack thereof, is in the eyes of the beholder. It often comes down to how concentrated an ETF is. In other words, how few stock holdings it includes. Here are four ETFs I am comparing below:
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and **** eX Earnings on Tap
#holdings


1 month ago
1 month ago
This story was originally published on Restaurant Dive. To receive daily news and insights, subscribe to our free daily Restaurant Dive newsletter.
McDonald's appointed Skye Anderson as president of McDonald's USA, effective Tuesday, the company said in a press release.
Anderson succeeds Joe Erlinger, who is leaving the company after a 20-year tenure, including nearly seven years overseeing the U.S. business. Erlinger will work with Anderson to ensure a seamless transition and serve as an advisor until early next year.
Anderson has worked at McDonald's for over 26 years, and she was appointed chief operating officer of McDonald's USA in April as part of a "deliberate leadership transition plan" to ensure continuity and prepare her to lead the chain's largest market, according to the press release.
In her new position, Anderson will oversee the U.S. portion of McDonald's > NEXT strategy, which the chain unveiled in June.
#press
McDonald's appointed Skye Anderson as president of McDonald's USA, effective Tuesday, the company said in a press release.
Anderson succeeds Joe Erlinger, who is leaving the company after a 20-year tenure, including nearly seven years overseeing the U.S. business. Erlinger will work with Anderson to ensure a seamless transition and serve as an advisor until early next year.
Anderson has worked at McDonald's for over 26 years, and she was appointed chief operating officer of McDonald's USA in April as part of a "deliberate leadership transition plan" to ensure continuity and prepare her to lead the chain's largest market, according to the press release.
In her new position, Anderson will oversee the U.S. portion of McDonald's > NEXT strategy, which the chain unveiled in June.
#press

2 months ago
Longtime Apple (NASDAQ: AAPL) CEO Tim Cook will host his final earnings conference call after the bell on Thursday, July 30. While Cook was not the same type of innovator as his predecessor, Apple founder and legendary CEO Steve Jobs, he did a great job of nurturing Apple's core strengths. He will leave as Apple is the largest company in the world, with a market cap of $5 trillion. The question, though, is whether the stock is still a buy with him ready to depart.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
When Apple reports its fiscal third-quarter results, investors should expect much of the same. iPhone sales should be solid, with the company reportedly seeing a 3% increase in shipments during the quarter and gaining its highest-ever global market share at 20%, according to Centerpoint Research. This should then feed into its high-margin service revenue, which has consistently grown at a mid-teen rate.
Cook leaves Apple as having one of the best business models on the planet, making it easy for its next CEO to get off to a running start. The beauty of Apple is its closed ecosystem, which helps lock in customers. Once someone buys an iPhone, the cost of switching becomes increasingly difficult with each photo taken, subscription bought, and app downloaded. Users then become a part of Apple's huge service revenue machine. Apple is getting a high-margin revenue stream every time someone clicks on a search ad (as it gets a 36% revenue cut from Alphabet's Google), uses Apple Pay, buys cloud storage, or purchases a subscription or app.
Meanwhile, Apple just increased prices for several devices and certain service plans. This should be a nice revenue driver in the coming quarters after Cook leaves, giving incoming CEO John Ternus a solid revenue tailwind as he takes the reins. Ternus will also have time to execute a more comprehensive AI strategy for the company. That said, I wouldn't be surprised if Cook's decision to sit back and not throw huge amounts of money into chasing AI models proves to be a smart one.
#revenue #signal #same
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
When Apple reports its fiscal third-quarter results, investors should expect much of the same. iPhone sales should be solid, with the company reportedly seeing a 3% increase in shipments during the quarter and gaining its highest-ever global market share at 20%, according to Centerpoint Research. This should then feed into its high-margin service revenue, which has consistently grown at a mid-teen rate.
Cook leaves Apple as having one of the best business models on the planet, making it easy for its next CEO to get off to a running start. The beauty of Apple is its closed ecosystem, which helps lock in customers. Once someone buys an iPhone, the cost of switching becomes increasingly difficult with each photo taken, subscription bought, and app downloaded. Users then become a part of Apple's huge service revenue machine. Apple is getting a high-margin revenue stream every time someone clicks on a search ad (as it gets a 36% revenue cut from Alphabet's Google), uses Apple Pay, buys cloud storage, or purchases a subscription or app.
Meanwhile, Apple just increased prices for several devices and certain service plans. This should be a nice revenue driver in the coming quarters after Cook leaves, giving incoming CEO John Ternus a solid revenue tailwind as he takes the reins. Ternus will also have time to execute a more comprehensive AI strategy for the company. That said, I wouldn't be surprised if Cook's decision to sit back and not throw huge amounts of money into chasing AI models proves to be a smart one.
#revenue #signal #same

2 months ago
The physical infrastructure enabling artificial intelligence requires considerably more than just high-performance accelerators and primary grid connections. It also relies on millions of high-density connectors, backplane interconnects, and power-filtering devices to connect rack-level structures, areas where TE Connectivity plc (NYSE:TEL) holds a significant bottleneck position. As hyperscalers and enterprise data center operators ramp up capital expenditure deployment around the world, demand for critical electrical connector systems has transformed from a passive secondary tailwind to a direct beneficiary of the AI growth cycle.
The company's fiscal third-quarter 2026 report showed this demand in real time, with record top-line performance, order velocity, and profitability. Despite exceeding Wall Street expectations in every fundamental indicator, shares fell roughly 7% following the release, indicating the market's focus on sequential forecast trends over historical trailing figures.
Operational execution in the third quarter set new highs across numerous business areas. Net revenue increased 14% year-over-year to $5.16 billion, above Wall Street expectations by more than 3%. Adjusted earnings per share rose 22% year-over-year to $2.94, exceeding the average estimate of $2.85. The report's defining metric was order flow, which increased 27% year-over-year to a record $5.7 billion, reflecting over $1 billion in incremental booking expansion vs. the prior year period. Meanwhile, profitability increased significantly, with adjusted operating margins improving 90 basis points to 22% and quarterly free cash flow totaling $883 million.
The underlying sector distribution highlights where AI momentum is growing the fastest. Industrial Solutions revenue increased 22% year-over-year to $2.58 billion, driven mainly by data center rack deployments and energy infrastructure growth. Chief Executive Officer Terrence Curtin stated that AI cloud momentum is far above initial multi-year predictions, with data center connection and power distribution orders rising more than 70% year-to-date.
Moreover, to back up its power-handling portfolio, TE Connectivity plc (NYSE:TEL) signed a $1.4 billion formal agreement to acquire Astrodyne TDI. The acquisition includes specialized power management and electromagnetic filtering solutions for critical industrial, semiconductor, and defense applications, providing approximately $250 million in annual revenue to the Industrial Solutions segment once completed.
#year #solutions #data
The company's fiscal third-quarter 2026 report showed this demand in real time, with record top-line performance, order velocity, and profitability. Despite exceeding Wall Street expectations in every fundamental indicator, shares fell roughly 7% following the release, indicating the market's focus on sequential forecast trends over historical trailing figures.
Operational execution in the third quarter set new highs across numerous business areas. Net revenue increased 14% year-over-year to $5.16 billion, above Wall Street expectations by more than 3%. Adjusted earnings per share rose 22% year-over-year to $2.94, exceeding the average estimate of $2.85. The report's defining metric was order flow, which increased 27% year-over-year to a record $5.7 billion, reflecting over $1 billion in incremental booking expansion vs. the prior year period. Meanwhile, profitability increased significantly, with adjusted operating margins improving 90 basis points to 22% and quarterly free cash flow totaling $883 million.
The underlying sector distribution highlights where AI momentum is growing the fastest. Industrial Solutions revenue increased 22% year-over-year to $2.58 billion, driven mainly by data center rack deployments and energy infrastructure growth. Chief Executive Officer Terrence Curtin stated that AI cloud momentum is far above initial multi-year predictions, with data center connection and power distribution orders rising more than 70% year-to-date.
Moreover, to back up its power-handling portfolio, TE Connectivity plc (NYSE:TEL) signed a $1.4 billion formal agreement to acquire Astrodyne TDI. The acquisition includes specialized power management and electromagnetic filtering solutions for critical industrial, semiconductor, and defense applications, providing approximately $250 million in annual revenue to the Industrial Solutions segment once completed.
#year #solutions #data

2 months ago
By Mike Dolan
July 27 (Reuters) -
What matters in U.S. and global markets today
By Mike Dolan, Editor-at-Large, Finance and Markets
A pause in the Iran conflict and a sizeable retreat in crude oil prices away from $100 per barrel offer some relief at the start of what's set to be another turbulent week for markets.
#dolan #reuters #finance #matters
July 27 (Reuters) -
What matters in U.S. and global markets today
By Mike Dolan, Editor-at-Large, Finance and Markets
A pause in the Iran conflict and a sizeable retreat in crude oil prices away from $100 per barrel offer some relief at the start of what's set to be another turbulent week for markets.
#dolan #reuters #finance #matters

2 months ago
Like most investors, I stepped into the stock market rather cautiously, doing my best to follow Warren Buffett's primary rule: "Don't lose money."
Three decades later, I now realize I didn't fully appreciate the nuances of this tip. Namely, I conflated temporary setbacks with locking in losses. Oh, I knew the difference between realized and unrealized. It's just that, mentally, I convinced myself that some pullbacks never stop. Big mistake. Most do. This mindset kept me out of some stocks that would have ended up being very big winners.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I can't go back in time and do things over. I can, however, help others learn from my mistakes and tell them the very first stock I would have bought and held back then if I had known then what I know now. That's Google parent Alphabet (NASDAQ: GOOGL) (NASDAQ: GOOG).
OK, Google wasn't around when I first started investing. It wouldn't exist until 1998, and it didn't go public until 2004. If I were just starting out or starting over again today, however, it would be the foundational position in my portfolio.
#flashing
Three decades later, I now realize I didn't fully appreciate the nuances of this tip. Namely, I conflated temporary setbacks with locking in losses. Oh, I knew the difference between realized and unrealized. It's just that, mentally, I convinced myself that some pullbacks never stop. Big mistake. Most do. This mindset kept me out of some stocks that would have ended up being very big winners.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
I can't go back in time and do things over. I can, however, help others learn from my mistakes and tell them the very first stock I would have bought and held back then if I had known then what I know now. That's Google parent Alphabet (NASDAQ: GOOGL) (NASDAQ: GOOG).
OK, Google wasn't around when I first started investing. It wouldn't exist until 1998, and it didn't go public until 2004. If I were just starting out or starting over again today, however, it would be the foundational position in my portfolio.
#flashing


2 months ago
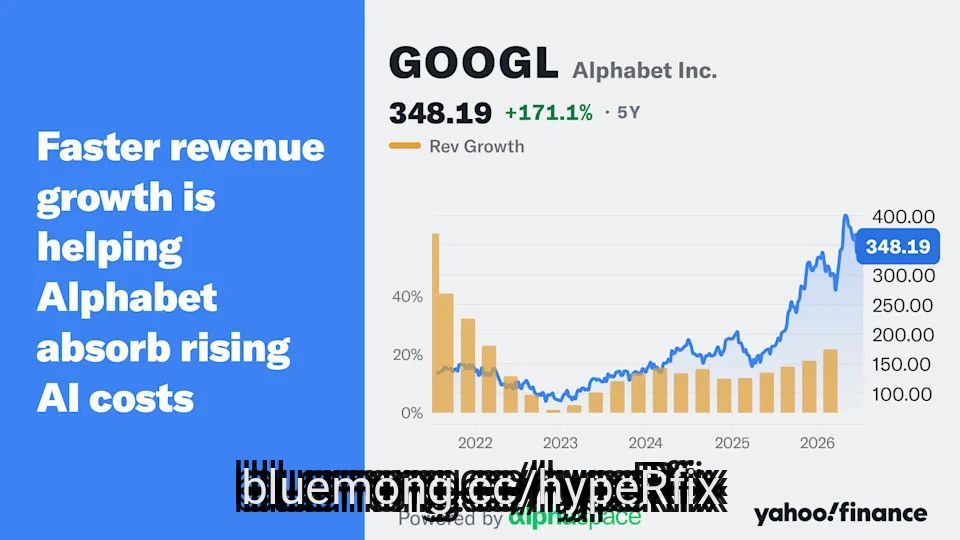
Alphabet's (GOOGL) AI spending has surged. So have sales and profits.
Earnings after the bell will show whether that unlikely combination can hold.
So far, Alphabet has made the balancing act look almost easy.
Its operating margin — the share of sales left after running the business — reached 36.1% in the first quarter, its highest level in five years. Revenue grew 22%, while operating income jumped 30%.
Growth has helped do the heavy lifting.
#googl #alphabet #Growth #surged
Earnings after the bell will show whether that unlikely combination can hold.
So far, Alphabet has made the balancing act look almost easy.
Its operating margin — the share of sales left after running the business — reached 36.1% in the first quarter, its highest level in five years. Revenue grew 22%, while operating income jumped 30%.
Growth has helped do the heavy lifting.
#googl #alphabet #Growth #surged


2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Delivered a 5.5% economic return and 1.7% book value growth, driven by lower rate volatility and the structural advantages of a diversified housing finance model.
Increased the quarterly common dividend to $0.75 per share, reflecting nine consecutive quarters of earnings exceeding the dividend and confidence in long-term earnings power.
Achieved record residential credit acquisition of $7.1 billion in Q2, utilizing the Onslow Bay correspondent channel to manufacture proprietary, high-yielding investments.
Maintained a conservative economic leverage of 5.6x while raising $450 million in accretive equity to scale the residential credit and MSR platforms.
#economic #credit
Delivered a 5.5% economic return and 1.7% book value growth, driven by lower rate volatility and the structural advantages of a diversified housing finance model.
Increased the quarterly common dividend to $0.75 per share, reflecting nine consecutive quarters of earnings exceeding the dividend and confidence in long-term earnings power.
Achieved record residential credit acquisition of $7.1 billion in Q2, utilizing the Onslow Bay correspondent channel to manufacture proprietary, high-yielding investments.
Maintained a conservative economic leverage of 5.6x while raising $450 million in accretive equity to scale the residential credit and MSR platforms.
#economic #credit

2 months ago
Bristol Gate Capital Partners, an investment management company, published its Q2 2026 investor letter for the "US Equity Strategy". A copy of the letter can be downloaded here. The Strategy lagged the S&P 500 Total Return Index in the quarter in terms of returns, but outperformed in dividend growth. Despite debate over capital cycle returns, AI remained the dominant market theme, expanding from early adoption to broader enterprise adoption. The firm continues to focus on high-dividend-growth companies while maintaining discipline around valuation and earnings durability. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Bristol US Equity Strategy highlighted Costco Wholesale Corporation (NASDAQ:COST). Costco Wholesale Corporation (NASDAQ:COST) is a leading US-based multinational retailer that specializes in the operation of membership-only warehouses. On July 22, 2026, Costco Wholesale Corporation (NASDAQ:COST) closed at $927.31 per share, reflecting a market capitalization of $411.24 billion. Costco Wholesale Corporation (NASDAQ:COST) posted a one-month return of -1.58%, and its shares lost 0.70% over the past 52 weeks.
Bristol US Equity Strategy stated the following regarding Costco Wholesale Corporation (NASDAQ:COST) in its Q2 2026 investor update:
"Costco Wholesale Corporation (NASDAQ:COST) operates a membership-based model with a durable competitive moat in retail, anchored by industry-leading renewal rates and a value proposition that strengthens with scale. The recurring membership-fee stream is high-margin, predictable, and compounds alongside member growth and periodic fee increases. Backed by an experienced and capable management team, we believe this combination will translate into continued high dividend growth."
Costco Wholesale Corporation (NASDAQ:COST) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 107 hedge fund portfolios held Costco Wholesale Corporation (NASDAQ:COST) at the end of the first quarter, up from 106 in the previous quarter. While we acknowledge the potential of Costco Wholesale Corporation (NASDAQ:COST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#costco #NASDAQ #bristol #Equity
In its Q2 2026 investor letter, Bristol US Equity Strategy highlighted Costco Wholesale Corporation (NASDAQ:COST). Costco Wholesale Corporation (NASDAQ:COST) is a leading US-based multinational retailer that specializes in the operation of membership-only warehouses. On July 22, 2026, Costco Wholesale Corporation (NASDAQ:COST) closed at $927.31 per share, reflecting a market capitalization of $411.24 billion. Costco Wholesale Corporation (NASDAQ:COST) posted a one-month return of -1.58%, and its shares lost 0.70% over the past 52 weeks.
Bristol US Equity Strategy stated the following regarding Costco Wholesale Corporation (NASDAQ:COST) in its Q2 2026 investor update:
"Costco Wholesale Corporation (NASDAQ:COST) operates a membership-based model with a durable competitive moat in retail, anchored by industry-leading renewal rates and a value proposition that strengthens with scale. The recurring membership-fee stream is high-margin, predictable, and compounds alongside member growth and periodic fee increases. Backed by an experienced and capable management team, we believe this combination will translate into continued high dividend growth."
Costco Wholesale Corporation (NASDAQ:COST) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 107 hedge fund portfolios held Costco Wholesale Corporation (NASDAQ:COST) at the end of the first quarter, up from 106 in the previous quarter. While we acknowledge the potential of Costco Wholesale Corporation (NASDAQ:COST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#costco #NASDAQ #bristol #Equity





