3 mins. ago
On August 4, Willis Lease Finance Corporation (NASDAQ:WLFC) reported second-quarter results that pulled in two directions at once. The lessor of commercial aircraft engines grew its operating business at a healthy clip, yet net income fell by more than half, a split that makes this quarter harder to read than the headline suggests.
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months

24 mins. ago
Leeds United made it four unbeaten to start the Premier League campaign with a convincing 4-1 victory over Newcastle United under the lights at Elland Road.
Riding the momentum and scoring three first half goals, Noah Okafor added to the tally in the second period to shoot the Whites up to third in the top-flight standings.
After the game, Daniel Farke said: "On rare occasions even for a manager, it is a joy to watch a football game, and especially his team playing. But this was one of those rare occasions so I also enjoyed my team playing tonight.
"It was an excellent performance, really, from the first to nearly the last second, and also sadly not a clean sheet in the end. But overall, a top-class performance and I am proud of my boys.
"We wanted to press Newcastle and wanted to dominate this game. But on the other hand, you also have to be aware how much pace they have up front.
#newcastle #rare #occasions #performance
Riding the momentum and scoring three first half goals, Noah Okafor added to the tally in the second period to shoot the Whites up to third in the top-flight standings.
After the game, Daniel Farke said: "On rare occasions even for a manager, it is a joy to watch a football game, and especially his team playing. But this was one of those rare occasions so I also enjoyed my team playing tonight.
"It was an excellent performance, really, from the first to nearly the last second, and also sadly not a clean sheet in the end. But overall, a top-class performance and I am proud of my boys.
"We wanted to press Newcastle and wanted to dominate this game. But on the other hand, you also have to be aware how much pace they have up front.
#newcastle #rare #occasions #performance


52 mins. ago
On September 10, Lovesac (NASDAQ:LOVE) reported record second quarter revenue of $161.2 million, its highest Q2 total ever, even as its entry-level furniture shopper kept pulling back. The 0.4% sales increase came almost entirely from showrooms rather than higher-margin online orders, and the quarter's real profit boost was traced to a one-time source. A $20 million tariff refund lifted gross margin by 1,200 basis points to 68.4%, masking an underlying business that actually lost money once that windfall is stripped out.
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue

58 mins. ago
On September 10, Shoe Station Group (NASDAQ:SHOE) held its first earnings call under its new name, and the numbers told a story of a company still finding its footing. Second quarter net sales fell 7.2% to $284.3 million from $306.4 million a year earlier, with comparable sales down 7.1%. But buried in the report was a sharper signal: August comparable sales improved to a 2.7% decline, a real jump from the second quarter's pace, and management is pointing to store-by-store product changes as the reason why.
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha
Shoe Station's turnaround argument rests on giving up the idea that every store should look the same. Interim CEO Clifton Sifford said the company had been running nearly identical ***** ortments across its stores even though its two banners serve very different customers, and that approach stopped working. The shift already shows up in the numbers. Once the company localized its athletic ***** ortments ahead of back-to-school, adult athletic sales moved from a low single-digit decline in the second quarter to a low single-digit increase in August.
Running shoes comped positive in both men's and women's categories, and men's work boots, a replenishment category with loyal repeat buyers, grew 2%. Management believes this fall's boot lineup is the best it has fielded in years, heading into what Sifford expects to be a bigger nonathletic fashion cycle. E-commerce sales grew 18.8% even as store traffic fell, and in-store conversion actually improved, evidence that customers who show up are buying; they just are not showing up in the same numbers yet. The company also ended the quarter debt-free with $131.6 million in cash, up $39.7 million from a year ago, giving it room to fund the localized rollout without straining the balance sheet.
The flip side is that the entire second quarter was ugly across the board. Shoe Carnival branded stores, still 63% of revenue, saw sales fall 6.5%, while the newly converted Shoe Station banner dropped 8.4%. Gross profit margin fell 690 basis points to 31.9%, a mix of a promotional footwear market and management's decision to accelerate liquidation of aged inventory, trading margin for cash. That combination cut net income to $6.3 million, or $0.23 per diluted share, down from $19.2 million and $0.70 a year earlier.
Management is not projecting relief anytime soon. Sifford said plainly, "We are not ***** uming the environment improves," and CFO Kerry Jackson noted that gross margins in fiscal August were still running below last year's levels at a pace comparable to the second quarter. Full-year gross margin guidance of 32.5% to 32.7% implies 390 to 410 basis points of compression for the year. Store impairment charges reached $6.7 million on 11 stores year to date, and management has already conceded that the core problem is not price, since conversion rates rose while total customer visits kept falling. That points to a marketing and trust problem rather than a demand problem, and fixing it will take more tha


59 mins. ago
Win or lose, any football game is sure to include some standout individual performances.
Luckily for us, the Jacksonville Jaguars obliterated the Cleveland Browns in Week 1, and there are plenty of game ****** to pass around.
Trevor Lawrence threw 4 touchdowns; Parker Washington had the coolest one of them; Foye Oluokun logged an interception and another pass breakup; Ventrell Miller had a team-high 9 tackles plus a sack and a forced fumble; and Josh Hines-Allen stuffed the stat sheet with 5 tackles, 1.5 sacks, a forced fumble, and a fumble recovery (on different plays!).
After the final whistle, we asked Jaguars fans to pick Big Cat Country's Player of the Week.
81% of voters chose Trevor Lawrence.
#fumble #week #game #forced
Luckily for us, the Jacksonville Jaguars obliterated the Cleveland Browns in Week 1, and there are plenty of game ****** to pass around.
Trevor Lawrence threw 4 touchdowns; Parker Washington had the coolest one of them; Foye Oluokun logged an interception and another pass breakup; Ventrell Miller had a team-high 9 tackles plus a sack and a forced fumble; and Josh Hines-Allen stuffed the stat sheet with 5 tackles, 1.5 sacks, a forced fumble, and a fumble recovery (on different plays!).
After the final whistle, we asked Jaguars fans to pick Big Cat Country's Player of the Week.
81% of voters chose Trevor Lawrence.
#fumble #week #game #forced

1 hr. ago
West Ham United have received a warning despite their emphatic 6-0 win over Wrexham, with former Championship striker Bradley Allen urging caution before winter. The comments, originally broadcast by BBC Radio London and covered by Inside Futbol, followed a performance that gave Nuno Espírito Santo's side a boost in the promotion race.
Six players scored, including captain Jarrod Bowen and Joel Piroe, while West Ham created 19 shots on goal and kept a clean sheet. Allen described the display as outstanding from start to finish and said West Ham possessed too much quality for Wrexham. Yet he stressed that bigger tests await, particularly as the winter schedule stacks fixtures together. His message was: West Ham can leave the Championship quickly, but the examination has not arrived.
Allen said on BBC Radio London: "What a performance, outstanding from start to finish, a clean sheet as well.
"Playing dominant football in front of a big crowd.
"That will put down a marker, but there will be bigger tests; we haven't got to the depths of winter.
#west #sheet
Six players scored, including captain Jarrod Bowen and Joel Piroe, while West Ham created 19 shots on goal and kept a clean sheet. Allen described the display as outstanding from start to finish and said West Ham possessed too much quality for Wrexham. Yet he stressed that bigger tests await, particularly as the winter schedule stacks fixtures together. His message was: West Ham can leave the Championship quickly, but the examination has not arrived.
Allen said on BBC Radio London: "What a performance, outstanding from start to finish, a clean sheet as well.
"Playing dominant football in front of a big crowd.
"That will put down a marker, but there will be bigger tests; we haven't got to the depths of winter.
#west #sheet


1 hr. ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands


5 hours ago
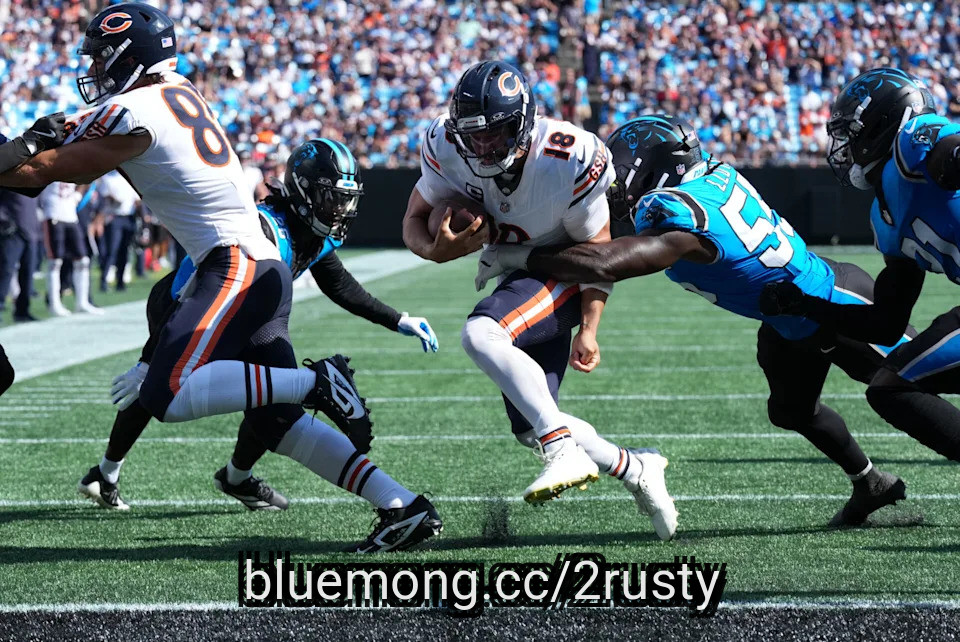
Caleb Williams and the Chicago Bears enjoyed an incredible offensive performance in their 59-37 win over the Carolina Panthers on Sunday afternoon. However, they are keeping their eye on the ball with some issues they must address as the 2026 campaign is underway.
Williams filled up the stat sheet as he enjoyed his activity in the offense. He completed 21 out of 29 passes for 269 yards and two touchdowns while racking up 10 rushes for 65 yards and two touchdowns.
Williams reflected on the performance after the game, per reporter Chris Emma. He surprisingly said this game will be the team's worst as he anticipates stronger displays throughout the coming weeks this year.
"That's who we want to be this week. We got to go clean up. We want to be truthers. Obviously, this is going to be our kind of worst game. I know points don't necessarily show that, but execution, the blocking, the penalties, all these different things," Williams said.
Sep 13, 2026; Charlotte, North Carolina, USA; Chicago Bears quarterback Caleb Williams (18) runs the ball while defended by Carolina Panthers linebacker Devin Lloyd (55) in the second half at Bank of America Stadium. Mandatory Credit: Jim Dedmon-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#williams #caleb #bears #images
Williams filled up the stat sheet as he enjoyed his activity in the offense. He completed 21 out of 29 passes for 269 yards and two touchdowns while racking up 10 rushes for 65 yards and two touchdowns.
Williams reflected on the performance after the game, per reporter Chris Emma. He surprisingly said this game will be the team's worst as he anticipates stronger displays throughout the coming weeks this year.
"That's who we want to be this week. We got to go clean up. We want to be truthers. Obviously, this is going to be our kind of worst game. I know points don't necessarily show that, but execution, the blocking, the penalties, all these different things," Williams said.
Sep 13, 2026; Charlotte, North Carolina, USA; Chicago Bears quarterback Caleb Williams (18) runs the ball while defended by Carolina Panthers linebacker Devin Lloyd (55) in the second half at Bank of America Stadium. Mandatory Credit: Jim Dedmon-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#williams #caleb #bears #images

6 hours ago
SPY surged 11% year-to-date while home prices hit all-time highs, powering a record $12.5 trillion single-quarter wealth gain to $185.7 trillion total.
The personal saving rate collapsed to 2.8% from 5.8% a year ago as Americans spend paper gains concentrated among the wealthiest households.
Household net worth hit 571% of GDP, just shy of the 574% record that previously preceded the Fed's most aggressive rate-hiking cycle in four decades.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
American households just booked the largest quarterly wealth gain in history, and most Americans do not feel any richer. Federal Reserve data released this month shows U.S. household net worth jumped $12.5 trillion in the second quarter of 2026, reaching a record $185.7 trillion. That single-quarter increase exceeds the annual gross domestic product of every country on earth except the United States and China. It is the eleventh straight quarter of gains, a streak that has added $43.4 trillion to household balance sheets and pushed ***** ulative wealth creation since the 2020 pandemic to $83.9 trillion. Yet the University of Michigan's consumer sentiment index came in at 55.2 in July, a level the survey's own interpretation guide classifies as recessionary.
#trillion #quarter #record #year
The personal saving rate collapsed to 2.8% from 5.8% a year ago as Americans spend paper gains concentrated among the wealthiest households.
Household net worth hit 571% of GDP, just shy of the 574% record that previously preceded the Fed's most aggressive rate-hiking cycle in four decades.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
American households just booked the largest quarterly wealth gain in history, and most Americans do not feel any richer. Federal Reserve data released this month shows U.S. household net worth jumped $12.5 trillion in the second quarter of 2026, reaching a record $185.7 trillion. That single-quarter increase exceeds the annual gross domestic product of every country on earth except the United States and China. It is the eleventh straight quarter of gains, a streak that has added $43.4 trillion to household balance sheets and pushed ***** ulative wealth creation since the 2020 pandemic to $83.9 trillion. Yet the University of Michigan's consumer sentiment index came in at 55.2 in July, a level the survey's own interpretation guide classifies as recessionary.
#trillion #quarter #record #year

7 hours ago
Hola amigos!
Welcome to the Monday mailbag post. This is where you can submit your questions to us, the humble staff at MMA Mania. If you have something you want to ask, pop it in the comment section below.
We'll answer everything and anything (so long as you're not trying to get us in trouble). But priority goes to time sensitive questions. For this week, that means stuff related to Noche UFC 4 or the upcoming UFC 331. You might also want to ask about Tom Aspinall vacating the Heavyweight ****** le.
You don't have to ask UFC or MMA questions, though. I welcome off-topic and also very silly questions. If we don't get to your question this week, don't worry. They all get logged on a big sheet so they don't get forgotten and can be answered another week.
Ok, shoot! Whatya got?
#want #hola #mania
Welcome to the Monday mailbag post. This is where you can submit your questions to us, the humble staff at MMA Mania. If you have something you want to ask, pop it in the comment section below.
We'll answer everything and anything (so long as you're not trying to get us in trouble). But priority goes to time sensitive questions. For this week, that means stuff related to Noche UFC 4 or the upcoming UFC 331. You might also want to ask about Tom Aspinall vacating the Heavyweight ****** le.
You don't have to ask UFC or MMA questions, though. I welcome off-topic and also very silly questions. If we don't get to your question this week, don't worry. They all get logged on a big sheet so they don't get forgotten and can be answered another week.
Ok, shoot! Whatya got?
#want #hola #mania


2 days ago
ATLANTA − Tennessee football quarterback Faizon Brandon faced some adversity while playing on the road for the first time in his very young college career.
Furman offered little resistance in his first career start but Brandon was challenged in Week 2 at Georgia Tech. His first road start didn't look pretty in the final box score but it was more than enough to get the No. 18 Vols (2-0) to a 45-24 win over the Yellow Jackets (0-2) on Sept. 12 at Bobby Dodd Stadium.
"The stat sheet's not going to be elite. I actually really like how he played the game," UT coach Josh Heupel said. "I thought he was composed, he handled himself in situational football pretty well. First game on the road, 18 years old, handled himself well."
Brandon completed 10 of 21 passes for 148 yards, two touchdowns and no interceptions. He was sacked once and added 23 yards on five rushing attempts.
He was particularly inaccurate in the first half, completing only 5 of 15 passes but racking up 106 yards and two touchdown passes. Of his five first-half completions, four went for 15 yards or more and three gained 20 yards or more.
#road #Career #start
Furman offered little resistance in his first career start but Brandon was challenged in Week 2 at Georgia Tech. His first road start didn't look pretty in the final box score but it was more than enough to get the No. 18 Vols (2-0) to a 45-24 win over the Yellow Jackets (0-2) on Sept. 12 at Bobby Dodd Stadium.
"The stat sheet's not going to be elite. I actually really like how he played the game," UT coach Josh Heupel said. "I thought he was composed, he handled himself in situational football pretty well. First game on the road, 18 years old, handled himself well."
Brandon completed 10 of 21 passes for 148 yards, two touchdowns and no interceptions. He was sacked once and added 23 yards on five rushing attempts.
He was particularly inaccurate in the first half, completing only 5 of 15 passes but racking up 106 yards and two touchdown passes. Of his five first-half completions, four went for 15 yards or more and three gained 20 yards or more.
#road #Career #start


2 days ago
KANSAS CITY, Mo. -- LAFC spent the first half of Saturday night looking like a team that had forgotten what was at stake.
Sporting Kansas City came into the match with the worst goal difference in MLS and 58 goals conceded through 23 games, yet it was LAFC that looked overwhelmed for long stretches at Sporting Park. By halftime, Sporting had built a 2-0 lead, and although LAFC fought its way back into the match after the break, a late defensive mistake turned what briefly looked like a comeback into a 3-1 loss.
Marc Dos Santos did not have a complicated explanation for what went wrong.
"The problem is in the first half we stayed in the plane," Dos Santos said. "I think in the first half we were still in LA, maybe very disappointing. We defended far from each other, passive. We didn't win any duels in the first half."
It was a startling opening from an LAFC team that had just set a club record with its 13th clean sheet against the New York Red Bulls on Wednesday. Five days later, the Black & Gold were repeatedly exposed by a Sporting attack that had been among the league's least productive.
#first #half
Sporting Kansas City came into the match with the worst goal difference in MLS and 58 goals conceded through 23 games, yet it was LAFC that looked overwhelmed for long stretches at Sporting Park. By halftime, Sporting had built a 2-0 lead, and although LAFC fought its way back into the match after the break, a late defensive mistake turned what briefly looked like a comeback into a 3-1 loss.
Marc Dos Santos did not have a complicated explanation for what went wrong.
"The problem is in the first half we stayed in the plane," Dos Santos said. "I think in the first half we were still in LA, maybe very disappointing. We defended far from each other, passive. We didn't win any duels in the first half."
It was a startling opening from an LAFC team that had just set a club record with its 13th clean sheet against the New York Red Bulls on Wednesday. Five days later, the Black & Gold were repeatedly exposed by a Sporting attack that had been among the league's least productive.
#first #half


2 days ago
ATLANTA — Josh Heupel and Faizon Brandon can rely on Tennessee's defense to carry it through some rough patches — at least to a certain point.
That was apparent in the way the 18th-ranked Vols beat Georgia Tech 45-24 amid a crowd with plenty of orange at Bobby Dodd Stadium on Sept. 12.
Heupel's offense didn't have to light up the scoreboard or stat sheet to win. And Brandon, the freshman quarterback, didn't have to reel off eye-popping highlights for the Vols (2-0) to protect a lead on the road over the Yellow Jackets (0-2).
They just needed to do enough and trust in Jim Knowles, the defensive wiz that Heupel hired as coordinator in the offseason. His squad carried the Vols through some critical lulls.
Knowles' defense scored a touchdown on Dejuan Lane's pick-6. It had another red-zone stop that yielded only a field goal. Jeremiah Telander's interception prevented points before halftime. And the Vols stopped Georgia Tech's rally on fourth down at the goal line early in the fourth quarter.
#vols #georgia #didn 't
That was apparent in the way the 18th-ranked Vols beat Georgia Tech 45-24 amid a crowd with plenty of orange at Bobby Dodd Stadium on Sept. 12.
Heupel's offense didn't have to light up the scoreboard or stat sheet to win. And Brandon, the freshman quarterback, didn't have to reel off eye-popping highlights for the Vols (2-0) to protect a lead on the road over the Yellow Jackets (0-2).
They just needed to do enough and trust in Jim Knowles, the defensive wiz that Heupel hired as coordinator in the offseason. His squad carried the Vols through some critical lulls.
Knowles' defense scored a touchdown on Dejuan Lane's pick-6. It had another red-zone stop that yielded only a field goal. Jeremiah Telander's interception prevented points before halftime. And the Vols stopped Georgia Tech's rally on fourth down at the goal line early in the fourth quarter.
#vols #georgia #didn 't

2 days ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company

2 days ago
Dave Ramsey told caller Hazel her secret teen payments aren't a money problem but a marriage problem requiring full financial transparency and counseling.
Secret spending makes joint wealth-building impossible. Hiding $400 monthly from a spouse means losing its compounding potential in a Roth IRA or 529.
Transparency alone flips the outcome: a joint kid-support budget lets both spouses plan together, while secret contributions force decisions based on false information.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
On the September 9 episode of The Ramsey Show, a caller named Hazel admitted she has been slipping money to her three teenagers from a prior marriage, quietly, from her own account, because her husband of almost seven years refuses to help pay for their sports and school costs. Dave Ramsey did not reach for a spreadsheet. He told her: "You don't have a combining money problem and you don't have a who pays for what problem. You have a marriage problem."
#problem #secret
Secret spending makes joint wealth-building impossible. Hiding $400 monthly from a spouse means losing its compounding potential in a Roth IRA or 529.
Transparency alone flips the outcome: a joint kid-support budget lets both spouses plan together, while secret contributions force decisions based on false information.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
On the September 9 episode of The Ramsey Show, a caller named Hazel admitted she has been slipping money to her three teenagers from a prior marriage, quietly, from her own account, because her husband of almost seven years refuses to help pay for their sports and school costs. Dave Ramsey did not reach for a spreadsheet. He told her: "You don't have a combining money problem and you don't have a who pays for what problem. You have a marriage problem."
#problem #secret


2 days ago
Investors seeking exposure to artificial intelligence infrastructure must weigh the explosive growth of Astera Labs Inc (NASDAQ:ALAB) against the established scale and diverse portfolio of Marvell Technology Inc(NASDAQ:MRVL) to determine the better buy.
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million

2 days ago
High-performance computing is currently undergoing a massive generational shift. Deciding between Astera Labs Inc (NASDAQ:ALAB) and Applied Materials Inc (NASDAQ:AMAT) means choosing between a fast-growing connectivity specialist and an established ******* an of manufacturing equipment.
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ

2 days ago
Greg Abel took over as CEO of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the start of 2026. Former CEO Warren Buffett left Abel a huge gift: nearly $400 billion in cash on the company's balance sheet. Abel has put some of that cash to work buying Taylor Morrison Home, and some has been spent on publicly traded stock investments. However, Abel has also decided to buy back Berkshire Hathaway stock. That could be a positive sign. Here's why.
Under Warren Buffett, Berkshire Hathaway didn't make a habit of buying back stock. The world-famous investor preferred to put cash to work by buying shares in other companies or buying companies outright. When he did buy back Berkshire Hathaway stock, it was because he believed the shares were undervalued.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This dynamic is clearly explained in the company's 2025 10k, where the company states: "Berkshire's common stock repurchase program currently permits Berkshire to repurchase shares any time that Berkshire's Chief Executive Officer, after consultation with the Chairman of the Board, believes that the repurchase price is below Berkshire's intrinsic value, conservatively determined." The only limit on repurchase activity is that it can't reduce the company's cash and short-term investment balance below $30 billion.
Some market watchers had hypothesized that Berkshire Hathaway bought as much as $11 billion of its own stock in the second quarter, but the real number turned out to be roughly $4.5 billion. That said, the number was still quite large and, even then, given the huge cash balance the company has, it didn't put the company anywhere near the $30 billion cash limitation.
#Stock
Under Warren Buffett, Berkshire Hathaway didn't make a habit of buying back stock. The world-famous investor preferred to put cash to work by buying shares in other companies or buying companies outright. When he did buy back Berkshire Hathaway stock, it was because he believed the shares were undervalued.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This dynamic is clearly explained in the company's 2025 10k, where the company states: "Berkshire's common stock repurchase program currently permits Berkshire to repurchase shares any time that Berkshire's Chief Executive Officer, after consultation with the Chairman of the Board, believes that the repurchase price is below Berkshire's intrinsic value, conservatively determined." The only limit on repurchase activity is that it can't reduce the company's cash and short-term investment balance below $30 billion.
Some market watchers had hypothesized that Berkshire Hathaway bought as much as $11 billion of its own stock in the second quarter, but the real number turned out to be roughly $4.5 billion. That said, the number was still quite large and, even then, given the huge cash balance the company has, it didn't put the company anywhere near the $30 billion cash limitation.
#Stock

2 days ago
As artificial intelligence matures, investors must decide between the high-growth niche players and the foundational giants. Choosing between Astera Labs Inc (NASDAQ:ALAB) and Taiwan Semiconductor Manufacturing Co (NYSE:TSM) involves weighing explosive potential against established dominance.
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
2 days ago
On September 10, Piper Sandler **** yst Bill Carcache initiated coverage of Q2 Holdings, Inc. (NYSE:QTWO), giving the stock an Overweight rating and setting the price target at $82.
The research firm started coverage on companies in the payments and consumer finance group and named Q2 Holdings, Inc. (NYSE:QTWO) as its preferred name in the sector.
According to Piper Sandler, the company offers the "clearest combination" of subscription revenue growth, visibility into annual recurring revenue, and improving free cash flow conversion. The firm also highlighted the company's growing margins and debt-free balance sheet. Piper Sandler said these factors support what it sees as the clearest path toward durable growth among the payments and consumer finance group.
Q2 Holdings, Inc. (NYSE:QTWO) delivered strong financial performance in Q2 2026. The company reported revenue of $219.8 million, an increase of 13% year-over-year and 2% sequentially. GAAP gross margin improved to 59.2% from 53.6% in the prior-year quarter, while GAAP net income rose to $29.9 million from $11.8 million.
Adjusted EBITDA reached a record $62.8 million, up 37% year-over-year. The company said it delivered another quarter of consistent execution, with strong bookings across its solutions.
#year #NYSE #revenue
The research firm started coverage on companies in the payments and consumer finance group and named Q2 Holdings, Inc. (NYSE:QTWO) as its preferred name in the sector.
According to Piper Sandler, the company offers the "clearest combination" of subscription revenue growth, visibility into annual recurring revenue, and improving free cash flow conversion. The firm also highlighted the company's growing margins and debt-free balance sheet. Piper Sandler said these factors support what it sees as the clearest path toward durable growth among the payments and consumer finance group.
Q2 Holdings, Inc. (NYSE:QTWO) delivered strong financial performance in Q2 2026. The company reported revenue of $219.8 million, an increase of 13% year-over-year and 2% sequentially. GAAP gross margin improved to 59.2% from 53.6% in the prior-year quarter, while GAAP net income rose to $29.9 million from $11.8 million.
Adjusted EBITDA reached a record $62.8 million, up 37% year-over-year. The company said it delivered another quarter of consistent execution, with strong bookings across its solutions.
#year #NYSE #revenue


2 days ago
U.S. Bancorp (NYSE:USB) has raised its quarterly dividend by 3.8% to $0.54 per share. That brings the annualized payout at $2.16 and the yield at 3.5%.
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth
For income-focused investors, the increase adds to the bank's appeal. But the more important point is what supports the higher payout.
U.S. Bancorp enters the second half of 2026 on firm footing. The bank's latest results show accelerating earnings, strong loan growth, and a solid capital position.
U.S. Bancorp (NYSE:USB)'s revenue increased 10% YoY in Q2 to a record $7.7 billion. Net interest margin jumped to 2.79%, up from 2.66% a year ago. That helped push the net income attributable to the bank up 20% to $2.18 billion. Diluted EPS rose 21.6% to $1.35.
The bank's balance sheet also continued to expand. Average loans increased 7.1% to $405.5 billion, supported by strong commercial, commercial real estate and credit card lending activity. Average deposits increased 2.4% to $515.1 billion, providing low-cost funding for the loan growth.
#Growth

2 days ago
More than 30 years ago, all over the walls of a high school about an hour west of downtown San Antonio, the signs started appearing.
In breezeways, next to lockers, and around the cafeteria, the motivational slogans kept popping up, some scrawled in magic marker on poster board, and others printed out on long sheets of dot-matrix paper. They were hung by a D'Hanis baseball coach who wanted to remind students that they could win anything with the "RIGHT MENTAL ATTITUDE," and that "PRESSURE MAKES DIAMONDS," and that "WHEN THE GOING GETS TOUGH, THE TOUGH GET GOING."
A bunch of clichés, maybe, but harmless ones. The coach meant well, and his team wound up winning state.
One of his colleagues, though, was a world-class wiseacre, and couldn't resist the opportunity to poke fun. Bill Lovett coached boys basketball and taught history. And above the chalkboard in his classroom one day, there was a long dot-matrix printout bearing a slogan of his own creation.
"AN ELEPHANT IN DISGUISE IS STILL BIG," it read.
#going #tough #matrix
In breezeways, next to lockers, and around the cafeteria, the motivational slogans kept popping up, some scrawled in magic marker on poster board, and others printed out on long sheets of dot-matrix paper. They were hung by a D'Hanis baseball coach who wanted to remind students that they could win anything with the "RIGHT MENTAL ATTITUDE," and that "PRESSURE MAKES DIAMONDS," and that "WHEN THE GOING GETS TOUGH, THE TOUGH GET GOING."
A bunch of clichés, maybe, but harmless ones. The coach meant well, and his team wound up winning state.
One of his colleagues, though, was a world-class wiseacre, and couldn't resist the opportunity to poke fun. Bill Lovett coached boys basketball and taught history. And above the chalkboard in his classroom one day, there was a long dot-matrix printout bearing a slogan of his own creation.
"AN ELEPHANT IN DISGUISE IS STILL BIG," it read.
#going #tough #matrix

2 days ago
A Bahamian national who arrived in the U.S. during President Gerald Ford's administration and was living with a green card racked up a violent rap sheet before investigators found he voted illegally in the 2020 election, sparking the deportation process, officials say.
The case of Anthony Tyrone Higgs is only the latest in a slew of arrests connected to illegal votes cast in recent elections, as the Trump administration engages in a broader crackdown on election integrity-related crimes.
"This alien was a guest in our country who forfeited his right to be in the U.S. when he committed these violent crimes and voted in the 2020 election," White House spokeswoman Lauren Bis exclusively told Fox News Digital on Friday.
Ice Arrests Peruvian National Accused Of Illegally Voting In 2024 Election As Dhs Cites Similar Cases
ICE agents **** emble in Minnesota, left; Anthony Tyrone Higgs, inset right.
#national
The case of Anthony Tyrone Higgs is only the latest in a slew of arrests connected to illegal votes cast in recent elections, as the Trump administration engages in a broader crackdown on election integrity-related crimes.
"This alien was a guest in our country who forfeited his right to be in the U.S. when he committed these violent crimes and voted in the 2020 election," White House spokeswoman Lauren Bis exclusively told Fox News Digital on Friday.
Ice Arrests Peruvian National Accused Of Illegally Voting In 2024 Election As Dhs Cites Similar Cases
ICE agents **** emble in Minnesota, left; Anthony Tyrone Higgs, inset right.
#national



2 days ago
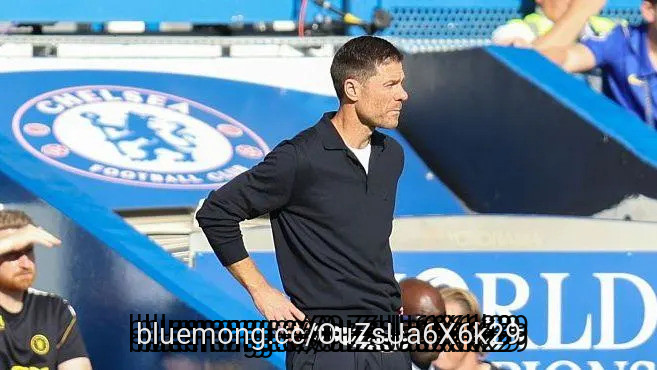
There was a subdued atmosphere at the final whistle among Chelsea's players, staff and supporters.
They had watched the team's free-flowing attacking football come unstuck against a Hull City side who had not conceded a Premier League goal before kick-off.
Chelsea had previously beaten Fulham 3-2, won 4-3 at home to Brighton and lost 2-1 at ***** nal. They also overcame Leeds 6-3 in the Carabao Cup on Wednesday.
Having conceded twice here, Chelsea have now gone 20 Premier League matches without a clean sheet, a run stretching back to January. They have also conceded two or more goals in every match against Premier League opposition under new manager Xabi Alonso.
Although Chelsea are the division's top scorers with 10 goals this season, they have also conceded nine, more than all but two other Premier League sides.
#premier #brighton
They had watched the team's free-flowing attacking football come unstuck against a Hull City side who had not conceded a Premier League goal before kick-off.
Chelsea had previously beaten Fulham 3-2, won 4-3 at home to Brighton and lost 2-1 at ***** nal. They also overcame Leeds 6-3 in the Carabao Cup on Wednesday.
Having conceded twice here, Chelsea have now gone 20 Premier League matches without a clean sheet, a run stretching back to January. They have also conceded two or more goals in every match against Premier League opposition under new manager Xabi Alonso.
Although Chelsea are the division's top scorers with 10 goals this season, they have also conceded nine, more than all but two other Premier League sides.
#premier #brighton

2 days ago
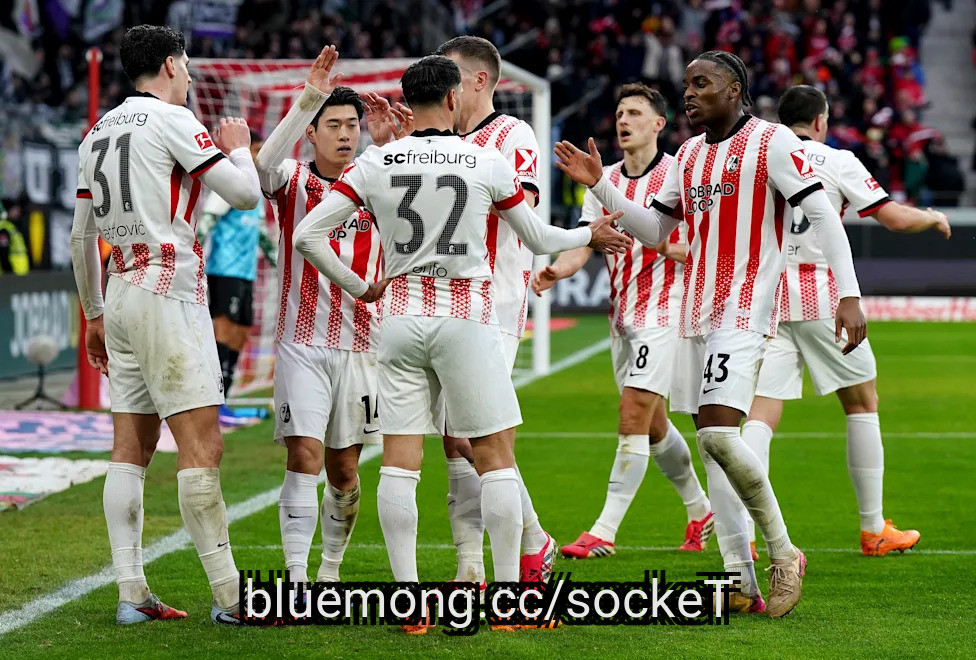
The defining topic of Saturday's football action was definitely the major crisis and nightmare start of Borussia Mönchengladbach, which was completed in brutal fashion this afternoon with a 0–5 thrashing in Breisgau.
So far, comparatively little has been said about the team that made the situation for Polanski's side even more dramatic today. Probably too little.
Because SC Freiburg currently find themselves at the opposite extreme. With three wins from three games, they sit top of the table and have enjoyed a perfect start to the new season.
The club has never before won each of its first three matches in a season.
The attack in particular has been highly impressive. In the team's six competitive matches so far this season, no fewer than eleven different players have already gotten on the scoresheet.
#start #breisgau
So far, comparatively little has been said about the team that made the situation for Polanski's side even more dramatic today. Probably too little.
Because SC Freiburg currently find themselves at the opposite extreme. With three wins from three games, they sit top of the table and have enjoyed a perfect start to the new season.
The club has never before won each of its first three matches in a season.
The attack in particular has been highly impressive. In the team's six competitive matches so far this season, no fewer than eleven different players have already gotten on the scoresheet.
#start #breisgau

2 days ago
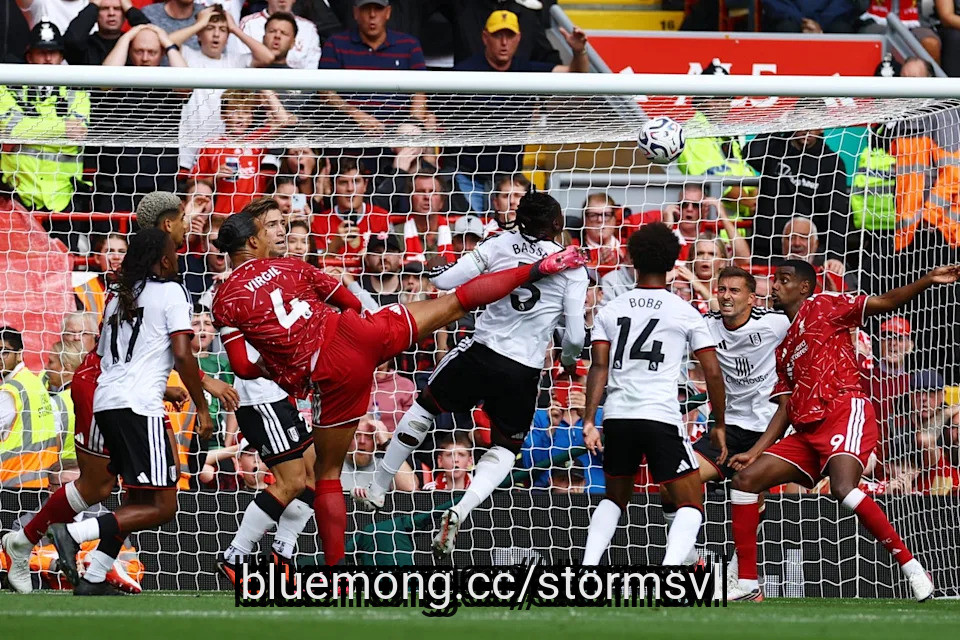
If part of the challenge for Andoni Iraola when he took the Liverpool job was mastering the art of winning Premier League games after midweek Champions League dates, he failed his first test. An Anfield afternoon against a side with the wrong sort of 100 percent record ought to have been the ideal introduction to such ******* ignments.
Instead, Fulham got their first point of the season. A Spanish manager with a playing career at right-back had much to savour; but it was Alvaro Arbeloa, not Iraola. A terrific defender under Rafa Benitez, Arbeloa contributed to many a clean sheet in his time at Liverpool. Now Fulham have a first in the Premier League in his reign. Having conceded three goals to left wing-backs against Crystal Palace last week, they conceded none to Liverpool's three £100m men.
Alvaro Arbeloa could celebrate a first point in the Premier League with Fulham (Getty)
"Happy with the point and more happy with the performance," said Arbeloa. "We were more balanced today. We defended so well." He had made the bold decision to give the Austrian centre-back David Affengruber a debut at Anfield. "He proved how good he is," Arbeloa said.
But Iraola's side delivered a disjointed display, failing to touch the heights they reached in their comeback against Atletico Madrid and failing to score for the first time under him. "What was lacking was quite clear. It is the first game we had problems to create chances and score goals," he admitted.
#first #league #point #alvaro
Instead, Fulham got their first point of the season. A Spanish manager with a playing career at right-back had much to savour; but it was Alvaro Arbeloa, not Iraola. A terrific defender under Rafa Benitez, Arbeloa contributed to many a clean sheet in his time at Liverpool. Now Fulham have a first in the Premier League in his reign. Having conceded three goals to left wing-backs against Crystal Palace last week, they conceded none to Liverpool's three £100m men.
Alvaro Arbeloa could celebrate a first point in the Premier League with Fulham (Getty)
"Happy with the point and more happy with the performance," said Arbeloa. "We were more balanced today. We defended so well." He had made the bold decision to give the Austrian centre-back David Affengruber a debut at Anfield. "He proved how good he is," Arbeloa said.
But Iraola's side delivered a disjointed display, failing to touch the heights they reached in their comeback against Atletico Madrid and failing to score for the first time under him. "What was lacking was quite clear. It is the first game we had problems to create chances and score goals," he admitted.
#first #league #point #alvaro

2 days ago
On September 3, Genesco (NYSE:GCO) reported a second quarter that should not have worked on paper. Revenue fell 3% to $530 million, yet the company nearly halved its adjusted operating loss and raised full-year earnings guidance to the top end of its range. That combination, shrinking sales alongside expanding profit, is the footwear-first strategy showing up in real numbers. Every one of the company's three brands beat internal expectations, and management says the toughest sales pressure ahead is coming from a deliberate choice rather than a weakening business.
Journeys, the company's teen-focused chain, delivered its eighth consecutive quarter of positive comparable sales, up 2%, even while lapping strong growth from a year earlier. The more interesting story sits underneath that number. The Journeys 4.0 store format, a redesigned concept built around a more elevated ***** ortment, is generating a sales lift of 25% or more wherever it opens, and the company expects roughly 180 locations, about a fifth of its fleet, running that format by year-end. That rollout, combined with fleet optimization and more efficient use of selling staff, handed Journeys 180 basis points of expense leverage in the quarter. Comparable sales kept accelerating into August, marking Journeys' ninth straight month of positive comps and a mid-single-digit gain during the back-to-school peak.
Johnston & Murphy is running its own streak, with comparable sales up 4% in its third consecutive positive quarter, helped by a newly extended, multiyear partnership with Peyton Manning and a broader shift in menswear toward more refined, put-together dressing. Companywide, adjusted gross margin expanded 140 basis points to 47.2%, and the adjusted operating loss narrowed to $8 million from $14 million a year ago. Genesco also collected $22.5 million in tariff refunds during the quarter and cut total debt to $15.8 million from $71 million a year earlier, giving a new CFO and a new Schuh president a far healthier balance sheet to work with as they settle into their roles.
The drag comes almost entirely from Schuh, Genesco's UK chain, where comparable sales fell 9% as management deliberately pulled back on discounting to protect margin. Executives were blunt about the cost of that choice. CEO Mimi Vaughn said "the UK consumer market remains challenged and price sensitive," and the Schuh turnaround is expected to take longer than the one already underway at Journeys. That pressure is now baked into guidance. Full-year total sales are expected to fall about 2%, worse than the prior forecast of down 1% to flat, with management incorporating more back-half sales pressure than it originally planned for given how promotional the UK footwear market has become.
#comparable #schuh #management #pressure
Journeys, the company's teen-focused chain, delivered its eighth consecutive quarter of positive comparable sales, up 2%, even while lapping strong growth from a year earlier. The more interesting story sits underneath that number. The Journeys 4.0 store format, a redesigned concept built around a more elevated ***** ortment, is generating a sales lift of 25% or more wherever it opens, and the company expects roughly 180 locations, about a fifth of its fleet, running that format by year-end. That rollout, combined with fleet optimization and more efficient use of selling staff, handed Journeys 180 basis points of expense leverage in the quarter. Comparable sales kept accelerating into August, marking Journeys' ninth straight month of positive comps and a mid-single-digit gain during the back-to-school peak.
Johnston & Murphy is running its own streak, with comparable sales up 4% in its third consecutive positive quarter, helped by a newly extended, multiyear partnership with Peyton Manning and a broader shift in menswear toward more refined, put-together dressing. Companywide, adjusted gross margin expanded 140 basis points to 47.2%, and the adjusted operating loss narrowed to $8 million from $14 million a year ago. Genesco also collected $22.5 million in tariff refunds during the quarter and cut total debt to $15.8 million from $71 million a year earlier, giving a new CFO and a new Schuh president a far healthier balance sheet to work with as they settle into their roles.
The drag comes almost entirely from Schuh, Genesco's UK chain, where comparable sales fell 9% as management deliberately pulled back on discounting to protect margin. Executives were blunt about the cost of that choice. CEO Mimi Vaughn said "the UK consumer market remains challenged and price sensitive," and the Schuh turnaround is expected to take longer than the one already underway at Journeys. That pressure is now baked into guidance. Full-year total sales are expected to fall about 2%, worse than the prior forecast of down 1% to flat, with management incorporating more back-half sales pressure than it originally planned for given how promotional the UK footwear market has become.
#comparable #schuh #management #pressure

2 days ago
Defending champion Lando Norris narrowly beat championship leader Kimi Antonelli to claim pole position for the Formula One Spanish Grand Prix on Saturday.
The McLaren driver topped the timesheets with the best time of 1 minute 31.824 seconds on the new Madrid circuit to take his third pole of the season.
Antonelli was just 0.011 seconds behind, while Max Verstappen of Red Bull completed the top three, 0.140 seconds off the pace.
Lewis Hamilton thought he would recover from a crash in the final practice session in style as he had provisional pole with the fastest time after the first flying laps.
But the seven-time champion was beaten by Antonelli, who then lost the top position to Norris.
#champion
The McLaren driver topped the timesheets with the best time of 1 minute 31.824 seconds on the new Madrid circuit to take his third pole of the season.
Antonelli was just 0.011 seconds behind, while Max Verstappen of Red Bull completed the top three, 0.140 seconds off the pace.
Lewis Hamilton thought he would recover from a crash in the final practice session in style as he had provisional pole with the fastest time after the first flying laps.
But the seven-time champion was beaten by Antonelli, who then lost the top position to Norris.
#champion

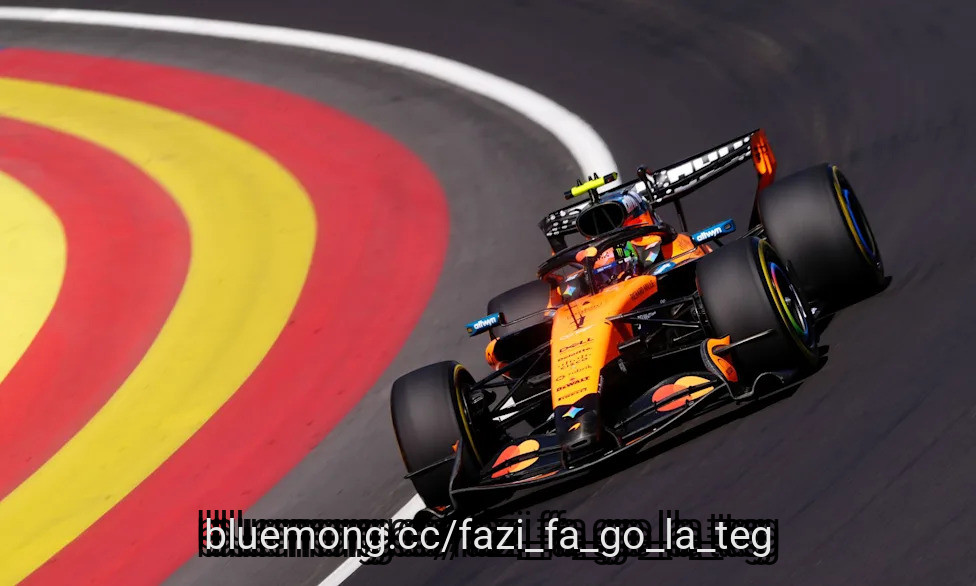

2 days ago
Chelsea welcome newly promoted Hull City to the Bridge today, though Hull have not been playing like newcomers, earning seven points from their first three games, keeping three clean sheets along the way. Can they resist our free-scoring attack? Let's hope not!
Xabi Alonso has made a couple changes to the usual early mix, with Maxence Lacroix taking a seat on the bench after starting every single game so far and Malo Gusto deployed at nominal left wing-back, at least according to the published lineup.
Here we go!
Chelsea starting lineup (3-4-2-1)
Martínez | Hato, Colwill, Fofana | Gusto, Lavia, James (c), Neto | Rogers, Palmer | João Pedro
Substitutes from: Penders, Acheampong, Lacroix, Chavarría, Barco, Quenda, Gittens, Estêvão, Welbeck
#Chelsea #lacroix #gusto
Xabi Alonso has made a couple changes to the usual early mix, with Maxence Lacroix taking a seat on the bench after starting every single game so far and Malo Gusto deployed at nominal left wing-back, at least according to the published lineup.
Here we go!
Chelsea starting lineup (3-4-2-1)
Martínez | Hato, Colwill, Fofana | Gusto, Lavia, James (c), Neto | Rogers, Palmer | João Pedro
Substitutes from: Penders, Acheampong, Lacroix, Chavarría, Barco, Quenda, Gittens, Estêvão, Welbeck
#Chelsea #lacroix #gusto
2 days ago
Diego Simeone says Atlético Madrid must improve at the back to start winning again.
Atlético have had a difficult week with Tuesday's 2-1 Champions League defeat at Liverpool following the 3-0 loss at Athletic Bilbao last weekend.
They return to La Liga action at Real Sociedad on Saturday seeking to rediscover the form that brought them seven points from their first three matches.
"We have room for improvement, but the team has done some very good things," Atlético boss Simeone said ahead of his side's trip to San Sebastián.
"We need to improve defensively to keep clean sheets and have more opportunities to improve because we've scored in every match except one.
#madrid #league #bilbao
Atlético have had a difficult week with Tuesday's 2-1 Champions League defeat at Liverpool following the 3-0 loss at Athletic Bilbao last weekend.
They return to La Liga action at Real Sociedad on Saturday seeking to rediscover the form that brought them seven points from their first three matches.
"We have room for improvement, but the team has done some very good things," Atlético boss Simeone said ahead of his side's trip to San Sebastián.
"We need to improve defensively to keep clean sheets and have more opportunities to improve because we've scored in every match except one.
#madrid #league #bilbao