2 months ago
Oracle's remaining performance obligations surged 363% to $638 billion, but $56 billion in quarterly capex pushed free cash flow deeply negative.
Jensen Huang disclosed NVIDIA can only meet 70% of current demand, while CoreWeave burned $5.7 billion in Q2 free cash flow against $104 billion in backlog.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Oracle didn't make the cut. Enter your email to see the names that beat ORCL. The report is free. Enter your email and see if any of your stocks made the cut.
OpenAI now plans to spend roughly $750 billion on compute infrastructure through 2030, a figure that represents a 25% increase from earlier 2026 estimates. The company still calls itself "really short" on capacity. That gap, between three-quarters of a trillion dollars in planned spend and a stated capacity shortfall, is the number that reframes every AI infrastructure bet on the board, starting with Oracle (NYSE:ORCL).
Oracle is the clearest public-market conduit for that OpenAI dollar. In Q4 FY26, Oracle disclosed remaining performance obligations of $638 billion, up 363% year over year, of which $75 billion is tied to prepaid or customer-supplied GPU arrangements. Cloud Infrastructure revenue reached $5.79 billion, up 93% year over year, and Oracle Multicloud AI Database grew 404% in Q4. Global GPU utilization sits at 97.5%, and management said "there's still a massively higher demand than there is supply."
#free #orcl



2 months ago
A portion of a $400,000 CCRC entrance fee qualifies as prepaid medical care, deductible on Schedule A the year you write the check.
Only itemizers qualify, and just medical costs exceeding 7.5% of AGI reduce taxable income. Standard-deduction filers get nothing.
Pairing the entrance-fee payment year with a Roth conversion or large capital gains lets the medical deduction shelter substantial income.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
If you or a parent is about to write a six-figure check to move into a continuing care retirement community (a CCRC, meaning a campus that bundles independent living, ****** isted living, and skilled nursing under one contract), stop before you sign. A meaningful slice of that entrance fee (often on a $400,000 ticket) counts as prepaid medical care under federal tax law, and it is deductible on the return for the year you pay it. You do not have to wait until you actually use the health wing. This is the CCRC entrance fee medical deduction, and it is one of the largest one-year itemized deductions a retiree will ever see.
#ccrc #care #prepaid #write


2 months ago
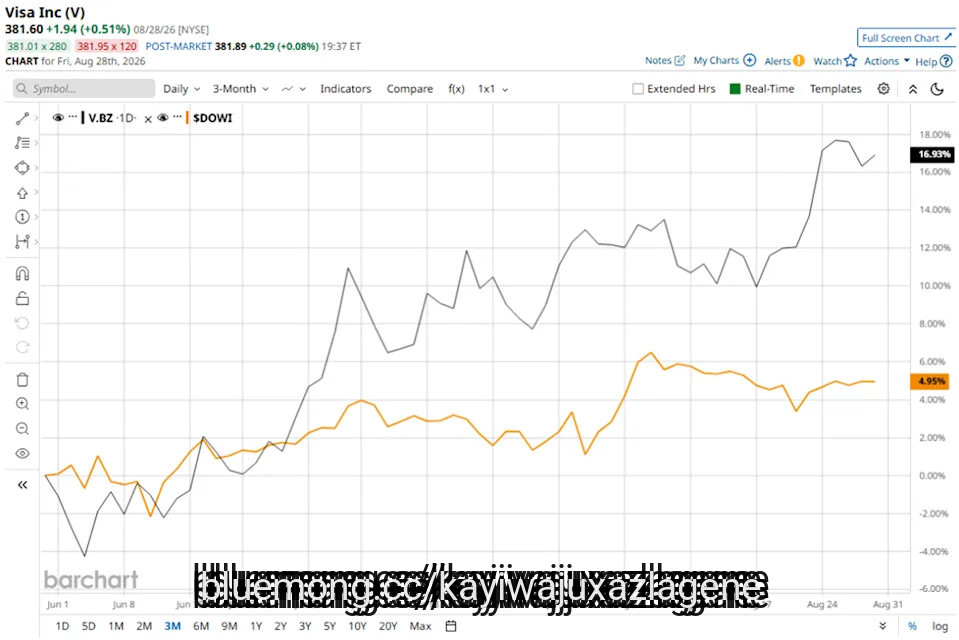
With a market cap of $680.9 billion, Visa Inc. (V) is a global payments technology company that facilitates digital transactions across more than 200 countries and territories through its secure processing network, VisaNet. The company offers a broad portfolio of products and services, including credit, debit, prepaid solutions, digital payment innovations, risk management, and data ***** ytics.
Companies worth more than $200 billion are generally labeled as "mega-cap" stocks and Visa fits this criterion perfectly. Serving financial institutions, merchants, governments, and consumers, Visa also strengthens its brand through partnerships and sponsorships with organizations such as the Olympic Games, FIFA, and the NFL.
Sandisk Stock Could Nearly Double to $3,000, According to Wall Street
Warren Buffett's Granddaughter Says He Disowned Her and Twin Sister in a Letter —'I Have Not Emotionally or Legally Adopted You as a Grandchild…'
How to Play the Post-Earnings Selloff in Marvell Technology Stock
#billion
2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Delta SkyMiles® Gold American Express Card charges a higher annual fee than other mid-tier airline cards, but the perks alone can make it worth your while. If you fly with Delta at least once or twice a year, this card should be on your radar.
Here are some of the Delta SkyMiles Gold card's more notable features:
Annual Delta flight credit: For each calendar year in which you spend $10,000, you'll receive a $200 Delta flight credit good for future travel. The credit is good for one year from the date you receive it.
Delta Stays credit: Each year, you'll get up to $100 in statement credits when you use your card to book prepaid hotels or vacation rentals through Delta Stays.
#credit #annual



2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Planning a vacation is exciting, but buying travel insurance can feel like homework. Between comparing plans, checking what your credit card already covers, and sorting through policy fine print, it's easy to get bogged down in the details before you even pack your bags.
Here's everything you need to know about how to buy travel insurance without the guesswork.
You don't need travel insurance for every trip. If you're driving two hours to visit family, a standalone policy is probably overkill. But if you're spending thousands of dollars up front — or leaving the country — travel insurance deserves a second look.
Travel insurance is most useful for protecting prepaid, nonrefundable costs and covering medical emergencies. Purchasing a policy makes the most sense if you're taking an international trip, cruise, safari, luxury tour, or any vacation where you'd lose a meaningful amount of money if you had to cancel.
#insurance #you 're #need #trip



2 months ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On August 21, 2026, Visa Inc. (NYSE:V) closed at $371.04 per share, reflecting a market capitalization of $692.74 billion. Visa Inc. (NYSE:V) posted a one‑month return of 2.35%, while its shares gained 6.37% over the past 52 weeks.
Aoris Investment Management stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor letter:
"Visa Inc. (NYSE:V) is the world's largest payment network, enabling consumers and businesses to transact with over 130 million merchants globally in a convenient and secure way. It earns 70% of its revenue by charging fixed and percentage-based fees on transactions processed over its network. The other 30% comes from a range of payment-related services that help financial institutions and merchants to reduce fraud, improve back-office efficiency, increase sales and deepen customer loyalty.
If AI agents start making purchases on behalf of consumers and businesses, which is known as agentic commerce, then Visa's secure credentials, fraud controls, acceptance, dispute resolution and trusted network rules will become increasingly important. More digital commerce usually means more transactions, which would benefit Visa's transaction-based fees. Agentic commerce may also accelerate Visa's market share gains against domestic card networks like Eftpos, many of which still aren't accepted for onl


2 months ago
Aoris Investment Management, a specialist international equity manager, released its Q2 2026 investor letter for "Aoris International Fund". A copy of the letter can be downloaded here. The fund invests in high-quality, wealth-generating businesses managed by prudent and capable teams, targeting an annual return of 8–12% after fees over a 5–7-year market cycle. During the June quarter, international equity markets, as represented by the MSCI AC World Accumulation Index ex Australia, returned 13.8% in AUD terms. In local currencies, the return 15.1%. The Portfolio's Class A (Unhedged) returned 5.7% after fees, underperforming its benchmark by 8.1%, while the Class C (Hedged) gained 6.7%, 8.4% less than its benchmark. The June quarter continued to reflect an unusual year, marked by significant share price increases among AI infrastructure companies, particularly semiconductor producers and data center suppliers. Economic sectors like banks and commodity producers saw gains, but the firm chose not to invest due to their cyclicality and low growth prospects. Conversely, concerns about enterprise software and data companies, challenged by AI, negatively impacted performance. The letter outlined potential incremental opportunities for portfolio companies through AI. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, Aoris Investment Management highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On August 21, 2026, Visa Inc. (NYSE:V) closed at $371.04 per share, reflecting a market capitalization of $692.74 billion. Visa Inc. (NYSE:V) posted a one‑month return of 2.35%, while its shares gained 6.37% over the past 52 weeks.
Aoris Investment Management stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor letter:
"Visa Inc. (NYSE:V) is the world's largest payment network, enabling consumers and businesses to transact with over 130 million merchants globally in a convenient and secure way. It earns 70% of its revenue by charging fixed and percentage-based fees on transactions processed over its network. The other 30% comes from a range of payment-related services that help financial institutions and merchants to reduce fraud, improve back-office efficiency, increase sales and deepen customer loyalty.
If AI agents start making purchases on behalf of consumers and businesses, which is known as agentic commerce, then Visa's secure credentials, fraud controls, acceptance, dispute resolution and trusted network rules will become increasingly important. More digital commerce usually means more transactions, which would benefit Visa's transaction-based fees. Agentic commerce may also accelerate Visa's market share gains against domestic card networks like Eftpos, many of which still aren't accepted for onl
In its Q2 2026 investor letter, Aoris Investment Management highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On August 21, 2026, Visa Inc. (NYSE:V) closed at $371.04 per share, reflecting a market capitalization of $692.74 billion. Visa Inc. (NYSE:V) posted a one‑month return of 2.35%, while its shares gained 6.37% over the past 52 weeks.
Aoris Investment Management stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor letter:
"Visa Inc. (NYSE:V) is the world's largest payment network, enabling consumers and businesses to transact with over 130 million merchants globally in a convenient and secure way. It earns 70% of its revenue by charging fixed and percentage-based fees on transactions processed over its network. The other 30% comes from a range of payment-related services that help financial institutions and merchants to reduce fraud, improve back-office efficiency, increase sales and deepen customer loyalty.
If AI agents start making purchases on behalf of consumers and businesses, which is known as agentic commerce, then Visa's secure credentials, fraud controls, acceptance, dispute resolution and trusted network rules will become increasingly important. More digital commerce usually means more transactions, which would benefit Visa's transaction-based fees. Agentic commerce may also accelerate Visa's market share gains against domestic card networks like Eftpos, many of which still aren't accepted for onl


2 months ago
On August 6, Petrobras (NYSE:PBR) held its second-quarter 2026 earnings webcast, reporting strong quarterly net profit and gross profit driven by record production volumes rather than peak Brent prices. Executives said the quarter delivered the highest recurring net profit and the highest gross profit in company history, even though oil prices in the period ranked outside the ten highest quarters Petrobras has ever posted. That distinction matters, because it points to something more durable than a commodity tailwind: production that keeps beating its own targets.
Petrobras pumped 2.7 million barrels of oil per day in the quarter, a 15% jump from a year earlier and 200,000 barrels per day above its own 2.5 million target. Several platforms are doing more than they were built for. The Almirante Tamandare FPSO at Buzios has a nameplate capacity of 225,000 barrels per day but hit a peak of 270,000, making it the highest-producing platform in Brazil. Six other platforms are running above their original capacity too, adding more than 100,000 barrels per day combined, output the company says required no new construction spending.
Refining kept pace. Utilization topped 100% for the quarter and hit 102% in April and May, while the company held its mix of diesel, jet fuel, and gasoline steady rather than shifting toward cheaper output. That let Petrobras cut oil product imports by 40% from the prior quarter and lift exports by 12%. Adjusted EBITDA, excluding one-off items, reached $20 billion, up 70% from the first quarter and nearly double a year earlier, while operating cash flow climbed almost 50% quarter-over-quarter to $12.3 billion.
Growth this fast isn't free. Petrobras spent $5.3 billion on capital projects in the quarter, up 4% from the first quarter's $5.1 billion, with 82% of that aimed at exploration and production. First-half operating expenses reached $11.7 billion, already more than half the full-year plan of $20.2 billion, pressured by freight and logistics costs tied to the added output plus exchange-rate swings. Management said expenses could exceed that plan if logistics costs and the exchange rate hold at current levels.
Debt tells a mixed story. Petrobras prepaid $2.9 billion in loans and bonds during the quarter and is targeting $65 billion in net debt over its plan horizon, versus the $60.4 billion net debt and $70.8 billion gross debt it reported. But renegotiating recharter and well-service contracts to save over $1 billion through 2030 required reorganizing lease liabilities right away, pushing them higher near-term even as future payments shrink. And despite record output, Petrobras still needs imports to fully cover diesel demand.
#debt #highest #barrels #first

3 months ago
Wall Street has been fretting over a potential AI bubble burst and whether huge AI spending by companies would ever pay off. But Cathie Wood is doubling down. Ark recently bought 80,000 shares of Nvidia (NASDAQ:NVDA) across five funds. Ark also decreased its stake in Roblox (NYSE: RBLX).
Nvidia bears say AI infrastructure spending is running too hot and will eventually slow. That will directly impact Nvidia as its GPU sales will slow down.
Bulls say that fear misses the point. Nvidia's data center networking revenue jumped nearly 200% year over year last quarter. That shows Nvidia is capturing value beyond the GPU itself, through racks, interconnects, and software. Roughly half of data center revenue now comes from AI cloud, industrial, enterprise, and sovereign customers rather than the handful of hyperscalers everyone watches closely. Combined, Meta, Amazon, Microsoft, and Alphabet plan to spend up to $725 billion this year, up 77% year over year, and Nvidia is positioned to capture 35% to 40% of that.
The bear case is about the balance sheet, not the growth rate. Nvidia's inventories more than doubled year over year, and prepaid expenses grew over 40%, as the company locks up more supply commitments to protect delivery timelines. Three customers make up 30%, 18%, and 16% of Nvidia's accounts receivable, so any shift by a major buyer toward custom chips would hit hard. Non-marketable securities, mostly stakes in AI startups and infrastructure partners, now make up 17% of Nvidia's total ****** ets.
Cathie Wood of ARK Investment Management
#year #NVIDIA #spending #infrastructure


3 months ago
Montaka Global Investments, an investment management company, released its second-quarter 2026 investor letter. A copy of the update is available to download here. Montaka manages a concentrated portfolio of high–conviction, long-term, competitively advantaged businesses bought when prices are attractive. While it delivered positive returns in the June quarter, its 12-month performance was largely negative due to declines in the March quarter amid the 'SaaSpocalypse', yet the underlying businesses performed well. Montaka's strategy focuses on owning businesses that grow earnings in large markets, which struggled against short-term bottleneck trades that gained popularity. However, Montaka aims for long-term excess returns above market indices, anticipating that current mispricing will eventually correct. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Montaka Global Investments highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On July 22, 2026, Visa Inc. (NYSE:V) closed at $353.42 per share. One-month return of Visa Inc. (NYSE:V) was 5.95%, and its shares lost 1.07% over the past 52 weeks. Visa Inc. (NYSE:V) has a market capitalization of $665.89 billion.
Montaka Global Investments stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor update:
"On the other side of the market are some of the world's highest quality businesses which have been overlooked during the semiconductor–mania.
Take Visa Inc. (NYSE:V) and Mastercard, for example. Both are extraordinarily advantaged businesses and have consistently grown annual revenues at double–digit percentage rates for many years. And in our view, strong growth will likely continue – driven by new value–added services attached to their payment networks (related to stablecoins, agentic commerce, fraud detection, and other data services) which are growing at even faster rates.
#NYSE #Services #quarter #investor


3 months ago
Dodge & ****** Fund, an investment management company, released its second-quarter 2026 investor letter for "Dodge and ****** Stock Fund". A copy of the letter can be downloaded here. Despite volatile oil prices and rising inflation, U.S. equities reached record highs in Q2 2026, driven by a technology-led rally, particularly in memory semiconductors. The Fund's Class A shares returned 5.57%, underperforming the S&P 500 Index's 15.20% return and the Russell 1000 Value Index's 13.84% gain, mainly due to underweighting in Information Technology and weak performances from several holdings. Concerns over AI disruption negatively impacted companies with strong franchises. The Fund's bottom-up investment approach allowed it to acquire shares in industry leaders with strong long-term fundamentals. The firm believes that increased exposure to high-quality businesses and a diversified portfolio positions the Fund well for future growth. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Dodge and ****** Stock Fund highlighted its new purchase, Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On July 21, 2026, Visa Inc. (NYSE:V) closed at $355.82 per share. One-month return of Visa Inc. (NYSE:V) was 7.10%, and its shares gained 0.15% over the past 52 weeks. Visa Inc. (NYSE:V) has a market capitalization of $676.68 billion.
Dodge and ****** Stock Fund stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor update:
"During the second quarter, concerns about AI disruption led to declines in a number of companies with strong franchises and solid profitability. Our bottom-up approach led us to establish several new positions in industry leaders whose shares have lagged, and where we believe the long-term fundamentals are not fully reflected in their current prices. We initiated a position in Visa, a leader in global payments, an industry characterized by strong network effects and high barriers to entry.
Visa Inc. (NYSE:V) is expanding beyond transaction processing into fraud prevention, data ****** ytics, and digital commerce. We believe the shares are undervalued at less than 24 times forward earnings, a price that reflects investor concerns over potential regulatory headwinds, including proposed caps on credit card interest rates and fees. Given Visa's high operating margins, strong free cash flow, and growth opportunities beyond its core business, we believe investors are underestimating the durability of its competitive advantages."
#NYSE #shares #strong #concerns


3 months ago
Dodge & ******* Fund, an investment management company, released its second-quarter 2026 investor letter for "Dodge and ******* Stock Fund". A copy of the letter can be downloaded here. Despite volatile oil prices and rising inflation, U.S. equities reached record highs in Q2 2026, driven by a technology-led rally, particularly in memory semiconductors. The Fund's Class A shares returned 5.57%, underperforming the S&P 500 Index's 15.20% return and the Russell 1000 Value Index's 13.84% gain, mainly due to underweighting in Information Technology and weak performances from several holdings. Concerns over AI disruption negatively impacted companies with strong franchises. The Fund's bottom-up investment approach allowed it to acquire shares in industry leaders with strong long-term fundamentals. The firm believes that increased exposure to high-quality businesses and a diversified portfolio positions the Fund well for future growth. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Dodge and ******* Stock Fund highlighted its new purchase, Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On July 21, 2026, Visa Inc. (NYSE:V) closed at $355.82 per share. One-month return of Visa Inc. (NYSE:V) was 7.10%, and its shares gained 0.15% over the past 52 weeks. Visa Inc. (NYSE:V) has a market capitalization of $676.68 billion.
Dodge and ******* Stock Fund stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor update:
"During the second quarter, concerns about AI disruption led to declines in a number of companies with strong franchises and solid profitability. Our bottom-up approach led us to establish several new positions in industry leaders whose shares have lagged, and where we believe the long-term fundamentals are not fully reflected in their current prices. We initiated a position in Visa, a leader in global payments, an industry characterized by strong network effects and high barriers to entry.
Visa Inc. (NYSE:V) is expanding beyond transaction processing into fraud prevention, data ******* ytics, and digital commerce. We believe the shares are undervalued at less than 24 times forward earnings, a price that reflects investor concerns over potential regulatory headwinds, including proposed caps on credit card interest rates and fees. Given Visa's high operating margins, strong free cash flow, and growth opportunities beyond its core business, we believe investors are underestimating the durability of its competitive advantages."
#Visa #strong #technology


3 months ago
With a market cap of $23.9 billion, Corpay, Inc. (CPAY) is a global payments company that provides businesses and consumers with solutions to manage and pay expenses through services such as corporate payments, vehicle payments, lodging payments, and prepaid cards. It serves a wide range of customers by offering fuel and fleet solutions, cross-border and virtual payments, travel and lodging management, and workforce payment services.
The Atlanta, Georgia-based company is set to announce its fiscal Q2 2026 results soon. Ahead of this event, ***** ysts expect Corpay to report a profit of $6.17 per share, up 28.3% from $4.81 per share in the year-ago quarter. It has surpassed Wall Street's earnings estimates in each of the last four quarters.
Alibaba Stock Just Got Apple's Biggest AI Endorsement. This Could Be a Game Changer for BABA.
Elon Musk Says If ***** eX Accomplishes Its Goals, 'It Will Be Worth More Than The Rest of Earth' — Though He's Also Said 'Money Will Stop Being Relevant'
AI Bubble Fears, Earnings and Other Can't Miss Items this Week
#corpay #earnings #company #solutions
3 months ago
Taysha Gene Therapies Inc. (NASDAQ:TSHA) is one of the 10 affordable biotech stocks to buy right now.
On June 24, Taysha Gene Therapies Inc. (NASDAQ:TSHA) disclosed the pricing of an underwritten public offering of 32.5 million of its common stock, priced at $6 per share. The offering also involved prepaid warrants to buy 833,333 shares at $5.999 per warrant.
Pixabay/Public domain
The company anticipates gross proceeds of around $200 million before accounting for underwriting commissions, discounts, and expenses, not including any underwriters' option exercise. The company has granted the underwriters a 30-day option to buy up to an additional 5 million common shares.
On June 23, Bank of America Securities increased its target price on Taysha Gene Therapies Inc. (NASDAQ:TSHA) from $9 to $10, leading to an adjusted upside potential of more than 57%. The firm maintained a Buy rating on the stock following the company's update regarding the Part A REVEAL study to evaluate TSHA-102 in Rett syndrome.


4 months ago
T-Mobile US Inc. (NASDAQ:TMUS) is one of the best QQQ Stocks to invest in. On July 7, T-Mobile announced a major evolution of its executive leadership team to accelerate its expansion into new business areas, including AI and 6G development. Wireless industry veteran Chris Sambar will join the company as Chief Enterprise Officer by mid-October, where he will lead the expansion of T-Mobile's SMB, enterprise, and government portfolios while scaling emerging growth opportunities like T-Ads and Physical AI.
Concurrently, André Almeida has been promoted to the expanded role of Chief Marketing, Brand, and Broadband Officer, where he will partner with COO Jon Freier to focus on consumer wireless and broadband growth. Additionally, T-Mobile is consolidating its network, technology, product engineering, and cyber divisions under Chief Technology Officer Dr. John Saw to facilitate the seamless delivery of next-generation connected experiences.
Kappri/Shutterstock.com
These leadership changes coincide with the departure of Mike Katz, the company's Chief Business & Product Officer, who will transition into a strategic advisory role through the end of 2026. CEO Srini Gopalan emphasized that these appointments are intended to provide the focus and expertise necessary to maintain T-Mobile's momentum, disrupt traditional industry models, and achieve the ambitious growth goals outlined in the company's recent capital markets updates.
T-Mobile US Inc. (NASDAQ:TMUS) is a telecom services company that offers wireless communications services, such as voice, messaging, and data, to postpaid, prepaid, and wholesale customers. The company also deals in wireless devices.

4 months ago
Vltava Fund, a value-focused investment management company, published its investor letter for the second quarter of 2026. A copy of the letter can be downloaded here. The letter explores the growing role of AI and how certain facets of human intelligence may become less valuable economically, while other skills become more important. The author emphasizes that despite AI's expanding capabilities in information collection and basic modeling, qualities like sound judgment, good taste, patience, original thinking, strategic skepticism, and the ability to recognize significance will continue to hold their value. Despite the excitement around A.I., fundamental investment principles remain unchanged. Please review the Fund's top five holdings to gain insights into their key selections for 2026.
In its second-quarter 2026 investor letter, Vltava Fund highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On July 2, 2026, Visa Inc. (NYSE:V) closed at $351.08 per share. One-month return of Visa Inc. (NYSE:V) was 11.92%, and its shares gained 0.91% over the past 52 weeks. Visa Inc. (NYSE:V) has a market capitalization of $688.68 billion.
Vltava Fund stated the following regarding Visa Inc. (NYSE:V) in its Q2 2026 investor letter:
"We bought shares in Visa Inc. (NYSE:V) and Kaspi.kz. Visa probably needs little introduction. Nevertheless, I'll describe the company briefly, as people are often surprised by just how complex and sophisticated its business is. Visa is not a "card company" in the simple sense of the word. It is a global technology infrastructure for electronic payments that connects banks, merchants, consumers, payments processors, governments, and companies. Its main role is to ensure that payments between two parties are processed quickly, securely, reliably, and with minimal risk without regard to the country, currency, bank, card type, or sales channel involved.
The sophistication of Visa's business lies in the fact that it is not just about forwarding the payment itself. Visa operates an extensive payment network full of rules, technologies, and security standards. It also handles transaction authorization, fraud prevention, settlement, tokenization, data ***** ytics, and risk management. Every payment looks simple to the customer. A person taps with a card or clicks in an online store, but behind all of this lies a highly complex system coordinating among many participants in the financial ecosystem…" (Click here to read the full text)


4 months ago
T-Mobile US, Inc. (NASDAQ:TMUS) has declined roughly 10% over the past 30 days, mainly due to competitive pressure from ***** eX's Starlink push in mobile services. However, ***** ysts project roughly 42% upside from the current level, driven by the company's aggressive 5G monetization. T-Mobile US, Inc. (NASDAQ:TMUS) ranks as one of the Top Large Cap Stocks to Invest In At 52-Week Lows.
Recently, on June 26, Reuters reported that ***** eX has told investors it is planning to launch a direct retail mobile service for US consumers under the Starlink brand. This will place the company in direct competition with T-Mobile, Verizon, and AT&T.
The report noted that ***** eX President Gwynne Shotwell, during the IPO roadshow, reportedly disclosed that the company is considering building its own terrestrial US mobile network. This goes well beyond the company's current partnership with T-Mobile, which only provides supplemental satellite coverage in remote areas. Moreover, the move is supported by significant spectrum acquisitions. The company purchased wireless spectrum licenses from EchoStar in two deals totaling around $17 billion, giving it the airwaves needed to offer a robust and affordable direct-to-cell service.
Recently, TD Cowen ***** yst Gregory Williams floated the idea that ***** eX could eventually look to acquire T-Mobile as part of its ambition to build a full-scale wireless and broadband platform. He noted that Starlink is no longer just a satellite internet service and aims to become a comprehensive connectivity network spanning broadband, mobile, and a hybrid of satellite and ground-based wireless infrastructure. To achieve that, ***** eX would likely need a wholesale network agreement with a major US carrier such as T-Mobile.
T-Mobile US Inc. (NASDAQ:TMUS) is a telecom services company that offers wireless communications services, such as voice, messaging, and data, to postpaid, prepaid, and wholesale customers. The company also deals in wireless devices.

4 months ago
More than half a million Americans are currently waiting for the IRS to resolve their tax identity theft cases — and the agency is taking roughly 20 months to close them, according to a new report from the federal government's internal tax watchdog.
The findings come from a recent report published by the National Taxpayer Advocate. The report calls the delays "unconscionable" and warns that the backlog is growing, not shrinking — even as the problem of tax-related identity theft worsens nationwide (1).
"For many low- and middle-income taxpayers, waiting nearly two years for a refund is not merely an inconvenience — it can mean falling behind on rent, utilities, transportation costs, and other basic living expenses," National Taxpayer Advocate Erin Collins wrote in the report (1).
Tax-related identity theft occurs when a criminal uses a stolen Social Security number to file a fraudulent tax return and claim a refund before the real taxpayer has a chance to file their own return.
In 2025, the FBI's Internet Crime Complaint Center reported receiving more than 1,000 complaints about this type of crime in one year alone — a 26% jump from the prior year. Stolen refunds are typically redirected to bank accounts, prepaid debit cards or mail drops controlled by the criminals (2).


4 months ago
América Móvil, S.A.B. de C.V. (NYSE:AMX) is one of the best low volatility stocks to buy under $50. Scotiabank cut the price target on América Móvil, S.A.B. de C.V. (NYSE:AMX) to $20.80 from $21.80 on May 27 and maintained a Sector Perform rating on the shares, telling investors that the firm updated its price targets for LatAm Telecom stocks under its coverage. It further stated that the global risk premium for holding stocks versus bonds has diminished, and the LatAm telecom sector is no exception.
For reference, in its financial results for fiscal Q1 2026, América Móvil, S.A.B. de C.V. (NYSE:AMX) reported that it added 3.0 million wireless subscribers in the quarter, all of them postpaid, having disconnected 90 thousand prepaid subscribers. Mobile service revenue growth for the quarter reached 6.4% year-on-year, with prepaid revenue expanding 5.0% and postpaid revenue 7.3%. It added that fiscal Q1 revenue was 2.1% higher than a year ago in Mexican peso terms, to 237 billion Mexican pesos.
América Móvil, S.A.B. de C.V. (NYSE:AMX) is involved in the provision of telecommunications services. The company's operations are divided into the following segments: Mexico Wireless, Mexico Fixed, Brazil, Colombia, Southern Cone (Argentina, Chile, Paraguay and Uruguay), Andean Region (Ecuador and Peru), Central America (Costa Rica, El Salvador, Guatemala, Honduras, Nicaragua and Panama), the Caribbean (the Dominican Republic and Puerto Rico) and Europe (Austria, Belarus, Bulgaria, Croatia, Macedonia, Serbia and Slovenia).
While we acknowledge the potential of AMX as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.


4 months ago
Visa Inc. (NYSE:V) is one of the safe stocks for beginners to buy in 2026. Visa Inc. (NYSE:V) announced on June 25 the launch of Visa Destinations in 10 major locations across the globe. Visa Destinations is a "passion-led travel platform" and is a move forward in the company's attempt to redefine its role in the rapidly growing experience-driven travel economy.
Management stated that the initiative marks a strategic expansion of the company's role, extending beyond payments, and positions it at the center of how trips are planned, discovered, and experienced by travelers. It added that according to Visa research, an increase can be observed in travelers choosing destinations based on experiences, purpose, and passion, instead of just geography. Visa Inc. (NYSE:V) stated that in 2025 alone, 4 in 10 American travelers made a trip to experience music, art festivals, or sports, with major cultural moments attracting international visitors and acting as catalysts for local economies.
Visa Inc. (NYSE:V) provides digital payment services. It offers credit cards, debit cards, prepaid products, global automated teller machines, and commercial payment solutions.
While we acknowledge the potential of V as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 15 Stocks That Will Make You Rich in 10 Years AND 12 Best Stocks That Will Always Grow.


4 months ago
Grow Funds, an investment Advisor, released its Q1 2026 investor letter for "GROW Small Cap Equity Long/Short Fund". A copy of the letter can be downloaded here. In Q1 2026, GROW Small Cap Equity Long/Short L.P (Fund) returned 4.18%, outperforming the Russell 2000 Growth Index's –2.80%, HFRI Equity Hedge Index's -0.24%, and the HFRI Fundamental Growth Index's 0.47% returns. Long positions and hedges, and short positions, safeguarded the portfolio amid the volatility driven by the Iran War. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its first-quarter 2026 investor letter, Grow Funds highlighted Paysign, Inc. (NASDAQ:PAYS). Paysign, Inc. (NASDAQ:PAYS) is a financial technology company specializes in prepaid card programs, patient affordability offerings, digital banking, life science software technology solutions, and integrated payment processing services. On June 18, 2026, Paysign, Inc. (NASDAQ:PAYS) closed at $7.40 per share. One-month return of Paysign, Inc. (NASDAQ:PAYS) was 10.12%, and its shares gained 35.78% over the past 52 weeks. Paysign, Inc. (NASDAQ:PAYS) has a market capitalization of $413.70 million.
Grow Funds stated the following regarding Paysign, Inc. (NASDAQ:PAYS) in its Q1 2026 investor letter:
"Paysign, Inc. (NASDAQ:PAYS) operates a vertically integrated prepaid card payment solutions and processing business, primarily serving the pharmaceutical and healthcare sectors. The company manages the entire prepaid card lifecycle—design, issuance, and processing—generating revenue through transaction fees, cardholder fees, program management fees, and funds breakage. Paysign stock had underperformed significantly in January and February due to AI fears and pharmaceutical disruption from the Trump Administration. On March 24th, PAYS reported their Q4 2025 Earnings which proved these fears to be overblown. They beat expectations significantly on the top and bottom lines as well as raised guidance for 2026. The stock remains inexpensive at 7x EV/EBITDA while growing revenues 40% last year. We believe this trajectory can continue as management executes. With their excess cashflow, we believe PAYS could begin paying a dividend or buying back shares to return capital to shareholders."
Paysign, Inc. (NASDAQ:PAYS) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 14 hedge fund portfolios held Paysign, Inc. (NASDAQ:PAYS) at the end of the first quarter, compared to 18 in the previous quarter. In Q1 2026, Paysign, Inc.'s (NASDAQ:PAYS) revenue grew 50.8% to $28 million. While we acknowledge the potential of Paysign, Inc. (NASDAQ:PAYS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock

4 months ago
Greenskeeper **** et Management, an independent firm that specializes in disciplined value investing, recently released its Q1 2026 scorecard. A copy is available to download here. The Middle East conflict triggered a sharp stock sell-off in the market, resulting in the Greenskeeper Value Fund posting a -8.1% return in Q1. Despite this challenging quarter, the fund took the opportunity to reinforce its portfolio. Please review the Fund's top five holdings to gain insights into their key selections for 2026.
In its first-quarter 2026 investor letter, Greenskeeper **** et Management highlighted Visa Inc. (NYSE:V). Visa Inc. (NYSE:V) is a multinational financial services company known for its payment technology network that offers credit, debit, and prepaid card products and other services. On June 12, 2026, Visa Inc. (NYSE:V) closed at $322.39 per share. One-month return of Visa Inc. (NYSE:V) was -3.08%, and its shares lost 9.31% over the past 52 weeks. Visa Inc. (NYSE:V) has a market capitalization of $613.10 billion.
Greenskeeper **** et Management stated the following regarding Visa Inc. (NYSE:V) in its Q1 2026 investor letter:
"Our second-worst performer in the quarter was Visa Inc. (NYSE:V) -13.8%. Visa's fundamentals remain exceptional, with 2025 global payment volumes rising 8% and driving double-digit growth in both revenue and earnings. However, the stock has been pressured by macro concerns, specifically the risk of a global slowdown and rising oil prices stemming from the conflict in the Middle East. Higher fuel costs typically dampen cross-border travel—one of Visa's highest-margin revenue streams. Despite these near-term headwinds, Visa remains one of the highest-quality businesses we have ever encountered. We remain confident that its long-term earnings power will compound at attractive rates for many, many years."
Visa Inc. (NYSE:V) ranks 9th on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 181 hedge fund portfolios held Visa Inc. (NYSE:V) at the end of the first quarter, compared to 184 in the previous quarter. In the second quarter of fiscal 2026, Visa Inc.'s (NYSE:V) net revenue grew 17% year-over-year to $11.2 billion and EPS increased 20%. While we acknowledge the potential of Visa Inc. (NYSE:V) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.

5 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Travel insurance can save your budget when a covered emergency ruins a trip. But standard trip cancellation benefits come with a catch: Your reason has to be on the policy’s approved list.
Cancel for any reason travel insurance (CFAR) gives you more wiggle room than a standard plan does. CFAR won’t refund everything, and it isn’t cheap — but if you’re planning an expensive trip, it could be the difference between losing your entire prepaid costs and recouping a portion of your money.
Here’s everything you need to know.
Cancel for any reason travel insurance is an optional upgrade that gives you more flexibility to cancel your trip.