12 days ago
The Chargers returned from their Week 7 bye with offensive coordinator Mike McDaniel addressing the media Thursday, giving a look at the work to get the offense on track ahead of Sunday's matchup with the Rams.
McDaniel did extensive film work with quarterback Justin Herbert. He said they watched "probably 4 hours" of tape together and called it "a very healthy experience." He stressed their strong relationship and a constructive approach to the struggles.
"There's a healthy way to be accountable, so you're not misdirecting blame to yourself when things aren't working," McDaniel said.
The Chargers remain the NFL's only winless team at 0-6, with the offense ranking last in points per game (15.0) after a season-low six points in the Week 6 loss to the Chiefs. Harbaugh confirmed Wednesday that McDaniel would keep the call sheet, stating, "We're very confident in Mike and his talent, his work ethic and his ability. We continue to be."
Herbert also recently backed his coordinator. On Wednesday, he said the issues are "not his fault, it's our fault as an offense," adding that "the guys are open" and "plays are being made," while stressing the need for better execution.
#chargers #week
McDaniel did extensive film work with quarterback Justin Herbert. He said they watched "probably 4 hours" of tape together and called it "a very healthy experience." He stressed their strong relationship and a constructive approach to the struggles.
"There's a healthy way to be accountable, so you're not misdirecting blame to yourself when things aren't working," McDaniel said.
The Chargers remain the NFL's only winless team at 0-6, with the offense ranking last in points per game (15.0) after a season-low six points in the Week 6 loss to the Chiefs. Harbaugh confirmed Wednesday that McDaniel would keep the call sheet, stating, "We're very confident in Mike and his talent, his work ethic and his ability. We continue to be."
Herbert also recently backed his coordinator. On Wednesday, he said the issues are "not his fault, it's our fault as an offense," adding that "the guys are open" and "plays are being made," while stressing the need for better execution.
#chargers #week

2 months ago
Space Exploration Technologies Corp. (NASDAQ:SPCX) is increasingly confident it can reach a $100 billion annual revenue run rate by year-end. The company's CFO said there is now "even more conviction" around the target. A new AI hosting agreement worth $13 billion on an annualized basis adds significant support to that outlook and reflects how quickly ***** eX's compute business is scaling. But the financial picture behind that growth is less straightforward. The same AI division that management is relying on to help reach that target posted a $1.3 billion loss in the latest quarter alone. The loss wiped out what would have otherwise been a profitable quarter, while the company generated roughly negative $25 billion in free cash flow during the first half of 2026.
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly

2 months ago
With a market cap of $18.8 billion, Zimmer Biomet Holdings, Inc. (ZBH) is a global medical technology company specializing in musculoskeletal healthcare solutions. The company designs, manufactures, and markets products ranging from orthopedic reconstructive implants to sports medicine, spine, craniomaxillofacial, and thoracic solutions.
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and Zimmer Biomet fits this criterion perfectly. Its innovations support surgeons and healthcare providers worldwide in treating disorders and injuries of bones, joints, and soft tissues.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#Stock
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and Zimmer Biomet fits this criterion perfectly. Its innovations support surgeons and healthcare providers worldwide in treating disorders and injuries of bones, joints, and soft tissues.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#Stock


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor

2 months ago
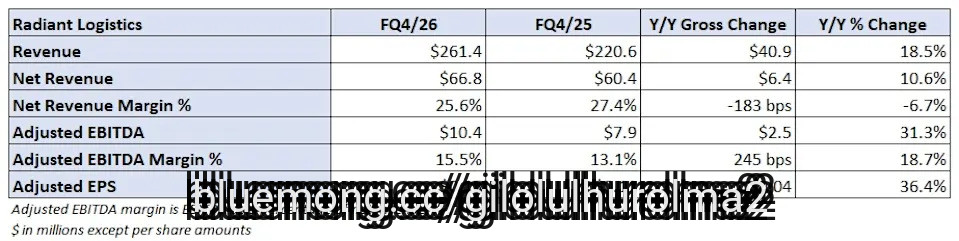
Third-party logistics provider Radiant Logistics beat fiscal fourth-quarter expectations Monday after the market closed. A volatile trade landscape is driving demand higher for its customs brokerage and compliance services. It also flagged further tightening in the domestic truckload and intermodal markets, which will propel financial results over time.
"While these market trends are not fully reflected in our results for the June quarter, we view these developments as constructive for our domestic operations in general and our U.S. Brokerage operations, in particular," said Bohn Crain, founder and CEO, in a news release. "If these trends continue, we believe they support a more broad-based and durable recovery for the domestic freight market."
The report sent shares of RLGT 16% higher in early trading on Tuesday versus the S&P 500, which was down 0.2%.
The Renton, Washington-based company reported revenue of $261 million for its fiscal fourth quarter, ended June 30. The result was 19% higher year over year and $30 million ahead of the consensus estimate.
Adjusted earnings per share of 15 cents ($7.4 million) were 4 cents higher y/y and 6 cents ahead of consensus. Disaster relief shipments following typhoons in the Western Pacific drove international airfreight results higher in the period.
#june
"While these market trends are not fully reflected in our results for the June quarter, we view these developments as constructive for our domestic operations in general and our U.S. Brokerage operations, in particular," said Bohn Crain, founder and CEO, in a news release. "If these trends continue, we believe they support a more broad-based and durable recovery for the domestic freight market."
The report sent shares of RLGT 16% higher in early trading on Tuesday versus the S&P 500, which was down 0.2%.
The Renton, Washington-based company reported revenue of $261 million for its fiscal fourth quarter, ended June 30. The result was 19% higher year over year and $30 million ahead of the consensus estimate.
Adjusted earnings per share of 15 cents ($7.4 million) were 4 cents higher y/y and 6 cents ahead of consensus. Disaster relief shipments following typhoons in the Western Pacific drove international airfreight results higher in the period.
#june

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by U.S. forwarding operations and international airfreight strength, particularly in disaster relief efforts following Western Pacific typhoons.
The Navegate platform is acting as a growth catalyst, enabling enterprise customers to manage complex supply chains, including one client managing over 1,400 vendors.
Domestic market dynamics are improving as capacity exits the North America truckload and intermodal sectors through carrier attrition and tighter driver availability.
Management observed constructive cyclical indicators, including rising spot rates and tender rejections, which began to manifest late in the fourth fiscal quarter.
#tell #navegate #America
Performance was driven by U.S. forwarding operations and international airfreight strength, particularly in disaster relief efforts following Western Pacific typhoons.
The Navegate platform is acting as a growth catalyst, enabling enterprise customers to manage complex supply chains, including one client managing over 1,400 vendors.
Domestic market dynamics are improving as capacity exits the North America truckload and intermodal sectors through carrier attrition and tighter driver availability.
Management observed constructive cyclical indicators, including rising spot rates and tender rejections, which began to manifest late in the fourth fiscal quarter.
#tell #navegate #America

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund #letter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund #letter

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ******* ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ******* ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #quarter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #quarter
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Revolution Medicines, Inc. (NASDAQ:RVMD) as a new addition. Revolution Medicines, Inc. (NASDAQ:RVMD) is a clinical-stage precision oncology company that develops novel targeted therapies for RAS-addicted cancers. On September 15, 2026, Revolution Medicines, Inc. (NASDAQ:RVMD) closed at $204.86 per share. Over the past month, Revolution Medicines, Inc. (NASDAQ:RVMD) declined 6.53% and its shares gained 358.00% over the past 52 weeks. Revolution Medicines, Inc. (NASDAQ:RVMD) has a market capitalization of $43.91 billion.
Parnassus Growth Equity Fund stated the following regarding Revolution Medicines, Inc. (NASDAQ:RVMD) in its Q2 2026 investor letter:
"In the Health Care sector, we see compelling long-term idiosyncratic growth opportunities in drug discovery, diagnostics and medical innovation. During the quarter, we added Revolution Medicines, Inc. (NASDAQ:RVMD), developer of a promising new drug for pancreatic cancer. Revolution Medicines' lead drug candidate, daraxonrasib, has delivered strong late-stage clinical results in pancreatic cancer, with data suggesting it could become a new standard of care and support significant commercial potential, alongside additional opportunities in other cancers over time."
Revolution Medicines, Inc. (NASDAQ:RVMD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 105 hedge fund portfolios held Revolution Medicines, Inc. (NASDAQ:RVMD) at the end of the second quarter, compared to 106 in the previous quarter. While we acknowledge the potential of Revolution Medicines, Inc. (NASDAQ:RVMD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Tr
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Revolution Medicines, Inc. (NASDAQ:RVMD) as a new addition. Revolution Medicines, Inc. (NASDAQ:RVMD) is a clinical-stage precision oncology company that develops novel targeted therapies for RAS-addicted cancers. On September 15, 2026, Revolution Medicines, Inc. (NASDAQ:RVMD) closed at $204.86 per share. Over the past month, Revolution Medicines, Inc. (NASDAQ:RVMD) declined 6.53% and its shares gained 358.00% over the past 52 weeks. Revolution Medicines, Inc. (NASDAQ:RVMD) has a market capitalization of $43.91 billion.
Parnassus Growth Equity Fund stated the following regarding Revolution Medicines, Inc. (NASDAQ:RVMD) in its Q2 2026 investor letter:
"In the Health Care sector, we see compelling long-term idiosyncratic growth opportunities in drug discovery, diagnostics and medical innovation. During the quarter, we added Revolution Medicines, Inc. (NASDAQ:RVMD), developer of a promising new drug for pancreatic cancer. Revolution Medicines' lead drug candidate, daraxonrasib, has delivered strong late-stage clinical results in pancreatic cancer, with data suggesting it could become a new standard of care and support significant commercial potential, alongside additional opportunities in other cancers over time."
Revolution Medicines, Inc. (NASDAQ:RVMD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 105 hedge fund portfolios held Revolution Medicines, Inc. (NASDAQ:RVMD) at the end of the second quarter, compared to 106 in the previous quarter. While we acknowledge the potential of Revolution Medicines, Inc. (NASDAQ:RVMD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Tr
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#lumentum #lite #Growth #investor
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#lumentum #lite #Growth #investor

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #fund
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #fund

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX). Netflix, Inc., a leading subscription-based streaming entertainment platform, detracted from the fund's performance during the quarter. On September 15, 2026, Netflix, Inc. closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. posted a one‑month return of -3.50%, while its shares lost 36.99% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX) reported solid first-quarter results, but company management did not raise revenue guidance for the full year, disappointing some investors. Cofounder Reed Hastings announced plans to step down from the board, which may have further weighed on shares."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #investor
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX). Netflix, Inc., a leading subscription-based streaming entertainment platform, detracted from the fund's performance during the quarter. On September 15, 2026, Netflix, Inc. closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. posted a one‑month return of -3.50%, while its shares lost 36.99% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX) reported solid first-quarter results, but company management did not raise revenue guidance for the full year, disappointing some investors. Cofounder Reed Hastings announced plans to step down from the board, which may have further weighed on shares."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #investor
2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#charter #multi #investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#charter #multi #investor
2 months ago
Lithium Americas Corp. (LAC) is back on Wall Street's radar after JPMorgan turned bullish on the lithium developer, upgrading the stock to an "Overweight" rating from "Neutral" and setting a $6 price target. The target implies close to 100% upside from the stock's previous close, giving investors a potentially significant re-rating opportunity if the bank's bullish **** umptions play out.
The call reflects a more constructive outlook for lithium prices. JPMorgan recently raised its lithium price **** umptions, arguing that lithium carbonate prices have remained above $20 per kilogram and that the market could face a supply deficit through the end of the decade. Those higher price **** umptions materially improve JPMorgan's estimates for Lithium Americas' long-term earnings and net **** et value.
Dear **** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#play
The call reflects a more constructive outlook for lithium prices. JPMorgan recently raised its lithium price **** umptions, arguing that lithium carbonate prices have remained above $20 per kilogram and that the market could face a supply deficit through the end of the decade. Those higher price **** umptions materially improve JPMorgan's estimates for Lithium Americas' long-term earnings and net **** et value.
Dear **** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#play

2 months ago
HSBC Holdings plc (NYSE:HSBC) is winding down its transaction services business in Germany, with more than 300 positions at HSBC Transaction Services GmbH and HSBC Service Company Germany GmbH expected to be phased out by 2028. The division provides securities processing, administration and custody services.
HSBC said the move is part of its broader strategy to strengthen its position in businesses where it has competitive advantages and sees stronger growth opportunities. The decision follows HSBC Germany's sale of its private banking business to BNP Paribas last year, highlighting the bank's continued effort to streamline its European operations.
Northfoto/Shutterstock.com
The biggest positive for HSBC Holdings plc (NYSE:HSBC) is that the German exit could improve the bank's efficiency and profitability over time. Rather than continuing to allocate capital and employees to a transaction-services operation that HSBC apparently sees as less strategically attractive, the bank can redirect resources toward areas where it has stronger competitive advantages. This fits CEO Georges Elhedery's broader restructuring strategy of reducing complexity, cutting costs and concentrating HSBC on businesses with better growth prospects. Reuters has reported that HSBC has already been selling non-core operations as part of this transformation, while its shares have risen substantially since the restructuring began.
The timing could also be constructive. Germany's economy remains under pressure, with industrial production falling unexpectedly in July and manufacturing activity still facing significant challenges. Reducing exposure to a business tied to the German market could therefore protect HSBC Holdings plc (NYSE:HSBC) from maintaining costs in an environment where growth is relatively weak.
#german
HSBC said the move is part of its broader strategy to strengthen its position in businesses where it has competitive advantages and sees stronger growth opportunities. The decision follows HSBC Germany's sale of its private banking business to BNP Paribas last year, highlighting the bank's continued effort to streamline its European operations.
Northfoto/Shutterstock.com
The biggest positive for HSBC Holdings plc (NYSE:HSBC) is that the German exit could improve the bank's efficiency and profitability over time. Rather than continuing to allocate capital and employees to a transaction-services operation that HSBC apparently sees as less strategically attractive, the bank can redirect resources toward areas where it has stronger competitive advantages. This fits CEO Georges Elhedery's broader restructuring strategy of reducing complexity, cutting costs and concentrating HSBC on businesses with better growth prospects. Reuters has reported that HSBC has already been selling non-core operations as part of this transformation, while its shares have risen substantially since the restructuring began.
The timing could also be constructive. Germany's economy remains under pressure, with industrial production falling unexpectedly in July and manufacturing activity still facing significant challenges. Reducing exposure to a business tied to the German market could therefore protect HSBC Holdings plc (NYSE:HSBC) from maintaining costs in an environment where growth is relatively weak.
#german

2 months ago
The inaugural Spanish Grand Prix at the Madring has drawn heavy criticism from F1 fans and drivers over the limited overtaking opportunities on the narrow circuit. Its layout reportedly made the race a dull spectacle for many, and now even Spain's Minister of Transport and Sustainable Mobility, Óscar Puente, has weighed in. Puente didn't hold back, describing the event as "an absolute dud."
Puente has kept his criticism constructive, comparing the Spanish GP with the Monaco GP, which is also known for offering limited overtaking opportunities. Monaco's narrow city streets have become increasingly challenging as F1 cars have grown larger over the decades, while significantly widening the roads is simply not a realistic option.
Despite Monaco's reputation for limited overtaking, this year's race featured 10 overtakes during the entire race, according to a social media post from Autosport. By comparison, the Madrid race last weekend saw just four overtakes.
Spanish Grand Prix, Sunday Madrid: Motorsport: FIA F1 Grand Prix of Spain, Formula 1 2026
on September, 13, 2026, (Photo by Hoch Zwei)
Start
01 NORRIS Lando (gbr), McLaren F1 Team MCL40, action
12 KIMI ANTONELLI Andrea (ita), Mercedes AMG F1 Team W17, action
44 HAMILTON Lewis (gbr), Scuderia Ferrari SF-26, action
Puente expressed his view while replying to a user on X who stated that the sporting side of the event suffered the most. The minister wrote:
#spanish #race #team
Puente has kept his criticism constructive, comparing the Spanish GP with the Monaco GP, which is also known for offering limited overtaking opportunities. Monaco's narrow city streets have become increasingly challenging as F1 cars have grown larger over the decades, while significantly widening the roads is simply not a realistic option.
Despite Monaco's reputation for limited overtaking, this year's race featured 10 overtakes during the entire race, according to a social media post from Autosport. By comparison, the Madrid race last weekend saw just four overtakes.
Spanish Grand Prix, Sunday Madrid: Motorsport: FIA F1 Grand Prix of Spain, Formula 1 2026
on September, 13, 2026, (Photo by Hoch Zwei)
Start
01 NORRIS Lando (gbr), McLaren F1 Team MCL40, action
12 KIMI ANTONELLI Andrea (ita), Mercedes AMG F1 Team W17, action
44 HAMILTON Lewis (gbr), Scuderia Ferrari SF-26, action
Puente expressed his view while replying to a user on X who stated that the sporting side of the event suffered the most. The minister wrote:
#spanish #race #team

2 months ago
Fundstrat's Tom Lee took the Future Proof Citywide stage earlier this year with CNBC's Scott Wapner for a session that landed in the middle of a jittery tape that included geopolitical conflict, oil spiking, private credit cracking, and fresh doubts about AI spending. Not too far off where we find ourselves currently, but with an awful lot of volatility and shifting, uncertain outlooks between these six months. While their conversation was a snapshot in time, you can expect more of this kind of sharp, thoughtful ****** ysis next week.
The contrarian take of the session was oil. High crude, Lee argued, is actually constructive for U.S. equities. With the U.S. as a net exporter, our economic competitors are importers, and stalled global growth pushes investors toward growth stocks, which is about 80% of the U.S. market. On AI CapEx, he pushed back on the sticker shock, claiming roughly $700 billion a year is a fraction of the $60 trillion global labor market and small change against daily moves in gold.
Lee also made the case that software had bottomed at the time, that enterprises building their own tools inherit the maintenance burden software companies exist to carry, and that private credit is genuinely bad but not a GFC repeat, with the real fix being taking private companies public rather than pushing private product into retail portfolios. On crypto, his argument shifted from a perspective of digital gold to one of plumbing whereby Wall Street tokenizes ****** ets, and AI agents needing a settlement rail that handles fractions of a penny.
His parting advice was the oldest one in the book, dressed in new clothes: miss the 10 best days of each year and a 16% average return goes to roughly nothing. Danger and opportunity show up together. Staying invested is the perpetual drumbeat of advisors to their clients, but one that needs banging louder when markets feel much less certain.
Future Proof Festival is September 14–17 in Huntington Beach and includes four days on the boardwalk with advisors, ****** et managers, and fintechs building the modern wealth management industry. Find us at the ETF Oasis and don't miss the stellar agenda we've got lined up.
#find #session #credit #time
The contrarian take of the session was oil. High crude, Lee argued, is actually constructive for U.S. equities. With the U.S. as a net exporter, our economic competitors are importers, and stalled global growth pushes investors toward growth stocks, which is about 80% of the U.S. market. On AI CapEx, he pushed back on the sticker shock, claiming roughly $700 billion a year is a fraction of the $60 trillion global labor market and small change against daily moves in gold.
Lee also made the case that software had bottomed at the time, that enterprises building their own tools inherit the maintenance burden software companies exist to carry, and that private credit is genuinely bad but not a GFC repeat, with the real fix being taking private companies public rather than pushing private product into retail portfolios. On crypto, his argument shifted from a perspective of digital gold to one of plumbing whereby Wall Street tokenizes ****** ets, and AI agents needing a settlement rail that handles fractions of a penny.
His parting advice was the oldest one in the book, dressed in new clothes: miss the 10 best days of each year and a 16% average return goes to roughly nothing. Danger and opportunity show up together. Staying invested is the perpetual drumbeat of advisors to their clients, but one that needs banging louder when markets feel much less certain.
Future Proof Festival is September 14–17 in Huntington Beach and includes four days on the boardwalk with advisors, ****** et managers, and fintechs building the modern wealth management industry. Find us at the ETF Oasis and don't miss the stellar agenda we've got lined up.
#find #session #credit #time

2 months ago
Saia, Inc. (NASDAQ:SAIA) reported that August less-than-truckload shipments per workday increased 1.1% year over year, while tonnage per workday rose 8.7% and weight per shipment increased 7.5%. For July and August combined, shipments per workday increased 1.0%, tonnage per workday rose 8.3%, and weight per shipment grew 7.2%.
The data show higher freight intensity, but most of the tonnage growth came from heavier shipments rather than strong shipment-count growth. The investment question is whether that mix can improve trailer utilization and spread terminal, driver, and line-haul costs across more freight without weakening yield or service.
Heavier shipments can support operating leverage when added weight fills available trailer capacity and moves through the network efficiently. The 218-terminal network of Saia, Inc. (NASDAQ:SAIA) may provide room to absorb incremental tonnage, although Saia, Inc. (NASDAQ:SAIA) did not disclose network utilization.
Second-quarter results offer evidence that higher volume can translate into improved economics. Saia, Inc. (NASDAQ:SAIA) increased tonnage per workday 8.4%, grew revenue 17.1%, and increased operating income 26%. The operating ratio improved to 86.9% from 87.8%, meaning operating expenses consumed a smaller share of revenue.
Pricing and shipment economics were mixed but constructive. Second-quarter revenue per shipment, excluding fuel surcharge revenue, increased 1.5%. If heavier freight continues to raise revenue per shipment while fixed network costs grow more slowly, Saia, Inc. (NASDAQ:SAIA) could produce additional operating leverage.
#operating #revenue #shipments
The data show higher freight intensity, but most of the tonnage growth came from heavier shipments rather than strong shipment-count growth. The investment question is whether that mix can improve trailer utilization and spread terminal, driver, and line-haul costs across more freight without weakening yield or service.
Heavier shipments can support operating leverage when added weight fills available trailer capacity and moves through the network efficiently. The 218-terminal network of Saia, Inc. (NASDAQ:SAIA) may provide room to absorb incremental tonnage, although Saia, Inc. (NASDAQ:SAIA) did not disclose network utilization.
Second-quarter results offer evidence that higher volume can translate into improved economics. Saia, Inc. (NASDAQ:SAIA) increased tonnage per workday 8.4%, grew revenue 17.1%, and increased operating income 26%. The operating ratio improved to 86.9% from 87.8%, meaning operating expenses consumed a smaller share of revenue.
Pricing and shipment economics were mixed but constructive. Second-quarter revenue per shipment, excluding fuel surcharge revenue, increased 1.5%. If heavier freight continues to raise revenue per shipment while fixed network costs grow more slowly, Saia, Inc. (NASDAQ:SAIA) could produce additional operating leverage.
#operating #revenue #shipments
2 months ago
It's been a long wait for this day to get here, but now we can finally turn the page to (I hope) more constructive play and move on from the UVA debacle. So what are we keeping our eyes on in the bigger picture tonight?
1.) Find at least the beginnings of an identity offensively. NC State's performance at Virginia was so bad as to look incoherent, and the offense wasn't on the field enough to develop a rhythm, much less discover its most important foundational aspects. Pretty much nothing worked, and what did—or could have—worked, often wasn't well-executed. The Pack has to take the opportunity presented by Richmond to start sorting itself out and establish concepts that work. Where's the bread and ***** er?
2.) To that end, who are the playmakers in this offense? We know that NC State would like to lean on Duke Scott and certainly he has better days ahead of him, but I'd like to see a more concerted effort to get Victor Snow the ball tonight. We learned next to nothing about the passing game in Week 0—well, nothing good, anyway—and still don't really know what we've got at receiver. It might end up essential for Snow to get 8-10 touches each week, and now's a good time to figure that out. I won't be surprised if Keenan Jackson is a focal point, either.
3.) What does this defense look like when it isn't in a bad position for 60 minutes? They were set up to fail by the offense in the first game, and Virginia never had to get out of its conservative comfort zone. Still the defense did some good things against actual handoffs, and needs to build on that. Richmond shouldn't have much of a downfield passing game to speak of, and I want to see how the defense performs against more regular passing downs.
#much #passing
1.) Find at least the beginnings of an identity offensively. NC State's performance at Virginia was so bad as to look incoherent, and the offense wasn't on the field enough to develop a rhythm, much less discover its most important foundational aspects. Pretty much nothing worked, and what did—or could have—worked, often wasn't well-executed. The Pack has to take the opportunity presented by Richmond to start sorting itself out and establish concepts that work. Where's the bread and ***** er?
2.) To that end, who are the playmakers in this offense? We know that NC State would like to lean on Duke Scott and certainly he has better days ahead of him, but I'd like to see a more concerted effort to get Victor Snow the ball tonight. We learned next to nothing about the passing game in Week 0—well, nothing good, anyway—and still don't really know what we've got at receiver. It might end up essential for Snow to get 8-10 touches each week, and now's a good time to figure that out. I won't be surprised if Keenan Jackson is a focal point, either.
3.) What does this defense look like when it isn't in a bad position for 60 minutes? They were set up to fail by the offense in the first game, and Virginia never had to get out of its conservative comfort zone. Still the defense did some good things against actual handoffs, and needs to build on that. Richmond shouldn't have much of a downfield passing game to speak of, and I want to see how the defense performs against more regular passing downs.
#much #passing

2 months ago
Gabelli Investment Management Firm recently released its "Global Content & Connectivity Fund" second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The Fund delivered a strong second quarter of 2026, with its Class I shares gaining 12.88%, more than double the 6.02% return of the MSCI AC World Communication Services Index, though trailing the broader MSCI AC World Index's 15.06% gain. The fund's performance reflected renewed investor interest in AI-related investments, easing tensions in the Middle East, and lower Brent crude prices, with Information Technology gaining 39.2% and Communication Services advancing 6.0% during the quarter. Over the past year, the fund gained 25.50%, compared with 13.06% for its communication-services benchmark and 24.16% for the MSCI AC World Index. Looking ahead, Gabelli remains constructive on the long-term opportunities created by AI adoption, expanding digital infrastructure, connectivity, and the continued growth of content and entertainment, while recognizing that higher interest rates, geopolitical tensions, and the sustainability of AI-related spending could create volatility. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Global Content & Connectivity Fund highlighted stocks like Anterix Inc. (NASDAQ:ATEX). Anterix Inc. (NASDAQ:ATEX) is a wireless communications company focused on private broadband spectrum and utility communications applications. The one-month return of Anterix Inc. (NASDAQ:ATEX) was -7.03% while its shares traded between $17.58 and $113.00 over the last 52 weeks. On September 3, 2026, Anterix Inc. (NASDAQ:ATEX) stock closed at approximately $87.10 per share, with a market capitalization of about $1.69 billion.
Global Content & Connectivity Fund stated the following regarding Anterix Inc. (NASDAQ:ATEX) in its Q2 2026 investor letter:
Leading the list of positive contributors to Fund performance in the second quarter was Anterix Inc. (NASDAQ:ATEX) (8.8% of net ******* ets as of June 30, 2026; +169.6%) as it continued rallying following the Federal Communications Commission (FCC) approval of expanding broadband allocation in the 900 MHz band to 10 MHz (from 6 MHz) in February, allowing the firm to offer enhanced capacity and, possibly, address additional use cases. In addition, in May, the FCC approved an experimental license to explore the use of Lynk Global's satellite direct-to-device communications network in Anterix's licensed 900 MHz broadband spectrum.
#content #connectivity #global
In its second-quarter 2026 investor letter, Global Content & Connectivity Fund highlighted stocks like Anterix Inc. (NASDAQ:ATEX). Anterix Inc. (NASDAQ:ATEX) is a wireless communications company focused on private broadband spectrum and utility communications applications. The one-month return of Anterix Inc. (NASDAQ:ATEX) was -7.03% while its shares traded between $17.58 and $113.00 over the last 52 weeks. On September 3, 2026, Anterix Inc. (NASDAQ:ATEX) stock closed at approximately $87.10 per share, with a market capitalization of about $1.69 billion.
Global Content & Connectivity Fund stated the following regarding Anterix Inc. (NASDAQ:ATEX) in its Q2 2026 investor letter:
Leading the list of positive contributors to Fund performance in the second quarter was Anterix Inc. (NASDAQ:ATEX) (8.8% of net ******* ets as of June 30, 2026; +169.6%) as it continued rallying following the Federal Communications Commission (FCC) approval of expanding broadband allocation in the 900 MHz band to 10 MHz (from 6 MHz) in February, allowing the firm to offer enhanced capacity and, possibly, address additional use cases. In addition, in May, the FCC approved an experimental license to explore the use of Lynk Global's satellite direct-to-device communications network in Anterix's licensed 900 MHz broadband spectrum.
#content #connectivity #global