
7 days ago
The 10-year Treasury yield recently hit its highest level in 24 years at 5.3%. That high yield has income-seeking investors wondering whether to load up on Treasuries while they're at a historically high level.
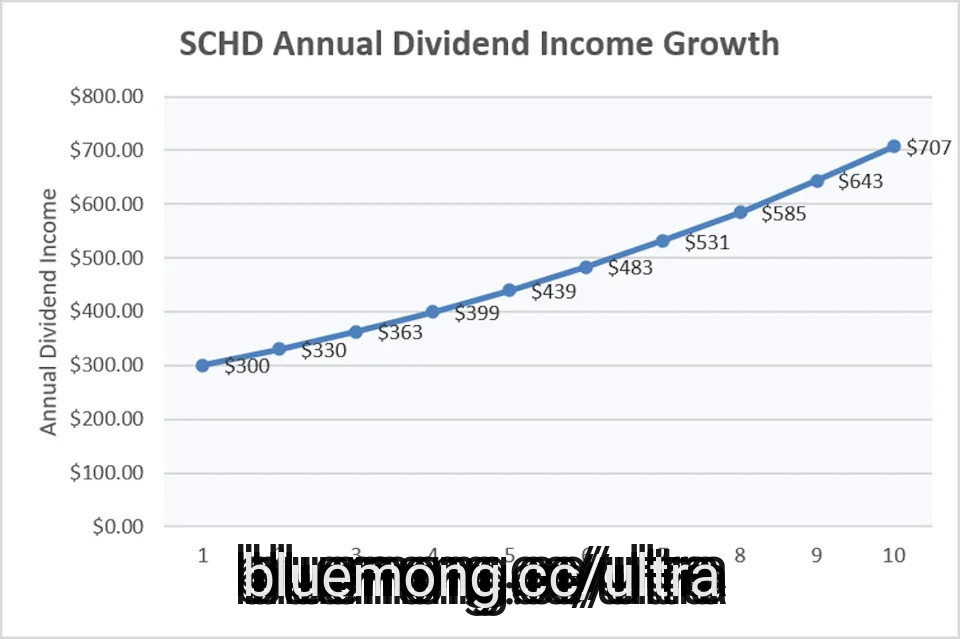
Here's a look at how much passive income you can generate over the next 10 years on Treasury bonds compared to another popular income-focused investment: the Schwab U.S. Dividend Equity ETF (NYSEMKT:SCHD).
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
A 10-year Treasury bond is a fixed-income investment backed by the full faith and credit of the U.S. government. It's a global financial benchmark that influences the rates of almost all consumer and corporate credit, including mortgages.
#treasury #missed #year #investors

7 days ago
Americans are falling behind on their mortgages and are increasingly having their homes repossessed, a new report has found.
New data from real estate data firm ATTOM's August 2026 U.S. Foreclosure Market Report showed lenders repossessed 5,794 U.S. properties in August through completed foreclosures (REOs), an increase of a whopping 42 percent from a year earlier, and 22 percent from the previous month.
Texas was the hardest-hit state, with 1,835 REOs, followed by California (589 REOs), North Carolina (356 REOs), Arizona (296 REOs) and Alabama (286 REOs).
The report also showed a total of 40,277 U.S. properties with foreclosure filings – default notices, scheduled auctions or bank repossessions – a 13 percent increase from a year ago and up 1 percent from a month ago.
Rob Barber, CEO of ATTOM – a leading provider of property data, AI-powered intelligence and real estate ******* ytics solutions – said: "August's data shows that foreclosure activity continues to trend above year-ago levels, particularly in completed foreclosures, which saw a notable annual increase.
#Foreclosure
8 days ago
WASHINGTON (AP) — Most Federal Reserve officials expect that another interest rate increase will likely be needed this year to combat inflation, according to minutes released Wednesday from the central bank's most recent meeting.
The officials unanimously agreed that inflation was still elevated and had not made much progress toward their 2% target in recent months, the minutes said. The Fed increased its key interest rate at the Sept. 15-16 meeting by a quarter-point to about 3.9%, its first increase in three years.
The increase defied President Donald Trump's repeated calls for the Fed to cut rates and prompted the president to criticize the Fed's rate-setting committee, though he still expressed support for Chairman Kevin Warsh, whom he appointed earlier this year. The rate increase comes as Americans are already struggling with high costs for groceries, gas and housing, and as affordability has taken on a leading role in the upcoming midterm elections, just seven weeks away.
Longer-term interest rates for mortgages and other borrowing have also jumped in the past few months for a range of reasons, including rising government debt, heavy borrowing by tech firms to finance data center construction, climbing oil and gas prices, and signs that growth and inflation remain elevated. The Fed's rate hike has likely played only a limited role in the increase.
Still, key policymakers have said since the meeting that the Fed can take some time to monitor the economy and the impact of last month's rate hike before making another move. Wall Street investors now forecast the Fed will keep its rate unchanged at its next meeting Oct. 28-29, according to futures pricing, and raise it when they meet in December.
#officials


9 days ago
Americans are falling behind on their mortgages and are increasingly having their homes repossessed, a new report has found.
New data from real estate data firm ATTOM's August 2026 U.S. Foreclosure Market Report showed lenders repossessed 5,794 U.S. properties in August through completed foreclosures (REOs), an increase of a whopping 42 percent from a year earlier, and 22 percent from the previous month.
Texas was the hardest-hit state, with 1,835 REOs, followed by California (589 REOs), North Carolina (356 REOs), Arizona (296 REOs) and Alabama (286 REOs).
The report also showed a total of 40,277 U.S. properties with foreclosure filings – default notices, scheduled auctions or bank repossessions – a 13 percent increase from a year ago and up 1 percent from a month ago.
Rob Barber, CEO of ATTOM – a leading provider of property data, AI-powered intelligence and real estate ***** ytics solutions – said: "August's data shows that foreclosure activity continues to trend above year-ago levels, particularly in completed foreclosures, which saw a notable annual increase.
#real
9 days ago
The bond-market rout of 2026 may be jolting markets, but it's also gaining a important following among savers and the risk-averse.
Wall Street has been gripped by the volatile moves in bond yields over the past few weeks. The all-important 10-year Treasury yield BX:TMUBMUSD10Y was up another 3.4 basis points on Monday to 5.35%, it highest level since April 2002, according to Dow Jones Market Data.
My wife never went back to work after raising our kids. Do I have to share my retirement savings 50/50?
Go ahead and get that poetry degree. Republican law won't prevent people with humanities majors from getting student loans.
That's raised the costs of new mortgages, corporate borrowing and financing the $40 trillion national debt. It also has many bond portfolios sitting in a sea of red ink for 2026, with the bond market's equivalent of the S&P 500 SPX — the Bloomberg U.S. Aggregate Index's — total return having turned negative. Bond yields and prices move in the opposite direction.
#bond #treasury #tmubmusd10y


27 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Today, the Federal Reserve increased its target interest rate by 25 basis points — its first rate hike in more than three years.
When the Fed changes interest rates, the impact reaches far beyond Wall Street. Higher rates can help savers earn more on their cash, while lower rates can make mortgages, car loans, and credit cards more affordable. But because every rate move creates both winners and losers, there's no simple answer to whether high or low rates are best.
Understanding why the Fed raises and lowers rates — and how those decisions affect your money — can help you make smarter choices about saving and borrowing.
The Federal Reserve is mandated by Congress to promote stable prices and maximum employment within the U.S. economy. One of the tools it has at its disposal to achieve these goals is the federal funds rate.
#federal #reserve #interest #make


27 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Today, the Federal Reserve increased its target interest rate by 25 basis points — its first rate hike in more than three years.
When the Fed changes interest rates, the impact reaches far beyond Wall Street. Higher rates can help savers earn more on their cash, while lower rates can make mortgages, car loans, and credit cards more affordable. But because every rate move creates both winners and losers, there's no simple answer to whether high or low rates are best.
Understanding why the Fed raises and lowers rates — and how those decisions affect your money — can help you make smarter choices about saving and borrowing.
The Federal Reserve is mandated by Congress to promote stable prices and maximum employment within the U.S. economy. One of the tools it has at its disposal to achieve these goals is the federal funds rate.
#federal #interest #disclosure
27 days ago
Interested in Truist Financial Corporation? Here are five stocks we like better.
Truist will sell its $5.5 billion near-prime auto loan portfolio and exit its Regional Acceptance Corporation business, which was roughly break-even despite high loan yields. The transaction is expected to modestly improve earnings, tangible book value and credit metrics.
The bank reaffirmed its financial outlook, including third-quarter net interest income growth of about 1.5%, full-year growth of 1% to 1.5%, and its $5 billion share-repurchase plan. The sale is expected to generate approximately $950 million in capital but reduce net interest margin by 4 to 5 basis points.
New CEO Mike Lyons is accelerating a broader portfolio and capital-allocation review, with Truist emphasizing relationship banking, deposits, commercial lending, payments, wealth management and potentially credit cards, mortgages and home equity lending.
Smart Money Shifts: U.S. Bancorp Pairs Tech With Yield
#truist #financial #loan #credit

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Open Market Committee (FOMC) — a division of the Federal Reserve responsible for setting monetary policy — will soon meet again to evaluate the health of the economy and make key decisions regarding the federal funds rate.
These decisions impact not only how the economy functions as a whole but also everyday consumers, as they influence rates on savings accounts, credit cards, mortgages, and more.
Statements and forecasts released during FOMC meetings provide valuable information on the economic outlook. Knowing when the Fed meets to discuss monetary policy and make important decisions can help you get a snapshot of the economy's overall health and adjust your own financial strategy accordingly.
The FOMC holds eight regularly scheduled meetings per year. Its most recent meeting took place July 28-29, 2026. The next one is scheduled for Sept. 15-16.
#monetary #Health


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Adjustable-rate mortgages (ARMs) can allow you to land a lower interest rate in today's high-rate environment. However, ARMs aren't without risk, and they're only right for certain borrowers in certain situations. Find out how ARMs work and whether this type of home loan is right for you.
ARMs behave like two different mortgages rolled into one loan agreement. It begins with a fixed-rate term, usually between five and 10 years. During this period, your interest rate and payment will remain the same.
After that, it converts to a variable-rate loan with an interest rate that can change (up or down) every six months or annually. This means your monthly mortgage payment also changes.
To fully understand how ARMs work, you need to understand what their formulas mean. For example, let's examine the "5/1" ARM:
#rate


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Adjustable-rate mortgages (ARMs) can allow you to land a lower interest rate in today's high-rate environment. However, ARMs aren't without risk, and they're only right for certain borrowers in certain situations. Find out how ARMs work and whether this type of home loan is right for you.
ARMs behave like two different mortgages rolled into one loan agreement. It begins with a fixed-rate term, usually between five and 10 years. During this period, your interest rate and payment will remain the same.
After that, it converts to a variable-rate loan with an interest rate that can change (up or down) every six months or annually. This means your monthly mortgage payment also changes.
To fully understand how ARMs work, you need to understand what their formulas mean. For example, let's examine the "5/1" ARM:
#interest #right #understand


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're looking for a place to keep your money, big national banks and online banks aren't your only options. Mutual banks are depositor-owned financial institutions that operate for the benefit of their customers rather than outside shareholders. That structure can translate to competitive rates, lower fees, and a greater focus on the local community — but there are potential drawbacks, too.
Here's how mutual banks work, their pros and cons, and how to decide whether one is right for you.
Mutual savings banks, or mutual banks, offer all the same accounts you can get at other banks, but they have some fundamental differences. These institutions are owned by customers instead of shareholders, and their main focus is on giving you access to savings accounts and mortgages.
Mutual banks, which represent less than 10% of all financial institutions in the U.S., tend to be small. While they may lack some of the conveniences you get with large banks, such as technology-driven services and vast ATM networks, there are some compelling reasons to switch banks and join a mutual institution:
#banks #owned #savings
1 month ago
Garn-St Germain bars lenders from calling a parent's mortgage due at death, letting heirs keep a 3% rate locked against today's 6.73% average.
Heirs must file a death certificate or probate order with the servicer to establish successor-in-interest status before making payments on the inherited loan.
Reverse mortgages fall outside Garn-St Germain, and a HECM becomes due at the borrower's death, forcing heirs to pay off, sell, or surrender the property.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
If your parent still holds a mortgage locked in near 3% from the refinancing wave earlier this decade, that loan itself has become an ****** et worth considering. With the 30-year fixed averaging 6.73% at the end of August 2026 and the 10-year Treasury yield at 4.75% as of August 31, 2026, a below-market fixed rate is effectively something you inherit along with the house. A federal law passed back in 1982 says that when a homeowner dies and the property passes to a relative, the lender cannot use the death as an excuse to call the loan due. The kids can keep both the house and the rate.
#heirs
1 month ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Intercontinental Exchange, Inc. (NYSE:ICE), a US-based financial services company that provides technology, data, and market infrastructure to financial institutions, corporations, and government entities. On September 1, 2026, Intercontinental Exchange, Inc. (NYSE:ICE) closed at $159.60 per share. Over the past month, Intercontinental Exchange, Inc. (NYSE:ICE) returned 4.85%, while its shares have declined 10.30% in the last 52 weeks. Intercontinental Exchange, Inc. (NYSE:ICE) has a market capitalization of $89.6 billion, and its stock has traded within a 52-week range of $121.79 to $177.00.
Sands Capital Select Growth Fund stated the following regarding Intercontinental Exchange, Inc. (NYSE:ICE) in its Q2 2026 investor letter:
"Intercontinental Exchange, Inc. (NYSE:ICE) is one of the world's largest operators of financial exchanges and clearinghouses. Shares declined as investor concerns around AI disruption in ICE's Mortgage business and potential competition from perpetual futures contracts weighed on the stock. Much of the underperformance appears to reflect multiple compression rather than a weakening of fundamentals, which remain solid. In our view, the market is overestimating the risk that AI will displace ICE Mortgage. The business is not simply a workflow solution; it is a platform that connects lenders, data vendors, and other participants required to originate, sell, and service mortgages, while also serving as a system of record for a significant portion of the U.S. mortgage ecosystem. We also believe concerns around perpetual futures competition are overstated, as the structure of these products may limit their use in institutional hedging and risk management, particularly before accounting for liquidity. As such, we believe the recent sell-off more than discounts these risks."
#investor

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
When Treasury yields reach multiyear highs, some investors get nervous. Higher bond yields are triggered by lower bond prices, and the effects are felt across the financial spectrum: from investing in stocks and bonds to borrowing costs and savings returns.
Global bond yields are gripping markets, jumping back to their highest level in almost two decades as higher oil prices, inflation fears, and heavy government borrowing continue to add pressure.
Here is how rising Treasury yields could impact your finances, including mortgages, credit cards, and car loans.
The Treasury yield is the return an investor receives for lending money to the government — for example, 4.5% on a 10-year Treasury note.
#prices #disclosure


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
When Treasury yields reach multiyear highs, some investors get nervous. Higher bond yields are triggered by lower bond prices, and the effects are felt across the financial spectrum: from investing in stocks and bonds to borrowing costs and savings returns.
Global bond yields are gripping markets, jumping back to their highest level in almost two decades as higher oil prices, inflation fears, and heavy government borrowing continue to add pressure.
Here is how rising Treasury yields could impact your finances, including mortgages, credit cards, and car loans.
The Treasury yield is the return an investor receives for lending money to the government — for example, 4.5% on a 10-year Treasury note.
#treasury #yields #disclosure #global


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
When Treasury yields reach multiyear highs, some investors get nervous. Higher bond yields are triggered by lower bond prices, and the effects are felt across the financial spectrum: from investing in stocks and bonds to borrowing costs and savings returns.
Global bond yields are gripping markets, jumping back to their highest level in almost two decades as higher oil prices, inflation fears, and heavy government borrowing continue to add pressure.
Here is how rising Treasury yields could impact your finances, including mortgages, credit cards, and car loans.
The Treasury yield is the return an investor receives for lending money to the government — for example, 4.5% on a 10-year Treasury note.
#yields #prices



2 months ago
Mortgage rates ticked higher this week, nudging the average long-term U.S. home loan rate closer to its recent high for the year.
The benchmark 30-year fixed rate mortgage rate edged up to 6.66% from 6.65% last week, mortgage buyer Freddie Mac said Thursday. One year ago, the average rate was 6.56%.
Higher mortgage rates can add hundreds of dollars a month in costs for borrowers, limiting homebuyers' purchasing power. As rates rise, that can lead prospective home shoppers to delay buying a home, one reason U.S. home sales remain in a rut this year.
The average rate is now back to where it was four weeks ago and is just shy of 6.69%, the high for the year it reached earlier this month.
Borrowing costs on 15-year fixed-rate mortgages, often sought by borrowers refinancing a home loan, also rose this week. That average rate increased to 5.98% from 5.95% last week. A year ago, it was at 5.69%.
#rate #average #high
2 months ago
reAlpha Tech Corp. (NASDAQ:AIRE) announced on August 21 that it completed the approximately $8.5 million acquisition of InstaMortgage on August 19. The companies closed after waiving a condition tied to outstanding regulatory approvals in Virginia and New York. Shares closed 10.5% higher at $1.58 on August 21 following the announcement.
The consideration includes $500,000 in cash and $1.5 million of reAlpha common stock issued at closing. reAlpha Tech Corp. (NASDAQ:AIRE) may pay up to another $6.5 million through semiannual installments over three years using cash or common shares, although at least $1.5 million of the deferred consideration must be paid in cash.
Source: pexels
InstaMortgage adds full-cycle lending capabilities covering origination, underwriting, funding, and loan sales. reAlpha Tech Corp. (NASDAQ:AIRE) said its combined mortgage platform now covers 38 states and Washington, D.C. Bringing lending in-house could retain economics previously passed to outside partners while giving reAlpha greater control over customer execution.
According to reAlpha Tech Corp. (NASDAQ:AIRE)'s acquisition announcement, InstaMortgage reported originating more than $4 billion of mortgages over the past five years. Combining that infrastructure with brokerage, mortgage and ****** le services could improve cross-selling and reduce customer handoffs.
#corp
2 months ago
Public perception often **** ociates high-profile investors with speculative **** ets like gold, real estate, or cryptocurrency. As a fan of the 24/7 horse racing TV channel from FanDuel, I have seen Tom Selleck, Henry Winkler, and even J.J. "Dynomite" Walker using their name recognition to hawk products from gold to reverse mortgages.
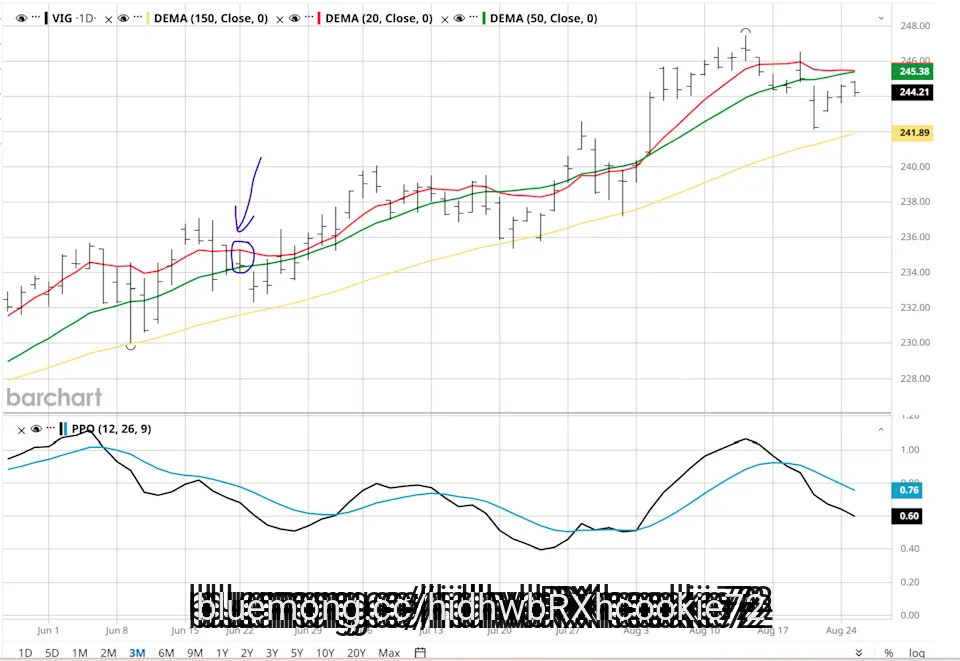
But this one is different. Because a certain U.S. president with a history of finding opportunity in everything from buildings to steaks, and more recently, crypto, has apparently been linked to active trading in the Vanguard Dividend Appreciation ETF (VIG).
Seagate vs. Western Digital: Which One is The Best AI Storage Play for Dividend Investors?
Dear Dollar General Stock Fans, Mark Your Calendars for August 27
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market **** ysis you won't find anywhere else.
#investors #fanduel


2 months ago
Better Mortgage and Coinbase (NASDAQ: $COIN) have moved their token-backed conforming mortgage into general availability, taking a product that closed its first Bitcoin-backed Fannie Mae loan in June into a broader nationwide offering for Coinbase One members.
The mortgages are originated and serviced by Better and powered by Coinbase, with the first lien structured under Fannie Mae guidelines as a standard conforming home loan. The crypto-backed portion sits alongside that mortgage, allowing qualified borrowers to pledge digital **** ets toward the down payment without first selling their holdings.
Coinbase One members approved for a Better loan can also receive a lender-funded credit equal to 1% of the mortgage value, capped at $10,000. Better said the credit now extends beyond the token-backed product to standard mortgages, home equity lines of credit and refinances.
More From Cryptoprowl:
MEXC TradFi Gala Concludes With Over 170,000 Registrations and $4.3 Billion in Daily Trading Volume
#Coinbase #first #loan

2 months ago
Mortgage rates ticked higher this week, nudging the average long-term U.S. home loan rate closer to its recent high for the year.
The benchmark 30-year fixed rate mortgage rate edged up to 6.66% from 6.65% last week, mortgage buyer Freddie Mac said Thursday. One year ago, the average rate was 6.56%.
Higher mortgage rates can add hundreds of dollars a month in costs for borrowers, limiting homebuyers' purchasing power. As rates rise, that can lead prospective home shoppers to delay buying a home, one reason U.S. home sales remain in a rut this year.
The average rate is now back to where it was four weeks ago and is just shy of 6.69%, the high for the year it reached earlier this month.
Borrowing costs on 15-year fixed-rate mortgages, often sought by borrowers refinancing a home loan, also rose this week. That average rate increased to 5.98% from 5.95% last week. A year ago, it was at 5.69%.
#rates #higher #high

2 months ago
HSBC Holdings plc (NYSE:HSBC) posted a stronger-than-expected first-half profit this week and resumed its share buyback program. UBS Group AG (NYSE:UBS) posted its own profit beat, but it's facing a $125 million fine from U.S. regulators. Hedge funds had already been quietly trimming their UBS positions before that fine even became public.
Europe's biggest banks are having a strong earnings season, but HSBC is telling the cleaner story of the two. Its profit beat came from wealth management growth, a resumed buyback, and a raised outlook for net interest income. On the other hand, UBS Group AG (NYSE:UBS) beat estimates too, but its win comes with a catch, i.e., a $125 million fine from U.S. regulators for repeated anti-money-laundering failures, alongside a hedge fund base that had already been quietly pulling back heading into the quarter.
This makes you wonder: does a clean earnings beat matter more to investors than a resolved regulatory problem? Or does UBS's history as a "repeat offender" cast a longer shadow over its recovery than HSBC Holdings plc (NYSE:HSBC)'s cleaner quarter?
First-half profit rose 23% to $19.5 billion, beating the $18.9 billion ***** ysts expected. HSBC Holdings plc (NYSE:HSBC) resumed its buyback with a plan of up to $1 billion after pausing for three quarters to fund its Hang Seng Bank takeover. It also raised its guidance for net interest income to exceed $46 billion. Wealth revenue grew 18%. The bank added 640,000 new clients in the first half. Corporate and institutional banking is now HSBC's biggest income source, generating a third of first-half profit. The bank has more than 70 IPOs lined up across Asia.
However, Citi flagged that the new $1 billion buyback came in well below the $2.2 billion investors expected, raising the question of whether HSBC is permanently scaling back its repurchases. The stock dropped from its own record high right after the earnings release. HSBC is also still exiting several businesses, including its Singapore insurance unit, Egypt retail banking, and Australian mortgages, which is a sign of ongoing restructuring rather than pure growth.
#buyback

2 months ago
Prince Harry and Meghan Markle's reported return to the UK is reportedly due to this major reason. According to insiders, the Sussexes' financial status was part of their decision-making. Earlier, several reports suggested that the couple has been going through money troubles in California. However, it was recently reported that the parents of two are "not out of money," but their expenses seemed to be high.
One of the reasons why Prince Harry and Meghan Markle are reportedly returning to the UK has been revealed. An insider told Page Six that "cash is a big" reason for their move. "They are not out of money," they said, adding, "Anything that comes in instantly goes out." According to a source, the Sussexes' expenses affected their financial status, allegedly leading them to move to Britain.
Furthermore, the insider claimed that Harry has seemingly inherited a fortune from some of his relatives. Over the years, Markle has also helped financially through her lifestyle brand, As Ever, and her Netflix project, "With Love, Meghan." From philanthropic work to exploring the entertainment market, the couple has dived into many opportunities. Thanks to their hard work, they reportedly had "more money than most even before Megxit!"
However, the more they earned, the more expenses they dealt with. According to the outlet, Markle and Harry had two mortgages on their mansion in Montecito, California. They also had a large household staff, so their salaries might have put a strain on the couple financially. Moreover, the Sussexes owned a vacation estate in Portugal. On top of these expenses, Harry lost a multi-million-dollar lawsuit against ***** ociated Newspapers.
Meanwhile, Harry and Markle are said to be returning to the UK. It has not been confirmed when they will move or how long they plan to stay. But reports claimed that they would stay outside London and their kids would start school in September.
#markle #meghan #sussexes

2 months ago
The U.S. Treasury said on Aug. 19 that it will double the amount of longer-term government bonds it buys back, from $2 billion to at least $4 billion per operation starting Sept. 9.
The move can help stabilize the bond market, push yields lower and ease some borrowing costs across the economy, including rates tied to mortgages and other loans.
Related: Mysterious trader buys millions ahead of Trump's 2:30 PM meeting
The key point is that this is not new stimulus or debt cancellation. It is a market-support measure designed to improve liquidity and reduce stress in longer-dated Treasurys.
Long-dated Treasurys are U.S. government bonds that mature 10-30 years from now. The Treasury said it is increasing buybacks to provide "greater liquidity support" in that part of the market, with the move coming a day after a sharp bond selloff pushed the 30-year yield to its highest level since 2007.
#buys #billion

2 months ago
Vishal Garg has long invoked "the American dream" as the motivation behind Better Home & Finance, known as Better, the online mortgage firm he launched 10 years ago to make mortgages more accessible.
But his own dreams appear to be going up in flames. Garg — who abruptly dismissed 900 employees via Zoom in December 2021 — was himself abruptly fired this month. As Forbes reports, Better's board ousted Garg because under his watch, the business experienced $1.5 billion in losses and its stock price cratered 90%.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#make #american #home

2 months ago
By Yoruk Bahceli, Ben Welsh, Dhara Ranasinghe and Rocky Swift
LONDON/NEW YORK/TOKYO, August 20 (Reuters) - U.S. debt has topped $40 trillion for the first time, underscoring the pressures on the world's major economies to fund ever-increasing spending demands -- from ageing populations to climate change and defence.
This year, the Iran war has rekindled inflation risks, while damage wrought by Europe's increasingly volatile weather is a further strain on public finances.
No wonder perhaps that U.S. 30-year Treasury yields have risen to their highest since 2007, prompting government action to contain rising borrowing costs. ******* anese borrowing costs are also near their highest in three decades and even Germany -- whose debt load is considerably lighter -- has seen its yields jump to the highest levels since 2011.
A high debt burden that brings higher borrowing costs risks hurting living standards by constraining spending and capping growth. Sovereign debt sets the benchmark for borrowing costs for companies and other loans, including household mortgages.
#spending #since

2 months ago
Only two weeks ago, Fed Chairman Kevin Warsh said markets had done "quite a bit" of the Fed's tightening. Wall Street has since taken it all back — and then some.
A gauge of US market conditions published by Bloomberg rose Thursday to its easiest level since 1996, capping a remarkable reversal from late July.
"Financial conditions" is Wall Street shorthand for how easy or hard markets are making it to take risk and raise money. Rising stocks, calmer markets, and cheaper corporate borrowing make them easier. Falling stocks and rising borrowing costs tighten the screws.
The index in the chart is especially geared toward those market signals, so this isn't saying mortgages or credit cards are suddenly cheap. It's saying Wall Street itself is unusually loose.
Between Warsh's first Fed meeting on June 17 and his next on July 29, Treasury yields rose, stocks slipped, volatility jumped, and corporate borrowing got more expensive. The Fed left its benchmark rate untouched at 3.5% to 3.75%, but markets tightened around it.
#street


2 months ago
Zillow Group (NASDAQ:Z) delivered a second quarter that beat its own outlook on nearly every line, then turned around and eliminated jobs and reshuffled its leadership team. On the call held August 5, CEO Jeremy Wacksman and newly expanded COO and CFO Jeremy Hofmann laid out a business growing far faster than the housing market around it, alongside a restructuring meant to fund that growth. The two stories sitting side by side are worth pulling apart.
Q2 revenue rose 18% year-over-year to $772 million, ahead of the high end of guidance, while EBITDA hit $176 million for a 23% margin. For Sale revenue climbed 14% to $549 million even though the purchase mortgage market was flat, and mortgages revenue jumped 75% to $84 million as purchase loan origination volume nearly doubled. Rentals revenue grew 31% to $209 million, powered by 42% growth in multifamily and a record 79,000 multifamily properties on the platform, up 23% from a year earlier.
Management is also leaning into AI Mode, now live for about 20% of signed-in users, where engaged consumers spend more than three times as long on the site and contact an agent at nearly three times the rate of everyone else. Zillow Home Loans has become a top-25 purchase lender nationally, and the shift toward its "preferred" agent model generated 23% more revenue per connection in 2025, with management targeting 35% by the end of 2026. The company backed that confidence with $200 million in buybacks during the quarter and $826 million year-to-date.
The other side of the ledger is messier. A day before the call, Zillow eliminated roughly 7% of its workforce, booking $36 million in restructuring costs in the quarter with another $23 million to $28 million expected in the third quarter. Chief Operating Officer Jun Choo is stepping down to focus on his health, replaced in an expanded role by Hofmann. Despite the adjusted net income of $118 million, Zillow posted a GAAP net loss of $4 million.
Management also revised its view of the purchase mortgage market lower, now expecting originations down low to mid single digits rather than flat, citing rates that have risen since their lows earlier in the year. The accounting mechanics of the preferred transition are adding real drag too: residential revenue is expected to be flat in the third quarter and only in line with a shrinking mortgage industry in the fourth, as 600 to 800 basis points of revenue shifts from residential into mortgages and seasonality adds another 200 to 300 basis points of headwind in Q4.
#market


2 months ago
Zillow Group (Z) is a leading real estate technology company reimagining how people buy, sell, rent, and finance homes across the United States. Headquartered in Seattle, Washington, Zillow operates the most visited real estate app and website in the country, connecting hundreds of millions of consumers with trusted local agents, loan officers, and innovative digital tools.
The company has built a diversified real estate marketplace spanning residential listings, rentals, mortgages, and agent software solutions like Zillow Showcase and Zillow Pro. Its portfolio also includes legacy brands such as Trulia, StreetEasy, and HotPads, reinforcing its dominant position in online real estate.
Jeff Bezos Says He's Selling $1 Billion In Amazon Stock Every Year to Fund Blue Origin — 'It's The Most Important Work I'm Doing'
Apple's New CEO Is Bringing a Familiar Face Back From Retirement. The Shift Is Happening.
Nasdaq Futures Climb as Tech Rally Continues on Palantir Boost, U.S. JOLTS Report and ******* eX Earnings on Tap
#united



