7 days ago
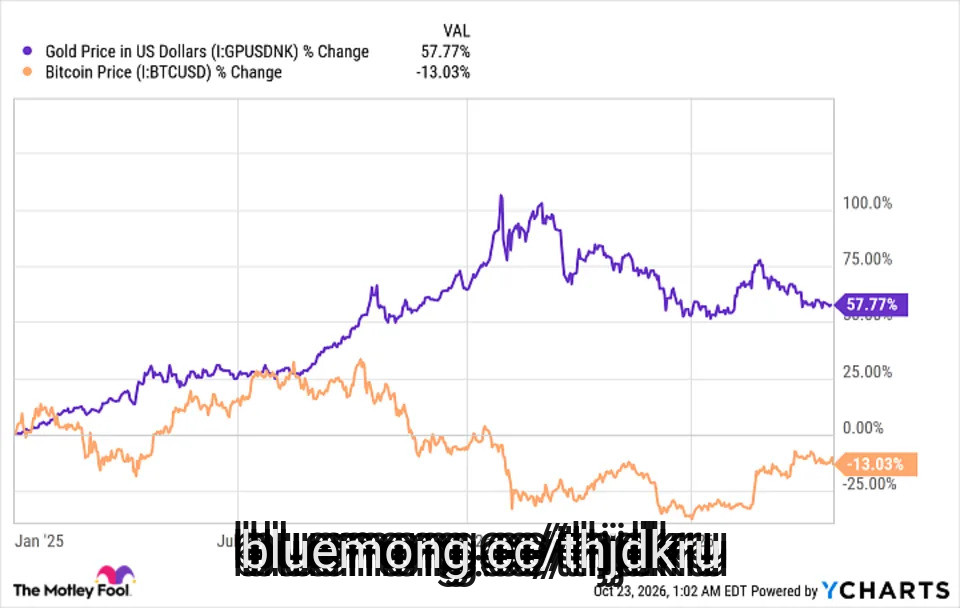
Bitcoin (CRYPTO: BTC) fell to a 52-week low of $58,566 in July, which represented a 53% decline from last year's all-time high of $124,773. It has since rallied back to $81,800 (as of this writing on Oct. 23), giving investors hope that a new bull cycle may be underway.
Ark Investment Management, founded by technology investor Cathie Wood, is very bullish about Bitcoin's potential. It believes the cryptocurrency could amass a market capitalization of $16 trillion by 2030, which would translate to a price of $796,000 per coin.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That implies a whopping 873% upside from the current level, so should investors buy Bitcoin today?
#Bitcoin #Crypto #july #investment
Ark Investment Management, founded by technology investor Cathie Wood, is very bullish about Bitcoin's potential. It believes the cryptocurrency could amass a market capitalization of $16 trillion by 2030, which would translate to a price of $796,000 per coin.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That implies a whopping 873% upside from the current level, so should investors buy Bitcoin today?
#Bitcoin #Crypto #july #investment

25 days ago
In January, then-CEO Tim Cook said that there were more than 2.5 billion active Apple (NASDAQ: AAPL) devices around the world. During the most recent fiscal quarter (the third quarter, ended June 27), the business exceeded 1.5 billion paid subscriptions to its family of services. These two data points demonstrate how dominant the consumer tech juggernaut has become.
If you'd invested $10,000 in this "Magnificent Seven" stock 10 years ago, here's how much you'd have today.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past decade, Apple shares have produced a total return of 1,190% (as of Oct. 5). This gain would've turned a starting $10,000 investment into more than $129,000 today.
In October 2016, Apple was the world's most valuable enterprise. While its market capitalization has ballooned to $4.9 trillion, it has given up the top spot to Nvidia.
#flashing #billion
If you'd invested $10,000 in this "Magnificent Seven" stock 10 years ago, here's how much you'd have today.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past decade, Apple shares have produced a total return of 1,190% (as of Oct. 5). This gain would've turned a starting $10,000 investment into more than $129,000 today.
In October 2016, Apple was the world's most valuable enterprise. While its market capitalization has ballooned to $4.9 trillion, it has given up the top spot to Nvidia.
#flashing #billion

27 days ago
Warren Buffett stepped down from his role as the chief executive officer of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the end of 2025. During his 60-year tenure, he grew the company into a $1 trillion conglomerate with multiple wholly owned subsidiaries, a $350 billion stock portfolio, and over $350 billion in cash.
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing


1 month ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management


1 month ago
Apple's (NASDAQ: AAPL) new iPhones are here, and this could be just the ticket to get the consumer tech ******* an back on top of the market cap throne. It doesn't have far to go to get there.
The stock's recent gains now place it within 2% of hitting a market cap of $5 trillion. Perhaps even more intriguingly, Apple is now less than 10% away from overtaking Nvidia (NASDAQ: NVDA) to become the market's most valuable company by market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple's business isn't growing as quickly as Nvidia's these days, but it is closing the gap in market cap. Nvidia investors can't feel too bad, with the stock up 26% over the past year. It's just that Apple stock has soared by more than 40% in that time. Momentum is on its side, and that's before a bar-raising device hits the market.
For more than a dozen years, Apple has fallen into a predictable pattern. It delivers double-digit revenue growth in a fiscal year in which it rolls out a revolutionary iPhone model. Then it follows that with two -- and lately more than two -- years of single-digit or negative top-line growth, settling for merely evolutionary smartphone updates.
#NASDAQ
The stock's recent gains now place it within 2% of hitting a market cap of $5 trillion. Perhaps even more intriguingly, Apple is now less than 10% away from overtaking Nvidia (NASDAQ: NVDA) to become the market's most valuable company by market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple's business isn't growing as quickly as Nvidia's these days, but it is closing the gap in market cap. Nvidia investors can't feel too bad, with the stock up 26% over the past year. It's just that Apple stock has soared by more than 40% in that time. Momentum is on its side, and that's before a bar-raising device hits the market.
For more than a dozen years, Apple has fallen into a predictable pattern. It delivers double-digit revenue growth in a fiscal year in which it rolls out a revolutionary iPhone model. Then it follows that with two -- and lately more than two -- years of single-digit or negative top-line growth, settling for merely evolutionary smartphone updates.
#NASDAQ

1 month ago
JPMorgan Chase (NYSE: JPM) is the largest bank in the U.S., by far. It's a financial giant with robust consumer and commercial segments, and it's reliable in driving growth under pressure. It also pays a growing dividend that yields 1.7% at the current price, and it's a fantastic value addition to any investor's diversified portfolio.
While it's likely to become the first bank stock with a $1 trillion valuation in the near future (it currently sports a $927.5 billion market capitalization), there are smaller digital banks that are likely to grow much faster in the next two years, and probably a lot longer. SoFi Technologies (NASDAQ: SOFI) and Nu Holdings (NYSE: NU) are two of them.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
SoFi is a young digital bank that's growing at the rate of a tech start-up, which makes sense, since it's a combination of both -- a classic fintech company.
What started as a loan cooperative for college students has expanded into a comprehensive financial app for anyone seeking an easy-to-use digital platform. It's attracting new members at a fast pace, and its strategy of bringing customers into the ecosystem and getting them to adopt more products is working.
#sofi #bank
While it's likely to become the first bank stock with a $1 trillion valuation in the near future (it currently sports a $927.5 billion market capitalization), there are smaller digital banks that are likely to grow much faster in the next two years, and probably a lot longer. SoFi Technologies (NASDAQ: SOFI) and Nu Holdings (NYSE: NU) are two of them.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
SoFi is a young digital bank that's growing at the rate of a tech start-up, which makes sense, since it's a combination of both -- a classic fintech company.
What started as a loan cooperative for college students has expanded into a comprehensive financial app for anyone seeking an easy-to-use digital platform. It's attracting new members at a fast pace, and its strategy of bringing customers into the ecosystem and getting them to adopt more products is working.
#sofi #bank

1 month ago
It's hard to overstate how important the Model Y was for Tesla's (NASDAQ: TSLA) overall growth journey. Today, that model alone accounts for more than 90% of Tesla's vehicle sales. The Model Y allowed Tesla to significantly expand its sales base, which, in turn, enabled the company to scale its production facilities to reach economies of scale -- the driving force behind Tesla's 24-quarter streak of consecutive profits.
In short, the Model Y is one of the biggest factors behind Tesla's current $1.1 trillion market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Rivian Automotive's (NASDAQ: RIVN) valuation, meanwhile, still hovers just above $20 billion. This valuation gap has many causes. But for years, the biggest issue was that Rivian lacked an affordable vehicle priced for the masses like the Model Y. Rivian addressed that problem this summer when it began deliveries of its R2 SUV -- its first vehicle priced under $50,000.
Next month, investors will get the first meaningful update on how Rivian's sales and production capacities are scaling for the R2. Here's exactly what you should be paying attention to.
#rivian #signal
In short, the Model Y is one of the biggest factors behind Tesla's current $1.1 trillion market capitalization.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Rivian Automotive's (NASDAQ: RIVN) valuation, meanwhile, still hovers just above $20 billion. This valuation gap has many causes. But for years, the biggest issue was that Rivian lacked an affordable vehicle priced for the masses like the Model Y. Rivian addressed that problem this summer when it began deliveries of its R2 SUV -- its first vehicle priced under $50,000.
Next month, investors will get the first meaningful update on how Rivian's sales and production capacities are scaling for the R2. Here's exactly what you should be paying attention to.
#rivian #signal
1 month ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source


1 month ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa

1 month ago
Fenimore ***** et Management, an investment management company, released its Q2 2026 investor letter. The letter can be downloaded here. U.S. equity markets saw broad gains in Q2, driven by strong corporate earnings, economic resilience, and enthusiasm for artificial intelligence (AI). Major indices reached all-time highs, though the energy sector declined. Continued earnings growth, especially among AI-related investments, supported the rally. Technology, particularly semiconductors, led performance as demand for AI infrastructure surged. Despite macroeconomic uncertainties and interest rate influences, Fenimore remains committed to investing in high-quality businesses. The Fenimore Small Cap Strategy returned 9.51% in the quarter, lagging the Russell 2000 Index's 21.49% gain. The underperformance was largely driven by avoiding lower-quality tech stocks linked to data center expansions. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Fenimore ***** et Management highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On September 17, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $40.03 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -8.32%, and its shares lost 25.53% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $10.15 billion.
Fenimore ***** et Management stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"We initiated a position in Ryan Specialty Holdings, Inc. (NYSE:RYAN), which we had previously owned after its initial public offering. The insurance industry has seen softness in rates. While RYAN's model differs from traditional retail brokerage, the company released results citing a volatile environment which led to a decrease in their earnings outlook for the year. We're encouraged by the business's long-term prospects and, in our opinion, its legendary leader Pat Ryan. He is also purchasing shares of RYAN's stock during this weakness."
Ryan Specialty Holdings, Inc. (NYSE:RYAN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 32 hedge fund portfolios held Ryan Specialty Holdings, Inc. (NYSE:RYAN) at the end of the second quarter, compared to 35 in the previous quarter. While we acknowledge the potential of Ryan Specialty Holdings, Inc. (NYSE:RYAN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
In its second-quarter 2026 investor letter, Fenimore ***** et Management highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On September 17, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $40.03 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -8.32%, and its shares lost 25.53% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $10.15 billion.
Fenimore ***** et Management stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"We initiated a position in Ryan Specialty Holdings, Inc. (NYSE:RYAN), which we had previously owned after its initial public offering. The insurance industry has seen softness in rates. While RYAN's model differs from traditional retail brokerage, the company released results citing a volatile environment which led to a decrease in their earnings outlook for the year. We're encouraged by the business's long-term prospects and, in our opinion, its legendary leader Pat Ryan. He is also purchasing shares of RYAN's stock during this weakness."
Ryan Specialty Holdings, Inc. (NYSE:RYAN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 32 hedge fund portfolios held Ryan Specialty Holdings, Inc. (NYSE:RYAN) at the end of the second quarter, compared to 35 in the previous quarter. While we acknowledge the potential of Ryan Specialty Holdings, Inc. (NYSE:RYAN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


2 months ago
Semiconductor rivalries rarely move stock prices the way headlines suggest they should. MediaTek unveiled a new flagship smartphone processor on Tuesday, Sept. 15, built to challenge Qualcomm directly in the premium handset market.
Qualcomm Inc (QCOM)'s stock rose anyway, closing up 4.25% at $187.80.
That is not a new pattern. MediaTek's market value first surpassed Qualcomm's earlier this year, according to Reuters. The new chip was meant to widen that lead, not just defend it.
The gap is real money. MediaTek's market capitalization stood near $223 billion on Sept. 15, PitchBook noted. Even after Qualcomm's 4.25% rally that same day, its market cap reached $200.6 billion, according to CompaniesMarketCap, leaving it about $22 billion behind MediaTek.
MediaTek said the Dimensity 9600 Pro is its first mobile processor built on TSMC's 2-nanometer process. Its neural processing unit delivers 51% faster prompt handling for on-device AI models than the prior generation. That lets phones run generative AI tasks without sending data to the cloud.
#market #qualcomm #built #according
Qualcomm Inc (QCOM)'s stock rose anyway, closing up 4.25% at $187.80.
That is not a new pattern. MediaTek's market value first surpassed Qualcomm's earlier this year, according to Reuters. The new chip was meant to widen that lead, not just defend it.
The gap is real money. MediaTek's market capitalization stood near $223 billion on Sept. 15, PitchBook noted. Even after Qualcomm's 4.25% rally that same day, its market cap reached $200.6 billion, according to CompaniesMarketCap, leaving it about $22 billion behind MediaTek.
MediaTek said the Dimensity 9600 Pro is its first mobile processor built on TSMC's 2-nanometer process. Its neural processing unit delivers 51% faster prompt handling for on-device AI models than the prior generation. That lets phones run generative AI tasks without sending data to the cloud.
#market #qualcomm #built #according


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre


2 months ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus

2 months ago
PulteGroup, Inc. (PHM) is one of America's largest homebuilders, headquartered in Atlanta, Georgia. It acquires and develops land for residential use and constructs and sells single-family detached homes, townhomes, condominiums, and duplexes. Operating in U.S. markets, the company serves diverse homebuyers through brands including Centex, Pulte Homes, Del Webb, and DiVosta Homes. The company has a market capitalization of $22.76 billion, which makes it a "large-cap" stock.
PulteGroup's shares reached a 52-week low of $108.49 on May 19, but are up 10.1% from that level. Over the past three months, the stock has dropped 2.7%, as investors weigh persistent housing-market headwinds. Meanwhile, the broader S&P 500 Index ($SPX) is up marginally over the past three months. Therefore, PHM has clearly underperformed over this period.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Stock #months #atlanta
PulteGroup's shares reached a 52-week low of $108.49 on May 19, but are up 10.1% from that level. Over the past three months, the stock has dropped 2.7%, as investors weigh persistent housing-market headwinds. Meanwhile, the broader S&P 500 Index ($SPX) is up marginally over the past three months. Therefore, PHM has clearly underperformed over this period.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Stock #months #atlanta


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands


2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor


2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor


2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second

2 months ago
Wasatch Global Investors, an **** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #remax #NASDAQ #long
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #remax #NASDAQ #long


2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Mettler-Toledo International Inc. (NYSE:MTD). Mettler-Toledo International Inc. (NYSE:MTD) manufactures and supplies precision instruments and services in the Americas, Europe, Asia, and internationally. On September 15, 2026, Mettler-Toledo International Inc. (NYSE:MTD) closed at $1,330.40 per share. Over the past month, Mettler-Toledo International Inc. (NYSE:MTD) declined 6.64%, and its shares gained 4.43% over the past 52 weeks. Mettler-Toledo International Inc. (NYSE:MTD) has a market capitalization of $26.66 billion.
Weitz Multi Cap Equity Fund stated the following regarding Mettler-Toledo International Inc. (NYSE:MTD) in its Q2 2026 investor letter:
"Less familiar to shareholders may be our new position in Mettler-Toledo International Inc. (NYSE:MTD), a global supplier of precision measurement instruments across laboratory, industrial and food retailing applications where accuracy, reliability and regulatory compliance are vital. Its highly specialized sales and service organization is a key competitive advantage, working collaboratively with customers to optimize their workflows and improve productivity, reinforcing long-term customer relationships. We have long admired Mettler's business and purchased a small position during a brief period of price dislocation during the quarter."
Mettler-Toledo International Inc. (NYSE:MTD) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 48 hedge fund portfolios held Mettler-Toledo International Inc. (NYSE:MTD) at the end of the second quarter, down from 50 in the previous quarter. While we acknowledge the potential of Mettler-Toledo International Inc. (NYSE:MTD) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mettler #quarter

2 months ago
Wasatch Global Investors, an ****** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund

2 months ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alphabet #NASDAQ #quarter #conventum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG). Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On September 15, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $341.43 per share, reflecting a market capitalization of $4.2 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -0.08%, while its shares gained 36.65% over the past 52 weeks.
Conventum – Alluvium Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Alphabet Inc. (NASDAQ:GOOG) was the Fund's strongest performer over the quarter, up 24.4%. There's little to add from our last report, except that its 22% revenue growth exceeded our expectations, and it seems it can't keep up with demand, hence it has increased, yet again (and somewhat worryingly) its capital expenditure to budget (to USD 190b) and expects further increases next year."
Alphabet Inc. (NASDAQ:GOOG) ranks 7th on our list of 40 Most Popular Stocks Among Hedge Funds. As per our database, 195 hedge fund portfolios held Alphabet Inc. (NASDAQ:GOOG) at the end of the second quarter, which was 201 in the previous quarter. While we acknowledge the potential of Alphabet Inc. (NASDAQ:GOOG) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#alphabet #NASDAQ #quarter #conventum

2 months ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted LyondellBasell Industries N.V. (NYSE:LYB). LyondellBasell Industries N.V. (NYSE:LYB) is a multinational chemical and plastic manufacturing company. On September 15, 2026, LyondellBasell Industries N.V. (NYSE:LYB) closed at $65.43 per share. Over the past month, LyondellBasell Industries N.V. (NYSE:LYB) declined 0.95% while its shares gained 22.25% over the past 52 weeks. LyondellBasell Industries N.V. (NYSE:LYB) has a market capitalization of $21.14 billion, and its stock has traded within a 52-week range of $41.58 and $83.94.
Conventum – Alluvium Global Fund stated the following regarding LyondellBasell Industries N.V. (NYSE:LYB) in its Q2 2026 investor letter:
"LyondellBasell Industries N.V. (NYSE:LYB), the plastics producer gave back some of that 88.3% return of last quarter, and fell 34.0%, We are continually amazed by the market's response to the war in Iraq. It seems that this so called "ceasefire" (the one where Iran keeps attacking ships in the Strait of Hormuz and the US keeps bombing) has led to expectations that all is well for the affected commodity markets. Management provided results in early May, and reported expectations that the higher prices will be sustained for some time. That makes sense to us. But since then, Polyethylene and Polypropylene prices, for example, have fallen by around 15%. After we sold around two thirds of our holding during the March quarter, we ceased as the price fell to levels below our valuation. It currently accounts for 2.1% of the Fund and we are comfortable with maintaining this position."
LyondellBasell Industries N.V. (NYSE:LYB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 57 hedge fund portfolios held LyondellBasell Industries N.V. (NYSE:LYB) at the end of the second quarter which was 59 in the previous quarter. While we acknowledge the potential of LyondellBasell Industries N.V. (NYSE:LYB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trum
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted LyondellBasell Industries N.V. (NYSE:LYB). LyondellBasell Industries N.V. (NYSE:LYB) is a multinational chemical and plastic manufacturing company. On September 15, 2026, LyondellBasell Industries N.V. (NYSE:LYB) closed at $65.43 per share. Over the past month, LyondellBasell Industries N.V. (NYSE:LYB) declined 0.95% while its shares gained 22.25% over the past 52 weeks. LyondellBasell Industries N.V. (NYSE:LYB) has a market capitalization of $21.14 billion, and its stock has traded within a 52-week range of $41.58 and $83.94.
Conventum – Alluvium Global Fund stated the following regarding LyondellBasell Industries N.V. (NYSE:LYB) in its Q2 2026 investor letter:
"LyondellBasell Industries N.V. (NYSE:LYB), the plastics producer gave back some of that 88.3% return of last quarter, and fell 34.0%, We are continually amazed by the market's response to the war in Iraq. It seems that this so called "ceasefire" (the one where Iran keeps attacking ships in the Strait of Hormuz and the US keeps bombing) has led to expectations that all is well for the affected commodity markets. Management provided results in early May, and reported expectations that the higher prices will be sustained for some time. That makes sense to us. But since then, Polyethylene and Polypropylene prices, for example, have fallen by around 15%. After we sold around two thirds of our holding during the March quarter, we ceased as the price fell to levels below our valuation. It currently accounts for 2.1% of the Fund and we are comfortable with maintaining this position."
LyondellBasell Industries N.V. (NYSE:LYB) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 57 hedge fund portfolios held LyondellBasell Industries N.V. (NYSE:LYB) at the end of the second quarter which was 59 in the previous quarter. While we acknowledge the potential of LyondellBasell Industries N.V. (NYSE:LYB) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trum

2 months ago
Alluvium **** et Management, an **** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Liberty Capital Corporation (NASDAQ:GLIBK). Liberty Capital Corporation (NASDAQ:GLIBK) is a communication services company that provides a range of data, wireless, video, voice, and managed services. GCI Liberty, Inc. rebranded to Liberty Capital Corporation (NASDAQ:GLIBK) in May 2026. On September 15, 2026, Liberty Capital Corporation (NASDAQ:GLIBK) closed at $25.55 per share. Over the past month, Liberty Capital Corporation (NASDAQ:GLIBK) declined 1.50% and its shares lost 27.02% over the past 52 weeks. Liberty Capital Corporation (NASDAQ:GLIBK) has a market capitalization of $1.02 billion, and its stock trades within a 52-week range of $19.30 and $41.18.
Conventum – Alluvium Global Fund stated the following regarding Liberty Capital Corporation (NASDAQ:GLIBK) in its Q2 2026 investor letter:
"GCI Liberty, the Alaskan cable business that was spun out of Liberty Broadband, has been renamed Liberty Capital Corporation (NASDAQ:GLIBK) (to reflect a future which is expected to include a broader array of businesses, and with its legacy GCI Alaska cable business being the solid "cash cow"). It fell 40.6%. There was plenty of news. Most notable was its USD 360m acquisition of Quintillion, which owns around 3,000 kilometres of fibre cable and plans to expand it by a further 2,500 kilometres or so. This perfectly aligns with Liberty's GCI operations. We understand Quintillion generates around USD 55-60m in revenue and USD 30m in free cash. We would expect significant synergies (reportedly around USD 20m) so we have little doubt that the deal adds value. And in fact, when we incorporate it into our model, the valuation uplift is around 35%. Management also decided to retreat from the competitive and low margin video business. And finally, Liberty Capital had intended to acquire an interest in Liberty Latin America by striking a deal for an initial 6% stake and building on that by buying John Malone's interest. For some reason this did not proceed which perhaps spooked the market. With the share price falling (to levels approximating half our valuation), and encouraged by its CEO buying shares, we increased our