13 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

13 days ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid

14 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
16 days ago
Wasatch Global Investors, an **** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #remax #NASDAQ #long


16 days ago
Wasatch Global Investors, an ****** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund

17 days ago
Wasatch Global Investors, an ***** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#wasatch


17 days ago
Wasatch Global Investors, an **** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #reax


23 days ago
Blaming declining mall traffic for retail store failures ignores what's actually happening.
"Malls' H1 2026 momentum continued going into the second half of the year, with year-over-year (YoY) visits to shopping centers up across all three formats ******* yzed (indoor, open-air, and outlet) in July 2026," according to data from Placer.ai.
Retailers like Claire's, Joann, and Macy's, which have either fully closed or have shut down dozens of locations, may have failed to capitalize on mall foot traffic, but it's unfair to say that people did not visit malls.
"Open-air shopping centers — which have led the category since the beginning of the year — continued their outperformance, with YoY traffic up 5.1%, followed closely by indoor malls (+4.3%)," the data showed.
Francesca's, a mall staple since its launch in 1999, closed all its more than 450 stores in March and has now received court permission to liquidate its remaining ******* ets.
#year #mall #continued #indoor

23 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance outperformance was driven by disciplined channel management, with legacy field inventory reduced by approximately 30% year-over-year to improve turns to better than pre-pandemic levels.
The MasterCraft brand's success was anchored by the next-generation X Series rollout, which drove a favorable premium mix and offset lower industry-wide volumes.
Management attributed the 730 basis point expansion in legacy adjusted EBITDA margin to improved fixed cost absorption on higher unit volumes and lower promotional discounting.
The combination with Chaparral and Robalo is framed as a transformational pivot to a larger, more diversified platform spanning inland and coastal markets with broader price points.
#management #lower #NVIDIA

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
26 days ago
Earnings season refuses to end. While others may have had enough, earnings reports are my lifeblood! Well, that and 1,500 milligrams of caffeine a day.
I'm glad earnings season rages on because it gives us the very latest insights on all things AI. This is super helpful information as I embark for the Super Bowl of tech conferences: the Goldman Sachs Communacopia tech gathering. More on that in a moment.
The past two weeks have been bonkers for the AI investment thesis. Any talk about peak AI needs to be tossed aside.
Broadcom's (AVGO) revenue surged 86% year over year in its most recent quarter. Adjusted earnings per share exploded 96%. Both metrics easily thumped ***** yst estimates.
The massive outperformance was fueled by relentless hyperscaler demand for custom AI chips and networking gear, with quarterly AI semiconductor revenue alone tripling to $16.7 billion.
#super #season #revenue #sachs

29 days ago
On August 10, Joe Gomes from ***** le Capital reiterated his Outperform rating on CoreCivic Inc. (NYSE:CXW). In the process, the ***** yst increased his target price on the stock from $35 to $42, resulting in a revised upside potential in excess of 24% based on stock's closing price on August 27. This upward adjustment in price target came after an impressive second quarter print above management estimates. Let's explore the underlying drivers of this outperformance, and which additional factors are expected to shape up investor sentiment toward the stock.
Earlier in August, the company reported its second quarter results which exceeded management's expectations. Topline figures were recorded at $684.9 million, up by 27.3% compared to Q2 2025. Adjusted EBITDA of $109.4 million exhibited 5.9% year-on-year growth, while adjusted diluted EPS of $0.38 reflected a 5.6% growth compared to the same period last year. Such expansion in adjusted diluted EPS was supported by lower operating costs and slightly higher ICE populations, while strong federal revenue also contributed to growth. Following the quarter and subsequent facility sales, management raised its full-year 2026 guidance.
During 2026, CoreCivic has been focusing on strengthening its financial position while expanding its footprint as a federal detention operator. The company generated $734 million in gross proceeds from sales of Prairie Correctional Facility and Midwest Regional Reception Center, to the Department of Homeland Security. It expects to continue to operate both facilities under current arrangements, and was also awarded a new ICE contract to operate the 1,600 bed Prairie Correctional Facility till August 2031. The contract award offers potential for $75 million in revenue boost in the future once fully activated, with no material impact expected during 2026.
CoreCivic can benefit from this demand tailwind without the time and capital required to construct entirely new facilities, although activating idle sites still involves staffing and start-up costs. It also strengthens the company's position as a trusted partner for federal detention requirements, and might create potential opportunities for more contracts in the future.
The company has also taken an aggressive approach toward debt reduction and returning capital to shareholders. On August 10, it entered a $500 million accelerated share repurchase agreement, supported by the proceeds from recent facility sales. A portion of those sale proceeds was also utilized for $608.5 million debt repayment, which included early redemption of senior notes that were due in 2027.
#price
29 days ago
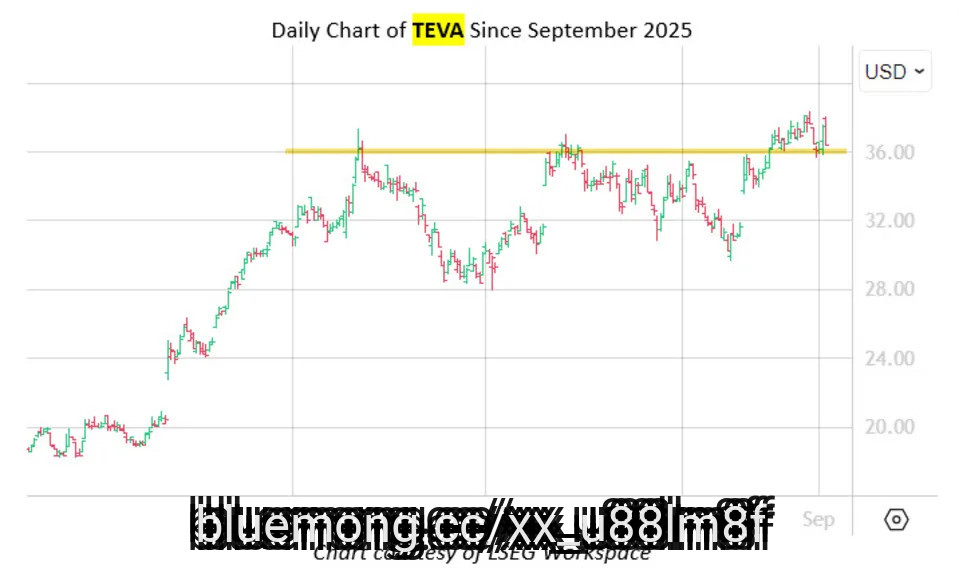
Teva Pharmaceuticals Industries (NYSE:TEVA) is moving 2.9% lower to trade at $36.41, pulling back from its Aug. 27, nearly nine-year high of $38.36. The $36 level looks to have moved in as a floor of support, a former level of resistance for the shares since late January. More gains could be on the table, however, with a fresh bull signal now flashing for the drug maker.
TEVA's long-term outperformance comes amid historically low implied volatility (IV). Specifically, the equity's current SVI of 29% stands in the low 5th percentile of its annual range.
According to data from Schaeffer's Senior Quantitative ******* yst Rocky White, there have been five instances in the past five years when the equity traded within 2% of its 52-week high, while its Schaeffer's Volatility Index (SVI) ranked in the 20th percentile of its annual range or lower.
TEVA was higher one month later 80% of the time after those signals, averaging a 5.5% gain. From its current perch, a shift of this amount would put the equity back above $38 -- within a chip-shot of its August peak.
Options traders are still not convinced. This is per the equity's 10-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX), which sits higher than 96% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger more tailwinds for the shares.
#exchange
30 days ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted DPC Holdings PLC (NYSE:DPC) as a new addition. DPC Holdings PLC (NYSE:DPC) manufacturers engine products, including complex precision cast components and nickel- and cobalt-based superalloys for aerospace, industrial gas turbine and transportation industries. On September 1, 2026, DPC Holdings PLC (NYSE:DPC) closed at $41.48 per share. Over the past month, DPC Holdings PLC (NYSE:DPC) declined 20.69%. DPC Holdings PLC (NYSE:DPC) has a market capitalization of $6.02 billion.
Baron Global Opportunity Fund stated the following regarding DPC Holdings PLC (NYSE:DPC) in its Q2 2026 investor letter:
We also initiated a new position in DPC Holdings PLC (NYSE:DPC), a leading manufacturer of precision-cast superalloy components – the turbine blades, vanes, and structural castings that must perform under very harsh operating conditions including very high temperatures (1000c) and high pressure. These parts go into both commercial aircraft engines and industrial gas turbines (IGT) that generate electricity. The company occupies a hard-to-replicate market positioning as a critical supplier of the inner parts of an engine that only a handful of qualified manufacturers in the world are capable of producing.
Since the company began its turnaround in 2020 after over a decade under poor ownership, with the leadership of CEO Mike Quinn, who spent over a decade at Precision Castparts, and Co Chairperson of the Board Dirkson Charles, who built and currently is CEO of aerospace and defense proprietary parts provider

30 days ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted CrowdStrike Holdings, Inc. (NASDAQ:CRWD). CrowdStrike Holdings, Inc. (NASDAQ:CRWD), a leading cybersecurity technology company, contributed 2.23% to the fund's performance this quarter. On September 1, 2026, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) closed at $215.07 per share. Over the past month, CrowdStrike Holdings, Inc. (NASDAQ:CRWD) declined 2.01%, but its shares are up 99.08% over the past year. CrowdStrike Holdings, Inc. (NASDAQ:CRWD) has a market capitalization of $220.22 billion.
Baron Global Opportunity Fund stated the following regarding CrowdStrike Holdings, Inc. (NASDAQ:CRWD) in its Q2 2026 investor letter:
"Leading cloud-native cybersecurity platform CrowdStrike Holdings, Inc. (NASDAQ:CRWD) contributed to performance during the quarter with the stock up 95.6% as the market increasingly recognized the company as one of the primary beneficiaries of enterprise AI adoption. As organizations increasingly adopt AI, cybersecurity has moved to the forefront of C-suite concerns, and CrowdStrike is well positioned to potentially benefit as a leading platform with unmatched data and a large installed base that helps it defend better against breaches. That standing was reinforced when CrowdStrike was named a launch partner in major AI-industry security collaborations, including Anthropic's Project Glasswing and OpenAI's Trusted Access for Cyber program, underscoring its role in addressing new security challenges created by AI. This is already translating into demand. CrowdStrike's AI detection
30 days ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted Nu Holdings Ltd. (NYSE:NU). Nu Holdings Ltd. (NYSE:NU) is a leading digital banking platform, which detracted from the fund's performance this quarter. On September 01, 2026, Nu Holdings Ltd. (NYSE:NU) closed at $14.46 per share. Over the past month, Nu Holdings Ltd. (NYSE:NU) returned 3.21%, but its shares are up 0.30% over the past year. Nu Holdings Ltd. (NYSE:NU) has a market capitalization of $69.85 billion.
Baron Global Opportunity Fund stated the following regarding Nu Holdings Ltd. (NYSE:NU) in its Q2 2026 investor letter:
"Shares of Nu Holdings Ltd. (NYSE:NU) underperformed during the quarter, declining 7.1% following a weaker-than-expected 1Q26 earnings release. Provisions exceeded expectations by 37%, resulting in a 7% earnings miss and raising investor concerns about the near term outlook for credit costs and profitability. The unexpected departure of the CFO also weighed on sentiment. Concerns were further compounded by management's ambitions in the U.S., where the competitive landscape is materially more mature and the long-term returns on incremental investment remain less certain. That said, the CEO subsequently outlined a more measured approach to U.S. expansion (limiting investment to 1% of revenues over 2026-2027) and capital deployment, which provided us with greater comfort regarding execution and resource allocation. We viewed the market's reaction as an attractive opportunity to increase our position, taking advantage of the pullback in the share price. While these developm

30 days ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted Wix.com Ltd. (NASDAQ:WIX). Wix.com Ltd. (NASDAQ:WIX), a cloud-based web development platform for registered users and creators, detracted from the fund's performance this quarter. On September 1, 2026, Wix.com Ltd. (NASDAQ:WIX) closed at $88.38 per share. Over the past month, Wix.com Ltd. (NASDAQ:WIX) returned 40.93%, and its shares are down 37.09% over the past year. Wix.com Ltd. (NASDAQ:WIX) has a market capitalization of $3.7 billion.
Baron Global Opportunity Fund stated the following regarding Wix.com Ltd. (NASDAQ:WIX) in its Q2 2026 investor letter:
"Shares of Wix.com Ltd. (NASDAQ:WIX), a cloud-based platform for building and managing websites and online businesses, declined 51.0% during the second quarter. The stock came under pressure as growth in the company's core business decelerated, with bookings and new user cohorts softening relative to prior quarters. While the newer AI-driven offering (Base 44) continued to grow, it was not enough to offset slowing momentum in the established core business, raising questions about the durability of the overall growth algorithm. We had valued Wix for its combination of durable subscription revenue, expanding free cash flow, and disciplined capital returns, but the deceleration in the core business undermined a central pillar of our thesis. We have therefore exited the position during the quarter, redeploying capital toward opportunities with clearer growth trajectories."
#quarter

1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Coupang, Inc. (NYSE:CPNG). Coupang, Inc. (NYSE:CPNG), a Korean technology and e-commerce platform that operates through Product Commerce and Developing Offerings segments, detracted from the fund's performance this quarter. On August 31, 2026, Coupang, Inc. (NYSE:CPNG) closed at $16.06 per share. Over the past month, Coupang, Inc. (NYSE:CPNG) declined 4.29%, and its shares are down 43.47% over the past year. Coupang, Inc. (NYSE:CPNG) has a market capitalization of $28.87 billion, and its stock has traded within a 52-week range of $14.92 to $34.08.
Baron Fifth Avenue Growth Fund stated the following regarding Coupang, Inc. (NYSE:CPNG) in its Q2 2026 investor letter:
"Coupang, Inc. (NYSE:CPNG), Korea's largest e-commerce platform, detracted from performance with shares down 7.7%. The stock came under pressure following first-quarter results, where in-line revenue was overshadowed by softer second-quarter guidance as capacity and supply chain investments made ahead of Coupang's 2025 data breach weighed on margins while customer volumes recovered. Sentiment was further weighed down by a record KRW 624.7 billion (about US $430 million) privacy fine stemming from an investigation into the breach, while a rotation of fast money into AI and semiconductor names added to the weakness. Despite these headwinds, our conviction remains intact. We view the margin pressure as temporary, and the fine removes a key overhang and reinforces our belief that the breach does not reflect a structural loss of market share. By the end of April, Coupang recovered roughly 80% of the post-breach decline in WOW Membership (its paid subscription program), with returning members resuming prior spending levels. We continue to view Coupang as a competitively advantaged e-commerce business gaining share in its core market while scaling Taiwan operations."
#fund #baron

1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On August 31, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $147.37 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) returned 19.52%, but its shares are up 5.99% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $189.59 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Baron Fifth Avenue Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP), a leading global commerce platform serving merchants across online and offline channels, detracted from performance in the second quarter with the stock down 3.7%. The decline was driven by multiple compression (its P/E was down 8.5%11) rather than any deterioration in the underlying business or fundamental outlook. Shopify continued to post healthy growth in gross merchandise volume and revenue, which were up 30% and 32% year-on-year, respectively. Instead, the pressure reflected investor concerns about the company's long-term positioning in a future state of e-commerce that may rely more heavily on AI-driven applications than traditional websites. We view those concerns as misplaced and see Shopify as an AI winner. Two decades of proprietary data across millions of merchants provide Shopify with a strong foundation for AI tools that improve merchant outcomes. Recent product releases also embed the platform more deeply within the emerging agentic commerce ecosystem while creating new monetization opportunities. We continue to believe that Shopify is the category-defining platform for modern commerce, benefiting from durable secular growth
1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) as a notable contributor to performance. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's leading contract chip manufacturer, producing advanced semiconductors for major global technology companies. On August 31, 2026, Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) closed at $415.32 per share. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) fell 0.44% over the past month, while its shares gained 81.85% over the past 52 weeks. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) has a market capitalization of $1.97 Trillion.
Baron Fifth Avenue Growth Fund stated the following regarding Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) in its Q2 2026 investor letter:
"Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's largest contract chipmaker and the leading manufacturer of advanced logic semiconductors used in modern AI accelerators. Shares rose 41.6% during the quarter as the company continues to report stellar financial results underpinned by AI demand with revenue growth of 35% year-on-year and EPS growth of 58%, with 66% gross margins and 58% operating margins. High-performance computing now represents the majority of TSMC's business. AI demand is consuming so much leading-edge capacity that smartphone and PC production is increasingly shifting to older technology nodes, reversing a dynamic that defined the foundry industry for much of the past decade. Management also raised its full-year outlook and increased capital spending to support demand that remains well above available supply. We retain long term conviction in TSMC and view its leading-edge manufacturing monopoly, pricing power, and technology roadmap as durable advantages that support a long duration of growth."
#baron
1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On August 31, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $147.37 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) returned 19.52%, but its shares are up 5.99% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $189.59 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Baron Fifth Avenue Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP), a leading global commerce platform serving merchants across online and offline channels, detracted from performance in the second quarter with the stock down 3.7%. The decline was driven by multiple compression (its P/E was down 8.5%11) rather than any deterioration in the underlying business or fundamental outlook. Shopify continued to post healthy growth in gross merchandise volume and revenue, which were up 30% and 32% year-on-year, respectively. Instead, the pressure reflected investor concerns about the company's long-term positioning in a future state of e-commerce that may rely more heavily on AI-driven applications than traditional websites. We view those concerns as misplaced and see Shopify as an AI winner. Two decades of proprietary data across millions of merchants provide Shopify with a strong foundation for AI tools that improve merchant outcomes. Recent product releases also embed the platform more deeply within the emerging agentic commerce ecosystem while creating new monetization opportunities. We continue to believe that Shopify is the category-defining platform for modern commerce, benefiting from durable secular growth
1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) as a notable contributor to performance. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's leading contract chip manufacturer, producing advanced semiconductors for major global technology companies. On August 31, 2026, Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) closed at $415.32 per share. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) fell 0.44% over the past month, while its shares gained 81.85% over the past 52 weeks. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) has a market capitalization of $1.97 Trillion.
Baron Fifth Avenue Growth Fund stated the following regarding Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) in its Q2 2026 investor letter:
"Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's largest contract chipmaker and the leading manufacturer of advanced logic semiconductors used in modern AI accelerators. Shares rose 41.6% during the quarter as the company continues to report stellar financial results underpinned by AI demand with revenue growth of 35% year-on-year and EPS growth of 58%, with 66% gross margins and 58% operating margins. High-performance computing now represents the majority of TSMC's business. AI demand is consuming so much leading-edge capacity that smartphone and PC production is increasingly shifting to older technology nodes, reversing a dynamic that defined the foundry industry for much of the past decade. Management also raised its full-year outlook and increased capital spending to support demand that remains well above available supply. We retain long term conviction in TSMC and view its leading-edge manufacturing monopoly, pricing power, and technology roadmap as durable advantages that support a long duration of growth."
#company #fund #

1 month ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Coupang, Inc. (NYSE:CPNG). Coupang, Inc. (NYSE:CPNG), a Korean technology and e-commerce platform that operates through Product Commerce and Developing Offerings segments, detracted from the fund's performance this quarter. On August 31, 2026, Coupang, Inc. (NYSE:CPNG) closed at $16.06 per share. Over the past month, Coupang, Inc. (NYSE:CPNG) declined 4.29%, and its shares are down 43.47% over the past year. Coupang, Inc. (NYSE:CPNG) has a market capitalization of $28.87 billion, and its stock has traded within a 52-week range of $14.92 to $34.08.
Baron Fifth Avenue Growth Fund stated the following regarding Coupang, Inc. (NYSE:CPNG) in its Q2 2026 investor letter:
"Coupang, Inc. (NYSE:CPNG), Korea's largest e-commerce platform, detracted from performance with shares down 7.7%. The stock came under pressure following first-quarter results, where in-line revenue was overshadowed by softer second-quarter guidance as capacity and supply chain investments made ahead of Coupang's 2025 data breach weighed on margins while customer volumes recovered. Sentiment was further weighed down by a record KRW 624.7 billion (about US $430 million) privacy fine stemming from an investigation into the breach, while a rotation of fast money into AI and semiconductor names added to the weakness. Despite these headwinds, our conviction remains intact. We view the margin pressure as temporary, and the fine removes a key overhang and reinforces our belief that the breach does not reflect a structural loss of market share. By the end of April, Coupang recovered roughly 80% of the post-breach decline in WOW Membership (its paid subscription program), with returning members resuming prior spending levels. We continue to view Coupang as a competitively advantaged e-commerce business gaining share in its core market while scaling Taiwan operations."
#coupang #NYSE #letter

1 month ago
Hayden Capital, an investment management firm, released its second-quarter 2026 investment letter. The letter can be downloaded here. In the second quarter, the portfolio gained 6.9%, compared to the S&P 500's 15.2%. Overall, approximately 34% of the portfolio is in Asia, 43% in North America, and the rest spread across other regions. Hayden Capital remains guided by a strategy focused on high-quality franchises with stable earnings power, continuing to invest despite this year's challenging results. Their largest investments are experiencing over 40% revenue growth yet are trading at similar valuations to the broader market, indicating potential for future outperformance. The recent market corrections in AI investments have prompted a healthier perspective among investors, emphasizing the importance of strong business fundamentals. Companies are leaning towards partnerships with AI firms rather than outright replacements, ensuring better access to data and operational efficiency. Six months into the "SaaS-pocalypse," software incumbents remain resilient despite initial fears of disruption. While AI is indeed transformative, the anticipated rapid changes in markets have not materialized as quickly as expected. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hayden Capital highlighted PDD Holdings Inc. (NASDAQ:PDD). PDD Holdings Inc. (NASDAQ:PDD) is a multinational commerce group that owns and operates Pinduoduo and Temu platforms. On August 27, 2026, PDD Holdings Inc. (NASDAQ:PDD) closed at $84.69 per share. Over the past month, PDD Holdings Inc. (NASDAQ:PDD) returned 2.69%, while its shares have declined 28.31% in the last 52 weeks. PDD Holdings Inc. (NASDAQ:PDD) has a market capitalization of $120.55 billion.
Hayden Capital stated the following regarding PDD Holdings Inc. (NASDAQ:PDD) in its Q2 2026 investor letter:
"PDD Holdings Inc. (NASDAQ:PDD): Four years ago, China was still in the middle of its "zero-covid" policy, with city-wide lock-downs. US-China tensions were running high with many US institutions dumping their Chinese investments, and China's economic health remained highly uncertain.
It was against this background, that we originally invested in Pinduoduo in 2022. I believed the market was misunderstanding the company and the operating leverage inherent in the model.
#NASDAQ #hayden #capital


1 month ago
Hayden Capital, an investment management firm, released its second-quarter 2026 investment letter. The letter can be downloaded here. In the second quarter, the portfolio gained 6.9%, compared to the S&P 500's 15.2%. Overall, approximately 34% of the portfolio is in Asia, 43% in North America, and the rest spread across other regions. Hayden Capital remains guided by a strategy focused on high-quality franchises with stable earnings power, continuing to invest despite this year's challenging results. Their largest investments are experiencing over 40% revenue growth yet are trading at similar valuations to the broader market, indicating potential for future outperformance. The recent market corrections in AI investments have prompted a healthier perspective among investors, emphasizing the importance of strong business fundamentals. Companies are leaning towards partnerships with AI firms rather than outright replacements, ensuring better access to data and operational efficiency. Six months into the "SaaS-pocalypse," software incumbents remain resilient despite initial fears of disruption. While AI is indeed transformative, the anticipated rapid changes in markets have not materialized as quickly as expected. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hayden Capital highlighted MercadoLibre, Inc. (NASDAQ:MELI). MercadoLibre, Inc. (NASDAQ:MELI) operates online commerce platforms in Brazil, Mexico, Argentina, and internationally. On August 27, 2026, MercadoLibre, Inc. (NASDAQ:MELI) closed at $1,930.75 per share. Over the past month, MercadoLibre, Inc. (NASDAQ:MELI) returned 2.81%, while its shares have declined 21.92% in the last 52 weeks. MercadoLibre, Inc. (NASDAQ:MELI) has a market capitalization of $97.88 billion, and its stock has traded within a 52-week range of $1,495.00 to $2,548.50.
Hayden Capital stated the following regarding MercadoLibre, Inc. (NASDAQ:MELI) in its Q2 2026 investor letter:
"Another situation I'm following closely is MercadoLibre, Inc.'s (NASDAQ:MELI) reinvestment program in Latin America. The company has been building out same and next-day shipping, and offering free shipping on low-ticket items (those under R$19 in Brazil).
By my calculations, Mercado Libre has spent ~$2.2BN in ***** ulative reinvestment spend since mid-last year. The initiative is still early, but we're starting to see signs of it paying off. New buyers grew ~+18M over the last twelve months (+26% y/y), against a pre-investment run-rate of ~15% y/y.
#mercadolibre #second

1 month ago
Nvidia's (NVDA) stock isn't having its typical year.
No epic gains on earning reports. Nvidia stock has fallen in response to earnings in six of the past eight quarters, including the last four, per Yahoo Finance AlphaSpace ****** ysis.
No major outperformance versus the S&P 500. Nvidia's stock is up 14% year to date, while the S&P 500 (^GSPC) is up 12%.
No major outperformance versus other key players in the AI chip supply chain. Micron (MU) shares have gained a sizzling 225%. Intel (INTC) is up 138%. AMD (AMD) is up 124%.
Raymond James ****** yst Simon Leopold lists four reasons the chip king stock is stuck in neutral in a new note:
#major


1 month ago
Investments in secondaries drove returns at private foundations in 2025, according to new research by Commonfund. This may, however, be something of a mirage.
Investments in the PE secondary market, whether by acquiring secondhand fund stakes or backing managers that do, generated an average gain of 20.6% at the private foundations observed in the report, published last week by the $31.5 billion investment manager and the Council on Foundations, a nonprofit membership ***** ociation. This was the highest return of any alternative ***** et class among the 17 respondents that reported secondaries returns.
This doesn't mean that mature PE funds are once again exiting companies and throwing off cash.
Mark Hoeing, president and CEO of CF Private Equity, Commonfund's private equity arm, attributed the outperformance to secondary-market buyers' practice of purchasing ***** ets at a discount and marking them to par after purchase.
This practice has been employed against a backdrop of record secondary transaction volumes, multiplying the impact of the mark-ups in performance. Total secondary deal volume surpassed $120 billion in the first six months of 2026, a 20% jump over H1 2025, the previous record.
#private #foundations #Investments #billion

1 month ago
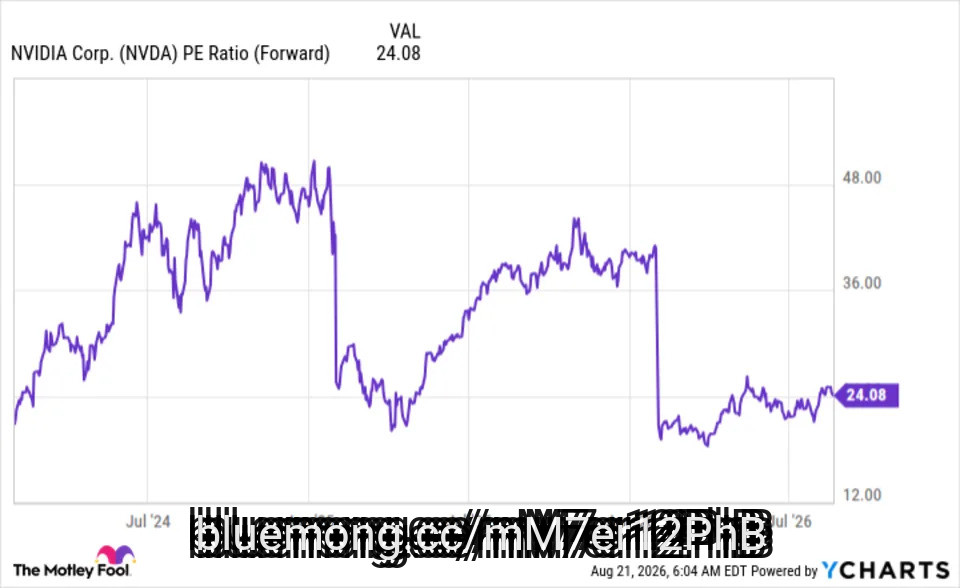
Nvidia (NASDAQ: NVDA) currently sits around a $5.25 trillion market cap -- a fair bit over second-place Apple at a $4.5 trillion market cap. However, I think this gap will widen quickly, and it all starts this week after Nvidia reports second-quarter earnings on Aug. 26.
After that, I believe that Nvidia's stock will produce a major rally, and lead to it being valued at greater than a $6 trillion valuation by the end of 2026.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That makes it a no-brainer buy before earnings, as that indicates about a 14% upside -- about double what Nvidia's stock has returned so far this year. Nvidia looks like a smart buy now, and is destined to set new records after Q2 results are available.
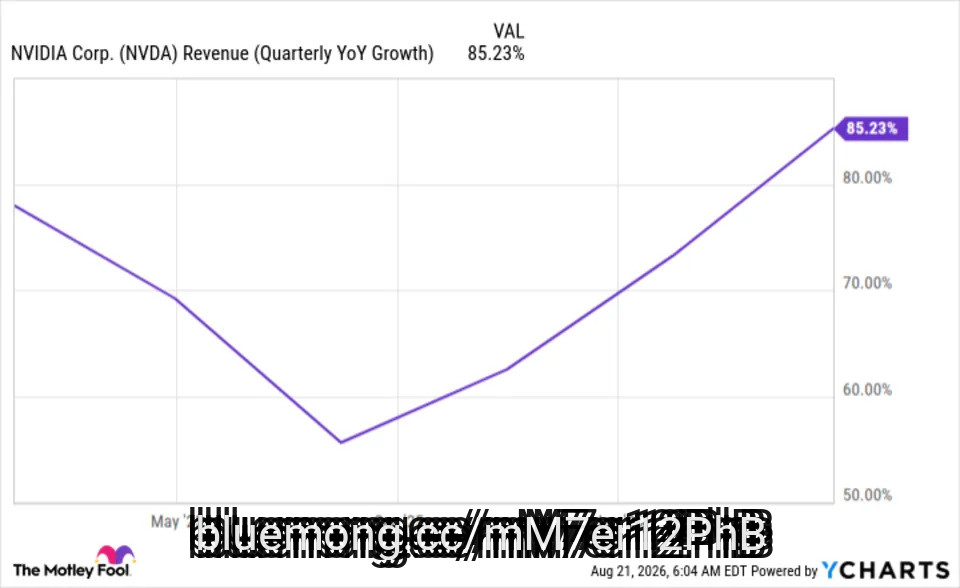
With Nvidia, exceeding expectations has become the norm. For Q4 FY 2026, Nvidia expected $65 billion in revenue; it ended up producing $68 billion. For Q1 FY 2027, management guided for $78 billion, yet Nvidia generated $82 billion. This level of outperformance has become the expectation, and with Nvidia projecting $91 billion in revenue for Q2, most investors are likely expecting something in the $93 billion to $94 billion range. Why is that a big deal? Because during Q2 of last year, Nvidia generated $46.7 billion in revenue, which would require revenue of $93.4 billion to double its revenue year over year.
#NVIDIA #billion #double #flashing

1 month ago
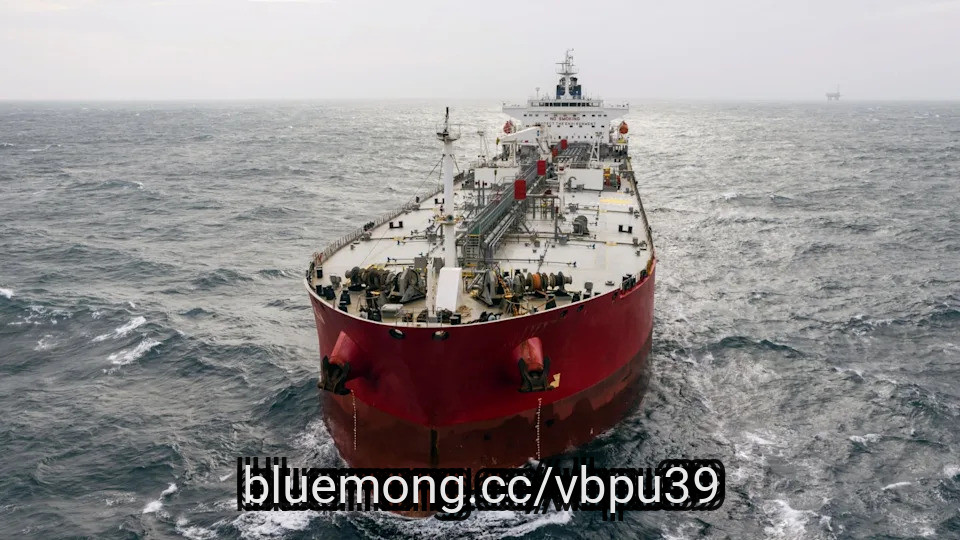
Pouyanne revealed moving a supertanker through Hormuz costs only $10 per barrel, far below what panicked investors feared.
Iraq's SOMO offered discounts up to $29.80 per barrel on Basrah crude, more than covering the $10 Hormuz shipping premium.
TotalEnergies generated $9.8 billion in Q2 cash flow and authorized $1.5 billion in buybacks while its trading arm added $500 million in outperformance.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and TotalEnergies didn't make the cut. Grab the names FREE today.
Oil has become the thread running through the global inflation story. The Iran war has disrupted production, refining, shipping, and the routes connecting them, pushing energy costs higher across transportation, manufacturing, food, and household budgets.
#NVIDIA
1 month ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was anchored by the women's business, which grew 9.5% on top of high prior-year comparisons, driven by a successful shift toward wider leg silhouettes and alternative pant categories.
Merchandise margins expanded by 110 basis points, benefiting from 65 basis points of one-time tariff refunds and 45 basis points of underlying improvement from strong regular-price selling and reduced markdowns.
The men's business remained flat as softness in higher-priced national brand denim was offset by the outperformance of private label offerings and growth in the tops category.
Buckle reported an inventory of $161 million, an increase of 13.3% from the same period in the prior year.
#basis #year #NVIDIA

1 month ago
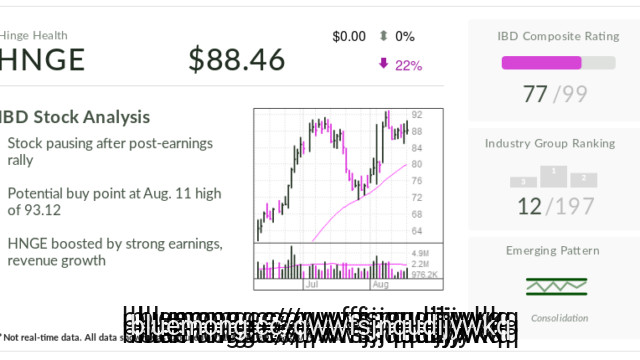
Recent initial public offering Hinge Health (HNGE) is the IPO Stock Of The Week as it continues to rebound from a key support level, while new entries are within striking distance. The healthcare stock also sits on Investor's Business Daily's IPO Leaders screen.
The San Francisco-based company offers online physical therapy and pain care for muscles and joints. It's also expanding into migraine and surgeries, and earlier this month announced a takeover of Cylinder Health for $105 million in cash. Cylinder is focused on gastrointestinal, musculoskeletal and migraine care.
Hinge, also named Wednesday's IBD Stock Of The Day, posted a 69% jump in adjusted earnings to 59 cents per share from a year ago. Revenue climbed 53% to $212.8 million for the June-ended quarter.
"This quarter's outperformance was driven by continued high member conversion and reflects our ability to deliver a great experience, improve member outcomes and lower client costs," Chief Executive Daniel Perez said in the press release.
For the full year, Wall Street expects the health services leader to earn $2.35 per share, a 10% year-over-year decline. A return to growth of 33% is anticipated in 2027, according to IBD MarketSurge.
#Stock