

2 months ago
Recent initial public offering NB Bancorp (NBBK) is the IPO Stock Of The Week as it attempts to find support at a key level and with the stock within striking distance of a new buy point. This regional banking name also sits on Investor's Business Daily's IPO Leaders screen.
Massachusetts-based NB Bancorp is the holding company for Needham Bank, which was founded in 1892.
On July 22, NB Bancorp said its earnings growth accelerated to 33% in the second quarter, up from 9% in the first quarter. That was fueled by net interest margin expansion to 4% along with solid loan and deposit growth. Revenue jumped 46% from the year-ago period, to $74.7 million.
For the third quarter, ***** ysts expect NB Bancorp to earn 59 cents per share on revenue of $77.3 million. Those are respective year-over-year increases of 30% and 49%. Also, third-quarter earnings come due in late October.
And for the full year, Wall Street expects the banking leader to earn $2.14 per share, a 25% year-over-year increase. ***** ysts see further growth of 22% in 2027, according to IBD MarketSurge.
#revenue
Massachusetts-based NB Bancorp is the holding company for Needham Bank, which was founded in 1892.
On July 22, NB Bancorp said its earnings growth accelerated to 33% in the second quarter, up from 9% in the first quarter. That was fueled by net interest margin expansion to 4% along with solid loan and deposit growth. Revenue jumped 46% from the year-ago period, to $74.7 million.
For the third quarter, ***** ysts expect NB Bancorp to earn 59 cents per share on revenue of $77.3 million. Those are respective year-over-year increases of 30% and 49%. Also, third-quarter earnings come due in late October.
And for the full year, Wall Street expects the banking leader to earn $2.14 per share, a 25% year-over-year increase. ***** ysts see further growth of 22% in 2027, according to IBD MarketSurge.
#revenue
2 months ago
On September 15, Needham ***** yst James Ricchiuti lifted the firm's price target on Teledyne Technologies Incorporated (NYSE:TDY) to $760 from $750, and reiterated a Buy rating. The revised price target reflected an upside of 27% from the close of the note.
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september


2 months ago
The most talked about and market moving research calls around Wall Street are now in one place. Here are today's research calls that investors need to know, as compiled by The Fly.
Top 5 Upgrades:
Wolfe Research upgraded Paychex (PAYX) to Peer Perform from Underperform without a price target. The firm sees reduced estimate risk for the company amid stable employment trends.
UBS upgraded Union Pacific (UNP) to Buy from Neutral with a price target of $339, up from $310. The firm says its **** ysis of key customer markets points to a second year of strong volume growth in 2027 for Union Pacific.
Needham upgraded Rocket Pharmaceuticals (RCKT) to Buy from Hold with a $9 price target after the FDA reaffirmed the pivotal study design for RP-A501 in Danon Disease, except for a recalibrated dose and prophylaxis.
Needham upgraded Similarweb (SMWB) to Buy from Hold with an $11 price target after meeting with management. Needham was encouraged by AI's potential to increase the value and consumption of Similarweb's data.
#needham #Research #union #pacific
Top 5 Upgrades:
Wolfe Research upgraded Paychex (PAYX) to Peer Perform from Underperform without a price target. The firm sees reduced estimate risk for the company amid stable employment trends.
UBS upgraded Union Pacific (UNP) to Buy from Neutral with a price target of $339, up from $310. The firm says its **** ysis of key customer markets points to a second year of strong volume growth in 2027 for Union Pacific.
Needham upgraded Rocket Pharmaceuticals (RCKT) to Buy from Hold with a $9 price target after the FDA reaffirmed the pivotal study design for RP-A501 in Danon Disease, except for a recalibrated dose and prophylaxis.
Needham upgraded Similarweb (SMWB) to Buy from Hold with an $11 price target after meeting with management. Needham was encouraged by AI's potential to increase the value and consumption of Similarweb's data.
#needham #Research #union #pacific

2 months ago
NVIDIA Corporation (NASDAQ:NVDA) has officially committed billions on AI developer platform Hugging Face for a $12.9 billion. The deal signifies the chipmaker's move beyond hardware and up the AI stack.
The AI chipmaker buying the open-source model hub millions of developers are already using reads differently when compared to Broadcom's earlier forecast to double its AI chip revenue to roughly $230 billion in fiscal 2028.
Even though AVGO is facing increased competition in Google's TPU programs, it is also gaining ground with customers such as OpenAI and Anthropic. This makes Nvidia's recent move look more like insurance rather than opportunism.
In response to the acquisition, Needham ******* yst Rajvindra Gill reiterated a Buy rating on Nvidia on September 4, ******* igning a $300.00 price target.
"Yesterday, NVIDIA announced its agreement to buy Hugging Face for $12.930BN. Hugging Face is the open source platform for hosting open source and open weight models and datasets enabling developers to easily access ready-to-use models instead of building and training them from scratch."
#developers
The AI chipmaker buying the open-source model hub millions of developers are already using reads differently when compared to Broadcom's earlier forecast to double its AI chip revenue to roughly $230 billion in fiscal 2028.
Even though AVGO is facing increased competition in Google's TPU programs, it is also gaining ground with customers such as OpenAI and Anthropic. This makes Nvidia's recent move look more like insurance rather than opportunism.
In response to the acquisition, Needham ******* yst Rajvindra Gill reiterated a Buy rating on Nvidia on September 4, ******* igning a $300.00 price target.
"Yesterday, NVIDIA announced its agreement to buy Hugging Face for $12.930BN. Hugging Face is the open source platform for hosting open source and open weight models and datasets enabling developers to easily access ready-to-use models instead of building and training them from scratch."
#developers

2 months ago
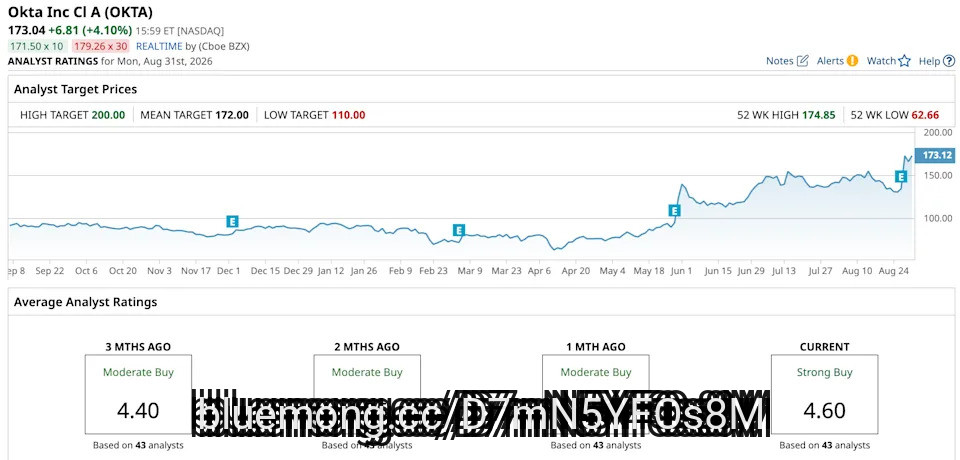
Okta (OKTA) is giving investors another reason to revisit its growth story after a stronger-than-expected second-quarter performance sparked a fresh wave of Wall Street optimism.
Needham has now raised its price target to a Street-high $200 from $140 on Aug. 27 and maintained a "Buy" rating, citing broad-based demand across Okta's Workforce and Customer Identity platforms, strength among large enterprises and momentum in newer products such as Identity Governance. The bullish call comes after Okta reported better-than-expected Q2 results and lifted its full-year outlook, with growing demand for identity security amid the rise of artificial intelligence (AI) agents adding another potential catalyst.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#street #demand
Needham has now raised its price target to a Street-high $200 from $140 on Aug. 27 and maintained a "Buy" rating, citing broad-based demand across Okta's Workforce and Customer Identity platforms, strength among large enterprises and momentum in newer products such as Identity Governance. The bullish call comes after Okta reported better-than-expected Q2 results and lifted its full-year outlook, with growing demand for identity security amid the rise of artificial intelligence (AI) agents adding another potential catalyst.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#street #demand

2 months ago
The recent recovery across digital ****** ets could have further room to run, according to Needham & Company, which has increased its crypto trading volume forecasts for the exchanges and platforms covered by the firm.
"How sustainable is the crypto rebound? We believe it has legs," ****** yst John Todaro wrote in a note to clients, identifying three factors supporting the firm's ****** sment.
The first factor is a potential rotation in investor attention and capital. Needham said artificial intelligence stocks, which previously attracted significant retail participation, have cooled as regulatory pressures increase ahead of the midterm elections.
Retail trading activity in commodities, including oil and metals, has also moderated.
Against that backdrop, Needham believes digital ****** ets could become relatively more attractive to investors again as competing speculative trades lose some of their momentum.
#Crypto #trading #company
"How sustainable is the crypto rebound? We believe it has legs," ****** yst John Todaro wrote in a note to clients, identifying three factors supporting the firm's ****** sment.
The first factor is a potential rotation in investor attention and capital. Needham said artificial intelligence stocks, which previously attracted significant retail participation, have cooled as regulatory pressures increase ahead of the midterm elections.
Retail trading activity in commodities, including oil and metals, has also moderated.
Against that backdrop, Needham believes digital ****** ets could become relatively more attractive to investors again as competing speculative trades lose some of their momentum.
#Crypto #trading #company


3 months ago
Gemini ***** e Station (NASDAQ: GEMI) stock is selling off in Monday's trading. The company's share price was down 9.1% as of 11:30 a.m. ET and had been off as much as 13.8% earlier in the session.
Gemini stock is losing ground today in response to a slew of downward price target revisions from ***** ysts. As of this writing, the company's share price has fallen roughly 64.5% year to date.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Investment firms weighed in with new coverage on Gemini ***** e Station stock today, and each newly published note delivered a downward price target revision. Rosenblatt lowered its price target from $9 per share to $6 per share, Mizuho lowered its target from $8 per share to $7 per share, Needham lowered its target from $8 per share to $6 per share, and Goldman Sachs lowered its target from $4 per share to $3.50 per share.
Rosenblatt, Mizuho, and Needham each reiterated the equivalent of a buy rating on the stock, but each firm issued a significant downward adjustment for its valuation forecast. Meanwhile, Goldman maintained its sell rating on Gemini.
#lowered
Gemini stock is losing ground today in response to a slew of downward price target revisions from ***** ysts. As of this writing, the company's share price has fallen roughly 64.5% year to date.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Investment firms weighed in with new coverage on Gemini ***** e Station stock today, and each newly published note delivered a downward price target revision. Rosenblatt lowered its price target from $9 per share to $6 per share, Mizuho lowered its target from $8 per share to $7 per share, Needham lowered its target from $8 per share to $6 per share, and Goldman Sachs lowered its target from $4 per share to $3.50 per share.
Rosenblatt, Mizuho, and Needham each reiterated the equivalent of a buy rating on the stock, but each firm issued a significant downward adjustment for its valuation forecast. Meanwhile, Goldman maintained its sell rating on Gemini.
#lowered

3 months ago
NEEDHAM — An eighth-grade Chris Vargas watched Ohio State lose to Michigan in the horseshoe.
Now he calls the Wolverines "the team up North."
Massachusetts' first ever five-star quarterback and the nation's top-rated passer in the Class of 2028 committed to the Buckeyes on August 8.
"There were always one that I had in my mind, but something just changed; like flipped the entire thing where I wanted to be at Ohio State was that last visit that I had in June," Vargas said. "It was getting around the coaches, seeing how they coach their own players, getting in the meeting room with them and seeing how they coach on the board and stuff like that."
Vargas, an incoming junior at Saint John's Prep, had more than 20 offers from the likes of Alabama, Georgia, Oregon and yes, the team up North. He gravitated to the atmosphere in Columbus and the way coach Ryan Day and his staff develop quarterbacks. Ohio State reached the Big 10 championship game last season and qualified for the College Football Playoff.
#vargas #last
Now he calls the Wolverines "the team up North."
Massachusetts' first ever five-star quarterback and the nation's top-rated passer in the Class of 2028 committed to the Buckeyes on August 8.
"There were always one that I had in my mind, but something just changed; like flipped the entire thing where I wanted to be at Ohio State was that last visit that I had in June," Vargas said. "It was getting around the coaches, seeing how they coach their own players, getting in the meeting room with them and seeing how they coach on the board and stuff like that."
Vargas, an incoming junior at Saint John's Prep, had more than 20 offers from the likes of Alabama, Georgia, Oregon and yes, the team up North. He gravitated to the atmosphere in Columbus and the way coach Ryan Day and his staff develop quarterbacks. Ohio State reached the Big 10 championship game last season and qualified for the College Football Playoff.
#vargas #last


3 months ago
Over the past few decades, the majority of media and entertainment companies were characterized by the strength and ability of their content libraries and growth in subscribers. This framework is now evolving as streaming continues to mature and advertising becomes more data-backed. As a result, investors are now focusing on companies capable of turning customer relationships into high margins. Simply put, a key shift is underway, i.e., from owning greater IP (Intellectual Property) to owning distribution, data, and consumer engagement, which can provide support in making IP more valuable.
Moving forward, the broader market will reward companies capable of bringing advertising, streaming, theme parks, merchandise, and live experiences in the single customer ecosystem. This transition has been supporting The Walt Disney Company (NYSE:DIS), with Wall Street ***** ysts becoming optimistic despite increased competition.
The company is not being valued as a movie studio or an operator of theme parks. Rather, it is being seen as a consumer ecosystem company that can bring customers throughout parks, sports, streaming, and merchandise. This thesis is further strengthened by the recent quarterly results. Its revenues saw an increase of 7% YoY to reach $25.2 billion, while total segment operating income rose 21% YoY to $5.6 billion. Furthermore, its adjusted EPS grew from $1.61 to $2.06, with management reiterating full-year outlook despite a challenging economic environment.
Apart from the numbers, the breadth of the company's consumer engagement grabbed the attention of investors and ***** ysts. Robust spending and attendance through Experiences, success in the consumer products ***** ociated with franchises like Toy Story, along with ESPN viewership gains, highlight a business model capable of monetizing the same customer throughout multiple platforms. This is exactly what the market wants. The company wants to show that the strongest ***** et is not a single movie or a streaming service, but it is the network of relationships connecting them.
An ***** yst at Needham, Laura Martin, kept a "Buy" rating on The Walt Disney Company (NYSE:DIS)'s stock with a price objective of $125. The ***** yst's reasoning is over and above the quarterly earnings. The thesis centers on the company's first-party data ecosystems, which are among the most valuable in the broader entertainment industry. It collects customer information throughout Disney+, ESPN, Hulu, cruises, theme parks, and consumer products. The management remains focused on integrating such datasets into the unified platform.
#Streaming #parks #Companies #capable
Moving forward, the broader market will reward companies capable of bringing advertising, streaming, theme parks, merchandise, and live experiences in the single customer ecosystem. This transition has been supporting The Walt Disney Company (NYSE:DIS), with Wall Street ***** ysts becoming optimistic despite increased competition.
The company is not being valued as a movie studio or an operator of theme parks. Rather, it is being seen as a consumer ecosystem company that can bring customers throughout parks, sports, streaming, and merchandise. This thesis is further strengthened by the recent quarterly results. Its revenues saw an increase of 7% YoY to reach $25.2 billion, while total segment operating income rose 21% YoY to $5.6 billion. Furthermore, its adjusted EPS grew from $1.61 to $2.06, with management reiterating full-year outlook despite a challenging economic environment.
Apart from the numbers, the breadth of the company's consumer engagement grabbed the attention of investors and ***** ysts. Robust spending and attendance through Experiences, success in the consumer products ***** ociated with franchises like Toy Story, along with ESPN viewership gains, highlight a business model capable of monetizing the same customer throughout multiple platforms. This is exactly what the market wants. The company wants to show that the strongest ***** et is not a single movie or a streaming service, but it is the network of relationships connecting them.
An ***** yst at Needham, Laura Martin, kept a "Buy" rating on The Walt Disney Company (NYSE:DIS)'s stock with a price objective of $125. The ***** yst's reasoning is over and above the quarterly earnings. The thesis centers on the company's first-party data ecosystems, which are among the most valuable in the broader entertainment industry. It collects customer information throughout Disney+, ESPN, Hulu, cruises, theme parks, and consumer products. The management remains focused on integrating such datasets into the unified platform.
#Streaming #parks #Companies #capable


3 months ago
This article was originally published on ETFTrends.com.
Robinhood Markets (HOOD) reports second-quarter results on Wednesday, July 29. That could be an ideal time for active traders to consider single-stock ETFs such as the Direxion Daily HOOD Bull 2X ETF (HODU).
Ahead of the report, traders considering this leveraged ETF should examine some of the catalysts that could move Robinhood shares. It should also be noted that HODU attempts to deliver 200% of the daily returns of the financial services stock. That is to say, this is a short-term ETF, not one that should be treated as a buy-and-hold fund.
Heading into Robinhood earnings, Wall Street is bullish on the financial services stock. On Monday, Needham reiterated a "buy" rating on the stock, while boosting its price target to $123 from $97. Citing strength across various business lines, including cryptocurrency, equities, options and prediction markets, Needham boosted its 2026 and 2027 revenue estimates on Robinhood. It noted that the brokerage firm's core retail customer remains heavily engaged with the platform.
In recent months, prediction markets have increasingly become a focal point in the Robinhood investment thesis. It's an issue for traders considering HODU to stay abreast of as well.
#hodu
Robinhood Markets (HOOD) reports second-quarter results on Wednesday, July 29. That could be an ideal time for active traders to consider single-stock ETFs such as the Direxion Daily HOOD Bull 2X ETF (HODU).
Ahead of the report, traders considering this leveraged ETF should examine some of the catalysts that could move Robinhood shares. It should also be noted that HODU attempts to deliver 200% of the daily returns of the financial services stock. That is to say, this is a short-term ETF, not one that should be treated as a buy-and-hold fund.
Heading into Robinhood earnings, Wall Street is bullish on the financial services stock. On Monday, Needham reiterated a "buy" rating on the stock, while boosting its price target to $123 from $97. Citing strength across various business lines, including cryptocurrency, equities, options and prediction markets, Needham boosted its 2026 and 2027 revenue estimates on Robinhood. It noted that the brokerage firm's core retail customer remains heavily engaged with the platform.
In recent months, prediction markets have increasingly become a focal point in the Robinhood investment thesis. It's an issue for traders considering HODU to stay abreast of as well.
#hodu
4 months ago
Celsius Holdings, Inc. (NASDAQ:CELH) is one of the 10 Fastest Growing Consumer Stocks to Buy Now.
On July 9, 2026, Needham lowered the firm's price target on Celsius Holdings, Inc. (NASDAQ:CELH) to $55 from $75 and kept a Buy rating on the shares. Needham said expectations are low heading into Q2 earnings, but the firm is cautious on the setup and lowered revenue estimates to reflect recent scanner trends for both of Celsius' driver brands. Needham said fundamentals have slowed more quickly than expected, though a significant amount of bad news is already reflected in the shares, and called the current risk/reward setup "compelling" with a cleaner 2027 ahead.
On June 30, UBS lowered the firm's price target on Celsius to $50 from $55 and kept a Buy rating on the shares. UBS said management is still optimizing SKUs and shelf ****** e, while core fruit flavors remain resilient despite weakness in newer product lines. UBS sees attractive upside from a potential return to organic revenue growth and double-digit earnings growth by 2027.
IVASHstudio/Shutterstock.com
On June 25, Roth Capital lowered the firm's price target on Celsius to $57 from $65 and kept a Buy rating on the shares. Roth reduced estimates ahead of the Q2 report to reflect slower growth in the North America energy drink category relative to 2025, and said market share for the Celsius brand continues to lag expectations. Still, Roth expects Alani to outperform the energy category and the Celsius brand to show better year-over-year performance in the back half of 2026.
On July 9, 2026, Needham lowered the firm's price target on Celsius Holdings, Inc. (NASDAQ:CELH) to $55 from $75 and kept a Buy rating on the shares. Needham said expectations are low heading into Q2 earnings, but the firm is cautious on the setup and lowered revenue estimates to reflect recent scanner trends for both of Celsius' driver brands. Needham said fundamentals have slowed more quickly than expected, though a significant amount of bad news is already reflected in the shares, and called the current risk/reward setup "compelling" with a cleaner 2027 ahead.
On June 30, UBS lowered the firm's price target on Celsius to $50 from $55 and kept a Buy rating on the shares. UBS said management is still optimizing SKUs and shelf ****** e, while core fruit flavors remain resilient despite weakness in newer product lines. UBS sees attractive upside from a potential return to organic revenue growth and double-digit earnings growth by 2027.
IVASHstudio/Shutterstock.com
On June 25, Roth Capital lowered the firm's price target on Celsius to $57 from $65 and kept a Buy rating on the shares. Roth reduced estimates ahead of the Q2 report to reflect slower growth in the North America energy drink category relative to 2025, and said market share for the Celsius brand continues to lag expectations. Still, Roth expects Alani to outperform the energy category and the Celsius brand to show better year-over-year performance in the back half of 2026.


4 months ago
The Oncology Institute, Inc. (NASDAQ:TOI) is one of the best medical care facilities stocks to buy according to ***** ysts. It ranks first by average ***** yst upside in this screen, with ***** ysts seeing roughly 46.8% upside. The latest stronger investor-relevant development came on June 17, when Needham raised its price target on the stock to $7 from $5 while maintaining a Buy rating. That followed another positive ***** yst move on June 8, when BTIG raised its price target to $8 from $7 and also kept a Buy rating.
The updates are relevant because The Oncology Institute's investment case depends on whether its community-based oncology platform can keep scaling value-based cancer care while narrowing losses and improving cash generation. The company remains smaller and riskier than large hospital operators, but the recent ***** yst target increases suggest confidence in the platform's growth outlook. For a medical care facilities list ranked by ***** yst upside, that is a cleaner hook than routine investor conference participation.
The Oncology Institute, Inc. (NASDAQ:TOI) provides community-based oncology care through clinics and affiliated locations across several U.S. states.
While we acknowledge the potential of TOI as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 33 Stocks That Should Double in 3 Years and 15 Stocks That Will Make You Rich in 10 Years.
The updates are relevant because The Oncology Institute's investment case depends on whether its community-based oncology platform can keep scaling value-based cancer care while narrowing losses and improving cash generation. The company remains smaller and riskier than large hospital operators, but the recent ***** yst target increases suggest confidence in the platform's growth outlook. For a medical care facilities list ranked by ***** yst upside, that is a cleaner hook than routine investor conference participation.
The Oncology Institute, Inc. (NASDAQ:TOI) provides community-based oncology care through clinics and affiliated locations across several U.S. states.
While we acknowledge the potential of TOI as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 33 Stocks That Should Double in 3 Years and 15 Stocks That Will Make You Rich in 10 Years.

4 months ago
Zeta Global Holdings Corp. (NYSE:ZETA) is one of the Best AI and Technology Stocks to Buy Now. On June 24, Needham maintained a "Buy" rating on the company's stock and maintained a price objective of $25. According to the firm, the company's new partnership with AI software firm Palantir remains strategically positive. The agreement focuses on combining Zeta Global Holdings Corp. (NYSE:ZETA)'s data and AI tools with Palantir's Foundry platform, which will create an enterprise marketing infrastructure.
The ****** yst believes that the key benefit is that Palantir's Foundry can improve the performance of Zeta Global Holdings Corp. (NYSE:ZETA)'s Data Cloud. This will be done through serving as the data operating layer underneath Athena. The firm views this alliance as a strategic improvement rather than an immediate financial catalyst. That being said, the agreement can result in longer-term upside.
Notably, it was earlier highlighted that Palantir and Zeta Global Holdings Corp. (NYSE:ZETA) are combining AI infrastructure with the latter's intelligent decisioning as well as trusted data. This can help bring a new standard of data-driven, agentic marketing to the enterprise.
Zeta Global Holdings Corp. (NYSE:ZETA) operates an omnichannel data-driven cloud platform, which is engaged in providing enterprises with consumer intelligence and marketing automation software.
While we acknowledge the potential of ZETA as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
The ****** yst believes that the key benefit is that Palantir's Foundry can improve the performance of Zeta Global Holdings Corp. (NYSE:ZETA)'s Data Cloud. This will be done through serving as the data operating layer underneath Athena. The firm views this alliance as a strategic improvement rather than an immediate financial catalyst. That being said, the agreement can result in longer-term upside.
Notably, it was earlier highlighted that Palantir and Zeta Global Holdings Corp. (NYSE:ZETA) are combining AI infrastructure with the latter's intelligent decisioning as well as trusted data. This can help bring a new standard of data-driven, agentic marketing to the enterprise.
Zeta Global Holdings Corp. (NYSE:ZETA) operates an omnichannel data-driven cloud platform, which is engaged in providing enterprises with consumer intelligence and marketing automation software.
While we acknowledge the potential of ZETA as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


4 months ago
CEVA, Inc. (NASDAQ:CEVA) is one of the Best Small-Cap Semiconductor Stocks to Buy Right Now. Recently, on June 15, Needham initiated CEVA, Inc. (NASDAQ:CEVA) with a Buy rating and a $55 price target.
The stock has gained roughly 4% over the past month, mainly due to the strong momentum from Q1 2026 earnings. The company witnessed licensing growth during the quarter and also raised the full-year guidance to the top end of its 8% to 12% growth range.
Needham sees CEVA as an attractive play on the emerging Physical AI sector. The firm believes that Physical AI requires a much broader set of semiconductors beyond just compute and memory. The company is well positioned in this sector and holds a 68% global market share in wireless connectivity, alongside strong positions in sensing and DSP/NPU technology.
Needham acknowledges that widespread Physical AI adoption is likely still more than two years away, but remains bullish on the stock, expecting significant upside in the near-term.
CEVA, Inc. (NASDAQ:CEVA) delivers silicon and software IP that facilitates smart edge devices to connect, sense, and process data. Established in 1999, the company is based in Rockville, Maryland.
The stock has gained roughly 4% over the past month, mainly due to the strong momentum from Q1 2026 earnings. The company witnessed licensing growth during the quarter and also raised the full-year guidance to the top end of its 8% to 12% growth range.
Needham sees CEVA as an attractive play on the emerging Physical AI sector. The firm believes that Physical AI requires a much broader set of semiconductors beyond just compute and memory. The company is well positioned in this sector and holds a 68% global market share in wireless connectivity, alongside strong positions in sensing and DSP/NPU technology.
Needham acknowledges that widespread Physical AI adoption is likely still more than two years away, but remains bullish on the stock, expecting significant upside in the near-term.
CEVA, Inc. (NASDAQ:CEVA) delivers silicon and software IP that facilitates smart edge devices to connect, sense, and process data. Established in 1999, the company is based in Rockville, Maryland.


4 months ago
We just covered The Next SanDisk: 9 Potential Breakout AI Stocks You Shouldn't Miss. Cerebras Systems (NASDAQ:CBRS) ranks #9 (see The Next SanDisk: 5 Potential Breakout AI Stocks You Shouldn't Miss).
Number of Hedge Fund Investors: N/A
Cerebras Systems (NASDAQ:CBRS) is an AI chipmaker that sells Wafer-Scale Engine (WSE-3) processors. Its customers are OpenAI and Amazon Web Services, with potential for enterprise customers down the line.
Wall Street turned bullish on the company because it makes the industry's only commercially deployed wafer-scale AI chip. Bulls point to the company's massive $24.6 billion backlog, which is 48 times Cerebras Systems (NASDAQ:CBRS) FY25 revenue of $510 million. The backlog is supported by a $20 billion three-year deal with OpenAI announced in January 2026. In that deal, OpenAI will deploy approximately 750 megawatts of Cerebras compute capacity through 2028, with an option for an additional 1.25 gigawatts. The company also has a collaboration with AWS for disaggregated inference announced in March 2026.
Cerebras Systems (NASDAQ:CBRS) expects revenue growth with a 120% forward topline CAGR through fiscal 2028 from fiscal 2025. This is based entirely on the OpenAI and AWS commitments. Morgan Stanley recently started coverage of the stock with a $250 price target and called it one of the most differentiated AI infrastructure companies with a first-mover advantage against Nvidia. UBS came out with a $300 price target and a Buy rating. Needham also came out with $300 and a Buy rating.
Number of Hedge Fund Investors: N/A
Cerebras Systems (NASDAQ:CBRS) is an AI chipmaker that sells Wafer-Scale Engine (WSE-3) processors. Its customers are OpenAI and Amazon Web Services, with potential for enterprise customers down the line.
Wall Street turned bullish on the company because it makes the industry's only commercially deployed wafer-scale AI chip. Bulls point to the company's massive $24.6 billion backlog, which is 48 times Cerebras Systems (NASDAQ:CBRS) FY25 revenue of $510 million. The backlog is supported by a $20 billion three-year deal with OpenAI announced in January 2026. In that deal, OpenAI will deploy approximately 750 megawatts of Cerebras compute capacity through 2028, with an option for an additional 1.25 gigawatts. The company also has a collaboration with AWS for disaggregated inference announced in March 2026.
Cerebras Systems (NASDAQ:CBRS) expects revenue growth with a 120% forward topline CAGR through fiscal 2028 from fiscal 2025. This is based entirely on the OpenAI and AWS commitments. Morgan Stanley recently started coverage of the stock with a $250 price target and called it one of the most differentiated AI infrastructure companies with a first-mover advantage against Nvidia. UBS came out with a $300 price target and a Buy rating. Needham also came out with $300 and a Buy rating.


4 months ago
Vicor Corporation (NASDAQ:VICR) is one of the best electrical equipment stocks to buy according to **** ysts.
On June 22, Needham maintained a Buy rating on the stock and raised its price target to $400 from $350 after Vicor's 2026 annual meeting. The note pointed to a larger long-term financial model, with management lifting its revenue target to $2.5 billion from a prior $1.0 billion, alongside 70% gross margin and 40% operating income targets. The rating is relevant to the electrical equipment theme because Vicor's growth case is tied to high-density power conversion, a bottleneck area as AI systems and advanced computing platforms draw more power at the rack and board level.
Needham also highlighted an improved second-generation VPD solution expected to sample to Cerebras in the first quarter of 2027, as well as possible second-generation VPD design wins with existing licensees that could ramp in late 2027, upside to licensing and royalty revenue, and progress toward a second ChiP fab.
Vicor Corporation (NASDAQ:VICR) designs and manufactures modular power components and power systems used in computing, communications, industrial, automotive, aerospace, and defense electronics.
While we acknowledge the potential of VICR as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
On June 22, Needham maintained a Buy rating on the stock and raised its price target to $400 from $350 after Vicor's 2026 annual meeting. The note pointed to a larger long-term financial model, with management lifting its revenue target to $2.5 billion from a prior $1.0 billion, alongside 70% gross margin and 40% operating income targets. The rating is relevant to the electrical equipment theme because Vicor's growth case is tied to high-density power conversion, a bottleneck area as AI systems and advanced computing platforms draw more power at the rack and board level.
Needham also highlighted an improved second-generation VPD solution expected to sample to Cerebras in the first quarter of 2027, as well as possible second-generation VPD design wins with existing licensees that could ramp in late 2027, upside to licensing and royalty revenue, and progress toward a second ChiP fab.
Vicor Corporation (NASDAQ:VICR) designs and manufactures modular power components and power systems used in computing, communications, industrial, automotive, aerospace, and defense electronics.
While we acknowledge the potential of VICR as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.


4 months ago
Micron Technology, Inc. (NASDAQ:MU) is one of the 15 AI Stocks ******* ysts Are Watching: Microsoft, Nvidia, and More.
With memory markets continuing to improve over the past three months, Wall Street is becoming more bullish on Micron Technology. On June 22, Needham ******* yst N. Quinn Bolton raised the price target on the stock to $1,550.00 (from $500.00) while maintaining a Buy rating.
Ahead of Micron's earnings report on 6/24, we are meaningfully raising our estimates and increasing our 12-month PT to $1,550.
Needham has highlighted how the memory market has been strengthening over the past 90 days and market fundamentals continue to demonstrate robustness. This strength has been a result of robust demand, strong pricing environment, and also limited capacity additions.
To top off these favorable conditions, the firm noted how long-term agreements being signed are offering suppliers such as Micron with better demand visibility extending over multiple years. This, in turn, reduces uncertainty around future sales which is important considering how large technology companies continue to invest heavily in AI data centers.
With memory markets continuing to improve over the past three months, Wall Street is becoming more bullish on Micron Technology. On June 22, Needham ******* yst N. Quinn Bolton raised the price target on the stock to $1,550.00 (from $500.00) while maintaining a Buy rating.
Ahead of Micron's earnings report on 6/24, we are meaningfully raising our estimates and increasing our 12-month PT to $1,550.
Needham has highlighted how the memory market has been strengthening over the past 90 days and market fundamentals continue to demonstrate robustness. This strength has been a result of robust demand, strong pricing environment, and also limited capacity additions.
To top off these favorable conditions, the firm noted how long-term agreements being signed are offering suppliers such as Micron with better demand visibility extending over multiple years. This, in turn, reduces uncertainty around future sales which is important considering how large technology companies continue to invest heavily in AI data centers.


4 months ago
The rally in Micron (MU) stock has been nothing short of a dream run. In the last 52-weeks, MU stock has returned almost 800%. The most important point about this rally is that it's not euphoria. It's purely based on fundamental developments for the company and industry.
It's therefore not surprising that ******* ysts remain bullish on Micron's stock. With Q3 results on June 24, Needham has reiterated its "Buy" rating for MU stock and increased the price target to $1,550. At the core of this bullish thesis is continued strength in the memory market and limited capacity additions. Recently, Deutsche Bank also raised Micron stock's price target to $1,500 with "AI-driven DRAM demand and pricing tailwinds" being the key factors.
D-Wave Just Unveiled a Major Quantum Breakthrough. QBTS Stock Looks Ready for Another Surge.
Micron Technology Earnings: Bull Put Spread Trade
Ahead of Micron Earnings, Here's What Barchart Data Says Comes Next for MU Stock
It's therefore not surprising that ******* ysts remain bullish on Micron's stock. With Q3 results on June 24, Needham has reiterated its "Buy" rating for MU stock and increased the price target to $1,550. At the core of this bullish thesis is continued strength in the memory market and limited capacity additions. Recently, Deutsche Bank also raised Micron stock's price target to $1,500 with "AI-driven DRAM demand and pricing tailwinds" being the key factors.
D-Wave Just Unveiled a Major Quantum Breakthrough. QBTS Stock Looks Ready for Another Surge.
Micron Technology Earnings: Bull Put Spread Trade
Ahead of Micron Earnings, Here's What Barchart Data Says Comes Next for MU Stock



4 months ago
Hailing from Brockton, AJ Dybantsa was selected number one overall by the Washington Wizards in Tuesday's NBA Draft. He's the first athlete born and raised in Massachusetts to be selected number one overall in any of the four major U.S. sports drafts (NBA, NHL, NFL, and MLB).
Dybantsa, 6'9, 217 pounds, averaged 25.5 points per game this past season with the BYU Cougars. In January, Dybantsa passed Celtics legend Danny Ainge for the most points posted by a BYU freshman in a game, recording 43 points in a 91–78 victory over Utah.
Dybantsa played high school basketball at St. Sebastian's School in Needham. He was offered scholarships from all the top universities, including Boston College, but Dybantsa said he chose BYU to play ball and keep a low profile off the court.
The son of a Jamaican immigrant mother and a father from the Republic of Congo, Dybantsa is the latest athlete produced by the "City of Champions." 80 years ago, heavyweight champion Rocky "the Brockton Blockbuster" Marciano trained at the old fire station on Pleasant Street - a building that had its electrical wiring installed by Thomas Edison. Fellow champion "Marvelous" Marvin Hagler also sculpted his legendary boxing career in Brockton. Both have statutes in the city.
Brockton also produced Ken MacAfee, a 3x All-American tight end who caught passes from Joe Montana at Notre Dame. He was third in voting for the Heisman Trophy in 1977 and won the National ****** le that same year. He played two seasons in the NFL with the San Francisco 49ers.
Dybantsa, 6'9, 217 pounds, averaged 25.5 points per game this past season with the BYU Cougars. In January, Dybantsa passed Celtics legend Danny Ainge for the most points posted by a BYU freshman in a game, recording 43 points in a 91–78 victory over Utah.
Dybantsa played high school basketball at St. Sebastian's School in Needham. He was offered scholarships from all the top universities, including Boston College, but Dybantsa said he chose BYU to play ball and keep a low profile off the court.
The son of a Jamaican immigrant mother and a father from the Republic of Congo, Dybantsa is the latest athlete produced by the "City of Champions." 80 years ago, heavyweight champion Rocky "the Brockton Blockbuster" Marciano trained at the old fire station on Pleasant Street - a building that had its electrical wiring installed by Thomas Edison. Fellow champion "Marvelous" Marvin Hagler also sculpted his legendary boxing career in Brockton. Both have statutes in the city.
Brockton also produced Ken MacAfee, a 3x All-American tight end who caught passes from Joe Montana at Notre Dame. He was third in voting for the Heisman Trophy in 1977 and won the National ****** le that same year. He played two seasons in the NFL with the San Francisco 49ers.


5 months ago
With an upside potential of 56.13%, Cellebrite DI Ltd. (NASDAQ:CLBT) ranks among the stocks under $20 that will explode. Cellebrite (NASDAQ:CLBT) received a fresh vote of confidence from Wall Street, and the timing aligns with a quarter that gave ***** ysts plenty to ***** yze.
On May 27, 2026, DA Davidson initiated coverage of Cellebrite DI Ltd. (NASDAQ:CLBT) with a "Buy" rating and a $20 price target. The firm told investors in a research note that Cellebrite's total addressable market is large, growing, and likely understated. The ***** yst pointed to multiple drivers behind continued wallet share gains, along with the company's guided acceleration in organic annualized recurring revenue growth as a key reason for the bullish call.
That initiation came shortly after Cellebrite DI Ltd. (NASDAQ:CLBT)'s first-quarter 2026 results, where revenue climbed 19% year-over-year to $128.3 million and subscription revenue rose 23% to $117.9 million. Annual Recurring Revenue reached $493.0 million, up 21% from the prior year.
Needham had also weighed in earlier, on May 15, 2026, trimming its price target on Cellebrite DI Ltd. (NASDAQ:CLBT) to $15 from $18 while keeping a "Buy" rating. The firm said the company's first-quarter results had outperformed consensus estimates across the board, though it lowered its target to reflect a compressed valuation multiple in the stock.
Looking ahead, Cellebrite DI Ltd. (NASDAQ:CLBT) guided for full-year 2026 revenue between $565 million and $571 million, with ARR expected to land between $567 million and $573 million.
On May 27, 2026, DA Davidson initiated coverage of Cellebrite DI Ltd. (NASDAQ:CLBT) with a "Buy" rating and a $20 price target. The firm told investors in a research note that Cellebrite's total addressable market is large, growing, and likely understated. The ***** yst pointed to multiple drivers behind continued wallet share gains, along with the company's guided acceleration in organic annualized recurring revenue growth as a key reason for the bullish call.
That initiation came shortly after Cellebrite DI Ltd. (NASDAQ:CLBT)'s first-quarter 2026 results, where revenue climbed 19% year-over-year to $128.3 million and subscription revenue rose 23% to $117.9 million. Annual Recurring Revenue reached $493.0 million, up 21% from the prior year.
Needham had also weighed in earlier, on May 15, 2026, trimming its price target on Cellebrite DI Ltd. (NASDAQ:CLBT) to $15 from $18 while keeping a "Buy" rating. The firm said the company's first-quarter results had outperformed consensus estimates across the board, though it lowered its target to reflect a compressed valuation multiple in the stock.
Looking ahead, Cellebrite DI Ltd. (NASDAQ:CLBT) guided for full-year 2026 revenue between $565 million and $571 million, with ARR expected to land between $567 million and $573 million.


6 months ago
Needham Raises CleanSpark Price Target on Hyperscaler Talks: Is the Bitcoin...
Needham raised its price target on CleanSpark (NASDAQ:CLSK | CLSK Price Prediction) stock to $18 from $17 while maintaining a Buy rating, after meeting with management on Monday, May 4. The catalyst: CleanSpark indicated it is in “advanced discussions” with a direct investment-grade (IG) hyperscaler customer for its data center capacity.
For investors, the price target raised by Needham reframes CleanSpark stock from a pure Bitcoin proxy into a potential artificial intelligence (AI) infrastructure host. A signed deal could re-rate the shares, but the agreement isn’t done yet.
According to Needham, CleanSpark’s hyperscaler conversations have notably progressed since earlier in fiscal year 2026, with only a few sticking points still in negotiations. That puts CleanSpark in the running to convert raw megawatts into long-duration tenant revenue.
The pivot is backed by infrastructure scale. CleanSpark’s portfolio now exceeds 1.8 GW of power, land, and data center capacity, including up to 890 MW of utility-grade power capacity in the Houston region and an advancing Sandersville, Georgia site for AI tenancy.
CleanSpark is one of the largest publicly traded Bitcoin (CRYPTO:BTC) miners, with FY2025 revenue of $766.31 million and adjusted EBITDA of $823.37 million. The company surpassed 50 EH/s of operational hashrate in June 2025, with roughly 6% of global hashrate under management.
https://247wallst.com/inve...
Needham raised its price target on CleanSpark (NASDAQ:CLSK | CLSK Price Prediction) stock to $18 from $17 while maintaining a Buy rating, after meeting with management on Monday, May 4. The catalyst: CleanSpark indicated it is in “advanced discussions” with a direct investment-grade (IG) hyperscaler customer for its data center capacity.
For investors, the price target raised by Needham reframes CleanSpark stock from a pure Bitcoin proxy into a potential artificial intelligence (AI) infrastructure host. A signed deal could re-rate the shares, but the agreement isn’t done yet.
According to Needham, CleanSpark’s hyperscaler conversations have notably progressed since earlier in fiscal year 2026, with only a few sticking points still in negotiations. That puts CleanSpark in the running to convert raw megawatts into long-duration tenant revenue.
The pivot is backed by infrastructure scale. CleanSpark’s portfolio now exceeds 1.8 GW of power, land, and data center capacity, including up to 890 MW of utility-grade power capacity in the Houston region and an advancing Sandersville, Georgia site for AI tenancy.
CleanSpark is one of the largest publicly traded Bitcoin (CRYPTO:BTC) miners, with FY2025 revenue of $766.31 million and adjusted EBITDA of $823.37 million. The company surpassed 50 EH/s of operational hashrate in June 2025, with roughly 6% of global hashrate under management.
https://247wallst.com/inve...


