3 days ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

3 days ago
On Monday, Sept. 21, Sandisk (NASDAQ:SNDK) takes a spot in the S&P 100, a subset of the S&P 500 (SNPINDEX:^GSPC) made up of 100 of its largest blue-chip companies. Dell Technologies, Palo Alto Networks, and Arista Networks enter with it. The announcement came from S&P Dow Jones Indices on Sept. 4, and the changes take effect before Monday's open.
Four companies are leaving to make room: Nike (NYSE:NKE), Colgate-Palmolive, Simon Property Group, and Honeywell Aerospace.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The swap says a lot about how 2026 has gone. Sandisk shares have gained more than 600% this year, more than any other stock in the S&P 500.
Nike's stock, meanwhile, reached a 52-week low this week. And Sandisk, worth about $260 billion, is currently more than four times the size of the roughly $54 billion sportswear giant.
#sandisk #networks #four #Companies
Four companies are leaving to make room: Nike (NYSE:NKE), Colgate-Palmolive, Simon Property Group, and Honeywell Aerospace.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The swap says a lot about how 2026 has gone. Sandisk shares have gained more than 600% this year, more than any other stock in the S&P 500.
Nike's stock, meanwhile, reached a 52-week low this week. And Sandisk, worth about $260 billion, is currently more than four times the size of the roughly $54 billion sportswear giant.
#sandisk #networks #four #Companies

5 days ago
Arista Networks (ANET) is a highly rated stock that is holding up well during the recent market weakness. Income investors who want to generate some option premium on Arista stock could look at a covered call trade.
A covered-call strategy is one way to slightly reduce the risk on a long stock position while also generating some option premium. The catch: a limited upside above the covered-call strike.
Let's look at how a covered-call trade on Arista might take shape.
Buying 100 shares of Arista Networks would cost around $19,800. An Oct. 16, 200-strike call option is trading around $10.25 a share, generating $1,025 in option premium per contract. Selling the call option generates an income of 5.2% in one month, equaling around 61% annualized.
If Arista Networks stock closes above 200 on the expiration date, the shares will be called away at 200, leaving the trader with a total profit of $1,225. That counts as the $200 gain on shares plus the $1,025 option premium received.
#option
A covered-call strategy is one way to slightly reduce the risk on a long stock position while also generating some option premium. The catch: a limited upside above the covered-call strike.
Let's look at how a covered-call trade on Arista might take shape.
Buying 100 shares of Arista Networks would cost around $19,800. An Oct. 16, 200-strike call option is trading around $10.25 a share, generating $1,025 in option premium per contract. Selling the call option generates an income of 5.2% in one month, equaling around 61% annualized.
If Arista Networks stock closes above 200 on the expiration date, the shares will be called away at 200, leaving the trader with a total profit of $1,225. That counts as the $200 gain on shares plus the $1,025 option premium received.
#option

6 days ago
Ciena stock rebounds 4% as investors reprice CEO Gary Smith's projection of a $10B backlog by fiscal year-end, despite a 19% monthly slide.
Arista rises just 2% and Cisco barely moves at 0.4%, confirming today's surge is Ciena's own order book story, not a broad networking rally.
CFO Marc Graff guided for at least 30% revenue growth next fiscal year, backed by backlog that extends beyond that period.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Ciena (NYSE:CIEN) stock is climbing early Wednesday, up 4% to $347.60. The advance is a rebound rather than a breakout, since Ciena stock is down 19% over the past month. No fresh company news landed this morning, and the market is re-pricing disclosures Ciena made at the start of September, when the company reported record quarterly results with revenue at the top end of guidance.
#backlog
Arista rises just 2% and Cisco barely moves at 0.4%, confirming today's surge is Ciena's own order book story, not a broad networking rally.
CFO Marc Graff guided for at least 30% revenue growth next fiscal year, backed by backlog that extends beyond that period.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Ciena (NYSE:CIEN) stock is climbing early Wednesday, up 4% to $347.60. The advance is a rebound rather than a breakout, since Ciena stock is down 19% over the past month. No fresh company news landed this morning, and the market is re-pricing disclosures Ciena made at the start of September, when the company reported record quarterly results with revenue at the top end of guidance.
#backlog



6 days ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
9 days ago
Dow Jones futures will open Sunday evening, along with S&P 500 futures and Nasdaq futures. Iran-related news will be focus over the weekend. The Federal Reserve meeting will take center stage this coming week, with markets largely pricing in an interest rate hike on Sept. 16.
The stock market lost ground this past week as Treasury yields and oil prices surged, but rebounded Friday following the CPI inflation report. The S&P 500 and Nasdaq in particular made bullish technical moves.
Apple (AAPL), Moderna (MRNA), NetApp (NTAP) and Arista Networks (ANET) flashed buy signals heading into the weekend, with many others setting up.
Investors can make buys, but the market remains rangebound and ****** e to rapid sector rotation.
Apple stock is on SwingTrader. Arista Networks and NetApp stock are on the IBD 50. Apple stock and NetApp are on the IBD Big Cap 20. Arista stock is on IBD Sector Leaders.
#NASDAQ #sector #weekend
The stock market lost ground this past week as Treasury yields and oil prices surged, but rebounded Friday following the CPI inflation report. The S&P 500 and Nasdaq in particular made bullish technical moves.
Apple (AAPL), Moderna (MRNA), NetApp (NTAP) and Arista Networks (ANET) flashed buy signals heading into the weekend, with many others setting up.
Investors can make buys, but the market remains rangebound and ****** e to rapid sector rotation.
Apple stock is on SwingTrader. Arista Networks and NetApp stock are on the IBD 50. Apple stock and NetApp are on the IBD Big Cap 20. Arista stock is on IBD Sector Leaders.
#NASDAQ #sector #weekend

11 days ago
Ciena surged 5% Friday to erase its post-earnings selloff, with Arista Networks also gaining 5% as money rotated into networking equipment as a group.
IYW gained just 2% and SPY 1% while networking stocks surged 4-5%, confirming the move as a targeted sector rotation, not a broad tech rally.
Ciena's 10.7% weekly gain makes it the group's swing name, where the post-earnings gap is nearly filled and further upside requires fresh buyers or a new catalyst.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Cisco Systems didn't make the cut. Enter your email to see the names that beat CSCO. The report is free. Enter your email and see if any of your stocks made the cut.
Ciena (NYSE:CIEN) stock is up 5% to $351.38 in early Friday afternoon trading, extending a rebound that's now stretched across the full week. The move reverses the post-earnings selloff that followed Ciena's September 3 fiscal third quarter release. Today's advance has effectively closed the door on the initial negative reaction to the report and pushed the stock back through the level it held before the release.
#Stock #Friday
IYW gained just 2% and SPY 1% while networking stocks surged 4-5%, confirming the move as a targeted sector rotation, not a broad tech rally.
Ciena's 10.7% weekly gain makes it the group's swing name, where the post-earnings gap is nearly filled and further upside requires fresh buyers or a new catalyst.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Cisco Systems didn't make the cut. Enter your email to see the names that beat CSCO. The report is free. Enter your email and see if any of your stocks made the cut.
Ciena (NYSE:CIEN) stock is up 5% to $351.38 in early Friday afternoon trading, extending a rebound that's now stretched across the full week. The move reverses the post-earnings selloff that followed Ciena's September 3 fiscal third quarter release. Today's advance has effectively closed the door on the initial negative reaction to the report and pushed the stock back through the level it held before the release.
#Stock #Friday



19 days ago
With a market cap of $238.7 billion, California-based Arista Networks Inc (ANET) is a leading cloud and AI networking company that provides high-performance Ethernet switching, routing, and software solutions for large data centers, AI infrastructure, cloud providers, and enterprise networks. Its flagship Extensible Operating System (EOS) gives customers a highly programmable, automated, and scalable platform for managing complex networks.
Companies valued over $200 billion are generally described as "mega-cap" stocks, and Arista Networks fits right into that category. The company has become an important player in the AI infrastructure buildout, with its high-speed networking platforms designed to connect massive AI and cloud workloads. Arista is also expanding beyond its core data-center business into campus, routing, security, and WAN networking, broadening its addressable market.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ****** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#deal #business
Companies valued over $200 billion are generally described as "mega-cap" stocks, and Arista Networks fits right into that category. The company has become an important player in the AI infrastructure buildout, with its high-speed networking platforms designed to connect massive AI and cloud workloads. Arista is also expanding beyond its core data-center business into campus, routing, security, and WAN networking, broadening its addressable market.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ****** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#deal #business
19 days ago
Cisco (CSCO) rates BUY with a $134 price target, backed by $9.3 billion in hyperscale AI orders and 40% Q4 networking order growth.
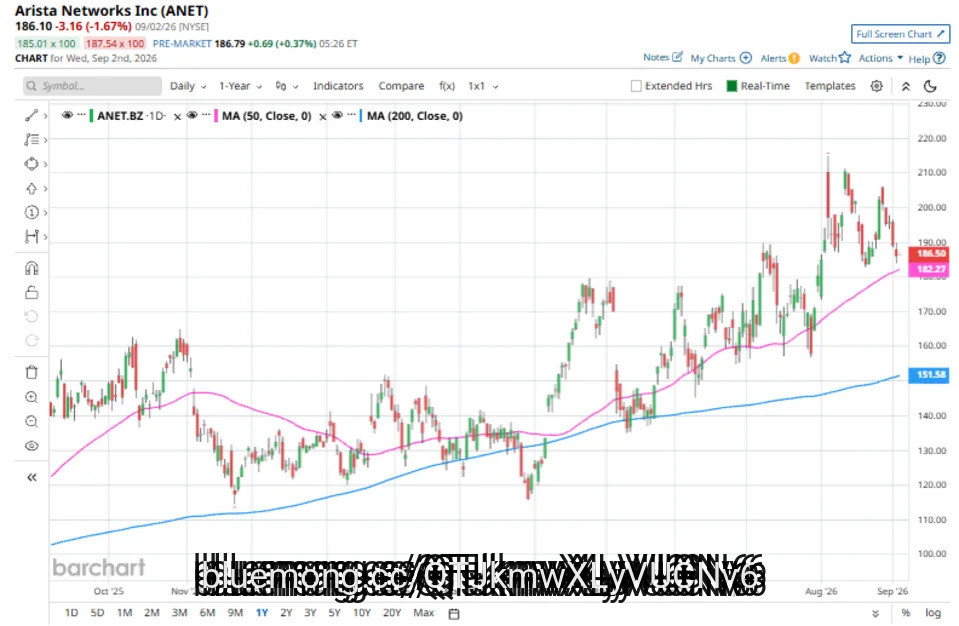
Cisco's 21x forward P/E makes it the value standout versus Arista (ANET) near 70x trailing and HPE weighed down by acquisition charges.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Cisco Systems (NASDAQ:CSCO) has quietly become one of the most important names in the AI infrastructure buildout, yet trades like a legacy networking vendor. With $9.3 billion in FY2026 hyperscale AI orders and management guiding to $7.5 billion in AI infrastructure revenue in FY2027, the setup for the next twelve months looks compelling.
Our 24/7 Wall St. price target for Cisco is $134.21, roughly 21.47% above the recent close of $110.49. Our recommendation is buy, with a high confidence rating of 90%.
#cisco #Networking
Cisco's 21x forward P/E makes it the value standout versus Arista (ANET) near 70x trailing and HPE weighed down by acquisition charges.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Cisco Systems (NASDAQ:CSCO) has quietly become one of the most important names in the AI infrastructure buildout, yet trades like a legacy networking vendor. With $9.3 billion in FY2026 hyperscale AI orders and management guiding to $7.5 billion in AI infrastructure revenue in FY2027, the setup for the next twelve months looks compelling.
Our 24/7 Wall St. price target for Cisco is $134.21, roughly 21.47% above the recent close of $110.49. Our recommendation is buy, with a high confidence rating of 90%.
#cisco #Networking


29 days ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Intuit Inc. (NASDAQ:INTU). Intuit Inc. (NASDAQ:INTU) provides financial management, payments and capital, compliance, and marketing products and services. On August 21, 2026, Intuit Inc. (NASDAQ:INTU) closed at $367.00 per share. The one-month return of Intuit Inc. (NASDAQ:INTU) was 20.76%, and its shares lost 44.14% over the past 52 weeks. Intuit Inc. (NASDAQ:INTU) has a market capitalization of $100.4 billion.
SGA Global Growth Strategy stated the following regarding Intuit Inc. (NASDAQ:INTU) in its Q2 2026 investor letter:
"We liquidated our position in Intuit Inc. (NASDAQ:INTU) during the quarter. Following the company's fiscal third quarter results, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. As a result, we exited the position and reallocated the capital to a new position in Arista Networks.
Intuit was a detractor from performance during the quarter. The company reported fiscal third quarter results that included a modest revenue beat and a full-year guidance increase, though results were overshadowed by weaker than expected Consumer Tax performance. TurboTax revenue grew 7%, below guidance, with notable weakness in the DIY segment. Management cited pressure among lower income, price sensitive filers and a contraction in total IRS filers of roughly 30 basis points. Despite double-digit revenue growth and ongoing margin expansion above 40%, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. Given these factors, we chose to exit the position and
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Intuit Inc. (NASDAQ:INTU). Intuit Inc. (NASDAQ:INTU) provides financial management, payments and capital, compliance, and marketing products and services. On August 21, 2026, Intuit Inc. (NASDAQ:INTU) closed at $367.00 per share. The one-month return of Intuit Inc. (NASDAQ:INTU) was 20.76%, and its shares lost 44.14% over the past 52 weeks. Intuit Inc. (NASDAQ:INTU) has a market capitalization of $100.4 billion.
SGA Global Growth Strategy stated the following regarding Intuit Inc. (NASDAQ:INTU) in its Q2 2026 investor letter:
"We liquidated our position in Intuit Inc. (NASDAQ:INTU) during the quarter. Following the company's fiscal third quarter results, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. As a result, we exited the position and reallocated the capital to a new position in Arista Networks.
Intuit was a detractor from performance during the quarter. The company reported fiscal third quarter results that included a modest revenue beat and a full-year guidance increase, though results were overshadowed by weaker than expected Consumer Tax performance. TurboTax revenue grew 7%, below guidance, with notable weakness in the DIY segment. Management cited pressure among lower income, price sensitive filers and a contraction in total IRS filers of roughly 30 basis points. Despite double-digit revenue growth and ongoing margin expansion above 40%, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. Given these factors, we chose to exit the position and

1 month ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Intuit Inc. (NASDAQ:INTU). Intuit Inc. (NASDAQ:INTU) provides financial management, payments and capital, compliance, and marketing products and services. On August 21, 2026, Intuit Inc. (NASDAQ:INTU) closed at $367.00 per share. The one-month return of Intuit Inc. (NASDAQ:INTU) was 20.76%, and its shares lost 44.14% over the past 52 weeks. Intuit Inc. (NASDAQ:INTU) has a market capitalization of $100.4 billion.
SGA Global Growth Strategy stated the following regarding Intuit Inc. (NASDAQ:INTU) in its Q2 2026 investor letter:
"We liquidated our position in Intuit Inc. (NASDAQ:INTU) during the quarter. Following the company's fiscal third quarter results, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. As a result, we exited the position and reallocated the capital to a new position in Arista Networks.
Intuit was a detractor from performance during the quarter. The company reported fiscal third quarter results that included a modest revenue beat and a full-year guidance increase, though results were overshadowed by weaker than expected Consumer Tax performance. TurboTax revenue grew 7%, below guidance, with notable weakness in the DIY segment. Management cited pressure among lower income, price sensitive filers and a contraction in total IRS filers of roughly 30 basis points. Despite double-digit revenue growth and ongoing margin expansion above 40%, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. Given these factors, we chose to exit the position and
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Intuit Inc. (NASDAQ:INTU). Intuit Inc. (NASDAQ:INTU) provides financial management, payments and capital, compliance, and marketing products and services. On August 21, 2026, Intuit Inc. (NASDAQ:INTU) closed at $367.00 per share. The one-month return of Intuit Inc. (NASDAQ:INTU) was 20.76%, and its shares lost 44.14% over the past 52 weeks. Intuit Inc. (NASDAQ:INTU) has a market capitalization of $100.4 billion.
SGA Global Growth Strategy stated the following regarding Intuit Inc. (NASDAQ:INTU) in its Q2 2026 investor letter:
"We liquidated our position in Intuit Inc. (NASDAQ:INTU) during the quarter. Following the company's fiscal third quarter results, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. As a result, we exited the position and reallocated the capital to a new position in Arista Networks.
Intuit was a detractor from performance during the quarter. The company reported fiscal third quarter results that included a modest revenue beat and a full-year guidance increase, though results were overshadowed by weaker than expected Consumer Tax performance. TurboTax revenue grew 7%, below guidance, with notable weakness in the DIY segment. Management cited pressure among lower income, price sensitive filers and a contraction in total IRS filers of roughly 30 basis points. Despite double-digit revenue growth and ongoing margin expansion above 40%, we became increasingly concerned with the DIY Tax weakness, continued deterioration in Mailchimp, and reduced visibility on the timing of any growth reacceleration, as well as management's ability to execute in a challenging environment. Given these factors, we chose to exit the position and


1 month ago
Brown Brothers Harriman, an investment management company, released its Q2 2026 investor letter for the "BBH Select Mid Cap ETF". A copy of the letter can be downloaded here. In the quarter, the fund increased 9.7% on a total return basis compared to the Russell Midcap Index's 13.8% return. Artificial intelligence is a key factor influencing market performance, with high-valuation and high-beta companies consistently outperforming others. The portfolio saw gains from being overweight in technology and industrials but missed opportunities due to underweighting more cyclical stocks. At the end of Q2 2026, the Fund held positions in 27 companies, with 48% of **** ets concentrated in the top 10 holdings. The Fund's strategy focuses on companies priced below intrinsic value to ensure a margin of safety, rather than on whether valuations are high or low. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, BBH Select Series – Mid Cap ETF highlighted Entegris, Inc. (NASDAQ:ENTG). Headquartered in Billerica, Massachusetts, Entegris, Inc. (NASDAQ:ENTG) provides materials and process solutions for the semiconductor and other high-technology industries. On August 19, 2026, Entegris, Inc. (NASDAQ:ENTG) closed at $144.28 per share, reflecting a market capitalization of $22.05 billion. Entegris, Inc. (NASDAQ:ENTG) posted a one‑month return of 6.64%, while its shares gained 75.76% over the past 52 weeks.
BBH Select Series – Mid Cap ETF stated the following regarding Entegris, Inc. (NASDAQ:ENTG) in its Q2 2026 investor letter:
"For the quarter, the Fund's largest positive contributors were Entegris, Inc. (NASDAQ:ENTG) and Arista Networks Inc. (Arista), both clear beneficiaries of the AI infrastructure buildout. Entegris returned 53.5% during the quarter, ending with a weight of 6.4%. Entegris is a key supplier to the semiconductor industry of essential filtration products, materials, and related delivery equipment that enables the high precision fabrication of semiconductor chips. Entegris reported strong first quarter 2026 results and provided second quarter guidance above consensus with accelerating growth in second and third quarter 2026. This matches an upgraded view of industry end markets, with wafer volumes now expected to grow mid- to-high-single digits for 2026 and fab construction to grow high-single digits, both of which were low-single digits expectations just last quarter. Relatively new CEO Dave Reeder indicated a focus on gross margins when he started, and that is evident from the substantial im provement in first quarter 2026 that is expected to continue over the year. Gross margin of 46.9% was significantly above guidance of 44.5-45.5% and increased 310 basis points (bps)1 from fourth quarter 2025. Lastly, Entegris now aims to bring net leverage to 3.0x by year end, driven by robust free cash flow of at least $450m."
#entg #select
In its Q2 2026 investor letter, BBH Select Series – Mid Cap ETF highlighted Entegris, Inc. (NASDAQ:ENTG). Headquartered in Billerica, Massachusetts, Entegris, Inc. (NASDAQ:ENTG) provides materials and process solutions for the semiconductor and other high-technology industries. On August 19, 2026, Entegris, Inc. (NASDAQ:ENTG) closed at $144.28 per share, reflecting a market capitalization of $22.05 billion. Entegris, Inc. (NASDAQ:ENTG) posted a one‑month return of 6.64%, while its shares gained 75.76% over the past 52 weeks.
BBH Select Series – Mid Cap ETF stated the following regarding Entegris, Inc. (NASDAQ:ENTG) in its Q2 2026 investor letter:
"For the quarter, the Fund's largest positive contributors were Entegris, Inc. (NASDAQ:ENTG) and Arista Networks Inc. (Arista), both clear beneficiaries of the AI infrastructure buildout. Entegris returned 53.5% during the quarter, ending with a weight of 6.4%. Entegris is a key supplier to the semiconductor industry of essential filtration products, materials, and related delivery equipment that enables the high precision fabrication of semiconductor chips. Entegris reported strong first quarter 2026 results and provided second quarter guidance above consensus with accelerating growth in second and third quarter 2026. This matches an upgraded view of industry end markets, with wafer volumes now expected to grow mid- to-high-single digits for 2026 and fab construction to grow high-single digits, both of which were low-single digits expectations just last quarter. Relatively new CEO Dave Reeder indicated a focus on gross margins when he started, and that is evident from the substantial im provement in first quarter 2026 that is expected to continue over the year. Gross margin of 46.9% was significantly above guidance of 44.5-45.5% and increased 310 basis points (bps)1 from fourth quarter 2025. Lastly, Entegris now aims to bring net leverage to 3.0x by year end, driven by robust free cash flow of at least $450m."
#entg #select

1 month ago
Brown Brothers Harriman, an investment management company, released its Q2 2026 investor letter for the "BBH Select Mid Cap ETF". A copy of the letter can be downloaded here. In the quarter, the fund increased 9.7% on a total return basis compared to the Russell Midcap Index's 13.8% return. Artificial intelligence is a key factor influencing market performance, with high-valuation and high-beta companies consistently outperforming others. The portfolio saw gains from being overweight in technology and industrials but missed opportunities due to underweighting more cyclical stocks. At the end of Q2 2026, the Fund held positions in 27 companies, with 48% of ******* ets concentrated in the top 10 holdings. The Fund's strategy focuses on companies priced below intrinsic value to ensure a margin of safety, rather than on whether valuations are high or low. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its Q2 2026 investor letter, BBH Select Mid Cap ETF highlighted Arista Networks, Inc. (NYSE:ANET) as one of its leading performance contributors. Arista Networks, Inc. (NYSE:ANET) is a high-speed switching and cloud networking solutions provider for hyperscale users. On August 19, 2026, Arista Networks, Inc. (NYSE:ANET) closed at $186.45 per share, reflecting a market capitalization of $235.15 billion. Arista Networks, Inc. (NYSE:ANET) posted a one‑month return of 5.94%, while its shares gained 41.71% over the past 52 weeks.
BBH Select Mid Cap ETF stated the following regarding Arista Networks, Inc. (NYSE:ANET) in its Q2 2026 investor letter:
"For the quarter, the Fund's largest positive contributors were Entegris Inc. (Entegris) and Arista Networks, Inc. (NYSE:ANET), both clear beneficiaries of the AI infrastructure buildout. Arista returned 38.4% during the quarter, ending with a weight of 5.1%. Arista is the leading provider of data center switches to cloud network customers. Arista reported strong first quarter results with record revenue and free cash flow ahead of expectations, but guidance fell short of high expectations due to increasing supply chain short ages. In addition, extended customer acceptance cycles on new AI products have pushed a growing volume of contracted demand into deferred revenue ahead of recognition, temporarily understating reported revenue growth and creating some investor confusion. However, management subsequently clarified this dynamic, clearly delin eating 54% growth inclusive of deferred product revenue. Management also expressed confidence in the outlook for 2026 along with a constructive demand backdrop for 2027. Finally, rising component costs are an industry-wide challenge, but Arista's multiyear supply commitments and execution track record leave us confident in their ability to execute throughout the next several years. Gross margin guidance of 62% to 64% was maintained despite the rising input cost pressures. Management also continues to expect one or pos
In its Q2 2026 investor letter, BBH Select Mid Cap ETF highlighted Arista Networks, Inc. (NYSE:ANET) as one of its leading performance contributors. Arista Networks, Inc. (NYSE:ANET) is a high-speed switching and cloud networking solutions provider for hyperscale users. On August 19, 2026, Arista Networks, Inc. (NYSE:ANET) closed at $186.45 per share, reflecting a market capitalization of $235.15 billion. Arista Networks, Inc. (NYSE:ANET) posted a one‑month return of 5.94%, while its shares gained 41.71% over the past 52 weeks.
BBH Select Mid Cap ETF stated the following regarding Arista Networks, Inc. (NYSE:ANET) in its Q2 2026 investor letter:
"For the quarter, the Fund's largest positive contributors were Entegris Inc. (Entegris) and Arista Networks, Inc. (NYSE:ANET), both clear beneficiaries of the AI infrastructure buildout. Arista returned 38.4% during the quarter, ending with a weight of 5.1%. Arista is the leading provider of data center switches to cloud network customers. Arista reported strong first quarter results with record revenue and free cash flow ahead of expectations, but guidance fell short of high expectations due to increasing supply chain short ages. In addition, extended customer acceptance cycles on new AI products have pushed a growing volume of contracted demand into deferred revenue ahead of recognition, temporarily understating reported revenue growth and creating some investor confusion. However, management subsequently clarified this dynamic, clearly delin eating 54% growth inclusive of deferred product revenue. Management also expressed confidence in the outlook for 2026 along with a constructive demand backdrop for 2027. Finally, rising component costs are an industry-wide challenge, but Arista's multiyear supply commitments and execution track record leave us confident in their ability to execute throughout the next several years. Gross margin guidance of 62% to 64% was maintained despite the rising input cost pressures. Management also continues to expect one or pos


1 month ago
Networking equipment and software provider Arista Networks, Inc. (NYSE:ANET) is one of Cramer's favorite stocks. In fact, as far back as February 2025, the CNBC TV host remarked that going against Arista Networks, Inc. (NYSE:ANET) and its CEO meant an "invitation to your funeral." The shares are up by 49% over the past year and by 52% year-to-date. Over the month, they are up by 11.5% and closed 3.6% higher on August 5th, the day after Arista Networks, Inc. (NYSE:ANET)'s second quarter earnings report. Yet, as the shares dipped on the 6th, Cramer called the move profit taking:
"I was talking to Jayshree Ullal yesterday, for ANET, which is just a fantastic company, had an amazing quarter. And she's on the board of Snowflake. And I just said, no one noticed that Snowflake just goes up and up and up. That's the kind of thing that is coming up for profit taking taking today. As is ANET. As is Arista. And I just say, okay, wait a second, this is a take your breath moment. These companies are all doing really, really well. Or they have, like the long term agreement kind of thing with Western Digital. This is a profit taking thing, Carl. And I think that this is blessed. You want this."
Arista Networks, Inc. (NYSE:ANET) reported $3.04 billion in revenue and $1.02 in earnings per share for its second quarter and beat ***** yst estimates for both. The firm's third quarter revenue forecast of $3.3 billion also beat the estimates. With Arista Networks, Inc. (NYSE:ANET) counting tech giant such as Microsoft and Amazon, the healthy results indicated the strength of the ongoing AI buildout. The strength of the buildout and the firm's role in it is also key to the investment debate. With Arista Networks, Inc. (NYSE:ANET)'s competency in Ethernet networks, a faster switch to the technology can help the firm. Additionally, the firm also benefits from strong margins (63.4% non-GAAP gross margin in Q2) courtesy of its software model. Yet, at the same time, the fact that Arista Networks, Inc. (NYSE:ANET) relies on a few big-tech customers, which might switch to custom products creates risk that might not be reflected through the forward P/E of 46.73.
Snowflake Inc. (NYSE:SNOW), on the other hand, is a classic software-as-a-service (SaaS) firm. It enables data management and warehousing. Its data business benefits the firm in today's AI era, as it enables users to use their own data to create AI models. Consequently, Snowflake Inc. (NYSE:SNOW)'s net revenue retention (NRR) was 126% in its FY27Q1. Additionally, the firm had 779 customers with trailing 12-month product revenue greater than $1 million in the same quarter. While these figures point towards a robust business, if spending slows due to concerns about AI's returns or if platforms such as DataBricks and Google's BigQuery step up competition, the firm could struggle. For a firm with a forward. P/E of 169, there's little room for error.
#software
"I was talking to Jayshree Ullal yesterday, for ANET, which is just a fantastic company, had an amazing quarter. And she's on the board of Snowflake. And I just said, no one noticed that Snowflake just goes up and up and up. That's the kind of thing that is coming up for profit taking taking today. As is ANET. As is Arista. And I just say, okay, wait a second, this is a take your breath moment. These companies are all doing really, really well. Or they have, like the long term agreement kind of thing with Western Digital. This is a profit taking thing, Carl. And I think that this is blessed. You want this."
Arista Networks, Inc. (NYSE:ANET) reported $3.04 billion in revenue and $1.02 in earnings per share for its second quarter and beat ***** yst estimates for both. The firm's third quarter revenue forecast of $3.3 billion also beat the estimates. With Arista Networks, Inc. (NYSE:ANET) counting tech giant such as Microsoft and Amazon, the healthy results indicated the strength of the ongoing AI buildout. The strength of the buildout and the firm's role in it is also key to the investment debate. With Arista Networks, Inc. (NYSE:ANET)'s competency in Ethernet networks, a faster switch to the technology can help the firm. Additionally, the firm also benefits from strong margins (63.4% non-GAAP gross margin in Q2) courtesy of its software model. Yet, at the same time, the fact that Arista Networks, Inc. (NYSE:ANET) relies on a few big-tech customers, which might switch to custom products creates risk that might not be reflected through the forward P/E of 46.73.
Snowflake Inc. (NYSE:SNOW), on the other hand, is a classic software-as-a-service (SaaS) firm. It enables data management and warehousing. Its data business benefits the firm in today's AI era, as it enables users to use their own data to create AI models. Consequently, Snowflake Inc. (NYSE:SNOW)'s net revenue retention (NRR) was 126% in its FY27Q1. Additionally, the firm had 779 customers with trailing 12-month product revenue greater than $1 million in the same quarter. While these figures point towards a robust business, if spending slows due to concerns about AI's returns or if platforms such as DataBricks and Google's BigQuery step up competition, the firm could struggle. For a firm with a forward. P/E of 169, there's little room for error.
#software

1 month ago
At $157.8 billion, FCNTX's scale forces it into mega-caps, with six tech giants alone consuming 35% of the portfolio.
Arista Networks (ANET) and Amphenol (APH) deliver the fund's real contrarian edge, returning 795% and 370% over five years.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and FCNTX didn't make the cut. Grab the names FREE today.
Fidelity Contrafund's contrarian pitch runs into a $157.8 billion problem: the fund is so big that its bets against the crowd often are the crowd.
Fidelity Contrafund (NASDAQ:FCNTX) is an actively managed large-cap growth mutual fund whose 428 positions mix mega-cap tech, a few defensive value names, and a rare slate of private-market stakes. As of the fund's March 31, 2026 NPORT filing, the top 10 holdings represent 45.66% of net ***** ets, and the combined Meta, Nvidia, Amazon, Microsoft, Apple, and Alphabet stack alone accounts for 34.65% of the portfolio. That is broad-market leadership wearing an active manager's badge.
#fcntx #alone #Portfolio
Arista Networks (ANET) and Amphenol (APH) deliver the fund's real contrarian edge, returning 795% and 370% over five years.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and FCNTX didn't make the cut. Grab the names FREE today.
Fidelity Contrafund's contrarian pitch runs into a $157.8 billion problem: the fund is so big that its bets against the crowd often are the crowd.
Fidelity Contrafund (NASDAQ:FCNTX) is an actively managed large-cap growth mutual fund whose 428 positions mix mega-cap tech, a few defensive value names, and a rare slate of private-market stakes. As of the fund's March 31, 2026 NPORT filing, the top 10 holdings represent 45.66% of net ***** ets, and the combined Meta, Nvidia, Amazon, Microsoft, Apple, and Alphabet stack alone accounts for 34.65% of the portfolio. That is broad-market leadership wearing an active manager's badge.
#fcntx #alone #Portfolio

1 month ago
Cisco Systems (NASDAQ:CSCO), a global networking hardware and security provider, closed at $113.47, down 8.40%. The stock fell after better-than-expected fiscal fourth-quarter results and guidance, but investors are focusing on margin pressure, even as the stock is still up nearly 50% this year.
Trading volume reached 61.1 million shares, coming in about 137% above its three-month average of 25.7 million shares.
The S&P 500 (SNPINDEX:^GSPC) rose 0.65% to 7,799, and the Nasdaq Composite (NASDAQINDEX:^IXIC) gained 0.81% to 26,803. In networking equipment and enterprise communications technology, Arista Networks (NYSE:ANET) fell 3.27% to $203.62, while Hewlett Packard Enterprise (NYSE:HPE) rose 1.75% to $59.82 as investors weighed Cisco Systems' earnings reaction and broader spending trends.
Investors approached Cisco's fiscal fourth-quarter earnings with high expectations for the company. Cisco stock was up 60% year-to-date entering today's trading. While the company delivered record top and bottom-line results, total (non-GAAP) gross margin for the quarter dropped to 66.3% from last year's 68.4%. This decline was partly attributed to the increased cost of components used in AI hardware, such as memory.
AI-related demand remains strong, however. Some **** ysts also noted the decline in gross margin, but suggested that operating margins would expand in fiscal 2027. This expansion could result in profits growing faster than revenue.
That may make today's plunge a good opportunity to at least begin a position in Cisco stock.
#cisco #quarter #trading
Trading volume reached 61.1 million shares, coming in about 137% above its three-month average of 25.7 million shares.
The S&P 500 (SNPINDEX:^GSPC) rose 0.65% to 7,799, and the Nasdaq Composite (NASDAQINDEX:^IXIC) gained 0.81% to 26,803. In networking equipment and enterprise communications technology, Arista Networks (NYSE:ANET) fell 3.27% to $203.62, while Hewlett Packard Enterprise (NYSE:HPE) rose 1.75% to $59.82 as investors weighed Cisco Systems' earnings reaction and broader spending trends.
Investors approached Cisco's fiscal fourth-quarter earnings with high expectations for the company. Cisco stock was up 60% year-to-date entering today's trading. While the company delivered record top and bottom-line results, total (non-GAAP) gross margin for the quarter dropped to 66.3% from last year's 68.4%. This decline was partly attributed to the increased cost of components used in AI hardware, such as memory.
AI-related demand remains strong, however. Some **** ysts also noted the decline in gross margin, but suggested that operating margins would expand in fiscal 2027. This expansion could result in profits growing faster than revenue.
That may make today's plunge a good opportunity to at least begin a position in Cisco stock.
#cisco #quarter #trading


1 month ago
Santa Clara, California-based Arista Networks, Inc. (ANET) engages in the development, marketing, and sale of data-driven, client-to-cloud networking solutions for AI, data center, campus, and routing environments in the Americas and internationally. The company has a market cap of $238 billion and offers cloud networking solutions consisting of Extensible Operating System (EOS), a publish-subscribe state-sharing networking operating system offered in combination with a set of network applications and more.
ANET stock has rallied the broader market over the past year, surging 36.4% compared to the S&P 500 Index's ($SPX) 22.4% surge. Moreover, in 2026, the stock has grown by nearly 44.9%, outpacing the SPX's 13.3% rise.
Don't ****** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Why Didn't a $100 Billion Lockup Expiration Crash ****** eX Stock? 3 Numbers That Explain Its 10% Rally.
#billion #cloud
ANET stock has rallied the broader market over the past year, surging 36.4% compared to the S&P 500 Index's ($SPX) 22.4% surge. Moreover, in 2026, the stock has grown by nearly 44.9%, outpacing the SPX's 13.3% rise.
Don't ****** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Why Didn't a $100 Billion Lockup Expiration Crash ****** eX Stock? 3 Numbers That Explain Its 10% Rally.
#billion #cloud


1 month ago
One company powers the world's creative output, while the other builds the high-speed digital highways that make modern artificial intelligence possible. Choosing between Adobe (NASDAQ:ADBE) and Arista Networks (NYSE:ANET) means weighing software stability against infrastructure growth.
Adobe provides the essential software suite for digital creators, while Arista dominates the high-performance networking equipment market for data centers. Both companies are pivotal to the artificial intelligence revolution, though they play very different roles. Investors can compare them to decide whether to prioritize established software platforms or the hardware infrastructure powering the cloud.
Adobe is a ****** an among tech stocks, providing essential tools for digital creation, document management, and marketing ****** ytics. Its recent acquisitions of Semrush and Topaz Labs aim to boost AI-driven content marketing and image enhancement capabilities. These strategic moves help the company serve a massive base of 50 million Behance community members and global enterprise clients.
In its 2025 fiscal year (FY), revenue reached $23.8 billion, representing 10.5% growth over the previous year. The company reported net income of $7.1 billion for the same period. This resulted in a net margin of 30%, which measures the portion of revenue that remains as profit after all expenses are paid.
As of its November 2025 balance sheet, the debt-to-equity ratio was 0.6x. This metric shows the relationship between total debt and shareholder equity, indicating a manageable level of leverage. The current ratio of 1.0x shows the company can meet its immediate financial obligations, while free cash flow reached $9.9 billion for the year, which is the cash a business has left after paying for operating costs and equipment.
#billion #arista #artificial
Adobe provides the essential software suite for digital creators, while Arista dominates the high-performance networking equipment market for data centers. Both companies are pivotal to the artificial intelligence revolution, though they play very different roles. Investors can compare them to decide whether to prioritize established software platforms or the hardware infrastructure powering the cloud.
Adobe is a ****** an among tech stocks, providing essential tools for digital creation, document management, and marketing ****** ytics. Its recent acquisitions of Semrush and Topaz Labs aim to boost AI-driven content marketing and image enhancement capabilities. These strategic moves help the company serve a massive base of 50 million Behance community members and global enterprise clients.
In its 2025 fiscal year (FY), revenue reached $23.8 billion, representing 10.5% growth over the previous year. The company reported net income of $7.1 billion for the same period. This resulted in a net margin of 30%, which measures the portion of revenue that remains as profit after all expenses are paid.
As of its November 2025 balance sheet, the debt-to-equity ratio was 0.6x. This metric shows the relationship between total debt and shareholder equity, indicating a manageable level of leverage. The current ratio of 1.0x shows the company can meet its immediate financial obligations, while free cash flow reached $9.9 billion for the year, which is the cash a business has left after paying for operating costs and equipment.
#billion #arista #artificial

2 months ago
Markets enter an earnings-dominated week with a huge concentration of corporate results spanning technology, industrials, healthcare, consumer discretionary, and entertainment sectors.
This will provide a critical ******* sment of economic health and corporate fundamentals amid persistent uncertainty about technology sector valuations and AI infrastructure spending.
Apple Delivers Strong Free Cash Flow, But What is the Best AAPL Play?
Stop Missing Market Moves: Get the FREE Barchart Brief – your midday dose of stock movers, trending sectors, and actionable trade ideas, delivered right to your inbox. Sign Up Now!
The earnings calendar features major reports from ******* eX (SPCX), Advanced Micro Devices (AMD), Palantir Technologies (PLTR), Pfizer (PFE), McDonald's (MCD), Arista Networks (ANET), Caterpillar (CAT), Spotify (SPOT), Merck (MRK), SanDisk (SNDK), Uber Technology (UBER), AppLovin (APP), Shopify (SHOP), Disney (DIS), and Eli Lilly (LLY).
#earnings #corporate #delivers
This will provide a critical ******* sment of economic health and corporate fundamentals amid persistent uncertainty about technology sector valuations and AI infrastructure spending.
Apple Delivers Strong Free Cash Flow, But What is the Best AAPL Play?
Stop Missing Market Moves: Get the FREE Barchart Brief – your midday dose of stock movers, trending sectors, and actionable trade ideas, delivered right to your inbox. Sign Up Now!
The earnings calendar features major reports from ******* eX (SPCX), Advanced Micro Devices (AMD), Palantir Technologies (PLTR), Pfizer (PFE), McDonald's (MCD), Arista Networks (ANET), Caterpillar (CAT), Spotify (SPOT), Merck (MRK), SanDisk (SNDK), Uber Technology (UBER), AppLovin (APP), Shopify (SHOP), Disney (DIS), and Eli Lilly (LLY).
#earnings #corporate #delivers


2 months ago
A finance employee at the global design firm Arup transferred $25.6 million in a deepfake fraud after joining a video call with synthetic versions of senior executives. The faces looked real. The voices sounded real. The instructions were false.
That was not an isolated warning. Starbucks quietly retired an AI inventory system only nine months after deployment after baristas reported that it miscounted products and slowed their work. Deloitte's Australian member firm agreed to partially refund the government for a $290,000 AI-assisted report that included nonexistent academic sources and a fabricated court quotation. Different industries. Different technologies. The same failure: people could not trust the output, the identity, or the system.
Trust is becoming a form of economic infrastructure. Companies that cannot engineer it will move slower, spend more, and lose markets. When trust is strong, capital moves, partnerships form, and companies scale. When it breaks, transactions slow, compliance and insurance costs rise, and leaders retreat from risk.
Trust is not blind faith. It is earned confidence that facts are real, identities are authentic, systems are secure, contracts will be honored, and someone will be accountable when things go wrong. In business terms, trust reduces friction. In strategic terms, it creates speed.
As America marks its 250th anniversary, we should remember that trust was not a side note to the founding. It was the bet. In my first three essays in this Freedom & Enterprise series, I described the Declaration of Independence as America's first founding bet, the system it created as one that let people build free, and the freedom to fail as one of our greatest competitive advantages. Beneath all three is a more fundamental principle: America trusted free people to govern themselves, take risks, honor commitments, and build institutions strong enough to survive disagreement.
#trust #different #America #freedom
That was not an isolated warning. Starbucks quietly retired an AI inventory system only nine months after deployment after baristas reported that it miscounted products and slowed their work. Deloitte's Australian member firm agreed to partially refund the government for a $290,000 AI-assisted report that included nonexistent academic sources and a fabricated court quotation. Different industries. Different technologies. The same failure: people could not trust the output, the identity, or the system.
Trust is becoming a form of economic infrastructure. Companies that cannot engineer it will move slower, spend more, and lose markets. When trust is strong, capital moves, partnerships form, and companies scale. When it breaks, transactions slow, compliance and insurance costs rise, and leaders retreat from risk.
Trust is not blind faith. It is earned confidence that facts are real, identities are authentic, systems are secure, contracts will be honored, and someone will be accountable when things go wrong. In business terms, trust reduces friction. In strategic terms, it creates speed.
As America marks its 250th anniversary, we should remember that trust was not a side note to the founding. It was the bet. In my first three essays in this Freedom & Enterprise series, I described the Declaration of Independence as America's first founding bet, the system it created as one that let people build free, and the freedom to fail as one of our greatest competitive advantages. Beneath all three is a more fundamental principle: America trusted free people to govern themselves, take risks, honor commitments, and build institutions strong enough to survive disagreement.
#trust #different #America #freedom


2 months ago
As demand for artificial intelligence (AI) reshapes data centers, investors are hunting for infrastructure plays. Choosing between high-growth Astera Labs (NASDAQ:ALAB) and the established Arista Networks (NYSE:ANET) requires weighing explosive potential against proven scale.
Astera Labs focuses on specialized connectivity chips that eliminate bottlenecks within AI servers, while Arista Networks provides the broad networking switches and software that link those servers together. Comparing them highlights two different ways to profit from the massive shift toward high-performance computing and cloud infrastructure.
Astera Labs designs connectivity solutions that facilitate high-speed data transfers within AI infrastructure. It operates among semiconductor stocks, serving major cloud providers and GPU vendors through products like PCIe and CXL controllers. Customer concentration like this adds a layer of risk to the business, as one end customer represented roughly 70% of revenue in 2025.
In 2025, revenue reached nearly $852 million, which represents a massive year-over-year increase of approximately 115%. The company reported net income of roughly $219 million for the period. This marks a significant swing from the net loss reported in the previous fiscal year.
As of its December 2025 balance sheet, the current ratio is approximately 10.2x, which measures a company's ability to cover short-term obligations with current ***** ets. The company has essentially no debt.
#arista
Astera Labs focuses on specialized connectivity chips that eliminate bottlenecks within AI servers, while Arista Networks provides the broad networking switches and software that link those servers together. Comparing them highlights two different ways to profit from the massive shift toward high-performance computing and cloud infrastructure.
Astera Labs designs connectivity solutions that facilitate high-speed data transfers within AI infrastructure. It operates among semiconductor stocks, serving major cloud providers and GPU vendors through products like PCIe and CXL controllers. Customer concentration like this adds a layer of risk to the business, as one end customer represented roughly 70% of revenue in 2025.
In 2025, revenue reached nearly $852 million, which represents a massive year-over-year increase of approximately 115%. The company reported net income of roughly $219 million for the period. This marks a significant swing from the net loss reported in the previous fiscal year.
As of its December 2025 balance sheet, the current ratio is approximately 10.2x, which measures a company's ability to cover short-term obligations with current ***** ets. The company has essentially no debt.
#arista


2 months ago
Giverny Capital ******* et Management, LLC, an investment management company, recently published its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The model portfolio returned 13.70% this quarter, compared to the S&P 500's 15.20% return. YTD, the portfolio gained 5.89%, while the index increased by 10.21%. The long-term link between stock appreciation and earnings growth is strong; Benjamin Graham described the market as a "voting machine" in the short term and a "weighing machine" in the long term. Despite the S&P 500's 10.2% rise in the first half of the year, 210 stocks lost value, indicating market anomalies. High-quality earnings compounders that benefit from AI capabilities are likely to maintain their competitive edge. Recently, the market has increasingly chased momentum. Tech giants are taking advantage of the optimism of investors amid fears of an AI bubble. Despite strong profit margins, reliance on "moonshot" investments raises sustainability concerns. The author recommends investing in both emerging tech leaders and established firms. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Giverny Capital ******* et Management highlighted Arista Networks, Inc. (NYSE:ANET) as one of its leading performance contributors. Arista Networks, Inc. (NYSE:ANET) is a high-speed switching and cloud networking solutions provider for hyperscale users. On July 21, 2026, Arista Networks, Inc. (NYSE:ANET) closed at $174.58 per share, reflecting a market capitalization of $219.82 billion. Arista Networks, Inc. (NYSE:ANET) posted a one-month return of 7.94%, while its shares gained 54.44% over the past 52 weeks.
Giverny Capital ******* et Management stated the following regarding Arista Networks, Inc. (NYSE:ANET) in its Q2 2026 investor update:
"Our two largest positions are Alphabet and Arista Networks, Inc. (NYSE:ANET), which I believe have strong positions in the emerging AI economy. Arista is the leading provider of networking equipment for hyperscale data centers. As AI traffic grows exponentially, data center owners increasingly need signal to move seamlessly not only within a given data center, but between data centers. The demands on the routers and switches that direct the flow of traffic are considerable. As the most sophisticated networking provider, Arista's growth may accelerate in coming years. As for portfolio activity for the quarter, we trimmed Alphabet and Arista. We sold about 20% of our position in Arista in April in two tranches at an average price of about $160. The stock finished the quarter higher than our sale price. Arista and Alphabet remain our largest positions as of June 30. The valuations on both are high enough that future returns likely will be lower than we're used to, even if the businesses continue to grow."
#NYSE #anet #capital
In its Q2 2026 investor letter, Giverny Capital ******* et Management highlighted Arista Networks, Inc. (NYSE:ANET) as one of its leading performance contributors. Arista Networks, Inc. (NYSE:ANET) is a high-speed switching and cloud networking solutions provider for hyperscale users. On July 21, 2026, Arista Networks, Inc. (NYSE:ANET) closed at $174.58 per share, reflecting a market capitalization of $219.82 billion. Arista Networks, Inc. (NYSE:ANET) posted a one-month return of 7.94%, while its shares gained 54.44% over the past 52 weeks.
Giverny Capital ******* et Management stated the following regarding Arista Networks, Inc. (NYSE:ANET) in its Q2 2026 investor update:
"Our two largest positions are Alphabet and Arista Networks, Inc. (NYSE:ANET), which I believe have strong positions in the emerging AI economy. Arista is the leading provider of networking equipment for hyperscale data centers. As AI traffic grows exponentially, data center owners increasingly need signal to move seamlessly not only within a given data center, but between data centers. The demands on the routers and switches that direct the flow of traffic are considerable. As the most sophisticated networking provider, Arista's growth may accelerate in coming years. As for portfolio activity for the quarter, we trimmed Alphabet and Arista. We sold about 20% of our position in Arista in April in two tranches at an average price of about $160. The stock finished the quarter higher than our sale price. Arista and Alphabet remain our largest positions as of June 30. The valuations on both are high enough that future returns likely will be lower than we're used to, even if the businesses continue to grow."
#NYSE #anet #capital


2 months ago
Giverny Capital **** et Management, LLC, an investment management company, recently published its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The model portfolio returned 13.70% this quarter, compared to the S&P 500's 15.20% return. YTD, the portfolio gained 5.89%, while the index increased by 10.21%. The long-term link between stock appreciation and earnings growth is strong; Benjamin Graham described the market as a "voting machine" in the short term and a "weighing machine" in the long term. Despite the S&P 500's 10.2% rise in the first half of the year, 210 stocks lost value, indicating market anomalies. High-quality earnings compounders that benefit from AI capabilities are likely to maintain their competitive edge. Recently, the market has increasingly chased momentum. Tech giants are taking advantage of the optimism of investors amid fears of an AI bubble. Despite strong profit margins, reliance on "moonshot" investments raises sustainability concerns. The author recommends investing in both emerging tech leaders and established firms. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Giverny Capital **** et Management highlighted Alphabet Inc. (NASDAQ:GOOGL). Alphabet Inc. (NASDAQ:GOOGL), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence, and is a significant contributor to the Strategy's performance. On July 21, 2026, Alphabet Inc. (NASDAQ:GOOGL) closed at $347.15 per share, reflecting a market capitalization of $4.22 trillion. Alphabet Inc. (NASDAQ:GOOGL) posted a one-month return of 0.54%, while its shares gained 82.49% over the past 52 weeks.
Giverny Capital **** et Management stated the following regarding Alphabet Inc. (NASDAQ:GOOGL) in its Q2 2026 investor update:
"Our two largest positions are Alphabet Inc. (NASDAQ:GOOGL) and Arista, which I believe have strong positions in the emerging AI economy. Alphabet has a near monopoly in search, a robust cloud data center business, a leading computer chip used in AI data centers, a highly profitable **** et in YouTube and the premier autonomous driving platform in Waymo. It has built a tremendous collection of **** ets.
As for portfolio activity for the quarter, we trimmed Alphabet and Arista. We sold 17% of our position in Alphabet in April at about $380. Management subsequently sold $80 billion of stock in a secondary offering at $350 to raise money to fund more investment in data centers. I feel we did the responsible thing in trimming Alphabet as it got to nearly 12% of our portfolio. Arista and Alphabet remain our largest positions as of June 30. The valuations on both are high enough that future returns likely will be lower than we're used to, even if the businesses continue to grow."
#googl #management #Portfolio
In its Q2 2026 investor letter, Giverny Capital **** et Management highlighted Alphabet Inc. (NASDAQ:GOOGL). Alphabet Inc. (NASDAQ:GOOGL), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence, and is a significant contributor to the Strategy's performance. On July 21, 2026, Alphabet Inc. (NASDAQ:GOOGL) closed at $347.15 per share, reflecting a market capitalization of $4.22 trillion. Alphabet Inc. (NASDAQ:GOOGL) posted a one-month return of 0.54%, while its shares gained 82.49% over the past 52 weeks.
Giverny Capital **** et Management stated the following regarding Alphabet Inc. (NASDAQ:GOOGL) in its Q2 2026 investor update:
"Our two largest positions are Alphabet Inc. (NASDAQ:GOOGL) and Arista, which I believe have strong positions in the emerging AI economy. Alphabet has a near monopoly in search, a robust cloud data center business, a leading computer chip used in AI data centers, a highly profitable **** et in YouTube and the premier autonomous driving platform in Waymo. It has built a tremendous collection of **** ets.
As for portfolio activity for the quarter, we trimmed Alphabet and Arista. We sold 17% of our position in Alphabet in April at about $380. Management subsequently sold $80 billion of stock in a secondary offering at $350 to raise money to fund more investment in data centers. I feel we did the responsible thing in trimming Alphabet as it got to nearly 12% of our portfolio. Arista and Alphabet remain our largest positions as of June 30. The valuations on both are high enough that future returns likely will be lower than we're used to, even if the businesses continue to grow."
#googl #management #Portfolio

2 months ago
Giverny Capital ***** et Management, LLC, an investment management company, recently published its second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The model portfolio returned 13.70% this quarter, compared to the S&P 500's 15.20% return. YTD, the portfolio gained 5.89%, while the index increased by 10.21%. The long-term link between stock appreciation and earnings growth is strong; Benjamin Graham described the market as a "voting machine" in the short term and a "weighing machine" in the long term. Despite the S&P 500's 10.2% rise in the first half of the year, 210 stocks lost value, indicating market anomalies. High-quality earnings compounders that benefit from AI capabilities are likely to maintain their competitive edge. Recently, the market has increasingly chased momentum. Tech giants are taking advantage of the optimism of investors amid fears of an AI bubble. Despite strong profit margins, reliance on "moonshot" investments raises sustainability concerns. The author recommends investing in both emerging tech leaders and established firms. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Giverny Capital ***** et Management highlighted Arista Networks, Inc. (NYSE:ANET) as one of its leading performance contributors. Arista Networks, Inc. (NYSE:ANET) is a high-speed switching and cloud networking solutions provider for hyperscale users. On July 21, 2026, Arista Networks, Inc. (NYSE:ANET) closed at $174.58 per share, reflecting a market capitalization of $219.82 billion. Arista Networks, Inc. (NYSE:ANET) posted a one-month return of 7.94%, while its shares gained 54.44% over the past 52 weeks.
Giverny Capital ***** et Management stated the following regarding Arista Networks, Inc. (NYSE:ANET) in its Q2 2026 investor update:
"Our two largest positions are Alphabet and Arista Networks, Inc. (NYSE:ANET), which I believe have strong positions in the emerging AI economy. Arista is the leading provider of networking equipment for hyperscale data centers. As AI traffic grows exponentially, data center owners increasingly need signal to move seamlessly not only within a given data center, but between data centers. The demands on the routers and switches that direct the flow of traffic are considerable. As the most sophisticated networking provider, Arista's growth may accelerate in coming years. As for portfolio activity for the quarter, we trimmed Alphabet and Arista. We sold about 20% of our position in Arista in April in two tranches at an average price of about $160. The stock finished the quarter higher than our sale price. Arista and Alphabet remain our largest positions as of June 30. The valuations on both are high enough that future returns likely will be lower than we're used to, even if the businesses continue to grow."
#networks
In its Q2 2026 investor letter, Giverny Capital ***** et Management highlighted Arista Networks, Inc. (NYSE:ANET) as one of its leading performance contributors. Arista Networks, Inc. (NYSE:ANET) is a high-speed switching and cloud networking solutions provider for hyperscale users. On July 21, 2026, Arista Networks, Inc. (NYSE:ANET) closed at $174.58 per share, reflecting a market capitalization of $219.82 billion. Arista Networks, Inc. (NYSE:ANET) posted a one-month return of 7.94%, while its shares gained 54.44% over the past 52 weeks.
Giverny Capital ***** et Management stated the following regarding Arista Networks, Inc. (NYSE:ANET) in its Q2 2026 investor update:
"Our two largest positions are Alphabet and Arista Networks, Inc. (NYSE:ANET), which I believe have strong positions in the emerging AI economy. Arista is the leading provider of networking equipment for hyperscale data centers. As AI traffic grows exponentially, data center owners increasingly need signal to move seamlessly not only within a given data center, but between data centers. The demands on the routers and switches that direct the flow of traffic are considerable. As the most sophisticated networking provider, Arista's growth may accelerate in coming years. As for portfolio activity for the quarter, we trimmed Alphabet and Arista. We sold about 20% of our position in Arista in April in two tranches at an average price of about $160. The stock finished the quarter higher than our sale price. Arista and Alphabet remain our largest positions as of June 30. The valuations on both are high enough that future returns likely will be lower than we're used to, even if the businesses continue to grow."
#networks

2 months ago
With a market cap of $228.1 billion, Arista Networks, Inc. (ANET) develops and delivers data-driven networking solutions for AI, cloud, data center, campus, and routing environments, serving customers across the Americas, Europe, the Middle East, Africa, and Asia-Pacific. It offers its Extensible Operating System (EOS), cloud and AI networking products, cognitive network software and services, and customer support solutions to industries including finance, healthcare, government, manufacturing, and media.
The Santa Clara, California-based company is slated to announce its fiscal Q2 2026 results after the market closes on Tuesday, Aug. 4. Ahead of this event, ***** ysts expect ANET to report an adjusted EPS of $0.79, a 17.9% increase from $0.67 in the year-ago quarter. It has exceeded Wall Street's earnings expectations in the past four quarters.
Elon Musk Dubs Him 'Scam Altman' Not Sam — Then Altman Clapped Back: 'Homeboy You're The One Selling ***** e Datacenters'
Oracle Stock Crashes to a 52-Week Low. Here's Why It Might Be Time to Buy.
Short Seller Hunterbrook Attacked Bloom Energy's Supply-Chain Claims. BE Stock Is Bruised, But Not Broken.
The Santa Clara, California-based company is slated to announce its fiscal Q2 2026 results after the market closes on Tuesday, Aug. 4. Ahead of this event, ***** ysts expect ANET to report an adjusted EPS of $0.79, a 17.9% increase from $0.67 in the year-ago quarter. It has exceeded Wall Street's earnings expectations in the past four quarters.
Elon Musk Dubs Him 'Scam Altman' Not Sam — Then Altman Clapped Back: 'Homeboy You're The One Selling ***** e Datacenters'
Oracle Stock Crashes to a 52-Week Low. Here's Why It Might Be Time to Buy.
Short Seller Hunterbrook Attacked Bloom Energy's Supply-Chain Claims. BE Stock Is Bruised, But Not Broken.



2 months ago
Arista Networks (ANET) demonstrates strong technical momentum, recently setting an all-time high.
Shares are up more than 70% over the past year.
ANET maintains a 100% "Buy" technical opinion from Barchart.
Wall Street ***** ysts overwhelmingly rate ANET a "Strong Buy," although some note its high valuation is a drawback.
Valued at $235 billion, Arista Networks (ANET) is engaged in providing cloud networking solutions for data centers and cloud computing environments.
Shares are up more than 70% over the past year.
ANET maintains a 100% "Buy" technical opinion from Barchart.
Wall Street ***** ysts overwhelmingly rate ANET a "Strong Buy," although some note its high valuation is a drawback.
Valued at $235 billion, Arista Networks (ANET) is engaged in providing cloud networking solutions for data centers and cloud computing environments.


2 months ago
Beneath its strong run, the options market is pricing a year of extreme outcomes for Arista Networks, a two-sided risk you already carry in your portfolio.
If you hold shares of Arista Networks (ANET), the options market has a message for you, and it's priced into your position whether you've ever traded a derivative or not. The market is pricing an implied volatility of 65% over the next year. That figure, which sits in the 100th percentile of its own recent history, is a direct measure of uncertainty, a price tag on a wide-open future.
How Wide Is the Range Priced Into Your ANET Shares?
Let's translate that 65% volatility into dollars and cents. Over the coming year, the options market sees a 68% probability that ANET stock will finish somewhere between a floor near $100 and a ceiling near $345.45. From today's price of about $184.69, the path to that ceiling represents an 87% gain. The drop to the floor is a 46% decline. You are carrying the full exposure to that two-sided swing.
Why Is the Market Pricing More Risk Than Usual?
If you hold shares of Arista Networks (ANET), the options market has a message for you, and it's priced into your position whether you've ever traded a derivative or not. The market is pricing an implied volatility of 65% over the next year. That figure, which sits in the 100th percentile of its own recent history, is a direct measure of uncertainty, a price tag on a wide-open future.
How Wide Is the Range Priced Into Your ANET Shares?
Let's translate that 65% volatility into dollars and cents. Over the coming year, the options market sees a 68% probability that ANET stock will finish somewhere between a floor near $100 and a ceiling near $345.45. From today's price of about $184.69, the path to that ceiling represents an 87% gain. The drop to the floor is a 46% decline. You are carrying the full exposure to that two-sided swing.
Why Is the Market Pricing More Risk Than Usual?


3 months ago
Big Cap 20 component Arista Networks (ANET) is still forming a long handle, as shares trade just below a proper buy point. Arista stock is also part of the No. 9-ranked computer networking industry group, which indicates leadership.
Shares of the cloud networking products manufacturer traded close to a 177.48 proper entry from a cup-with-handle base on a daily chart on June 22 before reversing lower. In the days following, shares have gone back and forth, trading around the 50-day line.
As Arista stock undercut this level once again in Thursday's action, investors should watch closely. Failing to hold support here could signal a more bearish move to the downside.
On the weekly chart, shares are still holding slightly above their 10-week line, according to MarketSurge pattern recognition. The buy point here is 179.80.
Arista stock's relative strength line has drifted sideways since August as shares formed multiple consolidations and failed to fully break out. But a Relative Strength Rating of 83 shows there's still some room for improvement here.
Shares of the cloud networking products manufacturer traded close to a 177.48 proper entry from a cup-with-handle base on a daily chart on June 22 before reversing lower. In the days following, shares have gone back and forth, trading around the 50-day line.
As Arista stock undercut this level once again in Thursday's action, investors should watch closely. Failing to hold support here could signal a more bearish move to the downside.
On the weekly chart, shares are still holding slightly above their 10-week line, according to MarketSurge pattern recognition. The buy point here is 179.80.
Arista stock's relative strength line has drifted sideways since August as shares formed multiple consolidations and failed to fully break out. But a Relative Strength Rating of 83 shows there's still some room for improvement here.

3 months ago
DUBAI, United Arab Emirates (AP) — Iranian state television claimed this week that a foreign ship got stuck in the Strait of Hormuz after ignoring instructions to use a route laid out by the Islamic Republic's paramilitary Revolutionary Guard.
But the ship is tied to Iran — and seems to have been in the strait for months.
The vessel, based on its shape, reported location and other details, is the container ship Arista, reportedly flying a false flag linking it to the island nation of Comoros. That ship was known last year as the Panama-flagged Gauja, which the U.S. Treasury included in sanctions targeting what it described as a network that had been "generating tens of billions of dollars in profit" for Iran's ruling elite.
Here's a closer look.
Iranian state television aired on-screen alerts Wednesday about what it described as a foreign ship that got stuck ignoring the commands of the Guard's navy.
But the ship is tied to Iran — and seems to have been in the strait for months.
The vessel, based on its shape, reported location and other details, is the container ship Arista, reportedly flying a false flag linking it to the island nation of Comoros. That ship was known last year as the Panama-flagged Gauja, which the U.S. Treasury included in sanctions targeting what it described as a network that had been "generating tens of billions of dollars in profit" for Iran's ruling elite.
Here's a closer look.
Iranian state television aired on-screen alerts Wednesday about what it described as a foreign ship that got stuck ignoring the commands of the Guard's navy.


3 months ago
Cisco Systems, Inc. (NASDAQ:CSCO) is one of the 15 Best AI Stocks That Will Make You Rich in 10 Years.
On June 25, 2026, KeyBanc raised its price target on Cisco Systems, Inc. (NASDAQ:CSCO) to $130 from $125 and kept an Overweight rating. KeyBanc's chief investment officer survey for the first half of 2026 showed that the gap "between the haves and the have-nots in the IT budget just got wider." The firm said AI and AI-readiness spending rose sharply in priority, and it recommended investors stick with security, data, infrastructure, and monitoring names.
On June 16, Equinix (EQIX) expanded its collaboration with Cisco and Nvidia (NVDA) to accelerate enterprise AI. The companies will enable customers to deploy Cisco Secure AI Factory with Nvidia across Equinix's global data center network, using standardized AI factory blueprints and automation. Equinix is also working with Presidio to deploy the Programmable AI Technology Hub Lab, a real-world environment inside Equinix data centers where customers can test, validate, and refine AI infrastructure before broader deployment.
Source: Pixabay
On June 12, Morgan Stanley raised its price target on Cisco to $130 from $120 and kept an Overweight rating. Morgan Stanley said Cisco and Arista Networks (ANET) remain its preferred ways to play "an underappreciated front-end networking refresh cycle," as inference and rising CPU intensity drive a front-end refresh.
On June 25, 2026, KeyBanc raised its price target on Cisco Systems, Inc. (NASDAQ:CSCO) to $130 from $125 and kept an Overweight rating. KeyBanc's chief investment officer survey for the first half of 2026 showed that the gap "between the haves and the have-nots in the IT budget just got wider." The firm said AI and AI-readiness spending rose sharply in priority, and it recommended investors stick with security, data, infrastructure, and monitoring names.
On June 16, Equinix (EQIX) expanded its collaboration with Cisco and Nvidia (NVDA) to accelerate enterprise AI. The companies will enable customers to deploy Cisco Secure AI Factory with Nvidia across Equinix's global data center network, using standardized AI factory blueprints and automation. Equinix is also working with Presidio to deploy the Programmable AI Technology Hub Lab, a real-world environment inside Equinix data centers where customers can test, validate, and refine AI infrastructure before broader deployment.
Source: Pixabay
On June 12, Morgan Stanley raised its price target on Cisco to $130 from $120 and kept an Overweight rating. Morgan Stanley said Cisco and Arista Networks (ANET) remain its preferred ways to play "an underappreciated front-end networking refresh cycle," as inference and rising CPU intensity drive a front-end refresh.