9 days ago
NEW YORK – Another forensic dive into a disappointing Yankees finish is underway, discussing method and gathering intel on how to make a better run at the Canyon of Heroes in 2027.
That storied stretch of lower Broadway hasn't seen a parade of Yankees in 17 years.
Nearly two weeks since his team was swept by the Tampa Bay Rays in the AL Division Series, Yankees GM Brian Cashman has yet to publicly address how it ended or hint at the strategy ahead.
These are among the biggest questions revolving around Yankees Universe as the World Series begins elsewhere later this week:
Cashman's contract expires at year's end, while manager Aaron Boone's deal runs through the 2027 season.
#york #heroes #nearly


22 days ago
One of the secrets of Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) and its success in the stock market has been its focus on value. Whether led by former Chief Executive Officer Warren Buffett or its current leader, Greg Abel, Berkshire has always focused on buying stocks when they are significantly below their intrinsic value.
On top of that, Berkshire's management team has sought companies that have significant advantages over their competitors -- an economic moat -- operating in a mature industry with reliable cash flow.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That strategy has helped Berkshire Hathaway build an investment portfolio valued at about $350 billion -- and generate returns that averaged 19.7% during the past 60 years, nearly double the S&P 500's (SNPINDEX: ^GSPC) return.
In today's go-go market, which is focused so heavily on artificial intelligence, machine learning, and other technological advances, it's easy to forget that there are some great value stocks available -- and at comparatively dirt cheap prices. Three such stocks currently in Berkshire's portfolio are American Express (NYSE: AXP), The New York Times Company (NYSE: NYT), and DaVita (NYSE: DVA). Here's the case for buying and holding each of them right now.
#NVIDIA #value #stocks

1 month ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management

1 month ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management

1 month ago
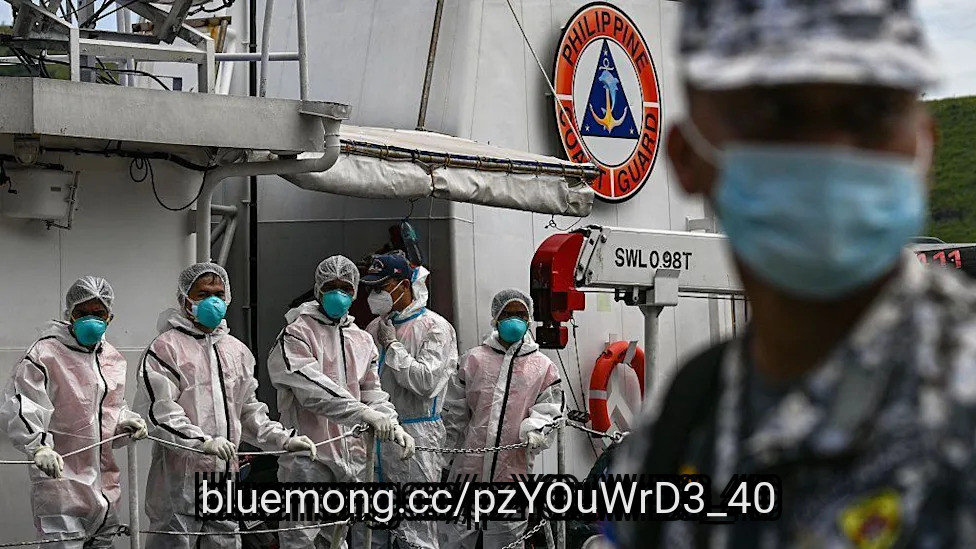
Philippine authorities said it could take weeks or months to identify victims of a ferry fire that killed 76 people last week.
"Most of them are already in a charred condition," Richard Allan Mangalip, a forensic specialist from the Philippine National Police, told reporters on Sunday. Family members have been asked to help identify victims with personal items or DNA samples.
The MV June Aster was heading from Manila to Coron in Palawan province, a popular holiday destination, when a fire started in its cargo hold and spread rapidly throughout the vessel.
Forty-three people survived the disaster, while 13 people remain unaccounted for, authorities said.
Mangalip said they were "trying [their] best to collect the possible identifying marks" from victims' remains.
#mangalip #authorities #national
2 months ago
Greg Abel took over as CEO of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the start of 2026. Former CEO Warren Buffett left Abel a huge gift: nearly $400 billion in cash on the company's balance sheet. Abel has put some of that cash to work buying Taylor Morrison Home, and some has been spent on publicly traded stock investments. However, Abel has also decided to buy back Berkshire Hathaway stock. That could be a positive sign. Here's why.
Under Warren Buffett, Berkshire Hathaway didn't make a habit of buying back stock. The world-famous investor preferred to put cash to work by buying shares in other companies or buying companies outright. When he did buy back Berkshire Hathaway stock, it was because he believed the shares were undervalued.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This dynamic is clearly explained in the company's 2025 10k, where the company states: "Berkshire's common stock repurchase program currently permits Berkshire to repurchase shares any time that Berkshire's Chief Executive Officer, after consultation with the Chairman of the Board, believes that the repurchase price is below Berkshire's intrinsic value, conservatively determined." The only limit on repurchase activity is that it can't reduce the company's cash and short-term investment balance below $30 billion.
Some market watchers had hypothesized that Berkshire Hathaway bought as much as $11 billion of its own stock in the second quarter, but the real number turned out to be roughly $4.5 billion. That said, the number was still quite large and, even then, given the huge cash balance the company has, it didn't put the company anywhere near the $30 billion cash limitation.
#Stock

2 months ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like CNH Industrial N.V. (NYSE:CNH). CNH Industrial N.V. manufactures and sells specialized machines and services for the farming and construction industries. The one-month return of CNH Industrial N.V. (NYSE:CNH) was 30.96% while its shares traded between $9.00 and $14.46 over the last 52 weeks. On September 7, 2026, CNH Industrial N.V. (NYSE:CNH) stock closed at approximately $14.40 per share, with a market capitalization of about $22.02 billion.
Moerus Worldwide Fund stated the following regarding CNH Industrial N.V. (NYSE:CNH) in its Q2 2026 investor letter:
"We also initiated a position in shares of CNH Industrial N.V. (NYSE:CNH) in H1. CNH Industrial manufactures and sells specialized machines and services for the farming and construction industries under the Case IH and New Holland brands. The production of high horsepower agricultural equipment (i.e. tractors, combines, etc.) for professional farmers is an oligopoly, of which CNH is the second largest original equipment manufacturer behind John Deere."
#NYSE #investor #letter

2 months ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and **** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Douglas Elliman Inc. (NYSE:DOUG). Douglas Elliman Inc. is a residential real estate brokerage company with a strong presence in high-end U.S. housing markets. The one-month return of Douglas Elliman Inc. (NYSE:DOUG) was -2.19% while its shares traded between $1.5300 and $3.1900 over the last 52 weeks. On September 7, 2026, Douglas Elliman Inc. (NYSE:DOUG) stock closed at approximately $1.8100 per share, with a market capitalization of about $162.69 million.
Moerus Worldwide Fund stated the following regarding Douglas Elliman Inc. (NYSE:DOUG) in its Q2 2026 investor letter:
"Outside of Materials, other meaningful detractors from H1 came from different industries but were similarly impacted by various concerns related to the war and its effects in various areas, including real estate activity (Douglas Elliman Inc. (NYSE:DOUG)) given heightened inflation concerns and increased interest rate expectations. We would argue that the current valuations of each of these holdings are unusually modest, belying the formidable, leading presence that each boasts in its respective markets."
#douglas #NYSE


2 months ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ****** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Tidewater Inc. (NYSE:TDW). Tidewater Inc. is an offshore supply vessel operator that provides support services to the offshore energy industry. Moerus identified Tidewater as one of the Fund's five most significant positive contributors during the first half of 2026. The one-month return of Tidewater Inc. (NYSE:TDW) was 3.68% while its shares traded between $46.65 and $101.58 over the last 52 weeks. On September 7, 2026, Tidewater Inc. (NYSE:TDW) stock closed at approximately $94.26 per share, with a market capitalization of about $4.61 billion.
Moerus Worldwide Fund stated the following regarding Tidewater Inc. (NYSE:TDW) in its Q2 2026 investor letter:
"Similarly, we'd argue that offshore supply vessel (OSV) operator Tidewater Inc. (NYSE:TDW) has grown the per share value of its business dramatically since 2018 through a combination of a relentless focus on costs, share repurchases, and most notably, the utilization of its OSV industry-leading balance sheet to make three acquisitions of ****** ets (with a fourth pending) from distressed and/or motivated sellers at deep discounts to replacement costs during a years-long industry depression."
#tidewater #fund #energy #second

2 months ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Transocean Ltd. (NYSE:RIG) while discussing its investment in Valaris. Transocean Ltd. is an offshore drilling contractor. Moerus discussed the company in connection with its agreement to acquire Valaris in an all-stock transaction, which it said helped surface significant latent value in Valaris. The one-month return of Transocean Ltd. (NYSE:RIG) was 2.53% while its shares traded between $3.01 and $7.66 over the last 52 weeks. On September 7, 2026, Transocean Ltd. (NYSE:RIG) stock closed at approximately $5.85 per share, with a market capitalization of about $6.56 billion.
Moerus Worldwide Fund stated the following regarding Transocean Ltd. (NYSE:RIG) in its Q2 2026 investor letter:
"Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean Ltd. (NYSE:RIG) in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock)."
#valaris

2 months ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ****** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Valaris Limited (NYSE:VAL). Valaris Limited is a U.S.-based provider of offshore drilling services. Moerus described Valaris as its largest individual contributor to performance in the first half of 2026. The one-month return of Valaris Limited (NYSE:VAL) was 1.62% while its shares traded between $46.70 and $114.12 over the last 52 weeks. On September 7, 2026, Valaris Limited (NYSE:VAL) stock closed at approximately $86.74 per share, with a market capitalization of about $6.03 billion.
Moerus Worldwide Fund stated the following regarding Valaris Limited (NYSE:VAL) in its Q2 2026 investor letter:
"For example, consider Valaris Limited (NYSE:VAL), the largest individual contributor to performance in H1. Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock). Valaris was added to the Fund in early 2025 following a slide in its share price, amid then-subdued oil prices and what we believed to be a temporary lull in offshore drilling activity caused by support infrastructure constraints (among other factors)."
#worldwide #Stock

2 months ago
Orionx, a crypto trading exchange backed by the stablecoin giant Tether, announced on Sep. 3 that it is shutting down after an audit discovered a gap in client ******* ets worth $7 million.
A Chilean exchange, Orionx revealed that a forensic audit confirmed a transfer of ******* ets worth more than $7 million held in custody to wallets not administered by the company.
Related: Andrew Tate sends harsh message on crypto from Miami prison
The exchange said it filed a complaint with the Public Prosecutor's Office for an investigation and filed a criminal lawsuit against co-founders Joaquín Díaz and Roberto Zibert.
Orionx said its sole priority right now is to work toward returning the largest possible amount of their ******* ets to the clients in the fastest and fairest way possible. It said it has already reported the ******* et closure and restitution plan to the authorities, with the first phase currently under implementation.
#assets #Crypto #million #filed


2 months ago
Warren Buffett, the former CEO of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB), is one of the world's most famous investors. In fact, his long-term success as an investor earned him the nickname the Oracle of Omaha. So investors should pay attention when he issues a warning about elevated risk, as he recently did by suggesting there's a gambling mentality on Wall Street today. However, Wall Street's long-term history still has an important story to tell, too.
Buffett lamented that "we've never had people in a more gambling mood than now," in an interview with Fortune. He even invoked the notion of religious fervor, opining that Wall Street is like a church with a casino attached. That is a very negative view of the market environment, but it isn't unrealistic.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
After rushing headlong into cryptocurrencies, droves of people have now taken up prediction markets. Cryptocurrencies have no intrinsic value and are worth only what their owners are willing to pay. And prediction markets, by definition, have binary outcomes based on time-limited events. That predicting the outcome of a sports event (effectively gambling) can now take place at the same broker a person uses to buy stock in a company should be pretty shocking. And yet it is the norm today for many discount brokers.
However, even if you are as worried as Buffett, that doesn't mean you should dump your long-term investment approach. As the chart above highlights, the market has recovered after every bear market in history. In fact, the S&P 500 index (SNPINDEX: ^GSPC) has gone on to achieve new highs after every single downturn in history so far. It is highly likely that this trend will continue, even if investment risk is high today.
#wall #signal #long #even


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted StoneX Group Inc. (NASDAQ:SNEX) as a notable contributor. StoneX Group Inc. (NASDAQ:SNEX) operates as a US-based global financial services network that connects companies, organizations, traders, and investors to a market ecosystem. On August 31, 2026, StoneX Group Inc. (NASDAQ:SNEX) closed at $68.48 per share. StoneX Group Inc. (NASDAQ:SNEX) fell 8.97% over the past month while its shares gained 50.63% over the past 52 weeks. StoneX Group Inc. (NASDAQ:SNEX) has a market capitalization of $8.26 billion with a 52-week trading range between $36.45 - $94.66.
Riverwater Partners Small Cap Strategy stated the following regarding StoneX Group Inc. (NASDAQ:SNEX) in its Q2 2026 investor letter:
"StoneX Group Inc. (NASDAQ:SNEX), our financial services and clearing holding, was the portfolio's largest contributor as shares gained approximately 47% during the quarter. Elevated market volatility stemming from the Middle East conflict drove exceptional trading and clearing activity, and the stock ground steadily higher after quarterly earnings results. With shares having roughly doubled from their lows and valuation approaching the high end of historical ranges, we trimmed the position into strength while keeping it among our largest holdings. We continue to view it as an unusually durable compounder across market environments."
#group #NASDAQ #market
2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Atmus Filtration Technologies Inc. (NYSE:ATMU). Atmus Filtration Technologies Inc. (NYSE:ATMU), a US-based filtration products manufacturer, known for its Fleetguard brand, detracted from the strategy's performance this quarter. On August 31, 2026, Atmus Filtration Technologies Inc. (NYSE:ATMU) closed at $47.23 per share. Filtration Technologies Inc. (NYSE:ATMU) fell 14.31% over the past month while its shares gained 5.47% over the past 52 weeks. Atmus Filtration Technologies Inc. (NYSE:ATMU) has a market capitalization of $3.85 billion with a 52-week trading range between $42.60 - $66.50.
Riverwater Partners Small Cap Strategy stated the following regarding Atmus Filtration Technologies Inc. (NYSE:ATMU) in its Q2 2026 investor letter:
"Atmus Filtration Technologies Inc. (NYSE:ATMU), the engine filtration business spun out of ******* mins (CMI), fell approximately 10% as readthroughs from the freight market turned mixed, with softer commentary on new truck builds and some margin pressure weighing on sentiment. We continue to like the durable, replacement-driven aftermarket core of the business, but we respected the change in tone and trimmed the position back to a standard weight during the quarter."
#strategy #small #quarter


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Warby Parker Inc. (NYSE:WRBY). The Fund exited its position in Warby Parker Inc. (NYSE:WRBY), a leading eyewear brand and retailer that offers eyeglasses and sunglasses, and contact lenses, during the quarter. On August 31, 2026, Warby Parker Inc. (NYSE:WRBY) closed at $24.60 per share. Warby Parker Inc. (NYSE:WRBY) fell 17.78% over the past month while its shares lost 3.72% over the past 52 weeks. Warby Parker Inc. (NYSE:WRBY) has a market capitalization of $3.04 billion with a 52-week trading range between $14.96 - $31.00.
Riverwater Partners Small Cap Strategy stated the following regarding Warby Parker Inc. (NYSE:WRBY) in its Q2 2026 investor letter:
"We also sold Warby Parker Inc. (NYSE:WRBY) and Canada Goose (GOOS) during the quarter as we redeployed capital into the new positions described above. WRBY is a name we like, though we believe a lot of AI hype was built into the stock around the glasses launch. The unveiling of the glasses was somewhat underwhelming and we would potentially underwrite the stock again at lower levels."
Warby Parker Inc. (NYSE:WRBY) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 36 hedge fund portfolios held Warby Parker Inc. (NYSE:WRBY) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Warby Parker Inc. (NYSE:WRBY) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to


2 months ago
A laptop arrived late. What was on it made things worse. And now Apple is asking a federal court to move faster, arguing that evidence in its lawsuit against OpenAI is being actively destroyed.
Apple filed a new brief on Aug. 31, escalating its legal battle against the ChatGPT maker. The filing accuses OpenAI of withholding key evidence and alleges that a former Apple engineer sent instructions to an OpenAI colleague to destroy documents. The colleague confirmed she would comply, Bloomberg reported.
The brief was filed Monday, Aug. 31, in support of Apple's motion for expedited pretrial fact-finding in its trade secrets lawsuit against OpenAI.
Apple's lawyers said OpenAI only recently provided a critical piece of evidence: an Apple-issued MacBook that former engineer Chang Liu had been using since leaving the company.
Initial forensic ***** ysis of the laptop found that Liu and colleagues at OpenAI "were well aware" of his continued unauthorized access to Apple's third-party cloud storage providers. The filing alleges Liu also "sent instructions for destroying evidence to an OpenAI colleague who confirmed she would comply."
#filing #alleges

2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Coupang, Inc. (NYSE:CPNG). Coupang, Inc. (NYSE:CPNG), a Korean technology and e-commerce platform that operates through Product Commerce and Developing Offerings segments, detracted from the fund's performance this quarter. On August 31, 2026, Coupang, Inc. (NYSE:CPNG) closed at $16.06 per share. Over the past month, Coupang, Inc. (NYSE:CPNG) declined 4.29%, and its shares are down 43.47% over the past year. Coupang, Inc. (NYSE:CPNG) has a market capitalization of $28.87 billion, and its stock has traded within a 52-week range of $14.92 to $34.08.
Baron Fifth Avenue Growth Fund stated the following regarding Coupang, Inc. (NYSE:CPNG) in its Q2 2026 investor letter:
"Coupang, Inc. (NYSE:CPNG), Korea's largest e-commerce platform, detracted from performance with shares down 7.7%. The stock came under pressure following first-quarter results, where in-line revenue was overshadowed by softer second-quarter guidance as capacity and supply chain investments made ahead of Coupang's 2025 data breach weighed on margins while customer volumes recovered. Sentiment was further weighed down by a record KRW 624.7 billion (about US $430 million) privacy fine stemming from an investigation into the breach, while a rotation of fast money into AI and semiconductor names added to the weakness. Despite these headwinds, our conviction remains intact. We view the margin pressure as temporary, and the fine removes a key overhang and reinforces our belief that the breach does not reflect a structural loss of market share. By the end of April, Coupang recovered roughly 80% of the post-breach decline in WOW Membership (its paid subscription program), with returning members resuming prior spending levels. We continue to view Coupang as a competitively advantaged e-commerce business gaining share in its core market while scaling Taiwan operations."
#fund #baron
2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Shopify Inc. (NASDAQ:SHOP). Shopify Inc. (NASDAQ:SHOP), a Canada-based e-commerce technology company that provides a cloud-based platform for individuals and companies to create and manage their operations, detracted from performance in the quarter. On August 31, 2026, Shopify Inc. (NASDAQ:SHOP) closed at $147.37 per share. Over the past month, Shopify Inc. (NASDAQ:SHOP) returned 19.52%, but its shares are up 5.99% over the past year. Shopify Inc. (NASDAQ:SHOP) has a market capitalization of $189.59 billion, and its stock has traded within a 52-week range of $94.00 to $182.19.
Baron Fifth Avenue Growth Fund stated the following regarding Shopify Inc. (NASDAQ:SHOP) in its Q2 2026 investor letter:
"Shopify Inc. (NASDAQ:SHOP), a leading global commerce platform serving merchants across online and offline channels, detracted from performance in the second quarter with the stock down 3.7%. The decline was driven by multiple compression (its P/E was down 8.5%11) rather than any deterioration in the underlying business or fundamental outlook. Shopify continued to post healthy growth in gross merchandise volume and revenue, which were up 30% and 32% year-on-year, respectively. Instead, the pressure reflected investor concerns about the company's long-term positioning in a future state of e-commerce that may rely more heavily on AI-driven applications than traditional websites. We view those concerns as misplaced and see Shopify as an AI winner. Two decades of proprietary data across millions of merchants provide Shopify with a strong foundation for AI tools that improve merchant outcomes. Recent product releases also embed the platform more deeply within the emerging agentic commerce ecosystem while creating new monetization opportunities. We continue to believe that Shopify is the category-defining platform for modern commerce, benefiting from durable secular growth
2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Fifth Avenue Growth Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 24.6% (Institutional Shares), outperforming the Russell 1000 Growth Index (16.7%) and the S&P 500 (15.2%). Year to date, it's up 11.7%, surpassing its benchmarks. The first half of 2026 mirrored the previous year, with a 10.4% drawdown in Q1 due to geopolitical tensions, similar to last year's tariff-related decline. However, the fund rebounded with a 24.6% gain in Q2 after a cease-fire and declining oil prices. Stock selection drove the outperformance, contributing 940bps, while sector allocation detracted 152bps. In a volatile market, the firm remains focused on identifying high-quality, competitively advantaged companies and is optimistic about long-term prospects, investing when prices align with intrinsic values. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Fifth Avenue Growth Fund highlighted Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) as a notable contributor to performance. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's leading contract chip manufacturer, producing advanced semiconductors for major global technology companies. On August 31, 2026, Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) closed at $415.32 per share. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) fell 0.44% over the past month, while its shares gained 81.85% over the past 52 weeks. Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) has a market capitalization of $1.97 Trillion.
Baron Fifth Avenue Growth Fund stated the following regarding Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) in its Q2 2026 investor letter:
"Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) is the world's largest contract chipmaker and the leading manufacturer of advanced logic semiconductors used in modern AI accelerators. Shares rose 41.6% during the quarter as the company continues to report stellar financial results underpinned by AI demand with revenue growth of 35% year-on-year and EPS growth of 58%, with 66% gross margins and 58% operating margins. High-performance computing now represents the majority of TSMC's business. AI demand is consuming so much leading-edge capacity that smartphone and PC production is increasingly shifting to older technology nodes, reversing a dynamic that defined the foundry industry for much of the past decade. Management also raised its full-year outlook and increased capital spending to support demand that remains well above available supply. We retain long term conviction in TSMC and view its leading-edge manufacturing monopoly, pricing power, and technology roadmap as durable advantages that support a long duration of growth."
#baron
2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Grand Canyon Education, Inc. (NASDAQ:LOPE). Grand Canyon Education, Inc. (NASDAQ:LOPE), a US-based education services company, detracted from performance this quarter. On August 31, 2026, Grand Canyon Education, Inc. (NASDAQ:LOPE) closed at $148.13 per share. Grand Canyon Education, Inc. (NASDAQ:LOPE) fell 1.77% over the past month, and its shares are down 27.09% over the past 52 weeks. Grand Canyon Education, Inc. (NASDAQ:LOPE) has a market capitalization of around $3.86 billion with a 52-week trading range between $134.27 - $223.04.
Riverwater Partners Small Cap Strategy stated the following regarding Grand Canyon Education, Inc. (NASDAQ:LOPE) in its Q2 2026 investor letter:
"Grand Canyon Education, Inc. (NASDAQ:LOPE), the education services provider, declined approximately 16% and was the portfolio's largest detractor. Our investment thesis remains intact; LOPE's steady, profitable, countercyclical enrollment business was simply left behind in a market that rewarded beta and speculation. Enrollment trends and cash generation remain consistent with our expectations, and we continue to hold the position."
#Education #lope #market #partners


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted LeMaitre Vascular, Inc. (NASDAQ:LMAT). LeMaitre Vascular, Inc. (NASDAQ:LMAT) is a medical device company focusing on the manufacturing and development of products and services for vascular surgery. On August 31, 2026, LeMaitre Vascular, Inc. (NASDAQ:LMAT) closed at $80.28 per share.LeMaitre Vascular, Inc. (NASDAQ:LMAT) declined 24.11% in a month and 15.52% over the past 52 weeks. LeMaitre Vascular, Inc. (NASDAQ:LMAT) has a market capitalization of $1.84 billion with a 52-week trading range between $78.27 - 118.01.
Riverwater Partners Small Cap Strategy stated the following regarding LeMaitre Vascular, Inc. (NASDAQ:LMAT) in its Q2 2026 investor letter:
"LeMaitre Vascular, Inc. (NASDAQ:LMAT), our peripheral vascular device holding, declined approximately 12% in a quarter when nearly everything profitable in small cap health care went down and nearly everything speculative went up. The company's niche leadership, pricing power, and consistent execution are unchanged, and we view the weakness as sentiment-driven rather than fundamental."
LeMaitre Vascular, Inc. (NASDAQ:LMAT) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 22 hedge fund portfolios held LeMaitre Vascular, Inc. (NASDAQ:LMAT) at the end of the second quarter which was 26 in the previous quarter. While we acknowledge the potential of LeMaitre Vascular, Inc. (NASDAQ:LMAT) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI sto


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Oceaneering International, Inc. (NYSE:OII). Oceaneering International, Inc. (NYSE:OII), a subsea engineering and offshore services company that serves the offshore energy, defense, aerospace, and manufacturing industries, was added to the portfolio in the quarter. On August 31, 2026, Oceaneering International, Inc. (NYSE:OII) closed at $51.76 per share. The one-month return of Oceaneering International, Inc. (NYSE:OII) was 2.64% and its shares gained 112.92% over the past 52 weeks. Oceaneering International, Inc. (NYSE:OII) has a market capitalization of $5.15 billion.
Riverwater Partners Small Cap Strategy stated the following regarding Oceaneering International, Inc. (NYSE:OII) in its Q2 2026 investor letter:
"Within energy, we repositioned toward services. We initiated Oceaneering International (OII), a leader in subsea robotics and offshore services, as offshore and subsea capital spending emerges from a seven-year drought and the U.S. rig count climbs; the position was funded in part by our exit of natural gas producer CNX Resources (CNX)."
#small #riverwater #investor #letter


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Werner Enterprises, Inc. (NASDAQ:WERN). The Fund added Werner Enterprises, Inc. (NASDAQ:WERN) which engages in transporting truckload shipments of general commodities in interstate and intrastate commerce, to its portfolio during the quarter. On August 31, 2026, Werner Enterprises, Inc. (NASDAQ:WERN) closed at $39.18 per share. The one-month return of Werner Enterprises, Inc. (NASDAQ:WERN) was 2.27% and its shares gained 37.43% over the past 52 weeks. Werner Enterprises, Inc. (NASDAQ:WERN) has a market capitalization of $2.35 billion with a 52-week trading range between $23.06 to $47.49.
Riverwater Partners Small Cap Strategy stated the following regarding Werner Enterprises, Inc. (NASDAQ:WERN) in its Q2 2026 investor letter:
"Late in the quarter we initiated Werner Enterprises, Inc. (NASDAQ:WERN), one of the largest truckload carriers. A landmark liability ruling now places responsibility for driver safety squarely on carriers with the balance sheets to insure it, a change we believe will force as much as a third of industry capacity, concentrated among small and marginal operators, to consolidate or exit. Large, well-capitalized carriers such as Werner should be the direct beneficiaries through pricing power and share gains. Only two of fifteen covering ****** ysts rated the stock a buy when we purchased it, which is precisely the setup we look for: identifying the inflection before the upgrade cycle begins."
#wern


2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#stevanato #partners #investor
2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted NetScout Systems, Inc. (NASDAQ:NTCT) as a new addition. NetScout Systems, Inc. (NASDAQ:NTCT) provides carrier service ****** urance, cybersecurity, and Distributed Denial-of-Service (DDoS) solutions to protect digital business services against disruptions. On August 31, 2026, NetScout Systems, Inc. (NASDAQ:NTCT) closed at $38.83 per share. The one-month return of NetScout Systems, Inc. (NASDAQ:NTCT) was -8.01% and its shares gained 57.59% over the past 52 weeks. NetScout Systems, Inc. (NASDAQ:NTCT) has a market capitalization of $2.82 billion with a 52-week trading range between $24.27 - $45.28.
Riverwater Partners Small Cap Strategy stated the following regarding NetScout Systems, Inc. (NASDAQ:NTCT) in its Q2 2026 investor letter:
"We initiated a position in NetScout Systems, Inc. (NASDAQ:NTCT) in April. Founded in 1984, NetScout Systems, Inc. (NTCT), with a stated mission of "Guardians of A Connected World," has been a technology innovator providing service ****** urance and cybersecurity solutions based on its pioneering deep packet inspection technology at scale. While high-growth competitors trade at significant premiums, NetScout offers a more attractive valuation for what we view as a durable software business with deeply embedded customer relationships among the Fortune 500. Its deep packet inspection technology is increasingly critical as enterprises navigate complex digital transformations, cloud migrations, and a heightened threat landscape. We view NTCT as a disciplined way to gain exposure to secular technology tail

2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Kaiser Aluminum Corporation (NASDAQ:KALU) as a portfolio addition. Kaiser Aluminum Corporation (NASDAQ:KALU) manufactures and sells semi-fabricated specialty aluminum mill products. On August 31, 2026, Kaiser Aluminum Corporation (NASDAQ:KALU) closed at $158.78 per share. Kaiser Aluminum Corporation (NASDAQ:KALU) fell 9.07% over the past month, while its shares are up 107.53% over the last 52 weeks. Kaiser Aluminum Corporation (NASDAQ:KALU) has a market capitalization of $2.59 billion.
Riverwater Partners Small Cap Strategy stated the following regarding Kaiser Aluminum Corporation (NASDAQ:KALU) in its Q2 2026 investor letter:
"We also purchased Kaiser Aluminum Corporation (NASDAQ:KALU) as roughly two and a half million tons of global aluminum capacity remains offline following the Middle East smelter disruptions, a supply shock we believe supports elevated pricing for well-positioned domestic producers through at least 2027. Also, continued tariffs on aluminum and alumina products will help pricing stay elevated, even if Middle East capacity comes on faster than expected."
#investor


2 months ago
A laptop arrived late. What was on it made things worse. And now Apple is asking a federal court to move faster, arguing that evidence in its lawsuit against OpenAI is being actively destroyed.
Apple filed a new brief on Aug. 31, escalating its legal battle against the ChatGPT maker. The filing accuses OpenAI of withholding key evidence and alleges that a former Apple engineer sent instructions to an OpenAI colleague to destroy documents. The colleague confirmed she would comply, Bloomberg reported.
The brief was filed Monday, Aug. 31, in support of Apple's motion for expedited pretrial fact-finding in its trade secrets lawsuit against OpenAI.
Apple's lawyers said OpenAI only recently provided a critical piece of evidence: an Apple-issued MacBook that former engineer Chang Liu had been using since leaving the company.
Initial forensic ****** ysis of the laptop found that Liu and colleagues at OpenAI "were well aware" of his continued unauthorized access to Apple's third-party cloud storage providers. The filing alleges Liu also "sent instructions for destroying evidence to an OpenAI colleague who confirmed she would comply."
#Apple #laptop #lawsuit #alleges
2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Digi International Inc. (NASDAQ:DGII) as a material contributor. Digi International Inc. (NASDAQ:DGII) provides business and mission-critical Internet of Things (IoT) connectivity products, services, and solutions in the United States and internationally. On August 28, 2026, Digi International Inc. (NASDAQ:DGII) closed at $75.77 per share. Over the past month, Digi International Inc. (NASDAQ:DGII) returned 6.61%, while its shares have gained 116.16% in the last 52 weeks. Digi International Inc. (NASDAQ:DGII) has a market capitalization of $2.88 billion, and its stock has traded within a 52-week range of $33.41 to $86.84.
Riverwater Partners Small Cap Strategy stated the following regarding Digi International Inc. (NASDAQ:DGII) in its Q2 2026 investor letter:
"Digi International Inc. (NASDAQ:DGII), our industrial internet-of-things connectivity holding, gained approximately 55% as demand for connected infrastructure accelerated alongside the broader AI and automation buildout. Given its expansion into one of our largest holdings, we trimmed modestly during the quarter to fund new ideas and maintain sizing discipline."
#NASDAQ #strategy #riverwater #partners

2 months ago
Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) bought back $4.5 billion in stock in the second quarter, its first major buyback activity since early 2024. While other companies buy back billions of dollars in stock, Berkshire's buyback program is a unique one.
Specifically, Berkshire buys back stock only when its leaders believe it trades at a considerable discount to intrinsic value. This lets investors use Berkshire's buyback as a signal that the stock might be cheap.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Of course, there's more to the story. For one thing, Berkshire started the second quarter with a record high $397.4 billion in cash and Treasuries, and new CEO Abel has been eager to find ways to put it to work.
Also, the second quarter's buyback could be an especially strong signal that Abel believes the stock is cheap right now. Not only is $4.5 billion the most Berkshire Hathaway has spent on buybacks in a single quarter since 2021, but Berkshire's buybacks in recent years have generally occurred while Berkshire was a net seller of stocks.
#second