
1 month ago
With a market cap. of $13.4 billion, McCormick & Company, Incorporated (MKC) is a global leader in flavor, manufacturing and distributing herbs, spices, seasonings, condiments, and flavors across 150 countries and territories. Its portfolio includes well-known brands such as McCormick, French's, Frank's RedHot, OLD BAY, Cholula, and Gourmet Garden, serving retailers, food manufacturers, and foodservice businesses.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet


1 month ago
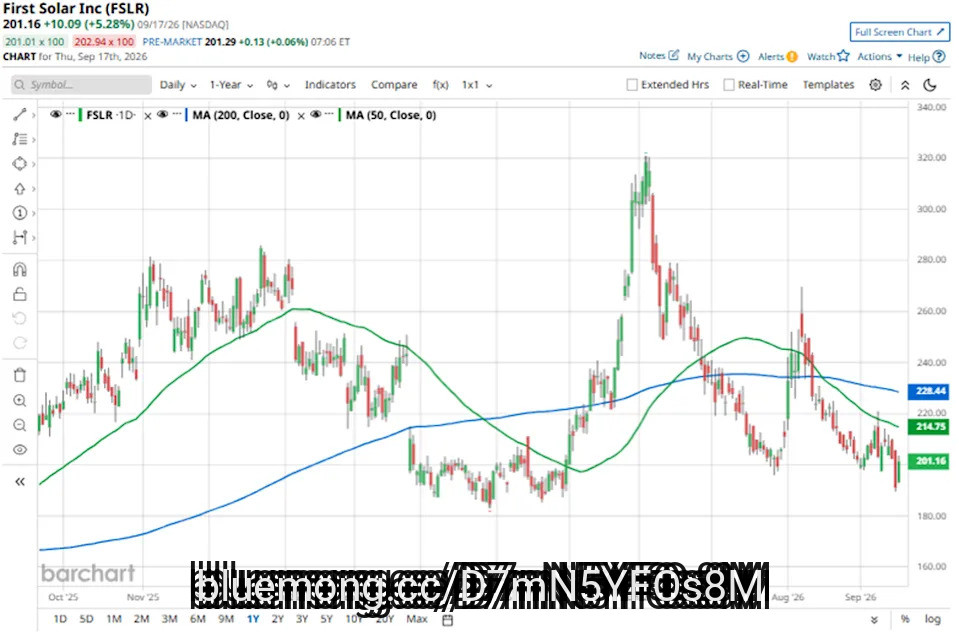
Tempe, Arizona-based First Solar, Inc. (FSLR) is a leading photovoltaic (PV) solar technology and manufacturing company. The company develops and manufactures solar modules using its proprietary thin-film semiconductor technology, offering an alternative to conventional crystalline silicon PV modules. First Solar operates a global manufacturing network spanning the United States, India, Malaysia, and Vietnam. With a market cap of $21.6 billion, the company is one of the largest solar manufacturers.
Companies worth $10 billion or more are generally described as "large-cap stocks," and First Solar fits this description. The company is also one of the few major solar manufacturers with a significant U.S. manufacturing footprint, positioning it to benefit from domestic-content incentives and the broader push to expand U.S. solar manufacturing capacity. First Solar ended the second quarter with a contracted sales backlog of approximately 45.1 GW extending through 2030.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Solar #first #billion #tempe
1 month ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas
1 month ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry

1 month ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
The oil crisis is leaking into other parts of the car. Costco, the land of big and cheap, flipped the script and doubled the price of its full-synthetic motor oil and started rationing purchases. As crude pushes toward $100 a barrel, a 10-quart case that cost roughly $30 now runs $57.99, with purchases capped at two units per member per week.
U.S. diesel crossed $6 a gallon for the first time this week, and global oil inventories have drawn down more than 500 million barrels since the U.S.-Iran conflict began. This is affecting the entire crude industrial complex.
Base oil, which is the feedstock for motor oil, comes from the same barrel as gasoline and diesel so when refiners can earn more finishing crude into fuel than into lubricants, lubricant stock gets squeezed first.
The pressure for Costco, however, is more intense: Its signature Kirkland oil carries GM's Dexos1 Gen 3 certification, which requires manufacturers to pay GM separately per product and per unit sold. As a result, and much against its brand ethos, changing your own oil with Kirkland product now costs roughly what an independent shop would charge, thus eroding the DIY savings case entirely.
#crude #motor #case #week

1 month ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
The oil crisis is leaking into other parts of the car. Costco, the land of big and cheap, flipped the script and doubled the price of its full-synthetic motor oil and started rationing purchases. As crude pushes toward $100 a barrel, a 10-quart case that cost roughly $30 now runs $57.99, with purchases capped at two units per member per week.
U.S. diesel crossed $6 a gallon for the first time this week, and global oil inventories have drawn down more than 500 million barrels since the U.S.-Iran conflict began. This is affecting the entire crude industrial complex.
Base oil, which is the feedstock for motor oil, comes from the same barrel as gasoline and diesel so when refiners can earn more finishing crude into fuel than into lubricants, lubricant stock gets squeezed first.
The pressure for Costco, however, is more intense: Its signature Kirkland oil carries GM's Dexos1 Gen 3 certification, which requires manufacturers to pay GM separately per product and per unit sold. As a result, and much against its brand ethos, changing your own oil with Kirkland product now costs roughly what an independent shop would charge, thus eroding the DIY savings case entirely.
#costco #Stock #roughly
1 month ago
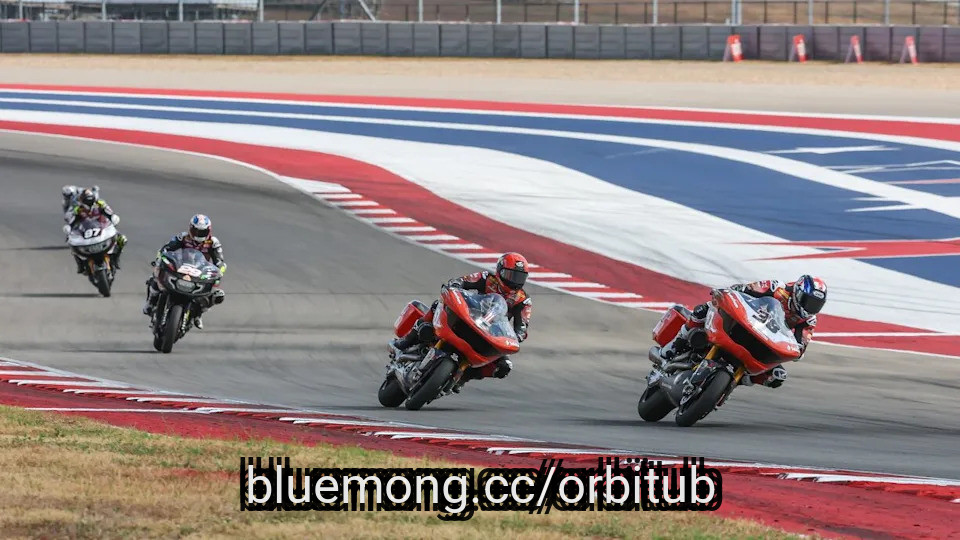
Hayden Gillim won his second King of the Baggers Championship after splitting wins with Bradley Smith at Circuit of the Americas. Gillim also won the **** le in 2023 riding for the Vance & Hines Harley-Davidson team, and after the team switched to Indian this season, he became the first rider to win the **** le for two different manufacturers.
Gillim arrived at COTA with a 23-point lead over teammate Troy Herfoss and a 54-point gap over Harley-Davidson x Dynojet rider Smith. Gillim took Race 1 ahead of Smith and teammate Rocco Landers, while Herfoss retired after a crash on his third lap.
That result set up Race 2 on Sunday, where all Gillim needed to do was manage the gap rather than win outright. Gillim passed Herfoss on the opening lap but ceded the lead to Smith on the fourth lap. Smith held on to win by 4.717 seconds while Gillim held off SDI Racing's Tyler O'Hara to finish second. Herfoss finished off the podium in fifth, behind Harley-Davidson's James Rispoli.
With only a maximum of 50 points remaining across the two-race New Jersey finale, Gillim's 54-point cushion over Smith was enough to secure his second King of the Baggers crown.
"We didn't get the bikes until late and got one test in before the season started, and we came out winning," said Gillim, who won 8 of 12 races heading into New Jersey. "To be able to finish it early is pretty special, especially against the guys that we're racing against."
#smith #harley #king #baggers

1 month ago
Howmet Aerospace Inc. (NYSE:HWM) is facing a mixed outlook after GE Aerospace agreed to acquire Consolidated Precision Products (CPP) for about $11.75 billion to secure more control over critical engine castings and expand production capacity. The announcement initially hit Howmet shares, which fell about 10%, as investors worried that GE could eventually rely less on outside suppliers such as Howmet.
However, Howmet CEO John Plant said he is comfortable with the deal and remains confident in Howmet's ability to grow. The bigger issue for Howmet right now appears to be how quickly it can expand capacity to keep up with soaring demand. Commercial aircraft production, defense activity and aftermarket demand are all increasing, while Howmet is also benefiting from demand for turbine components used in data centers. Plant said the scale of the required capital expansion is itself "testing" the company.
The strongest bullish argument for Howmet Aerospace Inc. (NYSE:HWM) is that GE's decision to spend nearly $12 billion on CPP validates how strategically valuable aerospace castings and engine components have become. The acquisition is aimed at addressing a supply bottleneck rather than signaling weak demand. GE expects airfoil demand to rise by more than 30% through 2030, while aircraft manufacturers and defense customers continue to push production higher. That creates a favorable industry backdrop for Howmet as well.
Howmet also has an opportunity to benefit from customers looking for additional capacity outside GE's newly integrated supply chain. If demand continues to exceed available casting capacity, Howmet's existing manufacturing footprint and expertise could give it significant pricing power and support further investment. Plant's comments that the company is being "tested" by the sheer scale of expansion suggest that Howmet is dealing with a capacity problem caused by strong demand, rather than a lack of orders.
Another positive is that Howmet Aerospace Inc. (NYSE:HWM)'s exposure extends beyond commercial aircraft. Its blades and vanes are also used in gas turbines serving the rapidly expanding data-center market, providing another avenue for growth alongside aerospace. Plant has also indicated that the company intends to revisit its longer-term revenue targets, after previously saying revenue could potentially double from 2025 levels within three to five years.
#commercial


1 month ago
CHATTANOOGA, Tenn. — Kenco opened a 30,000-square-foot Innovation Lab on Sept. 10, tripling a testing footprint the third-party logistics provider first built in 2015.
The larger facility allows Kenco to run warehouse automation testing on larger and more complex systems. It also allows more of those systems to run side by side. Testing takes place inside a building designed to mirror real-world warehouse conditions so results carry over to a live distribution center.
Ainsley Williams, vice president of automation and innovation at Kenco, described the expansion as benefiting both manufacturers and customers.
"The Innovation Lab has long stood as the convergence point for leading technologies and real-world applications, helping both manufacturers and customers identify and realize what's possible," Williams said. "By tripling our innovation footprint, we can further provide a ***** e for OEMs to continue experimenting with their products in a real environment and for customers to explore product and value without having to invest in them."
The original lab was created to help the company understand how emerging technologies such as automation would affect its operations.
#real #customers #larger

1 month ago
Costco has raised the price of its Kirkland Signature full-synthetic motor oil and begun limiting how much any one member can purchase, as a global lubricant shortage tied to the ongoing Middle East conflict pushes crude oil toward $100 a barrel.
That 10-quart case — two 5-quart bottles, enough for a typical V6 or V8 oil change — has jumped to $57.99, compared with the roughly $30 price members had grown accustomed to paying, according to The Drive. Stores are capping purchases at two units per customer per week. The retailer has also imposed a five-per-member limit on Mobil 1, with six quarts of that brand running $44.
The rationing reflects pressure from multiple directions. The connection to fuel prices runs through the refinery: base oil shares its crude-oil origins with gasoline and diesel, so when margins on finished fuel are strong, refiners have a financial reason to favor fuel production over lubricant stock, according to The Auto Wire. EIA data showed the gasoline crack spread sitting roughly a dollar per gallon higher than where it stood at the same point in 2025, a gap that has squeezed base oil availability and pushed its price upward.
Regulatory and licensing costs add a separate layer of expense. The Kirkland 5W-30 displays the dexos1 Gen 3 certification, GM's proprietary specification, and earning that mark is not free — manufacturers must put their formulation through GM's independent testing protocol and obtain a license from the automaker, paying separately for each product and each unit sold, according to The Auto Wire. Layered on top of that is an industry-wide burden: when the API SP category took effect around 2020, it introduced seven additional laboratory tests with no equivalent in the previous standard, among them a procedure targeting low-speed pre-ignition, the knock-like detonation problem **** ociated with modern turbocharged, direct-injection engines.
The supply squeeze is unfolding against a backdrop of a worsening global oil deficit. The International Energy Agency cut its 2026 global oil supply forecast to 102 million barrels per day in August, projecting a deficit of 1.8 million barrels per day in the third quarter — more than double its prior estimate. **** ulative global inventory draws since the start of the U.S.-Iran conflict have reached more than 500 million barrels, and Chevron CEO Mike Wirth said last week that the cushions that had softened earlier price increases have been exhausted. U.S. diesel prices crossed $6 per gallon for the first time, sitting at $6.06 as of Monday, an 8-cent increase from Sunday and 21 cents above week-earlier levels, according to AAA.
#barrels #wire

1 month ago
Investors seeking exposure to artificial intelligence infrastructure must weigh the explosive growth of Astera Labs Inc (NASDAQ:ALAB) against the established scale and diverse portfolio of Marvell Technology Inc(NASDAQ:MRVL) to determine the better buy.
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million
1 month ago
As artificial intelligence matures, investors must decide between the high-growth niche players and the foundational giants. Choosing between Astera Labs Inc (NASDAQ:ALAB) and Taiwan Semiconductor Manufacturing Co (NYSE:TSM) involves weighing explosive potential against established dominance.
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
1 month ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Gold doesn't rise or fall because of a single economic event. Its price reflects the decisions of millions of investors, central banks, manufacturers, jewelers, and others around the world. Those decisions are shaped by changing economic conditions and future expectations.
Understanding what drives the price of gold means learning how multiple forces interact. Sometimes they reinforce one another. Sometimes they pull in opposite directions. That's why different headlines can describe the same market move from different angles.
Every second the global gold market is open, buyers and sellers are negotiating a price — but they're not all buying gold for the same reason.
An investor may be looking to diversify a portfolio. A jewelry manufacturer may need gold for finished products. A technology company may use it in electronic components. A central bank may be increasing its reserves. Another investor may believe interest rates are about to fall.
#Gold #price #economic #different


1 month ago
Railroad retirement coverage follows the employer, not the work, so independent locomotive manufacturers' workers earn zero creditable railroad service regardless of their job.
Paycheck deductions reveal which system applies. Railroad employees pay Tier I and Tier II taxes, while Social Security-covered workers see only standard withholding.
Workers should confirm RRB employer coverage, check payroll records for Tier II deductions, and review their Social Security earnings record before building any retirement plan.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
In February, Union Pacific signed a $1.2 billion deal with Wabtec to modernize locomotives, a reminder that the companies building the machines and the railroads running them can sit on opposite sides of a surprisingly important retirement line.
#railroad

1 month ago
Is it better to own a company already selling drugs or one with a potential blockbuster in testing? Investors are weighing Axsome Therapeutics (NASDAQ:AXSM) against Viking Therapeutics (NASDAQ:VKTX) to decide.
Axsome focuses on commercializing treatments for depression and sleep disorders, showing significant revenue growth. Viking is a clinical-stage developer targeting the massive obesity market but has no products on the market yet. Both represent different stages of growth within the biotech world, making them popular choices for healthcare-minded portfolios.
Axsome develops and sells treatments for central nervous system conditions such as depression, migraines, and narcolepsy. It is a prominent name among biotech stocks, with a portfolio that includes Auvelity, Sunosi, and Symbravo. The company recently entered a settlement that grants license rights to five generic manufacturers for Sunosi starting in 2040, providing long-term clarity on its patent life and market position. In its latest annual report, filed in early 2026, the company noted it had over 900 full-time employees to support its commercial reach.
In FY 2025, revenue reached nearly $638.5 million, marking growth of close to 65.5% compared to the prior year. This increase was driven by the continued expansion of its key central nervous system treatments into new geographic markets. The company reported a net loss of approximately $183.2 million, resulting in a negative net margin, which is the percentage of revenue left after all expenses are paid, of roughly 28.7%. Some investors focus on the P/S ratio to value the business relative to this growing revenue.
As of December 2025, the debt-to-equity ratio was nearly 2.7x, meaning the company uses significant debt relative to its equity. The current ratio of approximately 1.6x indicates it has $1.60 in ****** ets for every $1.00 in liabilities due within a year. Free cash flow, or cash from operations minus capital spending, was nearly negative $93.9 million as the company continues to invest in its commercial pipeline. This spending is intended to support the long-term growth of its approved products and the development of new candidates.
#ratio #therapeutics
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
A dispute over allegations of defective work that resulted in trailers catching fire now is threatening to drag in the manufacturers of some of those components that may be at the root of the incidents.
The case of Indiana-based Summitt Leasing and Summitt Trucking vs. Fruehauf was first filed in the U.S. District Court for the Western district of Kentucky at the end of last year, with an amended complaint filed soon after. Summitt is a carrier as well as a supplier of leased trailers.
Long cast of characters
Last week, Fruehauf, a manufacturer of trailers, moved to bring in as defendants SAF-Holland Inc., Bendix Commercial Vehicle Systems LLC and Hoosier Trailer Acquisition Corp. Two of those companies, SAF-Holland and Bendix, manufactured components in the trailers that van leasing company Summitt says failed in several different ways, which may have led to the fires.
Hoosier is a trailer dealer that supplied the Fruehauf-manufactured trailer to Pace Transportation Services, which then moved the trailers to Summitt. Pace already was a defendant in the original case along with Fruehauf.
#fruehauf #trailer

2 months ago
Andvari ****** ociates, an investment management firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow ****** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari ****** ociates highlighted Texas Instruments Incorporated (NASDAQ:TXN), a semiconductor manufacturer providing chips and solutions for electronics designers and manufacturers. On September 02, 2026, Texas Instruments Incorporated (NASDAQ:TXN) closed at $254.80 per share. Over the past month, Texas Instruments Incorporated (NASDAQ:TXN) fell 8.48%, while its shares gained 36.05% over the past 52 weeks. Texas Instruments Incorporated (NASDAQ:TXN) has a market capitalization of $232.7 billion.
Andvari ****** ociates stated the following regarding Texas Instruments Incorporated (NASDAQ:TXN) in its Q2 2026 investor letter:
"I also added Texas Instruments Incorporated (NASDAQ:TXN), which makes ****** og and power management chips. Texas Instruments and Martin Marietta might be getting a nice temporary ****** p in profits and revenues from helping build out AI infrastructure, but AI and data center-related revenues are by no means the majority of revenues for either of these two companies."
Texas Instruments Incorporated (NASDAQ:TXN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 111 hedge fund portfolios held Texas Instruments Incorporated (NASDAQ:TXN) at the end of the second quarter, up from 71 in the previous quarter. While we acknowledge the potential of Texas Instruments Incorporated (NASDAQ:TXN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#andvari
2 months ago
Foster City, California-based Gilead Sciences, Inc. (GILD) discovers, develops, and commercializes medicines in the areas of unmet medical need in the United States and internationally. The company has a market cap of $185.9 billion and provides Biktarvy, Descovy, Genvoya, Odefsey, Sunlenca, Symtuza, and Yeztugo for the treatment of HIV-1 infection in patients, as well as other related drugs.
Companies with a market cap of $10 billion or more are typically referred to as "large-cap stocks." GILD fits perfectly into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the general drug manufacturers industry.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ******* eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#gild #deal #Stock #sciences

2 months ago
Ford Motor (NYSE:F), the global light-vehicle and truck maker with Ford and Lincoln brands, closed at $14.14, up 2.17%. Wednesday's session followed reports that August U.S. sales fell 10.3%. Investors will be closely watching pickup production and demand next.
Trading volume reached 51.7 million shares, coming in roughly 3.1% above its three-month average of 50.2 million shares.
The S&P 500 (SNPINDEX:^GSPC) closed at 7,667, up 0.47%, while the Nasdaq Composite (NASDAQINDEX:^IXIC) finished at 26,218, up 0.45%. Among automobile manufacturers, General Motors (NYSE:GM) closed at $84.88, down 0.88%, and Stellantis (NYSE:STLA) ended at $5.27, down 1.50%, highlighting softer trading in auto peers during the session.
Ford reported August U.S. sales fell 10.3%, marking an eighth straight month of year-over-year declines. Investors were encouraged, however, after the automaker said its production of the large, highly profitable "Super Duty" trucks last month reached a 20-year high. At the same time, the output of F-150 pickups reached its highest point in two years, reports CNBC. Ford was significantly affected by supplier issues due to its large aluminum bodies and other components following an aluminum plant fire late last year.
August electric vehicle (EV) sales were down nearly 80%, while hybrid sales were down 20%. Ford stock is nearly 20% off its 2026 highs, reached after the company announced the formation of Ford Energy in May. That came after it repurposed some EV ******* ets as part of a pivot to tap into demand for energy storage. That helped investors shrug off the plunging EV and hybrid sales.
Before you buy stock in Ford Motor Company, consider this:
#sales

2 months ago
Baron Capital, an investment management company, released its second-quarter 2026 investor letter for its "Baron Global Opportunity Fund". The letter can be downloaded here. The fund achieved a strong quarter, gaining 26.7% (Institutional Shares), exceeding a 14.9% gain for the MSCI ACWI Index (the Index), and a 19.8% gain for the MSCI ACWI Growth Index. YTD, the Fund is up 20.6% compared to gains of 11.3% and 10.6% for the benchmarks, respectively. In mid-2026, market patterns show similarities to the previous year, following three years of over 25% gains driven by a healthy economy and AI investments. Elevated geopolitical risks persisted, with a pullback likely. A tariff-related market dip was followed by a recovery, reflecting a growing market indifference to geopolitical uncertainties. Similarly, airstrikes against Iran and subsequent tension led to an initial market sell-off, yet a lull in hostilities led to a strong market rally. The Fund noted significant outperformance, credited to stock selection and sector allocation, with 1,173bps of overall outperformance relative to the Index. It excelled in developed markets while underperforming in emerging markets, particularly due to a spectacular rise in Korea. The Fund remains optimistic about its investments and seeks attractive opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Baron Global Opportunity Fund highlighted DPC Holdings PLC (NYSE:DPC) as a new addition. DPC Holdings PLC (NYSE:DPC) manufacturers engine products, including complex precision cast components and nickel- and cobalt-based superalloys for aerospace, industrial gas turbine and transportation industries. On September 1, 2026, DPC Holdings PLC (NYSE:DPC) closed at $41.48 per share. Over the past month, DPC Holdings PLC (NYSE:DPC) declined 20.69%. DPC Holdings PLC (NYSE:DPC) has a market capitalization of $6.02 billion.
Baron Global Opportunity Fund stated the following regarding DPC Holdings PLC (NYSE:DPC) in its Q2 2026 investor letter:
We also initiated a new position in DPC Holdings PLC (NYSE:DPC), a leading manufacturer of precision-cast superalloy components – the turbine blades, vanes, and structural castings that must perform under very harsh operating conditions including very high temperatures (1000c) and high pressure. These parts go into both commercial aircraft engines and industrial gas turbines (IGT) that generate electricity. The company occupies a hard-to-replicate market positioning as a critical supplier of the inner parts of an engine that only a handful of qualified manufacturers in the world are capable of producing.
Since the company began its turnaround in 2020 after over a decade under poor ownership, with the leadership of CEO Mike Quinn, who spent over a decade at Precision Castparts, and Co Chairperson of the Board Dirkson Charles, who built and currently is CEO of aerospace and defense proprietary parts provider

2 months ago
On August 10, Chemours (NYSE:CC) launched two new refrigerants, Opteon ZE and Opteon 515B, built specifically for stationary chillers that cool data centers, commercial buildings, and other facilities that cannot afford downtime. The announcement lands as data center operators everywhere are scrambling to keep pace with the heat that AI workloads generate, and Chemours is betting its chemistry can be part of the answer.
Chemours designed these products around a specific problem: AI infrastructure is pushing heat loads and uptime requirements past what older cooling systems were built for. Joseph Martinko, President of Thermal & Specialized Solutions at Chemours, said the company is expanding the choices available to chiller manufacturers and operators as they build and maintain the systems powering data centers and other mission-critical environments. That framing matters because it puts Chemours squarely inside the AI infrastructure buildout rather than on its periphery, and the company describes this as part of a broader push into higher-value, high-growth cooling applications.
The two products are designed to work together rather than compete for the same customer. Opteon ZE, the R-1234ze(E) formulation, is an HFO-based refrigerant with a GWP of approximately 1 and zero ozone depletion potential, aimed at air- and water-cooled chillers, commercial air conditioning, heat pumps, and data center cooling specifically. It also offers high energy efficiency and works with commonly used POE lubricants, which matters for equipment makers who do not want to redesign their systems from scratch.
Opteon 515B is a blend of roughly 91.1% R-1234ze(E) and 8.9% R-227ea, with a GWP near 293, pitched at operators running conventional chillers who want an easier path away from higher-GWP refrigerants without a full system overhaul. Having both a near-zero-GWP option and a lower-friction transitional option lets Chemours sell into new builds and legacy fleets at the same time.
The launch is not without caveats. Opteon ZE carries an ASHRAE A2L classification, meaning it is mildly flammable, while Opteon 515B carries the non-flammable A1 rating. That difference alone could steer certain customers toward one product over the other depending on local codes and installation requirements.
#heat #cooling

2 months ago
Red Bull could be locked in a race against the clock as a massive F1 engine crisis looms that could dominate early discussions at the Italian GP in Monza.
As the technical landscape of the new regulations continues to evolve, the ongoing ADUO debate is emerging as a critical focal point for the sport's leading power unit manufacturers.
At the sharp end of this discussion is Red Bull Powertrains, where the approaching third **** sment window presents a high-stakes operational dilemma dictated entirely by manufacturing realities.
Internal combustion and hybrid powertrain programmes require immense lead times. Component design, dynamometer validation, casting, and precision machining collectively demand lead times in the region of 36 weeks.
Consequently, by the time the FIA conducts its third scheduled evaluation window, Red Bull may find itself boxed into a corner by its own production calendar.
#monza

2 months ago
Investment management company First Pacific Advisors recently released its "FPA Queens Road Small Cap Value Fund" second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The Fund returned 27.02% in the first half of 2026, outperforming the Russell 2000 Value Index's 22.99% gain and the S&P 600 Index's 23.90% return. Small-cap earnings growth also began accelerating relative to large caps, while the small-cap technology sector surged nearly 100% in 26H1. The fund's technology holdings gained 72.39%, contributing 14.87 percentage points, compared with a 95.27% return and 7.10-point contribution from the benchmark's technology sector. Excluding IT and cash, the Fund contributed 12.73% versus 15.89% for the Russell 2000 Value Index; on a fully invested basis, the figures were 16.62% and 17.59%, respectively. The portfolio continued to trim appreciated technology holdings amid the AI-driven rally, while maintaining a bottom-up approach and avoiding beaten-down SaaS stocks due to the widening range of AI-related outcomes. The fund also eliminated about $62 million in capital gains during Q2 and approximately $140 million year-to-date through July, while ending the quarter with 10.2% in cash. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, FPA Queens Road Small Cap Value Fund highlighted stocks like InterDigital (NASDAQ:IDCC). InterDigital (NASDAQ:IDCC) develops wireless and video technologies and generates licensing revenue from its portfolio of cellular and digital communications patents. The one-month return of InterDigital (NASDAQ:IDCC) was 3.67% while its shares traded between $249.14 and $412.60 over the last 52 weeks. On August 31, 2026, InterDigital (NASDAQ:IDCC) stock closed at approximately $335.15 per share, with a market capitalization of about $8.65 billion.
FPA Queens Road Small Cap Value Fund stated the following regarding InterDigital (NASDAQ:IDCC) in its Q2 2026 investor letter:
"Interdigital (NASDAQ:IDCC) owns an expansive collection of wireless patents. Most of their revenue comes from licensing agreements with smart phone manufacturers, but the company has also started licensing to consumer electronics, auto, industrial and media companies. CEO Liren Chen joined in 2021 from Qualcomm and has done an exceptional job ramping up the pace of licensing deals. The stock price has followed earnings growth higher and IDCC was a top performer for the Fund in 2023, 2024 and 2025. We have trimmed all the way up but still hold a less than 2% position in IDCC."
#fund #small #road

2 months ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted PDF Solutions, Inc. (NASDAQ:PDFS). PDF Solutions, Inc. (NASDAQ:PDFS) provides proprietary software, physical intellectual property for integrated circuit designs, electrical measurement hardware tools, proven methodologies, and professional services. On August 28, 2026, PDF Solutions, Inc. (NASDAQ:PDFS) closed at $44.81 per share. One-month return of PDF Solutions, Inc. (NASDAQ:PDFS) was -7.31% and its shares gained 117.56% over the past 52 weeks. PDF Solutions, Inc. (NASDAQ:PDFS) has a market capitalization of $1.89 billion.
Riverwater Partners Small Cap Strategy stated the following regarding PDF Solutions, Inc. (NASDAQ:PDFS) in its Q2 2026 investor letter:
"PDF Solutions, a provider of yield ***** ytics and data software for semiconductor manufacturers, returned approximately 52% in the quarter. During May, long-time strategic holder Advantest exited its entire 8% stake through an upsized secondary offering, with PDF selling additional shares alongside to fund general corporate purposes and potential debt reduction. We interpreted the heavily oversubscribed deal as a sign of management taking control of its own destiny, and we used the offering-related weakness to add a full percentage point to the position, funded by a sale of Veeco (VECO) to keep our overall semiconductor exposure in check. Late in the quarter we trimmed a portion of the position after the sharp run, consistent with our practice of harvesting gains in extended semiconductor names..." (Click here to read the full text)
#solutions #quarter #investor #lette

2 months ago
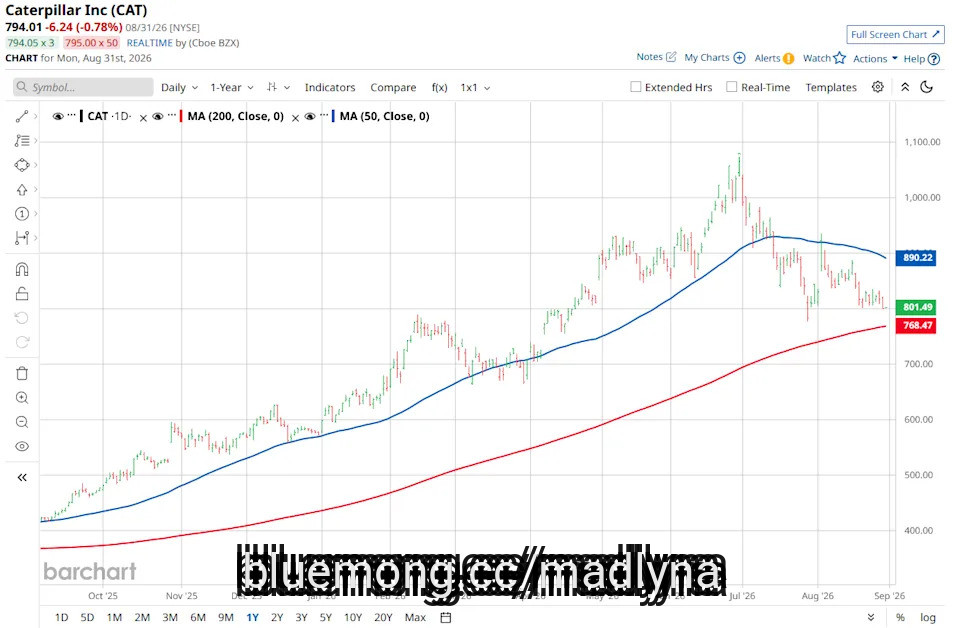
Irving, Texas-based Caterpillar Inc. (CAT) manufactures and sells construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives in the United States and internationally. The company has a market capitalization of $367.9 billion and is one of the world's largest manufacturers of the said equipment.
Companies with a market cap of $200 billion or more are typically referred to as "mega-cap stocks." CAT fits perfectly into that category, with its market cap exceeding this threshold and reflecting its substantial size and influence in the farm and heavy construction machinery industry.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#Stock #construction #Diesel #billion

2 months ago
The S&P 500 (SNPINDEX: ^GSPC) is hovering near a record high, but the ongoing geopolitical tensions in the Middle East, the rising odds of an interest rate hike, and the upcoming midterm congressional elections in November could disrupt what has been an incredible (nearly) four-year bull market.
The S&P 500 is currently trading at a Shiller Cyclically Adjusted Price-to-Earnings (CAPE) ratio of 41.8, its second-highest valuation in history, behind only the dot-com bubble peak in 2000. Even if the index were to plunge into a technical bear market by suffering a 20% decline from its recent peak, it would still be expensive by historical standards.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But the broader market has always trended higher over the long term, so sell-offs can be a great opportunity for investors to scoop up bargains. One stock that could be a great buy at a discount is Corning (NYSE: GLW), which has become a key player in the global artificial intelligence (AI) data center build-out. Here's why.
Corning has been one of America's leading glass manufacturers for the last 175 years. It was the main supplier of glass for Thomas Edison's original lightbulb in 1880, and today, it makes the glass for all of Apple's iPhones. But the company's biggest opportunity currently lies in manufacturing fiber-optic connectivity solutions for data centers that accelerate processing speeds for AI workloads.
#years

2 months ago
The wait for a large gas turbine now runs longer than the time it takes to design, permit, and build the plant it will sit in. Order one today from any of the three largest manufacturers, and the delivery slot lands four or more years out—if a slot is available at all. The queue to connect a new plant to the grid runs about as long. For developers racing to power the data centers hyperscalers are building, the timeline no longer works, and it is pushing the U.S. generation build toward whatever can be constructed without waiting in either line.That dislocation is the backdrop to a quieter story about where capital is moving, and it surfaced in July when a familiar U.S. plant operator changed hands. IHI Power Services Corp., a company with roughly four decades of experience running American power plants, became Kyuden Energy Partners Corp. on completion of its acquisition by Kyuden International Corp., the overseas arm of a company fully owned by **** an's Kyushu Electric Power Co. The rebrand is the news of the day. The more instructive part is what a foreign utility chose to buy: not power plants, but the capability to run them.
Tony Dabbene, who led IHI Power Services through the transition and stays on as CEO, was blunt about the market. "We are seeing the most dynamic environment in decades," he told POWER, pointing to demand tied to the hyperscalers' data center buildout. Major gas turbine manufacturers, he said, are quoting lead times of four-plus years, with interconnection queues running about the same. The manufacturers' own disclosures bear that out: GE Vernova's gas turbine backlog and slot reservations reached 116 GW by mid-2026, and Siemens Energy has described itself as booked into the back half of the decade, treating 2029 delivery slots as near-term availability.What Dabbene described next was the market's response. Rather than wait for an interconnection that may not clear before mid-decade, developers are building behind the meter and on private grids that sidestep the queue entirely. To power them, they're reaching for whatever can be deployed the fastest: reciprocating engines, fuel cells, and battery storage paired with microgrids, engineered to achieve the high-availability targets that around-the-clock computing demands while managing the power-quality swings that come when those loads shift in an instant. "It is a brand-new world in the energy **** e," he said.This is where a multi-fuel operator has the edge. A company that already runs natural gas, hydro, biomass, wind, solar, and storage has done the work developers are now rushing toward—operating mixed generation and meeting high availability targets. The turbine shortage may be a headache for those building facilities, but it's an opportunity for reliable operators.
#corp #runs #plant #four
2 months ago
The race to build more data centers for artificial intelligence is driving demand for more than chips and electricity.
It also requires vast networks of high-speed optical fiber to move data between servers, putting one of America's oldest manufacturers at the center of the boom.
Corning, the New York-based company best known to many Americans for its kitchenware and smartphone glass, is ramping up optical-fiber production as the data-center buildout accelerates. Nearly 175 years after its founding, the company is supplying a critical piece of the infrastructure behind the AI boom, the glass connections linking the servers inside the facilities powering it.
One Of The World's Hottest Industries Is Sparking A Blue-collar Jobs Boom
The company is partnering with NVIDIA to build three advanced optical-manufacturing facilities in North Carolina and Texas. The project is expected to create more than 3,000 jobs and expand Corning's U.S. optical-manufacturing capacity tenfold.
#boom


2 months ago
North Chicago, Illinois-based AbbVie Inc. (ABBV) is a global, research-driven biopharmaceutical company focused on developing and commercializing medicines for complex and serious diseases. Valued at a market cap of $386.3 billion, its key therapeutic areas include immunology, neuroscience, oncology and aesthetics, with operations spanning more than 75 countries.
Companies with a market capitalization of $200 billion or more are typically referred to as "mega-cap stocks." ABBV fits right into that category, with its market cap exceeding this threshold, reflecting its substantial size and influence in the general drug manufacturers industry. AbbVie combines a large established pharmaceutical portfolio with a rapidly expanding immunology franchise and a broad pipeline.
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Tesla Just Killed Its Solar Roof After Years of Struggling to Scale. What It Means for TSLA Stock.
Tesla Stock Could Benefit as Trump Locks Down the U.S. Power Grid
#abbvie #abbv #billion