5 days ago
Being a "buy-and-hold" investor sounds simple, but it can be harder to do in real life. When stocks are wobbly, when the tech-heavy Nasdaq-100 goes into a sell-off, when economists question the economic value of artificial intelligence (AI), it's easy to get nervous and make fear-driven moves based on short-term news.
But for most people who are not professional investors or money managers or hedge fund executives, the best investment strategy is often just to buy and hold. Buy stocks in a diversified portfolio like the S&P 500 index. Keep buying stocks as often as you can.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
And then: hold them. Don't sell. Hold them for years -- five years, 10 years, or more. Don't try to day trade, don't try to move in and out of the market, don't try to sell your stocks based on a hunch about what the market will do tomorrow. If you're really in it for the long run, buy-and-hold investing can generate significant wealth for everyday investors.
My two favorite stock exchange-traded funds (ETFs) are low-cost index funds. They're simple. They're "boring." But these two ETFs together let me own basically all the stocks in the world.
#hold #sell #investors #missed
But for most people who are not professional investors or money managers or hedge fund executives, the best investment strategy is often just to buy and hold. Buy stocks in a diversified portfolio like the S&P 500 index. Keep buying stocks as often as you can.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
And then: hold them. Don't sell. Hold them for years -- five years, 10 years, or more. Don't try to day trade, don't try to move in and out of the market, don't try to sell your stocks based on a hunch about what the market will do tomorrow. If you're really in it for the long run, buy-and-hold investing can generate significant wealth for everyday investors.
My two favorite stock exchange-traded funds (ETFs) are low-cost index funds. They're simple. They're "boring." But these two ETFs together let me own basically all the stocks in the world.
#hold #sell #investors #missed
5 days ago
BUFFALO Funds, an actively managed mutual fund advised by Kornitzer Capital Management, released its third-quarter 2026 investor letter for "Buffalo Growth Fund". The letter can be downloaded here. The Buffalo Growth Fund advanced 4.57% in Q3, significantly outperforming the Russell 3000® Growth Index's 0.45%. The primary driver of this outperformance was stock selection in Information Technology, particularly among hyperscaler stocks that benefited from higher cloud revenue. However, rising oil prices and inflation challenged the market, prompting the Federal Reserve to raise interest rates for the first time since July 2023 and prompting caution within the Fund. The fund has reduced some positions, noting the cost of capital's impact on business models. There is optimism for hyperscalers following the upcoming Anthropic IPO, which could provide investor transparency for future capex. Also, check the Fund's top five holdings to see its best picks for 2026.
In its Q3 2026 investor letter, Buffalo Growth Fund noted that it sold its position in SanDisk Corporation (NASDAQ:SNDK) during the quarter. SanDisk Corporation (NASDAQ:SNDK) is a US-based semiconductor company that provides data storage devices and solutions using NAND flash technology for AI developers and enterprise workloads. On November 03, 2026, SanDisk Corporation (NASDAQ:SNDK) closed at $1,126.52, with a $160.29 billion market capitalization. Driven by strong momentum, SanDisk Corporation (NASDAQ:SNDK) has surged 335.83% year-to-date, trading within a 52-week range of $164.56 to $2,354.39.
Buffalo Growth Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q3 2026 investor letter:
"In the previous quarter we determined the portfolio was lacking exposure to the memory ***** e and initiated small positions in both Micron and Sandisk Corporation (NASDAQ:SNDK). Unfortunately, the timing on Sandisk was poor as the stock advanced rapidly through the end of June and then experienced the bottom drop out with nasty momentum unwind in July. We decided to take losses on Sandisk and move on from a ***** e that has historically been incredibly cyclical. Typically, cyclical businesses like this aren't where we focus our time and this experience reminded us of that."
Sandisk Corporation (NASDAQ:SNDK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth
In its Q3 2026 investor letter, Buffalo Growth Fund noted that it sold its position in SanDisk Corporation (NASDAQ:SNDK) during the quarter. SanDisk Corporation (NASDAQ:SNDK) is a US-based semiconductor company that provides data storage devices and solutions using NAND flash technology for AI developers and enterprise workloads. On November 03, 2026, SanDisk Corporation (NASDAQ:SNDK) closed at $1,126.52, with a $160.29 billion market capitalization. Driven by strong momentum, SanDisk Corporation (NASDAQ:SNDK) has surged 335.83% year-to-date, trading within a 52-week range of $164.56 to $2,354.39.
Buffalo Growth Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q3 2026 investor letter:
"In the previous quarter we determined the portfolio was lacking exposure to the memory ***** e and initiated small positions in both Micron and Sandisk Corporation (NASDAQ:SNDK). Unfortunately, the timing on Sandisk was poor as the stock advanced rapidly through the end of June and then experienced the bottom drop out with nasty momentum unwind in July. We decided to take losses on Sandisk and move on from a ***** e that has historically been incredibly cyclical. Typically, cyclical businesses like this aren't where we focus our time and this experience reminded us of that."
Sandisk Corporation (NASDAQ:SNDK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth
10 days ago
The world mourned the loss of Patrick Stewart on Thursday as the iconic actor passed at the age of 86 after a battle with Alzheimer's Disease and Lewy Body Dementia. Stewart was a prolific stage actor as well as taking on massive roles in both television and film. He played Captain Jean-Luc Picard for 176 episodes of Star Trek: The Next Generation, as well as starring as Professor X in eight X-Men movies -- including post-credit scenes and cameos -- across both the Fox and Marvel Cinematic universes (with the ninth coming this December with Avengers: Doomsday).
But one of the things that made Stewart so special and beloved was his willingness to do something goofy or funny. Such was the case in a 2024 Super Bowl commercial for Paramount+. Not only did Stewart star alongside well-known CBS and Paramount+ characters like Survivor's Jeff Probst, Knuckles from Sonic the Hedgehog, daytime host Drew Barrymore and Miami Dolphins QB Tua Tagovailoa.
Knuckles appears in the new Paramount+ Super Bowl commercial. pic.twitter.com/tuD7G4GfXz
— Sonic The Wereblog (Sonic_Hedgeblog) February 1, 2024
It's a truly ridiculous commercial that features Stewart trying to convince Tagovailoa to throw Arnold of Hey Arnold! to the top of a mountain. "Not built for the moment, I see," Stewart delivers as if he's on stage in the West End.
#well
But one of the things that made Stewart so special and beloved was his willingness to do something goofy or funny. Such was the case in a 2024 Super Bowl commercial for Paramount+. Not only did Stewart star alongside well-known CBS and Paramount+ characters like Survivor's Jeff Probst, Knuckles from Sonic the Hedgehog, daytime host Drew Barrymore and Miami Dolphins QB Tua Tagovailoa.
Knuckles appears in the new Paramount+ Super Bowl commercial. pic.twitter.com/tuD7G4GfXz
— Sonic The Wereblog (Sonic_Hedgeblog) February 1, 2024
It's a truly ridiculous commercial that features Stewart trying to convince Tagovailoa to throw Arnold of Hey Arnold! to the top of a mountain. "Not built for the moment, I see," Stewart delivers as if he's on stage in the West End.
#well

21 days ago
CLEVELAND — The Guardians have repeatedly shown they are not going to live in their fears during the MLB playoffs.
On Sunday, Oct. 18, Game 5 of the American League Championship Series proved the bold approach can backfire.
For the first time, the Guardians paired starting pitcher Parker Messick with catcher Patrick Bailey instead of Austin Hedges. Perhaps Messick still would have had a rough outing if Hedges were catching. Although Messick insisted his arm and body feel good, he has pitched 200 innings in the 2026 regular season and postseason combined — far more than he had ever pitched in a single college or minor-league season.
Whether Messick is fatigued or fresh, the bottom line is the Guardians used a new wrinkle with a rookie pitcher under the bright lights of the playoffs, and he did not perform well in a monumental Game 5.
Messick struggling is certainly not the only reason the Guardians lost 3-1 to the Tampa Bay Rays at Progressive Field and now trail 3-2 in the best-of-seven ALCS as the series returns to St. Petersburg, Florida, for Game 6 at 8:08 p.m. Monday, Oct. 19, at Tropicana Field.
#messick #game #field #series
On Sunday, Oct. 18, Game 5 of the American League Championship Series proved the bold approach can backfire.
For the first time, the Guardians paired starting pitcher Parker Messick with catcher Patrick Bailey instead of Austin Hedges. Perhaps Messick still would have had a rough outing if Hedges were catching. Although Messick insisted his arm and body feel good, he has pitched 200 innings in the 2026 regular season and postseason combined — far more than he had ever pitched in a single college or minor-league season.
Whether Messick is fatigued or fresh, the bottom line is the Guardians used a new wrinkle with a rookie pitcher under the bright lights of the playoffs, and he did not perform well in a monumental Game 5.
Messick struggling is certainly not the only reason the Guardians lost 3-1 to the Tampa Bay Rays at Progressive Field and now trail 3-2 in the best-of-seven ALCS as the series returns to St. Petersburg, Florida, for Game 6 at 8:08 p.m. Monday, Oct. 19, at Tropicana Field.
#messick #game #field #series

1 month ago
Under Warren Buffett, Berkshire Hathaway stock returned 19.7% annually between 1965 and 2025, nearly doubling the 10.5% annual return in the S&P 500 (SNPINDEX:^GSPC). That makes Buffett a great source of inspiration, and he consistently recommended an S&P 500 index throughout his career.
"In my view, for most people, the best thing to do is to own the S&P 500 index fund," Buffett said at Berkshire Hathaway's shareholder meeting in 2021. Investors have several options, but Buffett himself selected the Vanguard S&P 500 ETF (NYSEMKT:VOO) when going head-to-head with a hedge fund in the early 2000s.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Following Buffett's advice could turn $400 per month into $820,000. Here's what investors should know.
Image source: Getty Images.
#source
"In my view, for most people, the best thing to do is to own the S&P 500 index fund," Buffett said at Berkshire Hathaway's shareholder meeting in 2021. Investors have several options, but Buffett himself selected the Vanguard S&P 500 ETF (NYSEMKT:VOO) when going head-to-head with a hedge fund in the early 2000s.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Following Buffett's advice could turn $400 per month into $820,000. Here's what investors should know.
Image source: Getty Images.
#source
1 month ago
During the second quarter, Pershing Square Capital Management, the hedge fund firm founded by Bill Ackman, initiated positions in Visa (NYSE: V) and Mastercard (NYSE: MA). While their share prices have appreciated in recent months, these businesses traded at attractive valuations at purchase.
Here are three reasons the billionaire investor is bullish on these two S&P 500 stocks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman's firm believes these are two of the highest-quality businesses on Earth. There are three notable factors supporting this view.
Visa and Mastercard, which connect consumers, merchants, and banks around the world, have developed robust network effects. This makes their platforms almost impossible to disrupt.
#pershing
Here are three reasons the billionaire investor is bullish on these two S&P 500 stocks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman's firm believes these are two of the highest-quality businesses on Earth. There are three notable factors supporting this view.
Visa and Mastercard, which connect consumers, merchants, and banks around the world, have developed robust network effects. This makes their platforms almost impossible to disrupt.
#pershing

1 month ago
Under Warren Buffett, Berkshire Hathaway stock returned 19.7% annually between 1965 and 2025, nearly doubling the 10.5% annual return in the S&P 500 (SNPINDEX:^GSPC). That makes Buffett a great source of inspiration, and he consistently recommended an S&P 500 index throughout his career.
"In my view, for most people, the best thing to do is to own the S&P 500 index fund," Buffett said at Berkshire Hathaway's shareholder meeting in 2021. Investors have several options, but Buffett himself selected the Vanguard S&P 500 ETF (NYSEMKT:VOO) when going head-to-head with a hedge fund in the early 2000s.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Following Buffett's advice could turn $400 per month into $820,000. Here's what investors should know.
Image source: Getty Images.
#buffett #investors #hathaway
"In my view, for most people, the best thing to do is to own the S&P 500 index fund," Buffett said at Berkshire Hathaway's shareholder meeting in 2021. Investors have several options, but Buffett himself selected the Vanguard S&P 500 ETF (NYSEMKT:VOO) when going head-to-head with a hedge fund in the early 2000s.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Following Buffett's advice could turn $400 per month into $820,000. Here's what investors should know.
Image source: Getty Images.
#buffett #investors #hathaway

2 months ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

2 months ago
Cybersecurity provider CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s shares are up by more than 100% year to date. With AI continuing to dominate the market narrative, the firm has found itself at the center of the industry's concerns about cybersecurity. While some, such as Anthropic's Dario Amodei, have claimed that their AI software is sufficient for cybersecurity purposes, others have argued that firms such as CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play a key role in the industry. Cramer is in the latter camp, and in his morning appearance on September 15th, the CNBC TV host discussed the recent discussions about AI being a threat:
"I had George Kurtz last night, who has partnered both with OpenAI and Anthropic. And he encouraged me to say look, they are doing a lot of things about safeguards. I think he was so much surprised, that there was so much doomsaying, of course, doomsaying being heavily refuted. Now there's a stock, remember that stock was up the most of any stock in the S&P."
While Cramer believes CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play an important role in cybersecurity in the AI era, the broader debate about the firm is about its AI-driven cybersecurity initiatives and whether they are sufficient to stay competitive and justify the eye-watering share price performance. On this front, the firm's annual recurring revenue (ARR) grew by 25% and net new ARR grew by 55% in its fiscal second quarter. Additionally, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s net new ARR set a new record of $333 million. Cramer's bullishness on the firm is also matched by others, such as ******* ysts from Argus. Argus has set a $425 share price target for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) and argued that growth in agentic AI use presents a major tailwind for the firm.
Yet, in a classic case of the bigger you are, the harder you fall, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s massive growth creates risk. For its fiscal second quarter, the firm has guided net new ARR to range between $343 million and $347 million to imply growth ranging between 29% to 31%. Considering that the metric grew by 55% in Q1, the new figures do indicate a slowdown. As for catalysts from agentic AI, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s next-gen SIEM (Security Information and Event Management) ending ARR grew by 60% to $695 million in the second quarter.
Hedge fund interest in CrowdStrike Holdings, Inc. (NASDAQ:CRWD) grew in Q2. According to Insider Monkey's data, 89 out of 1,006 funds had held a stake in the firm during the period. This marked a jump over the 89 out of the 1,022 funds in Q1. As for valuation, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s forward P/E ratio of 188 is significantly higher than peer firm Palo Alto's 89 which should increase the pressure to maintain growth. Short interest as a percentage of float is 2.41% for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) compared to 2.65% for Palo Alto.
#NASDAQ #firm #grew
"I had George Kurtz last night, who has partnered both with OpenAI and Anthropic. And he encouraged me to say look, they are doing a lot of things about safeguards. I think he was so much surprised, that there was so much doomsaying, of course, doomsaying being heavily refuted. Now there's a stock, remember that stock was up the most of any stock in the S&P."
While Cramer believes CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play an important role in cybersecurity in the AI era, the broader debate about the firm is about its AI-driven cybersecurity initiatives and whether they are sufficient to stay competitive and justify the eye-watering share price performance. On this front, the firm's annual recurring revenue (ARR) grew by 25% and net new ARR grew by 55% in its fiscal second quarter. Additionally, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s net new ARR set a new record of $333 million. Cramer's bullishness on the firm is also matched by others, such as ******* ysts from Argus. Argus has set a $425 share price target for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) and argued that growth in agentic AI use presents a major tailwind for the firm.
Yet, in a classic case of the bigger you are, the harder you fall, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s massive growth creates risk. For its fiscal second quarter, the firm has guided net new ARR to range between $343 million and $347 million to imply growth ranging between 29% to 31%. Considering that the metric grew by 55% in Q1, the new figures do indicate a slowdown. As for catalysts from agentic AI, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s next-gen SIEM (Security Information and Event Management) ending ARR grew by 60% to $695 million in the second quarter.
Hedge fund interest in CrowdStrike Holdings, Inc. (NASDAQ:CRWD) grew in Q2. According to Insider Monkey's data, 89 out of 1,006 funds had held a stake in the firm during the period. This marked a jump over the 89 out of the 1,022 funds in Q1. As for valuation, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s forward P/E ratio of 188 is significantly higher than peer firm Palo Alto's 89 which should increase the pressure to maintain growth. Short interest as a percentage of float is 2.41% for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) compared to 2.65% for Palo Alto.
#NASDAQ #firm #grew

2 months ago
A $10,000 SPY investment at its 1993 launch would have compounded to $312,667 today, representing a 3,027% gain without adding a single dollar.
SPY's 0.0945% expense ratio costs roughly three times more than VOO or IVV, a gap that quietly compounds against long-term buy-and-hold investors.
RSP owns the same 500 stocks as SPY but weights each equally, cutting megacap dominance and serving as a hedge against a leadership rotation.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A $10,000 stake placed in the SPDR S&P 500 ETF (NYSEARCA:SPY) on its opening day in January 1993 would be worth roughly $312,667 today. That works out to a 3,027% **** ulative gain, or about 10.8% a year compounded across 33 years. No stock picking, no market timing, no additional contributions.
#roughly #years #january
SPY's 0.0945% expense ratio costs roughly three times more than VOO or IVV, a gap that quietly compounds against long-term buy-and-hold investors.
RSP owns the same 500 stocks as SPY but weights each equally, cutting megacap dominance and serving as a hedge against a leadership rotation.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A $10,000 stake placed in the SPDR S&P 500 ETF (NYSEARCA:SPY) on its opening day in January 1993 would be worth roughly $312,667 today. That works out to a 3,027% **** ulative gain, or about 10.8% a year compounded across 33 years. No stock picking, no market timing, no additional contributions.
#roughly #years #january

2 months ago
The State Department's approval of two potential arms sales to Saudi Arabia totaling $5.75 billion, including JDAM-ER munitions and AGT-1500 tank engines, offers a modest but meaningful data point for two very different defense players. For The Boeing Company (NYSE:BA), the potential sale represents an additional international defense opportunity as the company continues working through margin pressure elsewhere. For Honeywell Aerospace Inc. (NASDAQ:HONA), the package reinforces a stable business line while the firm tackles its first quarter as a standalone public company.
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi

2 months ago
When Ray Dalio speaks, investors tend to listen, and likely for good reason. He ran Bridgewater **** ociates, the hedge fund he founded, for half a century, and over that time, he was one of the most successful investment managers in history.
In fact, he has long used history as a guide for deploying capital, and today, he believes history offers lessons for how investors should approach the AI boom. Specifically, he sees echoes of 1929 and 2000 in the current situation, and is urging investors to approach AI stocks with caution. Here is what he said and why investors may want to heed his advice.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
First of all, investors should remember that Dalio has stepped down from Bridgewater. Thus, the fund's investments in AI stocks like ServiceNow and Nutanix were likely made without his input.
Given what he has said recently, he may even disagree with those purchases. When Dalio appeared on the podcast The Diary of a CEO in August, he said that AI shows "classic signs" of a bubble.
#dalio #signal #flashing #likely
In fact, he has long used history as a guide for deploying capital, and today, he believes history offers lessons for how investors should approach the AI boom. Specifically, he sees echoes of 1929 and 2000 in the current situation, and is urging investors to approach AI stocks with caution. Here is what he said and why investors may want to heed his advice.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
First of all, investors should remember that Dalio has stepped down from Bridgewater. Thus, the fund's investments in AI stocks like ServiceNow and Nutanix were likely made without his input.
Given what he has said recently, he may even disagree with those purchases. When Dalio appeared on the podcast The Diary of a CEO in August, he said that AI shows "classic signs" of a bubble.
#dalio #signal #flashing #likely


2 months ago
On September 16, Evolution Petroleum Corporation (NYSEAMERICAN:EPM) held its fiscal fourth-quarter and full-year 2026 earnings call, and the numbers told a story of a company climbing out of a rough patch. Revenue jumped 20% sequentially to $24.2 million as oil prices realized before hedge settlements shot up 49% year over year to $90.74 a barrel. Adjusted EBITDA more than doubled to $6.5 million. After a bruising third quarter, the fourth quarter finally looked like the recovery management had promised investors back in May.
The fourth-quarter turnaround wasn't just about crude. NGL prices realized $32.49 a barrel, up 27% year over year, and because Evolution leaves its NGL production entirely unhedged, every dollar of that gain flowed straight through. That combination of higher liquids pricing, growing production, and the roll-off of a prior-period transportation adjustment at the Delhi Field pushed operating cash flow to $6.8 million in the quarter, nearly double the $3.5 million generated in the third quarter.
Behind the quarterly numbers sits a longer-term shift in how Evolution makes money. The company closed a roughly $16 million acquisition of mineral and royalty acreage in the Permian's Midland Basin after the fiscal year ended, adding about 3,420 net royalty acres and more than 200 barrels of oil equivalent per day of current production, all without Evolution spending a dime on development. That mirrors what's already happening in the SCOOP/STACK play, where fourth-quarter production climbed 14% year over year to 1,275 BOE per day while unit operating costs fell to $10.33 a barrel. Evolution also replaced more than 100% of the 2.6 million barrels of oil equivalent it produced during the year, ending fiscal 2026 with 27.2 million barrels of proved reserves, an outcome that matters directly to a dividend now in its 52nd consecutive quarter.
Not every part of the business bounced back. Average daily production fell 4% year over year to 6,901 barrels of oil equivalent per day, largely because the flush production from new Chaveroo wells that boosted last year's fourth quarter has since tapered off. Natural gas pricing remained the softest spot in the portfolio, especially at the Jonah Field, where CEO Kelly Loyd said "regional differentials have weighed on realizations" even as broader demand for gas keeps growing. CFO Ryan Stash noted that stronger oil and NGL results helped offset "continued weakness in natural gas realizations, particularly at Jonah."
#barrel
The fourth-quarter turnaround wasn't just about crude. NGL prices realized $32.49 a barrel, up 27% year over year, and because Evolution leaves its NGL production entirely unhedged, every dollar of that gain flowed straight through. That combination of higher liquids pricing, growing production, and the roll-off of a prior-period transportation adjustment at the Delhi Field pushed operating cash flow to $6.8 million in the quarter, nearly double the $3.5 million generated in the third quarter.
Behind the quarterly numbers sits a longer-term shift in how Evolution makes money. The company closed a roughly $16 million acquisition of mineral and royalty acreage in the Permian's Midland Basin after the fiscal year ended, adding about 3,420 net royalty acres and more than 200 barrels of oil equivalent per day of current production, all without Evolution spending a dime on development. That mirrors what's already happening in the SCOOP/STACK play, where fourth-quarter production climbed 14% year over year to 1,275 BOE per day while unit operating costs fell to $10.33 a barrel. Evolution also replaced more than 100% of the 2.6 million barrels of oil equivalent it produced during the year, ending fiscal 2026 with 27.2 million barrels of proved reserves, an outcome that matters directly to a dividend now in its 52nd consecutive quarter.
Not every part of the business bounced back. Average daily production fell 4% year over year to 6,901 barrels of oil equivalent per day, largely because the flush production from new Chaveroo wells that boosted last year's fourth quarter has since tapered off. Natural gas pricing remained the softest spot in the portfolio, especially at the Jonah Field, where CEO Kelly Loyd said "regional differentials have weighed on realizations" even as broader demand for gas keeps growing. CFO Ryan Stash noted that stronger oil and NGL results helped offset "continued weakness in natural gas realizations, particularly at Jonah."
#barrel

2 months ago
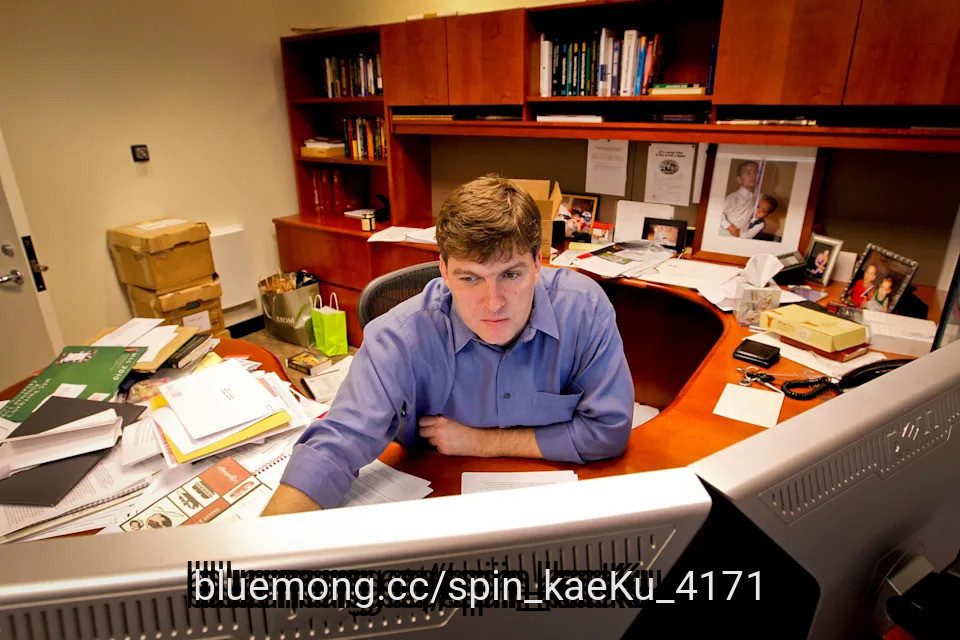
Michael Burry is back to short selling.
The investor who bet against the U.S. housing market to become one of Wall Street's most renowned contrarians will serve as a senior adviser to Minerva Investment Management as the business prepares to establish a short-biased investment vehicle.
The decision comes less than a year after Burry liquidated Scion ******* et Management, the hedge fund where he handled his ******* ets.
Scion's regulatory registration was terminated in November 2025, Reuters confirmed. The firm had managed about $155 million as of March of that year.
Later, Burry moved most of his public market ******* ysis inside his paid "Cassandra Unchained" newsletter.
#michael #wall
The investor who bet against the U.S. housing market to become one of Wall Street's most renowned contrarians will serve as a senior adviser to Minerva Investment Management as the business prepares to establish a short-biased investment vehicle.
The decision comes less than a year after Burry liquidated Scion ******* et Management, the hedge fund where he handled his ******* ets.
Scion's regulatory registration was terminated in November 2025, Reuters confirmed. The firm had managed about $155 million as of March of that year.
Later, Burry moved most of his public market ******* ysis inside his paid "Cassandra Unchained" newsletter.
#michael #wall
2 months ago
Space Exploration Technologies Corp. (NASDAQ:SPCX) is increasingly confident it can reach a $100 billion annual revenue run rate by year-end. The company's CFO said there is now "even more conviction" around the target. A new AI hosting agreement worth $13 billion on an annualized basis adds significant support to that outlook and reflects how quickly ***** eX's compute business is scaling. But the financial picture behind that growth is less straightforward. The same AI division that management is relying on to help reach that target posted a $1.3 billion loss in the latest quarter alone. The loss wiped out what would have otherwise been a profitable quarter, while the company generated roughly negative $25 billion in free cash flow during the first half of 2026.
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly
CFO Bret Johnsen said ***** eX has "even more conviction" that it can reach a $100 billion annual revenue run rate. The outlook is supported by a newly signed AI hosting agreement worth $1.11 billion per month beginning in December, or roughly $13 billion on an annualized basis. The company plans to end the year with a little over 2 gigawatts of terrestrial AI-computing capacity and scale to between 5 and 10 gigawatts in 2027. Orbital computing remains a longer-term option for overcoming power constraints. Its current agreements include a $6.7 billion cloud-services contract that is scheduled to ramp up in October. Existing arrangements with Google and Anthropic are worth more than $2 billion per month combined. Reaching the $100 billion target would require monthly revenue to more than triple from second-quarter's pace.
SpaceX's rocket and Starlink businesses generated roughly $1.1 billion in combined operating income in the second quarter. But the AI division's $1.3 billion loss more than wiped out that profit. The company also generated roughly negative $25 billion in free cash flow during the first half of 2026. The stock declined more than 5% after the second-quarter results despite a revenue beat.
The AI contract pipeline is clearly expanding and gaining momentum. However, the $100 billion target is a revenue run-rate measure rather than a profitability target. At the same time, the division driving this expansion remains the company's largest contributor to both both operating losses and capital spending, making the growth opportunity financially costly for now.
SpaceX had 119 hedge funds among its institutional holders at the end of the second quarter of fiscal 2026. Meanwhile, short interest stood at just 2.76% of float as of August 31, 2026. The ownership and the short interest figures show that institutional sentiment remains broadly constructive and toward the company's long-term outlook.
#roughly

2 months ago
Fenimore ***** et Management, an investment management company, released its Q2 2026 investor letter. The letter can be downloaded here. U.S. equity markets saw broad gains in Q2, driven by strong corporate earnings, economic resilience, and enthusiasm for artificial intelligence (AI). Major indices reached all-time highs, though the energy sector declined. Continued earnings growth, especially among AI-related investments, supported the rally. Technology, particularly semiconductors, led performance as demand for AI infrastructure surged. Despite macroeconomic uncertainties and interest rate influences, Fenimore remains committed to investing in high-quality businesses. The Fenimore Small Cap Strategy returned 9.51% in the quarter, lagging the Russell 2000 Index's 21.49% gain. The underperformance was largely driven by avoiding lower-quality tech stocks linked to data center expansions. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Fenimore ***** et Management highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On September 17, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $40.03 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -8.32%, and its shares lost 25.53% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $10.15 billion.
Fenimore ***** et Management stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"We initiated a position in Ryan Specialty Holdings, Inc. (NYSE:RYAN), which we had previously owned after its initial public offering. The insurance industry has seen softness in rates. While RYAN's model differs from traditional retail brokerage, the company released results citing a volatile environment which led to a decrease in their earnings outlook for the year. We're encouraged by the business's long-term prospects and, in our opinion, its legendary leader Pat Ryan. He is also purchasing shares of RYAN's stock during this weakness."
Ryan Specialty Holdings, Inc. (NYSE:RYAN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 32 hedge fund portfolios held Ryan Specialty Holdings, Inc. (NYSE:RYAN) at the end of the second quarter, compared to 35 in the previous quarter. While we acknowledge the potential of Ryan Specialty Holdings, Inc. (NYSE:RYAN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
In its second-quarter 2026 investor letter, Fenimore ***** et Management highlighted Ryan Specialty Holdings, Inc. (NYSE:RYAN). Ryan Specialty Holdings, Inc. (NYSE:RYAN) is a specialty insurance services company that provides distribution, underwriting, product development, administration, and risk management services. On September 17, 2026, Ryan Specialty Holdings, Inc. (NYSE:RYAN) closed at $40.03 per share. The one-month return of Ryan Specialty Holdings, Inc. (NYSE:RYAN) was -8.32%, and its shares lost 25.53% over the past 52 weeks. Ryan Specialty Holdings, Inc. (NYSE:RYAN) has a market capitalization of $10.15 billion.
Fenimore ***** et Management stated the following regarding Ryan Specialty Holdings, Inc. (NYSE:RYAN) in its Q2 2026 investor letter:
"We initiated a position in Ryan Specialty Holdings, Inc. (NYSE:RYAN), which we had previously owned after its initial public offering. The insurance industry has seen softness in rates. While RYAN's model differs from traditional retail brokerage, the company released results citing a volatile environment which led to a decrease in their earnings outlook for the year. We're encouraged by the business's long-term prospects and, in our opinion, its legendary leader Pat Ryan. He is also purchasing shares of RYAN's stock during this weakness."
Ryan Specialty Holdings, Inc. (NYSE:RYAN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 32 hedge fund portfolios held Ryan Specialty Holdings, Inc. (NYSE:RYAN) at the end of the second quarter, compared to 35 in the previous quarter. While we acknowledge the potential of Ryan Specialty Holdings, Inc. (NYSE:RYAN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Sandisk Corporation (NASDAQ:SNDK) as a newly added position. Sandisk Corporation (NASDAQ:SNDK) develops, manufactures, and sells data storage devices and solutions using NAND flash technology in the United States and internationally. On September 15, 2026, Sandisk Corporation (NASDAQ:SNDK) closed at $1,530.90 per share. Over the past month, Sandisk Corporation (NASDAQ:SNDK) declined 2.32%, but its shares are up 1,530.74% over the past year. Sandisk Corporation (NASDAQ:SNDK) has a market capitalization of $224.15 billion, and its stock has traded within a 52-week range of $90.22 to $2,354.39.
Parnassus Growth Equity Fund stated the following regarding Sandisk Corporation (NASDAQ:SNDK) in its Q2 2026 investor letter:
"Other positions added during the quarter included Sandisk Corporation (NASDAQ:SNDK), a leader in flash memory solutions; Comfort Systems, a mechanical, electrical and plumbing contractor. Sandisk makes NAND flash memory, which is seeing a surge in demand from data centers and AI workloads. While NAND remains cyclical, we believe the combination of accelerating AI-driven storage demand and constrained supply provides an attractive opportunity to participate in the current upcycle."
Sandisk Corporation (NASDAQ:SNDK) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 128 hedge fund portfolios held Sandisk Corporation (NASDAQ:SNDK) at the end of the second quarter which was 114 in the previous quarter. While we acknowledge the potential of Sandisk Corporation (NASDAQ:SNDK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre

2 months ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global


2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Brown & Brown, Inc. (NYSE:BRO). Brown & Brown, Inc. (NYSE:BRO) is a leading insurance brokerage firm operating through Retail and Specialty Distribution segments. On September 15, 2026, Brown & Brown, Inc. (NYSE:BRO) closed at $67.23 per share, reflecting a market capitalization of $22.5 billion. Brown & Brown, Inc. (NYSE:BRO) posted a one‑month return of -6.29%, while its shares lost 27.35% over the past 52 weeks.
Parnassus Growth Equity Fund stated the following regarding Brown & Brown, Inc. (NYSE:BRO) in its Q2 2026 investor letter:
"We sold Brown & Brown Inc. during the quarter. Brown & Brown, Inc. (NYSE:BRO) remains a high-quality business, but we see rising near term risks as the company navigates an industry downturn, integrates a large acquisition and works to close an AI capability gap versus larger peers."
Brown & Brown, Inc. (NYSE:BRO) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 44 hedge fund portfolios held Brown & Brown, Inc. (NYSE:BRO) at the end of the second quarter, compared to 41 in the previous quarter. While we acknowledge the potential of Brown & Brown, Inc. (NYSE:BRO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #letter
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Insmed Incorporated (NASDAQ:INSM). The Fund exited its position in Insmed Incorporated (NASDAQ:INSM), a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases, during the quarter. On September 15, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $119.92 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) declined 7.49%, but its shares are down 16.51% over the past year. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $26.19 billion, and its stock has traded within a 52-week range of $90.39 and $212.75.
Parnassus Growth Equity Fund stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Insmed Incorporated (NASDAQ:INSM)shares fell after sales of the biopharmaceutical company's new lung drug Brinsupri fell short of ****** ysts' expectations. We exited the position during the quarter. Insmed's thesis had largely played out following positive TPIP data and upward revisions to Brinsupri sales. We redeployed capital to Twist Bioscience, which offers a longer runway for growth."
Insmed Incorporated (NASDAQ:INSM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 88 hedge fund portfolios held Insmed Incorporated (NASDAQ:INSM) at the end of the second quarter, compared to 67 in the previous quarter. While we acknowledge the potential of Insmed Incorporated (NASDAQ:INSM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #parnassus
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Lumentum Holdings Inc. (NASDAQ:LITE). Lumentum Holdings Inc. (NASDAQ:LITE) is a leading technology company that manufactures and sells optical and photonic products. On September 15, 2026, Lumentum Holdings Inc. closed at $838.96 per share. Over the past month, Lumentum Holdings Inc. gained 6.57%, and its shares are up 439.98% over the past year. Lumentum Holdings Inc. has a market capitalization of $75.25 billion, and its stock has traded within a 52-week range of $144.52 to $1,085.68.
Parnassus Growth Equity Fund stated the following regarding Lumentum Holdings Inc. (NASDAQ:LITE) in its Q2 2026 investor letter:
"Lumentum Holdings Inc. (NASDAQ:LITE) offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems. Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms."
Lumentum Holdings Inc. (NASDAQ:LITE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 111 hedge fund portfolios held Lumentum Holdings Inc. (NASDAQ:LITE) at the end of the second quarter, down from 123 in the previous quarter. While we acknowledge the potential of Lumentum Holdings Inc. (NASDAQ:LITE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#Growth #fund #quarter #parnassus
2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Charter Communications, Inc. (NASDAQ:CHTR). Charter Communications, Inc. (NASDAQ:CHTR) is a US-based broadband connectivity company. On September 15, 2026, Charter Communications, Inc. closed at $141.20 per share. Over the past month, Charter Communications, Inc. declined 7.39% and its shares lost 47.32% over the past 52 weeks. Charter Communications, Inc. has a market capitalization of $24.73 billion and its stock has traded within a 52-week range of $111.55 and $285.82.
Weitz Multi Cap Equity Fund stated the following regarding Charter Communications, Inc. (NASDAQ:CHTR) in its Q2 2026 investor letter:
"Charter Communications, Inc. (NASDAQ:CHTR) (the principal **** et of portfolio holding Liberty Broadband) shares were weak as investors remain laser-focused on the impact of competition in Charter's core broadband market. Although the stock price has not yet improved, we remain constructive and believe Charter's growing wireless business, forecasted reduction in investment spending and impending combination with **** provide reasons for optimism."
Charter Communications, Inc. (NASDAQ:CHTR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 63 hedge fund portfolios held Charter Communications, Inc. (NASDAQ:CHTR) at the end of the second quarter which was 48 in the previous quarter. While we acknowledge the potential of Charter Communications, Inc. (NASDAQ:CHTR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#communications #quarter #investor

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted CoStar Group, Inc. (NASDAQ:CSGP). CoStar Group, Inc. (NASDAQ:CSGP), an information, ****** ytics, and online marketplace services provider for commercial and residential property markets. On September 15, 2026, CoStar Group, Inc. (NASDAQ:CSGP) closed at $31.56 per share, reflecting a market capitalization of $12.79 billion. CoStar Group, Inc. (NASDAQ:CSGP) posted a one-month return of -6.43%, while its shares lost 64.08% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding CoStar Group, Inc. (NASDAQ:CSGP) in its Q2 2026 investor letter:
"CoStar Group, Inc.'s (NASDAQ:CSGP) management prevailed in its struggle with an activist investor and remains undeterred in its residential real estate strategy. Investors are clearly skeptical of management's plan, but at current prices, we believe the punishment has gone too far."
CoStar Group, Inc. (NASDAQ:CSGP) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 58 hedge fund portfolios held CoStar Group, Inc. (NASDAQ:CSGP) at the end of the second quarter, down from 62 in the previous quarter. While we acknowledge the potential of CoStar Group, Inc. (NASDAQ:CSGP) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#group #NASDAQ #fund #weitz

2 months ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Netflix, Inc. (NASDAQ:NFLX) as a newly added postion. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On September 15, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $77.90 per share, reflecting a market capitalization of $324.37 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of -2.89%, while its shares lost 36.59% over the past 52 weeks.
Weitz Multi Cap Equity Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"We initiated two new positions during the second quarter. Most will be familiar with global streaming giant, Netflix, Inc. (NASDAQ:NFLX). The company made headlines as it tried to acquire Warner Bros. from Warner Bros. Discovery before ultimately walking away from a bidding war for the company. Some investors feared its bid signaled stagnation in its streaming business. At the time of this writing, the 2026 FIFA World Cup is also captivating audiences and draining attention and engagement from Netflix's service. Despite these near-term perception headwinds, we are optimistic that Netflix's introduction of an ad-supported tier is a savvy strategy to extend its growth runway: Netflix will not only participate in the large, multi-billion-dollar global advertising market, but a lower-price ad-tier broadens its potential customer base while simultaneously enhancing the pricing power of its premium, ad free tier."
Netflix, Inc. (NASDAQ:NFLX) ranks 13 on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 121 hedge fund portfolios held Netflix, Inc. (NASDAQ:NFLX) at the end of the second quarter, down from 144 in the previous quarter. While we acknowledge the potential of Netflix, Inc. (NASDAQ:NFLX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#second