
9 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus

10 days ago
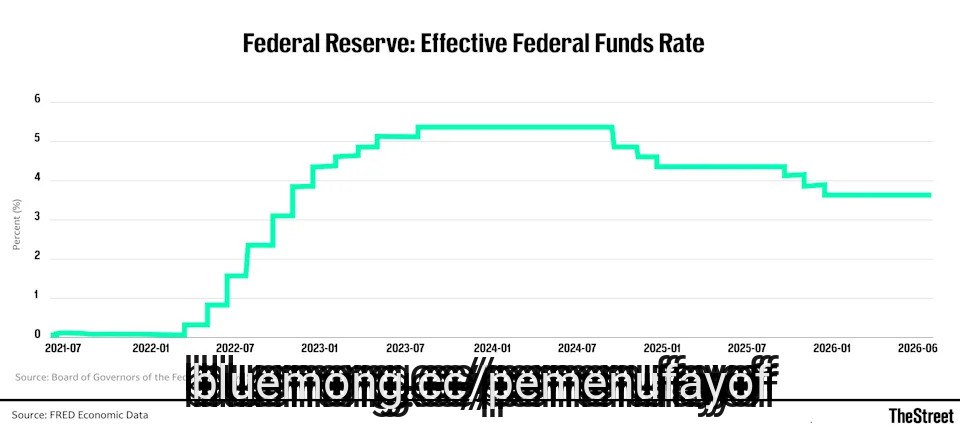
Wall Street is looking beyond this week's Federal Reserve interest-rate decision to a potentially bigger market-moving signal: the Fed's latest dot plot and what it says about the path for rates after an expected quarter-point hike.
Fed Chair Kevin Warsh faces a pivotal test of his inflation-fighting credibility as policymakers confront hotter prices, rising energy costs, and mounting bets on further rate increases.
A hike on Sept. 16 would be the Fed's first increase since July 2023, but investors may care even more what the dot plot signals for additional hikes and how aggressively Warsh intends to push rates to bring inflation back to the central bank's 2% goal.
Note that a rate hike is certain to draw highly vocal criticism from President Donald Trump and his allies, who have been campaigning for a drastic slash to 1% or less for years.
Remember, the Fed doesn't traditionally pull the "one and done" game when it comes to increasing the benchmark short-term interest rate. The Federal Open Market Committee reset of the Federal Funds Rate usually lands in a package of at least two, if not more.
#rate
Fed Chair Kevin Warsh faces a pivotal test of his inflation-fighting credibility as policymakers confront hotter prices, rising energy costs, and mounting bets on further rate increases.
A hike on Sept. 16 would be the Fed's first increase since July 2023, but investors may care even more what the dot plot signals for additional hikes and how aggressively Warsh intends to push rates to bring inflation back to the central bank's 2% goal.
Note that a rate hike is certain to draw highly vocal criticism from President Donald Trump and his allies, who have been campaigning for a drastic slash to 1% or less for years.
Remember, the Fed doesn't traditionally pull the "one and done" game when it comes to increasing the benchmark short-term interest rate. The Federal Open Market Committee reset of the Federal Funds Rate usually lands in a package of at least two, if not more.
#rate
12 days ago
Strategy (NASDAQ: $MSTR) has again left its Bitcoin (CRYPTO: $BTC) holdings unchanged as it focuses on repurchasing its preferred stock (NASDAQ: $STRC).
The serial cryptocurrency acquirer bought back 1.42 million of its preferred shares over the past week at a cost of $139.3 million U.S.
A regulatory filing with the U.S. Securities and Exchange Commission (SEC) shows that Strategy funded the stock repurchases through its cash reserve.
As of Sept. 14, the balance on the company's cash reserve stood at $6.4 billion U.S.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#preferred
The serial cryptocurrency acquirer bought back 1.42 million of its preferred shares over the past week at a cost of $139.3 million U.S.
A regulatory filing with the U.S. Securities and Exchange Commission (SEC) shows that Strategy funded the stock repurchases through its cash reserve.
As of Sept. 14, the balance on the company's cash reserve stood at $6.4 billion U.S.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#preferred

15 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributed record-breaking results to a 'stellar' market environment where geopolitical tensions, specifically the closure of the Strait of Hormuz, have significantly increased ton-mile dislocation.
The company is executing a massive $3.1 billion fleet renewal program involving 26 newbuildings, with management noting that these ****** ets have already appreciated by approximately 30% since contracting.
Strategic positioning focuses on a 'balanced' model, using fixed-rate charters to cover all-in break-even costs while utilizing spot and profit-sharing contracts to capture market upside.
Management highlighted an unprecedented appetite from major oil companies, who are now seeking long-term charters of up to 7 years for vessels aged 10 years or younger.
#management #years #hormuz
Management attributed record-breaking results to a 'stellar' market environment where geopolitical tensions, specifically the closure of the Strait of Hormuz, have significantly increased ton-mile dislocation.
The company is executing a massive $3.1 billion fleet renewal program involving 26 newbuildings, with management noting that these ****** ets have already appreciated by approximately 30% since contracting.
Strategic positioning focuses on a 'balanced' model, using fixed-rate charters to cover all-in break-even costs while utilizing spot and profit-sharing contracts to capture market upside.
Management highlighted an unprecedented appetite from major oil companies, who are now seeking long-term charters of up to 7 years for vessels aged 10 years or younger.
#management #years #hormuz
16 days ago
India's refineries have been running at 105% to 108% capacity utilization in the past six months as demand for diesel soars and international fuel markets tighten amid the ongoing Middle East crisis.
Refinery capacity utilization in the world's third-largest crude oil importer has been between 105% and 108% since the war began, a senior executive at Mangalore Refinery and Petrochemicals Limited (MRPL) said at the APPEC petroleum conference in Singapore on Wednesday.
"Most of our refiners are complex, can take a wide variety of crude from an API range of something like 16 to 45 or 48," Nandakumar Pillai, a company director at MRPL, said at the event, as carried by Reuters.
MRPL operates a refinery with the capacity to process 300,000 barrels per day (bpd) on the coast of India's southern state of Karnataka. The refinery has a versatile design with complex secondary processing units and high flexibility to process crudes of various API, delivering a variety of quality products, the refiner says.
MRPL will continue to run its refinery at above 100% until March 2027, Pillai told Reuters on the sidelines of the conference.
#mrpl #utilization #crude
Refinery capacity utilization in the world's third-largest crude oil importer has been between 105% and 108% since the war began, a senior executive at Mangalore Refinery and Petrochemicals Limited (MRPL) said at the APPEC petroleum conference in Singapore on Wednesday.
"Most of our refiners are complex, can take a wide variety of crude from an API range of something like 16 to 45 or 48," Nandakumar Pillai, a company director at MRPL, said at the event, as carried by Reuters.
MRPL operates a refinery with the capacity to process 300,000 barrels per day (bpd) on the coast of India's southern state of Karnataka. The refinery has a versatile design with complex secondary processing units and high flexibility to process crudes of various API, delivering a variety of quality products, the refiner says.
MRPL will continue to run its refinery at above 100% until March 2027, Pillai told Reuters on the sidelines of the conference.
#mrpl #utilization #crude
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
22 days ago
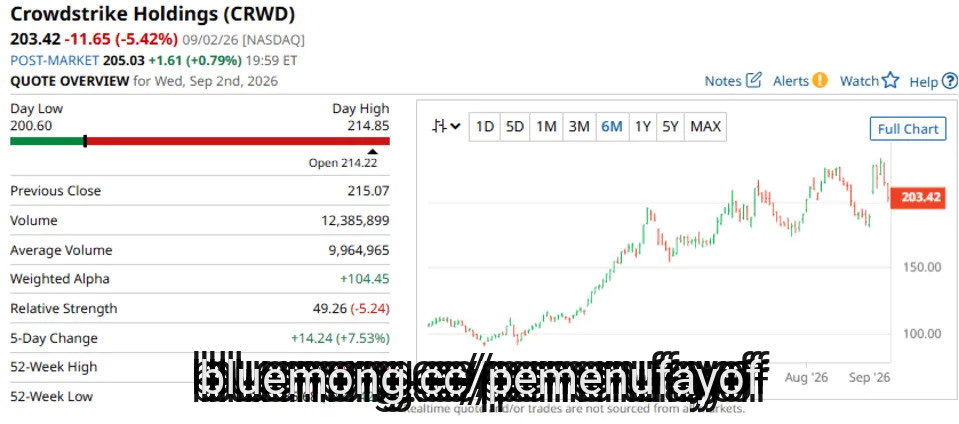
CrowdStrike (CRWD) is holding nicely above rising 50 and 200-day moving averages and is a highly rated stock among many ***** ysts.
Today, we are looking at an unbalanced iron condor, with a slightly bullish bias.
Unusually Heavy Volume in Snowflake Call Options Ahead of Earnings Today
Home Depot Bear Put Spread Could Return 181% in 45 Days
If You Have Some 'Silly' Money, United Microelectronics (UMC) Stock Is Worth a Look
#snowflake
Today, we are looking at an unbalanced iron condor, with a slightly bullish bias.
Unusually Heavy Volume in Snowflake Call Options Ahead of Earnings Today
Home Depot Bear Put Spread Could Return 181% in 45 Days
If You Have Some 'Silly' Money, United Microelectronics (UMC) Stock Is Worth a Look
#snowflake
23 days ago
By
Sept. 2, 2026 11:32 am ET
Listen
(1 min)
Here’s a surprise about the countries at the center of the bond-market selloff: They’re all borrowing far less than Uncle Sam.
#selloff
Sept. 2, 2026 11:32 am ET
Listen
(1 min)
Here’s a surprise about the countries at the center of the bond-market selloff: They’re all borrowing far less than Uncle Sam.
#selloff
23 days ago
Data centers are a hot-button issue in the U.S. right now. In the stock market, major tech companies are building artificial intelligence (AI) infrastructure to meet the massive demand for generative and agentic AI applications. But on Main Street, there's growing resistance from communities who don't want to see data centers in their areas, and are worried about the ever-growing power demand.
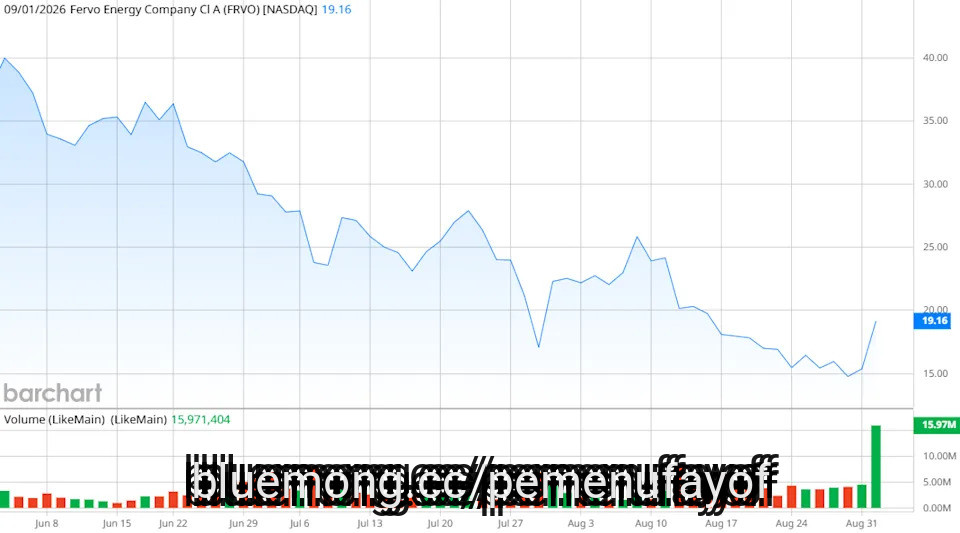
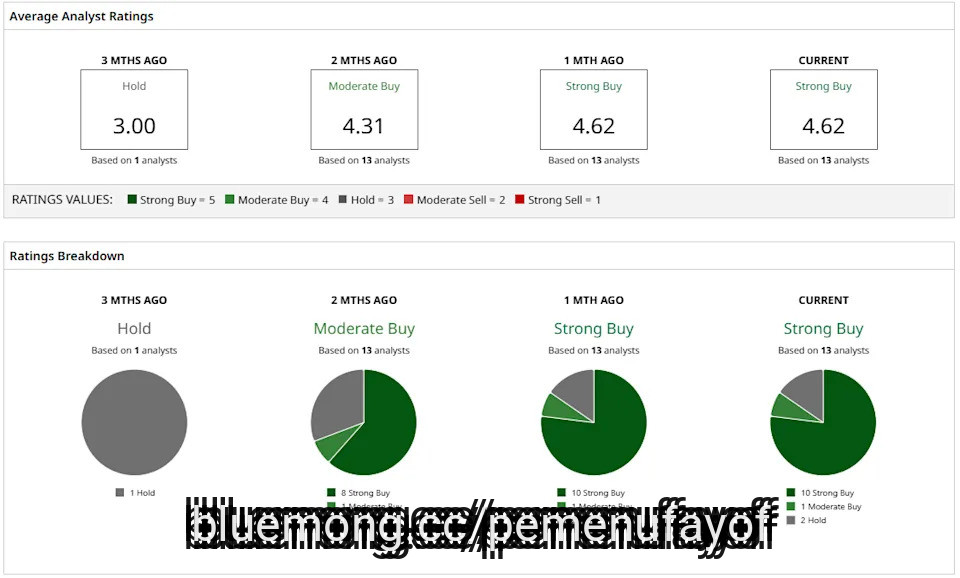
That's why the new deal announced today by Fervo Energy (FRVO) and Alphabet (GOOGL) is so interesting. Fervo just signed a 396-megawatt power purchase agreement with Google to supply carbon-free electricity for a potential data center in Utah. The agreement is the largest enhanced geothermal power purchase agreement on record.
I've Been Taking a Beating on This AI Energy Stock. Here's Where I'm Looking to Add More Shares – and Why.
As US Bond Selloff Accelerates, Treasury Secretary Scott Bessent Says a Stronger Yen is Coming
August's Top Commodity Performers and Underperformers
#Stock #centers #purchase
That's why the new deal announced today by Fervo Energy (FRVO) and Alphabet (GOOGL) is so interesting. Fervo just signed a 396-megawatt power purchase agreement with Google to supply carbon-free electricity for a potential data center in Utah. The agreement is the largest enhanced geothermal power purchase agreement on record.
I've Been Taking a Beating on This AI Energy Stock. Here's Where I'm Looking to Add More Shares – and Why.
As US Bond Selloff Accelerates, Treasury Secretary Scott Bessent Says a Stronger Yen is Coming
August's Top Commodity Performers and Underperformers
#Stock #centers #purchase

24 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: The Chase Sapphire Preferred is one of the best cards for travelers because it earns Chase Ultimate Rewards points. These can be used for various redemptions, including flights or transfers to a Chase transfer partner. The Sapphire Preferred provides up to a 50% bonus on eligible travel redemptions made through Chase Travel℠.
Read our full Chase Sapphire Preferred review
Why we like it: The Southwest Rapid Rewards Plus makes sense if you want to earn Southwest points on everyday purchases and enjoy a few additional benefits when flying Southwest. That includes 3,000 anniversary points and a 10,000 Companion Pass qualifying points boost.
Read our full Southwest Rapid Rewards Plus review
#chase #rewards #plus
Why we like it: The Chase Sapphire Preferred is one of the best cards for travelers because it earns Chase Ultimate Rewards points. These can be used for various redemptions, including flights or transfers to a Chase transfer partner. The Sapphire Preferred provides up to a 50% bonus on eligible travel redemptions made through Chase Travel℠.
Read our full Chase Sapphire Preferred review
Why we like it: The Southwest Rapid Rewards Plus makes sense if you want to earn Southwest points on everyday purchases and enjoy a few additional benefits when flying Southwest. That includes 3,000 anniversary points and a 10,000 Companion Pass qualifying points boost.
Read our full Southwest Rapid Rewards Plus review
#chase #rewards #plus


29 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you've spent any time on social media lately, you've probably come across trends such as "looksmaxxing," "sleepmaxxing," and even "proteinmaxxing."
The "-maxxing" trend is basically internet shorthand for taking something in your life and trying to optimize it as much as possible. And users are now adapting the concept for their financial lives.
If you've ever switched savings accounts for a better APY or hunted down a promo code before hitting "buy," you're already "moneymaxxing" to some degree. But is this just another fleeting internet trend, or is there real value in moneymaxxing?
Moneymaxxing is a social media-driven trend centered on optimizing as many aspects of your finances as possible. This can include moves such as moving cash to a high-yield savings account, stacking discounts and cash-back offers, negotiating bills, or taking advantage of bank account bonuses.
#internet
If you've spent any time on social media lately, you've probably come across trends such as "looksmaxxing," "sleepmaxxing," and even "proteinmaxxing."
The "-maxxing" trend is basically internet shorthand for taking something in your life and trying to optimize it as much as possible. And users are now adapting the concept for their financial lives.
If you've ever switched savings accounts for a better APY or hunted down a promo code before hitting "buy," you're already "moneymaxxing" to some degree. But is this just another fleeting internet trend, or is there real value in moneymaxxing?
Moneymaxxing is a social media-driven trend centered on optimizing as many aspects of your finances as possible. This can include moves such as moving cash to a high-yield savings account, stacking discounts and cash-back offers, negotiating bills, or taking advantage of bank account bonuses.
#internet


1 month ago
Do you ever wish you could buy stakes in companies before they go public? It's not impossible, although it can be difficult, and somewhat convoluted. Most of these few offerings still aren't exactly suited for smaller investors.
Hedge fund manager Bill Ackman plans on changing this, and soon.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman is the chief stock picker behind Pershing Square Capital Management, L.P. (aimed at larger, accredited investors) and Pershing Square USA (NYSE: PSUS) (for smaller retail investors), which holds a hand-picked portfolio of publicly traded equities. Ackman also runs Pershing Square Inc. (NYSE: PS), an alternative ****** et management firm, while its primary investment vehicle is Pershing Square Holdings (OTC: PSHZF).
Ackman is working on a new investment vehicle for smaller retail traders that will own private stakes in pre-IPO companies. He spoke about it earlier this month.
#NVIDIA #signal
Hedge fund manager Bill Ackman plans on changing this, and soon.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman is the chief stock picker behind Pershing Square Capital Management, L.P. (aimed at larger, accredited investors) and Pershing Square USA (NYSE: PSUS) (for smaller retail investors), which holds a hand-picked portfolio of publicly traded equities. Ackman also runs Pershing Square Inc. (NYSE: PS), an alternative ****** et management firm, while its primary investment vehicle is Pershing Square Holdings (OTC: PSHZF).
Ackman is working on a new investment vehicle for smaller retail traders that will own private stakes in pre-IPO companies. He spoke about it earlier this month.
#NVIDIA #signal

1 month ago
Broadcom's AI orders exceeded $30B this quarter while Micron secured ~$100B in contracted memory revenue through five-year take-or-pay deals.
Micron's HBM4 is ramping twice as fast as its predecessor, with DRAM prices jumping 60% sequentially and gross margins hitting a record 84.9%.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Broadcom (NASDAQ:AVGO) and Micron Technology (NASDAQ:MU) delivered blockbuster quarters mapping onto the shift from AI training to inference and agentic workloads. Broadcom sells custom accelerators and networking silicon that stitch hyperscaler clusters together. Micron supplies the high-bandwidth memory those clusters need. Two different business models. One shared tailwind.
Broadcom's fiscal Q2 revenue hit $22.2 billion, up 48% year-on-year, with AI semiconductor revenue of $10.8 billion, up 143%. Hock Tan told investors "networking represented almost 40% of our Q2 AI revenue" and guided Q3 AI silicon to $16 billion, up over 200% year-on-year. Bookings were the headline: AI semiconductor orders exceeded $30 billion in the quarter, with programs now stretching to Google TPUs, Meta MTIA XPUs, OpenAI silicon, and Anthropic compute capacity.
#billion
Micron's HBM4 is ramping twice as fast as its predecessor, with DRAM prices jumping 60% sequentially and gross margins hitting a record 84.9%.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Broadcom (NASDAQ:AVGO) and Micron Technology (NASDAQ:MU) delivered blockbuster quarters mapping onto the shift from AI training to inference and agentic workloads. Broadcom sells custom accelerators and networking silicon that stitch hyperscaler clusters together. Micron supplies the high-bandwidth memory those clusters need. Two different business models. One shared tailwind.
Broadcom's fiscal Q2 revenue hit $22.2 billion, up 48% year-on-year, with AI semiconductor revenue of $10.8 billion, up 143%. Hock Tan told investors "networking represented almost 40% of our Q2 AI revenue" and guided Q3 AI silicon to $16 billion, up over 200% year-on-year. Bookings were the headline: AI semiconductor orders exceeded $30 billion in the quarter, with programs now stretching to Google TPUs, Meta MTIA XPUs, OpenAI silicon, and Anthropic compute capacity.
#billion

1 month ago
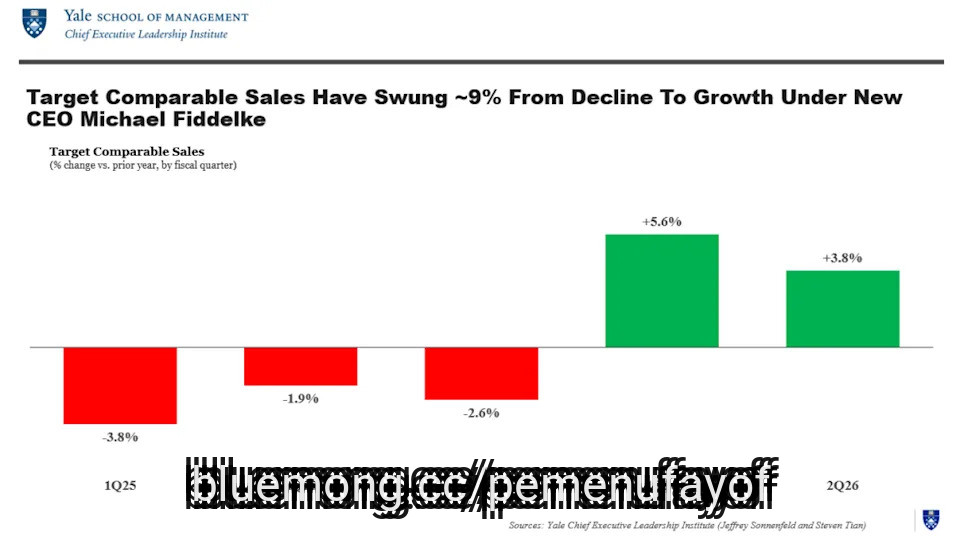
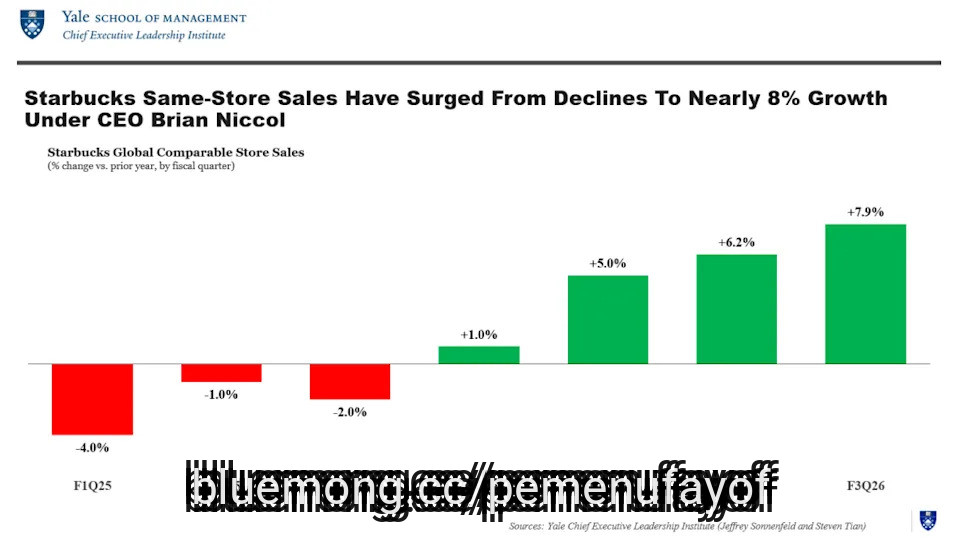
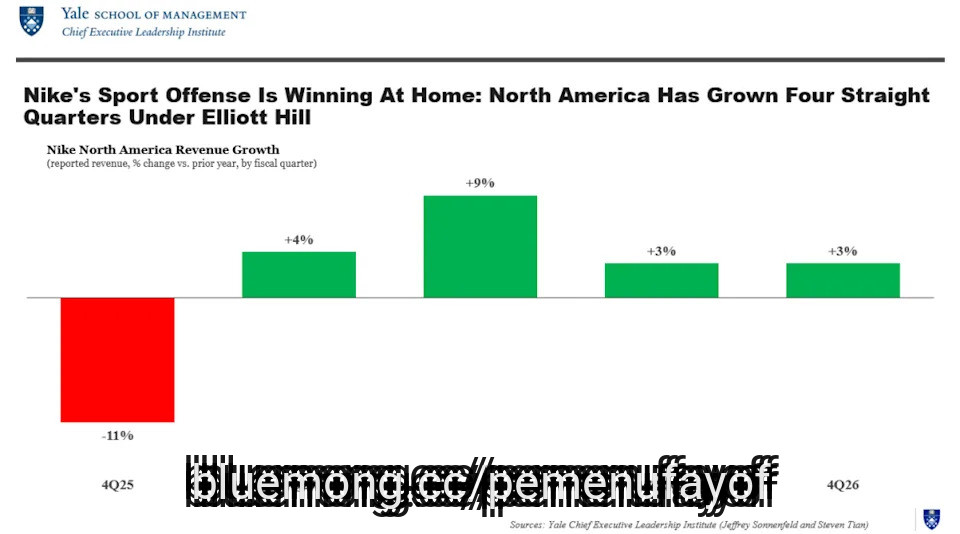
What did Target, Starbucks, and Nike have in common barely a year ago? All three consumer icons had freshly announced new CEOs, which were wrongly greeted with hasty skepticism from ***** ysts. Target's Michael Fiddelke was scoffed at as an uninspired insider; Nike's Elliott Hill was underestimated as a nostalgia hire, unable to stem Nike's loss of market share, while questions abounded over whether Brian Niccol could actually turn around Starbucks amidst pervasive in-store service struggles, despite his sterling record at Chipotle.
We saw it differently. At the time of their appointments, we vocally and presciently touted all three new CEOs as the right person for the job at the right time, while other ***** ysts rolled their eyes. Unlike the frequent, sometime successful model of the messianic hiring of industry outsiders as turnaround tians, these new CEOs hit the ground running as each had decades of experience in their sectors with glowing track records, priceless relationships, and balanced expertise across marketing, finance, strategy, and operations,.
Furthermore, we were the first to confidently predict the certainty of their success, even knowing that it would take some time to reposition their enterprises and for their new leadership to gain traction. Now the receipts are in, showing striking progress in all three cases, with each already well on their way to cementing their reputations as the architects of some of the most remarkable corporate turnarounds of our era.
When Michael Fiddelke, a Target lifer who had risen up the ranks from a lowly intern over two decades ago, was named CEO, cynics sneered that the board had chosen entrenched groupthink over fresh blood. We argued precisely the opposite—that the data overwhelmingly shows internal candidates outperform splashy external saviors, with insider CEOs appointed over the prior year delivering roughly 15% annualized shareholder returns while external hires averaged negative 9%. New brooms sweep clean, but the old broom knows the corners. Furthermore, we argued that Fiddelke was uniquely positioned to build on the many successes of his widely admired predecessor, Brian Cornell, despite simultaneous urgent challenges.
This week brought resounding vindication. Target's second-quarter sales jumped 5.3%, digital sales grew nearly 9%, Target raised its full-year outlook for the second consecutive quarter, and the stock soared nearly 5%. Indeed, on a year to date basis, Target stock has soared nearly 60%.
#year #time
We saw it differently. At the time of their appointments, we vocally and presciently touted all three new CEOs as the right person for the job at the right time, while other ***** ysts rolled their eyes. Unlike the frequent, sometime successful model of the messianic hiring of industry outsiders as turnaround tians, these new CEOs hit the ground running as each had decades of experience in their sectors with glowing track records, priceless relationships, and balanced expertise across marketing, finance, strategy, and operations,.
Furthermore, we were the first to confidently predict the certainty of their success, even knowing that it would take some time to reposition their enterprises and for their new leadership to gain traction. Now the receipts are in, showing striking progress in all three cases, with each already well on their way to cementing their reputations as the architects of some of the most remarkable corporate turnarounds of our era.
When Michael Fiddelke, a Target lifer who had risen up the ranks from a lowly intern over two decades ago, was named CEO, cynics sneered that the board had chosen entrenched groupthink over fresh blood. We argued precisely the opposite—that the data overwhelmingly shows internal candidates outperform splashy external saviors, with insider CEOs appointed over the prior year delivering roughly 15% annualized shareholder returns while external hires averaged negative 9%. New brooms sweep clean, but the old broom knows the corners. Furthermore, we argued that Fiddelke was uniquely positioned to build on the many successes of his widely admired predecessor, Brian Cornell, despite simultaneous urgent challenges.
This week brought resounding vindication. Target's second-quarter sales jumped 5.3%, digital sales grew nearly 9%, Target raised its full-year outlook for the second consecutive quarter, and the stock soared nearly 5%. Indeed, on a year to date basis, Target stock has soared nearly 60%.
#year #time
1 month ago
The next few years will test whether Pfizer Inc. (NYSE:PFE) can replace yesterday's blockbusters, and whether Gilead Sciences, Inc. (NASDAQ:GILD) can become more than an HIV company. Pfizer's (NYSE:PFE) newer medicines are gaining traction, but that growth has yet to accelerate the wider business. Gilead (NASDAQ:GILD) is expanding faster, although its performance remains concentrated in one therapeutic area. For investors, this is ultimately a choice between an unfinished turnaround and a stronger growth story still searching for greater breadth.
Pfizer's (NYSE:PFE) strongest result was the performance of its non-COVID portfolio. Revenue excluding Comirnaty and Paxlovid grew 5% operationally, while launched and acquired products generated $3.2 billion and increased 18% operationally. Growth also came from several franchises. Padcev revenue rose 23% operationally to $667 million, supported by increased market share in bladder cancer. The Vyndaqel family generated $1.76 billion, up 8% operationally, while Lorbrena grew 37% operationally. These products give Pfizer more than one avenue for rebuilding revenue as COVID-related demand declines.
Pfizer (NYSE:PFE) lowered its 2026 COVID-product forecast from approximately $5 billion to $4 billion after low infection levels weighed on Paxlovid utilization. Nevertheless, stronger-than-expected non-COVID sales allowed the company to raise the midpoint of its total revenue guidance by $500 million. Cost reductions provide additional support for the company. Pfizer (NYSE:PFE) expects approximately $6.7 billion in savings from its cost-realignment program through 2029. A separate manufacturing-optimization program is expected to generate another $3 billion, bringing anticipated savings across the two programs to approximately $9.7 billion. This leaner cost base could help Pfizer (NYSE:PFE) preserve margins and continue investing in areas such as oncology and obesity.
Gilead (NASDAQ:GILD), however, is currently delivering much stronger underlying growth. Product sales excluding Veklury increased 10% to $7.6 billion, and HIV sales rose 12% to $5.7 billion, with Biktarvy revenue increasing 7% to $3.8 billion and Descovy sales climbing 48% to $967 million. Yeztugo, Gilead's (NASDAQ:GILD) twice-yearly injectable HIV-prevention medicine, contributed $232 million as its launch gained momentum. The product adds a potentially important growth driver to an already dominant HIV portfolio.
Growth, however, was not confined to HIV alone, as liver-disease sales increased 10% to $877 million, while Livdelzi revenue more than doubled from $78 million to $167 million. Trodelvy sales rose 26% to $457 million, providing further evidence that Gilead (NASDAQ:GILD) is building a meaningful oncology franchise. Management subsequently raised its 2026 product-sales outlook to $30.1–$30.4 billion and increased guidance for product sales excluding Veklury to $29.8–$30.1 billion.
#NYSE #million #gild
Pfizer's (NYSE:PFE) strongest result was the performance of its non-COVID portfolio. Revenue excluding Comirnaty and Paxlovid grew 5% operationally, while launched and acquired products generated $3.2 billion and increased 18% operationally. Growth also came from several franchises. Padcev revenue rose 23% operationally to $667 million, supported by increased market share in bladder cancer. The Vyndaqel family generated $1.76 billion, up 8% operationally, while Lorbrena grew 37% operationally. These products give Pfizer more than one avenue for rebuilding revenue as COVID-related demand declines.
Pfizer (NYSE:PFE) lowered its 2026 COVID-product forecast from approximately $5 billion to $4 billion after low infection levels weighed on Paxlovid utilization. Nevertheless, stronger-than-expected non-COVID sales allowed the company to raise the midpoint of its total revenue guidance by $500 million. Cost reductions provide additional support for the company. Pfizer (NYSE:PFE) expects approximately $6.7 billion in savings from its cost-realignment program through 2029. A separate manufacturing-optimization program is expected to generate another $3 billion, bringing anticipated savings across the two programs to approximately $9.7 billion. This leaner cost base could help Pfizer (NYSE:PFE) preserve margins and continue investing in areas such as oncology and obesity.
Gilead (NASDAQ:GILD), however, is currently delivering much stronger underlying growth. Product sales excluding Veklury increased 10% to $7.6 billion, and HIV sales rose 12% to $5.7 billion, with Biktarvy revenue increasing 7% to $3.8 billion and Descovy sales climbing 48% to $967 million. Yeztugo, Gilead's (NASDAQ:GILD) twice-yearly injectable HIV-prevention medicine, contributed $232 million as its launch gained momentum. The product adds a potentially important growth driver to an already dominant HIV portfolio.
Growth, however, was not confined to HIV alone, as liver-disease sales increased 10% to $877 million, while Livdelzi revenue more than doubled from $78 million to $167 million. Trodelvy sales rose 26% to $457 million, providing further evidence that Gilead (NASDAQ:GILD) is building a meaningful oncology franchise. Management subsequently raised its 2026 product-sales outlook to $30.1–$30.4 billion and increased guidance for product sales excluding Veklury to $29.8–$30.1 billion.
#NYSE #million #gild

1 month ago
By Toby Sterling and Rashika Singh
AMSTERDAM, Aug 20 (Reuters) - Nebius Group said on Thursday its $5 billion convertible bond was one of the largest on record and reflected strong demand for AI services and data centre capacity, despite recent jitters over the sector's huge financing needs.
Amsterdam-based Nebius, which sells AI services to tech firms and data centre capacity to customers including Meta and Microsoft, raised the size from $4.5 billion late on Wednesday and the total could be increased to $5.75 billion if buyers exercise all options.
"We think it's one of the largest, and the largest in recent history, in the corporate convertible world," Nebius chief communications officer Tom Blackwell told Reuters, adding that the firm's total convertible debt is now around $12 billion.
Proceeds of the new offer, led by Goldman Sachs and JPMorgan, will be used to fund the company's data centre buildout and further develop its AI services offerings.
#convertible #reuters
AMSTERDAM, Aug 20 (Reuters) - Nebius Group said on Thursday its $5 billion convertible bond was one of the largest on record and reflected strong demand for AI services and data centre capacity, despite recent jitters over the sector's huge financing needs.
Amsterdam-based Nebius, which sells AI services to tech firms and data centre capacity to customers including Meta and Microsoft, raised the size from $4.5 billion late on Wednesday and the total could be increased to $5.75 billion if buyers exercise all options.
"We think it's one of the largest, and the largest in recent history, in the corporate convertible world," Nebius chief communications officer Tom Blackwell told Reuters, adding that the firm's total convertible debt is now around $12 billion.
Proceeds of the new offer, led by Goldman Sachs and JPMorgan, will be used to fund the company's data centre buildout and further develop its AI services offerings.
#convertible #reuters
1 month ago
A couple of weeks ago during "Market on Close," I fielded a question about refining stocks like Valero (VLO), Marathon (MPC), and Phillips 66 (PSX). I basically said the price action represented a pause, because the market had mispriced the risk in the refined product market.
It's a supply-and-demand story I've also detailed in this ***** e with regard to the VanEck Vectors Oil Refiners ETF (CRAK), which is now up about 10% since I made those comments on the livestream, and spiking to new highs today.
As 30-Year Yields Spike to 5.31%, Our Top Chart Strategist Warns There's a Risk to Stocks: 'In a Word, Yes'
Cooler US Weather Forecasts Weigh on Nat-Gas Prices
Did the Commodities Complex See Turnaround Activity Overnight?
#market #stocks #marathon
It's a supply-and-demand story I've also detailed in this ***** e with regard to the VanEck Vectors Oil Refiners ETF (CRAK), which is now up about 10% since I made those comments on the livestream, and spiking to new highs today.
As 30-Year Yields Spike to 5.31%, Our Top Chart Strategist Warns There's a Risk to Stocks: 'In a Word, Yes'
Cooler US Weather Forecasts Weigh on Nat-Gas Prices
Did the Commodities Complex See Turnaround Activity Overnight?
#market #stocks #marathon


1 month ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
We have a combined pension and Social Security income of $8,400 per month that will only drop to $6,730 if one of us passes away. Our RMDs will start soon and we have $1.6 million in a 401(k) which we feel we can use a low-cost (expense ratio 0.12%) total return target fund to avoid the use of a robo-advisor that charges 0.3 – 0.8%. Plus, we have another $350,000 in Roths and a taxable brokerage account of $300,000 which RMDs would flow into. We own our home outright. In place of an annuity purchase can I simply use a target date fund in my IRA from which RMDs would be drawn automatically?
-JR
I hear a few different questions here, JR. First, should you purchase an annuity or rely on your investment portfolio? Next, is the cost of a robo-advisor worth it compared to a target date fund? And lastly, is a target date fund or robo-advisor sufficient for managing a portfolio like yours? Let's dig into each of them to help you get some answers. (And if you need more help answering questions like these, consider speaking with a financial advisor.)
An annuity is a form of insurance. You purchase it with the expectation that over the long term, the cost will be greater than the benefit. But, as with other types of insurance, it protects against a key risk. In this case, that risk is the possibility of running out of money, especially if you live longer than expected.
#cost #questions
We have a combined pension and Social Security income of $8,400 per month that will only drop to $6,730 if one of us passes away. Our RMDs will start soon and we have $1.6 million in a 401(k) which we feel we can use a low-cost (expense ratio 0.12%) total return target fund to avoid the use of a robo-advisor that charges 0.3 – 0.8%. Plus, we have another $350,000 in Roths and a taxable brokerage account of $300,000 which RMDs would flow into. We own our home outright. In place of an annuity purchase can I simply use a target date fund in my IRA from which RMDs would be drawn automatically?
-JR
I hear a few different questions here, JR. First, should you purchase an annuity or rely on your investment portfolio? Next, is the cost of a robo-advisor worth it compared to a target date fund? And lastly, is a target date fund or robo-advisor sufficient for managing a portfolio like yours? Let's dig into each of them to help you get some answers. (And if you need more help answering questions like these, consider speaking with a financial advisor.)
An annuity is a form of insurance. You purchase it with the expectation that over the long term, the cost will be greater than the benefit. But, as with other types of insurance, it protects against a key risk. In this case, that risk is the possibility of running out of money, especially if you live longer than expected.
#cost #questions


1 month ago
Wetter weather forecasts for the Corn Belt over the next couple weeks will likely limit buyer interest in corn (ZCZ26) and soybean (ZSX26) futures. It's very likely going to take a U.S. soybean crop weather market scare in August to reignite bullish enthusiasm in soybeans and corn. So far, weather forecasts are not indicating such.
However, a positive for the grain markets recently has been a slumping U.S. dollar index ($DXY) that Friday hit a seven-week low.
Coffee Prices Decline as Colombian Coffee Exports Partially Resume
Coffee Prices Decline as Colombian Coffee Exports Partially Resume
Bulls Are Back in Charge of Corn Prices as a New Rally Forms
#colombian
However, a positive for the grain markets recently has been a slumping U.S. dollar index ($DXY) that Friday hit a seven-week low.
Coffee Prices Decline as Colombian Coffee Exports Partially Resume
Coffee Prices Decline as Colombian Coffee Exports Partially Resume
Bulls Are Back in Charge of Corn Prices as a New Rally Forms
#colombian


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Options trading offers retail investors flexible ways to speculate on market movements or hedge existing portfolio positions. But, like all financial markets, it requires careful navigation and can be risky. This guide explains the core mechanics of options trading, the key risks, and how to manage your exposure.
An option is a derivative contract — a financial agreement where value is "derived" from an underlying ***** et, such as a stock, index, or commodity. It grants the right, but not the obligation, to buy or sell that ***** et at a set price (called the strike price) within a specified time frame.
Every options trade involves two entities: a buyer and a seller. The buyer pays for the contract and gains the right to buy or sell the ***** et. They have no obligation to act if the trade moves against them. The seller sells the contract, taking on an obligation to buy or sell the ***** et if the buyer chooses to exercise that right.
There are two primary types of options, calls and puts, and they work like this:
#options #trading #like
Options trading offers retail investors flexible ways to speculate on market movements or hedge existing portfolio positions. But, like all financial markets, it requires careful navigation and can be risky. This guide explains the core mechanics of options trading, the key risks, and how to manage your exposure.
An option is a derivative contract — a financial agreement where value is "derived" from an underlying ***** et, such as a stock, index, or commodity. It grants the right, but not the obligation, to buy or sell that ***** et at a set price (called the strike price) within a specified time frame.
Every options trade involves two entities: a buyer and a seller. The buyer pays for the contract and gains the right to buy or sell the ***** et. They have no obligation to act if the trade moves against them. The seller sells the contract, taking on an obligation to buy or sell the ***** et if the buyer chooses to exercise that right.
There are two primary types of options, calls and puts, and they work like this:
#options #trading #like

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Find out how much you could earn by locking in a high CD rate today. The Federal Reserve cut its federal funds rate three times in 2025. So far in 2026, the Fed has left interest rates alone, and so now could be your last chance to lock in a competitive CD rate before rates move further. CD rates vary widely across financial institutions, so it's important to ensure you're getting the best rate possible when shopping around for a CD.
The following is a breakdown of CD rates today and where to find the best offers.
Generally, the best CD rates today are offered on shorter terms of around one year or less. Online banks and credit unions, in particular, offer the top CD rates.
Today, Saturday, August 8, 2026, the highest CD rate is 4.15%. This rate is offered by Synchrony Bank on its 14-month CD.
#rate #best #find #advertiser
Find out how much you could earn by locking in a high CD rate today. The Federal Reserve cut its federal funds rate three times in 2025. So far in 2026, the Fed has left interest rates alone, and so now could be your last chance to lock in a competitive CD rate before rates move further. CD rates vary widely across financial institutions, so it's important to ensure you're getting the best rate possible when shopping around for a CD.
The following is a breakdown of CD rates today and where to find the best offers.
Generally, the best CD rates today are offered on shorter terms of around one year or less. Online banks and credit unions, in particular, offer the top CD rates.
Today, Saturday, August 8, 2026, the highest CD rate is 4.15%. This rate is offered by Synchrony Bank on its 14-month CD.
#rate #best #find #advertiser


2 months ago
Platinum ****** et Management, an investment management company, released its Q2 2026 investor letter for "Platinum International Brands Fund". A copy of the letter can be downloaded here. The fund returned over 4% in the quarter but lost 14% over the past year, primarily due to the dominance of tech stocks amid an AI investment boom. Consumer-focused sectors underperformed due to weak sentiment and challenges such as high interest rates and rising oil prices, which have contributed to record-low consumer confidence. However, the fund's holdings remain fundamentally strong, with top holdings averaging 13% sales growth and 19% profit growth. The letter noted that positive developments include resumed job growth, reduced oil prices, and easing fiscal policy, which potentially enhance consumer sentiment. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Platinum International Brands Fund highlighted Caterpillar Inc. (NYSE:CAT) as a notable contributor. Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On July 28, 2026, Caterpillar Inc. (NYSE:CAT) closed at $840.85 per share, reflecting a market capitalization of $387.29 billion. Caterpillar Inc. (NYSE:CAT) posted a one-month return of -15.19%, and its shares gained 93.69% over the past 52 weeks.
Platinum International Brands Fund stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor update:
"Caterpillar Inc. (NYSE:CAT) (+36%) was another strong performer, shrugging off a 14% fall in profit. Steel is a key input and tariffs hurt; management is working on remedies, but they will take time. Beneath the surface, demand is heating up. Cat's engines and turbines power locomotives, ships, oil rigs, gas pipelines and now datacentres, a source of demand as ferocious as it is price-insensitive. Add a mining and energy complex emerging from a decade of underinvestment and a depressed construction sector turning the corner and the prospects look bright."
Caterpillar Inc. (NYSE:CAT) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 87 hedge fund portfolios held Caterpillar Inc. (NYSE:CAT) at the end of the first quarter, up from 86 in the previous quarter. While we acknowledge the potential of Caterpillar Inc. (NYSE:CAT) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #letter #international #Consumer
In its Q2 2026 investor letter, Platinum International Brands Fund highlighted Caterpillar Inc. (NYSE:CAT) as a notable contributor. Caterpillar Inc. (NYSE:CAT) is a leading manufacturer of construction and mining equipment, off-highway diesel and natural gas engines, industrial gas turbines, and diesel-electric locomotives. On July 28, 2026, Caterpillar Inc. (NYSE:CAT) closed at $840.85 per share, reflecting a market capitalization of $387.29 billion. Caterpillar Inc. (NYSE:CAT) posted a one-month return of -15.19%, and its shares gained 93.69% over the past 52 weeks.
Platinum International Brands Fund stated the following regarding Caterpillar Inc. (NYSE:CAT) in its Q2 2026 investor update:
"Caterpillar Inc. (NYSE:CAT) (+36%) was another strong performer, shrugging off a 14% fall in profit. Steel is a key input and tariffs hurt; management is working on remedies, but they will take time. Beneath the surface, demand is heating up. Cat's engines and turbines power locomotives, ships, oil rigs, gas pipelines and now datacentres, a source of demand as ferocious as it is price-insensitive. Add a mining and energy complex emerging from a decade of underinvestment and a depressed construction sector turning the corner and the prospects look bright."
Caterpillar Inc. (NYSE:CAT) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 87 hedge fund portfolios held Caterpillar Inc. (NYSE:CAT) at the end of the first quarter, up from 86 in the previous quarter. While we acknowledge the potential of Caterpillar Inc. (NYSE:CAT) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #letter #international #Consumer

2 months ago
London looks set to open in the red on Friday, with tech selling and oil topping $100 a barrel combining to darken the mood heading into the weekend.
Futures traders have the FTSE 100 called 40 points lower, building on Thursday's 77-point decline to 10,639. The blue-chip index faces pressure from two directions: a sharp Wall Street sell-off driven by disappointing Big Tech earnings, and fresh geopolitical anxiety in the Middle East pushing oil prices to triple figures for the first time in months.
US stocks fell heavily overnight, with the Nasdaq leading the way down 2.2% as investors took a dim view of quarterly results from Alphabet and Tesla. The S&P 500 dropped 1.2%, its worst session of the month, while the Dow shed 1%.
The problem wasn't the earnings themselves, according to Swissquote's Ipek Ozkardeskaya; it was the spending. "Earnings themselves were not the problem; spending and evaporating free cash flow were," she said. "Both Alphabet and Tesla stood by their capital investment plans, while Alphabet raised its capex outlook by $15 billion to $205 billion. Meanwhile, free cash flow at both Alphabet and Tesla turned negative in the second quarter."
Ozkardeskaya warned that Big Tech, once defined by being capital-light and cash-heavy, is becoming the opposite: increasingly reliant on equity and debt issuance to finance AI ambitions at a time when interest rate expectations are moving higher.
#tesla #ozkardeskaya
Futures traders have the FTSE 100 called 40 points lower, building on Thursday's 77-point decline to 10,639. The blue-chip index faces pressure from two directions: a sharp Wall Street sell-off driven by disappointing Big Tech earnings, and fresh geopolitical anxiety in the Middle East pushing oil prices to triple figures for the first time in months.
US stocks fell heavily overnight, with the Nasdaq leading the way down 2.2% as investors took a dim view of quarterly results from Alphabet and Tesla. The S&P 500 dropped 1.2%, its worst session of the month, while the Dow shed 1%.
The problem wasn't the earnings themselves, according to Swissquote's Ipek Ozkardeskaya; it was the spending. "Earnings themselves were not the problem; spending and evaporating free cash flow were," she said. "Both Alphabet and Tesla stood by their capital investment plans, while Alphabet raised its capex outlook by $15 billion to $205 billion. Meanwhile, free cash flow at both Alphabet and Tesla turned negative in the second quarter."
Ozkardeskaya warned that Big Tech, once defined by being capital-light and cash-heavy, is becoming the opposite: increasingly reliant on equity and debt issuance to finance AI ambitions at a time when interest rate expectations are moving higher.
#tesla #ozkardeskaya

2 months ago
By Leo Marchandon
July 23 (Reuters) - SAP's finance chief said on Thursday that artificial intelligence in enterprise software must move beyond chatbots and coding tools into more complex business processes, where clean data, reliability and cost control matter more than access to the most powerful model.
Companies have poured money into generative AI but are still seeking evidence of broad productivity gains, and SAP is arguing that the returns will come less from general-purpose models than from governed systems embedded in specific business processes.
CFO Dominik Asam told reporters after SAP's second-quarter results that the "lion's share" of AI token consumption today was spent in "low-hanging fruits" coding ******* istant and chatbots, where AI's hallucinations matter less because the output carries limited risk if it fails.
But applying AI to finance, supply chain or other core business processes is harder because errors carry over multiple steps, increasing risk against compliance standards, he said.
#coding #matter #marchandon #july
July 23 (Reuters) - SAP's finance chief said on Thursday that artificial intelligence in enterprise software must move beyond chatbots and coding tools into more complex business processes, where clean data, reliability and cost control matter more than access to the most powerful model.
Companies have poured money into generative AI but are still seeking evidence of broad productivity gains, and SAP is arguing that the returns will come less from general-purpose models than from governed systems embedded in specific business processes.
CFO Dominik Asam told reporters after SAP's second-quarter results that the "lion's share" of AI token consumption today was spent in "low-hanging fruits" coding ******* istant and chatbots, where AI's hallucinations matter less because the output carries limited risk if it fails.
But applying AI to finance, supply chain or other core business processes is harder because errors carry over multiple steps, increasing risk against compliance standards, he said.
#coding #matter #marchandon #july

2 months ago
With a market cap of $60.6 billion, Targa Resources Corp. (TRGP) owns and operates a diversified portfolio of natural gas, natural gas liquids (NGL), and crude oil **** ets across North America. Through its Gathering and Processing and Logistics and Transportation segments, the company provides integrated services spanning production, storage, transportation, marketing, and resale of energy commodities.
The Houston, Texas-based company is set to deliver its fiscal Q2 2026 results soon. Ahead of this event, **** ysts forecast TRGP to report an EPS of $2.64, a decline of 8% from $2.87 in the previous year's quarter. It has exceeded Wall Street's bottom-line estimates in two of the past four quarters while missing on two other occasions.
Huge, Unusual Intel Options Volume Today Ahead of Earnings This Week
Intel Stock Is Down, But Put Premiums are High - Put Short Sellers Love the High Yields
The Number Tesla Stock Bulls Are Really Waiting for This Earnings Season Has Nothing to Do With Cars
#Stock
The Houston, Texas-based company is set to deliver its fiscal Q2 2026 results soon. Ahead of this event, **** ysts forecast TRGP to report an EPS of $2.64, a decline of 8% from $2.87 in the previous year's quarter. It has exceeded Wall Street's bottom-line estimates in two of the past four quarters while missing on two other occasions.
Huge, Unusual Intel Options Volume Today Ahead of Earnings This Week
Intel Stock Is Down, But Put Premiums are High - Put Short Sellers Love the High Yields
The Number Tesla Stock Bulls Are Really Waiting for This Earnings Season Has Nothing to Do With Cars
#Stock


2 months ago
This article was originally published on ETFTrends.com.
In another one of this week's tests of investor sentiment around artificial intelligence (AI) – and a tentpole one at that -- Google's parent company, Alphabet (NASDAQ: GOOGL), reports second-quarter results after the close of U.S. markets on Wednesday, July 22.
This report could be an opportune time for short-term traders to consider Alphabet single-stock ETFs, such as the Direxion Daily GOOGL Bull 2X Shares (GGLL) and the Direxion Daily GOOGL Bear 1X Shares (GGLS). When preparing for Alphabet's earnings with these funds, traders should note that GGLL attempts to deliver 200% of the daily returns of the internet stock, while the bearish GGLS seeks intraday performances corresponding with the inverse returns of Alphabet.
Although shares of Alphabet are up 12% year to date, they have slipped 3% over the past month — perhaps signaling a near-term burden of proof for the company as it heads into its earnings report. If that's accurate, either GGLL or GGLS could be worth considering.
"Look for Google Cloud growth in both quarterly numbers and contracted future revenue (or backlog)," noted Malik Khan of Morningstar. "We think investors want certainty that the $460 billion backlog will convert to sales over the next two years, and also want to know what that trajectory will look like. Non-backlog factors, such as consumption-based spending and new commitments, will be important for understanding the health of the cloud business."
#daily #cloud
In another one of this week's tests of investor sentiment around artificial intelligence (AI) – and a tentpole one at that -- Google's parent company, Alphabet (NASDAQ: GOOGL), reports second-quarter results after the close of U.S. markets on Wednesday, July 22.
This report could be an opportune time for short-term traders to consider Alphabet single-stock ETFs, such as the Direxion Daily GOOGL Bull 2X Shares (GGLL) and the Direxion Daily GOOGL Bear 1X Shares (GGLS). When preparing for Alphabet's earnings with these funds, traders should note that GGLL attempts to deliver 200% of the daily returns of the internet stock, while the bearish GGLS seeks intraday performances corresponding with the inverse returns of Alphabet.
Although shares of Alphabet are up 12% year to date, they have slipped 3% over the past month — perhaps signaling a near-term burden of proof for the company as it heads into its earnings report. If that's accurate, either GGLL or GGLS could be worth considering.
"Look for Google Cloud growth in both quarterly numbers and contracted future revenue (or backlog)," noted Malik Khan of Morningstar. "We think investors want certainty that the $460 billion backlog will convert to sales over the next two years, and also want to know what that trajectory will look like. Non-backlog factors, such as consumption-based spending and new commitments, will be important for understanding the health of the cloud business."
#daily #cloud

2 months ago
QQQ trades near $720, up 17% YTD, but NVIDIA's $5.1 trillion weighting means a handful of mega-caps effectively control the fund's direction.
Nvidia guided Q2 revenue to $91 billion while Meta raised its 2026 capex guide to $145 billion, validating AI infrastructure spending for now.
The 10-year Treasury at 4.62% sits near 12-month highs, and a sustained break above 4.75% would compress QQQ's long-duration growth-stock multiples fastest.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
The Invesco QQQ Trust (NASDAQ:QQQ) trades near $720, up roughly 17% year to date and about 29% over the past year. Memory names like Micron Technology (NASDAQ:MU) are up roughly 245% YTD while Microsoft has fallen about 20% in the same window. For anyone holding QQQ into the second half of 2026, two factors matter more than the fund's 100-stock label suggests.
Nvidia guided Q2 revenue to $91 billion while Meta raised its 2026 capex guide to $145 billion, validating AI infrastructure spending for now.
The 10-year Treasury at 4.62% sits near 12-month highs, and a sustained break above 4.75% would compress QQQ's long-duration growth-stock multiples fastest.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
The Invesco QQQ Trust (NASDAQ:QQQ) trades near $720, up roughly 17% year to date and about 29% over the past year. Memory names like Micron Technology (NASDAQ:MU) are up roughly 245% YTD while Microsoft has fallen about 20% in the same window. For anyone holding QQQ into the second half of 2026, two factors matter more than the fund's 100-stock label suggests.

3 months ago
The company's stock climbed less on the sales it made and more on the mountain of orders it couldn't yet fill.
If you held Hewlett Packard Enterprise (HPE) over the last year, congratulations. You watched a legacy tech giant deliver a +141% return, leaving the S&P 500's +22% in the dust. The story behind that run reveals something more fundamental than a great quarter or two: a company suddenly facing so much demand that its biggest problem is figuring out how to build everything fast enough.
The entire move was underpinned by a simple, powerful dynamic: orders were coming in far faster than products were going out. Management put it plainly, stating that in its most recent quarter, "Orders more than doubled significantly outpacing revenue, resulting in a record company backlog." That backlog became the market's focal point, a tangible sign of future revenue that gave investors confidence in a story that was just getting started.
Why Are Orders Surging Outside Of AI?
While AI gets all the headlines, the demand surge at HPE was surprisingly broad. Yes, the company booked another $1.8 billion in new AI systems orders. But the real tell was in the less glamorous corners of the data center. "Traditional server orders increased triple digits," the CEO noted, as companies rushed to modernize their existing infrastructure to handle the coming wave of AI inferencing workloads. The demand extended beyond training large models to the crucial task of upgrading everything else to actually use them. This demand was so strong that management now expects to hit its long-term earnings and cash flow targets two years ahead of schedule.
If you held Hewlett Packard Enterprise (HPE) over the last year, congratulations. You watched a legacy tech giant deliver a +141% return, leaving the S&P 500's +22% in the dust. The story behind that run reveals something more fundamental than a great quarter or two: a company suddenly facing so much demand that its biggest problem is figuring out how to build everything fast enough.
The entire move was underpinned by a simple, powerful dynamic: orders were coming in far faster than products were going out. Management put it plainly, stating that in its most recent quarter, "Orders more than doubled significantly outpacing revenue, resulting in a record company backlog." That backlog became the market's focal point, a tangible sign of future revenue that gave investors confidence in a story that was just getting started.
Why Are Orders Surging Outside Of AI?
While AI gets all the headlines, the demand surge at HPE was surprisingly broad. Yes, the company booked another $1.8 billion in new AI systems orders. But the real tell was in the less glamorous corners of the data center. "Traditional server orders increased triple digits," the CEO noted, as companies rushed to modernize their existing infrastructure to handle the coming wave of AI inferencing workloads. The demand extended beyond training large models to the crucial task of upgrading everything else to actually use them. This demand was so strong that management now expects to hit its long-term earnings and cash flow targets two years ahead of schedule.
3 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
Shares in the membership-based retailer Costco fell 4.1% on Thursday after a June sales update failed to meet Wall Street's lofty expectations.
That continued a weeks-long slump, but it also means the stock is looking more and more like one of the chain's hot dog deals.
Sign up for The Daily Upside at no cost for premium ****** ysis on all your favorite stocks.
READ ALSO: Can SK Hynix Escape Chipmaking's Cyclical Curse After Nasdaq Debut? and AstraZeneca Plunges After New Heart Disease Drug Fails Trial
Shares in the membership-based retailer Costco fell 4.1% on Thursday after a June sales update failed to meet Wall Street's lofty expectations.
That continued a weeks-long slump, but it also means the stock is looking more and more like one of the chain's hot dog deals.
Sign up for The Daily Upside at no cost for premium ****** ysis on all your favorite stocks.
READ ALSO: Can SK Hynix Escape Chipmaking's Cyclical Curse After Nasdaq Debut? and AstraZeneca Plunges After New Heart Disease Drug Fails Trial
3 months ago
With an average upside potential of 37.37% according to Wall Street **** ysts, SLB N.V. (NYSE:SLB) is included among the 10 Most Promising Energy Stocks to Buy Now.
SLB N.V. (NYSE:SLB) engages in the provision of technology for the energy industry worldwide.
On July 1, Citi cut its price recommendation on SLB N.V. (NYSE:SLB) from $68 to $63, but maintained a 'Buy' rating on the shares. The lowered target still represents an upside of over 18% from the current levels.
Citi trimmed its estimates for SLB's second quarter, saying that the ongoing weakness in the Middle East is expected to negatively impact the company's EBITDA growth. The **** yst firm believes that SLB is unlikely to see any significant upside unless the headwinds in the region begin to subside.
Back in January, SLB N.V. (NYSE:SLB) guided its FY 2026 revenue to be between $36.9 billion and $37.7 billion, but this outlook **** umed oil prices to remain range-bound in the high 50s to low 60s. However, the recent US-Iran war pushed global crude prices to multi-year highs, providing a significant boost to operators like SLB. The company is also targeting to nearly double annual revenues in its digital business to as much as $2 billion by 2030, with margins expanding to a range of 38%-42% towards the end of the decade.
SLB N.V. (NYSE:SLB) engages in the provision of technology for the energy industry worldwide.
On July 1, Citi cut its price recommendation on SLB N.V. (NYSE:SLB) from $68 to $63, but maintained a 'Buy' rating on the shares. The lowered target still represents an upside of over 18% from the current levels.
Citi trimmed its estimates for SLB's second quarter, saying that the ongoing weakness in the Middle East is expected to negatively impact the company's EBITDA growth. The **** yst firm believes that SLB is unlikely to see any significant upside unless the headwinds in the region begin to subside.
Back in January, SLB N.V. (NYSE:SLB) guided its FY 2026 revenue to be between $36.9 billion and $37.7 billion, but this outlook **** umed oil prices to remain range-bound in the high 50s to low 60s. However, the recent US-Iran war pushed global crude prices to multi-year highs, providing a significant boost to operators like SLB. The company is also targeting to nearly double annual revenues in its digital business to as much as $2 billion by 2030, with margins expanding to a range of 38%-42% towards the end of the decade.

3 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted Permian Resources Corporation (NYSE:PR). Headquartered in Midland, Texas, Permian Resources Corporation (NYSE:PR) is an independent oil and natural gas company. On July 7, 2026, Permian Resources Corporation (NYSE:PR) closed at $19.09 per share. One-month return of Permian Resources Corporation (NYSE:PR) was -3.24%, and its shares gained 34.91% over the past 52 weeks. Permian Resources Corporation (NYSE:PR) has a market capitalization of $15.98 billion.
Artisan Mid Cap Value Fund stated the following regarding Permian Resources Corporation (NYSE:PR) in its Q1 2026 investor letter:
"Our energy holdings were well represented among our top contributors, benefiting from higher energy prices. Permian Resources Corporation (NYSE:PR), an independent oil and gas company, and NOV, the largest manufacturer of oilfield equipment, led the way. We added PR to the portfolio in Q1 2025. PR is focused solely on the Delaware Basin of West Texas and southwestern New Mexico—the most prolific oil-producing region in the US. The founders and co-CEOs, who also have large ownership interests in the business, have sought to build a business that can produce substantial free cash flow, return capital to shareholders and generate attractive equity returns across varied commodity price environments. To achieve these goals, PR has pursued best-in-class operations and responsible capital stewardship by thoughtfully acquiring ****** ets it believes are undervalued and divesting acreage it believes would be better in someone else's hands, while meaningfully returning capital to shareholders in the form of dividends. We always seek to align ourselves with shareholder-oriented management teams, but we believe this is even more critical when investing in mid-sized energy companies given their depe
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted Permian Resources Corporation (NYSE:PR). Headquartered in Midland, Texas, Permian Resources Corporation (NYSE:PR) is an independent oil and natural gas company. On July 7, 2026, Permian Resources Corporation (NYSE:PR) closed at $19.09 per share. One-month return of Permian Resources Corporation (NYSE:PR) was -3.24%, and its shares gained 34.91% over the past 52 weeks. Permian Resources Corporation (NYSE:PR) has a market capitalization of $15.98 billion.
Artisan Mid Cap Value Fund stated the following regarding Permian Resources Corporation (NYSE:PR) in its Q1 2026 investor letter:
"Our energy holdings were well represented among our top contributors, benefiting from higher energy prices. Permian Resources Corporation (NYSE:PR), an independent oil and gas company, and NOV, the largest manufacturer of oilfield equipment, led the way. We added PR to the portfolio in Q1 2025. PR is focused solely on the Delaware Basin of West Texas and southwestern New Mexico—the most prolific oil-producing region in the US. The founders and co-CEOs, who also have large ownership interests in the business, have sought to build a business that can produce substantial free cash flow, return capital to shareholders and generate attractive equity returns across varied commodity price environments. To achieve these goals, PR has pursued best-in-class operations and responsible capital stewardship by thoughtfully acquiring ****** ets it believes are undervalued and divesting acreage it believes would be better in someone else's hands, while meaningfully returning capital to shareholders in the form of dividends. We always seek to align ourselves with shareholder-oriented management teams, but we believe this is even more critical when investing in mid-sized energy companies given their depe