3 days ago
For younger generations, the idea of living a life of leisure in retirement — playing golf, pursuing hobbies, going on bucket-list trips — seems increasingly out of reach.
At least one expert is saying they're right — and the new retirement plan is to "keep your job." Cultural historian Lawrence Samuel told Marketwatch he believes the modern idea of a leisurely retirement has come and gone.
Indeed, he says it's a powerful myth — just like the American dream. "But most Americans don't realize their American dream. The odds are against you," he told MarketWatch.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
#like #cultural #lawrence
At least one expert is saying they're right — and the new retirement plan is to "keep your job." Cultural historian Lawrence Samuel told Marketwatch he believes the modern idea of a leisurely retirement has come and gone.
Indeed, he says it's a powerful myth — just like the American dream. "But most Americans don't realize their American dream. The odds are against you," he told MarketWatch.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
#like #cultural #lawrence

3 days ago
I'll admit that like many economists and market commentators, I have warned about more market calamities than have actually come to pass. I'll say this in my defense:
If you ignore risk, you take your chances with what the market does next. If you always seek to account for risk, you can ride the highs without being pummeled by all the lows. Over time, that's a more gratifying investment experience.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#little
If you ignore risk, you take your chances with what the market does next. If you always seek to account for risk, you can ride the highs without being pummeled by all the lows. Over time, that's a more gratifying investment experience.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#little


3 days ago
Just over a year ago, investors largely viewed IREN (IREN) as a bitcoin mining company. Today, the company supplies AI infrastructure to Microsoft (MSFT) and signs billion-dollar contracts with some of the biggest names in the AI market, including Nvidia (NVDA) and Dell Technologies (DELL). These developments provide evidence that IREN's shift toward AI infrastructure is translating into actual business activity, and the market has responded strongly to that progress. IREN shares have been rewarded with two strong moves over the last two months.
IREN's AI transformation centers on a major five-year agreement with Microsoft. The company entered into a $9.7 billion cloud services agreement with Microsoft, with 20% of the contract value paid upfront. Once fully commissioned, the deal is expected to generate nearly $1.94 billion in annualized run-rate revenue. That gives IREN a significant source of contracted business as it builds out its AI cloud operations.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
JPMorgan Changed Its Mind on Meta Stock After This Major AI Breakthrough
#NVIDIA
IREN's AI transformation centers on a major five-year agreement with Microsoft. The company entered into a $9.7 billion cloud services agreement with Microsoft, with 20% of the contract value paid upfront. Once fully commissioned, the deal is expected to generate nearly $1.94 billion in annualized run-rate revenue. That gives IREN a significant source of contracted business as it builds out its AI cloud operations.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
JPMorgan Changed Its Mind on Meta Stock After This Major AI Breakthrough
#NVIDIA


3 days ago
Risk management is my number one priority. As I see it, you can't get where you want to be as an investor if you don't control the risk you take.
That ranges from the use of cash, incorporation of hedging techniques, and a whole lot more. Here, I want to draw your attention to one of the less research intensive aspects of risk management.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#risk #known #jensen #quietly
That ranges from the use of cash, incorporation of hedging techniques, and a whole lot more. Here, I want to draw your attention to one of the less research intensive aspects of risk management.
Here's Another Little-Known Firm Jensen Huang's Nvidia Is Quietly Backing
MediaTek Is Stepping Up Competition Against Qualcomm With a New 2-Nanometer Chip. What This Means for QCOM Stock.
1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon
#risk #known #jensen #quietly



3 days ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

3 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell

3 days ago
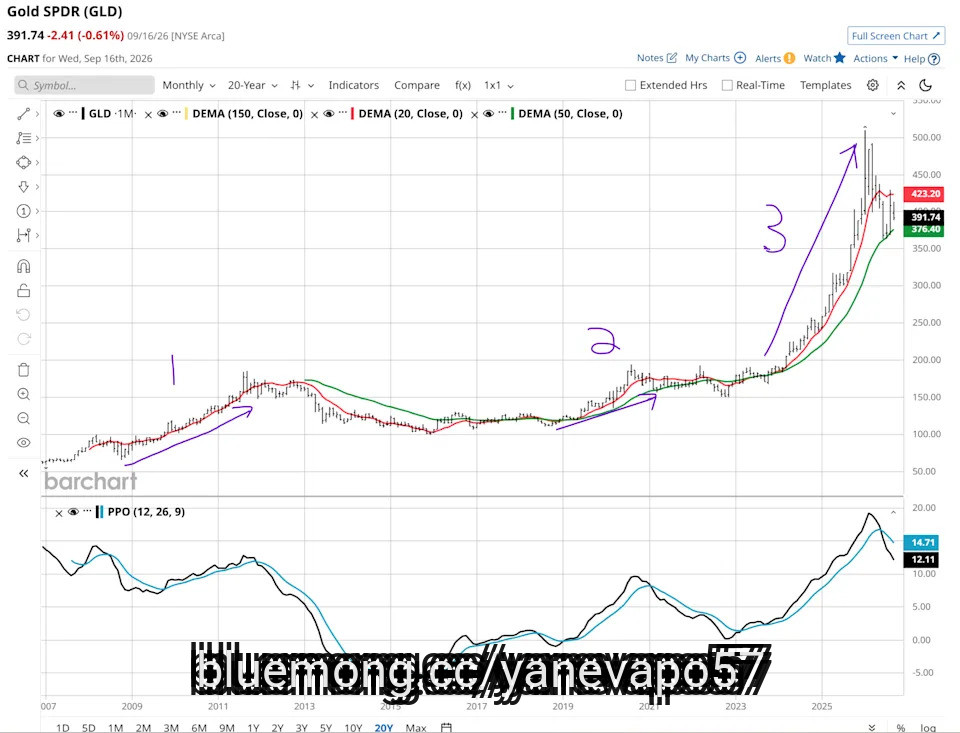
Is there any investment market segment more debated than gold (XAUUSD)? I'm not sure there is. We have "gold bugs," including those who see the yellow metal as the ***** et to own when the world goes haywire.
Then, there are the "we're going back on the gold standard" types. The ones that preceded crypto bros in believing fiat currencies weren't for this world. It follows that gold would return to its former role as the reserve currency.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ***** ysis you won't find anywhere else.
Of course, there are also plenty of investors who don't really think about gold investing very much, and who will simply trade it when there's a good opportunity. I'm in this camp.
Financial media pundits routinely tout gold as some sort of bulletproof allocation. Inflation worries? Own gold. Currency debasement? Own gold. Want your kitchen to be decorated like the Oval Office? You'll need a lot of gold.
#Gold #free #barchart #brief
Then, there are the "we're going back on the gold standard" types. The ones that preceded crypto bros in believing fiat currencies weren't for this world. It follows that gold would return to its former role as the reserve currency.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ***** ysis you won't find anywhere else.
Of course, there are also plenty of investors who don't really think about gold investing very much, and who will simply trade it when there's a good opportunity. I'm in this camp.
Financial media pundits routinely tout gold as some sort of bulletproof allocation. Inflation worries? Own gold. Currency debasement? Own gold. Want your kitchen to be decorated like the Oval Office? You'll need a lot of gold.
#Gold #free #barchart #brief

3 days ago
Millions of Americans recently received unwelcome news about their cell phone bills.
In late June, T-Mobile (TMUS) said it was retiring over 1,000 older plans, shifting customers to newer offerings at an added cost of as much as $6 per line per month. And starting in August, AT&T (T) hiked rates on some of its older plans by $10 to $20 and increased a monthly per-line fee by $1.
The changes contributed to a steep 5.9% jump in Americans' wireless bills from July to August alone, according to Consumer Price Index data. It was the largest single-month jump since the Bureau of Labor Statistics began tracking the category nearly three decades ago.
In a twist, last month's rising phone bills may have helped convince the Federal Reserve to implement its first interest rate hike in three years. The steep price jump likely contributed about 10 basis points of August's 0.3% month-over-month rise in core consumer prices, according to Wall Street ******* ysts. The hotter-than-expected jump in this category, which strips out price changes in the particularly volatile food and energy sectors, helped cement expectations for the Fed's 25 basis point hike to benchmark rates last Wednesday.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
#august #plans
In late June, T-Mobile (TMUS) said it was retiring over 1,000 older plans, shifting customers to newer offerings at an added cost of as much as $6 per line per month. And starting in August, AT&T (T) hiked rates on some of its older plans by $10 to $20 and increased a monthly per-line fee by $1.
The changes contributed to a steep 5.9% jump in Americans' wireless bills from July to August alone, according to Consumer Price Index data. It was the largest single-month jump since the Bureau of Labor Statistics began tracking the category nearly three decades ago.
In a twist, last month's rising phone bills may have helped convince the Federal Reserve to implement its first interest rate hike in three years. The steep price jump likely contributed about 10 basis points of August's 0.3% month-over-month rise in core consumer prices, according to Wall Street ******* ysts. The hotter-than-expected jump in this category, which strips out price changes in the particularly volatile food and energy sectors, helped cement expectations for the Fed's 25 basis point hike to benchmark rates last Wednesday.
Read more: How the Fed rate decision affects your bank accounts, loans, credit cards, and investments
#august #plans

3 days ago
Around 57% of households have some type of unsecured debt, including credit cards and personal loans. This debt can be a financial burden because borrowers must make monthly payments and cover interest.
Once you've taken on debt, you're committed to paying it back. Otherwise, you could hurt your credit score and face collection activity. But what happens if the company you borrowed from runs into financial trouble and goes out of business? Does that mean your debt disappears?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#around #once #otherwise
Once you've taken on debt, you're committed to paying it back. Otherwise, you could hurt your credit score and face collection activity. But what happens if the company you borrowed from runs into financial trouble and goes out of business? Does that mean your debt disappears?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#around #once #otherwise


4 days ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited

4 days ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

4 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

4 days ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management


4 days ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
4 days ago
On September 9, 2026, Reuters reported that Alphabet Inc. (NASDAQ:GOOGL)'s Google will invest at least €13 billion, or about $15.1 billion, in AI infrastructure in Finland over the next two years, its biggest European investment, including three new data centers and a 22-year deal for up to 50% of the output of one of Finland's two nuclear power plants. The agreement with Finnish utility Fortum is Google's first nuclear energy deal outside the United States, and Fortum's stock jumped as much as 15.5% on the news, its biggest gain in Europe that day.
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl
4 days ago
On September 9, 2026, Reuters reported that Stellantis N.V. (NYSE:STLA) is recalling 201,976 Jeep vehicles in the U.S., including certain Grand Cherokee, Wagoneer and Grand Wagoneer models. It happened after the National Highway Traffic Safety Administration found a software error that can prevent the tire-pressure monitoring system from detecting low tire pressure or alerting the driver, raising crash risk.
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software
Dealers will update the affected radio-frequency hub software free of charge. The recall is the latest in a year that has already included a 1.5-million-vehicle Ram seat-belt recall, a 955,000-vehicle camera-glitch recall in August, and more than 1 million Wranglers and Gladiators recalled in June for fire risk.
The recall should carry a relatively limited direct financial burden because Stellantis N.V. (NYSE:STLA) can fix the defect with a software update. The recall covers 201,976 Jeep vehicles, but Stellantis does not need to replace a physical component. A software-based remedy should reduce parts and labor costs and allow dealers to complete the repair relatively quickly, limiting the recall's immediate impact on earnings and cash flow.
Stellantis has already begun rebuilding its financial performance, giving investors a stronger foundation to absorb another recall. Second-quarter net profit reached €293 million compared with a €1.87 billion loss a year earlier. Revenue surged 13% to €43.5 billion. The business also generated €1 billion in industrial free cash flow during the quarter, showing real improvement as CEO Antonio Filosa executes his turnaround plan.
Strong North American demand shows the recall has not yet undermined demand for Stellantis' key Jeep and Ram products. Second-quarter North American shipments increased 38% to 445,000 vehicles. It was backed up by refreshed models, including the Jeep Grand Wagoneer and Grand Cherokee and the Ram 1500. So the company enters this recall with improving volumes and strong demand for several of the brands that matter most to its North American turnaround.
#software

4 days ago
On September 9, 2026, Reuters reported that Amazon.com, Inc. (NASDAQ:AMZN) raised £4.25 billion, or about $5.76 billion, in its first-ever sterling bond sale, slightly more than initially expected, as part of a four-tranche deal spanning 3 to 19 years. Final investor demand came in at more than £10.65 billion, roughly 2.5 times the amount raised, but that was notably lower than the demand Alphabet saw for its own sterling debut in February, a sign ******* ysts said shows hyperscaler borrowing may be starting to test the limits of investor appetite.
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn

4 days ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
4 days ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth

4 days ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue
4 days ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional
4 days ago
SPX Technologies, Inc. (NYSE:SPXC) announced on September 15 that it completed the acquisition of FIS Water, LLC for approximately $410 million in cash, including certain tax attributes. The acquired business is expected to generate approximately $105 million of revenue in 2026.
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE
4 days ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ

4 days ago
Microsoft's (NASDAQ:MSFT) fiscal 2026, which ended June 30, was arguably the strongest year in the software giant's history. Revenue grew 18% to $331.8 billion. Net income jumped 31% year over year, to $133.7 billion.
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter
4 days ago
No matter how well you plan for retirement, there are surprises that could throw you for a loop. The stock market might crash unexpectedly. Your healthcare costs might increase. Or, worse yet, you could end up needing long-term care at some point.
But one hiccup you should know to plan for is inflation. Over time, the cost of living is likely to rise. And if you aren't prepared, you could easily end up losing out on buying power. These two adjustments to your retirement plan could help you avoid that fate.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
It's fairly common for retirees to reduce their stock holdings to minimize risk in their portfolios. But while it's OK to de-risk to some degree, you don't want to dump your stocks completely. Doing so could cause your portfolio to trail inflation, leading you to lose buying power and putting your savings at risk of being depleted.
If you're not comfortable holding individual stocks in retirement, buy shares of an S&P 500 exchange-traded fund (ETF). This effectively gives you exposure to the market. Or load up on dividend ETFs that generate steady income.
#plan #market
But one hiccup you should know to plan for is inflation. Over time, the cost of living is likely to rise. And if you aren't prepared, you could easily end up losing out on buying power. These two adjustments to your retirement plan could help you avoid that fate.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
It's fairly common for retirees to reduce their stock holdings to minimize risk in their portfolios. But while it's OK to de-risk to some degree, you don't want to dump your stocks completely. Doing so could cause your portfolio to trail inflation, leading you to lose buying power and putting your savings at risk of being depleted.
If you're not comfortable holding individual stocks in retirement, buy shares of an S&P 500 exchange-traded fund (ETF). This effectively gives you exposure to the market. Or load up on dividend ETFs that generate steady income.
#plan #market


4 days ago
Nvidia (NVDA) CEO Jensen Huang is challenging the people warning that AI could end humanity, suggesting their alarming predictions may serve another purpose.
Speaking with CBS News, Huang rejected the 'AI apocalypse' debate and questioned the motives behind those spreading that fear, adding a sharper edge to an increasingly public industry split.
OpenAI and Anthropic leaders, alongside Elon Musk, have backed calls to slow advanced AI development over safety concerns and fears that the technology might be advancing quicker than companies can control it, as reported by Financial Times.
For Nvidia investors, that debate carries financial weight. Shares have returned 20% year-to-date and 23% over the six months, according to Seeking Alpha data.
A coordinated slowdown could complicate the spending boom supporting its chip business. Huang's response, however, reaches beyond defending continued investment.
#NVIDIA #anthropic
Speaking with CBS News, Huang rejected the 'AI apocalypse' debate and questioned the motives behind those spreading that fear, adding a sharper edge to an increasingly public industry split.
OpenAI and Anthropic leaders, alongside Elon Musk, have backed calls to slow advanced AI development over safety concerns and fears that the technology might be advancing quicker than companies can control it, as reported by Financial Times.
For Nvidia investors, that debate carries financial weight. Shares have returned 20% year-to-date and 23% over the six months, according to Seeking Alpha data.
A coordinated slowdown could complicate the spending boom supporting its chip business. Huang's response, however, reaches beyond defending continued investment.
#NVIDIA #anthropic

4 days ago
Though it's down by 33% over the last five years, Ethereum (CRYPTO: ETH) climbed from about $130 in early 2020 to over $4,800 in early November 2021, which would have been sufficient to turn an investment of $27,000 into about $1 million. It's natural for investors to wonder if another historic run is in the cards for the coin, given that it's more widely known now than it was then.
Today, with a market cap of $292 billion as of Sept. 15, Ethereum can still grow your wealth substantially, but it probably won't be a millionaire maker for those with small positions anytime soon. Let's first look at the math to see why, then examine its upcoming catalysts.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Ethereum isn't going to be a millionaire-maker investment from here, even if you're willing to pony up a lot more capital than most investors have on hand or are willing to allocate to a lottery ticket, and even if it becomes the next cryptocurrency to explode.
Turning $10,000 into $1 million requires a 100x gain, which would boost Ethereum's market cap to $29.2 trillion.
#even
Today, with a market cap of $292 billion as of Sept. 15, Ethereum can still grow your wealth substantially, but it probably won't be a millionaire maker for those with small positions anytime soon. Let's first look at the math to see why, then examine its upcoming catalysts.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Ethereum isn't going to be a millionaire-maker investment from here, even if you're willing to pony up a lot more capital than most investors have on hand or are willing to allocate to a lottery ticket, and even if it becomes the next cryptocurrency to explode.
Turning $10,000 into $1 million requires a 100x gain, which would boost Ethereum's market cap to $29.2 trillion.
#even

4 days ago
Bloom Energy Corporation (NYSE:BE) garnered significant investor attention after it unveiled a new 800V DC-native fuel-cell power architecture on September 16, designed to supply continuous direct current to the next generation of AI data centers.
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture


4 days ago
The Vanguard Bond Market ETF (NASDAQ:BND) is the largest bond ETF with nearly $162.3 billion in ***** ets. If you invested $10,000 into BND today, it could grow into over $18,000 in 20 years, given its historical 3% annualized return since inception (assuming you reinvest your interest payments). That's likely a lot less than you'd earn if you invested the same amount in an S&P 500 index fund. However, bonds are income generators and portfolio stabilizers, not wealth-building tools.
Here's a look at why you might still want to consider investing in this top bond ETF, despite its low historical returns.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
Vanguard launched BND in early 2007, right before the financial crisis, when interest rates were at their peak:
#bond
Here's a look at why you might still want to consider investing in this top bond ETF, despite its low historical returns.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
Vanguard launched BND in early 2007, right before the financial crisis, when interest rates were at their peak:
#bond

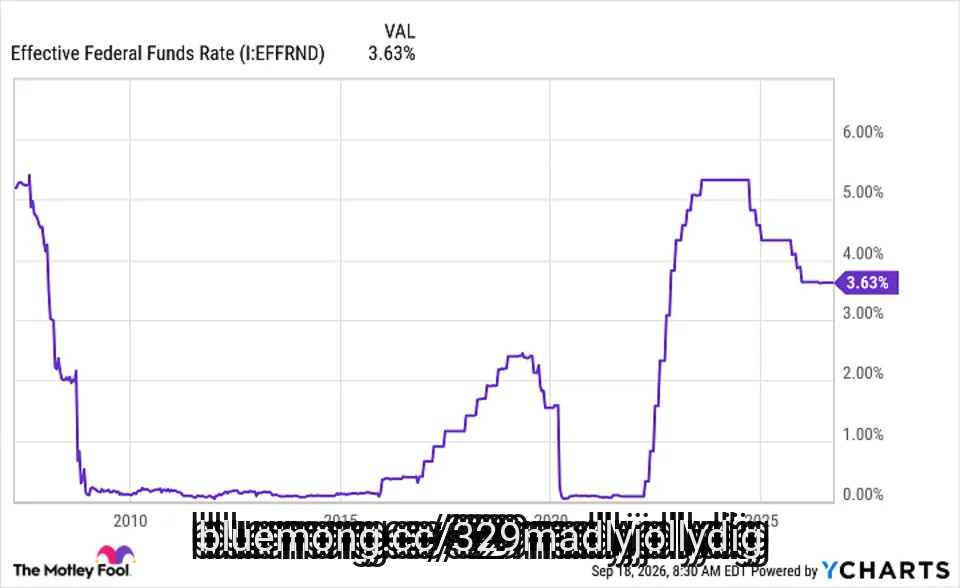
4 days ago
A Wall Street Journal report on September 16 revealed that ExxonMobil Holdings Corporation (NYSE:XOM) is nearing a preliminary agreement with Venezuela's state-owned PDVSA, potentially marking its return to the country almost two decades after its ***** ets were nationalized. According to Reuters, Exxon has shown interest in the large Petromonagas heavy oil project in the Orinoco Belt, as well as in areas in the neighboring Carabobo block.
While the talks are still in their preliminary phase and could still fall apart or be delayed, they mark a major turnaround from Exxon's previous stance on Venezuela. The company's CEO, Darren Woods, stated in January that the country was "uninvestable" without durable investment protections, legal reforms, and changes to its hydrocarbon laws.
The development comes amid a broader push by the Trump administration to open Venezuela's oil industry to American companies and revive the country's dilapidated oil infrastructure. The South American nation is sitting on the largest proven crude oil reserves in the world, accounting for roughly 17% of the global total.
Venezuela could provide Exxon with access to an enormous resource base at a time when the company is actively seeking low-cost and long-duration ***** ets. The fields under consideration are estimated to contain more than 50 billion barrels of oil buried underground.
Exxon already holds an advantage through its previous experience in the country. Petromonagas, formerly called Cerro Negro, was once the energy firm's flagship project in Venezuela, giving it familiarity with the country's vast heavy and extra-heavy crude resources. Petromonagas also remains one of the few Venezuelan projects with an operational upgrader capable of turning the Orinoco's extra-heavy crude into lighter exportable grades.
#heavy #project
While the talks are still in their preliminary phase and could still fall apart or be delayed, they mark a major turnaround from Exxon's previous stance on Venezuela. The company's CEO, Darren Woods, stated in January that the country was "uninvestable" without durable investment protections, legal reforms, and changes to its hydrocarbon laws.
The development comes amid a broader push by the Trump administration to open Venezuela's oil industry to American companies and revive the country's dilapidated oil infrastructure. The South American nation is sitting on the largest proven crude oil reserves in the world, accounting for roughly 17% of the global total.
Venezuela could provide Exxon with access to an enormous resource base at a time when the company is actively seeking low-cost and long-duration ***** ets. The fields under consideration are estimated to contain more than 50 billion barrels of oil buried underground.
Exxon already holds an advantage through its previous experience in the country. Petromonagas, formerly called Cerro Negro, was once the energy firm's flagship project in Venezuela, giving it familiarity with the country's vast heavy and extra-heavy crude resources. Petromonagas also remains one of the few Venezuelan projects with an operational upgrader capable of turning the Orinoco's extra-heavy crude into lighter exportable grades.
#heavy #project