1 month ago
When AI stocks rebounded last week, optical networking companies did not rebound equally.
Lumentum Holdings Inc. (NASDAQ:LITE) jumped nearly 10% in Wednesday trading and led the S&P 500, while Coherent rose 6.9%. Corning Incorporated (NYSE:GLW) managed only a 0.4% gain and remained down sharply for the week.
All three sit inside the same broad AI-connectivity buildout. The divergence suggests investors are beginning to distinguish between different pieces of that infrastructure rather than buying every optics name together.
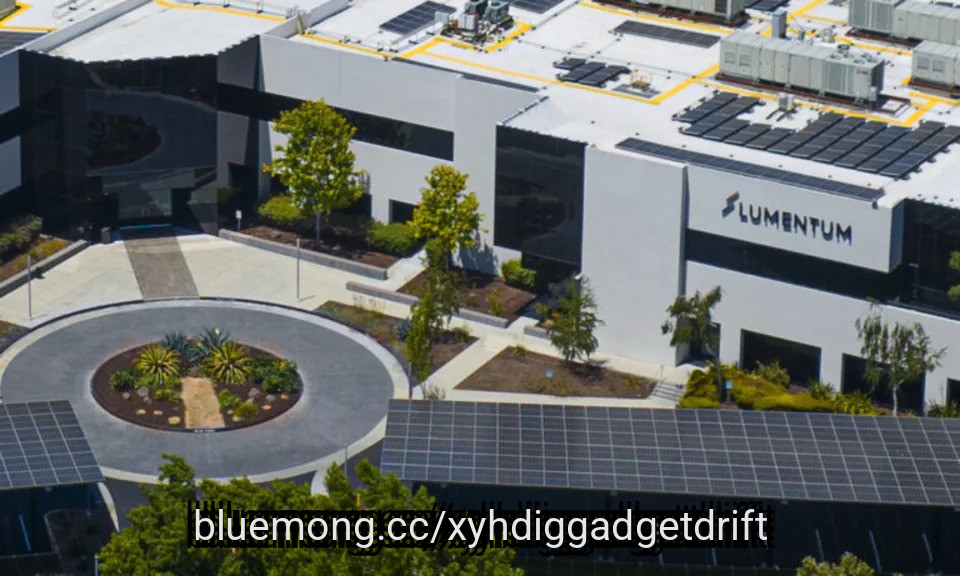
Photo from Lumentum Holdings website
AI clusters increasingly need optical connections as more accelerators communicate across larger physical distances. That drives demand for high-speed transceivers, lasers and other photonic components.
#NASDAQ #lite #wednesday #coherent
Lumentum Holdings Inc. (NASDAQ:LITE) jumped nearly 10% in Wednesday trading and led the S&P 500, while Coherent rose 6.9%. Corning Incorporated (NYSE:GLW) managed only a 0.4% gain and remained down sharply for the week.
All three sit inside the same broad AI-connectivity buildout. The divergence suggests investors are beginning to distinguish between different pieces of that infrastructure rather than buying every optics name together.
Photo from Lumentum Holdings website
AI clusters increasingly need optical connections as more accelerators communicate across larger physical distances. That drives demand for high-speed transceivers, lasers and other photonic components.
#NASDAQ #lite #wednesday #coherent
1 month ago
Former Intel CEO Pat Gelsinger is backing a startup that thinks AI's next bottleneck is not the accelerator. It is everything waiting for data to arrive.
Delos Data announced on September 15 that it raised more than $100 million to develop networking chips and software for increasingly heterogeneous AI data centers. Playground Global, where Gelsinger is a general partner, joined the round. Reuters reported that Delos is designing the network to work across different types of compute hardware rather than **** uming every accelerator comes from NVIDIA Corporation (NASDAQ:NVDA).
That makes Advanced Micro Devices, Inc. (NASDAQ:AMD) an important read-through even though AMD is not an investor in Delos.
For illustration purposes only. Photo by Brett Sayles on Pexels
Nvidia does not dominate AI simply because its GPUs are fast. NVIDIA Corporation (NASDAQ:NVDA) sells a tightly integrated system of accelerators, networking, interconnects and software. That makes large clusters easier to deploy and gives customers fewer reasons to mix architectures.
#delos #data #Networking #software
Delos Data announced on September 15 that it raised more than $100 million to develop networking chips and software for increasingly heterogeneous AI data centers. Playground Global, where Gelsinger is a general partner, joined the round. Reuters reported that Delos is designing the network to work across different types of compute hardware rather than **** uming every accelerator comes from NVIDIA Corporation (NASDAQ:NVDA).
That makes Advanced Micro Devices, Inc. (NASDAQ:AMD) an important read-through even though AMD is not an investor in Delos.
For illustration purposes only. Photo by Brett Sayles on Pexels
Nvidia does not dominate AI simply because its GPUs are fast. NVIDIA Corporation (NASDAQ:NVDA) sells a tightly integrated system of accelerators, networking, interconnects and software. That makes large clusters easier to deploy and gives customers fewer reasons to mix architectures.
#delos #data #Networking #software
1 month ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ
2 months ago
On September 17, B. Riley initiated coverage of Nokia Oyj (NYSE:NOK), giving the stock a Buy rating and setting the price target at $15. The firm pointed to the company's position in telecom infrastructure, cloud software, and hardware networking solutions.
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
2 months ago
NBIS revenue surged 454% to $582M with a $37.49B contracted backlog, while ALAB posted its eighth straight EPS beat on 104% revenue growth.
GPUs are worthless without high-speed interconnects, making cables, switches, and optical modules the AI industry's most critical and most overlooked bottleneck.
CRDO plunged 42% last month despite delivering 114.7% revenue growth and guiding for over 85% full-year growth in fiscal 2027.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Astera Labs didn't make the cut. Enter your email to see the names that beat ALAB. The report is free. Enter your email and see if any of your stocks made the cut.
The interconnect layer beneath AI clusters is the current bottleneck. GPUs are useless if they cannot exchange gradients and tokens at line rate, and the cables, switches, retimers, and optical modules that carry that traffic have become the constraint the industry is racing to relieve. One data point frames the pressure: (NASDAQ:ALAB) said PCIe 6 products already made up more than 50% of its total revenue in Q2, up from one third in Q1, evidence that the connectivity generation shift is happening in quarters, not years.
#gpus #cables
GPUs are worthless without high-speed interconnects, making cables, switches, and optical modules the AI industry's most critical and most overlooked bottleneck.
CRDO plunged 42% last month despite delivering 114.7% revenue growth and guiding for over 85% full-year growth in fiscal 2027.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Astera Labs didn't make the cut. Enter your email to see the names that beat ALAB. The report is free. Enter your email and see if any of your stocks made the cut.
The interconnect layer beneath AI clusters is the current bottleneck. GPUs are useless if they cannot exchange gradients and tokens at line rate, and the cables, switches, retimers, and optical modules that carry that traffic have become the constraint the industry is racing to relieve. One data point frames the pressure: (NASDAQ:ALAB) said PCIe 6 products already made up more than 50% of its total revenue in Q2, up from one third in Q1, evidence that the connectivity generation shift is happening in quarters, not years.
#gpus #cables


2 months ago
As the artificial intelligence revolution shifts from experimentation to industrial scale, choosing between Cerebras Systems (NASDAQ:CBRS) and CoreWeave (NASDAQ:CRWV) presents a unique choice for investors seeking infrastructure growth in 2026.
Cerebras builds massive chips designed to accelerate intensive workloads, while CoreWeave offers specialized cloud services for those same tasks. Both companies have seen rapid growth as businesses scramble for computing power, making them key names to watch among semiconductor stocks and infrastructure providers.
Cerebras Systems focuses on a single, bold hardware proposition: the Wafer-Scale Engine. This processor is the size of an entire silicon wafer, designed to train complex models much faster than traditional clusters. The company serves enterprise, government, and high-performance computing customers across North America, Europe, and the Middle East. While its latest annual report does not disclose specific major customers, its global reach continues to expand as it targets large-scale research and national security projects.
Financial performance has trended upward significantly in recent years. In its 2025 fiscal year (FY), revenue reached $510.0 million, representing growth of 75.7% compared to the prior year. The company also achieved profitability during this period, reporting net income of $237.8 million. This results in a net margin of 46.6%, which measures the percentage of revenue that remains as profit after all expenses are paid.
As of its December 2025 balance sheet, the company maintains a current ratio of 2.1x, indicating its ability to cover short-term obligations with short-term ***** ets while the debt-to-equity ratio is -0.5x. During FY 2025, free cash flow was negative at $392.8 million. Free cash flow is the cash a business generates after paying for its operations and capital expenditures to maintain the business.
#cerebras #million #cash #wafer
Cerebras builds massive chips designed to accelerate intensive workloads, while CoreWeave offers specialized cloud services for those same tasks. Both companies have seen rapid growth as businesses scramble for computing power, making them key names to watch among semiconductor stocks and infrastructure providers.
Cerebras Systems focuses on a single, bold hardware proposition: the Wafer-Scale Engine. This processor is the size of an entire silicon wafer, designed to train complex models much faster than traditional clusters. The company serves enterprise, government, and high-performance computing customers across North America, Europe, and the Middle East. While its latest annual report does not disclose specific major customers, its global reach continues to expand as it targets large-scale research and national security projects.
Financial performance has trended upward significantly in recent years. In its 2025 fiscal year (FY), revenue reached $510.0 million, representing growth of 75.7% compared to the prior year. The company also achieved profitability during this period, reporting net income of $237.8 million. This results in a net margin of 46.6%, which measures the percentage of revenue that remains as profit after all expenses are paid.
As of its December 2025 balance sheet, the company maintains a current ratio of 2.1x, indicating its ability to cover short-term obligations with short-term ***** ets while the debt-to-equity ratio is -0.5x. During FY 2025, free cash flow was negative at $392.8 million. Free cash flow is the cash a business generates after paying for its operations and capital expenditures to maintain the business.
#cerebras #million #cash #wafer
2 months ago
Between 2023 and 2025, Nvidia (NASDAQ: NVDA) was the market's most obvious artificial intelligence (AI) trade. During this period, the stock went parabolic, surging by 1,180% and turning the chipmaker into the world's most valuable company by market cap. On a split-adjusted basis, that was a climb from about $14 per share to $186 by the end of 2025.
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
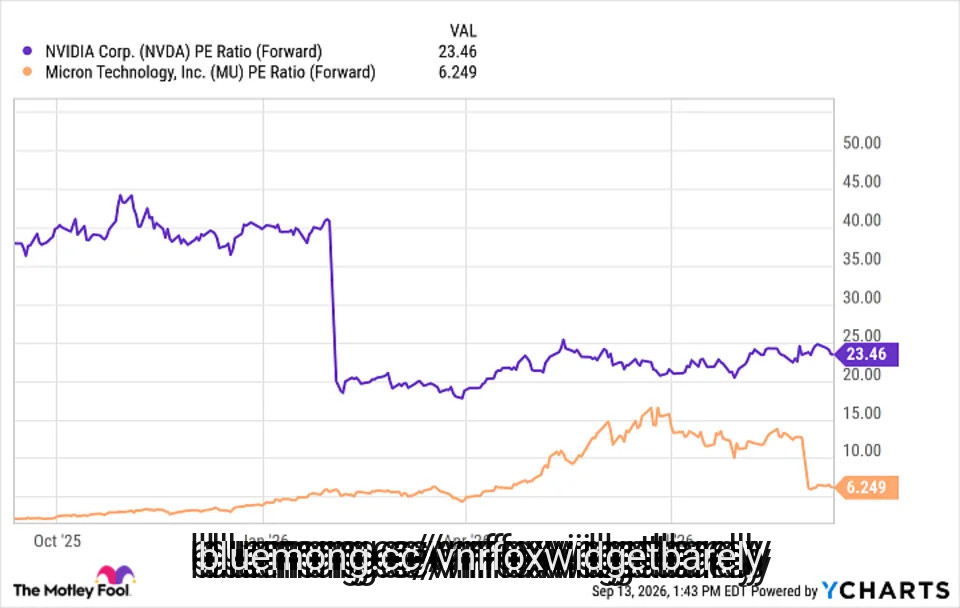
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker
Currently, Nvidia stock sits around $218, up another 17% year to date. This is what it looks like when a company owns a scarce product that's in heavy demand -- in this case, graphics processing units (GPUs).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology's (NASDAQ: MU) rocket-like move came a bit later, but hit much harder. Memory chips were an afterthought during the initial GPU gold rush. But as training clusters got larger and inference workloads got hungrier, supplies of high bandwidth memory (HBM) started running short. Prices for HBM soared, and Micron stock responded epically -- rising 239% in 2025 and another 242% so far this year. This type of price action indicates the market has recognized that memory is no longer just another tech commodity -- its supply is one of the key bottlenecks dictating the pace at which data centers can be built.
Nvidia and Micron are not the same bet. While Nvidia sells engines, Micron is selling the tanks for the fuel these engines cannot operate without. This begs the question: At this point, which of these AI chip stocks would be the better one to buy and hold for the next five years?
#signal #Stock #chipmaker

2 months ago
To summarize my investment approach, I prefer to buy companies with long histories of dividend increases and historically high yields. Those two traits don't come around all that often, and sometimes I find clusters of stocks in specific sectors. I need to think specifically about diversification, one of the simplest and most effective ways to reduce risk. Here's how I've done it as I've built my portfolio of around 34 investments.
The Motley Fool recommends that investors own 50 stocks. That's a perfectly fine number, but also a lot of work. And just owning 50 stocks doesn't actually mean you are diversified. You could own 50 technology stocks, for example, which would leave you with exposure to just a single sector. That's not diversification. Diversification is really about owning a reasonable number of investments across a wide range of sectors and ****** et classes.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My first step toward diversification was to take an honest look at what I want to achieve and what I'm capable of. My goal is a mixture of income and capital appreciation. I am fairly confident in my ability to select dividend stocks, though every investor makes mistakes from time to time, and I know I can only juggle so many stocks at once. In other words, 50 stocks are too many for me, so a core part of my diversification strategy is to outsource some of my work.
For example, I own two Baron mutual funds to gain exposure to growth stocks and smaller companies. I own several closed-end funds: one focused on healthcare stocks with an option income overlay, one investing in convertible securities, and one with a broadly diversified dividend portfolio. And I own three exchange-traded funds: one with an option income focus and two that use very different screening approaches to pick dividend stocks.
#Diversification #funds
The Motley Fool recommends that investors own 50 stocks. That's a perfectly fine number, but also a lot of work. And just owning 50 stocks doesn't actually mean you are diversified. You could own 50 technology stocks, for example, which would leave you with exposure to just a single sector. That's not diversification. Diversification is really about owning a reasonable number of investments across a wide range of sectors and ****** et classes.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My first step toward diversification was to take an honest look at what I want to achieve and what I'm capable of. My goal is a mixture of income and capital appreciation. I am fairly confident in my ability to select dividend stocks, though every investor makes mistakes from time to time, and I know I can only juggle so many stocks at once. In other words, 50 stocks are too many for me, so a core part of my diversification strategy is to outsource some of my work.
For example, I own two Baron mutual funds to gain exposure to growth stocks and smaller companies. I own several closed-end funds: one focused on healthcare stocks with an option income overlay, one investing in convertible securities, and one with a broadly diversified dividend portfolio. And I own three exchange-traded funds: one with an option income focus and two that use very different screening approaches to pick dividend stocks.
#Diversification #funds

2 months ago
Hewlett Packard Enterprise Company (NYSE:HPE) announced an expanded collaboration with Oracle Corporation (NYSE:ORCL) on September 2 to scale Oracle's global AI infrastructure using HPE Juniper Networking across Oracle Cloud Infrastructure (OCI) data centers. The partnership builds on over a decade of joint engineering, leveraging HPE's routing and switching platforms to support OCI's expanding gigawatt-scale GPU superclusters. To align long-term incentives, HPE issued stock warrants to Oracle.
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure
Following the announcement, Wall Street delivered fast price target hikes: Barclays' Tim Long raised HPE's target by $12 to $79 (Overweight), citing server upside and robust margins, while Morgan Stanley's Sanjit Singh boosted Oracle's target by $3 to $210 (Equal Weight), noting a tactically positive setup driven by GPUaaS demand.
Hewlett Packard Enterprise Company (NYSE:HPE) and Oracle both delivered strong results, although Oracle operates at a significantly larger scale. HPE reported record Q3 2026 revenue of $12.2 billion, up 34% year over year, driven by strong server demand and a 74.9% increase in Networking revenue to $2.9 billion. GAAP diluted EPS reached $1.06, while strong execution led management to raise full-year FY26 revenue growth guidance to 34%-37% and its free cash flow target to at least $3.75 billion.
Oracle Corporation (NYSE:ORCL), meanwhile, ended fiscal 2026 with record Q4 revenue of $19.2 billion, up 21% year over year, and full-year revenue of $67.4 billion, up 17%. Q4 Cloud Infrastructure (IaaS) revenue surged 93% to $5.8 billion, while full-year GAAP EPS rose 34% to $5.83 and Remaining Performance Obligations (RPO) jumped 363% to $638 billion.
Overall, ORCL leads in hyper-growth and long-term backlog, reinforcing its position as the stronger software and cloud play, while HPE is demonstrating stronger near-term hardware momentum and attractive cash flow generation for value-oriented investors.
#billion #revenue #infrastructure

2 months ago
Credo Technology Group Holding Ltd (NASDAQ:CRDO) reported fiscal first-quarter 2027 revenue of $479.0 million, up 9.6% sequentially. Management said the company's connectivity portfolio now spans copper and optical products, while total revenue increased 114.7% year over year. GAAP gross margin fell to 64.5% from 68.2% in the preceding quarter and 67.4% one year earlier.
GAAP operating expenses increased to $188.4 million from $142.2 million sequentially, while GAAP operating income declined to $120.7 million from $155.8 million. Credo Technology Group Holding Ltd (NASDAQ:CRDO) nevertheless expects another quarter of growth, guiding fiscal second-quarter revenue to $525 million to $535 million. The $530 million midpoint implies approximately 10.6% sequential expansion.
The question is whether revenue growth and the broader AI connectivity portfolio can offset acquisition-related costs and rising operating expenses.
Revenue scale remains the central strength. Credo Technology Group Holding Ltd (NASDAQ:CRDO) offers active electrical cables, optical transceivers, digital signal processors, silicon-photonics components, retimers, and chip-to-chip connectivity. These products address connections spanning short distances inside AI systems through longer links across clusters.
Absolute GAAP gross profit still increased to $309.1 million from $298.1 million sequentially despite the lower margin. Credo Technology Group Holding Ltd (NASDAQ:CRDO) ended the quarter with $764.3 million in cash and short-term investments, down from approximately $1.44 billion following completion of the DustPhotonics acquisition during the quarter. The remaining liquidity supports research, product development, and capacity requirements.
#crdo
GAAP operating expenses increased to $188.4 million from $142.2 million sequentially, while GAAP operating income declined to $120.7 million from $155.8 million. Credo Technology Group Holding Ltd (NASDAQ:CRDO) nevertheless expects another quarter of growth, guiding fiscal second-quarter revenue to $525 million to $535 million. The $530 million midpoint implies approximately 10.6% sequential expansion.
The question is whether revenue growth and the broader AI connectivity portfolio can offset acquisition-related costs and rising operating expenses.
Revenue scale remains the central strength. Credo Technology Group Holding Ltd (NASDAQ:CRDO) offers active electrical cables, optical transceivers, digital signal processors, silicon-photonics components, retimers, and chip-to-chip connectivity. These products address connections spanning short distances inside AI systems through longer links across clusters.
Absolute GAAP gross profit still increased to $309.1 million from $298.1 million sequentially despite the lower margin. Credo Technology Group Holding Ltd (NASDAQ:CRDO) ended the quarter with $764.3 million in cash and short-term investments, down from approximately $1.44 billion following completion of the DustPhotonics acquisition during the quarter. The remaining liquidity supports research, product development, and capacity requirements.
#crdo
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Hewlett Packard Enterprise said on September 2 that Oracle may deploy its Juniper networking equipment across Oracle Cloud Infrastructure data centers under a multi-year collaboration. The potential footprint includes PTX and MX routing plus QFX and EX switching, along with support and financing. Hewlett Packard Enterprise Company (NYSE:HPE) also issued warrants to Oracle Corporation (NYSE:ORCL), making the arrangement strategically important without turning every possible deployment into booked revenue.
For HPE, the bull case is that AI clusters are becoming networking systems, not merely collections of GPUs. Training at enormous scale requires fast links inside a data center and between facilities. Juniper gives HPE credible routing and switching ******* ets, while Oracle supplies a demanding reference customer. Insider Monkey counted 85 hedge funds holding HPE at June 30, up from 58 at March 31. Elliott Management held 32,271,985 shares after increasing its disclosed position by 18% during the quarter.
The bear case is conversion. The release describes potential deployments and several product families but discloses neither guaranteed purchase volume nor revenue. Warrants can align the customer while diluting existing owners if exercised. HPE also must integrate Juniper, defend margins, and compete with entrenched networking vendors while customers bargain aggressively over large orders.
Oracle's advantage is supply-chain flexibility. Adding HPE gives OCI another route to build high-bandwidth infrastructure as AI demand strains capacity. Oracle can combine cloud contracts, database relationships, and financing to pull customers onto its infrastructure. Hedge-fund participation remained broad: 119 funds held Oracle Corporation (NYSE:ORCL) in Q2, up from 115 in Q1. Fisher ******* et Management reported 13,261,451 shares, 39% more than in the previous filing.
Oracle still carries the heavier capital burden. Data centers require chips, land, power, and debt-funded construction before contracted demand becomes cash. A networking partnership improves execution options but does not protect returns if utilization or pricing disappoints.
#oracle #Networking #NYSE #enterprise
For HPE, the bull case is that AI clusters are becoming networking systems, not merely collections of GPUs. Training at enormous scale requires fast links inside a data center and between facilities. Juniper gives HPE credible routing and switching ******* ets, while Oracle supplies a demanding reference customer. Insider Monkey counted 85 hedge funds holding HPE at June 30, up from 58 at March 31. Elliott Management held 32,271,985 shares after increasing its disclosed position by 18% during the quarter.
The bear case is conversion. The release describes potential deployments and several product families but discloses neither guaranteed purchase volume nor revenue. Warrants can align the customer while diluting existing owners if exercised. HPE also must integrate Juniper, defend margins, and compete with entrenched networking vendors while customers bargain aggressively over large orders.
Oracle's advantage is supply-chain flexibility. Adding HPE gives OCI another route to build high-bandwidth infrastructure as AI demand strains capacity. Oracle can combine cloud contracts, database relationships, and financing to pull customers onto its infrastructure. Hedge-fund participation remained broad: 119 funds held Oracle Corporation (NYSE:ORCL) in Q2, up from 115 in Q1. Fisher ******* et Management reported 13,261,451 shares, 39% more than in the previous filing.
Oracle still carries the heavier capital burden. Data centers require chips, land, power, and debt-funded construction before contracted demand becomes cash. A networking partnership improves execution options but does not protect returns if utilization or pricing disappoints.
#oracle #Networking #NYSE #enterprise
2 months ago
Nvidia rose only 0.8% on September 4, while Astera Labs jumped 9.8% and Marvell gained 7.1%. The comparison was consistent with investors broadening the AI trade beyond accelerators into connectivity suppliers. Astera's rally also coincided with speculation that the company could be added to the S&P 500, although it was ultimately not selected in the September rebalance. Bigger accelerator clusters need retimers, switches, optical links, and custom silicon to move data without leaving expensive processors idle. Astera Labs, Inc. (NASDAQ:ALAB) and Marvell Technology, Inc. (NASDAQ:MRVL) monetize that connectivity bottleneck from different positions.
Photo from Astera Labs
Astera is the focused rack-scale connectivity play. Its second-quarter update said a Q3 production ramp of the Scorpio X-Series 320-lane fabric switch was expected to drive the next revenue inflection, alongside growth opportunities across Aries, Taurus, and Leo. The bull case is content growth: each new generation of AI rack can require more connectivity silicon and software. The bear case is dependence on a concentrated group of hyperscale customers, product-transition timing, and a valuation that ***** umes strong adoption before every design win becomes revenue.
Hedge-fund breadth strengthened before the rally. Insider Monkey counted 73 funds holding Astera Labs, Inc. (NASDAQ:ALAB) at June 30, up from 53 at March 31. Lee Ainslie's Maverick Capital disclosed 1,067,215 shares, 12% more than in Q1. The quarter-end filing cannot show whether Maverick participated in the September move.
Marvell is more diversified. Its data-center business spans custom compute, electro-optics, switching, and interconnect, giving it multiple ways to benefit as cloud companies redesign AI systems. That breadth is the bull case because one customer's architecture can pull several product families. It is also the risk: custom programs can be lumpy, development costs arrive before revenue, and investors may overestimate the near-term contribution of announced wins.
#september #alab
Photo from Astera Labs
Astera is the focused rack-scale connectivity play. Its second-quarter update said a Q3 production ramp of the Scorpio X-Series 320-lane fabric switch was expected to drive the next revenue inflection, alongside growth opportunities across Aries, Taurus, and Leo. The bull case is content growth: each new generation of AI rack can require more connectivity silicon and software. The bear case is dependence on a concentrated group of hyperscale customers, product-transition timing, and a valuation that ***** umes strong adoption before every design win becomes revenue.
Hedge-fund breadth strengthened before the rally. Insider Monkey counted 73 funds holding Astera Labs, Inc. (NASDAQ:ALAB) at June 30, up from 53 at March 31. Lee Ainslie's Maverick Capital disclosed 1,067,215 shares, 12% more than in Q1. The quarter-end filing cannot show whether Maverick participated in the September move.
Marvell is more diversified. Its data-center business spans custom compute, electro-optics, switching, and interconnect, giving it multiple ways to benefit as cloud companies redesign AI systems. That breadth is the bull case because one customer's architecture can pull several product families. It is also the risk: custom programs can be lumpy, development costs arrive before revenue, and investors may overestimate the near-term contribution of announced wins.
#september #alab
2 months ago
Becoming a millionaire through artificial intelligence (AI) investing doesn't necessarily mean betting on the next big chipmaker; it could mean finding the companies solving the infrastructure bottlenecks behind the boom. These three stocks are powering the AI build-out in different ways, and if the growth continues, they could have serious millionaire-making potential.
Astera Labs (NASDAQ: ALAB) solves a problem **** ody thought about until AI clusters got enormous. When you connect thousands of accelerators, the signal degrades over distance, and the connection between compute and memory becomes the bottleneck rather than the compute itself.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Revenue hit $308.4 million in the first quarter of 2026, up 93% year over year, with gross margin at 76.3%. That margin tells you this is a design business, not a manufacturing one.
Astera Labs' Scorpio product family is worth paying attention to. Management expects it to become the company's largest product line by the end of this year, and the new X-Series 320-lane fabric switch targets a merchant scale-up market projected to reach $20 billion by 2030. Astera also holds a $6.5 billion warrant agreement with Amazon, which aligns a hyperscaler directly with its success.
#astera #millionaire #mean
Astera Labs (NASDAQ: ALAB) solves a problem **** ody thought about until AI clusters got enormous. When you connect thousands of accelerators, the signal degrades over distance, and the connection between compute and memory becomes the bottleneck rather than the compute itself.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Revenue hit $308.4 million in the first quarter of 2026, up 93% year over year, with gross margin at 76.3%. That margin tells you this is a design business, not a manufacturing one.
Astera Labs' Scorpio product family is worth paying attention to. Management expects it to become the company's largest product line by the end of this year, and the new X-Series 320-lane fabric switch targets a merchant scale-up market projected to reach $20 billion by 2030. Astera also holds a $6.5 billion warrant agreement with Amazon, which aligns a hyperscaler directly with its success.
#astera #millionaire #mean
2 months ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Corning Incorporated (NYSE:GLW) as a new position. Corning Incorporated (NYSE:GLW) is a technology company that operates through optical communication, display technologies, environmental technologies, specialty materials, and life sciences business segments. On September 01, 2026, Corning Incorporated (NYSE:GLW) closed at $145.56 per share. Corning Incorporated (NYSE:GLW) declined 8.08% over the past month, while its shares gained 107.73% over the past 52 weeks. Corning Incorporated (NYSE:GLW) has a market capitalization of $125.38 billion with a 52-week trading range between $66.14 - $271.78.
Artisan Global Opportunities Strategy stated the following regarding Corning Incorporated (NYSE:GLW) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Corning Incorporated (NYSE:GLW). Corning and STMicroelectronics represent earlier stage semiconductor supply chain opportunities that we believe will see growing demand as AI infrastructure spending broadens beyond today's most obvious beneficiaries. In both cases, we see a potential opportunity for higher value, higher margin products as data centers require greater optical connectivity, semiconductor content and related infrastructure. Corning is a leading global supplier of specialty glass and optical connectivity solutions. We initiated a GardenSM position because we believe Corning is well positioned to meet rising optical connectivity needs as AI infrastructure shifts toward larger clusters and scale-up architectures. While we are not early to the story, we believe the company's fiber capacity, US-based manufacturing footprint and ability to deliver higher complexity optical solutions to hyperscaler
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Corning Incorporated (NYSE:GLW) as a new position. Corning Incorporated (NYSE:GLW) is a technology company that operates through optical communication, display technologies, environmental technologies, specialty materials, and life sciences business segments. On September 01, 2026, Corning Incorporated (NYSE:GLW) closed at $145.56 per share. Corning Incorporated (NYSE:GLW) declined 8.08% over the past month, while its shares gained 107.73% over the past 52 weeks. Corning Incorporated (NYSE:GLW) has a market capitalization of $125.38 billion with a 52-week trading range between $66.14 - $271.78.
Artisan Global Opportunities Strategy stated the following regarding Corning Incorporated (NYSE:GLW) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Corning Incorporated (NYSE:GLW). Corning and STMicroelectronics represent earlier stage semiconductor supply chain opportunities that we believe will see growing demand as AI infrastructure spending broadens beyond today's most obvious beneficiaries. In both cases, we see a potential opportunity for higher value, higher margin products as data centers require greater optical connectivity, semiconductor content and related infrastructure. Corning is a leading global supplier of specialty glass and optical connectivity solutions. We initiated a GardenSM position because we believe Corning is well positioned to meet rising optical connectivity needs as AI infrastructure shifts toward larger clusters and scale-up architectures. While we are not early to the story, we believe the company's fiber capacity, US-based manufacturing footprint and ability to deliver higher complexity optical solutions to hyperscaler

2 months ago
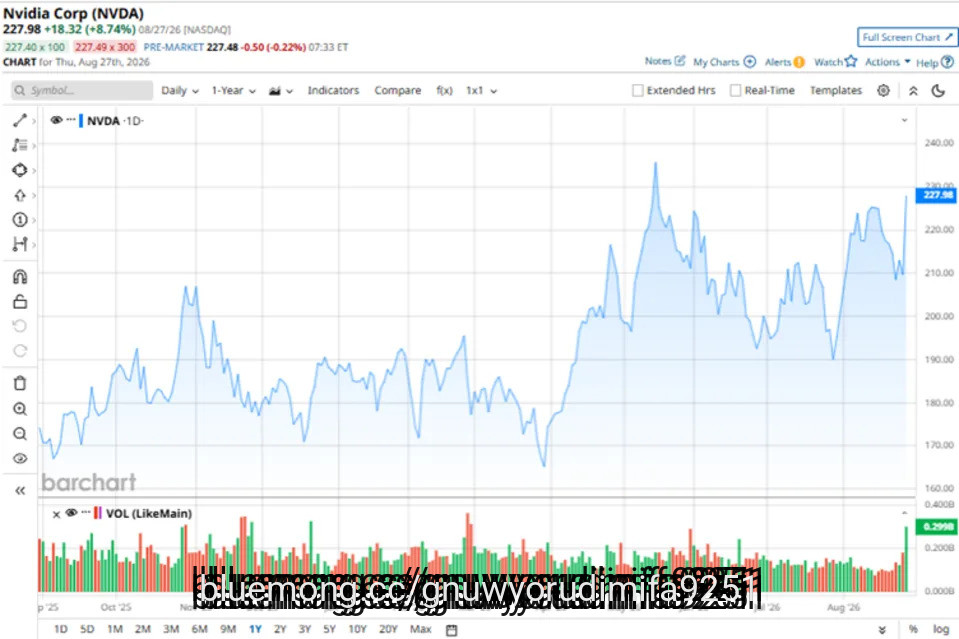
Nvidia (NVDA) reported blockbuster second-quarter fiscal 2027 results on Aug. 26, led by a solid surge in data-center revenue, which climbed by a whopping 117% year-over-year (YOY) to $89 billion. With the data-center business making up more than 90% of its top line, Nvidia has capitalized on the fact that more companies need large GPU clusters.
While the semiconductor industry leader faces "threats" that its near-monopoly on advanced artificial intelligence (AI) chips may be coming to an end, Nvidia remains the primary beneficiary of the AI boom. The company is also reportedly set to buy open-source AI platform Hugging Face for $12.9 billion, aligning with CEO Jensen Huang's strategy of building the AI world on the American stack.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#fans #hour #data #year
While the semiconductor industry leader faces "threats" that its near-monopoly on advanced artificial intelligence (AI) chips may be coming to an end, Nvidia remains the primary beneficiary of the AI boom. The company is also reportedly set to buy open-source AI platform Hugging Face for $12.9 billion, aligning with CEO Jensen Huang's strategy of building the AI world on the American stack.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#fans #hour #data #year
2 months ago
Nvidia has placed a large financial bet on the lasers that connect AI systems. On March 2, NVIDIA Corporation (NASDAQ:NVDA) invested $2 billion in Coherent Corp. (NYSE:COHR) common stock and entered a nonexclusive multiyear strategic arrangement covering optics development, purchase commitments, and access to manufacturing capacity. Coherent's August filing keeps attention on the capital required to meet that opportunity. The deal suggests bandwidth, not raw compute alone, may determine how quickly next-generation data centers scale.
Photo from Coherent website
NVIDIA Corporation (NASDAQ:NVDA) needs faster and more power-efficient connections as clusters grow to enormous numbers of accelerators. Strategic access to lasers and optical components can reduce supply risk and help Nvidia coordinate networking with its computing roadmap. The bull case is that Nvidia secures a critical input before demand peaks. The bear case is that purchase commitments could become less attractive if technologies shift or capacity expands faster than customers need.
Coherent Corp. (NYSE:COHR) gains capital, demand visibility, and validation from the AI industry's most influential platform company. Its lasers, transceivers, and materials can participate as data movement consumes a larger share of system power and cost. Yet scaling production requires capital expenditures and working capital well before all revenue is recognized. Customer concentration, manufacturing yields, pricing negotiations, and technology transitions can determine whether volume growth becomes attractive free cash flow.
The nonexclusive structure is important here. Nvidia can support capacity without surrendering alternative suppliers, while Coherent can sell beyond Nvidia. That makes the arrangement more resilient than an acquisition, but it also limits exclusivity as a competitive moat. The strongest thesis is not that one partner controls optics. It is that AI architectures need substantially more optical content, allowing both partners to benefit if execution holds.
#capital #nvda #NYSE
Photo from Coherent website
NVIDIA Corporation (NASDAQ:NVDA) needs faster and more power-efficient connections as clusters grow to enormous numbers of accelerators. Strategic access to lasers and optical components can reduce supply risk and help Nvidia coordinate networking with its computing roadmap. The bull case is that Nvidia secures a critical input before demand peaks. The bear case is that purchase commitments could become less attractive if technologies shift or capacity expands faster than customers need.
Coherent Corp. (NYSE:COHR) gains capital, demand visibility, and validation from the AI industry's most influential platform company. Its lasers, transceivers, and materials can participate as data movement consumes a larger share of system power and cost. Yet scaling production requires capital expenditures and working capital well before all revenue is recognized. Customer concentration, manufacturing yields, pricing negotiations, and technology transitions can determine whether volume growth becomes attractive free cash flow.
The nonexclusive structure is important here. Nvidia can support capacity without surrendering alternative suppliers, while Coherent can sell beyond Nvidia. That makes the arrangement more resilient than an acquisition, but it also limits exclusivity as a competitive moat. The strongest thesis is not that one partner controls optics. It is that AI architectures need substantially more optical content, allowing both partners to benefit if execution holds.
#capital #nvda #NYSE

2 months ago
Microsoft's next major AI constraint may be measured in turbines rather than processors. On June 22, Microsoft Corporation (NASDAQ:MSFT) entered a 20-year power purchase agreement with Energy Forge One LLC, a wholly owned subsidiary of Chevron Corporation (NYSE:CVX), for a planned West Texas data-center project. The Kilby development targets 2.67 gigawatts of generation, with initial power expected in 2028. Its scale suggests that securing dependable electricity is becoming as strategic to hyperscalers as securing accelerators.
Tupungato / Shutterstock.com
Microsoft Corporation (NASDAQ:MSFT) gets a dedicated path to capacity in a grid-constrained market. Natural gas can provide round-the-clock generation that complements intermittent renewables and supports the reliability AI clusters require. A two-decade contract can also give developers confidence to finance construction. The bull case is simple: Microsoft protects its cloud growth by solving power locally instead of waiting years for transmission expansion.
Chevron Corporation (NYSE:CVX) gains a new outlet for its gas and an opportunity to move downstream into integrated power. If Kilby works, Chevron can replicate a model that converts energy resources and project expertise into long-duration data-center cash flows. Yet the project has not reached a final investment decision. Construction, permitting, fuel costs, emissions rules, and customer requirements can all change the economics before power begins flowing.
Those uncertainties create bear cases for both companies. Microsoft is committing to an energy pathway as AI hardware and efficiency evolve rapidly, and a long contract can become less attractive if power markets change. Chevron and its partners must commit capital years before the **** et is operational while managing construction, fuel-cost and carbon-policy risks. Gas solves the reliability problem, but it may intensify political and regulatory scrutiny around AI's environmental footprint. The critical milestones are final investment approval, permitting, construction costs, and data showing that the first power date remains achievable. Until those arrive, the agreement secures intent rather than operating supply.
#power #data
Tupungato / Shutterstock.com
Microsoft Corporation (NASDAQ:MSFT) gets a dedicated path to capacity in a grid-constrained market. Natural gas can provide round-the-clock generation that complements intermittent renewables and supports the reliability AI clusters require. A two-decade contract can also give developers confidence to finance construction. The bull case is simple: Microsoft protects its cloud growth by solving power locally instead of waiting years for transmission expansion.
Chevron Corporation (NYSE:CVX) gains a new outlet for its gas and an opportunity to move downstream into integrated power. If Kilby works, Chevron can replicate a model that converts energy resources and project expertise into long-duration data-center cash flows. Yet the project has not reached a final investment decision. Construction, permitting, fuel costs, emissions rules, and customer requirements can all change the economics before power begins flowing.
Those uncertainties create bear cases for both companies. Microsoft is committing to an energy pathway as AI hardware and efficiency evolve rapidly, and a long contract can become less attractive if power markets change. Chevron and its partners must commit capital years before the **** et is operational while managing construction, fuel-cost and carbon-policy risks. Gas solves the reliability problem, but it may intensify political and regulatory scrutiny around AI's environmental footprint. The critical milestones are final investment approval, permitting, construction costs, and data showing that the first power date remains achievable. Until those arrive, the agreement secures intent rather than operating supply.
#power #data
2 months ago
OpenAI revoked Cursor's API access after **** eX's $60 billion acquisition, citing Musk's pattern of contract violations, though OpenAI served just 5% of traffic.
SpaceX's Colossus clusters, targeting 1 million H100 equivalents, now power Cursor's $4 billion revenue base, eliminating dependence on rival AI suppliers.
Analysts set a $219 average price target on **** eX, representing over 50% upside, as AI vertical integration mirrors the playbook that collapsed launch costs.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and **** eX didn't make the cut. Grab the names FREE today.
The long-running dispute between OpenAI CEO Sam Altman and Elon Musk has simmered for years, rooted in Musk's exit from the AI lab he co-founded and his subsequent legal and public challenges over its direction. That rivalry just moved from boardroom barbs to operational consequences.
#openai #grab #altman
SpaceX's Colossus clusters, targeting 1 million H100 equivalents, now power Cursor's $4 billion revenue base, eliminating dependence on rival AI suppliers.
Analysts set a $219 average price target on **** eX, representing over 50% upside, as AI vertical integration mirrors the playbook that collapsed launch costs.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and **** eX didn't make the cut. Grab the names FREE today.
The long-running dispute between OpenAI CEO Sam Altman and Elon Musk has simmered for years, rooted in Musk's exit from the AI lab he co-founded and his subsequent legal and public challenges over its direction. That rivalry just moved from boardroom barbs to operational consequences.
#openai #grab #altman
3 months ago
Broadcom's AI orders exceeded $30B this quarter while Micron secured ~$100B in contracted memory revenue through five-year take-or-pay deals.
Micron's HBM4 is ramping twice as fast as its predecessor, with DRAM prices jumping 60% sequentially and gross margins hitting a record 84.9%.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Broadcom (NASDAQ:AVGO) and Micron Technology (NASDAQ:MU) delivered blockbuster quarters mapping onto the shift from AI training to inference and agentic workloads. Broadcom sells custom accelerators and networking silicon that stitch hyperscaler clusters together. Micron supplies the high-bandwidth memory those clusters need. Two different business models. One shared tailwind.
Broadcom's fiscal Q2 revenue hit $22.2 billion, up 48% year-on-year, with AI semiconductor revenue of $10.8 billion, up 143%. Hock Tan told investors "networking represented almost 40% of our Q2 AI revenue" and guided Q3 AI silicon to $16 billion, up over 200% year-on-year. Bookings were the headline: AI semiconductor orders exceeded $30 billion in the quarter, with programs now stretching to Google TPUs, Meta MTIA XPUs, OpenAI silicon, and Anthropic compute capacity.
#billion
Micron's HBM4 is ramping twice as fast as its predecessor, with DRAM prices jumping 60% sequentially and gross margins hitting a record 84.9%.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Broadcom (NASDAQ:AVGO) and Micron Technology (NASDAQ:MU) delivered blockbuster quarters mapping onto the shift from AI training to inference and agentic workloads. Broadcom sells custom accelerators and networking silicon that stitch hyperscaler clusters together. Micron supplies the high-bandwidth memory those clusters need. Two different business models. One shared tailwind.
Broadcom's fiscal Q2 revenue hit $22.2 billion, up 48% year-on-year, with AI semiconductor revenue of $10.8 billion, up 143%. Hock Tan told investors "networking represented almost 40% of our Q2 AI revenue" and guided Q3 AI silicon to $16 billion, up over 200% year-on-year. Bookings were the headline: AI semiconductor orders exceeded $30 billion in the quarter, with programs now stretching to Google TPUs, Meta MTIA XPUs, OpenAI silicon, and Anthropic compute capacity.
#billion

3 months ago
When someone asks me to name the best semiconductor stock to buy for now and the next few years, my answer is Nvidia (NASDAQ: NVDA). I look at plenty of other chip names, including Broadcom and Advanced Micro Devices, yet I keep coming back to Nvidia because it sits at the center of how artificial intelligence (AI) is built and used, not just at the edge of the hardware market.
The core of the story is Nvidia's data center business. In the most recent fiscal year (ended Jan. 25, 2026), Nvidia reported quarterly data center revenue of $62.3 billion, up 75% year over year, and full-year data center sales are expected to be in the neighborhood of $180 billion. These are massive numbers and show that data centers are the main engine for the company. When hyperscalers and enterprises decide how many AI clusters to build, they start with Nvidia's platform, then layer everything else around it.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company's platform is not just about a single AI chip. The company's Blackwell architecture connects hundreds of billions of transistors, custom interconnects, and massive pools of memory into unified graphics processing units (GPUs), then scales those GPUs into rack-level systems like GB200 and GB300 that act like giant accelerators. On top of those systems sit DGX SuperPODs, Grace CPUs, and software like CUDA and TensorRT that developers already know and trust. When I picture the AI factories that companies are building, I see Nvidia in the center of the blueprints.
All the above is the technical side. The psychological side matters, too. Nvidia has become the default AI stock for many investors. It is the ticker people think of when they hear about new models, new data centers, or new AI enterprise rollouts. **** ysts often mention Nvidia first when discussing AI infrastructure, and the stock still carries a broad buy rating and targets pointing to meaningful upside from current levels. That attention can create volatility, yet it also means the company gets a steady stream of capital and scrutiny, which pushes management to keep delivering.
#NVIDIA #like #gpus #flashing
The core of the story is Nvidia's data center business. In the most recent fiscal year (ended Jan. 25, 2026), Nvidia reported quarterly data center revenue of $62.3 billion, up 75% year over year, and full-year data center sales are expected to be in the neighborhood of $180 billion. These are massive numbers and show that data centers are the main engine for the company. When hyperscalers and enterprises decide how many AI clusters to build, they start with Nvidia's platform, then layer everything else around it.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company's platform is not just about a single AI chip. The company's Blackwell architecture connects hundreds of billions of transistors, custom interconnects, and massive pools of memory into unified graphics processing units (GPUs), then scales those GPUs into rack-level systems like GB200 and GB300 that act like giant accelerators. On top of those systems sit DGX SuperPODs, Grace CPUs, and software like CUDA and TensorRT that developers already know and trust. When I picture the AI factories that companies are building, I see Nvidia in the center of the blueprints.
All the above is the technical side. The psychological side matters, too. Nvidia has become the default AI stock for many investors. It is the ticker people think of when they hear about new models, new data centers, or new AI enterprise rollouts. **** ysts often mention Nvidia first when discussing AI infrastructure, and the stock still carries a broad buy rating and targets pointing to meaningful upside from current levels. That attention can create volatility, yet it also means the company gets a steady stream of capital and scrutiny, which pushes management to keep delivering.
#NVIDIA #like #gpus #flashing

3 months ago
In the AI infrastructure boom, Nvidia (NASDAQ: NVDA) sells the brains of the AI factory while Micron (NASDAQ: MU) supplies the memory that keeps those brains fed with data, and that difference shapes which stock will benefit more from the current phase of this historic spending wave. In my view, Nvidia is the clearer winner because a greater fraction of every dollar of hyperscaler capex is spent on its accelerators than goes toward memory chips of the type that Micron manufactures. Micron still looks like a powerful second-derivative play, since AI servers can't be built without the high-bandwidth memory it supplies.
The money flow this year is wildly high. The hyperscalers themselves say they plan to spend hundreds of billions of dollars in 2026 alone to expand AI data centers, GPU clusters, networking, and power infrastructure, a sharp jump from already elevated 2025 levels. One estimate puts combined capex for Amazon, Microsoft, Alphabet, and Meta Platforms at around $700 billion, with roughly two-thirds of that directed toward AI infrastructure rather than traditional cloud. Within that budget, the largest line item is the AI server stack itself, where accelerated servers built around high-end GPUs drive most of the component revenue growth. And of course, the hyperscalers are not the only tech players building data centers now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia sits directly in the center of this buying spree. Its data center business now revolves around entire racks of AI computing power, not just single chips. Systems like the GB200 Grace Blackwell Superchip and GB200 NVL72 tie together dozens of CPUs and GPUs into logical accelerators that can train and serve trillion-parameter models more efficiently than the prior-generation Hopper platforms. Hyperscalers are lining up to deploy these systems in their AI clouds, with massive companies committing to offer GB200 NVL72 instances to customers who want to run large language models at scale. All this sounds dense, but the basic point is that Nvidia products are in steady demand.
Nvidia's roadmap also continues to push the limits of performance and memory. Architectures like Blackwell and its new Vera Rubin processors combine vast computing throughput with enormous pools of high bandwidth memory (HBM), turning racks into "AI factories." That keeps Nvidia at the absolute center of procurement decisions when cloud providers are calculating how many clusters they will need to handle their training and inferencing workloads in 2026 and beyond.
#memory #high #signal
The money flow this year is wildly high. The hyperscalers themselves say they plan to spend hundreds of billions of dollars in 2026 alone to expand AI data centers, GPU clusters, networking, and power infrastructure, a sharp jump from already elevated 2025 levels. One estimate puts combined capex for Amazon, Microsoft, Alphabet, and Meta Platforms at around $700 billion, with roughly two-thirds of that directed toward AI infrastructure rather than traditional cloud. Within that budget, the largest line item is the AI server stack itself, where accelerated servers built around high-end GPUs drive most of the component revenue growth. And of course, the hyperscalers are not the only tech players building data centers now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia sits directly in the center of this buying spree. Its data center business now revolves around entire racks of AI computing power, not just single chips. Systems like the GB200 Grace Blackwell Superchip and GB200 NVL72 tie together dozens of CPUs and GPUs into logical accelerators that can train and serve trillion-parameter models more efficiently than the prior-generation Hopper platforms. Hyperscalers are lining up to deploy these systems in their AI clouds, with massive companies committing to offer GB200 NVL72 instances to customers who want to run large language models at scale. All this sounds dense, but the basic point is that Nvidia products are in steady demand.
Nvidia's roadmap also continues to push the limits of performance and memory. Architectures like Blackwell and its new Vera Rubin processors combine vast computing throughput with enormous pools of high bandwidth memory (HBM), turning racks into "AI factories." That keeps Nvidia at the absolute center of procurement decisions when cloud providers are calculating how many clusters they will need to handle their training and inferencing workloads in 2026 and beyond.
#memory #high #signal

3 months ago
Minda Corporation will invest close to Rs2.70bn ($28.2m) to build a new manufacturing facility in Pune, Maharashtra, to produce thin film transistor (TFT) displays for automotive use, executive director Aakash Minda told CNBC.
The project has secured approval under the Indian government's Scheme for Promotion of Manufacturing of Electronic Components and Semiconductors.
According to the report, it is designed to cut the company's reliance on imported displays while strengthening its manufacturing presence within India.
At the outset, the plant will concentrate on automotive displays for instrument clusters, infotainment systems and ******* pits.
Minda already produces clusters and other display-related components and intends to supply the displays made at the new facility to its own operations alongside external customers.
#clusters
The project has secured approval under the Indian government's Scheme for Promotion of Manufacturing of Electronic Components and Semiconductors.
According to the report, it is designed to cut the company's reliance on imported displays while strengthening its manufacturing presence within India.
At the outset, the plant will concentrate on automotive displays for instrument clusters, infotainment systems and ******* pits.
Minda already produces clusters and other display-related components and intends to supply the displays made at the new facility to its own operations alongside external customers.
#clusters
3 months ago
Micron Technology (NASDAQ: MU) has been on a tear recently, and its run in this artificial intelligence (AI) era is about more than just selling more memory. Micron's run is about solving one of the quiet bottlenecks in artificial intelligence (AI) infrastructure, which is power, and that is where I think the story bleeds directly into utility stocks in a way the market has not fully priced in yet.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron's latest numbers show just how central it has become to AI. In the third quarter of its fiscal 2026, total revenue hit $41.5 billion, up 346% year over year and marking the fifth straight quarterly record. DRAM revenue alone was $31.3 billion, up 343% and now 76% of total sales, while data center revenue topped $25 billion on an annualized run rate north of $100 billion. ****** ysts have pushed estimates higher, largely on the back of AI-driven demand for high-bandwidth memory (HBM) and high-performance dynamic random-access memory (DRAM).
Underneath those numbers is a very specific technology angle. Micron's HBM3E memory, which sits right next to Nvidia's H200 GPUs and AMD's next-generation accelerators, delivers more than 1.2 terabytes per second of bandwidth while using about 30% less power than competing offerings. This means that AI clusters can either cut their electricity bills or pack more GPUs into the same power envelope, which is exactly what hyperscalers care about now that power availability has become a defining constraint for scaling AI.
Micron just raised its planned U.S. investment to more than $250 billion through 2035, aiming to put about 40% of its DRAM output on American soil to supply AI data centers and to support more than 90,000 jobs. Its solid-state drive (SSD) business is also framed in power terms now.
#power #billion #memory #NVIDIA
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron's latest numbers show just how central it has become to AI. In the third quarter of its fiscal 2026, total revenue hit $41.5 billion, up 346% year over year and marking the fifth straight quarterly record. DRAM revenue alone was $31.3 billion, up 343% and now 76% of total sales, while data center revenue topped $25 billion on an annualized run rate north of $100 billion. ****** ysts have pushed estimates higher, largely on the back of AI-driven demand for high-bandwidth memory (HBM) and high-performance dynamic random-access memory (DRAM).
Underneath those numbers is a very specific technology angle. Micron's HBM3E memory, which sits right next to Nvidia's H200 GPUs and AMD's next-generation accelerators, delivers more than 1.2 terabytes per second of bandwidth while using about 30% less power than competing offerings. This means that AI clusters can either cut their electricity bills or pack more GPUs into the same power envelope, which is exactly what hyperscalers care about now that power availability has become a defining constraint for scaling AI.
Micron just raised its planned U.S. investment to more than $250 billion through 2035, aiming to put about 40% of its DRAM output on American soil to supply AI data centers and to support more than 90,000 jobs. Its solid-state drive (SSD) business is also framed in power terms now.
#power #billion #memory #NVIDIA

3 months ago
Groq, a San Francisco-based AI infrastructure company, has raised $350m in a Series A round that values the company at $3.5bn.
The round was led by technology investment company Disruptive, with Nvidia expected to participate.
Alongside the $650m secured in June 2026, the latest fundraise takes Groq's recent funding to $1bn.
Completion of the Series A remains subject to customary closing conditions.
Groq aims to use the funding to expand its data centre network and support customers seeking access to medium and larger clusters of Nvidia accelerated computing for training and inference work.
#round
The round was led by technology investment company Disruptive, with Nvidia expected to participate.
Alongside the $650m secured in June 2026, the latest fundraise takes Groq's recent funding to $1bn.
Completion of the Series A remains subject to customary closing conditions.
Groq aims to use the funding to expand its data centre network and support customers seeking access to medium and larger clusters of Nvidia accelerated computing for training and inference work.
#round
3 months ago
The artificial intelligence (AI) memory supercycle has transformed semiconductor investing, fueled by explosive demand for high-bandwidth memory (HBM) and advanced DRAM to power hyperscalers' training clusters, inference deployments, and data center expansion.
Surging demand for graphics processing units (GPUs) and expanding agentic AI workloads are tightening memory chip supply -- driving higher average selling prices and record profits for manufacturers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology (NASDAQ: MU) and Sandisk (NASDAQ: SNDK) have emerged as two popular plays in the AI memory boom. As of Aug. 6, Micron stock has gained roughly 715% over the past year and about 212% year-to-date. Sandisk has posted even more dramatic gains, nearing 3,000% returns over the last 12 months and roughly 439% so far in 2026.
With that said, I think a stronger opportunity may be hiding in plain sight with South Korean rival SK Hynix (NASDAQ: SKHY). Let's dig into why.
#signal
Surging demand for graphics processing units (GPUs) and expanding agentic AI workloads are tightening memory chip supply -- driving higher average selling prices and record profits for manufacturers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Micron Technology (NASDAQ: MU) and Sandisk (NASDAQ: SNDK) have emerged as two popular plays in the AI memory boom. As of Aug. 6, Micron stock has gained roughly 715% over the past year and about 212% year-to-date. Sandisk has posted even more dramatic gains, nearing 3,000% returns over the last 12 months and roughly 439% so far in 2026.
With that said, I think a stronger opportunity may be hiding in plain sight with South Korean rival SK Hynix (NASDAQ: SKHY). Let's dig into why.
#signal


3 months ago
Oracle's (NYSE: ORCL) stock has rallied 27% over the past two weeks. Let's see what catalysts drove its stock higher, and if it can maintain its momentum over the next few months.
The biggest catalyst for Oracle's stock was the expansion of its partnership with Alphabet's (NASDAQ: GOOG) (NASDAQ: GOOGL) Google on July 30. Google will integrate its advanced Gemini AI models into Oracle's AI Agent Studio, enabling Oracle's Cloud Infrastructure (OCI) customers to build and deploy AI agents with Google's AI software.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
OCI has been Oracle's primary growth engine over the past year. In fiscal 2026 (which ended on May 31), its cloud infrastructure revenue surged 77% to $18.1 billion, accounting for 27% of its top line, as more companies used its high-peformance GPU clusters to power AI applications.
OCI is much smaller than Amazon (NASDAQ: AMZN) Web Services (AWS), Microsoft (NASDAQ: MSFT) Azure, and Google Cloud, but it integrates its services into those larger cloud infrastructure platforms so that its enterprise customers can run their workloads seamlessly across multiple cloud providers without being locked into a single ecosystem. Its expanded partnership with Google complements that strategy and increases its exposure to the AI market.
#cloud #Google #infrastructure #Stock
The biggest catalyst for Oracle's stock was the expansion of its partnership with Alphabet's (NASDAQ: GOOG) (NASDAQ: GOOGL) Google on July 30. Google will integrate its advanced Gemini AI models into Oracle's AI Agent Studio, enabling Oracle's Cloud Infrastructure (OCI) customers to build and deploy AI agents with Google's AI software.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
OCI has been Oracle's primary growth engine over the past year. In fiscal 2026 (which ended on May 31), its cloud infrastructure revenue surged 77% to $18.1 billion, accounting for 27% of its top line, as more companies used its high-peformance GPU clusters to power AI applications.
OCI is much smaller than Amazon (NASDAQ: AMZN) Web Services (AWS), Microsoft (NASDAQ: MSFT) Azure, and Google Cloud, but it integrates its services into those larger cloud infrastructure platforms so that its enterprise customers can run their workloads seamlessly across multiple cloud providers without being locked into a single ecosystem. Its expanded partnership with Google complements that strategy and increases its exposure to the AI market.
#cloud #Google #infrastructure #Stock

3 months ago
Emerald Wealth Partners, an independent ******* et and wealth management firm based in Zurich, released its Q2 2026 investor letter for the "Focused Equity Strategy." A copy of the letter can be downloaded here. The Strategy reported a 0.8% gross return for the second quarter of 2026. Equity markets rallied after the first quarter's Iran shock faded and oil prices reversed their spike, but the advance remained narrow and concentrated in cyclical semiconductor and memory stocks benefiting from supply constraints. The letter warned that investors were treating peak-cycle earnings as durable, while FOMO, IPO demand, and a US cyclically adjusted P/E ratio near 40 pointed to late-cycle market behavior. Long-term fundamentals are currently undervalued by the market, leading to underperformance in the strategy, notably due to the portfolio's avoidance of low-quality momentum-driven semiconductor stocks, which boosted the benchmark this quarter. It remains focused on enterprise infrastructure, digital platforms, custom silicon, and networking businesses that hold customer relationships, workflow data, distribution, and efficiency advantages, which could allow them to monetize AI rather than be displaced by it. Please review the Strategy's top five holdings for its key selections.
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted Broadcom Inc. (NASDAQ:AVGO). Broadcom Inc. (NASDAQ:AVGO), a leading American company that designs and develops various semiconductor devices and infrastructure software solutions, contributed 64 bps to the strategy's performance during the quarter. On August 4, 2026, Broadcom Inc. (NASDAQ:AVGO) closed at $418.16 per share. One-month return of Broadcom Inc. (NASDAQ:AVGO) was 7.58% and its shares gained 38.62% over the past 52 weeks. Broadcom Inc. (NASDAQ:AVGO) has a market capitalization of $1.99 trillion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding Broadcom Inc. (NASDAQ:AVGO) in its Q2 2026 investor letter:
"Broadcom Inc. (NASDAQ:AVGO) added 64 bps, its 22.3% share price climb helped by the news OpenAI has selected the company to design its custom inference chip. Broadcom is the dominant designer of custom AI silicon: it has long co-designed Google's Tensor Processing Units, which power Gemini and some of Anthropic's inference capacity through Google Cloud. Few companies possess the engineering depth to develop bespoke accelerators at hyperscale. AI spending is shifting from training models to running them, where custom chips deliver materially better performance per watt and a lower cost per token than Nvidia's general purpose GPUs. Under Hock Tan, one of the industry's ablest capital allocators, the company has ******* embled two further pillars that sit at the center of the AI buildout: It dominates the Ethernet switching silicon that interconnects AI clusters — content that grows with cluster size, whether those clusters run on Nvidia
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted Broadcom Inc. (NASDAQ:AVGO). Broadcom Inc. (NASDAQ:AVGO), a leading American company that designs and develops various semiconductor devices and infrastructure software solutions, contributed 64 bps to the strategy's performance during the quarter. On August 4, 2026, Broadcom Inc. (NASDAQ:AVGO) closed at $418.16 per share. One-month return of Broadcom Inc. (NASDAQ:AVGO) was 7.58% and its shares gained 38.62% over the past 52 weeks. Broadcom Inc. (NASDAQ:AVGO) has a market capitalization of $1.99 trillion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding Broadcom Inc. (NASDAQ:AVGO) in its Q2 2026 investor letter:
"Broadcom Inc. (NASDAQ:AVGO) added 64 bps, its 22.3% share price climb helped by the news OpenAI has selected the company to design its custom inference chip. Broadcom is the dominant designer of custom AI silicon: it has long co-designed Google's Tensor Processing Units, which power Gemini and some of Anthropic's inference capacity through Google Cloud. Few companies possess the engineering depth to develop bespoke accelerators at hyperscale. AI spending is shifting from training models to running them, where custom chips deliver materially better performance per watt and a lower cost per token than Nvidia's general purpose GPUs. Under Hock Tan, one of the industry's ablest capital allocators, the company has ******* embled two further pillars that sit at the center of the AI buildout: It dominates the Ethernet switching silicon that interconnects AI clusters — content that grows with cluster size, whether those clusters run on Nvidia

3 months ago
Emerald Wealth Partners, an independent ***** et and wealth management firm based in Zurich, released its Q2 2026 investor letter for the "Focused Equity Strategy." A copy of the letter can be downloaded here. The Strategy reported a 0.8% gross return for the second quarter of 2026. Equity markets rallied after the first quarter's Iran shock faded and oil prices reversed their spike, but the advance remained narrow and concentrated in cyclical semiconductor and memory stocks benefiting from supply constraints. The letter warned that investors were treating peak-cycle earnings as durable, while FOMO, IPO demand, and a US cyclically adjusted P/E ratio near 40 pointed to late-cycle market behavior. Long-term fundamentals are currently undervalued by the market, leading to underperformance in the strategy, notably due to the portfolio's avoidance of low-quality momentum-driven semiconductor stocks, which boosted the benchmark this quarter. It remains focused on enterprise infrastructure, digital platforms, custom silicon, and networking businesses that hold customer relationships, workflow data, distribution, and efficiency advantages, which could allow them to monetize AI rather than be displaced by it. Please review the Strategy's top five holdings for its key selections.
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted Broadcom Inc. (NASDAQ:AVGO). Broadcom Inc. (NASDAQ:AVGO), a leading American company that designs and develops various semiconductor devices and infrastructure software solutions, contributed 64 bps to the strategy's performance during the quarter. On August 4, 2026, Broadcom Inc. (NASDAQ:AVGO) closed at $418.16 per share. One-month return of Broadcom Inc. (NASDAQ:AVGO) was 7.58% and its shares gained 38.62% over the past 52 weeks. Broadcom Inc. (NASDAQ:AVGO) has a market capitalization of $1.99 trillion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding Broadcom Inc. (NASDAQ:AVGO) in its Q2 2026 investor letter:
"Broadcom Inc. (NASDAQ:AVGO) added 64 bps, its 22.3% share price climb helped by the news OpenAI has selected the company to design its custom inference chip. Broadcom is the dominant designer of custom AI silicon: it has long co-designed Google's Tensor Processing Units, which power Gemini and some of Anthropic's inference capacity through Google Cloud. Few companies possess the engineering depth to develop bespoke accelerators at hyperscale. AI spending is shifting from training models to running them, where custom chips deliver materially better performance per watt and a lower cost per token than Nvidia's general purpose GPUs. Under Hock Tan, one of the industry's ablest capital allocators, the company has ***** embled two further pillars that sit at the center of the AI buildout: It dominates the Ethernet switching silicon that interconnects AI clusters — content that grows with cluster size, whether those clusters run on Nvidia GPUs
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted Broadcom Inc. (NASDAQ:AVGO). Broadcom Inc. (NASDAQ:AVGO), a leading American company that designs and develops various semiconductor devices and infrastructure software solutions, contributed 64 bps to the strategy's performance during the quarter. On August 4, 2026, Broadcom Inc. (NASDAQ:AVGO) closed at $418.16 per share. One-month return of Broadcom Inc. (NASDAQ:AVGO) was 7.58% and its shares gained 38.62% over the past 52 weeks. Broadcom Inc. (NASDAQ:AVGO) has a market capitalization of $1.99 trillion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding Broadcom Inc. (NASDAQ:AVGO) in its Q2 2026 investor letter:
"Broadcom Inc. (NASDAQ:AVGO) added 64 bps, its 22.3% share price climb helped by the news OpenAI has selected the company to design its custom inference chip. Broadcom is the dominant designer of custom AI silicon: it has long co-designed Google's Tensor Processing Units, which power Gemini and some of Anthropic's inference capacity through Google Cloud. Few companies possess the engineering depth to develop bespoke accelerators at hyperscale. AI spending is shifting from training models to running them, where custom chips deliver materially better performance per watt and a lower cost per token than Nvidia's general purpose GPUs. Under Hock Tan, one of the industry's ablest capital allocators, the company has ***** embled two further pillars that sit at the center of the AI buildout: It dominates the Ethernet switching silicon that interconnects AI clusters — content that grows with cluster size, whether those clusters run on Nvidia GPUs
3 months ago
Corvex (NASDAQ:MOVE) secured a multi-year agreement to provide NVIDIA Blackwell GPU infrastructure, funding the expansion through debt, customer prepayments, and existing cash rather than issuing new shares.
Corvex (NASDAQ:MOVE) signed a multi-year agreement to provide NVIDIA Blackwell GPU clusters to a leading AI company.
The expansion is being funded without issuing additional equity, relying instead on debt financing, customer prepayments, and cash on hand.
The company deployed high-density, liquid-cooled GPU infrastructure in approximately two weeks within an existing air-cooled facility.
Revenue from the agreement has already been recognized as cluster deliveries progressed, with full run-rate revenue expected to begin midway through the current quarter.
#corvex #NVIDIA #multi #year
Corvex (NASDAQ:MOVE) signed a multi-year agreement to provide NVIDIA Blackwell GPU clusters to a leading AI company.
The expansion is being funded without issuing additional equity, relying instead on debt financing, customer prepayments, and cash on hand.
The company deployed high-density, liquid-cooled GPU infrastructure in approximately two weeks within an existing air-cooled facility.
Revenue from the agreement has already been recognized as cluster deliveries progressed, with full run-rate revenue expected to begin midway through the current quarter.
#corvex #NVIDIA #multi #year
3 months ago
Arete Research, an independent research firm, has upgraded Texas Instruments Incorporated (NASDAQ:TXN) to Buy from Neutral and lifted its price target to $405 from $303. This 34% raise in the PT comes days after the company posted a strong quarter – a surprise from an ***** og cyclical sector. Texas Instruments' Q2 revenue reached $5.46 billion, up 23% year-over-year, beating the $5.24 billion consensus. The company's EPS rose 52% year-over-year, beating the $1.92 Street estimate with $2.14. The most crucial piece of information tucked away in the report is the twofold growth in data center income.
According to an Arete Research ***** yst, the surging AI demand is anticipated to cause three years of ***** og semiconductor shortages. The ***** yst believes that Texas Instruments is well-positioned with respect to capacity, which should yield significant market share gains during this cycle. Arete projects revenue of approximately $34 billion with earnings of $17 per share by fiscal 2028. These structural tailwinds, discussed by the ***** yst, align with the company's operational and financial performance. Let's break them down.
The AI buildout faces one severe bottleneck – power shortage. And power is exactly what Texas Instruments, nicknamed by the market as "boring ***** og," sells. Hyperscalers are shifting toward 800-volt DC architectures to support denser GPU clusters. As a result, the need for ***** og content per rack increases. Texas Instruments serves this critical conversion layer through high-voltage gallium-nitride (GaN) power devices, real-time motor control, and sensing technology. Additionally, the company's March collaboration with Nvidia on humanoid robotics expands this portfolio. These demands fuel the quarterly ***** og revenue, which rose 26% to $4.37 billion. Texas Instruments is not relying on an industrial market recovery but is working on strengthening its position as a significant supplier for technology's most capital-intensive infrastructure cycle.
A more durable driver stems from timing rather than the AI narrative. Texas Instruments is completing a six-year, roughly $24 billion fab expansion that constrained free cash flow. Spending is dropping significantly. The 2026 capex projected at $2 billion to $3 billion stands in contrast to the comparatively high $4.55 billion in 2025. The fabs are complete, and revenue is recovering now, allowing management to anticipate free cash flow per share exceeding $8 in 2026, compared to $3.23 in 2025. Cash generation is tripling alongside declining capital expenditure, altering the investment profile investors have avoided during the build.
#instruments #analog #Research #cash
According to an Arete Research ***** yst, the surging AI demand is anticipated to cause three years of ***** og semiconductor shortages. The ***** yst believes that Texas Instruments is well-positioned with respect to capacity, which should yield significant market share gains during this cycle. Arete projects revenue of approximately $34 billion with earnings of $17 per share by fiscal 2028. These structural tailwinds, discussed by the ***** yst, align with the company's operational and financial performance. Let's break them down.
The AI buildout faces one severe bottleneck – power shortage. And power is exactly what Texas Instruments, nicknamed by the market as "boring ***** og," sells. Hyperscalers are shifting toward 800-volt DC architectures to support denser GPU clusters. As a result, the need for ***** og content per rack increases. Texas Instruments serves this critical conversion layer through high-voltage gallium-nitride (GaN) power devices, real-time motor control, and sensing technology. Additionally, the company's March collaboration with Nvidia on humanoid robotics expands this portfolio. These demands fuel the quarterly ***** og revenue, which rose 26% to $4.37 billion. Texas Instruments is not relying on an industrial market recovery but is working on strengthening its position as a significant supplier for technology's most capital-intensive infrastructure cycle.
A more durable driver stems from timing rather than the AI narrative. Texas Instruments is completing a six-year, roughly $24 billion fab expansion that constrained free cash flow. Spending is dropping significantly. The 2026 capex projected at $2 billion to $3 billion stands in contrast to the comparatively high $4.55 billion in 2025. The fabs are complete, and revenue is recovering now, allowing management to anticipate free cash flow per share exceeding $8 in 2026, compared to $3.23 in 2025. Cash generation is tripling alongside declining capital expenditure, altering the investment profile investors have avoided during the build.
#instruments #analog #Research #cash