
1 month ago
XRP ranks last for Q4 after the CLARITY Act's Senate failure removed every legislative catalyst and invalidated year-end targets built around the bill.
Ethereum leads the Q4 outlook as the only coin carrying a dated technical upgrade still on the calendar, edging out Bitcoin and crushing XRP.
Bitcoin reclaiming $80,000 before the November midterms is the single falsifiable trigger that tightens the base scenario for all three coins.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
The U.S. Senate voted 49-50 against advancing the CLARITY Act on September 15, falling eleven votes short of the 60 needed to end debate. The defeat leaves crypto's market-structure rules in the hands of the SEC and CFTC rather than Congress, at least for the remainder of 2026.
#senate #learn #september
1 month ago
Palantir Technologies (PLTR) trades near $172.56, and the options market has already drawn the year ahead in dollars. The one-year band runs from $96.77 at the floor to $307.69 at the ceiling. That is not a forecast. It is the size of the uncertainty you are holding, and it raises a question about position size rather than direction.
What You Are Actually Risking On A Palantir Position
That range is where the options market puts roughly a two-in-three chance over the twelve months ahead. On a $10,000 holding, that is about $4,400 at risk down to the floor. Up to the ceiling there is about $7,800 of room. The two sides are not the same size because a stock cannot fall below zero but can rise without limit.
Outside that band sit two tails: roughly a one-in-six chance the stock finishes above the ceiling, and the same chance it finishes below the floor. So $96.77 is the edge of the ordinary, not the bottom of it.
Palantir Has Been Moving More Than Its Options Imply
#options #position

1 month ago
Forward Industries (NASDAQ: $FWDI) has raised its takeover offer for SkyAI (NASDAQ: $SKYA), proposing a deal that would value the Solana (CRYPTO: $SOL) treasury company at a 50% premium to its latest closing price.
Forward said Tuesday that it had delivered an updated non-binding proposal to acquire all outstanding SkyAI common stock. Under the new terms, SkyAI shareholders would receive the value of 0.306 shares of Forward Industries for each SkyAI share, with investors able to choose cash, Forward shares, or a combination of both.
Based on Forward's $6.95 closing price on Monday, the proposal values each SkyAI share at about $2.13, compared with SkyAI's $1.42 close. Forward has asked SkyAI's board to respond by September 25. The proposal remains subject to regulatory approvals and a shareholder vote.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#skyai #proposal #price
2 months ago
Americans ages 65–74 have a median net worth of $410,000, the highest of any age group.
About 76% own a home and 51% have a retirement account, making home equity and savings the biggest drivers of wealth at this stage.
Debt is less common but still present, with roughly 65% carrying some debt and about a third holding a credit card balance.
Americans ages 65–74 are typically in retirement or just a few years removed from full-time work, making this a key moment to ******* s how wealth looks once paychecks have largely stopped. For many households, this stage represents the high-water mark for net worth before savings begin to be drawn down.
According to the Federal Reserve's latest Survey of Consumer Finances, the median net worth for households in this age range is $410,000, the highest of any age group in the U.S.
#americans #highest


2 months ago
I asked why ICE World Sugar futures were stuck in neutral in a July 16, 2026, Barchart article, concluding with the following:
Historically, sugar can be a highly volatile soft commodity, but the current price action is tame. Given the uncertainty of energy prices, sugar could experience significant volatility. A break of 13.34 or 16.10 could trigger a substantial move in the soft commodity that is food and fuel.
The Outlook for More Global Supply Weighs on Coffee Prices
Cocoa Prices Retreat as Supply Fears Abate
Sugar Prices Fall on Speculation India Will Import Less
#prices #soft #World #given


2 months ago
Meta (META) agreed to settle a social media addiction case with a group of state attorneys general on Wednesday, putting an end to the trial in its second week. The stock initially popped on the news before paring gains.
The case revolved around allegations from 29 states that Instagram and Facebook developed products to hook young users on the platforms and harvested the data of children under 13 to their benefit.
According to court filings, Meta denied wrongdoing and agreed to pay up to $16.68 billion.
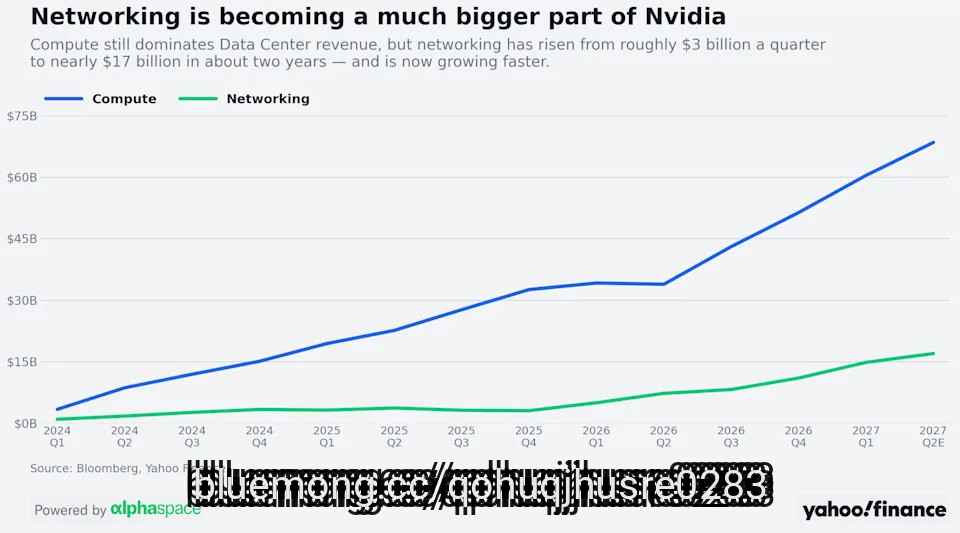
Meta isn't the only tech giant making headlines. Another key moment for Wall Street is due to arrive after the bell on Wednesday: Nvidia's (NVDA) second quarter earnings.
While its Big Tech peers reported their results nearly a month ago, Nvidia is finally giving us the lowdown on its latest quarter when it reports Q2 earnings after the close on Wednesday.
#Tech #agreed #earnings #Facebook
2 months ago
On August 13, Stratasys (NASDAQ:SSYS) held its second-quarter earnings call, and the headline number was consumables revenue hitting a record $66.3 million. For a company trying to prove it has moved beyond selling prototyping machines into recurring, production-grade manufacturing, that record matters more than the top line itself. But underneath the record sat a cash flow warning that investors will want to weigh carefully.
Aerospace and defense is Stratasys's largest business, and it grew 17% year over year in the second quarter. Management pointed to expanding adoption across the U.S. Air Force, where the company's F900 system is certified for flightworthy production parts, describing the orders as increasing in volume across the Air Force's sustainment enterprise rather than one-time purchases. Once a part is qualified on a Stratasys platform, switching suppliers becomes costly, which is the basis for calling this demand structural. Stratasys Direct, the company's parts manufacturing arm, grew 12.1% year over year, fueled by defense technology customers building drones and munitions.
The quarter also delivered two large multiyear systems deals. Quickparts expanded its relationship with Stratasys by purchasing 12 Neo 800-plus systems on top of six units it already owned, with three of the new systems placed in Europe. FAW Group, one of China's largest auto manufacturers, signed for 12 F900 systems by year-end, with two shipped in the second quarter, adding to five F900s and eight other Stratasys machines it already runs to make interior parts like armrests and panels. Stratasys was also awarded a two-year, $7.8 million program through the 2026 America Makes OIB Modernization Challenge to develop monitoring technology for its F900 and F3300 platforms. Layered on top is the pending $42.5 million cash acquisition of MarkForged, whose continuous carbon fiber technology generated about $70 million in revenue in 2025 and which management expects to add positively to EBITDA within a year of closing.
System revenue fell to $26.4 million from $30.6 million a year earlier, meaning machine sales are shrinking even as the recurring materials business grows. Gross margin slipped too, with non-GAAP gross margin at 47.2% versus 47.7% a year ago, which the company attributed largely to a stronger Israeli shekel raising costs incurred in that currency. GAAP net loss widened slightly to $16.9 million, compared to $16.7 million a year ago, though GAAP loss per diluted share improved slightly to $0.19 from $0.20.
#stratasys #gaap

2 months ago
China flooded the world with cheap solar panels a decade ago, driving Western competitors out of business. It did the same with electric vehicles, prompting tariffs from Washington and Brussels. In 2025, the pattern repeated with batteries. Chinese manufacturers who had built twice as many factories as the world needed slashed prices to keep them running, pushing stationary storage packs down to $70 per kilowatt-hour, 45% cheaper than the year before. The decline was steep enough to reshape what power companies pay for electricity during the most expensive hours of the day.
Chinese overbuilding was the biggest single force behind the price collapse, but it wasn't the only one. A shift toward cheaper battery chemistry, a crash in lithium prices, and a decades-long accumulation of manufacturing improvements all hit at the same time, each amplifying the others. On its own, any one of those forces would have pushed prices down gradually. Their convergence is what turned a steady decline into a collapse.
Cheaper batteries are good news for electricity costs and for the climate. But the conditions that made them possible are unwinding. Lithium prices have already rebounded, and the tariffs designed to counter China's trade practices are adding new costs of their own.
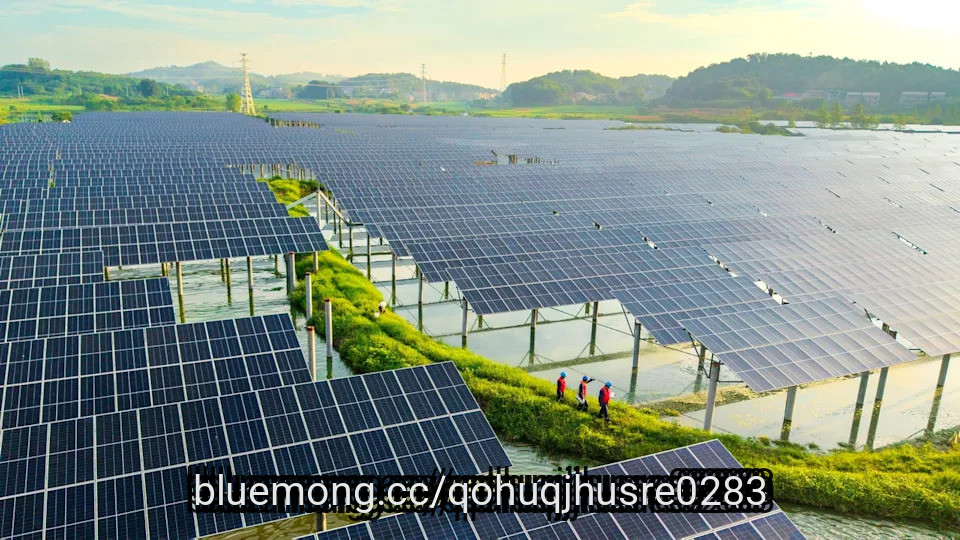
Chinese battery manufacturers spent the early 2020s building factories at a pace that ***** umed electric vehicle demand would keep surging. It worked for a while. By 2024, China produced enough battery cells — the basic units that store electricity and power electric vehicles — for every car sold on the planet that year. But global manufacturing capacity far outstripped what anyone needed. At roughly 2,600 gigawatt-hours, the world's factories could supply every battery the market demanded and still have enough idle capacity to outfit nearly every home in America with its own storage system.
Even as the surplus became apparent, manufacturers kept adding capacity through 2025. The world's battery factories nearly doubled their capacity to more than 4,000 gigawatt-hours of cells a year — more than four times what the market actually bought — with China accounting for more than 80% of the total.
#battery #capacity #manufacturers
2 months ago
In the AI infrastructure boom, Nvidia (NASDAQ: NVDA) sells the brains of the AI factory while Micron (NASDAQ: MU) supplies the memory that keeps those brains fed with data, and that difference shapes which stock will benefit more from the current phase of this historic spending wave. In my view, Nvidia is the clearer winner because a greater fraction of every dollar of hyperscaler capex is spent on its accelerators than goes toward memory chips of the type that Micron manufactures. Micron still looks like a powerful second-derivative play, since AI servers can't be built without the high-bandwidth memory it supplies.
The money flow this year is wildly high. The hyperscalers themselves say they plan to spend hundreds of billions of dollars in 2026 alone to expand AI data centers, GPU clusters, networking, and power infrastructure, a sharp jump from already elevated 2025 levels. One estimate puts combined capex for Amazon, Microsoft, Alphabet, and Meta Platforms at around $700 billion, with roughly two-thirds of that directed toward AI infrastructure rather than traditional cloud. Within that budget, the largest line item is the AI server stack itself, where accelerated servers built around high-end GPUs drive most of the component revenue growth. And of course, the hyperscalers are not the only tech players building data centers now.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nvidia sits directly in the center of this buying spree. Its data center business now revolves around entire racks of AI computing power, not just single chips. Systems like the GB200 Grace Blackwell Superchip and GB200 NVL72 tie together dozens of CPUs and GPUs into logical accelerators that can train and serve trillion-parameter models more efficiently than the prior-generation Hopper platforms. Hyperscalers are lining up to deploy these systems in their AI clouds, with massive companies committing to offer GB200 NVL72 instances to customers who want to run large language models at scale. All this sounds dense, but the basic point is that Nvidia products are in steady demand.
Nvidia's roadmap also continues to push the limits of performance and memory. Architectures like Blackwell and its new Vera Rubin processors combine vast computing throughput with enormous pools of high bandwidth memory (HBM), turning racks into "AI factories." That keeps Nvidia at the absolute center of procurement decisions when cloud providers are calculating how many clusters they will need to handle their training and inferencing workloads in 2026 and beyond.
#memory #high #signal

3 months ago
The XLU or the Utilities ETF looks like it's going to jump a bit early based on pre-market trading. So therefore, I think we've got a situation where traders are looking at this through the prism of whether or not we can pick up a little bit of momentum. The market is one that typically is a little bit of a safety play, so this is interesting to see how we have bounced off this support.
And with that being the case, if we can break from here, we'll test the 200-day EMA first and possibly try to grind our way back to the top of the range if momentum can pick up. For myself, I actually like the utilities as a small part of a portfolio, almost like a little bit of insurance. It looks like we are at least trying to defend the range.
The XLF, or financials, looks like it is going to gap higher during the day and just continue to rise. This has been a nice channel for some time and a nice 45-degree angle. I don't see anything on this chart personally that changes that attitude. Slow and steady is the way this one goes as it goes higher over the last couple of months, and it looks like we're going to get more of the same here on Wednesday so far.
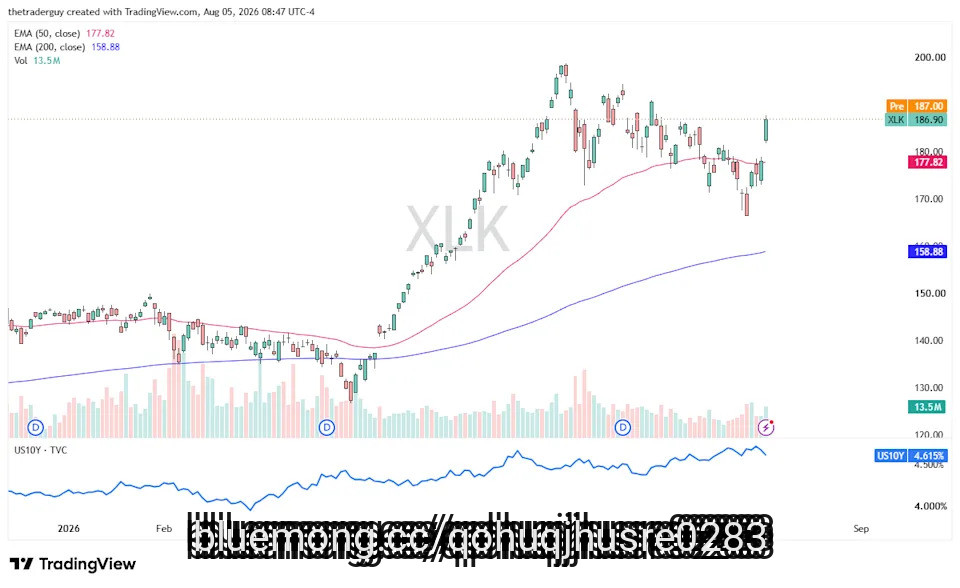
XLK, now this is the technology sector. It looks like it's going to open up about 10 cents above where it closed, but it's worth noting that on Tuesday it just launched. And with the earnings season going the way it is and the sudden reemergence of certain high-flying technology companies in the last couple of days, this does make sense.
Certainly looks like it's trying to continue the upward momentum. If rates continue to drop, historically speaking, that's good for tech companies; we'll have to see if that plays out. Certainly, a healthy-looking chart.
#like #going #certainly


3 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Hotchkis & Wiley Mid-Cap Value Fund." A copy of the letter can be downloaded here. Equity markets posted strong returns in the second quarter of 2026, with the Russell Midcap Index rising 13.8% and the Russell Midcap Value Index returning 13.4%, despite concerns about inflation, a hawkish Federal Reserve, and rising oil prices due to the Iran conflict. Narrow market leadership was evident, particularly semiconductor stocks and other stocks in the AI sector, which saw returns exceeding 100%. The Firm favors quality businesses with attractive valuations, believing that fears regarding AI's impact are overstated. The Hotchkis & Wiley Mid-Cap Value Fund lagged the Russell Midcap Value Index, achieving a 4.74% return in the second quarter, primarily due to underperformance in technology and energy sectors, while stock selection in healthcare contributed positively. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Hotchkis & Wiley Mid-Cap Value Fund highlighted Marriott Vacations Worldwide Corporation (NYSE:VAC). Marriott Vacations Worldwide Corporation (NYSE:VAC), a leading vacation and timeshare ownership company, delivered strong performance during the quarter. On August 3, 2026, Marriott Vacations Worldwide Corporation (NYSE:VAC) closed at $97.40 per share, reflecting a market capitalization of $3.34 billion. Marriott Vacations Worldwide Corporation (NYSE:VAC) posted a one-month return of -1.96%, while its shares gained 33.46% over the past 52 weeks.
Hotchkis & Wiley Mid-Cap Value Fund stated the following regarding Marriott Vacations Worldwide Corporation (NYSE:VAC) in its Q2 2026 investor letter:
"Marriott Vacations Worldwide Corporation (NYSE:VAC) is one of the largest timeshare operators in the US, building, selling, financing, and managing upper-upscale and luxury resorts under the Marriott, Westin, Ritz-Carlton, and Hyatt brands, alongside a high-margin exchange business. We view it as a misunderstood, good-quality company whose branded network, affluent customer base with ~$1.5 million average net worth, and recurring financing and fee streams help insulate it from the cyclicality of travel. The stock outperformed this quarter as results topped low Street expectations, management maintained full-year guidance while raising its contract-sales outlook, and free cash flow generation remained strong."
#hotchkis #quarter

3 months ago
AMLP's C-corp structure forces the fund to pay corporate taxes on gains, and this erodes its advertised 7 to 8% yield before distributions ever reach investors.
Over ten years, MLPX returned 212% and ENFR returned 208% versus AMLP's 97%, thanks to RIC structures that avoid corporate tax entirely.
Are you ahead, or behind on retirement? SmartAsset's free tool can match you with a financial advisor in minutes to help you answer that today. Each advisor has been carefully vetted, and must act in your best interests. Don't waste another minute; learn more here.
If you own the Alerian MLP ETF (NYSEARCA:AMLP), you are paying both a fund manager and a corporate tax bill that the marketing materials rarely draw attention to. AMLP is structured as a C-corporation, which means the fund itself pays federal and state income tax on the gains inside your portfolio before you ever see them.
Start with the sticker fee. AMLP carries a 0.85% expense ratio, or about $85 per year on every $10,000 invested. Some third-party trackers cite an all-in figure closer to 1.01% once operating costs are folded in. Either way, it is expensive for what is essentially a rules-based basket of midstream pipeline partnerships.
#amlp #fund #gains #returned

3 months ago
By Amanda Cooper
July 29 (Reuters) - Shares in companies driving the AI boom have been under pressure for weeks. Now their bonds are coming under strain too, pushing up the cost of insuring debt issued by companies such as Oracle, Nvidia and Apple against default.
The move reflects growing concern among investors about when the billions of dollars being poured into artificial intelligence will generate returns.
Technology companies have raised billions of dollars in debt this year to fund AI investments, with firms including Nvidia tapping bond markets for the first time. But the cost of the AI build-out is so high that even blockbuster earnings have failed to reassure some investors about the durability of future returns.
Demand for AI-linked credit default swaps (CDS), a form of insurance against default that gained prominence during the 2008 financial crisis, has surged.
#Companies #cost #billions #dollars


3 months ago
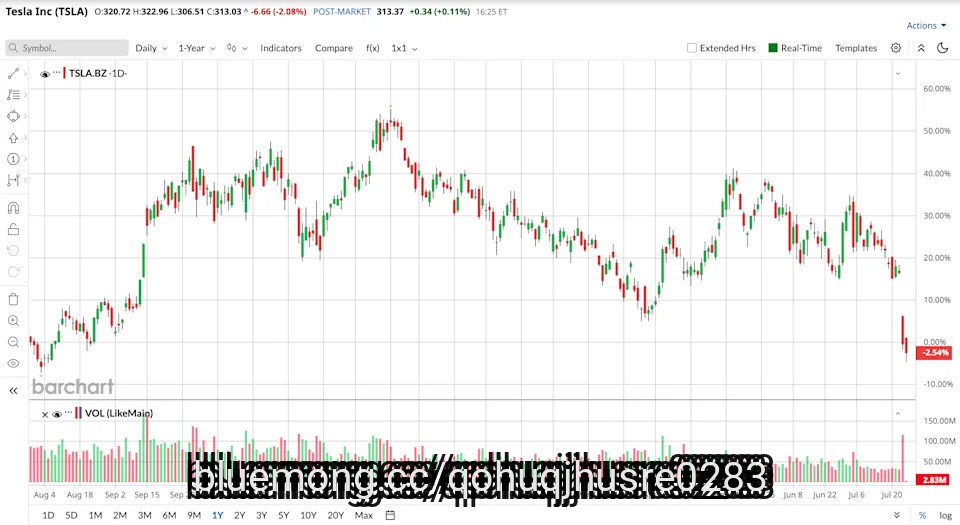
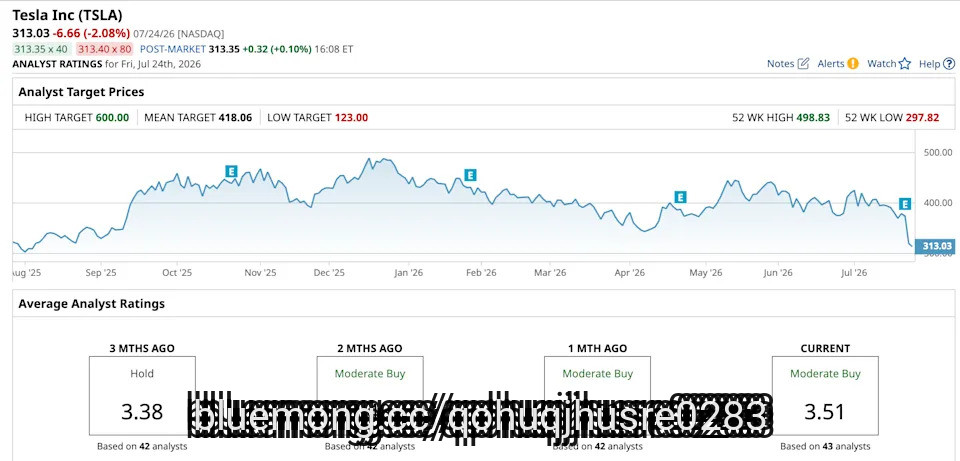
Elon Musk gave Tesla (TSLA) investors a clearer picture of a key supply issue on July 22. He said Micron (MU) recently gave Tesla a "very significant allocation" of memory chips on "reasonable terms," and added that Micron is "making room for Tesla in the years to come."
Musk also said memory prices across the industry are "pretty insane" and were "the biggest price jump in anything I've ever seen." That matters because this looks like more than a short-term fix.
Dear ***** eX Stock Fans, Mark Your Calendars for August 6
Amazon Stock Just Hit a Major Hurdle Ahead of Earnings
What a Major Anthropic Chip Deal Really Means for AMD Stock
#tesla #Stock #major