

2 days ago
ExxonMobil Holdings Corporation (NYSE:XOM) agreed to increase its Papua LNG interest from 28.7% to 34.1% and ***** ume operatorship, as disclosed on September 7. The proposed ownership percentages reflect Papua New Guinea's state participation rights.
Papua LNG targets a fourth-quarter 2026 final investment decision, or FID. Santos Limited (ASX:STO) disclosed FID as a closing condition for its own stake acquisition; the operatorship announcement did not specify an equivalent condition.
TotalEnergies SE (NYSE:TTE) said redesign and contractor rebidding had reduced estimated development spending by nearly $4 billion since 2024 to approximately $14 billion. The project would produce 5.6 million tonnes of liquefied natural gas annually. The question is whether that smaller budget can support attractive returns through construction and an uncertain LNG market.
ExxonMobil Holdings Corporation (NYSE:XOM) already operates neighboring PNG LNG. Combining operatorship could improve coordination during construction and operations, including the redesigned handling of upstream condensate. That gives the proposed efficiency gains a practical basis in existing infrastructure and local experience.
The cost reduction is substantial. Mechanically, nearly $4 billion off an approximately $18 billion previous estimate represents about 22%. For ExxonMobil Holdings Corporation (NYSE:XOM), lower development spending would reduce the capital required to generate each future dollar of project cash flow, ***** uming production and operating economics hold.
#holdings #operatorship
Papua LNG targets a fourth-quarter 2026 final investment decision, or FID. Santos Limited (ASX:STO) disclosed FID as a closing condition for its own stake acquisition; the operatorship announcement did not specify an equivalent condition.
TotalEnergies SE (NYSE:TTE) said redesign and contractor rebidding had reduced estimated development spending by nearly $4 billion since 2024 to approximately $14 billion. The project would produce 5.6 million tonnes of liquefied natural gas annually. The question is whether that smaller budget can support attractive returns through construction and an uncertain LNG market.
ExxonMobil Holdings Corporation (NYSE:XOM) already operates neighboring PNG LNG. Combining operatorship could improve coordination during construction and operations, including the redesigned handling of upstream condensate. That gives the proposed efficiency gains a practical basis in existing infrastructure and local experience.
The cost reduction is substantial. Mechanically, nearly $4 billion off an approximately $18 billion previous estimate represents about 22%. For ExxonMobil Holdings Corporation (NYSE:XOM), lower development spending would reduce the capital required to generate each future dollar of project cash flow, ***** uming production and operating economics hold.
#holdings #operatorship

2 days ago
WASHINGTON, Sept 11 (Reuters) - The contractor responsible for renovating the Lincoln Memorial Reflecting Pool in Washington told U.S. President Donald Trump's administration that errors in its work and flaws in the repair plan caused the pool's liner to peel and break loose, the New York Times reported on Friday, citing documents it reviewed.
Trump has repeatedly blamed problems with the newly renovated pool, including its new blue paint peeling off, on vandalism.
According to the New York Times, citing the documents, Atlantic Industrial Coatings found problems in the design and execution of the renovation.
Workers did not spray enough primer in some areas, the contractor said in the cited documents, and layers of the liner included incompatible chemicals. The bottom layer blistered and loosened as the chemical on top reached a hotter temperature than the one underneath could withstand, the New York Times said.
The documents include the contractor's reports to the government and daily progress updates from the National Park Service over the past two months, the New York Times said.
#sept
Trump has repeatedly blamed problems with the newly renovated pool, including its new blue paint peeling off, on vandalism.
According to the New York Times, citing the documents, Atlantic Industrial Coatings found problems in the design and execution of the renovation.
Workers did not spray enough primer in some areas, the contractor said in the cited documents, and layers of the liner included incompatible chemicals. The bottom layer blistered and loosened as the chemical on top reached a hotter temperature than the one underneath could withstand, the New York Times said.
The documents include the contractor's reports to the government and daily progress updates from the National Park Service over the past two months, the New York Times said.
#sept

3 days ago
Quanta Services, Inc. (PWR) is a leading specialty infrastructure contractor that designs, builds, upgrades, repairs, and maintains critical energy and communications infrastructure across the U.S., Canada, Australia, and select international markets.
With a market cap of $96.1 billion, Quanta Services fits squarely within the large-cap stock category. It is particularly well positioned to benefit from the surging demand for electricity and grid investment. Data-center expansion, AI infrastructure, manufacturing reshoring, electrification, renewable-energy buildouts, and grid modernization are all driving demand for the infrastructure Quanta provides.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#energy
With a market cap of $96.1 billion, Quanta Services fits squarely within the large-cap stock category. It is particularly well positioned to benefit from the surging demand for electricity and grid investment. Data-center expansion, AI infrastructure, manufacturing reshoring, electrification, renewable-energy buildouts, and grid modernization are all driving demand for the infrastructure Quanta provides.
'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History
What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments
RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for ******* e
#energy



3 days ago
Wall Street has bid up defense contractors on geopolitical tensions alongside expanded missile-defense funding, but Northrop Grumman Corporation (NYSE:NOC) remains an outlier. On September 4, 2026, the company secured a $508.5 million Missile Defense Agency contract for ICBM and IRBM target flight-test support running through 2035. The non-competitive contract follows the $3 billion (approx.) in framework agreements to expand solid-rocket-motor production for PAC-3 and THAAD interceptors. Despite these bookings, stock slipped 2.5% to $515. The stock is trading near 16 times earnings and 33% below its peak, making Northrop one of the lowest-multiple prime defense contractors.
Northrop is one of the largest-cap defense contractors with exposure to Golden Dome through ******* e sensors and interceptors, while the Sentinel ICBM and the B-21 bomber provide additional exposure to broader U.S. strategic modernization. The recent bookings back that up: the $508.5 million MDA award, the ~$3 billion PAC-3 and THAAD agreements that will double and triple solid-rocket-motor capacity, and $1.4 billion of IBCS-related U.S. and Polish air-and-missile-defense awards announced in 2025. The latest MDA contract includes cost-plus, cost-reimbursable, and fixed-price-incentive elements, which reduce some financial exposure compared with purely fixed-price development work. Long-term missile-shield funding, however, remains tied to both political and defense bets. Legislative approval introduces timing risk, but the bull thesis is already working.
Execution problems explain the valuation discount. The Sentinel ICBM program triggered a critical Nunn-McCurdy breach after projected costs rose 81% to roughly $141 billion, forcing a Pentagon program restructuring. Concurrently, low-rate initial production on the B-21 bomber generated approximately $2 billion in pre-tax charges on fixed-price commitments. Management must demonstrate that these losses have ceased. Till then, multiple expansion will remain limited. Lockheed trades at roughly 19 times earnings compared with Northrop at about 16 times.
Institutional positioning does not point to aggressiveness in short trades. Our Insider Monkey database tracked 59 hedge funds holding NOC in the second quarter of 2026, compared to 62 in the first quarter. Short interest sits at 1.7% of the float, representing a low number of bets against the stock. Paired with -0.11 beta and a 1.9% dividend yield, the stock offers portfolio diversification at a discounted entry multiple.
#northrop
Northrop is one of the largest-cap defense contractors with exposure to Golden Dome through ******* e sensors and interceptors, while the Sentinel ICBM and the B-21 bomber provide additional exposure to broader U.S. strategic modernization. The recent bookings back that up: the $508.5 million MDA award, the ~$3 billion PAC-3 and THAAD agreements that will double and triple solid-rocket-motor capacity, and $1.4 billion of IBCS-related U.S. and Polish air-and-missile-defense awards announced in 2025. The latest MDA contract includes cost-plus, cost-reimbursable, and fixed-price-incentive elements, which reduce some financial exposure compared with purely fixed-price development work. Long-term missile-shield funding, however, remains tied to both political and defense bets. Legislative approval introduces timing risk, but the bull thesis is already working.
Execution problems explain the valuation discount. The Sentinel ICBM program triggered a critical Nunn-McCurdy breach after projected costs rose 81% to roughly $141 billion, forcing a Pentagon program restructuring. Concurrently, low-rate initial production on the B-21 bomber generated approximately $2 billion in pre-tax charges on fixed-price commitments. Management must demonstrate that these losses have ceased. Till then, multiple expansion will remain limited. Lockheed trades at roughly 19 times earnings compared with Northrop at about 16 times.
Institutional positioning does not point to aggressiveness in short trades. Our Insider Monkey database tracked 59 hedge funds holding NOC in the second quarter of 2026, compared to 62 in the first quarter. Short interest sits at 1.7% of the float, representing a low number of bets against the stock. Paired with -0.11 beta and a 1.9% dividend yield, the stock offers portfolio diversification at a discounted entry multiple.
#northrop

4 days ago
Queen Máxima brought her signature flair to a working engagement in the Netherlands on Thursday, stepping out in an autumn-ready printed dress for a symposium focused on the future of health care.
You may also like
Queen Letizia, Queen Máxima and other royals wore pearls to King Harald's funeral: The symbolic reason why
Queen Máxima gets behind the wheel of a tractor in glamorous royal look
Princess Ariane begins surprising new chapter that follows in late royal's footsteps
#brought
You may also like
Queen Letizia, Queen Máxima and other royals wore pearls to King Harald's funeral: The symbolic reason why
Queen Máxima gets behind the wheel of a tractor in glamorous royal look
Princess Ariane begins surprising new chapter that follows in late royal's footsteps
#brought


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

6 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like CNH Industrial N.V. (NYSE:CNH). CNH Industrial N.V. manufactures and sells specialized machines and services for the farming and construction industries. The one-month return of CNH Industrial N.V. (NYSE:CNH) was 30.96% while its shares traded between $9.00 and $14.46 over the last 52 weeks. On September 7, 2026, CNH Industrial N.V. (NYSE:CNH) stock closed at approximately $14.40 per share, with a market capitalization of about $22.02 billion.
Moerus Worldwide Fund stated the following regarding CNH Industrial N.V. (NYSE:CNH) in its Q2 2026 investor letter:
"We also initiated a position in shares of CNH Industrial N.V. (NYSE:CNH) in H1. CNH Industrial manufactures and sells specialized machines and services for the farming and construction industries under the Case IH and New Holland brands. The production of high horsepower agricultural equipment (i.e. tractors, combines, etc.) for professional farmers is an oligopoly, of which CNH is the second largest original equipment manufacturer behind John Deere."
#NYSE #investor #letter
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like CNH Industrial N.V. (NYSE:CNH). CNH Industrial N.V. manufactures and sells specialized machines and services for the farming and construction industries. The one-month return of CNH Industrial N.V. (NYSE:CNH) was 30.96% while its shares traded between $9.00 and $14.46 over the last 52 weeks. On September 7, 2026, CNH Industrial N.V. (NYSE:CNH) stock closed at approximately $14.40 per share, with a market capitalization of about $22.02 billion.
Moerus Worldwide Fund stated the following regarding CNH Industrial N.V. (NYSE:CNH) in its Q2 2026 investor letter:
"We also initiated a position in shares of CNH Industrial N.V. (NYSE:CNH) in H1. CNH Industrial manufactures and sells specialized machines and services for the farming and construction industries under the Case IH and New Holland brands. The production of high horsepower agricultural equipment (i.e. tractors, combines, etc.) for professional farmers is an oligopoly, of which CNH is the second largest original equipment manufacturer behind John Deere."
#NYSE #investor #letter

6 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and **** ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Douglas Elliman Inc. (NYSE:DOUG). Douglas Elliman Inc. is a residential real estate brokerage company with a strong presence in high-end U.S. housing markets. The one-month return of Douglas Elliman Inc. (NYSE:DOUG) was -2.19% while its shares traded between $1.5300 and $3.1900 over the last 52 weeks. On September 7, 2026, Douglas Elliman Inc. (NYSE:DOUG) stock closed at approximately $1.8100 per share, with a market capitalization of about $162.69 million.
Moerus Worldwide Fund stated the following regarding Douglas Elliman Inc. (NYSE:DOUG) in its Q2 2026 investor letter:
"Outside of Materials, other meaningful detractors from H1 came from different industries but were similarly impacted by various concerns related to the war and its effects in various areas, including real estate activity (Douglas Elliman Inc. (NYSE:DOUG)) given heightened inflation concerns and increased interest rate expectations. We would argue that the current valuations of each of these holdings are unusually modest, belying the formidable, leading presence that each boasts in its respective markets."
#douglas #NYSE
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Douglas Elliman Inc. (NYSE:DOUG). Douglas Elliman Inc. is a residential real estate brokerage company with a strong presence in high-end U.S. housing markets. The one-month return of Douglas Elliman Inc. (NYSE:DOUG) was -2.19% while its shares traded between $1.5300 and $3.1900 over the last 52 weeks. On September 7, 2026, Douglas Elliman Inc. (NYSE:DOUG) stock closed at approximately $1.8100 per share, with a market capitalization of about $162.69 million.
Moerus Worldwide Fund stated the following regarding Douglas Elliman Inc. (NYSE:DOUG) in its Q2 2026 investor letter:
"Outside of Materials, other meaningful detractors from H1 came from different industries but were similarly impacted by various concerns related to the war and its effects in various areas, including real estate activity (Douglas Elliman Inc. (NYSE:DOUG)) given heightened inflation concerns and increased interest rate expectations. We would argue that the current valuations of each of these holdings are unusually modest, belying the formidable, leading presence that each boasts in its respective markets."
#douglas #NYSE


6 days ago
Moerus Capital Management LLC, an investment management firm, recently released its "Worldwide Fund " second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The fund navigated a highly bifurcated investment environment in the second quarter of 2026, as investor enthusiasm for artificial intelligence and technology drove a sharp rally in growth stocks while capital moved away from more traditional, value-oriented areas. The Fund's Institutional Class returned 0.14% in Q2, compared with 14.49% for the MSCI ACWI ex USA and 14.93% for the MSCI ACWI, while its first-half return stood at 5.37%, versus 13.69% and 11.25%, respectively, for the two benchmarks. The relative underperformance was primarily driven by the Fund's limited exposure to Information Technology as semiconductor and AI-related stocks surged, while its Energy holdings also gave back some earlier gains as oil prices declined; however, the Fund benefited from several energy-related investments during the first half. Looking ahead, Moerus views the extreme gap between expensive AI-focused areas and neglected parts of the market as an opportunity, maintaining its long-term deep-value approach of investing in unpopular businesses and ******* ets at significant discounts to intrinsic value and using market volatility to identify potentially attractive investments. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Transocean Ltd. (NYSE:RIG) while discussing its investment in Valaris. Transocean Ltd. is an offshore drilling contractor. Moerus discussed the company in connection with its agreement to acquire Valaris in an all-stock transaction, which it said helped surface significant latent value in Valaris. The one-month return of Transocean Ltd. (NYSE:RIG) was 2.53% while its shares traded between $3.01 and $7.66 over the last 52 weeks. On September 7, 2026, Transocean Ltd. (NYSE:RIG) stock closed at approximately $5.85 per share, with a market capitalization of about $6.56 billion.
Moerus Worldwide Fund stated the following regarding Transocean Ltd. (NYSE:RIG) in its Q2 2026 investor letter:
"Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean Ltd. (NYSE:RIG) in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock)."
#valaris
In its second-quarter 2026 investor letter, Moerus Worldwide Fund highlighted stocks like Transocean Ltd. (NYSE:RIG) while discussing its investment in Valaris. Transocean Ltd. is an offshore drilling contractor. Moerus discussed the company in connection with its agreement to acquire Valaris in an all-stock transaction, which it said helped surface significant latent value in Valaris. The one-month return of Transocean Ltd. (NYSE:RIG) was 2.53% while its shares traded between $3.01 and $7.66 over the last 52 weeks. On September 7, 2026, Transocean Ltd. (NYSE:RIG) stock closed at approximately $5.85 per share, with a market capitalization of about $6.56 billion.
Moerus Worldwide Fund stated the following regarding Transocean Ltd. (NYSE:RIG) in its Q2 2026 investor letter:
"Shares of this U.S.-based provider of offshore drilling services surged in response to the February 9th announcement that the company had agreed to be acquired by Transocean Ltd. (NYSE:RIG) in an all-stock transaction, which was priced at a roughly 32% premium to Valaris' stock price (based on the previous day's closing price of each stock)."
#valaris

6 days ago
Harbor Funds, an investment management company, released its Q2 2026 investor letter for "Harbor Mid Cap Value Fund". The letter can be downloaded here. Global equities experienced a sharp rally in Q2 2026, with the S&P 500 returning 15.2%, its strongest quarter since 2020, driven by a shift from software to hardware in the Artificial Intelligence capital spending cycle. Small caps outperformed large caps, with the Russell 2000® gaining 21.5% compared to the Russell 1000's 15.1%. Growth stocks led within large caps, while Information Technology rose about 33%, contributing significantly to the S&P 500's return. The Harbor Mid Cap Value Fund returned 13.99%, outperforming its benchmark, the Russell Midcap Value Index. Strong stock selection in Consumer Discretionary, Real Estate, and Financials contributed positively, although an underweight in Information Technology negatively impacted results. Despite ongoing economic uncertainties, the investment philosophy remains committed to a disciplined value approach. Check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Harbor Mid Cap Value Fund highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 04, 2026, The Kroger Co. (NYSE:KR) closed at $58.59 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 1.83%, but its shares are down 15.42% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $35.89 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Harbor Mid Cap Value Fund stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Other detractors were The Kroger Co. (NYSE:KR) in the Consumer Staples sector and Matador Resources in the Energy sector. Kroger was down more than 20% as slowing same-store sales and inflation weighed on the stock. Competition from lower cost providers has forced Kroger to reduce prices to maintain market share."
The Kroger Co. (NYSE:KR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 56 hedge fund portfolios held The Kroger Co. (NYSE:KR) at the end of the second quarter, up from 52 in the previous quarter. While we acknowledge the potential of The Kroger Co. (NYSE:KR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #value #fund
In its second-quarter 2026 investor letter, Harbor Mid Cap Value Fund highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 04, 2026, The Kroger Co. (NYSE:KR) closed at $58.59 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 1.83%, but its shares are down 15.42% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $35.89 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Harbor Mid Cap Value Fund stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Other detractors were The Kroger Co. (NYSE:KR) in the Consumer Staples sector and Matador Resources in the Energy sector. Kroger was down more than 20% as slowing same-store sales and inflation weighed on the stock. Competition from lower cost providers has forced Kroger to reduce prices to maintain market share."
The Kroger Co. (NYSE:KR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 56 hedge fund portfolios held The Kroger Co. (NYSE:KR) at the end of the second quarter, up from 52 in the previous quarter. While we acknowledge the potential of The Kroger Co. (NYSE:KR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #value #fund


6 days ago
Harbor Funds, an investment management company, released its Q2 2026 investor letter for "Harbor Mid Cap Value Fund". The letter can be downloaded here. Global equities experienced a sharp rally in Q2 2026, with the S&P 500 returning 15.2%, its strongest quarter since 2020, driven by a shift from software to hardware in the Artificial Intelligence capital spending cycle. Small caps outperformed large caps, with the Russell 2000® gaining 21.5% compared to the Russell 1000's 15.1%. Growth stocks led within large caps, while Information Technology rose about 33%, contributing significantly to the S&P 500's return. The Harbor Mid Cap Value Fund returned 13.99%, outperforming its benchmark, the Russell Midcap Value Index. Strong stock selection in Consumer Discretionary, Real Estate, and Financials contributed positively, although an underweight in Information Technology negatively impacted results. Despite ongoing economic uncertainties, the investment philosophy remains committed to a disciplined value approach. Check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Harbor Mid Cap Value Fund highlighted Matador Resources Company (NYSE:MTDR). Matador Resources Company (NYSE:MTDR), a US-based independent energy company engages in the acquisition, exploration, development, and production of oil and natural gas resources, detracted from the performance during the quarter. On September 04, 2026, Matador Resources Company (NYSE:MTDR) closed at $59.15 per share. Over the past month, Matador Resources Company (NYSE:MTDR) returned 16.27%, and its shares are up 28.26% over the past year. Matador Resources Company (NYSE:MTDR) has a market capitalization of $7.32 billion, and its stock has traded within a 52-week range of $37.14 to $66.84.
Harbor Mid Cap Value Fund stated the following regarding Matador Resources Company (NYSE:MTDR) in its Q2 2026 investor letter:
"Other detractors were Kroger in the Consumer Staples sector and Matador Resources Company (NYSE:MTDR) in the Energy sector. Matador Resources fell 20%. ***** ysts downgraded the stock during the quarter as natural gas prices fell and costs increased, squeezing margins."
Matador Resources Company (NYSE:MTDR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 38 hedge fund portfolios held Matador Resources Company (NYSE:MTDR) at the end of the second quarter, up from 35 in the previous quarter. While we acknowledge the potential of Matador Resources Company (NYSE:MTDR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #Stock
In its second-quarter 2026 investor letter, Harbor Mid Cap Value Fund highlighted Matador Resources Company (NYSE:MTDR). Matador Resources Company (NYSE:MTDR), a US-based independent energy company engages in the acquisition, exploration, development, and production of oil and natural gas resources, detracted from the performance during the quarter. On September 04, 2026, Matador Resources Company (NYSE:MTDR) closed at $59.15 per share. Over the past month, Matador Resources Company (NYSE:MTDR) returned 16.27%, and its shares are up 28.26% over the past year. Matador Resources Company (NYSE:MTDR) has a market capitalization of $7.32 billion, and its stock has traded within a 52-week range of $37.14 to $66.84.
Harbor Mid Cap Value Fund stated the following regarding Matador Resources Company (NYSE:MTDR) in its Q2 2026 investor letter:
"Other detractors were Kroger in the Consumer Staples sector and Matador Resources Company (NYSE:MTDR) in the Energy sector. Matador Resources fell 20%. ***** ysts downgraded the stock during the quarter as natural gas prices fell and costs increased, squeezing margins."
Matador Resources Company (NYSE:MTDR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 38 hedge fund portfolios held Matador Resources Company (NYSE:MTDR) at the end of the second quarter, up from 35 in the previous quarter. While we acknowledge the potential of Matador Resources Company (NYSE:MTDR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #Stock

6 days ago
Pop star Pink is under fire online for resharing an anti-Israel message and then following it up with a series of Instagram posts directed at her detractors.
Macklemore, whose real name is Benjamin Hammond Haggerty, supported British musician Ed Sheeran on stage at MetLife Stadium in New Jersey in a show called Loop Tour on September 4 and 5. Donning a keffiyeh in front of an 80,000-strong audience, the rapper shouted "Free Palestine" and addressed Gaza and the occupied West Bank, saying that they are not being forgotten.
"Every human being walking on this earth deserves exactly the same freedom," he added, as reported by Variety.
The rapper then performed his protest song "Hind's Hall," which featured flashes of Gaza on the stadium screens. Macklemore referenced Hind Rajab, a young Palestinian girl killed in Gaza, named after student demonstrators at Columbia University who renamed a campus building in her honor. The rapper then addressed Jewish concertgoers, saying that criticizing Israel and condemning their actions as genocide is not a condemnation of Jewish people and that his message is a message of peace and dignity for everyone.
American pop diva, whose legal name is Alecia Beth Moore Hart, posted a video with the message "Awful" to her Instagram Story, claiming that Jewish fans who came to see Sheeran's performance are exposed to propaganda against Israel. According to Pink, Macklemore's speech and video presentation amount to a false accusation of genocide, and people who came to the concert are entitled to "apologies and refunds."
#Instagram #macklemore
Macklemore, whose real name is Benjamin Hammond Haggerty, supported British musician Ed Sheeran on stage at MetLife Stadium in New Jersey in a show called Loop Tour on September 4 and 5. Donning a keffiyeh in front of an 80,000-strong audience, the rapper shouted "Free Palestine" and addressed Gaza and the occupied West Bank, saying that they are not being forgotten.
"Every human being walking on this earth deserves exactly the same freedom," he added, as reported by Variety.
The rapper then performed his protest song "Hind's Hall," which featured flashes of Gaza on the stadium screens. Macklemore referenced Hind Rajab, a young Palestinian girl killed in Gaza, named after student demonstrators at Columbia University who renamed a campus building in her honor. The rapper then addressed Jewish concertgoers, saying that criticizing Israel and condemning their actions as genocide is not a condemnation of Jewish people and that his message is a message of peace and dignity for everyone.
American pop diva, whose legal name is Alecia Beth Moore Hart, posted a video with the message "Awful" to her Instagram Story, claiming that Jewish fans who came to see Sheeran's performance are exposed to propaganda against Israel. According to Pink, Macklemore's speech and video presentation amount to a false accusation of genocide, and people who came to the concert are entitled to "apologies and refunds."
#Instagram #macklemore


6 days ago
The biggest oil companies in the United States are playing hardball in unionized labor negotiations in a bid to get more concessions from workers' unions in the new contracts.
Over the past few years, some of the top U.S. refining companies have resorted to lockouts to ensure most of the company management's proposals in new labor contracts are accepted.
The trend began earlier this decade with Exxon locking out in 2021 as many as 650 workers out of the Beaumont refinery for 10 months. This was the longest labor dispute at a U.S. refinery in four decades.
Five years later, BP and Marathon are currently in a similar position, locking out workers at their Whiting, Indiana, and Martinez, California, refineries, respectively, amid labor disputes over union contracts.
The refineries continue to operate with contractors, supervisors, and replacement workers. The continued operations show that Big Oil is not as afraid as it used to be to use replacement staff while seeking concessions from the unions.
#contracts #unions #refinery
Over the past few years, some of the top U.S. refining companies have resorted to lockouts to ensure most of the company management's proposals in new labor contracts are accepted.
The trend began earlier this decade with Exxon locking out in 2021 as many as 650 workers out of the Beaumont refinery for 10 months. This was the longest labor dispute at a U.S. refinery in four decades.
Five years later, BP and Marathon are currently in a similar position, locking out workers at their Whiting, Indiana, and Martinez, California, refineries, respectively, amid labor disputes over union contracts.
The refineries continue to operate with contractors, supervisors, and replacement workers. The continued operations show that Big Oil is not as afraid as it used to be to use replacement staff while seeking concessions from the unions.
#contracts #unions #refinery
7 days ago
Florida Attorney General James Uthmeier says his office will seek the death penalty for the two adults who allegedly confined four children to the cab of a tractor-trailer, some for more than six years, and ***** ually abused them.
Keisha Monique Epps, 51, and Tamra Marshon Stewart, 37, have been charged with ***** ual battery, molestation and neglect of two girls and two boys — two 5-year-olds, a 6-year-old and a 9-year-old, Uthmeier said.
Epps and Stewart, who has been identified as her fiancé, had been living in the cab with the children. Epps worked as a truck driver, frequenting a route between Miami and Atlanta, according to court documents.
Florida Couple Allegedly Held Four Children In Tractor-trailer Cab For Nearly Seven Years
Keisha Epps and Tamra Marshon Stewart were arrested Aug. 6 and remain jailed as they await trial on child neglect charges.
#keisha #allegedly
Keisha Monique Epps, 51, and Tamra Marshon Stewart, 37, have been charged with ***** ual battery, molestation and neglect of two girls and two boys — two 5-year-olds, a 6-year-old and a 9-year-old, Uthmeier said.
Epps and Stewart, who has been identified as her fiancé, had been living in the cab with the children. Epps worked as a truck driver, frequenting a route between Miami and Atlanta, according to court documents.
Florida Couple Allegedly Held Four Children In Tractor-trailer Cab For Nearly Seven Years
Keisha Epps and Tamra Marshon Stewart were arrested Aug. 6 and remain jailed as they await trial on child neglect charges.
#keisha #allegedly

8 days ago
The biggest oil companies in the United States are playing hardball in unionized labor negotiations in a bid to get more concessions from workers' unions in the new contracts.
Over the past few years, some of the top U.S. refining companies have resorted to lockouts to ensure most of the company management's proposals in new labor contracts are accepted.
The trend began earlier this decade with Exxon locking out in 2021 as many as 650 workers out of the Beaumont refinery for 10 months. This was the longest labor dispute at a U.S. refinery in four decades.
Five years later, BP and Marathon are currently in a similar position, locking out workers at their Whiting, Indiana, and Martinez, California, refineries, respectively, amid labor disputes over union contracts.
The refineries continue to operate with contractors, supervisors, and replacement workers. The continued operations show that Big Oil is not as afraid as it used to be to use replacement staff while seeking concessions from the unions.
#contracts
Over the past few years, some of the top U.S. refining companies have resorted to lockouts to ensure most of the company management's proposals in new labor contracts are accepted.
The trend began earlier this decade with Exxon locking out in 2021 as many as 650 workers out of the Beaumont refinery for 10 months. This was the longest labor dispute at a U.S. refinery in four decades.
Five years later, BP and Marathon are currently in a similar position, locking out workers at their Whiting, Indiana, and Martinez, California, refineries, respectively, amid labor disputes over union contracts.
The refineries continue to operate with contractors, supervisors, and replacement workers. The continued operations show that Big Oil is not as afraid as it used to be to use replacement staff while seeking concessions from the unions.
#contracts


9 days ago
On August 21, Kurt Yinger from DA Davidson initiated his coverage of Everus Construction Group Inc. (NYSE:ECG) with a $168 target price and an upside potential of more than 43%, as of September 4 closing. The **** yst **** igned a Buy rating to the stock based on a highly compelling story that revolves around recent accretive acquisitions, expanding profit margins, lucrative project backlog, and strong order bookings. Kurt anticipated the $295 million Epsilon acquisition to bolster the existing forecasts. Let's explore what fuels this bullish narrative around this specialty contractor.
youssef-abdelwahab-qyzo7TDSVQs-unsplash
Everus finalized its $295 million cash acquisition of Epsilon Industries on September 1. Epsilon is an established designer and manufacturer of mechanical and electrical building infrastructure systems. The transaction was financed using a mix of cash on hand and borrowings under the company's existing credit facilities.
The deal expands Everus' prefabrication and modular construction capabilities, enabling it to cater to high-demand sectors through custom fabrication, design-assist and turnkey installation solutions. These sectors include data centers, advanced manufacturing, and healthcare. Epsilon's numerous strategic centers in the U.S. and Canada will contribute to Everus' nationwide distribution network and augment its current geographic presence within priority growth markets.
By integrating Epsilon's workforce and technical expertise, Everus is well-positioned to meet the increased customer demand, penetrate key end-markets and capitalize on favorable industry trends. With this the company will ultimately reinforce its competitive edge and long-term growth trajectory within the construction sector.
#everus
youssef-abdelwahab-qyzo7TDSVQs-unsplash
Everus finalized its $295 million cash acquisition of Epsilon Industries on September 1. Epsilon is an established designer and manufacturer of mechanical and electrical building infrastructure systems. The transaction was financed using a mix of cash on hand and borrowings under the company's existing credit facilities.
The deal expands Everus' prefabrication and modular construction capabilities, enabling it to cater to high-demand sectors through custom fabrication, design-assist and turnkey installation solutions. These sectors include data centers, advanced manufacturing, and healthcare. Epsilon's numerous strategic centers in the U.S. and Canada will contribute to Everus' nationwide distribution network and augment its current geographic presence within priority growth markets.
By integrating Epsilon's workforce and technical expertise, Everus is well-positioned to meet the increased customer demand, penetrate key end-markets and capitalize on favorable industry trends. With this the company will ultimately reinforce its competitive edge and long-term growth trajectory within the construction sector.
#everus


9 days ago
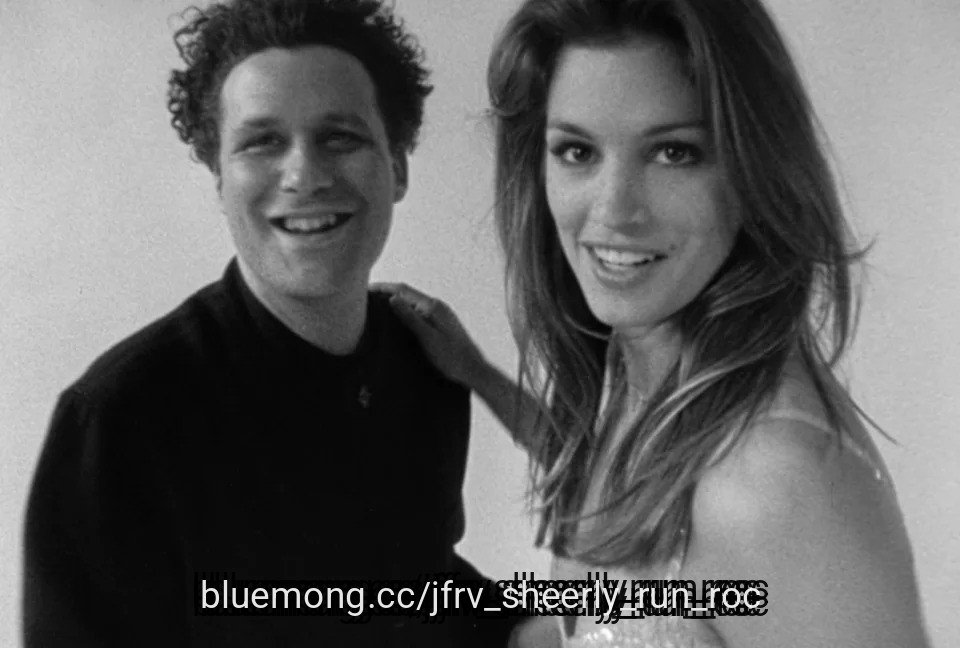
On a cold November morning, designer Isaac Mizrahi gets up, leaves his apartment, and trudges to the corner newsstand to pick up a copy of Women's Wear Daily. It's the day after Mizrahi's Spring/Summer 1994 show, and the ink on the reviews is still wet. Reading from the pages, he quotes, "'His usually great color sense failed him, his fabric sense failed him, and certainly, his sense of how a modern woman dresses after 8 p.m. failed him." The verdict is withering. Mizrahi, one of the great artists of '90s ready-to-wear fashion, has been tossed out. Disgraced. Lightly "cancelled," as some might call it these days.
Douglas Keeve's sublime 1995 documentary, "Unzipped," follows Mizrahi in the aftermath of a train wreck, piecing his reputation back together with his next collection, attempting to make something beautiful from the rubble. We find Mizrahi's world in grayscale, drained of color in the wake of critical and cultural failure. Then, the opening notes of Sandra Bernhard's 1994 cover of Sylvester's "You Make Me Feel (Mighty Real)" cue the pigmentation, cascading over bright images of models in fittings, garments hanging from racks, and plenty of DayGlo faux furs. In her version, Bernhard alters the lyrics to pay tribute to Sylvester, whose untimely death left an immense legacy. "Sylvester, sister," Bernhard coos, "You were so beautiful, you were so fragile, you were so . . . real."
But just before Bernhard finishes the word, the song fades to silence, as if to say that realness — genuine authenticity in your life and work, at the cost of criticism — will always be snuffed out before it can be fully appreciated. That is the price of beauty. What is up must always come down.
(Janus Films) Isaac Mizrahi in "Unzipped"
After years in cinematic obscurity — the film hasn't been readily available outside of the eBay market in decades — "Unzipped" will return to theaters later this month, with a loving 4K restoration from Janus Films, just as another fashion-world controversy is heating up. Earlier this week, the Metropolitan Museum of Art declared it would no longer proceed with its Costume Institute's upcoming exhibition honoring John Galliano, scheduled to debut next year. When the scrapped "John Galliano: Horizons" was announced in July, the exhibition was immediately met with an outpouring of criticism. Detractors accused the museum of being tone deaf, citing a 2011 video of Galliano going on a drunken antisemitic and racist rant at a Paris bar, for which Galliano was promptly ousted from his spot as creative director at Dior. Following the video surfacing, Galliano apologized, went to rehab, and, over the last few years, experienced a brand resurgence that some would call a whitewashing.
#mizrahi #bernhard #sense
Douglas Keeve's sublime 1995 documentary, "Unzipped," follows Mizrahi in the aftermath of a train wreck, piecing his reputation back together with his next collection, attempting to make something beautiful from the rubble. We find Mizrahi's world in grayscale, drained of color in the wake of critical and cultural failure. Then, the opening notes of Sandra Bernhard's 1994 cover of Sylvester's "You Make Me Feel (Mighty Real)" cue the pigmentation, cascading over bright images of models in fittings, garments hanging from racks, and plenty of DayGlo faux furs. In her version, Bernhard alters the lyrics to pay tribute to Sylvester, whose untimely death left an immense legacy. "Sylvester, sister," Bernhard coos, "You were so beautiful, you were so fragile, you were so . . . real."
But just before Bernhard finishes the word, the song fades to silence, as if to say that realness — genuine authenticity in your life and work, at the cost of criticism — will always be snuffed out before it can be fully appreciated. That is the price of beauty. What is up must always come down.
(Janus Films) Isaac Mizrahi in "Unzipped"
After years in cinematic obscurity — the film hasn't been readily available outside of the eBay market in decades — "Unzipped" will return to theaters later this month, with a loving 4K restoration from Janus Films, just as another fashion-world controversy is heating up. Earlier this week, the Metropolitan Museum of Art declared it would no longer proceed with its Costume Institute's upcoming exhibition honoring John Galliano, scheduled to debut next year. When the scrapped "John Galliano: Horizons" was announced in July, the exhibition was immediately met with an outpouring of criticism. Detractors accused the museum of being tone deaf, citing a 2011 video of Galliano going on a drunken antisemitic and racist rant at a Paris bar, for which Galliano was promptly ousted from his spot as creative director at Dior. Following the video surfacing, Galliano apologized, went to rehab, and, over the last few years, experienced a brand resurgence that some would call a whitewashing.
#mizrahi #bernhard #sense

9 days ago
On August 6, Frontdoor (NASDAQ:FTDR) reported second-quarter results that outpaced its own recent history. Revenue rose 5% to $645 million, but profit grew faster: net income jumped 13% to $125 million, and earnings per share climbed 19% to $1.76. Adjusted EBITDA rose 10% to $220 million. Management liked what it saw enough to raise full-year revenue and Adjusted EBITDA guidance, a signal it expects the momentum to carry through the rest of 2026 rather than fade as a one-quarter ******* p.
Frontdoor's growth mix should please shareholders. About three percentage points of the 5% revenue increase came from higher realized price through its dynamic pricing model, with roughly one point from volume. That pricing lever flowed straight through to margins, as gross profit margin rose to 59% for the quarter. The renewal channel, the largest and stickiest part of the business, grew revenue 4% to $479 million, while total home warranty membership climbed 1% to 2.11 million.
The company's own earnings bridge shows why profit outran revenue: contract claims costs fell $7 million year over year, helped by $5 million in favorable weather, even after absorbing low-single-digit cost inflation across its contractor network and replacement parts. Frontdoor also leaned harder into buybacks, repurchasing $181 million of stock through July, up more than 21% from the same stretch a year earlier. For 2026, management now guides to revenue of $2.19 billion to $2.21 billion and Adjusted EBITDA of $585 million to $600 million, both raised, with first-year home warranty membership expected to grow roughly 5% for the full year.
The same release shows cracks alongside the strength. Direct-to-consumer revenue fell 2% to $55 million, as Frontdoor leaned on promotional pricing to win new members, a trade-off between growth and realized price that shows up directly in that line. Cash generation cooled too: operating cash flow for the first six months of 2026 came in at $245 million, down from $251 million a year earlier, and the period's total cash increase slowed to $62 million from $141 million, partly because investing activities swung to a $14 million outflow from a $42 million inflow the year before.
Financing activities used $169 million, more than the $153 million spent in the same period last year, largely reflecting the faster buyback pace plus $14 million in scheduled debt payments. For the full year, Frontdoor is guiding gross profit margin down to roughly 55%, well below the 59% posted this quarter, and it still expects direct-to-consumer revenue to decline at a low-single-digit rate. SG&A is projected at $685 million to $695 million, with low-single-digit cost inflation across contractors, parts, and equipment that could bite harder if weather turns less favorable than it was this quarter.
#revenue #adjusted #cash
Frontdoor's growth mix should please shareholders. About three percentage points of the 5% revenue increase came from higher realized price through its dynamic pricing model, with roughly one point from volume. That pricing lever flowed straight through to margins, as gross profit margin rose to 59% for the quarter. The renewal channel, the largest and stickiest part of the business, grew revenue 4% to $479 million, while total home warranty membership climbed 1% to 2.11 million.
The company's own earnings bridge shows why profit outran revenue: contract claims costs fell $7 million year over year, helped by $5 million in favorable weather, even after absorbing low-single-digit cost inflation across its contractor network and replacement parts. Frontdoor also leaned harder into buybacks, repurchasing $181 million of stock through July, up more than 21% from the same stretch a year earlier. For 2026, management now guides to revenue of $2.19 billion to $2.21 billion and Adjusted EBITDA of $585 million to $600 million, both raised, with first-year home warranty membership expected to grow roughly 5% for the full year.
The same release shows cracks alongside the strength. Direct-to-consumer revenue fell 2% to $55 million, as Frontdoor leaned on promotional pricing to win new members, a trade-off between growth and realized price that shows up directly in that line. Cash generation cooled too: operating cash flow for the first six months of 2026 came in at $245 million, down from $251 million a year earlier, and the period's total cash increase slowed to $62 million from $141 million, partly because investing activities swung to a $14 million outflow from a $42 million inflow the year before.
Financing activities used $169 million, more than the $153 million spent in the same period last year, largely reflecting the faster buyback pace plus $14 million in scheduled debt payments. For the full year, Frontdoor is guiding gross profit margin down to roughly 55%, well below the 59% posted this quarter, and it still expects direct-to-consumer revenue to decline at a low-single-digit rate. SG&A is projected at $685 million to $695 million, with low-single-digit cost inflation across contractors, parts, and equipment that could bite harder if weather turns less favorable than it was this quarter.
#revenue #adjusted #cash


9 days ago
Diamond Hill Capital, a First Eagle Investment Management company, issued its Q2 2026 investor letter for its "Small Cap Strategy". The letter can be downloaded here. The strategy returned 24.01% in the second quarter, outperforming the Russell 2000 Index's 21.49% return. Performance was positively affected by stock selection in health care and industrials, while the Fund's underweight position in information technology was the largest relative detractor as AI-related companies drove market gains. Small-cap equities benefited from strong earnings, resilient economic conditions, and easing geopolitical concerns, with technology leading sector performance while energy declined alongside lower oil prices. Despite the market's focus on AI, the Fund's strongest contributors came from businesses outside the theme, particularly in health care, defense-oriented companies, and tangible-asset industries. Looking ahead, the Fund remains focused on resilient, underfollowed companies tied to infrastructure, defense modernization, and essential industries where disciplined capital allocation and long-term demand can support value creation. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted United States Lime & Minerals, Inc. (NASDAQ:USLM). United States Lime & Minerals, Inc. (NASDAQ:USLM) manufactures and supplies lime and limestone products in the United States. On September 02, 2026, United States Lime & Minerals, Inc. (NASDAQ:USLM) closed at $115.05 per share. Over the past month, United States Lime & Minerals, Inc. (NASDAQ:USLM) declined 0.94%, and its shares lost 4.79% over the past 52 weeks. United States Lime & Minerals, Inc. (NASDAQ:USLM) has a market capitalization of $3.3 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding United States Lime & Minerals, Inc. (NASDAQ:USLM) in its Q2 2026 investor letter:
"United States Lime & Minerals, Inc. (NASDAQ:USLM), a producer and supplier of limestone products, underperformed as several near-term headwinds—weather disruptions, labor shortages and higher fuel costs—pressured demand and margins. Despite these challenges, the company's scarce limestone reserves in Texas continue to support strong pricing power, and we maintain a constructive long-term view for the business."
United States Lime & Minerals, Inc. (NASDAQ:USLM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 26 hedge fund portfolios held United States Lime & Minerals, Inc. (NASDAQ:USLM) at the end of the second quarter which was 24 in the previous quarter. While we acknowledge the potential of United States Lime & Minerals, Inc. (NASDAQ:USLM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tarif
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted United States Lime & Minerals, Inc. (NASDAQ:USLM). United States Lime & Minerals, Inc. (NASDAQ:USLM) manufactures and supplies lime and limestone products in the United States. On September 02, 2026, United States Lime & Minerals, Inc. (NASDAQ:USLM) closed at $115.05 per share. Over the past month, United States Lime & Minerals, Inc. (NASDAQ:USLM) declined 0.94%, and its shares lost 4.79% over the past 52 weeks. United States Lime & Minerals, Inc. (NASDAQ:USLM) has a market capitalization of $3.3 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding United States Lime & Minerals, Inc. (NASDAQ:USLM) in its Q2 2026 investor letter:
"United States Lime & Minerals, Inc. (NASDAQ:USLM), a producer and supplier of limestone products, underperformed as several near-term headwinds—weather disruptions, labor shortages and higher fuel costs—pressured demand and margins. Despite these challenges, the company's scarce limestone reserves in Texas continue to support strong pricing power, and we maintain a constructive long-term view for the business."
United States Lime & Minerals, Inc. (NASDAQ:USLM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 26 hedge fund portfolios held United States Lime & Minerals, Inc. (NASDAQ:USLM) at the end of the second quarter which was 24 in the previous quarter. While we acknowledge the potential of United States Lime & Minerals, Inc. (NASDAQ:USLM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tarif

9 days ago
Diamond Hill Capital, a First Eagle Investment Management company, issued its Q2 2026 investor letter for its "Small Cap Strategy". The letter can be downloaded here. The strategy returned 24.01% in the second quarter, outperforming the Russell 2000 Index's 21.49% return. Performance was positively affected by stock selection in health care and industrials, while the Fund's underweight position in information technology was the largest relative detractor as AI-related companies drove market gains. Small-cap equities benefited from strong earnings, resilient economic conditions, and easing geopolitical concerns, with technology leading sector performance while energy declined alongside lower oil prices. Despite the market's focus on AI, the Fund's strongest contributors came from businesses outside the theme, particularly in health care, defense-oriented companies, and tangible-asset industries. Looking ahead, the Fund remains focused on resilient, underfollowed companies tied to infrastructure, defense modernization, and essential industries where disciplined capital allocation and long-term demand can support value creation. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Magnolia Oil & Gas Corporation (NYSE:MGY). Magnolia Oil & Gas Corporation (NYSE:MGY) is a US-based leading independent oil and natural gas company, which detracted from the performance this quarter. On September 02, 2026, Magnolia Oil & Gas Corporation (NYSE:MGY) closed at $27.38 per share. The one-month return of Magnolia Oil & Gas Corporation (NYSE:MGY) was 10.28%, and its shares gained 10.96% over the past 52 weeks. Magnolia Oil & Gas Corporation (NYSE:MGY) has a market capitalization of $6.56 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Magnolia Oil & Gas Corporation (NYSE:MGY) in its Q2 2026 investor letter:
"Exploration and production company Magnolia Oil & Gas Corporation (NYSE:MGY) saw shares decline after an agreement was reached to end the war between the US and Iran and reopen the Strait of Hormuz. Although the situation in the Middle East remains fragile, the market increasingly viewed the risk of a meaningful supply disruption as diminished, and the war-related risk premium that had supported US exploration and production companies earlier in the year largely dissipated."
Magnolia Oil & Gas Corporation (NYSE:MGY) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 32 hedge fund portfolios held Magnolia Oil & Gas Corporation (NYSE:MGY) at the end of the second quarter which was 32 in the previous quarter. While we acknowledge the potential of Magnolia Oil & Gas Corporation (NYSE:MGY) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit s
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Magnolia Oil & Gas Corporation (NYSE:MGY). Magnolia Oil & Gas Corporation (NYSE:MGY) is a US-based leading independent oil and natural gas company, which detracted from the performance this quarter. On September 02, 2026, Magnolia Oil & Gas Corporation (NYSE:MGY) closed at $27.38 per share. The one-month return of Magnolia Oil & Gas Corporation (NYSE:MGY) was 10.28%, and its shares gained 10.96% over the past 52 weeks. Magnolia Oil & Gas Corporation (NYSE:MGY) has a market capitalization of $6.56 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Magnolia Oil & Gas Corporation (NYSE:MGY) in its Q2 2026 investor letter:
"Exploration and production company Magnolia Oil & Gas Corporation (NYSE:MGY) saw shares decline after an agreement was reached to end the war between the US and Iran and reopen the Strait of Hormuz. Although the situation in the Middle East remains fragile, the market increasingly viewed the risk of a meaningful supply disruption as diminished, and the war-related risk premium that had supported US exploration and production companies earlier in the year largely dissipated."
Magnolia Oil & Gas Corporation (NYSE:MGY) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 32 hedge fund portfolios held Magnolia Oil & Gas Corporation (NYSE:MGY) at the end of the second quarter which was 32 in the previous quarter. While we acknowledge the potential of Magnolia Oil & Gas Corporation (NYSE:MGY) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit s

9 days ago
Diamond Hill Capital, a First Eagle Investment Management company, issued its Q2 2026 investor letter for its "Small Cap Strategy". The letter can be downloaded here. The strategy returned 24.01% in the second quarter, outperforming the Russell 2000 Index's 21.49% return. Performance was positively affected by stock selection in health care and industrials, while the Fund's underweight position in information technology was the largest relative detractor as AI-related companies drove market gains. Small-cap equities benefited from strong earnings, resilient economic conditions, and easing geopolitical concerns, with technology leading sector performance while energy declined alongside lower oil prices. Despite the market's focus on AI, the Fund's strongest contributors came from businesses outside the theme, particularly in health care, defense-oriented companies, and tangible-asset industries. Looking ahead, the Fund remains focused on resilient, underfollowed companies tied to infrastructure, defense modernization, and essential industries where disciplined capital allocation and long-term demand can support value creation. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Ducommun Incorporated (NYSE:DCO) as a leading contributor. Ducommun Incorporated (NYSE:DCO) provides engineering and manufacturing services for products and applications used in the aerospace and defense, industrial, medical, and other industries. On September 02, 2026, Ducommun Incorporated (NYSE:DCO) closed at $165.60 per share. Over the last month, Ducommun Incorporated (NYSE:DCO) declined 17.80% and its shares gained 81.24% over the past 52 weeks. Ducommun Incorporated (NYSE:DCO) has a market capitalization of $2.55 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Ducommun Incorporated (NYSE:DCO) in its Q2 2026 investor letter:
"Shares of aerospace and defense manufacturer Ducommun Incorporated (NYSE:DCO) rose as both of its primary end markets strengthened simultaneously for the first time in years. Missile revenue increased by nearly a quarter, supported by funded Department of Defense contracts calling for substantial production increases, while commercial aerospace returned to growth following a prolonged period of lower activity."
Ducommun Incorporated (NYSE:DCO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 31 hedge fund portfolios held Ducommun Incorporated (NYSE:DCO) at the end of the second quarter which was 18 in the previous quarter. While we acknowledge the potential of Ducommun Incorporated (NYSE:DCO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free rep
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Ducommun Incorporated (NYSE:DCO) as a leading contributor. Ducommun Incorporated (NYSE:DCO) provides engineering and manufacturing services for products and applications used in the aerospace and defense, industrial, medical, and other industries. On September 02, 2026, Ducommun Incorporated (NYSE:DCO) closed at $165.60 per share. Over the last month, Ducommun Incorporated (NYSE:DCO) declined 17.80% and its shares gained 81.24% over the past 52 weeks. Ducommun Incorporated (NYSE:DCO) has a market capitalization of $2.55 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Ducommun Incorporated (NYSE:DCO) in its Q2 2026 investor letter:
"Shares of aerospace and defense manufacturer Ducommun Incorporated (NYSE:DCO) rose as both of its primary end markets strengthened simultaneously for the first time in years. Missile revenue increased by nearly a quarter, supported by funded Department of Defense contracts calling for substantial production increases, while commercial aerospace returned to growth following a prolonged period of lower activity."
Ducommun Incorporated (NYSE:DCO) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 31 hedge fund portfolios held Ducommun Incorporated (NYSE:DCO) at the end of the second quarter which was 18 in the previous quarter. While we acknowledge the potential of Ducommun Incorporated (NYSE:DCO) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free rep

9 days ago
Diamond Hill Capital, a First Eagle Investment Management company, issued its Q2 2026 investor letter for its "Small Cap Strategy". The letter can be downloaded here. The strategy returned 24.01% in the second quarter, outperforming the Russell 2000 Index's 21.49% return. Performance was positively affected by stock selection in health care and industrials, while the Fund's underweight position in information technology was the largest relative detractor as AI-related companies drove market gains. Small-cap equities benefited from strong earnings, resilient economic conditions, and easing geopolitical concerns, with technology leading sector performance while energy declined alongside lower oil prices. Despite the market's focus on AI, the Fund's strongest contributors came from businesses outside the theme, particularly in health care, defense-oriented companies, and tangible-asset industries. Looking ahead, the Fund remains focused on resilient, underfollowed companies tied to infrastructure, defense modernization, and essential industries where disciplined capital allocation and long-term demand can support value creation. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Astrana Health, Inc. (NASDAQ:ASTH). Astrana Health, Inc. (NASDAQ:ASTH), a US-based healthcare management company that provides medical care services, contributed positively to the Strategy's performance this quarter. On September 2, 2026, Astrana Health, Inc. (NASDAQ:ASTH) closed at $38.57 per share. Astrana Health, Inc. (NASDAQ:ASTH) was up 11.75% over the past month, and its shares gained 23.75% over the past 52 weeks. Astrana Health, Inc. (NASDAQ:ASTH) has a market capitalization of $1.91 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Astrana Health, Inc. (NASDAQ:ASTH) in its Q2 2026 investor letter:
"Astrana Health, Inc. (NASDAQ:ASTH), a leader in value-based health care, outperformed as the company results have continued to demonstrate that it was not taking advantage of loopholes within Medicare coding, the balance sheet is back in good shape after the recent Prospect Health acquisition, which is performing well, and recent Medicare Advantage rates came in better than expected."
Astrana Health, Inc. (NASDAQ:ASTH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 18 hedge fund portfolios held Astrana Health, Inc. (NASDAQ:ASTH) at the end of the second quarter which was 15 in the previous quarter. While we acknowledge the potential of Astrana Health, Inc. (NASDAQ:ASTH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#astrana
In its second-quarter 2026 investor letter, Diamond Hill Capital Small Cap Strategy highlighted Astrana Health, Inc. (NASDAQ:ASTH). Astrana Health, Inc. (NASDAQ:ASTH), a US-based healthcare management company that provides medical care services, contributed positively to the Strategy's performance this quarter. On September 2, 2026, Astrana Health, Inc. (NASDAQ:ASTH) closed at $38.57 per share. Astrana Health, Inc. (NASDAQ:ASTH) was up 11.75% over the past month, and its shares gained 23.75% over the past 52 weeks. Astrana Health, Inc. (NASDAQ:ASTH) has a market capitalization of $1.91 billion.
Diamond Hill Capital Small Cap Strategy stated the following regarding Astrana Health, Inc. (NASDAQ:ASTH) in its Q2 2026 investor letter:
"Astrana Health, Inc. (NASDAQ:ASTH), a leader in value-based health care, outperformed as the company results have continued to demonstrate that it was not taking advantage of loopholes within Medicare coding, the balance sheet is back in good shape after the recent Prospect Health acquisition, which is performing well, and recent Medicare Advantage rates came in better than expected."
Astrana Health, Inc. (NASDAQ:ASTH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 18 hedge fund portfolios held Astrana Health, Inc. (NASDAQ:ASTH) at the end of the second quarter which was 15 in the previous quarter. While we acknowledge the potential of Astrana Health, Inc. (NASDAQ:ASTH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#astrana


10 days ago
Chris Sutton claimed that Liverpool 'may have got away' with a potential red card offence at Portman Road on Friday night.
The Reds surged into a 2-0 lead against Ipswich inside nine minutes thanks to a brace of Alexander Isak goals, both of which were set up by Cody Gakpo, although the home side asked a few questions of the visitors later in the first half.
Seven minutes after the interval, Jeremy Jacquet was shown a yellow card by Darren England for a collison with Tractor Boys striker Emersson near the halfway line.
That prompted Sutton to say on co-commentary for Sky Sports that the Liverpool defender 'has had the odd clumsy moment in this game', perhaps referring to a first-half moment of hesitation between him and Alisson Becker inside the Reds' penalty area.
Just a couple of minutes after being booked, the 21-year-old took a heavy touch near the sideline and gave the Ipswich striker the chance to steal the ball off him, with the Frenchman then tripping his opponent but not being penalised by the referee.
#Liverpool #ipswich
The Reds surged into a 2-0 lead against Ipswich inside nine minutes thanks to a brace of Alexander Isak goals, both of which were set up by Cody Gakpo, although the home side asked a few questions of the visitors later in the first half.
Seven minutes after the interval, Jeremy Jacquet was shown a yellow card by Darren England for a collison with Tractor Boys striker Emersson near the halfway line.
That prompted Sutton to say on co-commentary for Sky Sports that the Liverpool defender 'has had the odd clumsy moment in this game', perhaps referring to a first-half moment of hesitation between him and Alisson Becker inside the Reds' penalty area.
Just a couple of minutes after being booked, the 21-year-old took a heavy touch near the sideline and gave the Ipswich striker the chance to steal the ball off him, with the Frenchman then tripping his opponent but not being penalised by the referee.
#Liverpool #ipswich

10 days ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#NASDAQ #global #quarter
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#NASDAQ #global #quarter


10 days ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#insm #artisan #global #quarter
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Insmed Incorporated (NASDAQ:INSM). Insmed Incorporated (NASDAQ:INSM) is a clinical-stage biotechnology company that develops and commercializes therapies for patients with serious and rare diseases. On September 01, 2026, Insmed Incorporated (NASDAQ:INSM) closed at $121.51 per share. Over the past month, Insmed Incorporated (NASDAQ:INSM) returned 25.42%, and its shares lost 13.45% over the past 52 weeks. Insmed Incorporated (NASDAQ:INSM) has a market capitalization of $27.14 billion.
Artisan Global Opportunities Strategy stated the following regarding Insmed Incorporated (NASDAQ:INSM) in its Q2 2026 investor letter:
"Our biggest detractors in Q2 were Insmed Incorporated (NASDAQ:INSM), BAE Systems and L3Harris Technologies. Insmed is a commercial-stage biotechnology company focused on pulmonary diseases. BRINSUPRI® continued its rapid launch, with robust patient uptake and encouraging third-party data. While Q1 sales came in modestly below elevated investor expectations, reflecting concerns around discontinuation rates, continuation on therapy and typical early-year seasonality, we believe the underlying launch trajectory remains encouraging. We continue to view BRINSUPRI® as a significant long-term opportunity. Our due diligence suggests the therapy remains well tolerated and is on track to achieve blockbuster-level sales. We trimmed the position during the quarter."
#insm #artisan #global #quarter
10 days ago
With the news earlier this evening that Michael Lombardi has resigned as General Manager, WRAL has reported that UNC is still looking into a number of allegations surrounding the football program. The allegations are quite serious, and would almost certainly be enough for several more people to lose their jobs.
According to WRAL, lawyers are investigating whether defensive coordinator Steve Belichick used drugs while on the job or provided drugs to a player on the team. The younger Belichick has been on leave since over the summer for undisclosed reasons.
There is also an investigation into the existence of inappropriate relationships between recruiting staff and a player as well as ******* istant coaches and recruiting staff. WRAL notes that those questioned in the matter were asked whether or not they'd reported any issues to Bill Belichick.
If there is indeed validity to these claims, particularly if it is confirmed that Bill Belichick was made aware of what was going on within his program, it seems likely that the entire house of cards may fall. While it's clear that Lombardi was a real problem, the school is concerned enough that he was not the root of the entire problem to keep digging into what was going on in the Kenan Football Center.
Some of the allegations simply feel too big to recover from if they are proven to be true. It's a significant black eye on the program and the university that there is enough smoke to even reach this point. Almost the entire Bill Belichick Experience has been a punchline in the college football world, and all of the detractors were just given a boatload more fuel for the fire.
#wral #Football #entire
According to WRAL, lawyers are investigating whether defensive coordinator Steve Belichick used drugs while on the job or provided drugs to a player on the team. The younger Belichick has been on leave since over the summer for undisclosed reasons.
There is also an investigation into the existence of inappropriate relationships between recruiting staff and a player as well as ******* istant coaches and recruiting staff. WRAL notes that those questioned in the matter were asked whether or not they'd reported any issues to Bill Belichick.
If there is indeed validity to these claims, particularly if it is confirmed that Bill Belichick was made aware of what was going on within his program, it seems likely that the entire house of cards may fall. While it's clear that Lombardi was a real problem, the school is concerned enough that he was not the root of the entire problem to keep digging into what was going on in the Kenan Football Center.
Some of the allegations simply feel too big to recover from if they are proven to be true. It's a significant black eye on the program and the university that there is enough smoke to even reach this point. Almost the entire Bill Belichick Experience has been a punchline in the college football world, and all of the detractors were just given a boatload more fuel for the fire.
#wral #Football #entire
11 days ago
Private equity firm Trident Management appears to be an early mover in bolting together small courier businesses onto a platform that can offer shippers greater regional density and reach as an alternative to large, legacy parcel carriers.
Trident-backed Priority Courier Experts, which serves B2B customers in the Minneapolis-St. Paul area and upper Midwest, last week said it acquired Priority Dispatch Inc. and Diamond Expedited, Midwest providers of same-day courier and box-truck freight services for the healthcare and e-commerce industries, and Atlanta-based Inpax Shipping Solutions.
Priority Dispatch was founded in Cincinnati in 1973. Diamond Expedited began serving the greater Chicago area in 1995. The companies, which were bought from the same individual, also cover Columbus, Cleveland, Dayton and Toledo, Ohio; Indianapolis; Detroit and Milwaukee, with 43 employees and more than 500 independent-contractor drivers. Their combined delivery traffic is about 250,000 orders per year.
Inpax is active in seven markets across the South, including Charlotte and Raleigh, North Carolina, Tennessee, South Carolina and Florida. With 75 employees and more than 335 owner-operators it delivers more than 400,000 orders per year. In addition to e-commerce pickup and delivery, it offers local and regional truck brokerage and tractor trailer freight.
In December 2024, Priority Courier Experts purchased Indianapolis-based Now Courier.
#Experts #indianapolis
Trident-backed Priority Courier Experts, which serves B2B customers in the Minneapolis-St. Paul area and upper Midwest, last week said it acquired Priority Dispatch Inc. and Diamond Expedited, Midwest providers of same-day courier and box-truck freight services for the healthcare and e-commerce industries, and Atlanta-based Inpax Shipping Solutions.
Priority Dispatch was founded in Cincinnati in 1973. Diamond Expedited began serving the greater Chicago area in 1995. The companies, which were bought from the same individual, also cover Columbus, Cleveland, Dayton and Toledo, Ohio; Indianapolis; Detroit and Milwaukee, with 43 employees and more than 500 independent-contractor drivers. Their combined delivery traffic is about 250,000 orders per year.
Inpax is active in seven markets across the South, including Charlotte and Raleigh, North Carolina, Tennessee, South Carolina and Florida. With 75 employees and more than 335 owner-operators it delivers more than 400,000 orders per year. In addition to e-commerce pickup and delivery, it offers local and regional truck brokerage and tractor trailer freight.
In December 2024, Priority Courier Experts purchased Indianapolis-based Now Courier.
#Experts #indianapolis
11 days ago
Sunnyvale, California-based Intuitive Surgical, Inc. (ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care. Valued at $133.1 billion by market cap, the company offers endoscopes, endoscopic retractors and disectors, scissors, scalpels, forceps, needle holders, electrocautery, ultrasonic cutters, and accessories during surgical procedures.
Companies worth $10 billion or more are generally described as "large-cap stocks," and ISRG definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical instruments & supplies industry. Intuitive Surgical excels in robotic-assisted surgery with its gold-standard da Vinci system, backed by strong brand reputation, continuous R&D investment, and comprehensive surgeon training, driving user proficiency and patient outcomes.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#intuitive #dear
Companies worth $10 billion or more are generally described as "large-cap stocks," and ISRG definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical instruments & supplies industry. Intuitive Surgical excels in robotic-assisted surgery with its gold-standard da Vinci system, backed by strong brand reputation, continuous R&D investment, and comprehensive surgeon training, driving user proficiency and patient outcomes.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#intuitive #dear

11 days ago
First Eagle Investment Management, an investment management company, released its Q2 2026 investor update for "First Eagle Global Fund". The letter can be downloaded here. Easing tensions in the Middle East led to a strong rally in risk markets in Q2. The S&P 500 Index rose 15.2%, while the MSCI EAFE Index gained 10.8%. Growth stocks outperformed, with the MSCI World Growth Index significantly exceeding value returns. A notable shift in U.S. interest rate expectations followed Kevin Warsh's appointment as chair of the Federal Open Market Committee, pushing Treasury yields higher and strengthening the dollar. Despite the optimistic market environment, concerns about fiscal constraints and limited policy flexibility remain. Tighter credit spreads and elevated equity valuations reflect strong demand for financial ****** ets, with household wealth in equities at a post-WWII high. Earnings expectations are buoyant, driven by AI infrastructure developments. Against this backdrop, Global Fund A Shares returned 2.86% in Q2 2026, with emerging markets and developed Europe as the primary contributors. Developed Asia (excluding ****** an) was the only detractor, and ****** an lagged. Information technology and financials led among equity sectors, while materials and energy detracted. The fund underperformed relative to the MSCI World Index during this period. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG) as a leading performance contributor. Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On August 31, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $335.41 per share, reflecting a market capitalization of $4.13 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -11.22%, while its shares gained 57.19% over the past 52 weeks.
First Eagle Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Shares of Alphabet Inc. (NASDAQ:GOOG)—the parent company of Google and YouTube—rose during the quarter as contracted future revenues from cloud operations continued to be strong, amplified by explosive demand for AI infrastructure, strong AI-focused memory chip production and resilient digital-ad sales. Google's full-stack AI solution underpins prospective long-term momentum for the company, with an anticipated near-term boost from hosting OpenAI's latest generative AI model."
#goog #eagle
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted Alphabet Inc. (NASDAQ:GOOG) as a leading performance contributor. Alphabet Inc. (NASDAQ:GOOG), the parent company of Google, offers various platforms and services, including online search and advertising, cloud solutions, and artificial intelligence. On August 31, 2026, Alphabet Inc. (NASDAQ:GOOG) closed at $335.41 per share, reflecting a market capitalization of $4.13 trillion. Alphabet Inc. (NASDAQ:GOOG) posted a one-month return of -11.22%, while its shares gained 57.19% over the past 52 weeks.
First Eagle Global Fund stated the following regarding Alphabet Inc. (NASDAQ:GOOG) in its Q2 2026 investor letter:
"Shares of Alphabet Inc. (NASDAQ:GOOG)—the parent company of Google and YouTube—rose during the quarter as contracted future revenues from cloud operations continued to be strong, amplified by explosive demand for AI infrastructure, strong AI-focused memory chip production and resilient digital-ad sales. Google's full-stack AI solution underpins prospective long-term momentum for the company, with an anticipated near-term boost from hosting OpenAI's latest generative AI model."
#goog #eagle

11 days ago
First Eagle Investment Management, an investment management company, released its Q2 2026 investor update for "First Eagle Global Fund". The letter can be downloaded here. Easing tensions in the Middle East led to a strong rally in risk markets in Q2. The S&P 500 Index rose 15.2%, while the MSCI EAFE Index gained 10.8%. Growth stocks outperformed, with the MSCI World Growth Index significantly exceeding value returns. A notable shift in U.S. interest rate expectations followed Kevin Warsh's appointment as chair of the Federal Open Market Committee, pushing Treasury yields higher and strengthening the dollar. Despite the optimistic market environment, concerns about fiscal constraints and limited policy flexibility remain. Tighter credit spreads and elevated equity valuations reflect strong demand for financial ***** ets, with household wealth in equities at a post-WWII high. Earnings expectations are buoyant, driven by AI infrastructure developments. Against this backdrop, Global Fund A Shares returned 2.86% in Q2 2026, with emerging markets and developed Europe as the primary contributors. Developed Asia (excluding ***** an) was the only detractor, and ***** an lagged. Information technology and financials led among equity sectors, while materials and energy detracted. The fund underperformed relative to the MSCI World Index during this period. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted Salesforce, Inc. (NYSE:CRM). Salesforce, Inc. (NYSE:CRM) is a cloud computing company that offers Customer Relationship Management (CRM) technology that brings companies and customers together. On August 31, 2026, Salesforce, Inc. (NYSE:CRM) closed at $257.54 per share. Over the past month, Salesforce, Inc. (NYSE:CRM) returned 36.58%, and its shares are up 3.16% over the past year. Salesforce, Inc. (NYSE:CRM) has a market capitalization of $211.96 billion.
First Eagle Global Fund stated the following regarding Salesforce, Inc. (NYSE:CRM) in its Q2 2026 investor letter:
"Despite reporting better-than-expected results for its most recent quarter, shares of enterprise software developer Salesforce, Inc. (NYSE:CRM) were weak during the quarter because of ongoing industrywide concerns that generative AI will trigger an exodus from software applications. We believe that Salesforce's technology serves as an economic moat to the potential disruption of AI because its products are embedded as the foundational system of record for its customers. In addition, we continue to believe that the company is well positioned to grow and scale its Agentforce platform over time."
#NYSE #global #index #management
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted Salesforce, Inc. (NYSE:CRM). Salesforce, Inc. (NYSE:CRM) is a cloud computing company that offers Customer Relationship Management (CRM) technology that brings companies and customers together. On August 31, 2026, Salesforce, Inc. (NYSE:CRM) closed at $257.54 per share. Over the past month, Salesforce, Inc. (NYSE:CRM) returned 36.58%, and its shares are up 3.16% over the past year. Salesforce, Inc. (NYSE:CRM) has a market capitalization of $211.96 billion.
First Eagle Global Fund stated the following regarding Salesforce, Inc. (NYSE:CRM) in its Q2 2026 investor letter:
"Despite reporting better-than-expected results for its most recent quarter, shares of enterprise software developer Salesforce, Inc. (NYSE:CRM) were weak during the quarter because of ongoing industrywide concerns that generative AI will trigger an exodus from software applications. We believe that Salesforce's technology serves as an economic moat to the potential disruption of AI because its products are embedded as the foundational system of record for its customers. In addition, we continue to believe that the company is well positioned to grow and scale its Agentforce platform over time."
#NYSE #global #index #management
11 days ago
First Eagle Investment Management, an investment management company, released its Q2 2026 investor update for "First Eagle Global Fund". The letter can be downloaded here. Easing tensions in the Middle East led to a strong rally in risk markets in Q2. The S&P 500 Index rose 15.2%, while the MSCI EAFE Index gained 10.8%. Growth stocks outperformed, with the MSCI World Growth Index significantly exceeding value returns. A notable shift in U.S. interest rate expectations followed Kevin Warsh's appointment as chair of the Federal Open Market Committee, pushing Treasury yields higher and strengthening the dollar. Despite the optimistic market environment, concerns about fiscal constraints and limited policy flexibility remain. Tighter credit spreads and elevated equity valuations reflect strong demand for financial ****** ets, with household wealth in equities at a post-WWII high. Earnings expectations are buoyant, driven by AI infrastructure developments. Against this backdrop, Global Fund A Shares returned 2.86% in Q2 2026, with emerging markets and developed Europe as the primary contributors. Developed Asia (excluding ****** an) was the only detractor, and ****** an lagged. Information technology and financials led among equity sectors, while materials and energy detracted. The fund underperformed relative to the MSCI World Index during this period. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted HCA Healthcare, Inc. (NYSE:HCA). HCA Healthcare, Inc. (NYSE:HCA) owns and operates hospitals and related healthcare entities. On August 31, 2026, HCA Healthcare, Inc. (NYSE:HCA) closed at $414.45 per share. HCA Healthcare, Inc. (NYSE:HCA) returned 3.42% over the past month, and its shares are up 2.05% over the past year. HCA Healthcare, Inc. (NYSE:HCA) has a market capitalization of $89.72 billion.
First Eagle Global Fund stated the following regarding HCA Healthcare, Inc. (NYSE:HCA) in its Q2 2026 investor letter:
"The leading detractors in the quarter were gold bullion, Charter Communications, Inc. Class A, HCA Healthcare, Inc. (NYSE:HCA), Exxon Mobil Corporation and Salesforce.com, Inc. HCA Healthcare is the largest for-profit hospital operator in the US, with a difficult-to-replicate network of large urban hospitals. Although the company reported sales and profit growth for its most recent growth, HCA reported that patient volumes grew at the low end of guidance, driven partially by declines in respiratory-related emergency room visits, inpatient surgeries and outpatient surgeries. A decrease in enrollment in both Medicaid and Affordable Care Act exchanges was also a headwind. We continue to view HCA's management as an effective steward of both operations and the balance sheet as it continues to return capital to shareholders through share buybacks."
#fund #first
In its second-quarter 2026 investor letter, First Eagle Global Fund highlighted HCA Healthcare, Inc. (NYSE:HCA). HCA Healthcare, Inc. (NYSE:HCA) owns and operates hospitals and related healthcare entities. On August 31, 2026, HCA Healthcare, Inc. (NYSE:HCA) closed at $414.45 per share. HCA Healthcare, Inc. (NYSE:HCA) returned 3.42% over the past month, and its shares are up 2.05% over the past year. HCA Healthcare, Inc. (NYSE:HCA) has a market capitalization of $89.72 billion.
First Eagle Global Fund stated the following regarding HCA Healthcare, Inc. (NYSE:HCA) in its Q2 2026 investor letter:
"The leading detractors in the quarter were gold bullion, Charter Communications, Inc. Class A, HCA Healthcare, Inc. (NYSE:HCA), Exxon Mobil Corporation and Salesforce.com, Inc. HCA Healthcare is the largest for-profit hospital operator in the US, with a difficult-to-replicate network of large urban hospitals. Although the company reported sales and profit growth for its most recent growth, HCA reported that patient volumes grew at the low end of guidance, driven partially by declines in respiratory-related emergency room visits, inpatient surgeries and outpatient surgeries. A decrease in enrollment in both Medicaid and Affordable Care Act exchanges was also a headwind. We continue to view HCA's management as an effective steward of both operations and the balance sheet as it continues to return capital to shareholders through share buybacks."
#fund #first



