

21 days ago
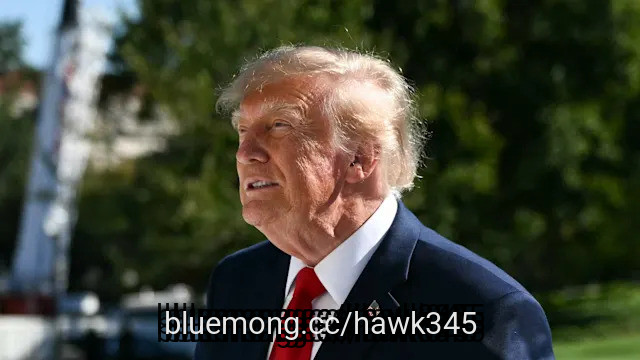
WASHINGTON (AP) — A day after President Donald Trump said he would start paying for controversial taxpayer-funded ads with a campaign account, there's no sign he plans to refund the millions of federal dollars already spent on them.
Nearly $12 million worth of ads have already aired, according to AdImpact, as part of the $20 million the Department of Homeland Security tapped for the contract.
But Trump's plan to pay for the ads with MAGA Inc. doesn't mean there's any reimbursement coming, said a White House official who was not authorized to talk publicly and spoke on the condition of anonymity.
Speaking to reporters Tuesday, Trump said the ads were "really good" and "promotion for the country, done by many presidents before." Asked whether he'd repay the funds already spent, he said, "We'll decide."
Senate Democratic Leader Chuck Schumer slammed Trump for not committing to reimbursement and said he believes the president's plan for covering future costs represents illegal coordination with his super PAC.
#Trump #donald


1 month ago
Vera Bradley, Inc. (NASDAQ:VRA) reported on September 15 that fiscal 2027 second-quarter revenue from continuing operations increased 1.1% to $71.6 million. For the quarter ended August 1, 2026, GAAP operating income from continuing operations reached $4.2 million, compared with a $4.6 million loss a year earlier.
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley


1 month ago
On August 18, Amer Sports (NYSE:AS) reported second-quarter results that beat its own guidance and then raised the bar for the rest of the year. Revenue climbed 32% to $1.63 billion, adjusted operating profit nearly tripled, and every region and segment posted double-digit growth. Diluted earnings per share reached $0.18, up from a much smaller figure a year earlier. What stands out about August 18 is not just the size of the beat but how broad it was.
Technical Apparel grew 32% to $674 million, led by Arc'teryx and backed by a 17% omni-comp gain across owned stores and e-commerce. Outdoor Performance grew even faster, up 37% to $569 million, driven by Salomon Softgoods. Ball & Racquet Sports rose 24% to $390 million on the strength of Wilson Tennis 360. CEO James Zheng pointed to strong double-digit growth across every segment, geography, and channel as the reason for confidence in the outlook.
That confidence showed up in the numbers: Amer Sports raised full-year 2026 guidance to roughly 24% reported revenue growth, a gross margin of 60.5% to 61.0%, an operating margin of 14.2% to 14.5%, and diluted EPS of $1.27 to $1.30. The balance sheet backs up the reinvestment CFO Andrew Page described, with $573 million in net cash and $720 million in cash and equivalents at quarter-end.
Some of the second quarter's biggest numbers lean on a one-time tailwind. Gross margin expanded 710 basis points to 65.6%, but 390 of those points came from net tariff refunds. Operating margin's 820 basis point jump included the same 390-point benefit. The effect is largest in Ball & Racquet Sports, where adjusted segment operating margin rose 1,300 basis points to 17.2%, yet 970 of those points came from tariff refunds alone. Selling, general and administrative expenses rose 30% to $909 million, and on an adjusted basis SG&A grew 33%, faster than revenue itself.
Inventories climbed 19% year over year to $1,897 million. The guidance for the next quarter also points to a slower pace: third quarter revenue growth is guided at 18% to 20%, well below the 32% just reported, with gross margin guided down to about 59.0% and net finance cost alone guided to $15 million to $20 million, against roughly $85 million for the entire year.
#revenue #basis


1 month ago
On September 10, 2026, The Lovesac Company (NASDAQ:LOVE) reported second-quarter fiscal 2027 results for the period ended August 2, 2026. Net sales rose 0.4% to $161.2 million, a record for the quarter, and the company swung to net income of $7.4 million, or $0.51 per diluted share, from a loss of $6.7 million a year earlier. Inside that $0.51 sits $0.86 of net benefit from IEEPA tariff refunds. Omni-channel comparable sales fell 1.9%.
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter


1 month ago
The Children's Place, Inc. (NASDAQ:PLCE) reported on September 14 that fiscal second-quarter net sales declined 18.9% year over year to $241.8 million. Reported gross margin rose to 34.4% from 34.0% a year earlier for the quarter ended August 1, 2026.
The apparent margin improvement depended heavily on $39 million of tariff refunds recognized as a reduction of cost of sales. That benefit was equivalent to nearly 47% of reported gross profit of $83.3 million.
Management said gross margin excluding the refunds declined 1,550 basis points, or 15.5 percentage points, year over year. This non-GAAP comparison removes the cost-of-sales benefit. The central question is whether inventory cleanup can establish a healthier operating base.
The Children's Place, Inc. (NASDAQ:PLCE) reduced inventory to $340.2 million, down 23.2% from $442.7 million a year earlier. A smaller inventory position allows management to improve the merchandise mix and reduce future exposure to aging products.
Clearing excess stock can release working capital and create room for products better aligned with demand. The eventual benefit depends on rebuilding sales with less discounting, but reducing the stock burden is a useful starting point.
#reported #Margin

1 month ago
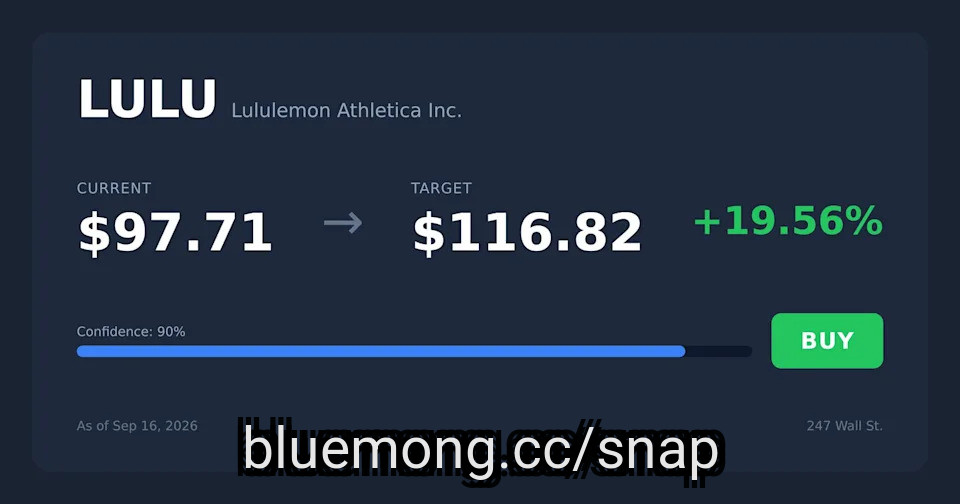
Lululemon fell 18% after Meghan Frank delivered a second guidance cut, dropping the full-year EPS outlook to roughly $9.60 from last year's $13.26.
Nike fell 10% and On Holding dropped 14% over the same month, suggesting athletic-apparel sector headwinds extend well beyond Lululemon alone.
An 86-cent tariff refund inflated Q2 EPS but won't recur, making Lululemon's reported profit look cleaner than the challenge facing incoming CEO Heidi O'Neill.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Lululemon didn't make the cut. Enter your email to see the names that beat LULU. The report is free. Enter your email and see if any of your stocks made the cut.
Lululemon Athletica (NASDAQ:LULU) stock is under sustained pressure after a September earnings update that lowered management's outlook for the year. Retail broadly softened alongside it, and the broad market held up better, which frames the question of how much of the damage is company-specific and how much is sector-wide. Peer moves are part of that same picture, since athletic-apparel names moved lower together across the past month.
#lululemon #enter #outlook



1 month ago
In March, shortly after the Supreme Court struck down President Donald Trump's International Emergency Economic Powers Act (IEEPA) tariffs and paved the way for $100 billion in import taxes being redistributed back to American importers, U.S. Trade Representative Jamieson Greer shared his idea of what these companies should do with this influx of cash.
"If I were these companies, and somehow they get this windfall, the most important thing and the smartest thing they should do is give it as bonuses to their workers," Greer told CNBC.
It appears some companies have heeded Greer's suggestion. As businesses receive more than $100 billion the U.S. Treasury has doled out in refunds since May, many are vowing to lower prices or pay down debts. A handful, however, are giving the cash back to their employees.
In its second quarter earnings report last month, houseware brand Williams Sonoma said it would allocate $10 million for one-time payments to 401(k) accounts to eligible employees "in recognition of their efforts navigating the IEEPA tariffs."
"We're so appreciative to have the money back and to be able to reward our employees with part of it," President and CEO Laura Alber said on an earnings call. "They have done such an amazing job."
#Companies #employees

1 month ago
Inquiring about Walmart Inc. (NASDAQ:WMT) on September 10, a caller asked if they should "keep it." Mad Money host Jim Cramer replied:
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose

1 month ago
On September 9, American Eagle Outfitters Inc. (NYSE:AEO) revealed results for its fiscal 2026 second quarter. The company achieved an 8% year-over-year topline growth with net revenue figures of $1.38 billion. The second quarter operating profit jumped up to $211 million compared to $103 million during the same period last year. As a result, diluted earnings per share for the quarter stood at $0.79 in comparison with $0.45 for Q2 FY25. This led to a $21 million distribution to shareholders with a dividend payout of $0.125 per share.
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable


1 month ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Delivered total revenue growth of 1.1%, marking the second consecutive quarter of expansion as the Project Sunshine transformation gains traction.
Direct segment revenue grew 8% with comparable sales up 9.2%, serving as the primary indicator of customer resonance with new product and marketing strategies.
Gross margin expanded by more than 40 basis points (excluding tariff refunds) through disciplined pricing, promotion governance, and improved product ****** ortment productivity.
Indirect channel revenue contracted 39% due to intentional shifts in marketplace strategy and a strategic reduction in liquidation sales to protect brand equity.
#tell
1 month ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period

1 month ago
Jim Cramer raised concerns about The TJX Companies, Inc. (NYSE:TJX) during the September 10 episode of Mad Money, as he said:
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#year


1 month ago
Jim Cramer raised concerns about The TJX Companies, Inc. (NYSE:TJX) during the September 10 episode of Mad Money, as he said:
We had our CNBC Investing Club meeting today… I review each of the Charitable Trust positions on the call. This time, it was pretty clinical until I got to TJX, the off-price retailer. Candidly, I lost it on TJX. I've owned the stock for the Trust for as long as I can remember, and I've never felt so worried about this franchise. They have a bunch of divisions, but the biggest one, Marmaxx, consisting of TJ Maxx and Marshalls, really blew it. Management told us that they had figured out what had gone wrong and they've already fixed it, but because of competitive reasons or whatever, they wouldn't tell us what went wrong and they wouldn't tell us how they fixed it. I found that infuriating…
I came close to saying, forget it, Jim, it's retail. Sometimes retail is seductive. I love my local TJ Maxx, and I think Home Goods is a fun place to shop. The company's almost always about the best in the industry, crushing Burlington and Ross Stores. But this time, shockingly, Ross Stores upside surprised. It crushed TJX, much better than expected... So why bother sticking your neck out for something in this group? Simple. Because some of the greatest stories of all time have come from retail. Costco's been an incredible long-term performer. Walmart's been terrific. And TJX, it's been a wonder, one of the best stocks ever.
Could they really suddenly have lost it? Did they go all LULU? I don't think so. What happens, though, is you have to be conscious that TJX is right now being buffeted by its group, which is trading down because of the decline in discretionary income from the tax that is higher gasoline. We can't tell how much of its underperformance comes from that alone or maybe the mistakes that management made and says they've corrected. In other words, these retail stocks are very hard to own, even as they seem so easy to grasp.
TJX Companies, Inc. (NYSE:TJX) reported second-quarter fiscal 2027 sales of $15.18 billion, up 5% year over year, while consolidated comparable sales increased 4%. Adjusted diluted EPS rose 11% to $1.22, and the company raised its full-year diluted EPS outlook to $5.31-$5.36, or $5.15-$5.20 excluding an expected $0.16 net benefit from tariff refunds. The weakness was concentrated in Marmaxx, which includes TJ Maxx, Marshalls and Sierra. Comparable sales increased just 1%, down from 6% in the first quarter, while HomeGoods, TJX Canada and TJX International each posted comparable-sales growth of 6% or more.
#sales #time #NYSE


1 month ago
On September 10, Lovesac (NASDAQ:LOVE) reported record second quarter revenue of $161.2 million, its highest Q2 total ever, even as its entry-level furniture shopper kept pulling back. The 0.4% sales increase came almost entirely from showrooms rather than higher-margin online orders, and the quarter's real profit boost was traced to a one-time source. A $20 million tariff refund lifted gross margin by 1,200 basis points to 68.4%, masking an underlying business that actually lost money once that windfall is stripped out.
Configurations priced above $6,000 grew by double digits during the quarter, even against a strong comparison from a year earlier, and management pointed to that segment as the clearest sign the brand's value proposition still resonates. Showroom net sales climbed 4.6% to $114.1 million, helped by 14 net new locations opened over the past year and a double-digit jump in conversion rates that offset softer foot traffic.
The Snugg platform, a smaller and more digitally oriented sofa line, helped push "other products" revenue up 198.2%, with more than half of Snugg sales happening online, giving Lovesac a lower-priced entry point into the brand. The Loved by Lovesac resale program is doing similar work, with 70% of its customers new to the company.
Behind all of this sits a pipeline of four major launches set for the second half: a personalized comfort feature for Sactionals, an entirely new large-format premium seating platform, Snugg accessories including a corner piece and swivel base, and the start of onshore Sactionals seat manufacturing, alongside a national rollout of White Glove and Room of Choice delivery. The balance sheet backs it up, with $68.8 million in cash, no debt, $34 million in unused borrowing capacity, and $7.2 million in buybacks with $46.9 million left under the current authorization.
Omni-channel comparable sales fell 1.9%, driven by demand pressure below $6,000, where management said inflation, higher interest rates, and a spike in gas prices have hit the same buyers for several quarters running. Internet sales dropped 5.3%, Sacs sales fell 8.6%, and the exit of the Best Buy shop-in-shop partnership cut "other" net sales by 23.2%. Strip out the tariff refund and adjusted EBITDA was actually a loss of $1.3 million, compared with income of $0.8 million a year earlier, a sign the core business is less profitable than the headline numbers suggest.
#million #quarter #revenue


1 month ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands


1 month ago
On September 10, 1-800-Flowers.com Inc. (NASDAQ:FLWS) reported fiscal 2026 results that read like a company still finding its footing after a hard year. Full year revenue fell 10.8% to $1.5 billion, and the fourth quarter alone dropped 12.9% to $293.1 million, as consumers stayed selective with discretionary spending on gifts and gourmet food. Buried under those declines, though, is a different story: inventory shrank, free cash flow improved by $55 million, and the company hit a two-year cost savings target a full year early. The question now is whether that discipline can outrun the sales slide.
1-800-Flowers spent fiscal 2026 tearing down the walls between its brands. Instead of separate teams running each brand in silos, the company shifted to functional teams built around marketing, merchandising, and the digital shopping experience, with one team now acting as store manager for every website. That shift already shows up in products: the floral business combined its florist-fulfilled and direct-ship merchandising teams, so the same popular arrangements are available either way, instead of competing against itself on one landing page. Harry & David rolled out a redesigned, mobile-first website with AI-powered search that is currently in A/B testing, and several low-traffic standalone sites were folded into harryanddavid.com to concentrate traffic rather than split it.
The financial discipline behind that reorganization is real. The company reached its $50 million cost savings run rate a full year ahead of schedule and has already lined up another $15 million to $20 million in savings for fiscal 2027, with the full benefit landing in fiscal 2028. That, combined with tighter working capital management, pushed free cash flow up $55 million year over year and cut inventory to $153 million from $177 million. Average order value rose 5.5%, third-party marketplace sales through Amazon, Walmart, and DoorDash are growing at double-to-triple-digit rates and are already contribution margin positive, and BloomNet grew 1.9% on the back of local delivery partnerships with apps like DoorDash and Instacart.
The rest of the story is bleaker. Total transactions fell 17.6% for the year, and the fourth quarter's decline was broad-based: consumer floral and gifts dropped 13.4% to $182.8 million as the company pulled back on promotional discounting, and gourmet foods and gift baskets fell 15.4% to $85.8 million, a decline made worse by the timing of Easter. Adjusted EBITDA for the year collapsed to $2.9 million from $29.2 million, and adjusted gross margin slipped 110 basis points to 38%. Even the fourth quarter's 34.7% gross margin leaned on a one-time $7 million tariff refund.
#fiscal

1 month ago
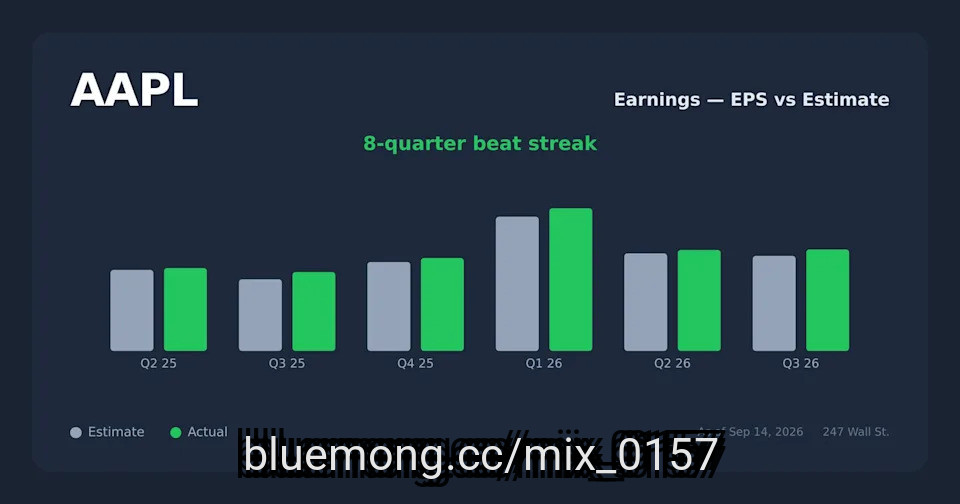
Apple trades at 37x earnings after a 45% one-year run; Microsoft sits at 27x and is up just 3% year to date, offering a cheaper AI entry point.
Apple's quarterly beat included tariff refunds worth 2 points of gross margin, making the underlying business performance thinner than headline numbers suggest.
Azure crossed $100B in annual revenue growing 43%, and Microsoft's $678B commercial backlog, which is up 84%, signals compounding enterprise AI earnings power into 2028.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Apple didn't make the cut. Enter your email to see the names that beat AAPL. The report is free. Enter your email and see if any of your stocks made the cut.
Apple (NASDAQ: AAPL) and Microsoft (NASDAQ: MSFT) both closed the summer with blowout quarters.
#Apple #NASDAQ #stocks



2 months ago
Lululemon Athletica Inc. (NASDAQ:LULU) recently issued its second guidance cut of the year, and investors responded immediately by sending shares down roughly 18%. That selloff came despite an EPS beat, but the headline result was heavily supported by a tariff refund rather than underlying business strength. Brand sentiment, traffic, and leggings sales are all weakening across the company's two largest markets. The key issue for investors is no longer whether the quarter was weak, but whether the stock's low valuation and new CEO can provide the catalyst for a meaningful recovery.
Lululemon shares dropped 18% after the company lowered its full-year guidance for the second time this year. Revenue is now projected to range from $10.35 billion to $10.5 billion, while EPS guidance was reduced to $9.48 to $9.73. Both represent sharp reductions from its earlier guidance ranges. Second-quarter revenue was particularly weak, falling 4% to $2.4 billion and coming in below consensus estimates, while comparable sales dropped 9%, or 10% on a constant-dollar basis. According to the company, negative commentary had affected traffic in both the U.S. and China, while leggings sales slowed more than expected. Although reported EPS beat estimates, nearly all of that upside came from an $0.86 per share tariff refund. For the third quarter, management expects revenue to decline another 10% to 11%.
Lululemon still has several financial advantages that could support the business through its current slowdown. The company has no outstanding borrowings and maintains $1.4 billion in cash. First-half operating cash flow climbed to $589 million, more than double the prior year. Inventory per unit also declined roughly 7% year over year, reducing the risk of a margin-damaging clearance event. Meanwhile, shares have fallen over 50% year-to-date and now trade at a historically depressed valuation, potentially creating an out-of-favor-setup for investors. At the same time, management continued its buyback program, repurchasing $330 million worth of shares during the quarter.
The weakness in traffic and leggings sales cannot be ignored, and both remain serious concerns. However, the company has a debt-free balance sheet, stronger cash generation, and a valuation that already reflects much of the recent bad news. That gives Lululemon room to prove that its current struggles are mainly execution-related rather than signs of a structural decline.
#year #shares #company

2 months ago
Apple (AAPL) is selling iPhones and Macs faster than it can build them, but the number a holder should fear most is the gross margin underneath those sales. Leaving out tariff refunds, that margin fell in the June quarter and is guided lower again for the September quarter. Management puts both steps down to rising memory prices, while the stock's price-to-earnings multiple sits near the top of its 10-year range.
Excluding Tariff Refunds, Apple's Margin Slips As iPhone And Mac Set June-Quarter Records
Demand is not the worry. iPhone revenue rose 22% from a year earlier in the June quarter and Mac revenue rose 29%, both June-quarter records. Management says the brake on sales is supply of the advanced nodes its chips are made on.
Reported gross margin was 50.1% in the June quarter, but tariff refunds supplied about two points of it. Without them, the margin fell 120 basis points from 49.3% in the March quarter, and the September-quarter guide takes off another 160 basis points at its midpoint. On $466.8 billion of revenue over the past year, each point of gross margin is worth about $4.7 billion of gross profit.
And Management Says Memory Prices Explain All Of That Slide
#gross #tariff #year


2 months ago
As continuous inflation squeezes household budgets, the discount retail sector should potentially benefit across the board, with middle- and lower-income consumers looking for value driving foot traffic into value chains. That's roughly what happened in the second-quarter reports from Dollar General Corporation (NYSE:DG) and Dollar Tree, Inc. (NASDAQ:DLTR), both of which were released in late August. Both retailers outperformed expectations, though only one company's stock was rewarded for this.
Dollar General Corporation (NYSE:DG) reported second-quarter results on August 27 that exceeded expectations, and shares rose more than 6.5% in premarket trading. Net sales increased 5.2% to $11.29 billion, surpassing the $11.2 billion market forecast, while diluted EPS came in at $2.48, up 33.3% year-over-year and well above the $2.01 ******* ysts projected. Same-store sales increased 3.5%, driven by a 2.0% increase in customer traffic and a 1.5% increase in average transaction amount, marking the fifth consecutive quarter of traffic growth and the sixth consecutive quarter of positive comps across all four merchandise categories.
Management improved their full-year estimate across the board: same-store sales growth is now expected to be 2.5% to 2.9%, up from 2.2% to 2.7% before, while full-year EPS guidance increased to $7.80-$8.00 from $7.20-$7.45. Tariff refunds, a lower LIFO provision, and improved shrink and damages helped increase the gross margin by 127 basis points to 32.6%. CEO Todd Vasos also pointed to continued market share gains from higher-income households switching away from traditional grocers, a trend the company has cited for several quarters, with management announcing plans to resume up to $700 million in share buybacks in the latter half of the year, backed by remodels under its Project Renovate and Project Elevate initiatives.
Dollar Tree's results, released on August 27, indicate a more complicated situation. Diluted EPS came in at $2.70, including a $1.31-per-share net benefit related to tariff refunds, while revenue increased 7% year-over-year to $4.89 billion. Comparable store sales up 3.7%, driven by a 3.3% gain in average ticket and a 0.4% increase in traffic, a return to positive traffic that occurred a full quarter ahead of management's internal plan.
However, the headline figure includes an important caveat: $1.31 of the $2.70 in EPS came from the net impact of $383 million in IEEPA tariff refunds after related reinvestment spending, duties, and taxes. Strip that out, and underlying EPS was $1.39, above the $1.00-$1.15 range management had guided to in May and about 23% above the $1.13 consensus estimate.
#TRAFFIC
2 months ago
On September 3, Genesco (NYSE:GCO) reported a second quarter that should not have worked on paper. Revenue fell 3% to $530 million, yet the company nearly halved its adjusted operating loss and raised full-year earnings guidance to the top end of its range. That combination, shrinking sales alongside expanding profit, is the footwear-first strategy showing up in real numbers. Every one of the company's three brands beat internal expectations, and management says the toughest sales pressure ahead is coming from a deliberate choice rather than a weakening business.
Journeys, the company's teen-focused chain, delivered its eighth consecutive quarter of positive comparable sales, up 2%, even while lapping strong growth from a year earlier. The more interesting story sits underneath that number. The Journeys 4.0 store format, a redesigned concept built around a more elevated ***** ortment, is generating a sales lift of 25% or more wherever it opens, and the company expects roughly 180 locations, about a fifth of its fleet, running that format by year-end. That rollout, combined with fleet optimization and more efficient use of selling staff, handed Journeys 180 basis points of expense leverage in the quarter. Comparable sales kept accelerating into August, marking Journeys' ninth straight month of positive comps and a mid-single-digit gain during the back-to-school peak.
Johnston & Murphy is running its own streak, with comparable sales up 4% in its third consecutive positive quarter, helped by a newly extended, multiyear partnership with Peyton Manning and a broader shift in menswear toward more refined, put-together dressing. Companywide, adjusted gross margin expanded 140 basis points to 47.2%, and the adjusted operating loss narrowed to $8 million from $14 million a year ago. Genesco also collected $22.5 million in tariff refunds during the quarter and cut total debt to $15.8 million from $71 million a year earlier, giving a new CFO and a new Schuh president a far healthier balance sheet to work with as they settle into their roles.
The drag comes almost entirely from Schuh, Genesco's UK chain, where comparable sales fell 9% as management deliberately pulled back on discounting to protect margin. Executives were blunt about the cost of that choice. CEO Mimi Vaughn said "the UK consumer market remains challenged and price sensitive," and the Schuh turnaround is expected to take longer than the one already underway at Journeys. That pressure is now baked into guidance. Full-year total sales are expected to fall about 2%, worse than the prior forecast of down 1% to flat, with management incorporating more back-half sales pressure than it originally planned for given how promotional the UK footwear market has become.
#comparable #schuh #management #pressure
2 months ago
Sen. Ted Cruz (Texas), a prominent conservative voice in the Senate GOP conference, says he's willing to support President Trump's proposal to give $5,000 dividend payments to U.S. adults provided that they are structured as tax refunds and go to people who work and pay taxes.
Asked about Trump's proposal, Cruz told Fox News's Jesse Watters that his support "depends on how it's structured."
"I would like to see it structured as a tax refund," he said. "I would be all for structuring it as a tax refund."
"But I think we should be incentivizing work. I don't think we should be paying people that are not working," he argued.
Trump unveiled the proposal at the GOP midterm convention in Dallas and has drawn pushback from both Republican moderates and conservatives.
#texas


2 months ago
Oxford Industries, Inc. (NYSE:OXM) reported fiscal second-quarter net sales of $394.4 million, down 2.2%. Full-price direct-to-consumer sales declined 1%, while wholesale sales fell 14%, primarily reflecting lower off-price sales.
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap


2 months ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the sequential improvement in comparable sales to enhanced digital conversion and the successful scaling of private brand franchises like THERMACHILL.
The company is navigating a structural shift in customer behavior driven by GLP-1 medication adoption, which has led to temporary pauses in apparel purchasing during weight loss journeys.
Performance was significantly bolstered by a $4.6 million IEEPA tariff refund, which masked a 70 basis point decline in underlying merchandise margins caused by higher markdowns and shipping surcharges.
Strategic focus has shifted toward 'Fit Authority' through the FITMAP initiative, which has scanned 150,000 customers and resulted in higher average order values and lower return rates.
#performance

2 months ago
Apple Inc. (NASDAQ:AAPL) and Intel Corporation (NASDAQ:INTC) represent two sides of a historical silicon transition. A September 2 report from MacRumors highlighted a key milestone: Apple notified developers that universal Mac App Store apps requiring macOS 13 or later can now drop support for Intel-based Macs. Removing Intel binary slices simplifies app development and reduces download sizes. While symbolic, the move underscores Apple's completed transition to Apple Silicon and highlights Intel's diminishing footprint within Apple's high-margin ecosystem.
Financially, Apple is faring significantly better than Intel.
For Q3 2026 (ended June 27, 2026), Apple reported record quarterly revenue of $109.4 billion, up 16% year-over-year, driven by double-digit growth across iPhone, Mac, and Services. The company's gross margin reached 50.1%, supported by a 2 percentage point favorable impact from tariff refunds. Diluted earnings per share (EPS) surged 29% year-over-year to $2.02, which included a $0.11 favorable boost from tariff refunds. Operating cash flow and active installed base both set new June quarter records.
Intel's Q2 2026 financial results (ended June 27, 2026) delivered $16.1 billion in quarterly revenue, up 25% year-over-year, marking its fastest top-line growth in over 15 years. Intel reported a GAAP net loss of $11.0 billion (GAAP EPS of -$2.16), largely driven by non-cash charges and mark-to-market adjustments. However, on a non-GAAP basis, net income reached $2.2 billion ($0.42 diluted EPS), nearly doubling consensus expectations. Non-GAAP gross margin expanded to 41.8% (40.4% GAAP) on strong product mix and factory yields.
Apple's bull case centers on expanding Services margins, strong ecosystem lock-in, and the potential for Apple Intelligence to drive further demand and engagement across iOS and macOS devices, supporting high-margin growth. On the other hand, Apple faces risks from elevated valuation multiples, sluggish growth in Greater China, where Q3 revenue reached $14.7 billion, and ongoing global antitrust scrutiny over App Store fees.
#revenue

2 months ago
Ollie's Bargain Outlet Holdings Inc.'s (NASDAQ:OLLI) second quarter results were characterized by robust loyalty membership growth, store count expansion, and a notable boost in earnings despite weakness in comparable store sales. During the quarter, the retailer opened 15 new locations and shut down one store because of storm-related damages. This pushed its overall store count to 686 across 36 states, a year-over-year jump of 11.9%. The ongoing growth in its store network continues to be the core focus of Ollie's expansion roadmap, as the management recently confirmed its plans to open 75 new stores by the end of this fiscal year. Such a strategy strongly reflects on the extended growth potential of Ollie's existing business model.
Photo by Franki Chamaki on Unsplash
The company's loyalty program, Ollie's Army, continued to gain momentum during the recent quarter, raising its reach to 18.1 million members. This helped push net sales higher by 9.1% to $741.3 million, with the gain coming mainly from newly opened stores rather than sales at existing locations. Even with comparable sales trending downward, key profitability figures showed clear improvement.
With lower supply chain-related costs, gross margins expanded to 43.5%. A key factor behind this jump was the IEEPA tariff refunds, which contributed 380 basis points to gross margin on their own, in addition to broader reductions in tariff rates. This tariff-related benefit served as a meaningful cushion, helping to overcome the drop in comparable sales.
Together, these factors fueled substantial growth in the bottom line as the adjusted net income climbed 40.3% to $85.4 million, and adjusted net income per diluted share rose 43.4% to $1.42. This represented an outsized growth compared to overall sales growth, which highlights the impact of tariff refunds and margin improvements on the overall results.
#Growth #tariff
2 months ago
Signet Jewelers early Wednesday easily beat fiscal second-quarter earnings estimates and guided higher for the full year. Shares of the long-term laggard surged in morning trade.
For its second fiscal quarter, Signet Jewelers (SIG) reported adjusted earnings per share of $2.19, up 36% vs. a year earlier and handily beating **** ysts' expectations of $1.74, reflecting improved margins. Sales of $1.53 billion were in line with views and a fraction below the $1.54 a year earlier.
The owner of Kay Jewelers, Zales and Jared now eyes 2027 adjusted EPS of $10.45 to $12.15, up from its prior target range of $9.20 to $11. It still sees sales of $6.7 billion to $6.9 billion. **** ysts' expect $10.82 in adjusted EPS on revenue of $6.84 billion.
Signet also announced plans for a $125 million accelerated share repurchase deal "this month."
"We are raising our full year adjusted EPS guidance by over 10% to reflect year-to-date operating performance, additional share repurchases, refunds of tariffs previously paid, and the terms of the new consumer credit agreement," said COO and CFO Joan Hilson.
#year #second

2 months ago
On August 5, Cytek Biosciences (NASDAQ:CTKB) reported financial results for the second quarter ended June 30, and the report reads like two different companies at once. Revenue climbed, margins widened, and the installed base of instruments kept expanding. At the same time, the net loss more than doubled from a year earlier and adjusted EBITDA swung negative. For a company selling hardware into cell ***** ysis labs, that split between growing revenue and growing losses is the story investors need to untangle.
Total revenue reached $48.1 million in the second quarter of 2026, up 6% from the second quarter of 2025, and the growth came from more than one source. Cytek expanded its installed base to 3,933 instruments as of June 30, 2026, adding 142 units in the quarter, and each new machine tends to pull in service and reagent sales over time. That dynamic already shows up in the numbers: recurring revenue from service and reagents hit $18.5 million in the quarter, and on a trailing 12-month basis it now makes up 35% of total revenue, up from 32% a year earlier.
Gross profit told a similar story, climbing 19% to $28.3 million, with GAAP gross margin rising to 59% from 52% and adjusted gross margin reaching 61% from 56%. Some of that lift came from a one-time tariff refund, but even stripped of it, adjusted gross margin still improved to 56%. Cytek also launched the Borealis, a 7-laser flow cytometer built for 60-color panels, and rolled out more automated configurations of its Aurora Evo line, giving the sales team new hardware to sell into the rest of 2026. Full-year revenue guidance moved up to a range of $207 million to $212 million, raising the midpoint by $1 million.
The same quarter that grew revenue also widened the losses. Operating expenses rose 15% year over year to $39.7 million, with general and administrative costs jumping 24% to $16.8 million because of litigation-related expenses, severance, and other personnel costs. R&D spending grew 10% to $9.7 million, and sales and marketing rose 9% to $13.2 million, so the increase was not confined to one line item. The loss from operations widened to $11.4 million from $10.6 million a year earlier, and net loss more than doubled to $12.2 million from $5.6 million.
Adjusted EBITDA, which strips out stock-based compensation and currency swings, swung to a $1.5 million loss from a positive $1.3 million a year earlier, after also adjusting for a write-off tied to an early-stage technology investment. The tariff refund that boosted this quarter's headline gross margin also means the underlying figures, 53% GAAP and 56% adjusted, are the more honest baseline going forward. Cash and marketable securities held roughly flat at $262.0 million as of June 30, 2026, down only slightly from $262.2 million three months earlier, so the balance sheet has not yet felt the strain.
#quarter #adjusted

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributed the significant improvement in adjusted operating income to tariff claim refunds received during the quarter, while also noting gross profit expansion driven by elevated ****** ortment, disciplined sourcing, and improved markdown management.
Retail segment softness was primarily driven by a 200 basis point headwind from seasonal sandals, which suffered from early weather-related challenges and failed to rebound.
The company achieved 150 basis points of core gross margin expansion through disciplined markdown management and elevated ****** ortments, despite operating in a highly promotional market environment.
Brand portfolio growth of 18% was fueled by double-digit wholesale increases, demonstrating the successful scaling of exclusive brands like Topo and Jessica Simpson across multiple distribution channels.
#operating #gross #expansion

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Pop star Pink is under fire online for resharing an anti-Israel message and then following it up with a series of Instagram posts directed at her detractors.
Macklemore, whose real name is Benjamin Hammond Haggerty, supported British musician Ed Sheeran on stage at MetLife Stadium in New Jersey in a show called Loop Tour on September 4 and 5. Donning a keffiyeh in front of an 80,000-strong audience, the rapper shouted "Free Palestine" and addressed Gaza and the occupied West Bank, saying that they are not being forgotten.
"Every human being walking on this earth deserves exactly the same freedom," he added, as reported by Variety.
The rapper then performed his protest song "Hind's Hall," which featured flashes of Gaza on the stadium screens. Macklemore referenced Hind Rajab, a young Palestinian girl killed in Gaza, named after student demonstrators at Columbia University who renamed a campus building in her honor. The rapper then addressed Jewish concertgoers, saying that criticizing Israel and condemning their actions as genocide is not a condemnation of Jewish people and that his message is a message of peace and dignity for everyone.
American pop diva, whose legal name is Alecia Beth Moore Hart, posted a video with the message "Awful" to her Instagram Story, claiming that Jewish fans who came to see Sheeran's performance are exposed to propaganda against Israel. According to Pink, Macklemore's speech and video presentation amount to a false accusation of genocide, and people who came to the concert are entitled to "apologies and refunds."
#Instagram #macklemore




