

1 month ago
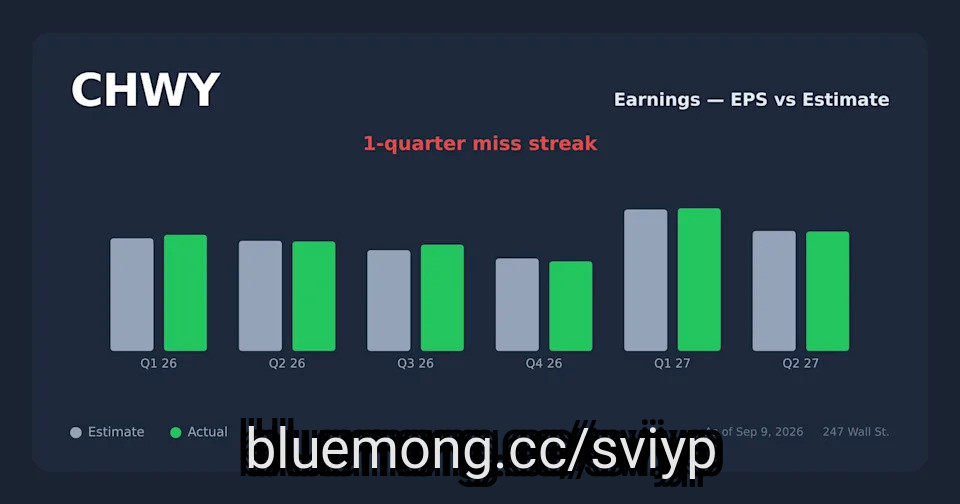
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

2 months ago
Investors are bailing on Chewy (CHWY) shares on Sept. 11 after a senior JPMorgan ***** yst downgraded the online pet food and supplies retailer to "Neutral." In his research note, Doug Anmuth reduced his price objective on CHWY to $24, although that still represents about a 20% upside from current levels.
Chewy stock has been out of favor with investors in 2026. It is currently down nearly 40% versus the start of this year.
GME Stock Jumps as GameStop CEO Ryan Cohen Buys $20 Million Worth of Shares
Rocket Lab Stock Just Scored a New Bullish Rating
Cathie Wood Just Bet $45 Million on This Beaten-Down ***** e Stock. Wall Street Sees 70% Upside.
#Stock #investors #jpmorgan



2 months ago
Chewy dropped 9% after free cash flow fell 15% to $89.5M despite beating revenue estimates, while Petco slid 6% on sector contagion.
Freshpet bucked the sector weakness, rising 2% on 15.5% revenue growth and a raised 2026 sales outlook.
Chewy's Autoship sales hit 84.6% of revenue with 21.7 million active customers, anchoring the bull case for its multi-quarter reinvestment cycle.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Chewy didn't make the cut. Enter your email to see the names that beat CHWY. The report is free. Enter your email and see if any of your stocks made the cut.
Chewy (NYSE:CHWY) stock is down 11% midday on Wednesday to $20.68 after the online pet retailer reported fiscal Q2 2027 results that carried a free cash flow shortfall large enough to swamp a raised full-year outlook. The setup is unusual because both the revenue and the adjusted earnings landed close to where **** ysts had expected.
#enter #cash #raised #sales


2 months ago
One problem in the artificial intelligence industry that just doesn't seem to be going away: Companies still aren't saying new AI tools are making them more profitable.
"While it's easy to find anecdotal examples of AI-driven margin gains or cost-cuts, economically meaningful implementation seems uneven at best," Barclays strategist Venu Krishna wrote in a note on Thursday.
"While nearly half of all companies talked about AI [on recent earnings calls], only 12% were willing to quantify AI-related value capture," Krishna added. "Of those, tech, financials, and healthcare companies were over-indexed at 68% of the total. The average reported gain in operational efficiencies seems impressive at first blush at 56%, but these ******* sments have not meaningfully changed over the last three years of LLM advances, calling their precision into question."
Krishna noted that Meta's (META) AI tools delivered an 8.3% increase in Facebook ad clicks and a 15.7% uplift in conversions.
Online pet care retailer Chewy (CHWY) is targeting $50 million in cost savings in fiscal year 2027 through AI deployed across fulfillment and customer service.
#cost #barclays


2 months ago
Ro Khanna is a Democratic congressman from California whose stock picks keep making headlines. His latest financial disclosures show steady buying in two names through June and July.
Uber Technologies, Inc. (NYSE:UBER) shows up more than any other stock in the filing. Khanna's disclosures list several separate Uber purchases between June 15 and July 29, with no sales in that stretch. Uber is down about 18% over the past year.
Chewy Inc. (NYSE:CHWY) is the second name. The filing shows nine Chewy purchases between July 13 and July 30.
Chewy is down about 40% over the past year and 30% so far this year. Is this a potential opportunity to buy the stock on the dip? Let's **** yze.
Chewy, Inc. (NYSE:CHWY) sells pet food, treats, supplies and medications online. The business runs on Autoship, a subscription program where customers set up recurring deliveries.
#chewy #chwy #shows


2 months ago
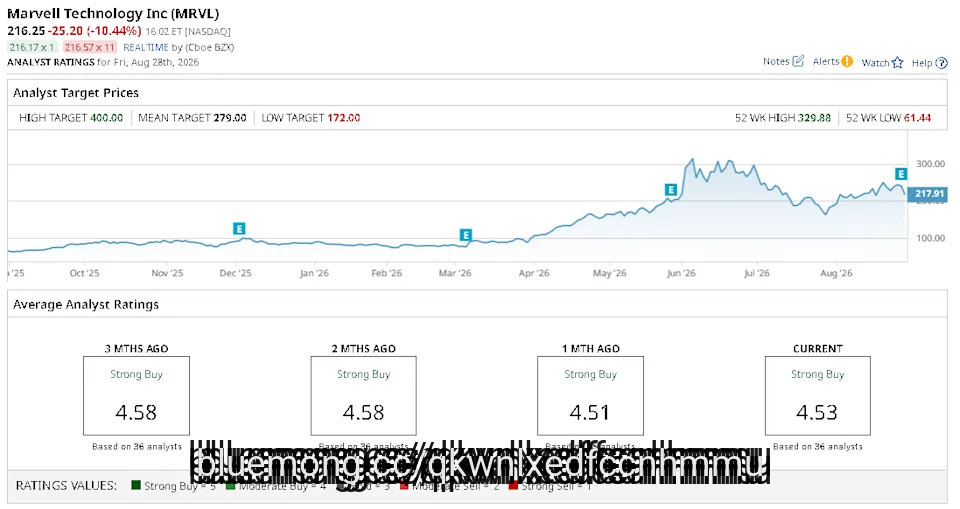
Marvell (MRVL) stock was under significant pressure on Aug. 28 even though the custom chip specialist posted a market-beating Q2, featuring a 37% year-on-year increase in revenue.
Crucially, the semiconductor giant also raised its guidance for fiscal 2028 to around $18 billion, which would represent 50% growth on a year-over-year basis.
HP, Inc. Delivers Strong Earnings, Revenue and FCF - Short-Put Plays Still Have High Yields
BAC, CHWY, SONY: Play Unusual Options Activity in These 3 Low-Cost Call Options Under $100
PayPal Stock Drops as Buyout Plans Fall Through. Where Barchart Options Data Says PYPL Could Be Headed Next.
#marvell


3 months ago
Choosing between a high-growth technology powerhouse and a steady consumer leader requires a look at whether you prefer rapid innovation or predictable recurring revenue. Axon Enterprise Inc (NASDAQ:AXON) and Chewy Inc (NYSE:CHWY) offer very different paths.
Axon provides mission-critical hardware and software for law enforcement, making it a vital infrastructure play for public safety. Chewy dominates the digital pet supply market by focusing on high-frequency consumable goods. While their industries differ, both companies utilize technology to build deep competitive moats in their respective sectors.
Axon Enterprise operates as a leader among defense stocks by providing an integrated ecosystem of Taser energy devices, body-worn cameras, and cloud-based evidence management software. The company primarily serves federal, state, and local law enforcement agencies, but it is expanding its reach into fire, EMS, and commercial security markets. This strategy creates a sticky business model where hardware sales lead to long-term software subscriptions for data storage and ******* ysis.
In FY 2025, revenue reached nearly $2.8 billion, representing a roughly a third increase over the prior year. The company reported net income of nearly $125 million, down from $377 million in 2024, resulting in a net margin of approximately 5% in 2025. This performance highlights the company's challenge of scaling its operations while maintaining positive returns for its shareholders.
As of its December 2025 balance sheet, the debt-to-equity ratio is roughly 0.6x, a metric comparing total debt to shareholder equity to show reliance on loans. Free cash flow for the period was nearly $75.1 million, though stock-based compensation represented roughly 300% of operating cash flow, meaning reported cash generation is heavily inflated by this non-cash add-back.
#axon #million



4 months ago
Chewy Inc. (NYSE:CHWY) is one of the top mid-cap stocks to own for decades, according to hedge funds. On June 30, BofA Securities reiterated a Buy rating on Chewy Inc. (NYSE:CHWY) and a $31 price target. Earlier on June 23, TD Cowen touted Chewy as the best mid cap idea for 2026 while reiterating a Buy rating and a $34 price target. The price target represent significant upside potential as the stock is trading at about $20 a share.
The bullish stance comes on the heels of the company delivering solid first-quarter 2026 results, characterized by revenue and earnings growth, on June 10. The company continued to outperform the pet category while expanding profitability and free cash flow in the first quarter.
Net sales in the quarter were up 7.7% year over year to $3.36 billion, affirming strength in execution. Adjusted net income was up by $31 million to $179.9 million as adjusted diluted earnings per share increased by $0.08 to $0.43 a share.
Chewy Inc. achieved record profitability in the first quarter on the back of 200,000 net customer additions. According to Sumit Singh, Chief Executive Officer, the company is well positioned to gain market share and deliver profitable growth throughout the year. The focus is also on creating long term shareholder value.
Chewy Inc. (NYSE:CHWY) operates as a major e-commerce retailer that sells pet food, supplies, and healthcare products, primarily in the United States. The company combines the personalized service of a local pet store with the convenience of fast home delivery.

4 months ago
Chewy, Inc. (NYSE:CHWY) is one of the best stocks to invest in according to Two Sigma Advisors with huge upside potential. On June 23, TD Cowen ***** yst William Kerr named Chewy, Inc. (NYSE:CHWY) as the firm's best small- and mid-cap, or Smid-cap, stock idea for 2026, and at the same time reiterated a Buy rating and a $34 price target on the shares.
Kerr said his firm's endorsement was built around several growth and margin levers it believes Chewy has not yet fully monetized. These include its veterinary care partnership through CVC and Modern Animal, an expanding advertising business, ongoing automation of its fulfillment operations, the Chewy+ membership program, and the integration of generative AI into its platform.
Kerr added that at the time of the note, Chewy was trading at just 6.3 times its enterprise value-to-EBITDA. He described this valuation as attractive given the company's expected EBITDA compound annual growth rate of 15% over the next five years. Put simply, the ***** yst believes the stock is too cheap relative to how fast the business is expected to grow.
The ***** yst also pointed out that as online shopping for pet products continues to grow as a share of total industry sales, Chewy is well positioned to pull customers away from physical competitors. The competitors include local pet stores, traditional retailers, and grocery chains.
The Smid-cap designation places Chewy in a curated list of TD Cowen's top investment picks for companies with a market capitalization generally below $10 billion. This is the firm's annual selection that signals its highest-conviction ideas in that size category.

4 months ago
Phillips 66 (PSX) is a U.S. downstream energy company engaged in refining, midstream operations, chemicals, renewable fuels, and marketing and specialty businesses. Formed in 2012 following the spin-off from ConocoPhillips, the company operates an extensive network of refineries, pipelines, terminals, and retail fuel distribution **** ets serving customers worldwide. Phillips 66 is headquartered in Houston and has a market cap of around $70.7 billion.
The leading downstream energy provider is expected to announce its fiscal second-quarter earnings on Wednesday, Aug. 5, 2026. Ahead of the event, **** ysts expect PSX to report a profit of $6.99 per share, up 193.7% from $2.38 per share in the year-ago quarter. The company beat the consensus estimates in each of the last four quarters.
Cisco Is Up 46% and Oracle Is Down 25% in 2026. The Better Dividend Buy Might Surprise You.
SK Hynix Stock's Upcoming U.S. Listing Is a Sign the Memory Trade Could Soon Topple. 2 Ways to Profit from the Pain.
Five July 4th Fireworks: Unusual Options Activity Flags Cheap Lottery-Ticket Calls in CHWY, AVGO, PYPL, STLA and WMT


4 months ago
At some point, investors need to call a spade a spade, which brings us to pet e-commerce specialist Chewy (CHWY). Fundamentally, the appeal of the business is rather obvious: Americans love their four-legged friends. They also love convenience, as evidenced by the rise of Amazon (AMZN). Combine these two elements together and you should have a strong bullish case for CHWY stock.
Unfortunately, that narrative has simply not panned out. Shares are down nearly 44% on a year-to-date basis, leading the Barchart Technical Opinion indicator to downgrade CHWY stock as a 100% Strong Sell. With this kind of negative performance, it's difficult not to view Chewy as a falling knife.
Kraft Heinz Stock is Treading Water - Time to Buy KHC?
2 Covered Call Ideas on KO Stock
McDonald's Corp Stock May Have Hit Bottom - Ways to Play MCD Stock



4 months ago
The pet and rural lifestyle sectors have shown remarkable resilience in changing markets. Deciding between Chewy (NYSE:CHWY) and Tractor Supply (NASDAQ:TSCO) requires weighing digital convenience against physical dominance in your portfolio.
Chewy revolutionized pet ownership through its high-tech e-commerce platform and subscription-heavy model. Conversely, Tractor Supply serves the "life out here" crowd with essential hardware and farm supplies across thousands of stores. Both companies are expanding aggressively into pet health services, making them direct competitors in the lucrative animal care market.
Chewy operates in the competitive landscape of retail stocks by offering about 190,000 products through its website and apps. It recently expanded its pet healthcare ecosystem by acquiring Modern Animal, a technology-enabled veterinary provider. The company relies on its Autoship subscription program to drive customer retention and provide revenue visibility while partnering with Amazon Web Services (AWS) for infrastructure.
In FY 2025, revenue reached nearly $12.6 billion, representing growth of approximately 6.2% compared to the previous year. The company reported a net income of roughly $222.8 million for the period. This resulted in a net margin of close to 1.8%, which measures the percentage of revenue a company keeps as profit after all expenses.
As of its February 2026 balance sheet, the debt-to-equity ratio was roughly 1.1x while the current ratio was approximately 0.9x. These metrics compare total debt to shareholder equity and short-term ****** ets to liabilities, respectively. Free cash flow reached nearly $562.4 million, but note that stock-based compensation represented roughly 43.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.

4 months ago
Investing in stocks that have been doing poorly can seem risky. But if those stocks have strong underlying fundamentals, they can turn out to be attractive contrarian investments to buy and hold. Think of it as buying in a bear market. You might be scared to do so as you see stock prices go down, and the temptation is to think they'll keep going down. However, buying at extremely low prices can set you up for significant gains in the future -- as long as the business is in good shape.
Three stocks I think could be enticing contrarian buys today are Adobe (NASDAQ: ADBE), Chewy (NYSE: CHWY), and Duolingo (NASDAQ: DUOL). Their share prices haven't been this low in years, and while there is some risk with them these days, here's why they could prove to be excellent buys for the long haul.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Adobe's stock has been struggling mightily, and it's down 66% over the past five years and 48% in just the past 12 months. It's trading at levels it hasn't been at since 2018. Investors are concerned about the company's long-term future. This is, after all, a company whose business centers on creating images, and with chatbots able to do so with ease, there are serious question marks about Adobe's ability to compete in the long run.
However, Adobe has been incorporating artificial intelligence (AI) into its products as well, making it easy for users to create images and videos with AI. And with Adobe's software, you can also make more precise edits and changes. As anyone who's used chatbots to make images knows, there's not always much consistency from one image to another, and users can quickly burn through credits trying to fine-tune the process. Creating an image with an AI chatbot may be easy, but creating precisely what you want is a whole other story.


4 months ago
Chewy, Inc. (NYSE:CHWY), among the stocks under $20 that will explode, has an upside potential of 64.28%. Chewy, Inc. (NYSE:CHWY) is drawing renewed attention from Wall Street after delivering a mixed but profitable start to fiscal 2026, even as the company trims its outlook for the year ahead.
On June 11, 2026, UBS lowered its price target on Chewy, Inc. (NYSE:CHWY) to $24 from $32 while maintaining a "Neutral" rating on the stock. The cut followed the company's first-quarter results announced the previous day. UBS ***** yst Michael Lasser said Chewy's business model is not fully immune to macroeconomic pressures.
Lasser said Chewy, Inc. (NYSE:CHWY) is showing signs of maturation as a company. Earlier in its growth trajectory, the pet products retailer was able to outrun difficult consumer periods, he noted.
That maturing process brings benefits such as improved profitability, though UBS said Chewy, Inc. (NYSE:CHWY) may not handily outperform its guidance the way it has in the past. The firm said the market needs to see realistic expectations for the back half of the year and beyond. UBS expects the stock to trade around its recent range in the near term.
Copyright: antonioguillem / 123RF Stock Photo





