

1 month ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer

1 month ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

2 months ago
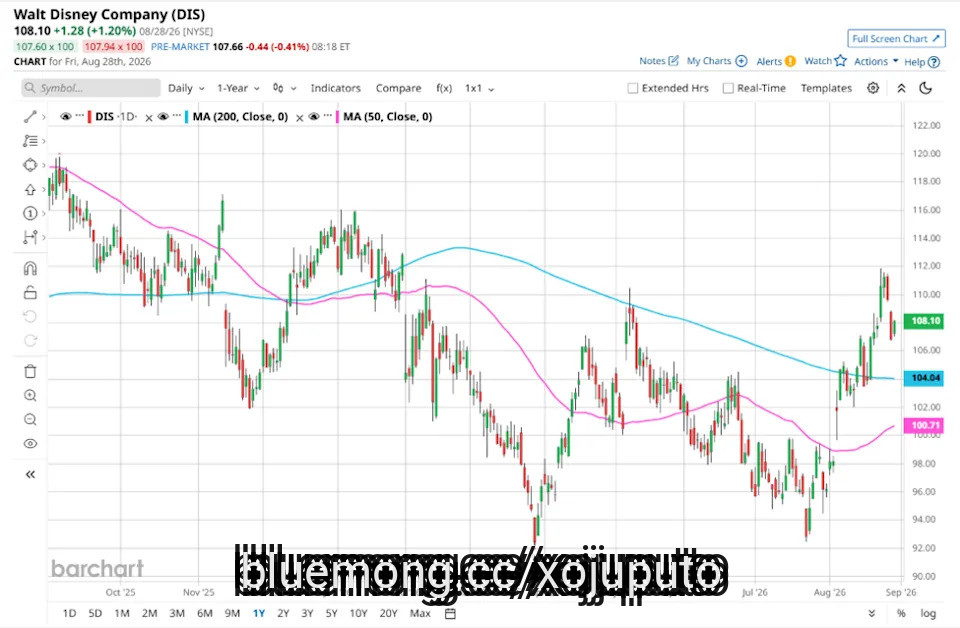
Burbank, California-based The Walt Disney Company (DIS) operates as an entertainment company worldwide. Valued at $186.7 billion by market cap, the company's businesses include, media networks, parks and resorts, studio entertainment, consumer products, and interactive media.
Companies worth $10 billion or more are generally described as "large-cap stocks," and DIS definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the entertainment industry. Disney's edge comes from its unmatched IP - Mickey, Star Wars, Marvel, Pixar, that fuels content across movies, streaming, parks, and merchandise. Vertical integration gives it control over creation to distribution, cutting costs and protecting quality. With global reach, heavy investment in data and AI for personalization, and a strong track record of attracting top creative talent, Disney keeps leveraging its brands across platforms to drive revenue and customer loyalty.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#palantir #market

2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the Q2 sales beat to tangible progress in the 'Consumer First Formula,' specifically citing a return to digital growth and accelerated expanded distribution through Amazon and Ulta.
The company is shifting from seasonal collections to enduring franchises, exemplified by the Fruit Fusion launch which exceeded expectations and achieved higher average unit retail (AUR) than core **** ortments.
Strategic portfolio discipline led to the decision to exit the Home Care category (laundry and kitchen), as it represents less than 1% of sales and creates disproportionate operational complexity.
Digital performance improved 4 percentage points sequentially, driven by enhanced storytelling, personalization, and a lower free shipping threshold of $50.
#tell #formula


2 months ago
For decades, Natalie Portman has been one of our most cerebral stars. A 1999 Vanity Fair cover, promoting "The Phantom Menace," asked whether the then-17-year-old might "choose Harvard over Hollywood." She managed to do both, earning an Ivy League degree and an Oscar. Her characters in movies from "Jackie" to "May December" are often overthinkers, and her Instagram book club picks tend toward high literature.
Who better, then, to serve as the heroine of a Rachel Cusk novel?
Cusk, the experimental novelist, is set to publish "Life of M," about an unnamed actress coping with feelings of alienation and depersonalization, on Aug. 25. Cusk's work, like the well-loved "Outline" trilogy, favors deep excavation of inner turmoil over what might be called "plot," and "Life of M" is no exception. Still, the obvious similarities to the known facts of Portman's life have earned the book plenty of buzz.
To wit: M, a former child star who received her greatest acclaim for playing a ballerina, is raising children, seemingly solo, in Paris. All of this checks out, and Portman's putative connection to Cusk — she selected Cusk's last novel, 2024's "Parade," for Natalie's Book Club, and both actress and author live in Paris — lends the enterprise a juicy overlay of gossip.
There's no public information indicating Portman's involvement in the project, or whether she approved it at all. (Portman's rep and the book's publicist at Farrar, Straus and Giroux did not respond to requests for comment.) And if people are reading "Life of M" as a document of truth, it may be in part because the novel so confidently places its reader within restricted access zones. We see M through the eyes of a narrator, an unnamed person who has obtained M's permission to document her life. And so we accompany M to a spa, where she and a younger actress chitchat about their peers and discuss Hollywood's gender pay gap, and to an interview at a chic restaurant, where she observes strangers snapping her picture. The access Cusk grants extends deep into M's mind as well: With her friend, M ponders how she might help a new generation of actresses despite her own "ennui" about the industry; with the journalist interviewing her, M is burdened "by the impossibility of anyone ever understanding what she is."
The project of this book is to help us to know a person who rejects examination, just as journalists have struggled to crack Portman, who avoids discussing her personal life in interviews. "Life of M" is not the sort of novel that one can "spoil," but suffice it to say that M ultimately makes her displeasure at the narrator's project plain: Being under a writer's gaze is, for her, intolerable. M comes by this aversion to fame honestly. We're informed that "starring in a film as a child had immediately brought her childhood to an end," and that press coverage of her entanglements as an adult have strained her relationship with her family. She has constructed a series of walls, and w


2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance outperformance was driven by a disciplined focus on price and margin over sales volume, particularly within the luxury move-up segment which represents 61% of revenue.
Management attributes the resilience of their demand to an affluent customer base characterized by high incomes, substantial home equity, and lower sensitivity to mortgage rate fluctuations.
The company successfully reduced finished spec inventory to 1.9 homes per community, prioritizing early-cycle sales to maximize personalization opportunities and margin-accretive design studio upgrades.
Strategic community count growth of 8% to 10% served as a primary volume driver, offsetting a broader sales environment weighed down by low consumer confidence and elevated rates.
#analysts


3 months ago
Updated July 30, 2026 5:22 pm ET
Listen
(4 min)
The latest Market Talks covering the Auto and Transport sector. Published exclusively on Dow Jones Newswires at 4:20 ET, 12:20 ET and 16:50 ET.
0929 ET – (Dow Jones) Automaker Ferrari’s results are strongly ahead of consensus in a quarter dominated by pricing and mix improvement underpinned by higher vehicle personalization, Bernstein ***** ysts write. This more than offset the expected drop in shipments, which was due to model changeovers, the bank says. Full-year guidance for revenue, Ebitda and EBIT was slightly raised, while there is no change to the Ebitda and EBIT margin guidance. The good set of results and a small raise in guidance are welcome after concerns were raised about the health of the luxury consumer and about the cadence of Ferrari’s own margin development, it adds. Bernstein sees further mix and personalization potential in the second half and also sees scope for another guidance upgrade at the third quarter results. Shares fall 1.7%. (dominic.choppingwsj.com)
#results #ebit #quarter #personalization


3 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Revenue growth of 19% was driven by strong consumer response to trend-right **** ortments in the flagship Steve Madden brand and the integration of Kurt Geiger.
Brand heat for Steve Madden accelerated significantly, evidenced by a 71% increase in global online searches during the quarter.
The Kurt Geiger U.S. expansion is yielding high profitability, with new premium mall locations and a unique 'one-of-a-kind' personalization service driving 17% of handbag sales in participating stores.
Management attributed the return to strong growth in handbags to a successful pivot toward trending materials like straw, jelly, and denim.
#steve #madden #kurt #geiger
4 months ago
Mars Inc. Lead Global CMO and Mars Snacking Global Chief Growth Officer Gulen Bengi discusses the importance of community co-creation for a portfolio that includes 130 brands. Bengi highlights how shifting from one-way messaging to two-way engagement allows for personalization at scale, using a recent Twix campaign as an example.

4 months ago
Spotify Technology S.A. (NYSE:SPOT) is one of the 12 High Quality Stocks to Buy for the Long Term.
On June 12, 2026, Spotify Technology S.A. (NYSE:SPOT) removed tens of thousands of fake podcasts that promoted illegal online pharmacies following media scrutiny and an investigation by Senator Maggie Hassan, CNN's Clare Duffy reported. The findings raised concerns about Spotify's ability to proactively identify and remove harmful content before it reaches users. Hassan said online platforms need to "step up, protect their users, and enforce comprehensive strategies to remove illegal content" as criminals use AI to scale scams and other dangerous activity.
On June 8, 2026, Spotify Technology S.A. (NYSE:SPOT) was reported to be exploring live music content, including livestreamed concerts and festivals, Bloomberg's Lucas Shaw reported, citing people familiar with the discussions. Spotify has approached concert promoters about licensing rights to broadcast events and has already begun testing concert-related video, including footage from a live Dua Lipa performance in Mexico City. The company has also started offering selected users early access to concert tickets.
Copyright: dennizn / 123RF Stock Photo
Last month, Raymond James raised the firm's price target on Spotify Technology S.A. (NYSE:SPOT) to $615 from $555 and maintained an Outperform rating on the shares. The firm said Spotify's Investor Day highlighted a stronger-than-expected AI-driven product roadmap, including new personalization and monetization features supported by proprietary user data. Raymond James also pointed to Spotify's rights-holder-aligned AI framework through its deal with Universal Music Group (UMGNF), along with mid-term financial targets that appear achievable.


4 months ago
This week, before we get into anything else, I’d like to share some big news with everyone:
I finally got the Leaf Reggie Jackson autograph/inscription that says “I must kill the queen.”
It was little over $100 with shipping.
When I first discovered this card over a year ago (I bought a 2026 version; there’s a 2025 one in a couple Leaf lines — they seem to all be 1/1 variations) I researched prices on Reggie personalizations and appearances. There are a billion little restrictions and add-ons where getting him to sign something with that inscription would cost way more than the price I paid for the card. A ball alone on his website is about $150.00. Here are some of the rules if you want to see him live at Cooperstown:
If you’re wondering, a “premium inscription” is an EXTRA $100 and I’m still not clear if that means you’re limited to just three words. So…go up, get “I must kill” and then you have to go to the back of the line, pay another $100, and get “the queen”?



4 months ago
Spotify Technology S.A. (NYSE:SPOT) is one of the 12 High Quality Stocks to Buy for the Long Term.
On June 12, 2026, Spotify Technology S.A. (NYSE:SPOT) removed tens of thousands of fake podcasts that promoted illegal online pharmacies following media scrutiny and an investigation by Senator Maggie Hassan, CNN's Clare Duffy reported. The findings raised concerns about Spotify's ability to proactively identify and remove harmful content before it reaches users. Hassan said online platforms need to "step up, protect their users, and enforce comprehensive strategies to remove illegal content" as criminals use AI to scale scams and other dangerous activity.
On June 8, 2026, Spotify Technology S.A. (NYSE:SPOT) was reported to be exploring live music content, including livestreamed concerts and festivals, Bloomberg's Lucas Shaw reported, citing people familiar with the discussions. Spotify has approached concert promoters about licensing rights to broadcast events and has already begun testing concert-related video, including footage from a live Dua Lipa performance in Mexico City. The company has also started offering selected users early access to concert tickets.
Copyright: dennizn / 123RF Stock Photo
Last month, Raymond James raised the firm's price target on Spotify Technology S.A. (NYSE:SPOT) to $615 from $555 and maintained an Outperform rating on the shares. The firm said Spotify's Investor Day highlighted a stronger-than-expected AI-driven product roadmap, including new personalization and monetization features supported by proprietary user data. Raymond James also pointed to Spotify's rights-holder-aligned AI framework through its deal with Universal Music Group (UMGNF), along with mid-term financial targets that appear achievable.
On June 12, 2026, Spotify Technology S.A. (NYSE:SPOT) removed tens of thousands of fake podcasts that promoted illegal online pharmacies following media scrutiny and an investigation by Senator Maggie Hassan, CNN's Clare Duffy reported. The findings raised concerns about Spotify's ability to proactively identify and remove harmful content before it reaches users. Hassan said online platforms need to "step up, protect their users, and enforce comprehensive strategies to remove illegal content" as criminals use AI to scale scams and other dangerous activity.
On June 8, 2026, Spotify Technology S.A. (NYSE:SPOT) was reported to be exploring live music content, including livestreamed concerts and festivals, Bloomberg's Lucas Shaw reported, citing people familiar with the discussions. Spotify has approached concert promoters about licensing rights to broadcast events and has already begun testing concert-related video, including footage from a live Dua Lipa performance in Mexico City. The company has also started offering selected users early access to concert tickets.
Copyright: dennizn / 123RF Stock Photo
Last month, Raymond James raised the firm's price target on Spotify Technology S.A. (NYSE:SPOT) to $615 from $555 and maintained an Outperform rating on the shares. The firm said Spotify's Investor Day highlighted a stronger-than-expected AI-driven product roadmap, including new personalization and monetization features supported by proprietary user data. Raymond James also pointed to Spotify's rights-holder-aligned AI framework through its deal with Universal Music Group (UMGNF), along with mid-term financial targets that appear achievable.


4 months ago
Is SG a good stock to buy? We came across a bullish thesis on Sweetgreen, Inc. on TradersPro's Substack. In this article, we will summarize the bulls' thesis on SG. Sweetgreen, Inc.'s share was trading at $8.86 as of June 15th. SG's trailing and forward P/E were 73.83 and 17.73 respectively according to Yahoo Finance.
Pixabay/Public Domain
Sweetgreen, Inc. (SG) is a fast-casual restaurant chain positioned at intersection of health-forward dining, digital ordering adoption, and automation, with revenue increasingly driven by digital channels reflecting shifting consumer preferences toward convenience and personalization and increasing share of digital orders now dominates the revenue mix across its store base. It operates 300+ locations across US, serving salads, bowls, grain plates, wraps built around fresh ingredients targeting health-conscious millennials and Gen Z consumers.
Read More: 15 AI Stocks That Are Quietly Making Investors Rich
Read More: Undervalued AI Stock Poised For Massive Gains: 10000% Upside Potential


7 months ago
Joe Kent says if US destroys Iran via destruction, the global order will be shattered
We, and our third-party partners, use cookies, pixels, and other technologies to collect, record, and share information you provide, as well as information about your interactions with our site, for ad targeting, **** ytics, personalization, and site functionality. By clicking one of the **** ons below, you agree to the use of these technologies as described in our Privacy Policy and subject to your settings, and our Terms & Conditions.
WASHINGTON (TNND) — Joe Kent, the former director of the National Cou
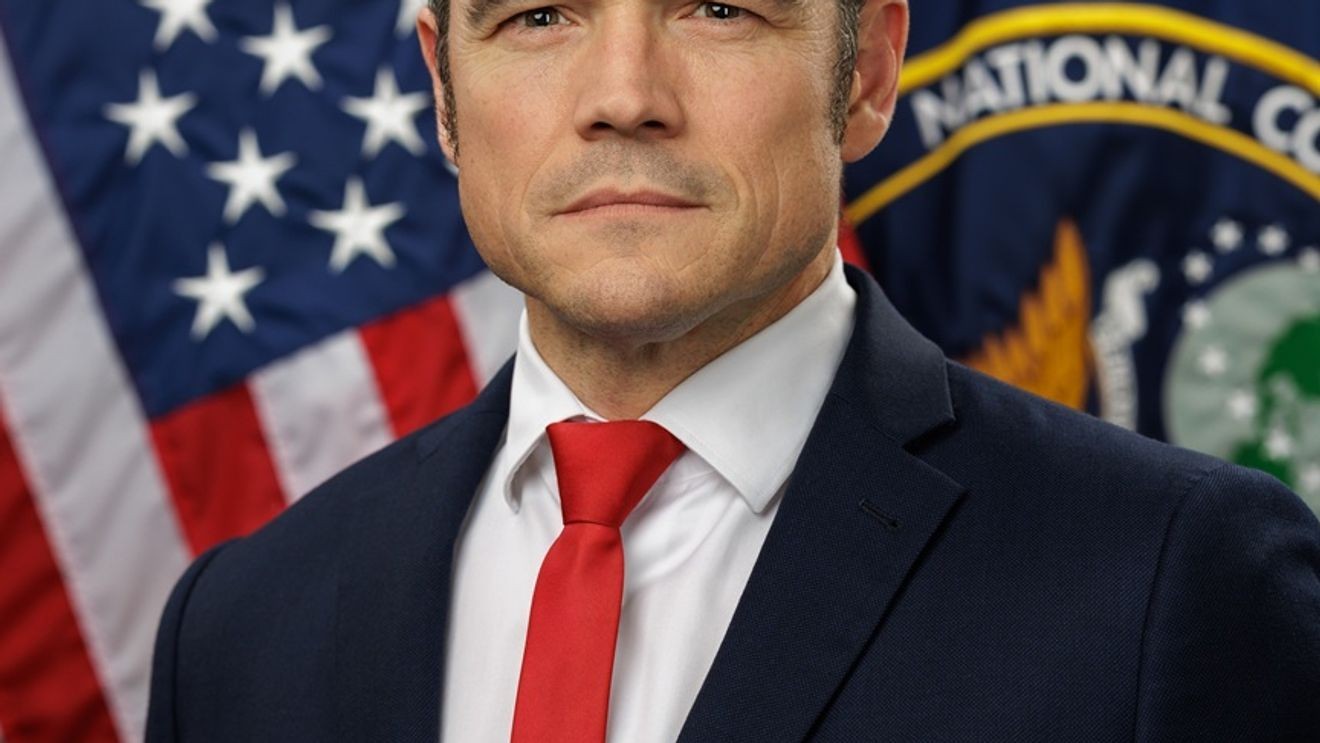
Joe Kent says if US destroys Iran via destruction, the global order will be shattered
Joe Kent, the former director of the National Counterterrorism Center, said Tuesday that Iran being destroyed would upend the U.S. economy.
https://abc7amarillo.com/news/nation-world/joe-kent-says-if-us-destroys-iran-via-destruction-the-global-order-will-be-shattered-regime-change-donald-trump-israel
9 months ago
State Police investigate over $30K Bitcoin warrant payment fraud in Northampton...
We, and our third-party partners, use cookies, pixels, and other technologies to collect, record, and share information you provide, as well as information about your interactions with our site, for ad targeting, **** ytics, personalization, and site functionality. By clicking one of the **** ons below, you agree to the use of these technologies as described in our Privacy Policy and subject to your settings, and our Terms & Conditions.
NORTHAMPTON CO. (WOLF) — The Pennsylvania State Police Troop M – Bethleh




