
2 days ago
The first full week of trading in September didn't give Zscaler (NASDAQ: ZS) investors much to celebrate. During the shortened trading week that followed Labor Day, Zscaler dropped about 3%. This week, however, is a very different story, thanks to a firm providing an auspicious outlook for the cybersecurity stock.
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week
3 days ago
On September 8, 2026, CNBC reported that Novartis' failed pelacarsen trial has raised the stakes for rival experimental cholesterol drugs from Amgen Inc. (NASDAQ:AMGN) and Eli Lilly and Company (NYSE:LLY), both of which are racing to prove that lowering lipoprotein(a), or Lp(a). It can meaningfully reduce heart attacks and strokes.
Analysts said Amgen's olpasiran faces the clearest negative read-through given its similar trial design. Lilly's lepodisiran is being tested in a broader patient population that could limit how directly Novartis' failure applies. It is also described as less material to Lilly's overall valuation than pelacarsen was for Novartis.
Copyright: stocking / 123RF Stock Photo
Amgen Inc. (NASDAQ:AMGN) and Eli Lilly and Company (NYSE:LLY) could still succeed where Novartis failed. Pelacarsen's failure does not establish that lowering Lp(a) cannot reduce cardiovascular events. **** ysts noted that Novartis' trial faced a high statistical hurdle and that Amgen's olpasiran and Lilly's lepodisiran have produced stronger Lp(a) reductions in earlier studies. Both companies also continue testing their drugs in specific patient populations with high Lp(a). It leaves room for their trials to produce different outcomes from Novartis' study.
Lilly's lepodisiran faces a less direct read-through than Amgen's olpasiran. **** ysts view Amgen's olpasiran as the closest comparison to pelacarsen because the programs use similar trial designs. Lilly's lepodisiran is being tested in an overall patient population. It could make Novartis' failure less directly applicable. **** ysts also view lepodisiran as less material to Lilly's overall valuation than pelacarsen was to Novartis. It reduces the potential financial impact of an unsuccessful outcome.
#lepodisiran #less
Analysts said Amgen's olpasiran faces the clearest negative read-through given its similar trial design. Lilly's lepodisiran is being tested in a broader patient population that could limit how directly Novartis' failure applies. It is also described as less material to Lilly's overall valuation than pelacarsen was for Novartis.
Copyright: stocking / 123RF Stock Photo
Amgen Inc. (NASDAQ:AMGN) and Eli Lilly and Company (NYSE:LLY) could still succeed where Novartis failed. Pelacarsen's failure does not establish that lowering Lp(a) cannot reduce cardiovascular events. **** ysts noted that Novartis' trial faced a high statistical hurdle and that Amgen's olpasiran and Lilly's lepodisiran have produced stronger Lp(a) reductions in earlier studies. Both companies also continue testing their drugs in specific patient populations with high Lp(a). It leaves room for their trials to produce different outcomes from Novartis' study.
Lilly's lepodisiran faces a less direct read-through than Amgen's olpasiran. **** ysts view Amgen's olpasiran as the closest comparison to pelacarsen because the programs use similar trial designs. Lilly's lepodisiran is being tested in an overall patient population. It could make Novartis' failure less directly applicable. **** ysts also view lepodisiran as less material to Lilly's overall valuation than pelacarsen was to Novartis. It reduces the potential financial impact of an unsuccessful outcome.
#lepodisiran #less

4 days ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment

14 days ago
Jeff Klingelhofer, CFA, Managing Director, Portfolio Manager & Senior Research **** yst, Securitized **** ets at Aristotle Pacific didn't set out to be a bond guy but a launchpad at PIMCO, stops in Tokyo and London, and a Chicago MBA detour into a scrappy five-person hedge fund rewired how he thinks about fixed income. The internship stuck, with Klingelhofer building out Thornburg's taxable fixed income desk from employee #3 to Head of Investments, before joining Aristotle Pacific in 2024. The firm is a 15-year-old franchise (formerly Pacific **** et Management) now running roughly $16 billion and, as of July 30, three brand-new ETFs: the Aristotle Core Plus Income ETF (ARCP), the Aristotle Multi-Sector Income ETF (ARMS), and the Aristotle Short Term Income ETF (SDUR).
The pitch isn't about taking on more risk to boost returns but about capturing returns with minimal risk, and that means shopping across every fixed income silo instead of hunting inside one. Klingelhofer gives the example of February 2020, when American Airlines' corporate bond and its aircraft-backed EETC both priced at 3.75% with the same issuer, same tenor, same yield. A month later, COVID hit and the corporate bond cratered to 27 cents on the dollar while the EETC held at 65 cents. Same company, wildly different outcomes because Wall Street desks looked at each instrument in isolation instead of comparing across the capital stack. That's the whole Aristotle Pacific thesis, and it's why he sees the same mispricing setting up today in data center financing.
The three funds slot into that framework by risk level, with SDUR as a low-duration, active-credit alternative to cash, ARCP as a core-bond upgrade aiming to beat the Agg by 100-150bps, and ARMS as the full relative-value expression targeting 250bps over a cycle with real flexibility to shift credit quality. Macro-wise, Klingelhofer thinks the market is underestimating new Fed Chair Warsh, who, unlike his predecessor, inherits a purely high-inflation world with no disinflationary tailwind. It means the firm is positioning the funds slightly long duration as a hedge against credit risk elsewhere in the book. His closing advice to advisors was a cautionary and practical one, that they shouldn't expect Aristotle to work in every environment (no fund does), and to pair its bottom-up process with top-down managers like PIMCO so the two zig and zag differently throughout market cycles.
To learn more about Aristotle Pacific, go here, or you can learn more about their new ETFs here.
#pacific #same #fixed
The pitch isn't about taking on more risk to boost returns but about capturing returns with minimal risk, and that means shopping across every fixed income silo instead of hunting inside one. Klingelhofer gives the example of February 2020, when American Airlines' corporate bond and its aircraft-backed EETC both priced at 3.75% with the same issuer, same tenor, same yield. A month later, COVID hit and the corporate bond cratered to 27 cents on the dollar while the EETC held at 65 cents. Same company, wildly different outcomes because Wall Street desks looked at each instrument in isolation instead of comparing across the capital stack. That's the whole Aristotle Pacific thesis, and it's why he sees the same mispricing setting up today in data center financing.
The three funds slot into that framework by risk level, with SDUR as a low-duration, active-credit alternative to cash, ARCP as a core-bond upgrade aiming to beat the Agg by 100-150bps, and ARMS as the full relative-value expression targeting 250bps over a cycle with real flexibility to shift credit quality. Macro-wise, Klingelhofer thinks the market is underestimating new Fed Chair Warsh, who, unlike his predecessor, inherits a purely high-inflation world with no disinflationary tailwind. It means the firm is positioning the funds slightly long duration as a hedge against credit risk elsewhere in the book. His closing advice to advisors was a cautionary and practical one, that they shouldn't expect Aristotle to work in every environment (no fund does), and to pair its bottom-up process with top-down managers like PIMCO so the two zig and zag differently throughout market cycles.
To learn more about Aristotle Pacific, go here, or you can learn more about their new ETFs here.
#pacific #same #fixed

14 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
According to average rates from the Zillow lender marketplace, mortgage rates are lower heading into the holiday-shortened week.
The current 30-year fixed rate today, Tuesday, September 8, 2026, fell 4 basis points to 6.67%, the 15-year fixed rate decreased 10 basis points to 6.04%, and the 5/1 ARM fell 39 basis points to 6.64%.
Read more: Weekly survey of mortgage lenders with the lowest rates: Minor pricing changes
Here are the current mortgage rates today, Tuesday, September 8, 2026, according to the latest Zillow data:
#zillow
According to average rates from the Zillow lender marketplace, mortgage rates are lower heading into the holiday-shortened week.
The current 30-year fixed rate today, Tuesday, September 8, 2026, fell 4 basis points to 6.67%, the 15-year fixed rate decreased 10 basis points to 6.04%, and the 5/1 ARM fell 39 basis points to 6.64%.
Read more: Weekly survey of mortgage lenders with the lowest rates: Minor pricing changes
Here are the current mortgage rates today, Tuesday, September 8, 2026, according to the latest Zillow data:
#zillow


19 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
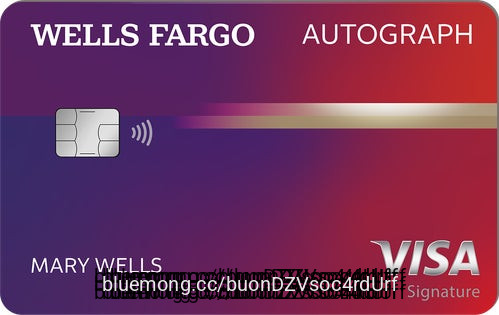
The Wells Fargo Autograph® Card is an excellent travel rewards card if you want a high rate on everyday purchases, no annual fee, and a 0% introductory APR offer. While it doesn't offer premium travel perks, it holds its own as a low-stress, rewarding card option.
Cell phone protection: Subject to a $25 deductible, you can receive up to $600 of cell phone protection against damage or theft as long as you pay your cell phone bill with your card.
No foreign transaction fee: There are no foreign transaction fees when you use your card to make purchases from foreign merchants, including when you're traveling internationally.
#card #phone #travel #protection
The Wells Fargo Autograph® Card is an excellent travel rewards card if you want a high rate on everyday purchases, no annual fee, and a 0% introductory APR offer. While it doesn't offer premium travel perks, it holds its own as a low-stress, rewarding card option.
Cell phone protection: Subject to a $25 deductible, you can receive up to $600 of cell phone protection against damage or theft as long as you pay your cell phone bill with your card.
No foreign transaction fee: There are no foreign transaction fees when you use your card to make purchases from foreign merchants, including when you're traveling internationally.
#card #phone #travel #protection

21 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: The Chase Freedom Unlimited is a heavy-hitter rewards earner and has a generous intro APR, all with no annual cost. Even better, you have flexibility with your redemption options, with complete control over redeeming your rewards for cash back, travel, gift cards, and more.
Why we like it: The Chase Sapphire Preferred is one of the best cards for travelers because it earns valuable Chase Ultimate Rewards points and has a low annual fee. You also have flexibility with your redemption options, including redeeming points for airfare, hotel stays, rental cars, transfer partners, and more.
Why we like it: If you want a straightforward card for earning travel rewards on all your eligible purchases, look no further than the Capital One Venture Rewards. This card doesn't have confusing spend categories, making it the perfect addition to your wallet if you want one card for everything.
Why we like it: The Capital One Savor has an excellent 0% intro APR offer for new cardmembers, and it also checks multiple other boxes to ensure it provides lasting value. It has no foreign transaction fees, no annual fee, and one of the best rewards rates available for earning unlimited cash back on everyday purchases.
#annual #capital
Why we like it: The Chase Freedom Unlimited is a heavy-hitter rewards earner and has a generous intro APR, all with no annual cost. Even better, you have flexibility with your redemption options, with complete control over redeeming your rewards for cash back, travel, gift cards, and more.
Why we like it: The Chase Sapphire Preferred is one of the best cards for travelers because it earns valuable Chase Ultimate Rewards points and has a low annual fee. You also have flexibility with your redemption options, including redeeming points for airfare, hotel stays, rental cars, transfer partners, and more.
Why we like it: If you want a straightforward card for earning travel rewards on all your eligible purchases, look no further than the Capital One Venture Rewards. This card doesn't have confusing spend categories, making it the perfect addition to your wallet if you want one card for everything.
Why we like it: The Capital One Savor has an excellent 0% intro APR offer for new cardmembers, and it also checks multiple other boxes to ensure it provides lasting value. It has no foreign transaction fees, no annual fee, and one of the best rewards rates available for earning unlimited cash back on everyday purchases.
#annual #capital

27 days ago
SK hynix Inc. (NASDAQ:SKHY) announced a 40 trillion won, or approximately $28.6 billion, program to repurchase and cancel as many as 24.07 million common shares between August 20 and November 19. The shares represent approximately 3.3% of outstanding stock. The company's U.S.-listed ADSs initially gained nearly 4% on August 19 but closed only approximately 0.4% higher after falling 9% during the preceding session.
The timing creates the central tension. SK hynix has committed to return more than 50% of ***** ulative free cash flow generated from 2025 through 2027. For SK hynix Inc. (NASDAQ:SKHY), the question is whether that commitment reflects confidence in structural HBM demand or cash distribution near an unusually profitable point in the memory cycle.
SK hynix Inc. (NASDAQ:SKHY) ended the second quarter with 69.4 trillion won of net cash after cash and short-term investments reached 88 trillion won, and debt declined to 18.6 trillion won. That position provides room to return capital while continuing its production expansion.
SK hynix Inc. (NASDAQ:SKHY) will cancel the repurchased stock instead of retaining it as treasury shares. At unchanged profit, a 3.3% reduction in outstanding shares would lift earnings per share by approximately 3.4%. The economic payoff will ultimately depend on the purchase price and the returns the company could otherwise earn on the cash.
The program would also reverse the dilution from the July Nasdaq offering. SK hynix Inc. (NASDAQ:SKHY) issued 177.9 million ADSs representing 17.79 million new common shares and generated gross proceeds of $26.51 billion before underwriting discounts and offering expenses. A completed 24.07 million-share cancellation would retire approximately 6.28 million more common shares than the offering created.
#skhy #shares #trillion #common
The timing creates the central tension. SK hynix has committed to return more than 50% of ***** ulative free cash flow generated from 2025 through 2027. For SK hynix Inc. (NASDAQ:SKHY), the question is whether that commitment reflects confidence in structural HBM demand or cash distribution near an unusually profitable point in the memory cycle.
SK hynix Inc. (NASDAQ:SKHY) ended the second quarter with 69.4 trillion won of net cash after cash and short-term investments reached 88 trillion won, and debt declined to 18.6 trillion won. That position provides room to return capital while continuing its production expansion.
SK hynix Inc. (NASDAQ:SKHY) will cancel the repurchased stock instead of retaining it as treasury shares. At unchanged profit, a 3.3% reduction in outstanding shares would lift earnings per share by approximately 3.4%. The economic payoff will ultimately depend on the purchase price and the returns the company could otherwise earn on the cash.
The program would also reverse the dilution from the July Nasdaq offering. SK hynix Inc. (NASDAQ:SKHY) issued 177.9 million ADSs representing 17.79 million new common shares and generated gross proceeds of $26.51 billion before underwriting discounts and offering expenses. A completed 24.07 million-share cancellation would retire approximately 6.28 million more common shares than the offering created.
#skhy #shares #trillion #common

28 days ago
The Treasury General Account ballooned to $950 billion. Nearly double Biden's $550-$600 billion target. Giving Bessent firepower to fund expanded bond buybacks.
Treasury doubled its long-bond buyback program to at least $4 billion, sending the 30-year yield to 5.23%, a level not seen since 2007.
Draining the TGA creates a thinner debt-ceiling cushion, estimated around winter or early spring, and restoring it would require selling additional bonds.
Don't wait: the ***** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
The federal government's checking account at the Federal Reserve has quietly ballooned to around $950 billion, roughly the size of Switzerland's economy. On Monday, CNBC's Steve Liesman reported, citing two senior Treasury officials, that Secretary Scott Bessent could tap that cash pile to fund the department's recently expanded bond buyback program. Officials would not say how much would be used or when, but conveyed that the balance "is considered to be available." Under the Biden administration, the stated target was around $550 billion to $600 billion. The gap is the story.
#bessent #federal #ballooned
Treasury doubled its long-bond buyback program to at least $4 billion, sending the 30-year yield to 5.23%, a level not seen since 2007.
Draining the TGA creates a thinner debt-ceiling cushion, estimated around winter or early spring, and restoring it would require selling additional bonds.
Don't wait: the ***** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
The federal government's checking account at the Federal Reserve has quietly ballooned to around $950 billion, roughly the size of Switzerland's economy. On Monday, CNBC's Steve Liesman reported, citing two senior Treasury officials, that Secretary Scott Bessent could tap that cash pile to fund the department's recently expanded bond buyback program. Officials would not say how much would be used or when, but conveyed that the balance "is considered to be available." Under the Biden administration, the stated target was around $550 billion to $600 billion. The gap is the story.
#bessent #federal #ballooned

29 days ago
J.P. Morgan's Jason Hunter warns of autumn S&P 500 weakness, citing AI stock divergence that mirrors the 1999 to 2000 tech crash alongside rising Treasury yields.
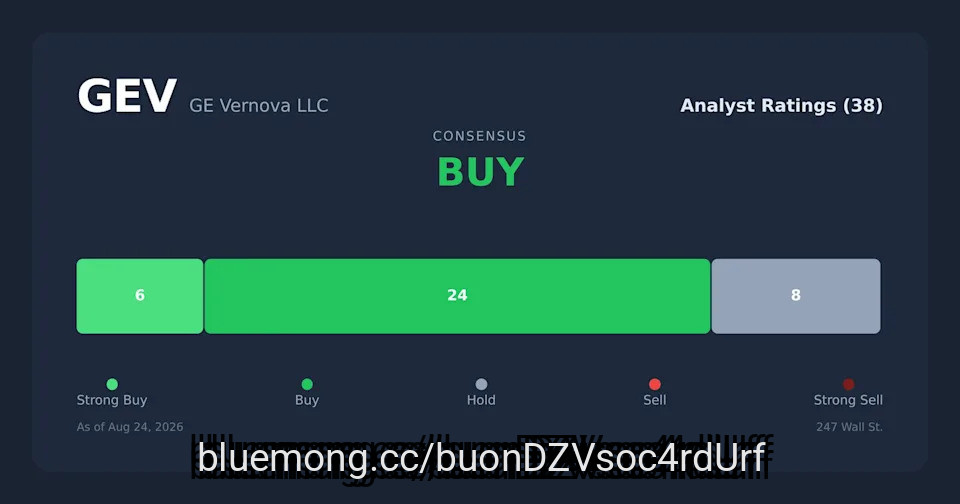
BMY yields nearly 4% with JPMorgan's recently raised $73 target, while GEV carries a $1,330 target as the firm's top electrification conviction pick.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Walmart didn't make the cut. Grab the names FREE today.
Each year, September rolls around, and it tends to be the worst month for stocks. Historical data show that September is the worst-performing month for the stock market. Since 1928, the S&P 500 has averaged a negative return of about 0.7% to 1% in September, making it the weakest month of the year. Institutional investors and large funds often sell off stocks near the end of the third quarter to lock in gains or adjust ***** et allocations. Some fund managers take advantage of improved liquidity after the summer months to tax-harvest portfolios by selling losers. In addition, traders return from vacations to reevaluate portfolios and often move to more defensive risk-off strategies.
The technical team at J.P. Morgan sees a storm brewing and published reports had this to say:
#yields #worst
BMY yields nearly 4% with JPMorgan's recently raised $73 target, while GEV carries a $1,330 target as the firm's top electrification conviction pick.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Walmart didn't make the cut. Grab the names FREE today.
Each year, September rolls around, and it tends to be the worst month for stocks. Historical data show that September is the worst-performing month for the stock market. Since 1928, the S&P 500 has averaged a negative return of about 0.7% to 1% in September, making it the weakest month of the year. Institutional investors and large funds often sell off stocks near the end of the third quarter to lock in gains or adjust ***** et allocations. Some fund managers take advantage of improved liquidity after the summer months to tax-harvest portfolios by selling losers. In addition, traders return from vacations to reevaluate portfolios and often move to more defensive risk-off strategies.
The technical team at J.P. Morgan sees a storm brewing and published reports had this to say:
#yields #worst


1 month ago
By Chris Prentice and Harry Robertson
NEW YORK/LONDON, Aug 10 (Reuters) - Wall Street indexes retreated and oil prices rallied over 4% on Monday, with markets focused on the outlook for Federal Reserve interest rates and on a potential deal between the U.S. and Iran to reopen the Strait of Hormuz.
Iran insisted that the United States must satisfy several demands before the Strait can reopen, fueling uncertainty. [O/R]
Gold drifted toward a seven-week high as inflation data loomed. [GOL/]
On Wall Street, the Dow Jones Industrial Average fell 0.25% to 53,901.23, the S&P 500 lost 0.11 to 7,749.16 and the Nasdaq Composite was down 0.42%, at 26,577.28.
#wall #strait #prentice #york
NEW YORK/LONDON, Aug 10 (Reuters) - Wall Street indexes retreated and oil prices rallied over 4% on Monday, with markets focused on the outlook for Federal Reserve interest rates and on a potential deal between the U.S. and Iran to reopen the Strait of Hormuz.
Iran insisted that the United States must satisfy several demands before the Strait can reopen, fueling uncertainty. [O/R]
Gold drifted toward a seven-week high as inflation data loomed. [GOL/]
On Wall Street, the Dow Jones Industrial Average fell 0.25% to 53,901.23, the S&P 500 lost 0.11 to 7,749.16 and the Nasdaq Composite was down 0.42%, at 26,577.28.
#wall #strait #prentice #york
1 month ago
One company powers the world's creative output, while the other builds the high-speed digital highways that make modern artificial intelligence possible. Choosing between Adobe (NASDAQ:ADBE) and Arista Networks (NYSE:ANET) means weighing software stability against infrastructure growth.
Adobe provides the essential software suite for digital creators, while Arista dominates the high-performance networking equipment market for data centers. Both companies are pivotal to the artificial intelligence revolution, though they play very different roles. Investors can compare them to decide whether to prioritize established software platforms or the hardware infrastructure powering the cloud.
Adobe is a ****** an among tech stocks, providing essential tools for digital creation, document management, and marketing ****** ytics. Its recent acquisitions of Semrush and Topaz Labs aim to boost AI-driven content marketing and image enhancement capabilities. These strategic moves help the company serve a massive base of 50 million Behance community members and global enterprise clients.
In its 2025 fiscal year (FY), revenue reached $23.8 billion, representing 10.5% growth over the previous year. The company reported net income of $7.1 billion for the same period. This resulted in a net margin of 30%, which measures the portion of revenue that remains as profit after all expenses are paid.
As of its November 2025 balance sheet, the debt-to-equity ratio was 0.6x. This metric shows the relationship between total debt and shareholder equity, indicating a manageable level of leverage. The current ratio of 1.0x shows the company can meet its immediate financial obligations, while free cash flow reached $9.9 billion for the year, which is the cash a business has left after paying for operating costs and equipment.
#billion #arista #artificial
Adobe provides the essential software suite for digital creators, while Arista dominates the high-performance networking equipment market for data centers. Both companies are pivotal to the artificial intelligence revolution, though they play very different roles. Investors can compare them to decide whether to prioritize established software platforms or the hardware infrastructure powering the cloud.
Adobe is a ****** an among tech stocks, providing essential tools for digital creation, document management, and marketing ****** ytics. Its recent acquisitions of Semrush and Topaz Labs aim to boost AI-driven content marketing and image enhancement capabilities. These strategic moves help the company serve a massive base of 50 million Behance community members and global enterprise clients.
In its 2025 fiscal year (FY), revenue reached $23.8 billion, representing 10.5% growth over the previous year. The company reported net income of $7.1 billion for the same period. This resulted in a net margin of 30%, which measures the portion of revenue that remains as profit after all expenses are paid.
As of its November 2025 balance sheet, the debt-to-equity ratio was 0.6x. This metric shows the relationship between total debt and shareholder equity, indicating a manageable level of leverage. The current ratio of 1.0x shows the company can meet its immediate financial obligations, while free cash flow reached $9.9 billion for the year, which is the cash a business has left after paying for operating costs and equipment.
#billion #arista #artificial

2 months ago
Hotchkis & Wiley, an investment management company, released its second-quarter 2026 investor letter for the "Hotchkis & Wiley Mid-Cap Value Fund." A copy of the letter can be downloaded here. Equity markets posted strong returns in the second quarter of 2026, with the Russell Midcap Index rising 13.8% and the Russell Midcap Value Index returning 13.4%, despite concerns about inflation, a hawkish Federal Reserve, and rising oil prices due to the Iran conflict. Narrow market leadership was evident, particularly semiconductor stocks and other stocks in the AI sector, which saw returns exceeding 100%. The Firm favors quality businesses with attractive valuations, believing that fears regarding AI's impact are overstated. The Hotchkis & Wiley Mid-Cap Value Fund lagged the Russell Midcap Value Index, achieving a 4.74% return in the second quarter, primarily due to underperformance in technology and energy sectors, while stock selection in healthcare contributed positively. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its Q2 2026 investor letter, Hotchkis & Wiley Mid-Cap Value Fund highlighted Centene Corporation (NYSE:CNC) as a leading performance contributor. Centene Corporation (NYSE:CNC) is a US-based healthcare enterprise that offers services to underinsured and uninsured families and commercial organizations. On August 3, 2026, Centene Corporation (NYSE:CNC) closed at $63.76 per share, reflecting a market capitalization of $31.49 billion. Centene Corporation (NYSE:CNC) posted a one-month return of -3.57%, while its shares gained 146.27% over the past 52 weeks.
Hotchkis & Wiley Mid-Cap Value Fund stated the following regarding Centene Corporation (NYSE:CNC) in its Q2 2026 investor letter:
"Centene Corporation (NYSE:CNC) is a managed care organization focused on the Medicaid market, with approximately 28 million at-risk enrollees and one of the largest Medicaid market share among publicly traded peers. It is a capital-light business well positioned to potentially benefit as the U.S. continues shifting healthcare toward government-funded, cost-controlled programs. Centene outperformed sharply this quarter as adjusted EPS beat consensus by 48%, management raised full-year guidance, and investors gained confidence that the Medicaid margin recovery and ACA membership reset were both tracking ahead of plan."
Centene Corporation (NYSE:CNC) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 72 hedge fund portfolios held Centene Corporation (NYSE:CNC) at the end of the first quarter, compared to 78 in the previous quarter. While we acknowledge the potential of Centene Corporation (NYSE:CNC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre
In its Q2 2026 investor letter, Hotchkis & Wiley Mid-Cap Value Fund highlighted Centene Corporation (NYSE:CNC) as a leading performance contributor. Centene Corporation (NYSE:CNC) is a US-based healthcare enterprise that offers services to underinsured and uninsured families and commercial organizations. On August 3, 2026, Centene Corporation (NYSE:CNC) closed at $63.76 per share, reflecting a market capitalization of $31.49 billion. Centene Corporation (NYSE:CNC) posted a one-month return of -3.57%, while its shares gained 146.27% over the past 52 weeks.
Hotchkis & Wiley Mid-Cap Value Fund stated the following regarding Centene Corporation (NYSE:CNC) in its Q2 2026 investor letter:
"Centene Corporation (NYSE:CNC) is a managed care organization focused on the Medicaid market, with approximately 28 million at-risk enrollees and one of the largest Medicaid market share among publicly traded peers. It is a capital-light business well positioned to potentially benefit as the U.S. continues shifting healthcare toward government-funded, cost-controlled programs. Centene outperformed sharply this quarter as adjusted EPS beat consensus by 48%, management raised full-year guidance, and investors gained confidence that the Medicaid margin recovery and ACA membership reset were both tracking ahead of plan."
Centene Corporation (NYSE:CNC) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 72 hedge fund portfolios held Centene Corporation (NYSE:CNC) at the end of the first quarter, compared to 78 in the previous quarter. While we acknowledge the potential of Centene Corporation (NYSE:CNC) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our fre





