

1 month ago
Palantir surged 60% in Q3 after reporting 93% revenue growth, but trades at 100x forward earnings versus Microsoft's 25x.
Michael Burry holds puts through 2027 while UBS and DA Davidson set $250 targets, signaling a sharply divided Wall Street on Palantir.
Palantir's November earnings must hit $2.16 billion guidance, which is a bar the current share price already ****** umes it clears.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Palantir Technologies (NASDAQ:PLTR) rose 60.3% in the third quarter. That was its best three-month run since the second quarter of 2025. Even so, Palantir is up just 6.55% this year, because it lost most of that ground in the first half.
#burry #davidson
Michael Burry holds puts through 2027 while UBS and DA Davidson set $250 targets, signaling a sharply divided Wall Street on Palantir.
Palantir's November earnings must hit $2.16 billion guidance, which is a bar the current share price already ****** umes it clears.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Palantir Technologies (NASDAQ:PLTR) rose 60.3% in the third quarter. That was its best three-month run since the second quarter of 2025. Even so, Palantir is up just 6.55% this year, because it lost most of that ground in the first half.
#burry #davidson


2 months ago
Data center developer Crusoe said Thursday it raised $3.9 billion in a Series F round that pushes its valuation to $30.9 billion. The massive round was co-led by Atreides Management, Mubadala Capital, and Valor Equity Partners. Founders Fund, GIC, Nvidia, Qatar Investment Authority (QIA), Radical Ventures, and TPG also participated, according to Crusoe.
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round
Crusoe also announced three new board members, including Cloudflare CFO Thomas Seifert; Bill Stein, partner and CIO at Primary Digital Infrastructure; and Redwood Materials founder and CEO JB Straubel, who also sits on Tesla's board. Straubel already has ties to Crusoe; he personally invested in the company in 2021, and Crusoe later became the first customer of Redwood's energy storage business.
The eight-year-old company's fresh capital infusion will help finance existing data center projects, including a large site in Abilene, Texas, used by OpenAI, as well as smaller, modular AI factories that can be transported by truck and connected to large power sources almost anywhere.
By manufacturing these modular data centers, called Spark, at its own facilities, Crusoe can deploy compute capacity quickly and without the need for large construction workforces. The smaller centers could also help Crusoe sidestep, at least in part, another major obstacle facing data center developers: backlash from local communities protesting massive complexes near their neighborhoods.
Crusoe co-founder and CEO Chase Lochmiller, who is pictured above, said in a statement he believes AI will usher in an era of abundance, but to get there will mean "controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction."
#straubel #round

2 months ago
The Federal Reserve's interest rate hike — the first in three years — is a policy shift that will have a domino effect for retirees.
Those in retirement and those nearing retirement need to factor interest rates into their investment decisions. To explain what the Fed hike might mean, Yahoo Finance talked to several wealth management advisers and finance professionals.
First off, it's important to keep in mind that one quarter-point rate hike won't drastically alter anyone's fortunes.
"A single rate hike rarely helps or hurts a retiree outright," said Michael Cochran, chief investment officer at BentOak Capital in Fort Worth, Texas. "It reshuffles the deck where there are benefits, but also some pressures."
A rate hike could be good news because it means that savings yields will likely rise, said LendingTree chief consumer finance **** yst Matt Schulz.
#first #Retirement #chief #michael
Those in retirement and those nearing retirement need to factor interest rates into their investment decisions. To explain what the Fed hike might mean, Yahoo Finance talked to several wealth management advisers and finance professionals.
First off, it's important to keep in mind that one quarter-point rate hike won't drastically alter anyone's fortunes.
"A single rate hike rarely helps or hurts a retiree outright," said Michael Cochran, chief investment officer at BentOak Capital in Fort Worth, Texas. "It reshuffles the deck where there are benefits, but also some pressures."
A rate hike could be good news because it means that savings yields will likely rise, said LendingTree chief consumer finance **** yst Matt Schulz.
#first #Retirement #chief #michael
2 months ago
Fast-growing stocks and artificial intelligence (AI) seem to go hand in hand, and there are several examples of stocks growing their revenue at 50%, 100%, or even 200%. But none quite touch how rapidly Nebius (NASDAQ: NBIS) is growing. During its most recent quarter, revenue rose by a jaw-dropping 454% year over year. What's even more impressive is that this growth rate is expected to last through the rest of the year, and 2027's will also be elevated.
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft
It's starting to make a lot of sense that Nvidia (NASDAQ: NVDA) is investing in Nebius, and there's still a great buying opportunity here for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Nebius is a neocloud business that provides AI-focused cloud computing power to its clients. Among its biggest clients are Meta Platforms and Microsoft, each of which has signed multi-year deals with Nebius to expand capacity. Both Microsoft and Meta have their own data centers, and Microsoft rents out its capacity to others, so why are they renting from Nebius?
Nebius' deal with Nvidia provides it with leading hardware before others, so it's a way to gain early access to the best computing units. Furthermore, these companies like having a bit of flexibility and not having to build too many data centers, as well as getting their hands on as much computing capacity as quickly as possible.
#Microsoft

2 months ago
Download the Complete Report Here
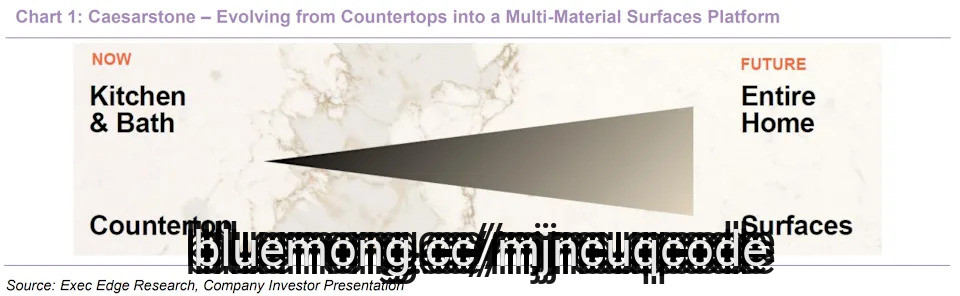
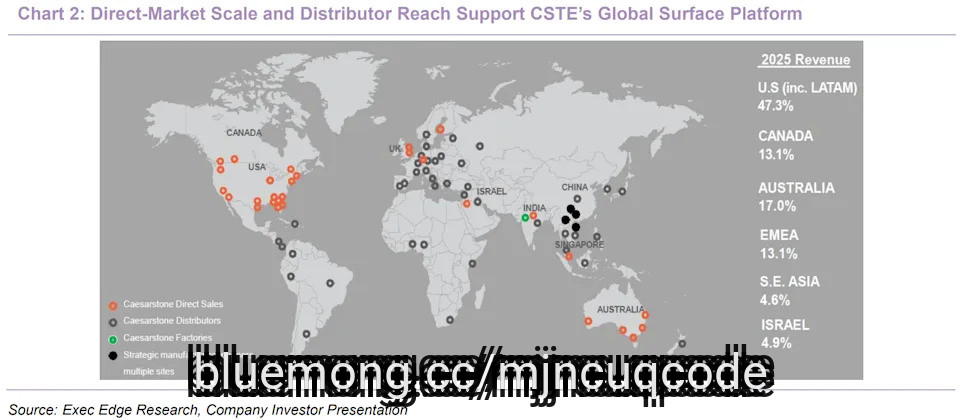
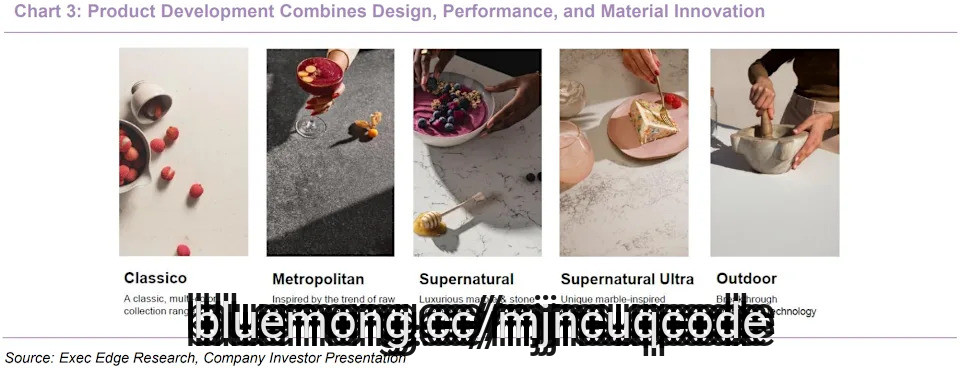
A premium multi-material surfaces platform becoming structurally lighter and more flexible. CSTE designs, develops, sources and markets premium quartz, ICON, porcelain, natural stone and complementary surface products, generating $397.2 million of revenue in 2025, with direct sales contributing 89% of revenue across its largest markets. The company has transitioned quartz production to external partners while retaining product development, quality, brand and customer control, with Lioli providing owned porcelain capacity. This broadens CSTE beyond legacy quartz while reducing fixed manufacturing exposure and increasing sourcing flexibility.
A differentiated model built on reinforcing sourcing, design, brand and direct-market capabilities supports commercial relevance across materials. CSTE combines partner-led quartz production with proprietary formulations, quality ***** urance, design know-how, premium brand recognition and local sales infrastructure. ICON provides the clearest proof point, with Australia delivering four consecutive quarters of y/y growth following the full rollout of CSTE's crystalline-silica-free collection. Porcelain extends the same commercial platform into additional applications, broadening the competitive advantage beyond any single product or manufacturing ***** et.
Growth strategy pairs a structural cost reset with targeted commercial and category expansion. CSTE is completing the partner-led production transition, rebuilding North American customer and channel engagement, sustaining Australia's ICON-led momentum, expanding porcelain and extending brand-led geographic reach. The restructuring targets more than $100 million of annualized savings by 2027 versus 2023, including approximately $22 million from the Bar-Lev closure. Execution is now focused on stabilizing core volumes, improving Lioli's commercial alignment, expanding channel productivity and mitigating the new U.S. quartz tariffs.
Material substitution and selective regional recovery broaden CSTE's addressable opportunity beyond legacy quartz. CSTE's existing and adjacent categories span approximately 53% of global countertop volume, while engineered quartz is forecast to recover and porcelain offers materially faster growth from a smaller base. Natural stone adds further U.S. optionality, while Australia demonstrates how regulatory change can redirect rather than eliminate premium-surface demand. North America remains the largest earnings opportunity, with renovation, ageing housing stock and material substitution providing recovery potential even before a full housing upcycle.
#porcelain #premium #icon #material
A premium multi-material surfaces platform becoming structurally lighter and more flexible. CSTE designs, develops, sources and markets premium quartz, ICON, porcelain, natural stone and complementary surface products, generating $397.2 million of revenue in 2025, with direct sales contributing 89% of revenue across its largest markets. The company has transitioned quartz production to external partners while retaining product development, quality, brand and customer control, with Lioli providing owned porcelain capacity. This broadens CSTE beyond legacy quartz while reducing fixed manufacturing exposure and increasing sourcing flexibility.
A differentiated model built on reinforcing sourcing, design, brand and direct-market capabilities supports commercial relevance across materials. CSTE combines partner-led quartz production with proprietary formulations, quality ***** urance, design know-how, premium brand recognition and local sales infrastructure. ICON provides the clearest proof point, with Australia delivering four consecutive quarters of y/y growth following the full rollout of CSTE's crystalline-silica-free collection. Porcelain extends the same commercial platform into additional applications, broadening the competitive advantage beyond any single product or manufacturing ***** et.
Growth strategy pairs a structural cost reset with targeted commercial and category expansion. CSTE is completing the partner-led production transition, rebuilding North American customer and channel engagement, sustaining Australia's ICON-led momentum, expanding porcelain and extending brand-led geographic reach. The restructuring targets more than $100 million of annualized savings by 2027 versus 2023, including approximately $22 million from the Bar-Lev closure. Execution is now focused on stabilizing core volumes, improving Lioli's commercial alignment, expanding channel productivity and mitigating the new U.S. quartz tariffs.
Material substitution and selective regional recovery broaden CSTE's addressable opportunity beyond legacy quartz. CSTE's existing and adjacent categories span approximately 53% of global countertop volume, while engineered quartz is forecast to recover and porcelain offers materially faster growth from a smaller base. Natural stone adds further U.S. optionality, while Australia demonstrates how regulatory change can redirect rather than eliminate premium-surface demand. North America remains the largest earnings opportunity, with renovation, ageing housing stock and material substitution providing recovery potential even before a full housing upcycle.
#porcelain #premium #icon #material
2 months ago
While the State Street Technology Select Sector SPDR ETF (NYSEMKT:XLK) and Vanguard Information Technology ETF (NYSEMKT:VGT) both track the U.S. tech sector, the Vanguard fund offers significantly broader diversification through its multi-cap index.
These funds serve as foundational blocks for investors targeting the innovation-driven growth of the American tech sector, including exposure to the artificial intelligence boom. While they may appear identical at first glance, subtle differences in index construction and portfolio concentration can lead to different outcomes during various market cycles.
The Vanguard fund is larger, with $160.2 billion in ******* ets under management (AUM), compared to $119.3 billion for the State Street fund. This ******* ysis explores how their unique weighting methodologies influence risk and reward.
Metric
XLK
#sector #technology #nysemkt
These funds serve as foundational blocks for investors targeting the innovation-driven growth of the American tech sector, including exposure to the artificial intelligence boom. While they may appear identical at first glance, subtle differences in index construction and portfolio concentration can lead to different outcomes during various market cycles.
The Vanguard fund is larger, with $160.2 billion in ******* ets under management (AUM), compared to $119.3 billion for the State Street fund. This ******* ysis explores how their unique weighting methodologies influence risk and reward.
Metric
XLK
#sector #technology #nysemkt

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Why we like it: The Citi Custom Cash was the highest-ranking Citi card in multiple categories, including cash back, 0% APR, and groceries. As a no-annual-fee credit card, it's a formidable force on multiple fronts, especially if you want to earn high rewards rates on everyday purchases.
Read our full Citi Custom Cash Card review
Why we like it: The Citi Strata Premier has a low annual fee and an excellent rewards rate unmatched by many similar travel credit cards. This is especially true with its 3x return at supermarkets and gas stations, making the Strata Premier an exceptional choice for earning travel rewards on common expenses.
Why we like it: The Citi Double Cash provides a 0% intro APR period on balance transfers that's well above the average length, giving you plenty of time to pay down existing debt without worrying about accruing interest. In addition, this is a top-tier cash-back card with its 2% cash-back rate on all eligible purchases.
#like
Why we like it: The Citi Custom Cash was the highest-ranking Citi card in multiple categories, including cash back, 0% APR, and groceries. As a no-annual-fee credit card, it's a formidable force on multiple fronts, especially if you want to earn high rewards rates on everyday purchases.
Read our full Citi Custom Cash Card review
Why we like it: The Citi Strata Premier has a low annual fee and an excellent rewards rate unmatched by many similar travel credit cards. This is especially true with its 3x return at supermarkets and gas stations, making the Strata Premier an exceptional choice for earning travel rewards on common expenses.
Why we like it: The Citi Double Cash provides a 0% intro APR period on balance transfers that's well above the average length, giving you plenty of time to pay down existing debt without worrying about accruing interest. In addition, this is a top-tier cash-back card with its 2% cash-back rate on all eligible purchases.
#like

2 months ago
On August 28, Frontline (NYSE:FRO) posted the best quarter in company history, with net income of $659 million and adjusted profit of $580 million for the second quarter of 2026, up $235 million from the prior quarter. The gains came from tanker rates that climbed across every vessel class Frontline operates, from its largest crude carriers to its smaller product tankers. CEO Lars Barstad described a market with no playbook, one where geopolitical disruption is reshaping how oil moves around the world. The bigger question left hanging on the call is how much of that strength holds once the disruptions ease.
VLCC rates hit $153,000 per day in the second quarter of 2026, while Suezmax and LR2/Aframax vessels earned $111,000 and $92,400 per day. That strength has carried into the third quarter, where Frontline has already booked 86% of VLCC days at $157,000 per day, 79% of Suezmax days at $117,000 per day, and 70% of LR2 days at $81,000 per day, evidence that rates are holding rather than sliding back. The fleet backing those numbers is young and efficient, averaging 6.6 years old, fully eco-designed, and 69% scrubber-fitted, which keeps cash breakeven costs between $22,200 and $25,700 per day, well under what the ships are currently earning.
That spread between cost and rate is throwing off real cash. Management estimated annual cash generation potential at $2.3 billion, or $10.35 per share, based on rates as of August 28, a 24% yield against the current share price. The balance sheet has room to match it: $1.2 billion in liquidity, no debt maturities until 2030, and a refinancing that cut the average interest rate margin by 52 basis points to 1.26%. Frontline also collected $270 million selling two VLCCs at about $135 million apiece, with Barstad noting some buyers are paying premiums for older tankers just to control their own logistics chains.
Much of the current rate strength traces back to friction rather than growth in oil demand. Crude exports from inside the Strait of Hormuz are down 82% amid recent disruptions, and China's crude imports have fallen 35%, cushioned by inventory drawdowns rather than fresh buying. Barstad pointed to a 23% increase in VLCC idling days, driven by ship-to-ship transfers off Fujairah and Malaysia that can triple the distance a cargo travels before reaching its final buyer. That inefficiency is tightening effective fleet supply even as actual volumes shrink, which is a different story than genuine demand growth.
#million #vlcc #strength #rather
VLCC rates hit $153,000 per day in the second quarter of 2026, while Suezmax and LR2/Aframax vessels earned $111,000 and $92,400 per day. That strength has carried into the third quarter, where Frontline has already booked 86% of VLCC days at $157,000 per day, 79% of Suezmax days at $117,000 per day, and 70% of LR2 days at $81,000 per day, evidence that rates are holding rather than sliding back. The fleet backing those numbers is young and efficient, averaging 6.6 years old, fully eco-designed, and 69% scrubber-fitted, which keeps cash breakeven costs between $22,200 and $25,700 per day, well under what the ships are currently earning.
That spread between cost and rate is throwing off real cash. Management estimated annual cash generation potential at $2.3 billion, or $10.35 per share, based on rates as of August 28, a 24% yield against the current share price. The balance sheet has room to match it: $1.2 billion in liquidity, no debt maturities until 2030, and a refinancing that cut the average interest rate margin by 52 basis points to 1.26%. Frontline also collected $270 million selling two VLCCs at about $135 million apiece, with Barstad noting some buyers are paying premiums for older tankers just to control their own logistics chains.
Much of the current rate strength traces back to friction rather than growth in oil demand. Crude exports from inside the Strait of Hormuz are down 82% amid recent disruptions, and China's crude imports have fallen 35%, cushioned by inventory drawdowns rather than fresh buying. Barstad pointed to a 23% increase in VLCC idling days, driven by ship-to-ship transfers off Fujairah and Malaysia that can triple the distance a cargo travels before reaching its final buyer. That inefficiency is tightening effective fleet supply even as actual volumes shrink, which is a different story than genuine demand growth.
#million #vlcc #strength #rather
2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Arm Holdings plc (NASDAQ:ARM) as a leading contributor. Arm Holdings plc (NASDAQ:ARM) is a UK-based technology company that develops and licenses central processing unit designs and related technologies for semiconductor companies and original equipment manufacturers. On August 21, 2026, Arm Holdings plc (NASDAQ:ARM) closed at $243.32 per share. The one-month return of Arm Holdings plc (NASDAQ:ARM) was -8.64%, and its shares gained 76.60% over the past 52 weeks. Arm Holdings plc (NASDAQ:ARM) has a market capitalization of $259.87 billion.
SGA Global Growth Strategy stated the following regarding Arm Holdings plc (NASDAQ:ARM) in its Q2 2026 investor letter:
"Arm Holdings plc (NASDAQ:ARM), leading designer and licensor of CPU architectures and related subsystems, was a top contributor to performance again this quarter. The company delivered solid quarterly results, including 20% revenue growth and 12% profit growth, with continued strength in licensing activity and sustained royalty expansion despite a tougher comparison period. Management guidance reinforced confidence in maintaining roughly 20% revenue growth, supported by increasing demand for Arm-based CPUs and expanding adoption across data center and AI workloads, which helped offset expected weakness in handset markets. Confidence was further supported by evidence of strong CPU demand, improving share gains versus x86 architectures, and growing customer traction, including an expanding roster of signed partners and management's confidence in achieving long-term revenue targets. With strong pricing power, highly recurring revenues, and expanding royalty rates as Arm captures more value across the compute stack, we continue to view the company as a high-quality, long-term compounder well-positioned to benefit from the proliferation of AI and power efficient computing. We
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Arm Holdings plc (NASDAQ:ARM) as a leading contributor. Arm Holdings plc (NASDAQ:ARM) is a UK-based technology company that develops and licenses central processing unit designs and related technologies for semiconductor companies and original equipment manufacturers. On August 21, 2026, Arm Holdings plc (NASDAQ:ARM) closed at $243.32 per share. The one-month return of Arm Holdings plc (NASDAQ:ARM) was -8.64%, and its shares gained 76.60% over the past 52 weeks. Arm Holdings plc (NASDAQ:ARM) has a market capitalization of $259.87 billion.
SGA Global Growth Strategy stated the following regarding Arm Holdings plc (NASDAQ:ARM) in its Q2 2026 investor letter:
"Arm Holdings plc (NASDAQ:ARM), leading designer and licensor of CPU architectures and related subsystems, was a top contributor to performance again this quarter. The company delivered solid quarterly results, including 20% revenue growth and 12% profit growth, with continued strength in licensing activity and sustained royalty expansion despite a tougher comparison period. Management guidance reinforced confidence in maintaining roughly 20% revenue growth, supported by increasing demand for Arm-based CPUs and expanding adoption across data center and AI workloads, which helped offset expected weakness in handset markets. Confidence was further supported by evidence of strong CPU demand, improving share gains versus x86 architectures, and growing customer traction, including an expanding roster of signed partners and management's confidence in achieving long-term revenue targets. With strong pricing power, highly recurring revenues, and expanding royalty rates as Arm captures more value across the compute stack, we continue to view the company as a high-quality, long-term compounder well-positioned to benefit from the proliferation of AI and power efficient computing. We

2 months ago
Guinness Global Innovators, an investment management company, recently released its Q2 2026 quarterly investor update for its "Guinness Global Innovators Fund". You can download the letter here. The Guinness Global Innovators Fund focuses on investing in global companies that benefit from innovation in technology, communication, globalization, and management strategies. In the second quarter of 2026, the Guinness Global Innovators Fund returned 13.8% in GBP, compared with 13.0% for the MSCI World Index and 13.1% for the IA Global sector average. Easing Middle East tensions, falling oil prices, and renewed enthusiasm for artificial intelligence helped reverse much of the caution seen earlier in the year, with investors rotating back toward growth stocks and AI infrastructure beneficiaries. The Fund benefited from its overweight position in Information Technology sector, while overweight position in Communication Services detracted. Avoiding weaker Utilities, Materials, and Energy also supported relative performance. The letter examines the five distinct market phases that shaped the first half, changing Federal Reserve policy expectations, surging hyperscaler and semiconductor capital expenditure, and record capital raising across the AI ecosystem. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Guinness Global Innovators Fund highlighted Netflix, Inc. (NASDAQ:NFLX) noting it was one of the weaker performers during the quarter. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On August 21, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $79.59 per share, reflecting a market capitalization of $331.41 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of 13.05%, while its shares lost 34.66% over the past 52 weeks.
Guinness Global Innovators Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX), the streaming giant, was one of the Fund's weaker performers over the quarter, following a harsh share price reaction to its last quarterly print. Shares sold off despite strong organic growth driven by strong membership numbers, higher pricing, and increased advertising revenue. There was also a boost to earnings per share from the termination fee related to Paramount's merger with Warner Bros, as Netflix had previously been in talks to acquire the latter's studio and streaming ******* ets. However, the market was disappointed by Netflix choosing to maintain guidance for 2026 despite the positive momentum seen in the first quarter. This was taken as a potential indicator of growth deceleration in future quarters, with some questioning whether Netflix can sustain pricing power given the increases it has already pushed through the subscriber base. The company also announced the departure of its Co-founder and Chairman Reed Hastings to focus on philanthropic and
In its second-quarter 2026 investor letter, Guinness Global Innovators Fund highlighted Netflix, Inc. (NASDAQ:NFLX) noting it was one of the weaker performers during the quarter. Netflix, Inc. (NASDAQ:NFLX) is a leading subscription-based streaming entertainment platform. On August 21, 2026, Netflix, Inc. (NASDAQ:NFLX) closed at $79.59 per share, reflecting a market capitalization of $331.41 billion. Netflix, Inc. (NASDAQ:NFLX) posted a one‑month return of 13.05%, while its shares lost 34.66% over the past 52 weeks.
Guinness Global Innovators Fund stated the following regarding Netflix, Inc. (NASDAQ:NFLX) in its Q2 2026 investor letter:
"Netflix, Inc. (NASDAQ:NFLX), the streaming giant, was one of the Fund's weaker performers over the quarter, following a harsh share price reaction to its last quarterly print. Shares sold off despite strong organic growth driven by strong membership numbers, higher pricing, and increased advertising revenue. There was also a boost to earnings per share from the termination fee related to Paramount's merger with Warner Bros, as Netflix had previously been in talks to acquire the latter's studio and streaming ******* ets. However, the market was disappointed by Netflix choosing to maintain guidance for 2026 despite the positive momentum seen in the first quarter. This was taken as a potential indicator of growth deceleration in future quarters, with some questioning whether Netflix can sustain pricing power given the increases it has already pushed through the subscriber base. The company also announced the departure of its Co-founder and Chairman Reed Hastings to focus on philanthropic and

3 months ago
The oil market has remained complacent for months amid the worst disruption in global supply, with crude oil futures rarely topping $100 per barrel over the six months in which tanker traffic at the Strait of Hormuz is a trickle compared to pre-war levels.
While market participants have been putting too much hope of a resolution of the conflict in their bets on future crude prices, product supply of the fuel of the economies – diesel – has been shrinking.
So much has the diesel market tightened in recent months that the diesel crack spread, the pricing difference between a barrel of crude oil and the diesel refined from it, hit record highs in both the United States and Europe this week.
The crude oil market shows traders' expectations of near-term supply, but the diesel markets are flashing the very real physical tightness of the petroleum product whose consumption has yet to rise this year and whose availability and prices drive economies and inflation.
The diesel crack spread in the United States hit triple digits this week, for the first time ever. The premium over crude prices jumped to as high as $102 per barrel on Monday, before easing slightly to about $100 a barrel on Tuesday.
#market #states
While market participants have been putting too much hope of a resolution of the conflict in their bets on future crude prices, product supply of the fuel of the economies – diesel – has been shrinking.
So much has the diesel market tightened in recent months that the diesel crack spread, the pricing difference between a barrel of crude oil and the diesel refined from it, hit record highs in both the United States and Europe this week.
The crude oil market shows traders' expectations of near-term supply, but the diesel markets are flashing the very real physical tightness of the petroleum product whose consumption has yet to rise this year and whose availability and prices drive economies and inflation.
The diesel crack spread in the United States hit triple digits this week, for the first time ever. The premium over crude prices jumped to as high as $102 per barrel on Monday, before easing slightly to about $100 a barrel on Tuesday.
#market #states

3 months ago
Maridea Wealth Management has acquired advisory business Park Ridge Financial, expanding its presence in the Chicago.
Financial terms of the deal remain undisclosed.
Park Ridge Financial is known for offering financial planning services to individuals, families, and business owners, covering investment management, retirement planning, and estate conservation.
Maridea formally set up its presence in Chicago in September 2025.
The Park Ridge Financial team will move into Maridea's current Chicago office.
#financial
Financial terms of the deal remain undisclosed.
Park Ridge Financial is known for offering financial planning services to individuals, families, and business owners, covering investment management, retirement planning, and estate conservation.
Maridea formally set up its presence in Chicago in September 2025.
The Park Ridge Financial team will move into Maridea's current Chicago office.
#financial
3 months ago
Cloudflare (NET) stock is getting a fresh vote of confidence from Wall Street after the company delivered a stronger-than-expected second quarter and raised its full-year outlook. Shares jumped following the report, pushing the stock to record territory as investors digested accelerating growth, stronger customer additions, and rising demand tied to artificial intelligence.
The bigger story is that ******* ysts now see Cloudflare as more than a cybersecurity and content-delivery company. Its network is increasingly becoming infrastructure for the AI-driven internet, giving Wall Street another reason to raise its expectations for NET stock.
Don't ******* ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Shaq Says His Dad Treated Him to White Castle, But When He Saw Homeless Man With a Sign, He Gave 3 of His Burgers to the Guy — 'Always Look Out for the Little Man'
#wall
The bigger story is that ******* ysts now see Cloudflare as more than a cybersecurity and content-delivery company. Its network is increasingly becoming infrastructure for the AI-driven internet, giving Wall Street another reason to raise its expectations for NET stock.
Don't ******* ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Shaq Says His Dad Treated Him to White Castle, But When He Saw Homeless Man With a Sign, He Gave 3 of His Burgers to the Guy — 'Always Look Out for the Little Man'
#wall


3 months ago
Space Exploration Technologies Corp. (NASDAQ: SPCX) stock rocketed 15.8% higher on Friday while the S&P 500 and the Nasdaq Composite jumped 0.6% and 1.2%, respectively.
Shares of Elon Musk's rocket company rose after a post-IPO lock-up expiration failed to drag the stock down. At the same time, the announcement of a major project in Texas helped buoy the stock price.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
On Thursday, 911.5 million shares became eligible to trade as the first tranche of the lockup expired -- the stretch after an initial public offering (IPO) when insiders and early backers are barred from selling. That more than doubled the stock available to public markets, and investors were nervous the share price would tank as early investors and employees rushed to sell part of their stakes.
The fact that did not come to pass was taken by the market as a sort of endorsement from company insiders.
#Stock #same #time
Shares of Elon Musk's rocket company rose after a post-IPO lock-up expiration failed to drag the stock down. At the same time, the announcement of a major project in Texas helped buoy the stock price.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
On Thursday, 911.5 million shares became eligible to trade as the first tranche of the lockup expired -- the stretch after an initial public offering (IPO) when insiders and early backers are barred from selling. That more than doubled the stock available to public markets, and investors were nervous the share price would tank as early investors and employees rushed to sell part of their stakes.
The fact that did not come to pass was taken by the market as a sort of endorsement from company insiders.
#Stock #same #time
3 months ago
Applied Digital Corp (NASDAQ:APLD)'s transformation from a crypto-mining/data-center hosting company to an AI infrastructure provider is beginning to reflect in its earnings. The company is enjoying robust growth fueled by rapid conversion of its data center footprint into artificial intelligence and high-performance computing infrastructure. Likewise, hyperscaler leases and tenant buildout are increasingly driving near-term revenue growth.
Shares have gained more than 20% year to date, with the stock remaining volatile and below some of its recent highs. The market is particularly focused on the company's execution, financing, profitability, and timing of future cash flows. Sentiment and outlook for the stock are slowly changing, triggering prospects of a potential breakout after months of underperformance.
Robust revenue growth affirms why Applied Digital Corp (NASDAQ:APLD) is a compelling investment play on improving underlying fundamentals. The company delivered fiscal fourth quarter 2026 revenue of $258.7 million, up 407% year over year and topping estimates of $94.8 million. Similarly, full-year revenue was up 167% to $611.3 million. Adjusted earnings per share came in at $0.04 above expectations of a $0.22 loss.
The 407% revenue growth suggests the company is no longer a future AI story but a company that's converting data center capacity into sales. The growth has come as the company shifts toward building large, power-dense data centers that it leases to hyperscalers and AI cloud companies, thereby securing key revenue streams.
The Data Center Hosting segment generated $38 million in revenue in Q4 FY2025. Revenue in the segment increased to $203 million as of Q4 FY2026, suggesting new leases are becoming bigger than Traditional Data Center Hosting, which was essentially flat at $37.3 million.
#Growth
Shares have gained more than 20% year to date, with the stock remaining volatile and below some of its recent highs. The market is particularly focused on the company's execution, financing, profitability, and timing of future cash flows. Sentiment and outlook for the stock are slowly changing, triggering prospects of a potential breakout after months of underperformance.
Robust revenue growth affirms why Applied Digital Corp (NASDAQ:APLD) is a compelling investment play on improving underlying fundamentals. The company delivered fiscal fourth quarter 2026 revenue of $258.7 million, up 407% year over year and topping estimates of $94.8 million. Similarly, full-year revenue was up 167% to $611.3 million. Adjusted earnings per share came in at $0.04 above expectations of a $0.22 loss.
The 407% revenue growth suggests the company is no longer a future AI story but a company that's converting data center capacity into sales. The growth has come as the company shifts toward building large, power-dense data centers that it leases to hyperscalers and AI cloud companies, thereby securing key revenue streams.
The Data Center Hosting segment generated $38 million in revenue in Q4 FY2025. Revenue in the segment increased to $203 million as of Q4 FY2026, suggesting new leases are becoming bigger than Traditional Data Center Hosting, which was essentially flat at $37.3 million.
#Growth

3 months ago
For allocators, the formula for strong returns is simple: a blend of strategic portfolio construction and scrutinous manager selection.
Though the execution is a complex balance between quantitative and qualitative ******* ysis, one of the first steps in manager selection will always be past performance.
The PitchBook 2025 Global Manager Performance Score League Tables rank each private equity firm's family of funds by comparing their returns to similar funds raised in the same years. It then converts that outperformance (or underperformance) into a single 0-100 score, with 50 indicating average.
Topping the middle-market buyout category with a perfect 100 for the second year in a row is SSC Partners, the flagship family of Dallas-based Sole Source Capital. This is the only fund family across all 13 strategies in this year's report to reach PitchBook's scale ceiling. Its most recent vintage is open for commitments.
Here's a list of the top-performing fund families per buyout category:
#score #buyout
Though the execution is a complex balance between quantitative and qualitative ******* ysis, one of the first steps in manager selection will always be past performance.
The PitchBook 2025 Global Manager Performance Score League Tables rank each private equity firm's family of funds by comparing their returns to similar funds raised in the same years. It then converts that outperformance (or underperformance) into a single 0-100 score, with 50 indicating average.
Topping the middle-market buyout category with a perfect 100 for the second year in a row is SSC Partners, the flagship family of Dallas-based Sole Source Capital. This is the only fund family across all 13 strategies in this year's report to reach PitchBook's scale ceiling. Its most recent vintage is open for commitments.
Here's a list of the top-performing fund families per buyout category:
#score #buyout




