

1 month ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral


2 months ago
On the September 2 episode of Mad Money, Jim Cramer called Cardinal Health, Inc. (NYSE:CAH) one of his "absolute favorites" and mentioned its growing exposure to specialty pharmaceuticals and higher-margin healthcare services.
Cardinal's been running circles around McKesson and Cencora. They consistently put up the best numbers because this company has gradually become less of a commoditized service provider and more of a specialized player.
Cardinal Health, Inc.'s (NYSE:CAH) fiscal fourth-quarter revenue rose 6% to $63.7 billion but missed estimates, while adjusted earnings per share came in at $2.91. Excluding a $0.31 per share tariff refund benefit, adjusted EPS was $2.60. Management forecast fiscal 2027 non-GAAP EPS of $12.40 to $12.60, a 13% to 15% growth, while adjusted free cash flow is expected at $3.5 billion to $4 billion.
The revenue miss is less significant if the company continues converting pharmaceutical volume into earnings. Lower branded-drug prices, including those affected by Medicare negotiations, can reduce reported sales without a proportional decline in distributor fees. The shift toward generics can have a similar effect because lower-priced drugs generate less revenue but can support attractive margins and high volumes. As Cramer said:
Remember, volume is where Cardinal really makes the money, volume, okay? That's why I keep shrugging off the revenue misses.
#cardinal #less #billion #NYSE


3 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record quarterly revenue and adjusted EBITDA, driven by a 43% year-over-year increase in Cortrophin Gel sales and persistent execution in the Generics segment.
Completed the single largest rare disease sales force expansion in company history, increasing headcount by 50% to approximately 180 representatives to target the acute gouty arthritis market.
Attributed strong Cortrophin growth to existing specialties like ophthalmology, where volumes doubled year-over-year, and rheumatology, despite early-year insurance reverification headwinds.
Maintained a dominant position in the Generics market as the #2 player in Competitive Generic Therapy (CGT) filings, utilizing cash flow to fund rare disease R&D and commercial infrastructure.
#cortrophin #generics #achieved


3 months ago
With a market cap of $20.5 billion, Viatris Inc. (VTRS) is a global healthcare company committed to empowering people worldwide to live healthier lives at every stage. With a diverse portfolio spanning generics, established brands, and innovative medicines, it delivers effective, scalable healthcare solutions to address significant unmet needs globally.
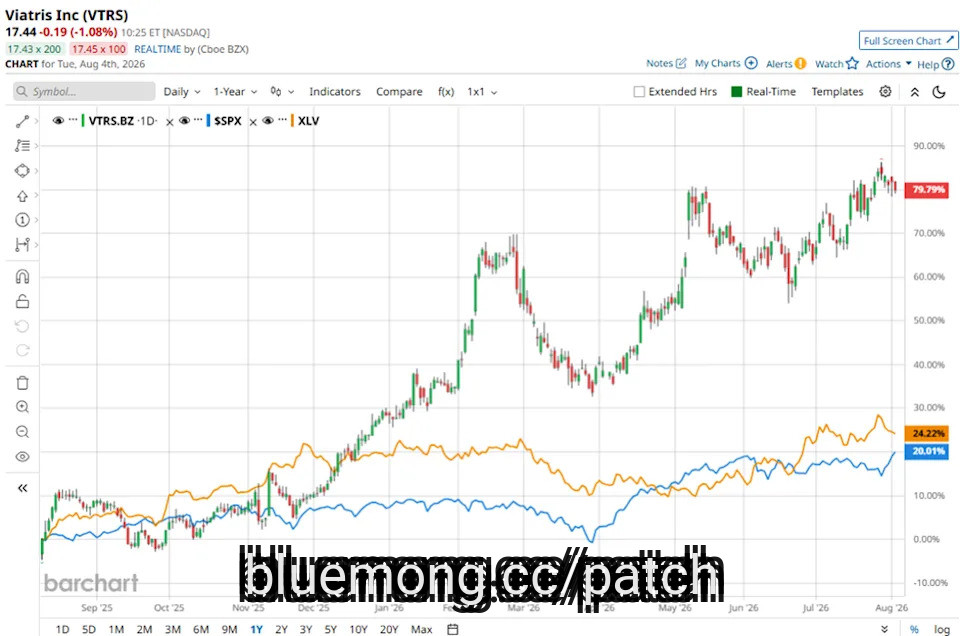
Shares of the Canonsburg, Pennsylvania-based company have surpassed the broader market over the past 52 weeks. VTRS stock has soared 96.7% over this time frame, while the broader S&P 500 Index ($SPX) has gained nearly 21%. Moreover, the stock has returned 41.2% on a YTD basis, compared to SPX's 11.9% rise.
General Motors vs. Ford: 1 Auto Giant Is Winning the EV Race
1 **** anese Company Just Waved a Red Flag for Micron Stock. How to Play It Here.
Billionaire Ken Griffin Just Saved Situational Awareness, But Here's What a Rescue Call From Citadel Really Sounds Like — 'I… Heard the Grim Reaper's Scythe'
#company #shares



3 months ago
Canonsburg, Pennsylvania-based Viatris Inc. (VTRS) is a global healthcare company that develops, manufactures, and markets branded medicines, generic drugs, complex generics, biosimilars, and over-the-counter products. Valued at a market cap of $19.8 billion, Viatris aims to expand access to affordable, high-quality medicines worldwide.
The healthcare ****** an is expected to release its Q2 2026 earnings before the market opens on Thursday, Aug. 6. Ahead of the event, ****** ysts expect the company's EPS to be $0.62 on a diluted basis, flat from the year-ago quarter. The company has exceeded Wall Street's EPS estimates in each of its last four quarters.
PayPal Says a $53 Billion Takeover Offer from Stripe Undervalues It. How to Play PYPL Stock Here.
Billionaire Jeff Bezos Called Amazon's Customer Service to Prove a Point But Waited in Silence for More Than 10 Minutes — 'It Was Really Long'
Micron Stock Is Near Bear-Market Territory. Here's Why ASML's Guidance Says Buy the Dip.
#Stock #healthcare #medicines



4 months ago
By Andrew Silver
SHANGHAI, July 9 (Reuters) - China will add a second GLP-1 drug, used to treat diabetes, to a list of essential drugs all public hospitals are required to prioritise having in their formulary, a government statement said on Thursday.
China, the world's second-biggest pharmaceutical market, has the highest number of adults with diabetes in the world, according to estimates from the International Diabetes Federation.
Justin ***** , a partner at global strategy consultancy L.E.K. Consulting in Shanghai, told Reuters the essential listing would mean the drug, semaglutide, should be available even in remote rural hospitals.
So far only the Ozempic brand version has approval, but ***** said the inclusion of semaglutide in the National Essential Drug List would also "pave the way for generics to be broadly listed" once they are approved in China.


4 months ago
Biogen (NASDAQ: BIIB) built itself into a biotech giant thanks to its portfolio of multiple sclerosis (MS) drugs -- but in biotech and pharma, revenue growth depends on the life of a patent. Once a company loses exclusivity, generics or biosimilars enter the market, and the leader's drug sales decline. This is the challenge Biogen has faced in recent years, as MS blockbusters faced growing competition.
But the biotech giant put into place a recovery and growth plan, shifting many costs out of the MS franchise and into areas that represented growth potential. Biogen also made strategic acquisitions, announcing its intention to buy Apellis Pharmaceuticals, an immunology and rare diseases drug company, in March and closing the deal in May.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
And just recently, Biogen announced another purchase. This time, the biotech is paying $1 billion for a company that won't say what it makes. Here's why this actually is good news for Biogen investors.
Let's start with a quick update on Biogen. As mentioned, the biotech company was once known as an MS giant, and it still sells a number of important MS drugs, such as Tecfidera and Tysabri. But loss of exclusivity made a significant dent in revenue, with Tecfidera's peak sales of $4.4 billion in 2019 dropping to $1.4 billion in 2022. In the latest fiscal year, all of Biogen's MS drugs, together, delivered $4 billion in revenue, further highlighting this decline.






