
14 days ago
A Medicaid divorce lets the at-home spouse keep the house and up to $162,660 while Medicaid covers the nursing home's $9,277 monthly bill.
The strategy requires a real court-ordered divorce, since Medicaid's five-year look-back treats uneven transfers as gifts and penalizes them.
Before filing, families should exhaust spousal refusal, Medicaid-compliant annuities, and exempt-asset conversions, since a divorce strips survivor benefits and medical decision rights.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
A Medicaid divorce, involves a long-married couple legally ending their marriage as part of a long-term care strategy. He enters a nursing home that Medicaid may cover, while she keeps the house and a larger share of their savings to protect her retirement. It's a real but uncommon strategy. State laws may vary, and many attorneys consider it a last resort.
#medicaid #real #since #stocks
1 month ago
Looking for passive income and a lot of it? Who wouldn't like that? Passive income can come from multiple sources, such as certificates of deposit (CDs), pensions, annuities, royalty checks, rental properties, and dividends, to name a few. I think dividend income is particularly compelling because:
Healthy and growing dividend payers tend to increase their payouts over time, often helping shareholders keep up with inflation.
Such companies also tend to keep paying no matter whether the economy is booming or in a slump.
Dividend payers are simply great investments, in general. Check it out:
Dividend-Paying Status
#tend
1 month ago
Newark, New Jersey-based Prudential Financial, Inc. (PRU) is a diversified global financial services company that helps individuals and institutions protect wealth, prepare for retirement and pursue long-term financial goals. Valued at a market cap of $41.2 billion, its businesses span life insurance, annuities, retirement solutions, group insurance and investment management through PGIM, its global ****** et-management arm.
Companies with a market cap of $10 billion or more are typically referred to as "big-cap stocks." PRU fits right into that category. Prudential dominates the market due to its diversified insurance, retirement and investment-management businesses, which provide multiple sources of earnings and reduce reliance on any single market or product. Its established brand, extensive distribution network, large institutional and individual customer base and PGIM ****** et-management platform support scale, recurring fee income and cross-selling opportunities.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ****** ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#management #financial #prudential #Stock


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
One of the toughest hurdles for retirees is working out how to pay themselves and then spending the money.
For decades, the pressure has been to save. When the time comes to start drawing on those funds, it can be paralyzing.
Personal finance expert Jean Chatzky has a solution: Use an annuity to provide a paycheck.
To annuitize essentially means to convert a lump sum portion of a retirement account into a contract that pays you a fixed monthly amount for a specified period or for the rest of your life.
The trouble is that annuities sold by insurance companies have a bad undertone for many people. They can be difficult to understand and typically come with a variety of fees. It's hard to know what the real cost is and what the penalties are if you need to tap the money for an emergency.
#spending

2 months ago
One of the toughest hurdles for retirees is working out how to pay themselves and then spending the money.
For decades, the pressure has been to save. When the time comes to start drawing on those funds, it can be paralyzing.
Personal finance expert Jean Chatzky has a solution: Use an annuity to provide a paycheck.
To annuitize essentially means to convert a lump sum portion of a retirement account into a contract that pays you a fixed monthly amount for a specified period or for the rest of your life.
The trouble is that annuities sold by insurance companies have a bad undertone for many people. They can be difficult to understand and typically come with a variety of fees. It's hard to know what the real cost is and what the penalties are if you need to tap the money for an emergency.
#personal #chatzky #retirees #themselves

2 months ago
Hennessy Fund's Q2 2026 investor letter for the Hennessy Equity and Income Fund. The letter can be downloaded here. The letter discusses portfolio changes, emphasizing opportunities in equity and fixed income markets that can withstand economic uncertainty. The portfolio held businesses with a 23.0% pre-tax return on invested capital versus 16.1% for the S&P 500. The letter notes a reversal in U.S. equities, driven by AI spending and strong earnings, despite cautious sentiment among lower-income households. The focus on high-quality firms with durable advantages is expected to yield positive outcomes as valuation pressures mount, indicating that future market performance may hinge on fundamentals rather than speculative trends. The portfolio aims to capitalize on the overlooked valuations of quality companies, presenting significant investment opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hennessy Equity and Income Fund highlighted Equitable Holdings, Inc. (NYSE:EQH), a leading diversified financial services company focusing on life insurance, annuities, ******* et management, and retirement solutions. The Fund disclosed that it sold its position in Equitable Holdings, Inc. (NYSE:EQH) during the quarter. On August 31, 2026, Equitable Holdings, Inc. (NYSE:EQH) closed at $50.13 per share. Over the past month, Equitable Holdings, Inc. (NYSE:EQH) returned 3.90%, but its shares are down 4.97% over the past year. Equitable Holdings, Inc. (NYSE:EQH) has a market capitalization of $13.67 billion, and its stock has traded within a 52-week range of $35.19 to $55.15.
Hennessy Equity and Income Fund stated the following regarding Equitable Holdings, Inc. (NYSE:EQH) in its Q2 2026 investor letter:
"Equitable Holdings, Inc. (NYSE:EQH) triggered our soft stop-loss review, and with no insider buying to reinforce conviction, we sold the position. While Equitable continues to generate strong cash flow and return capital in a disciplined manner, the underlying core business has remained inconsistent. Earnings quality is uneven, flows are mixed, and ongoing pressure in the individual life and retirement segments raises concern. Although valuation appears attractive, our confidence in the ability to deliver consistent results and successfully execute a turnaround was lowered."
Equitable Holdings, Inc. (NYSE:EQH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 49 hedge fund portfolios held Equitable Holdings, Inc. (NYSE:EQH) at the end of the second quarter, which was 42 in the previous quarter. While we acknowledge the potential of Equitable Holdings, Inc. (NYSE:EQH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
2 months ago
Hennessy Fund's Q2 2026 investor letter for the Hennessy Equity and Income Fund. The letter can be downloaded here. The letter discusses portfolio changes, emphasizing opportunities in equity and fixed income markets that can withstand economic uncertainty. The portfolio held businesses with a 23.0% pre-tax return on invested capital versus 16.1% for the S&P 500. The letter notes a reversal in U.S. equities, driven by AI spending and strong earnings, despite cautious sentiment among lower-income households. The focus on high-quality firms with durable advantages is expected to yield positive outcomes as valuation pressures mount, indicating that future market performance may hinge on fundamentals rather than speculative trends. The portfolio aims to capitalize on the overlooked valuations of quality companies, presenting significant investment opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Hennessy Equity and Income Fund highlighted Equitable Holdings, Inc. (NYSE:EQH), a leading diversified financial services company focusing on life insurance, annuities, ******* et management, and retirement solutions. The Fund disclosed that it sold its position in Equitable Holdings, Inc. (NYSE:EQH) during the quarter. On August 31, 2026, Equitable Holdings, Inc. (NYSE:EQH) closed at $50.13 per share. Over the past month, Equitable Holdings, Inc. (NYSE:EQH) returned 3.90%, but its shares are down 4.97% over the past year. Equitable Holdings, Inc. (NYSE:EQH) has a market capitalization of $13.67 billion, and its stock has traded within a 52-week range of $35.19 to $55.15.
Hennessy Equity and Income Fund stated the following regarding Equitable Holdings, Inc. (NYSE:EQH) in its Q2 2026 investor letter:
"Equitable Holdings, Inc. (NYSE:EQH) triggered our soft stop-loss review, and with no insider buying to reinforce conviction, we sold the position. While Equitable continues to generate strong cash flow and return capital in a disciplined manner, the underlying core business has remained inconsistent. Earnings quality is uneven, flows are mixed, and ongoing pressure in the individual life and retirement segments raises concern. Although valuation appears attractive, our confidence in the ability to deliver consistent results and successfully execute a turnaround was lowered."
Equitable Holdings, Inc. (NYSE:EQH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 49 hedge fund portfolios held Equitable Holdings, Inc. (NYSE:EQH) at the end of the second quarter, which was 42 in the previous quarter. While we acknowledge the potential of Equitable Holdings, Inc. (NYSE:EQH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
In its second-quarter 2026 investor letter, Hennessy Equity and Income Fund highlighted Equitable Holdings, Inc. (NYSE:EQH), a leading diversified financial services company focusing on life insurance, annuities, ******* et management, and retirement solutions. The Fund disclosed that it sold its position in Equitable Holdings, Inc. (NYSE:EQH) during the quarter. On August 31, 2026, Equitable Holdings, Inc. (NYSE:EQH) closed at $50.13 per share. Over the past month, Equitable Holdings, Inc. (NYSE:EQH) returned 3.90%, but its shares are down 4.97% over the past year. Equitable Holdings, Inc. (NYSE:EQH) has a market capitalization of $13.67 billion, and its stock has traded within a 52-week range of $35.19 to $55.15.
Hennessy Equity and Income Fund stated the following regarding Equitable Holdings, Inc. (NYSE:EQH) in its Q2 2026 investor letter:
"Equitable Holdings, Inc. (NYSE:EQH) triggered our soft stop-loss review, and with no insider buying to reinforce conviction, we sold the position. While Equitable continues to generate strong cash flow and return capital in a disciplined manner, the underlying core business has remained inconsistent. Earnings quality is uneven, flows are mixed, and ongoing pressure in the individual life and retirement segments raises concern. Although valuation appears attractive, our confidence in the ability to deliver consistent results and successfully execute a turnaround was lowered."
Equitable Holdings, Inc. (NYSE:EQH) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 49 hedge fund portfolios held Equitable Holdings, Inc. (NYSE:EQH) at the end of the second quarter, which was 42 in the previous quarter. While we acknowledge the potential of Equitable Holdings, Inc. (NYSE:EQH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on
2 months ago
Annuities are popular with many retirees because they offer what seems to be a guaranteed fixed income for the rest of your life. Financial advisor Suze Orman warns that they might not be as safe a bet as they seem.
"[An annuity is] subject to the claims paying ability of the issuing company," said Orman on an episode of her podcast, Suze Orman's Women & Money. "Meaning that if the insurer gets in trouble… your guarantee is only as good as their balance sheet."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#orman

2 months ago
Annuities are popular with many retirees because they offer what seems to be a guaranteed fixed income for the rest of your life. Financial advisor Suze Orman warns that they might not be as safe a bet as they seem.
"[An annuity is] subject to the claims paying ability of the issuing company," said Orman on an episode of her podcast, Suze Orman's Women & Money. "Meaning that if the insurer gets in trouble… your guarantee is only as good as their balance sheet."
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#orman #financial #women #bezos

2 months ago
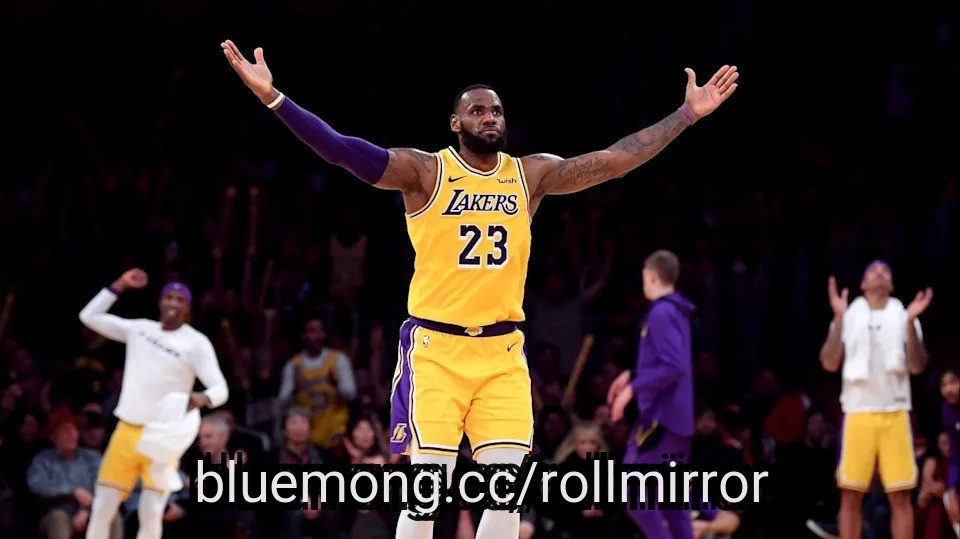
Two Midwestern insurers hold $245 million in LeBron James Nike-backed bonds, with those same balance sheets also backing annuities from Jackson (JXN) and Apollo (APO).
Non-qualified annuity gains face ordinary income tax up to 37%, no capital gains rates apply, and heirs inherit no step-up in basis at death.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Somewhere in the general accounts of two Midwestern life insurers sits roughly $245 million in bonds backed by LeBron James's Nike deal.
According to Bloomberg, an LLC named King James Funding borrowed almost $300 million in 2018 from North American Company for Life and Health Insurance and Midland National Life Insurance Co., with bonds due in 2049 at a 4.8% coupon. A follow-on $60 million in 34-year bonds priced at 5.75% in August 2022. Guggenheim Partners arranged the deal, and the pledged revenue stream includes James's lifetime Nike sponsorship.
#million #james

2 months ago
A fixed annuity guarantees the dollar amount, not purchasing power. With PCE inflation at 3.7%, a $1,900 check buys meaningfully less each decade.
Social Security's annual COLA, tracking 3.1% for 2027, preserves purchasing power over time in a way fixed private annuities fundamentally cannot.
Retirees can fight inflation erosion by adding a COLA rider, laddering annuity purchases across ages, or keeping part of the portfolio invested outside the contract.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A $1,900 monthly annuity check that lands on the first of every month solves one problem exceptionally well. You cannot outlive it. That is really the case for annuitization in a single sentence, and it is exactly why insurers can market these contracts as guaranteed for life. But here is the catch. That guarantee covers the nominal dollar amount, not what it can buy. A decade later, that same $1,900 is going to buy a smaller basket of groceries, a smaller share of a Medicare supplement premium, and a much smaller slice of any long-term care bill.
#purchasing
3 months ago
Inheriting an annuity comes with a deadline that's easy to miss. Your contract typically offers multiple payout options, including a choice that stretches distributions across your lifetime. The window to elect that option stays open for only one year. The wrong election or a delayed decision compresses your inheritance and tax bill into far fewer years.
Nonqualified annuities purchased outside an IRA or employer plan follow Section 72(s) of the Internal Revenue Code, not the SECURE Act's inherited IRA rules.1 That means you don't automatically get a 10-year withdrawal window. Instead, federal law creates two potential paths for distributing the contract.
Payout Path
General Timeline
Main Requirement
#payout


3 months ago
(please put "Fix My Portfolio" in the subject line).
I always saved and invested for the "long term," but now I am 75 and my long term is not so long anymore. I sold a lot of my mostly stock portfolio and invested in CDs and some bond funds, as well as cash and long-term-care insurance for myself and my husband, who is 83. We have no debt and try to live off our Social Security, pension and annuities, only withdrawing from our Roth or IRAs for major expenses like a roof or vacations. Our expenses run $100,000 a year.
My girlfriend is 62. Can she claim her late husband's full Social Security benefit — or does she have to wait?
My ex-husband's sister died — so why is Fidelity asking me for her death certificate?
College kids are moving into retirement communities for reasons beyond 'cheap rent'
#long #Social #Portfolio
3 months ago
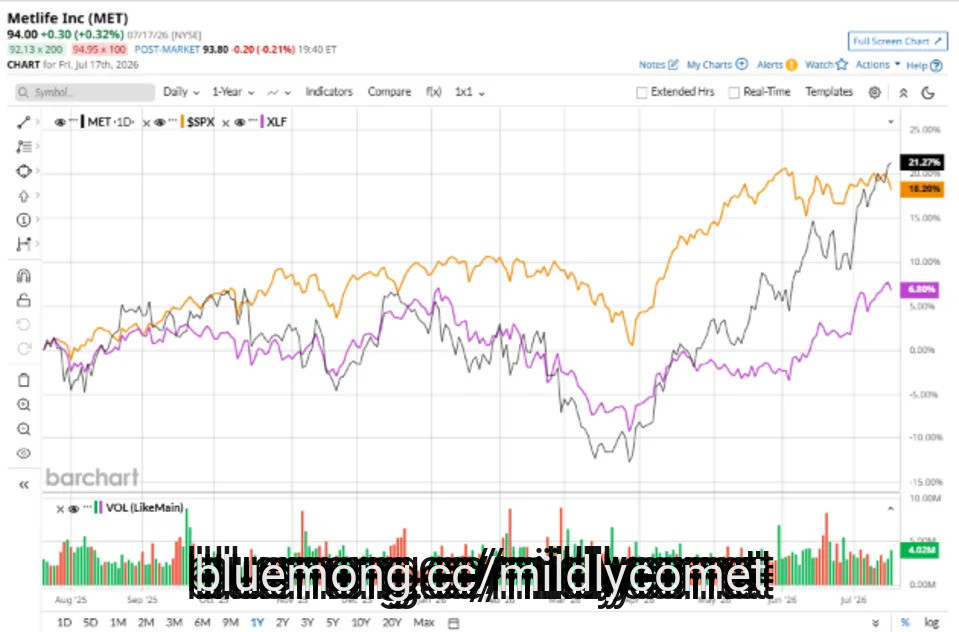
New York-based MetLife, Inc. (MET) is a financial services company that provides insurance, annuities, employee benefits, and ******* et management services worldwide. Valued at $60.5 billion by market cap, the company also provides pension risk transfers, institutional income annuities, structured settlements, and capital markets investment products, as well as other products and services. The global provider of insurance, annuities, and employee benefit programs is expected to announce its fiscal second-quarter earnings for 2026 after the market closes on Wednesday, Aug. 5.
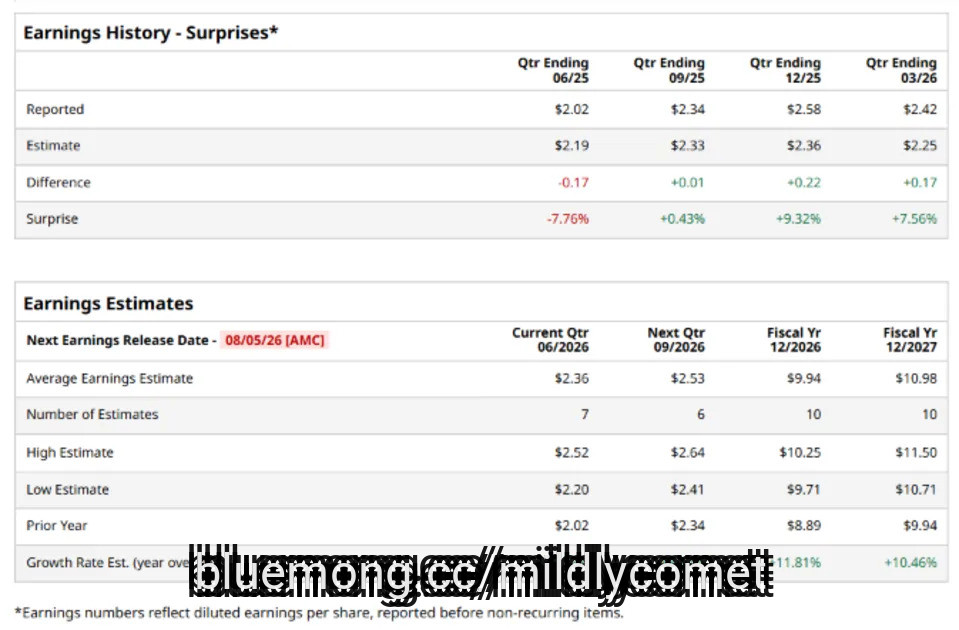
Ahead of the event, ******* ysts expect MET to report a profit of $2.36 per share on a diluted basis, up 16.8% from $2.02 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Alibaba Stock Just Got Apple's Biggest AI Endorsement. This Could Be a Game Changer for BABA.
Elon Musk Says If ******* eX Accomplishes Its Goals, 'It Will Be Worth More Than The Rest of Earth' — Though He's Also Said 'Money Will Stop Being Relevant'
AI Bubble Fears, Earnings and Other Can't Miss Items this Week
#annuities #products


4 months ago
Globe Life Inc. (GL), headquartered in McKinney, Texas, provides various life and supplemental health insurance products, and annuities to lower middle- and middle-income families in the U.S. Valued at $13.4 billion by market cap, the company offers term, whole, and children's life insurance, as well as accidental benefits, mortgage protection, and medicare supplement plans.
Companies worth $10 billion or more are generally described as "large-cap stocks," and GL perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the life insurance industry. GL has built a strong reputation for reliability and trustworthiness. With a diverse range of insurance products tailored to different customer requirements and budgets, GL is able to provide competitive pricing while keeping operational costs in check. The company's stable financial standing, fueled by steady revenue streams and sound investment practices, further bolsters its credibility in the industry.
Ahead of Micron Earnings, Here's What Barchart Data Says Comes Next for MU Stock
Huge, Unusual In-the-Money Call Option Volume in Intel Stock Today Shows Investors Bullish
Stock Index Futures Plunge as Tech Selloff Rages On, U.S. PMI Data in Focus