1 month ago
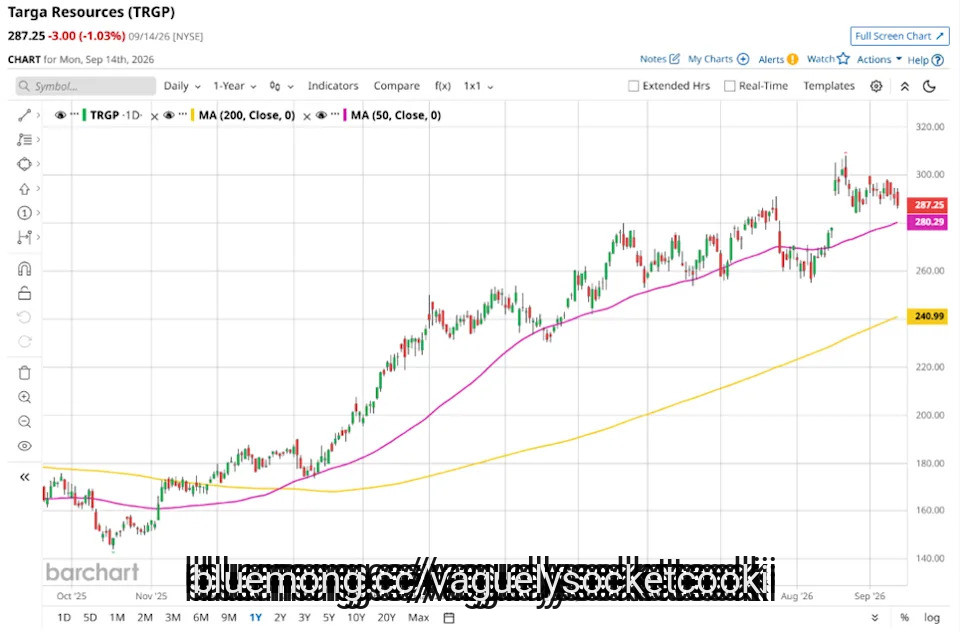
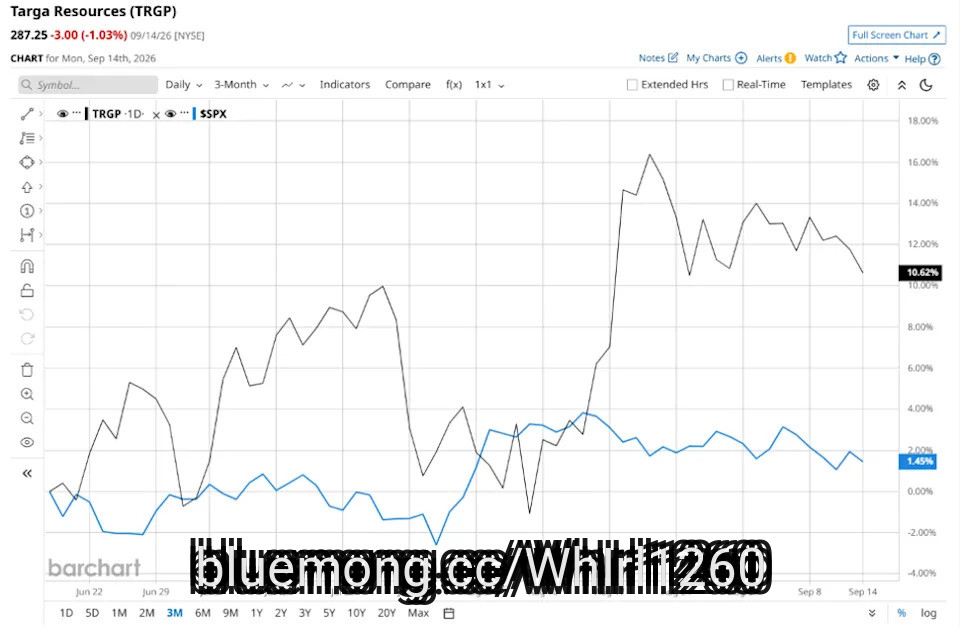
Targa Resources Corp. (NYSE:TRGP) has significantly outperformed the wider market this year, posting gains of over 56% since the beginning of 2026. A major catalyst behind this growth was the 20-year fee-based agreement that the company signed with ExxonMobil last month.
While there are concerns that the stock's rally may have topped out, the **** ysts over at TD Cowen see further growth ahead. On September 18, the firm upgraded TRGP from 'Hold' to Buy', while also boosting its price target from $275 to $350. The revised target implies an upside of almost 20% from the current levels and even exceeds the stock's record high of just under $308 achieved last month.
TD Cowen cited Targa's expected Permian Basin wet gas growth and peer-leading EBITDA growth for the upgrade. The **** yst expects the company's free cash flow yield to rise from 6% in 2026 to more than 10% in 2028, compared with an estimated 8.5% FCF yield for peers in 2030. The improvement is expected to be driven by EBITDA growth from new processing plants and the completion of a major capital project in the Speedway NGL pipeline.
According to TD Cowen, a key driver for Targa's growth is the rising wet gas production in the Permian, which means that the **** yst's thesis is tied to physical volume growth rather than simply a higher-commodity price **** umption.
Targa's recently announced deal with ExxonMobil provides greater visibility into future volumes and infrastructure demand. The company has also planned three new natural gas processing plants in the Permian Delaware as part of the deal, with an aggregate capacity of roughly 825 MMcf/day. Targa expects this agreement to add significantly to its "strong growth rate well into the next decade and bolster its outlook for durable and growing adjusted free cash flow over the long term".
#exxonmobil #ebitda
1 month ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
1 month ago
Targa Resources Corp. (TRGP), headquartered in Houston, Texas, owns, operates, acquires, and develops a portfolio of complementary domestic infrastructure ***** ets. Valued at $62.2 billion by market cap, the company's ***** ets connect natural gas and NGLs to domestic and international markets with growing demand for cleaner fuels and feedstocks.
Companies worth $10 billion or more are generally described as "large-cap stocks," and TRGP perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the oil & gas midstream industry. TRGP benefits from strategic positioning in key shale plays including Permian, STACK, SCOOP, and Bakken, giving it a competitive edge in midstream. Its diversified service portfolio, including the Grand Prix NGL pipeline and Mont Belvieu fractionation capacity, underpins a strong market presence and stable revenue base.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#market


1 month ago
Targa Resources Corp. (TRGP), headquartered in Houston, Texas, owns, operates, acquires, and develops a portfolio of complementary domestic infrastructure ****** ets. Valued at $62.2 billion by market cap, the company's ****** ets connect natural gas and NGLs to domestic and international markets with growing demand for cleaner fuels and feedstocks.
Companies worth $10 billion or more are generally described as "large-cap stocks," and TRGP perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the oil & gas midstream industry. TRGP benefits from strategic positioning in key shale plays including Permian, STACK, SCOOP, and Bakken, giving it a competitive edge in midstream. Its diversified service portfolio, including the Grand Prix NGL pipeline and Mont Belvieu fractionation capacity, underpins a strong market presence and stable revenue base.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#prices #market #assets #midstream


2 months ago
If Targa wanted to lure in hyperscaler customers, it just secured some tremendous bait. The energy stock is rising on news of a 20-year deal with Exxon for three new natural gas processing plants and related services in the Permian Basin. Targa Resources (TRGP) spiked more than 7%, jumping above a flat base buy point at 280 and an alternate…
#trgp #lure #hyperscaler
#trgp #lure #hyperscaler
3 months ago
With a market cap of $60.6 billion, Targa Resources Corp. (TRGP) owns and operates a diversified portfolio of natural gas, natural gas liquids (NGL), and crude oil **** ets across North America. Through its Gathering and Processing and Logistics and Transportation segments, the company provides integrated services spanning production, storage, transportation, marketing, and resale of energy commodities.
The Houston, Texas-based company is set to deliver its fiscal Q2 2026 results soon. Ahead of this event, **** ysts forecast TRGP to report an EPS of $2.64, a decline of 8% from $2.87 in the previous year's quarter. It has exceeded Wall Street's bottom-line estimates in two of the past four quarters while missing on two other occasions.
Huge, Unusual Intel Options Volume Today Ahead of Earnings This Week
Intel Stock Is Down, But Put Premiums are High - Put Short Sellers Love the High Yields
The Number Tesla Stock Bulls Are Really Waiting for This Earnings Season Has Nothing to Do With Cars
#Stock